Raising bank capital requirements

I’ve been a little slow to get round to much comment on the Reserve Bank Governor’s proposals to require banks to fund a much larger share of their balance sheets with equity capital.  These aren’t small changes: from a starting point where they more or less accept that New Zealand bank capital ratios are already higher than those in most advanced countries, they want to compel banks incorporated here to adopt capital ratios that would be higher than (almost?) anywhere else in the world (including, notably, higher than in Australia).

I had a couple of initial posts (here and here) immediately after the consultative document was released, and one a couple of weeks ago on the way in which the Bank has continued to discount the results of demanding stress tests it has required banks to undertake.     Since I wrote that post the Reserve Bank has finally released (in response to OIA requests from me and others) various background papers.  One of them specifically addressed the issue of the stress tests.  Suffice to say, whatever the validity of some of the specific points the authors identified, it did not materially my view of an awkwardness that the Bank still has to contend with; repeated very demanding stress tests suggests a very robust system, and yet the Bank proposes to go out on a limb with its capital requirements for banks incorporated here.  Various other people have written comments on the Reserve Bank’s proposals, and I’d commend to your attention most of a column by my former Reserve Bank colleague Geof Mortlock, and some observations from Roger Partridge of the New Zealand Initiative on the striking absence from the consultative document of any serious attempt at a cost-benefit analysis.

It is striking just how little substantive supporting analysis, and robust testing of alternatives, there is in the consultative document.  And although they have finally released various background documents, some of which are interesting, as those papers stretch back over almost three years through a couple of changes of Governor, it is impossible to know what bits the current Governor is or is not drawing from in reaching his proposals.  There has been no substantive speeches from, or searching interviews with, the Governor or his deputy since the document went out.

Of course, the Bank has a long history of not taking consultation very seriously –  they’d jump through the formal required hoops, and perhaps even amend the odd working detail here or there, but there was never much of a sense of being genuinely open to alternative perspectives.   On this particular proposal, so much money is involved that one can only hope that they are eventually forced to do better.  Perhaps there really as a compelling case for going out on a limb as they propose, but if so that case has not yet been made.  On the specific issue –  imposing more-demanding capital requirements than almost any of our peers (eg small open floating-exchange rate countries, with moderate-sized locally-focused banking systems, and government finances in good order) – nothing in the consultative document even makes the attempt.  Apparently we are just supposed to take the Governor’s word for it that it is all fine; that he knows what is best for us.

There is a range of areas where the analytical support is very weak.  I might come back to some of them. But today I’m going to start at the end and highlight one absence that I found particularly glaring.   Having reached the conclusion that a 16 per cent capital requirement would be appropriate for the large locally-incorporated banks, there is almost no discussion at all as to how banks and the financial system more generally might respond, whether in the protracted transition or in the longer-run.   Which might be okay in some quasi-academic document (of the sort they cite from overseas, trying to estimate “optimal” capital ratios), but shouldn’t be remotely acceptable when a regulator is consulting on far-reaching proposals, directly affecting private businesses (and potentially firms and households more generally), that it wishes to put the force of law behind.   We should expect to see that regulator lay out its workings, and tell us how it thinks things will unfold, in the specifics of the New Zealand economy and financial system.  Only then can we really unpick and challenge their reasoning and assumptions (implicit or otherwise).

The bottom-line appears to be that they think bank lending margins will rise to some extent (they report  –  reasonably enough –  not believing that Modigliani-Miller offset effects hold in full, at least in a potentially protracted transition) but that otherwise banks’ shareholders will happily divert most of their profits over the next few years into reinvesting in the business.  But they show no sign of having tested those assumptions, let alone of having thought more widely.

Why, for example, would the Reserve Bank not suppose that existing locally incorporated banks would respond to large increases in capital requirements in part by pulling back on their willingness to lend?  There are two ways to increase actual capital ratios: increase capital or reduce the volume (at least the growth rate) of assets relative to your prior plans.  It is not as if no banks anywhere have ever responded to increased capital ratio expectations (market or regulatory) by looking to reduce risk-weighted assets (it was a common in the EU after the last crisis).  Whether or not, in the long run, Modigliani-Miller effects really hold nearly in full, shareholders don’t tend to believe they do,  and if the New Zealand authorities insist on higher capital requirements, lending into the New Zealand market is going to look less attractive to shareholders in banks subject to those requirements.  Perhaps the Governor thinks there is already too much credit in the New Zealand economy and wouldn’t be unhappy if it becomes harder to get.  But none of that is discussed or analysed in the discussion document.

Similarly, there is no discussion at all of the fact that we are now eight or nine years into a growth phase, and that most probably there will be another recession along at some stage in the next five years (the planned transition period).  Now, of course, in truth the best time to increase capital requirements was always five years ago, but it doesn’t change the fact that  –  with capital ratios already comfortably high by international standards –  the specific proposal is to increase them over the next five.  In recessions borrowers tend to become more reluctant to borrow, and (typically quite rationally) lenders become more reluctant to lend, but if we go into a new recession in the next few years with banks still facing several years of increased capital requirements, isn’t it quite plausible that banks would become even more reluctant to lend than usual, exacerbating –  or dragging out –  the downturn.  And recall that the Reserve Bank has nowhere near as much monetary policy leeway in the next downturn as it did in previous ones.  That might reasonably make one more nervous than otherwise about ramping capital requirements over the next few years even if one could make a decent case in the abstract.  But none of this –  none –  is discussed, not even to allay concerns, in the consultative document.

There is also no discussion or analysis of the way in which the proposals will affect Australian (and other foreign) locally-incorporated banks differently than New Zealand owned banks.   Dividend imputation means that debt and equity are taxed similarly for New Zealand owned companies.  But dividend imputation doesn’t hold for foreign-owned companies, and substantial increases in capital requirements will impose a direct additional cost on the shareholders in foreign-owned banks (in this case, the Australian parents).   In other words, the Governor’s proposals skew the playing field away from the Australian banks (large and more diversified) in favour of the domestic banks (small, undiversified, and typically capital-constrained).  The Governor is known to have some animus towards the Australian banks –  and on that score he might even have political sympathisers (at least from rabble-rousers like Shane Jones) –  but none of this is identified or discussed in the consultative document.   I’d argue that we are generally better off having big banks that are part of offshore banking groups. Perhaps the Governor disagrees, but if so the onus should be on him to make his case, not to attempt to slip through regulatory measures that consciously disadvantage the foreign-owned banks incorporated here.  It is far from clear that boosting the competitive position of a 100% state-owned bank (Kiwibank) is any sort of longer-term gain to financial system soundness or efficiency.

There was also no discussion in the consultative document on the potential lenders who will not be subject to the Governor’s proposed capital requirements.  For example, those requirements will not apply to non-bank deposit-taking lenders (let alone any lenders who aren’t deposit-takers at all).  NBDT capital requirements aren’t something the Reserve Bank can set itself (same goes for LVR restrictions, which is why LVR restrictions were never applied to the NBDTs) and so it would appear that one set of regulated intermediaries will have materially lower capital requirements than another set.  All else equal, mightn’t we expect to see at least some disintermediation to these lenders?   At the other end of the spectrum, banks that aren’t locally incorporated are also not subject to Reserve Bank capital requirements.  If the Governor proceeds with his proposals, wouldn’t we expect to see more lending gravitate towards these lenders (subject to the local incorporation threshold limits), and at the “big end of town” to banks that aren’t registered in New Zealand at all.   The SME down the street might need to get credit from a local lender, but Fonterra or Air New Zealand don’t.   These effects wouldn’t arise if authorities around the world were all raising capital requirements to a similar extent, but they aren’t.   Not even APRA.  And yet there is no sign the Reserve Bank has thought hard about the potential disintermediation issues.

And even if all banks (broadly defined) globally were subject to much the same capital requirements, one might have to think about disintermediation to non-institutional providers of credit.  If capital requirements on a portfolio of mortgage loans are increased markedly and there is incipient pressure for bank lending margins to rise, it opens the door for more securitisation options.   But, again, none of this is touched on in the consultative document.

There have been suggestions, notably from at least one investment bank/broking firm, that the Reserve Bank’s capital proposals could increase New Zealand lending interest rates by as much as 100 basis points.   That, frankly, seems unlikely to me, not because banks (especially the Australian banks) won’t pull back on the supply of credit or because bank shareholders won’t look to maintain high targets ROEs for a while, but because of the potential disintermediation from the existing big-4 institutions.   Those alternatives limit the extent to which lending margins could increase (while the potential for offsetting OCR adjustments limits the extent to which retail lending rates themselves would rise).     On my story, there is a cost to the efficiency of the financial system –  a key constraint the Bank is required by law to take account of.   The core big institutions –  already very robust –  might be made a bit stronger, but in the process they would be of diminished importance in the financial system.  Any gains from stronger core institutions could be compromised by the greater proportion of credit flowing through other channels.  (A topic for another day is that entire proposal is built around the idea that the costs policy should try to mitigate relate narrowly to the failure of regulated institutions, rather than to the gross misallocation of credit –  and investment resources – in the good times, whether or not any core institutions fail when the reckoning occurs.   But there is no sign the Reserve Bank has considered whether the allocation of credit, and lending standards, will be maintained if there were to be significant disintermediation.)

I could go on, but won’t for now.  My point wasn’t to attempt to isolate every possible channel, but to note that in their consultative document –  where they are judge and jury in their own case –  the Reserve Bank has provided no analysis of any of these issues, not even to set our minds at rest.   Just nothing.  We should be able to expect better.


Looking towards the new MPC

Next week will bring the first Reserve Bank Monetary Policy Statement of the year. It will be the last –  after 29 years – prepared solely on the responsibility of a single individual, the Governor.     He gets to make one more OCR decision on his own and then on 1 April the new statutory Monetary Policy Committee –  established under legislation passed just before Christmas – takes over.   It is an apt date given that the new regime is designed to have the appearance of being a significant reform but is in fact likely to do little to reduce the undue dominance of a single unelected official, the Governor.   In this case, a Governor who after almost 11 months in office hasn’t managed to make a single on-the-record speech about what is still (for a few more weeks) his primary function, monetary policy (and the associated cyclical economic position).

The first OCR decision to be made by the new Monetary Policy Committee is not scheduled until May, but we can expect some important announcements in the next couple of weeks.

Under the amended legislation, there is a raft of new formal documents required.

The most important of them is the “remit”.   This replaces the Policy Targets Agreement framework, and is the mechanism that tells the Monetary Policy Committee what specific targets to pursue.

On an ongoing basis, the remit will be set directly by the Minister of Finance –  it won’t need to be agreed by the Governor or the MPC.   The Bank will have to provide advice about the possible content of the remit, and in providing that advice the Governor is required to (a) consult with the MPC, and (b) seek input from members of the public.

But those provisions don’t apply at all to the first remit.  Under the legislation, the remit is required to be agreed by the Governor and the Minister, with no input from either the public or the MPC members.  It is also supposed to be published within two months of the royal assent having been given to the legislation, which means it will almost certainly be published by 20 February.  (There is provision for the Minister to issue a remit directly if the Governor and Minister can’t reach agreement in that time, but that seems very unlikely –  it would be in neither side’s interest to allow it to happen, even if there were some differences between them.)  As there have been no hints suggesting, or preparing the ground for, anything else, I expect the first remit will have substantive content very similar to the existing Policy Targets Agreement signed when the Governor was appointed last year.

The second new document is the “charter”.  The charter is supposed to cover issues around transparency, accountability, and decisionmaking procedures for the MPC, and is required to include provisions around recording and publishing minutes of meetings.  On an ongoing basis, the charter is agreed between the Minister and the MPC as a whole. But the first charter –  which will set the terms for how the MPC first operates, and as the default operating model will be hard to deviate from  –  is to be implemented simply by agreement between the Governor and the Minister.  It is also supposed to be published by 20 February.  There is no public consultation, and no consultation with MPC members either –  who haven’t been appointed yet. They will, presumably, just be offered a “take it or leave it”.   We know the Minister’s predilections in this area –  highly summarised minutes only –  and the Bank’s previous biases against any sense of individual accountability or responsibility –  but it will be interesting to see how restrictively the document is worded. I’m not optimistic.

The third document is the “code of conduct” for the MPC (particularly as it will affect the external part-time members).  This is approved by the Bank’s Board, rather than the Minister.  It also has to be published by 20 February.   In fact, the Bank (the Governor) –  the only people allowed input here –  was required to prepare the code and submit it to the Board by 20 January.   I presume that what emerges will be reasonably sensible, but there was considerable work needing to be done on the draft code of conduct that was around at the time the Board was advertising for MPC candidates last year (when, as I recall it, activities like writing a blog or newsletter on matters macroeconomic would not have been a problem).

So within the next two weeks, we can expect to see that suite of documents published.  Even if they aren’t released before the Monetary Policy Statement next week, it would be reasonable to expect the Governor to be asked about them at his press conference.  After all next week MPS (whatever the talk about future monetary policy) isn’t at all binding about the future: the decisionmakers will ( in principle) be different, and so will the rules under which they will be working.   In principle, the transition to a new regime ushers in a period of some greater uncertainty about monetary policy decisions and (in particular) around monetary policy communications.

The biggest uncertainty, however, is about the membership of the Monetary Policy Committee.  You will recall that under the new legislation there is required to be a majority of internal (executive) members.  Indications have been that there will be four executive members, and three part-time non-executive members, plus the Treasury observer.   These appointments are formally made by the Minister of Finance, but he can only appoint people nominated by the Bank’s Board, and they in turn are likely to be heavily influenced by the Governor (who is a member of the Board, and the only Board member who knows anything much about monetary policy).

Even on the executive side, there is some uncertainty.  The Governor will be a member, and chair, as we can safely presume will the Deputy Governor, Geoff Bascand.   The newly appointed Assistant Governor for monetary policy and financial markets, Christian Hawkesby, seems certain to get one of the appointments (he’d hardly have taken the job without that sort of assurance), and the fourth slot is likely to be reserved for the chief economist.  The Bank is advertising that position at present, and unless there is an internal appointment it might be a stretch to even have someone in place by  1 April.   Under the new legislation, there is also a non-voting Treasury observer.  Since Gabs Makhlouf leaves office in a few months, that is additional (minor) source of uncertainty around how the MPC will function.  We wouldn’t expect the Secretary to have enough time to spare (or regard it as a priority) to take the role themselves (although in the transition Makhlouf has), but we also don’t know who will be nominated and quite what role they will play.

And what of the non-executives?  As I’ve noted before, these are positions that involve a significant commitment of time (they advertised for 50 days a year), and yet there will inevitably be quite significant constraints on what other activities such appointees can take on, and 50 days out at the Reserve Bank doesn’t fit easily with most other full-time jobs.  New Zealand government boards and committees don’t typically pay that well either.  But the biggest obstacle to getting decent people, who will be able to make an effective contribution, is the neutered nature of the role.     The non-executives will always be a minority of the committee.  They won’t, we are told, be able to give speeches or interviews about the economy or monetary policy (unlike, say, peers in the UK, US, or Sweden). They won’t, so far as we know, have any dedicated research or analysis resources –  and at one stage last year the Governor was talking about how he didn’t want economists anyway.  And if they disagree with the majority view, they won’t even able to make their case openly, and have that identified dissent (and the reasons for it) on record.      And they’ll be appointed by the Board, with key input from the Governor, and we know that the Board has long operated to protect the Governor.  There is little likelihood that anyone remotely awkward will be appointed.  The sort of people who might actually add value are unlikely to be seriously interested, given the way the system has been set up.

And they face the executive members.   They work closely together all the time.  And each of them work for and to the Governor (who also controls salaries and internal resource allocation).  In fact, both Hawkesby and the new chief economist will have been directly and personally chosen by the Governor, a Governor not known for welcoming challenge or dissent.  It would be a surprise if the internal members don’t maintain a pretty solid bloc vote almost all the time.  If they were a group of people with compelling skills in economic analysis and policy that might usually work okay (if being less than ideal), but by the standards of many overseas central banks the executive team itself looks under strength.

It is still anyone’s guess who they will find for these positions. But I did have a response the other day to an OIA request I had lodged last year about people being considered for MPC positions.  I had the first part of the response last year, about the applicants, but this latest response was about the second part of my request, about people who the Board had taken more seriously.  This is what I got from them

Your 23 October request under section 12 of the Official Information Act (the OIA) stated a willingness to split the response into two parts if timing of the process made this necessary. The Reserve Bank provided a response to the first part of your request on 20 November. In the final part of your request you sought:

. . . information on the applicants for the external MPC roles, (as advertised, applications having closed on 7 Sept 2018):

  • the number of applications taken further (not just immediately set aside as clearly unsuitable/unacceptable by the Board or its agents;
  • the proportion of those applications taken further from (a) women (as best you can tell), (b) people currently resident in New Zealand, and (c) people currently employed at a university.

In response to the information requested in the bullet points above: nine applicants have been taken to the stage of final consideration. Of the nine, two are women, all are New Zealand resident, and one is currently employed at a university.

I was interested to learn that all those at the final stage of consideration for appointment are New Zealand residents.   There has long been a reasonable argument that the Reserve Bank could benefit from having someone from overseas on the committee, especially in view of the limited pool of potential high quality, available, candidates here.  It wasn’t obvious that the role would be particularly attractive, given the institutional design (see above) and New Zealand remuneration rates.  And so it seems to have proved.

Even with the weak statutory framework, the new MPC could have been a materially useful step forward, with a Governor and Minister who were seriously committed to greater openness and accountability, and a serious contest of ideas.  But, of course, if that were Grant Robertson and Adrian Orr, we wouldn’t have the law written as it is.  My working hypothesis has long been that the Minister and Governor want to have things look a bit different without actually being materially different at all.  Perhaps they will get one good external (at least first time round), but that person will either find it frustrating, or will just settle in to being a bit player, an honorary members of the Bank’s Economics Department.  Most likely, it will end up a lot like the system in place now for almost 20 years, when there have been a couple of part-time external advisers to the (internal) Monetary Policy Committee.  Most were business people – although a couple were trained economists –  who sat through all the meetings, provided business anecdotes and perspectives (some genuinely useful) but who had little real impact, and often found it all rather frustrating.   For them, at best it was probably an interesting experience, a diversion from the day job.  Even allowing for the statutory nature of the new positions, I don’t really expect things to be much different in future.  After all, like the current advisers, these new people will be selected at the Governor’s choosing, with a strong emphasis on “all working together”, while the Governor –  a Governor known for sounding off on all manner of things – is the only public face.

There are also some other unsatisfactory aspects of the new law.  The MPC is responsible for the content of future Monetary Policy Statements, but not for the new five-yearly reviews of monetary policy –  those are the Governor’s responsibility (surely any worthwhile review would primarily be done by outsiders, commissioned by Treasury or the Minister?).  And as I’ve noted before what the Act makes the MPC responsible for is drawn very narrowly.  It will work okay while monetary policy involves OCR adjustments, but it is much less clear that the MPC will have an effective (statutorily-based) say in the deployment of any unconventional instruments that may become necessary if the OCR hits the practical lower bound.  Parliament should have given the MPC responsibility for all matters relating to monetary policy, with the MPC able to then delegate to the Governor some operational matters.    They’d have done so if this legislation were much other than a cover for something little different than the status quo, where the Governor runs the show –  somthing like prosecutor, judge, jury, and appeal court in his own case.  In an open democratic society, no one individual should have that much untrammelled power, and certainly not an unelected person.

Perhaps some of you will be thinking that none of this much matters, as the Reserve Bank has done an adequate job.  Personally, I would dispute that –  and “adequate” –  shouldn’t be the standard we look for – but more importantly, I’d argue that key government institutions should be designed to promote substantive accountability, high levels of transparency, minimising single person exposures, and promoting the contest of ideas and evidence (in areas characterised by huge uncertainty).  These reforms look like just papering over the cracks.

This is one of those issues on which I’d like to be proved wrong. Perhaps I’ll be pleasantly surprised and a succession of high quality appointments will hope make these reforms one that make a real difference. But I’m not holding my breath.

(On another matter, scrolling for various websites yesterday I found someone linking to a post I’d written back in 2017.  I wasn’t quite sure why, but then I noticed that they were actually retweeting something from a Twitter handle called croakingcassandraredux.  Someone, unknown to me, has started a Twitter account describing itself as “Michael Reddell’s alter ego”, a “public service venture” intending to give a wider audience to my material by tweeting links to various posts.   I guess readers here have already found me, and anyone who wants can sign up to get the posts by email, but if the account is any use here is the link. )


Yes, but….

Yesterday – no doubt with Waitangi Day in view –  the history teachers’ association was out with a call (even a petition) for the compulsory teaching of New Zealand history in schools.   You might suppose this was a job creation scheme for history teachers, but I’m happy to grant that that won’t be the only motivation behind the association’s call.

You might suppose that history teachers –  in particular –  might be interested in the entire story of our country, ancient and modern.  And yet, oddly, the “Petition Reason” seems only interested in one brief period.

Too few New Zealanders have a sound understanding of what brought the Crown and Māori together in the 1840 Treaty, or of how the relationship played out over the following decades. We believe it is a basic right of all to learn this at school

As it happens, in principle I strongly favour the teaching of New Zealand history in our schools.  I find it utterly astonishing how little  of the story of our country –  and what little there is (ANZAC Day, Waitangi Day) typically wrenched from context –  and of our people and cultures is taught in our schools.  As I recall, I got through the whole of school with no New Zealand history, other than one School Certificate history unit on the New Zealand and US welfare system.   From what three children wending their way through the school system tell me, it doesn’t seem much different now, unless one chooses to do history in years 11-13 (a pretty small minority), but where apparently it is now only permitted to study history with “implications for New Zealand”.  No man an island and all that, so I’m happy to argue all human history (and certainly western history) has implications for who we are today, but I don’t think that is quite what the history teachers or the Ministry of Education have in mind.  I don’t know much about how it is done in other countries, but I’m struck by my daughter’s English penfriends who tell about studying specific history courses at around ages 10 to 12.  There is so much about New Zealand, New Zealanders, and our interaction with the rest of western history, that could –  and ideally should –  be taught.

Of course, the whole philosophy of many of our “educators” is opposed to learning facts, let alone placing them in a coherent narrative.  How vividly I recall the activist principal of our local primary school telling a group of parents of new entrants that the school tried not to teach facts, as nothing specific they taught now would be any use fifteen or twenty years hence.  Any serious teaching of history –  not isolated tiny NCEA standards –  would fly in the face of that sort of mentality.

I’d almost go as far as the history teachers in calling it a “basic right” for children to be educated in where our country today has come from.  We don’t invent ourselves anew with each new generation, but as individuals and societies we are formed –  and informed –  by what came before us.  That is so even when many want to turn their backs on much of their origins.  Origins they still are.  And choices made yesterday affect institutions (broadly defined) today.

And what counts as history doesn’t simply begin at Paihia in 1840 (or even the few years just prior to that).   So, in principle, I would strongly favour teaching (say) 1000 years of history, introduced from new entrants and expanded as the capacity of the children to make sense of the material grows.    Look back to the first human settlement of New Zealand, and to (say, and inevitably arbitrarily) the Norman Conquest and subsequent British (and European) history.  Tell the stories, establish a sense of the flow, cover (inevitably a bit lightly for most) the politics, the religion, the key figures, the way in which governments developed.   For New Zealand, I’d tell the more recent story partly in a cross-country comparative sense –  New Zealand vs (say) Australia, Ireland, Canada, Newfoundland, or even Fiji and South Africa.  As it is, smart historically-oriented children probably know more about British Prime Ministers and US Presidents than they do about those who’ve directly led and shaped our own country.        One can, of course, mount an argument that those big countries were “more important”, and I wouldn’t really disagree, but New Zealand history is our history.  Depriving our kids of serious exposure to New Zealand history is akin to depriving them of any knowledge of their great-grandparents.

My son’s year 12 history teacher told the class yesterday that he didn’t support the history teachers’ association call, because kids typically weren’t interested in New Zealand history and there was no point teaching stuff kids weren’t interested in.  Frankly, that seems like an abdication of responsibility –  most kids aren’t that interested in maths and yet we give them no choice about learning it.  And it is also something of a vote of no-confidence in teachers: sure, most kids probably won’t be that interested in New Zealand history at 15 if they’ve never learned any previously (I wasn’t then), but if you start early and introduce key figures, key stories, in age-appropriate ways I’m reluctant to believe that kids will have no interest.  But even if they still claimed no interest, they need to know where we’ve come from.  After all, in a very few years each of them will be eligible voters.

What I found most interesting in the articles yesterday was where the pushback from teaching history was coming from.

But the associate minister of education and minister of Crown Māori relations, Kelvin Davis, was quick to quash any impression the government might make the topic compulsory.

Davis was formerly a teacher, so one might have thought he’d favour making New Zealand history, including New Zealand’s place in the world, an integral part of what schools teach.   It is the sort of subject that probably matters even more for those from disadvantaged backgrounds, who aren’t as likely to go digging themselves, or to be introduced to some structured narrative of New Zealand from home.

But supportive as I am in principle of a much more central role for history –  New Zealand history –  in what is taught in schools, what leaves me rather more ambivalent (“yes, but….”)  is the sort of people who would be teaching our history, and/or designing any curriculum.      Few of them seem to see New Zealand history as something to celebrate (I’m going to be fascinated to see how our Prime Minister treats the 250th anniversary of Captain Cook’s first visit), and there is a strong theme of shame –  the “black armband” approach to history –  combined with some agenda for how these people think society should be organised now or what role (say) the Treaty of Waitangi should play.  There is little sense of handing down the traditions and insights that made us who we are –  the sense that any society stands on the shoulders of those who went before –  and little interest in the past for its own sake (understanding, for example, why people believed and acted as they did), only as subject for judgement or grist to the mill in current political contests.   And I guess that is why the government resists the idea of making the teaching of history compulsory: they sense that many parents probably really aren’t keen on ill-educated indoctrination.

Give parents effective choice over schools –  proper and full funding for independent schools –  and I’d be a lot keener on translating support in principle for some serious structured teaching of New Zealand history (ups and down, successes and failures, and so on) into something worth implementing, in ways that might usefully amount to more than (often unwitting –  most teachers know no better) indoctrination.

There was a quote from G K Chesterton in an article I was reading yesterday (in the Australian periodical Quadrant)

The trouble with too many of our modern schools is that the State, being controlled so specially by the few, allows cranks and experiments to go straight to the schoolroom when they never have passed through the parliament, the public house, the private house, the church, or the marketplace. Obviously it ought to be the oldest things that are taught to the youngest people; the assured and experienced truths that are put first to the baby. But in a school today the baby has to submit to a system that is younger than himself.  the flopping infant of four actually has more experience and has weathered the world longer than the dogma to which he is made to submit.  Many a school boasts of having the latest ideas in education, when it has not even the first idea; for the first idea is that even innocence, divine as it is, may learn something from experience.

Dated as the wording may be, the ideas seem apt nonetheless.

And there is an interesting new article in Foreign Affairs by Harvard historian Jill Lepore on “Why a Nation Needs a National Story”.   I’m ambivalent about, or even unsympathetic to, where she gets to –  she wouldn’t quite put it like this, but it amounts to history as indoctrination/shaping –   but I was quite taken with this line

“Writing national history creates plenty of problems. But not writing national history creates more problems, and those problems are worse.”

We owe it to our kids to form them in where we (they) have come from.   Only when given a decent base of knowledge can they intelligently challenge interpretations and reach useful views as to what from history should be taken forward and what left behind.  Whether agents of the state, imbibing radical agendas often upending that heritage, can be trusted to do that job is quite another question altogether.

House prices and building: Australia and NZ

You may, like me, be intrigued by the stories emerging from Australia about falling house prices.    The fall in nationwide house prices isn’t that large –  still less than we experienced in New Zealand in 2008 – but (a) the economy isn’t in a recession, and (b) there is little sign yet that the falls are about to end soon.  Lower house prices would seem likely to mostly be “a good thing” –  cheaper goods and services typically are – and the banks are well-capitalised to cope with even some serious combination of bad economic times and falling house prices.  But on the other hand, whatever was causing this particular fall, I’d heard little to suggest that land-use rules were being substantially liberalised in Australia (any more than in New Zealand), so I’ve been –  and remain –  quite sceptical about the idea that Australian house prices would fall sharply and stay down.  And, of course, of anything similar in New Zealand.

Time will tell, but out of curiosity I decided to dig out a few numbers.   The first was a comparison of residential investment as a share of GDP.   This chart is in nominal (current price terms).

res nz and aus 1

And this is in real terms (which isn’t strictly kosher and is an approach frowned on by SNZ, but some analysts do it anyway).

res nz and aus 2

There are differences between the two charts, but the bit that caught my eye was that New Zealand has been devoting a larger share of GDP to house-building (and additions and alternations etc) than Australia for almost the entire decade.

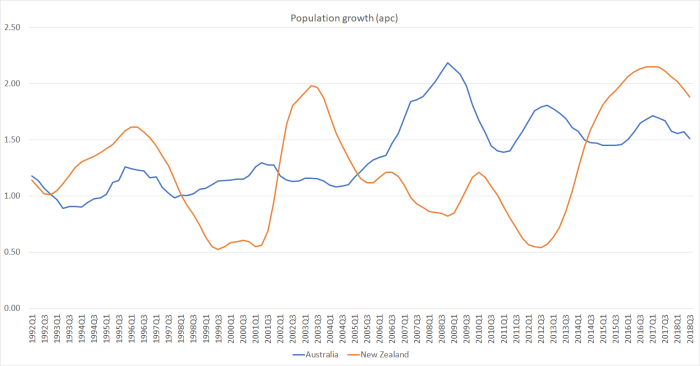
Population growth is one of the biggest determinants of how much accommodation will be demanded.  Here is annual population growth in the two countries.

popn nz and aus

Over the last four to five years, our population growth rate has run quite a bit ahead of Australia’s.   All else equal, one percentage point faster population growth requires something like two percentage points of GDP larger share of residential investment (the net stock of residential dwellings – themselves depreciated –  is well above 100 per cent of GDP).

At least two other things complicate comparisons.  First, a big chunk of residential investment spending in New Zealand for several years after the Canterbury earthquakes was about repair and rebuild, not adding to the housing stock (relative to the pre-quake situation) at all.  There was nothing comparable in Australia, and so all else equal one should have expected a larger share of resources devoted to housebuilding here than in Australia.  And the other relevant factor is that intensification often involves the demolition (and loss) of existing dwellings: even in normal (non-quake) times not all new dwelling approvals add to the housing stock.

New Zealand has a reasonably long-running quarterly series on the estimated number of private dwellings.   I could only find the comparable Australia series back to 2011.  But this is what trends in the number of people per dwelling look like over the last few years.

people per dwelling

On the face of it, that is a pretty startling difference. (I did find reference to some Australia census data suggesting that in 1991 population per dwelling in Australia was also around 2.7.)

A declining ratio of people per dwelling is what might one expect in functioning house and land markets.  After all, both countries are getting richer, birth rates are lower than they used to be, people are living longer (ie a larger share of life after kids have left home), lifelong marriage from an early age doesn’t seem to be becoming more a thing.  But it –  a fall in the ratio –  is much harder to achieve when regulatory obstacles mean house prices are driven sky-high.   Then people squash together a bit more.

Another way of looking at the last few years of that chart is that over the seven years to September 2018 Australia had population growth of 11.8 per cent and the stock of dwellings increased by 12.7 per cent.  In New Zealand, over the same period, the population is estimated to have risen by  11.6 per cent and the stock of dwellings increased by only 8.6 per cent.   For the entire housing stock –  slow-moving at best –  that is a really big difference.

I haven’t mentioned (a) the large share of apartments built in Australia in recent years (which some look on favourably –  the Reserve Bank here always used to tout that record –  and others are more inclined to mutter about future potential urban slums etc), or (b) differences in credit conditions on the two sides of the Tasman (responsible, on some tellings, for the recent weakness of the housing market).

But looking across the numbers I’ve presented here, and bearing in mind that there has been little or no effective liberalisation of land use laws in New Zealand (or a fix to the construction products market), it is hard to see any good reason to expect that we will see any material or sustained drop in house and urban land prices here.

house prices jan 19

There will be a recession along eventually, ringfencing and a capital gains tax (both dubious new economic distortions) might dampen things a little, and the Reserve Bank’s capital proposals if implemented might exacerbate any downturn, but in the end if land remains artifically scarce (a bit like new cars in 1950s New Zealand) it remains hard to envisage a serious or substantial adjustment.   And responsibility for that failure –  and failure it is –  has to be sheeted home to the political parties that vie to govern us, notably National and Labour.

Wages, earnings capacity and all that

There has been a line run in many quarters over recent years suggesting that wage inflation is surprisingly low.   There was a bit of that tone in several articles on such issues in the Sunday Star-Times yesterday, and it even appeared in the Leader of the Opposition’s speech last week

For many New Zealanders, incomes are struggling to keep up with the rising cost of living.

We’ll probably see more such stories when the next round of labour market statistics are released later this week.

As I’ve noted in various posts over a couple of years now (including recently), I’m not at all convinced by this story.

My preferrred measure of wage inflation is the Statistics New Zealand analytical unadjusted Labour Cost Index series.  The LCI is designed to be stratified –  comparing wage inflation for the same jobs (and so not facing the compositional issues the QES measures have) –  and the “analytical unadjusted” refers to the idea that these are straight wage measures, not ones that attempt to adjust for individual job productivity changes (as the headline LCI numbers do).  The series is only available back to the 1990s, but here is the history.

LCI 1

Nominal wage inflation has picked up a little, but is still well below what people got used to in the five years or so prior to the last recession.  But so is inflation for goods and services.

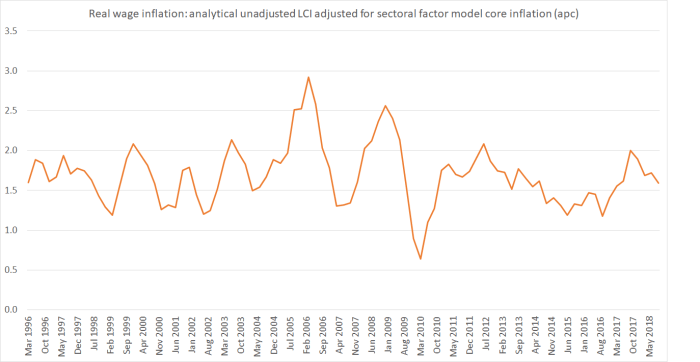
Here is the same wage series adjusted for the Reserve Bank’s sectoral factor model measure of core inflation (I could have used the headline CPI –  the averages don’t change materially, but there is a lot more “noise” in the CPI itself).

LCI 2

Two things caught my eye:

  • first, each and every year real wages (on aggregate across the economy) have risen –  even in the depths of the last recession.   It won’t have been (and won’t be) true for every individual, but it is true –  at least on these measures (generated by our national statistics agency, and the official agency best placed to tell us about core inflation) –  across the economy as a whole.
  • second, real wage inflation this decade looks to have averaged not materially different to what we experienced in the late 1990s and 00s.  There were individual years where faster wage inflation was recorded, but if there is a systematic weakness in real wage increases  this decade compared to what went before, the difference is pretty small.   And notwithstanding talk –  in those SST articles –  that the current labour market is “as good it gets” actually the unemployment rate is still above the lows of the 00s.

All of which is a little strange, because economywide productivity growth has slumped (to basically zero in recent years).  Here is a chart of estimated labour productivity back to 1995 when the LCI series starts. I’ve shown it in logs, so that a less steeply rising line accurately illustrates a declining growth rate of productivity.

lci 3

There is a bit of short-term noise in the series, but the key story is pretty easily visible: growth in labour productivity has been slowing, mostly recently to nothing.   All else equal, it should be a bit surprising if there are persistent gains in economywide real wages when there is little or no productivity growth.

Of course, the other consideration that affects economywide potential is the terms of trade. If the terms of trade increase then even if there is no growth in real labour productivity, the overall pot is bigger and –  all else equal –  it is likely that over time wages will rise to some extent to reflect that improvement.  It is a mechanical process, or a certain one, and there is a variety of possible channels, but in an economy that experiences considerable terms of trade variability it isn’t a factor that can simply be overlooked.

I’ve attempted to take account of the terms of trade in this chart, which I ran in post last month.

lci wages vs gdp

This chart compares how wages have been rising relative to the increase in nominal GDP per hour worked (the latter measure including both productivity and terms of trade effects).   A rising line –  as New Zealand has experienced (on these data) this century –  suggests that wages have been rising at a faster rate than the earnings potential of the economy.      That difference –  perhaps 13 percentage points over 17 years –  adds up to something quite significant.  On its own –  taken in isolation –  it is neither something necessarily good nor something necessarily bad.   There are distributional changes in any economy over time.  But it is something that could not continue at the same rate indefinitely (this isn’t a statement of ideology or sophisticated economic argumentation,  but simply a matter of basic arithmetic).

Here is another way to look at the issue. The chart shows the OECD’s relative unit labour cost measure of New Zealand’s real exchange rate, in this case back to 1980.

rer to end 18

I’ve broken into two the period since liberalisation in 1984.  In both periods –  although especially the earlier one –  there has been plenty of variability in the real exchange rate.  But the average in the second half of the period has been far higher than in the first half.  Since standard theory tells us to have expected exchange rate overshoots temporarily as part of getting inflation down, I could quite legitimately have focused simply on, say, the 10 years after 1991 and compared them to the more recent period.  My point is not that any single point of comparison is somehow the “right” one, simply that in an economy where productivity growth has lagged behind that in most of the rest of the advanced world, there is something anomalous about a real exchange rate as high as ours have been.  Since this is a unit labour cost measure, it fits nicely with the previous chart –  wages and salaries have been rising faster than the economy’s earnings capacity, and to a greater extent than in many other countries.   Consistent with all that, our firms (as a whole) haven’t been able to successfully increase their penetration of world markets (export shares have been flat or falling).

Not this is in any sense the fault of wage-earners, or indeed of individual firms, all of whom are mostly responding to the incentives the economy has thrown up, and how policy has tilted the playing field.  This decade, some of those things were unavoidable (the earthquakes) but others were pure, deeply misguided, public policy choices.   Rapid population growth generates lots of activity and demand for labour but –  at least in New Zealand’s case –  appears to have done nothing to improve the longer-term earnings capacity of the economy.

In the end, material living standards in any economy will largely reflect productivity growth.  And yet, somewhat weirdly –  but perhaps consistent with the increasing political cone of silence around that failure –  as far as I could see not one of the SST articles yesterday even mentioned the productivity failure as the biggest obstacle to sustainably higher wages and material living standards.    For now, we’ve been in a bit of a fool’s paradise –  wages appear to have been growing faster than economic capacity.  But unless something serious is done to reverse the productivity failure, it is hard to see that real wage inflation in the next decade will be able to be as high as it has been this decade.  The bigger question right now shouldn’t be why wage inflation is so low, but why it is still so high.

(None of this is to rule out the possibility of some problems with the analytical unadjusted LCI data, but (a) SNZ has not pointed users to serious problems, and (b) the picture I’m painting doesn’t seem inconsistent with either the labour share of GDP data or the real exchange rate measures.)


Donations, the PRC etc

There was interesting Herald story a couple of weeks ago suggesting that the National Party may be beginning to feel some heat about their affiliations with, and excuses for, and funds flowing from, the People’s Republic of China (or people with close associations thereto).    The story drew on a speech given by National’s spokesman on electoral law, longserving MP Nick Smith,  to the Nelson Rotary Clubs.  In that speech Nick Smith argued as follows

4.2 Banning Foreign Donations

The second change I want to promote is a ban on foreign donations. This proposal was floated by former Attorney General and SIS Minister Chris Finlayson in his valedictory speech last month with him forcefully arguing that New Zealand’s democracy is ours and should not be open to manipulation by any foreign influence. This risk has been highlighted in recent overseas elections.

The existing electoral law does put limits on foreign donors, but needs strengthening. Only kiwi citizens and residents should be able to donate to political parties or to campaigns that seek to influence an election outcome.

Such a change would need to be done with finesse so as not to discourage political participation by new New Zealanders. The issue is not about ethnicity. It is about New Zealand not allowing its democracy to be inappropriately influenced by overseas interests.

It isn’t that I disagree with Nick Smith on this specific, just that in raising it (and not other issues around electoral donations) he seems to be avoiding –  probably consciously and deliberately – some of the real specific issues that are apparent in New Zealand.

The Herald article summarised the current law this way

Current electoral law prohibits non-citizens or residents from donating more than $1500 to political parties, but these can be avoided by donating through New Zealand-registered corporate entities – such as companies, incorporated societies and trusts – which are allowed to donate regardless of whether they are owned or controlled by New Zealanders.

and in a recent commentary, Simon Chapple, director of Victoria University’s Institute for Governance and Policy Studies observed

Currently in New Zealand foreign donations to a party of up to NZ$1,500 are permissible. Moreover, foreign donations below this amount are not individually or collectively disclosed.

It would be easy for a foreign state or corporate body seeking political influence to channel a large number of donations into the system just under the threshold via numerous proxies. Whether such interference has been happening is unclear, since New Zealanders do not know how much money currently comes in to political parties via foreign actors.

Even if foreign donations are not a problem now, one could rapidly develop. A strong argument can be made that foreign money has no place in democracy, including New Zealand’s.

New Zealand would not be going out on an international limb by banning foreign donations. Foreign donations to political parties are not permissible in the [United Kingdom, Ireland and the United States. They are also banned in Canada but unfortunately a significant loophole exists. Australia is currently in the process of banning foreign donations.

And I’d certainly agree with Simon on that general point: foreign money should have no place in funding election campaigns or political parties.

So there probably is a good case for a blanket prohibition on donations (in cash or in kind) to political parties by non-resident non-citizens.  But that looks mostly like pre-emptively closing a possible source of a problem (although perhaps real in the case of Phil Goff’s last mayoral campaign) –  and thus looking as though you care –  when the real actual issues New Zealand faces in this area would not be addressed at all.   For example, the largest single (acknowledged) donation to the National Party a couple of years ago was from a New Zealand registered company owned and controlled by a PRC billionaire.  That is foreign money in New Zealand politics, and shouldn’t be allowed.  It would be bad enough if it were from donors in countries that generally shared New Zealand values and democratic norms.   It is far worse when the donor is from the PRC – or, if you like, North Korea, Equatorial Guinea or other repressive authoritarian states –  and (according to the media coverage) clearly in the good graces of Xi Jinping.   Personally, I would probably favour banning all corporate donations to political parties –  people are citizens, companies aren’t –  but at very least we should apply the same restrictions to foreign-controlled companies that we apply to non-resident non-citizen individual donations.

But laws can take you only so far, and I’m not convinced they can deal with what appears to be the rather bigger issue around New Zealand political party financing (probably mainly National, although it seems likely that Labour now in government will be seeking to get in on the act).   That requires decency, integrity, and a willingness to make a sacrifice –  in this case, not to take money from people –  not even New Zealand citizens or residents – with close associations with, declared support for, political regimes with values so inimical to, and inconsistent with, those that have underpinned New Zealand democracy, and its fairly free and open society.

It seems to be widely understood that National Party Jian Yang is the party’s biggest single fundraiser.  Jian Yang, as is now widely known, served in PLA overseas intelligence system and was (perhaps is) a CCP member, who eventually acknowledged that he misrepresented his past to get residency and citizenship in New Zealand. In all his years in Parliament he has never once criticised the PRC –  not even over Tiananmen Square (perhaps there is an opportunity for him on the 30th anniversary in a few months time) – he is observed to be very close to the PRC Embassy, and even a former diplomat (now a lobbyist, so hardly someone deliberately trying to stir up trouble) declared that he was always very careful what he said in front of Jian Yang.    It is, to put it mildly, hard to be confident that he is primarily serving the interests of New Zealand and New Zealanders.

I’ve noted previously comments made last year by serious senior people at a Chatham House rules event I was invited to

There was clear unease, from people in a good position to know, about the role of large donations to political parties from ethnic minority populations –  often from cultures without the political tradition here (in theory, if not always observed in practice in recent decades) that donations are not about purchasing influence.  One person observed that we had very much the same issues Australia was grappling with (although our formal laws are tighter than the Australian ones).  Of ethnic Chinese donations in particular, the description “truckloads” was used, with a sense that the situation is almost “inherently unhealthy”.   With membership numbers in political parties dropping, and political campaigning getting no less expensive, this ethnic contribution (and associated influence seeking) issue led several participants to note that they had come round to favouring serious consideration of state funding of political parties.

These will probably (almost) all be donations made by New Zealand citizens or residents, and nothing in what Nick Smith (or Chris Finlayson) was saying would even touch on them.

And thus late last year, Yikun Zhang sprang to brief public prominence, when Jami-Lee Ross revealed the tape-recording of his discussion with Simon Bridges about the $100000 donation(s), and the possible bid by one of Yikun Zhang’s associates for a place on National’s list.   I’m not mostly concerned with the question of whether this donation (or set of donations) was appropriately disclosed –  although in general I think there is a strong case for a lower, and more binding, disclosure threshold, tying all material donations back to identifiable natural persons –  but about the affiliations and identifications of Yikun Zhang and his associates.  We learned at the time the story broke that Yikun Zhang – despite being a long-time New Zealand resident (and citizen) doesn’t speak English.  We learned a lot about his involvement –  at senior levels –  in various United Front bodies, and the strong ties he appears to have with CCP entities back in the PRC.  It is, to put it mildly, hard for a dispassionate observer to be confident that he primarily has at heart the interests of New Zealand and New Zealanders.   Given the nature of the regime he enthusiastically and repeatedly assoicates with, no decent political party should voluntarily have any but the most formal relations with such a person, and certainly shouldn’t be soliciting money from, or through them.  It isn’t what decent people, with any regard for the integrity of our system, do.

In fact, of course, not only do they take his money, but Phil Goff, Jian Yang, and former National MP Eric Roy got together to nominate Yikun Zhang for an honour, something bestowed last year by the current government.  In effect, it appears, for services to one of the more evil –  most evil, judged by the numbers it rules –  regimes on the planet.

And of course we know that not just MPs but party officials seem to fall over themselves to praise that same regime, and run interference whenever there is a suggestion of problems (think of Todd McClay running Beijing propaganda lines about “vocational training camps in Xinjiang).  Peter Goodfellow, the National Party president, seems to work very closely with Jian Yang to pander to the regime, and keep the local donation flow going.  And on the Labour side, Nigel Haworth seemed to be little better.

So by all means, take up the specific suggestion to ban completely foreign donations.  It would be a small improvement on the current situation, but it would not even begin to tackle the deep corruption of the our political system around the PRC regime.  People who were long-serving senior ministers – Nick Smith and Chris Finlayson –  know that very well, even if they are genuinely well-meaning on their specific proposal.

But attempting to fool the public otherwise seems to be a bit of new theme.  That Herald story where I first saw reference to Nick Smith’s speech included this gem

In a related move, Parliament’s justice select committee have issued a rare invitation to the country’s intelligence agencies to give a – likely closed-doors and secret – briefing to MPs about “foreign interference” in local elections.

Nick Smith, a member of the committee and his party’s spokesperson for electoral law reform, confirmed the committee as a whole late last year sent a letter to the New Zealand Security and Intelligence Service (NZSIS) and Government Communications and Security Bureau (GCSB) inviting them to give evidence.

Smith yesterday said he hoped the NZSIS and GCSB would be able to provide insight on the local risks posed by issues such as the hacking the public officials’ communications, foreign donations, and anonymous and politicised social media campaigns.

“There is the issue of funding, and whether foreign governments are either directly, or indirectly through shelf companies, are using funds to inappropriately influence outcomes,” he said.

Smith said the invitation to the NZSIS and GCSB offered evidence to be given in secret if required. He conceded this would be an unusual move for usually-open committee meetings, but was justified: “I think this is a really important issue,” he said.

So a committee chaired by Raymond Huo, he of various United Front bodies, he who chose a slogan of Xi Jinping’s for Labour Chinese-language compaign in 2017, with a senior National MP promoting only the narrowest reform (while providing cover for Jian Yang) will invite the intelligence agencies to provide advice on foreign influence issues, but in secret.   Perhaps –  but only perhaps, because the fact of this hearing might be used to simply play distraction – it is marginally better than nothing, but we don’t need intelligence agencies to tell us there is an issue around the PRC. Both main parties know what they are doing –  who they associate with, who they take money from, who they honour, who they seek closer relations with, and who they refuse ever to criticise, no matter how egregious the regime’s abuses.  All the minor parties keep quiet and go along too.

There was column this week on Newsroom by political scientist Bryce Edwards argues that it is “urgent” that we start having a proper debate in New Zealand about the PRC and the relationship with New Zealand.   I don’t really disagree with him, although he seems to want an “elite” debate, and seems scared by the idea that the public might have a (strong) view (an “overly simplistic one” apparently, like ideas of good and evil perhaps?).

Edwards writes

Obviously, we can’t rely on the politicians to lead that [debate] – they’re too compromised, and they’re just too inclined to suppress the discussion. Instead it has to be other parts of the public sphere – especially the media and other public figures – that needs to step up to examine and discuss the issues.

But it seems like wishful thinking.  Sure there is the occasional voice from the margins –  whether Edwards or Anne-Marie Brady – but there doesn’t seem any sign that anyone in “elite New Zealand”, anyone who commands serious respect, is about to break ranks from the “keep quiet, keep the deals and donations flowing” sickening consensus of the last few decades.  Not former leading politicians, not church leaders, not leading business figures, no one.  Even if a few people mutter quietly –  even Fran O’Sullivan had some recent encouraging comments about donations – no one seriously breaks ranks.   The taxpayer even funds bodies that condemn taking action on Huawei.  So who does Edwards seriously think might lead such a debate?

As he says, all politicians have all sold their souls.  I was exchanging notes earlier this week with someone about Jian Yang.  It is easy to blame John Key and Peter Goodfellow for Jian Yang –  they either knew his background or should have, and didn’t really care (or worse) either way.  But the story of Jian Yang has been public for almost 18 months now and no one in politics has disowned him, called for his resignation, called for the National Party to remove him from their caucus.  Not Jacinda Ardern or Andrew Little, certainly not Bill English or Simon Bridges, not James Shaw or Marama Davidson, not David Seymour, not even (despite occasional timorous hints) Winston Peters.  Not even Jami-Lee Ross, who was at the centre of the whole donations business.  Not a single backbencher, of any party, was willing to break ranks and declare the situation unacceptable.  Fixed with knowledge, by their silence they now share responsibility.

It is little different on any of the other aspects of the PRC relationships:

  • the effective PRC control of the local Chinese language media,
  • the refusal to say a word about the Xinjiang abuses (or Falun Gong or Christian churches),
  • the refusal to say anything in support of Canada over the abduction of two of its nationals.

Probably most of these so-called leaders like to think they are somehow serving New Zealand interests.  People fool themselves that way, sometimes without necessarily fully realisng what they are doing.  They aren’t.

So, much as Bryce Edwards might deplore the prospect of an “overly-simplistic” serious public debate, or swelling tide of discontent, I’d cheer on the fact that it was happening at all.  Corrupted systems are rarely, if ever, upended and reformed without a strong strand of –  almost unreasonable –  public outrage.  It hasn’t happened here yet.  I’d like to say it was only a matter of time, but I’m a pessimist.    What would turn things around now after all these years in which our “elites” have degraded our political system (to complement their failures on other fronts, notably productivity)?  Labour and National are, after all, two sides of same coin on such issues, and together they seem to have a stronger hold on the political system (vote share combined) than we’ve seen for some decades.   We don’t have politicians of decency and integrity, and the public show little sign of (effectively) demanding something different.  The PRC Embassy must be pleased.


UPDATe (4/2):   There is a new column by Simon Chapple and a co-author on reviewing the rules around political donations.  I’m pretty sympathetic to the sorts of changes they propose, although as I argue above the PRC-influence issues around donations or more about atttitudes and integrity –  knowing what is right and wrong and eschewing the latter –  than something formal external (eg statutory) rules can deal with.


Highly productive countries tend to do more social spending

Earlier in the week I saw somewhere some charts drawn from the OECD’s Social Expenditure database, so I went to have a look.  In this database, and an associated report, the OECD attempts to gather reasonably consistent cross-country estimates of (what they describe as) social expenditure.  In this case, the numbers exclude spending on education (other than early childhood spending).

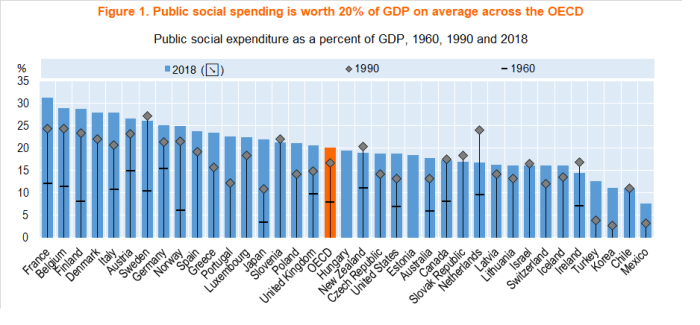
This is the first chart,

socex1

This is direct government spending on such things (health, unemployment and disability benefits, active labour market policies, age pensions and the like).   There probably isn’t much very surprising in the 2018 ranking themselves, although a few things caught my eye:

  • in among the European countries with above-median spending Japan now appears.  Not that long ago Japan had relatively low rates of government spending (share of GDP) but now it is higher than all the English-speaking countries,
  • among those English-speaking countries the Irish numbers are very misleadingly low because of the way features of the corporate tax regime have led measured GDP in Ireland to far outstrip the “true” level of economic activity occurring in Ireland, let alone the income accruing to Irish residents.
  • New Zealand was very close to being the median country in 2018.
  • and, whether or not one approves of such high levels of social spending (and I’m pretty uneasy) it should not be overlooked that among the nine largest spenders (share of GDP), seven are in the top-tier OECD group for average labour productivity (exceptions being Finland and Italy).       I’m not offering any thoughts about causation (and other very high productivity countries – US, Ireland, and the Netherlands –  below the median), but it remains a data point one has to take seriously.

And, of course, the other thing that is striking is how much social spending as a share of GDP has increased.  Perhaps 20 per cent of OECD countries have such spending a bit lower or much the same as in 1990 (New Zealand is one of them –  in 1990 the NZS eligibility age was still 60 and the unemployment rate was rising rapidly in the midst of our disinflation and restructuring), but in most countries there has been an increase even since 1990.   For the countries for which 1960 data were available, the increases have been very large in every single country –  although Japan (still pretty poor in 1960) stands out.

Interesting as these charts of direct public outlays are, they can be only part of the picture.  If the government compels you to save, or compels you to buy medical insurance, or offers tax treatments that incentivise such private spending, the differences between public and private spending can quickly get rather blurry.  Switzerland, for example, has a low share of public social spending but requires everyone to take out medical insurance.  That might, or might not, be a better system, but it means that low-ish direct public spending numbers don’t always tell a simple small-government (or self-reliant) story.   This isn’t a big issue for New Zealand, but here is the OECD’s attempt to reflect some of these different institutional arrangements and produce some bottom line estimates of net social expenditures (apologies that it is a little hard to read –  you can click here for a more legible version).  The orange dots are the ones to focus on.

socexp3

On this measure, the Netherlands and the US move a long way to the left (on the chart), only just behind France.  Switzerland (and Australia) also move a long way to the left.  Of the English-speaking countries, only Ireland now ranks below New Zealand, and that is just because of the tax-system distortion to the GDP numbers (done as a share of net national income, Ireland would spend more on social expenditure than New Zealand).

There are all sorts of quibbles possible about these numbers, including how safe it is to simply add them up (to what extent are the components really apples and oranges?), but it is probably salutary to note that there is now a stronger alignment between income/productivity levels and net social expenditure as a share of GDP than was evident in the first chart.  Countries towards the right of the chart are (almost entirely) the poorer and less productive OECD countries, and countries to the left of the chart tend to be the richer/more productive OECD countries (the outliers being Greece and Portugal).    Whether or not one approves of high rates of social spending, it is at least consistent with the story that much higher productivity gives countries, and individuals, options (practical and political) that poorer and less productive countries don’t have.   That might be something for our political officeholders –  increasingly indifferent to New Zealand’s productivity failure –  to reflect on.

And don’t think you can put the cart before the horse – in general, raising social expenditure won’t do anything much to raise (and may even lower) medium-term average economywide productivity.

Bridges and the State of the Nation

I mostly went looking for the text of Simon Bridges’ “state of the nation” speech yesterday to see if there were any signs, at all, that the Leader of the Opposition was going to confront New Zealand’s appalling productivity growth performance.   He had, after all, been Minister of Economic Development only 18 months ago.  There weren’t.

I’ll come back to economic performance and economic policy later, but the rest of the speech had some interesting snippets.

There was a long section on law and order.  There was plenty of rhetoric but one line in particular caught my eye

I am determined that under the next National Government, New Zealand will become the safest place to live in the world.

Wow, I thought, that sounds like a bold promise.  I don’t carry crime data around in my head, so I went looking.   Reporting and collection differences muddy cross-country comparisons of the incidence of crime, and for a full comparison you’d want to look at the full gamut of violent crime, theft and so on.   But the most comparable data across countries is that for the homicide rate.   Here are the homicide rates (per 100000 people) for advanced countries, using UN compilations of data.

homicides

Dreadful as any intentional homicide is, New Zealand doesn’t rank too badly, just a bit better than the median of this group of countries.  But Simon Bridges says that under the next National government, New Zealand will be the safest country in the world.   Say they come to office next year, and are in office for nine years.  That means he thinks that within ten years, they can take steps that will lower New Zealand’s intentional homicide rate by just over two-thirds, to match the record in places like Singapore, Japan and Luxembourg.

I ran this chart in a post late last year, using NZ Police data.

murders

Cutting our murder rate by more than two-thirds would involve getting, and keeping, it, down to the very lowest individual years managed in the last 100 years or so.   It would be laudable goal…….at least if Mr Bridges had any serious and plausible ideas about how to do it.  And the sort of change that really would support, over time, a much lower prison population.   Fifteen murders a year would still be fifteen too many, but even that seems like a tall order, even with an ageing population.  Mr Bridges promises that National will “continue to put forward the ideas” between now and the election to make his “safest place to live in the world” vision a reality.  Count me a bit sceptical, but I’ll watch with interest to see if there is some substance there.

The headline from the Bridges speech was around the promise to index the income thresholds in the tax system.  It would be a welcome, but well overdue, reform if someone finally does it.  But I wondered about some of the details.  This is how Bridges explained what they are proposing.

We will amend the Income Tax Act to make sure income taxes are adjusted every three years in line with the cost of living.

Within a year after every election, Treasury will advise the Government on how much the tax thresholds should be adjusted to account for inflation.

That means income tax thresholds will increase every three years to stay in line with the cost of living.

The first change will be in 2021 and relate to the tax years of 2018, 2019 and 2020.

We will include a veto clause so the Government of the day can withhold the threshold changes in the rare circumstances that there is good reason to do so.

But it will have to explain that decision to New Zealanders.

But why not

(a) adjust the thresholds every year, and

(b) adjust them automatically, with the formula written into the Income Tax Act?

After all, we manage to adjust (for example) NZ Superannuation rates automatically each year.

One of the arguments for indexing the thresholds is to reduce the ability of politicians to use occasional adjustments to present themselves as giving a tax cut.  The Bridges model –  adjustments only every three years, and only on the basis of the Minister of Finance responding to a Treasury recommendation – still seems to keep too much of that potential intact.  Adjusting for inflation will be in ministerial gift, not simply an automatic calculation routinely notified to taxpayers (according to legislative formula) by the Commissioner of Inland Revenue.

I’m also uneasy about this idea that the Minister could reject a specific  indexation recommendation.  First, if the adjustment were being done annually, the amounts involved are so small there could be no compelling reason not to proceed (with triennial adjustments the amounts get chunkier). And, second, we don’t apply this approach to (say) New Zealand Superannuation payments.  What the statutory formula says goes.

If a government thinks there is a persuasive case to raise tax rates –  and from time to time that may be necessary or appropriate –  they should be willing to come to Parliament and make the case in an open and transparent way.  That is, for example, what they have to do if they want to lower (real) NZS payments.    Inflation shouldn’t be able to be used to be used as a silent cover, enabling governments to grab more (real) revenue.

And then there was the economy.  Simon Bridges devoted a lot of space to it in his speech but there was very little serious content.  What it all boiled down to was:

(a) when we were in government our economy was a rockstar (he doesn’t use the word, just ‘one of the best performing in the developed world’)

(b) Labour is raising taxes

(c) Labour is doing wasteful spending (fee-free tertiary education and the the Provincial Growth Fund), and

(d) National would reverse the Auckland fuel levy, and any capital gains taxes, and not increase other taxes in a first term.

(It was notable that despite the talk of wasteful spending –  with which I agree with him on the specifics –  there were no promises to unwind those measures.)

And that’s it.  There was no suggestion of an economic reform strategy –  not even ideas to come –  or even a need for one.  Things would, it appears, be fine if only we had lower (Auckland) petrol taxes and no capital gains taxes.

So, as an aide memoire for Mr Bridges and his economic team, lets remind ourselves of some key New Zealand data.  I ran this table a couple of weeks ago

GDP per hour worked
USD, constant prices, 2010 PPPs
1970 1990 2017
New Zealand 21.4 28.6 37.2
Netherlands 27.4 47.5 62.3
Belgium 25.0 46.7 64.6
France 21.7 43.3 59.5
Denmark 25.1 44.8 64.1
Germany 22.3 40.7 60.4
United States 31.1 42.1 63.3
Median of six 25.1 44.1 62.8
NZ as per cent of median 85.4 64.9 59.2
Source: OECD

When Mr Bridges’ parents were young, New Zealand was still among the very richest and most productive countries on earth.    His children are born into a country where average productivity levels are barely 60 per cent of those in the top tier of the OECD.

And what happened under the government in which he was, by the end, a senior minister.

real GDP phw dec 18

Barely any productivity growth at all in the last five or six years (and allowing for the lags, and the fact that the current government has done little, the most recent year’s data reflects those some policy frameworks and choices).  We dropped further behind Australia over the last decade, and various eastern European countries –  never previously close to us in the last 150 years –  are either snapping at our heels or overtaking us.   Well done them.  Shame on us (and the succession of governments and oppositions).

Successful economies tend to trade a lot with the rest of the world.  Early in their last term, the National Party in government knew this –  reflected in the (slightly wrong-headed) targets for much higher exports as a share of GDP).   Here is the actual and forecast data (for exports –  the import chart isn’t that different) from the most recent Treasury HYEFU.

exports hyefu 18

Foreign trade as a share of GDP has been shrinking this century – under both National and Labour governments –  and nothing Treasury can see suggests that underperformance is about to be reversed.

But in two pages of speech text about the economy there was not a mention –  not even a hint – of any of this.  Of course, none of this is as immediately topical, or offering political mileage, as a possible capital gains tax.  But a serious leader might at least be able to point to the need to do so much better on the economic performance –  material standard of living – front.

It is only about 19 months until the next election.  Sadly, there is no sign from this speech that a future National goverment would be any more serious about reversing our relative economic decline than their predecessors –  of whatever stripe –  for the last 25 years.  Worse still, they seem to have given up believing there even is an issue.

Marijuana and monetary policy

You might not think the two have much in common –  and the silliest, most damaging, monetary policy decisions (think of the MCI) were all our own reasoned doing.  But one of New Zealand’s most stimulating left-wing writers, Daryl McLauchlan thinks that monetary policy offers a model for how decisions about marijuana should be made.

When I saw his article the other day, under the heading “Why a public vote is the wrong way to determine drug policy”,  I assumed it was going to be something about the (de)merits of referenda, reminding readers that we are primarily a representative parliamentary democracy, not one where most decisions are made by plebiscite.  There are some merits to that particular argument –  and some counter-arguments.  But that turned out not be McLauchlan’s argument at all.

Instead, it was a bid to get not just the public out of any decisionmaking around drugs, but MPs as well.   McLauchlan doesn’t want elected people, or those who elect them, making the decisions, but “experts”.

Advanced liberal societies often solve problems of this class, not by politicising them further but by removing them from the political system and building independent, technocratic institutions. Elected MPs used to make decisions about what the official cash rate should be and which pharmaceutical drugs should be funded in the public health system, and they were so obviously terrible at this they devolved that power to the Reserve Bank and Pharmac.   I think we need to do that with drugs.

I’m rather sceptical of the cult of the expert, at least as any sort of decisionmaker.  There are plenty of decisions –  personal and societal –  where we benefit from expert technical advice, whether it is on treatment options for sickness or injury, house renovations, or how best to conduct a war.  But advice and decisions are two quite different things: we don’t, for example, want our generals deciding which wars to fight.   I wrote a post on these general issues –  arguing that experts should be harnessed for their advice, not allowed to set policy courses –  a couple of years ago.

I don’t know a great deal about Pharmac and pharmaceutical drugs –  although I do note that the ultimate decision (how much taxpayers’ money to spend on such drugs) is very much one for MPs and ministers (those we elect, and those we can toss out again).  But I do know quite a bit about monetary policy and decisionmaking frameworks for it.  And we have the added bonus of a recent book, by a former Deputy Governor of the Bank of England, reflecting on appropriate decisionmaking structures in a democratic society, working outwards from his experiences with monetary policy and banking regulation to offer a more generic framework for assessing whether or not decisions should be handed over to independent agencies.  I wrote various posts about it last year, and reviewed the book for the international central banking publication Central Banking.

Tucker sets a list of “delegation criteria” as follows:

A public policy regime should be entrusted to an independent agency insulated from day-to-day politics of both elected branches of government only after wide public debate and only if

  1. The goal can be specified.
  2. Society’s preferences are reasonably stable and concern a major social cost.
  3. There is a problem of credibly committing to a settled policy regime.
  4. The policy instruments are confidently expected to work and there exists a relevant community of expertise outside the independent agency.
  5. The independent agency will not have to make big choices on distributional trade-offs or society’s values or that materially shift the distribution of political power.
  6. The legislature has the capacity, through its committee system, properly to overseee each independent agency’s stewardship and, separately, whether the regime is working adequately.
  7. The society is capable of bestowing the esteem or prestige that can help bind the independent agency’s policy makers to the mast of the regime’s goal.

One can mount a reasonable argument that routine monetary policy decisions meet this standard.  After all, the overarching goal of monetary policy is set by Parliament, and the specific goals (under the legislation passed late last year) are directly set by the Minister of Finance.  And that legislation is backed up by a fairly widely-accepted literature that there are no long-term adverse trade-offs between inflation and output.   The Reserve Bank still has some important discretionary choices –  those short-term trade-offs can matter – but they aren’t choices about what sort of society we want to be, or who –  which sectors/classes –  will benefit at the expense of others.

Even then, the case for an operationally independent Reserve Bank conducting monetary policy is less strong than it once seemed –  those short-term tradeoffs are more important than the designers of the 1989 Act (which bestowed operational independence) really appreciated, and whereas the long-running argument was that inflation couldn’t be kept low enough without independence, we’ve now had a decade when central bankers haven’t delivered inflation as high as society (represented by its elected politicians) asked them to.  Throw in serious doubts about the effectiveness of parliamentary monitoring and scrutiny, and it is hardly an open and shut case any longer.

I’m not arguing to remove operational independence from the Reserve Bank –  although our system in particular still leaves far too much power in the hands of a single unelected official, who isn’t even appointed by people who were elected.  But if day-to-day monetary policy decisions possibly pass the Tucker test, I can’t see how decisions about the legal status of marijuana (or other drugs) could possibly do so.

After all, to set up such a regime –  in which some independent board (presumably appointed by ministers) would make decisions around which drugs should be legalised, for whom, and under what terms and conditions –  authorising legislation would need to be passed by Parliament.  And that legislation would –  under decent principles of legal drafting and institutional design –  need to outline criteria that the independent agency would have to use to make their decisions.   Of course, those principles could be waffly, non-specific, with no clear sense of which tradeoffs matter or which considerations should get the greatest weight.  Some might perhaps even be mutually inconsistent.

But that is no decent basis for delegating power in a democratic society.   And to get to a serious list of goals and constraints, one would have to go through much the same sort of contentious political process involved in either legislating directly or using a referendum to make decisions about legalising (or not) marijuana.   A goal might be able to be specified –  although I doubt it –  but there is no way that, at this point in society’s evolution, social preferences around these issues could reasonably be described as stable.  We can’t even agree on what the relevant criteria, or relevant sets of expertise, might be.  There are libertarians at one hand, people opposed to allowing any intoxicating substances at the other, and all manner of intermediate positions, shaped by all sorts of different considerations (be it about health, crime, freedom, responsibility, nature of society etc).   That is the stuff of politics.  Competing visions, competing philosophies, competing values, competing intepretations of evidence (or even of what evidence is even relevant).   It is what politics is about, and only political processes have the legitimacy to make such decisions (messy as they often will be).

And even if legislation were able to be passed, handing these big decisions over to unelected unaccountable people sitting on a committee, what is gained?   There is no stable agreed body of expertise relevant to making these decisions –  some will emphasis criminal aspects, some health and mental health aspects, some political philosophy, and some…..  By contrast, given a specific inflation target there is a reasonably specific set of expertise relevant to monetary policy decisions. And boards and committees don’t just appear out of thin air: the members are appointed, by elected politicians.  And so, most likely, you policy set depending on the preferences of the politicians who happen to be doing the appointment at the time, and yet without any direct accountability.  Or appointees purusing their own interests, ideologies or preferences – again with no direct accountability.

And, as I’ve mentioned previously around monetary policy, the willingness and/or ability of our parliamentary select committees to provide serious scrutiny and accountability for indepedent agencies is…..to put it politely…..limited at best.   Limited time and limited resources matter, but so do does careerism –  making life awkward in a select committee might be just what the public interest demands, but it isn’t a reliable path to the next promotion into the ministry.

I’m not wedded to referenda in preference to Parliament itself making final decisions (although in general I quite like the model in which referenda are used to give a final yes or no to specific legislation, so that we know exactly what we are –  and aren’t – voting on) but I can’t see how appropriate policy around drugs is, by almost any test, something that should be decided by people we haven’t elected –  whether judges (the unelected committees that have too much policy say in the US in particular) or statutory boards and committees.  Why preference the preferences and biases of those people over our own, especially as we have ample opportunity to hear –  and follow or discount –  their advice anyway?

I ended my previous post, responding to Sebastian Mallaby’s call for more powers to be handed to “experts”, this way

Like most cults, the “cult of the expert” is more dangerous than Mallaby – or most of the expert class – acknowledges.[ partly because “experts” have a track record of badly misjudging all sort of key issues] And hotly contested political debate, messy as it often, wrong directions that it sometimes takes, are how we make the hard choices, the trade-offs, amid the inevitable uncertainty. Abandoning that model is akin to gutting our democracy of much of its substance. So I still want an expert operating on my child, but I want parliaments making laws and setting taxes (not officials) and parliaments taking us to war (not generals).

And I want MPs –  who we can toss out –  or the voters making to key decisions around whether or not to liberalise drugs.  As slowly as is necessarily to thrash through all the details and alternative perspectives relevant to such decisions.

The road to ruin

Venezuela has, of course, been much in the news in the last few days.   Fascinating as the politics and geopolitics seems, there is also an economic story – about one of the greatest economic catastrophes of modern times, perhaps of almost any time.  And all the more sad for being entirely manmade.

Go back 100 years and Venezuela didn’t stand out from the countries around it.  Angus Maddison’s collection of historical GDP estimates suggests that in 1913 real GDP per capita in Venezuela was just a bit higher than that in Brazil and just a bit lower than that in Colombia.   The southern cone countries of Latin America –  Chile, Uruguay, and Argentina-  were much more prosperous.

The presence of oil in Venezuela had been known for centuries.  According to one paper I found

The presence of oil was known in Venezuela even before the Discovery of the Americas in 1492; back then, Indians were aware of the existence of hydrocarbons that appear on the surface of their lands. They used them for medicinal and illumination purposes. Also, they collected oil from small creeks near seepages by impregnating blankets and then wringing them out. They also found asphalt, and they used it for caulking their canoes and impregnating the sails of their boats.

In 1499 Spanish conquerors were impressed with the natural occurrences of hydrocarbons in Venezuela. They learned from Indians to use them for medicinal purposes. They also used it for caulking their ships, illumination and lubricating their weapons.

But the modern history of the Venezuelan oil industry appears to date to the granting of a concession in 1913 to Shell, and after 1919 oil exports became a major element in the economy.     And here is a picture, using Maddison’s data showing GDP per capita for the period 1900 to 1960 for Venezuela and for New Zealand, the United States, and Uruguay (as a representative Latin American country, that happens to fascinate me) and Australia (another resource-rich country).

venezuela 1

You can see how relatively poor Venezuela was early on, and then the really rapid growth in the 1920s –  catching Uruguay – and in the 1940s.    By the end of World War Two, on this measure real GDP per capita in Venezuela was matching that in Australia and New Zealand.  Another decade on and it was heading towards matching the United States.  It was –  according to a fascinating article in Foreign Affairs – about the time democracy and economic liberalisation came to Venezuela (so the authors claim, a very rare example of a resoure-rich autocracy, in which the state owns the resources, making a transition to democracy).

The period from the early 1950s onwards wasn’t particularly good for New Zealand.  None of the traditional advanced countries has done worse than us over that full period.  But consider Venezuela.

venezuela 2

This chart is from the Conference Board’s Total Economy Database, which only goes back to 1950, for the same group of countries.  The earlier chart was expressed in 1990 prices (and relative prices), while this chart uses 2017 international dollars.  Levels comparisons at any point in time are affected by which set of prices is used to convert data from national currency measures.   The period around 1957 still shows up as being Venezuela’s best relative performance, but on this set of relative prices Venezuela then was even more prosperous than the United States.  The key point is that in the late 1950s, Venezuela was right up there, in or around the very top tier of countries on a GDP per capita basis.

But whereas since 1957 even New Zealand’s real GDP per capita has more than doubled (and Australia and the US have done better again), in Venezuela there were only a couple of years when GDP per capita even matched 1957 levels.  At the most recent peaks a decade or so ago, the average Venezuelan was barely richer than their parents/grandparents had been 50 years earlier.   And all that was before things began to fall apart almost completely over the last decade.  No one can have much confidence in the most recent estimates, but if today’s Venezuela isn’t Somalia, it is no Uruguay either.

If one knew nothing more someone might suggest that perhaps Venezuela had had limited natural resources that had now been depleted and its former prosperity was never sustainable.   In fact, Venezuela today has more proven oil reserves than Saudi Arabia and substantial natural gas reserves as well.   This is a manmade catastrophe.   The optimistic take, of course, would be that when the manmade destruction ends, Venezuela can have a bright economic future ahead of it.  Perhaps –  and no doubt the decline of the last decade could be relatively easily reversed – but the allure of those state-controlled oil and gas resources will still be there, and the risks and temptations that took Venezuela down the self-destructive path of the last 50 years.

On a final note, here is the chart showing population growth in each of the five countries.

venezuela 3

From 1950 to about 1990, Australia’s population roughly doubled, but Venezuela’s population quadrupled.    Rapid population growth certainly isn’t a major element in the story of Venezuela’s relative economic decline, but when your economy rests almost wholly on fixed natural resources, exceeedingly rapid population growth tends to constrain the rate of growth in income per head (in ways not paralleled in economies –  such as most of western Europe –  little reliant on natural resources).   Things get rapidly worse when the population keeps on growing fairly rapidly, even as the production and sale of the natural resource goes sideways or backwards.   Despite all those reserves, Venezuela produces less oil now than it did in 1980, despite supporting more than twice as many people (those who haven’t fled across the borders to other Latin American countries).