The recent quarterly national accounts data prompted me to update a couple of charts that I used to run here regularly, one of which I hadn’t bothered updating since the start of Covid.
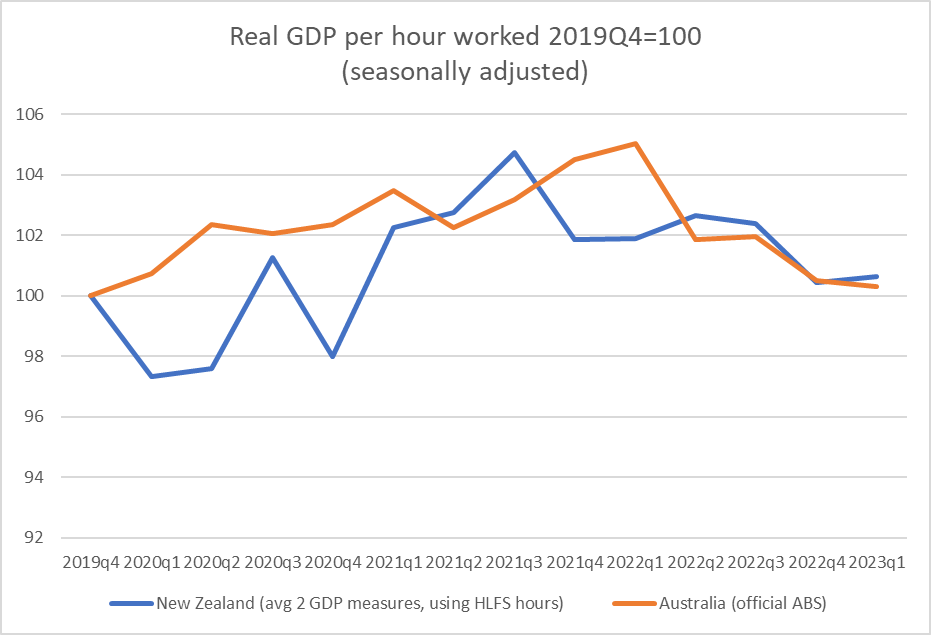
The first is for labour productivity. In New Zealand, we don’t have an official series (level or index) of economywide labour productivity (real GDP per hour worked) but it is easy enough to construct one (or several) using the two quarterly measures of real GDP (production and expenditure) and one or both of the HLFS hours worked and QES hours paid data. I used to simply turn all the series into indexes and divide the average of the two GDP series by the average of the two hours series.
Covid messed up those estimates. For example, under the wage subsidy scheme a lot of people were being paid (as a matter of policy) for hours they were forbidden to, or were otherwise unable to, work. And on a more enduring basis, we now have a higher baseline level of sickness, which comes and goes with waves of Covid, and so for the time being I’m just using the HLFS measure of hours (since it is measuring the hours people tell SNZ they were actually working for). It also then allows for a more-direct comparison with the official ABS real GDP per hour worked series for Australia.
With series for both countries indexed to 100 in 2019Q4, the last pre-Covid quarter, this is how the productivity indicators have done over the last few years.
There is quite a lot of “noise” in the New Zealand numbers, and I still have very little confidence in the any of the numbers for lockdown quarters themselves (in early 2020 and late 2021), but taken over the entire 13 quarters (from before Covid was on any horizons in either country, to now where there are few/no regulatory disruptions) both countries end up with – on current estimates – next to no productivity growh at all over the full Covid period.
I don’t find that particularly surprising (although who knows what the numbers will eventually be revised to) – Covid was a really big disruption and costly dislocation in all sorts of ways – and was much more puzzled by the earlier indications that a reasonable level of productivity growth had been maintained (even allowing for compositional points – eg low productivity motel cleaners and cafe waiters were some of the disproportionately most likely to have lost their jobs in 2020). Perhaps too there is now some cyclical and compositional effects at work: both labour markets have recently been substantially overheated and almost anyone who wanted a job could get one, probably averaged labour productivity a bit downwards.
But they are hardly numbers to be complacent about. For what it is worth, UK official numbers on growth in economywide real GDP per hour worked are (a bit) less bad than these Australian and New Zealand numbers, and US non-farm labour productivity (thus not strictly comparable) while weak in recent quarters still looks to be not far from a pre-Covid trend line.
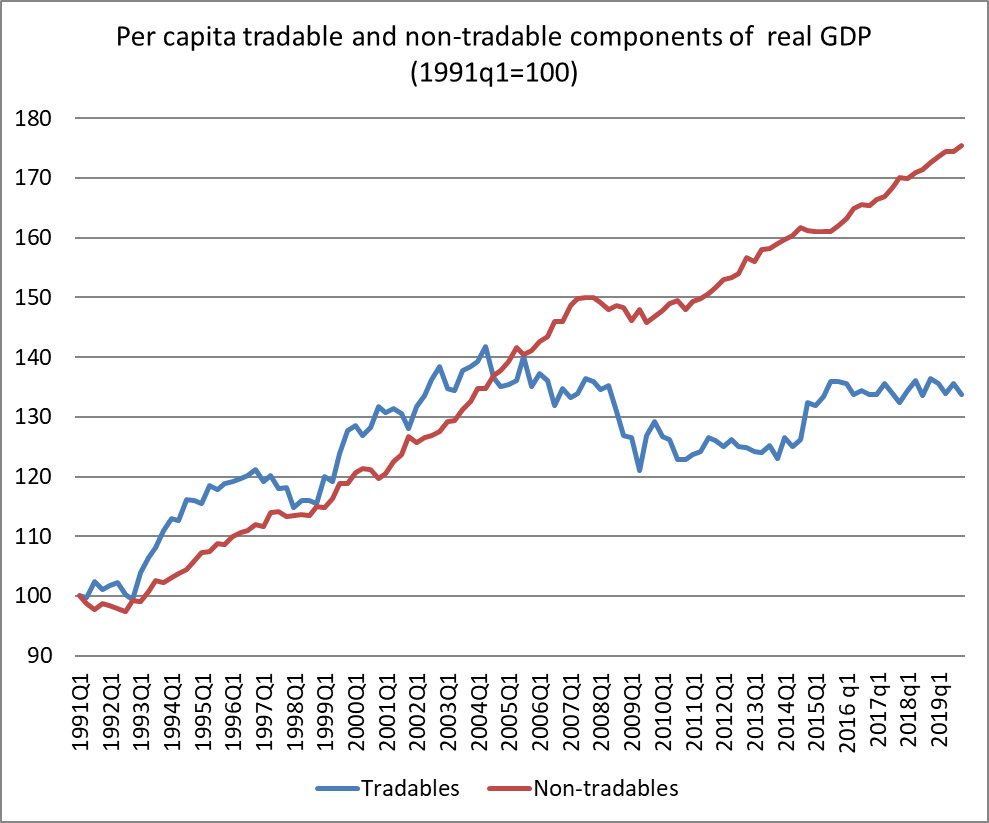
My second chart has, over time, raised more hackles. Almost 20 years ago a visiting IMF mission team were looking at how the (then newly) rising exchange rate was affecting the economy, and one of their people put together a chart crudely illustrating the relative performance of the tradables and non-tradables sectors of the economy. Tradables here was represented by the production GDP components for the primary and manufacturing sectors, to which was added (in a way that makes statisticians wince, but which isn’t without meaning) exports of services from the expenditure GDP accounts. They were, loosely, the bits of the economy either producing for exports or facing direct international competition. The non-tradables component was the rest. I think I later hit on the idea of expressing the series in per capita terms, to cope with longer runs of time.
This is roughly what the chart looked like around the time it was devised.
If anything, the tradables sector had been growing faster than the non-tradables sector in the 1990s and early 00s, which was sort of what the opening-up narratives had led people to expect. But after about 2002, activity in (this proxy for) the tradables sector seemed to be going sideways. All else equal that might not have been too surprising for a cyclical rise in the exchange rate (back then, the New Zealand real exchange rate experienced really big cyclical swings).
This is what the chart looked like the last time I bothered updating it, just prior to Covid
The non-tradables sector had continued to grow quite strongly (in per capita terms), while this proxy for per capita tradables sector output had had its ups and downs but was by the end of 2019 no higher than it had been in 2002. A common narrative on this blog through its first few years was that the economy had become increasingly inward-focused, even though sustainably successful economies tend to be ones with rapidly growing tradables sectors (not, to repeat myself for the umpteenth time, because exports are special, but because there is a big global market out there and successful competitive firms will tend to find global customers).
I stopped looking at the data for several years because when the government says people can’t travel then of course services exports (notably tourism, but also export education) were going to dip quite sharply, and all it was doing was reflecting the priority placed on Covid control, nothing about underlying competitiveness issues.
But now things are returning to normal. We don’t have restrictions on people coming, and nor do most countries, and even China is opening up (for outbound travel) again. So it seemed worth coming back to my indicator chart.
I was quite surprised by what I found.
Non-tradables real per capita output has still been running well above trend, consistent with an overheated economy (high inflation, large current account deficit), as we’d seen on a smaller scale in the mid 00s. But the proxy for the real per capita output of the tradables sector hasn’t yet recovered much at all, and is only about 10 per cent higher than it was 32 years ago.
Something didn’t seem right. After all, there were a lot more tourists around.
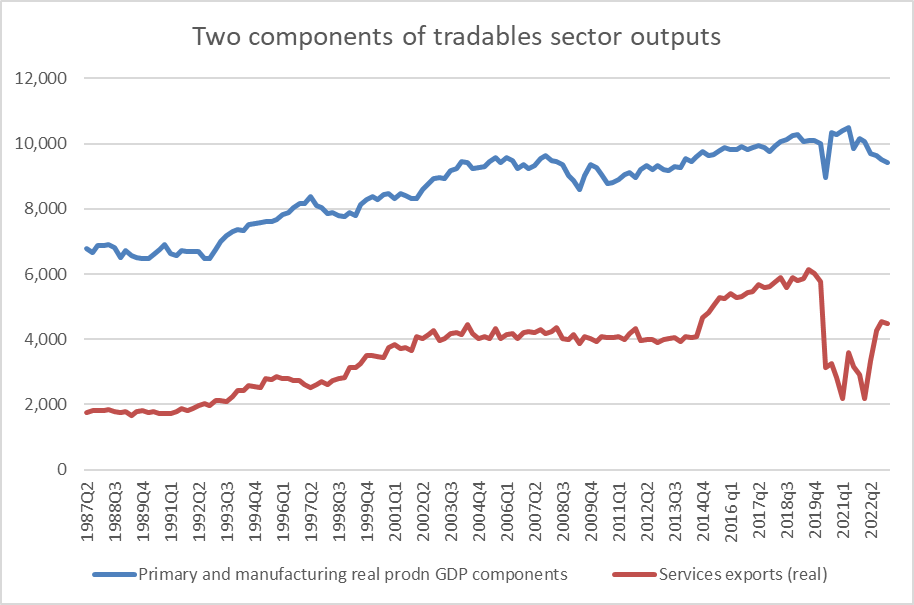
And sure enough the data (seasonally adjusted but not per capita here) show that services exports have recovered a lot as the Covid restrictions were lifted. But notice the blue line, the GDP components of the primary and manufacturing sectors. It has its ups and downs but the level of the latest observation was first reached in 2004Q1 (when the population has only just passed four million).
It is an increasingly inward-focused economy, where policy (such as it is) is only tending to reinforce such developments. It doesn’t have the feel of the foundations for a prosperous and highly productive economy for New Zealanders – this generations, or our children and grandchildren.
But while the big political parties fight over the keys to the Beehive offices and cars, it would be most surprising if one sees any serious or sustained engagement with data like these (or the policy choices that have given them rise) in the election campaign over the next few months.
The China Tightrope is the title of the new book by Newsroom’s foreign affairs reporter Sam Sachdeva. The subtitle is “Navigating New Zealand’s relationship with a world superpower”. In the quite limited New Zealand media coverage of the China issues, Newsroom has been better than most. In conjunction with the Financial Times, in 2017 they helped break the story of then National MP Jian Yang’s highly questionable, hidden from the public (and in important respects from the NZ immigration and citizenship authorities), past, including as a CCP member and teacher at a PLA university run at least in part to train spies. They gave considerable coverage to Anne-Marie Brady’s Magic Weapons paper that was released at about the same time. They even ran a post I’d originally written here on NZ/PRC issues.
There was quite a lot of coverage of these issues for a couple of years after 2017, but then the issue seemed to rather die away, at least as far as the media were concerned. And even as more and more of the true character of the CCP regime in China under Xi Jinping became apparent. The all-consuming nature of Covid probably helped, as did the (apparently) joint decision by Jacinda Ardern and Todd Muller (in perhaps the only worthwhile thing he did in his brief stint as National leader) to jettison MPs Raymond Huo and Jian Yang just prior to the 2020 election. Remove the headline risk and you reduce the frequency of headlines must have been the hope. Professor Brady, a world expert on Chinese influence issues, also appeared to turn away from public engagement (perhaps not entirely surprisingly after some of her experiences) and without prominent credible expert voices there often wasn’t that much for busy journalists to report. Establishment New Zealand had, after all, never really wanted scrutiny or challenge at all; there were too many cosy interests (all no doubt legal) to protect. Hadn’t the previous government set up and funded (and the current government maintained it) the New Zealand China Council largely to influence the public narrative in an emollient direction. There there, nothing to worry your heads about. We the bureaucrats and business people have it all under control, never ever uttering even a concerned word about the nature of the regime or its activities and interests here. And that suited both political parties, with strong fundraising interests.
So when it was reported a few months ago that Sam Sachdeva was writing a book on the issues it piqued my interest. There aren’t, after all, that many serious books on New Zealand current political issues.
Sachdeva appears to have faced considerable challenges in writing his book. There were probably practical issues (how much space the publishers would allow, where to pitch the book to get a reasonable level of sales in a small market, and so on). Then there was the problem that any journalist writing such a book needed to be conscious of his ongoing day job. Push too hard in the book and the access required to do the day job might well be jeopardised.
As it is, access seems to have proved to be quite an issue for Sachdeva in writing the book. We are explicitly told that Jacinda Ardern refused to engage at all (consistent with the Herald’s Matt Nippert’s experience earlier in her PM-ship in which he spent a year or more fruitlessly seeking an interview on PRC issues, Nippert also having pursued some of the Jian Yang story). Sachdeva is hardly some scandal-mongering reckless pseudo-journalist, but the then Prime Minister, and leader of a large political party implicated in a number of these issues, simply refused to engage. That was no doubt convenient for her.
The other person we are told who refused to engage was Professor Brady:
Brady initially indicated a willingness to speak with me for this book, before ultimately declining om the grounds that everything she might say was already in her research, and it would be ‘impossible’ for me to say anything authoritative about the New Zealand-China relationship given my lack of Mandarin-language skills and expertise in the CCP system.
For someone who has talked up the role of universities, and academics, as “critic and conscience” it didn’t seem a very constructive sort of approach. After all, quite a lot has happened since 2017. Then again, there have been indications that whereas in 2017 Brady was very much outside the official tent, and ready to air (what seemed like reasonable) complaints, that in recent years she may have taken on roles, formal or informal, that leave her feeling less free to speak. Her occasional comments on Twitter have tended to be relatively positive about the current government, and it would have been good to have heard some of those angles and arguments elaborated.
We know that Ardern and Brady refused to speak to Sachdeva. He provides a list of the people he did talk to, whose views are attributed. There is also a comment that “Other interviewees whose thoughts are included are not listed, as they agreed to speak on condition of confidentiality”. It isn’t clear quite what sort of people might be included here – if it is mostly people from within the ethnic Chinese community in New Zealand, well and good (there are probably legitimate fears of PRC intimidation and threats), but I recall a suggestion that at least one government (MFAT) official might have been included, which seems less than ideal. Either way, it is hardly as if there are revelations (breathtaking or otherwise) in the book.
What is less clear is the situation of others. Did Sachdeva not ask, or did they refuse to talk. Here, I have in mind:
current senior National Party figures (Luxon, Brownlee, McClay (he of, for example, the infamous “vocational training schools, and none of our business” approach to the Uighur concentration camps). I recall exchanging notes with Sachdeva on Twitter several months ago and if I recall correctly he told me he had had a request in for many many months for an interview with Luxon on foreign affairs issues, to no avail.
Simon Bridges (who – and not Bill English as Sachdeva says – signed the 2017 Belt and Road MOU, the one envisaging a “fusion of civilisations” etc, who did the 2019 trip to China, glowing state-media TV interview and all, organised by Jian Yang, and who did nothing to deal with the Jian Yang situation. Oh, and who was consistently critical of Ardern for not being sufficiently obeisant before China.
Jami-Lee Ross
Nanaia Mahuta, Damien O’Connor (for the foreign policy/trade side of things) and whoever was the Minister of Justice and the Minister for the intelligence services at the time the book was being written
Jian Yang or Raymond Huo
Phil Goff (he of the very large “donation” – auction proceeds for the works of Xi Jinping – from a Beijing source to an earlier mayoral campaign)
Peter Goodfellow
Nigel Haworth
The Green Party’s foreign affairs spokesperson
Ingrid Leary (the Labour backbencher who is now a co-chair of the Inter-Parliamentary Alliance on China, but who seems to keep very very quiet on such issues)
Remarkably, the only current member of Parliament Sachdeva (who was chair of the parliamentary press gallery only a handful of years ago) said he talked to is Simon O’Connor, the rather-marginalised National MP who is from time to time willing to speak up on these issues (also part of IPAC), but is nonetheless constrained by being a fairly junior member and spokesperson in a caucus whose leaders tend to have quite different views.
I was also a bit surprised that he had not talked to Prof Geremie Barmé, an Australian academic expert on PRC issues now resident in New Zealand (who had written an open letter – addressed broadly, but including to the then Prime Minister – urging people to take seriously the arguments and evidence Anne-Marie Brady was advancing). The letter ended thus
Since September 2017, Professor Anne-Marie Brady’s work has attracted overwhelmingly positive global attention. It has also been subjected to vilification by Chinese officialdom. Regardless, her work continues to influence the debate about China’s “sharp power” on the international stage, and it contributes to practical policy discussions in Europe, North America and in Australia. This work remains ever more pressingly relevant to the public life, and the future, of her homeland.
On the other hand, Sachdeva did get interviews with John Key, Tim Groser, and Murray McCully (and the former Executive Director and the current chair of the China Council) of the trade-trumps-all school (and who, to be fair, came to office before Xi Jinping).
And if he talked to the director of the Contemporary China Research Centre (which is apparently hosting a roundtable discussion on Sachdeva’s book in Wellington tomorrow night, which I can’t make), who seems to have become a bit more sceptical, and keen to distance himself from PRC interests, than when I wrote about some of his comments here in 2018, another surprising omission is Tony Browne. Browne is a former NZ ambassador to Beijing who for a considerable time chaired the Victoria University Confucius Institute (PRC funding etc and all, photo of Xi Jinping on its page on the Vic website), chairs the Contemporary China Research Centre (supposedly an independent forum for expertise and debate, but which shares an office with the Confucius Institute), and still appears to serve as a consultant to the PRC government entity that drives the entire Confucius Institute movement internationally. Oh, and he is also the NZ course director for the ANZSOG training programme run each year (but disrupted by Covid) for up and coming mid-level CCP officials (and where they get access to many of Australasia’s great, good, and powerful). I’m something of a Browne sceptic, but he does have a thoughtful case to make for the sort of engagement/involvement I’m critical of.
If I was extending the list of those I was surprised not to see interviewed it would include (a) at least one or two university vice-chancellors (supposedly balancing critic and conscience responsibilities with being big export businesses to China), (b) representatives (present or past) of entities like Fonterra or Zespri or Air New Zealand, or c) perhaps some freer-now-to-speak former senior MFAT officials. Perhaps a little flippantly, the New Zealand Police too, who like cosy relationships with Beijing, and allowed one of their own senior official to accept a role as visiting professor at a Chinese domestic security (aka repression and concentration camps) university. I guess they too have a case to make.
None of this is to suggest that Sachdeva is particularly sympathetic to the gruesome pro-China bonhomie that flows from the lips of John Key. He clearly isn’t. Or that he has not talked to sceptics and critics (Winston Peters and Ron Mark appear in the list of interviewees, and people like former FT Asia editor Jamil Anderlini and Australian researcher and author Alex Joske.
Nor does he fall for all the spin one sometimes hears. He rightly draws attention to the academic paper suggesting that the NZ-China preferential trade agreement probably made little or no difference to NZ GDP per capita (although reports unsceptically claims about China’s alleged role in “saving” or underpinning New Zealand economic performance after 2008, and reports uncritically conventional lines about new trade deals – UK and EU – being likely to make a material difference to New Zealand exporters’ trade with China).
There also isn’t much sense as to how perceptions and policies have been shifting over the years. Some argue that the current government is much better on PRC issues than its predecessor (perhaps just because the external backdrop is changing). Is it really so, and what is the evidence and the counter-arguments? I’m a bit sceptical myself, but Sachdeva should have had the connections and access to offer a persuasive case on issues like that. He didn’t do so.
Overall, I think my frustration with the book is that a) I didn’t learn anything and b) I wasn’t made to think harder/deeper. He didn’t seek (or at least find) sources who could shed light on events and interests (notably, for example, around the National Party, or around autonomous sanctions (where National has put forward legislation that Labour consistently refuses to support), let alone around the threats and pressures within the local Chinese community. And he doesn’t advance a robust and detailed argument for any particular approach to the PRC issues (whether one I’d prefer or some other), developed in ways that force one to think harder about one’s own view. For example, what, if any, place is there for morality in foreign policy? Is realpolitik everything, but even if it is where should that take New Zealand policymakers? Or to what extent should the business interests of particular and sectors shape the policy choices and stances of governments? Coverage of the Pacific issues (notably the Solomons) seemed weak, as did the treatment of Taiwan issues (is it really appropriate that no NZ political leader will ever explicitly acknowledge that China is threatening to invade Taiwan, and that invasion of other countries, notably free and democratic ones, really isn’t acceptable, and is it any more likely those same craven politicians will be any less bad after an invasion, when they willl presumably want their markets back pronto). He is more inclined to report someone’s glib line – eg big donations don’t really matter because migrant Chinese just want their photo with a decisionmaker, which they might struggle to do at home – rather than digging deeper and exploring (evaluating) the nature of the risks.
And so I’m left wondering what contribution the book finally makes: aren’t the sort of people who are likely to buy/read the book already fairly familiar with the issues at the level they are covered here? If others do buy and read, will they be left any better informed or influenced than some inchoate sense that “its awkward” (and that Sachdeva has a bit of hankering for a bit more state funding of political parties).
It is all coming into focus again now:
We have an election coming, and (as he notes) no serious changes have been made to electoral donations laws that allow foreign-controlled NZ resident companies to donate heavily,
We have an election coming, and the leader of the main opposition party has never it appears been willing to face serious questioning about his approach to PRC issues, whether as foreign policy or domestic intimidation and interference,
We still have a member of Parliament who has been described as having close United Front ties, and other political parties appear to continue to choose ethnic Chinese candidates based on their acceptability to the PRC interests,
Several of our universities now appear to be under severe financial pressure and would presumably champ at the bit to have more PRC students, with all the attendant economic leverage that would grant (and unwillingness to stand up as critic and conscience)
We have Prime Minister – amid a busy year, not doing that well in the polls – nevertheless not too busy to go and make obeisance in Beijing. Note that ministers will talk a talk about diversifying trade and reducing exposure to (the somewhat overstated wider coercion risks from) China, but where is the PM leading a big trade mission, talking of introducing new (and newly subsidised) industries to the market. Of course, he will say he will mention human rights etc issues, but (a) does anyone take that seriously, beyond a “Mr General Secretary, you know we have to mention Xinjiang” and his interlocutor nods knowingly, knowing that actions and inactions speak louder than ritual incantations. Hipkins trots off to China while the PRC authorities hold indefinitely on trumped up charges a journalist from our closest ally.
On trade, the issue is not whether private firms trade with partners in China, rather it is whether politicians here are, or are not, willing to adjust their behaviour to protect those specific sector interests, or the beliefs and values of New Zealanders.
The Taiwan threats become more pressing by the year, and yet there is no public debate or political leadership here on the issues/threat/risks,
Systematic media and political coverage of the PRC inroads in the Solomons (most notably but not exclusively) is limited to say the least.
There is even the small matter of whether Chinese language teaching in our state schools should be provided and funded by the New Zealand government and taxpayers or if it should continue to be heavily funded by the totalitarian, repressive, expansionist PRC authorities (through Confucius Institutes) including allowing those same authorities to vet for political/religious/ideological compliance the Mandarin language assistants put in front of kids in our classrooms. This would be an easy one to do the right thing on, but neither the universities (3 of them) that host these outposts of PRC policy, nor the schools, nor the government (nor the Opposition) seem to have any interest. What hope then for a more robust stance in other areas of policy, where vested interests are stronger. Sachdeva never did draw comparisons between New Zealand’s responses in the past to apartheid South Africa, Nazi Germany, or (nuclear testing) France. He should have.
I’ve written previously about the economic coercion issues and so won’t at length here. On specifics, I thought Sachdeva accepted too much at face value past stories of coercion (yes, Norwegian salmon exports to China fell sharply, while those to Vietnam – neighbouring country – rocketed) and didn’t really distinguish the interests of particular firms and sectors (which can be powerful lobbies, especially if they operate in secret) from overall national economic performance, especially for economies with their own monetary policy and a floating exchange rate. Similarly, he was too ready to take at face value lines about differences between Australia (iron ore exports) and New Zealand (milk powder): dairy is another globally traded product, and what isn’t sold in one market will end up being sold elsewhere (perhaps at a different prices). But my point in closing is not so much whether or no my argument is correct, as that in a rare NZ-focused book on the subject the arguments and issues just weren’t teased out and tested in a way that could have made a useful contribution to the (all too often too thin) New Zealand debate on the PRC issues.
The New Zealand Initiative’s Eric Crampton had a good column in Saturday’s Post making the case for land-value rating in Wellington. It was written with Eric’s customary clarity and, on the surface, makes a pretty persuasive case for change. I would normally provide a link but…….despite being a subscriber to the hard copy Post, the new website is anything but welcoming and I don’t feel inclined to send readers their way. But as I’m going to be arguing more with what isn’t in Eric’s column rather than what is, it shouldn’t matter unduly.
For a long time I’ve been more inclined than not to sympathise with the idea of land value rating. But in recent months there has been a group championing change in Wellington (including via an anonymous Twitter account), and since their arguments seemed less than entirely honest it got me thinking a bit harder about whether or not the case for change is really as persuasive as I might previously have been inclined to grant. (And before anyone asks, on the numbers this group used in a Stuff article a month or two back – that I can no longer find – my rates bill wouldn’t have been materially changed by what they were proposing.)
The basic argument for land-value rating is along the lines that, at the margin, it encourages a more economically efficient utilisation of land (a scarce fixed factor which is not going anywhere). The anonymous Twitter account was using as an example a section in the central city currently used as a (single level) carpark. On that site, capital value rates will be lower than land value rates would be, all else equal, and thus at the margin a shift in the rating base might encourage the owner to develop more quickly (or sell the land to someone else who would).
Which sounds fine on paper until one remembers the huge other distortions on land use that Wellington City Council already imposes.
The most obvious, in the rating space, is the egregious business differential, which the left-wing champions of change are very very quiet about indeed. From Eric’s article
If an apartment tower is right next to a commercial office tower [of identical capital value]…..the commercial tower will pay 3.7 times as much in rates
As Eric notes, Auckland and Christchurch also have differentials, but they are materially smaller than the one applied in Wellington (Christchurch is apparently increasing its to 2.2 times). I guess you get away with it in Wellington because of the huge captive industry (central government and all the supporting consultancies and other support services) but if I were interested in reforming the rates system in Wellington, and at all interested in providing a better environment for private sector business investment in the moribund Wellington economy
I’d be looking very hard at slashing (ideally abolishing) that business rate differential. All else equal, that would increase the average rates burden on the typical residential ratepayer………which wouldn’t be popular with the voters, but which might prompt harder questions about the extent of the wasteful spending undertaken by the Council (starting with uneconomic convention centres, moving on to super-expensive Town Hall refurbishments, or tens of millions on repairing (rather than replacing) a 30 year old library building, just as examples). Anyone proposing shifting to land value rating without doing something about the business rate differential isn’t making a serious contribution around economic efficiency at all, and is advocating a policy that could actually worsen overall outcomes.
And all that is before we focus in on the way the Wellington City Council (like many/most councils round the country, but egregiously so given Wellington prices) actively rigs urban land prices, by making it difficult, or often impossible, to develop the abundant amount of land (often, in Wellington’s case in particular, land with rather limited economic alternative uses) that the territorial local authoritiy includes. In the last year, their ideological allies on the Wellington Regional Council have also been at it, trying to entrench restrictions on expanding the physical footprint of urban areas. Those restrictions drive up the price of existing urban land, solely as a result of the artificial scarcity those same local authority politicians and their planner allies championed. There is nothing at all natural or fundamental about the land values the left-wing councillors and their allies want to tax: it is all the fruit of a rigged market of their own creation. So count me cautious of those campaigning for land value rating, when the same people show no willingness at all to free up land use and drive down land prices. In fact, having once made the change, they’d have a vested interest in not lowering land prices, because a reduction in land prices relative to capital values would shift the burden of rates back to those you promised relief to when making the case for change.
If, by contrast, the Wellington City Council (or any other local authority) was to see the light and actually allow land to be used as its owners desire (not just as politicians prefer), the case for land value rating might then be strengthened somewhat since as all private land would again be on a more or less equal footing, and the relationships between land values across space, and between land and typical capital values, would be more fundamentally grounded.
All that said, I might still be wary for a couple of reasons.
First, the same argument the champions of land value rating propound – encouraging development – could also be used to argue for higher rates generally (the heavier the burden on undeveloped or lightly developed land the more the incentive to develop it and earn some income off it). I have no enthusiasm for still-higher rates given the evident low quality of so much of the spending already – and yet the councillors reputedly keen on land value rating are mostly also big government people.
Second, it isn’t obvious that encouraging efficient land use is any natural part of a local authority’s business (let alone that local authorities would consistently seek to do so – the evidence of recent decades being against them, given the arbitrary, ideological preference-based, restrictions they’ve actually imposed). One might mount a central government case for a revenue-focused land tax which, if comprehensive and enduring (unlike past land taxes in NZ) might have some economic efficiency benefits (fewer efficiency costs than other possible revenue streams per dollar of revenue raised), but this is an issue of local governments. From them we might want efficient building consenting, clean and paved streets, functioning street lights (that don’t drop on heads), public libraries perhaps, and not much more, generally keeping themselves out of interfering with the choices of private firms and households as much as possible.
Third, somewhat linked to the second point, I’d like as much as possible of what local bodies do to be funded directly on a user-pays basis, and what can’t reasonably be done user-pays directly should be done using a revenue (rates) structure that bears as close a relationship as possible to those who benefit pay. And there I’m unpersuaded by the argument that land values are a better proxy for those who benefit than capital values (6 townhouses on one section will use more services than one house on the same section).
Fourth, there are localities in New Zealand (and Australia) that already (or still) use land-value rating. None of the advocates for change in Wellington have yet (that I’ve seen) produced careful studies showing the sustained difference the choice of land value rating can make (or has made). I recall doing a speech to the Property Investors Association in Nelson several years ago and the land-value rating issue came up. The people I was talking to told me that the Nelson and Tasman District Councils (both covering bits of the Nelson urban area) each had quite different rating bases: one land-based, one capital-based. If so, it would be really interesting to see a serious paper looking at what difference that choice had made (to, for example, land utilisation issues, house prices etc).
The actual experience of other localities and other models is relevant because what those calling for Wellington to shift to land-value rating as proposing is really quite a big redistribution, and it seems reasonable that the onus should be on those proposing material windfall gains and losses (even if for most the difference might be modest) to demonstrate that they system they propose has genuinely produced materially better results where it has been used (and thus represents a potential Pareto improvement).
In talking this over with my son, at one point I suggested that I’d have been fine with land-value rating had it been introduced in 1840 when modern Wellington was founded. But, on reflection, I’m not even sure I hold to that, and am quite sure that the left-wing of the Wellington City Council wouldn’t have been. After all, Wellington wasn’t some terra nullius but had Maori residents and landowners, many of whom would have had little or no market income from their land. The rational economist might have come along and suggested a land-value rating system to encourage efficient utilisation of scarce land, and to cries of “but we have no cash income” or “but this undermines our deep connection with the land” those rationalists would perhaps have responded “oh, no problem, just sell the land and move somewhere else; downsize, put the proceeds in the bank and sit back and watch the new city flourish”. Or they might have excluded the Maori land, which then would have dramatically undermined their original efficiency case.
But if that was 1840 hypotheticals, what about 2023 reality? Shift to land-value rating in a city where land prices have been rigged (by artificial regulatory scarcity) by the same council, and what happens to the economics of the local bowls or tennis club (properties that may, not incidentally, actually use very few council services). No doubt the council and the Crown would protect their own playing fields (schools, government reserves, and council parks don’t pay rates) but why should we be adopting a revenue model (quite unrelated to use of council services) that would have the effect of driving out private sector green spaces from our cities and towns (unless of course you are a left-winger who doesn’t really like private provisions and intermediate civil associations at all).
And then there are the elderly. There are many (private) reasons why an older person or couple might rationally choose to downsize, shift to a retirement village or whatever (stairs, maintenance burdens, or just freeing up some capital) but there is no public policy interest in seeking to affect or accelerate that process (contrary to some rhetoric you hear at times, about how old people “need” to move out – or be moved out – of big old family houses). But that is exactly the sort of effect land-value rating has – and to some is designed to have. If some elderly couple wants to sell their grossly overpriced Wellington house (mostly section) and move to (much cheaper) Christchurch, that is their affair and potentially a quite rational response to the Council’s artificial land-use scarcity. But a lot of elderly people want to stay in the locality they have lived in for decades, close to the people and institutions they’ve been part of for decades. There is no public policy merit in whacking a tax on their backyard – quite unrelated to any council services they are likely to be using – to encourage them to move on and allow conversion into townhouses (after all, the Council could – and should – simply free up greenfields development in the land-abundant Wellington City. And it is no consolation to be told “oh, never mind that you don’t have the cash – you can give us a charge over your estate and build up a big debt to be settled by your heirs”. There is just no public policy case. The underlying issue – which should be easily affordable readily available housing – could, and should, be dealt with directly.
There is a case, at least on paper, for a modest land-value tax, applied equally to all land, at a national level. That such taxes are not widespread should give pause for thought (when I was involved in the 2025 Taskforce and the issue came up David Caygill reminded us that he’d been the Minister of Finance who’d abolished New Zealand’s land tax which by then had been whittled down to applying only to CBD commercial properties), as should the fact that land is becoming steadily less important as a factor of production. But there is a reasonable debate to be had at a national level, as one strand in a national efficient revenue strategy.
At a Wellington City Council level, it all has the feel of something that appropriates in bastardised form the economic arguments and wants to use them to serve the ideological interests of the same councillors who have no general interest in economic efficiency at all, but are keen on some intensively-developed, relatively poor, pseudo Manhattan on Port Nicholson, not because the fundamental economics and individual personal choices drove such outcomes (if they did, then fine) but simply because this sort of urban leftist really hates New World cities and the sort of well-spread cities that wealth and transport technologies (and modest populations – Wellington City has less than 250000 people) made possible. They really don’t like backyards, sunlight, gardens, or soccer or cricket with the kids down the drive. And, refusing to accommodate private choices (costs appropriately internalised) they now want to transform the rates system to reinforce their personal and ideological preferences.
But if the councillors want to surprise us and (a) remove that huge business differential, and (b) free up land use across the whole city (abundant land and all) then perhaps it might make sense to have a conversation as to whether a shift to land-value rating, or perhaps a 50/50 mix (that might better reflect service use), would on-balance make some sense.
It was the Monday a few days before Christmas 1992 when a colleague wandered into my office and asked if, by any chance, I was interested in a couple of years in Zambia. My colleague had just returned from a few years at the IMF in Washington and had been rung the previous day by a former colleague of his desperately looking for someone who was interested in being resident economic adviser to the Zambian central bank, all at short notice, as the incumbent was due to leave shortly, and the reform programme (and IMF programme) was in trouble, with inflation through the roof. If I recall correctly, they’d had someone lined up, who had a baby, but news of a cholera outbreak had come through a few days previously. The job was going vacant again.
My knowledge of central Africa was sufficiently sketchy that, in those pre-internet days, I had to wander down to Bennetts bookshop on Lambton Quay and buy a Lonely Planet guide to Africa to (a) securely locate Zambia on a map and (b) find anything at all about it. I rang the guy who was just about to finish up (an RBA secondee I knew), and if some of his stories were sobering – consumer good scarcity so real that he told me that afternoon they’d released the staff because some or other essential had finally appeared in shops – the job itself sounded challenging and potentially rewarding, with a new Governor with no background in central banking or macro but with a serious commitment to overhauling and lifting the performance of the institution. Within 24 hours I had a (very remunerative) offer on the table.
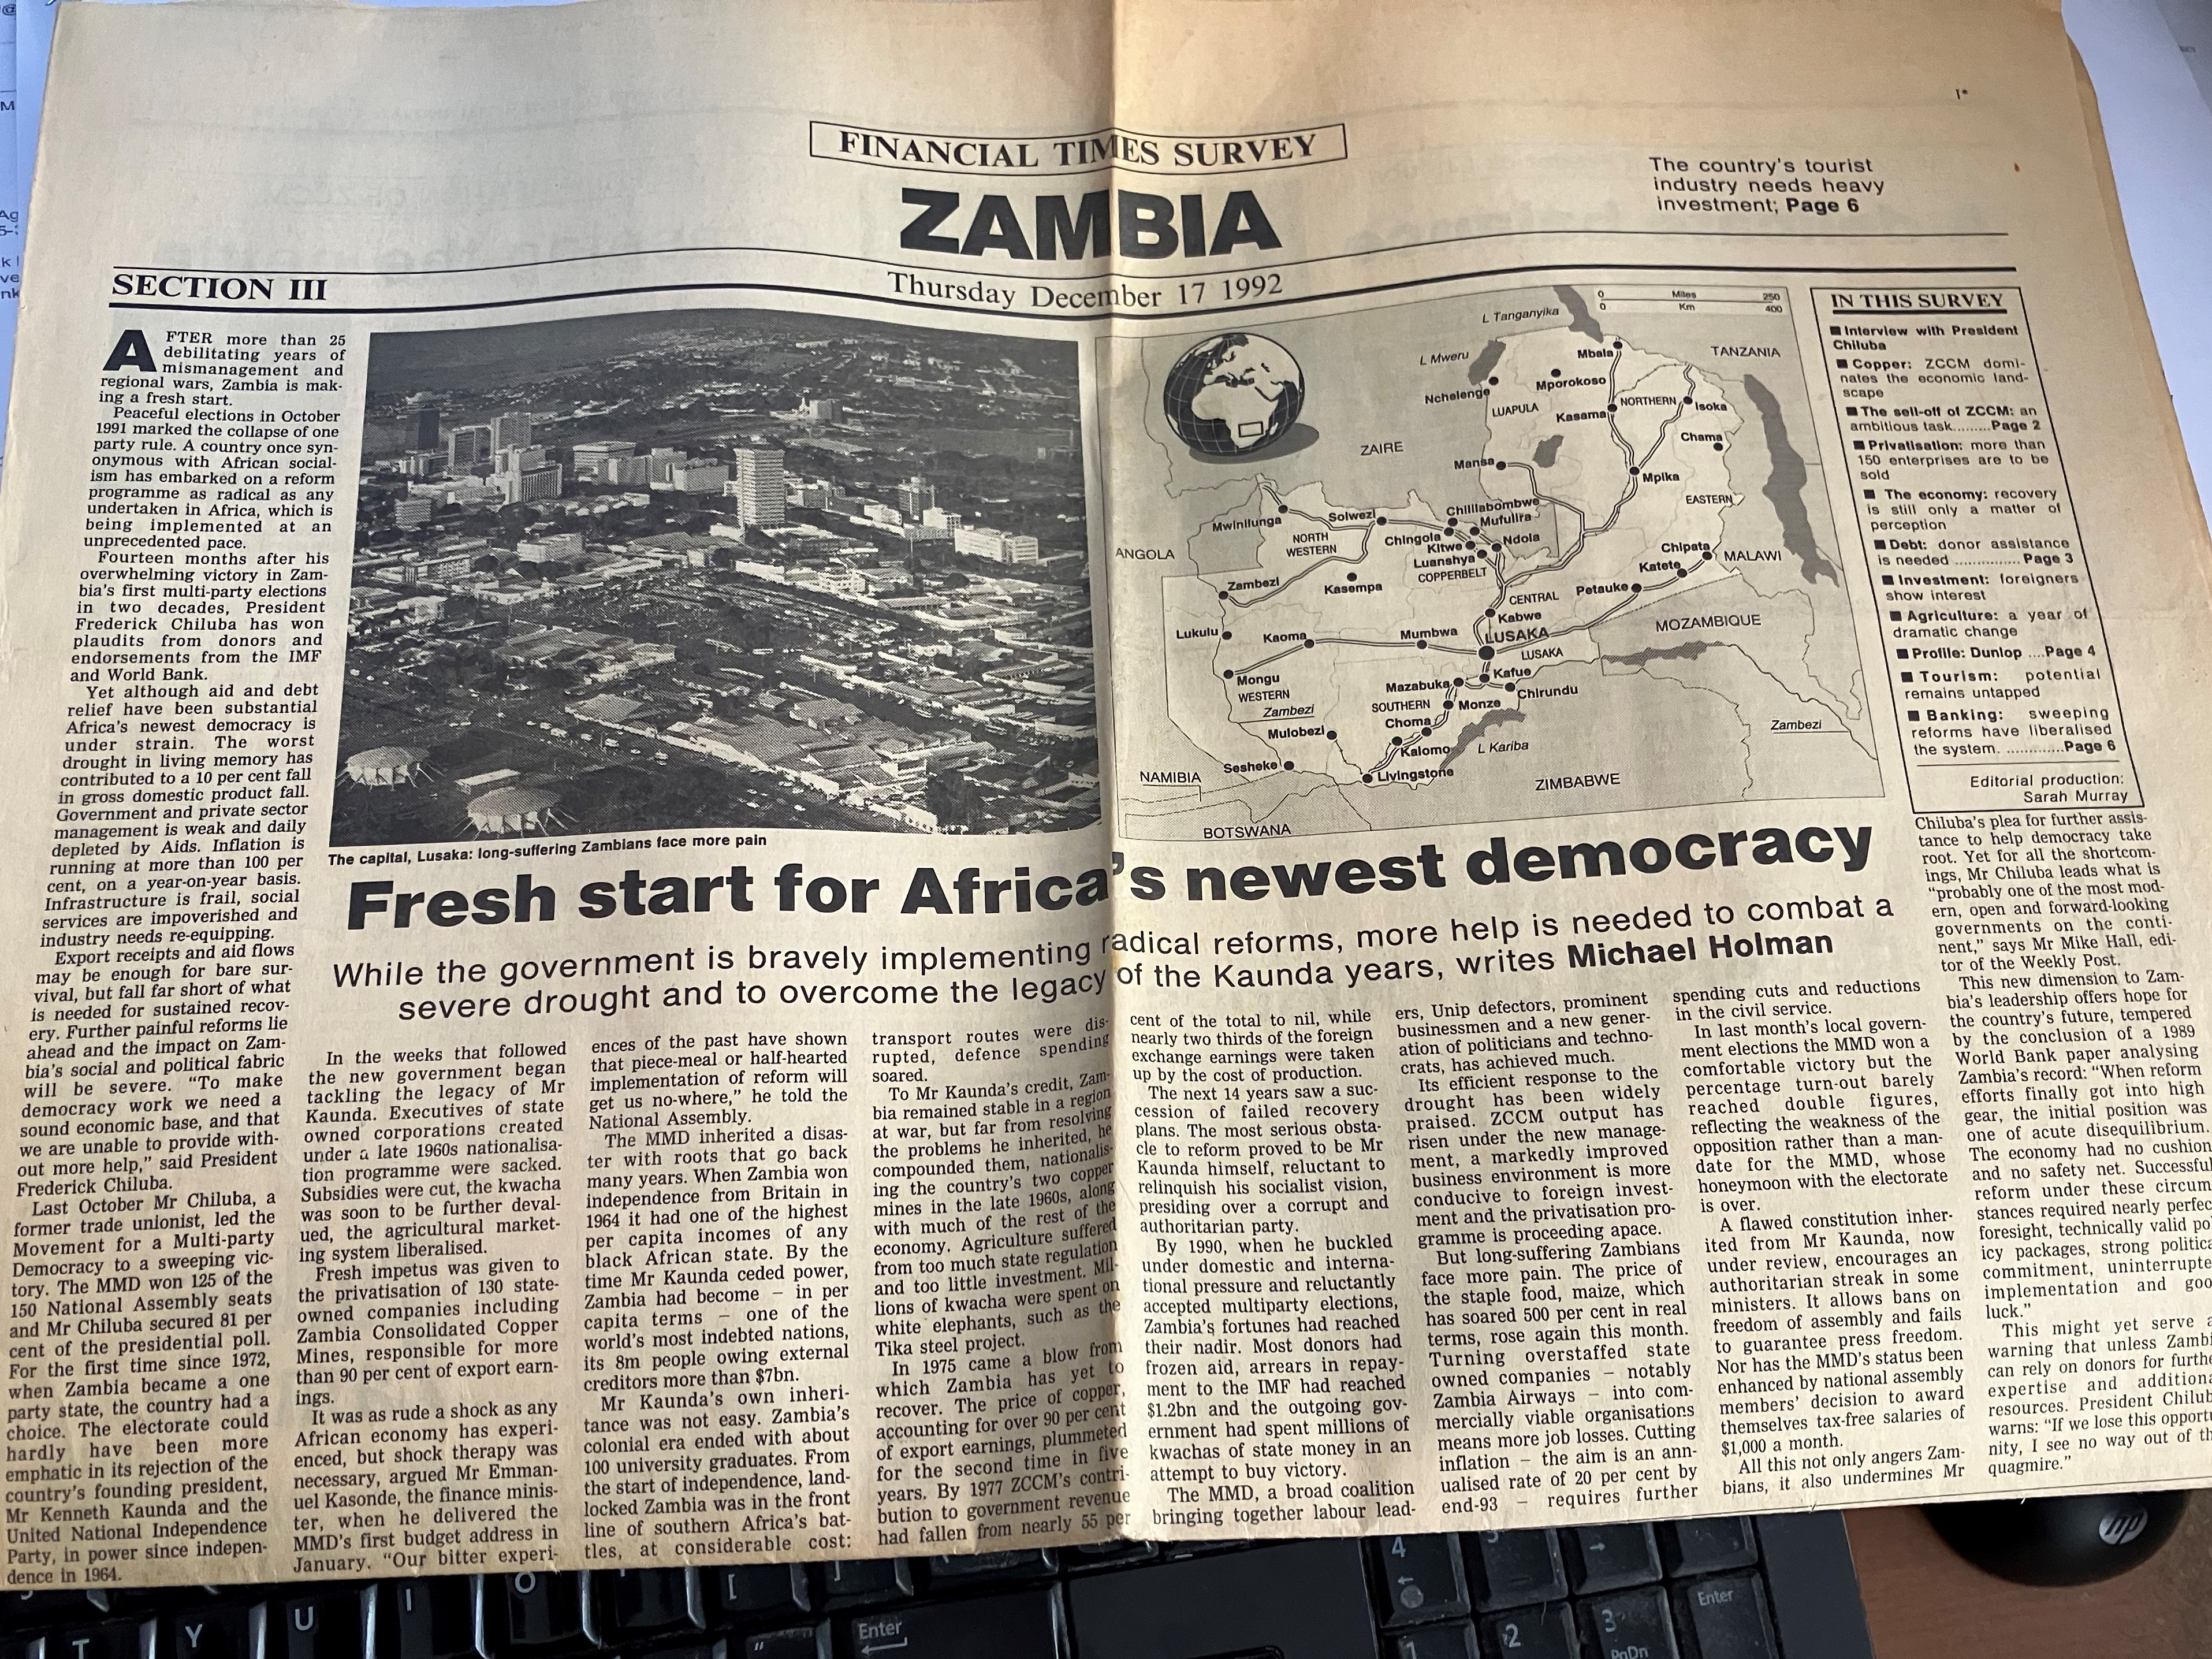
The Reserve Bank subscribed to the hard copy Financial Timesand a couple of days later an issue with a Zambia supplement landed on my desk
What wasn’t to appeal? Idealism even in the FT headline. Zambia was, if I recall correctly, only the second African country to have restored multi-party elections and to have changed governments.
I was young and single and had more or less done what the Bank had asked me to do when they’d prevailed on me to take my then-current job a year earlier. The slaying the inflation beast phase in New Zealand looked to be more or less over. The Bank knew I was looking round, although their ideas of a next role were a bit less unorthodox than heading off to somewhere like Zambia. A little reluctantly, they agreed to the secondment.
Inflation in Zambia was 181 per cent in the year to December 1992 and, if anything, rising (monthly inflation rates were about 10-12 per cent), and with all the donor goodwill in the world (and there was a lot of it towards the Chiluba government, just 12 months into the new era) things had to change. Making sense of what was going on wasn’t helped by the (literal) inability of the central bank to produce a balance sheet (there had been a serious computer system failure months earlier.
It was a wild, exciting and often frustrating, time to be there. As a place to live – and despite the mostly great climate – there was a little to commend it, but professionally that first chaotic year pushed one to the limit. In some respects, it was the best job I ever had, with that sense of being able to make a real difference, and see the people around me growing and developing capability.
As the blame for any really serious bouts of inflation rests with politicians, so ultimately does the credit for beating it (not only wasn’t our central bank formally independent, but when the governing party has 80 per cent of the seats in Parliament changing legislation wouldn’t have been much of an obstacle anyway). And if the roots of really serious inflation are always fiscal, so are the solutions. Zambia’s was the “cash budget”: the Minister agreed that money would not be spent that was not first in the government’s accounts at the central bank (whether from taxes, donor grants, or domestic borrowing), and each morning we and Ministry of Finance officials would pore over the numbers to get a sense of what payments could go through.
When it was made to work – and it was harder than it sounds, with threats and political tensions almost by the day – we presided over a liquidity squeeze on a scale rarely seen. Flicking through old diaries yesterday I found reference to Treasury bill auction yields at times averaging 600 per cent or more. The exchange rate, which had relentlessly trended down for many years, stopped falling and even began appreciating in nominal terms – it was to be a savage appreciation in real terms. I don’t have monthly data to hand (yes, even then Zambia – unlike modern New Zealand – had a monthly CPI) but if I recall correctly we even had a couple of negative inflation months. It wasn’t a new dawn of price stability – annual inflation settled in a range around 30-40 per cent – but the looming threat of hyperinflation has been beaten.
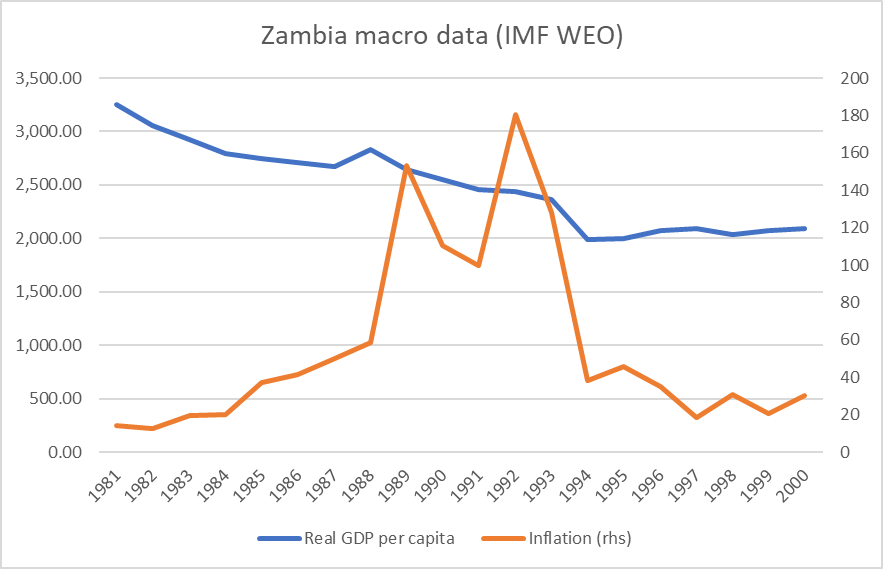
It was hardly a new dawn of prosperity. As in most places, difficult structural reforms have short-term real economic costs, and driving out entrenched inflation is rarely costless either. We didn’t have timely national accounts data then, so this chart caught my eye when I put it together a few weeks ago: notice the almost 20 per cent fall in real GDP per capita in a single year from 1993 to 1994. We knew it was tough – aside from anything else, exporting firms were not slow telling us – but the numbers are still sobering. Cold turkey treatments aren’t easy. In the space of a few months, we went from having the IMF doubting the seriousness of the authorities (and in fact outright lies were at times told by the authorities to the IMF to keep the programme on course) to having them concerned we had “got religion” and were overdoing things.
The Governor, Dominic Mulaisho, was probably the most inspiring person I ever worked for. As I said earlier, he’d had no background in central banking or macro, had only been appointed in 1992, and had had a history as a senior official in various leading government agencies in the post-independence period. He was also a published novelist, educated in Catholic mission schools before university in (then) Southern Rhodesia, and was, I think, always disappointed that my own command of Shakespeare and English poetry didn’t match his. He could be endlessly frustrating – I found diary reference to a 7 hour Monetary Policy Committee meeting one Saturday, an MPC that then was just about data presentations and lifting the quality of economic analysis and debate – but had an absolute commitment to better days for his country, and for the institution, and a stubborn integrity that finally cost him his job a couple of weeks before my term ended in 1995 (we were trying to close down a Zambian multi-national banking group that was evidently insolvent, but which had powerful friends). As just one indication of what he was up against, the night before I left the country he invited me round to his house and over drinks told me the story of travelling abroad with the then Minister of Finance who took him aside and (so my diary records) said “Governor, my aim is to get rich and to get rich quick. Your job is to help me do that, not to obstruct me. Why don’t you help me?” (both men are now dead).
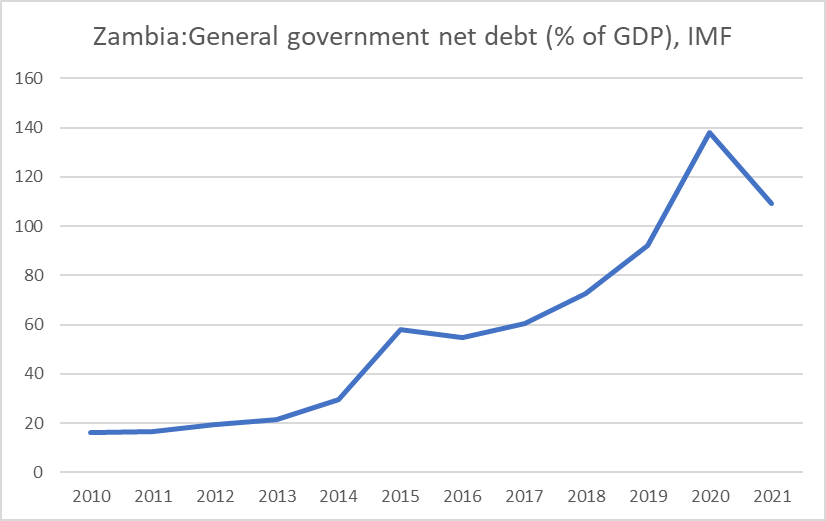
The prompt for this post is that I have spent the last couple of weeks back in Zambia. Times have changed. Several of the young grads I worked with then now hold some of the most senior positions in the central bank (and the chief economist from those days is now the Minister of Finance). Zambia isn’t without its continuing macroeconomic challenges. Debt-fuelled splurges over the last decade ended in a default on the foreign debt in 2020.
And if there seems to be lots of donor and international agency goodwill towards the new government (and many of the great and good have visited Lusaka this year, including Janet Yellen, Kamala Harris, and the IMF Managing Director), hopes of a substantial debt writedown are currently stalled.
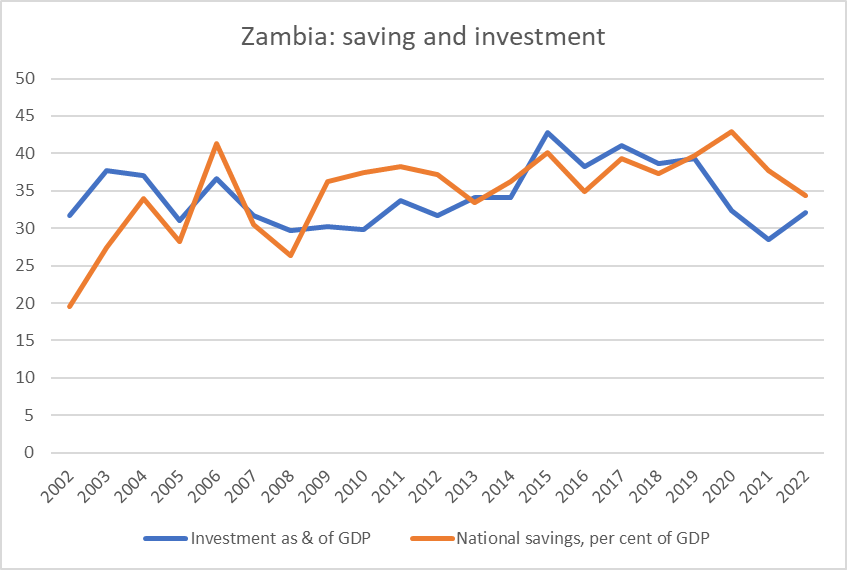
You can see the investment the debt helped finance in the data
Investment rates of 40 per cent of GDP are high by anyone’s standards.
But it was also visible as I walked and was driven around Lusaka over the last couple of weeks. You can see the new public infrastructure and the new private investment (shiny new office complexes, and the proliferation of small malls in the middle income parts of the city), even if the old main street, Cairo Road where the central bank is, was much the same as ever. It is visibly a different, and less raw, place than it had been 30 years ago. And you find something of that in the numbers too: in a country with a very rapid population growth rate, real GDP per capita is estimated to have risen 60 per cent since 2000.
The group I was working with asked a lot of questions about the contrasts and my experiences 30 years previously. As I reflected on it, one that struck me was the nature of the region. In 1993 when I first went, Zambia itself was a little more than year on from a democratic transition. Lusaka had hosted the ANC in exile and if they’d mostly returned home, the transition to democracy in South Africa was still a hopeful prospect rather than an accomplished fact (Chris Hani was assassinated just a few weeks later). The Angolan civil war still raged, the Mozambique conflict had ended only a year earlier, Namibia had become independent as recently as 1990, in Malawi the brutal Hastings Banda still ruled, and the genocide in Rwanda was only a year away. The DRC was, well, the DRC. (By contrast, Harare was a haven of functionality, before the chaos descended in Zimbabwe). These days, if democratic transitions aren’t common outside Zambia, peace and relative stability reigns, and there is a sense of relative normality about much of the region. Various countries have managed some material real income growth. And the best hotel in Lusaka – that I lived in for a year, and stayed in again last month – is now owned by, of all entities, the Angolan sovereign wealth fund.
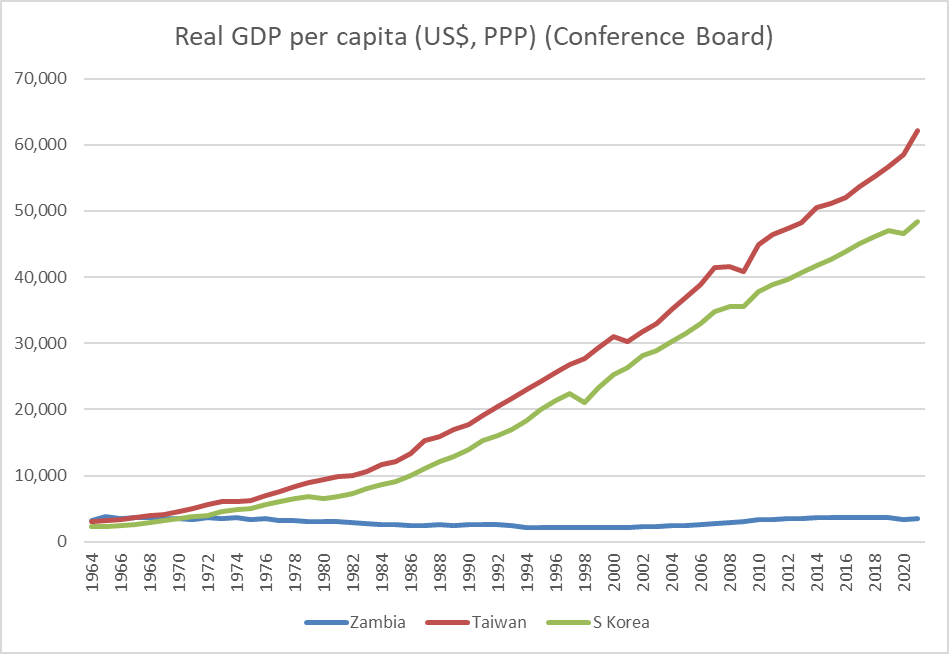
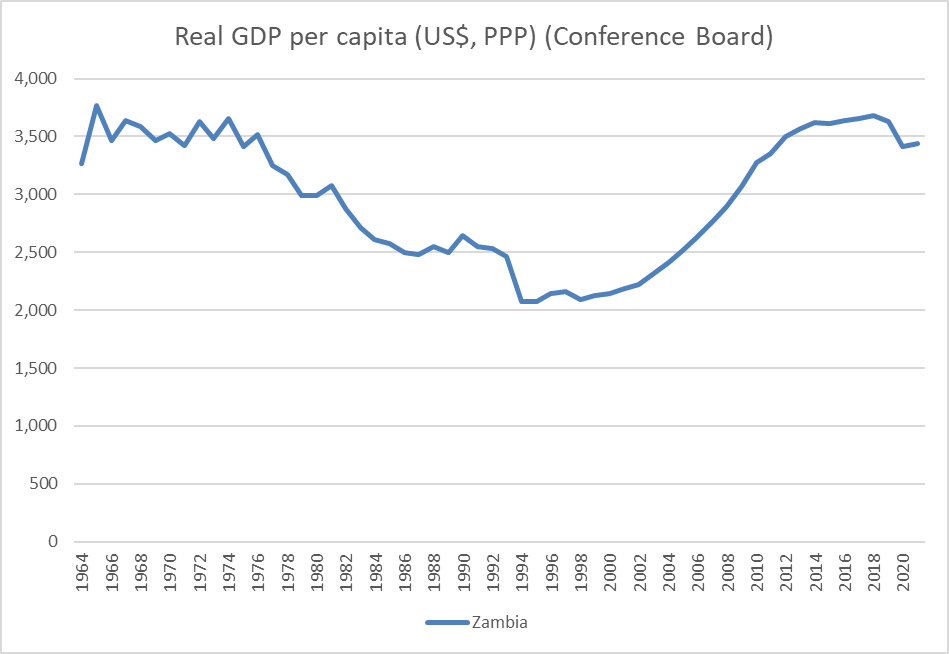
But then there is the longer-term context. Back in the 1990s we used to tell the story (including to the numerous international visitors who passed through) that at independence in 1964 Zambia had been a bit richer (per capita income) than Taiwan and South Korea (one of the richest countries in Africa, at a time when South Korea and Taiwan were already in the early stages of their growth trajectory). I put this chart on Twitter a few weeks ago
And here is the Zambian version alone
Almost 60 years on, real GDP per capita is barely higher now than it was at Independence.
It is a great country, with friendly people, abounding in physical resources (land area alone is equal to France and Germany combined) and still a major copper producer. If you have never been to the Victoria Falls you really should one day. And there are many countries in Africa worse off than Zambia (and much richer South Africa has also seen next to no real per capita GDP growth since the mid 70s). There is a lot I like about the place, but……the challenges before them to achieve and sustain big improvements in material living standards for their people are huge.
(Among the things to like, I picked up Covid while I was in Zambia. Unlike New Zealand, a colleague could wander down the street to the nearby chemist and buy me a cold and flu remedy that really worked – no bans on pharmacy sales of pseudoephidrene products there.)
In the government’s Budget, the Treasury projects that on current policies the government will be running an operating deficit for six straight years (while in the 7th the surplus is so tiny that even if it were not for Eric Crampton’s point about tobacco excise revenue we might as well just call it a coin toss as to whether, if the economy played out as Treasury projects we’d see a surplus or a deficit that year).
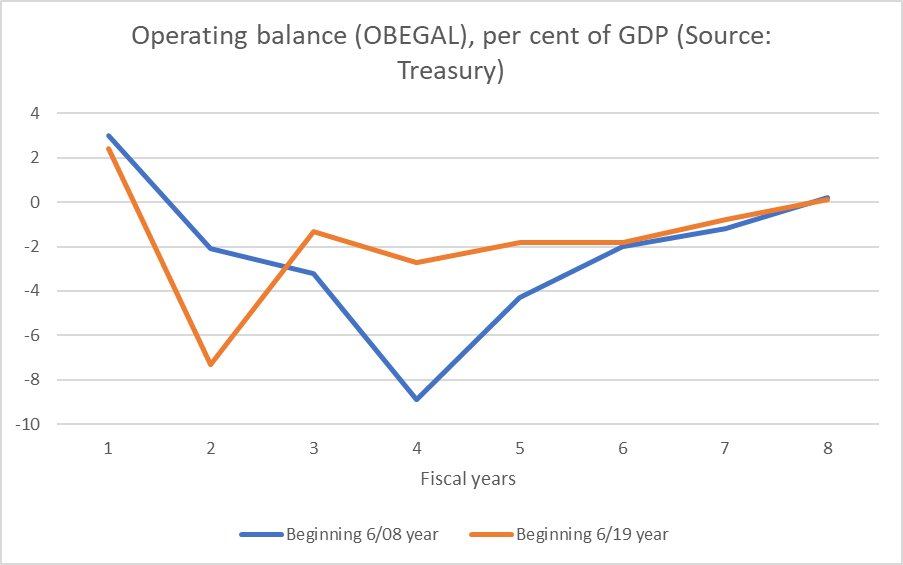
People have from time to time pointed out that under the previous National government there was also a spell of six straight years of deficits. In fact, here is a chart. The blue lines shows actual fiscal balances from the last surplus (year to June 2008) to the first surplus again (year to June 2015), while the orange line shows actual and Treasury forecasts from the year to June 2019 (last surplus) to the first (tiny) projected surplus (year to June 2026)
In each period, there was one really really large deficit year. In the earlier period that was the year to June 2011, which captured much of the cost to the Crown resulting from the Canterbury earthquakes. In the more recent period, the peak deficit was the year to June 2020, the period encompassing the first and longest Covid lockdown (huge wage subsidy outlays and all).
If these forecasts come to pass we”ll have had an operating surplus (or balance) in five of the last seventeen years.
What about context? In both periods there was a very big exogenous event: earthquakes in the one period and Covid (lockdowns) in the other. Both were, almost necessarily, very expensive for the government. Few people have much problem with meeting many of the direct costs as fiscal obligations.
But….there was a really important difference between the two periods. In the first, the economy headed straight into a fairly deep recession (partly domestically-sourced – our inflation rate had got above the top of the target band – and partly the global downturn associated with the 2008 financial crisis. It was all aggravated by the fact that the 2008 Budget was very expansionary – and yes, that was extravagant and it was election year, but the Treasury advised them that such an approach would not push the budget into deficit over the forecast horizon. It wasn’t one of Treasury’s better calls.
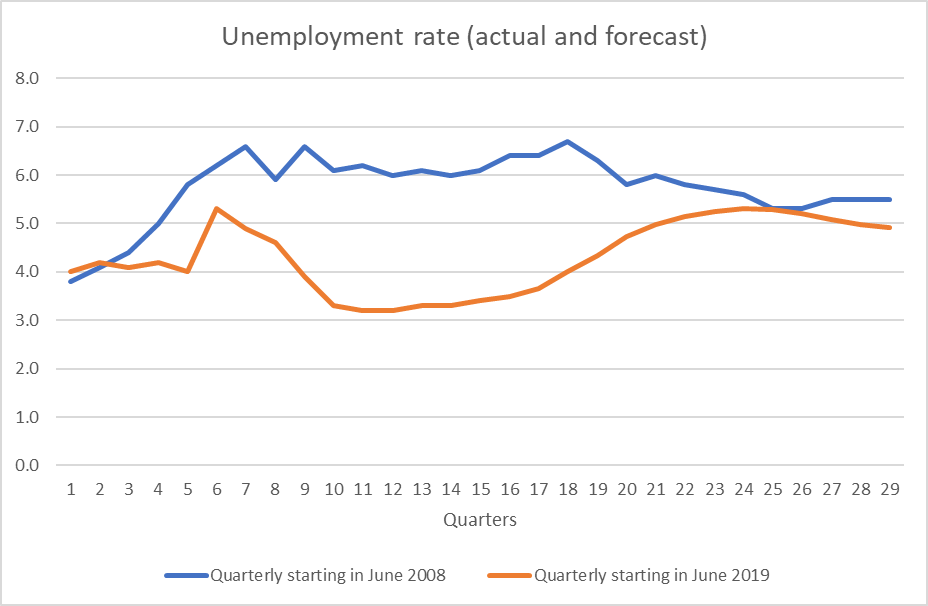
By contrast, at the end of 2019, the unemployment rate was low and, notwithstanding the brief but severe interruption to output around the lockdowns, has mostly remained very low since. When there isn’t excess capacity in the economy, tax revenue tends to come flooding in.
Here is a comparative chart of the unemployment rates in the two periods.
That difference in the unemployment rates makes quite a big difference to the fiscal outcomes, for any set of spending choices. You might criticise the previous government for doing nothing about a Reserve Bank that let unemployment linger well above the NAIRU for so long, as you might criticise the current government for doing nothing about a Reserve Bank that had the economy so overheated for so long. But the economic backdrops to those paths of fiscal deficits were simply very different: with an overheated economy and lots (and lots) of fiscal drag, the revenue was flooding into Treasury over recent years. There was simply no good macroeconomic reason for having operating fiscal deficits at all in an overheated economy, especially once the big direct Covid spending had come to an end (which it had a year ago). By contrast, the earlier government presided over a very sluggish recovery – and so weak, relative to target, was inflation that there was barely any fiscal drag. Even if the Budget was structurally balanced, cyclical factors would have left a small deficit (on Treasury and Reserve Bank numbers there was a negative output gap every year through to 2016).
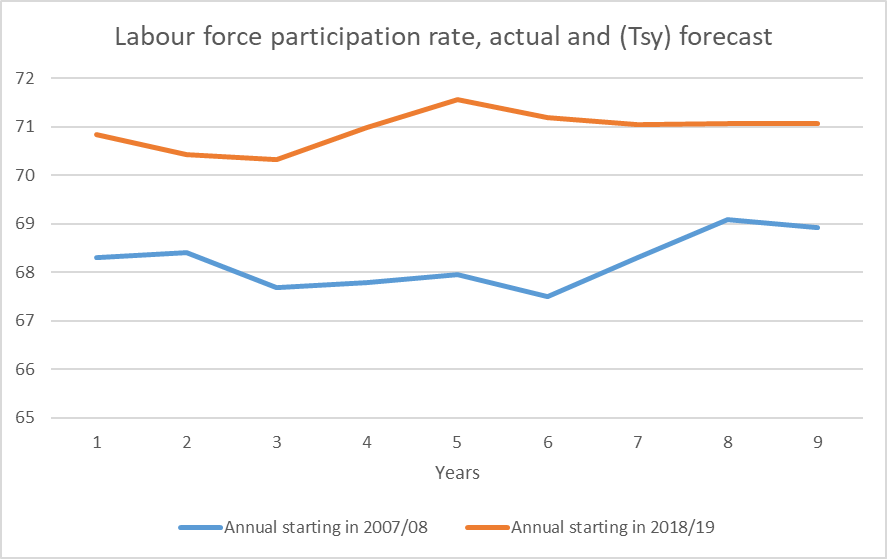
If the unemployment rates and output gaps give a sense of the cyclical slack (or overheating), labour force participation rates are also valuable context
A materially larger share of the population is now in the labour force now than in the period of that previous run of deficits (and given that unemployment rates have been lower this time, the difference in employment rates is even larger. Revenue has been abundant.
I’m not really convinced there was an overly strong case for the previous government having continued to run operating deficits in the last couple of years of their stretch of six. Had the Reserve Bank been doing its job better, perhaps they wouldn’t have (the economy would have been more fully employed and inflation would have been nearer the target).
But I’m quite convinced there has been no good economic case at all for operating deficits in 22/23. 23/24, or 24/25. Take 22/23 (the year just ending) as an example: on Treasury estimates there has been a positive output gap, and the unemployment will have averaged about 3.5 per cent (well below anyone’s estimate of NAIRU). And with 6-7% inflation, fiscal drag has been a big revenue raiser. And if there has been any residual direct Covid spending (a few vaccinations?), the amounts involved must have been vestigial indeed. So cyclically the revenue was flooding in, but they still ran a deficit: it was pure choice to undertake routine operational spending without the honesty to go to the electorate and raise the taxes to pay for that spending.
The cyclical position is less favourable over the next couple of years – the recesssion (as indicated by the 2 percentage point rise in the unemployment rate) required to get inflation back down again – but the government has chosen to adopt discretionary new giveaways with borrowed money.
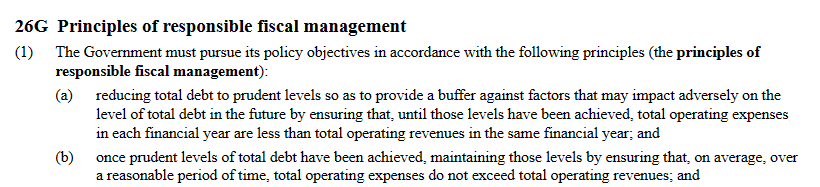
It isn’t just some idiosyncratic Reddell view that operating budgets should be balanced (none of this is about capital spending or arguments about infrastructure). It is there in the Public Finance Act
Now, if I was writing the Public Finance Act, I wouldn’t word things quite that way. But……the Public Finance Act is something both main parties have signed up to. It may make sense to borrow to fund useful longer-term investment, but it makes no sense to be borrowing to pay the groceries, especially in times when income has been more abundant than usual.
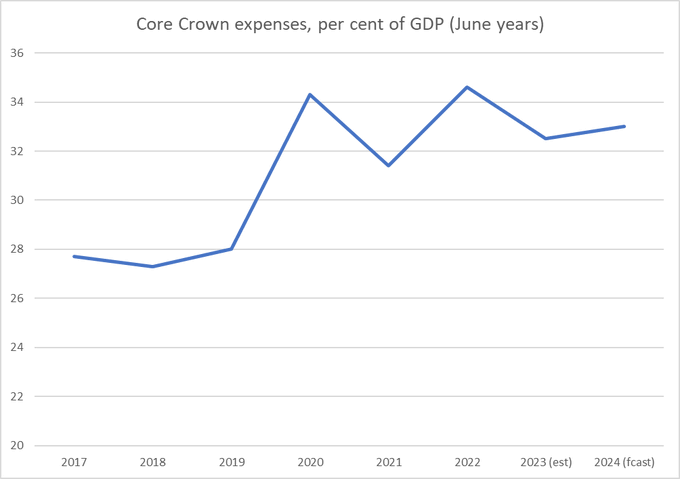
Just two more Budget charts. The first is one I showed on Twitter yesterday
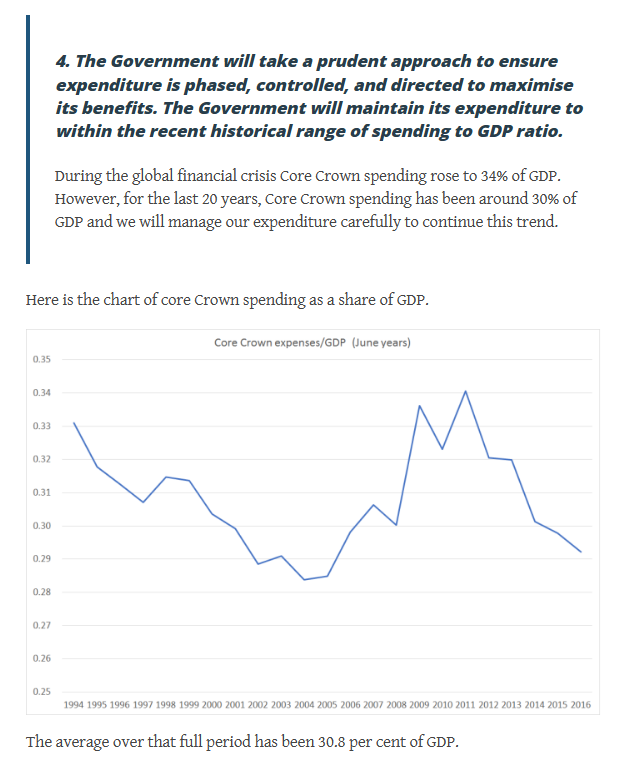
Now, there is plenty of scope for political argument about the appropriate size of government spending, and left-wing parties will typically be keener on higher numbers than right-wing parties. My own interest here is more about fiscal balances, but it is worth being conscious of just how much larger a share of the economy is now represented by Crown operating spending than was the case even five or six years ago. Those were the days of the pre-election Labour/Greens budget responsibility rules
Next year’s spending at 33 per cent of GDP is not quite at the previous peaks (Covid and the earthquake years) but nor might one really have expected it to be. But there is an election to win I guess.
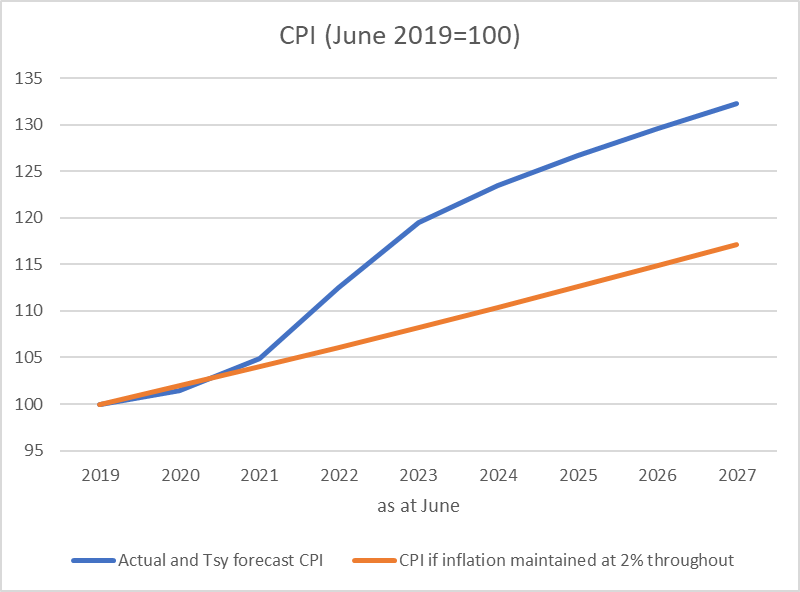
And finally, inflation. Treasury doesn’t run monetary policy but (a) the Secretary sits as a non-voting MPC member, and (b) Treasury are the Minister’s advisers on the Bank’s performance, so they aren’t just any forecaster. On the Treasury numbers, it isn’t until the year to June 2027 that CPI inflation gets back to the middle of the target range (the 2 per cent midpoint the MPC is supposed to focus on).
This chart uses Treasury’s annual numbers to illustrate what a difference the monetary policy mistake has made, and is making, to the price level
The blue line is the actual (annual) data and the Treasury forecasts. The orange line is what the price level would have looked like in a stylised scenario in which the MPC had delivered 2 per cent inflation each year over this period. The difference is substantial: the price level in the blue line is almost 13 per cent higher than in the orange line by the end of the period. The Minister of Finance appears to be quite happy for the current gap (about 10 per cent) to keep widening for the next five years. He shouldn’t be.
We do not run a price level targeting regime. That means bygones are treated as bygones and we don’t attempt to pull the actual inflation rate back down to the orange line having once made the policy mistake that pushed it so far above. It does not – or should not – mean indifference to the arbitrary redistributions that big unexpected changes in the price level impose, strongly favouring borrowers (especially those with nominal debt and long-term fixed interest rates) and heavily penalising financial savers (holders of real assets can be largely indifferent over time). Inflation – and especially unexpected inflation – is deeply damaging, and there were good reasons for reorienting monetary policy to deliver medium-term price stability. But now the powers that be appear unbothered by 7 years in succession of inflation above the target midpoint. It seems about on a par with being happy to set out to deliver six successive years of operating deficits. Poor fiscal policy, poor monetary policy, poor performance from both the Governor and MPC and the Minister of Finance (the latter not only having direct responsibility for fiscal policy, but overall responsibility for monetary policy and the people he appoints to conduct it). It will be interesting to compare the Reserve Bank (considerably more up to date) forecasts next week.
I’m going to be away for the next couple of weeks so there won’t be any new posts here until after King’s Birthday.
There have been various posts here over the last couple of years about the losses to the taxpayer resulting from the Reserve Bank’s Large Scale Asset Purchase (LSAP) programme. Some of these have been more about explaining than excoriating (the latest such explanatory post is here).
As I noted in that most recent post, in the early days of the LSAP the line item on the Reserve Bank balance sheet for the claim on the Crown indemnity was a rough but reasonable estimate of the total losses, based on market prices as at the successive balance dates. It became an increasingly inadequate indicator as the LSAP programme started to be unwound, with the longest-dated bonds being sold back to Treasury, losses being realised, and payments being made from the Treasury to the Reserve Bank under the indemnity.
But the amounts of those indemnity payments were not being routinely disclosed (eg the RB does not publish a monthly income statement) and analysts were reduced to picking up snippets of information from OIAed documents. It wasn’t exactly transparent.
Anyway, in an OIA request to the Treasury and in a conversation with someone from the Bank I suggested it would be helpful if the monthly indemnity payment amounts by Treasury were to be routinely disclosed. That way, whatever debates we might want to have about the merits or otherwise of the LSAP programme, at least we would all be working with the same numbers.
And thus it has come to be, and this morning a new spreadsheet on the Bank’s website went live with monthly updates on payments and receipts under the LSAP indemnity. The link to it is about half-way down this page.
Here are the two components
Here is the Bank’s own description of the numbers in the blue line
There were net transfers to Treasury for a while because the coupon rates the Reserve Bank was receiving were higher than the (OCR) funding cost.
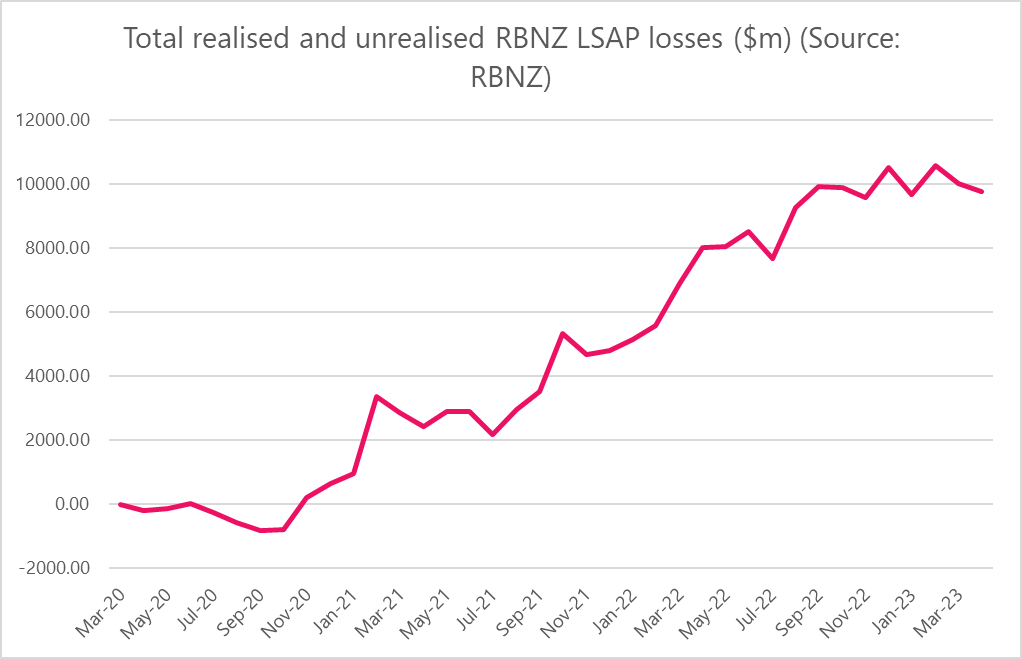
And here is the chart showing total losses, realised and unrealised.
The total will keep fluctuating a bit from month to month as market rates change, but the variability will gradually diminish as (a) the size of the remaining LSAP portfolio continues to steadily shrink, and (b) the longest-dated bonds have been sold back first. But for at least the last eight months, something around $10bn in total losses has been the best (market price) guess.
There were two points to this post. The first was to use the new data to illustrate better than has been possible until now with hard numbers just what has happened with the LSAP gains and losses over time. And the second was to acknowledge the Bank and thank them for making the data available. The losses probably aren’t something the Bank is really comfortable with, but one shouldn’t be hiding from the hard numbers, and in publishing them regularly now the Bank apparently is not. And that is welcome.
$10 billion is, however, a lot of taxpayers’ money to have lost.
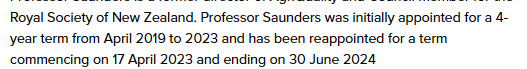
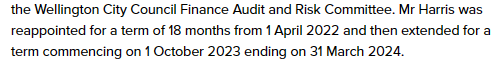
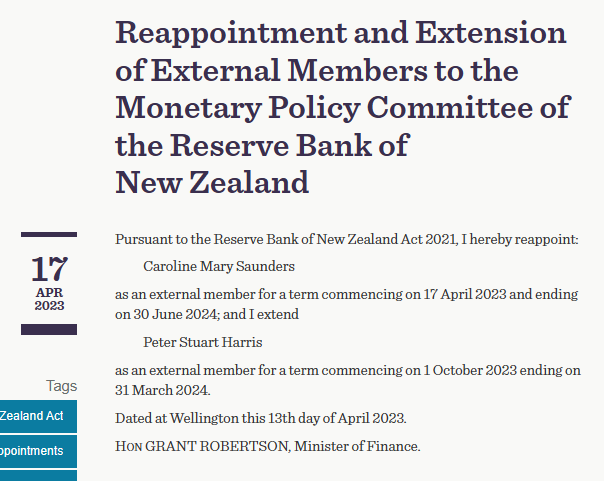
There have been a few posts here recently about Professor Caroline Saunders, whose initial term on the Reserve Bank MPC expired at the end of March and who was eventually, belatedly, and with no announcement at all, appointed by the Minister of Finance to a short second (and final) term on the MPC. The most recent of those posts was here.
When there was no announcement before the Saunders term expired, I had lodged OIA requests with both the Reserve Bank and the Minister of Finance for material relating to her reappointment (or otherwise). Responses to both emails have now come back.
If it is now clear that the bottom line reason why Saunders was not reappointed before her term was expired was administrative slackness (between the Minister’s office and Treasury mainly), the documents that were released don’t put any of those involved in a particularly good light.
My request to the Bank was fairly broadly phrased
I am writing to request all and any material (including any advice to the Minister) relating to the expiry of the MPC term of Caroline Saunders and any discussions or decisions to reappoint her (or not) or to extend her term
and since the Bank says it has not withheld any documents, it seems fair to assume that what I have is all there is.
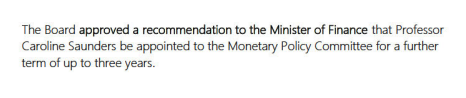
This was the first document they released, from the minutes of the Reserve Bank’s 7 December 2022 Board meeting/
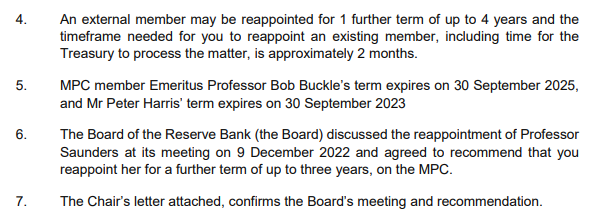
In other words, there was no paper analysing the record of the MPC or the personal contribution to the MPC made by Saunders, even though the decision to recommend reappointment was being made in the midst of the worst monetary policy failure in the decades since the Reserve Bank was given operational independence around monetary policy. There was also apparently no paper discussing the best balance of the MPC in the period ahead, or the appropriate length of time for a reappointment (not even, apparently, a discussion as to why the recommendation is for an extension of “up to three years” when the law would allow up to a four year second term. There is also no sign in those minutes of any substantive discussion or hard questions being posed by Board members (unsurprisingly perhaps given the lack of relevant background of all but the chair, who presumably had any conversations with the Governor in private, unminuted).
It was, it should be noted, no better when the other two external MPC members were reappointed (for terms from 1 April 2022), but the inadequacy of the process is all the more glaring by late 2022 when the extent of the monetary policy failure, for which MPC members are responsible, was much clearer than perhaps it was to the previous Board in late 2021.
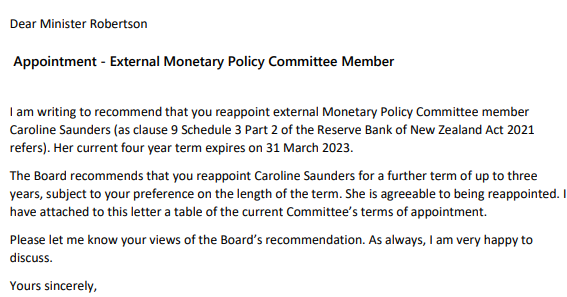
The Board chair then seems to have moved fairly expeditiously, sending a letter of recommendation to the Minister dated 16 December 2022.
although it is not entirely clear whether this was sent directly (it is signed and dated) or only as an attachment to a memorandum to the minister from Quigley dated 9 January 2023. This is the entire substance of that memo
Note several things
(trivially) there is actually a mistake in the letter (Buckle’s second term expires in March 2025 not September 2025
there is no advice (not a word) to Minister about the contribution Saunders had made over her (by then) 3.75 years on the MPC, a period in which (a) the regime was new, and (b) monetary policy was sorely tested.
despite explicitly noting to the Minister that Saunders could be reappointed for four years, the Board chair offers the Minister no information as to why the Board thinks the extension should be only “up to” three years.
presumably after discussions with Treasury, the Minister is told that the process for reappointment should take about two months (this in a document submitted on 9 January). Elsewhere in the formal recommendations the Minister is asked for a decision by 23 January.
And then there are no other documents (and the Minister has also not indicated that he has withheld whole documents) for more than two months. The next document is dated 8 March, only three weeks before the Saunders term expires.
In any country with serious scrutiny of the MPC – and a belief that external MPC members made any difference whatever – serious questions would have been being asked by now, by market participants and by journalists. After all, on paper MPC members wield a great deal of power, and things hadn’t been going that well with monetary policy. But there weren’t.
In an internal Reserve Bank email (to the Governor) we learn that on 2 February “the MoF’s office asked for a clarification to be made to the letters/report which we provided (that CS be reappointed ‘up to 3 years’ subject to the preference of the MoF”.
And again nothing until 4 March when the timeline in this same email records that “MoF’s office call Neil Quigley to seek clarification on Caroline Saunders’ reappointment. On 6 March, the Reserve Bank learns “from MoF’s office that the recommendation will go in the weekend bag….and we should get an outcome early next week”.
And they did
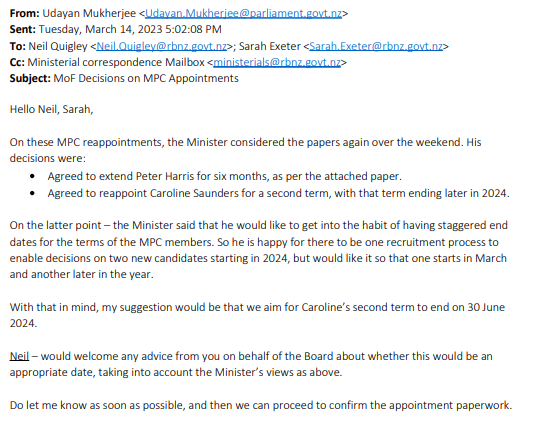
which is strange again, because while the Minister is reported as favouring staggered terms for MPC members (and very sensibly so) he deliberately, and with no officials’ recommendation plumped for a term for Saunders which will mean that the terms of all three external members expire between 31 March 2024 and 31 March 2025. It would have been easy to have given Saunders a three year term or even a four year term and really stretched things out. But he did not, and there is no indication why in any of the papers.
Quigley reverts to the Minister accepting the general idea and a very short extension to 30 June 2024 is agreed. Quigley observes that “Caroline’s term ending at that time is entirely workable from my point of view. As you say, the search for a replacement can still be part of the same search that we undertake to fill the other vacancy from 1 April 2024”. Since it is already May, one might suppose that a new search process – since both Saunders and Harris cannot be reappointed again – will be getting underway fairly shortly.
At this point it is realised that they are too late to get the Saunders reappointment confirmed before her term expires (it needed to go through the Cabinet Appointment and Honours Committee and to be confirmed by the full Cabinet) but nobody seems very bothered by this. As the documents note, and as I initially missed, the (dubious) statutory provisions for MPC appointments allow an MPC to stay in place after their term ends unless advised otherwise by the Minister. But there is no sense of urgency, no sense (perhaps accurately) of any likely media or market interests (despite the on-paper power these positions wield), at least until I wrote a post on 3 April, which prompted the Reserve Bank comms staff to (a) prepare a draft statement if at that late point there were to be any media questions (which there weren’t) and (b) quickly update their website to make clear that members could remain in office after the expiry of their term,
There is no hint in any of the papers released as to why the Minister of Finance chose not to announce formally the reappointment of Saunders (or the extension of Harris, to get around election timing) and rather leave the fact to be discovered either by chance or by assiduous readers of the Gazette.
In the grand scheme of things, perhaps none of this matters a great deal, but the promise was, in reforming the Reserve Bank Act, that MPC members really would matter, and would make a difference. Over four years, there has not been the slightest evidence for it.
But it still seems to be a very bad look, given that the government chose to keep on with the curious appointment model in which the Minister can only appoint people his hand-picked (and not for relevant expertise) Board recommends, that there is no evidence the Board itself engaged in (or received) any serious analysis or review of Saunders’ contribution to the MPC through such a challenging period, and that there is no evidence that any serious substantive advice was being provided to the Minster on her contributions, strengths and weaknesses. It doesn’t reflect much better that there is no sign that the Minister cared, or sought such advice (despite how far outside the target range core inflation has been). The Minister’s office processes seem to have been slack, to say the least. No doubt he is a busy man, but he has a fully staffed office, and there is much justification for sitting doing nothing for two months on a recommendation for an appointment that really should be somewhat market sensitive.
As for Saunders, were she really making a stellar contribution to the MPC (a) the Board might have been expected to have highlighted that and recommended a full four year term extension, and (b) the Minister might have been expected to have enthusiastically agreed (she was after all his preference four years ago). Instead, nothing, and about the shortest credible extension it was possible to have given her.
Finally, there are some issues for any incoming government later this year. As I often point out, a new government that was unhappy with how the Reserve Bank and MPC have been operating cannot simply get rid of the Governor. They can however make appointments around him (including Board and MPC members). Any different government has been given quite a gift by Robertson, in that all the external MPC member positions will expire by 31 March 2025 and all have to be replaced. The Board chair’s own term expires on 30 June 2024 (he was given only a two year (presumably final, transitional) term on the new Board. Given the mediocre appointments to date, and lack of evidence of serious scrutiny and review, if an incoming government really cares about making things better at the Reserve Bank, they will need to take the issue in hand early and make it clear to the Board – themselves quite unqualifed to judge – just what sort of people the Minister will consider appointing (removing, for example, and one would hope, the current blackball on anyone actually engaged now or in future in any serious macroeconomic analysis and research). It is most unlikely that better outcomes (people, process, policy) if Orr and Quigley are simply left to do things as they’ve been done for the last four years.
The question of course is whether the Opposition parties really do care. It is easy to run lines now about “cost of living crises” and high inflation, but (core) inflation is a Reserve Bank outcome and the Minister of Finance is ultimately responsible for, and wields more than a few levers over, the Reserve Bank (people, processes, budgets, and policy goals).
In the meantime, what this little episode reveals again is the empty charade the new MPC is, and always was. We have a minister who was interested in the appearance of change rather than the substance of change, and who has shown no interest at all in holding policymakers to account for signal policy failures. And a Governor who could live with (perhaps even embrace the rhetoric of ) the appearance of change so long as his actual dominance of the process and institution was left substantively unchallenged. A double coincidence of wants, just not one well aligned with the wider public interest.
Back in 2020 and 2021, in and around the straight economics and economic policy posts, there were quite a few on aspects of the Covid experience in New Zealand, particularly in a cross-country comparative light.
More recently, you see from time to time suggestions that New Zealand’s experience may have been so good that in fact excess mortality here since Covid began might actually have been negative (in which case, fewer people would have died than might have been expected had Covid never come along.
A couple of alternative perspectives on that caught my eye in the last couple of months, both from academics, one from a physicist and one from an economist.
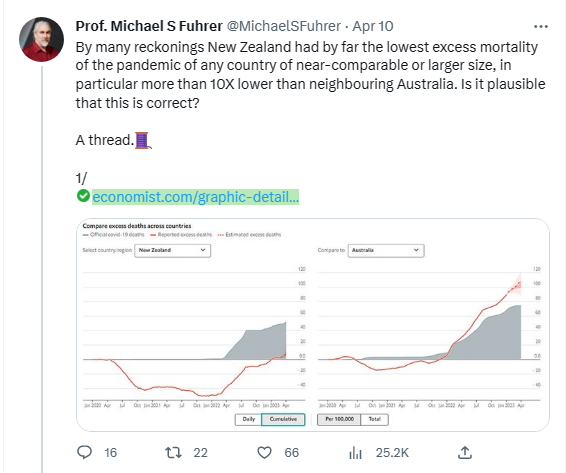
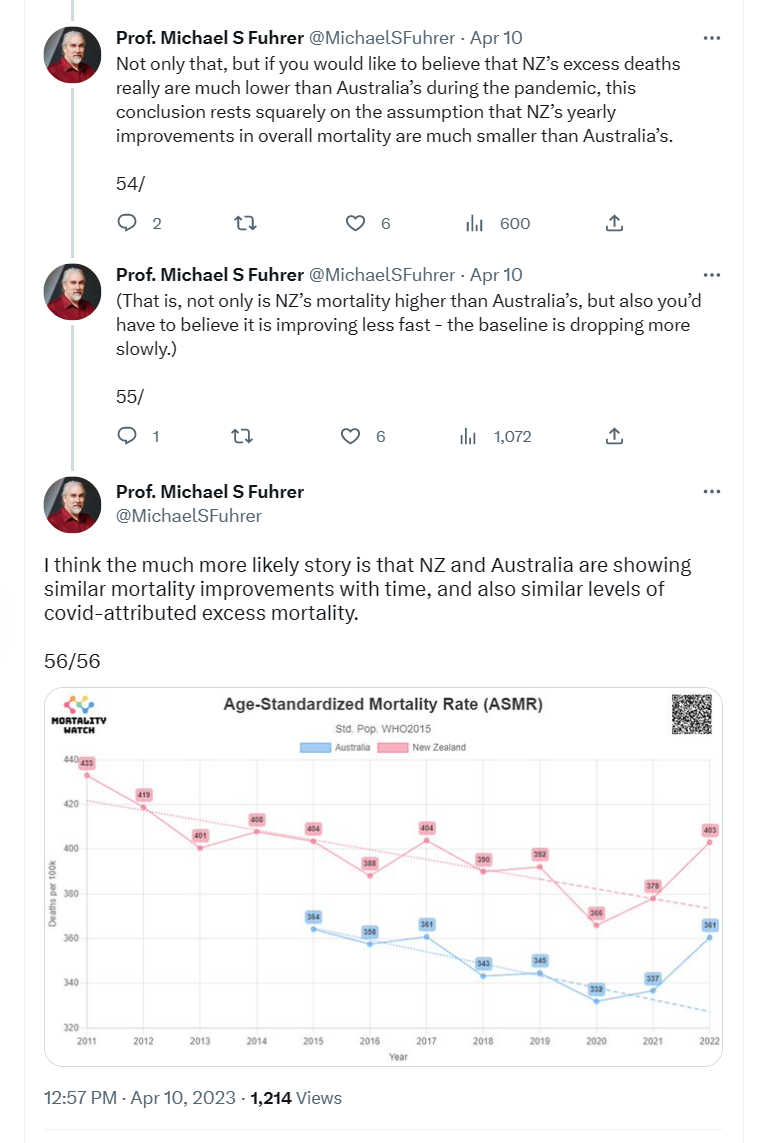
The first was a very very long Twitter thread from Professor Michael Fuhrer at Monash in Melbourne. His thread starts with this tweet
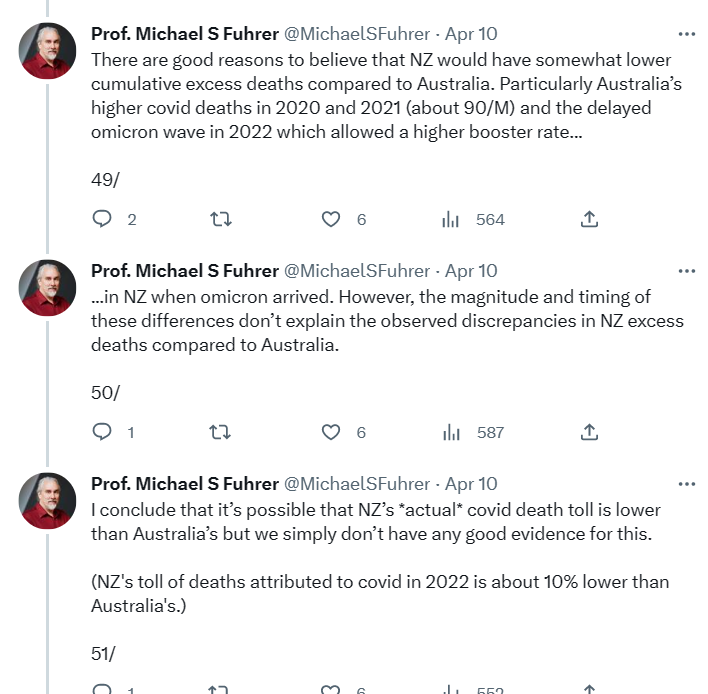
and after reviewing the evidence, and granting that
he concludes that
All of which sounded plausible, at least having read the entire thread.
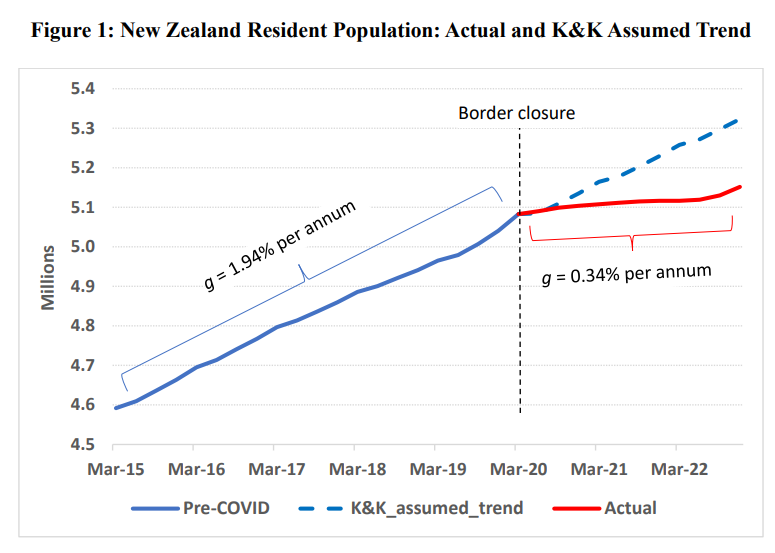
For New Zealand, one of the biggest things that changed over the first 2.5 years of the Covid era was a dramatic slowing in the population growth rate, not because of Covid or other deaths but because net migration went from a hugely positive annual rate to a moderately negative rate. Pre-Covid – and probably again now – migration is the biggest single influence on the year to year change in New Zealand’s population. He includes this chart
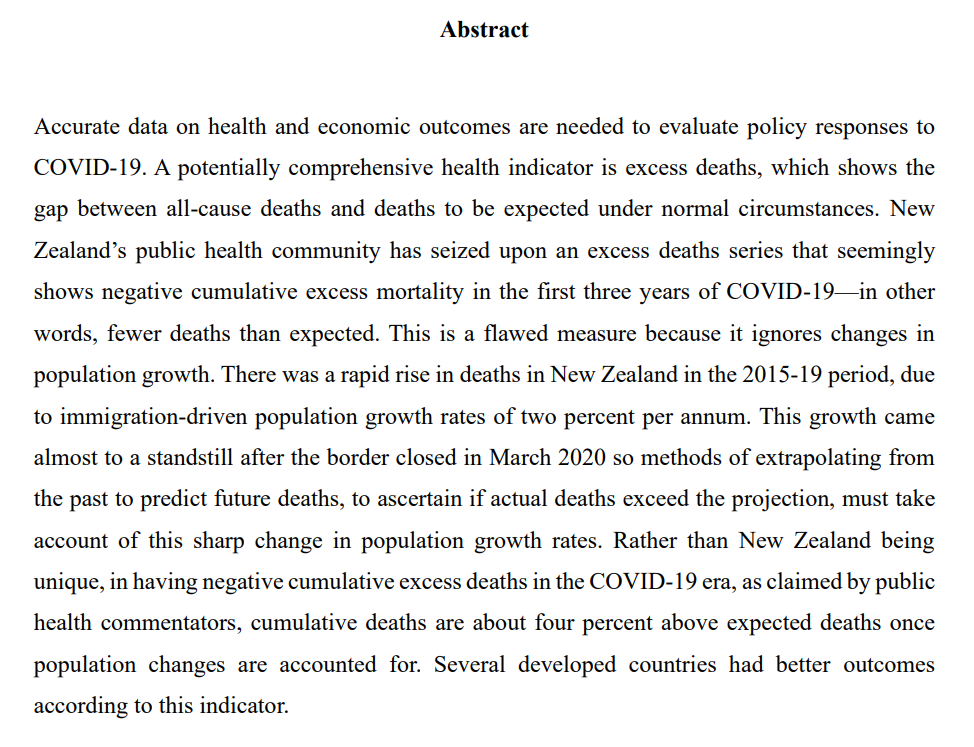
Here is Gibson’s abstract
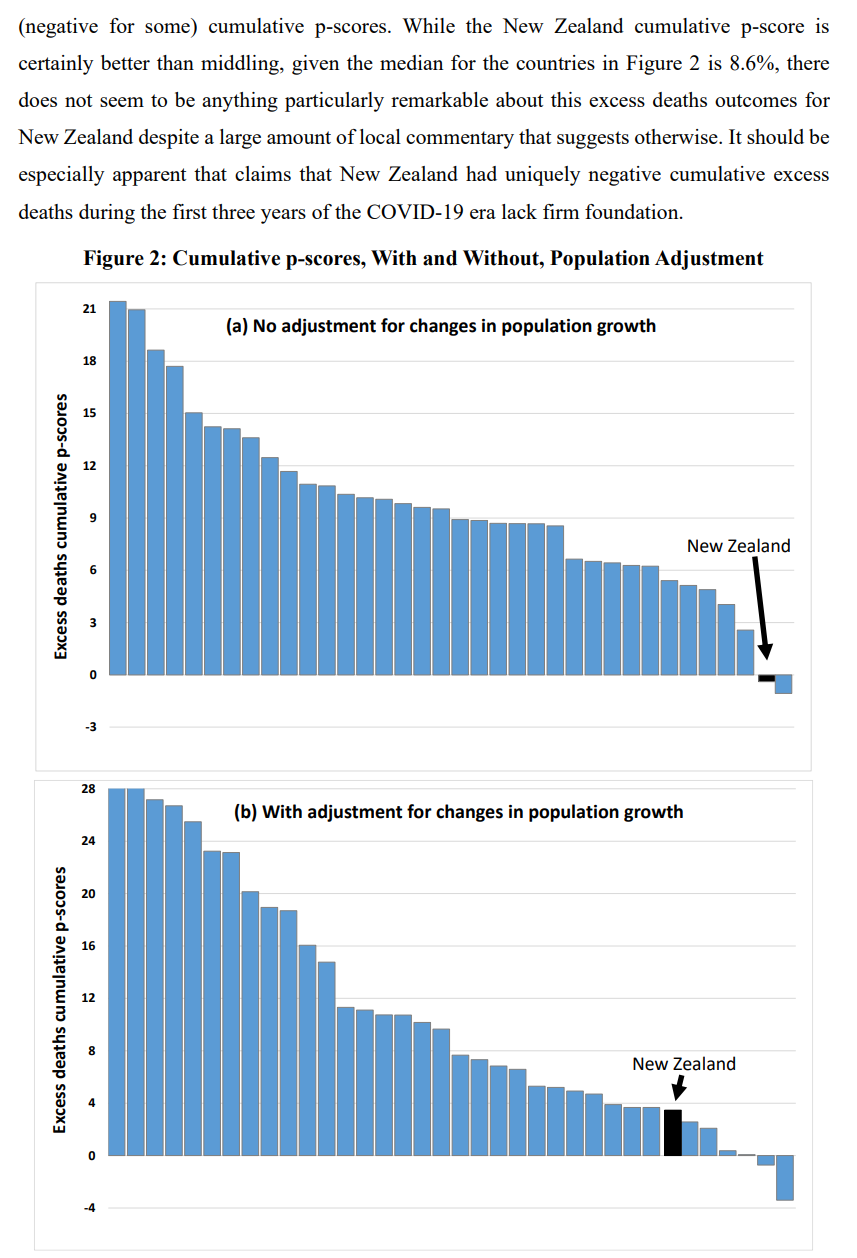
It is a short paper, and easy enough to read, so I’m not going to elaborate further, and will simply cut and paste the final page.
It is a shame he hasn’t labelled all the other countries, but his text tells us that the countries to the right of New Zealand on that bottom chart are Luxembourg, Canada, the Netherlands, Iceland, Israel, and Australia. Note too that several countries just to the left of New Zealand have estimated excess mortality barely different from that estimated for New Zealand.
Across the entire grouping of countries New Zealand still rates fairly well (there are many other things we might reasonably hope to be in the best quartile for but are not; this one we are), but as he notes for the three years to the end of 2022 even in New Zealand there does appear to have been positive excess mortality in the Covid era.
I have no particular point to make, but found both Fuhrer’s thread and Gibson’s note interesting notes, providing some useful context to thinking about the New Zealand experience. Since one still sees claims (including reportedly from David Seymour just a couple of days ago) that there have been no excess deaths in New Zealand over the Covid period, is it too much to hope that some media outlet or other might give some coverage to what appears to be careful work by, in particular, Gibson, a highly-regarded New Zealand academic?
The incoming Australian Labor government last year established an independent review of the Reserve Bank of Australia’s monetary policy functions, structures and performance. The review panel (chaired by a former Bank of Canada Deputy Governor) reported a few weeks ago and their full report is here. Periodic reviews of this sort aren’t uncommon, and are often triggered by episodes of discontent around the performance of the respective central bank (in New Zealand, the 2001 review conducted by Lars Svensson was an example).
There is no clear-cut single preferred way to organise policy functions that society (as represented by government and parliament) wishes to delegate decision-making responsibility to. That is true whether one thinks globally, or just of the subset of advanced economies that countries like New Zealand and Australia usually use as benchmarks or experiences/structures that might offer insight.
If this proposition is true generally, it is no less true of monetary policy specifically. And that shouldn’t really be surprising, including because monetary policy is really quite a recent thing. In New Zealand and Australia the transition to a market-based financial system and a floating exchange rate is not quite yet 40 years old, and even among larger economies floating exchange rates more generally date back only 50 years or so. Modern monetary policy is a cyclical management function (leaning against cyclical macroeconomic fluctuations subject to a constraint of keeping the inflation rate in check), and yet our data sets are really quite limited (since 1984/85 New Zealand has had 4 or 5 business cycles, and the creation of the euro means there are really only perhaps 15 or so advanced-country monetary policy agencies). We simply do not know with any degree of confidence that one form of monetary policy governance etc structure will produce better results over time than another. Instead we (all, including the RBA review panel) argue from small select samples, from specific historical incidents (where multiple influences are always likely to have been at work), and from the mental models we carry round (some likely to have achieved a professional consensus, others not).
None of which is to suggest that such reviews should not take place. Of course they should, and with good people and a government that is interested in good future structures (as distinct, say, from just being seen to having had the review – there were dimensions of the latter around the review then then New Zealand government commissioned from Lars Svensson) useful insights, outcomes, and reforms can often emerge. There will always be aspects of current practice or legislation than benefit from someone standing back and concluding that it is really time for an update, even if in practice the old arrangements were working tolerably adequately.
But one should also be cautious about expecting too much from any particular review or any particular set of reforms.
The current RBA model is not one anyone would prescribe today if they were setting up a central bank from scratch. A fair bit of the legislation dates back to the founding in 1959, including this
It has been interpreted, stretching language and concepts to a considerable extent, as encompassing the way monetary policy has been run for the last few decades, but really it was written for an age of (among other things) fixed exchange rates. No one would write it that way now.
And the governance? The Reserve Bank of Australia Board makes the monetary policy decisions (back in the day in practice the Treasurer did) and is much as constituted decades ago. The Governor, Deputy Governor, and the Secretary to the Treasury are ex officio members and there are six non-executive directors appointed by the Treasurer. The non-executive members have typically been (often quite prominent) business figures, but over recent decades it has been normal for one of the six to be a professional economist. It is a very unusual model these days for the conduct of monetary policy, although note that the sort of people appointed as non-executive directors is a matter of political choice (successive Treasurers) and I can’t see anything in the legislation that would have prevented six technical experts being appointed.
If the relevant bits of the legislation haven’t changed a lot over the decades, practice has. Monetary policy decisions are clearly made independently by the RBA, in pursuit of a target that is in practice agreed in advance with the Treasurer, they are announced transparently, there are minutes of a sort published, as well as the quarterly Statements on Monetary Policy. Senior managers appears before parliamentary committees and have fairly extensive and serious speech programmes. The RBA is a modern inflation targeting advanced country central bank, but operating on quite old legislative foundations. As an organisation, over the decades it has had considerable strengths, including typically a strong bench of very capable senior managers, and people coming up behind them. Successful organisations in many fields tend to promote mainly from within: that has been the RBA approach (and is very much in contrast, say, to the RBNZ). Note here that promoting from within is not itself a basis for a successful organisation, simply one feature that already successful organisations, continually refreshing themselves, often display.
I was an admirer of the RBA for a long time, and 20+ years ago when the Svensson review was underway (when I was both part of the small secretariat and a senior manager at the RB) thought that New Zealand should look to adopt elements of the structure and culture of the Reserve Bank of Australia. They tended to produce more stable outcomes, produce better research, communicate more effectively, and have a stronger sense of legitimacy than our “Governor as sole decisionmaker” system had achieved (or than Svensson’s preference, of a small internal decision-making committee (of which the position I then held would have been a member) was likely to be able to achieve. The RBA on the other hand saw us as somewhat strange, not always entirely fairly. I recall a time when Glenn Stevens as Assistant Governor and he came over to observe our monetary policy and forecasting week leading up to an MPS (shortly after we had started publishing forward interest rate projections), and he emerged from the week genuinely surprised that our approach was far less mechanical, nay mechanistic, than he had been led to expect. Or a visit from David Gruen, then head of research at the RBA, suggesting that the fact that our interest rates averaged higher than those in Australia suggested we had monetary policy consistently too tight (in fact prior to 2009 New Zealand inflation typically averaged in the top part of the target range).
Over recent decades, Australia has enjoyed a reasonable degree of macroeconomic stability (the review report includes a table showing the standard deviation of real GDP growth less than for any other country shown), this in any economy exposed to very big swings in the terms of trade. As noted above, the samples are small but there is nothing obvious to suggest that overall the Australian approach to monetary policy has delivered worse than other advanced country central banks. But there have been troubling episodes, notably including the one in the years running to Covid when Australian core inflation ran consistently well below target (much more so than anything seen at the time in other countries, including New Zealand where core inflation by then was getting close to the target midpoint). There are also more recent episodes of concern – about specifics of the RBA Covid response and latterly about the sharp rise in core inflation – but through that period it is perhaps hard to differentiate the RBA’s failure (underperformance) from that of a wide range of other advanced country central banks (themselves with a wide range of governance models).
This was one of the things that troubled me about the review report. The first substantive chapter is focused specifically on these recent episodes. It is easy to highlight areas where things could have been done better in (almost any) specific episode – and some of the material cited is pretty disconcerting – but that is almost certainly true of every central bank, and there is no attempt I saw in the report to illustrate that anything would have been very much different with a different governance/committee structure. We might hope it would have been, but the panel offers little reason (and realistically they couldn’t offer more) that it would have been. New Zealand, after all, has introduced a committee, and the panel notes favourably (too favourably) the expertise of its members relative to RBA external board members, but many or most of the same mistakes or weaknesses the panel highlight in Australia over the last three years were also evident in New Zealand – as far as we can tell, as less material has been released here than there, us not having had a recent external review and the Reserve Bank’s own review was largely defensive and unenlightening in nature). Should there have been a proper cost-benefit analysis, and serious questioning from the Board, before the RBA bond-buying programme was launched? No doubt (and the review report is properly critical about the absence, and the likely weak case) but there is no evidence of anything even slightly better in New Zealand. Or, as far as I’m aware, in any or many other advanced countries. Perhaps the RBA case was less excusable, since they started bond buying a lot later, rather than in the heat of the crisis, but the practical difference ends up being slight.
The review panel proposes a new model with these important features
monetary policy decisions would in future be made by a Monetary Policy Board (with a separate RBA governance board, and the existing Payment Systems Board),
the MPB would have nine members, the Governor, the Deputy Governor, the Secretary to the Treasury, and six expert non-executives appointed for non-renewable terms of five years, extendable for up to one year)
non-executive members would be expected to devote about one day a week to the role (around eight monetary policy decisions a year)
there would be a press conference for each decision,
votes would be disclosed but not attributable (ie a decision might be made 7:2, but the two would not be identified by name)
non-executive members would be expected to do at least one public engagement or speech a year,
non-executive vacancies would be advertised, but recommendations to the Treasurer (who would make the final appointments) would be by the Governor, the Deputy Governor and a third person (presumably to be chosen – altho by whom, Treasurer or the officials? – from time to time).
If you were starting from scratch, one could think of worse systems. But this proposal seems to have a number of weaknesses and reason to suspect that unless a strong political consensus developed early around making things work really differently (rather than differently in appearance) it is far less good a system than could have been devised. Even then, I would not be overly optimistic. More generally, my impression is that the report tends to underweight the relative importance of the Governor and very senior management to how central banks operate.
Starting with the small stuff, as the report notes it is highly unusual for the Secretary to the Treasury to be a full voting member of a central bank monetary policy decision-making body. It was one thing in 1959 – at that time New Zealand also had the Secretary to the Treasury as a full member of the (largely toothless) central bank board – but it is 2023. Other countries – including the UK and New Zealand – have preferred the model of a non-voting Treasury observer, which seems bit suited to (a) the desire to ensure at the highest levels that information flows freely between monetary and fiscal agencies) and (b) the Secretary’s own primary responsibilities and loyalties. The report proposes amending the legislation to make clear that the Secretary is voting his/her own judgement, but if so that tends to defeat the purpose of their place on the Board (being there solely ex officio), and in times of tension – and one should build system for resilience in tough times, not for when everyone is getting on fine and everything is going swimmingly – will likely complicate the Secretary’s own position (including as adviser to the Treasurer in holding MPB members to account for performance).
In general I am in favour of a model in which external members outnumber executives, but 6:3 in a nine person board doesn’t feel right (even if it parallels current numbers). 4:3, with the third executive being the Assistant Governor responsible for economic policy, seems a better size overall, and also more realistic about the ability of the system to continue to generate a steady stream of able people to fill (only) five year non-executive terms. And a 7 person committee is more likely to limit the risk of free-riding by individual non-executives.
It is difficult to see how a “day a week” model is likely to work IF the goal really were one having a powerful role, including as expert counterweight to staff, if non-executives were devoting only one day a week to the role. I am not aware of any precedents for such a small contribution, which seems to sit closer to the current RBA Board model (might such board members devote 2 days a month to the role, one to the meeting, one to the papers?) than to other advanced country MPCs. At the Bank of England MPC, probably still the best model, non-executives are paid for 3 days a week work, and at a rate that (least by academic standards would be a reasonable fulltime income). On a day a week model, not only is the actual amount of time any member can devote to RBA matters limited, but the remuneration would that for any non-retired person it would have to be just one part of the member’s employment/income. Most plausibly, they would be current academics, who might otherwise not spend a vast amount of time keeping track of data or of the literature in the specific fields relevant to central banking. We might assume that people will not be disbarred (as is NZ) for doing ongoing research in relevant fields, but even in Australia the numbers of such people are not limitless. One day a week looks like a recipe for an ongoing dominance of management and staff. Consistent with this, while the report suggests that externals should have direct access to staff, if they do not have dedicated analytical support staff of their own their ability to make a difference and shape what is in front of the MPB is likely to be limited. This is, incidentally, one argument for a quite different system – as in Sweden or the US – in which outsiders become full insiders while they are MPC members.
The appointment process is also a concern. One of the weaknesses of the New Zealand MPC system is that the Governor exercises considerable effective control on who serves on the MPC. A really good Governor would have a strong interest in promoting genuine diversity of view and real ongoing intellectual and policy challenge. Real world bureaucrats, running their own bureau, perhaps less so. No doubt there will be arguments about “fit” etc, but the value of outsiders is often in the extent to which they are willing to bring fresh thinking and not be easily deterred by management flannel and weight of paper. With a strong “third person”, perhaps it would work out okay, especially if a Treasurer was clearly committed to viewpoint diversity, challenge etc, but many potential “third persons” might be inclined just to defer to the perceived expertise of the Governor and Secretary.
Accountability does not appear to be a key element in the RBA reform proposal. That seems unfortunate – perhaps especially coming hard on the heels of the massive financial losses central bankers have run up and the scale of their inflation forecasting and policy mistake. If as a society we delegate great discretionary power to unelected officials – and that is what we do in MPCs – accountability is a key counterbalance, including in maintaining the long-term legitimacy of the model. At very least, MPB members should be required to have their named votes recorded and disclosed. Ideally – but it is probably only an ideal – people should be able to be removed from office for non-performance. In fact, one of the other weaknesses of the proposed single term model for externals is the complete absence of accountability. Their views don’t have to be disclosed, their votes don’t have to be disclosed, and since they can’t be reappointed, there is really no accountability at all. Lack of accountability doesn’t exactly encourage members to devote intense energies to getting things right. Some no doubt will, but it will be all too easy to defer to management and treat membership of the MPB as a prestige appointment (like being on the RBA Board now), this time narrowed down to being for economists, rather than a role in which one will make a difference and expect to be held to account.
As I said earlier, there is no one ideal structure. In the end, one is trying to combine technical expertise, experience, judgement, ability to communicate, and something around accountability to produce good policy outcomes taken in ways consistent with our open and democratic societies and under structures that are resilient to bad times and to bad people All in a field where uncertainty is pervasive.
Many of these requirements might well be met with no outsiders at all. You won’t see it highlighted in the review report but the Bank of Canada is one in which, formally and legally, the Governor himself wields the monetary policy powers (akin in that feature to the RBNZ system pre-2019). But in practice the BoC has built a strong internal culture and an effective system where a Governing Council of senior internal managers makes monetary policy decisions by consensus. I don’t think it is ideal – there is no individual accountability except (presumably) to the Governor – but the BoC has built partially compensating mechanisms with extensive research programmes, self-review programmes, and extensive engagement with academic and other wider communities. Indeed, the Bank of Canada model – which I do not champion – highlights just how important the quality of staff and internal processes are. It isn’t necessarily a problem if decisionmakers typically defer to staff and management expertise – in fact it is what you would expect in a normal corporate board – so long as those decisionmakers can continually assure themselves that staff and management have robust and resilient processes in place, including those that encourage, generate and accommodate, genuine diversity of view and openness to alternative perspectives. In that sort of context, some expert external MPC members can be very helpful (especially if they are familiar with, engaging with, perhaps contributing to) emerging literature, but they aren’t the only type of member who could add value. The willingness to actually ask the idiot question, and never to be content with management bluster, is valuable in any governance context. Thus, in an RBA context, one might wonder whether it is really worth having a whole new Board (especially when the RBA is not a “full service central bank” (doing prudential supervision)), when one could have left the RBA Board responsible for monetary policy but with a requirement say that several members should have directly relevant professional expertise. One could argue that being a board member, responsible for all the RBA functions and governance, might make for a person better able to contribute effectively as a monetary policy decisionmaker (and note that there is plenty of role for outside expert advisers anyway, and the report does suggest a more active macro research programme for Australia generally). And of course, in all our systems Ministers of Finance – rarely very expert at all – make major contentious economic policy decisions in climates of extreme uncertainty, drawing on expert advisers but rarely handing decision-making power to such experts.
Overall, I can’t help feeling that if the Australian government goes ahead and legislates all these changes, none of them (not all taken together) will matter quite as much as who gets appointed as Governor, and the sort of internal culture and people, the Governor (and his/her successors) build. That is a critical choice – in Australia, in New Zealand, probably anywhere – and is likely to far outweigh any potential difference that a few day-a-week academics, cycled through the decisionmaking system on five year terms, might make. A great Governor (and we can’t build systems that assume one) will build and maintain a culture that delivers most of what the review panel (often rightly) seems to be looking for.
This post has gone on long enough. It is about someone else’s country so why my interest? Two reasons I think. First, it is a significant report on a central bank in the midst of troubled times, and there are few of those yet. And second because the choices Australia makes are always likely to be an important backdrop to any future reforms in New Zealand. We have had extensive reforms, clearly designed to look different rather than be different, and any new government needs to look to do over quite a few of the aspects of the New Zealand model.
I was going to engage specifically with the AFR article last Friday by Ian Macfarlane, former RBA Governor, criticising the review (and I thank the two readers who sent me copies). Time and space is limited, so I won’t. It is worth reading, and he makes some fair points (some less so), but it is perhaps worth remembering that Macfarlane was Governor at the peak of the RBA’s past standing. The starting point now is less favourable.
Finally, one of the background papers for the review was commissioned from Professor Prasanna Gai at Auckland University (and ex BOE). Gai currently serves on the FMA board, but probably should be one of those considered for our MPC, but……he would be disqualified by our Governor and Board on the grounds of an ongoing active interest in areas the MPC would actually be responsible for. Anyway, his paper is quite a good read on international models around the governance of monetary policy, and he pulls few punches about the weaknesses of the New Zealand model.
On Monday I wrote about the MPC membership of Caroline Saunders, whose four-year term had expired on 2 April 2023 and who appeared to be continuing to serve only at the day-to-day pleasure of the Minister of Finance. The Reserve Bank’s website on Monday said that her term had expired, and there was no statement from the Reserve Bank or from the Minister of Finance to the effect that she had either been reappointed or told to go away. That all seemed less than desirable (fact, and lack of transparency).
As I noted in that post, it all seemed rather odd. The election is approaching and the Minister of Finance had already last year reappointed one member, Peter Harris, to a term expiring in October. Under the conventions around elections, no new appointment could be made by the current government when the new term would start smack in the middle of the election period. It seemed reasonable to expect that at some point the Minister would use the statutory power to extend Harris’s term for one final six month period into early next year (by law, having served two proper terms he cannot be reappointed).
But there had been nothing to stop the government reappointing Saunders for up to a further full four year term. And given the (on paper) importance of these MPC positions it seemed careless at best, and a bit disconcerting, that the government had not got on and made a permanent appointment (whether Saunders of someone else – although there had been no evidence of any open search process).
But this morning a piece on Business Desk drew my attention to the fact that decisions had been made on both Harris and Saunders. Naturally, one looks to the Minister of Finance Beehive page for an announcement – these are, after all (and in principle) powerful or influential macroeconomic policymakers at a time when inflation is miles outside the target range the MPC was supposed to be delivering – but there was nothing. There was no press release from the Reserve Bank either, but when I checked the Bank’s website page for the MPC sure enough, there it was:
and
The suggestion being, at least in the new Saunders description, that this might have happened a few weeks ago and neither the Minister nor the Bank had thought fit to tell us.
And so then I turned to the repository of all official appointment announcements, the Gazette, where there is this
which is all good and official, but not many macroeconomists and Reserve Bank watchers routinely read the Gazette.
I have no more to say about Harris specifically. He never should have been reappointed for a short term ending in election season, but given that he was an extension to early 2024 was pretty much inevitable (although a short period with a vacancy also wouldn’t have been a problem).
But what of Saunders? She could have been appointed for a full four year term but has been given only 15 months or so. Was she reluctant and had to have her arm twisted to take an extension. Was the Bank’s Board reluctant to recommend her? Was the Minister really not so keen (having, from the papers, first appointed her mainly for her sex). And why was none of its sorted out months ago well before her first time expired. It is hardly a ringing vote of confidence in a macro policymaker, amid a serious policy failure, to be reappointed for such a short period only, especially as the result of her appointment is the end of the external member terms (and all will have done two terms and have to go) are now bunched quite tightly: Harris finishes on 31 March next year, Saunders’ term finishes on 30 June, and the third member (Bob Buckle) has a term finishing on 31 March 2025.
If there were to be a change of government later this year, this combination looks opportune. I wrote a post last year about what a new government could and couldn’t do quickly if they were serious about overhauling the Bank and MPC. They can’t get rid of the Governor (who has just started a second, but final, five year term. But they would be able to (would have to) replace all three external MPC members in fairly short order. It would be an opportunity to insist on a quite different approach (eg the repeal of the blackball on anyone with ongoing macro analytical and research interests and output).
Which from a National Party perspective looks good of the current government. But one is still left wondering why Robertson left things this way. He could have reappointed Saunders for four years, or could have replaced her with someone he was comfortable with for a four year term. Instead, he is leaving the way open for the other side if the election does not go his way.
As I noted the other day, I have several OIA requests in around these appointments, which may (or may not) shed some light. They are perhaps unlikely to tell us why the Minister, the Governor, and the Board chair were so reluctant to let us know about the appointments of these (supposedly) powerful macro policymakers. Perhaps they’d have struggled to craft an honest press release on the achievements of these policymakers in their four years so far, when – for the first time in decades – inflation blasted well away from target, and none of them was prepared to front up with a good story about the inflation outcomes they’ve delivered, let alone the massive financial losses their choices resulted in for the taxpayer.
Perhaps some journalist might seek comment from Robertson, from Orr, from Quigley or from Saunders. Or perhaps even from Nicola Willis who no doubt expects to be in a position to make all those MPC appointments before too long.