Tossing away valuable emigration data

We had confirmation yesterday that departure cards are to be scrapped.    This was flagged by the Prime Minister a few months ago, and I wrote about the issue here.   Since then it appears that there has been no proper public consultative process.

As I noted in March

I’m sure airlines and airport operators hate the cards.  There have been prevous efforts to get rid of them.  They are, nonetheless, a core element of the data collections (in conjunction with arrivals cards) that give us some of the very best immigration data anywhere.  In a country with –  year in, year out – some of the very largest immigration, and emigration, flows anywhere in the advanced world.

We are told by the government that this brings us more into line with other countries

On Sunday, Lees-Galloway said the move would bring New Zealand into line with other countries, few of which had departure cards with the level of detail required by the New Zealand card.

(although even then we appear to overshooting in scrapping the cards completely).

But the statistical and related policy issues New Zealand grapples with are different from those in many other countries, most of whom don’t have big outflows of their own citizens, or big cyclical fluctuations in those flows.     Immigration of non-citizens is managed through the administrative approvals required to get a visa.  But people don’t need government approval to leave again and New Zealanders (of course) are free to come and go without any prior approval from the New Zealand government.

So departure cards captured the intentions of people coming and going.  Those stating that they intend to have changed countries for 12 months or more make up the permanent and long-term migration data that, for decades, has been a major and very timely indicator of what is going on, in a country with some of the largest swings in net migration of any country in the world.   It isn’t as perfect indicator by any means –  very timely ones rarely are – but it has consistently contained valuable information, especially around turning points.   And now the government proposes to scrap this data collection.

The Minister of Customs reckons the cards aren’t necessary

Customs Minister Meka Whaitiri said the cards were no longer needed for their original purpose – to account for all passengers crossing the New Zealand border.

“We have smarter systems now that capture passenger identity information and travel movement records electronically,” she said.

“Information captured by the departure cards is now mainly used for statistical purposes.

“Statistics NZ has developed an alternative way to produce migration and tourism statistics, based on actual movements rather than passengers’ stated intentions on the departure cards.”

I certainly agree that departure cards aren’t needed to capture the total flows, but it is the timely breakdown of that data that has been extensively used for decades.   And the operative word there is “timely”.  The new 12/16 method data –  looking back and seeing how long people were actually here/away – is better for long-term analytical purposes, but it is available only with a 17 month lag, whereas the departure card based data is available within weeks.  That difference matters, and it is worth bearing in mind that 17 months is almost half a parliamentary term.

We are told that Statistics New Zealand has “developed an alternative way to produce” the data, but we’ve seen no details of this, and there has been no consultative document made available for comment.  In  my earlier post I included this quote from SNZ claiming that in future estimates of the PLT breakdown

will be generated through a probabilistic predictive model of traveller type (ie short-term traveller, or long-term migrant), based on available characteristics of travellers. Such a model will provide a provisional estimate of migration, which we can then revise (if required) as sufficient time passes for us to apply the outcomes-based measure.

I commented then

I hope that they plan to rigorously evaluate the accuracy of such models, including when they’ve worked well and when they haven’t, and how well they capture the effects of policy changes, and that they expose their models and evaluation to external scrutiny before scrapping such a valuable source of hard data as the departure card.

But we have seen no sign of such an evaluation at all, and yet in a few months that data that have been used for decades will be discontinued, with  no ability to recreate it in future if the new models that are talked about prove not to have been very good.

Without seeing the models it is hard to comment on where they might go wrong.  But the key point is that statistical models often work fine when past behavioural patterns keep on as they were in the past, and they often fail when behaviour changes.   It is the behavioural changes that are often of most interest to the analyst, and it looks as though there will now be very long lags before we have the data to enable any such changes to be recognised.

I just heard Iain Lees-Galloway claiming on Radio NZ that future statistical information will be improved by scrapping the departure cards.  That seems very unlikely – essentially impossible, because you cannot really know the intentions of travellers other than by asking them, and intentions actually matter in this business.

I could add to the lament around official immigration statistics that there has still been very little progress in making available regular, timely, seasonally adjusted, accessible data from MBIE on visa approvals.  These are major economic and social data for New Zealand, which should be readily available almost instantly, including through SNZ’s Infoshare site.  There is no reason why immigration approvals data should not be at least as readily useable as, say, building approvals data. I know MBIE has a project underway to improve the situation, and make available an immigration data dashboard, but it seems to be moving very slowly –  it must be a year now since MBIE first told me about it, and it is months since the person doing the work invited me to provide comments on a prototype.  It is encouraging that something appears to be in the works, but in the meantime we limp on with inadequate, not user-friendly, administrative data, while the government simply abandons the best timely data we have on what people leaving New Zealand are planning to do.


The Fed looks to options in the next serious recession

I’ve written quite a bit recently about the apparent complacency of the Reserve Bank (and The Treasury and the Minister of Finance) around the ability of monetary policy to adequately cope with the next serious recession (here, here, and here).

Against that backdrop, it was interesting to see a substantive report of a recent discussion of exactly these sorts of issues in the minutes of a meeting a few weeks ago of the Federal Open Market Committee, the arm of the Federal Reserve that makes monetary policy decisions.   One might reasonably suggest that the discussion is happening several years later than it should have –  the problems and the limitations of conventional monetary policy have been apparent for some years now (especially in countries like the US that reached the effective lower bound in the last recession) – but better late than never.   And in the US context, some individual members of the FOMC have felt free to speak openly (eg here) on the issues and some possible policy responses.  It is the way open monetary policy committee systems can work.

Here are some extracts from the FOMC minutes

Monetary Policy Options at the Effective Lower Bound

The staff provided a briefing that summarized its analysis of the extent to which some of the Committee’s monetary policy tools could provide adequate policy accommodation if, in future economic downturns, the policy rate were again to become constrained by the effective lower bound (ELB). The staff examined simulations from the staff’s FRB/US model and various other economic models to assess the likelihood of the policy rate returning to the ELB and to evaluate how much additional policy accommodation could be delivered by the current toolkit.

Somewhat surprisingly, a footnote indicates that the staff modelling was still based on an effective lower bound of 12.5 basis points (the actual low the Fed went to for years after 2008), even though other countries have gone modestly negative (and our Reserve Bank has taken the view that the OCR could go to, say, 0.75 per cent.  There is no hint in the minutes of the FOMC discussing a lower effective floor, or what steps might be considered to lower it.

The staff’s analysis indicated that under various policy rules, including those prescribing aggressive reductions in the federal funds rate in response to adverse economic shocks, there was a meaningful risk that the ELB could bind sometime during the next decade.

Hardly surprising, given that the current Fed funds target is 1.75-2.0 per cent, and recessions seem to come round every decade or so.

In the discussion that followed the staff’s briefing, participants generally agreed that their current toolkit could provide significant accommodation but expressed concern about the potential limits on policy effectiveness stemming from the ELB. They viewed it as a matter of prudent planning to evaluate potential policy options in advance of such ELB events. Many participants commented on the monetary policy implications of the apparent secular decline in neutral real interest rates. That decline was viewed as likely driven by various factors, including slower trend growth of the labor force and productivity as well as increased demand for safe assets. In such circumstances, those participants saw monetary policy as having less scope than in the past to reduce the federal funds rate in response to negative shocks. Accordingly, in their view, spells at the ELB could become more frequent and protracted than in the past, consistent with the staff’s analysis. Moreover, the secular decline in interest rates was a global phenomenon, and a couple of participants emphasized that this decline increased the likelihood that the ELB could bind simultaneously in a number of countries. A few other participants raised the concern that frequent or extended ELB episodes could result in expectations for inflation that were below the Committee’s symmetric 2 percent objective, further limiting the scope for reductions in the federal funds rate to serve as a buffer for the economy and increasing the likelihood of ELB episodes.

There was clearly a range of views round the table, but it was encouraging to see some members highlight a variant of a point I’ve made here: because firms, households and market participants know that central banks will have relatively more limited firepower in the next recession, it may be harder to keep inflation expectations near the target, which may compound the challenges.

In the US, high government debt and large deficits are likely to be a constraint on the scope for active fiscal policy to complement monetary policy.

Fiscal policy was viewed as a potentially important tool in addressing a future economic downturn in which monetary policy was constrained by the ELB; however, countercyclical fiscal policy actions in the United States may be constrained by the high and rising level of federal government debt.

That might be on “technical” grounds –  genuine risks of bond market sell-offs –  or the wider political constraints that I highlighted in my post the other day, and which are likely to apply even in less-indebted countries like New Zealand.

Participants generally agreed that both forward guidance and balance sheet actions would be effective tools to use if the federal funds rate were to become constrained by the ELB. In the Addendum to the Policy Normalization Principles and Plans statement issued in June 2017, the Committee indicated that it would be prepared to use its full range of tools, including altering the size and composition of its balance sheet, if future economic conditions were to warrant a more accommodative monetary policy than can be achieved solely by reducing  the federal funds rate.  However, participants acknowledged that there may be limits to the effectiveness of these tools in addressing an ELB episode. They also emphasized that there was considerable uncertainty about the economic effects of these tools. Consistent with that view, a few participants noted that economic researchers had not yet reached a consensus about the effectiveness of unconventional policies. A number of participants indicated that there might be significant costs associated with the use of unconventional policies, and that these costs might limit, in particular, the extent to which the Committee should engage in large-scale asset purchases.

The uncertainties seem considerable.

The FOMC discussion concluded this way

While the Committee’s current toolkit was judged to be effective, participants agreed, as a matter of prudent planning, to discuss their policy options further and to broaden the discussion to include the evaluation of potential alternative policy strategies for addressing the ELB. Building on their discussions at previous meetings, participants suggested that a number of possible alternatives might be worth consideration and agreed to return to this topic at future meetings. Several participants indicated that it would be desirable to hold periodic and systematic reviews in which the Committee assessed the strengths and weaknesses of its current monetary policy framework.

As one reader noted in sending me the link to these minutes “refreshing (at least directionally)”,   which sounds about right to me.   The FOMC still seems quite a long way from really grappling with the severity of the next serious recession, when they (and all their major peer central banks) will have (it appears) little conventional monetary policy leeway, there is a great deal of uncertainty about the potential of unconventional instruments, and everyone –  especially in the financial markets –  will know it.

But it is to their credit that they are willing to have a discussion of this sort, publish fairly substantive minutes highlighting some important differences of emphasis and uncertainties, and are open to independent (named) perspectives from members in speeches.    That said, it should disconcert people that the FOMC is not already rather better prepared for the next serious recession –  like all central banks, their ability to anticipate the timing of the next such event is non-existent.

The Governor of the Reserve Bank has apparently been at the Jackson Hole retreat for central bankers this weekend.  Perhaps he could compare notes with his US counterparts and come back ready for some more open and substantive engagement on these issues in a New Zealand context (after all, in a day or two, he’ll have been in office for five months and we’ve still not had a substantive speech from him on any topic the Bank is responsible for).  Encouragingly, the Governor is reported as telling an interviewer in the margins of Jackson Hole that

The “biggest challenge” is to “get inflation to rise”

But it will be much more of a challenge in the next serious recession if people can’t be confident that central banks, here or abroad, can do all that needs to be done.  At present, no one can reasonably be that confident.  New Zealand can’t fix the world’s problems, but our policymakers can ensure our economy is well-positioned.  Not doing more just because others are still not doing enough should be no more excusable than when all too many countries drifted to the limits of conventional monetary policy at the end of the 1920s.  It wasn’t as if no one then was highlighting the risks.

I have a few other substantial commitments over the next two or three weeks, which means that blogging here may well be quite light for a while.


Political ructions and a better economic performance

Years ago we in New Zealand sometimes had the gruesome spectacle of governing party coups (and the like).  There was the failed (“Colonels’ coup”) attempt to oust Muldoon in 1980, the ructions that led to Lange’s departure in 1988 and then (unelected) Palmer’s a year later, and the ousting of Jim Bolger in late 1997, and then the break-up of the governing coalition a year later.  But you have to be a certain age to remember any, let alone all, of those.

In Australia, by contrast they’ve been two a penny in the last decade.   It isn’t exactly the rate at which Italian governments used to turn over until relatively recently, or French governments in the ill-fated Fourth Republic (22 prime ministerships in 12 years) but it is quite extraordinary by Anglo country standards.  Has there ever been a time previously –  in New Zealand, the UK, Ireland, Canada, Australia – when four people in a row who successfully led their party to an election victory –  limping home in Turnbull’s and Gillard’s cases –  didn’t complete the subsequent (three years) term?  Perhaps Turnbull will, in fact, limp on, but even if he does it is hard to see to what end.

A mere three years ago, when Turnbull ousted Abbott I wrote a post about the strange phenomenon then gripping the Australian centre-right: New Zealand envy.  Here was Turnbull speaking just after his coup.

“John Key has been able to achieve very significant economic reforms in New Zealand by doing just that, by taking on and explaining complex issues and then making the case for them. And I, that is certainly something that I believe we should do and Julie and I are very keen to do that again.”

As I noted, it was very hard to think of such “very significant economic reforms”.  Moreover, as I illustrated in that post, New Zealand seemed to have drifted a bit further behind Australia economically over the previous few years.

I noticed Julia Gillard yesterday engaging in a bit of New Zealand envy, suggesting (probably tongue in cheek) that Australians might well consider moving to New Zealand.  Only, surely, if they wanted to be colder as well as poorer.  Recall that Australian incomes are far higher than those in New Zealand, the main reason why for the last 40 years so many New Zealanders (net) have gone to Australia, and so few Australians have come to New Zealand.   Even just since 1991, a net 470.000 New Zealanders have gone to Australia, and only 49000 (net) other passport holders have come to New Zealand from Australia.

And, like it or not, political instability (including ructions in successive ruling parties) doesn’t seem to have been a material factor impairing economic performance.  That was so for France and Italy after the war, and if –  as I illustrated last week –  if Australia’s economic performance hasn’t been great, given its resource bounty, it has still been better than New Zealand’s.

Here I’m going to focus on the period since the end of 2007, for two reasons.  First, it was about the time the Rudd government took office which –  although it wasn’t apparent at the time –  was the beginning of the era of Australian political instability.  And, second, because it is just prior to the recession of 2008/09.  In New Zealand, Labour was still in office for most of 2008, but comparisons from troughs of recessions are rarely very meaningful (and if Australia didn’t have a recession in the sense of a couple of negative quarters of GDP, it still had a big fall in income measures –  as commodity prices fell –  and a material rise in the unemployment rate).

First, there is an important background feature that governments don’t have any material influence over; the terms of trade.

aus nz tot

Australia’s terms of trade have been much more volatile than those of New Zealand over the last decade or so, but taken over the whole period there hasn’t been that much difference.  Both countries have benefited from the movement in world prices to about the same extent (Australia had also had a substantial lift from about 2002, not mirrored in the New Zealand numbers).

Then there are the headline national accounts comparisons: real GDP per capita.

real gdp pc aus nz

On that measure, at the end of the period there has been no change in the relative position of the two economies  (although the gap between the two lines for much of the period is lost output that is never likely to be got back).  No sign of any catch-up, although also no falling further behind either.

The terms of trade can make a material difference to economic wellbeing, and terms of trade gains are not directly reflected in the real GDP numbers (although the indirect effects – any increases in consumption or investment etc in response –  are there).   But on this occasion we don’t need to worry too much about that point because, as the first chart illustrates, over the full period both countries’ terms of trade have risen by about the same amount.

But if real GDP per capita in the two countries has grown by about the same percentage in each country over the last decade, there has been a really big difference in the composition of that growth, and not one that is positive for New Zealand in the longer term.   I have shown the labour productivity chart previously, but here it is again anyway.

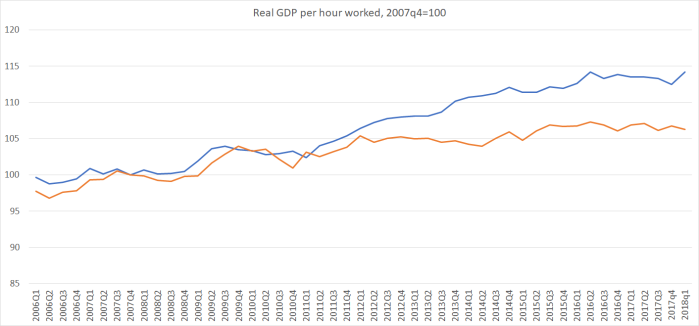
aus nz rgdp phw

Some years we match Australian productivity growth, and occasionally even exceed it, but over the period since the end of 2007, labour productivity growth in Australia has exceeded that in New Zealand by about 8 percentage points.  That is a lot, especially when New Zealand was starting from so far behind.

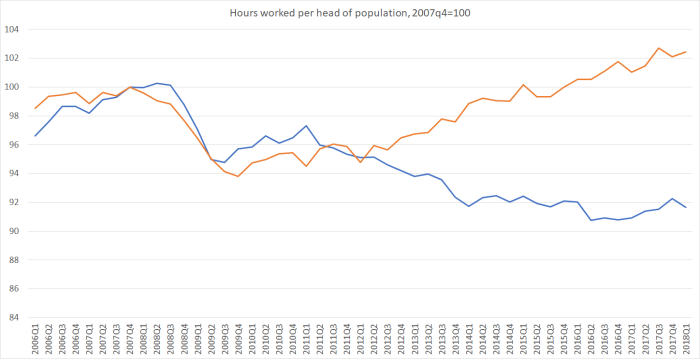
And here is a large component of the difference.  I’ve set hours worked per head of population equal to 100 in both countries in 2007q4, and shown how that measure has changed in each country since then.

hours worked per head

It looks a lot like that old story: New Zealand (in orange) more or less manages to “keep up” (not see real GDP per capita drop further behind) simply by working more hours.  That is no sustainable route to greater national prosperity, especially when hours worked per capita are already quite high by advanced country standards.

Of course, some will probably want to claim this as some sort of New Zealand success story –  “look at all those people we have in work etc etc”.   But working more hours isn’t some “good thing” for its own sake, and the unemployment rate is the best summary measure of whether there is slack in the labour market.   If Australia’s unemployment rate had increased materially more than New Zealand’s then one probably could tell a (cyclical) New Zealand success story.  But here are the two unemployment rates.

nz aus U rates

Most people reckon Australia’s NAIRU is higher than New Zealand’s (and that is a long-term negative for Australia, and the wellbeing of Australians), but that was so before the crisis too. In fact, the gap between New Zealand and Australian unemployment rates now (around 1 per cent) is exactly the same as the gap at the end of 2007.   Just as is the case in New Zealand, most Australian residents who actually want jobs have them.  So I don’t count the increase in hours worked here as any sort of mark of success.

None of this –  higher productivity growth in Australia in particular –  should be any great surprise.  If one looks across the OECD’s Going for Growth structural indicators (for example) the two countries score about as well, or poorly (on some indicators), as each other.  But Australia has seen come on stream huge new mineral production –  a new endowment they could tap –  and we’ve had nothing comparable (to what extent that is because similar resources aren’t there, or because policy choices prevent them being utilised is a topic for another day).  But with no other new opportunities apparent to match the new minerals –  and see the shrinkage in our foreign trade shares – our structural position relative to Australia has weakened further.

I’m not going to illustrate housing markets –  in any case mostly a state matter in Australia as I understand it –  but in both countries the best that can be said is that the outcomes, for ordinary people, have been lamentable, and disgraceful.

There is an argument sometimes mounted that the earthquakes were a significant drag that Australia didn’t have to face.  In terms of the existing stock of wealth, there is some truth in that (even recognising that much of the loss was reinsured abroad).  And the rebuild process –  which peaked several years ago now –  did take resources that couldn’t be used for other things.   But (a) on official estimates we had utilised capacity (output gap and unemployment gap) for most of the time, and (b) if there really were abundant international opportunities for firms here, bidding for capital and labour resources, we might have expected to see persistent upward pressure on our interest rates relative to those in the rest of the world, and associated inflation pressures.  We’ve not seen the inflation pressures at all (any more than in Australia) and the upward pressure on our interest rates relative to the rest of world occurred only while our Reserve Bank was messing up –  driving up the OCR before having to about-face and more than fully reverse themselves.

There isn’t a choice between chronic political infighting (of the Australian sort) and improved prosperity, but if there were I reckon I’d take the prosperity.  As it is, at least relative to New Zealand, Australia looks to have had both.  If there is an understandable tendency to rather look down on the political machinations, we should at least pause to ponder (again) our own long – and continuing – relative economic decline.

And now back to watching the gruesome spectacle across the Tasman.


Paying MPs

So poor have the economic outcomes been in New Zealand for decades –  that slippage from number one or two, to an also-ran lost well down the rankings –  that one could probably mount a reasonable case for asking all those who’ve been MPs –  or ministers at least –  for a refund on the salaries they’ve been paid.  The honourable ones among them should really hang their heads in shame.

But setting aside that perhaps unreasonable hankering, what to make of the latest angst over salaries for our members of Parliament?

First, what has become of the process doesn’t reflect well on either the previous government or the current government.  Both government seem to have panicked in the face of numbers that might have made awkward headlines (but typically involve small changes, the overall effect of which –  including any anomalies –  are likely to wash out over a period of several years), and rushed for crude interventions (freezes, legislation under urgency).  Take the current government as illustrative, they knew the previous government had passed legislation tying increases in MPs pay to public sector pay, and they knew on coming into office that public sector pay was going to be one of the pressure points they would face.   So why, if they weren’t willing to live with the current formula, didn’t they put in place a review (yes, another) as soon as they took office, 10 months ago.  Had they done so, any proposed changes could have extensively consulted on, perhaps even legislated by now.

Second, there is no way to put the setting of MPs salaries at a total remove from the political process.  The enabling legislation has to be passed by Parliament itself, and what is passed by Parliament can be amended by Parliament, even retrospectively.   But we should be looking to develop and maintain systems, and conventions, by which the main parties (a) agree on the rules, and (b) agree to live with the results.  It shouldn’t be that hard –  Parliament doesn’t remove judges who rule against them, and mostly doesn’t even legislate to overturn specific decisions the political process doesn’t like.   All sorts of things embarrass MPs and ministers, but when our system works well, it is just something they have to live with.  I guess it must be tempting to play politics with MPs pay, but it isn’t in the interests of our system of government in the longer run to do so.  It also isn’t in the interests of the systems to have MPs or ministers choosing not to take increases.  Nothing stops them donating to charity, but let their good deeds be done in secret, not as political plays.

There is an article in today’s Dominion-Post by Stacey Kirk taking a cursory look at how the pay of our MPs compares with that in the other Anglo countries (all of whom have considerably higher average per capita GDP than New Zealand does).

The superficial comparisons tend to suggest that our MPs do rather well.  But those comparisons don’t mean much for several reasons:

  • the conversions in the article are done at current market exchange rates, but New Zealand’s exchange rate is generally regarded as being structurally overvalued.  On such comparisons, all wage rates in New Zealand will be flattered.
  • as the article notes in passing, the comparisons she does only cover base salaries. It isn’t generally true that “perks and supplements” are “hidden” (her word), but they can be challenging for outsiders to fully track down, and put a price on.  Defined benefit pensions, for example (still provided in the US and UK for example, but not here), can be extremely valuable in a low yield environment.
  • the comparisons don’t take any account of post-political opportunities which in some countries (notably the US) can be very lucrative (arguably corruptly so).

There is no unalterably right or wrong answer to how much we should pay MPs (absolutely or relative to prevailing incomes in the economy).  Presumably no one favours the old UK (pre 20th century) system in which MPs were not paid at all.  The presumption was that MPs would have another income, which –  of necessity –  meant that the only people who could become MPs were those who did.   If it didn’t necessarily lead to much actual corruption in that historical context, it would certainly open the way for corruption if adopted today.  And I don’t suppose anyone much would support a system in which MPs were all paid $1 million a year: it might attract some really able people, but you’d also be pretty sure that most people competing for the role would be in it for the money.     Putting my cards on the table, I’m sure I wouldn’t want to pay MPs and experienced teachers the same, no matter how good the teacher (a principal of a decent-sized school might be another matter).

It pays to stand back and think about what we should expect from MPs.  There are only 120 of them ( almost a quarter of whom currently serve in the executive), with primary responsibility for scrutinising and holding to account the vast establishment that is the New Zealand government (myriad public agencies and departments, endless regulations and related instruments, and lots of new proposed legislation).  They aren’t the only bulwarks to be sure, but they are the ones with the formal powers and responsibilities –  the ability to summon public servants before select committtees, to demand answers from ministers in Parliament, to insist on changes in legislation, even on occasion to disallow regulatory instruments.  Details matter, context matters, principles matter.   The responsibilities range very broadly (not to mention the hours, for a job decently done).  These aren’t, or shouldn’t be, roles for some amiable person fresh off the street.  And, even in a small country, the public sector is formidably well-staffed, and well-resourced, relative to MPs.

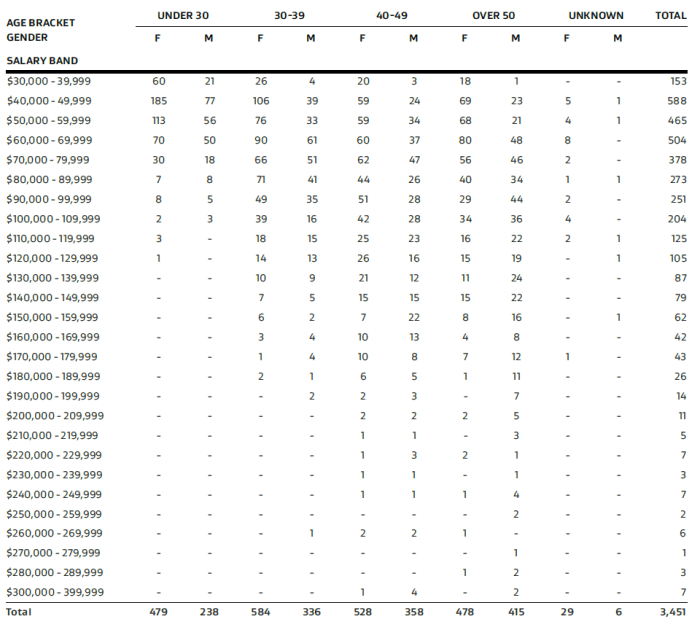
Take, for example, our largest government department, MBIE.  I went to their annual report and found the table of salaries.

MBIE salaries

Perhaps you could treat that very top-tier (chief executive and deputy CEs) as the equivalent of Cabinet ministers.  But this one agency also has 45 people earning between $200000 and $300000 per annum.  These will probably mostly be third-tier managers.    Some of you might be inclined to object that these people are themselves overpaid, but I rather doubt it for what we should be expecting from the sort of people who should fill these sorts of roles.    Of course, they are well above average salaries –  we expect much more than average sorts of skills from people filling them.

And these are sort of people whose work we expect MPs to challenge/scrutinise etc (without any of the sort of staff resources these public sector senior managers have at their disposal).

So I don’t have a sense at all that our MPs are overpaid, and wouldn’t have begrudged them a pay rise this year, or any year (in which private wages were rising).    There are perhaps anomalies in the sense that a new 25 year old MP gets the same as an immensely-experienced former Cabinet minister, but there is no easy way round that feature.  And we should steer well clear of the absurd suggestion from the far-left leader of the Greens, who proposed that MPs should get only the same dollar increase as in the average wage –  thus compressing the relative margins between MPs and the rest every future year for ever (well, unless we have a burst of deflation).

I’m not altogether persuaded by the story that able people won’t go into politics because the pay is too low.  No doubt it is so for some. For others, it will be the hours, the separation from family, the public spotlight or whatever. But we should be careful not to increase the risks of such a system, in some self-reinforcing spiral, in which we complain of dud MPs, and then set a reward structure which only increases the probability of disproportionately getting such people in future.  Ours is a thin democracy, with few effective protections against executive over-reach and the like.  We should be looking for very able people to fill select committee positions –  not just as a passage towards promotion, but as a vital role in and of itself.  I’ve argued previously we should provide more resources to members and select committees –  the public goods of good government need to be properly funded, not skimped on –  but while we consistently refuse to do that the calibre of people serving as MPs is all the more important.


If pushed on the New Zealand situation, the person I suspect could be overpaid in our system is the Prime Minister.  It is a big job to be sure, but it really isn’t one people pursue for the money.  No one we would want to be Prime Minister is likely to look, before entering Parliament, at the PM’s salary to decide if they can support a family on it.  As Stacey Kirk’s article points out, on the (crude) international comparisons we appear to pay our Prime Minister quite generously

Data released by international consultancy group IG in May showed Ardern was the fifth highest paid leader in a comparison of 32 members of the Organisation for Economic Cooperation and Development (OECD).

In a study of the pay gap between world leaders and average citizens, Ardern ranked third, earning 8.63 times the average New Zealand wage.

Post-politics opportunities are probably better for many of the heads of government in these other countries –  Bill Clinton or Barack Obama make their money from being President once out of office. Or Gerhard Schroder or Tony Blair.   That isn’t a model we could, or should want to, emulate. I’d rather pay the Prime Minister a decent salary, and expect a considerable degree of self-discipline and restraint once out of office.

As a bonus, perhaps they could take the steps need to reverse the decades of economic underperformance, that have depressed the earnings of most New Zealanders (and led so many to leave altogether).

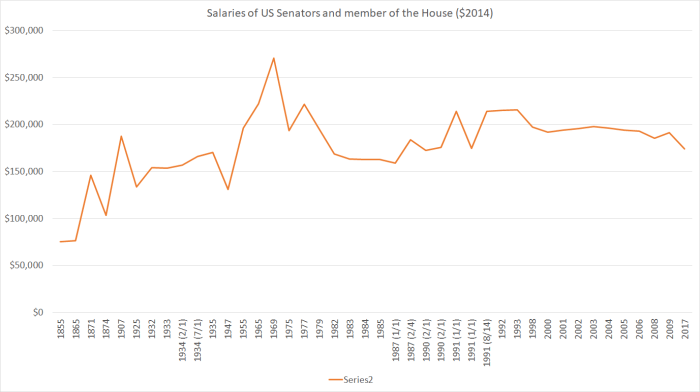
PS.   In digging around before writing this post, I stumbled on some data on the inflation-adjusted salaries of US Senators and members of the House of Representatives

us senator salaries

The dates aren’t evenly spaced, but remarkably there has been no growth in real salaries since the 1950s (and no growth in nominal salaries since 2009).  Real per capita GDP in the US today is about three times what it was in the mid 1950s.   That, at least, seems like a benchmark of badness, and something to avoid –  so bad is the US system, the members get no accommodation allowances, and so not a few sleep in their offices while in Washington, and look to opportunities to cash out in new roles in K Street.

Options for the next serious recession: fiscal policy

I’ve run various posts over the last few years urging the authorities (Reserve Bank, Treasury, and the Minister of Finance) to get better prepared for the next serious recession (and lamenting the relative inaction on this front in other countries too, many of whom are worse-positioned than New Zealand is).

As a reminder, we went into the last recession with the OCR at 8.25 per cent, while the OCR now –  years into a growth phase, with resources (on official assessments) fairly full-employed –  is 1.75 per cent.  In that last recession, the Reserve Bank cut interest rates a long way, the exchange rate fell a long way, there was really large fiscal stimulus cutting in as the recession deepened, and there were lots of other interventions (guarantee scheme, special liquidity provisions) and it was still as severe as any New Zealand recession for decades, and took years to fully recover from (on official output and unemployment gap estimates perhaps seven or eight years).   Lives were blighted, in some cases permanently, in an event where there were no material constraints on the freedom of action of the New Zealand authorities.  In fact, our Reserve Bank cut the OCR (over 2008/09) by more than any other advanced country central bank.

Next time, whenever it is, it seems very unlikely that the Reserve Bank will have that degree of freedom, particularly around monetary policy.  On current policies and practices around bank notes, it seems unlikely that the OCR could be usefully cut below about -0.75 per cent.  Beyond that point, most of the action would be in the form of people shifting from bank deposits etc to physical currency, rather than buffering the economic downturn.

Our Reserve Bank has long appeared disconcertingly complacent about this issue/risk.  The latest example was comments by the new Governor and his longserving chief economist following the latest Monetary Policy Statement.    They talk blithely about the unconventional policy options other countries have used, but never confront the fact that almost no advanced country could have been comfortable with the speed of the bounceback from the last recession.   Output and unemployment gaps of eight or nine years (the OECD’s estimate for advanced countries as a whole) aren’t normal and shouldn’t be acceptable.

Quite why the Reserve Bank is so complacent is something one can debate.   My hypothesis is that it is some mix of assuming we will never face the problem (recall that they have spent years hankering to get the OCR back up again) and of noting that other people/countries will most likely face the problem before New Zealand does.   They also like to remind us that New Zealand has a floating exchange rate as if this somehow differentiates us (as a reminder so do Australia, Canada, Norway, Sweden, the US, the UK, Japan, Korea, Israel, and even the euro-area as a whole).  Whatever the explanation,  robust contingency planning, and building resilience into the system, is what we should be expecting from the Reserve Bank (and Treasury).  There is no sign of it happening.  Meanwhile, the Governor plays politics in areas (eg here and here) that really aren’t his responsibility.

In my post on Saturday, I touched again on the desirability of doing something –  specific and early, consulted on and well-signalled –  about removing the effective lower bound on nominal interest rates.   That would tackle the issue at source.    Monetary policy has been the primary stabilisation tool for decades for good reasons.  Among other things, it is well-understood and there is a fair degree of (political and economic) consensus around the use of the tool.  And confidence that the tool is at hand in turn proves (somewhat) self-stabilising, because people expect –  and typically get – a strong monetary policy response.

Perhaps the other reason why authorities –  perhaps especially in New Zealand – have been so complacent is the view that “never mind, if monetary policy is hamstrung there is always fiscal policy”.  After all, by international standards, public debt here is low (on an internationally comparable measure from the OECD, general government net financial liabilities, about 1 per cent of GDP, which puts us in the lower quartile –  less indebted – among OECD countries.)

The implicit view appears to be that, with such modest levels of debt, if and when there is another serious recession, New Zealand governments can simply spend (or cut taxes) “whatever it takes” to get economic activity back on course again.   After all, the upper quartile of OECD countries have net general government liabilities in excess of 80 per cent of GDP.

I’m sceptical for a variety of reasons.

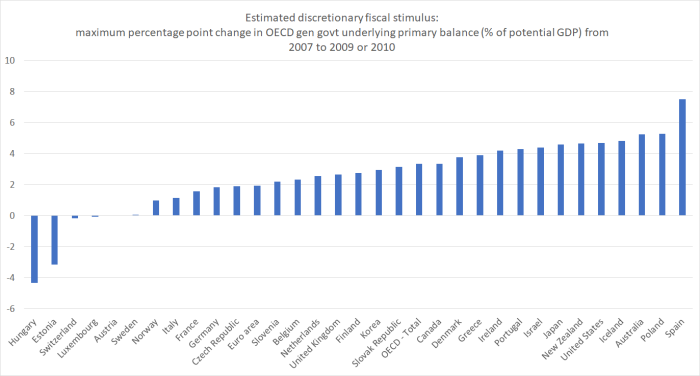
One of them is the experience of the last recession.  For this, I had a look at the OECD data on the underlying general government primary balance as a per cent of potential GDP:

  • general government = all levels of government
  • underlying = cyclically-adjusted (ie removing the impact of the fluctuating business cycle on revenue (mostly), and adjusted for identified one-offs (eg recapitalisations of banking systems)
  • primary balance =  excluding financing costs, so that comparisons aren’t affected by changes in interest rates themselves
  • as a per cent of potential GDP =  so that a temporary collapse in actual GDP doesn’t muddy the comparison

The numbers aren’t perfect, and there are inevitable approximations, but they are the best cross-country data we have.  Changes in this balance measure are a reasonable measure of discretionary fiscal policy.

Here is how those underlying primary balances changed from 2007 (just prior to the recession) over the following two or three years.  I’ve taken the largest change I could find, and in every case that was over either two years to 2009, or over three years to 2010.

fisc stimulus

Some countries (Hungary, Estonia) were engaged in severe fiscal consolidation from the start.  Several others experienced almost no change in their structural fiscal balances.

Quite a few countries saw 5 percentage point shifts in their underlying fiscal balances.   Spain –  a country with no control over its domestic interest rates –  is recorded as having gone well beyond that.  I don’t know much about the specifics of Spain, but for those who are upbeat about the potential scope of discretionary fiscal policy I’d take it with at least a pinch of salt – on the OECD numbers, the Spanish primary deficit dropped again quite sharply the next year (and Spanish unemployment didn’t peak until several years later).

Note that both Australia and New Zealand are towards the right-hand end of that chart.  In Australia’s case, most of the movement resulted from deliberate counter-cyclical use of fiscal policy (the Kevin Rudd stimulus plans).  In New Zealand, by contrast, the change in the underlying fiscal position was almost entirely the result of discretionary fiscal commitments made by Labour government at a time when Treasury official forecasts did not envisage a recession at all.  From a narrow counter-cyclical perspective, those measure might have been fortuitous, but they were not deliberate discretionary counter-cyclical fiscal policy measures.  In fact, at the time they were seen in some quarters as exacerbating pressure on the exchange rate, and limiting the scope of any interest rate reductions.

Perhaps it is worth stressing again that in not one of the OECD countries did the reduction in structural fiscal surpluses (expansion in deficits) last more than two years.  In every single country, by 2011 structural fiscal policy (on this measure) had moved –  sometimes modestly, sometimes quite sharply –  into consolidation phase.  In most countries, either conventional monetary policy limits had been reached or (as in individual euro area countries) there was no scope for conventional monetary policy.  And it was to be years before output and unemployment gaps closed in most of these countries.

What is my point?   Simply, that it looks as though the political limits of discretionary fiscal stimulus were reached quite quickly, even in countries where there was no market pressure (any of the established floating exchange rate countries other than Iceland), and even though the economic rebound in most was anaemic at best.   That is why so many countries needed more conventional monetary capacity than in fact they had (and QE in various forms was not much of a substitute).

The OECD table on underlying primary balances only has data going back a few decades.  No doubt experiences in wartime were rather different –  in those circumstances huge shares of the nation’s resources can be marshalled and deployed in ways which (incidentially) stimuluate demand and activity.  But looking across the OECD countries over several decades, I couldn’t any examples of discretionary fiscal policy being used as a counter-cyclical tool materially more aggressively than happened over 2008 to 2010.  In Japan, for example, the structural fiscal balance worsened by about 6 percentage points over seven years after 1989.

So from revealed behaviour patterns, I’m sceptical as to just how much practical capacity there is for fiscal policy to do much, and for long, in the next serious recession, even in modestly-indebted New Zealand.    The limits aren’t technical –  they mostly weren’t last time –  but political.   Perhaps people will push back and run some argument along the lines of “oh, but we’ve learnt the lessons of unnecessary premature austerity last time round”.     To which my response would be along the lines of “show me some evidence, or reason to believe that things would, or even should, be much different next time”.   When – outside wartime –  has it ever happened?  And what about our political systems makes you comfortable that it is likely to happen next time?     We could probably run large structural deficits for a year or two, but pretty quickly the pressure is likely to mount to begin reining things back in again (especially if, for example, the next recession is accompanied by heavy mark-to-market losses on government investments –  eg NZSF).

And recall that here in New Zealand we had almost as much fiscal stimulus last time as any country, and even supported by huge cuts in interest rates (and without a home-grown financial crisis), we had a nasty recession (even a double-dip in 2010) from which it took ages to recover.

And all of this is without even examining how effective realistic fiscal policy is likely to be.    The easiest fiscal stimulus is a tax cut (or even a lump sum cash handout).   You can do clever ones, like the UK temporary cut in GST, which not only put more money in people’s pockets, but actively encouraged them to shift consumption forward –  only to then create problems as the deadline for raising the value-added tax rate loomed.   But putting money in people’s pocket –  in a recession, and often explicitly temporarily –  doesn’t guarantee they spend much of it.  The most effective demand-stimulating fiscal policy (supply side measures are another issue –  but lets just agree that deep cuts in company tax and related rates will not happen in the depths of a recession) is direct government purchases of goods and services.  Most talked of is government capital expenditure, infrastructure and all that.

But, approve or otherwise, no government has a reserve list of projects, designed and consented, just waiting to get starting the moment it is apparent the next deep recession in upon us (that moment usually being several months after the recession has begun).  It is almost certainly politically untenable for them to do so –  if the project is so good, so the argument will run, why not do it when times are good?  And so realistic government fiscal stimulus through the capital expenditure side will take months and years (more probably the latter) to even begin to get underway.   Faced with the actual physical destruction in Christchurch, look how long it took for major reconstruction to get underway.

What of income tax cuts?   Either the cuts are focused on those who pay the most taxes (in which case there is quickly one form of political pushback) or perhaps they take the form of a tax credit paid as a lump sum to everyone (in which case there is likely to be pushback of another political type –  ideas around “everyone becoming a welfare beneficiary).  I’m not attempting to defend either type of response, just to anticipate the risks.

By contrast, monetary policy –  the OCR –  can be adjusted almost immediately, and often begins to have an effect before the central bank even announces its formal decision (market expectations and all that).  And if monetary policy changes don’t affect everyone equally, they affect the entire country –  a borrower/saver/exporter in Invercargill just as their counterparts in Auckland.  In the line from a US Fed governor, monetary policy gets in “all the cracks” (although he was contrasting it with regulatory interventions).  Government capital expenditure is, by its nature, very specific in location.  There probably isn’t a natural backlog of major (useful) capital projects in Invercargill or Dunedin.

I’m not saying fiscal policy has no useful place in the stabilisation toolkit –  although my prior is that it is better-oriented towards the medium-term, with the automatic stabilisers allowed to work fully –  but that we should be very cautious about expecting that it is any sort of adequate substitute for monetary policy in the real world of politics, distrust of governments and so on, in which we actually dwell.    It is well past time for the Reserve Bank and the Treasury, led by the Minister of Finance, to be taking open steps towards ensuring that New Zealand has the conventional monetary policy capacity it would need in any new serious recession.


The Minister of Finance champions an economic strategy

Longstanding readers will know that I was pretty critical of the previous government for the utter absence of any sign of a set of economic policies that might have begun to reverse the decades of relative economic decline.  Worse, they and their acolytes too often seemed to make up stories about how well things were going when the data pretty clearly pointed in the opposite direction.   I’m not sure I’d be quite as harsh as Kerry McDonald and Don Brash, who recently gave the Key-English government an overall score of 0/10, but I’d be close, especially around productivity (and also around housing).

What has become increasingly disconcerting is that the new government –  now almost a third of the way through its term –  also has no credible ideas about reversing the decline and little interest either.  They seem increasingly reduced to making stuff up as well, and trotting out the same lines again and again without any sign of a really understanding the challenge, without any sign of a compelling analytical framework, and without any reason to think that the policies they talk of will make any material (helpful) difference.

I woke this morning to the news that the Minister of Finance had an op-ed in the Herald explaining how the government was going to restore our economic fortunes.   With suitably low expectations, I tracked it down.   Even with low expectations, I was struck by how weak it was, and left wondering why the Minister and his PR team thought the article was a good idea.

The Minister begins thus

The coalition Government is helping business modernise our economy to be fit for purpose for the 21st century.

Presumably he is aware that one sixth of the 21st century has already gone?  And that his party was in government for half that time?  But let that pass: as rhetoric it might be empty, but it is probably harmless.

This means being smarter in how we work, lifting the value of what we produce and export, supporting the environment, planning for future generations and giving everyone a fair shot at success. It means making sure that all hard-working Kiwis share in the rewards of economic growth.

All of which is hard to argue with, but isn’t exactly a) specific, or (b) new.  I keep a copy of National’s 1975 election manifesto by my desk, and flicking through it –  43 years on now – I think I spotted all those points (actually, in light of Eugenie Sage’s announcement on Sunday, I also found a pledge to “discourage all forms of environmental pollution and encourage the recycling of materials.  We will place a levy on difficult-to-dispose-of products’).   Labour’s 1972 manifesto, or its 1984 one, or its 1999 one probably had them all too.

Most New Zealanders know we cannot go on relying on a volatile mix of population growth, an overheated housing market buoyed by speculation, and exporting raw commodities as our growth drivers.

Quite a bit of that was in the 1975 manifesto too.    They are old lines, each trotted out by politicians of either main party for decades as the symptoms presented.     Not always even very accurately – does anyone actually think an “overheated housing market buoyed by speculation” added to national prosperity?   And not with much sense that the speaker had any sort of robust model of the New Zealand economy.  Let alone serious policies in response: for example, if this paragraph is to be believed, the current government is apparently uneasy about rapid population growth, but continues to run the same immigration policy as both its predecessor governments for the last 20 years.

And despite all this, a few sentences later the Minister of Finance tries to assert that

the fundamentals fuelling the economy are strong

Quite which “fundamentals” he has in mind – presumably not those in the previous quote (above) –  isn’t clear.  In fact, all he offers in support of his view is

Last week, the Reserve Bank said growth will still average 3 per cent over the next three years. And Mainfreight managing director Don Braid said recently: “I think the business environment is good right now.”

A government agency whose forecasts seem to command increasing scepticism among other forecasters, and one prominent business person.  Perhaps you are persuaded.  I’m not.

But finally we get to some of the things the government is promising.  First, what the Minister presents as a key component

Our plan to become more productive is built on getting our infrastructure sorted. This year, and for the next 10 years, we will invest more than $4 billion getting roads, rail and coastal shipping humming. We are sorting out Auckland’s congestion to save the $1b loss in productivity it causes each year.

Haven’t we heard these infrastructure stories (“we are taking steps to clear the backlog”) for 15 years now?  But even if they are doing everything well in this area, look at the number in the final sentence.   $1 billion –  assuming the estimate is robust –  is a great deal of money to you and me individually, but this is an economy with an annual GDP of $280 billion.  On the Minister’s own numbers, fixing congestion would lift GDP by about 0.36 per cent.  It would be very welcome, but it is tiny relative to the scale of the economic underperformance: with no productivity growth at all for the last three years, it might take 10 similar initiatives to just reverse the further slippage (relative to other countries) in the last few years.  But this was the only hard number in the entire article.

So what else does the Minister have to offer in his economic strategy?

We are investing to improve the skills of our workforce so that workers can adapt to changing workplaces. New programmes like our Mana in Mahi/Strength in Work apprenticeship scheme will get young people off the dole and support employers with the costs of giving them an apprenticeship to help them grow their business.

As I’ve noted numerous times previously, on OECD data New Zealand workers are among the most highly-skilled in the OECD.   And where the government is spending most heavily in the broad area of skills, it seems to be in providing fee-free tertiary education –  a policy that will (a) mostly redistribute money to people (and their families) who would already undertake tertiary education, and (b) to the limited extent it encourages further participation, presumably do so mostly among those for whom tertiary education offers lower expected returns.  It doesn’t have the feel of a productivity-enhancing policy, and the government has not (that I’ve seen) offered any numbers to the contrary.   As for getting “young people off the dole”, it is (of course) a worthy objective but haven’t we seen many such initiatives in the last 50 years?

Other policies supporting small and medium enterprises to manage costs include greater access to training programmes, e-invoicing and cutting compliance costs.

There may well be some useful stuff in that list.  But surely every government in modern times has talked of cutting compliance costs?  And, in practice, haven’t most ended up increasing them overall?  The previous government liked to boast of the 500 (?) items that comprised its Business Growth Agenda, but none of it (not even all of it) began to reverse decades of underperformance.  It was symptom of the drive for action without analysis.

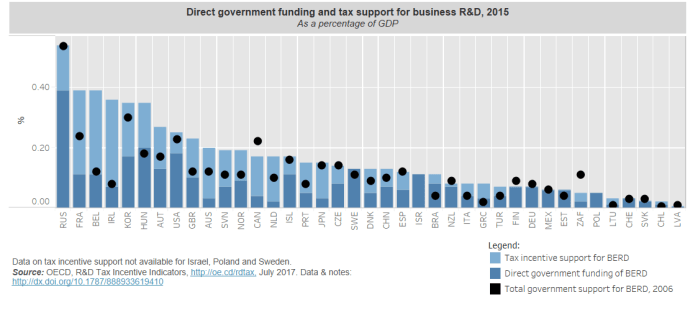
New Zealand was built on innovation. The best path for us to get richer as a country is to invest in new opportunities and find better ways of doing things. The coalition Government is supporting business to lift research and development investment, with $1b set aside in the Budget for R&D tax incentives.

Hard to disagree with the second sentence, but without some compelling analysis suggesting that the government and its advisers understand why firms haven’t regarded it as worth their while to spend more heavily on R&D, it is difficult to be optimistic that more subsidies are the answer.   As I noted in an earlier post on the government’s proposals in this area

R&D tax credits aren’t the only form of government spending to subsidise business R&D – in fact, the government’s new scheme involves doing away with the current grants. And as it happens, OECD numbers suggests we already spend more (per cent of GDP) on such subsidies than Germany (DEU), and quite a lot more than Switzerland (CHE). [both of which have far far higher levels of actual business R&D]

All of which might suggest taking a few steps back and thinking harder about why firms themselves don’t see it as worth undertaking very much R&D spending here. But given a choice between hard-headed sceptical analysis and being seen to “do something”, all too often it is the latter that seems to win out.

But we are only stepping up to the big stuff

Our bold goal for New Zealand to have a net zero emissions economy by 2050 is essential as we face up to climate change. This goal creates economic opportunities. The business community is alongside us, with 60 of our biggest firms forming the Climate Leaders Coalition. The $100 million Green Investment Fund and the One Billion Trees initiative are key parts of this work.

Perhaps it is “essential”.   Perhaps it even creates “economic opportunities” –  big changes in regulation and relative prices always do, for some people.   But the government’s own consultative document, and modelling commissioned for them from NZIER, suggests that once one looks at the entire economy, a serious net-zero emissions target by 2050 will result in losses of real GDP per capita of 10 to 22 per cent (relative to the baseline in which no such target is adopted by New Zealand).   No democratic government is history has ever consulted on proposals that would lead to such a dramatic fall in expected future living standards and productivity.  And, as a reminder, on the government’s own numbers, the costs would fall wildly disproportionately on the poorest New Zealanders.   And, yes, there probably will be a lot more trees planted –  many of them probably on good, easy to access and harvest, land –  but just last week the government had to announce large subsidies to get even that programme underway.  Subsidies have never been the path to improved economywide economic prosperity.  Of course, few suppose the government proposes adopting a net-zero target for economic purposes, but they should at least stop misrepresenting the analysis on the economic effects from their own consultants.

We are also committed to ensuring no one is left behind in our economy. That’s why we have put in place the Families Package and lifted the minimum wage. It is why we have a $1b annual fund for regional infrastructure and economic development opportunities.

So the regions are so “stuffed” that only an annual subsidy scheme is going to help ensure they aren’t “left behind”?    That seems to be the implication of what the Minister of Finance is saying there.   And perhaps the Minister skipped over the likely tension between the laudable desire (see above) to get young people off the dole, and the really substantial increase in the minimum wage his government is putting in place (at a time when there is little or no economywide productivity growth)?

There are challenges in the world that are outside of New Zealand’s control. That is why we are running a surplus and being prudent with our debt levels. We are also diversifying our export markets to create new opportunities for our exporters.

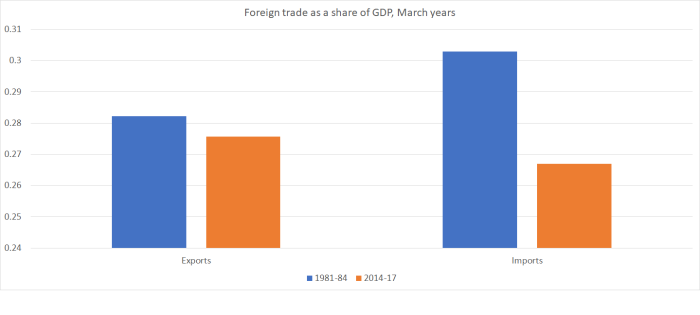
There is no hint of what, specifically, the Minister has in mind with his final sentence.  But there is a certain sameness to it, going back decades and decades (nice quotes –  including about the potential role of forestry –  in that 1975 manifesto I mentioned earlier).  And, actually, taken over the decades there has been a huge amount of diversification of export markets –  no single country takes more than a quarter of New Zealand firms’ exports – but it hasn’t enabled New Zealand to lift the foreign trade share of its GDP much.  In fact, over the last 35 years that share has shrunk.

As Don Brash noted in his article the other day, the previous government had fine words too

Key spoke about the need to increase the export orientation of the economy, and set a target for exports of goods and services of 40 per cent of GDP, up from 30 per cent when he came to office. Today, exports are just 27 per cent of GDP

Just no policies to make a difference.

The Minister of Finance attempts to end his article on an upbeat note

We are committed to working with business, workers and communities to build a stronger, more productive economy that delivers the quality of life that all New Zealanders deserve.

A worthy objective indeed, but there is nothing in what he told his readers that is likely to address –  and begin to reverse –  the decades and decades of underperformance.  If we take seriously the government’s own numbers around the proposed emissions goal, the relative underperformance could be even worse under this government (were it to win nine years in office) than under its two predecessors.

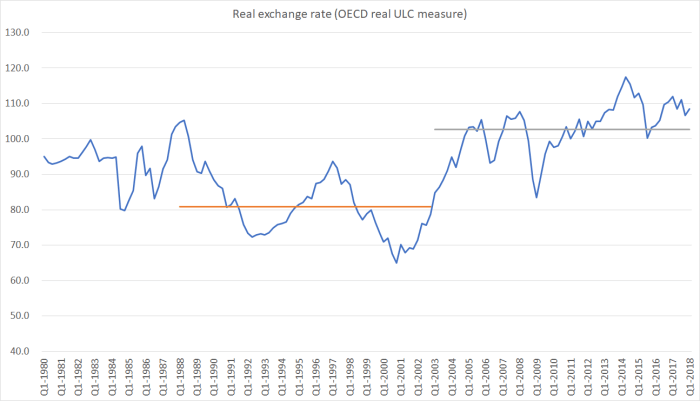
I presume (hope) the Minister believes what he says, but until he starts to confront the implications of charts like this he is unlikely to make any progress (except perhaps by chance)

With a real exchange rate now averaging 25 per cent higher than in the previous 15 years, in a country where productivity has dropped further behind, it shouldn’t be any surprise at all that foreign trade shares are falling, that the economy is increasingly skewed towards the non-tradables sector (where competition is often, and often of necessity) quite limited, or that firms don’t see the likely payoff to investing heavily in R&D.   These are classic symptoms of a severely unbalanced economy.  Most often they arise from misguided government choices.  In our case, the biggest single misguided choice is the grim determination –  or perhaps enthusiastic dream – to keep on rapidly driving up our population in such an isolated location where the opportunities to take on the world from here seem few –  and all the fewer with such a severely out-of-line real exchange rate.

Really successful economies  –  ones with materially stronger productivity growth than their peers –  tend to have strong, and rising, real exchange rates.  But that strength is a consequence of success, an outcome of success, a way of spreading the gains.  Driving up the real exchange rate has never been a part of successful strategy to lift the relative productivity performance of the economy.  The reformers here in the 1980s recognised the importance of a sustained lower real exchange rate as part of a successful economic transition.  It is tragic that today’s political and economic leaders seem to have almost completely lost sight of that.

We have –  and will have –  a 21st century economy.  But the question is whether it will be a struggling upper middle economy, with hazy memories of glory days long gone, or one that once again matches many of the richer countries in the advanced world, something I’m pretty sure we could do, but for a small number of people.  If the government really believes they have the answer for how they can do it with a population that they  actively drive further up every year, they surely owe it to us to lay out their reasoning, their analysis, with much more specificity than the Minister of Finance has yet done.  That might include explaining why their clever wheezes and proposed reforms will make the difference their predecessors also claim to have aspired to for decades now.

Then again, perhaps tangible achievement no longer matters.  Under the government’s wellbeing approach perhaps warm feelings will substitute for world-leading incomes?


Reflecting on the government and the PRC

Early last month, the government published its Strategic Defence Policy Statement.   That was the one that caused a bit of a flurry because of the inclusion of the odd, rather mild, honest statement that appeared to that put noses out of joint among the tyrants of Beijing and their representatives and advocates (not all PRC citizens) in Wellington.

And that was so even though early on the document reminded us that

New Zealand continues to build a strong and resilient relationship with China. Defence and security cooperation with China has grown over recent years, supported by a range of visits, exchanges, and dialogues.

It isn’t clear what values or interests the People’s Republic of China and New Zealand would share.   We knew better 50 years ago when we didn’t do military exchanges and joint exercises with the Soviet Union.

The pandering goes on with talk of how “China is deeply integrated into the rules-based order” (one of those much-used but very ill-defined phrases that seems to bear little relationship to reality).

Moving along, the report gets a little more frank, but in repeating lines that are news to no one.    China is not  –  and shows no sign of or interest in becoming – a liberal democracy, and its “views on human rights and freedom of information…stand in contrast to those that prevail in New Zealand”.   The document notes also growing Chinese military power and a disregard for international fora in dealing with “the status of sovereignty claims” in “disputed areas of maritime Asia”.     There is, rather brief, reference to attempts to “disrupt and influence Western nations’ political systems from the inside”, although those comments aren’t specific to China.

And (in a statement of what one would have hoped would have been blindingly obvious) there is this

Developments in Europe and Asia have crystallised a sense that non-democratic and democratic systems are in strategic competition, and that not all major powers’ aspirations can be shaped in accordance with the rules-based order [whatever the government means by that], in the way that had been hoped until recently.

And yet, if this is partly in reference to China, what have the presidents of both the Labour and National parties been doing praising Xi Jinping and the contribution of the PRC?  There has been no sign of them recanting.

A little later on in the document, there are two paragraphs specifically about China.  They are purely descriptive, with not a word of disapproval to be found among the descriptions of China’s aggression in the South and East China Seas, the construction of military bases on artificial islands in contested waters.  Remarkably –  but no doubt pleasingly to both Beijing and our Ministry of Foreign Affairs and Trade –  there is apparently no mention of Taiwan, a key potential flashpoint, at all.

You could perhaps read the document more charitably than I have done –  for example, hints of unease about Chinese activity in Antarctica –  but it is still a pretty anodyne document.  There is no explicit or outright criticism.   Even China’s major geopolitical initiative, the Belt and Road Initiative, is described in positive terms.

But Beijing didn’t like it

At a press conference in Beijing on Monday, China Foreign Ministry spokeswoman Hua Chunying said the country had taken note of the defence policy statement and “lodged stern representations with New Zealand on the wrong remarks it has made on China.”        …

“We urge New Zealand to view the relevant issue in an objective way, correct its wrong words and deeds and contribute more to the mutual trust and cooperation between our two countries.”

Quite telling that wording.  Not a matter, apparently, where reasonable people might disagree, but rather “wrong words” (and “deeds”) that need correcting.   New Zealand should abase itself.   And the PRC sometimes wonders why it doesn’t have more genuine friends….

The document itself is now rather old news.  But what struck me in the days and weeks after its release was that, anodyne as it was, it was made even weaker by the complete silence of the Prime Minister and senior Labour Party figures (and, for that matter, the Greens).  Labour is by far the largest component of the government, and not a peep has been heard from the Prime Minister (conveniently on leave when the policy statement was released).  But that is par for the course from the Prime Minister –  I wrote here about a speech she gave earlier in the year to the China Business Summit in Auckland.   There was no sign of any moral core to her views.   Not surprisingly, since her own party president has been in Bejing, since she became leader, praising Xi Jinping.   It is sickening.

Incidentally, for anyone inclined to look favourably on New Zealand First’s involvement in all this, I stumbled on an article on the PRC Embassy’s website about an event in Wellington a couple of weeks ago to celebrate the 91st anniversary of the People’s Liberation Army.  Among the speakers were our Defence Minister, Ron Mark, and our new Chief of Defence Force, Kevin Short.  Various other senior New Zealand officials also attended.  Neither man published the text of his remarks, but the Chinese Embassy reported them.

Here was Ron Mark

The New Zealand Minister of Defence Ron Mark extended his heartfelt congratulations on the 91st anniversary of the founding of the PLA and expressed his admiration for the contribution of the Chinese army towards safeguarding world peace. The Honourable Ron Mark noted that China is New Zealand’s strategic partner and that the relationship with China is one of New Zealand’s most important and valuable relations with foreign countries. Over the past 30 years since Royal New Zealand Navy frigates visited Shanghai in 1987, China-New Zealand military-to-military relations have continued to develop on the basis of openness and mutual respect.

What planet is the man on?  He’d probably have had a good word for the Wehrmacht and the Luftwaffe in 1938 as well.

As for the Air Marshal

Mr Short noted that over the past 91 years since its founding, the PLA has made tremendous contributions to China and the world.

A decades-long civil war, enabling one of the brutal and murderous regimes on the planet, and now  –  according to our own Strategic Defence Policy Statement

China’s military modernisation reflects its economic power and growing leadership ambitions. China’s growing military capabilities raise the costs of any potential internvetion against its interests and include stronger expeditionary capabilities, including a military presence in the Indian Ocean.  China has expanded its military and coastguard presence in disputed areas of maritime Asia. It has determined not to engage with an international tribunal ruling on the status of sovereignty claims.

Perhaps all that had slipped the Air Marshal’s mind when he made the kowtow before the PRC Ambassador, presumably with the approval of his Minister?

Distasteful as the PRC regime is, at least there was a bit more honesty in some of their reported remarks

In his speech, Defence Attaché Li Jingfeng stated that as socialism with Chinese characteristics entering a new era, the building of the PLA has also reached a new stage. With the deepening of defence and military reforms, the entire army adheres to the absolute leadership of the Chinese Communist Party and resolutely implements President Xi Jinping’s thought on building a strong military. By constantly advancing the policy of developing the military through political work, strengthening it through reform, and governing it according to law, the PLA’s combat effectiveness has been significantly enhanced

Against what external threat, other than those generated by the PRC’s own aggression, one has to wonder?

As the PRC Embassy reported it

The atmosphere at the reception was cordial and friendly. The participating New Zealand guests spoke highly of the achievements made by the Chinese armed forces and their contribution to world peace,

I guess we can take such propaganda with a pinch of salt, but it clearly wasn’t a remotely awkward occasion for such an expansionist power just a few weeks after that defence policy document had been released.  It should be a cause for shame among our ministers, officials and senior defence force officers.

And if I’m critical of our government and its officials, the Opposition is no better.  After all, they still have former PLA intelligence staffer Jian Yang –  the man who acknowledges he misrepresented his past to get into the country –  as one of the lesser lights of their parliamentary caucus.    Their leader was the man who, as a senior minister last year, signed New Zealand up to the Belt and Road Initiative, in a document full of nauseating and ingratiating rhetoric (next steps of which are due, in terms of the agreement, in the next six weeks).  Perhaps worse, when the government came out with its rather mild Strategic Defence Policy Statement, mostly just stating –  barely even criticising –  the blindingly obvious, Simon Bridges was all of a flutter.  The government couldn’t possibly say such things: it might upset Beijing.  There would be consequences he ominously warned.    Does the man have no respects for the values and systems of his own country at all?  Is he only interested in the perspective of a few businesses (including universities) that want better trade terms, never mind the character of the regime they pander to?  Never, ever, apparently must a disrespectful word be uttered.

There have been a few interesting articles around from abroad in recent weeks that are worth reading.  Perhaps most directly salient was a substantial piece in the Australian magazine The Monthly by John Garnaut, formerly a senior Fairfax journalist (and long-term China correspondent), more latterly an adviser to the Australian government.    His article is on the challenge PRC influence strategies pose in many countries –  in Asia, the Pacific, Europe and the Americas.

Garnaut writes

The CCP’s international influence system is a complex, subtle and deeply institutionalised set of inducements and threats designed to shape the way outsiders talk, think and behave. The modus operandi is to offer privileged access, build personal rapport and reward those who deliver. It seeks common interests and cultivates relationships of dependency with chosen partners. The Party uses overt propaganda and diplomacy, quasi-covert fronts and proxies, and covert operations to frame debates, manage perceptions, and tilt the political and strategic landscape to its advantage.

Beyond the foundational assumption of a single, civilisational “China”, the specific demands of United Front work are framed by permutations of three narratives: China is inherently peaceful and beneficent, the growth of Chinese power is inexorable, and China is vengeful and dangerous if provoked.

These narratives are internally contradictory but consistent over time. The first two are delivered openly by leaders, diplomats and state propaganda. The third is usually delivered via back channels with plausibly deniable connections to the state: PLA “hawks”, specialist military hardware websites, academic forums, personal meetings with top leaders, editorials in the Global Times. Together, this messaging orchestra is designed to condition audiences into believing that the rewards are great, resistance is futile, and outright opposition may be suicidal.

The meta-narrative of Beijing’s ever-growing power is the drumbeat that accompanies China’s policies of territorial coercion across its southern and eastern seas. It is the subtext that persuades foreign governments to remain silent as Beijing abandons restraint in the restive borderlands of Tibet and Xinjiang. It is also the incentive for economic beneficiaries to avoid seeing, or to rationalise, or to even actively support the Party’s efforts to degrade the values and institutions of civil society.

That final sentence sounds a great deal like the New Zealand situation.

But Garnaut isn’t just writing about distant places like New Zealand and Australia.  Of Taiwan he writes

In May I attended a closed-door forum hosted by the Taiwan Foundation for Democracy that was publicly opened by the deputy foreign minister, François Chih-Chung Wu. He set aside diplomatic platitudes to issue this plea for international help:

“In Taiwan, and in countries elsewhere, China moves from soft power to sharp power, and then to hard power. And it is becoming more brazen every day … In other countries, this process may begin with a Confucius Institute, scholarships, grants, but the next thing you know you must self-censor discussions China considers sensitive … In the face of this authoritarian onslaught of China’s misinformation, cyber hacking, bribery, economic coercion, theft of technology, and intrusion in internal politics – Taiwan is crucial. If it can hold on, other democracies will be able to hold on. But if it fails, there will be no security for the democratic governments of the world.”

He also writes about the Singaporean government’s expulsion last year of a resident Chinese-born US citizen, a reasonably prominent academic, for being an “agent of influence for a foreign country”.     Garnaut writes

What is striking about this official statement is that it makes detailed allegations relating to a form of espionage that sits a long way from the traditional Western counterintelligence agenda. The intelligence officers who were allegedly behind this operation were not stealing secrets. And nor were they aiming to directly control any policy lever. Rather, they were allegedly planting or nurturing a series of words and ideas in order to tilt the strategic decision-making landscape in a particular direction. They didn’t want to force Singaporean policy makers to make decisions in their favour. Rather, they wanted to condition policy makers to make such decisions of their own volition.

He quotes a recent speech from a retired top Singaporean diplomat (reprinted in the government-managed media in Singapore)

“China does not just want you to comply with its wishes. Far more fundamentally, it wants you to think in such a way that you will of your own volition do what it wants without being told. It’s a form of psychological manipulation.”

As I read that, it brought to mind Beijing’s description of the New Zealand defence document: “wrong words”.

Garnaut reports his own experiences, and the attempts of the regime to suborn his reporting

At first, my exposure to United Front work was all about inducements, with an occasional warning to keep me on my toes. I was offered red envelopes, neatly packed with US$100 bills. And sounded out for a lucrative “consultancy” arrangement with a Hong Kong bank. In one encounter, I was offered air tickets, hotel accommodation, a five-star family holiday, a job, and a gift bag containing bottles of Bordeaux wine valued at up to US$2000 each. These were all reciprocity traps, to be avoided at all costs. Gradually, over time, the ratio of carrots to sticks was inverted.

Garnaut was recently the subject of legal action by one extremely wealthy PRC resident in Australia,  put out by his open and sceptical reporting.

Another recent piece people might like to read was piece by Didi Kirsten Tatlow, long-serving (and then China-resident) journalist, and currently visiting fellow at the (German) Mercator Institute for China Studies, on some of the ideas, values, and language (often ancient) that seem to guide PRC actions today, including around the United Front activities  (“Imperial philosophy meets Marxist orthodoxy in Beijing’s global ambitions”).

In one quote, resonant of Beijing’s descriptions of the defence policy document,

A direct consequence of this worldview is that, from the party’s point of view, China’s sovereignty applies everywhere in the world. The party-state reserves for itself the right to negate values such as freedom of speech anywhere if it feels these challenge its sovereignty.

This stance is often expressed in terse demands to “outsiders” to apologize for getting things “wrong,” such as classifying Taiwan as a nation, or referencing the Dalai Lama in an advertisement, as happened recently to western airlines, hotels and car companies. These demands are increasingly coupled to direct threat to trade, in a classic example of jimi.

Rarely is the rationale behind the demand spelled out, but it was, in January, in an article in Global Times. The article responded to a previous New York Times article that documented how Chinese diplomats and soccer officials were interfering in political and speech freedoms in Germany. (That article was by this author.)

Efforts in Germany to support the rights of Tibetans were not a question of free speech, wrote Zhang Yi in Global Times: “What the author fails to understand is that the Tibet question is a matter of Chinese sovereignty; the Tibetan separatists aimed at splitting China and they should not use freedom of speech as an excuse,” Zhang wrote.

In that quote the underpinnings of the democratic order are removed and the intrinsic value of free speech negated everywhere. This isn’t simply change. This is revolution, in the sense of overturning. While the Global Times is not the party or government, the sovereignty argument expressed by Zhang cleaves to official thinking.

Towards the end of her paper, Tetlow notes

How can an anti-democratic, universalist China be accommodated and managed?

Firstly, a mental reset is needed. In a time of system competition it is of utmost importance to understand one’s competitor. Chinese officials and official commentators often talk about “changing and improving” global governance – pluralist societies must assume they mean to do it. Open societies must stop seeing the People’s Republic of China as a paler copy of themselves, merely lagging in terms of democratic modernity. Such teleology is unjustified, barring major political change in China.

By seeing the threads that the party is picking from the past and weaving into the future, we see China as it is – human yet totalitarian, strong yet weak, defensive yet aggressive, and ultimately a great challenge to democratic nations. When China calls for a tianxia-esque, civilizational system such as the “commonwealth of human destiny,” we must listen carefully, analyze closely the historical context and development of the term, identify the techniques used to achieve it, and assume party leaders mean to implement it if they can.

And what of the vaunted Belt and Road Initiative, that local taxpayer-funded PR outfits like the China Council and the Asia New Zealand Foundation are constantly keen to talk up (and on which the New Zealand government soon has to make decisions)?  I noticed a new short piece out of a US think-tank suggesting that all might not be well with the programme even inside the PRC.

the PRC’s policymaking apparatus appears to have already responded to concerns of BRI overreach by adjusting the scale of lending to limit possible financial risk. BRI lending by major PRC banks has dropped by 89% since 2015, and lending by commercial banks—who are dealing with their own financial issues domestically—has ceased almost entirely. Policy banks have also scaled back, despite their status as arms of PRC government policy.

What are these concerns?

On July 20, Sun Wenguang, a retired professor of physics at Shandong University, penned an open letter criticizing China for “offering almost CNY 400 billion in aid to 166 countries, and sending 600,000 aid workers” (Canyuwang, July 20). On August 1, as he expanded on his concerns in an interview with the US-based Voice of America, police forced their way into Sun’s apartment. As he was taken away, Sun could be heard saying, “Listen to what I say, is it wrong? Regular people are poor, let’s not throw our money away in Africa … throwing money around like this doesn’t do any good for our country or our society.” (VOA Youtube, August 2)

Ah, the character of the regime our politicians and officials pander to…..

As the author notes

Although a Western observer might dismiss a few professors’ unhappiness with the BRI as ivory tower grumbling, PRC academic critiques are worth noting, since outspoken academics are often the channel through which other PRC societal elites communicate their dissatisfaction with the CCP.

And draws atttention to one much-better-connected leading academic’s recent essay.

Although Sun has long been a government gadfly, he is also long retired, and resides far from the center of power in Beijing. But similar criticisms have found voice much closer to the corridors of power. On July 24, Xu Zhangrun (许章润), a professor at Beijing’s elite Tsinghua University, published an extraordinary essay entitled “Imminent Fears, Imminent Hopes” (我们当下的恐惧与期待). Among many other criticisms, Xu excoriates Xi’s government for its profligacy abroad, saying:

At the recent China-Arab States Cooperation Forum [on 10 July 2018], [Xi Jinping] announced that twenty billion US dollars would be made available for ‘Dedicated Reconstruction Projects’ in the Arab world, adding that [China] will investigate offering a further one billion yuan to support social stability efforts in the [Persian Gulf]. Everyone knows full well that the Gulf States are literally oozing with wealth. Why is China, a country with over one hundred million people who are still living below the poverty line, playing at being the flashy big-spender? (China Heritage, August 1)

Xu Zhungrun’s essay is a fascinating read (the readily available, and extensively quoted, translation was done by the Australian China scholar living in the Wairarapa).   As the translator notes in his introduction

On 24 July 2018, Xu published a lengthy online critique of China’s present political and social dilemmas. In issuing his Jeremiad, Xu, who is something of a latter-day rú 儒, locates himself in the Grand Tradition by effectively addressing a Memorial to the Throne, 諫言 or 上書. Given the relentless police repression and intensifying ideological clamp-down in Xi Jinping’s China, this is a daring act of ‘remonstrance’ 諫勸.

The professor doesn’t pull his punches

Over-investment in international aid may well result in deprivations at home. It is said that China is now the world’s largest source of international aid; its cash-splashes are counted in billions or tens of billions of dollars. For a developing country with a large population many of whom still live in a pre-modern economy, such behaviour is outrageously disproportionate. Such policies are born of a ‘Vanity Politics’; they reflect the flashy showmanship of the boastful and they are odious. The nation’s wealth — including China’s three trillion dollars in foreign reserves — has been accumulated over the past four decades using the blood and sweat of working people, in fact, it has actually been built up as a result of successive policies and countless struggles dating from the time of the Self-Strengthening Movement [launched during the Tongzhi Restoration during the 1860s when, following its defeat in the Second Opium War, the court of the Qing-dynasty adopted the first modernising reform agenda in Chinese history. By saying this Xu, to an extent, indicates that he does not completely embrace the Communist narrative or its soteriology]. How can this wealth be squandered so heedlessly?

The era of fast-paced economic growth will come to an end; how can such wanton generosity be tolerated — a generosity which, in many ways, replicates [the vainglorious Maoist-era policies when China boasted that it was the centre of world revolution to] ‘Support Asia-Africa-Latin America’ [which meant that an impoverished China was generously giving aid to Third World countries in an effort to gain political advantage and counter the influence both of the American imperialists and the Soviet revisionists] that led to countless millions of Chinese being forced to tighten their belts simply to survive, and which even saw the corpses of those who had starved to death scattered in the fields.

Recall that New Zealand too –  far richer than China per capita –  is a recipient of this lavish PRC “foreign aid” –  paying for language teaching assistance in numerous of our state schools,  all encouraged by our government at the expense of poor Chinese.

Average Chinese are most frequently offended by the way the state scatters large sums of money through international aid to little or no benefit. China is still slowly making its way up the steep slope of development. In terms both of basic infrastructure and social facilities, as well as in regard to people’s ability to access welfare, we are confronting massive problems; our burden is great and the road ahead leads far into the distance. And I make this point without even mentioning the crisis in aged care, or issues related to employment opportunities and education.

Or

Even the most commonplace international meeting organised in China involves extraordinary levels of expense. There is no regard for budgets; fiscal waste and the heedless loss of human work hours is considerable. Such activities are content-free and superficial. It’s all about pursuing ‘Vanity Politics’ not ‘Practical Politics’, let alone ‘Hard-edged Politics’. Such events have nothing to do with the so-called ‘venerable traditional of warmth and hospitality demonstrated by the Chinese people from ancient times’; only the most vain and self-serving [leaders and bureaucrats like to] indulge in such things. If foreigners were to copy what we ar constantly doing here, then the VIP-filled headquarters of the United Nations in New York would be on police lock-down 24/7, and the headquarters of the numerous international organisations based in Geneva and Paris would perforce have to stage nightly fireworks displays with their personnel expected to be decked out in all their finery all the time.

One might think of cocktails to celebrate the 91st anniversary of the PLA.  But more tellingly one might think of PRC gifts to PNG (a fancy convention centre and a new six lane highway for example) to enable it to host APEC this year.

Or

An emergency brake must be applied to the unfolding Personality Cult. Who would have thought that, after four decades of Reforms and the Open Door, our Sacred Land would once more witness a Personality Cult? The Party media is going to extreme lengths to create a new Idol, and in the process it is offering up to the world an image of China as Modern Totalitarianism. Portraits of the Leader are hoisted on high throughout the Land, as though they are possessed of some Spiritual Mana. This only adds to all the absurdity. And then, on top of that, the speeches of That Official — things previously merely to be recorded by secretaries in a pro forma bureaucratic manner — are now painstakingly collected in finely bound editions printed in vast quantities and handed out free throughout the world. The profligate waste of paper alone is enough to make you shake your head in disbelief.

Didn’t former Labour leader Phil Goff pay for a large chunk of his mayoral campaign auctioning off collected works of Xi Jinping, to PRC-based donors?

It is a bracing read, and one can wonder at the likely fate of the courageous author.

Meanwhile, our Prime Minister –  and her Opposition counterpart – refuse ever to utter a critical word about the regime, or what it represents here  (Jian Yang, the infiltration of Chinese community groups, control of the Chinese language media), abroad (South and East China Sea), or back home.    The most egregious recent example is around the mass concentration camp (actual detention, and extreme surveillance for those not detained) in Xinjiang.    What would it take for Jacinda Ardern, Simon Bridges, Winston Peters, Ron Mark, James Shaw, Marama Davidson to speak up and speak out.   Does nothing but a dollar matter in their world nowadays?  It looks a lot like civilisational decadence taken to whole new levels.  So well-schooled it doesn’t even occur to them to speak up.     Another cocktail party perhaps?  Pass the canapes, and quietly ignore the great evil Beijing and the CCP are responsible for –  not just in decades past, but (in more refined, and perhaps unnerving) forms right now.

These were parties that once prided themselves on standing against (variously) apartheid South Africa, French nuclear testing, the Soviet Union, Nazi Germany, mass murder in Cambodia or Rwanda, and so on.  Is there anything left they believe in enough, or care about enough, to speak up, take a stand, or do something?


Towards a (physical) currency auction

A week or so back, at the Monetary Policy Statement press conference, veteran Herald economics journalist/columnist Brian Fallow asked the Governor about how well-situated New Zealand was to cope with the next recession, given how low the OCR is now (1.75 per cent, as compared with 8.25 per cent going into the previous recession).

As I recorded in a post the same day, the Governor and his offsiders responded with a degree of confidence that wasn’t backed by much substance.  It all smacked of a worrying degree of complacency.

Fallow also apparently wasn’t persuaded, and returned to the issue in his weekly Herald column yesterday.  I wanted to pick up today on just one of the topics he touched on in that column.

The key issue is the effective lower bound on nominal interest rates.  The Reserve Bank has indicated that it believes the OCR probably couldn’t usefully be taken lower than -0.75 per cent (I agree with them, and that assessment of the effective lower bound is consistent with the lowest any other country has set its policy interest rate).  Beyond that point, it seems likely that an increasing proportion of holders of short-term financial assets would transfer into holdings of physical cash.  There is no direct cost of conversion, although there are storage and insurance costs for physical cash (which is why large scale conversion doesn’t occur at, say, -5 basis points).

When official interest rates were dropped below -0.75 per cent it still probably wouldn’t affect very much much (or how) little cash you hold in your wallet/purse.  If you hold much cash at all, it is probably for convenience (or privacy), balanced against (say) risk of loss/theft.  And a secure physical storage facility for even $10000 of cash would be much more inconvenient –  and probably expensive – than holding a short-term bank deposit.  You might well, grudgingly, live with an interest rate of -2.0 per cent per annum (as it is, since the last recession, marginal term deposit rates have been well above the OCR anyway).   Or you might seek to shift your money to riskier (potentially higher-yielding assets) –  in which case the lower policy interest rate would still be somewhat effective.

But the big issue here isn’t so much what the ordinary householder does.  Most don’t have that many financial assets that could be converted directly to cash anyway.  The bigger issue is institutional investors (resident and foreign, including –  for example –  Kiwisaver funds).   The funds management market is pretty intensely competitive, and (risk-adjusted) yield-driven (as an example, I was in a meeting yesterday where we looked at a restructuring option to save perhaps 3 basis points).     So if the Reserve Bank tried to cut the OCR to, say, -2.0 per cent (and it was expected to remain at least that low for a couple of years), there would be big incentives to find alternative assets yielding a less-negative (or positive) return.  The most obvious example is physical cash.   And if there are incentives for fund managers to find such alternative options, there are incentives for trusted operators to provide them (secure physical storage for large quantities of physical currency).   Willing buyers and willing sellers usually find a way to get together, at least if regulators don’t come between them (in this case the regulator –  the Reserve Bank –  actually creates the problem.  People sometimes talk about a lack of secure storage facilities, but $1 billion in $100 bills doesn’t take much space (nor, really, does $100 billion).  (On US note dimensions, the calculations are here.)  If conversions of this sort happened on a large scale, a lower OCR won’t have any material effect –  other than encouraging remaining asser holders to convert to cash.  It wouldn’t lower retail interest rates (much) and wouldn’t lower the exchange rate (much).

These sorts of conversions wouldn’t happen overnight.  Probably most funds managers and the like won’t have physical cash in their list of approved assets.  Some will be able to change that faster than others. Those that can will be able to offer better returns than those that don’t.   And such conversions would be much more likely in the next recession precisely because the starting point –  initial low interest rates –  is so bad.  It is quite likely that official rates could be negative for years.  Or perhaps the conversions will just never happen because central banks (here the Reserve Bank) just don’t lower their official rates far enough to make conversion economic.  But, if so. they will have made the point: conventional monetary policy will have very quickly exhausted its capacity.

And so various people, including me in the New Zealand context, have been arguing for some years now that something needs to be done –  and needs to be done early, to condition expectations about the next recession –  about the effective lower bound.  Brian Fallow refers to this in his article

Overseas experience suggests that at most, a negative policy rate might move the effective lower bound for interest rates 75 basis points into the red. Moving it lower still would require, economist Michael Reddell suggests, imposing a fee on banks switching from virtual to physical cash.

It wouldn’t be difficult.  There are more complex models on offer –  see Miles Kimball or Citibank’s Willem Buiter – but the desired results looks to me to be able to achieved quite simply by setting a cap on the regular holdings of physical currency (say 10 per cent above current levels).  It might need to be a seasonally adjusted cap (currency demand rises around Christmas and the summer holidays, and then falls back again).  The cap would need to rise through time (currency demand rises with the size of the nominal economy).  But the key point is that any net issuance beyond that level would be auctioned (perhaps fortnightly or monthly).   Any creditworthy entity –  the sort of institutions the Reserve Bank deals with routinely –  could participate in the auctions, and the marginal exchange price between settlement cash and wholesale volumes of physical cash would then be established quite readily, and could alter through time.  If the state of the economy and inflation meant the Reserve Bank needed to cut the OCR to -5 per cent (and in the US context, there are estimates that such a – temporary –  rate would have been desirable in 2009), there would be a lot of demand for physical currency, and no more supply.  The market-clearing price would rise, perhaps sharply.

Of course, banks supply currency to retail customers on demand, mostly through ATMs.   Banks would be free to respond to the rise in the marginal cost of obtaining new notes by passing those costs onto customers (retail or wholesale).   A (say) 5 per cent conversion cost of obtaining cash would encourage retail customers to economise on cash holdings (using EFTPOS etc instead), while allowing those who put most value on having physical currency to pay the price.  These days very few domestic transactions strictly require much cash.

Perhaps there are pitfalls in such a scheme.  If so, now is the time to be identifying them, not in the middle of the next serious recession.  Now is the time to be socialising –  including with the public – possible solutions, not in the middle of the next serious recession (when putting a premium price on physical currency suddenly announced might actually be seen as a negative signal about the soundness of banks –  ie discouraging people from holding cash).   Perhaps there even legislative obstacles – I’m not aware of any, but all sorts of obscure issues can arise when one looks into anything in depth. But, again, now is the time to identify those issues and fix them, not in the middle of the next serious recession.  There would probably need to be an override mechanism to cope with a genuine financial crisis driven run to cash.

And if there are better, workable, models, now is the time to identify them, and to test the alternative models in open dialogue, to ensure things are easily pre-positioned to cope with the next serious downturn.

Unfortunately, there is no sign of any of this sort of preparation occurring.  Certainly, nothing has been signalled by the Reserve Bank or by the Treasury or by the Minister of Finance.  If they aren’t doing the work, it is (complacent) negligence.  And if they are, but simply aren’t telling us, it would be quite unwise.

After all, as I noted in the earlier post, a key consideration the authorities need to be addressing is expectations (about inflation and policy).  In a typical serious downturn, inflation expectations fall but not too much, as all market participants expect that the downturn will be relatively shortlived, partly because of aggressive cuts to official interest rates.  But going into the next recession –  whenever it happens –  it seems increasingly likely that few central banks will have the interest rate adjustment capacity they would like.  And all economists and market participants will recognise the constraint, and are likely to factor it into their expectations are seen as a downturn in underway.  A rational response would be to cut inflation expectations (actual or implicit) much more sharply than usual  –  in turn, driving up real interest rates (for any given nominal rate), worsening the downturn, and worsening the reduction in inflation.  This issue doesn’t seem to get the attention it deserves even in the international discussions of these lower bound issues, but it looks to me like a pretty straightforward implication of the current situation.

Since none of us knows when the next severe recession will hit –  it could be years hence, but it could be next year –  this isn’t the time to let the issue drift.  Too many people paid the (unemployment) price of central bankers reaching their limits last time around to contemplate with equanimity going into the next recession starting from a situation where current low official interest rates are still only consistent with inflation at or below target in most countries, including New Zealand.  Dealing with the lower bound issue should be treated a matter of urgency.

(For those who are quite relaxed because of fiscal policy options, I might do a post next week on why it shouldn’t be very much consolation at all.)

Exchange rate moves: trivial in historical context

I saw a curious story the other day which reported the Minister of Finance and the National Party spokesperson on finance arguing over who was to blame (or who could take the credit) for the fall in the exchange rate that followed the Reserve Bank’s Monetary Policy Statement.  From one side there seemed to be talk of the fall being part of the much-vaunted (but little seen) economic transition –  the Prime Minister herself has claimed this –  and from the other talk of loss of confidence in the economy, combined with some inflation risks.

Mostly it seems to be a difference about almost nothing.  Here is one of the OECD measures of New Zealand’s real exchange rate, for which data are available back to 1970. Obviously, we don’t have Q3 data yet, but I’ve taken the fall in the nominal TWI measure of the exchange rate for this quarter to date (latest observation for the RB website today) and applied it to the Q2 data to proxy a current observation.

RER ULC aug 18

Over almost 50 years, there have been lots of ups and downs in the series, even in the period (up to early 1985) before the exchange rate was floating.  Some have been the start of something pretty sustained –  see the falls in the mid 70s, or after 1987.  Others have been very shortlived (see for example the fall in 1986 or 2006 –  times when, for example, markets got a bit ahead of themselves in thinking our economy was slowing and interest rates would be falling).     Over the full period (and this is quarterly average data, which takes out some of the noise anyway) there have been at least eight episodes when this real exchange rate index has fallen by at least 10 index points (roughly 10 per cent).  The last occasion was in 2015, as markets somewhat belatedly realised –  not quite as belatedly as the then Governor – that the Reserve Bank’s OCR increases weren’t going to be sustained.

This episiode isn’t one of them.  The latest (estimated) observation is a mere six per cent below the most recent peak (18 months ago).  And the latest observation is nowhere near the low reached in the second half of 2015.

In fact, the current level of the TWI is 2.4 per cent below the average level for the June quarter.   Over the entire life of the series (fixed and floating periods) the average quarterly change (up or down) has been 2.7 per cent.  Taking just the floating period (since March 1985), the average quarterly change has been 3.1 per cent per quarter, and if we take just this decade (which, eyeballing things, has been a bit more stable, at least as regards big sustained moves) the average quarterly change has been 2.4 per cent.

Perhaps the fall we’ve seen so far this quarter (or even since the MPS last week) will be the start of something more.   If there is a serious global risk-off event, or a serious New Zealand downturn, that probably would happen.  But all we’ve seen so far is a change that is about the size of the change one sees, on average, each and every quarter –  some up, some down, and most not implying anything very much for the economy.

The idea that the fall foreshadows some promised rebalancing in the economy is pretty laughable.  There have been no policy changes to bring about any such rebalancing (any more than there were with the other –  larger –  falls in the previous 20+ years).  Then again, so is the notion that a lower exchange rate –  a modest fall at that –  is a material inflation risk.    The Reserve Bank itself published research a few years back suggesting noting that, in fact, a lower exchange rate has tended to be associated with lower non-tradables inflation, and often –  notably when commodity prices are also fallling –  with lower overall inflation.


How poorly have Australians done?

Much of this blog focuses on the dismal long-term performance of the New Zealand economy.  A common benchmark is to compare our performance against Australia: once (and for a long time) we more or less matched them, these days we languish well behind, and as a result a huge number of New Zealanders have left for better opportunities abroad, notably in Australia  –  still, fortunately, a place where New Zealanders are relatively easily able to move, if not (any longer) to securely settle.

But how has Australia itself done?

Here is how things were 100 years or so ago, in 1913 –  the eve of World War One, the end of the first great age of globalisation.  And Australia itself had finally recovered from the devastating crash, financial crisis etc, after 1890.  The data are real GDP per capita (in 1990 dollars) from the Maddison database.

1913 GDP

Australia (and New Zealand), far from the industrial heartland of the North Atlantic (recall that the Industrial Revolution had spread out from the UK, and then places like Belgium, Netherlands and northern France), in 1913 had per capita incomes twice those of places like Norway and Italy, 50 per cent more than France and Germany, 25 per cent more than Belgium and the Netherlands.  Only the United States matched us (some years a touch higher, some a touch lower).

And here are the top 25 countries from the latest IMF WEO database.

2017 GDP pc

You could toss out some or all Macao (tiny, and really just past of China), San Marino (really tiny), Hong Kong (China), Ireland (numbers not really reflective of Irish incomes because of the corporate tax system) or Luxembourg (much GDP is produced by people living in neighbouring countries but working in Luxembourg) if you want, and Australia would still only just get into the top 15.   Australian per capita is now less than that of most of the countries in the first chart –  only just edging out Taiwan.

Comparable productivity data going back a long way are scarce. The Conference Board data on real GDP per hour worked start in 1950.   There is only data for about 30 countries for 1950 (mostly the advanced countries).  But of those countries, only the US and Switzerland were ahead of Australia.

2017 real GDP phw

Again, you could safely ignore the Irish number, but doing so doesn’t change the story.  Australia has slipped a long way back, and is now nowhere near (say) that bracket of Germany, Denmark, Netherlands, the US, and Belgium. (Taiwan –  see previous paragraph – is just behind Italy on this measure).

Here is one way of looking at the performance over decades.  Both Australia and  Norway abound in mineral resources (in Norway’s case mostly oil and gas, in Australia’s a huge range).    Belgium, Netherlands, and Denmark are three high-performing European countries, where the data aren’t complicated by tax systems (Ireland), absorbing a failed communist state (Germany) and the like.

aus norway 2

Back in 1970, both Australia and Norway (before the minerals booms really got underway) had slightly higher average levels of productivity than the average for those other three northern European countries.  In Norway, the development of the oil and gas resources from the 1970s seems to have contributed to a marked widening in average productivity (and incomes) in Norway’s favour.  That margin has narrowed a bit in the last decade –  oil itself is past its peak in Norway –  but there is a still a large margin (over Europe’s other high productivity economies).  And what of Australia?  Even now, after a decade with the challenges of the euro crisis, the marked slowing in productivity growth at the global frontiers, and with the huge new mineral resources that have been opened up and brought to market by Australia, Australian average productivity still languishes a long way behind.  Even now –  after their reforms (80s and 90s) and their new resources – the margin between Australian productivity and that of these northern European countries is only about where it was in the mid-80s.  At that time, there was a great deal of angst (similar to NZ) about Australian’s relative decline.  In fact, Paul Keating’s “banana republic” line dates from then.  There has been no reconvergence since then.

With staggering volumes of newly-economic resources able to be brought to market, it is really a quite remarkably mediocre economic performance.   One might quibble about things like Australian labour market laws, but Australia is a functioning market economy that still scores quite highly on economic freedom indices.  This is no Venezuela.

And yet, for all its riches –  and you see (in the second chart above) the difference natural resources can make – Australia is no better than a middling performer among the (old) OECD countries it once mostly far-outstripped.

I’m not here to scoff –  New Zealand has, after all, done so much worse, and the embarrassing exodus stems from that –  but to analyse and learn.   I’ll offer some thoughts on reasons why in another post, probably next week.