Participation rates

A passing comment in a post the other day about the labour force participation rates of older people prompted me to pull down the fuller data and see what we could see about various participation rates over the decades since the HLFS began in 1986.   As it happens, the unemployment rate in 1986 averaged 4.2 per cent, exactly the same as the current unemployment rate, so cyclical factors shouldn’t materially mess up long-term comparisons.

Here are the quarterly participation rates (employed plus unemployed as a percentage of the working age (15+) population.
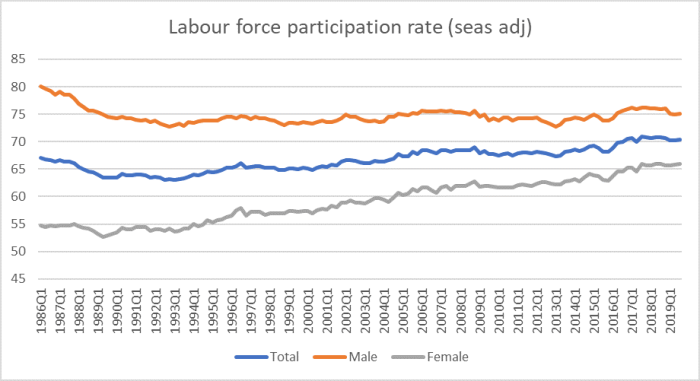
p rate q

From which I’d make only three quick observations:

  •  how stable the male participation rate has been since the end of the 1980s (even through a couple of very nasty recessions),
  • the strong upward trend in the female participation rate, and
  • while there is some modest cyclicality in the overall participation rate, it isn’t a stable or reliable cyclical indicator (eg the peak in the 00s was a year after the recession started, while the 90s peak was a year or so before the recession started).

But aggregates can mask a lot of interesting patterns, and around participation rates that has been particularly so for men (the female participation rates are just dominated by the strong upward underlying trend).   From here on, I’m using annual data (years to September), as there is less noise and more data reliability for some of the small age groupings.

Here is the data on participation rate for what you often see referred to as “prime age” people, those aged 25-54.
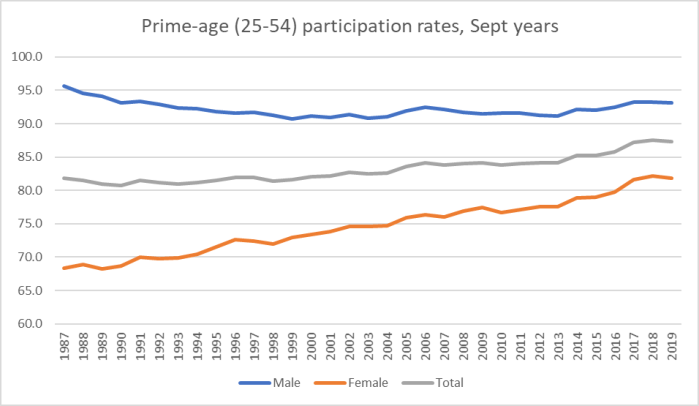
prime age total

Prime-age male participation isn’t back to where it was in the 1980s but over the last couple of years it has been higher than the 2000s peak.

What about the two youngest age bands?
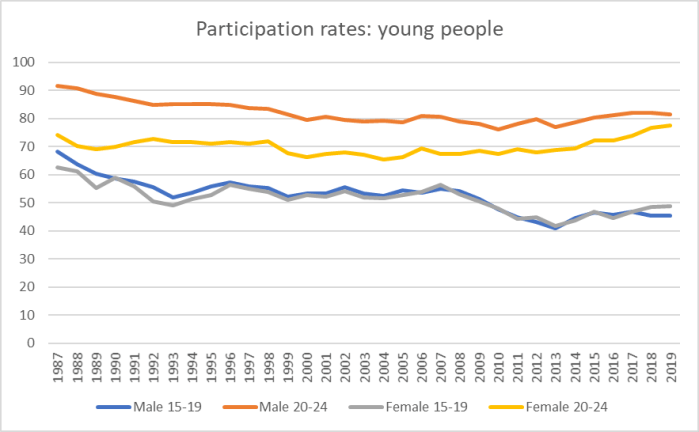
partic youth

In the 1980s (until 1989), people could leave school at 15, but I was interested –  and a bit surprised –  in the further step down in the participation rates of the 15-19 year olds ver the last 15 years or so.  Presumably there is some mix of factors at work: kids being less likely these days to have after-school jobs that was once the case, minimum wage changes, and……  Given the cost of tertiary education now (relative to say the 1980s) it still surprises me though.

Perhaps the bigger surprise though (at least to me) is that only around 80 per cent of 20-24 year olds are in the labour force.  You only need to have done one hour’s paid work in the reference week, or to have actively looked for work, to be included in this measure.

What sparked the post initially was participation rates of those in the older age groups.  Here are those for the 55-64 age.

p rate 55-64 Participation rates for this age group are much higher than they were for both men and women.   When the data start, the full rate of New Zealand Superannuation was available at age 60 (at, if I recall correctly, a higher rate relative to wages than is the case now).  I was a little surprised to note the dip in participation rates in the last couple of years: for this group of women the latest observation was lower than in any year since 2013.

And what about the participation rates of those 65 and over, almost all of whom have been eligible for NZS throughout?

p rates old

There has been some increase in participarion rates for those aged 70 and over, but the really striking movement has been in the 65-69 age group.   More than half of men, and almost 40 per cent of women, in this first NZS recipient age group, are still in the labour force. (Interestingly, the gap between male and female participation rates for this age group hasn’t materially changed over the 30+ years of the chart.)

And here is the comparisons between those aged 60-64 and those aged 65-69.
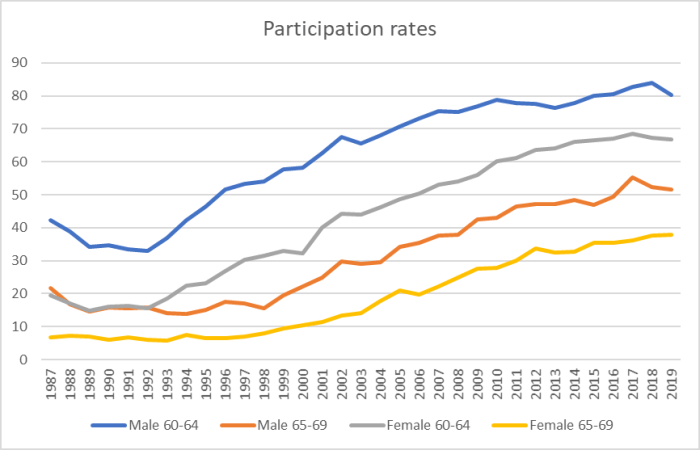
p rates NZS transition

In my post last week, I noted that the participation rates of those now aged 65-69 were higher than those for people aged 60-64 when the survey started, at a time when the NZS eligibility age was still 60.    I see this as a fact buttressing the case for raising the NZS eligibility age now (to, say, 68, and life expectancy indexing beyond that).  By some mix of revealed preference to work, and of need, large proportions of the population went on working for some years after being eligible for a universal pension, suggesting not only that they were physically capable of doing so, but that many of their peers who chose not to work would also be physically capable of doing so.

However, the comparative story over time is complicated at least a little by changing norms and expectations around female participation.  In 1987 under 20 per cent of women aged 60-64 were in the labour force: these were women born in the 1920s, (mostly) mothers of the first baby boomers at a time when female prime-age employment wasn’t that common.  Now almost 40 per cent of women 65-69 are in the labour force, almost as high a share as for the 60-64 year old males in the late 80s.    The increase in participation rates among males – today’s 65-69 year old compared with 1987’s 60-64 year olds is real, but less dramatic  –  up from just over 40 per cent to just over 50 per cent.

And just to end, a couple of international comparisons charts re participation rates for those aged 65-69.

Here is the participation rate in 2018

partic rates OECD 65 to 69.png

It really is an astonishing range.   It isn’t correlated with prosperity (there are poor performers at either end of the chart) or, that I could see, with life expectancy or health status.  I suspect –  but haven’t checked –  it is pretty strongly correlated with the abatement regimes (if any) around state pension.   One of the best things about the New Zealand system is that although NZS provides an income effect encouraging people to think about stopping work, there is no relative price or substitution effect: as an older person you can work as much as you like and it doesn’t affect how much NZS you receive.  In many countries, the rules aren’t like that; it often isn’t economically attractive to go working.

And what about the change over time in the proportion of those 65-69 in the labour force?  The OECD has complete date only since 2002 so here is the change since then.
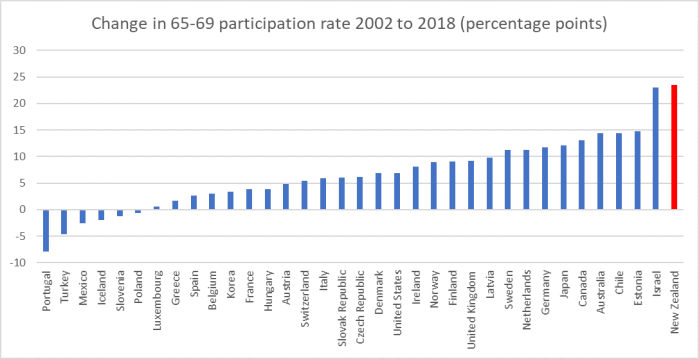
chg in partic rates 65 to 69

What I found interesting about that statistic for New Zealand is that that further large increase in the 65 to 69 participation rate has been exclusively in the years since the NZS eligibility age got to 65 (in 2002).  You can see in the chart above that our participation rates for those 60-64 also increased markedly over that period.

I’m not one of those inclined to celebrate (paid) labour for labour’s sake. I don’t think I was when I was in the paid workforce and I’m certainly not now.  But when the alternative is state income support then I do take a harder line view.  If you are able to work and are financially able not to, that is almost entirely a matter of individual/family choice, but you (generally) shouldn’t be eligible for long-term state income support.  New Zealand’s experience suggests that the overwhelming bulk of those aged, say, 65-67 are well able to work (we don’t have the data, but presumably –  given what happens from 70 on (see above) –  participation rates of those 68 and 69 are materially lower than those for people 65-67).   Against that backdrop, there is something just wrong about having a universal pension paid to them –  well, me not that many years hence on current policy –  simply on the basis of having got to that age.

Fans of a Universal Basic Income will, of course, not agree.  I am not a fan, having both practical and moral objections to a UBI.
 

Unserious defenders of NZ national interests

Our government finally made sufficient obeisance and secured a modest upgrade to its preferential trade agreement with the People’s Republic of China.  That included New Zealand agreeing (page 4) to take twice as many PRC-funded ideologically pre-screened Mandarin Language Assistants in our schools (rather than, say, properly funding language learning in schools ourselves).   The values-free cheerleaders for New Zealand deference and subservience to Beijing were all out praising the deal, and if the shameless National Party trade spokesman Todd McClay –  the one who last year was defending the PRC brutality in Xinjiang as being no more than a few vocational training schools and really none of anyone’s business –  was a bit carping and critical, he and his party were probably only critical that the current government does not (quite) do the full kowtow (they did actually sign that 22 country letter on Xinjiang, even if not one of them –  not an official, not a Minister, certainly not the Prime Minister –  will say a word about it).

Remarkably, for a pretty secretive government, sometimes one gets more coverage from the PRC government side than from our own.  The PRC Embassy here often has interesting statement or commentaries on its website.  There was such a commentary this week about the Prime Minister’s meeting with Li Keqiang in Thailand, including the prefential trade agreeement update, although for some mysterious reason I couldn’t see it on the PRC New Zealand embassy website but only on the PRC US embassy website.

Two lines caught my eye. There was this from the Chinese side

The Chinese side is committed to creating a market-oriented, and law-based international business environment, and hopes that the New Zealand side will create a level playing field in New Zealand for Chinese companies to invest and start business.

(One might scoff at the first half of that, but my interest was the second half)

and this describing the New Zealand government’s response

The New Zealand side is willing to provide a non-discriminative environment for companies from all countries investing and starting business in New Zealand.

Others noticed it to.  Here was the Executive Director of the China Council, the government/business propaganda arm of the New Zealand/PRC relationship

Pretty predictable (anything for the PRC, if only we – they – can get some more deals in the short term, is pretty much the China Council stance), but pretty unfortunate too.

The government is, or at least says it is, reviewing the Overseas Investment Act.  It was September last year when they issued terms of reference for the review.    There was a consultation document released in April this year, with a very short period for submissions, because –  according to the Cabinet paper released under the OIA – they wanted to ensure they had legislation passed this parliamentary term.  And yet here we are, now getting on for mid-November and nothing more has been heard.  They don’t seem to have even published the submissions yet.

National security was one of the dimensions covered (albeit superficially) in the consultation document.    Now ‘national security’ is one of those catch-alls that can be grossly abused –  see Trump’s grounds for steel tariffs on Canadian imports –  but the fact that it can be abused does not change the other, rather more important fact, that national security is an important issue, there are real threats (actual/potential), and one of the key roles of any government is to protect national security.    And, on the other hand, business interests have no particular concern for national security, especially if it gets in the way of their activities.

The worry here –  as the Prime Minister’s commitments are reported by the PRC –  is that neither does the government.    We seem to have governments more interested in enabling New Zealand businesses abroad, than in protecting the security, values, and integrity of New Zealand.

I generally have a pretty open approach to foreign investment.  It is often economically helpful and generally mutually beneficial.  Among firms and individuals from free and open societies, sharing similar values, and where companies are free to pursue their interests not those of their governments that is a pretty strong starting proposition.  Perhaps even more so when it involves investment from companies in countries near the frontiers of economic performance and productivity.  Personally, I’d favour removing pretty much all restrictions on such investment from abroad (perhaps preferably reciprocally, but the benefits to New Zealand mostly arise from opening up ourselves –  rather like removing all New Zealand tariffs (something successive governments refuse to do) would benefit New Zealand consumers).

I wrote about this briefly some months ago when I was lodging my own submission to the Overseas Invesment Act review, including how we should think about investment from the People’s Republic of China  and why treating all countries similarly simply does not make much sense (since neither the opportunities nor the risks are the same).  Here is what I wrote then

These days, New Zealand does not get much foreign direct investment –  and especially not much in the way of greenfields new developments.  I don’t think the screening etc regime is the main reason –  mostly, I suspect, we don’t have that much foreign investment because (a) there are few opportunities here, and (b) for the same sorts of reasons business investment generally has been weak for decades (high cost of capital, high real exchange rate, high taxes on business profits –  in that case, especially for foreign investors).  But I’d generally favour a more liberal environment, for almost all industries and for investors of almost all countries.

It is also worth recognising that most of any benefit (to productivity in New Zealand for example) from foreign investment will come from investment by firms based in rich and advanced countries.  Of course, there might be rare exceptions –  a firm based in Zambia, Laos or El Salvador –  but they will be exceptionally rare (the best ideas, technologies, management systems etc) will be in the rich countries –  part of why they got, and stay, rich.  So I’d favour a pretty-much open slather approach to foreign investment –  existing assets or new –  for investors based in rich countries (the OECD membership might be a decent starting point, and one could add in places like Singapore and Taiwan.

For most of the poorer or smaller countries, I really don’t care much what the rules are.  Probabilistically, there is almost nothing at stake (at least in economic terms) in maintaining restrictions on Zambia, Laos, El Salvador (or 100 others) if that is what the political process demands.  But, equally, there isn’t much risk or downside to opening up to them either, especially if one is focused on the benefit of New Zealanders being (generally) able to sell to the highest bidder.

There are various odious regimes in the world.  Most them don’t matter much to New Zealand at all (thinking places like Equatorial Guinea).  But the PRC does and in my view we should –  while the regime remains as it is – be treating investment from there quite differently, for various reasons.    One is a straightforward economic one.  Almost any large PRC firm is either an SOE or has a significant element of state/Party control to it.  We spent years here trying to reduce the hand of the state in direct business operations in New Zealand.  State entities typically don’t run businesses well, don’t allocate investment efficiently, and so on.  There is no more likelihood (to put it mildly) that PRC state-controlled companies will do so than the New Zealand government ones will –  and at least the New Zealand government ones are ultimately answerable to New Zealanders.  Such investment is likely to be a net negative for New Zealand even if the price paid to the initial New Zealand vendor is higher than that vendor could have got from another –  private –  purchaser, whether from New Zealand or another country.

But the deeper reason is that the PRC is a big and powerful totalitarian state, that has repeatedly displayed aggressive intent, which has values antithetical to those of most New Zealanders.   Individual PRC buyers may well be perfectly decent well-intentioned people –  as plenty of 1930s Germans were too –  but a totalitarian state has, and repeatedly demonstrated, its leverage over its own people, by fair means and (too often) foul.  We would simply be ill-advised to allow PRC-associated interests to have significant investments in many sectors in New Zealand.  One could think of media or telecom companies, or tech firms.    The PRC banks operating here should be a matter of concern, especially if they get materially larger than they are now.   But the concern should range wider.  For example, the greater the control PRC interests have of elements of the dairy industry, the more difficult New Zealand might find it to be handle the sort of economic coercion the PRC has attempted to engage in re various countries in recent years.

And, of course, to circle back to my earlier point, it is not as if the PRC is one of the world’s advanced economies.  Productivity levels languish far behind even New Zealand’s modest levels, and everyone recognises the dependence the regime has had on industrial espionage.  Deep pockets aside –  with a mix of market and non-market motives –  how much genuine benefit to New Zealanders is there likely to be from PRC foreign investment over time?

It is possible that this sort of restrictive regime could come at some economic cost, in terms of lost productivity opportunities for New Zealand. My sense is that it would probably be quite a small cost, but we can’t be sure.  Perhaps more importantly, many precautions have a cost –  whether it be a national defence force, Police, anti-virus software, or a lock on your front door.  The PRC is a threat to New Zealand and countries like us, and we need to be willing to spend some resources (perhaps sacrifice some short-term opportunities) to establish some resilience to those threats.

But, of course, our elected “leaders” and business establishment figures have no interest in any of this.  For them, it seems, the character of the regime matters not a jot, it demonstrated track record at home, abroad, and in New Zealand matter not a jot.  There are deals to be done, donations to be collected, and  –  if there are any risks –  well that will be someone else’s problem another day.  And in the process they’ve allowed our political system to become corrupted, indifferent to the character of the regime, indifferent to the values of New Zealanders.  But their “friends in Beijing” are no doubt happy.

I didn’t post a link then to my short submission, but I will do so now.

Submission on. reform of Overseas Investment Act May 2019

Some excerpts.  First, the liberalising proposal

As a general proposition, I suggest that the government should look at a model which more clearly distinguishes between countries which, broadly share similar values, interests, legal systems and approaches to business and remove all (or almost all) restrictions on foreign investment originating from such countries. A starting point for such a list might be the OECD countries plus Singapore and Taiwan. If the beneficial owners of a potential investor are predominantly from these countries, it isn’t obvious that the net benefits from screening would outweigh the costs, including deterrence of investment, of such a regime. Much of world cross-border foreign investment originates from these countries (and the countries at or near productivity frontiers are included in this group), and to the extent that there are prospective economic gains from liberalising the regime, those gains are likely to arise in respect of these countries.

And on the other hand

And at the other end of the spectrum should be a small list of named countries from which we should simply not welcome foreign direct investment, and where the presumption should be against granting approval for any but the smallest and most innocuous of investments. Such a list might include countries subject to United Nations sanctions (notably North Korea), mostly for global good-citizen reasons, and membership of the list might change over time – Germany might have appeared in the late 1930s, the Soviet Union and its satellites during the Cold War – but the key country that should feature on any such list today would be the People’s Republic of China.

In other words, the issue is not specific countries for all time, but specific assessments of the character of regimes, their control over business, and the nature of any threat.

The consultation document makes every effort to be neutral as between countries. But that is a mistake. It is right to recognise that the source of potential threats can change over time, but unless the government is willing to openly confront the nature of specific potentially-threatening countries, it is difficult to build a regime that will serve well both the national security and economic interest imperatives, and provide a clear framework for potential investors (and potential vendors).

What of the PRC?

The issues around the PRC are twofold. First, many of the larger potential foreign investors are state-owned enterprises (or state-controlled ones). We moved to reduce the role of state-owned companies in our economy, for good sound efficiency reasons, and we should establish a presumption in our foreign investment regime that foreign state-owned enterprises (especially ones that cannot operate at a genuine arms-length from government ownership/control) are unlikely to offer potential efficiency gains for the New Zealand economy. And second, because the People’s Republic of China is a regime (a) in which no one can operate fully at arms-length from the authorities (Party or state), (b) has a demonstrated record of not operating as a market economy, (c) shares almost none of the values of New Zealanders, and (d) represents a clear potential threat to the integrity and security of other countries, including in any future period of conflict. The fact that there may be many good, well-intentioned, investors from the PRC should simply not be relevant here, any more than the presence of decent well-intentioned Germans in the late 1930s should have left countries relaxed about German foreign investment at the time. The issue isn’t the individuals, but the authorities to which they are subject.

The risks around foreign investment from the PRC are not restricted to more-obviously sensitive assets (eg major media outlets or telecommunications systems) but apply more generally, partly because of the importance of PRC state-sponsored industrial espionage, but also because of the pervasive use by the PRC system of all sorts of potential sources of influence or connection. For example, vertically-integrated production and supply chains (including in the dairy industry, or the tourism sector would more difficult to withstand PRC attempts at economic coercion of the sort seen in various other countries in the last decade Investment from PRC sources represents a different and, generally, much more severe set of risks than that from Singapore, South Korea, Ireland or Canada.

More generally

The issue can be thought of in terms of a 2×2 matrix: there are benign countries large and small, and more troubling countries large and small. It is the larger and more troubling countries our restrictions should be focused on, and with regard not just to the current situation and immediate threats, but to maintaining resilience over, say, a 10 or 20 year horizon.

And to revert to the PRC

It is possible that such a near-complete ban on PRC-sourced foreign investment could come at some – likely modest – economic cost, the character of any such cost should not be seen as much different in kind to the price we pay for national defence and security systems. Without that expenditure, private consumption could be higher now – and potentially for decades to come – but we choose not to take that option because the recognise that there are risks and threats.

In this, as in other areas of public life, we shouldn’t be afraid to name the potentially hostile state and act accordingly, even as we would welcome such a state back into the fold when if the character of the regime changes. Germany and Japan were once our greatest threat, and are now close allies. They changed their regimes, systems, and strategic intent. When and if the government of China does, we should welcome foreign investment from there, commensurate with the values and practices of the new system. For now, however, we allow our system and society to be corroded from within to the extent we open our economy to significant PRC foreign investment, whatever the apparent short-term gains to individual vendors might be. It isn’t, by any means, the only (or perhaps even most important) set of PRC risks and threats but it is the one that is the subject of this consultation.

Businesses won’t care.  Governments should.  Ours appears not to.  The focus always –  be it on defence, the political system itself, or whatever (foreign investment, Confucius Institutes) – seems to be to minimise the issues, do as little as possible, try to pretend to the public there really isn’t an issue or potential threat at all.  That is pretty shameful and inexcusable.  That is our Prime Minister (and, of course, her chief rival has form suggesting that if anything he’d be worse on this score).

Talking of long-delayed inquiries, the Justice Committee’s inquiry into foreign interference –  the one the government didn’t want to open for public submissions at all –  has still not reported, and no reform legislation has been presented to Parliament either.   The big issues here are less about legislation than about will and mindset.  But again all the evidence points in the direction of big political parties preferring to minimise the issues to the very greatest extent possible.  Jian Yang, and the National and Labour Party “friends in Beijing” will be happy.

Long-term fiscal choices

Fifteen years ago now Parliament passed an amendment to the Public Finance Act requiring that every four years or so

the Treasury must prepare a statement on the long-term fiscal position

There is nothing in the Act as to what these long-term statement should cover, just a minimum time horizon” “at least 40 consecutive financial years”.

This wasn’t a pathbreaking fiscal reform by New Zealand.  By the time our amendment was enacted a fair range of other OECD countries had somewhat similar requirements (see table on page 4).

Fifteeen years ago I probably thought this new requirement was a good thing.  I’m much more sceptical now  It is unlikely that such reports do much harm, but:

  • they cost a lot to do (at least as Treasury typically does them –  the legal requirements could probably be met with a two page report),
  • come around much more frequently than any underlying issues change, and
  • there is little sign that long-term fiscal management is any better for them existing.

There are fiscally reckless countries and fiscally cautious countries, and there were both types before and after the introduction of long-term fiscal reports.  It isn’t obvious which country has switched sides (or moved much at all) as a result of these sorts of reports.  New Zealand, after all, introduced the requirement when our own fiscal surpluses were around an all-time high already.

What is more, the underlying issues are really pretty obvious to blind Freddy.   Here is what I wrote when the last Long-Term Fiscal Statement was released in late 2016

The Treasury yesterday released its latest Long-Term Fiscal Statement.  These documents, in some form or other, are now required under the Public Finance Act to be published at least every four years.  I was once a fan, but I’ve become progressively more sceptical about their value.  There is a requirement to focus at least 40 years ahead, which sounds very prudent and responsible.    But, in fact, it doesn’t take much analysis to realise that (a) permanently increasing the share of government expenditure without increasing commensurately government revenue will, over time, run government finances into trouble, and (b) that offering a flat universal pension payment to an ever-increasing share of the population is a good example of a policy that increases the share of government expenditure in GDP.  We all know that.  Even politicians know that.  And although Treasury often produces an interesting range of background analysis, there really isn’t much more to it than that.  Changes in productivity growth rate assumptions don’t matter much (long-term fiscally) and nor do changes in immigration assumptions.  What matters is permanent (well, long-term) spending and revenue choices.   

There really isn’t much more to it than that.

That statement was released in November 2016, which means –  time flying as it does –  the next report is due next year.   A Treasury that wanted impact might reasonably be expected to publish before the election, and if they do that they need to be sufficiently early in the year not to be caught up in the immediate highly partisan pre-election period.

As it happens I went to an event at Victoria University the other day at which one of Treasury’s researchers was presenting some modelling results of work done for the next Long-Term Fiscal Statement.  I can’t tell you about those results, but it did get me thinking about some of the past Statements and wondering how they looked with the passage of time.

In my excerpt above I referred only to spending on New Zealand Superannuation which, on current policies, will rise indefinitely as a share of GDP so long as life expectancy keeps increasing.  But the other big issue –  which sage Treasury officials will sometimes suggest is really the bigger one – is health spending.  There are new technologies and drugs, rising public demand, not much productivity growth (at least in the health sector in New Zealand), and an ageing population itself seems likely to create additional cost pressures.

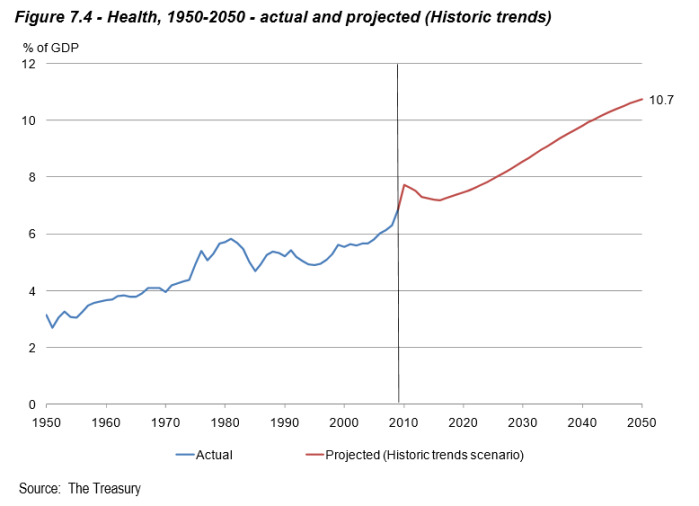
This is the sort of chart The Treasury likes to show, from the background papers to the 2009 Long-Term Fiscal Statement.

health 09

On those numbers, health would be a simply huge fiscal pressure, and the case for higher taxes might be hard to resist.

I’ve always been a bit more sceptical that health is quite the issue it is sometimes made out to be.  That is mostly because there are so many more dimensions on which government health spending can be adjusted than there are around NZS (for the latter, one can play with the age of eligibility, the rate, and the indexation formula, all of which get a lot of attention) and the societally-accepted boundaries are fuzzier (whose GP visits should be free or heavily subsidised, how much should be spent on drugs, how much other rationing should there be).

Anyway, on that 2009 Treasury chart, the projecting forward of historical trends (as Treasury did it) would have had government health spending by now (year to June 2020) well in excess of 7 per cent of GDP (eyeballing the chart suggests about 7.3 per cent).  Here is a chart from a recent post including budget numbers for the current (to June 2020) year.

cc2.png

Government health spending now is sitting just on 6 per cent.  It was about 6 per cent in the year to June 2008 (just prior to the recession) and not much below 6 per cent forty years (note that period –  the LTFS statutory focus) ago.

Now, quite possibly there is a totally unsustainable huge shortfall in government health spending at present.  But if so, none of the political parties is making that case (notwithstanding the rhetoric from Labour in the last campaign) or doing anything very much about, and since the issues around fiscal policy are really political in nature (how easy/hard is it to make decent choices in a timely way) it does suggest that the margins are more fluid, the fiscal outlook more readily malleable, than the quadrennial publications from The Treasury are sometimes taken as suggesting.   The system copes, and adjusts, perhaps less elegantly than officials might like, but that it does so nonetheless.  That is consistent with, now, 30 years of fairly sensible, often quite conservative, fiscal management by governments led by both main parties.  Adjustment rarely, if ever, occurs in response to projections 30 or 40 years ahead, but to pressures that become apparent within much more near-term windows.

As for NZS itself, personally I’m not overly interested in arguing the case for reform on fiscal grounds but on a rather more moral ground.    Even if we could afford it, even if there were no productive costs from the deadweight costs of the associated taxes, there just seems something wrong to me in providing a universal liveable income to every person aged 65 or over (subject only to undemanding residence requirements).    45 per cent of those 65-69 are now in the labour force –  suggesting they are physically able to work –  which is substantially greater than the 30 per cent of those aged 60-64 who were in the labour force 30 years ago when NZS eligibility was at age 60.

I don’t consider myself a welfare hardliner.  I think society should treat quite generously those genuinely unable to work, especially those who find themselves in that position unforeseeably.  Old age isn’t one of those (unforeseeable) conditions, but personally, I have no particular problem with something like the current flat rate of NZS, or even of indexing it to wage movements (which would be likely to happen over time anytime, whether it was the formal mechanism from year to year), from some age where we can generally agree a large proportion of the population might not be able to hold down much of a job.  I don’t have a problem with not being overly demanding in tests for those finding work increasingly physicallydifficult beyond, say, 60.   But what is right or fair about a universal flat rate paid – by the rest of the population – to a group where almost half are working anyway?  It is why I would favour raising the NZS age to, say, 68 now (in pretty short order) and then indexing the age in line with further improvements in life expectancy, and I’d favour that approach even if long-term fiscal forecasts showed large surpluses for decades to come.    At the margin, I’d reinforce that policy change with a provision that you have to have lived in New Zealand for 30 years after age 20 to be eligible for full NZS (a pro-rated payment for people with, say, between 10 and 30 years of actual residence).  Why?  Because in general you should only be expected to be supported by the people of New Zealand, unconditionally, in your old age, if most of your adult life was spent as part of this society.

Reasonable people can, of course, debate these suggestions.  But they are where I think the debate should be –  about what sort of society we should be, what sort of mix between self-reliance and public provision there should be, even about what mix of family support and public support there should be, or what (if any) stigma should attach to be funded by the taxpayer in old age –  not, mostly, about long-term fiscal forecasts.

Threadbare analysis and ideological causes

Last week a group calling themselves the Sustainable Finance Forum –  itself a creation of the self-selected left-wing environmental/political lobby group The Aotearoa Circle –  published an interim report.   The report is 70 pages long, but don’t let that deter you as there really isn’t much there.

Of course, this is not just any lobby group.  On the board of the Aotearoa Circle, for example, sits Vicky Robertson, chief executive of the Ministry for the Environment, and supposedly an apolitical public servant, advising ministers of whichever political stripe.  Oh well, never mind those old conventions…..   And one of the two co-chairs of the Sustainable Finance Forum is Matt Whineray, chief executive of the New Zealand Superannuation Fund, and supposedly an apolitical public servant charged with managing a large pool of taxpayers’ money from one government to the next.   Somewhat surprisingly (but welcome) the Reserve Bank Governor isn’t a full participant in this body –  although we’ve been left in no doubt of his ideological/political colours –  but the Bank (together with the FMA and the Ministry for the Environment itself) is described as an observer.

Of course, the participants aren’t all (or even mostly) public servants.   Woke left-wingery isn’t confined to the public sector and the second co-chair is a senior manager at Westpac, a bank which goes out of its way to advertise its enthusiasm for all such modern “worthy causes”.  There is a “technical working group” of 33 people and probably 85 per cent of them are employed in the private sector (it does seem rather a large technical working group for a report with only about 50 pages of text).

What there isn’t is much substance or much rigour.  There are dozens and dozens of grab-bag factoids –  some real, some not –  but little context.   There is no sense, for example, that these people have any real understanding of how our current levels of prosperity were achieved.  Perhaps more concerningly, given their breathless enthusiasm for stuff to be done, is that they demonstrate no awareness of the limitations of knowledge, the pervasiveness of uncertainty, or of the well-demonstrated capacity for governments to get things badly wrong.  There isn’t much sign either that they have read any economics beyond Kate Raworth.  And there is no sign either that they’ve engaged with Chesterton’s fence

In the matter of reforming things, as distinct from deforming them, there is one plain and simple principle; a principle which will probably be called a paradox. There exists in such a case a certain institution or law; let us say, for the sake of simplicity, a fence or gate erected across a road. The more modern type of reformer goes gaily up to it and says, “I don’t see the use of this; let us clear it away.” To which the more intelligent type of reformer will do well to answer: “If you don’t see the use of it, I certainly won’t let you clear it away. Go away and think. Then, when you can come back and tell me that you do see the use of it, I may allow you to destroy it.”

Perhaps the zealots are right and the end of the world is nigh, all that we have known must be up-ended etc, but it would be more reassuring if they showed signs of actually understanding why things are as they are.

The bottom line goal seems to “the transition to a sustainable economy” and yet this goal is simply not defined.   Since these peope are from the financial sector, they talk a lot about a “sustainable financial sector”.   In the media coverage of the report there was some coverage to the factoid that 95 per cent of respondents believed that the current financial system was not sustainable.  I was one of the people interviewed as part of the project and I was one of the 5 per cent –  partly perhaps because I was taken aback by the question: what on earth did “a sustainable financial system” actually mean?    As the financial system didn’t seem likely to fall over (even the Reserve Bank used to tell us that before the Governor when chasing capital whims), it had been with us in much the same form for a long time, and had proved adaptable as market demands and regulatory structures changed, it seemed a pretty obvious answer to me.   But clearly I wasn’t part of the inner sanctum, because in the report itself defines “a sustainable financial system” rather idiosyncratically as one that serves the ends favoured by the authors:

The aim of the project is to produce a Roadmap for Action on how to shift New Zealand to a sustainable financial system – from one which focuses primarily on (often shortterm) financial wealth creation, to one that supports long-term social, environmental, and economic wellbeing and prosperity for all  New Zealanders, protecting natural resources for future generations.

Strangely, there is no mention of the fact that –  relatively poor as New Zealand’s performance has been –  material living standards here are hugely higher than they were 100, let alone 200, years ago, and for most people the day-to-day experience of pollution is also much less serious than it was 100 years ago.  Technology, innovation, and finance have all contributed to those outcomes.   There is lots and lots of talk in the report about Maori perspectives and ways of thinking –  a better economic model we were told, one with no externalities apparently……. – but no apparent recognition –  or concern –  that Maori systems and worldviews (pre Western contact) had not exactly been tending towards the sort of high material living standards, and functioning financial system, that we take for granted today.

None of which is to be cavalier about where we stand now.  There are outstanding issues around water, for example. But it isn’t obvious what role the financial system has to play there –  regulatory issues around pricing, definition of property rights, access etc provide the backdrop against which borrowers/investors raise funds and other provide them.    And, of course, there is a climate change, but if anything is characterised by uncertainty it has to be that area.  One of the bugbears of the SFF (and the Reserve Bank Governor) is the (alleged) short-termism of the financial system, but they never seem to grapple –  including in this report –  with the fact that a relatively short-term approach is a prudent response to the risks created by uncertainty.

Pretty much every left-wing cause of the decade gets reference in the report.  Inequality is a big one for them, but with no substantial analysis one is left with the impression that it is mostly for effect, and mood affiliation.   Early in the report there was a referenced claim, for example, that  “New Zealand’s income inequality gap has impacted GDP by more than 15%”, but when I looked up the reference it was to a North and South article which itself claimed –  without a citation –  that

OECD researchers have suggested our gap has hobbled GDP by more than 15 percentage points in recent decades, largely because of disadvantaged families bailing out of education.

Well, perhaps….but since OECD statistics also show that New Zealand employee skill levels are among the very highest in the OECD it seems unlikely.  Oh, and returns to education in New Zealand appear to be quite low.  And what it had to be with a “sustainable financial system” wasn’t clear at all.  Being, apparently, a bunch of lefties they want a “comprehensive response to inequality” but what they mean, or what (if anything) it has to do with the financial system is left totally unspecified.   It was the feelings that mattered apparently.   They do claim the “current financial system” is contributing to “growing inequality”, but make no effort to justify either limb of that claim.

We got similarly feeble references to the so-called “gender pay gap”.  There was a whole page on modern slavery and labour exploitation, some of which was interesting, some of which was fair, but none of which had any discernible relevance to the New Zealand financial system.  Hard to disagree, I suppose, with the banner quote on that page that “a financial system cannot be sustainable if it undermines the basic human rights we all hold dear” but even if true –  and I’m thinking of exceptions as I type –  it isn’t overly helpful or offer any great insight on how the financial sector should adjust/evolve.

At the very front of the document the Aotearoa Circle told us about their vision which includes

They aim to achieve this by reversing the decline of our natural resources.

Which also seems pretty incoherent. I get the impression they have waterways in mind –  which is fair enough I suppose, within limits (the benchmark can’t be say pre-1000AD conditions) –  but natural resources include coal, gold, oil and gas, timber, ironsands and so on.  Did they not notice?   Are they proposing to put the coal back in the mountains –  the same coal burned in the process of generating the living standards we have now, and the potential to move towards newer (cleaner) technologies?    It is a small point in a way, but it is the sort of thing that is likely undermine any good a report of this sort might do among those who aren’t uncritical “true believers” to start with.

There is all the talk about rising sea levels and what this might mean.  That partly involves using scary numbers about the value of affected buildings, but without any reference to the twin facts that (a) the dates they are quoting are mostly many decades away, and (b) existing structures depreciate.   And then, of course, there is the talk about access to finance and insurance.  Which are real issues no doubt, but they don’t unfold overnight –  they are some of the better-foreshadowed risks companies have ever faced –  and no reason (identified in the report) why existing market participants (and perhaps new entrants) can’t/won’t respond and adjust, in response to their own incentives, as they’ve always done.     Same goes for wider climate change issues: the report claims ‘financial markets in New Zealand..are still largely misaligned with climate change and other sustainability imperatives”, but they offer no evidence for this –  not a shred.

These people also have a bunch of other ideological causes.  They appear to champion the Living Wage as a policy response to New Zealand’s poor productivity.  Not only is that incoherent, but there is no obvious connection to the financial system (“sustainable” or otherwise)     They rightly lament the high cost of housing –  although never point out that were these government-driven distortions ever to be reversed and the market able to function well that housing finance would be a much much smaller part of bank balance sheets in future.  Oh, and they are dead keen on Australia’s compulsory private superannuation system –  but I guess we should mostly just put that down to (consciously or unconsciously) pure self-interest (it is a great system for financial industry service providers, while our own retirement income system generates very low rates of elderly poverty with a pretty modest fiscal burden).

And we get the best part of a full page on the Reserve Bank/FMA crusade around bank culture and conduct, all of which skated over the fact that when those agencies reported back (on their largely ultra vires activities) the bottom line was that there was little evidence of any sustained problems.  But I guess that wasn’t the narrative these left-wing crusaders wanted to channel.

Buried amid the blather there are probably a few sensible paragraphs on a few specific regulatory issues, but what might be valuable is largely lost amid the rhetoric, and the rhetoric itself is of much-diminished value because there is so little hard-headed substance.  We know for example that the Orr/Whineray NZSF could get away with making a big active punt on climate change, and so mask the punt that we can never properly hold them to account for it.  But that is the weakly-accountable government for you.  Most investors, most savers, want more than idle calls for the financial system to work for the “good of society”, however ill-defined that may be.    All manner of chancers and opportunists  (public and private sector) will tell you their project, their plan is “the one”.  The challenge of anyone –  especially anyone investing other people’s money –  is to be able to recognise the good from the bad, manage the risks etc.  And none of that is easy.  None of us knows what the economy will look like 30 years hence, let alone this time next century.  Not even Whineray and Silk.

There is an opportunity to submit on the interim report (link here). I’m not sure I’ll even bother.  It is so bad (and so ideological) they’d really be better off ripping up the report and starting from scratch with a much more hard-headed approach to thinking through the issues and challenges, constraints and opportunities, including demonstrating a thorough understanding of the strengths and weaknesses of the current system   But I guess that wouldn’t suit their mates in the Labour and Green parties, for whom reports like this help provide cover, even when largely devoid of substance, insight, or sustained robust argument.


Officials in pursuit of more powers

It is a big few weeks for the Reserve Bank and, in particular, the Governor.   This week the Monetary Policy Committee is gathering for its deliberations leading to next week’s  Monetary Policy Statement.  A couple of weeks later there is the Governor’s six-monthly Financial Stability Report,  and the week after that we are told that the Governor will descend from the mountain-top and reveal his decision on bank capital.   There are at least two press conferences scheduled (MPS and FSR) and given that he has deliberately chosen to release the momentous capital decision only after the FSR press conference one has to hope that he will make himself available to explain and defend his choices (and, although he has staff, all the decisions –  and responsibility for them –  are his alone).

Meanwhile stories rumble around about the possibility that the Bank’s Board has,for once, found its voice and suggested to the Governor that he needed to change his style.  I heard yesterday another version of a story that culminated in the Governor yelling at the chair of the Board after the latter (so it was reported) suggested that aspects of the Governor’s conduct were unacceptable.   I have no way of knowing whether these stories are true, or are just wishful thinking, but given the quiescent and deferential track record of the Board over many years, it would be perhaps a little surprising if there was nothing to the stories now.

One of the other projects the Reserve Bank has underway, which attracts less attention and controversy, is that around the future of cash.  It is both an apt issue to be focusing on and, at the same time, something of an odd one.  And, remarkably, in the discussion document the Bank put out a few months ago there was no mention –  at all, as far as I can see – of the most immediately pressing issue: the limits on the ability to cut the OCR that arise because of the (near) free option people have to shift from bank deposits etc to physical cash.

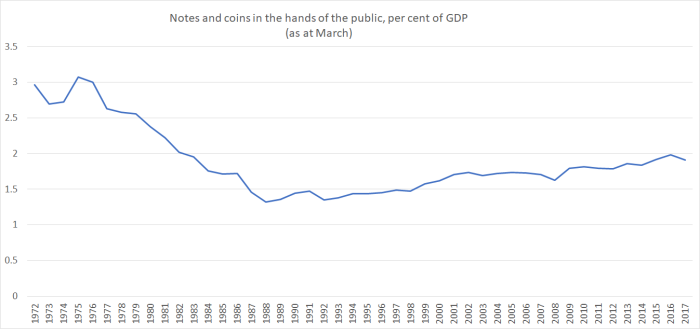
The future of (physical) cash is somewhat of an odd issue to be focusing on because cash outstanding has been rising relative to GDP.    This chart is from the Bank’s discussion document

cash 1.png

It tends to exaggerate the point, by starting from the trough.  Here is a longer-term chart from a post I wrote on these issues a while ago

notes and coin

All else equal, when interest rates are very low (and inflation is low too) people are more ready than otherwise to hold on to physical cash.  Of course, quite who is actually holding the cash, and for what purpose, is a bit of a mystery, one not really addressed in either the Bank discussion document or in the poll results they published last week, framed in terms of a high preference for using electronic payments media whenever possible.

The Bank included an interesting chart in its document illustrating that although the ratio of cash to GDP is quite low in New Zealand, the rise in that ratio wasn’t out of line with what has been seen in quite a few other advanced countries.  Sweden and Norway –  where the ratios have fallen –  are outliers.

cash 3.png

There is quite a strong suggestion that in the most recent period a big part of what is holding up currency in circulation was the surge in overseas tourism, especially from China.

cash 4

Overseas tourism remains one of the areas where physical cash is much more likely to be used than in normal domestic spending.

Notwithstanding these routine and entirely legitimate uses of physical cash, it is still hard not to conclude that a large chunk of the physical cash on issue –  in excess of $1000 per man, woman, and child –  is held to facilitate illegal transactions, including tax evasion.   That was Rogoff’s view, and as I wrote about here he –  against my priors – converted me to that way of thinking.

So there would seem to be no risk of cash disappearing from the New Zealand scene any time soon.   And yet the monetary policy constraint arguments, that the Bank simply doesn’t address in its discussion document, suggest that if anything the use of Reserve Bank cash (and especially the potential use of cash) should be constrained more tightly than at present.  The Governor may repeatedly assert that unconventional monetary policy options will do just fine, but few other people would look at the international experience of the last decade without thinking that monetary policy ran into limits.  Those limits arise mostly because of the non-interest bearing nature of the cash and the near-free option of converting into physical cash if returns on other short-term securities go, and are expected to stay, materially negative.

This limit need not exist, or at very least could be greatly eased.  Abolish the $100 note, for example, and at very least you double physical storage costs of secure large cash holdings.  Abolish the $50 note and you more than double the costs again (while the ability to give your kids pocket money in cash, or to use cash at the school fair isn’t materially affected).  That was, basically, Ken Rogoff’s argument in the US (restrict central bank notes to no more than $20 bills).  I’ve argued for one of a range of more-wholesale solutions that have been proposed: put a physical limit (perhaps indexed to nominal GDP) on the volume of currency in circulation (perhaps with overrides for bank runs), and auction the right to purchase new issuance (there is no reason why newly-issued cash has to trade at par).  Do that –  perhaps even set the limit fairly generously –  and the effective lower bound, as a convertibility risk issue, is abolished at a stroke.

This is coming close to being a fairly immediate issue.  No one supposes the Reserve Bank could, on current technologies, usefully cut the OCR by 200 basis points or more in a new recession, and yet in typical New Zealand recession something more like 500 basis points has been required.

It is pretty staggering that they haven’t addressed these considerations at all in their document.  Instead, having had submissions (lots of them) on the first consultation document, they issues another consultation document (deadline for submissions tomorrow) bidding for more Reserve Bank powers over the currency system.

The currency system seems to have rubbed along tolerably well for the 85 years since Parliament gave the Reserve Bank a statutory monopoly on the issuance of bank notes  (it seemed to function just fine in the earlier decades as well: whatever the case for setting up a Reserve Bank there was never a robust case for the statutory monopoly on bank notes).

But none of that deters the Reserve Bank.  It is a rare bureaucracy that looks to shrink itself, or is averse to an expansion of its powers, and the modern Reserve Bank seems to be no exception.  This is their bid

cash 5.png

As they note, there is no need for any such powers at present.  Which really should be determinative.  It isn’t like preparing for an extreme national disaster, where it makies sense to have some precautionary powers on the books.  This is about a payments media that is gradually being used less and less (for payments) and where change is exceptionally unlikely to happen overnight.     Were there ever to be severe problems, surely Parliament could address such issues when they arose, rather than inventing new laws now –  and delegating the use to unelected, not very accountable, officials –  just on the off chance?

There should be a strong pushback against this bid for power.  Their (short) document makes no compelling case for legislative action –  and more discretionary regulatory power – now.  Indeed, as they note

There is a host of international examples where cash system participants have found different solutions to fit their unique economies.

It is what the private sector does –  innovate in response to market incentives and opportunities.  They worry –  as busy bureaucrats will –  that “no single organisation has system-wide oversight of the cash system or a formal role to support it”.   There is no such organisation for, say, the corner dairy sector either.  Nor an obvious need for one –  let alone for the government to be taking charge.  They complain that they don’t have information gathering powers over participants who aren’t banks, but offer no analysis or convincing demonstration as to why they should have such powers.

They offer no analysis either as to why the market could adequately manage issues around ATMs or other processing machines, or even for the quality of the notes retained in circulation.    Much of it seems to be made up on the fly –  so it seems, to catch the decisionmaking process around other changes to the RB Act.  Thus they talk of powers to compel banks to distribute cash, but seem to have thought through very of this bid for power for hypothetical circumstances.  This, for example, is the last substantive paragraph of the document.

How accountability would be defined under such regulation, and therefore how sanctions could be applied, warrants further consideration. Banks could be held collectively accountable for the provision of cash services, meaning that banks would share the responsibility for providing access to cash, and all banks within scope would face sanctions for each case of noncompliance. This would be a novel regulatory structure in New Zealand, but might be practically workable and might encourage greater cooperation among banks. Alternatively, each bank could be individually accountable for the provision of certain services in certain areas. However, this presents challenges around how accountability is allocated. Both options present considerable practical challenges, which will need to be investigated in consultation with relevant parties if any policy is developed.

Doesn’t exactly instill much confidence.

Many of the problems the Reserve Bank worries about (perhaps arising one day) would, in any case, largely be a reflection of the statutory monopoly on banknotes. So perhaps a better legislative route would be to look at repealing that restriction –  simple one clause amendment to the Act would do it –  and allow banks to issue their own notes.   Perhaps it is now a little late for that, but we don’t know if we keep on ruling out the opportunity for innovation.  It might be considerably cheaper for banks to issue their own notes (as they issue their own deposits) –  since they wouldn’t have to worry about returning them to a central point for value –  and, conceivably, technological innovation might even allow interest-bearing bank notes  (it is the zero interest nature of  the existing notes that creates the lower bound issue for monetary policy).

Bids for new regulatory powers are often a response to issues, problems (or possible future risks) thrown up by existing regulatory or legislative interventions.  The Bank’s latest bid for more discretionary powers seems exactly in that class of bureaucratic initiatives.   The Minister of Finance should say firmly no to this latest bid, should insist on the Bank openly addressing the effective lower bound issue, and might consider asking the Bank what public policy end –  other than higher taxes –  is served by maintaining the 85 year old monopoly on note issuance.  We got rid of most statutory monopolies a long time ago.


2019 vs 1969

I was listening to a thoughtful podcast discussion yesterday between one of my favourite US commentators, Jonah Goldberg, and Marian Tupy of the Cato Institute (where he a responsible for the Human Progress website)    This morning I read a column by economist Noah Smith along very similar lines.   The bottom line: life just gets better and better (the podcast discussion was more wide-ranging, across history and across countries, and somewhat more reflective, while Smith’s –  much shorter – piece was comparing life in the US in the 1950s and now).

I’ve read numerous books and articles along similar lines: as just two examples, Steven Pinker’s Enlightenment Now and Matt Ridley’s  The Rational Optimist. I’ve even run some of these arguments myself in a New Zealand context, illustrating just how different material living standards are now relative to those 100 years ago.

You won’t get any disagreement from me to the proposition that a market-oriented economy is the best mechanism known to man –  although its innards, which bits matter most, still have elements of mystery –  for generating material prosperity.  You also won’t get any disagreement from me that some times/places in human history have been better than others (on almost any aspect conceivable).  Then again, there have been times and places worse –  sometimes materially so – than those that went before.   Any society in the midst of a civil war is almost inevitably in a particulary undesirable situation.   1970s Cambodia was almost certainly worse than, say, the colonial era, 1940s Germany worse than most times in German history (notwithstanding the fruits of material progress), and so on.

Material gains –  whether things, life expectancies, or whatever –  aren’t everything but they aren’t nothing either.   Even abstracting from the war going on at the time, I was sympathetic to the proposition that no amount of money would make any modern American change places with John D Rockefeller 100 years earlier (except of course that some things of value have no price). I don’t even suppose there are too many takers for 1969 Czechoslovakia (Tupy is of Slovak ancestry) over today’s Czech Republic or Slovakia (not even all those US millenials who answered a recent survey suggesting they had a favourable view of communism).

But some choices –  not ones actually open to us, of course, but thought experiments –  are much less clear-cut.   I got to reflecting on life in New Zealand 50 years ago and that now.

At a material level, even as a woeful underperformer on the productivity front (although yesterday’s release from SNZ suggests they may have found another 1-2 per cent of productivity –  level, not growth rate), real GDP per capita or per hour worked are significantly higher than they were 50 years ago.  But to what end is less clear.

Fifty years ago I lived in Kawerau, which was probably as prosperous a town, if new and a little raw, as could be found in the country –  fruit of the Think Big project of the 1950s.  (From all I’ve seen and read, life in Kawerau today is probably worse than it was then.)  But that isn’t really my comparison.   We didn’t have a great deal –  my father had just taken up a role as pastor of the local Baptist church –  but two of my uncles were partners, apparently reasonable successful, in professional practices in central Christchurch (one law, one accounting).   And if I contrast the lives they, and aunts and cousins, had then with the life my family lives now –  I was a well-paid public servant for decades, my wife now is a well-paid senior public servant –  it is hard to spot the nature of the substantial gains (which isn’t a complaint at all).  That is probably even more true if I contemplate the prospects for my children, given what successive governments have done to the housing market.

Perhaps it is something about my/our tastes, and I’m certainly not suggesting the average material standard of living is worse than it was, just that the gains don’t count for that much with me (unlike, say, the gains in the 50 or 100 years prior to that) –  mostly nice-to-haves rather than things which have me celebrating leaps and bounds in human progress.  Are the cars fancier?  Well, yes of course, but I’m not one of those who greatly values cars.  Is the internet nice to have?  Well, of course (and I’d not be writing this without it), but in what ways would we be substantially poorer without it (it offers an improvement on weekly news magazines and newspapers, but not that much of one most of the time)?  Mightn’t most parents prefer a world in which schools weren’t pervaded by smartphones and their distractions.   There is immense choice of eating out options I guess, but frankly I like to cook, as did my mother.  Again, perhaps it is a matter of tastes.   But the proposition of the evangelists of “progress” is that even the material gains are self-evident and (at least by implication) substantial.  I’m not disputing there are gains, but how much weight one might put on them is another matter.  For materialists, I guess quite a lot, unless diminishing marginal utility sets in for them as well.

(This isn’t, of course, an original point, and is –  among other things –  something of a variation of the story US economist Robert Gordon tells, in suggesting that the real lifestlye-improving gains happened decades ago.)

Perhaps the gains in life expectancy for those born seem less arguable.  And I’m certainly not going to dispute that they are real.  But it brings us closer to the deeper questions about the purpose of life. And about which lives.  And what life.

As compared to 1969, New Zealand now legalises –  and has the taxpayer fund –  13000+ abortions a year, and this ability to have one’s own child put to death is deemed by our leaders some sort of basic human right, a matter of “health”.

As compared to 1969, our society grapples with disconcertingly high suicide rates, especially among some of our young people.

And, as compared to 1969, our system is on the brink of legalising assisted suicide.

In some parts of other Western societies, even adult life expectancies are falling, fruit of some mix of drugs, isolation, despair or whatever.

And for any Christian –  and Christianity has shaped the culture from which the bulk of our population comes for perhaps 1500 years –  this earthly life is just the foretaste, the preparation, for eternal life with God.  That doesn’t make life on earth unimportant –  far from it –  but creates a different perspective on the value one might attach to a few more years here.    Societies in which there is nothing more are also ones in which it is much harder to envisage a cause, a choice, worth dying for.

Why else might one legitimately be underwhelmed by what has become of the country since, say, 1969? I could list:

  • the rise of welfarism,
  • the normalisation of birth outside marriage,
  • the abandonment of any societal recognition of the importance of marriage as a bedrock institution of society.
  • the coarsening of our culture (each Saturday I’m still astonished that the Herald runs a column celebrating what were once vices, in some traditions even “deadly sins”,
  • easy and extensive access to pornography (flip side of the advantages of the internet), that degrades all those involved,
  • the normalisation –  nay celebration – of the vice of homosexual practice,
  • the current transgender mania,
  • the loss of any sense of a unifying day of rest.

And, at the heart of it, the decline in Christian faith and observance (there were never “golden days”, but everyone recognises the difference between then and now.  Every society has a “religion” of sorts –  the taboos and understanding by which societies operate and people interact –  and I find almost nothing appealing about modern New Zealand’s provisional replacements for Christianity.

I could go on and add that in 1969 our main political parties and their leaders were pretty clear about the nature of Communism and the evil represented by the regimes in the Soviet Union and the People’s Republic of China.  The Soviet Union has, mercifully, gone, but the evil represented by the PRC/CCP is as real as ever, and more threatening to us, since our “elites” have abandoned all sense of right and wrong where the PRC is concerned, pursuing (it seems) only money, whether through trade or party donations.

And there is the increasing power of the state, enabled by technology.  Surveillance, and coercive, states aren’t just a threat in China.

And so on and so forth.

Are there alternative perspectives?  Well, of course.  Perhaps as many as there are “religions” or world views.   Some will regard where we’ve got to in the last 50 years as a giant step forward.  For all the material and (often double-edged) technological advantages, personally I’d exchange 2019 New Zealand for 1969 New Zealand.  It isn’t a choice or an option, but to me what we’ve gained is small compensation –  not even really directly comparable –  to what we’ve lost.

Credit conditions

Back in mid-2009, just as the first glimmers of recovery  from the severe recession were emerging, the Reserve Bank launched a credit conditions survey (of lending institutions).  It was a sensible enough initiative but, to be honest, I never paid much attention to it.  We knew conditions had got very tight during the recession and (at least in my remaining time at the Bank) the data weren’t that interesting –  of course credit conditions were easier than they’d been in the midst of that financial scare, and when there were changes shown they were for pretty obvious reasons (eg access to housing credit was reported as tightening when the Governor imposed LVR restrictions).   Also, the number of institutions covered was quite small, and one had to worry that results could be affected by who happened to fill out the form in a particular institution on a particular occasion (plus, when reporting to your prudential regulator incentives aren’t entirely straightforward).

There is a series of questions about:

  • observed loan demand (by class of loan),
  • expected loan demand,
  • observed credit availability,
  • expected credit availability, and (since early last year)
  • a series of factors potentially affecting the availability of credit.

That makes for lots of series.  I’m less interested in the demand side, which is largely going to reflect stuff we see captured in other data (eg housing turnover, business surveys etc).  But demand for new business loans does seem to have fallen away somewhat in recent years.

But what about the supply side?

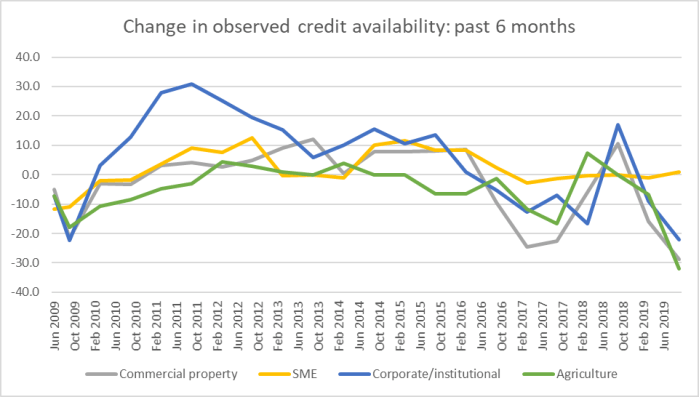
Here is observed credit availability over the last six months (the survey is six monthly) for the four business sectors (there was no particular change in availability to households).

credit 1

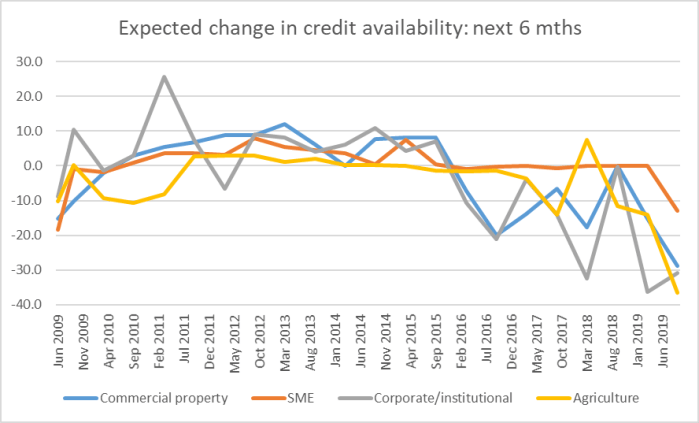
And here is what respondents expect (presumably from a position of knowledge, responsible for something around overall credit within their own institution).

credit 2.png

Yes, there is some idiosyncratic variability in the response at times, but in the ten year history of the series we’ve seen nothing like the tightening in expected conditions observed in the last few quarters, now across all the business classes (there is little movement on the mortgage and personal household lending categories).

It isn’t easy to know quite how much weight to put on these responses –  for a start, with only one incomplete cycle of observations, we have little idea of “normal” variability as economic conditions turn down.  But as the recent downturn is larger than the post-2009 upturn (coming off a pretty savage tightening in conditions) it doesn’t have the look of something that should be quickly glossed over.   It looks to represent a potentially quite material tightening in monetary and financial conditions.

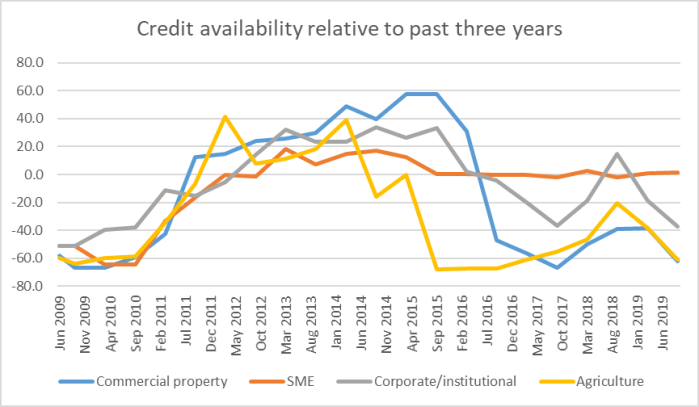
The other question they have about actual credit availability might also tend to confirm that unease.  Respondents are asked about how credit availability is now compared to the past three years (I guess to smooth through idiosyncratic influences on the past six months).  Here are the responses for the business sector loans (household was directly and materially affected by the waxing and waning of LVR restrictions, a policy intervention).

credit 3.png

Again interesting that there had been little movement re SMEs, but for the other three business categories the scores are getting back towards levels we saw just after the last recession.

Early last year the Reserve Bank did a welcome extension to the survey and started asking respondents about the influence of various specific factors that could reasonably influence credit availability.  Here are answers.

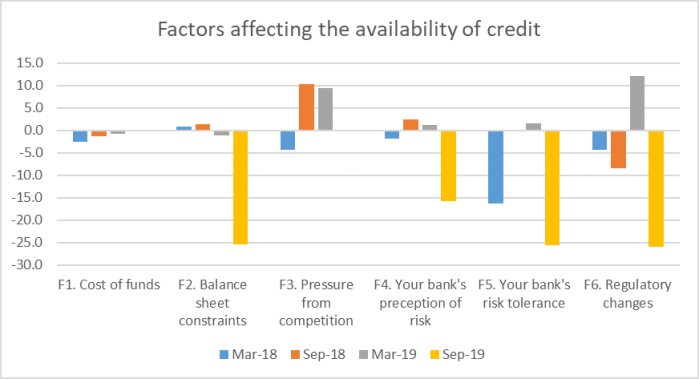
credit 4

Cost of funds hasn’t been an issue in changing credit availability (nor would you really expect it to be –  should affect price rather than availability), and neither has competitive pressure, but look at those four striking negative yellow bars.    Risk appetite among the lenders, risk capacity, and (distinctively) regulatory changes have all worked to (apparently materially) tightened credit conditions.

Sadly, here we reach the limits of the survey. It would be fascinating to be able to disentangle quite what is going on.  There is a quite plausible story that all three of the other negative yellow bars are primarily a reflection of the fourth, regulatory change (presumably the Governor’s capital whims).  Perhaps it isn’t so, and there are independent reassessments of risk and willingness to bear risk going on in head offices, whether here or in Australia, but whatever the precise combination of factors it is pretty likely that regulation is already weighing fairly heavily on credit availability in New Zealand. (I only qualify that claim a little because banks perhaps have an incentive to play up the issue, knowing that the Governor is about to make his final capital decisions, but I doubt that is more than a marginal factor here, given the small number of respondents and the ability of the Bank to query each).

You may recall the consultation document the Bank published almost a year ago on the Governor’s proposals to greatly increase capital requirements for locally-incorporated lenders.  You may not recall the discusssion of these sorts of effects, let alone the apparent differential sectoral effects.  That isn’t the fault of your memory.  There just was no discussion of those issues in the document.  Which seemed odd at the time, and even more extraordinary now.  It will be interesting to see how the Governor responds to these data in his two scheduled press conferences in the next few weeks (MPS and FSR).

While these data are clearly of some relevance to the bank capital debate, my main interest in them was in the more immediate issues around the appropriate stance of monetary policy and the setting of the OCR.   There appears to have been quite a sharp change in market sentiment/pricing and the views of some market economists this week on the chances of the Bank cutting the OCR on 13 November (the reasons for that change still aren’t fully clear, and one is left wondering if the Bank has been signalling –  by accident or design –  some change in its own view).

My interest is much less in what the Bank will do in the short-term, but in what they should do (which should, of course, make my commentary of interest to the Bank, given the Assistant Governor’s speech the other day, but…..).  “Will” and “should” eventually tend to converge, but it can take some considerable time for them to do so.

But if we grant that this credit conditions data is material the MPC did not have when they did their August forecasts, or made their slightly panicked last minute decision on a 50 basis point cut, and did not even have at the last OCR review, it really should be  colouring the projections they finalise next week (even if the variable might not feature in their formal models).  Add in own-activity business survey data that has shown no signs of rebounding since August, inflation expectations that have either fallen further (surveys) or remained very low (inflation bond breakevens), and a core inflation rate that remains consistently materially below the (focal) midpoint of the inflation target, the case for not cutting the OCR in November seems weak at best.  There isn’t another review opportunity until February, the world situation (if not one of sentiment spiralling downwards) seems no stronger substantively, and for a committee that was sufficiently rattled to do a 50 point cut only three months ago –  and not to have seen anything much improve since then –  to do nothing now would only further muddy the communications waters, leaving people even less clear about how the MPC thinks, or that there is a consistent and disciplined process at work, secreted away from the public/market spotlight.

(Bearing in mind that there is still some material local data to be released before 13 November) the risks around a further OCR cut in November at present look quite asymmetric.  As we drift closer to the next recession, and to the limits of conventional monetary policy, the very best thing that could possibly happen would be positive surprises on core inflation, spilling over into somewhat higher inflation expectations.  People are no longer convinced inflation will settle at 2 per cent or above. It would be better, for almost everyone (certainly for the management of the next downturn) if they were.   When credit conditions appear to be tightening quite materially –  and that even before the final decisions are announced –  getting that sort of outcome will be made harder than necessary if the Bank ends up setting on its hands, confusing messaging, all for what?  So that the Governor can get some perverse psychic satisfaction from surprising people again?   Unpredictability is not a desirable feature of public policy.


Monetary policy communications and the lack of transparency

The Reserve Bank’s Assistant Governor for monetary policy and financial markets, Christian Hawkesby, went off to Sydney earlier this week to talk to some investors about New Zealand monetary policy communications.  Hawkesby now has tenure and independence –  at least in principle – as a statutory officeholder, a member of the Monetary Policy Committee, appointed directly by the Minister of Finance.

It was perhaps telling that (a) the speech was delivered on a New Zealand public holiday, (b) the text wasn’t released for another 24 hours, and (c) we have no record of what Hawkesby actually said, including in response to questions.  That is no way to do monetary policy communications.

Perhaps while he was in Sydney Hawkesby dropped in on his peers at the Reserve Bank of Australia.   The RBA has about 45 speeches/presentations from senior managers showing on its Speeches page for 2019.   For all but three of them –  and none of those three on topics that appear market-sensitive –  there is video, audio or a Hansard transcript (several of the Governor’s appearances were to parliamentary committees).  It doesn’t seem to make any difference to the RBA whether the speeches etc are given overseas, out in the provinces in Australia, or in downtown Sydney or Melbourne: the standard they set for themselves is that when they say something, it is made generally available.    Anything else poses a risk –  actual or in appearances –  of unequal access to potentially market-moving, or just insightful, official information and perspectives.  That is just one aspect of communications on which the Reserve Bank of New Zealand falls a long way short of best practice.  There are 12 speeches from senior managers on the Reserve Bank of New Zealand’s Speeches page for 2019, and for only of them is there video footage (that a puff piece by the Governor –  which I wrote about here).

Hawkesby’s speech came in two parts.  The first was devoted to repeating longstanding Reserve Bank spin about how transparent it is, supplemented by some Orr-esque lines about how surprising the market is no bad thing (the second part was defensive play around the surprise August 50 bps OCR cut).  There were no fresh insights or arguments, which in itself was a bit disappointing from so senior a figure, relatively newly returned to the Bank  –  despite the relatively junior-sounding title, Hawkesby is, in effect (and in Wellington public service lingo) a deputy chief executive responsible for half the Bank’s core functions.  Anywhere else in the world he’d carry a Deputy Governor title.   Those are the standards his speeches should be held to.

The Reserve Bank (longstanding) main claim to being highly transparent is that it publishes a future track for the policy interest rate (the OCR) for a period two to three years ahead.  We were the first central bank to do so, in 1997.  As Hawkesby notes, despite 22 years experience, only a handful of other central banks  (four small advanced country ones) have followed our lead.  Reasonable people can debate whether publishing a forward interest rate track is the best way to do things (I’ve never been convinced myself) but when none of the world’s leading central banks have taken that path –  and all will, quite seriously, proclaim a commitment to transparency –  it probably isn’t something to put quite as much weight on as the Bank has done (through successive Governors/staff).

I’ve characterised the publication of the forward interest rate track as being highly transparent about something the Bank (now, at least formally, the MPC) knows almost nothing about.  Economic forecasting is a mug’s game, and there is little evidence that anyone can usefully forecast economic developments more than perhaps a quarter or two ahead….and yet, monetary policy works with a lag, so a medium-term OCR projections (for, say, 2.5 years ahead) implicitly requires –  to be meaningful – some intelligent view of inflation prospects perhaps four years hence.  No one can do it in a way that has any useful substantive information.

And if the Reserve Bank is pretty transparent about the stuff it knows almost nothing about –  and has to divert scarce resources to generating such tracks –  it is really quite strikingly non-transparent about the stuff it does know more about.  For example:

  • we have a Governor, clearly the most important player in the system, who has not yet given a particularly substantive speech on monetary policy, the economy, and inflation (which would otherwise offer insights on his thought processes, his mental models, his ability to process and analyse data etc),
  • we have a Chief Economist –  also a statutory appointee as member of the Monetary Policy Committee –  who has not given a speech or said a substantive word in public since he was appointed,
  • as above, the Bank isn’t particularly transparent around the speeches it does give (and especially around answers to questions),
  • we have three non-executive members of the Monetary Policy Committee from whom not a word has been heard since they were appointed.  We know nothing about how any of them think about the policy targets towards which they are working, about how economic developments are unfolding, or about the “reaction functions” they use  (and this is so even though the rules allow them to speak), and
  • the Bank is totally untransparent about the background analysis produced to support monetary policy decisionmaking.   The current government –  not naturally particularly transparent –  has adopted a practice of pro-active release of Cabinet papers, many Budget-related papers have long been pro-actively released, but ask for any background papers re monetary policy decisions –  even with quite a lag –  and the Bank will simply refuse (and, sadly, they have the ineffectual Ombudsmen –  over several appointees – wrapped around their little finger in clasping this taxpayer-funded analysis tightly to their chest).  Perhaps it is lawful, but it simply isn’t transparent.   (A few years ago, after many months of trying, I managed to get them to release background papers for an MPS from 10 years previously –  but no one supposes they would release such material from, say, two years ago.  If there is a decent argument for any confidentiality around this material, it could only credibly mounted for the period from one MPS to the next –  ie three months or so – at most.)

That isn’t good monetary policy transparency, nor is good open government (the latter not being a consideration that ever weighed much with the Bank).

Hawkesby attempts a defence of the Bank’s preferred practice, in which only the Governor speaks about monetary policy (no speeches of course, just MPS press conferences) and to the extent that underlings like Hawkesby speech they largely parrot the Governor.   This is the best he can manage

A third limitation of transparency is the noise that it can create – an example of this is how to capture the diversity of views of individual members of a committee tasked with setting interest rates.

An example of this is how to capture the diversity of views of individual members of a committee that sets interest rates. Each individual member regularly sharing their views on the economic and policy outlook can make it harder for financial markets to interpret the reaction function of the collective group. While I worked at the Bank of England, I always remember the head of communications bemoaning the cacophony of voices. More transparency around the perspectives of individual members could also create incentives for those individuals to hold on to a previously published position even as new information emerges, for fear of being seen as ‘conceding’ their position.

A paradox of these limitations is that greater transparency does not necessarily equate to increased clarity for market participants and the general public. Just because more information is available does not necessarily mean the audience will have a greater understanding of how and why central banks make decisions.

But there isn’t much there.  Of course Communications managers are keen on message discipline –  always have been, always will be –  and at the Bank of England management was long not very keen on the independence of the external MPC members anyway.  But isn’t it striking that whereas the Reserve Bank seems to believe that New Zealanders –  public, markets –  can’t cope with a diversity of views (about a highly uncertain business), the national central banks for the largest advanced economies –  the US, Japan, and the UK –  in fact do cope quite well with having MPC members explicitly voting against a majority view, or articulating a model or analytical insights a bit different from that of others on the relevant committee.   Sweden is a succesful small country example.  The ECB is a bit different –  and there are some reasons why, around minimising pressure on members to act for their own country’s national interests –  but even in the ECB there is plenty of open recognition of differences of view among the monetary policy decisionmakers.   It isn’t as if central bankers know from year to year –  often not from quarter to quarter –  what they are going to do: events happen, interpretations evolve, and particular hypotheses are openly challenged and scrutinised (including those of monetary policy decisionmakers, when we are allowed to see them).

So, no, the Reserve Bank of New Zealand really isn’t particularly transparent at all.  And the newly published minutes really represent not much of a step forward at all.

One of Hawkesby’s points is that the Bank is keen to learn from outsiders –  yes, even “bloggers”.

When private sector economists, analysts, commentators or bloggers don’t agree with our policy decisions or our projections for the economy, it can be an uncomfortable message to hear. But it is an invaluable exercise to test our assumptions and reasoning, even if we don’t agree with their conclusions, we inevitably learn something along the way and strengthen our analysis of the issues.

Good to know (although it is a bit to take seriously when we see how the Governor responds to challenge, criticism, or alternative perspectives on another of those highly complex and uncertain issues –  appropriate bank capital requirements).

But this line is really used to buttress a rather silly line the Governor has run on a few occasions about the (alleged) dangers of the markets paying too much attention to trying to guess what the Bank is up to, in turn (allegedly) reducing the information the Bank itself can get from market prices.   This is, we are told, one reason why it is just fine for the Bank to do things that take markets totally by surprise (notably, the 50 basis point OCR cut in August).

It really is a nonsense argument, even if he can find a couple of footnotes to attempt to buttress his case. In fact (and in effect) he more or less concedes later in the speech when he highlights things like falling medium to long-term inflation expectations (including from the indexed bond market –  a welcome Hawkesby innovation to have the Bank even acknowledge the indicator) that were concerning the MPC when they made their decision.  Almost certainly those indicators –  eg from 10 year bonds – would have been just as they were whether markets thought the Bank was going to cut 50 bps in one go, surprising almost everyone, or (say) spread the cuts over two 25 bps cuts.

I’m not one of those who think that monetary policy decisionmakers should always deliver on market expectations. But usually if market expectations are very wrong (not –  eg –  just 10 expected a cut, 12 expected no change) it is the fault of the monetary policy decisionmakers themselves.   In those circumstances, they add noise and volatility that is simply unnecessary and has no redeeming societal merit.

And as I noted at the time of the August MPS, the 50 point cut looked a lot like a rather rushed last minute decision, that wasn’t really supported by other the numbers (they themselves produced) or the MPS text.

And what makes it a bit more concerning is that it is pretty clear the Bank itself wasn’t intending to move by 50 basis points even a few days ago.  The projections they published yesterday were finalised on 1 August (last Thursday).   On those numbers, the projections for the OCR (quarterly average) were:

September quarter 2019    1.4 per cent

December quarter 2019     1.2 per cent

March quarter 2020            1.1 per cent

With the next OCR review in late September and the following one in md-November, those projections –  adopted by the whole MPC – clearly envisaged not getting to a 1 per cent OCR even by the end of the year.

The bulk of the Monetary Policy Statement itself is written in the same relatively relaxed style, with no hint of a change in policy approach, and thus no proper articulation of the reason for it, or (hence) for how we should think about how the Committee will react, in principle, at future OCR reviews.   The Bank has added to uncertainty around policy, not reduced it.    In a similar vein, there is a new two page Box A in the statement on “monetary policy strategy”, intended to run each quarter, which is so general as to add nothing to the state of understanding of what the MPC and the Bank are up to.

And you will look in vain for any real insight from the minutes of the MPC meeting.   We are told

The members debated the relative benefits of reducing the OCR by 25 basis points and communicating an easing bias, versus reducing the OCR by 50 basis points now. The Committee noted both options were consistent with the forward path in the projections. [a claim that demonstrably isn’t true –  see above] The Committee reached a consensus to cut the OCR by 50 basis points to 1.0 percent. They agreed that the larger initial monetary stimulus would best ensure the Committee continues to meet its inflation and employment objectives.

But nothing about the considerations Committee members took into account in belatedly lurching to a 50 point OCR cut, or how they think about the conventions and signalling around using 25 point moves vs 50 point moves (when things aren’t falling apart here –  and it was the Governor yesterday who announced, oddly, of New Zealand that “the country is in a great condition”).

That wasn’t good or effective monetary policy communications.  It wasn’t a transparent insight on how the Committee is operating, the sort of reaction functions members are using, their view of MPS reviews vs the other OCR reviews.    It was –  or came across as –  a lurch (even if, like me, you thought that the OCR needed to come down quite a bit, quite quickly).

I’m going to end with two more examples of a lack of serious transparency.  Near the end of his speech Hawkesby observes

There are plenty of communication challenges ahead, especially if monetary policy in New Zealand moves into a less conventional territory, and we end up adopting new tools and approaches.

These will need to be explained clearly to both financial markets and the people of New Zealand.

No doubt, but would be an open and transparent central bank, wanting to build and maintain confidence in (a) its potential instruments, and (b) its actual decisionmakers and their advisers want to be much more open than the Reserve Bank has actually been?  Wouldn’t discussion documents outlining potential issues and options be a good idea?  Wouldn’t seminars and workshops with outside experts and market participants be a good idea?  Apart from anything else, at least in principle (as the Assistant Governor said) the Bank learns something from such engagement, challenge, and critique and in the process improves its own understanding and analysis.  It isn’t as if anyone is suggesting they pre-commit to when particularly instruments might be used, so this stuff shouldn’t really be market-sensitive, but it is quite important, potentially to us all (and was we know the Bank’s own research capability has been gutted this year).  And it isn’t as if the Bank’s background analysis on other matters –  bank capital again –  should fill us with confidence and willingness to simply “trust us, we know what we are doing”.

And on a smaller note, the next Monetary Policy Statement  and OCR decision is on 13 November.  As the Assistant Governor highlighted, inflation expectations are quite a significant influence in Bank thinking at present (rightly or otherwise).  And yet the main inflation expectations series –  the two year ahead measure in the Bank’s own survey –  isn’t scheduled for release until 12 November.   I participate in that survey.   Responses were due by midday last Tuesday (22nd). It is an electronic survey and if the results are not already in the Bank’s hands, they assuredly could be (it is pretty simple survey with fewer than 100 respondents, taking a matter of hours to compile at most).  And yet the Bank is sitting on this information until the very last minute.  By the time we get it, their decision will have been all-but-finally made, their MPS document completely written. If they were really serious about the desire to listen and learn, from markets, commentators, nay even “bloggers”, they’d have made sure the information was compiled and published quickly, allowing the Bank itself to listen to the response of outsiders in processing the significance of such important (to them) economic data.

If they were really serious…..instead, they mostly seem interested in fending off critics and keeping to themselves the stuff they know, while distracting us with their transparency about the stuff they don’t know much about at all (and where most central banks have not thought it advisable to follow the New Zealand lead).


Lighthouses warn people away from the rocks

In a few weeks time Christians will begin to mark the season of Advent.  One of the texts often read in liturgies in that season is from the prophet Isaiah.

The people walking in darkness have seen a great light; on those living in the land of deep darkness a light has dawned.

At The Treasury yesterday, a visiting academic proposed such a vision for New Zealand’s place in the world, as the Pharos state.

Bernard Cadogan is a New Zealander now living in Oxford.  According to his bio

Dr Bernard Cadogan has his doctorate from Oxford University on Empire Studies and constitutional theory. He served Hon Bill English (1996-1999, 2005-8), the National Party Opposition (1999-2003), Hon Trevor Mallard (2003-5). He lives at Oxford UK with his wife and three children.

He was also, apparently, a foreign affairs adviser to Bill English in the latter’s brief stint as Prime Minister and has been a consultant to The Treasury on various occasions and issues.  He is formidably well-read, very fluent, often stimulating….and yet, so it seems to me, much better on history than on contemporary politics/policy, and really rather at sea when it comes to economics and economic policy.

I thought I’d written about his previous, extraordinary, Treasury guest lecture in 2016, given just a week after the Brexit referendum (a topic on which he had been providing consultancy services to Treasury), but it seems I never got round to it.    My notes record talk of “pogroms by ballot box”, of an EU that is “virulently alive” while there is “something dead in the British Isles”, comparisons with the Glorious Revolution of 1688, a summary remark along the lines of “darkness won: the fog has rolled back in”, the Brexiteers as “sons and daughters of the counter-enlightenment”, depriving young people of “a second European homeland so that some might have a Narnia”, and so on.   As it happens, the text of that earlier address is still on Treasury’s website –  which enables me to quote in its full “glory” this quote, only the gist of which I’d managed to jot down at the time.

Irrational romantic nationalism and the archaic narratives of historians and of the nationalist culture industry have prevailed over rational economic argument. Grub Street and Grub Street politicians from “Spectator-land”,  with the prose skills of another era, have worsted the experts and the technocrats, and rendered nugatory the best quantitative techniques.

You get the sense that Dr Cadogan wasn’t very keen on Brexit.

In yesterday’s address there was none of that tone at all.  It was quite a remarkable transformation, especially when Brexit still hasn’t happened –  if I heard correctly that might have something to do with consultancy services Cadogan is now offering to parts of the UK government.  But it seemed to be there by counterpoint, in his theme that in this troubled and turbulent world

Throughout his talk Dr Cadogan uses the image of the great lighthouse of Alexandria to represent New Zealand’s personality in global affairs, as a source of hope and comfort to countries and peoples sailing turbulent waters.

It was bringing to mind more of Isaiah

40 Comfort ye, comfort ye my people, saith your God.

2 Speak ye comfortably to Jerusalem, and cry unto her, that her warfare is accomplished, that her iniquity is pardoned: for she hath received of the Lord‘s hand double for all her sins.

3 The voice of him that crieth in the wilderness, Prepare ye the way of the Lord, make straight in the desert a highway for our God.

4 Every valley shall be exalted, and every mountain and hill shall be made low: and the crooked shall be made straight, and the rough places plain:

It was, and is, more than a bit of a mystery as to why anyone much –  at least in the advanced world –  should look to New Zealand for anything, let alone “hope and comfort”.  Cadogan never did address that point, apart from some quick passing reference to questions he gets abroad –  presumably from people within his own ideological bubble – about “how does New Zealand do it?”.  “It” here also never being defined, but I presume it had something to do with the popular adulation, in a few quarters abroad, for our current Prime Minister (shorn of any actual policy programme).

The lecture began with a painting by Nicholas Poussin in which the (small) servant Cedalion guides the giant Orion towards the sun, and healing.  Small nations may, Dr Cadogan asserts, have special powers –  at least if they can avoid getting stomped on by giants.   And New Zealand….oh New Zealand,

  • that radical democracy (the “most radical”)
  • exemplary in so many respects
  • admired for our democracy, values, responsibility, human rights, decency
  • a successful market economy,
  • excellent institutions,
  • where the Treaty of Waitangi combines utopianism and justice,
  • and where there is no hatred, no contempt, no ideologues (he seemed particular exercised here about some UK former junior minister, now ennobled as Lord Freud).

(He claimed that Henry Kissinger had once said that law was New Zealand’s greatest gift to civilisation. I’m not sure if someone was getting confused with Solon, or even Coke or, say, Blackstone.)

We, in Cadogan’s view, have a story to tell the world, we could be a “moral realist” “force multiplier” to the world.

There have been times in our past when a good number of serious people abroad have looked to New Zealand as some sort of exemplar.  Like them or not, the reforms of the Liberal governments in the 1890s attracted many visitors and attempts to explain the New Zealand story over the next couple of decades.  Probably not entirely unrelatedly, New Zealand was also among the handful of most prosperous places on earth.

There was a somewhat similar effect in the wake of the reforms of the late 80s and early 1990s.  Like them or not, they were adopted with energy, verve, vigour, rigour and with some genuine innovation. By this time, people –  here and abroad –  knew that New Zealand had fallen well behind (economically, and in terms of what a strongly performing economy could offer) and the reforms were some sort of beacon of hope, that would put New Zealand back on a high-performing path.  You still find the occasional residue of that sort of sentiment –  although mostly from people who haven’t looked at any data for the last 25 years.     In that period there was, at least among some on the left, some admiration for the New Zealand ban on nuclear ships –  some genuinely hoping that it would show the way to other countries (typically it didn’t).

But quite what are we to suppose that people –  elsewhere in the advanced world – should look to us now and admire or envy?  I’m at a loss.  A questioner in yesterday’s seminar pointed to the disgrace that is our housing market, the rise of homelessness etc.  I’d, of course, frame the issue more broadly, and highlight our continued relative economic decline.  In 1900, you might have missed great art and architecture, museums etc if you came to New Zealand, but at least average incomes would be as high as on offer anywhere.  Now, you face distance, a pretty thin representation of the best of our civilisation, and you get to be materially less well-off than you’d be in most other advanced countries.   Are we “leading the way” on climate change, or any other left-wing causes?  Not that I’d noticed.   No doubt there are niche areas where New Zealand people are well-regarded (one hears it re trade negotiations, but then again why not unilateral free trade?) and few people are ever likely to express much angst about New Zealand (a threat to no one).  But a light to the world?  Really?  Who is looking?  Who cares?  Where, for that matter, are these “values” Cadogan talks of –  none that are admirable on display re the PRC (and for a lecture supposedly on geopolitics, there was almost no mention of China).

Another questioner noted that for all Cadogan’s praise of our democracy, actually there were few checks on the executive, great concentrations of power, and little effective accountability.  It more or less stumbles on, but to what end?  And how resilient would it prove to be if really put under pressure?  The questioner might have added specific points about how weak the media generally is, the limited range and poor quality of much of the public debate, the weak role academics and think-tanks play here, and the degradation of the capability of the upper reaches of the public service.

Yet another sceptical questioner –  Prof Girol Karacaoglu from Victoria University –  noted that for all Cadogan’s talk about New Zealand exceptionalism, he (Karacaoglu) was reminded of a line from a book he’d read –  John Gould’s  The Rake’s Progress – soon after coming to New Zealand 40 years ago, suggesting that things in New Zealand both good and bad tended to follow, perhaps 15 years behind, trends from abroad.

Are there valid points in what Cadogan was saying?   Yes, although some probably don’t carry much substance.  Are we a great power or a small player?  A small player.  Ever was and probably ever will be.  Do small countries survive the rise and fall of great powers?  By and large, yes.   And are there areas in which it is more likely that we can learn from other small countries –  and perhaps work effectively with them – than from very large countries?  No doubt.

Cadogan urges a peripatetic “colloquy” of small countries –  he listed Norway, Sweden, Finland, Denmark, Netherlands, Portugal, Switzerland, Ireland, Australia and Canada (the latter two far from small) and “perhaps” Uruguay.  This grouping could, he suggested, learn from each other.   It is hardly a new idea, and of course in many areas of policy there are just such groupings (eg a “small inflation targeters” grouping of central banks).     But it wasn’t really obvious what New Zealand had to offer or –  at least on some key issues –  learn.    Our strategic position is very different from almost all these countries.  Which is a variant on the point that our geography is very different –  incredibly remote –  and there are few/no relevant national comparators (and not very encouraging subnational ones) when one contemplate the implications of that remoteness.    Perhaps Uruguay fits the bill, but for all its relative success in the last decade or so, it remains materially poorer and less productive –  with less of a record of political or economic stability – than New Zealand.

Cadogan seemed very taken with Ireland –  he’s an Irish citizen too apparently – but showed no sign of appreciating that for all of Ireland’s exaggerated GDP per capita, once you look at the bit of economic activity benefiting the Irish people, Ireland’s story (prosperity) is nothing out of the ordinary: it is a fairly prosperous (but not first rank) European economy, and if there are lessons for New Zealand they are mostly about what we can’t do (not being a short distance from hundreds of millions of other very prosperous people).

There was upbeat talk about what a difference a New Zealand Nokia –  a big brand signifying New Zealand –  might make: Cadogan saw such a brand as a “sports lifestyle” one that would “walk through the walls that ideology imposes”.  Perhaps, but isn’t this just wishful thinking?   A bit like the talk, inspired by mention of the top Swiss universities, of what a difference it might make if New Zealand had two really good universities, one in sciences and one in humanities.  And yet, starting relatively poor and very distant, there was no hint of how this alternative world might come to be.

There are plenty of places in the world worse than New Zealand. But the notion of the world –  advanced world –  looking to New Zealand as some sort of lead, exemplar or guiding light seems little more than ludicrous in our current diminished state.    If anything, we might be a bit of an embarrassment –  the nice little country, that did so many reforms, and yet look at them now, still drifting  ever so slightly further behind, without even a political system or civil society to insist on something better, to set a different course.  And so remote that we don’t ever matter much to most of the rest of the world.  Sure, we don’t have Donald Trump –  but, fortunately, neither does anyone else.     But we have a (former?) CCP member, former member of the PRC military intelligence system in Parliament (chairing a Select Committee no less), and no one in the establishment here says a word –  at least in the US there is disquiet, and more, about Trump.

Lighthouses –  grand or otherwise –  warn sailors off rocks.  I noticed in the NZ History Twitter feed that yesterday was the anniversary of a dreadful maritime disaster here in 1894 (one of the two or three worst days, per capita, for the peacetime loss of New Zealanders in history) –  no mention of a lighthouse in the write-up.  If New Zealand is any sort of lighthouse to the world –  on these rocks pointed at the heart of Antarctica –  it is perhaps in the form of the salutary lesson: don’t do as we did, don’t end diminished as we now are.

Fluent and stimulating as Cadogan can be, it might also be a bit more encouraging if our Treasury itself showed signs of leading the way towards a much better-performing economy.  Perhaps we never again can lead the world –  as we were doing 100 years ago –  but whether it is economic policy, housing, or just the quality of our diminished government institutions themselves, we have to be able to do better than we are now.


Two years on

The weekend newspapers had several articles highlighting the second anniversary of the New Zealand First choice that led to the creation of the current government.  There was, for example, the double-page spread  in the Herald devoted to a not-at-all-searching interview with the Prime Minister and the Minister of Finance.  And there was another double-page article in the Dominion-Post looking at the government’s performance under a range of policy headings.  Since the government’s term is now two-thirds over –  likely to be in full campaign mode (say) nine months from now –  it seems not unreasonable to take a look at performance.

The Stuff political stuff divided up nine policy areas between them and wrote short reviews of the government’s performance in each of them.  On my reading, they tended towards a generous assessment.  All governments do stuff –  sometimes even just things in the works under a previous government – and where this government has done most (education notably) there isn’t a huge amount of evidence that there were real problems that needed fixing, or that their fixes were dealing with whatever real problems there were.

Take housing, for example, where the Stuff journalists summarise thus

Two years into the Government’s term, housing is far from Labour’s strong point, but it is not an area of total failure.

So house prices are still rising, rents are still rising (even in a low-interest rate world in which provision of rental housing could/should have been cheaper than ever) and there has been no legislation to free-up urban land markets, or to compel local authorities to operate a more liberal approach.   Set against that, a foreign buyers’ ban was largely irrelevant, and there is little reason to suppose that building a lot more state houses will increase the overall effective supply of housing (certainly won’t deal with the land issues).  For what was declared to be a “crisis” –  I’ll just settle for disgrace –  what has been done, or accomplished, is astonishingly little.  And it isn’t as if markets are pricing in better outcomes in future either.

But what really caught my eye was that there was no discussion of the government’s economic policy performance.  One might reasonably grant them a pass mark on fiscal stewardship –  but on anything beyond that the best reason why Stuff might have chosen to overlook this key area of policy is that there just isn’t much there at all.

Back when they were in Opposition we would, occasionally, here about the lack of any decent productivity growth, talk about growing export sectors, and so on.  Even today, the mantra of a “productive and sustainable” economy gets rolled out from time to time…..but with almost nothing to back it.

Actual productivity growth still languishes – running at no more than 0.5 per cent per annum, slower than in most other OECD countries. (It is fair to note here that there could be material revisions to a large number of macro series over the next couple of months, consequent on the census (and subsequent creative efforts) results, but there is no obvious reason to anticipate material improvements.)

There is no sign that the external orientation of the economy has strengthened (eg exports and imports as a share of GDP). no sign of robust business investment, and of course we all know that business confidence results are in the doldrums.  Interest rates have had to be cut further and the real exchange rate remains pretty high.

And what response has government policy made?   The government seems to have made quite a fuss about the new research and development tax credit. But they’ve produced no sustained analysis illustrating why this will make a great difference – and no sustained either looking at why firms didn’t regard higher rates of R&D spending here as offering attractive risk-adjusted returns.  And that really is about it.

And on the other hand, we have the government sitting idly by while the Reserve Bank Governor pursues his whim of making credit less readily available and more expensive, a halt to most new road-building even as the population continues to increase rapidly (and not, even, say, a congestion-pricing regime that might help reconcile the two), a ban on most oil and gas exploration, looming new regulatory restrictions around water.  Oh, and immigration policy –  for which there is no evidence of systematic economywide gains, in a country where (fixed) natural resources underpin prosperity –  is, if anything, becoming more liberal.

The government keeps telling us it has a plan.  I wrote here at the start of the year about an economics speech the Prime Minister gave, concluding

If there is any sign of a plan, it isn’t one that is going to do anything to lift our economic performance, in the short or longer-term.   All indications are that the Prime Minister doesn’t care. 

And then last month the government released something they did call an “Economic Plan” – in fact a thirty year one.  Notwithstanding all the glossy pictures and long lists of points, it sank without a trace, barely even reported at the time, even with a supporting op-ed from the Prime Minister herself (my take was here).

Once upon a time, I wondered (perhaps naively) if perhaps they –  upper reaches of the Labour Party – really did care.  They should.  After all, it is their traditional voters –  the poorer people, the working classes, the younger –  who suffer most from the decades-long failure of successive governments to improve New Zealand’s woefully poor productivity performance.    But all the evidence from their time in office is that any care is superficial at best.  Sure, they’d probably welcome a much better performing economy if it suddenly dawned fresh and shiny.  But they seem to have no real ideas, no compelling narrative, for how to markedly re-orient our economic performance, and they is no apparent interest in finding answers, or ensuring that our economic policy and analytical institutions are delivering them serious advice, grounded in the actual experience of New Zealand, on policy approaches that might really make a difference.

It is an utter abdication of responsibility.  No one made them run for office, no one forces them to stay in office, but when they take office they have responsibilities for the future prosperity of New Zealanders that they show no sign of taking at all seriously.

An academic economist left this comment on one of my weekend posts

With this in mind, I must confess that I always threaten to fail my Otago students if they don’t migrate to Austalia, because it shows they haven’t learnt anything from me; but the university doesn’t allow me to deliver on the threat. Still, most would be financially better off if they took this advice, and migrated to a place where better firms are located, and sought jobs there.

Sadly true.  And what a sad commentary on decades of policy failure here: Labour ministers currently hold all the key portfolios (Prime Minister, Minister of Financem Minister of Economic Development) and it is their failure now.