Split the Reserve Bank in two

In the last few months, I’ve run a couple of posts making the case for splitting the prudential regulatory/supervisory functions of the Reserve Bank out into a standalone prudential regulatory agency.  The main post was here, with some follow-up comments here.  The case for structural reform has been further strengthened, in my view, by the results of the recent New Zealand Initiative survey on regulated entities, in which it is clear that most respondents have little or no respect or regard for the Reserve Bank in its supervisory roles (as distinct from the inevitable disagreements with a regulator that should be expected/encouraged).   There are good arguments in principle for structural separation, and there is no sign (say) that despite those in-principle arguments the Reserve Bank has been doing a superlative job anyway.

As I noted in the earlier post, in most OECD countries (outside the euro-area, where central banks no longer have a monetary policy job to do), banking regulation and supervision is done by a body other than the central bank.

But if we look at advanced countries that do have their own monetary policies, I could find only three others –  Czech Republic, Israel, and the United Kingdom –  in which the same agency is responsible for monetary policy as for prudential supervision.   The US is –  in this area as so many –  a curious hybrid system, in which the Federal Reserve has some –  but not remotely all – responsibility for prudential supervision.  But as far as I could tell, the following OECD countries have monetary policy and prudential supervision conducted by separate agencies:

Canada, Australia, Norway, Sweden, Korea, Japan, Poland, Chile, Turkey, Mexico, Switzerland, and Iceland

I’m not sure that Turkey or Mexico offer models of governance for New Zealand, but the presence on that list of small well-governed countries like Norway, Sweden and Switzerland –  as well as tiny Iceland –   gave me pause for thought.

Perhaps of most direct relevance to us in Australia’s place in that list.

Some others have also made the case for structural separation, including my former colleague Geof Mortlock.  Geof has a new substantive column out today forcefully making the case for change.   Geof and I have been disagreeing about things for 35 years since we started at the Bank in adjoining offices a couple of weeks apart.  He spent most of his Reserve Bank career in the regulatory side of the Bank and for the last decade or so has been a consultant on banking risk/regulatory issues, including a stint at the Australian Prudential Regulatory Authority.      Judging by the occasional emails we exchange and occasional comments here, I suspect we still don’t agree about very much –  quite probably including the substance and extent of financial system regulation and supervision.

But I agree with almost everything in his column today. I encourage you to read it, and I hope that Treasury officials working on Reserve Bank reforms and the Minister of Finance (and his associates) not only read it, but heed it.  It is an overdue change, and if the chance for reform isn’t grasped now the issue is likely to drift for another decade or two, with weak governance, weak accountability, and a regulatory body that is unlikely to command the respect it should earn whether from regulated entities, overseas supervisors or (most importantly) the New Zealand public.

Here is Geof’s list of the main reasons for change

  • It would reduce the concentration of excessive power in one government agency. Currently, the Reserve Bank has a very wide range of powers compared to most central banks in the OECD. It has responsibility for monetary policy, foreign exchange reserves management, currency intervention, operating significant parts of the payment system and securities settlement system, prudential regulation of banks, insurers and NBDTs, regulation of money laundering, regulation of the payment system, financial stability oversight, macro-prudential regulation and currency management. I will stop there. The sentence is already too long!  So is the range of functions under one agency. This concentrates excessive power in the Reserve Bank. It also creates potential and actual conflicts of interest, as I argue later in this article. A narrower span of functions would reduce this concentration of power and avoid conflicts of interest.
  • Removing regulatory functions from the Reserve Bank would enable the supervisory agency to focus on the job at hand without being distracted by the other central bank tasks, particularly monetary policy. ………the Reserve Bank has tended over the years to accord much greater emphasis, attention, management oversight, resourcing and public reporting to the monetary policy function than to its regulatory responsibilities. The Reserve Bank Board, likewise, has generally paid much greater attention to the monetary policy function than to financial sector regulation. (That said, the Board has performed very poorly in all of its monitoring roles. Sadly, it has been little more than a compliant rubber stamp and cheer leader for senior management).
  • Separation of the regulatory functions would also enable the Reserve Bank to focus on its core role of monetary policy and related functions, undistracted by the many regulatory issues which it currently oversees. This would likely be conducive to a more focused and effective central bank. It would help the central bank to lift its game in monetary policy – i.e. to keep inflation broadly around the mid-point of the inflation target range; something that it has consistently failed to achieve in recent years.
  • Separation of the regulatory functions would enable a senior management team to be appointed with the skills, knowledge and experience to perform the role effectively – i.e. people with deep knowledge of, and practical experience in, banking, insurance and financial regulatory issues. The current senior management team – and its predecessors – generally lack the skills, knowledge and experience required for the role.  …..
  • It would enable the regulatory agency to build the depth of knowledge and skills in its staff to perform the functions required of them. Currently, although the Reserve Bank has able people in the supervisory area, it lacks the depth and breadth of knowledge and industry experience to do the job as effectively as it should. ……

He adds a couple of other considerations that resonated with me

  • Separation of the supervisory function from the Reserve Bank would also remove potential conflicts of interest between the Bank’s functions. For example, there is a conflict of interest between the Reserve Bank’s role as owner and operator of core parts of the payment and settlement systems [notably the NZClear securities settlement system], and its supervisory responsibilities in these areas. It is rather like the referee of a rugby game also being an active player on the field. Even worse, this referee gets to write the rules of the game!
  • It would ensure that macro-prudential supervision policy is directed at the promotion of financial system stability rather than being used as a de facto monetary policy instrument or for other nefarious purposes that do not necessarily anchor to financial stability. Reflecting this, I very much doubt that, had the responsibility for macro-prudential policy been allocated to a separate prudential regulator, and not the Reserve Bank, the macro-prudential policy tools would have been used as aggressively and relatively clumsily as has been the case under the Bank.

I’m hopeful more than convinced of the argument in that final sentence.

Of course, structural separation is no panacea.  A new agency would need to be built from scratch, even if it took over the existing Reserve Bank staff.  It isn’t as if the field of suitable candidates to lead such an agency is thick on the ground, and building the sort of expertise and culture that the job requires will be the work of several years.  But, on the one hand, we face that challenge anyway: the Governor can’t simply ignore, or pay only lip-service to, the shocking feedback in the NZ Initiative survey.  And, on the other hand, if we don’t make a start –  and put in place structural preconditions that increase the chances of better institutions in the longer-term – things are unlikely to ever reach the standard they should.

It remains disconcerting that the second stage of the Reserve Bank Act review is being led jointly by the Reserve Bank and the Treasury, in a climate in which the Minister of Finance has shown little interest in these sorts of issues.  The situation is crying out for leadership from the government, and not allowing the existing Reserve Bank management to persuade the Minister to settle for something as little different as possible from the inadequate status quo.

(Geof’s comment on the severe weaknesses of the Reserve Bank Board echo my own over the years.  Neither their Annual Reports nor the minutes of their meetings record any dissatisfaction with management ever – even though their primary role is holding the Bank to account, and the Bank is made up of fallible human beings.    I wrote a few weeks ago about the “Charter” (really a code of conduct) the Board has devised for itself.  The “charter” talks of the Board’s right to advise the Governor, and asserts a right to be heard

The Board may advise the Governor on any matter relating to the performance of the Bank’s functions and the exercise of its powers. The Governor is not required to act on the Board’s advice, but is required to have regard to it.

Where advice relates to matters of significance, the Board may give that advice to the Governor in writing, having first discussed the matter with the Governor in a Board meeting.

The Board will maintain a record of any formal Board advice given to the Governor.

There was no record in the minutes over the last couple of years of any material oral advice (despite (a) legal requirements to maintain records of public affairs, and (b) some difficult issues, including –  for example –  the Toplis affair).  So I lodged an OIA request seeking copies of any written advice.

There was none of course. In fact, the Board chair went so far as to claim that this was a mark of the effectiveness of the Board.   I think he must have left off an “in”.    Geof’s term –  and I think I’ve used it before too –  was cheerleaders.  But hopeless at almost anything else, and useless to the citizenry. )

Is vapid rhetoric all our leaders can offer?

The Prime Minister gave what she billed as a “pre-Budget” speech yesterday to the leading business lobby group, Businss New Zealand.  It was, I’m pretty sure, her first prime ministerial speech mainly on economic matters.  In introducing her speech  she indicated that she would

outline our plans for the economy and how we want to partner with New Zealand businesses to bring about transformative change for the good of all New Zealanders.

and a few sentences later she added

We are committed to enabling a strong economy, to being fiscally responsible and to providing certainty. We have a clear focus on sustainable economic development, supporting regional economies, increasing exports, lifting wages and delivering greater fairness in our society.

But in the rest of the speech there was almost nothing there.   There were slogans, and feel-good phrases.  But there was no plans for the economy.  No plans to lift productivity –  a point she touched on not infrequently during the election campaign –  and barely even an acknowledgement of the problem, no plans to reverse the decline in the export/import shares of GDP in New Zealand, and no sign that she –  or her advisers or her Minister of Finance –  have a serious well thought-through story of how New Zealand ended up underperforming as badly as it has done, let alone how we might reverse the underperformance.

Governments of both political parties deserve credit for keeping the government’s finances more or less in order.  As I noted yesterday, that is more than most large OECD countries have managed in recent decades.  But it isn’t a substitute for policies that might finally offer a credible path out of the 70 years of relative economic decline –  drifting a bit further behind even as every country is richer than it was – that New Zealand has experienced.

Instead, we get attempts to shift the goalposts, aided and abetted by The Treasury.

On that score how we measure our success is important. In the past we have used economic growth as a sign of success. And yet a generation of New Zealanders can no longer afford a home. Some of our kids are growing up living in cars. Our levels of child poverty and homelessness in this country are much too high.

We all want a strong economy. But why do we want it? What is it for? It is vital that we remember the true purpose of having a strong economy is for us all to have better lives.

Well, sure.  GDP isn’t an end in itself, but it (and cognate measures) are a pretty important means to those ends, and a reflection of how well a society is providing for itself.    And how does the Prime Minister suppose that the crushing specifics of (New Zealand) poverty 100 years ago –  when New Zealand was the richest country on earth – became largely non-existent today?  By achieving sustained productivity growth.   And if we now score badly on some of the poverty indicator measures, it isn’t entirely surprising when productivity (real GDP per hour worked) isn’t even two-thirds of that in countries like France, Germany, the United States, and the Netherlands.  When it now also lags well behind Australia too.

In her speech, she claims that her plans are already clear

We have already spelled out our ambitious agenda to improve the wellbeing and living standards of New Zealanders through sustainable, productive and inclusive growth.  Now we want to work with business and investors to get on with it and to deliver shared prosperity for all.

and

We will encourage the economy to flourish, but not at the expense of damaging our sovereignty, our natural resources or people’s well-being. Our plans have been spelled out from the beginning, in the Speech from the Throne, in the first 100-days plan, and very soon you will see more detail in our first Budget.   ……

You will see a clear plan to build a robust, more resilient economy. You will see a strong focus on delivering economic growth, on running sustainable surpluses and reducing net debt as a proportion of GDP.


There was little of substance on this score in the Speech from the Throne.  And much as I wish it were otherwise, I won’t be holding my breath waiting for the “clear plan” for stronger sustained real economic (and productivity) growth in the Budget.  There is nothing in anything the government has said so far that suggests they or their advisers really grasp the issues.     Quite why simply wishing businesses would “get on with it” would now be expected to produce better outcomes than we’ve seen in recent decades is a bit beyond me.

Of course, there are nods in the direction of things Labour (or their partners believe in)

My Government is keen to future-proof our economy, to have both budget sustainability and environmental sustainability, to prepare people for climate change and the fact that 40 percent of today’s jobs will not exist in a few decades.

I’d love to see some data on what proportion of jobs that existed 40 years ago don’t exist today (the majority of the jobs that existed in the Reserve Bank I joined in 1983 don’t exist any more).  But while the government worries about work –  setting up a new tripartite forum involving the CTU and Business New Zealand – actual employment rates don’t seem to be the problem.

E rates by age

(Lack of) productivity is.   It is productivity growth that underpins any long-term growth in real incomes and living standards.

There is talk of skills, when OECD data have shown that New Zealander workers have some of the highest levels of skills anywhere in the OECD (indeed, the chair of the Productivity Commission was retweeting an OECD chart to that effect just a few days ago).

There is talk that “no-one has the same job for life any more”.  Perhaps, but there is data overseas suggesting that average length of time with a single employer is little different now than it was 30 years ago.

There is talk of “lifting R&D spending”, and the government has out for consultation at present its plan for new R&D subsidies, but no sense that the Prime Minister or her advisers have thought at all hard about why firms might not have found it worthwhile to do more R&D spending (or why, by contrast, firms in some rich countries with no R&D subsidies do a great deal).

There was lot of rhetoric

Business can be assured that this Government will support those who produce goods and services, export and provide decent jobs for New Zealanders.

But little substance, and nothing that shows signs of pulling it all together into a coherent narrative.

And, for all the mentions of climate change and related issues, nothing at all about how faster overall productivity growth –  and a stronger export/import orientation –  might be achieved in the face her government’s commitments to sharply reducing net emissions in a country with high marginal abatement costs.  “High marginal abatement costs” has meaning: it costs to do this stuff, and the cost is likely to be reflected in lower levels of economic activity (and productivity) than otherwise.  Perhaps the government disagrees –  and perhaps her audience were too polite to challenge her –  but there is nothing in the speech suggesting she has thought hard about squaring that circle.  There seems to be lots of wishful thinking, and not much substance.

And then there were “the regions”

And the regions need not fear they will be neglected. We have committed $1 billion per annum towards the new Provincial Growth Fund and over coming months there will be more detail about how this spending will be targeted. After all, nearly half of us live outside our main cities and our provinces also need to thrive if New Zealand is to do well.

The Provincial Growth Fund aims to enhance economic development opportunities, create sustainable jobs, contribute to community well-being, lift the productivity potential of regions, and help meet New Zealand’s climate change targets.

There might be a bit of a lolly scramble, redistributing the current cake.  But there is nothing from the government, or from the architects of the PGF –  and nothing in the announcements to data (eg here and here) suggesting that the government has any concept of how overall productivity growth rates, nationwide or in the regions, might be lifted.  (And not once was the real exchange rate mentioned.)

Perhaps defenders of the government would push back on one or another point.  But there is no sign of any sort of integrated narrative –  a rich understanding of how we got to our current sustained underperformance or, reflecting that, how might hope to reverse the decline.  No doubt in an attempt to woo her business audience, there weren’t even any references to tax system changes (CGT and all that) in this economic speech.

Perhaps that isn’t entirely the government’s fault.  The Treasury seems at sea as well.  But we don’t elect bureaucrats, and we do elect governments.

Of course, I wouldn’t want to be misinterpreted as suggesting that the Opposition was any less bad.  The new Leader of the Opposition also gave his first economic speech this week.   There were a few bits where I was nodding my head as I read

Labour and NZ First are more focused on government intervention. They believe they know how to run your businesses better than you do.

Shane Jones’ $1 billion Provincial Growth Fund is a good example. It’s terrible policy.

Now I’m sure there are some worthy projects that will get funded. But it will shift businesses from focusing on becoming more productive to chasing a subsidy from Matua Shane.

That’s not how to drive long-term productivity improvements.

Couldn’t disagree, but what did Bridges have to offer

When I was Economic Development Minister, our plan for the economy was set out in the Business Growth Agenda.

The BGA comprised over 500 different initiatives all designed to make it easier to do business by investing in infrastructure, removing red tape, and helping Kiwis develop the skills needed in a modern economy.

Some of those were big, some were small. I’ll admit some weren’t as exciting spending a billion dollars every year.

But together they were effective.

New Zealand has one of the best performing economies in the developed world.

500 initiatives and we still had barely any productivity growth in the last five years.  And, as I recall, one of the BGA goals was a big increase in the export (and, presumably, import) share of GDP: those shares have actually been shrinking.  Productivity levels languish miles behind the better advanced economis, and the gaps showed no sign of closing.

He ends

New Zealand is a great country. And if we maintain our direction and momentum of recent years we can make it even better for our kids.

Moving into opposition is a chance for National to look at our position on certain issues, and understand the things that New Zealanders want us to focus on.

Although the one thing I hope you’ll take from my speech is we won’t be changing our focus on the economy.

If we don’t start seeing a lot more hard-headed thinking –  and a quite material change of direction – from our political leaders and their advisers, a country that really was once the best place in the world to bring up kids, will increasingly be a country where wise parents can only counsel their kids that if they want first world living standards, the best option is to leave.     In my lifetime, 970000 (net) have already done so.  The Prime Minister and the Leader of the Opposition –  representing two sides of the same coin when it comes to our economic failure – are younger than me, but in just the 37 years the Prime Minister has lived, a net 780000 of our fellow New Zealanders have left.   Outflows of that scale – which, of course, ebb and flow with short-term developments in Australia and here –  just don’t happen in normal, successful, countries.


The government’s debt target

I’d seen various news stories suggesting that in a speech on Tuesday the Minister of Finance had made the case for sticking with the Budget Responsibility Rules agreed with the Green Party this time last year.  So I thought I should read the speech.    There wasn’t much there.  The rules were restated, including the debt commitment, but there was no case made for following those particular rules, rather than some others.  The furthest the Minister got was the standard fallback line

We must be fiscally responsible. We must ensure that New Zealand is well-placed to handle any natural disasters or economic shocks.

Which doesn’t help, because it doesn’t differentiate the Minister’s rules from those of any other reasonably conceivable alternative.  Resilience to natural disasters or economic shocks is the fiscal equivalent of a motherhood and apple pie standard.

In terms of the government’s self-imposed fiscal rules, the only one that really troubles me is the debt one.    There are also these two

We will deliver a sustainable operating surplus across an economic cycle.

and

We will maintain Government expenditure within the recent historical range of spending to GDP, which has averaged around 30 percent over the last 20 years.

But what of debt

We will reduce the level of net core Crown debt to 20 percent of GDP within five years of taking office. 

In general, debt targets –  with relatively short time horizons to achieve them –  aren’t very sensible as operational rules.   Such a rule can mean that a few fairly small, essentially random, forecasting errors in the same direction can cumulate to produce a need for quite a bit of (perhaps unnecessary) adjustments to spending or revenue.  More seriously, recessions can throw things badly off course for a while, and risk pushing a government into a corner –  either abandon the target just as debt is rising, or fallback on pro-cyclical (recession exacerbating) fiscal adjustments –  even though, in across-the-cycle terms, the government’s finances might be just fine.  No one looks forward to a recession, but governments (and central banks) need to work on the likelihood that another will be along before too long.   Natural disasters –  the other shock the Minister mentioned –  can have the same effect.

Personally, I would be much more comfortable with only two key quantitative fiscal rules:

  • a commitment to maintaining the operating balance in modest surplus, once allowance is made for the state of the economic cycle (cyclical adjustment in other words) and for extraordinary one-off items (eg serious natural disasters), and
  • something about size of government.    Simply as an economist I don’t have a strong view on what the number should be, although as I’ve noted previously it is curious that the current left-wing government, arguing all sorts of past underspends, was elected on a fiscal plan that promised spending as a share of GDP that undershot their own medium-term benchmark (that around 30 per cent of GDP).

The suggested fiscal surplus rule isn’t an ironclad protection (any more than a real-world inflation target in a Policy Targets Agreement is).  There are uncertainties about the state of the cycle and how best to do the cyclical adjustment, and incentives to try to game what might be counted as an “extraordinary one-off”.   That is why the fiscal numbers and Budget plans will always need scrutinising and challenging.  But if followed, more or less, such a rule would be sufficient to see debt/GDP ratios typically falling in normal times, and to avoid things going badly wrong over a period of several decades.  That is probably about as much as one can realistically hope for.

There are those arguing for the government to increase its debt levels at present.    I’m a bit sceptical of that notion, for several reasons.  The quality of a lot of government capital spending –  whether it is cycleways, trains, or roads, just to take the transport area –  often leaves a great deal to be desired.  Advocates of more debt often talk up the relatively low interest rates at present, and suggest those low rates offer great opportunities.  Except that when interest rates have been low –  and if anything still falling –  for a decade, they probably need to be treated as semi-permanent, and thus as revealing something about the perceived economic opportunities advanced economies are offering.  And –  a point I’ve made often –  low as our interest rates are by historical standards, they are still high by the standards of most other advanced economies.

One consideration that might suggest it would be sensible for New Zealand to run higher debt than most other advanced countries is that our population (boosted by immigration policy) is growing much more rapidly than those of most other advanced countries.  All else equal, that should lead to faster growth in future GDP (not GDP per capita, just the total) and future tax revenue, suggesting more capacity to carry debt now.    There is certainly something to that argument at the local level, and hence I hope the government’s talk of facilitating local authority SPVs, which will enable debt to be taken on, serviced by specific property owners’ future rates commitments but outside existing core local authority debt limits, comes to something.     I’m much more sceptical of the story at the national level since on the one hand champions of immigration will stress the idea of immigration providing immediate fiscal gains (a claim there is probably something to, even if –  as Fry and Wilson suggest –  those effects die away over time).   If there is really an upfront windfall, there shouldn’t need to be more debt taken on.  And, on the other hand, for whatever reason, New Zealand’s trend productivity growth rate has been lousy for a long time, suggesting that even if our numbers (of people) are growing faster than in other countries, our (total) GDP won’t be that much faster.  It would be a different story if, say, more people was transforming (lifting sharply) our productivity performance, and future incomes, but there isn’t much sign of that.

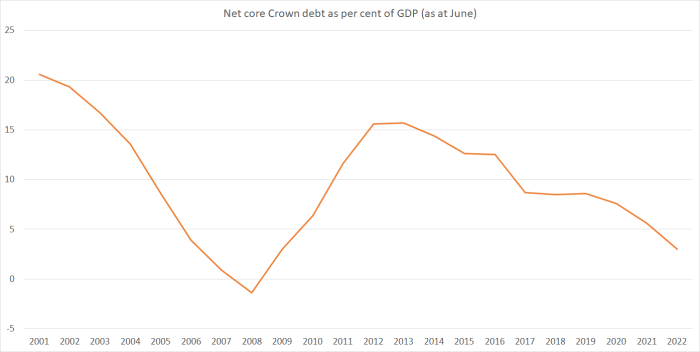
What about some numbers/pictures.  Here is a chart (including Treasury forecasts) of core Crown net debt as a per cent of GDP.  This isn’t the variable the government (and its predecessor) choose to target, since it excludes assets held in the New Zealand Superannuation Fund.  But it is all just money, and NZSF assets could be liquidated in quite short order if necessary.  (Even this variables excludes some government on-lending (“advances” in Treasury parlance) which seem to be about 5 per cent of GDP).

net debt 2018

After a serious recession and a weak recovery, and a series of pretty costly natural disasters, this measure of net debt peaked at a level lower than we’d had a decade earlier.   The estimate for June 2018 (from HYEFU numbers) is debt of 8.5 per cent of GDP.  On current plans –  as communicated by the government to Treasury – debt would drop away to 3 per cent of GDP by 2022.  At that point, it wouldn’t be quite as low as the 2007 or 2008 levels –  reached after a sequence of huge, unexpectedly large, and economically unnecessary surpluses, and partly reflecting a prolonged expansion in which the economt ran ahead of medium-term capacity –  but it  would be pretty close.

There is no easy metric for what an appropriate level of government debt is.  And the agency issues around government debt are much more severe than those for private debt –  governments aren’t spending their own money.  The parallels here aren’t exact either, but a typical middle-aged household is likely to have debt materially higher than 3 per cent –  or even 8 per cent –  of their GDP.

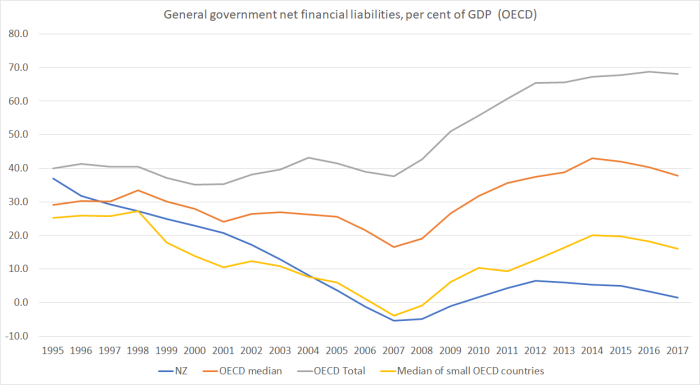
What about some cross-country comparisons?  Here I turn to the OECD and, in particular, their series on general government (ie not just central) net financial liabilities.  I start from 1995, because that is when the OECD has data for almost all countries.

net debt OECD

I thought there were a couple of interesting points here:

  • for all the talk of governments piling on debt since the 2008/09 recession, net debt in the median OECD country (orange line) last year wasn’t materially higher than it had been 20 years previously,
  • but total net debt over all the OECD countries (the grey line) has increased very substantially.  Of the big OECD economies –  US, Japan, Germany, France, Italy, UK –  only Germany doesn’t have a much higher debt ratio now than in 1995.
  • small OECD countries seem to have been much more conservative in managing their public debt (yellow line).  That group includes – at one extreme –  Greece and –  at the other – Norway.  The median net debt of those countries is materially above where it was in 2007, but it isn’t much different than it was in, say, 2002 (15 years earlier).

New Zealand doesn’t have the lowest net debt by any means (Norway has net financial assets of 280 per cent of GDP). In fact, we mark out something around the lower quartile.  We’ve had some disadvantages the other small countries didn’t –  earthquakes –  but on the other hand we’ve had an unusually strong terms of trade and weren’t constrained (as many of them were) by being in the euro.  But it looks hard to make a strong case for actively pursuing lower net debt from here.  It isn’t as if, for example, there is any sign of the economy overheating.

(Things not shown are often as important as those shown.  Unlike many of the more indebted countries, we do not have a large unfunded pension liability for public servants in New Zealand.  Those liabilities are not included in these debt numbers.)

Feckless governments in other countries don’t necessarily make for much of a benchmark. And, as above, I’m not actively calling for New Zealand governments to take on more debt.   But simply producing a sequence of modest cyclically-adjusted operating surpluses  (NOT several per cent of GDP) over the next few budgets would seem to be about as much as it would be sensible –  from a macroeconomic perspective –  to ask from a government.

And, on a final note, I am increasingly uneasy about one aspect of the Labour-Greens budget responsibility pledges that seems to have disappeared almost totally.

This was the promise

  • The credibility of our Budget Responsibility Rules requires a mechanism that makes the government accountable. Independent oversight will provide the public with confidence that the government is sticking to the rules.

  • We will establish a body independent of Ministers of the Crown who will be responsible for determining if these rules are being met. The body will also have oversight of government economic and fiscal forecasts, shall provide an independent assessment of government forecasts to the public, and will cost policies of opposition parties.

But nothing more has been heard.   I wrote about it here, and suggested that the idea should be broadened to become a Macroeconomic Advisory Council.  That still seems sensible to me, especially as the Reserve Bank reforms the Minister has announced to date do nothing to strengthen effective scrutiny of the Reserve Bank. But for now, it would be good if the Minister could update us on what has happened to the Fiscal Council promise.


Perhaps the Reserve Bank (and the FMA) should heal themselves

Suppose that the rules of a superannuation scheme explicitly required that any rules changes that could have an adverse effect on the interest of any member in that scheme could only be made with the unanimous consent of such members.

Suppose too that nonetheless the trustees of such a scheme went ahead and changed the rules of a defined benefit scheme in a way that allowed the employer to arbitrarily (ie no constraints at all) reduce the rate at which pension benefits were calculated (including in respect of periods of employment, and employee contributions, prior to the rule change).  No consent from potentially affected members was sought for this change.

Suppose that in making this change, they had the endorsement/consent of the board of directors of the employer, and of the chief executive of the organisation.

Suppose too that that new power was actually exercised by the employer, in a way which led to longstanding employees later retiring with pensions considerably lower than they would otherwise have been.  That represented a substantial wealth transfer (probably millions of dollars) to the employer.

And suppose that the Government Actuary had been required to give consent to such a rule change, and in fact did so.

That looks to me a lot like serious misconduct, quite possibly illegality.

And who are the players in this tawdry drama?

Well, there was the Government Actuary, a task now absorbed by the Financial Markets Authority.

And there was the Reserve Bank of New Zealand, its Governor (appointed by the then Minister of Finance), and its Board (all appointed by the then Minister of Finance).  Serving on both the board, and the trustees of this superannuation scheme, was the Governor, and someone who is now chair of the New Zealand arm of Transparency International, an NGO allegedly committed to good governance etc.

The initial misconduct happened quite long time ago.  In 1988 in fact.    But for years now some members have been trying to get redress, and even recognition of the problem.  It has been going for sufficiently long that when Adrian Orr was last at the Bank –  as Deputy Governor and Head of Financial Stability –  he was involved, fobbing off concerns raised by some of his own staff.

Four years ago, a particularly persistent member formally raised the issues (the one I’ve outlined here isn’t the only example, although is probably the most serious) with the trustees of the superannuation scheme.  The initial response of the Board-appointed chair (and current Deputy Governor and Head of Financial Stability) was to attempt to close the issues down immediately, without undertaking any investigation. I guess if you don’t turn over stones, there is no risk of finding awkward stuff under them.  Fortunately, other trustees stymied that bid.

After a couple of years’ delay, the trustees somewhat reluctantly came to the view that probably member consent should have sought, and that the decision not to have done so was not necessarily one they themselves would today have made.  But………they weren’t going to do anything at all about rectifying the situation, claiming (on grounds almost totally without foundation) that no one had actually been adversely affected.  These are trustees who, by common law and now by statute, are required to operate in the interests of the members of the scheme (beneficiaries of the trust).  But who could easily have been misinterpreted as operating in the interests of the Reserve Bank (a majority of trustees appointed by the Reserve Bank Board –  the entity that has spent the last few decades providing cover for Bank management).  Under the (relatively) new Financial Markets Conduct Act, superannuation schemes are now required to have an independent trustee –  the one on the Reserve Bank scheme (whatever his other useful contributions) declared early on that he had no desire to be caught in the middle trying to sort out such difficult issues, and (from my memory) has barely uttered a word in all the debates since about these issues.

And what of the FMA?  It is now must be almost a couple of years since the member elevated the issue to the FMA, lodging a formal complaint with them.    And since then the FMA appears to have done almost nothing (there was a meeting with the trustees well over a year ago, but it involved little more than description of the issue –  and at the time the FMA themselves didn’t even seem to have a good grasp on their own act).   Perhaps it is typical for the FMA?  I don’t have anything else to do with them, so have no basis for knowing.  Perhaps there are legal constraints (old legislation) on their ability to actually do anything formally.  But there has been no informal action, moral suasion, either.   Indeed, their inaction could be easily be misinterpreted as having something to do with the fact that the organisation itself (as the Government Actuary) had signed off on the, almost certainly unlawful, rule change.  And perhaps too from the sheer awkwardness of having to investigate serious concerns about an entity associated with their fellow regulator, the Reserve Bank, an entity then chaired by someone who is now Head of Financial Stability (Bascand is no longer the chair, but is still a trustee).  Or from signs that the independent trustee regime they administer seems to be adding only overhead.

I don’t want to bore readers with the details of this particular tawdry episode.

But when we have the new Governor  –  with legislative responsibility only for prudential issues –  lurching from two weeks ago suggesting there were no particular conduct issues in New Zealand, because we had a quite different culture, to last week suggesting that it really wasn’t his call (on an inquiry) but he was sure banks were examining themselves, to news this morning that he and the FMA head had summoned the heads of the big banks to a meeting, demanding they prove a negative (that there is no “misconduct” going on), and (in the FMA head’s case) apparently threatening legal action against those who don’t cooperate, I could only think

Physician heal thyself

or continuing the biblical theme

And why do you look at the speck in your brother’s eye, but do not consider the plank in your own eye? 4 Or how can you say to your brother, ‘Let me remove the speck from your eye’; and look, a plank is in your own eye? 5 Hypocrite! First remove the plank from your own eye, and then you will see clearly to remove the speck from your brother’s eye.

(As background, I am both a member and an elected trustee of this superannuation scheme. I have recorded in the minutes my dissent from the majority view of trustees, and have expressed my own concerns directly to the FMA.  As I joined the Bank, and the scheme, not long before this particular questionable rule change was made, it probably did not materially adversely affect me.)

New Zealanders leaving Auckland

Last month The Treasury published some new research aimed at providing better information on the population changes in each territorial local authority (TLA) between censuses.   At present we only have a census every five years –  and in some quarters there seems to be a push to reduce that frequency – and subnational population estimates between censuses have often been pretty poor, only to be updated and revised when the next census results finally appear.  At present, the published subnational population numbers are anchored to the 2013 Census, adjusted for estimates of the overseas net migration flow and data on  births and deaths.  In New Zealand we don’t have to tell some specific government agency when we move house or city.

Except that, as The Treasury observes, in practice we often do end up telling some government agency (or government-funded agency) or other –  in fact, are coerced to do so –  and the government has collated all that data in a single (anonymised) database.   That opens up enormous possibilities to use that data to, for example, update subnational population estimates in a way likely to be more accurate (albeit not very timely).   You might worry, as I do, about governments getting their hands on all that data combined, by some mix of coercion and seduction (eg have the slightest accident and you get into the ACC system) and worry that it might be used for ill as much as for good.  But, like it or not, the data are there and The Treasury is using them.

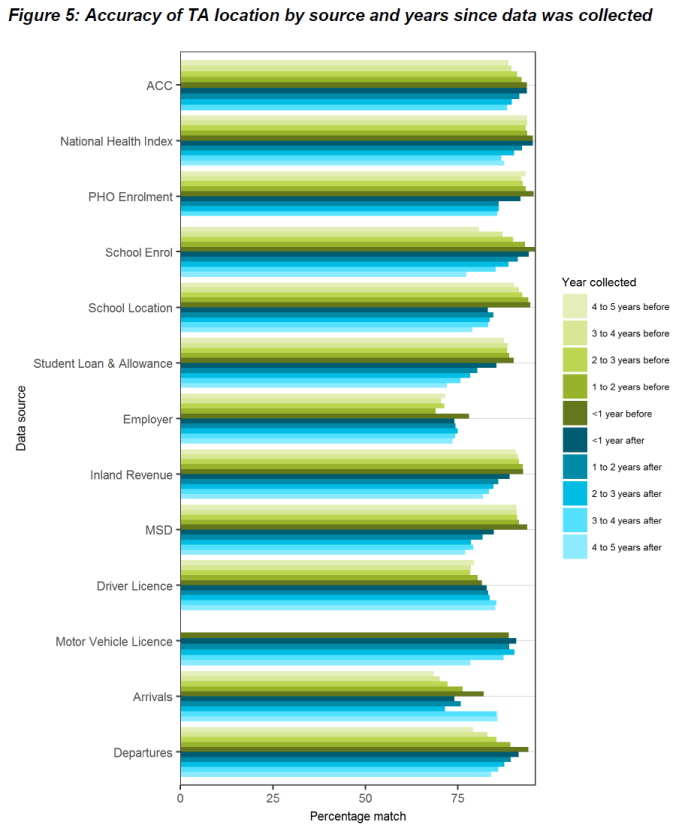
This chart from their paper gives you the picture of the data they are using

tsy popn

But my interest is less in the details of how they calculate their estimates, as in some of the bottom line results, and particularly those around estimated internal migration.

There are some interesting snippets.  The results suggests that New Zealanders’ rates of internal migration (one TLA to another) have been pretty stable, but that of immigrants has increased quite a lot.  The author offers no ideas about why that might have been (and I don’t have any to suggest either).

tsy popn 2 There is a fascinating picture of Christchurch following the earthquakes, including the continuing losses in recent years to neighbouring Selwyn and Waimakariri.
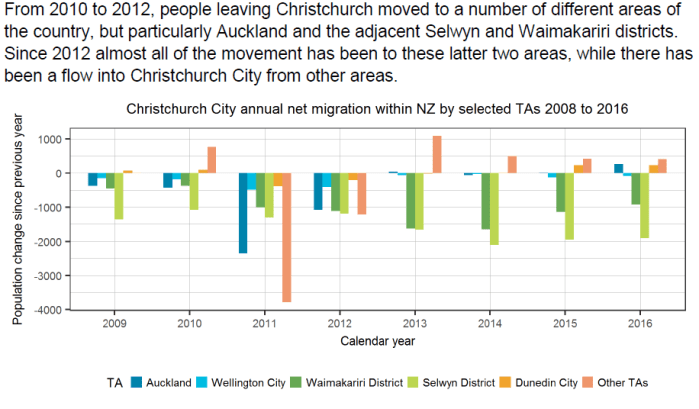
tsy popn 3

And then there is Auckland

tsy popn 4

There was a slight move into Auckland from elsewhere in New Zealand (mostly from Christchurch, see previous chart) in 2011, but otherwise the net flow of New Zealanders has been away from Auckland.  In fact, in the final year of the chart, the net outflow of New Zealanders (this is a NZ-born measure) was larger than the natural increase, so that the entire increase in Auckland’s population is (estimated to have been) due to international migration.

Readers with long memories may recall that I touched on the outflow of New Zealanders (as captured in Census data) in an earlier post.

This was the picture from the five years from 2008 to the 2013 Census.
internal migration 08 to 13As I observed then, we didn’t know what had happened since 2013.   Perhaps things had turned around?    But the new Treasury estimates suggest that if anything the outflow – still modest each year – may have accelerated.
We have the data going further back. Here is the extract from the earlier post.

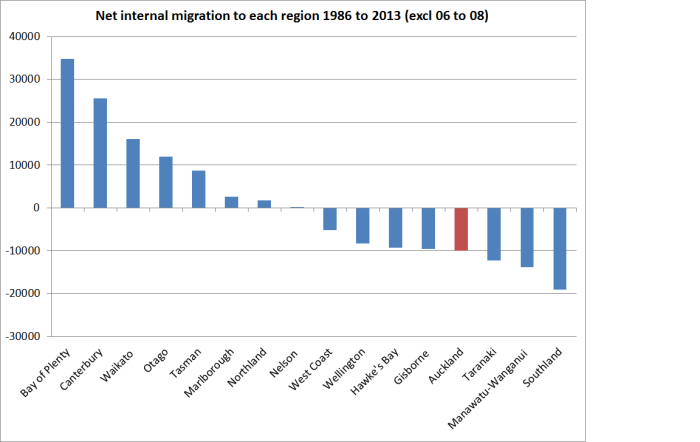
SNZ has compiled this data back as far as the 1986 to 1991 five-yearly period. The last five yearly period in which Auckland experienced a net inflow of people from elsewhere in the country was from 1991 to 1996.

Here is chart which covers the estimated net internal migration to each region for the period 1986 to 2013 (with the two years 2006 to 2008 missing, because they weren’t captured by any of the censuses).

internal migration 86 to 13.png


None of this should be very surprising.   After all:

  • Auckland house prices have become impossibly high,
  • Traffic congestion problems, if temporarily relieved now by Waterview, seem continually pressing, and
  • The gap between Auckland incomes and those in the rest of the country, never large, has been narrowing.

But it must be an inconvenient truth for boosters of the Auckland story, including bureaucrats in MBIE, the Secretary to the Treasury, assorted past and present ministers (recall John Key on “quality problems”).  The people who know Auckland best  –  the opportunities for themselves and their families –  are, at the margin, leaving the place.   People in the rest of New Zealand aren’t (net) flocking to the big city.   It simply doesn’t seem to offer them better opportunities than staying where they are (or going to Australia).

The latest issue of the London Review of Books turned up in the mail yesterday.   In one of the reviews –  of a new book by Richard Florida –  I found this

The new urban inequality has two distinct and related aspects. First, superstar cities have moved ahead of the nations they’re found in.  The trend is clear in the US, where cities like New York have become richer relative to the country as a whole. But it is most pronounced in the UK.  In the 1970s and 1980s, London’s GDP per head was around one and a quarter times that of the UK as a whole.  Today it’s one and three-quarters.

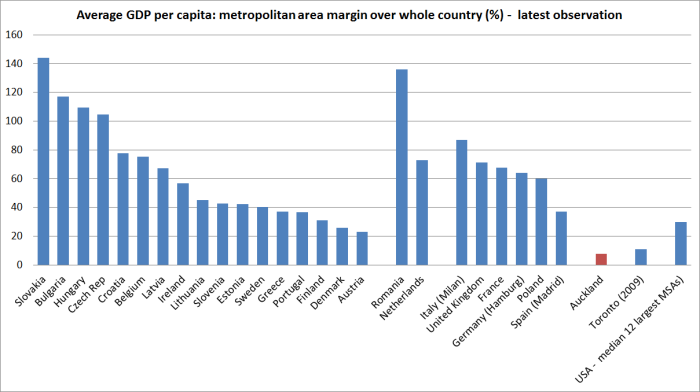
It isn’t just London or New York.   I’ve shown previously a chart looking at GDP per capita in EU countries, looking at the ratio over time of that in the biggest city relative to GDP per capita for the country as a whole.  Over this century there has been a clear upward trend.

As for Auckland, in 2000 GDP per head in Auckland was 15 per cent higher than for the country as a whole, but by last year it was only 9 per cent higher.   I’ve shown previously (a couple of years ago) this chart of how small the New Zealand gap is between GDP per capita in the biggest city and that for the country as a whole, by comparison with many other advanced countries.

gdp pc cross EU city margins

There are, perhaps, some good dimensions to the New Zealand story.   We don’t have whole swathes of the country being left behind as the metropolis powers ahead.  On the other hand, the metropolis isn’t powering ahead at all –  just getting more and more people, in a city which is underperforming a country with weak (almost non-existent in recent years) productivity growth.

It is well past time for a rethink, and for our politicians and officials to start focusing on the specifics of the New Zealand experience.   In terms of economic success, Auckland bears not the slightest resemblance to London or New York (or Paris, or perhaps even Bratislava).   And yet the growth strategy (perhaps flattering it to use the term “strategy”) has seemed to rest almost entirely on a wishful belief that if only we tried really hard, and poured more and more people into Auckland, it just might be.  But one of the lessons of economic geography is that location matters.  Ours –  Auckland’s –  is exceeedingly unpropitious.

That LRB review I mentioned earlier notes that trends in recent decades have turned out to be very good for “established global cities in particular”, in ways that few anticipated.  That particular discussion ends thus

The business districts of San Francisco, New York, and London are ludicrously prodigious. The Borough of Westminster produces as much wealth as all of Wales.

I can’t vouch for that final statistic, but it does leave one thinking that it is more likely that Auckland is a Cardiff or (moving north) Glasgow, than that it is a coming London or New York.

The Governor on banking and deposit insurance

There was another interview the other day with new Reserve Bank Governor Adrian Orr.  This one, on interest.co.nz, focused on issues somewhat connected to the Reserve Bank’s responsibility for financial sector prudential regulation/supervision, and associated failure management responsibilities.

In the interview Orr touched again on an idea he has already alluded to in one of his interviews: the idea of getting a clearer, more quantified, sense from Parliament as to what it is looking for from the Reserve Bank in its conduct of regulatory policy.

It is an appealing idea in principle.  For monetary policy, Parliament has specified a goal of price stability, and in the Policy Targets Agreement the (elected) Minister of Finance gives that operational form (a focus on 2 per cent annual inflation, within a range of 1 to 3 per cent).   There is nothing similar for the extensive regulatory powers the Bank has.

In respect of banks, section 68 of the Act sets out the goals

68 Exercise of powers under this Part

The powers conferred on the Governor-General, the Minister, and the Bank by this Part shall be exercised for the purposes of—

(a)  promoting the maintenance of a sound and efficient financial system; or

(b)  avoiding significant damage to the financial system that could result from the failure of a registered bank.

Which is fine as far as it goes –  and what isn’t there (eg a depositor protection mandate) is often as important as what is.   But it isn’t very specific, and provides no guidance as to how to interpret the idea of an “efficient” financial system (as a result, it has been debated internally for decades), no sense of how sound the system should be (or even what a “sound system”, as distinct from sound institutions, might be.   And the same overarching provision (sec 68) has seen the Reserve Bank’s approach to bank regulation and supervision change very substantially over the years, with little or no involvement from Parliament.

There is a reasonable argument –  made quite forcefully in former Bank of England Deputy Governor Paul Tucker’s new book on such matters – that if in a particular aspect society’s preferences aren’t reasonably stable, and able to be written down reasonably well, then policymaking powers in that area should not be delegated to an independent agency (let alone what is formally a one-man agency).  With the second stage of the review of the Reserve Bank Act underway, Orr can obviously see a threat to the Bank’s powers, and thus he suggests an attempt be made to have Parliament articulate its preferences, and views on possible trade-offs, more directly.  If they could do so, having unelected decisionmakers then working to deliver on that mandate might be less democratically objectionable, and the Reserve Bank might have a greater degree of legitimacy in these areas than it does now.

And so the Governor told his interviewer

“For inflation targeting we’ve got a clear target [being] 1% to 3% on average. For the prudential regulation, – how do we articulate that target? In other words what is the risk appetite of the people of New Zealand as represented by Members of Parliament for banking regulation? Do you screw it down to one corner where nothing can happen – it’s very sounds but totally inefficient, or do you have trade-offs allowing firms to come and go and consumers to be aware etc? So that is going to be a really good, useful articulation that will come out of that,” says Orr.

At first blush it sounds promising, and I’m certainly not going to discourage an effort to try to uncover such an articulation of preferences.  But I am a little sceptical that anything very stable or useful will emerge from the process.  I’d prefer that all rule-making powers were removed back to the Minister of Finance (or indeed Parliament), leaving the role of the Reserve Bank as (a) technical advisers, and (b) implementers.

It might be fine to express a view that banking system regulation should be designed on a view that there should be no major bank failure on average more than once in a hundred years   – actually about the rate in New Zealand history –  or, indeed, five hundred years.    That might (and has in the past internally) be some help in how one calibrates capital requirements for banks.  It will, however, be almost no help in deciding whether LVR restrictions are a legitimate use of coercive, redistributive, government powers.  Or whether we care much about small institutions.  Or, indeed, whether the Reserve Bank should have the power to approve (or not)  the appointment of senior staff in banks.   And even if society could express a stable preference for a regime designed to deliver no more than one failure per 100 years, it provides very little basis for that other vital strand of the governance of independent agencies –  serious accountability.    Good luck could readily deliver a 50 year run of no failures without reflecting any great actual credit on the central bankers in charge at the time (who might have been doing fine, or doing a lousy job).  And if the one in a hundred year shock happens next year, it will still be very difficult to say with any certainty that the central bankers were doing the job they were asked to do –  they may well have been, and just got unlucky, and the public is likely to want scapegoats.    Elected politicians serve that role better than unelected technocrats.

But if there is anything more to the idea the Governor is toying with, it would be good to get some material into the public domain in due course, and have it scrutinised or debated.

In his latest interview, the Governor also touched again on the calls for a royal commission into conduct in the financial sector, as underway at present in Australia.  This time he is a lot more moderate, explicitly recognising that it isn’t his call.

Against the backdrop of the unacceptable conduct coming to light in Australia’s Royal Commission on financial services, Orr doesn’t believe New Zealand needs its own Royal Commission. However, he says the impact of the Australian one is certainly being felt in NZ.

“There will be not a single bank in New Zealand that is not, at the moment, really checking every cupboard for skeletons here in New Zealand. That is without doubt. This has really put the wind up the banks to say ‘hey, what is the alternative to sound regulation, it’s a Royal Commission’. We’re meeting collectively with the CEOs, we’re meeting individually with the chairs, and we always do on a regular basis,” Orr says.

“Is a Royal Commission necessary? At the moment in my personal opinion no, but I’m not the one who would call one anyway.”

Orr says while the Australian Prudential Regulation Authority is “being held up as some [sort of] global best practice,” and works alongside the Australian Securities and Investments Commission and the Reserve Bank of Australia with all having “heavy boots on the ground,” they’re still having “this cultural challenge.” Thus more hands-on regulation than the Reserve Bank’s light touch regulatory oversight of banks isn’t necessarily the best way forward.

But it is an odd mix of responses.  On the one hand, Orr seems to come across as something of a champion or defender of the banks in New Zealand.  That is no part of his role.  He is the prudential (soundness) regulator, in the public interest –  recall section 68 of the Act, quoted earlier – and his role (the Reserve Bank’s role) has almost nothing to do with conduct standards.

And he seems to be attempting distraction on other issues by conflating prudential/systemic issues with conduct issues.  Thus, when various people (including the IMF) have argued that New Zealand should adopt a prudential regulatory regime more akin to APRA’s (which, in effect, operates here to a considerable extent anyway, because APRA is focused on the entire Australian banking groups), Orr doesn’t engage in the substance of that debate, but attempts to muddy the water by making the point that a more intensive prudential regime in Australia hasn’t prevented some of the conduct issues coming to light in the Royal Commission.  Indeed, but why would one imagine it should?   They are two quite different issues.  In the same way, an investigation into whether the local supermarket was meeting minimum wage or holiday pay provisions for its staff wouldn’t expect to shed any light on food-handling issues in the same supermarket.

Part of the legitimacy of independent central banks involves them being seen to speak in an authoritative and trustworthy way.

But the comment from the Governor that led me to read the account of the interview was on the vexed subject of deposit insurance.   The article had this as (part of) its headline

RBNZ Governor says differences between deposit insurance & minimum deposit not frozen in OBR scenario are ‘technicalities’

That sounded like an intriguing claim.  You’ll recall that the Reserve Bank has long staunchly opposed deposit insurance (eg articles/speeches referenced here), even though people like The Treasury, the IMF, and various other commentators (including me and my former RB colleague Geof Mortlock) favour it.  The new Governor doesn’t seem to share the Bank’s long-running opposition.

Asked whether the Reserve Bank should get an explicit statutory objective to protect bank depositors and/or insurance policyholders, Orr says deposit protection, or deposit insurance, is “something that’s going to be here in the future.” NZ’s currently an outlier among OCED countries in not having explicit deposit insurance.

“I think that’s something that’s going to be here in the future. We need to work our way through what it means

I’m surprised that change of stance didn’t get more coverage.  Of course, whether or not we have deposit insurance isn’t a decision for the Reserve Bank; it is a matter for the government and Parliament.  Nonetheless, if the Reserve Bank Governor is going to withdraw the bank’s opposition, that removes a significant bureaucratic roadblock.  Well done, Governor.    (To be clear, I favour deposit insurance not as a first-best outcome, but as a second-best that makes it more likely that future governments will allow troubled financial institutions to fail, rather than bail out all the creditors.)

But it was the Governor’s next comments on the issue that were more troubling, and which suggest he hasn’t yet got sufficiently to grips with the issue before opening his mouth.

I think people have been talking across each other a lot,” Orr says.

“The bank here has got a policy called Open Bank Resolution. And that is the idea that if a bank is too large to fail, we have to keep it open. But we have to recapitalise. So the current owners or investors who have largely done their dough, how do you recapitalise it and how do you have the door open the next day?”

“As part of that open bank resolution, we’ve already said there can be a de minimis around depositors money that they will have access to. We just need to speak in better English to say ‘you know you are going to have some cash there, you are going to be able to get your sandwiches, meet your bills, do all of that on the Monday. Because if it didn’t happen that way, then that one bank failure creates all banks to fail, there’s [bank] runs everywhere’,” adds Orr.

When it was put to him that depositors having access to a de minimis sum if open bank resolution was implemented on their bank isn’t the same as explicit deposit insurance, Orr suggested the difference is merely technical.

“We could have a discussion through that legislation to say ‘economically it’s the same, could we call it the same, or is it part of a failure management?’ I believe it’s the same end outcome, the technicalities behind it are just technicalities. We need to be able to say to the public ‘if we’re shutting the bank down, what do you have access to, what is the guaranteed de minimis or minimum, or protection,’ and then we need to work out how is that going to be funded.”

There is a lot of mixed-up stuff in there.

For a start, the question of how we manage the failure of a bank in New Zealand has nothing whatever to do with the idea of foreign taxpayers bailing out New Zealand depositors.  I’m not aware that anyone supposed that was very likely.  Indeed, all our planning –  including the requirement for most deposit-taking banks to incorporate locally –  has been based on the idea that New Zealand is on its own (although for the Australian banking groups, whatever happens in the event of failure is likely to be negotiated by politicians from the two countries).   Instead the general issue here is

  • should a large bank simply be allowed to close if it fails, and handled through normal liquidation procedures (few would say yes to that).
  • if not, how best can the bank be kept open,
  • it could be bailed out by the government (benefiting all creditors, including foreign wholesale ones),
  • or the OBR tool could be used, in which all creditors’ claims would be immediately “haircut”, so that the losses fall on shareholders and creditors not on taxpayers but  the bank’s doors remain open.

Within the OBR scheme there has always been the idea of a de minimis amount which might not be haircut at all.  It isn’t an issue about liquidity –  as the Governor suggests –  because in the reopened bank everyone has access to some of their money.  It is an explicitly distributional issue.   For example, a welfare beneficiary might have only $100 in their account (living almost from day to day),  such accounts in total won’t have much money in them, so it might be easier (involve many fewer creditors, and less immediate resort to eg foodbanks) and in some sense fairer just to give people with such small balances immediate access to all their money and not have them share in any losses (or have to bother about ongoing dealings with those handling the failure).  It has mostly been seen as a matter of administrative convenience, but also of realpolitik (reduce the number of voters affected by losses in a failure).   And if these very small creditors are fully paid out, it does involve a transfer of wealth from all other creditors, but the amounts involved, even cumulatively, are pretty small.

In recent years, there has been talk of this de minimis amount creeping up.    There have even been suggestions of something as large as $10000 –  in other words, if you have less than $10000 in your (failed) bank, you wouldn’t face any losses.    It must be this sort of thing the Governor has in mind when he talks of the difference between deposit insurance and the de minimis being little more than “technicalities”.

But he is still wrong:

  • first, the de minimis would only apply where OBR was used, and OBR is only one option.  Even if looks like an attractive option, in some circumstances, for a large bank, it might not be a necessary or appropriate response to the failure of a small bank.
  • second, the de minimis is being paid out of other creditors’ money (it is essentially a (small) depositor preference scheme).   That might be tolerable for very small balances –  other creditors have an interest in lowering administrative costs of managing the OBR –  but is most unlikely to be defensible, or acceptable, for larger de minimis amounts,   Perhaps the Governor has in mind, the government chipping in directly to cover the larger de minimis amounts, but relative to a proper priced deposit insurance regime that seems far inferior, and different by degree, not just by “technicalities”.
  • third, no de minimis amount I’ve ever heard mentioned comes close to the sorts of payout (coverage) limits in typical deposit insurance schemes abroad.  As the author of the interest.co.nz piece points out  “Under Australia’s deposit insurance scheme, deposits are protected up to a limit of A$250,000 for each account-holder at any bank, building society or credit union that’s authorised by the Australian Prudential Regulation Authority”.    Attempting to rely on the de minimis –  as people like the Governor sometimes do in advance of the failure –  is just a recipe for increasing the likelihood of a full bailout at point of failure, as the amount envisaged just won’t match public expectations/demands (as revealed in other countries).

To repeat, it is good that the new Governor appears to be shifting ground on deposit insurance.  But let’s not settle for half-baked responses, using a vehicle never designed to deal with the issue of deposit insurance.  Legislate and put in place a proper deposit insurance scheme, and levy depositors to pay for the insurance.

Do that and, as I’ve argued previously, the chances of being able to use OBR –  to impose losses on large and wholesale creditors, including foreign ones – will be materially increased.  Without sorting out deposit insurance properly, most likely any future government faced with a failure of a large bank will just fall back on the tried, true, and costly solution of a full state bailout.


LVR limits revisited

The Reserve Bank was out the other day with some research on the impact on house prices of the successive waves of loan to value limit restrictions put in place from 2013 to 2016.     It was a rare Reserve Bank discussion paper –  pieces typically designed to end up in a journal publication –  to get some media attention.   That was, no doubt, because of the rather bold claims made in the non-technical summary to the paper

Overall, we estimate that the LVR policies reduced house price pressures by almost 50 percent. ,,,,, When it becomes binding, LVR policy can be very effective in curbing housing prices.

Since nationwide average house prices (QV index measure) increased by about 40 per cent over the four years from September 2013 (just prior to the first LVR restrictions coming into effect) to September 2017), you might reasonably suppose that the researchers were suggesting that, all else equal, LVR restrictions had lowered house prices by almost 40 per cent (in other words, without them house prices would have increased by around 80 per cent).  Of course, that isn’t what they are claiming at all.

The paper was written by several researchers in the Bank’s Economics Department (two of whom appear to have since moved on to other things), and carries the usual disclaimer of not necessarily representing the views of the Bank itself.  Nonetheless, on an issue as contentious as LVRs, it seems safe to assume that senior policy and communications people will have been all over the communications of the results.  Even if the Governor himself didn’t see it, or devote any time to it, it seems likely this paper carries the effective imprimatur of the Assistant Governor  (Head of Economics),  the Deputy Governor (Head of Financial Stability) and (at least in the bottom line messages) the Head of Communications too.

In the paper, the authors attempt to identify the impact of the various waves of LVR controls using (a) highly-disaggregated data on property sales, and (b) the fact that shortly after the first LVR restrictions were put in place, the Bank buckled to political and industry pressure and exempted lending for new builds from the controls (even though, generally, such lending is riskier than that on existing properties).  By looking at the relationship between prices of new and existing properties before and after the various adjustments to LVR limits, they hope to provide an estimate of the effect on existing house prices of the LVR controls.

Trying to identify the statistical effects of things like LVR controls is hard, but I’m a bit sceptical of this proposed new approach.  After all, if new and existing houses were fully substitutable a new regulatory intervention of this sort could be expected to affect prices of both more or less equally.  People who were more credit-constrained (by the restrictions) would switch to buying new houses, and those who less affected by the contros (eg cash buyers) would switch more to existing houses.

In practice, of course, the two aren’t fully substitutable, for various reasons (including that most new builds are occurring in different locations –  even in the same TLA – than most existing houses), but in the Reserve Bank research paper I didn’t see any discussion of the issue at all.  If there is no substitutability at all then the research approach looks as though it should be reasonable, but that seems unlikely too.

But I’m more interested in whether the reported results are anywhere near as impressive as the authors claim.

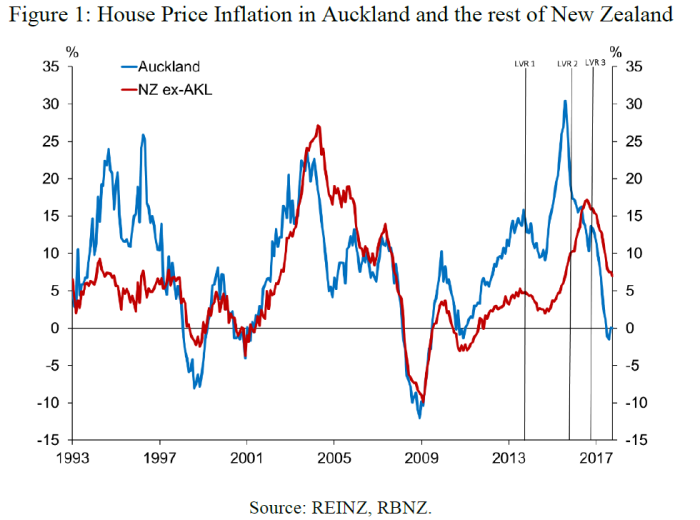
As a reminder, here is their chart of house price inflation developments, with the various LVR interventions marked.

LVR1

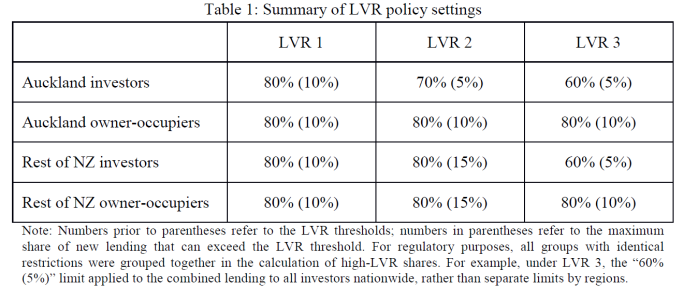
And here is their summary table of those successive interventions.

LVR2.png

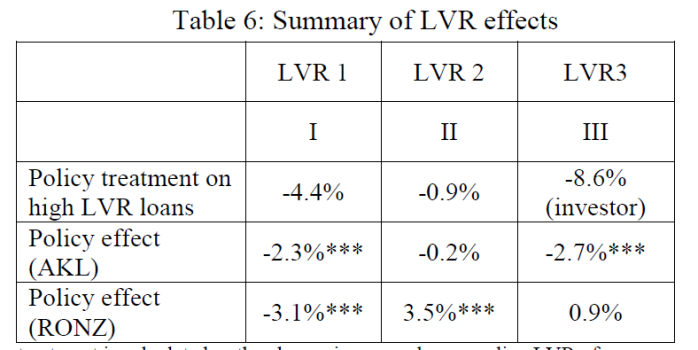
And here is their summary table of the impact of these LVR adjustments on house prices, as estimated from their model.

LVR3

My focus is on the last two lines of the table: the estimated percentage effect on the various different intervention on existing house prices in Auckland and the rest of New Zealand  (the three asterisks suggest that the results are highly statistically significant).

Take the initial LVR controls first (which had the added effect of being something out of the blue, shock effects of a tool never previously used in New Zealand).  Recall too that, at the time, the big concern was about Auckland house prices and associated financial stability risks.    On this particular set of model estimates, the effect on house prices outside Auckland –  where there wasn’t a particular problem –  was larger than the effect inside Auckland.  In both cases, the effect (2 to 3 per cent) isn’t much different to previous estimates, or (indeed) to the sorts of numbers that were being tossed around internally before the controls were imposed.  It was generally expected that the controls would have a temporarily disruptive effect, lowering house prices for a while, but the effects would wear off over the following few years. (There are some model estimates on page 9 of this paper the Bank published in 2013.)

And what about the second wave of controls (which tightened financing restrictions on investors in Auckland, and eased them for everyone outside Auckland)?  On these latest estimates, those restrictions had no discernible impact on prices in the Auckland market at all, even though they were avowedly put in place because of explicit gubernatorial concerns about investor property lending in Auckland.  On, on the other hand, the moderate easing in the rules outside Auckland was so potent that it full unwound the price effects of the first wave of controls.

And, finally, the third wave of controls.  These represented a substantial tightening in investor-finance restrictions (especially outside Auckland), and a reversal in the easing (in wave 2) of the owner-occupier financing restrictions outside Auckland.   And yet, even though the rule changes were materially larger for borrowers outside Auckland, there is no estimated effect on house prices outside Auckland at all (even though, in wave 2 the easing in owner-occupier restrictions, now reversed, was supposed to have had a large effect).  And although the Auckland rule changes are smaller those outside there is no estimated effect on Auckland prices at all.  These results aren’t very plausible and suggest that – even if the results are statistically significant –  the strategy they used to identify the effect on prices isn’t that good.

One could also note that if one added up the effects across the three columns (which isn’t kosher, but still…….) the total effect outside Auckland is basically zero (actually slightly positive).  Even in Auckland, the total is about 5 per cent.

One of the reasons why simply adding up the estimated effects isn’t kosher is because everyone has always recognised that LVR restrictions are unlikely to have long-term effects on house prices.  They disrupt established established financing patterns, and thus can dampen house prices a bit in the short-term, but the effects dissipate with time.

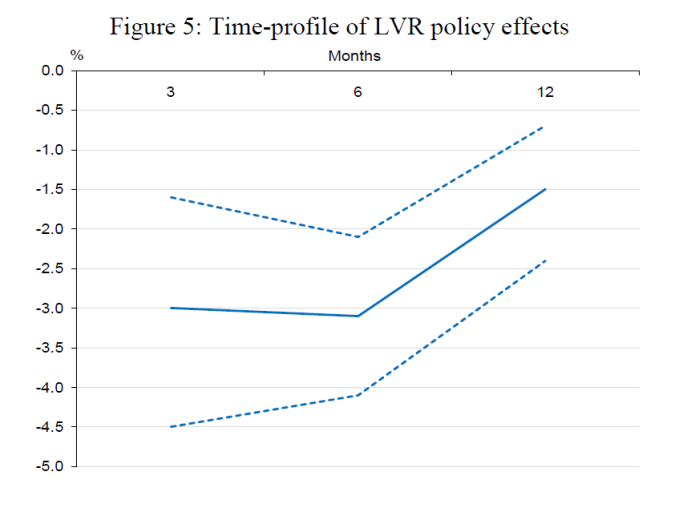
In fact, the Reserve Bank researchers illustrate exactly that point in this chart which (if I’m reading them correctly) relates to the first wave of LVR controls.

LVR4

As the authors themselves observe

Figure 5 plots the point estimates with 95 percent confidence intervals. Overall, the effect of the first LVR policy on house prices occurs within the first three months and is relatively stable over a six-month period. Thereafter, the moderating effect declines somewhat (to around 1.5 percent after 12 months), perhaps owing in part to individuals having saved up the required deposit under the policy and a price differential having opened up between existing and newly built houses.

Any substantial effects on house prices don’t seem to last long.

To be fair to the Bank, and the former Governor, they never claimed house price effects would last for long.  The argument was that LVR restrictions reduced financial system risks by altering the composition of bank balance sheets.  That is another contentious claim, but it isn’t touched on in the current paper and so I won’t deal with it further here either.

So what led them to write (and their bosses to approve) the extravagant claim that LVR policies reduced house price pressures by almost 50 per cent?    It seems to be this

The moderating effect of LVR 3 was clearly seen in Auckland with a 2.7 percent reduction in house prices. This LVR 3 effect is both statistically and economically significant, as during the same period the average house price increased by 5.8 percent.

Overall, we estimate that the LVR policies reduced house price pressures by almost 50 percent.

But

  • as the table above shows, there was no estimated effect on all (from LVR3) outside Auckland,
  • even inside Auckland, and granting their estimates, 2.7 per cent is under a third of pre-LVR price increases during that specific period (the 5.8 per cent that happened anyway, plus the 2.7 per cent they claim to have reduced prices by).
  • as the chart aboves shows, on their own estimates, the dampening effects of LVR controls seem to dissipate relatively quickly (in that case half of the effect had unwound within 12 months).
  • the estimate seems to take no account of the ongoing house price inflation outside the arbitrarily chosen period they measure.

Contrary to their claims, LVR policy is not very effective in curbing house prices.  Indeed, its staunchest advocates never really claimed otherwise (for them it was mostly about financial stability), which does leave one wondering why today’s Reserve Bank management are publishing such overblown (and undersupported) claims to be made.  As I noted earlier, over a period when nationwide house prices rose by about 40 per cent, this latest model suggests no sustained impact at all on house prices outside Auckland –  despite significant interruptions to established financial structures and effective property rights –  and probably quite limited effects in Auckland too.

Overblown claims about what LVR controls can do for house prices (especially with no discussion at all of efficiency/distributional costs etc) risk distracting attention from the real regulatory failures that explains the dysfunctional housing market.  And they also detracting from the credibility of the Reserve Bank, whose legitimacy depends in part of being authoritative when it speaks.


A sadly diminished central bank

Under the Reserve Bank Act as it stands at present, before a Governor is formally appointed the Minister of Finance is required to reach agreement on a Policy Targets Agreement (on monetary policy) with that person.  It is a strange system –  again one no other country has chosen to follow in law.  A Governor-designate may, for example, not know a great deal about monetary policy before taking up the job.  And it also appears to give a great deal of policy-setting power to an unelected official, treating the Governor-designate as almost an equal with the elected Minister of Finance.   Since the Governor-designate will generally be ambitious for the role –  and as even potential Governors give some deference to, for example, electoral mandates – in fact the Minister of Finance has the greater say.

The system is shortly to be replaced.  Here is what the Minister of Finance had to say in his announcement on the Reserve Bank reforms in late March.

Currently, the PTA is an agreement between the Minister of Finance and the Governor. Looking forward, as the MPC will be collectively responsible for making monetary policy decisions, it would be inappropriate for the Governor to be the sole member of the MPC to agree the operational objectives for monetary policy. As a result, we are changing to a model where the Minister of Finance sets the operational objectives for monetary policy. These objectives will be set after nonbinding advice from the Reserve Bank and the Treasury (as the Minister’s advisor) is released publicly.

The approach the Government has agreed to for the setting of operational objectives going forward was recommended by the Independent Expert Advisory Panel. This approach imposes discipline on the decisions of the Minister, given the fact that the Minister’s decision will need to take account of publicly disclosed advice from the Reserve Bank and the Treasury. Further accountability measures, such as requiring the Minister to justify decisions before the House, will be considered in the detailed design of this policy proposal.

It is also intended that the setting of monetary policy objectives going forward will involve greater transparency and public input. Decisions on monetary policy objectives are important, and therefore public debate and understanding should be required.

There are still a few unanswered questions, details to be fleshed out, but that looks a largely sensible approach.  I especially welcome the emphasis on

a) the routine pro-active disclosure of official (Treasury and Reserve Bank) advice on the setting of the operational objectives for monetary policy, and

(b) greater ex ante transparency, public input, and public debate.   Setting the operational objectives for monetary policy is the key bit of policy around macroeconomic stabilisation, and is far too important to be done secretly by the Minister and a few internal advisers.  In almost other area of multi-year policy, proposed frameworks would be open for much more public consultation, scrutiny and debate.  I’ve written previously about the much more open approach adopted to the five-yearly refresh of monetary policy targets in Canada.

So, well done Minister.

But despite the admirable promises about the future, in the most recent PTA (that signed with Adrian Orr in late March, a day before he took office), the process seems to have borne no resemblance to what the Minister promises for the future.

There was no public consultation (indeed, the Treasury papers that have been released talk of some consultation with some market economists in 2016 –  under a different government with a different view on monetary policy and the Reserve Bank).

The Treasury advice to the Minister has been pro-actively released (I wrote about it here), but it was disturbingly thin in key areas (issues around the effective lower bound for nominal interest rates, and the next recession).

And what of the Reserve Bank?  One might expect that the Reserve Bank itself would have the greatest concentration of official expertise on monetary policy and related issues –  not just drafting issues, but the key economic issues, including some of those monetary management issues that are just over the horizon).  One certainly wouldn’t want only Reserve Bank perspectives taken into account –  after all, one key part of the PTA involves the Minister, acting in the public interest, disciplining and holding to account the Reserve Bank –  but it would be astonishing if they didn’t have useful perspectives to add.   Perspectives that really should be seen by both the Minister of Finance and by the Governor-designate.  The Minister’s statement about future arrangements would suggest that, at least in principle, he’d agree.

When the Policy Targets Agreement was released I noted that I had lodged an Official Information Act request for the Reserve Bank’s analysis and advice on PTA issues, but that I didn’t really expect much, because I expected to be obstructed and delayed.

There was a bit of delay, in that the Bank took almost the full 20 working days to respond when –  as will shortly be clear –  they could have (and by law should have) responded almost immediately.

This was what I asked for

Copies of any papers relating to the new Policy Targets Agreement signed earlier this week.  I am interested in any advice to the Minister or his office, and any advice provided to the then Governor-designate, as well as any substantive internal advice or analysis papers prepared or obtained in the period since the current government was formed.

and this was the response

The Reserve Bank didn’t provide advice about the Policy Targets Agreement (PTA) to Adrian Orr prior to his start as Governor, and advice to the Minister of Finance was provided by the Treasury rather than the Reserve Bank.

That is a categorical statement: no advice (written or oral) to the Minister of Finance, and no advice (written or oral) to the Governor-designate.

In a follow-up email exchange, I also clarified with them that there were no “substantive internal advice or analysis papers prepared or obtained in the period since the current government was formed” either.

And there was also nothing of this sort in the Briefing for the Incoming Minister released late last year either.

It is almost literally incredible –  ie impossible to believe.  Public servants of my acquaintance have suggested that the Bank might just be lying, but I don’t believe that.  Or perhaps I crafted my request too narrowly?  Perhaps they had done substantive analytical pieces before the election rather than after it, but given the differences in emphasis between the two main parties it doesn’t seem likely that one would really be a substitute for the other.  And they probably will have provided comments to Treasury on drafts of its advice to the Minister, but nothing in that advice is a distinctively Reserve Bank contribution.

It seems rather a sad commentary on what the organisation seems to have become over recent years.  There has been much talk about collective monetary policy decisionmaking –  and ministerial commitments to legislate –  and yet the new Governor apparently neither sought nor received any advice from his (new) senior colleagues on the drafting of the Policy Targets Agreement, the key macroeconomic stabilisation policy document.  The Reserve Bank has substantial experience with the conduct of monetary policy here,  substantial exposure to what is done in other countries, and a significant research capability funded by taxpayers (presumably, at least in part, to shed light on such issues).   The Minister of Finance says he wants future PTAs (or their equivalent) to benefit from (published) advice from both the Reserve Bank and the Treasury, and yet he sought –  or at least received –  none this time from the Reserve Bank.  And yet the Bank itself, if its OIA response is to be believed, had done no substantive analysis or internal advice on PTA issues in the months between the government  – with, for example, its new emphasis on employment – taking office and the signing of a new PTA.

It seems like some sad mix of abdication of responsibility, and the sidelining of the institution that is supposed to be centre of official professional expertise in the area.

It is a far cry from, for example, the approach taken fifteen years earlier.  In April 2002 Don Brash resigned as Governor, and Rod Carr was appointed to act, holding the fort until a new permanent appointment could be made.  That process in turn spanned a general election.  At the time, Reserve Bank senior management took the view that it would prudent and useful for us to invest quite heavily in preparing background papers which could assist the Minister of Finance, The Treasury, the Board, and whoever was being considered for appointment as Governor to (a) get to grips with the issue, and (b) see where our reading of the evidence and arguments had led us to.  The resulting 100 page document is here.    And that wasn’t the limit of our involvement.  We provided advice to Alan Bollard (before he took office) for his discussions with the Minister of Finance, and participated directly in at least one (I say “at least” because I attended one  myself) of his meetings with the Minister on detailed issues around the negotiation of the Policy Targets Agreement.   It wasn’t a climate in which Reserve Bank staff and management perspectives were necessarily overly welcome –  the Bank was to some extent seen as almost an ideological “enemy” (see, as one cause, Don Brash’s 2001 speech I wrote about recently) and there was a great deal of opposition in the Beehive to the idea of anyone internal getting the job as Governor.     But it didn’t stop the Bank preparing and supplying what was (to my mind) reasonably good quality analysis and advice.

As I’ve said previously, the Reserve Bank certainly shouldn’t have a monopoly on advice/analysis in this area –  and much of its analysis on various issues in recent years has been less good than it should –  but the apparent complete lack of any serious analysis or advice to the Minister or the Governor-designate reflects pretty poorly on all involved –  Minister, “acting Governor”, Governor-designate.   It tells of a sadly diminished central bank.

Designing monetary policy committees, revisited

(This post is likely to interest only those with a relatively detailed interest in the reform of the Reserve Bank.)

A month or so ago the Minister of Finance announced the outline of his planned legislative reforms of the monetary policy provisions (objectives and decisionmaking) of the Reserve Bank of New Zealand Act.  According to the material released then

What are the next steps for progressing the outcomes of Phase 1 of the Review?
Officials will advise the Minister of Finance on detailed implementation issues associated with the high-level Phase 1 decisions by late May.

so presumably Treasury is beavering away at present, with the Reserve Bank chipping in to try to retain as much effective control with the Governor and his management team as possible.  Unless, that is, the new Governor is taking a quite different –  and more open and legitimacy-focused –  approach than the Deputy and Assistant Governor he inherited from Graeme Wheeler.   Legitimacy is a key focus in a major new book (Unelected Power) on the institutional design of central banks –  and other autonomous government policy/regulatory agencies – published a week or so ago, and written by Paul Tucker former Deputy Governor of the Bank of England.

I’ve written various posts on aspects of the detailed design issues.  And in a post last week, I dealt with a recent conference presentation on these and related issues by two former central bank officials, one of whom was David Archer, former Assistant Governor (and successively head of financial markets and head of economics) of the Reserve Bank, and now head of the department for central bank studies at the Bank for International Settlements (a “club” for central banks).

I’ve been learning from –  and often disagreeing with – David for almost 35 years now, since he was briefly my boss in my first year out of university, when I was tossed a paper he was writing on reforming the operational aspects of monetary policy and asked for my comments.  He was my boss in a couple of other stints, and then for most of his last few years at the Reserve Bank, he was head of economics and I was head of financial markets.  Frustrating as he could sometimes be –  and I’m sure the sentiment was reciprocated at times – I reckon that in many respects he’d have made a pretty good Governor, at least of a monetary policy focused central bank.  These days he has the advantage of moving among a bunch of very able experts, and perhaps the disadvantage that those people are mostly insiders (formally or not), and his employer is an organisation that doesn’t need to worry much about legitimacy.  Readers may think I’m given to idealism, but on a pragmatism-idealism scale, I’m further to the pragmatic/political end of the spectrum and David towards the idealistic/technocratic end.

As I hope was apparent in post last week, there is a great deal David and I agree on in the context of designing laws, and associated rules, for monetary policy.

  • moving away from a single decisionmaker model (an innovation in the 1989 Act that no one chose to follow, and which has become increasingly less appropriate),
  • that public confidence in the legitimacy of the institution is crucial if operational independence is to be sustained,

Thus far, most people would agree. But we go further:

  • groupthink is a serious risk in any institution, and in any Monetary Policy Committee, and groupthink can seriously undermine the advantages of establishing a committee,
  • free-riding is also a risk in any such committee, and thus
  • a Monetary Policy Committee should have a clear majority of outside members,
  • and those members should be individually accountable for their advice and their vote,
  • a diversity of views/perspectives should be sought, and encouraged (consistent with the high degree of uncertainty and the risks of groupthink in any institution),
  • a role for parliamentary scrutiny (in my case) or approval (in David’s) for people nominated to serve on an MPC,
  • proper and substantive minutes of MPC meetings should be published, with no more than a short lag.  Such minutes should capture and convey the differing perspectives that individual members bring to the discussion (whether about specific OCR decisions, or the approach the committee is taking to monetary policy).  A parallel exists in the form of the range of (majority and minority) opinions judges of higher courts often deliver in deciding cases.
  • individual MPC members should be free to give speeches or interviews articulating their perspective on monetary policy issues, and not be bound to present only a majority institutional view,
  • appointment terms should be staggered, and of a significant length.   David favours prohibiting reappointment, although I’m more hesitant about going that far (because very long term weakens the effective accountability we both seek).
  • periodic external reviews of monetary policy have an important role to play, and should be an established feature of the system (rather than, say, a response to specific episodes of discontent).

Since my post last week, David and I have been exchanging notes on a couple of the issues where our views diverge.  (There are probably others –  while I’d not be averse to a single non-New Zealand member of an MPC, David would  – on past form –  be more open to a larger foreign participation.  For me, one element of legitimacy is about –  in Paul Tucker’s phrase –  perceptions of “values compatibility”.  The New Zealand public need to be confident that an autonomous central bank is working for them, and that is more likely –  at the margin – when the decisionmakers are themselves drawn from that community).  David has given me permission to quote from our exchange.

In my earlier post, I quoted from the Archer/Levin slides

The MPC should formulate a systematic and transparent strategy that guides its specific policy decisions over the coming year or so.

and observed

Easy enough to write down, but hard to make it mean anything particularly specific.

In response he noted (emphasis and link added)

As in my comments on Rennie, and as in Andy’s presentation, I see 3 layers for policy. Call them framework, strategy and tactics. They correspond roughly with what goes into a PTA; the policy reaction function that goes into the forecasting model (alternatively, a Taylor rule or alternative rule that captures the systematic aspects of policy in pursuit of the target(s)); and the stuff around nowcasting and forecasting. Andy and John Taylor and others argue that the Fed should be articulating its strategy, and disclosing that, though Andy is more open on the form in which the strategy is articulated that John appears to be. You and I argue that the RBNZ should disclose its model, also so that the systematic parts of the Bank’s thinking are on display. We’re all talking about central banks being more open about the systematic elements that are under the their control, to improve discipline and legitimacy.

So I actually think we’re in a similar place. We might disagree on whether a Taylor Rule type of PRF [policy reaction function] “dumbs down” the policy process too much – in my view, the ability of the Taylor Rule (or variants thereof) to capture the essence of policy needs is remarkable and telling, as is the regularity with which departures from TRs have turned out to be mistakes. And we share the view that central banks should be required to explain why they think this time is different, which is helped by having a publicly disclosed benchmark.

We both agreed that forecasting is of little value.

Part of the context here is about proposals in the US to require, by law, the Federal Reserve to publish the reasons why its interest rate decisions deviate from the recommendations of, say, the Taylor rule (a fairly simple, but at times surprisingly useful, guide to how central banks (should/do) run monetary policy (using just a neutral interest rate, an output (or employment) gap, and the gap between the inflation rate and target).  David is more sympathetic to something along those lines than I am, and sees the primary role of an MPC as to formulate and articulate a strategy to guide monetary policy.

In response I wrote

I’m inclined to agree that the Taylor rule seemed to do a remarkably good job for a period, although am less sure of its value in the last 5-10 years, because one of the key questions that central banks have had to grapple with (implicitly or explicitly) is what is happening to the natural interest rate itself –  and Taylor can’t offer useful insights on that.  As you note, I would favour the RB publishing its forecasting model, including the reaction function (as part of much greater sense of input-transparency all round), altho I’m more sceptical about the ability of the reaction function to really represent all the contingencies a committee of policymakers (esp an individualistic one) is likely to have in mind.  I’d probably put more weight on the potential for good minutes –  of the sort you suggest –  combined with a requirement for MPC members to publish their individual estimates of key system parameters (neutral interest rate, NAIRU –  akin to the final observation in the Fed dot-plot) to provide a steer as to thinking, and something later to use for some sort of accountability.

In other words, I’m all in favour of an MPC publishing lots of its inputs (eg the background staff papers it receives) and a lot about individual members’ priors.  Like David, I favour the publication of good minutes.   But I’m sceptical that an MPC can usefully go very much beyond what is captured in a PTA –  the bit the Minister of Finance controls.   There is just too much uncertainty about how the economy works at any particular point in time –  more so in the last decade with a great deal of uncertainty about “the” neutral interest rate – for statements of MPC strategy to add very much value.

Our other area of disagreement seems to be over the type of people who should be appointed to serve on a statutory Monetary Policy Committee.

In his announcement of the proposed New Zealand reforms, the Minister of Finance indicated his view on that issue as follows:

External members will have knowledge and experience in relevant policy areas (such as economics, finance, banking, or public policy). However, members will not be limited to monetary policy experts. External members will need to be free from conflicts of interest and will not be on the MPC to represent a particular sector.

It is worth noting that there is no particular reason to expect that most of the internal members will be monetary policy experts either.  At present, for example, the Governor is chief executive for a broadranging organisation, and may not have had a strong background in monetary policy (neither Brash, Bollard nor Wheeler did), and the current deputy governor is a career public servant with an economics background mostly in labour and fiscal issues.

I wasn’t unhappy with Grant Robertson’s description of the sort of people he expected would be appointed.  But in the Archer/Levin slides, they argued

…..the MPC should comprise a diverse group of experts who are individually accountable for their policy decisions.

To which I responded briefly.

I’m not totally persuaded by the “experts” line myself –  one needs lots of expert input/advice to policy, but when it comes to decisionmaking, soundness is at least as important as cleverness.

To which David responded (we both agreed that the value of outsiders shouldn’t be in bringing a better class of business anecdote to the table –  the role the external advisers play at present)

….the big issues in policy-making, the ones that impact on welfare, concern choices of framework and choices of strategy. Right now, as you also argue, the greatest attention by far should be on whether policy design is right. Do we have the right tools? Can we get interest rates to move enough in response to demand perturbations, without banging into lower bounds? What do we think about the appropriate speed of response? If we had a price level “attractor”, would that help induce stronger responses to negative perturbations that risk acquiring a deflationary dynamic? When might asset prices or other indicators of collective manias sensibly affect policy making? Questions about the variability of the exchange rate come into play in open economies. These are the things that can make a real difference. Tactics don’t. So if we’re staffing a policy committee, we should staff it to be capable of handling such questions, and bring a diversity of approach to the thinking on them. From my observation, it’s in relation to these questions where Group Think has its greatest hold. People find it easy to disagree on timing and tactics, but find it very hard to challenge accepted frameworks.

Hence I come down in favour of a diversity of people with the expertise and inclination to handle evaluations of frameworks and strategy, rather than something aimed to reflect the composition of society or of economic activity. And I acknowledge a cost to that approach: political legitimacy is less readily supported, because the policy committee members are not obviously “like us”.

It is an ambitious vision.  I wasn’t persuaded though

…..where we disagree is whether one looks to the MPC members primarily as expert analysts and decisionmakers/communicators in one, or as customers/purchasers for expert analysis, and then decisionmakers/communicators.  I can’t think of many (any?) bodies in our society that function in the former way.  …..  I guess I”m inclined to think that I want MPC members (including the Governor) who will create a climate that encourages debate, and research, and engagement –  inside and outside the Bank –  on all the sorts of issues you raise, and more, rather than being those experts themselves.  It doesn’t mean I’m opposed to have some genuine experts on the committee, but it might be undesirable (even if enough were available) for them all to be experts. For a start, those people won’t necessarily have the (eg) communications skills a public agency needs, or the institutional political skills.  And realistically, not one of the Governors in my career (here and abroad, …..) has been what I would call a monetary policy expert.   Arguably, none of the deputy governors have been either.  Perhaps that should be changed, but there are pretty slim pickings, and frankly what worried me more about Graeme wasn’t his lack of expert background as his lack of openness to debate/challenge scrutiny.  Realistically also, even if we had resident academics who were strong in these areas, many might be better used –  and themselves prefer –  to be based in the academy, generating research and then interacting with policy people, than devoting large chunks of their time to “tactics” and related stuff.
You also note that “People find it easy to disagree on timing and tactics, but find it very hard to challenge accepted frameworks.”.   Maybe, altho your great chart from the Sept 08 FOMC [reproduced in last week’s post] argues against that (at a time when it counted).
On my telling, an MPC should be a balanced panel of people, dominated by outside non-executives, but drawing on high level technical expertise (staff and outside resources).  Since I favour separating monetary policy and regulatory functions into separate institutions, I would favour seeking a monetary policy expert as Governor (and chief executive).   To me, the parallel is with something like the Cabinet –  drawing on expert advice, sometimes ignoring it completely, without themselves being the experts.   That seems more like the way in which we typically run institutions in our society (a telecoms company board will typically benefit from having some people who really know tech/telecoms but will rarely be exclusively comprised of such people).
David responded, having emphasised his view that frameworks and strategies, rather than specific OCR decisions, are mainly what we want an MPC for.

How does one evaluate alternative frameworks and strategies? With extensive modelling exercises, and empirical evaluation of results of different frameworks and strategies at work in practice in comparable countries. Evaluating, making sense of, and extracting the lessons from such research is thus the main task. The expertise required should be sufficient to evaluate research effectively, but not necessarily to design and conduct that research. What the candidate MPC member needs is sufficient training in economics to understand the research they are being presented with. There’s a specialised vocabulary involved. Different research methods take quite some time to understand, especially in terms of the implicit assumptions involved in the choice of method. Perhaps most importantly, even very experienced lay people struggle to grasp the general equilibrium mind set, which is crucial to comprehending how the macroeconomy responds to various impulses over the time frames relevant to the design of frameworks and strategies.

…. Experts should not be equated with PhDs with great track records for research and publication (though they shouldn’t rule the person out).

I’m not persuaded.  There is certainly a need for plenty of background research, and the synthesising and application of that research to a New Zealand context. But I don’t think decisionmakers need to be literate in the issues in the sort of depth David suggests, and I think there is a real risk that – even if enough such people could be found in New Zealand –  such a panel of people might prove more interested in the esoterica of some of the debates (and the important issues that really matter, like the near-zero lower bound) than about actually making good OCR decisions that deliver inflation consistently at or near whatever target the Minister of Finance has set.  This is a point Paul Tucker makes in his book: reputation is a key element of public sector accountability, but for it to work, the appointed policymakers have to care about the stuff the public is looking for from th institution.   People with a stronger interest in the international conference circuit (I’m caricaturing, but it is a risk) than in short-medium term New Zealand macro outcomes, won’t end up with very much effective domestic accountability.

Tucker also makes a point I’ve made here repeatedly.   Requiring technical expertise to be brought to bear before decisions are made does not mean that the technical experts should be the decisionmakers.   We need to bring a lot of technical expertise to bear around monetary policy (tactical decisions and framework design) but in my view much of that expertise should reside on the staff of the Reserve Bank, and it should be one of the prime roles of the Governor to (a) foster such expertise, and (b) ensure it is exposed to external challenge and scrutiny (and alternative external perspectives) and (c) to ensure the results, and alternative interpretations, are translated into language decisionmakers –  on the MPC –  can make sense of, and can question and challenge (and where those decisionmakers have the incentive to do so).  I’m sure there is a place for some monetary policy experts on an MPC –  including among the externals – but the MPC should no more be dominated by such people than (say) major decisions on war and peace should be made by generals (no matter how valuable their technical advice might be).    Legitimacy is rarely achieved simply by technical expertise.

These are important issues to be thought through in the design of the new MPC for New Zealand, and in the process of making the first wave of appointments (which will establish much of how the MPC works).  In practice, in a New Zealand context (given limited pools of candidates) I’m not sure how far apart David Archer and I would end up being, but I hope Treasury and the Minister are giving some thought to the sorts of issues raised here.


Productivity Commission and the path of least resistance

The Productivity Commission’s draft report on making a transition to a low-emissions economy is out this morning.   It is a 503 page document and so, of course, I haven’t read very much of it.  But electronic search is a wonderful tool.

As I noted yesterday, despite having had a fairly large (by international standards) fall in emissions per unit of GDP since 1990, New Zealand has had one of the larger increases in total gross emissions of any OECD country.  What reconciles those two observations isn’t some incredible surge in New Zealand’s productivity and GDP per capita – as is generally recognised, we haven’t done well on those scores –  but a large increase in the population.  And most of that increase in population is due to the planned immigration of non-citizens to New Zealand.  In other words, it is more or less a direct result of the policy adopted by successive governments (including the current one).

For any given set of technologies and relative prices, more people means more emissions both directly (more transport, more power) and indirectly –  people need to earn a living and so emissions associated with, for example, manufacturing or agriculture also rise.   As a rough first approximation, if we’d stayed with the rate of non-citizen immigration New Zealand had in the late 1970s and much of the 1980s, total gross emissions in New Zealand now would be at least 20 per cent lower.  For governments that want to materially reduce emissions that should be something to ponder (especially as New Zealand average units of GDP are themselves quite carbon-intensive)  It is, of course, water under the bridge now.  But the same high non-citizen immigration targets are still in place and, all else equal, will continue to drive up emissions in future.    Given those immigration policy pressures, more of a (costly) burden of adjustment has to be imposed on the economy through other instruments.   As marginal abatement costs here are widely accepted to be higher than those in most other advanced countries, the likely adverse economic effects on New Zealanders are large.

But you don’t get much of a sense of any of this from the Productivity Commission’s report.  There are quite a few references to the role of population in the growth of emissions.  It even makes one of their formal findings

Finding 2.7     Economic and population growth have been important underlying factors in New Zealand’s rising emissions. Over the last 25 years, New Zealand’s emissions per person and emissions per unit of output have decreased, but the increase in population and output has caused overall emissions to increase.

Flowing from this short discussion.

Strong population growth and economic growth have been key underlying drivers of New Zealand’s rising emissions since 1990. Between 1990 and 2015, New Zealand’s real GDP nearly doubled. During the same period, population growth was higher than most other developed countries (Figure 2.10). More people means greater consumption of goods and services that contain emissions (eg, more vehicle use, and greater demand for electricity). Economic growth (and, indirectly, population growth) means more emissions-intensive goods and services are produced, leading to higher emissions.

And there is the odd passing observation, such as that

Future population growth will provide a challenge in bringing down transport emissions.

although no apparent recognition of the connections to agricultural emissions.

But the Commission has chosen to treat population growth (past and future) as some sort of exogenous given.  For example, they report some results of some commissioned modelling exercises, and in each of the scenarios exactly the same future population growth is assumed.  That might make sense in a country where population changes were almost entirely the result of developments in natural increase (or even of the emigration choices of nationals), neither of which should be any sort of policy lever.  It makes no sense at all in a country where most of the population growth (last quarter century and next) is directly the result of policy choices.

No analytical sense that is.  But perhaps it makes sense if you are a government agency feeling your way with a new government that is strongly committed to the “big New Zealand” mentality and to current immigration policy, and where much of that government seems more interested in having New Zealanders don hair shirts and feel the pain (or alternatively conjure up imaginary futures in which a forced adjustment to net-zero emissions won’t come at aggregate economic cost to New Zealanders).  The path of least resistance politically presumably led the Commission to conclude that it was better (“safer”) not to mention immigration (policy) at all.

And so they didn’t.   In the entire 503 pages there is a single reference to immigration.

But that is just part of the (reproduced in full) Terms of Reference for the inquiry, set out by the previous government.

New Zealand’s response also needs to reflect such features as its high level of emissions from agriculture, its abundant forestry resources, and its largely decarbonised electricity sector, as well as any future demographic changes (including immigration).

It feels a lot like abdication, and not at all like the sort of free and frank analysis and advice that a body like the Productivity Commission should be providing if it is to be any long-term use.  The Commission seems to have been so scared of upsetting its liberal readers –  political and other –  that it isn’t even willing to address the issue.

It would be one thing if they’d devoted some substantive discussion to the issue and concluded, whether on the basis of reasoned analysis or modelling, that the economic benefits to New Zealanders from the immigration policy were sufficiently large, and the marginal abatement costs of other approaches in a portfolio of measures to reduce emissions were sufficiently small, that winding back non-citizen immigration targets should not be part of a preferred response strategy.  Reasonable people could debate that sort of proposition and the evidence advanced for it.  But the Productivity Commission chose to totally ignore the issue.   Since as an institution they don’t seem to be gung-ho enthusiasts for the economic benefits of New Zealand’s immigration policy (see my discussion of their narrative of New Zealand’s economic underperformance) it looks a lot like playing politics, going along with a Labour/Greens (and their acolytes) narrative.  In the short run that might make it more likely they get a hearing from the government. In the long run, that sort of approach to issues won’t stand them  –  or the cause of good policymaking and analysis in New Zealand, already enfeebled enough – in good stead.

(It was also noticeable that amid all the happy talk in the document, there was no sign of any attempt to estimate, or model, the likely real economic costs of the sorts of carbon reduction policies the Commission is dealing with.   There is an entire chapter reporting initial modelling results, but –  as far as I could see –  no reference to the implications for GDP per capita (or any of the cognate national accounts measures).  No doubt, the average New Zealander in 2050 will be wealthier than we are today, but the relevant issue for policy isn’t that baseline, but the deviations from it.  In particular, they should have focused much more attention on what the economic implications of various possible policy levers –  perhaps including immigration policy –  might be, and how best to minimise the economic costs to New Zealanders of making the adjustment the government is planning to target.     And it is fine for enthusiasts for aggressive policies to talk of unpriced externalities etc, but even with those unpriced externalities our economic performance over decades has been startlingly poor, and it isn’t obvious why removing them won’t further worsen economic outcomes.  That might be an acceptable trade-off, but there doesn’t seem to be anything much in this report suggesting just how large those costs and benefits might be.)