Once over fairly lightly: the Covid monetary policy review

(No, two posts in two weeks does not foreshadow any sort of return to regular blogging – tempting as it has occasionally been at least for the pre-election period – but having written copious amounts on the Reserve Bank’s monetary policy, associated governance, and lack of serious accountability during and after the Covid period, I thought it would be worthwhile documenting some reactions to the report of the Independent Review of the Monetary Policy Response to the Covid-19 Pandemic which was released on Wednesday yesterday. And, of course, writing helps clarify my own thoughts.)

One of the (minor) odd features of the report was that it did not include the terms of reference given to the reviewers by the government when they commissioned it back in February. Interested readers had to go hunting for themselves. Here is a link to the terms of reference.

There were a number of weaknesses in the terms of reference. The very first purpose listed for the review was to “support accountability” and yet only the decisions of the MPC itself were in scope (not, notably, those charged with holding them to account, whether the Bank’s Board, The Treasury, or the (then) Minister of Finance). Given that the system, as legislated by Parliament, is supposed to balance operational autonomy for the MPC with meaningful accountability, it is a shame that the workings of the entire system over that period were not reviewed. Equally less than ideal was that the reviewers chose to focus solely on the committee as a whole and not on the roles, responsibilities, performance etc of individual members, executive and external.

And it was only when I went back and read the terms of reference yesterday that I was reminded of this.
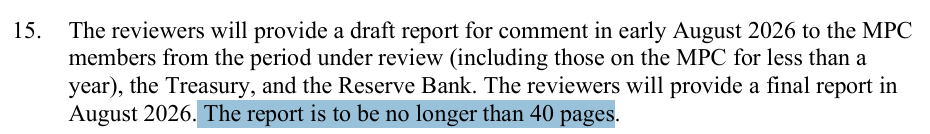
It seems very odd for ministers to put a page limit on an independent report, and especially one into matters so complex and consequential (and, as it happens, costly).

There was a KC report into the some specific issues around the conduct of the previous FMA chair Craig Stobo earlier this year, which (without apparent page limit) ran to 45 pages. The first of the reports into the Mount Maunganui landslide earlier this year ran to 250 pages. And more directly relevantly, as part of the 2023 (broad) review of the Reserve Bank of Australia, one of the authors of this review (Orphanides) wrote the reviewers a background paper on the RBA’s monetary policy near the effective lower bound, and it – just a background paper – ran to 62 pages. Lars Svensson’s 2001 independent review of Reserve Bank monetary policy ran to almost 80 pages.

Who knows quite why the Minister of Finance imposed such a limit, which more or less guaranteed that a lot of issues would have to be skated over all too lightly. Perhaps it was the delays they experienced with coalition partners and then finding potential reviewers, but we’d probably have gotten a more substantively useful document had the reporting deadline been extended somewhat (no doubt beyond the election) and the reviewers left freer to elaborate.

Another odd feature of this review – as opposed to Svensson’s – was that public submissions were not sought. The reviewers talked to a reasonable range of economists (only, listed at the back) but, for example, did not talk at all to one of Orr’s most vociferous economist critics during the period. Nor, for example, did they talk to (then) ministers or their advisers, to FEC members, to (it appears) senior Treasury people during the period (including the then Secretary, who was a non-voting MPC member) or even to people who were on the Reserve Bank Board (charged with holding MPC to account, and recommending (re)appointments) through the period. These sorts of people should have been relevant even if only as those who had direct exposure to the Bank and MPC members, and how they thought and operated, throughout this turbulent period. (To be clear, I’m not complaining for myself: not only did I have a fairly long meeting with the reviewers but at David Archer’s request I provided some written material at the start of the process, mostly as pointers to real-time perspectives and analysis I had written during the Covid period.)

The reviewers also seemed oblivious to (or at least uninterested in) the issue of whether or not, and if so to what extent, people (expert and otherwise) may have lost (or, I suppose, gained) confidence in the Reserve Bank/MPC through the experience of the period, whether from the substance of their decisions, the outcomes, the way they communicated and engaged, or otherwise. It is all a bit odd, especially as both Archer and Orphanides have had exposure to the wider governance/legitimacy side of things, Orphanides as Governor (central bank of Cyprus, admittedly part of the least-acccountable central bank system on earth, the ECB) and Archer latterly in his senior BIS role and various papers he has written or co-authored – I discussed one of those here a couple of years ago.

Back when the review was first announced to report in September (having been promised for some years) there were some feverish people on Twitter suggesting it was all a political jack-up designed to embarrass the Labour Party weeks out from the election. There was even talk of “evil” Atlas Network connections. I thought that was pretty much nonsense (and said so), initially because of what I knew of the reviewers (I worked with/for David on several occasions over 20 years, and today we are both trustees of the Reserve Bank’s troubled superannuation scheme), neither of whom seemed the type to do anything other than articulate their conclusions freely and frankly (and neither seemed likely to be wanting future business/appointments from the New Zealand government). As it happens, OIAed documents revealed that the original intention had been for the review to be done and completed ages ago, but…coalition parties and finding credible reviewers added delays.

And whatever your personal opinion of the government(s) in office over the period, I do not believe there is much evidence that the government or its ministers can be blamed for the succession of decisions that led to such a costly outbreak of inflation and such large financial losses. The MPC is set up to have operational autonomy over monetary policy, which is supposed to mean that specific governments neither get the blame when things go wrong (MPC makes bad calls) or gets the particular credit when things go well. In practice it isn’t like that, of course, but such pressures are to be resisted. Operational independence becomes hard to sustain if politicians get tarred with all the blame (or even the credit) but have none of the decision-making authority. Sure, bad appointments can be made but – to take Orr as an example – while he was appointed by Robertson in late 2017 it was (and had to be) on the recommendation of the Bank’s board, who had been wholly appointed by the outgoing National government. No doubt Robertson was weak to have gone along with the Orr/Quigley 2018/19 blackball on appointing experts as non-executive MPC members, but in doing so he was acting on advice (and Treasury seems not to have pushed back on that advice). Did those mediocre appointees make a difference? I’m a bit sceptical (much as I wish it was otherwise) and of course the reviewers never even touched on the quality of those on the MPC.

Where politics does come into focus primarily is in the context of the so-called dual mandate added to the Reserve Bank Act in 2018. The reviewers clearly did not like that amendment one little bit (which could readily have been predicted).
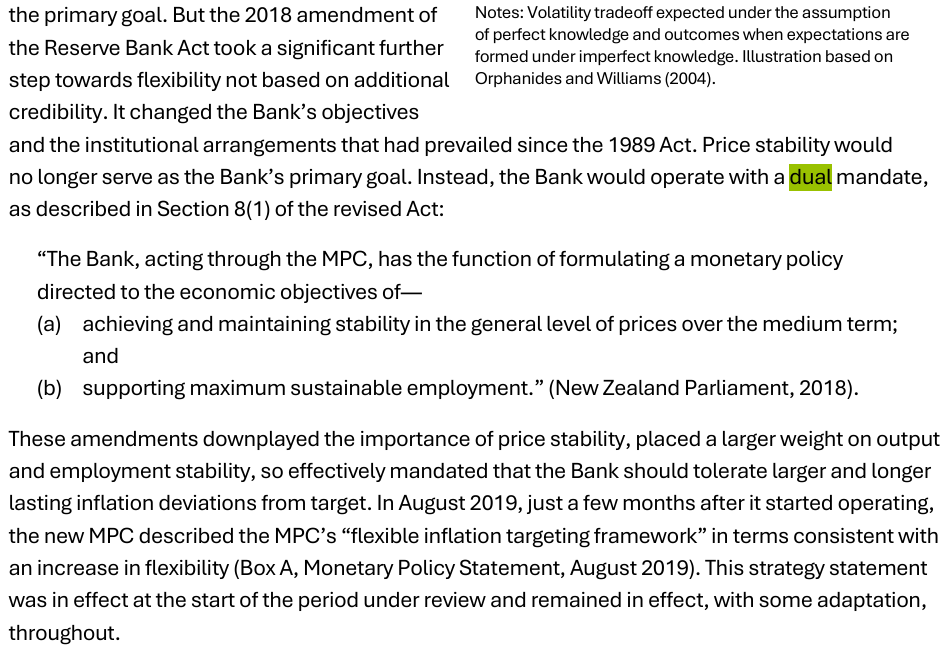
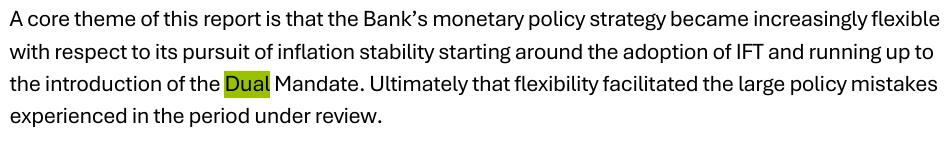
That was, no doubt, music to the ears of the Minister of Finance (quoted in her press release) but the problem is that the report itself offers no analysis at all to support the suggestion that the statutory change made any difference to policy choices or outcomes. They never, for example, even mention of the line run several times by the former Governor that in his assessment (and he did chair the committee) the change had made no difference to decisions made over this period, and they never (for example) engage in even the simplest cross-country assessment (did countries with dual-mandate specifications come through this period with worse outcomes than countries that retained a simpler specification?). It is well understood that in the face of demand shocks, you get exactly the same recommended policy response with a sole medium-term price stability focus (what the Bank was required to focus on immediately prior to the law change), as with something like a dual mandate specification. And since (as the report notes) no inflation-targeting central bank was ever an “inflation nutter” faced with near-term supply shocks to prices – precisely because of the output and employment consequences – it isn’t clear how the authors themselves believe the law change changed outcomes.

As I’ve pointed out on plenty of occasions, the Bank’s forecasts through 2020 and the first half of 2021 typically suggested that if anything MORE policy stimulus was required, and that such stimulus would both raise inflation towards the target midpoint and lower unemployment towards the non-inflationary sustainable rate (because forecast inflation was low and forecast unemployment was high). Their forecasts were very wrong, but there is nothing the reviewers point to – and they had access to MPC members and presumably to the unpublished background papers – suggesting the dual mandate made a difference. They were, of course, constrained by that page limit, but must have been aware of the political sensitivity of the issue. It is an unfortunate omission, and while they might seek to defend themselves by noting that the terms of reference explicitly refer to “the objectives of monetary policy that applied at the time”, they were the ones who chose to open up the dual mandate issue (probably rightly in my view, because it is a question that should be asked, and investigated seriously).

I noted that there was no attempt at a cross-country perspective on whether the form of the mandate made a difference (and I suspect they knew there was little reason to think it would) but it is just an example of another significant weakness of the report. They were specifically charged with considering as background “relevant decisions made by comparable central banks” but there are very few specific mentions of other central banks at all, and no attempts to compare and contrast policy choices, initial shocks (that central banks faced) or inflation outcomes (again allowing for things like different shocks – eg gas prices were to matter vastly in Europe in 2022, but not all in New Zealand). There is some reason to think that our Reserve Bank may have done worse than many (as I have long pointed out, and as more-recent Reserve Bank pieces note, we are estimated to have had probably large positive output gap – measure of economic overheating – of any advanced economy), but equally it is fair to point out (and the report never does) that central banks in most (but not all) advanced countries made very similar errors – notably forecasting errors – to those made by our Reserve Bank. On the one hand, that is some (modest) defence – it would be worse if ours had been uniquely bad – although on the other, each central bank takes on responsibility for outcomes only in its own country, and each has to be accountable for those national outcomes.

It is also puzzling that the report never looks closely at private sector, or implied market, views of the outlook for New Zealand inflation or required monetary policy. There is simply a parenthetic reference largely dismissing the fact that those views were very similar to the Bank’s (on grounds that the Bank’s forecasts can influence outside forecasters’ views). But when private forecasters and commentators think a central bank is getting things very wrong, they tend to say so (even if they also need to guess what the Bank will actually do). It is less bad when the MPC makes the same mistake as people operating in the private sector, with lots of money at stake, but……private forecasters, informed commentators, and hedge funds etc aren’t responsible for NZ monetary policy and inflation (or thus to the wider public at all), while the MPC is. In fact, the review is sometimes reluctant to even assign responsibility (on the very first page we are told, abstractly, that “mistakes were made”, but not that named individuals who assumed voluntarily the responsibility and prestige of MPC appointments themselves made those mistakes (here and abroad). The report is very light indeed on any serious form of accountability (including, for example, never once – in the body of the text – mentioning the names of those involved).

Incidentally, one wonders if journalists have sought comment on the report from those who were MPC members during the period. My guess is that they will be reasonably happy with it, to an extent they probably should not have been able to be.

They get off rather lightly, both individuallly and collectively. More than a few points are just never developed, Take, for example, this
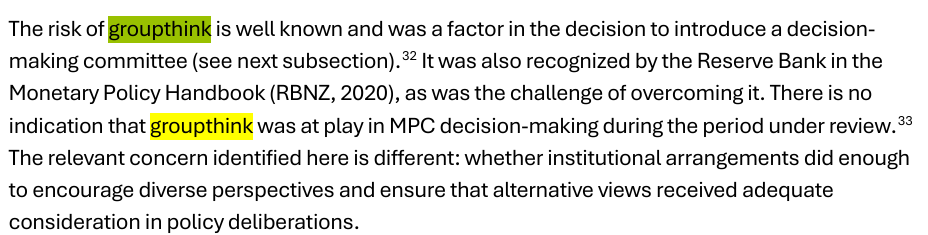
And that footnote? “One of the reviewers, Mr Archer, does not agree with this statement.” There were, after all, only two reviewers (so, for a start, how did they decide whose view got in the main text and whose in the footnote?), and this is the only highlighted difference between them, and yet there is no sign of what evidence or reports they each used to reach a view on this quite significant issue (on which Archer has had strong documented views for years). They seem to resolve to agreeing on the abstract (“institutional arrangements” doing “enough to encourage diverse perspectives”) without serious analysis of what actually happened in the specific, very costly, period of policy conduct they were asked to review.

And while there are abstract and general issues worth considering, and certainly in any committee constituted as MPC then was, it is pretty extraordinary that none of the specifics around individuals, notably the Governor, are engaged with. Orr has had a reputation for too often having been intolerant of dissent or challenge, whether internal or externally-sourced. And during this period he was cycling through senior managers, including those directly associated with monetary policy. The able Deputy Governor had apparently had enough and announced he was leaving, only to have his employment summarily terminated a few weeks early, the Chief Economist through the period seemed pleasant but not really up to the senior role and seems to have found it best to leave, and then of course late in the period under review an utterly unqualified (for MPC-type responsibilities) new DCE responsible for macro matters was appointed. In a committee required by law to have a majority of internals those people, and sets of circumstances, don’t sound like a mix that would have produced optimally open debate and mutual challenge. Committees don’t exist in the abstract, but with concrete individuals, with their personalities, dispositions, incentives, and so on. Perhaps it really was all okay, but the reviewers make no serious attempt to engage on the issue.

There isn’t even any reflection, anywhere in the report, on the fact that throughout the entire, very challenging, Covid period there was not one dissent recorded, ever (and while consensus was formally encouraged, votes were never prohibited, nor the clear expression of an alternative view). My bias is to the agree with Archer’s dissent, but….they had the opportunity to gather and report evidence from inside, and yet they seem to have chosen not to do so.

Perhaps in a similar vein, there is nothing in the report about the extent of external engagement, or otherwise, of MPC members during a period of extreme turbulence and great uncertainty. There were barely any serious speeches through the period, almost no external engagement by external MPC members, and little or no sign of any systematic attempts to engage with the uncertainty by, for example, hosting workshops or conferences to try to open themselves to alternative perspectives or explore the uncertainties they (and everyone else) faced. And, of course, because for example the external accountability stuff was out of scope, there is nothing about the frosty way in which the Bank engaged with any challenge or scrutiny at FEC. None of it suggested a “learning organisation”, an open one, or one that recognised the need to maintain its legitimacy and the centrality of accountability.

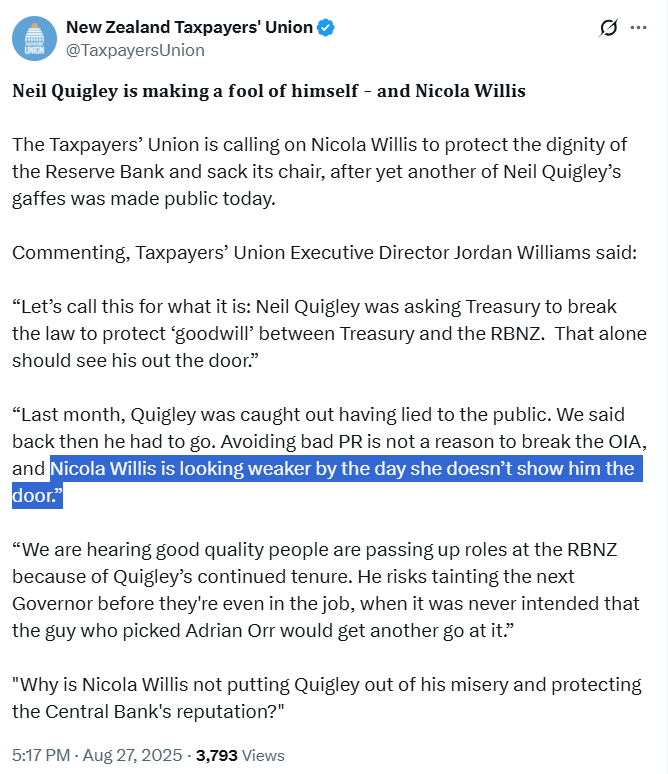
Not all punches are pulled. It was good to see the review highlight how extraordinary it was that nothing had been done before 2020 to ensure that banks’ systems etc could cope with negative (policy) interest rates (having had years of notice of the issue, and having themselves expressed in public the view that negative rates were likely to be a better tool than large scale asset purchases. Had they got onto that earlier – even had the new MPC raised concerns when it was established – it is likely the MPC would never have engaged in such large scale, risky, and (as it turned out) very costly LSAP purchases. Billions of dollars wasted for a failure by the Bank to have been suitably prepared for a foreseeable threat (makes MBIE’s technology project woes seem cheap). The Taxpayers’ Union may not be flavour of the week, but in their inimitable style they called out the waste.

But this is precisely where the official independent review gets weak. They suggest that the initial LSAP purchases were just fine (market stabilisation and all that), but don’t ever bother to engage on whether those RB purchases made any difference (to a temporary market liquidity crisis centred not here but in US Treasuries and where the Fed itself was intervening directly), or as to why once markets did settle profits weren’t quickly taken. More concerningly, there is no serious analysis of the effectiveness of the more-sustained LSAP purchase process that followed. They, fairly, note that to the extent there was much stimulus it proved, with hindsight, unwelcome (since inflation blew out) but never engage on the question of how much effective macroeconomic stimulus there actually was in the specific context of New Zealand. The financial losses are never quoted, and there is no attempt to engage or review with the claims, as recently as late last year, from the Reserve Bank that really it was all fine, and perhaps even net positive for the Crown. Without having done (or reported) any of that sort of analysis, they blithely suggest that there is a continuing role in the arsenal for LSAPs (and actually suggest legislative changes to remove some possible future roadblocks). And, on the other hand, despite those comments on negative interest rate capability earlier, there is nothing at all about the desirability of work to ease the remaining ELB constraint. Perhaps the reviewers think that would be a bad idea, but they don’t say, or offer any analysis. As it is, the OCR is about 350 basis points from the effective lower bound, and typical past cycles have involved 500 points of easing.

They also pull their punches around the Funding for Lending programme. They seem, reasonably, sceptical of the case for having introduced it (although, to be fair, it wasn’t completely inconsistent with their macro forecasts at the time) but never touch on the extraordianry way they went on providing crisis-support (cheap funding), exacerbating their OCR challenges long after any need for macro support had passed (claiming they were somehow “bound” – legally or morally was never clear, neither at all robust – to keep on).

Another area where I’d be critical of the report is around the initial monetary policy stimulus. The reviewers go to some lengths to portray the monetary policy approach from May to later in 2020 as reasonable given the forecasts the MPC was using. But in doing so they tend to treat the forecasts as a given, handed to the MPC by other people, when the forecasts themselves are the collective views of the MPC itself. They are certainly advised and supported by staff, but recall that the MPC at the time included the Governor and three other senior internal economists: the forecasts (or “baseline scenarios” as they were being called for a time in 2020) cannot be very meaningfully separated from the policy calls. In each case, each decisionmaker was applying their own “model” of the economy and of how the macroeconomics of the shock was going to play out, and then – given the Remit – how best policy should respond. MPC members had, certainly, to work with the initially limited data they had, but much more important in this case is that they were – again with hindsight – all clearly using the wrong models to think about how pandemic macroeconomics was going to play out (demand vs supply effects for example). This is a point that is simply never touched on in the report, even though it was (arguably) the single most important failing, not just by the Reserve Bank MPC but by macroeconomists around the world, in central banks and out. Perhaps we can call it pardonable to some extent – after all, it was a completely unknown sort of event – but it proved to be a huge and costly weakness. But also idiosyncratic.

Had we (they) properly understood the pandemic macroeconomics, and taken account of what fiscal policy was doing (as the Bank in fact did, so this isn’t the main issue), there would have been a strong case for the OCR never to have been cut in March 2020 and probably to have been raised very quickly, at least by the time the first successful lockdown was over. But again, the reviewers never engage with that sort of thought experiment, and they show no sign of having used their vast experience to reflect on why it was that the Bank (and so many others) misunderstood the economics. (I don’t purport to have a compelling answer either, but it was the root cause of what went so badly wrong later.)

Partly as a result, the report ends up being too inclined to absolve the MPC of responsibility for the mess (boom and bust, large unexpected transfers of purchasing power). If what was done initially was reasonable (“praiseworthy”, “rapid”, “innovative”, providing a “timely and much-need boost” [the latter as if lags are almost instant, and as if the aim of policy in March 2020 had not been to markedly shrink economic activity, temporarily]). And so the reviewers end up more or less buying into a line, run now by the Reserve Bank itself for several years, that really, while of course they should have started tightening a bit earlier, really it either wouldn’t have made much difference or would have done so only at untenable economic cost. The reviewers devote a lot of space to a little modelling exercise the Bank put out last year, suggesting that if they started tightening in late February 2021 with the goal of keeping inflation always at 3 per cent or less, it would have done huge economic damage (it first went through 3% in the June quarter, centred on mid-May). Well, of course, not only does no one thinks that monetary policy works with that short a lag, but….the bigger issue is why so much easing had been done in the first place. (I’m not suggesting the MPC members themselves deserve huge criticism for those March 2020 calls but….they did have quite the wrong model, and it was the source of what followed, the aftermath of which we are still living with.)

This has become a very long post. I want to finish with just a limited number of other specific points:

  • it is very odd that throughout the entire paper there is never a single reference to a core inflation measure (or concept). Now it is, of course, true that the inflation target is specified in terms of the headline CPI, but Remits and (previously PTAs) have always enjoined the Bank to “look through” temporary or one-off price disturbances, to extent consistent with maintaining medium-term price stability. Thus, central banks rarely respond directly to, eg, sharp rise or falls in petrol prices which can make a big difference to near-term headline inflation. In this case, for example, the report emphasises the large fall in the CPI in the June quarter 2020 (quoted in American-style annualised terms), while never noting the huge role that petrol prices played – you may recall world crude prices briefly going negative in a quarter when not much driving or flying was happening). The approach they take simply doesn’t engage with the practical and real challenges actual central bankers faced during that period (and thus one should be hesitant about their recommendation that “near-term inflation signals may be more robust than forecasts at the policy horizon – I’m no fan of medium-term forecasts, but the operative word there has to be “may”, in some circumstances.)
  • I agree with their broad approach to fiscal policy (consensus assignment remains appropriate and formal coordination is unlikely to be wise or called for) but am a bit hesitant about the suggestion that in some circumstances the Bank should build into its forecasts (or scenarios) its own view of what a government is likely to do. In terms of thinking about risks, there is probably some validity to the point, but I cannot see how it could be viable to include speculative numbers in published forecasts (it sets up potential for political fights in which the Bank is unncessarily caught in the middle).
  • Recommendation 11 proposes that “the Bank should allocate sufficient resources to support the effective functioning of the MPC, including policy, research and analysis to support diverse perspectives in policy deliberations”. There is no elaboration of this point in the body of the report (one of a couple of examples suggested the final process ended up rather rushed, another being around reviewing/altering the Remit), and I’m not fully sure what they have in mind. If, as I initially thought, they mean providing dedicated analytical resource to the external MPC members – as, for example, happens at the Bank of England – I strongly agree (otherwise the Governor has a stranglehold on what the Committee sees). But reading it again, it is possible they had something else in mind.
  • Recommendation 12 states “Sections 121 and 208 of the RBNZ Act create risks to monetary stability that should be reevaluated. The RBNZ Board should note have the authority to refuse to implement the MPC’s monetary policy.”. I want to devote some space to this because the Minister’s response to the report states explicitly that this “warrants further consideration and [the government] has commissioned further policy work from Treasury. Section 121 relates to powers of the Board, but actually (as the Report notes) section 208 relates to powers of the Minister, who can direct the Bank to “take all reasonable steps” to maintain a minimum level of capital specified by the Minister and have regard to the Minister’s expectations as to the Bank’s financial risk management. The report rather cavalierly suggests that “it is advisable to seek solutions that are implementable well before the Bank is required by unfortunate circumstances [emphasis added] to take on large financial risks to protect the New Zealand economy from from a deflationary shock”. This is melodramatic stuff, that not only does not engage with the likely actual effectiveness of either future LSAPs or big fx interventions, but more importantly does not engage with the guarantee powers the Minister of Finance already had under the Public Finance Act. To the Bank’s credit, it did not do the LSAP at its own risk (our risk imposed on us by them) but went and sought an indemnity from the Minister of Finance. It cannot be desirable that unelected officials, barely substantively accountable, can debauch the public finances without seeking the consent of the Minister of Finance. Extreme times call for political responsibility (including because, as demonstrated over 2020, with the best will in the world economists get thing badly wrong, and yet politicians are accountable). So I would urge The Treasury and whoever is Minister after the election not to be swayed by the these reviewers into re-establishing unlimited scope for the MPC to impose financial risks.

Overall, it is a fairly mixed bag of a report. If I scroll through the 12 formal recommendations I agree to a greater or lesser extent with most of them, although I think they probably tend to overstate what difference they might make in extreme unknown scenarios of the sort faced in 2020 and 2021. The recommendations are forward-looking, which is fine and has a place (including in the terms of reference they had to work to) but where the report is much weaker is on the backward-looking analysis and critical review. It gives passes to the MPC that aren’t really deserved and thus avoids some of the more difficult challenges of making sense of the period. It also tends, too much, to the purely technocratic – issues inside the Bank and the MPC – to the near-complete exclusion of the wider issues around legitimacy, accountability, and the confidence the public and markets might have in those who put their hands up to be entrusted with such huge delegated power.
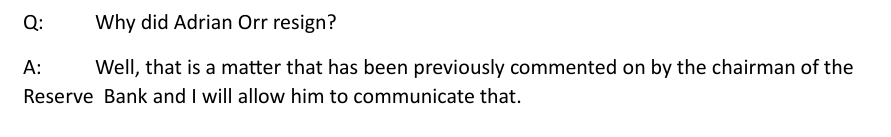
Outstanding questions

A couple of nights ago, shortly after the Minister and Treasury finally released the suite of texts between Willis and Rennie, ZB featured interviewer Heather du Plessis-Allan talking to Herald journalist Jenee Tibshraeny (who has been over the Orr/Quigley/Willis saga issue from day one). There wasn’t anything concrete that was new in the conversation but it was the ending that struck me.

Tibshraeny: In this instance I’m disappointed by the lot of them. I can’t even distinguish who is most culpable and feel like as a member of the public I’ve been misled and it is disappointing.

Du Plessis-Allan: It just looks like a giant cover-up doesn’t it?

Neither of them seem like zealots, let alone anti-government zealots with an agenda. So what a sad state of affairs we’ve come to in this country.

But the Minister has clearly found herself some supporters in The Post (their journalists have also been a bit sympathetic to Orr) with an article this morning where they claim – it must have been music to Willis’s ear – that “overall, Willis appears to have helped rather than hindered the fuller facts going on record while not at any point seeming to defend the Reserve Bank’s own miscommunications”. Which would be an extraordinary claim anyway, but it was belied by the fact that a few paragraphs earlier they had reminded readers that on 5 March, after the deeply problematic Quigley press conference, Willis told The Post journalists that she was satisfied with the explanation Quigley had given for the Governor’s departure. And, of course, none of the explanations given that day (and there were several, mostly designed to have us accept something like “inflation is in the target range, time to do something different, nothing to see here”) were at all convincing, and the Minister – who had urged Quigley to do the press conference – knew that the public had been actively misled then. And if perhaps she coulddn’t predict quite how badly Quigley was going to do when she got him to go out there, there is no sign – not the slightest – that she either expected or wanted him to tell the truth. And, of course, over the subsequent months she did occasionally wring her hands in public, regretting eventually that the Bank wasn’t being a bit more open. But…..she is the Minister of Finance, with knowledge and leverage, not “helpless mother from Karori” putting her thoughts in Letters to the Editor of The Post. She could have acted, she chose not to do so, and if it hadn’t been for the Ombudsman we might still have been dealing with official denial and avoidance, enabled by her. That she enabled the obstruction and coverup for months is nicely captured in this exchange with Heather du Plessis-Allan just six weeks or so ago.

Of course as I noted last Friday there are still material unanswered questions about how the choices – big picture and detailed – of communication of the Governor’s departure (and supportive messaging etc) came together. Statements of that sort don’t emerge in half an hour, and there were material choices to be made. It is hard to believe that no one in the Minister’s office had any involvement, or that they and the Minister were not actively thinking through the issues and risks and options pretty much from the time the Minister got that text from Rennie on the evening of 27 Feb suggesting things would now come to a head fairly quickly. I’ve lodged one more OIA on those matters this morning.

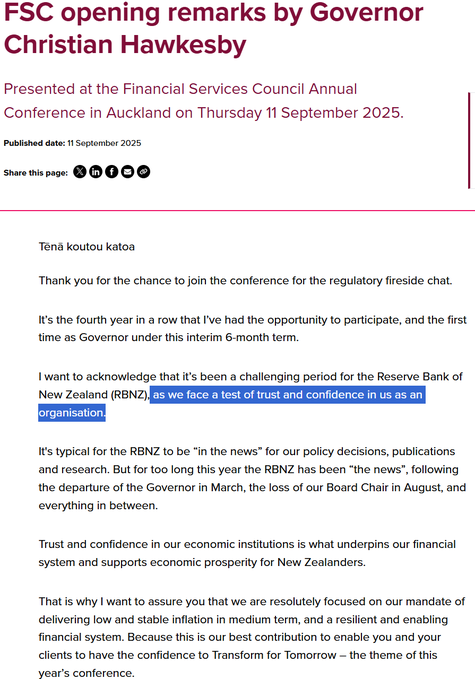
And then of course there is the Reserve Bank itself. The temporary Governor turned up yesterday to speak at the Financial Services Council and began this way

I suppose we should give him a little credit for even mentioning the “test of trust and confidence in us as an organisation”, except that….having giving it a passing mention he went on to talk about inflation.

There are still serious questions for all those involved at the top level of the Bank (temporary Governor, board members, key communications staff etc). Rather than write it all again here is a paragraph from last Friday

I’ve also lodged an OIA on those issues those issues this morning. But the wider questions for the Board become even more pointed now that we know they were so intent on getting Orr out that they were likely to recommend the Minister to dismiss him just a few days after their formal process had begun (predetermination and all that?). And yet they still apparently thought it just fine to deceive the public – approving Quigley’s actions presumably – and to go on doing so for months. People of integrity would resign at this point.

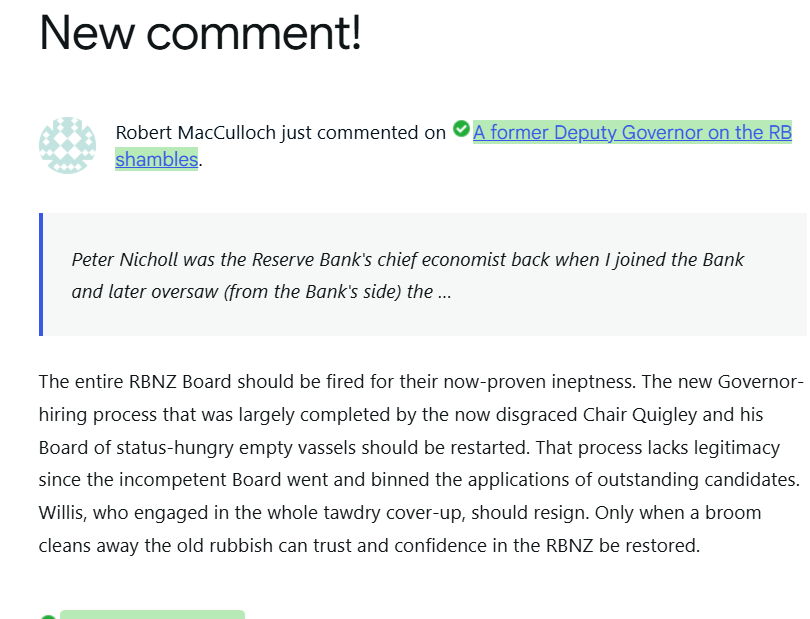
Late yesterday after my short post with former Deputy Governor Peter Nicholl’s article on the Reserve Bank shambles (and specifically the governance failures), Auckland university professor of economics Robert MacCulloch left this comment

Taking his point about the questionable legitimacy of the Quigley-led (and rest of Board) process for selecting a nominee, I’m not sure I’d go quite as far as he does. Time is moving on, and there is a pressing need to have permanent new management in place. On the other hand, quality really matters. So my stance is probably that the Minister (and the wider Cabinet) need to ask themselves very seriously whether any nominee they have settled on really reaches the standard needed now: a first rate independent highly credible person of gravitas, management capability, and some intellectual stature. If they have, well and good. If not, then there would be a case to reopen the process (preferably after sorting out the board members themselves). Rumour hath it (well, a journalist told me) that the nomination has already gone out to the other political parties for consultation. Here the role of Barbara Edmonds becomes really quite important. If she can really be persuaded that a nominee is not just “any warm body, because the job needs filling” but a serious credible and respected figure, then that could be quite persuasive (and recall that the legislative provision Labour introduced requiring consultation with other parties was presumably done in the spirit of the notion that a person appointed as Governor really should command at least grudging respect across the spectrum). But if Edmonds isn’t convinced – and the situation has deteriorated further in the last couple of weeks – she and her leader need to be willing to take Willis aside and say so.

And finally for now on this issue, this is the closing paragraph of a piece I wrote earlier this week on the whole grim saga.

And is that for a while. My wife are heading off on a month’s holiday tonight so it will be at least a month before there is anything more from me here. By then, one hopes, there might have been announcements of strong credible independent people to take up the two key roles, Governor and board chair (and, actually, a new MPC member too). Perhaps some new commitments to greater monetary policy transparency too, along the lines Kelly Eckhold at Westpac suggested last week. But we’ll see.

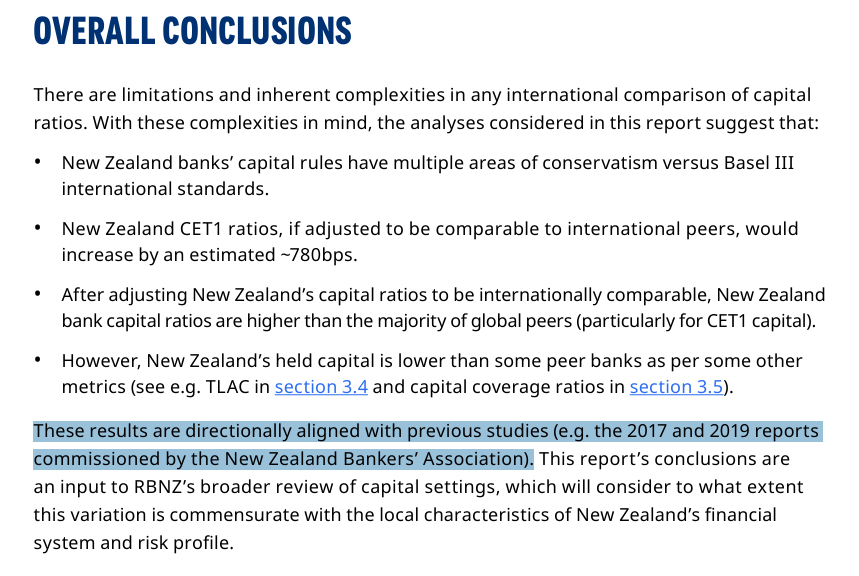
And that means that among the various other things I just never got to in recent weeks was making a submission and a substantive post on the Reserve Bank’s consultation on the capital requirements review that the Minister prompted them to initiate once Orr had gone. As it happens, I don’t have much problem with what they are proposing, and I really strongly welcome the fact that the interim guard (Hawkesby/Quigley) did go to the effort of commissioning a decent external consultant to review bank capital levels in New Zealand and those in a bunch of other somewhat comparable advanced economies (a measurement exercise rather than a policy one). Orr refused to commission anything of the sort when he was still unilaterally in charge in 2019. This was the conclusion of that new report.

My own issue with the entire framework – 2019 (eg here and here) and now – is that it is built on assumptions about the (GDP) cost of banking crises (themselves, the bits able to be ameliorated by capital buffers) that bare no relationship to reality in advanced economies, no matter many decades one looks back. The Bank now justifies sticking with this assumption – which is crucial to any serious cost-benefit analysis – on the grounds that it is “internationally conventional” in such work. No doubt “Internationally conventional” provides a safe harbour for bureaucrats, but it is no substitute for serious thought and critical review.

It is arguable that this unsafe assumption may not matter unduly at present, if market demands (shareholders, bondholders) mean that banks would choose to hold quite high capital ratios even if regulatory requirements were set lower. And of course – another thing not mentioned in the consultation – is that for our largest banks it would be APRA rules that would still be binding even if the Reserve Bank were to adopt an even less demanding model. But we really should be able to expect a higher standard of analysis – including such basics as the ability to distinguish the costs of misallocating credit and real investment in the preceding boom from those narrowly from actual bank failures or near-failures themselves – from our financial stability and bank regulatory agency.
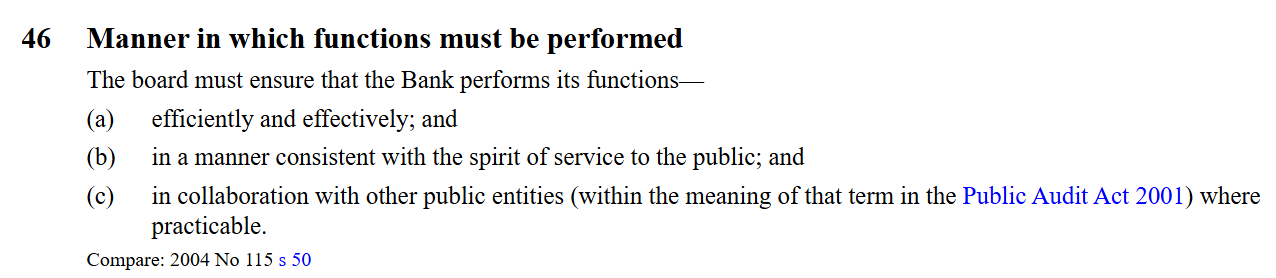
Tangled webs

Yes, Orr/Quigley/Willis again. For everyone’s sake now – well, perhaps except her own – one can only wish that the Minister of Finance would finally decide, more than six months on, to make a full and complete disclosure of what actually went on around the exit of Orr and the aftermath.

Instead, the snippet by painful snippet process continues. Since my post yesterday we’ve learned some more things:

First, questioned by Barbara Edmonds in the House yesterday, the Minister finally gave the gist of texts between her and Iain Rennie on 27 Feb re the commencement by the Bank’s Board of an “employment process”.   She and Treasury have withheld these texts for many months, long after she herself was the first to formally disclose (to FEC on 18 June) that there had indeed been an “employment process” prior to Orr’s departure.   That in turn lead her to realise – what she’d have known if only she were an assiduous reader of this blog! –  that in fact on 18 June she had also told FEC, three times with Rennie sitting next to her, that she’d first heard from him about the “employment process” on 24 February.   Last night just before the House rose she made a personal statement correcting this point.   No doubt it was an honest, if careless, mistake in June, although it doesn’t reflect very well that there was no earlier correction (when Rennie must have known, or suspected and should have quickly checked afterward, that his minister has mis-spoken).

Second, and much more importantly, just prior to 2 this afternoon Treasury finally released the set of texts in full. There are a couple about the funding agreement stance from 14 Feb, which are useful but don’t materially add to the information we already have (although do make clear that Rennie had only spoken to Quigley about the funding agreement bid on the morning of the special 14 Feb board meeting).  There is a mysterious one from Willis to Rennie on 17 Feb “Are you coming to the 230”, which has no obvious significance but Treasury must think it is somehow in scope.   And then there are the crucial 27 Feb texts.


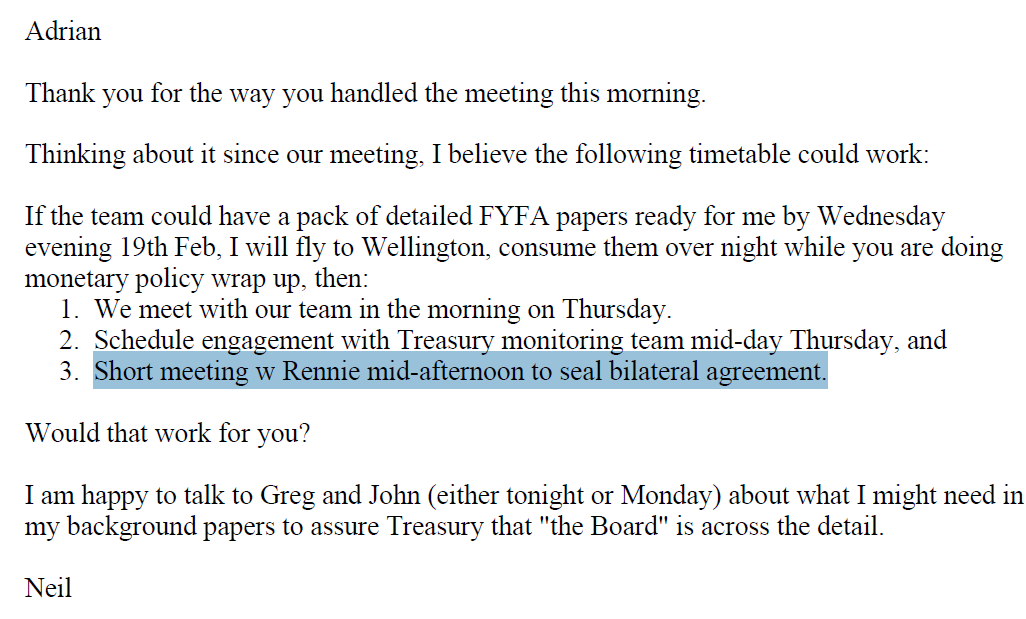
The first of those adds nothing new, but the second does (going beyond what Willis told the House yesterday).    Note that fourth sentence: “Neil’s current thinking is that you could receive recommendation later next week unless decision is taken to go down voluntary exit route”.   In context –  and given the range of the Minister’s power –  this could only be a possible recommendation to dismiss.    So not only did the Board envisage their process culminating in a dismissal recommendation (NB an interesting pre-judgement before hearing Orr’s response), but the Minister was fully informed of that (and actually tossed in the observation that the board would need good legal advice, apparently approving of the lawyer Rennie advised her the board was using.  (Incidentally, she would also have needed good legal advice had it come to a recommendation to dismiss, given that any decision could have been challenged in the courts).   This completely undercuts the line Willis herself has run for months about how it was all nothing to do with her because it was an “employment process” when, as I’ve stressed and the Board, she, and the Treasury clearly knew, she was the one with the (hiring and) firing powers, and only her.
Text messages between Nicola Willis and Iain Rennie Feb 2025 re Orr released by Tsy 10 Sept .

The third development was a question to Willis from Edmonds in the House this afternoon.   She asked whether the Minister considered that Quigley’s characterisation of the exit from 5 March (and beyond) as “a personal decision” was misleading.    The Minister said that she had relied on Quigley’s judgement that that was all that he could say.     Edmonds could have strengthened the question, because Quigley also said on the day that “the Governor had got inflation into the target range and felt it was time to go” and denied that there were any conduct, policy, or performance disputes at the heart of the exit.    The Minister is just making up stuff if she believes that any of those lines were really satisfactory, unless “satisfactory” involved keeping the substantive truth from the public.   We still do not know –  and MoF claims not to either –  what NDA provisions there actually were, and nor do we know why the Minister (operating in the public interest supposedly) did not insist on (a) finding out in advance, and b) tightly constraining them so that the public was not misled.

Edmonds moved on to ask why the Minister also didn’t correct the record on/after 11 June (the Bank’s deeply misleading selective release and statement, which tried actively to avoid suggesting there had been any employment issues –  even though it was implicit in the existence of an exit agreement).  The Minister responded that she had not been aware of the Board’s specific concerns, or of Orr’s responses, or of the terms of the exit, she did not want to expose taxpayers to legal risk, and (supposedly highmindedly) did not “want to politicise a sensitive employment process”).  None of this really stacks up.  As it is, on 18 June, at FEC (but barely if at all reported at the time –  I hadn’t noticed it) she noted, what Quigley had sought to obscure, that there had in fact been an “employment process”, and of all the answers she didn’t have she could –  and probably should –  have insisted on them.   She was aware the Board was driving the Governor out but had no idea what the concerns were?  Yeah right.   And, of course, decisions around funding, and decisions to fire the Governor were –  by Parliament’s design – ones made by politicians.   Willis concluded that she had relied on Quigley and he should have done better.  Well, of course, but he was her man, and she covered for his approach for months, deceiving the public in the process.
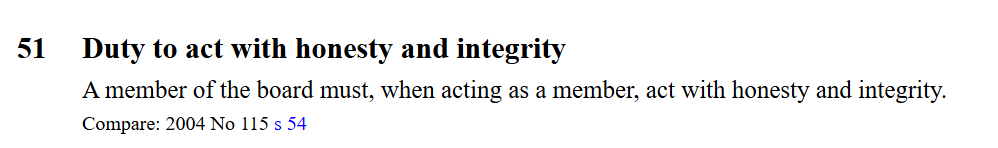
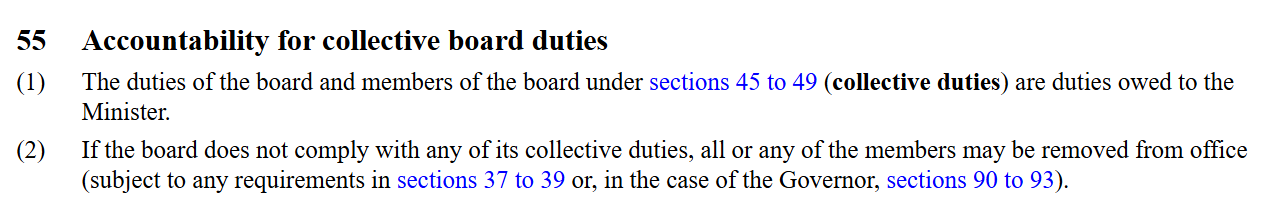
On the final question, Edmonds asked if (rhetorically no doubt) if Willis really believed New Zealanders could trust her when she had withheld information, had known she might receive a recommendation to dismiss etc and (with a final flourish) when it fact it was Willis who had driven Orr out.    Willis attempted (rather laughably) the high road, suggesting that Edmonds was free to be the great defender if Orr if she wished, but as for her (Willis) she wouldn’t deign to “politicise” Orr’s exit.

And those were the new developments.

But there are so many questions still outstanding.  For the Board, at what point did they engage external counsel to advise on a process that (it is finally clear) they envisaged leading to an unprecedented recommendation to dismiss the central bank Governor?  And was this prompted mainly by Orr’s behaviour at the 20th and 24th meetings or had it been brewing even before that?   Also for the Board, given that clear direction, how can any of them with any integrity remain in office having been collectively responsible for the 11 June release, which was now even more clearly deliberately deceptive (under a guise of pseudo-transparency).   

As for the Minister (and Treasury) it remains inconceivable that we have had the whole story.  You, as senior minister, don’t just get a text out of the blue suggesting the part-time (mostly Labour appointed) board might recommend firing the Governor without wanting to know more, unless of course you already knew more.  It is beyond belief that there were no discussions after Orr’s walkout from the 24 Feb meeting, and not very likely that –  given that Rennie was being used as the comms intermediary (why?) – that no one at Treasury was looking into legal processes, grounds etc.

And, of course, why did she take no steps to ensure that a reasonably honest (not necessarily full or complete) statement was given to New Zealanders on a) 5 March, b) 11 June or c) at any other time up to and including the Ombudsman determination a couple of weeks ago?  Whose interests was she serving then?  Was her stance more about distancing herself from a process than legitimate legal/privacy issues for Orr?

Someone who doesn’t follow these things much commented to me recently “how can anyone now trust anything the Reserve Bank says?”   A good question, but as information continues to seep out from Willis, much the same might, unfortunately, be asked about her.   I remain convinced the ousting Orr was well-warranted and welcome, to her credit given the opening Orr’s behaviour created.  But not the cover-up, the active misleading, and the obstruction.  Or the lack of full disclosure to this day.

Another snippet

It isn’t impossible that you, readers, are getting tired of the still-unfolding Orr/Quigley/Willis saga. You wouldn’t be alone in that. I have many more intrinsically interesting things to do (spent yesterday writing a review of new academic history of US banking supervision from 1798 to 1980, and am reading a history of little-known sovereign borrowing scandal from the early 19th century) but…..we are still short on answers and on accountability, notably from the Minister of Finance, who may have authorised but certainly enabled the systematic efforts led by Neil Quigley to mislead New Zealanders for months as to what went on. At any point, from and including 5 March (the day Orr’s resignation was announced) she could have a) insisted and b) personally ensured that the truth came out. She didn’t and still hasn’t given us a complete and straight story, or expressed any contrition for anything she was party to in the last six months. Deliberate efforts by, and enabled by, a senior minister to mislead New Zealanders would once, and once brought to light, have been treated as a very serious offence (but then, as I noted here repeatedly, MPs never seemed very bothered when Orr made a mockery of their place in the system and actively misled – or worse – them repeatedly). The rot runs quite deep.

Yesterday saw another OIA response from the Reserve Bank dribble in, and with it one more snippet of information. It exposed, once again, my tendency to look for the least-worst explanation, which has been quite unhelpful in making sense of the mess of recent months.

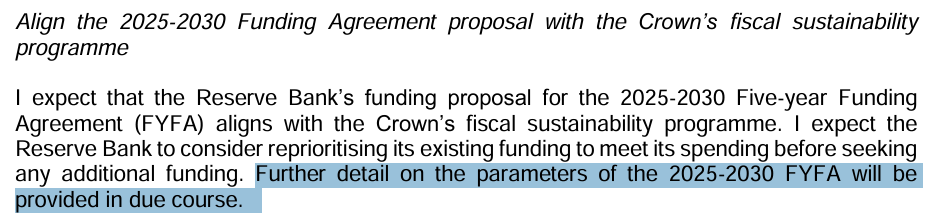
A couple of weeks ago, the Reserve Bank released to me a Letter of Expectations that the Minister of Finance had sent to the chair of the Bank’s board (Quigley) last year, outlining how the Minister expected that the Board would approach bidding for and negotiations on the next (2025-30) Funding Agreement. The Reserve Bank has a website page where it publishes ministerial letters of expectations. They simply never published this particular letter of expectation on that page, or on the website page gathering together material on the 2025-30 Funding Agreement. Par for the course you might reasonably think, given how obstructive and then slow and partial the Bank has been.

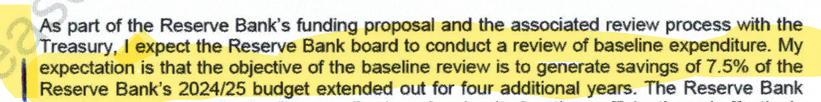
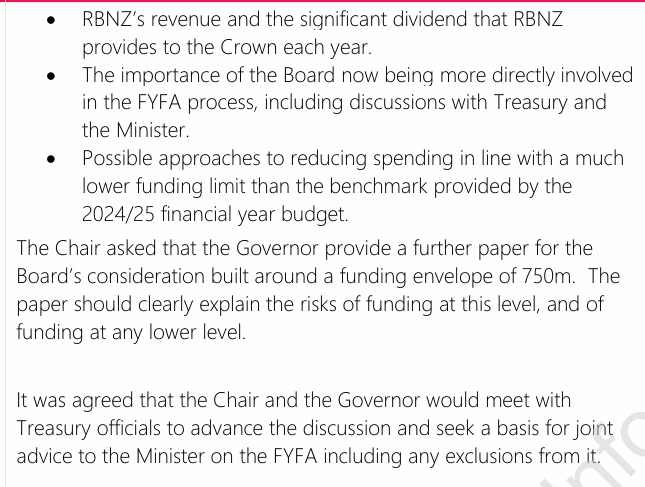
As I noted in that post a couple of weeks ago, the Funding Agreement letter of expectation had made it clear that the Minister was looking for cuts. This was the relevant snippet.

But the version of the letter the Bank was released was undated. The Bank had been quite open about the general 2024 Letter of Expectation, which was dated 3 April 2024. It was fine, but fairly general, noting that further detail relating to the next funding agreement would be coming “in due course”.

I guess I had in mind that perhaps that letter hadn’t been written until much later. After all, the existing Funding Agreement didn’t expire until 30 June 2025 (and when Treasury actually got the Bank’s bid in September 2024, the papers suggest they did nothing with it for months anyway, considering it mainly in the context of this year’s wider government budget)

But what the Bank disclosed to me yesterday was that the funding agreement letter of expectation had also been received by the board chair on 3 April 2024.

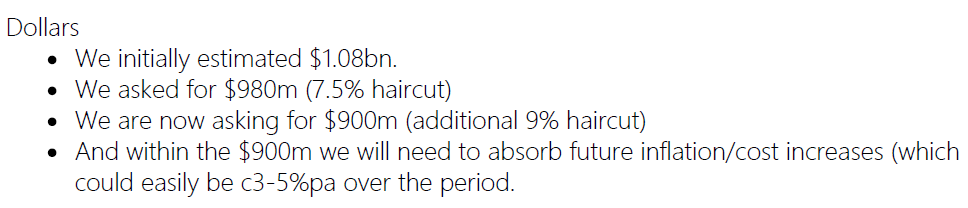
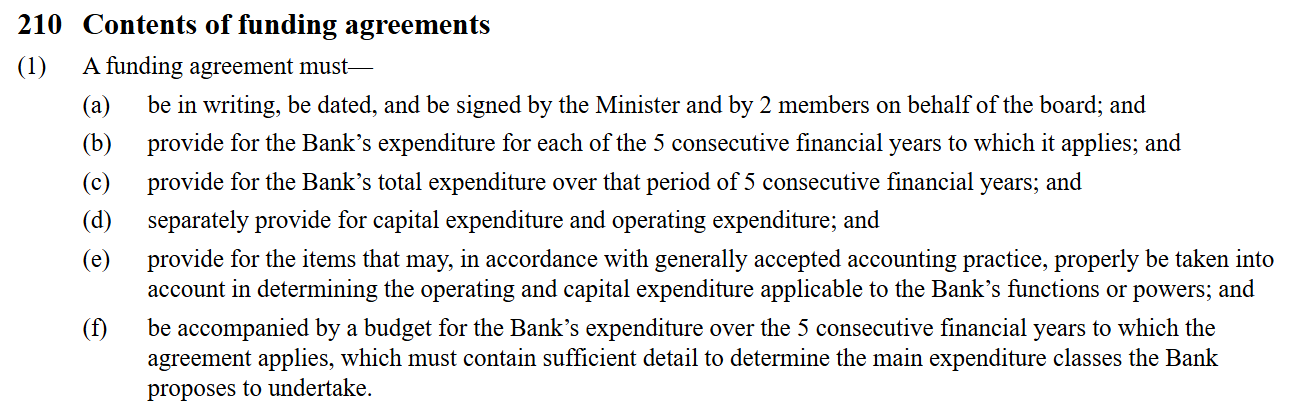
And that matters because it was well before the Reserve Bank board made final decisions about the Bank’s 2024/25 budget. Quite possibly, the Governor was already encouraging the Board to agree to a grand spend-up in 2024/25 anyway – on the dubiously legal, but morally outrageous, basis that their total spending over the five years of the 2020-25 Funding Agreement would still be under the total allowed spending in that term (even though a) the agreement and Act specifically referred to individual year limits, b) the limits for each of the last two years had been reset by Grant Robertson just before the 2023 election, and c) there was a wider climate of spending restraint being driven by the Minister of Finance). Perhaps he already planned that such a spend-up would lock in a level of spending/staffing that might make it hard for the Minister to cut much when the new Funding Agreement was finally determined.

But, on 3 April 2024, he had the Minister’s own words for an interpretation that a Funding Agreement bid would be okay if it involved a 7.5 per cent cut relative to the Bank’s budget for 24/25. Wherever that budget happened to be set, apparently. Talk about dangerous incentives….in a system where the Bank sets its own budget, not directly constrained by (eg) parliamentary appropriations…..and the board signed up to this and went along, setting a budget for 24/25 about 23 per cent above what the Robertson Funding Agreement variation had allowed for that year, and then pitching a new Funding Agreement bid just 7.5 per cent below that level (and far above what even Grant Robertson had approved for 24/25). It was a try-on that really amounted to spitting in the face of the Minister, operating in total disregard to the times (let alone to the wellbeing of the staff, if the double or quits gamble went wrong, as eventually it did).

It is breathtaking all round. The Governor and Board attempted to drive a cart and horses through dangerously loose wording. Neither the Treasury nor the Minister of Finance seem to have had the measure of the people they were dealing with, and both were so asleep at the wheel that (a) when the Bank came back with a draft Statement of Performance Expectations in late April 2024 that deliberately left the budget numbers blank, neither followed this up and insisted on straight answers, and b) when the inflated Funding Agreement bid came in a few months later they sat on it for months and did nothing. No one was dismissed, no one was even severely wrapped over the knuckles. A senior political journalist told me last week that in an interview on 30 October the Minister had, unprompted, indicated that she was going to cut Reserve Bank spending……but she’d done absolutely nothing as the board had run rampant for months, including staff numbers still growing markedly. It wouldn’t be until mid-February that things would finally come to a head. As any parent knows the time to deal with bad behaviour is firmly and early, not leaving the offender with the implicit message that Mum and Dad don’t care too much, only to make a fuss belatedly.

Realising that this Funding Agreement letter of expectation had been received as early as 3 April prompted me to dig out the published minutes of Board meetings from the March and June quarter of last year (from which we are told nothing has been withheld) and the Board chair’s response to the (general) 2024 Letter of Expectations (for some mysterious reason known as the Strategic Issues Letter).

Rereading those documents in the light of what we now know, it is interesting how early both the Bank and Treasury had started work on the next Funding Agreement issues (the February 2024 minutes record that a very senior Treasury official – deputy secretary Leilani Frew, now departed – had been named as relationship manager for the funding agrement process, and the board had approved a memo to Treasury “to establish and agree foundational interpretations relating to the funding agreement and the principles underlying our approach to setting our baseline expenditure forecast”). The May Board minutes record Frew and the macro deputy secretary visiting the board and noted that ‘the work towards the next funding agreement, noting that there has been constructive engagement between RBNZ and Treasury an that baseline savings are in the process of being identified” (but presumably neither Frew nor Board, nor their staff, asked the questions that would have revealed the spending spree the Bank was just about to go on with the draft 24/25 budget – the immediately previous item on the Board’s agenda).

You might have supposed that having (a) had two letters of expectation from the (new) Minister of Finance on 3 April, and b) having a deadline to submit to the (new) Minister of Finance, just about to bring down her first government budget in straitened fiscal times, for consultation/comment a draft Statement of Performance Expectations (including budget numbers) by the end of April, that these sets of documents would be the subject of serious discussion by the Board at its April meeting.

But the Board didn’t meet in April 2024 at all. Now, the March minutes record that there was an (unminuted) “workshop” on 23 April “to discuss the next iteration” of the Statement of Performance Expectations and Statement of Intent Refresh, but those minutes also just delegated to the Governor and chair the authority to sign out to MoF for consultation the draft SPE at the end of April. As it happens, the document was signed out by neither, but by one of Orr’s many deputies. Was the Board aware they weren’t planning to tell the Minister about the planned size of the 24/25 Budget? We don’t know, and the (published records) conveniently don’t show. Did they engage with the two letters of expectation then? We don’t know.

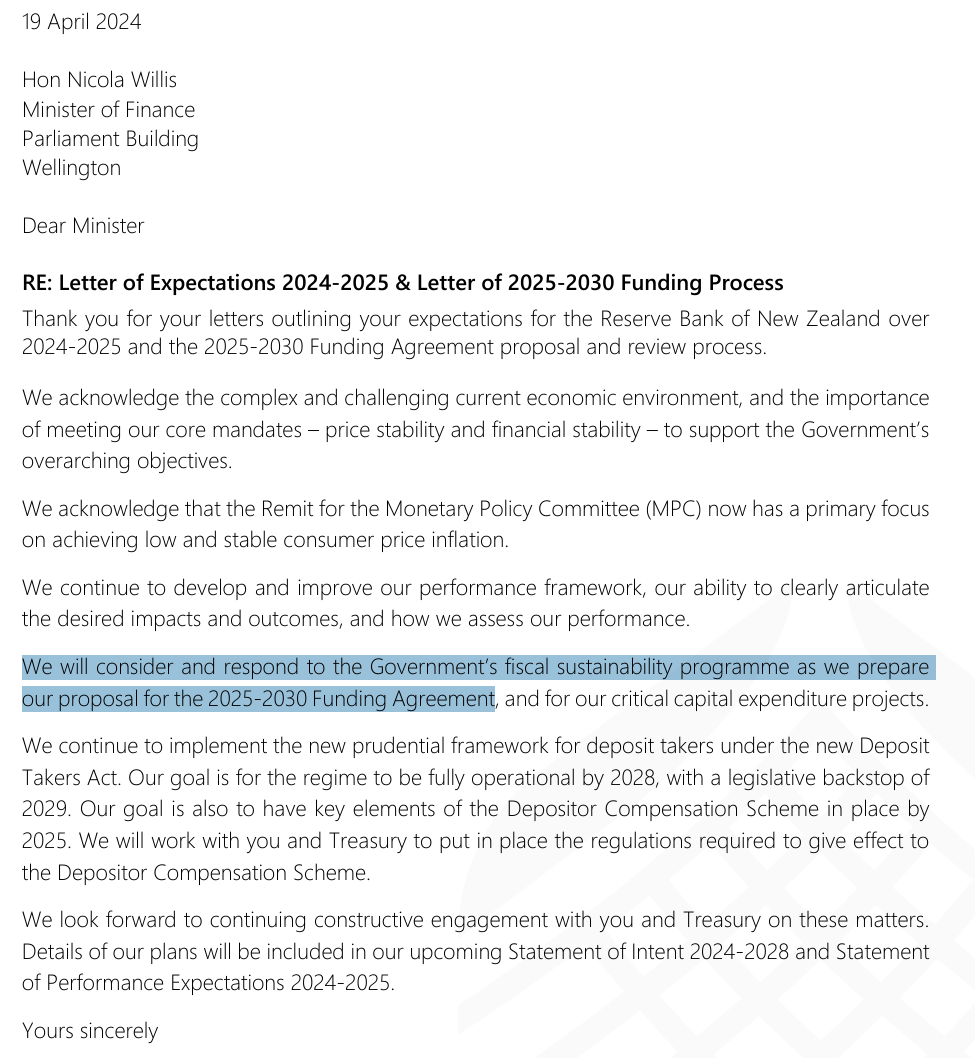
But it seems unlikely, because even if it came up at the 23 April workshop, Quigley had already sent his Strategic Issues Letter back to the Minister on 19 April, purporting to respond to both letters.

Note that he avoided the specifics from the Minister’s letter on the next Funding Agreement and gave only the vaguest indication of a more general approach (“we will consider and respond to”). Surely Treasury (Frew) and the Minister and her advisers should have been put on notice when they got such a vague response? But apparently not, given that they raised no questions/concerns when the budget numbers weren’t included when the draft Statement of Performance Expectations was sent in 10 days later?

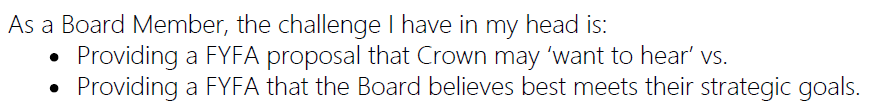
There is no suggestion in any of the June quarter minutes from 2024 that the Board ever discussed the Letters of Expectations or thought hard about the implications, or the environment against which they were written. The May minutes do mention the Strategic Issues Letter but only “The Board noted the Strategic Issues Letter”. They seem to have been out on another planet, perhaps led by the nose by Orr, but with no one – Board, Treasury, Minister – providing the sustained vigilance (protecting the public interest and public purse) that was needed. The only Board questions noted in the minutes were looking for assurance that the 24/25 budget was going to be legal – and perhaps Orr’s tame in-house provided some such dubious assurance, as lawyers (in-house and external) are so ready to do for clients – but with not even a hint of a question as to whether such a Funding Agreement blowing budget was right or responsible or was likely to prove sustainable, no stress testing (for example) of what the implications (for people and for the organisation) might be if they did later hit a wall.

It really astonishing (or perhaps not; this is modern NZ) how little serious accountability there is in New Zealand public life. Of course, Orr has gone, but not because of anything he was doing mid-late last year, and Quigley eventually went too – again not because of what he led and did last year but because eventually the post-Orr coverup got a bit embarrassing. I guess too that the relevant Treasury Deputy Secretary has moved on, although there is no hint of that having anything to with being asleep at the (leadership) wheel when the egregious foundations were being laid for the Feb/Mar blowup this year. No board member has been dismissed, or as we understand it even reprimanded, and one was even reappointed this year. The board deputy chair – fully party to last year’s decisions – is holding the fort post-Quigley.

And then there is the Minister of Finance. By far her worst offence was enabling the deliberate deception of New Zealanders for months, when she could have cleared things up at any time she choice (Quigley may have become a nuisance to her, but he was her man, she empowered and enabled him). She still hasn’t been fully straight with New Zealanders. But her role last year – both directly, and in insisting on a more active engaged performance from Treasury – looks pretty culpable. Perhaps if she’d taken a stronger stance from when she first took office, Orr and Quigley would have been reined in much earlier, and the chaos and dishonesty of this year – and damage to her own standing (and the disruption of staff lives) – might have been avoided (many of us were probably glad to see Orr gone in the abstract, but…..no one wanted this).

Remarkably, one other snippet in the May 2024 board minutes is a brief note “the Board discussed the chair’s first meeting with the Minister of Finance”. The government had been sworn in on 27 November 2023, the Minister had been on record with her concerns about Orr personally, and Bank bloat, she’d even promised an independent review of monetary policy. She knew the Funding Agreement had a year to run, but was insisting on immediate cuts elsewhere. It was hardly a quiet and easy corner of her domains and yet she seems not to have bothered meeting with the board chair – her agent, and board wielded the power on prudential policy, where she also had concerns – for months after taking office. You can only shake your head and wonder what she was thinking, and why she made so little effort for so long to use the tools – formal and informal – at her disposal.

Six months today

It was six months ago this afternoon that the resignation of the Governor of the Reserve Bank was announced, and with it the tangled and ongoing web of deception and obstruction.

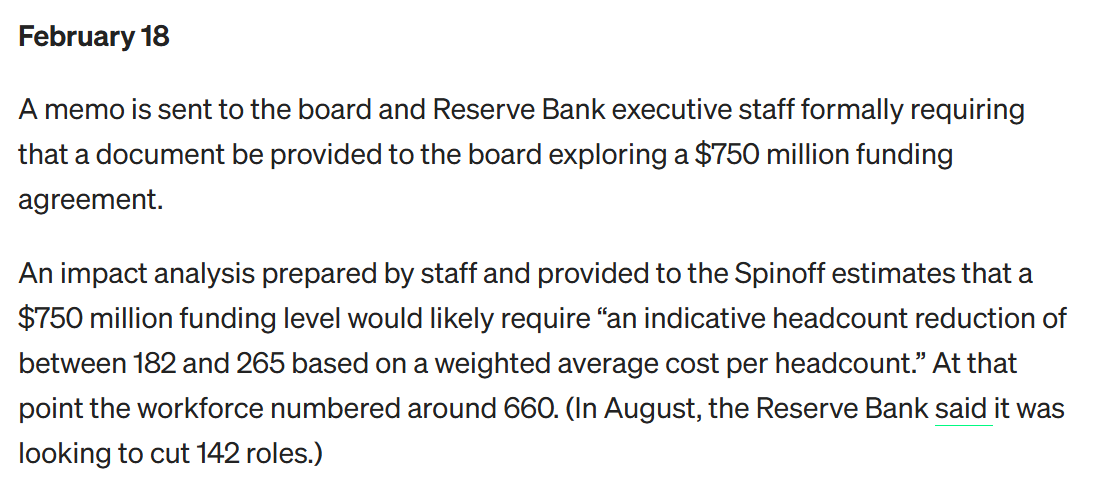
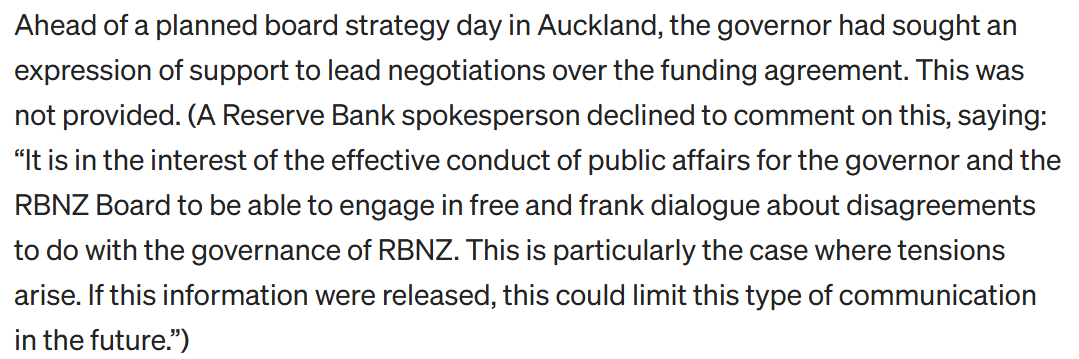
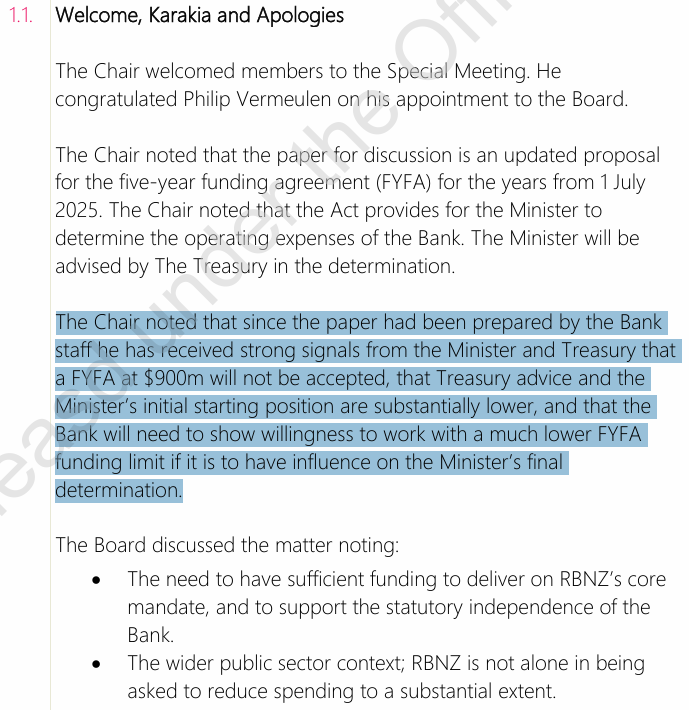
I wasn’t planning to write anything today, but information continues to seep out – occasionally proactively, sometimes involuntarily, and sometimes (apparently) through journalists’ sources. In just the last day or two, we’ve learned a whole lot more about the largely unknown – eg the Minister of Finance says she wasn’t aware of it at all – special Board-members-only Reserve Bank Board meeting on 14 Feb, when the Board finally has to stare in the face the reality that their fanciful bid for resources for the next five years was utterly unacceptable to Treasury and the Minister. It also turns out that Treasury’s first advice on the bid that had been lodged back in September, and which is still described as only a “preliminary assessment”, had only gone to the Minister the previous day (that paper was finally released by the Minister yesterday afternoon, Treasury having previously withheld it). None of this had made any of the Reserve Bank’s previous statements (11 June or 29 August).

This morning The Spinoff has a piece with material new details, apparently from an inside source. They don’t change the overall characterisation of the story but they flesh out the picture a bit more. The new snippets I spotted included

Days after that crucial special board meeting (I’ve now requested both papers from the RB)

and on 26 Feb (and note that ongoing obstructiveness, about events that are now months old and will hopefully never recur)

Quigley may have gone but the obstructive approach from Hawkesby and the remainder of the board seems to continue.

I have updated my own more detailed timeline to take account of Spinoff’s information. As and when anything more emerges I will attempt to update it but there is a standing link here.

It is worth being reminded of others things the Bank still refuses absolutely to disclose. I had a request in a couple of months ago for just the elements of the exit agreement governing a) the process for agreeing a statement [ie for the 5 March announcement] and b) the non-disclosure terms. The Bank has refused to release that information – so the public has no idea what secrecy they committed themselves (or Orr) to, as regards the departure of one of the most powerful and controversial officials in New Zealand. The Ombudsman lived down to form and confirmed to me yesterday that their office is backing the Reserve Bank on this one, despite what would seem to be a clear public interest now (and long since) in transparency (whether through release of specific documents or summaries of them – the latter done in last week’s partial timeline).

There are two other things where nothing material has been revealed yet. The first relates to the 5 March announcement itself, and the second to the subsequent RB obstructionism.

Nothing in the selective pack of documents released on 11 June, or in any OIAs since, has revealed anything about the bringing together of the Reserve Bank statement announcing the resignation on 5 March. The Bank seems to have known for several days, probably since the previous Friday (28th) that Orr was likely to be going, and agreement on exit agreement terms appears to have been reached by Monday 3 March (although not signed until 5 March). You don’t bring together a document like that press release on such a sensitive issue in half an hour, or without multiple drafts or sets of edits. There must have been discussions about the approach that should be taken – “just how untruthful and misleading can and should we really be?” sort of thing. We know from disclosed documents that Orr and his lawyers had to clear out and they presumably had both wording requests, objections to other proposed phrasings, and probably received pushback on their own proposed lines. There is also nothing about how Quigley’s mid-afternoon two sentence addition statement (which explicitly introduced the “personal decision” bait, reinforcing the line that it was about “inflation job done, time to go, nothing to see here”) came about. Did anyone – other board members, acting Governor, senior comms managers, legal staff – raise any objections? Did they even see what Quigley was planning to say before it went out? Was there any prepping of the board chair for his press conference that afternoon? (it would seem inconceivable in general not to have – someone inexperienced in a press conference on a highly sensitive issue – but after six months of this few things would surprise any longer). Oh, and of course, what input – or visibility – did the Minister or her office have as the comms strategy and press release were formulated (loss of a major economic official etc)?

And, of course, we know nothing about how the Bank has prepared for, deliberated on, debated etc the handling of the numerous OIA requests (other than the generic “not well”). If you go back to the 11 June pack of documents, they actually seemed to start off okay, with the ad hoc committee recognising that there would be OIAs and they needed to make sure that records were properly kept etc. But it must have been downhill from there, with a mix of carelessness, obstruction, the Quigley attitude that the public had no real right to know, and of – at taxpayers’ expense – the hiring of a KC to buttress their determination to try to keep the public and taxpayers in the dark. How involved was the board as a whole in this strategy? If they were, it reinforces why they should go. If they weren’t, they were next to useless and should also go. And what of the acting Governor? Did he just go along, concerned to keep his job application alive, did he wholeheartedly endorse the Quigley strategy, or did he in fact dissent – and yet, in a strong position (they couldn’t afford to lose two Governors), do nothing? And what about the Communications Manager and senior comms staff? Perhaps they were more focused on keeping their own jobs. Precisely whose interests did the board consider was being served by their obstruction, especially once the Minister – to whom they are accountable – became belatedly aware that the misleading and the coverup was not tenable?

Questions – more questions – and perhaps the basis for further OIAs if anyone chooses to ask.

Meanwhile, six months on we still don’t have a permanent Governor. Reports suggest the process is fairly far advanced, but how much confidence can we have in someone this board – chaired by Quigley until Friday afternoon – will have come up with. There is a crying need for a first rate candidate, and not one tarred by the Orr years or the months of obstruction. We must hope the government insists on one, but given the Willis/Luxon record to date – slow and weak in dealing with RB matters, not showing that much sign of caring much – it is difficult to be optimistic. And if the government goes along with a mediocre nominee, we must hope the Opposition parties insist on excellence, and don’t just nod through someone on “any warm body” grounds. A first-rate board chair also seems vital – including to both support, counsel, and challenge the new Governor – and it seems unlikely that that person can be found among the compromised existing board.

Willis and the Reserve Bank Board and Governor

I think my post yesterday made a pretty conclusive case that the Minister of Finance had been fully part of the choice to deliberately mislead New Zealanders about what went on with the resignation of Adrian Orr. It might, initially, have been a fairly passive involvement re the proposed comms lines – when she, as responsible minister, should have been taking the lead in the run-up to 5 March, not leaving things to Quigley and the post-Orr Bank management (who, to put it mildly, do not have a strong track record on openness and accountability, or much sense of the likely public and political interest and risks). But she and her office quickly became fully part of it – prevailing on Quigley to do a press conference, knowing that it was exceptionally unlikely he was going to tell the truth, never challenging his statements before they went out, and signalling to the media afterwards that she was comfortable that a sufficient explanation had been offered. And then for months, even as it appears she gradually realised the coverup wasn’t going to prove tenable and offered occasional rebukes of Quigley, she continued to defer to the Bank/Quigley and used none of the knowledge or leverage that she had to force a more truthful set of disclosures. When finally Quigley was tossed overboard on Friday, it was only in the wake of fresh public furore about stuff she’d known of all along, and even then her press release just (so she says) recycled Quigley’s excuses for going – “the good job, well done, time to move on” stuff, Quigley had for a long time tried to deceive us with about Orr. Yes, she got more honest in her radio interview shortly after, which was better than nothing but not a great deal.

All in all, it should be quite unacceptable behaviour from a very senior minister. And even at this late stage there is no contrition, no sense that she might ever have done anything better or different. In face of the pretty clear set of facts it is both unconvincing, and leaves her looking weak (prisoner of Quigley gone rogue, sort of thing).

When I wrote that post yesterday I hadn’t heard the interview/exchange on Radio New Zealand earlier that morning (audio here, article here). Willis was no more convincing than in any of her other defences (eg as reported by the Herald, in an article linked to in yesterday’s post). She knew, she actively deferred to the Board chair for months, and at any time she could have insisted on more truthful explanations (even if the RB persisted in its own obstructive OIA responses). But I wanted to touch just briefly on a line she used in that interview yesterday, where she claimed that the independence of the central bank needed to be respected, and it would have been quite inappropriate for her to be involved in anything around Orr’s exit.

The Minister knows very well that the Reserve Bank legislation is carefully designed to distinguish matters over which the Bank has policy-setting responsibilities (eg many areas of prudential policy, such as bank capital requirements), where the Minister sets the goal but the Bank has operational autonomy (around monetary policy: the Minister sets the inflation target, the MPC adjusts the OCR to (aim to) deliver inflation near target), and where the Minister has primary responsibility. The old mantra was that Act was designed to balance operational autonomy with accountability, and to delineate carefully where it was that ministerial powers and responsibilities should be, and needed to be, exercised. One can debate the structure of the Act – I do, in a number of respects – but it is the law, and the Minister voted for the current legislation when it went through the House in 2021.

No one, but no one, seriously suggests that the issues that prompted Orr’s departure (announced on 5 March) had anything at all to do with the conduct of monetary policy (where it is important for the Minister and Prime Minister to keep their distance, not offering OCR advice in private meetings). As far as we know – and the Minister says she hasn’t seen the letter of complaint – the issues the Board sought responses on related to Orr’s personal conduct, and issues around trust in the context of a breakdown over Funding Agreement negotiations. There has never been a hint that monetary policy decisions were in the mix.

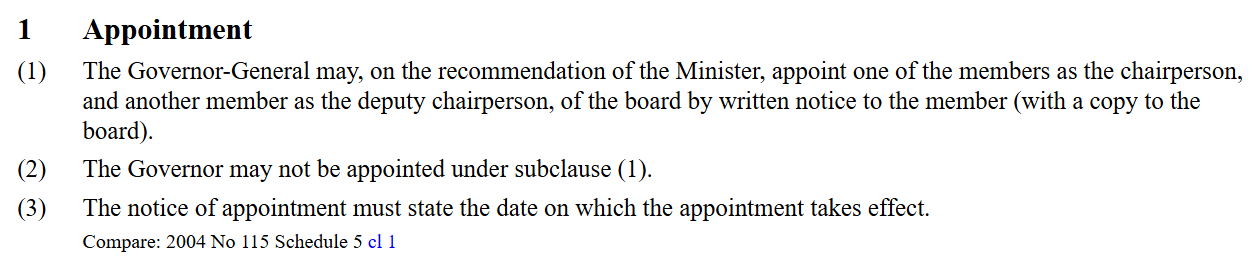
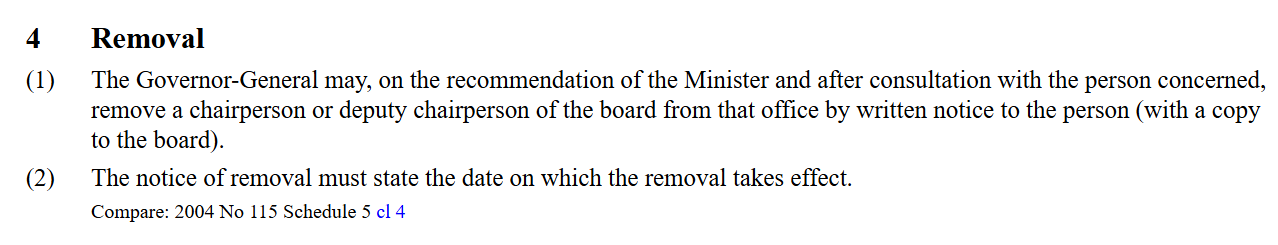
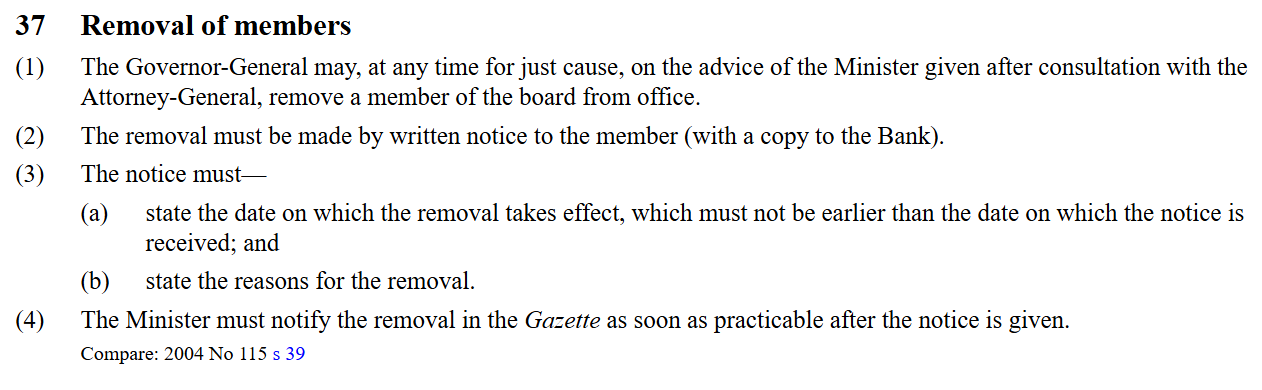
And the Act is quite clear that hiring and firing a Governor is finally a matter for the Minister (and Cabinet). The Board has roles in some of that – the Minister can only appoint as Governor a person the Board nominates (she is not bound though to accept any specific nominee), and the board can offer thoughts on whether the Governor’s performance or conduct rises to dismissal level, but even there the Minister (and only the Minister) can act to remove the Governor without a recommendation from the Board. Orr’s resignation was, as the law requires, submitted to the Minister, just cc’ed to the Board. So the repeated claim from the Minister that it was really important that she had nothing to do with any of it (was just a passive bystander, updated only when necessary) does not stand a moment’s scrutiny. Not only did the law give her a perfectly valid role, but so – frankly – did commonsense. In Opposition she’d objected to some of board appointees Robertson had made, who were mostly still there in February 2025. She knew that Quigley’s public handling of some past Bank issues had been questionable (to put it charitably). Wouldn’t any sensible senior minister, informed (say) on Friday 28 February that it was now all but certain that the Governor was going, after “employment discussions” initiated by the Board, have been all over the proposed communications lines? She might not have wanted her hands, or those of her office, to be too visible, but to sit idly by while the Bank (and Orr) dreamed up comms line – which would inevitably face robust external scrutiny – was to (voluntarily) make herself a hostage to fortune. That would be both risky and inept.

But the real point of this post wasn’t to repeat ground from yesterday. Instead, I want to put the Minister’s highly questionable part in the events of the last few months in the context of her overall handling of Reserve Bank issues since her days in Opposition.

Anyone who watched FEC hearings prior to the election could detect the frosty (at best) relationship between Orr and Willis. At times she did ask searching questions, and Orr did not like that, and tended to treat her – as so many of those who challenged or criticised him – dismissively. But there was never much follow through from Willis.

National opposed Orr’s reappointment, when (as the new law required) the other parties in Parliament were consulted. It was good that she did, but her central argument was half-baked (at best) and thus undercut the thrust of what could have made it hard for Robertson to proceed.

The point in the first sentence of that clip from her letter was quite right – and one hopes she bears that approach in mind with the appointment to be made shortly – but she’d already undercut the case with the half-baked “it’s election year argument”. People like me, who agreed with the bottom line (it really was dreadful that Orr was reappointing, leading us to this year’s mess), had to distance themselves from such an ineptly made case.

In Opposition she made much of the need for a strong independent inquiry into monetary policy during the Covid period (pushing back against the adequacy of the Bank’s own rather self-congratulatory and premature review of the MPC). One could debate how useful it might be, but it was a strong commitment, but nothing happened. (Curiously, in the March 2025 Board minutes there is this

and yet still nothing has been seen or heard.)

They made quite a bit about the staff bloat and loss of focus in Opposition, but then what?

Even in Opposition, there was no follow-up when Quigley was caught out actively misleading the Treasury, which in turn prompted them and Robertson to mislead the public in (about the infamous ban on experts serving on the first MPC).

It was pretty clear when National was in Opposition that they’d have preferred to be rid of Orr if they could. I pointed out back then (in a post prompted by a conversation with an interested party) that he couldn’t just be removed, but that there were quite a few things that could be done to put pressure on, to encourage early change, to improve how the MPC worked, and perhaps even to prompt Orr to think it really wasn’t an environment he wanted to stay on in). Almost none of it was done.

Quigley’s term as chair expired on 30 June last year. He’d covered for Orr for years, he’d led the board that recommended the reappointment, he’d been responsible for the blackball (and the lies), and he’d been chair since 2016. It was no-brainer to replace him, and would have been entirely uncontroversial, but she didn’t. She didn’t even keep the board fully manned (she was stuck with the Labour appointees until their terms ended, but you have to use the leverage and opportunities you have).

She did nothing to overhaul the charter for the Monetary Policy Committee, to encourage greater openness and accountability, or an expectation that members would be available for speeches/interviews. She seems to have done nothing more generally to encourage scrutiny and openness – it is now almost 11 months since the Governor or any second tier Bank person gave an on-the-record speech (extraordinary by modern central banking standards).

And if she did appoint two new MPC external members when the terms of the two 2019 originals finally ended, and the new ones appear to have been an improvement…..but we can’t really tell because we hear nothing of or from them. And then, again for reasons that escape understanding, she extended for one last six month period the last and elderly external MPC member from 2019 who’d been there through all the policy mistakes and communications lurches of recent years (that position now needs to be filled in the next few weeks).

We might also give her some credit for this year appointing a bit more economic expertise to the Board, although both appointees seem stronger on macroeconomics, which the Board isn’t directly responsible for, than on the regulatory side of things which the Board has direct responsibility for.

And what about the organisational/management side of things? Given the Minister’s evident unease about Orr, and her (quite appropriate) Opposition concerns about use of resources, you’d have thought that on coming into office she’d all over this (herself, and on her behalf her office and The Treasury) making life much less comfortable for the Bank from day one, even if (as was the case) they had a generous Funding Agreement running through to 30 June 2025.

Instead what we got was little and feeble for far too long.

Take last year’s Letter of Expectation to the Board (dated 3 April) These documents can’t compel agencies to do anything in particular, but wise boards are sensitive to the emerging expectations and priorities of ministers. There is six pages of the letter but nowhere does the Minister hone in on the very rapid increase in spending and staff numbers and signal a need for cutbacks. There is just woolly generic stuff

This was written in the run-up to last year’s government budget. Most departments were facing cuts immediately, and one other independent agency – ACC – while not directly controlled by ministers decided that, reading the times, they’d make savings anyway. It wasn’t even suggested to the Bank. And although there was a reference to the future

which should have been enough for a Board attuned to the times, it was pretty thin gruel and there is no sign the Minister ever sought to use the moral authority of her office, her bully pulpit.

The Bank doesn’t include the specific Letter of Expectation they got a bit later on the next Funding Agreement with the other documents on that deal, but it is here. I pointed out last week that, reasonable as it seemed, it contained a rookie error

talking in terms of savings relative to the Bank’s 24/25 budget, rather than savings relative to the Funding Agreement limits for 24/25. And even then, you might have hoped that in an agreement reached only every five years, in an institution that the Minister knew had lost focus and discipline, you might want a zero-based case for spending rather than just trimming the last level your predecessor happened to approve.

But, of course, it was all worse than that. The Bank actually set a budget that was about 23 per cent in excess of the Funding Agreement limits for 24/25 – fully and unanimously endorsed by the board – and when they had to consult the Minister on the Statement of Performance Expectations for 24/25 they simply left out the numbers. They didn’t tell the Minister what they were planning to spend. And neither she nor Treasury insisted on finding out. It isn’t clear when they finally realised, but it looks like not until very late last year at the earliest. And even when they did there is no sign of any consequences for anyone. There is no robust letter from the Minister rebuking the Bank for such egregious excess (and even if the Bank has a KC who claims – as lawyers do for their clients – that it wasn’t strictly illegal, it was entirely out of step with the thrust of government policy, and the times), the board chair wasn’t sacked, and no board members were removed (another of them was actually reappointed this year).

And then of course there was the egregious Funding Agreement bid approved by the board (unanimously) in late August and lodged with Treasury in September 2024. In a sane and serious world, Treasury would have opened the document, realised the gamesmanship that was afoot (at taxpayers’ expense) – this was trying to set a base for the next five years using the bloated 24/25 budget as base, not the previous Funding Agreement limits – and a) sent it back immediately, with clear expectations of something much lower, and b) immediately informed the Minister of what was going on, and advised her to call in, or write to (or both), the chair and the Governor to make clear that not only was the budget itself a fundamental breach of trust, but that the new bid was egregious and utterly unacceptable.

[UPDATE: This afternoon (4/9) MOF proactively released various documents relating to the Funding Agreement. Among them is Treasury’s preliminary assessment to the Minister of the Bank’s Funding Agreement bid, which is dated as late as 13 February.]

But there is no sign that the Minister did any of that, or that her expectations of Treasury monitoring of the Bank were sufficiently clear that Treasury did anything either. It seems not to have been until very early this year that the Bank finally began to get a sense that the bid was not going to fly.

In the end, she sort of got there. The final Funding Agreement limit was a lot lower than the Bank had wanted – and involved big dislocation for the Bank and staff because of the unauthorised spree the Bank had continued on with last year, when the Minister could have acted to bring it to a halt much earlier. Even then of course, the cuts relative to the Robertson levels were modest, and the current restructuring seems to be taking staff numbers back to about 2023 levels, probably still 50 per cent above what is necessary. And the Governor and board chair are now both gone. But what a messy and inadequate way to have got there.

It isn’t as if everything she has done as regards the Bank has been bad or wrong, but most of it has been late and/or weak, when she knew from Opposition days that it was a problem institution with a highly problematic chief executive. Who knows why. I wonder if some of it was that she just didn’t care much (it was a below the radar issue with no votes in it) and perhaps she was rather out of her depth (eg the limp arguments recently about independence, showing she has no deep feel for the legislative model, or an ability to articulate it). She seems to have been poorly advised, and ill-served by his own advisers and by The Treasury (which has since cleaned out and replaced almost all its senior managers).

But all in all it is a deeply underwhelming performance from such a senior minister. And if that stuff is just regrettable, avoidable and expensive, the coverup and deliberate sustained intention to mislead New Zealanders around Orr’s departure is inexcusable: weak, inept, and dishonest.

UPDATE: While I was typing this post I had an email from a senior political journalist who passed on this snippet (with permission to use it)

“On October 30 I interviewed Willis about her role as State Service Minister. So it was not an economic interview, per se. At the end of the formal part of the interview we chatted about a few things but we did not discuss the Reserve Bank until she brought it up and said she was determined to cut back its funding.”

Which is interesting, and perhaps consistent with my story. Her instincts were sound – the funding needed to be cut back – but it isn’t clear that she did anything at the time, and it isn’t even clear that she’d yet had any advice on the bid or was aware of the egregious 24/25 budget the Bank’s board had set for itself. The “strong signals” – see this morning’s post – don’t seem to have come until February, months later.

One more bit in the timeline

I had an OIA response yesterday from the Reserve Bank. There is more obstructionism, so a letter will be going off to the Ombudsman this morning, but there was also some interesting information released.

A while ago the Bank’s Board started publishing proactively minutes (carefully crafted ones) of its meetings. It seemed like (and was) a welcome (if limited) initiative, including because it minimised the number of OIA requests they’d need to deal with. But they leave out a lot, and it also only slowly became clear (to me anyway) that they were only releasing minutes of what they described as the regularly scheduled meetings (more or less monthly). The minutes of the February and March Board meetings included these

Of those this year, only the 27 February meeting was a regularly scheduled one (you can read the minutes of that meeting on their website, although almost all the interesting stuff isn’t included (there is nothing about the Funding Agreement or about the Governor – to be clear, not redacted or withheld on OIA grounds, simply not included in the minutes, despite the Public Records Act). Similarly at the full meeting in late March there is no discussion or debrief on the resignation of Orr, or of communications around it, or on approaches to the various OIAs they had already received. Yeah right.

Anyway I asked for the minutes of the other meetings, and received them (in full) yesterday. There are no redactions. The 5/6 March, 10 March and 13 March ones were done by email circular confirming a) Orr’s exit agreement and b) aspects of the revised Funding Agreement proposal. The meeting of the 18th dealt with the appointment of a temporary Governor, where there appears to have been substantive discussion including on expectations of such a person, but a decision that the only person they would seek an expression of interest from would be Hawkesby.

MInutes of RB board special meetings Feb and Mar 2025

[UPDATE 5/9 The minutes are now also on the Bank’s website.]

The one that caught my eye though, and the reason for this post, was the minutes of the 14 February special Board meeting. It was a virtual meeting attended by all board members, but with no other senior management present, just a staff notetaker. Here is the substance of the minutes (not forgetting the opening prayers)

Which seems like a rather important, and deliberate, omission from the carefully chosen set of documents the Bank released on 11 June, when they were still trying to divert us from what actually happened.

What they had released included the following.

From an Orr email of 5 Feb (to senior management, cc’ed to Quigley and Finlay). (I hadn’t previously noticed the rather surprising final bracketed observation – a Governor whose MPC was charged with keeping inflation near 2 per cent worries that inflation could average 3-5 per cent per annum over five years)

And from a long email from Orr to the Board on the morning of the special Board meeting (but before it)

And then an email exchange between Orr and Quigley after the board meeting. This is from Quigley

To which Orr responds with a “Yep all good”.

But what they didn’t release was the bit in the middle, which makes the timeline a bit clearer. The Bank had submitted its original Funding Agreement bid back in September, unanimously approved by the Board. This was the egregious one (seeking $981 million over five years), presented as offering savings of 7.5 per cent, but in fact involving materially higher future spending than the Funding Agreement covering the period to 30 June 2025 (variations approved by Grant Robertson had allowed). There is no sign in the minutes of December quarter Board meetings that they’d had any serious blowback (or feedback at all) and the only mention of the Funding Agreement is a discussion of the ‘nature and structure” of the next Funding Agreement when a couple of senior Treasury officials came for a regular visit.

The (still) missing bit is what initially prompted the Bank to propose to revise down its bid. That plan was the paper in front of the Board at the 14 February meeting, in which it appears to have been proposed to lower the bid from $981 million to $900 million. Perhaps there was some initial Treasury pushback, but it cannot have been too strong or clear, because note the chairman’s introductory comments (emphasis added).

The Chair noted that since the paper had been prepared by the Bank staff he has received strong signals from the Minister and Treasury that a FYFA at $900m will not be accepted, that Treasury advice and the Minister’s initial starting position are substantially lower, and that the Bank will need to show willingness to work with a much lower FYFA funding limit if it is to have influence on the Minister’s final
determination.

“Strong signals” and from both the Minister herself and from Treasury, that what was probably intended as a compromise offer would come nowhere near meeting the mark. (Which is to the credit of the Minister and Treasury, but why weren’t those messages being sent back almost as soon as the initial dropped into the Secretary to the Treasury’s inbox five months earlier? And why has none of this previously been disclosed?)

The Board’s response seems, belatedly, quite realistic (noting “RBNZ is not alone in being asked to reduce spending to a substantial extent”) but then you have to wonder how Quigley ever envisaged later that day that they would be able to “seal bilateral agreement” with Rennie at a meeting the following week. Did Orr not disclose to either Quigley or the rest of the board at the meeting on the 14th just how strongly opposed he was to having spending limits pulled back to around the levels in the expiring Funding Agreement? Did it only become clear when Orr lost his cool – and refused to apologise – at that meeting he and Quigley had with mid-level Treasury staffers on the 20th? In the end it wasn’t his call – the Funding Agreement is between the Board and the Minister, and the chief executive is responsible for working within it – but if he hadn’t put his cards on the table, in a calm and rational manner, at a special board meeting on the issue, it is hardly to his credit. And if the goal of the 20 February meeting had really been “joint advice” to the Minister, it is even more reason for Quigley to have regarded Orr’s behaviour as so unacceptable (and utterly counterproductive).

Does any of this greatly matter at this point? Probably not, but it does fill in a few more blanks (and prompt another OIA or two).

UPDATE 5/9 . There must have been quite serious and perhaps robust debate and exploration of issues/options, since the meeting ran for 105 minutes with no staff. Unsurprisingly the minutes don’t record the tenor of the debate but note that that same evening Quigley thanked Orr for the way he’d handled the meeting, so this one can’t have been explosive.

Yes (he has “given a sufficient explanation”)

That was the Minister of Finance’s chief press secretary responding on behalf of the Minister to an inquiry from Stuff journalists shortly after Neil Quigley’s ill-starred press conference late on the afternoon of 5 March, the day Adrian Orr’s resignation was announced. But I’ll come back to that.

The main problem for the Minister of Finance, in finally encouraging Neil Quigley to resign late last Friday afternoon, is that throwing him to the wolves (well overdue) left her exposed to the long-running questions about what she knew and when, and what part she had played – actively or passively – in the choice to deliberately mislead New Zealanders about what had gone on around the out-of-the-blue no-notice resignation of one of the most powerful unelected officials in New Zealand, one who had generated enormous controversy in his time and whose frosty relationship with Willis, dating back to Opposition days, was obvious to all.

I’ve been writing on this, and on Monday the Herald’s Jenee Tibshraeny had a powerful piece calling out the Minister and noting that – unlike the public – the Minister got no, or next to no, new information from the Ombudsman-led Reserve Bank release on Thursday. The title of her piece said it all really

but noting, importantly (and emphasis added), that “Both the Reserve Bank board and Willis have engaged in what looks like a cover-up of the circumstances surrounding Adrian Orr’s resignation as Governor in March”. offering chapter and verse. This wasn’t just Quigley’s doing (or that of his board and temporary Governor) but Willis’s too.

The Minister apparently claims to regard these criticisms as unfair to her. She was, we were supposed to believe, a helpless Karori mother, pleading in vain for Quigley to be upfront with the public about the loss of one of her key officials, holder of an office where she – as Minister – is personally responsible for any hiring and firing, the one to whom (as the law requires) Orr’s resignation was addressed. Tibshraeny had another piece yesterday afternoon reporting the Minister’s side of the story. This seems to be the essence of her case for the defence

Setting aside for now the question of how much money the Bank has spent trying to stop the public knowing, all this tells us is what we already knew: that the Minister realised rather sooner than the Bank – and Quigley specifically – that the coverup and active misleading was untenable and could not go on indefinitely, but (a) the resignation was in March, and her earliest such comments were in June, and b) she did nothing meaningful about it (until last Friday) when she could have insisted on transparency from day one, or any time onwards. She had (considerable) leverage. But it is pretty clear that she and her office were fully party to the strategy of deceiving New Zealanders, probably hoping interest would quickly die away.

At this point, it is probably helpful to step back and step through the timeline in February and early March. (My overall, and updated, timeline is here.)

In preparing yesterday for this post I went back and read quite a lot of the initial coverage (5/6 March) and some of the OIAs. It was in a BusinessDesk column, dated 5 March, by their highly-experienced and regarded Pattrick Smellie, that I noticed this

I don’t recall noticing it at the time, and it has had no apparent follow-up. Perhaps it seemed (like a number of other things) unimportant that day, when it appeared that Orr had simply tossed his toys and walked off, and if it was apparent that we weren’t getting the full story, there was no reason to think we were being outrightly lied to. I have no idea whether Smellie’s “it is understood” had substance – but he doesn’t seem like someone who just interviews his typewriter – and put no further reliance on it, but if there is anything to it (or to the suspicion of it), it is probably relevant context. Once again, on RNZ this morning, the Minister was claiming it was important that she had nothing to do with the hiring/firing (or facilitated resignation) of Reserve Bank Governors, even though her role is quite central and explicit in the carefully designed Reserve Bank Act (current version, and all its predecessors since 1989).

The story seems to have unfolded through February. On 5 February Orr, having become frustrated with Treasury, advises his board and senior management that he had told staff to “cease and desist” negotiating funding agreement issues with the Treasury, suggesting that it should now be a matter for the Board and Minister directly. That stance seems not to have lasted because 10 days later (14 Feb) Orr and Quigley were exchanging notes about agreeing a deal with Treasury the following week.

But in the meantime, the Minister had been trying to get meetings that month with Orr on both funding agreement and bank capital issues. One of the Herald’s various OIAs revealed that Orr had been stonewalling, using as an excuse the “sacrosanct” nature of MPC deliberations during mid-February, and suggesting that he couldn’t meet with the Minister then, even on quite separate matters (this of course didn’t stop him having his usual pre-MPS meeting with the Prime Minister and Minister of Finance the day before the MPS itself was released). The meeting between Orr, Quigley (and, for part of it, Hawkesby), the Secretary to the Treasury, and the Minister on the afternoon of Monday 24 February was the earliest date Orr appears to have agreed to. In the interim, Orr had once again lied to the Finance and Expenditure Committee and, that same day (20 Feb) he and Quigley held a Funding Agreement meeting with mid-level Treasury officials where, not only was there no meeting of minds or settlement, but Orr so completely lost his cool, and must have refused later to apologise, that Quigley chose to put in writing an apology to the official concerned. Just an extraordinary situation – a board chair helpless in the face of his chief executive’s misbehaviour, unable even to secure an apology from the chief executive himself.

We do not know whether the Minister was aware of this episode before the meeting on 24 February. There is no paper trail shedding light on that (one way or the other), but it would be surprising if she was not made aware of how combustible Orr had become over these issues (and would the mid-level official handling Funding Agreement negotiations not have told his own boss or Rennie himself what happened, would no one in Treasury have alerted the Treasury secondees in MoF’s office, or indeed her – ex Treasury – political adviser? Would Rennie not have mentioned it to Willis?) Phone calls and oral advice don’t easily get captured in OIA responses, unless it suits responders to do so.

And so we come to the 24 February meeting. The Treasury file note of that meeting – which so enraged Quigley when he learned about it as the OIAs rolled in – is here. I had previously defended Treasury, noting that the record – of a high level meeting on important outstanding issues – seemed both reasonable and moderately expressed. But, as it happens, Tibshraeny revealed that yesterday she had a OIA response from Willis (beyond the original deadline) making it clear that the Minister herself had been very keen to have the meeting properly documented, having staffers followup with Treasury to ensure that it was being done.

This was the meeting where the Governor distanced himself from the Board, bagged Treasury, and then (so it seems reasonable to deduce) stormed out.

One thing I hadn’t previously noticed about this file note is that it records comments from the Minister on the earlier agenda items (bank capital reviews she was seeking, and banking competition issues) but there is no comment from the Minister recorded on the Funding Agreement issues (either before or after Orr walked out). It also records no comments from Treasury. Is that really credible (was it really only Orr and then Quigley who made any comments of substance?) or did it suit the Minister not to have had anything she said on those issues documented (given that we now know she had an active interest in the file note)? I don’t know, but it seems a reasonable question.

Things must have escalated quite quickly from there. It just isn’t conceivable that after that performance by Orr, coming on top of the 20 February episode at Treasury, that there was no contact to reflect on what had gone on between Quigley and either the Minister herself or senior people in her office (the latter perhaps for plausible deniability?) Quigley had pro-actively apologised for Orr’s conduct to a mid level Treasury official, so how much more assiduous was he likely to have been around the Governor’s performance in front of the Minister (especially when so much – future Bank funding – depended on the Minister)? Perhaps it was a one on one after the meeting, perhaps a phone call or two, but surely something?

At very least we know (from the RB’s June release) that within 24 hours or so – and before the board itself had met – various top RB officials independently became aware that exit was possible and established an ad hoc to manage the situation if it escalated. I happened to be listening yesterday to the recording of the Minister’s estimates hearing in June and there she states (three times) that it was on 24 February itself that she was told by the Secretary to the Treasury that “employment discussions” were underway between the Board and the Governor. (Other material suggests she may have had that date wrong and that the advice was on the 27th, but she did repeat the 24th a couple of times, in a hearing for which she will have been extensively prepared.)

And if, and the Minister now claims, she had next to no involvement in what came next, that must have been wholly and solely a tactical choice by her. She was, after all, one of the government’s senior ministers, the person concerned was one of her most senior officials (and by far the most prominent) and, by contrast, the Bank’s board then was almost entirely made of underwhelming Grant Robertson appointees, and Quigley had an established track record of not being a safe pair of hands in front of journalists etc under scrutiny. The Minister may have wanted to establish a “look, no hands [of mine] in this” but not only can she not credibly disclaim responsibility, but if there were concerns the board had – about things not visible to her – surely (as the hirer and firer) she had an obligation (to Orr, if no one else) to check them out. It might just have been an aggrieved, out of their depth, board. But, of course, Willis was aware throughout that that 24 February meeting – in her office – had been the final catalyst for the ouster. (And to be clear, I am not in the slightest critical of the ousting itself – Orr should never have been reappointed, and he appears to have acted recently in ways that handed those with power his own head on a platter.)

The Board and Orr met, and then exchange emails, including notably the Board’s statement of concerns for which they sought a response from Orr. (The Bank’s release last week only explicitly mentions recent issues, although my – generally reliable – inside source told me that it included concerns dating back several years.)

Through these days the Minister chose to up the ante, by providing quite specific comments to the Herald’s Thomas Coughlan for this article on Reserve Bank funding he published on 27 February. At the time, I thought nothing particularly of it, except of course to welcome comments suggesting cuts were likely to be required, because I/we then knew nothing of the backdrop. But the Minister did, and it is probable that she chose to respond to Herald inquiries, and to be as specific as she was, after the 24 February meeting, and knowing that a showdown with Orr was underway, knowing indeed that the Board would be meeting – and Funding Agreements issues would be on the table – on the 27th.

It was on the 27th that the statement of concerns was sent to Orr, and also when he got board approval for him stepping aside, remaining out of the office until the situation was resolved, with Christian Hawkesby to act as Governor. The Minister has since said she was aware that Orr had stepped aside earlier (before 5 March), and we must presume she was advised of it that day (there are – content redacted – texts involving Rennie and MoF that day). Are we really supposed to be believe that a highly political senior minister didn’t ask what was going on, or gave no guidance? If so, it can only have been because she did not want to be fixed with knowledge, but that does not change the fact that the evolving situation was her responsibility (she hires and fires, she is accountable to Parliament, the Board is accountable to her). At any point, she could have intervened and taken control (and probably should have, most especially around exit agreement issues).

By this point it appears that both sides (Orr and the Quigley, the latter for the board) had resorted to “senior counsel” to negotiate terms. By Monday afternoon (3 March) the ad hoc management committee had heard that agreement had been reached – although presumably formally documenting it means it wasn’t signed until 5 March. The plan at this point was for an announcement on either the Friday (7th) or the following Monday (10th), although at the last minute this is brought forward to 1:30pm on 5 March after Orr alerted people to concerns about leaks.

The Minister says, and I guess we must believe her, that she did not see, and has not since seen, either the letter of concerns or the exit agreement. But, again, this does not absolve her of responsibility. They were her board, Orr was her responsibility, and she was the one who was going to have to face parliamentary scrutiny. Did she not seek any assurances about lump sum termination payments, or things that resembled them? Did she not raise any issues about what would be said, by whom, when, let alone what sort of NDAs Quigley and the Board might be signing up to? The paper trail does not tell us, but it seems utterly inconceivable that there was no communication about what the story was going to be or how it would be told. And, again, if the Minister just sat back and let Quigley get on with it, she made herself part of such a strategy, if only by acts by omission. She was not a helpless victim (of Quigley here) but a powerful player making deliberate choices.

The paper trail suggests that the Minister had the planned Reserve Bank press release by late morning on 5 March (sent across by Quigley). This statement, which had been lawyered by both sides, represented the first attempt to spin the story. Recall that the Minister was not an innocent bystander here – it was her to whom Orr was actually resigning. The press release was full of “good job, well done, time to step aside” fluff, and there is no sign that either the Minister or anyone in her office raised any objections (to the text, or to the Bank-attached note which indicated that there was no plans to say anything further “if” there were questions). Willis knew that the statement was intentionally misleading – she has since told us she knew about the “employment discussions”, she’d been in the 24 Feb meeting, she knew Orr had been gone for a week, and yet she raised no objections. She doesn’t even seem to have asked what commitments had been made, by either side, under an NDA. But those were her choices; she went along.

OIAs reveal that she instructed her staff not to reveal to journalists what the 24 Feb meeting had been about, briefing notes (backpocket Q&As) prepared by her staff (and provided to PMO) were actively deceptive (“Did you have confidence in Adrian Orr as Reserve Bank Governor? Yes, I’m confident he discharged his obligations under the Act and that is consistent with the advice I received from the Board”, “Is Adrian Orr’s resignation linked to the funding agreement? Not that I am aware of.”), and her office encouraged her to use the “personal reasons” story (which wasn’t in the first press release), although it seems that she didn’t quite go that far herself on the day. Her own press secretary conflated – no doubt to Quigley’s annoyance – “personal reasons” and a “personal decision”, and when mid-afternoon the office was advised that Quigley was releasing another brief (and known to be misleading) comment (“Adrian’s decision to resign as RBNZ Governor was a personal decision. He has conveyed that with consumer price inflation within its target band, this time was right for him to step down.”) there is no sign that the Minister or her advisers raised any concerns whatever, not even to wonder how tenable such a position would prove over time.

But it goes on. Reserve Bank releases, my insider leaker, and the Minister’s own OIA releases suggest that Quigley had not wanted to do a press conference, but that he and the Bank were pressured by the Minister and her office to do so. And so he did. No one thinks he handled it well. And what were the Minister and office expecting or hoping he was going to say? Not the truth surely? They were fully complicit in the Bank’s approach.

I’ve had a automatically-generated transcript of the audio for some months but it was hard to read. Yesterday, I found the video of the press conference in a Stuff article from the time. With that, I completed a full readable transcript.

To assist readers, here I have inserted – in red – comments on the truthfulness (or otherwise) and straightforwardness of Quigley’s answers.

Quigley press conference on Orr resignation 5 March 2025 WITH ANNOTATIONS

It really should serve as a case study for future crisis management communications courses and exercises in how utterly not to do it.

Much of the ground I’ve covered before so I won’t requote here in detail.   It was obstructive, it was deliberately and knowingly misleading, and on occasion it was just outright false.  As just one small example – which we have only known was false since last Thursday but the Minister says she knew all along – was his claim that there had only been an acting Governor since lunchtime that day.

It was utterly deceptive and misleading.

And yet, shortly thereafter a Post journalist emails the Minister’s chief press secretary and asks “is the minister satisfied that the Reserve Bank Board chair has given a sufficient explanation for why Adrian Orr suddenly resigned from his job.”  An hour later Venter replies with a simple “Yes”.    That was, as I noted above, reported in The Post at the time, but it didn’t seem very important, since we had no idea we were being lied to, apparently with the Minister’s knowledge and approval.

Willis has continued, to yesterday, to claim that, even thereafter, she was helpless, apparently an innocent victim of a board chair who ran amok.    It is a story that doesn’t stand even a moment’s scrutiny.    Not only could she have (threatened to) remove Quigley any time she liked (at will, not for cause), but (as she has confirmed) she was not party to any NDAs, and she (and Treasury) knew quite enough that she could have insisted on transparency at any time she chose.    She and Treasury could have released the 24 Feb file note months ago, or the Quigley email apologising for Orr at the 20 Feb meeting.   She could have insisted we were told “employment discussions” had been underway between the board and Orr, with her knowledge, she could have been open about the stark difference of view (she was aware of) on Funding Agreement issues, and by April she could have insisted on the release of that extraordinary Quigley email protesting that Treasury had written a file note of the 24 Feb meeting and might release it.   She could have insisted, without overriding the RB on specific OIAs, on an early statement –  or made it herself – on the lines on “Following employment discussions initiated by the Board, and brought to a head by differences between Orr and the board over funding agreement issues and Orr’s behaviour in several recent outside meetings, it was agreed that Orr would resign.”   There would still have been follow-up OIAs, but we’d have been starting from a truthful statement, not from false and/or misleading statements exposed only by OIA upon painful OIA, a leaker, and some (limited) support from the Ombudsman.

The Minister of Finance was, therefore, an active participant in choices about what was done and what was said about what was done.    That was so before the announcement on the afternoon of 5 March, before the Quigley press conference, and then for months afterwards.  She knew the truth and she chose repeatedly and persistently, to keep it from New Zealanders.  That is pretty extraordinary, pretty inexcusable.

One is left wondering how they (Board, Hawkesby, Willis, her advisers) ever thought they were going to get away with it.  No one seems to have stress-tested a comms plan, which is extraordinary in itself, for an event of such significance and inevitable public and commentator and (belatedly) political interest.    I guess it is good that Willis realised before the Bank that the game was up and that something closer to the truth would have to come out, but even then for too long her response was feeble, possibly concerned that doing more would –  as it has done – expose her involvement and support for the approach more fully.

The fault was not in helping to engineer Orr’s exit –  that is to her and Quigley’s credit, given the glaring behavioural record, come to a head in late February –  but in the choice to obstruct and to mislead New Zealanders.  And people wonder why trust in our institutions and politicians is in decline……

UPDATE:  Forgot to include here that press release of MoF’s last Friday afternoon announcing Quigley’s resignation, with all the spin about “good job, well done, time to go”.   Perhaps she never even read it before it went out, and she did back away moments later in a radio interview, but….


Weak minister, weak institutions

We’ve all seen or heard of the sort of parent who has a troubled teenager or young adult but who is always making excuses for, or minimising, the child’s repeated bad behaviour. Yes, yes, that [insert specific] was wrong, but really s/he is a good girl/boy. Parental love is, as it should be, a powerful force (mostly for good) but in those cases the indulgence and excuse-making rarely ends well.

It was a parallel that came to mind in thinking again about the extraordinary way in which Nicola Willis has indulged Neil Quigley, the chair of the of Reserve Bank Board, in which role he now seems to have had more lives than the proverbial cat. No one seems to understand why she reappointed him to one last two year term as chair last year (having already been caught out actively misleading Treasury and the public, and having accommodated pretty all of Orr’s own excesses, policy and behavioural, and uneasy relationship with the truth). And things have only gone downhill from there. The same week Quigley’s reappointment was announced, he released the Bank’s 2024/25 Statement of Performance Expectations which included an operating spending budget far in excess (23% in excess) of spending allowed to the Bank for that year in the last year of the old Funding Agreement, as amended by Grant Robertson just prior to the last election. When they had sought comment from the Minister on the draft SPE (as the law required them to) they simply failed to tell the Minister how much they proposed to spend – and it appears that neither she nor Treasury thought to ask (in their defence, presumably they implicitly assumed that the Bank would simply operate consistent with the Funding Agreement limits).

Then they – Quigley, Orr, and the rest – used that egregious budget not only to lock in fancy new and big long term office space in Auckland, to keep driving up staff numbers, but also as a base for their bid for spending for the next five years, all the while claiming their bid was quite consistent with the Minister’s expectation (as I noted on Wednesday, it seems that on the letter of what MoF had said it was – she and Treasury probably assumed they were dealing with decent and honourable people – but in spirit and substance it was anything but). They were eventually knocked back, but staff (lots of layoffs) and taxpayers (restructurings cost) are paying the price. The Board members, notably the chair, remain in office.

And, of course, it was capped by the extraordinary dishonesty of the last six months around the departure of Adrian Orr (I used to say “on 5 March” but it turned out yesterday he’d already been out of the office for a week prior to that) in which Quigley has – from the moment the first press release dropped – been actively misleading the public about what went on, attempting to block scrutiny, and (as revealed the other day) deploring Treasury’s compliance with the Public Records Act in writing a moderately-expressed file note of a major policy meeting between senior Bank and Treasury people and the Minister of Finance. Once again, it was too much for the Minister of Finance (and this time Labour’s finance spokesperson joined in), but….. Quigley (and the rest of the Board, and the governance of the Bank is vested in them collectively not in Quigley individually) is still there, even though his position as chair is one that Minister can remove him from more or less at will.

I won’t bore readers by tracing through all the chaotic litany of active misrepresentations we’ve been subjected to (and yes “litany” there was meant to evoke Peter Mahon) over the six months, through press statements claiming it was just that inflation was down and it was time to go, denial that there were any policy or conduct issues, claims that Quigley still had confidence in Orr, then the 11 June statement which again actively misled the public, through to yesterday’s new (and still selective) timeline. But just an example, compare and contrast his interview with Heather du Plessis-Allan little more than a month ago with the story revealed in yesterday’s release (which, incidentally, further confirms the story I first reported here from the anonymous insider who leaked to me). We have been misled and obstructed, deliberately, from day one – by someone who reveals repeatedly a disdain for public scrutiny and accountability, let alone the law when it might inconvenience him. Almost singlehandedly (although don’t forget Hawkesby and the rest of the Board) Quigley has materially furthered damaged the reputation of an institution already badly diminished by the now-departed Governor (who’d been lying to FEC the very morning he’d lost his cool at Treasury, forcing Quigley to apologise for at least the second of those). It is, frankly, scandalous that Quigley is still in office. A growing number of observers, not just those with a specialist in the Reserve Bank, seem to be reaching the conclusion that his position should be untenable.

It was, I think, the Taxpayers’ Union whose statement on Wednesday (ie before even yesterday’s release) which best captured for me what the repeated inaction says of the Minister of Finance herself.

This is a major and very powerful public institution. The Board is put in place by the Minister to serve taxpayers’ interests in governing the institutions, but they seem to have driven a cart and horses through any sense of acceptable standards (whether around the spending or the attempts to obstruct and cover up in recent months). The institution is diminished, the standing of the individuals (notably Quigley) is diminished, and the Minister of Finance – responsible to Parliament and the public for the Bank – does nothing beyond disclaiming all responsibility and occasionally wringing her hands and wishing that her recalcitrant or rogue chair would only behave a bit better. What sort of Minister of Finance does that make her? She (and Treasury) was played for a fool herself, and she has let the public be repeatedly lied to. An effective minister would have dished out condign punishment months ago. From Willis, nothing.

Quite why is anyone’s guess. Perhaps she is just grateful that Orr is gone (aren’t we all?) and the board did help trigger that. Perhaps there is something about the medical school – would it reflect badly on the government if they now ousted as chair the chap they’d just given a controversial medical school to? Some claim it is that Quigley is a National partisan (I don’t take that one very seriously. He might fancy himself as a political operator – though as Jonathan Milne’s profile a couple of months ago noted, people who’ve been on boards with him don’t think he is very good one – but….he was reappointed as chair as recently as 2022 by a Labour government). There are, of course, still substantial unanswered questions about the Minister’s own involvement in, and knowledge of, events leading up to the Orr resignation announcement (and Quigley and the Bank are clearly still covering for her, with no mention in any of their releases regarding contact with the Minister or what she was advised or, and aware of, when). But it all reflects very poorly on her, including associating – the Minister of Finance – with a sequence of events which has left the standing and authority of the nation’s central bank in the gutter, and with Quigley still responsible for wheeling up the nominee to be next Governor – and if the Minister accepts Quigley’s nominee, that person’s standing will be tarred from day one.

Quigley should have gone long ago. But he should go now. He should do the decent thing and resign. But if he (still) won’t, the Minister should not have any hesitation in removing him, certainly as chair, and probably as a board member too (the standard there is tougher, but clearly met).

For the rest of this post, I want to (a) step through the legal provisions, and b) address any concerns that somehow removing Quigley (and, possibly, other board members, especially those from 2024) would be in some sense Trumpian (with his current attempt to fire Lisa Cook from the Federal Reserve Board of Governors). It wouldn’t. These bits are for reference/reassurance and anyone who simply wants to take my word for what can be done can easily stop here.

Legal Provisions

In many government entities, board members can be removed more or less at will. That isn’t so with the Reserve Bank, a conscious choice made in overhauling the Act in 2021, presumably reflecting the key policy role the Board has around financial system regulation and supervision. One can debate the pros and cons of that model, but the law is what it is.

Take the chair’s position first. The chair and deputy chair are directly appointed from among board members by the Minister

There is no requirement to specify a term for the appointment, although Willis reappointed Quigley last year explicitly for what was envisaged as a final two year term.

And if the chair (or deputy chair) can’t be removed instantly, in substance it is pretty close

The Minister is not required to specify a cause and can act once she has consulted with the person affected.

Removing Quigley as chair would still leave him as a member of the Board.

There is a tougher test to be met to remove a board member. Here is what the Act says.

And here are the relevant bit of their duties. First, the collective ones

And these are from the individual duties

The Act is also pretty clear that the duties are owed to the Minister. For example

It would seem not difficult at all to remove Quigley from the Board altogether on multiple grounds including (a) not operating in a manner consistent with the spirit of service to the public (his disdain for legitimate public interest and scrutiny has been manifest and explicit on numerous occasions), b) not operating with honesty and integrity (in the coverup of the last six months), and c) in threatening non-collaboration with Treasury unless they defied the Public Records Act, and d) in not operating in a financially responsible manner (setting that 24/25 budget so far in excess of what was allowed for that year, and associated locking in property spending that could be warranted only if somehow the government had made something like that level of expenditure permanent, something for which he had no reasonable grounds to believe was likely to happen. But quite probably if Quigley was removed as chair, or stepped down voluntarily or under duress, he would not want to see out the last nine months as an ordinary board member again.

I reckon there is a pretty reasonable case that all the remaining 2024 board members could also be removed, since they have either supported or done nothing to stop, the decisions and behaviours described above. Probably the only board member in the clear is former Deputy Governor Grant Spencer who only took office in early July this year (although with each passing week of Quigley’s conduct and the Bank still providing only partial information his position is weakened), with Philip Vermeulen a marginal case (he was an observer – “future director” – last year, but became a full director on 13 February this year). I think there is a strong case for removing the deputy chair Rodger Finlay and Byron Pepper (both of whom had earlier ethical issues around their appointment) and Jeremy Banks and Susan Paterson, but I guess a) it isn’t likely to happen, and b) you would need a strong bench of replacements straight away. But it is a choice open to the Minister.

Lisa Cook comparisons

President Trump has, of course, been looking to oust members of the Federal Reserve Board of Governors. For now, he seems to have given up on the chair, Jerome Powell, but this week has (purported to) dismiss Lisa Cook, justifying it on the grounds of alleged misrepresentations (of the sort that, if true, could be fraudulent) relating to mortgage applications she had lodged before becoming a Governor.

People can and will debate the merits of the issues, and the legal one is likely only to be decided by the Supreme Court determining what “for cause” means in the context of the Federal Reserve legislation. But it is pretty clear that Trump wants more influence – direct, or through chosen appointees – as regards monetary policy decisions. Unsurprisingly, that is controversial and can be seen to go towards the heart of central bank operational independence, which has become a hallmark of most advanced country central banks in recent decades.

Quigley’s position (or indeed that of the other board members) is quite different in a number of ways.

In terms of policy/economic substance, the most important difference is that Cook is a monetary policy decisionmaker (all members of the board of governors have permanent positions on the decision-making FOMC). Quigley – and the Board – are not. Monetary policy decisions in New Zealand are made by the Monetary Policy Committee consisting of the Governor, three other internals, and three externals. The Board’s role is to (a) nominate MPC members, including the Governor (but the decision is finally the Minister’s and Cabinet’s) and b) to monitor and review their performance (since the Board can advise removal if MPC members breach their individual or collective duties). The Board does have important independent policymaking powers in respect of financial system regulation (eg bank capital requirements are a board policy decision now), and given the government’s expressed preferences re some of the banking regulatory issues there might be some queasiness about removing board members…..if it were not for the fact that their performance on quite other well-documented matters (and especially that of the chair) evidently rose to the standard for removal.

And that sentence is the other main point. We – and the RB – are not operating under decades-old legislation with fuzzy language around removal powers, but under brand new (2021) legislation, explicitly designed to ensure (a) that the chair is readily removeable, and b) that all board members are explicitly accountable to the Minister for their performance of their individual and collective duties, with removal an explicit remedy open to the Minister in the event of (serious) breaches.

The coincidence in timing with the Trump activities is unfortunate, but – frankly – the debasement of our institutions while the Minister wrings her hands and does nothing about egregious behaviour of the sort we’ve seen is, for want of a better word, more Trumpian (much more so) than taking breaches seriously and acting accordingly to signal that we will insist on high standards from those running our government agencies. That we will sweat the small stuff and (as this become) the big stuff.

Failure to act (specifically on Quigley) is a terrible signal from the government, both of the weakness of its own senior minister and (suggestive) of an indifference to high standards in public life.

A timeline

(I was going to follow-up on yesterday’s post and the associated (and welcome) media and political reaction regarding Neil Quigley’s latest disclosed (mis)conduct, but a new statement from the Reserve Bank this morning has seen that overtaken by events.)

The egregious chair of the Reserve Bank Board, Neil Quigley, has been at it again this morning. The Ombudsman has been inquiring into at least some of the complaints regarding the Bank’s handling of OIA requests around Adrian Orr’s departure. Here I stress – in contrast to the Bank’s statement this morning – “some”, since I have a letter from the Ombudsman yesterday that they are still looking into parts of my complaint on these issues

The outcome of the inquiry that the Ombudsman has concluded was that a) the Bank was not obliged to release any other documents than the carefully selected and very partial group, designed as much to mislead as to illuminate, that they released on 11 June, and b) that the Bank has, on the Ombudsman’s recommendation, nonetheless released a (also rather partial) “summary timeline of events relating to Mr Orr’s departure” (included in the statement at the link above).

Quigley engages in some self-congratulation in this morning’s statement thus

Which is just an extraordinary claim since (a) delaying tactics are a serious issue in their own right, b) many of their responses never identified (and still have not done so) specific reasons for withholding specific documents, c) some aspects of OIA requests were simply ignored, and d) some are still outstanding. To which I could add that the pro-active statement (and selective document release) of 11 June was clearly designed to mislead, and much light has since been shed by a combination of (a) the apparent insider who leaked to me, b) releases by the Treasury in the wake of that leak, and c) the timeline the Bank has just released. Between all that and Quigley’s own very public obstructionism, open disregard for the intense public interest in this matter, and actively misleading answers to questions dating all the way back to 5 March (probably questions to public officials formally count as Official Information Act requests), Quigley’s claim would be laughable if the situation weren’t so serious. Much is still unanswered.

Anyway, the point of this post is to put in place a rather fuller timeline, drawing on all that we now know, including but not limited to the Bank’s release this morning. In a small number of places I will insert things that must have been so but are not formally confirmed in documents, but where I do that I will explicitly indicate as much. As much as anything, those items point to continuing gaps in the record. A few comments follow below the timeline.

Orr departure timeline as at 28 August (the document might be updated if further information emerges but the current text is below)

Quite a few things are still less than clear, and are deliberately not being disclosed:

  • there has been no indication as to what the Minister knew, when she knew it, including what (if any) contact she or her office had with Quigley after that meeting on 24 Feb,
  • we have none of the text of emails between Orr and the Board after 24 Feb (despite others, that seem to suit the Bank, being released, and others having been released in the past), or of exchanges among Board members themselves,
  • we do not know why the Board agreed to an exit agreement at all (if, as it is described, Orr had lost trust in Treasury, the Board, and the Minister –  and noting that he was the employee –  the simplest thing would be for him to have resigned, under standard contractual conditions)
  • or why the exit agreement seems to have provided for Orr to have been paid in full despite being absent from the office for more than a month,
  • we do not know the character or general terms of that exit agreement (eg who isn’t allowed to say what –  noting that Quigley has previously attempted to hide behind that agreement, before a lot more later came out),
  • we do not have an explanation or apology from Quigley for what was pretty clearly sequential efforts to mislead (and worse) the public, starting from 5 March (and further reinforced by the attempt revealed in full yesterday to squash Treasury’s file note of an important policy meeting),
  • we do not know if the other board members knew of the exit agreement terms before they were signed, and
  • we are led to believe that MoF, to whom Orr actually resigned, had no knowledge of the terms of the exit agreement.  If not, why not (as the person actually responsible for hiring and firing).
  • do those ex gratia payments to seven staff, each made after Orr left, relate to complaints about Orr and his conduct?
  • And perhaps someone might ask how much staff/Board time and outside legal expense has been incurred in almost six months of obstruction and coverup, when things could have been set out simply and straightforwardly months ago.