Reserve Bank, Treasury, and Willis

There have been numerous OIA requests around events leading up to and surrounding the (pretty clearly) coerced exit of Adrian Orr on 5 March. The Reserve Bank in particular continues to keep on with a fair amount of delaying and stonewalling, clearly resistant to the idea that the public has any real right to know what happened, in a case involving one of the most powerful officials in New Zealand, with a track record of poor personal behaviour and very costly policy choices. Judging from a couple of their recent responses to me and one I noticed to someone else via fyi.org they seem to be working towards a date around 18 September (at least three requests are extended to that date), perhaps around the expected timing of any final Ombudsman determination on the various appeals already in train. By then it will be well over six months since Orr resigned, and that it is with the Ombudsman apparently taking this matter seriously. It is pretty bad, in both appearances and substance, and had the Bank and the Minister of Finance been at all serious about transparency and accountability we could have had a full reckoning within a couple of weeks of Orr’s departure, and then moved on towards rebuilding the institution and with it its credibility and authority (eg that “social licence” Orr used to like to bang on about).

And yet, various responses do come in. While I was away last week there were responses – each with some information – from the Reserve Bank itself, from The Treasury, and from the Minister of Finance. In their different ways, whether by acts of commission or omission, they do not show any of those three parties in a good light.

You’ll recall that it was the Reserve Bank’s egregious Funding Agreement bid, and the resistance to it by the Minister of Finance and Treasury, that finally sent Orr over the top, resulting in behavioural breakdowns (described in the Herald the other day, with apparent extreme understatement, as “including at least one indecorous outburst”) that led to his coerced resignation.

I’ve been trying for months to get to the bottom of this; both how they ever made such an egregious bid in the first place, and how Treasury and the Minister did so little for so long, such that this only came to a head in late February (the bid having been submitted in September).

We know:

  • that in her letter of expectation to the Bank’s Board in April 2024 the Minister set out her expectations about future spending.   Against the backdrop of what was happening to other agencies most people would read this as suggesting that the Bank could expect less authorised spending under the new Funding Agreement than under the old one.
  • The Reserve Bank nonetheless went ahead and set its own 24/25 budget (which it could, in law, do) 23 per cent above the amount of operating spending authorised for that year by Grant Robertson in a variation to the previous Funding Agreement made just prior to the 2023 election.
  • The Reserve Bank did not tell the Minister of Finance this, by the simple device that when –  as the law requires – they gave her the opportunity to comment on their 24/25 draft Statement of Performance Expectations, they simply left out the planned budget amount. (It was filled in in the final published version but…..who reads such things).
  • The Treasury seems not to have raised any concern about this egregious 24/25 budget –  it isn’t even clear they asked about it or were aware of it at any time during 2024 – and certainly did not alert the Minister to what had happened.
  • The Reserve Bank (and note that this was the Board, unanimously, and not just the Governor) in September 2024 lodged a bid for the 2025-30 Funding Agreement that was quite explicitly set on the basis of involving a level of future operating spending 7.5 per cent below their own (grossly inflated) 24/25 budget.
  • Numbers consistent with this bid found their way into the HYEFU expense tables in December last year (Treasury telling me that they simply took the numbers the Bank gave them).
  • Treasury appears not to have engaged seriously with the Funding Agreement bid until February this year.

It was pretty much beyond comprehension all round. How could the Reserve Bank Board have the gall to have a) set such an initial budget inconsistent with the recently updated funding agreement and b) then used that as the base for a bid for such a higher level of resources (incidentally going on to commit to large and expensive new office space in Auckland without any certainty as to their future approved spending)? How could the Minister of Finance, who had very evidently been no fan of Orr, have let all this happen (where was her suspicion/curiosity, where was that of her advisers)? And how could The Treasury, supposedly the guardians of the public purse and specifically charged with monitoring the Bank (and Board minutes show Treasury DCEs turning up for chats at Board meetings), have been so oblivious to what was going on (would this have been an acceptable standard in any other government department monitoring its Crown entities)?

The Bank has been quite obstructive in releasing the relevant material (Treasury, more cooperative, reveals that it really had none) and are still refusing to release the final Funding Agreement bid that went to the Bank’s Board (I really only want it to check whether the Board exercised any discipline on management excess but the minutes suggest not). However, in consultation with Treasury, they have now released a letter of expectation sent by the Minister of Finance to the Board chair headed “Expectations for the 2025-30 Funding Agreement proposal and review process”.

The version they released has no date on it (I asked yesterday, but perhaps they’ll take another 20 working days to reply), but it must have been after the April 2024 general letter of expectation (see above), although perhaps not much after it.

[UPDATE 8/9: The Bank has confirmed to me today that the Board chair received the funding agreement letter of expectation from the Minister of Finance on 3 April 2024.]

If you were dealing with honourable people, it would be a perfectly reasonable letter.

The Minister outlines the general fiscal context:

In pretty much any core government agency the budget for 24/25 would have been the appropriations made by Parliament for that department for that year. The Reserve Bank was different, because it had a five year Funding Agreement, in which approved operational spending for each individual year was specified. The Minister (and Treasury, as drafters of the letter) should still have been safe because you’d surely be able to count on the Bank having set a 24/25 operating expenses budget very much in line with the limits in that previous Funding Agreement for 24/25?

With decent people, but not it appears with the Reserve Bank Board (Quigley, Orr, and the rest). They simply set themselves a budget for 24/25 that bore no relationship at all to what they’d previously been allowed to spend for that year, and then took the Minister at her (literal) word and put in a bid 7.5% lower than that grossly inflated budget. And thus, per the covering Board paper dated 12 August 2024, Bank management (in this case, two of the – very many – deputy chief executives, Greg Smith and Simone Robbers) offer this assurance to the Board

And on the letter of the Minister’s request, it was indeed so. But it was fundamentally dishonest and any half-alert board members (including, but not limited to, Quigley and Orr) must have known that. It is almost inexcusable that any of the Board members involved – both in setting the 24/25 budget itself, and playing fast and loose with the clear intent of the Minister’s letter, in turn leading to the massive dislocation to the organisation and its staff this year – are still in office (driving the determination of the nominee to be the next Governor).

These are the guilty men and women who are still in office, drawing (incidentally) the highest board fees for any non-commercial government agency in New Zealand:

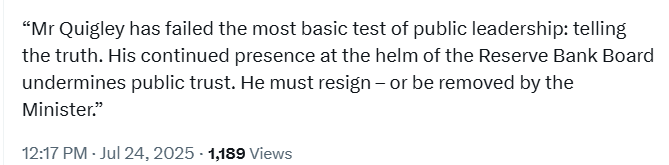
Nei Quigley (who, for reasons apparent to no one else, the Minister continues to express confidence in)

Rodger Finlay, the deputy chair

Jeremy Banks

Susan Paterson

Byron Pepper

Meanwhile, Treasury seems to have been asleep at the wheel, and doing a particularly poor job in pro-active advice to the Minister, in drafting things in a way that ethically challenged people could not drive a cart and horses through, and in undertaking constant and reasonable challenge and scrutiny of the Bank. And the Minister and her team hardly emerge looking good, when they been clear all along that they’d had doubts about Orr.

Where, you might also wonder, were the Opposition and FEC? But the primary responsibility rested with the Board, the Treasury, and the Minister. And if we can’t count on more honest and straightforward behaviour from those charged with monetary stability and the regulation of our financial system, or more effective scrutiny from those responsible for safeguarding the public purse, things are even further gone than this pessimist had come to fear. Mistakes will happen, but then the question is whether those in a position actually take them seriously and do something. There is no sign Nicola Willis has done that (after all, all those board members are still in office, and although their bid was cut back there were no consequences for them for the havoc they wreaked or the ethically-challenged try-on).

The second part of this post skips forward some months. But before we get to that take note of what the Bank and Quigley had done in the earlier section, hardly (one would have thought) conducive to good and trustworthy relationships going forward between the Bank and Treasury, if Treasury now realises they have to dot every i and cross every t, and check every single document that the Bank is not attempting to pull a fast one).

You might remember that a month or so ago I reported what an apparently well-informed insider had told me about what really happened around the Orr departure. Pretty much all of that story has checked out as things unfolded. One element of the story was that Neil Quigley had gone ballistic when he learned that Treasury had kept a fairly full file note of a critical meeting held on 24 February between the Minister of Finance, the Reserve Bank, and the Treasury. So I lodged an OIA request with The Treasury, and this was the response

Treasury response to OIA request re 20 and 24 RB meetings

From it

Personally, having taken many file notes of meetings with Ministers of Finance and Treasury earlier in my career, neither the fact of the file note nor its contents seemed particularly surprising or inappropriate. Major issues (not just the funding agreement but bank regulatory ones) were being discussed, the language is not inflammatory – although the Orr walkout (itself described in muted terms) certainly was.

The fault here seems (and not surprisingly) all with Quigley. As ever with him, there is never a sense of why the Official Information Act exists, or whose interests it is supposed to serve. Instead, we get implied threats of (a) “this will require the full force of RBNZ legal advice to be brought to bear on it”, and b) the suggestion that release would “immediately destroy the goodwill between Treasury and the Bank that I have tried to create over the past few years”. You might wonder how Quigley is feeling now that the full file note has been released, but even set that to one side……goodwill????? This was the same Board chair whose chief executive had behaved so egregiously in a meeting with Treasury that Quigley had felt compelled to provide a written apology, and whose Governor (in that 24 Feb meeting) had (in muted Treasury language) “expressed frustration at the relationship between the RBNZ and the Treasury”. And this was the Board chair who had pulled the wool over Treasury’s eyes by agreeing to a budget for 24/25 quite out of step either (and more importantly) with his own Funding Agreement, or with the spirit of government fiscal policy last year, and then used that abuse as the base for a bid for a big increase in authorised spending for the coming years.

Quigley then puts one of the Bank’s attack dogs, their General Counsel, onto the issue and we have his crucial email as well

So, the Bank’s General Counsel tries to threaten Treasury that the Bank would not in future be willing to hold meetings with Treasury and the Minister of Finance on its future funding? Yeah right, but it is an attempt to intimidate Treasury.

And then, of course, there is that second paragraph. Which goes to the whole point, that the Reserve Bank’s Board appears to have engaged in attempts to make end runs around any serious public scrutiny, including via the OIA, by doing sweet-heart deals with Orr, the terms of which they also refuse to disclose. Fortunately, sweetheart deals done by Quigley et al don’t bind The Treasury, without whom it seems we would have no idea what went on at that critical meeting, when things were so bad that within 24 hours the exit process was getting underway.

Quigley repeatedly displays no regard for the public interest, and any relationship to the truth or straightforwardness on Reserve Bank matters seems entirely incidental (ie whether or not it serves his ends of the moment – see the repeated active misleading of the public, both on 5 March and since).

And, just briefly, one final OIA, this time from Willis herself.

My informant had told me that on the afternoon of 5 March there had been heavy pressure from the Minister’s office for the board chair (Quigley) to do a press conference on the resignation. One of the Bank’s earlier OIAs had also mentioned such approaches. The Minister’s response confirms that there were two conversations that afternoon involving her Senior Press Secretary and the Bank’s communications head to that end, and it also releases the draft press release and Bank comms plan that Neil Quigley had provided to the Minister’s office late on the morning of 5 March which included this: “Recommended media response plan for if [ “if”???? Really?] we get questions: No further comment”. The ill-fated press conference, at which Quigley did so poorly and actively misled the public, was clearly Willis’s initiative.

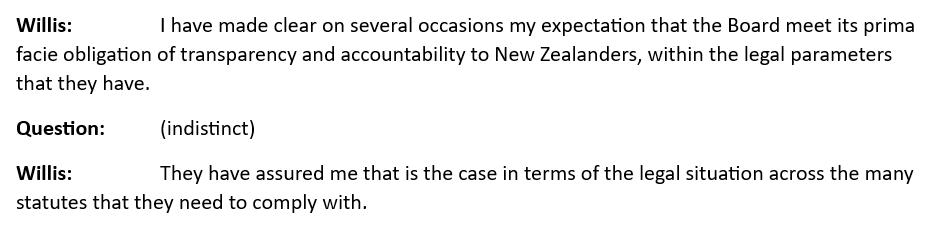
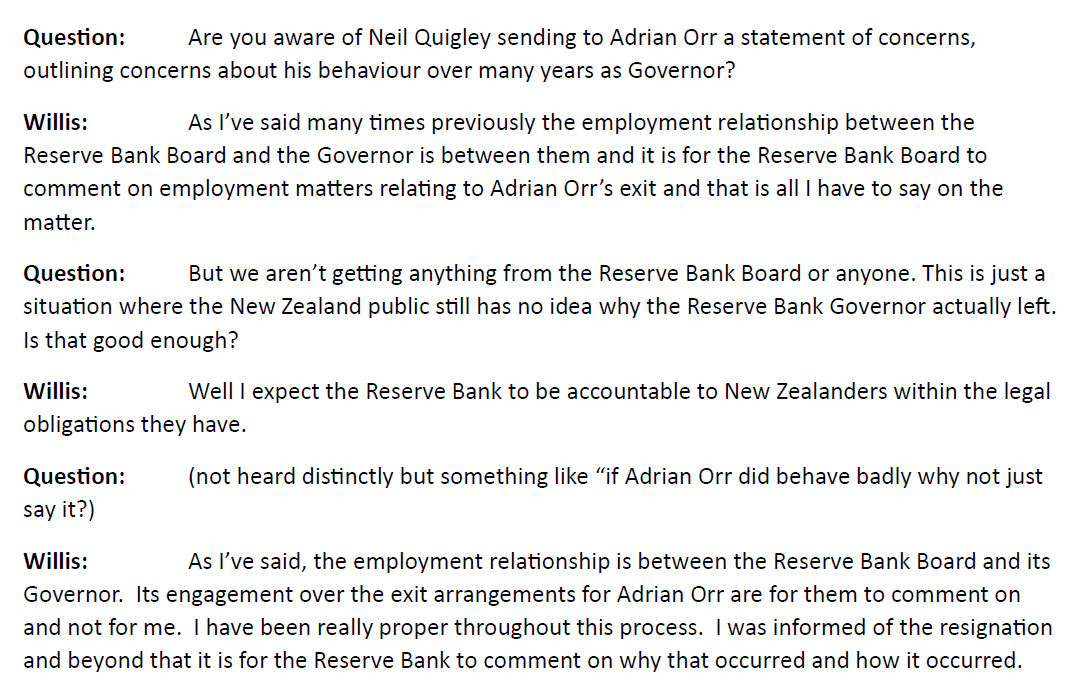
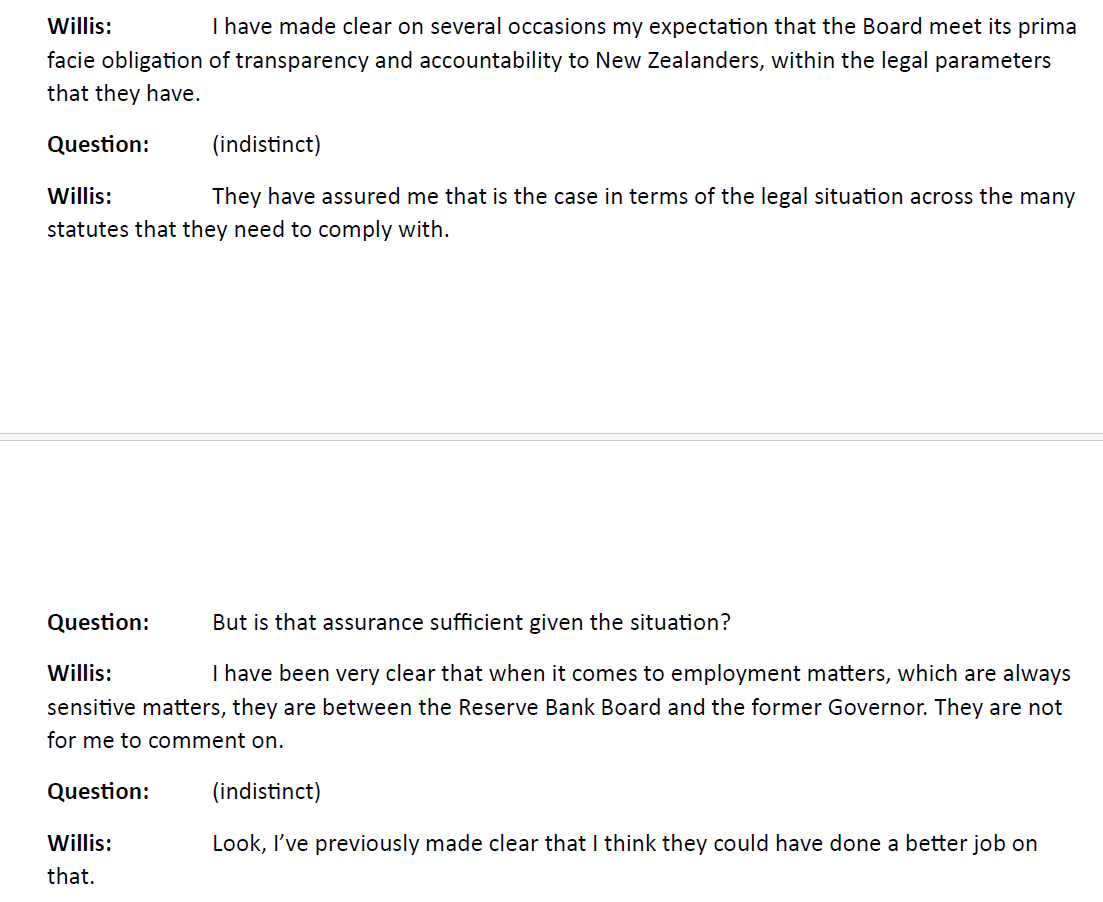
But that was not my main interest. I also asked for copies of “any material relating to exit conditions for Orr (process or substance)”. The Minister’s response was “No information about the Reserve Bank Governor’s exit conditions is held”. Which really is inexcusable. As a reminder, the Minister (and Cabinet) appoints the Governor, the Minister (and Cabinet) are the only ones who can dismiss the Governor, and the Governor’s resignation has to submitted to her specifically. The Minister is also responsible for the Board, and appoints – and can dismiss at will – the Board chair, and is the only person in the entire mix with any degree of direct public accountability. And yet we are expected to believe she is so incurious as not to enquire at all as to what sort of cover-up arrangements Quigley (and the “senior counsel” both sides engaged) was cooking up with Orr, as the basis for his departure, or even at what cost. And when a key precipitating event was a meeting she was part of?

I’m not sure I really believe it – not “holding material” is likely to be different from no phone calls were made, directly or indirectly, (and there is set of texts involving Iain Rennie on this topic that are still being withheld in full by Willis) – but if it is true it reflects very poorly on her as a steward of the public interest.

(And that is even granting that the wider public interest was almost certainly served by Orr’s departure, a couple of years after he would already have gone had the previous government not, inexplicably, reappointed him.)

One more Treasury OIA about RB spending

All the interest in the Orr-departure story – the background, and the subsequent and ongoing efforts to mislead the public by the Board and the temporary Governor – seems to now centre on the Ombudsman. Various people, including me, have appealed the Bank’s OIA obstructionism on specific requests and the Ombudsman seems to be pursuing the issue reasonably expeditiously. I received a draft of a provisional opinion the other day for comment (which I have now provided extensive comments on) but I’m guessing it might be a couple of weeks before we get a final decision. I’m going to be away for a while so I don’t expect to write anything more after this post for at least a couple of weeks.

For the record, the Herald has an article today on the Reserve Bank staff cuts. Most of it is ground covered in my post last Friday. But the one bit that caught my eye was this

To which there are so many possible thoughts in response:

  • Surely no serious external observer ever thought they needed what they had bid for to do their statutory duties effectively,
  • But if the Board is now confident that everything can be done with 20 per cent fewer staff than they had in January, why did they ever bid for so much more money?  (And it was the Board’s bid, perhaps championed by the then Governor but he was their agent and they had responsibility for governance, budgets etc),
  • And if “no work programmes have been cut” [“out altogether” appears from context to be the intended interpretation] a) what were all those people previously doing? and b) given all the non-core stuff the Bank got into under Orr, why on earth not?
  • It seems like further evidence that the modest cuts Willis imposed relative to what Grant Robertson had allowed the Bank to spend did not go anywhere near deep enough.

And it remains extraordinary that none of the Board members has had the decency to resign and that the Minister continues to express confidence in the chair, whose signature had been on that egregious bid late last year for so much more money, in which he and the Governor stated that that increased funding was what was appropriate “to deliver on our mandate and agreed outcomes”.

So many puzzles and so few explanations when it comes to explaining the last 10 months or so of the Orr tenure, that all ended so ignominiously on 5 March, coverups and all.

But another OIA response came in from The Treasury yesterday (having taken the best part of two months to provide two pages of information (and not withhold or redact anything)). Another of the puzzles around that final year or so is why Treasury appears to have been doing its monitoring role of the Bank so poorly (and this is a formal monitoring role, for which resources are formally allocated, established under the overhauled Reserve Bank Act in 2021).

This had been the request, lodged on 16 June

Some of this had already been overtaken by events because the Reserve Bank had already released to me Treasury’s comments on the draft 2024/25 Statement of Performance Expectations (SPE), and then had released the draft SPE and covering note the Bank had sent to the Minister of Finance.

The mystery, you will recall, was that the Bank had chosen to spend about 23 per cent more in 24/25 on matters covered by its Funding Agreement than the variation approved by Grant Robertson just before the 2023 election had allowed. Surely, it seemed, Treasury and the Minister of Finance would have pushed back strongly on this? But it emerged – all documented in previous posts – that the Bank simply chose to leave out the planned budget numbers from the draft SPE they consulted the Minister on. She simply wasn’t told about this planned excess, and Treasury had not flagged any concerns to her (they’d noted that the draft SPE didn’t have the budget figures in, but raised no particular concerns and simply noted that the numbers would have to be in the final version). They were, but there was no particular reason for the Minister or her office to look closely at the final version because they’d not been alerted to any particular areas of concern, or requested any major changes to the draft. As I’ve noted before, perhaps the Minister and her advisers should have been more suspicious – Willis had scarcely been on record as an Orr fan – but the real fault seemed to lie with Treasury. They are, after all, supposd to be the guardians of the public purse.

So what new do we learn from yesterday’s release? Mostly, it is about gaps – and not in what they released, but in what work never seems to have been done.

There were four limbs to my request.

On the first, it seems that there was no additional analysis or advice internally, and certainly nothing documented outlining any concerns as to what the Bank might be up to or suggesting (say) that they should insist that the Minister was alerted to the planned budget for 24/25. There is no sign in any of the material that Treasury was even aware of the scale of the planned spending blow-out, let alone suspicious of how such a blowout might be used to try and leverage more resources in the forthcoming Funding Agreement bid.

The third limb related to something I’d spotted in this year’s government Budget documents.

A not inconsiderable chunk of the “savings” in this year’s Budget ($144 million in fact) was this item. We were told, reasonably enough, that the figures now included in the 2025 government Budget reflected the new Funding Agreement that had been signed and released in mid-April. But why had figures so much higher ever been included by Treasury in the HYEFU last year? After all, much higher numbers had no warrant in any document any minister had ever seen (eg the draft SPE – see above) or signed (eg the Funding Agreement then still in place covering the period to 24/25). Why, in an environment of fiscal stringency, had Treasury included levels of Reserve Bank spending for the next few years far higher than anything authorised from the centre to that point?

The answer, it appears, is that no one bothered to look or check or think. Treasury told me that “there is no material in scope of the third part of your request”. And went on to tell me that “we note that the RBNZ provides the Treasury with operating expenditure forecasts which are used in the Treasury’s Half Year Economic and Fiscal Update (HYEFU)”. Which seems almost beyond belief. The Bank isn’t a tiny entity (say the Walking Access Commission), but one spending a couple of hundred million dollars a year, and one which had been increasing its spending substantially, and yet Treasury staff simply took whatever the Bank told them it planned to spend for the following few years and stuck it in the formal fiscal forecasts without apparently raising any questions at all. Not exactly a fearsome (or effective) watchdog.

One reason I’d asked about those HYEFU numbers is because I knew that the Bank had lodged its egregious bid for the following five years with the (acting) Secretary to the Treasury on 13 September. I’d assumed that between then and when the HYEFU fiscal numbers were finalised (27 November) somebody at Treasury would have (a) looked even a little closely at the Funding Agreement bid, and b) raised some red flags about a bid that used as a baseline spending levels so far ABOVE what was allowed in the still-current Funding Agreement, and c) perhaps (optimistically) gone back and looked at how the 24/25 budget had been set relative to those Funding Agreement limits. They might even have alerted the Minister.

And that was the gist of the second limb of my request. In fact, it appears that none of this happened. Treasury never actually responds directly to that bit of the request but (a) does not say it is withholding anything, and b) notes that two documents are in scope and soon to be released (as part of the long-delayed pro-active release of papers relating to the 2025 Budget). The first of those is “T2025/3027 Aide Memoire: Preliminary assessment of the Reserve Bank of New Zealand’s funding proposal for the 2025-30 Five Year Funding Agreement”, and is dated 13 February. That appears to be the first time anyone at The Treasury had put anything in writing on an egregious funding bid they’d received five months earlier (from an agency with a chief executive who was well known for his aggression etc). It seems almost unbelievable, but there it is.

I am loathe to accuse Treasury officials of playing fast and loose with the Official Information Act, but in this case it is hard to believe I have been given a straight answer. Why? Because we have the written words of the former Governor to his senior leadership team, cc’ed to the Board chair and deputy chair. This, from 5 February, is from the Bank’s 11 June release

You don’t tell people to “cease and desist negotiating with various Treasury Officials” if there had been no discussions and negotiations. And you don’t pull down your initial bid (see second to last line) if there’d been no prior reaction from Treasury or the Minister, and it is hard to believe that Treasury had put nothing at all in writing prior to then (and had not let the Minister know there was a looming issue).

But I guess it is plausible that no one much at Treasury had turned their minds to Funding Agreement issues for months after receiving the bid. Which doesn’t reflect well on them at all.

The fourth limb of my request covered any material of substance relating to Funding Agreement negotiations from 1 December until the date the Cabinet paper was lodged (1 April as it turns out). I’d narrowed the timeframe because I’d assumed there’d have been initial reactions earlier (after 13 September) but what I was interested in was the stuff that had led to the blow-up with the Governor). Treasury does not directly respond to this limb of my request either, but lists another paper soon to be released, dated 13 March (ie post Orr), a formal Treasury Report on funding agreement issues. And that is all. If Treasury’s responses are at least approximately truthful, it seems that they were very late in getting onto this set of issues (either future Funding Agreement bid, with its artificially high purported baseline, or the 24/25 budget itself, which had blasted through the then Funding Agreement limits).

If so, one might – just possibly, and in a mood of charity – be marginally less unsympathetic to the Governor. Perhaps he really thought he was going to get away with a) the massive 2024/25 overspend, and b) the artificial baseline for the new Funding Agreement. After all, it seems there had been no Treasury challenge or scrutiny at all, and his numbers even seemed to have found their way into the official fiscal forecasts with no challenge or question. It is astonishing that for months – dating all the way back to that draft SPE – there seems to have been no serious pushback, from the Minister or from Treasury. What sort of job were top Treasury officials doing in monitoring this powerful Crown agency? Not much of one it appears. Deputy Secretaries (both now out of the jobs they held then) are recorded as having turned up for chats at Board meetings, but what of it if excess of this sort was allowed to roll on for months unchallenged?

It is always possible that the way my OIA requests were drafted means something of significance has been able to be withheld as not quite falling within the specific scope of those requests. It is certainly difficult – nay impossible – to believe that there was nothing at all prior to 13 February. But it certainly doesn’t look as though Treasury was doing its job in a way citizens, let alone the Minister, might have reasonably expected that they would be.

That 24 February meeting again

After The Treasury released their file note of that 24 February meeting between the Reserve Bank, Treasury, and the Minister of Finance (full copy here) a few people got in touch directly about a couple of aspects of what was written there, and what I’d made of it.

The file note indicated at one point that in the middle of the Funding Agreement discussion “The Governor left the meeting”. A couple of charitable people (not typically Orr allies) suggested that perhaps I was overinterpreting things to suggest that he’d walked out. I think they were pretty readily convinced that this was a very unlikely interpretation (in a meeting of which the Minister of Finance had already said that it had been clear to her that “emotions were running high”).

Former academic and now consultant economist Martin Lally then sent me this rather neat piece. Some of the non-economists among you might roll your eyes and suggest ‘that’s economists for you”, but I thought it was a nice example of the use of the technique to help discipline thinking.

Seems like a great opportunity to apply Bayesian analysis. 

The hypothesis (H) is that Orr stormed out of this meeting.  Your background data concerns his type of behaviour on other occasions.  Suppose this alone leads you to the view that H has a 10% chance of being true.  This is likely to be too low.  The odds on H being true are then at least 1/9. 

The next piece of evidence is the anonymous information about Orr’s behaviour at the meeting.  I sense that you think this evidence would be much more likely to arise if H were true than if H were not true; maybe five times as likely?  So, the Likelihood ratio for this evidence is 5.  The odds on H being true now rise from 1/9 to 5/9. 

The next piece of evidence is the meeting at Treasury a few days before the meeting in question here, on the same funding issue, after which Quigley apologised on Orr’s behalf for Orr’s behaviour.  Since it was on the same contentious topic, this evidence seems much more likely to arise if H were true than if H were not true; maybe five times as likely.  So, the Likelihood ratio for this evidence is 5.  The odds on H being true now rise from 5/9 to 25/9. 

The last piece of evidence is the minutes of the meeting in question, which reveal that Orr left during discussion about the funding issue, which Orr had very strong feelings on.  If H were true, this evidence or something even more damning would be almost certain to arise because the minute taker would be most unlikely not to have recorded that Orr left.  Say a prob of 0.95.  If H were not true, the minutes could still have recorded him leaving at the time he did but in that case it would have to be due to quite extraordinary information he had just received that demanded his immediate departure from a discussion he would otherwise have strongly desired to be present for.  It could be news of his house burning down or a serious injury to a loved one.  These things happen but it would be extremely unlikely to have occurred in the 45 minute time slot in question.  So, if H were not true, the prob of his departure from the meeting at this time is close to zero.  Suppose events like his house burning down etc happen once every 6 months, so 1/180 chance of it happening on that day and, if on that day, 1/10 of it happening during the 45 minute duration of the meeting on that day, so 1/1,800 of it happening during the meeting, which is 0.0005.  So, the Likelihood ratio for this evidence is about 0.95/0.0005 = 1900.  The odds on H being true now rise from 25/9 to 47,500/9, so the prob that H is true is now 47,500/(47,500 + 9) = 0.9998, i.e., 99.98%. 

So, with all this evidence, it is virtually certain that Orr stormed out of the meeting. This nicely illustrates the power of Bayesian analysis.

A few other people got in touch about the earlier part of the meeting, on banking regulation and competition matters. This part of the meeting was attended by Reserve Bank Deputy Governor Christian Hawkesby, whose day job at the time was financial stability, supervisory and regulatory etc issues (and he left the meeting when his item ended, thus missing the – apparent – fireworks).

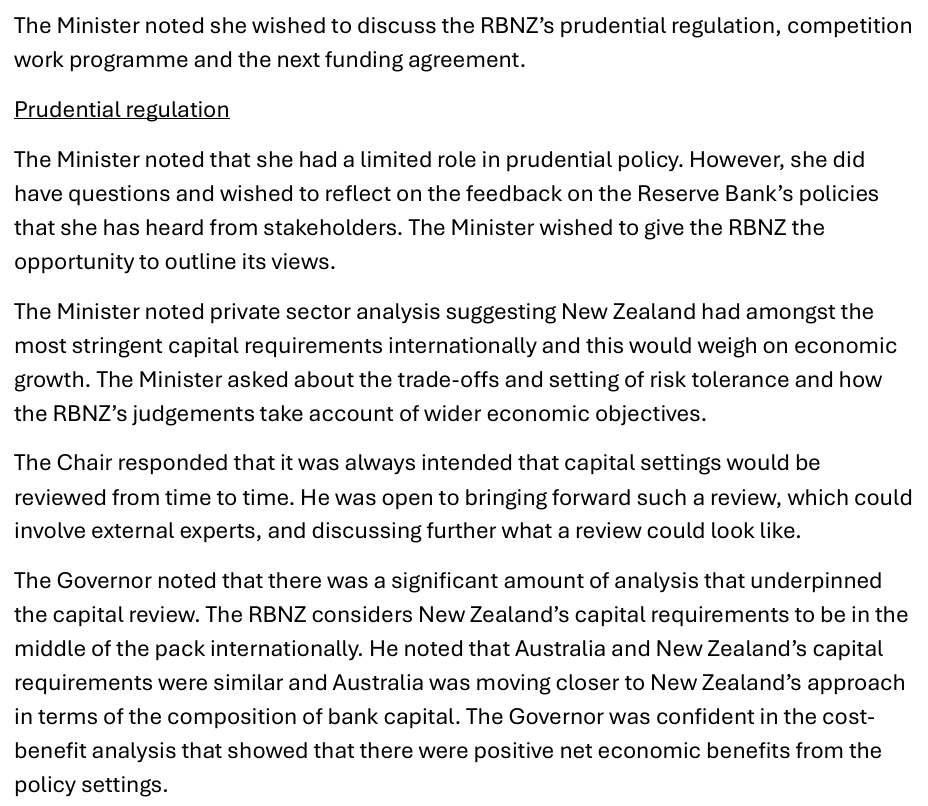
The relevant bit of the file note was this

It is pretty clear from that that the Minister of Finance wanted a review. Perhaps she didn’t say it directly, but it is the clear implication of what is recorded in those first two paragraphs, and Quigley clearly recognised it as such, noting (folllowing the Minister’s remarks) that he “was open to bringing forward such a review….and discussing further what a review could look like”.

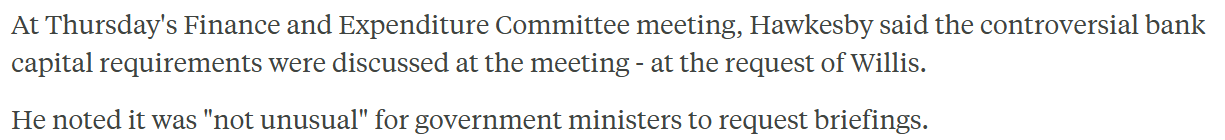
Why raise this now? Because Hawkesby is currently the temporary Governor, and supposed in some circles to be keen on getting the permanent job. Even if he doesn’t want to be permanent Governor, he is the deputy chief executive of a major government agency and a statutory appointee to the Monetary Policy Committee. Those who got in touch earlier this week reminded me that a few months ago (8 May) Hawkesby had been asked at Parliament’s Finance and Expenditure Committee about this meeting. Radio New Zealand’s report is here.

The first part of Hawkesby’s remarks seem fine

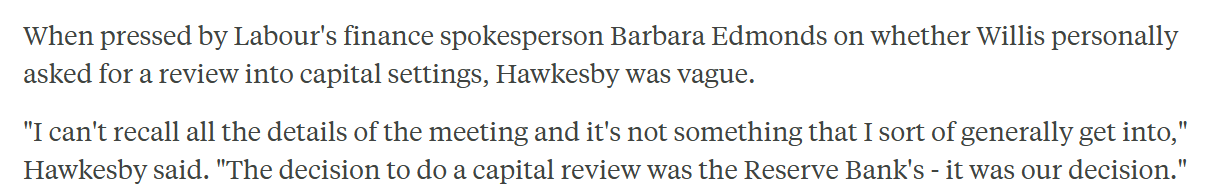
But then FEC was told this

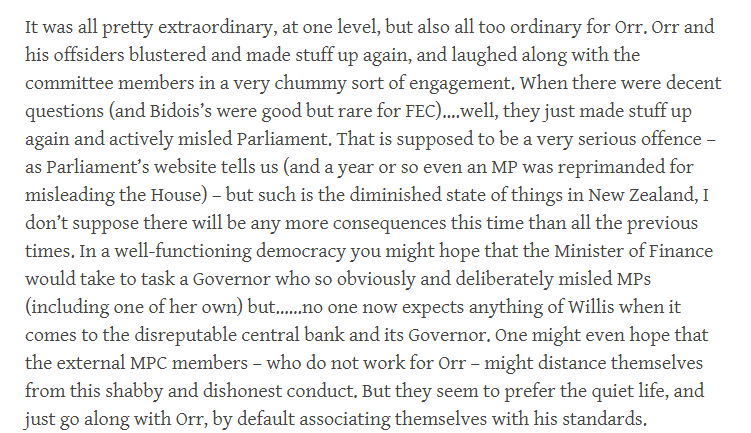
The meeting had been only two months previously, it had been only a 45 minute meeting (of which he was only there for half an hour or so), on matters he had direct responsibility for, and the meeting itself has to have stuck in his mind given the role it seems to have played, within days, in the Governor’s departure. What’s more, surely you’d normally expect that coming out of a meeting like that there’d have been some sort of file note (especially when his boss and the board chair had appeared to be singing from different song sheets) or even an email to his direct reports in that area, and if he was really in doubt as to what went on I guess he could have asked Treasury for their file note. And yet we are supposed to believe that whether or not the Minister had requested (or only strongly implied) that a review should be undertaken was “not something that I sort of generally get into”. It reads a lot like misleading Parliament – in much the same way Orr had done repeatedly, often with Hawkesby in the room.

To be clear, I’m sure he is quite correct that “the decision to do a capital review was the Reserve Bank’s”, but in much the same way that the Governor’s decision to resign was a “personal decision” – at one level it was, but he was clearly prevailed on, pressured to go. Under the law as it stands Willis couldn’t directly compel the Bank to undertake such a review, but it will have been the less bad choice for them (she could have changed the legislation or commissioned her own review for example). And it was also a time – the end of March when the final decision to do a capital setting review was announced – where it probably will have suited Quigley and Hawkesby not to have been difficult; Quigley wanted his medical school, and Hawkesby may well have wanted to be made permanent Governor. The review would not have happened when it did without the Minister’s lead.

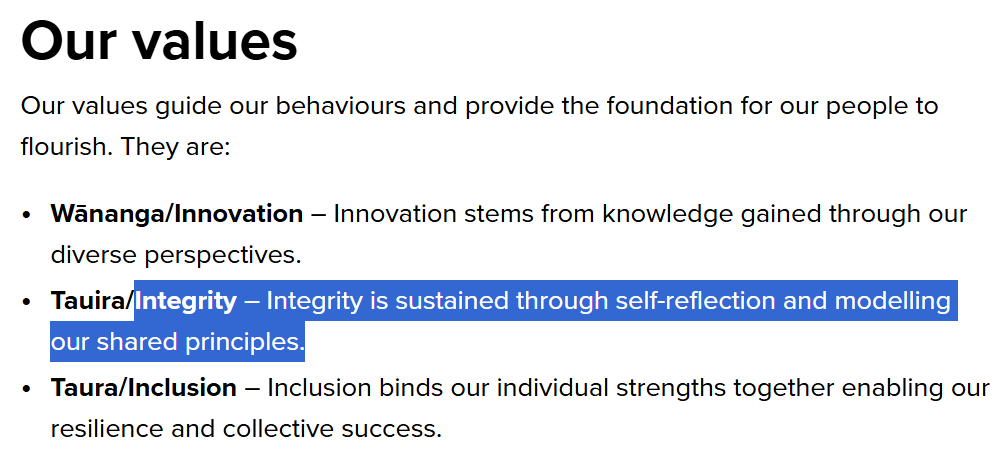
(And, to be clear, I don’t think that is a problem. As I’ve noted repeatedly, I think the law should be changed so that big picture prudential policy choices are made by ministers, with the Bank acting as (a) expert advisers, and b) implementing agents. I don’t think the Minister’s involvement here is inappropriate – whatever one’s view of actual capital settings – but really senior officials should not be misleading Parliament. And when they do, and when they sit silent while their bosses mislead Parliament, they really should not be serious contenders for high and very powerful office. Misleading Parliament is supposed to be a serious matter, and if MPs seem to have given up bothering over much (except when it suits), the rest of us should still insist on higher standards of integrity.

It is, in addition, supposedly one of the Reserve Bank’s own values

But perhaps those are just words. The actions at the top certainly haven’t aligning with the words for some time.

Orr, Quigley, and Willis: 31 July edition

I have other things to do with my time, but feel some obligation to my source – the (anonymous and unknown to me) person who seemed to take quite a personal risk, to help reopen the Orr departure story – to keep on making sense of developments, inch by inch as it often seems, in this story.

There are three things I wanted to comment on this morning, all prompted by yesterday’s release by Treasury of their internal file note of the 24 February meeting between the Bank, Treasury, and Willis.

  • an article in The Post this morning,
  • one on the Herald website last night, with further comments from Quigley, and
  • my own reflections on yesterday’s release.

The relevant section of the record of that 45 minute meeting is this

Post article

The Post article really isn’t worth linking to (you can no doubt find it if you want). It is noteworthy only for this extraordinary line:

“Hawkesby, and then Orr, left the 45-minute meeting shortly before it ended, but there is no evidence in the minutes that the discussion became heated.”

Which seems to ignore several things. First, the Deputy Governor is recorded as having left the meeting, but at the end of his item. He was the Bank’s senior manager responsible for financial stability and the first two items on the agenda (Prudential Regulation and Competition) were in his bailiwick, and he left when that discussion ended. He wasn’t a member of the Bank’s Board, and the Funding Agreement is between the Board and the Minister. He also wouldn’t have been one of the senior managers (CFOs and the like) providing technical/operational support on budgetary details.

Orr, by contrast, left in the middle of the Funding Agreement item. Moreover, Nicola Willis has confirmed (it is in the Herald piece – see below) that Orr “chose to leave the meeting early” (and she is likely to be phrasing that diplomatically). And Willis told Heather du Plessis-Allan several days ago that it was clear to her that emotions were running high in that meeting.

And, finally, I guess the journalist has never been a bureaucrat. Writing down that the Governor “expressed frustration” about the Bank/Treasury relationship is likely to be a very muted and diplomatic rendering of the summary of the actual words and the tone around them. An official writing up such meetings isn’t, say, a Bob Woodward looking to capture all the drama for publication. (Note that my source last week suggested that the account was still not muted enough for Quigley, who reportedly was very upset to learn that such a record existed at all and allegedly rang Treasury to complain in no uncertain terms – an OIA may shed light on whether that was so.)

It might not be going too far to suggest that a more accurate account might involve words like “stormed out”, walking out not only on the Minister but on his own board chair, having (so the account suggests) sought to undermine his own board by making a direct play to the Minister for his personal view of what the Funding Agreement level should be (recall that Orr was both a board member, and working under board delegations of authority etc on management and budgetary issues).
Herald article

The Herald article appears to have been prompted by yesterday’s Treasury release (they, like me, have had long running OIAs in with Treasury – theirs longer than mine – and this release was a partial response, while we wait for the rest of the issues to be addressed). But the article also contains quite a few comments from Quigley, apparently from an interview Tibshraeny did with him late last week after the Minister’s meeting with the Reserve Bank Board, as well as a fresh report that Willis had again expressed confidence in Quigley.

(It is to Treasury’s credit that they released both last week’s Quigley email (apologising for Orr’s conduct at a meeting with Treasury) and this file note. Either Rennie has decided that Treasury wants to be no part of the ongoing coverup and attempts to mislead by the Bank/Quigley, or (perhaps in addition) he has been encouraged in that direction by Willis, who seems to want more openness (and to be frustrated with the Board). If there are gag orders that Quigley signed the Bank up to they won’t bind Treasury.)

The article is behind a paywall so I’m not going to quote at length.

On Quigley, Willis is quoted as suggesting he is the right person for the job right now, including selecting a nominee for new Governor, and that at this “critical juncture” what matters is stability. It is pretty unbelievable, and utterly unconvincing stuff. The Bank is an embattled mess, and much of the mess is of Quigley’s own doing – spinning out the obstruction and misleading for months, overseeing the budget-busting spend up last year (that they’d not told the Minister about), and of course the appointment and reappointment of Orr in the first place. How can anyone have any confidence in a nominee out of a process led by Quigley? How could a good potential new Governor have any confidence in his chair? How can staff have any confidence in the board chair, when he is responsible for actively misleading them (as well as us) and for the big dislocations, layoffs etc the place is now going through? Rebuilding from here really demands a clean slate, led by someone commanding widespread respect and confidence.

But if the Minister’s line was perhaps predictable (you have to back someone until you fire them I suppose), Quigley’s comments were more interesting. He noted that the rest of the board had (we are told) expressed confidence in him – which perhaps isn’t unduly surprising as all but Spencer (new appointment) are as implicated as him in the events of recent months – but then must have been asked about the OIA obstructionism.

There has never ever been any sign that Quigley has any sort of commitment to openness or public scrutiny. The obstructionism, and reported quotes along the lines that he didn’t think the public had a right or need to know what went on (with one of the most powerful controversial officials in New Zealand), has to some extent been par for the course. But you did get the sense here that he feels the ground slipping away from under him. Most likely his staff gave him the sort of advice he wanted to hear on the law, but even if he got cover to hide there so far, it was a spectacularly bad call – in governance and public trust terms – to (a) be as obstructive as they’ve been (multiple OIAs have never been responded to directly, let alone completely) and b) to actively mislead the public repeatedly. No law required that. And any adviser who advised him that it was a good course of action shouldn’t be working there much longer.

In his final comments, Quigley seems to grudgingly acknowledge that his role included providing feedback to the Governor on his performance, but it is – on his telling – none of our business. He acts as if either Orr was some low level employee (say a junior accountant at Waikato University), or as if his responsibility is to the Bank and its management, rather than to the Minister and the public. And again, nothing warrants the calculated deceit of recent months, or attempts to substitute his judgement for the spirit and principles of the Official Information Act.

My thoughts prompted by yesterday’s Treasury release

A couple of additional thoughts occurred to me after reflecting further on yesterday’s release. The first (and probably not central) was this from their covering note.

The Bank had submitted its Funding Agreement bid to Treasury back in September 2024. Can it really only have been in early February that officials did even a preliminary assessment of what levels of spending they thought the Bank should be allowed? It seems odd, and yet in the papers the Bank released on 11 June in which an Orr email records him stating on 14 February “We have not heard from Treasury as to a preferred number”. It seems puzzling, but perhaps some of the outstanding OIAs will eventually shed some light.

But the bigger question is what we make of this episode of Orr’s extraordinary behaviour on Monday afternoon 24 February, in light of all else we know (or suspect). It must have been critical because, as I highlighted yesterday drawing from the Bank’s own 11 June selective release, within 24 hours various members of senior management were (a) aware an exit was a possibility, and b) putting together a working group to manage things at the Bank’s end. But, equally, it cannot have been final and determinative – except perhaps that Quigley and Willis may have concluded to themselves that Orr had to go (after undermining his board chair in front of the Minister and then walking out of the meeting, all only a couple of days after Quigley had had to apologise to Treasury for Orr’s conduct, because Orr himself wouldn’t).

I had a useful exchange yesterday afternoon with someone whose views always force me to think. This person argued that Orr’s behaviour in that meeting was tantamount to a resignation. I certainly agree that, on what we know, it was the sort of behaviour that shouldn’t be tolerated from any public sector chief executive, and there was no obvious way back from it (especially given the track record of Orr’s behavioural issues in the job, recent and past). But did Orr see it that way? Over the years he’d held the job he’d already gotten away with so much, and perhaps it is unlikely (to say the least) that it was the first time his undisciplined side had been on display in a Minister of Finance’s office. The Bank’s statement of 11 June may at one level have been accurate (if misleading)

“Distress” sounds like a reasonable description for what we now know of the 20 and 24 February meetings, and “necessary working relationships” must have been quite deeply impaired – but not just with the Board, but with the Minister and Treasury too – and Orr did finally come to a decision to go.

But there is still no sign that on 24 February he thought he was resigning, and every indication that his decision to go came only after quite a bit of pressure applied in the following few days. After all, recall my source’s story (and that person’s general account of what went on seems to have been vindicated so far where independent details have since emerged) that it wasn’t until 27 February that Quigley sent that Statement of Concerns to Orr, seeking a response (this wasn’t a quiet private chat, but something formal in writing by email), which seems to have been the final straw [UPDATE: Quigley probably also needed to get the rest of the Board squared away, who hadn’t witnessed Monday’s debacle]. And even then, if perhaps Orr wasn’t fighting too hard – it was clear he was going to lose the funding battle, and it clearly was close to his heart, and surely even he must have had some self-knowledge reflecting on his conduct over the past week – it was still a case of “senior counsel” called in by each side to negotiate, not a simple resort to standard resignation provisions in Orr’s contract, and getting him out of the office the very hour the resignation was announced.

Both Orr and Quigley will have known that it was most unlikely the Minister would sack him, and so he held leverage – I’ll go, but only if you sign up to a gag order (the limits of which, or the authority for which – did the Minister really not know? – are still not clear). He was clearly pushed, and there is no way by this point that the Board chair can have had confidence in Orr continuing (despite what he claimed on 5 March). Perhaps it was one thing to pledge that precise details of behaviour would not be disclosed, except as required by law (you can’t contract out of the OIA), but Quigley and Willis should have insisted on something like “After discussions initiated by the Board, the Governor has chosen to resign and left office today”. Except that – unless we see clear evidence to the contrary – perhaps they then preferred that we not know (and no one else on the Board seems to have objected). And so the obstructionism and repeated active deception of the public began, and continues to this day.

The Treasury file note of the 24 February meeting

A few minutes ago I had this email from The Treasury

This is the document that my source last week claimed Quigley went ballistic about when he learned of its existence,

Taking Treasury’s caveats re the views expressed by anyone including Orr, can we conclude at least from the description of events that Orr walked out of the meeting in the middle of the Funding Agreement discussion, having undercut his own governing board’s views in front of the minister and his chair?

Oh, and credit to The Treasury for releasing this in full now.

UPDATE: I just wanted to put the record out there rather than write much commentary. However, I’ve had a few people get in touch suggesting that the record is capable of a more benign (for Orr) interpretation, noting that the Deputy Governor, Christian Hawkesby is also shown as having left the meeting part way through. However, I don’t think this alternative interpretation is correct. Hawkesby is shown leaving at a natural break point, where the banking regulation and supervision discussion ends. His main role at the Bank at the time was responsibility for those functions. He was not on the Board and Funding Agreement issues were mainly a matter for the Board and chief executive (supported by other DCEs on the financial management side of the Bank), so it seems quite natural that he would have left at that point.

By contrast, Orr is recorded as having highlighted differences between himself (and management more generally) and his board, and then to have sounded off at Treasury (“expressed frustration” is an official’s record, not that of a fly on the wall biographer, so likely to be understated), and then is recorded as leaving the meeting while the Funding Agreement discussion is still going on. It has also been suggested that perhaps the Minister had simply asked Quigley to stay behind. That interpretation seems unlikely given that the Treasury team (and MoF’s office advisers) were all still there (a later one-on-one might not be a surprise, but Treasury officials would not have been there to record that).

In the end, we do not know with certainty, although either Willis or Quigley (or Orr for that matter) could give us straight answers (so could Rennie, but it isn’t his role to).

Rereading the material

As I outlined in my post on Friday, it now seems that much the most likely explanation for the sudden no-notice departure of the Governor of the Reserve Bank is that he was ousted; not formally sacked by the Minister of Finance (as she might well have had grounds to do, but it could have got messy), but – having left himself vulnerable by his record of questionable conduct – engineered out by the Bank’s Board (more specifically its chair), almost certainly with the foreknowledge and acquiescence, and possibly the direct encouragement, of the Minister of Finance herself. If so, well done them on that count. But the subsequent and ongoing active deception of the public (and of the Bank’s own staff), and the apparent defiance of the Official Information Act, is simply inexcusable, and it would seem that the Board (especially the chair), the Minister, and the temporary Governor share responsibility, to one degree or another, for that.

Looking back now, it is puzzling that this hadn’t seemed the most likely explanation pretty much ever since Orr left on 5 March, or at very least since the Bank’s big release, and statement, on 11 June. I guess that is what comes of treating words out of the mouth of the Bank, and especially its chair, as having any degree of trustworthiness whatsoever. More fool me.

Recall that the first set of statements and Board chair comments on 5 March was clearly intended to lead us to believe there was nothing to see here. It was just a “personal decision”, there were no conduct, performance or policy issues at the heart of it, and really….when a big job was done, why wouldn’t an impressive leader take the opportunity to hand over the reigns. I won’t repeat all the things Quigley said that day, but this statement, issued by the Bank mid-afternoon on 5 March, after many questions had already arisen, rather captures the tone

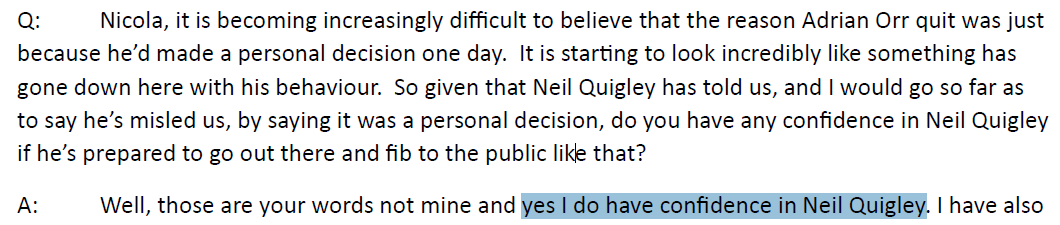
Cincinnatus and all that. A couple of hours later he told the hastily-called press conference that he personally had still had confidence in Orr, and answered a direct question thus

The Bank spent the next three months blocking OIA requests and refusing to add anything, until the great reveal on 11 June. There was a set of carefully selected papers released (while avoiding anything on whole chunks of what must have gone on) and an official statement, presumably owned by both the Board and the temporary Governor and probably carefully vetted by lawyers (including ones for Orr?).

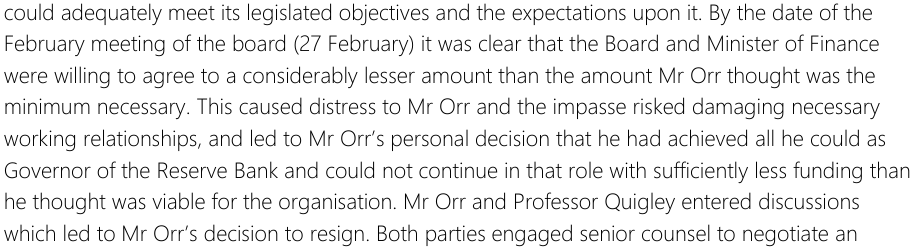
Having abandoned the 5 March story, this was all now carefully crafted to focus us on (a) that board meeting on 27 February, and b) a policy difference between the Board and the Governor which Orr, somewhat oddly, took so strongly to heart (“caused distress”) that he felt it would be better for him to simply go.

If you go back and read my posts when this release came out, you’ll see I never really bought the framing (which the Bank must have been pleased that much of the media followed) that this was a dispute over the Funding Agreement per se. As I have noted several times, many or most public service chief executives have suffered budgetary disappointment in the last couple of years, and none of them stormed off with no notice. But we were still clearly supposed to believe that whatever really happened, Orr had real agency (it was he who decided to leave, of his own accord, with no notice).

But there were still plenty of clues that it wasn’t the real story. There was, for example, the strident and repeated insistence by the Minister of Finance that it was all nothing to do with her, she knew little or nothing etc (even though she was the person responsible for the Governor, and to whom any resignation actually had to be addressed).

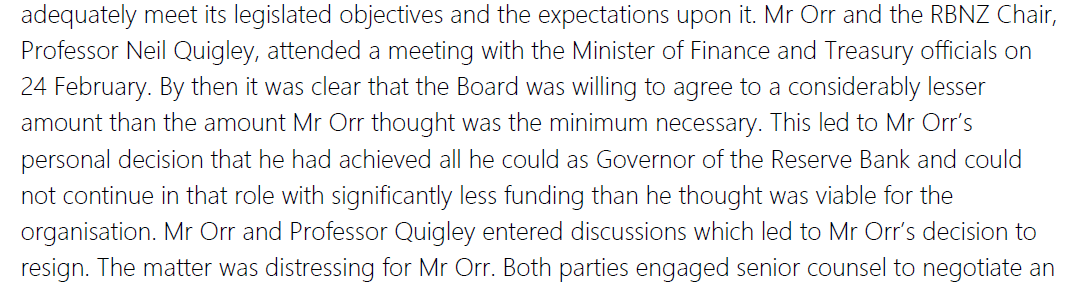
And there was the near-final version of the 11 June statement, which they’d sent out in error to OIA requesters shortly before the official general release time.

The shift from one (near-final) to the other (final) being clearly designed to remove any references to a meeting with the Minister and Treasury, and to draw attention away from them generally (and the earlier wording wasn’t going to have got into a near-final document of this magnitude by accident or the whims and failings of a junior staffer).

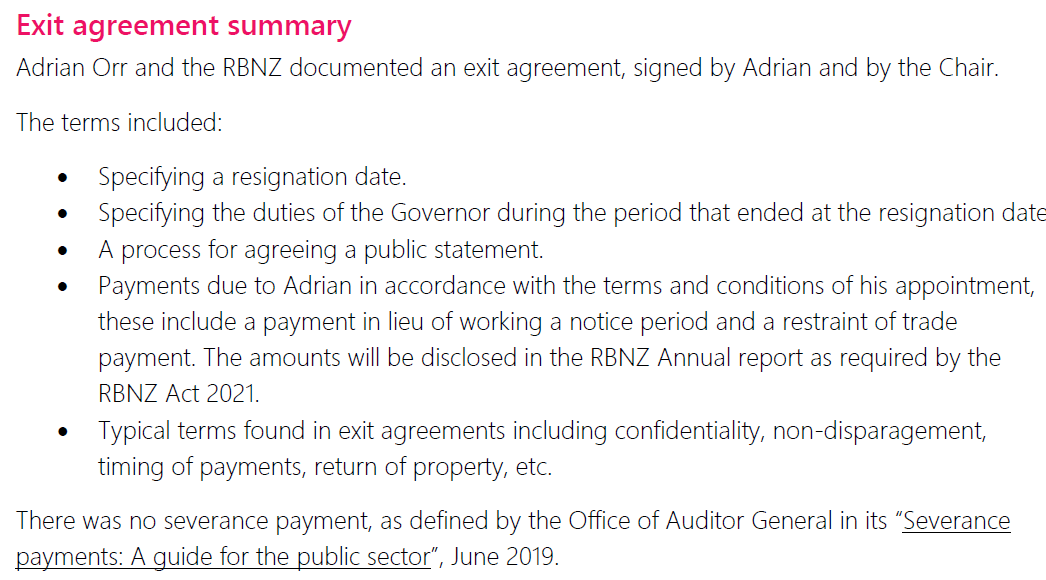
And there was the exit agreement itself, and negotiations being undertaken by “senior counsel” – interesting that that term was explicitly chosen by the Bank when they could easily just have used “lawyers” – for both sides. For an amicable departure, surely a quick chat with HR could have sorted out the application of Orr’s standard resignation terms, and any waivers of notice that might be sought or granted? And there was this summary (from the 11 June statement) of the exit agreement

Who typically has negotiated exit agreements? People being forced out (but not specifically fired). And Quigley has repeatedly referred to legal constraints on his ability to explain things, which can really only have arisen from the terms of this exit agreement, where Orr will have had some negotiating leverage (and were it all Cincinnatus-like there would be nothing for either side to want to hide – and no reason for Orr to have left the office the very day of the resignation, and yet be paid for several more weeks).

But things hung in limbo – hamstrung in part by the Bank’s obstructiveness over various OIA requests now having been appealed to the Ombudsman – until the account provided to me by someone who was clearly fairly close to events, and reported here. That person’s account was that (a) Orr’s behaviour had been very bad in a meeting with The Treasury on the Funding Agreement issues and then on 24 February in a meeting with both Treasury and the Minister of Finance, and that b) on the 27th, the day of the Bank’s board meeting, Quigley had emailed Orr a Statement of Concerns raising conduct issues stretching back several years and inviting a response. So the story went, at that point Orr decided to resign.

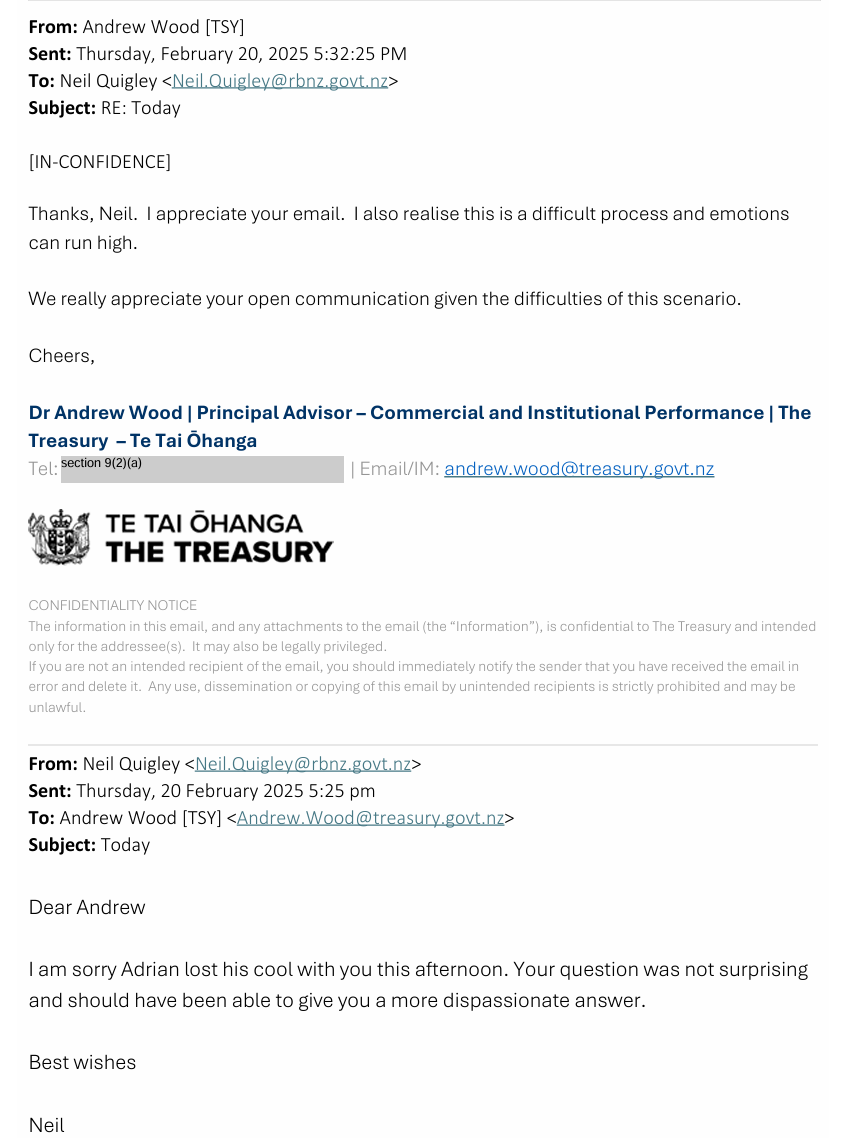
Treasury then disclosed an email sent by Quigley to a mid-level Treasury staffer after a meeting on 20 February apologising to that person that Orr had lost his cool in the meeting, in response to a perfectly reasonable question that Quigley acknowledged should have been anticipated and for which Bank management should have had a dispassionate answer. At a time when negotiations on the Bank’s future five-year funding were approaching climax Orr, in the presence of his chair, had (a) lost it with Treasury, and b) neither then nor later been willing to apologise himself (why otherwise was Quigley doing so, and not even on Orr’s behalf).

Then the Minister confirmed that “emotions were running high” in that meeting on 24 February too (around Funding Agreement disputes), while seeming to confirm that “employment negotiations” had been underway between Orr and the board in the days leading up to the resignation. And while the Bank has refused any further comment, they have also not chosen to deny any of it (including the alleged 27 February email, for which there is still no independent confirmation of its existence). Had there been no substance to any of this, they’d surely have owed it to both Orr and Quigley to (however briefly and tersely) set the record straight. They seem now to be hoping to wait out the Ombudsman.

And so the “engineered” ousting came to seem like the best working hypothesis for what had gone on. Perhaps on the spur of the moment, or perhaps lying in wait for some months, Orr’s conduct seems to have crossed the line (again – perhaps he’d been warned) and they had the leverage to get him to go. No doubt he was disheartened that he was going to lose the Funding Agreement fight and perhaps that made him readier than otherwise to go without much of a fight?

Anyway, having got to that point I decided to go back and reread that package of material the Bank had put out on 11 June, and see if any of it read differently in light of what we had since come to know.

I’d assumed – I think understandably enough – that the Bank’s Board meeting of Thursday 27 February might have been decisive. The 11 June statement seemed to point that way, as did my source’s report that the (apparently) decisive email had been sent to Orr on 27 February, and the fact that the only indications of advice to Treasury or the Minister had dated from then (I’ve now asked the Ombudsman to review the extensive withholdings in that release).

And perhaps there was some sort of final showdown then and a final decision made (to call in the “senior counsel” to negotiate exit terms). But the Bank’s information release pack included this (read from the bottom)

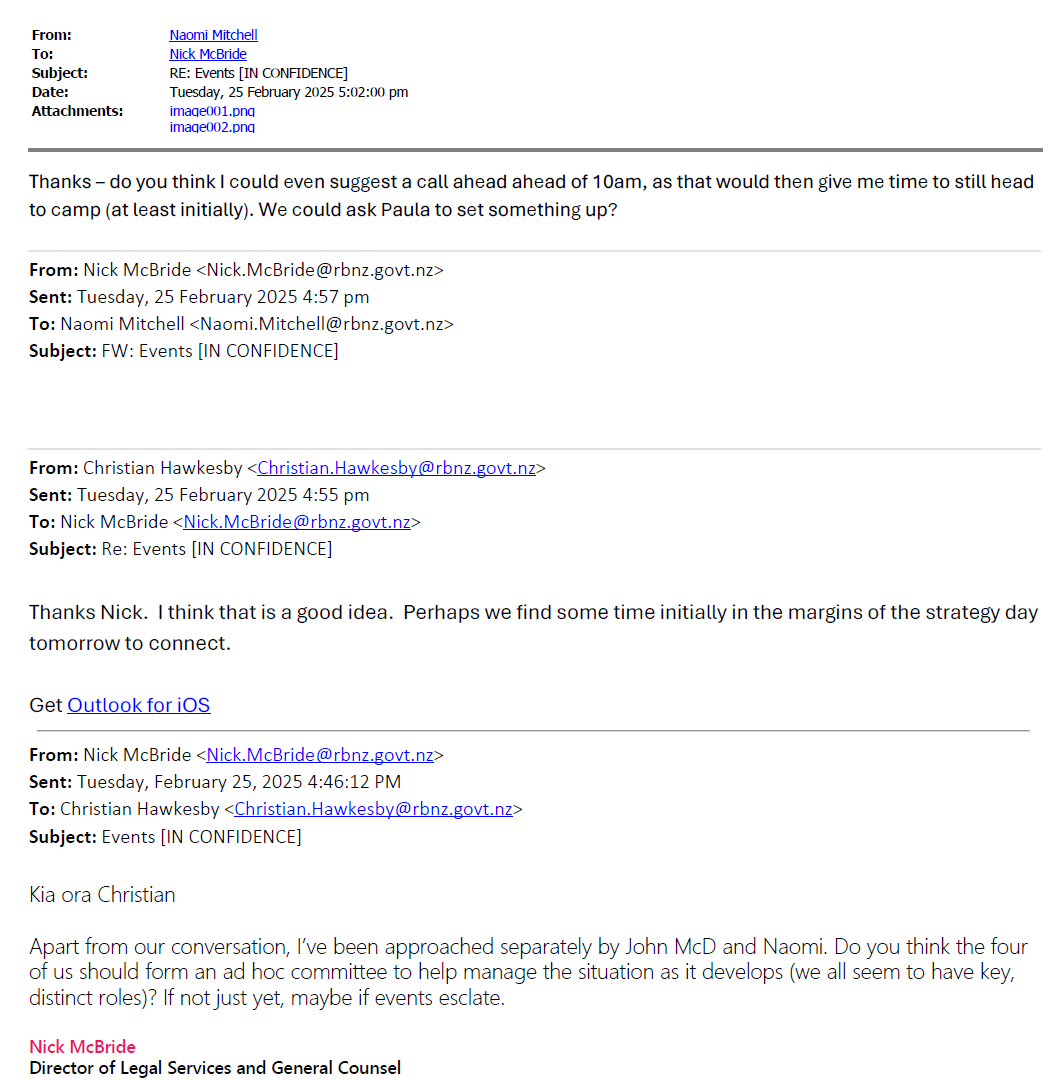
Who are the characters here? Hawkesby was (then) the Deputy Governor, McBride was (and is) the Bank’s General Counsel (but a third tier person, under an Assistant Governor who was also a lawyer), John McDermott was the Assistant Governor responsible for HR matters, and Naomi Mitchell was the (third tier) Director of Communications. And before 4:46pm on Tuesday 25 February [UPDATE: as it turns out, less than 24 hours after Quigley got out of that 24 Feb meeting] they already knew that something was afoot and agreed to the establishment of an “ad hoc committee” to help manage the situation. It seems clear that decisions had not yet been made (“If not just yet, maybe if events escalate.”) but this was two days before the Board meeting and just the day after that (“emotions were running high”) meeting with the Minister and Treasury. Was it Orr who told this group of his managers, or was it Quigley (Board chair)? We don’t know, but whatever had already unfolded – a serious risk of the Governor going presumably – was material enough for a range of key managers, not all direct reports to the CE, to have been brought into the picture (apparently separately/individually) this early. (This group then meets or exchanges messages over the remaining period pre and post resignation that was covered by the release.)

We don’t know what events were on the Statement of Concerns list Quigley is claimed to have sent Orr. As I noted last week, it isn’t as if he would have been short of examples just from material that had found its way into the public domain by then. But I wondered what other events might have been salient for the Minister and/or the Board.

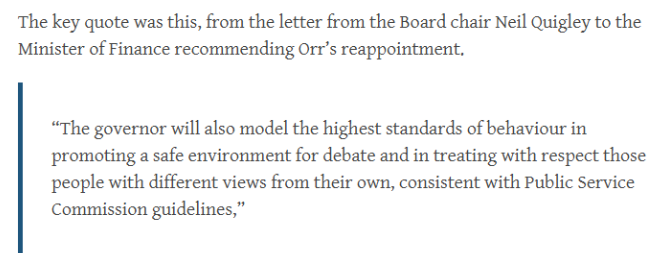
I noted last week that when (with spectacularly poor judgement) Quigley and the Board had recommended Orr’s reappointment in late 2022 there had been this.

When this was first released some time back it seemed like little more than make-believe stuff. But perhaps it had been the basis for conversations with Orr at the time? After all, the Board (and Quigley) can hardly have been oblivious to the long list of concerns and issues, so perhaps there was some attempt at insistence on better behaviour in a second term?

If so, it didn’t go well. Even externally, Orr continued to mislead (or worse) FEC and media. As the Minister noted last week, she’d last year passed a complaint about Orr’s behaviour to a New Zealand Initiative employee to the board to address.

And we learned just yesterday that it seems that the Bank never told the Minister of Finance that they were going to budget in 24/25 for operational spending far in excess of even what Grant Robertson had allowed them for that year (although, to be clear, responsibility for that must lie with both Quigley – as board chair – and Orr, as CEO). Perhaps when Willis finally realised she had been had, she was (and I would hope she was) really annoyed and perhaps, as regards Orr, steel entered her soul (belatedly) at that point. Of itself, not quite dismissal material perhaps (after all, Quigley was responsible too and she’d just reappointed him) but enough to put you on watch.

Who knows if Orr’s conduct at and after those two February meetings was itself enough to lay him open to pressure to go. As yet, we have only quite sanitised comments on how those meetings went down (including the Orr/Wood exchange, where they were both trying to settle things down after the event) but it was repeated behaviour from a very senior figure within days, at a time when the Bank really need to maintain good relationships. If it wasn’t enough in itself, there was other stuff going on at the very same time.

Going back to that period, I realised that it had been on the very morning of 20 February – the day of that unapologetic blow up at Treasury – that Orr had been telling demonstrable untruths again to Parliament’s Finance and Expenditure Committee (at his appearance on the February Monetary Policy Statement). I wrote about it in a post on 21 February, “Orr at it again”. I went back through that post the other day, and listened again to the video of the hearing to check that I’d heard and recorded things correctly. It was, as it turned out, probably his last public appearance as Governor and I counted five outright misrepresentations (two I would go so far as to call worse than that), all on matters where the Governor was either well aware of the truth, or should reasonably have been expected to have known the truth. (And just to be clear that responsibility is shared: at the table with him were his deputy responsible for monetary policy, Karen Silk, and the chief economist Paul Conway. In the row behind Orr you can see Christian Hawkesby, MPC member and Deputy Governor, Naomi Mitchell (Director of Communications), and one of the external MPC members. Not one of them made any attempt to correct Orr on any of these points.

The most egregious of Orr’s claims that day – although not necessarily particularly consequential, just the easiest to unambiguously refute – was the (repeated) claim that the Reserve Bank had been among the first central banks to tighten (when inflation took off a few years previously) and the new, and even more out of step with reality, claim that the Reserve Bank had then been among the first central banks to cut rates.

In my post that day I observed

As I noted, he’d done this sort of thing often enough before, but when I checked my records it seemed to have been the first time since the change of government that he’d been caught in such flagrant attempts to mislead a parliamentary committee (there are plenty documented in the years previously). Had he been less bad for a while, or had I not been paying so much attention? I ended up raising this episode with the Finance and Expenditure Committee the following week (before Orr’s resignation), in time with full chapter and verse – as I recall, I thought it was pointless to raise it with Willis, but the FEC chair was new.

I don’t suppose this particular episode of egregious behaviour – which his senior team seemed to walk by – had anything particularly to do with Orr’s ouster, underway just a few days later. My point is only that if for whatever reason you think what we know of those two private meetings mightn’t really have been serious enough to use as a lever to oust Orr, there was plenty more behaviour that could have, this one visible to anyone who chose to watch/read. If Willis helped engineer the ousting of the Governor, she did us – and standards of public life in New Zealand – a service.

None of which – not NDAs, not nothing – warrants participation in active and repeated, ongoing now, attempts to mislead New Zealanders and obstruct scrutiny. And if – as the Minister suggests – she isn’t overly happy with how the Bank is now handing things, the Board chair serves at her pleasure. If she wants different standards, a good way to signal that would be to replace the chair, now.

If something like what I’ve hypothesised here is what happened back in late February and early March, perhaps the Board and Minister should have insisted on a terse statement along the lines of “Following discussions initiated by the Board, the Governor has resigned and has left office today” and said nothing more that day. It wouldn’t have stopped the questions, or the OIAs. Perhaps it wouldn’t have proved tenable, or Orr wouldn’t have agreed. But there is just no excuse for the deliberate repeated ongoing effort to mislead us.

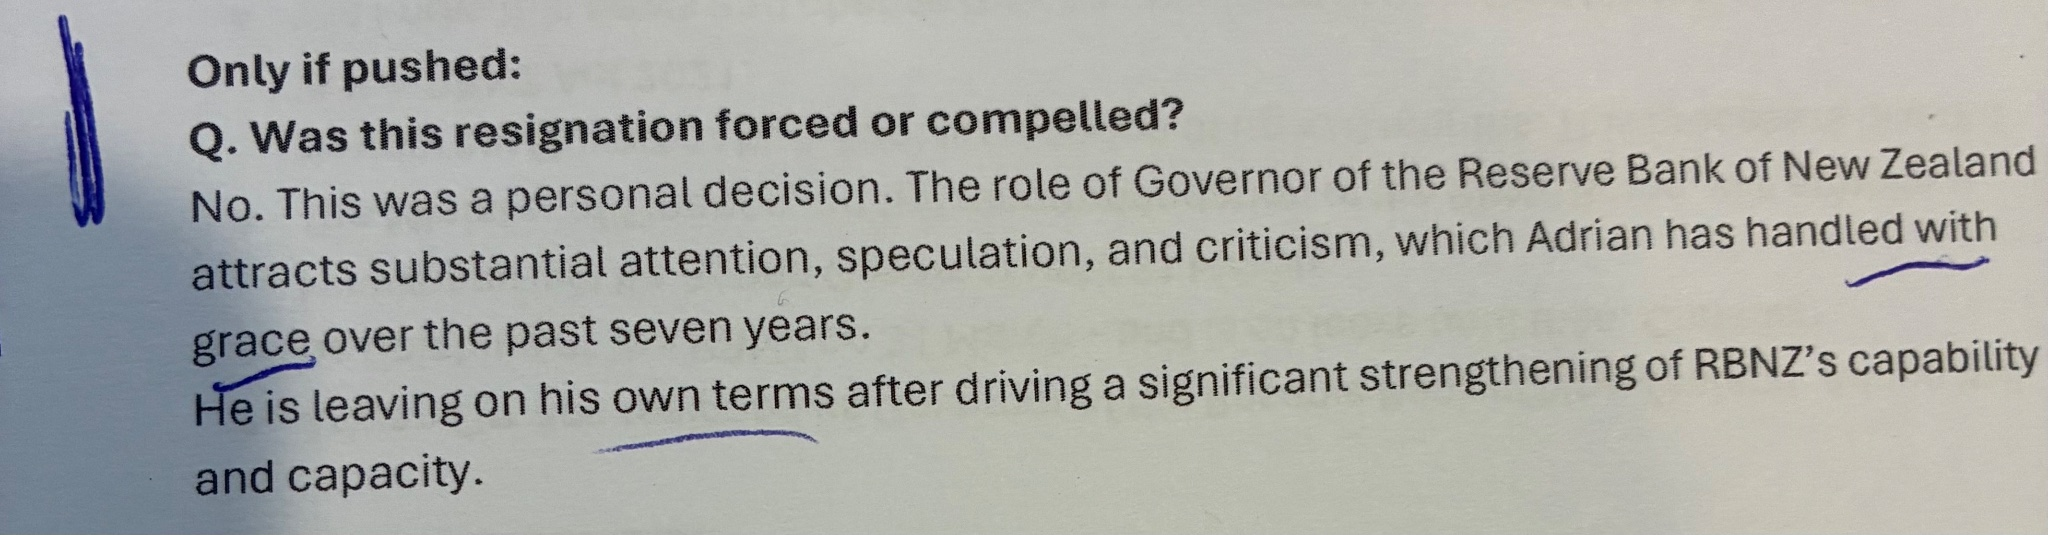
Or their staff. This was from the package of Q&As sent out by Naomi Mitchell to the entire Bank second and third tier mamagement group first thing in the morning the day after the resignation, for use with staff.

Yeah right.

They didn’t tell her

One of the mysteries of the months leading up to (what appears now to have been) Orr’s ousting as Governor, was how the Minister of Finance – apparently very focused last year on spending restraint in central government agencies, especially ones that weren’t really public facing – had let Orr and Quigley (and the rest of the Board) away with 2024/25 operating expenses so far in excess (23 per cent in excess) of the level of spending for that year allowed under the amended Funding Agreement Grant Robertson had signed off shortly before the 2023 election.

The Minister can’t directly control the Bank’s annual budget but the law requires the Bank to produce a Statement of Performance Expectations each year, to be published before the start of each financial year. The Act sets out what has to be included in a Statement of Performance Expectations (SPE)

The Act specifically provides for the Minister of Finance to be provided with the opportunity to comment on a draft of that SPE, and explicitly provides 15 working days for her to provide comments (drawing, no doubt, on advice from The Treasury which, again under the Act, has been made formally the Minister’s monitor of the Reserve Bank). The Minister also has the power of the bully pulpit: she could openly call out excess, if she knew about it.

In a post a couple of weeks ago I revealed that neither the Minister nor the Treasury had raised any concerns about Orr and the Board proposing to run levels of spending miles in excess of allowed levels, at a time when pretty much every other central government agency was facing actual cuts, and when the Minister had already (in early April 2024) reminded the Bank of her “fiscal sustainability programme” in her letter of expectation, in the context of approaching negotiations over a future Funding Agreement.

And when she mentioned reprioritising “before seeking any additional funding” you’d have to suppose that the benchmark against which “additional” would be understood by her was the level of funding her predecessor had approved only eight months earlier.

It seemed pretty surprising, to put it politely, that neither the Minister nor Treasury had raised any concerns when they were offered the opportunity to comment on the draft SPE. But I’d realised that although I had their comments, I didn’t have the draft they were reacting (or not) to. So on 3 July I asked for that and it turned up this morning, in full and unredacted (so should presumably have been supplied weeks ago).

And it turns out that the answer to my question as to why neither the Minister nor The Treasury had raised any concerns about the planned spending levels is that….the Bank just didn’t tell them.

You might find that surprising. I certainly did. You might wonder if I have misread something. But here is chapter and verse from the short covering memo to the Minister of Finance, dated 30 April 2024, and signed out by Simone Robbers, at the time one of Orr’s many deputy chief executives (formally, Assistant Governor, Strategy, Engagement and Sustainability).

It isn’t clear what about the “current operating environment” meant they thought they shouldn’t tell the Minister how much they were planning to spend. But whatever their reason, they didn’t. She didn’t know.

My view of the Minister of Finance has been revised up quite a bit in recent days, and this discovery is one of the reasons.

If you were being uncharitable you might think that the Minister should have asked, or the political advisers in her office should have asked, or – when it was sent on to them – The Treasury should have asked. And perhaps they should. But in the Minister’s case it was her first year in office, she had sent that Letter of Expectation just a few weeks previously, and she’d have had absolutely no prior reason to suspect that the Bank was going to adopt a budget with operating spending levels so far in excess of the elevated levels for 2024/25 Grant Robertson had approved the previous year. Who would? After all, this was Mr “cool your jets” Orr himself, who talked of fiscal restraint assisting in getting inflation down.

Perhaps The Treasury is more culpable, but I expect that the people reviewing the draft Statement of Performance Expectations were by nature more focused on the structures of documents and getting the Bank to jump through the right bureaucratic hoops. They won’t have been fiscal focused, and again….why would they suspect the Bank would just decide to blow out spending way beyond approved levels?

In bureaucrat land, “no surprises” is a big thing. But the Bank (Orr and Quigley) seem to have consciously chosen to run a great big surprise for the Minister of Finance. Perhaps the budgets were not quite locked down on 30 April (probably they weren’t) but if they’d been planning to stay within Funding Agreement limits it would have been easy enough to have included a brief mention that the forecast statement of comprehensive revenue and expense would include in-scope spending at levels consistent with the Funding Agreement allowance for 2024/25. Or, if they really thought they somehow had authority to spend so far beyond, they could at least have given the Minister an indicative range, and explained how it related to the (then) Funding Agreement limits. Instead, they seem to have told her nothing.

It is really quite extraordinary.

And one is left wondering when the Minister finally realised she’d been had. Perhaps it wasn’t until Treasury, many months later, got inside the Bank’s opening bid for the 2025-30 Funding Agreement, ran the numbers and realised that while the Bank purported to be offering up modest cuts, in fact they were from a level far above what had been allowed in the previous Funding Agreement; an inflated, bloated, baseline of their extravagant creation.

(It is always possible there is some other advice somewhere in which all this was pointed out early to the Minister, but if such advice exists the Bank has had every reason to helpfully – to them – disclose it. For the moment, it seems very unlikely that they were straightforward with her.)

And if the ousting of Orr has been accomplished, the board chair Neil Quigley remains in office. It wasn’t his signature on that 30 April advice to the Minister, but it was his Board that approved both the egregious 24/25 budget and the equally egregious 2025-30 Funding Agreement bid. Useful as he may have been to the Minister in late February and early March, there is no way he should still be in office.

The Bank purports to pride itself on integrity

But there has been little or none on display through any of this.

(By way of curiosity: I don’t usually pay much attention to which countries my readers come from, but I have noticed in the last few days quite an upsurge – from a vanishingly small base – in views from the Cook Islands. Perhaps some Wellington public servants need to find some lighter reading for their winter holidays, or is the former Governor now a quiet reader? Who knows.)

UPDATE (30/7):

Just for the record and future reference, here is the link to the comments Treasury and the Minister did make on the draft Statement of Performance Expectations and here is the Bank’s covering note (see above) when they sent the Minister the draft on 30 April 2024.

Two sets of Willis comments, and a plausible story

In the last day or so I’ve seen or heard two sets of comments from the Minister of Finance on the Orr/Quigley/Reserve Bank/Treasury/Willis – and it is now about all of them – business.

The first, that I want to deal with only briefly, was in The Post this morning under the heading “Willis dismay with RBNZ” (online here).

The journalist was obviously a bit of an Orr fan, as this article is the second time in two days The Post has talked of Orr’s “reputation for being charming”. No doubt he could and did turn it on when he chose, but not, surely, ever to anyone who ever challenged or disagreed with him (that included – very evidently – Nicola Willis when on occasion as Opposition finance spokesperson she asked Orr a slightly uncomfortable question at FEC hearings).

Much of what is in the article was also covered in my post yesterday. So I wanted to mention only this snippet

I guess she’d have looked a bit silly to have objected, but it is good to see her explicitly welcoming that Treasury release. On the second bit of that extract, it refers to the meeting on 24 February involving Quigley, Orr, Hawkesby, and senior Treasury people as well as the Minister herself. It is good to know that Treasury is considering releasing the minute of the meeting given that my request for it was lodged with them more than a month ago (as part of a larger request on Funding Agreement issues) but I presume there have been other requests, including since Tuesday when I reported the claim by my source that Quigley had been apoplectic and had complained to Treasury when he’d learned that such a minute existed. Again, it is good to know the Minister thinks Treasury should comply with the law, and we will look forward to the release.

The Minister’s more substantive comments were in an interview yesterday afternoon with Heather du Plessis-Allan. The audio is here and my transcript is here

Transcript of Heather du Plessis interview with Nicola Willis on 24 July 2025

Why do I bother doing the transcript?  Partly for future reference and partly as a way of focusing my mind on all the lines Willis used in answering (and avoiding answering) questions.   There were things I hadn’t really noticed when I listened live. 

What do we learn from the interview?  First that “emotions were running high” (the no doubt carefully chosen phrase for something like Adrian Orr losing his cool again) in the 24 February meeting she attended (although apparently there was no swearing) and she’d “heard reports” of the 20 February meeting between the Bank and Treasury where again “emotions ran high”.    About, of all things, the Funding Agreement…..as if almost every single agency in Wellington hadn’t already been facing budget cuts (and it presumably wasn’t as if anyone was proposing cutting out the role of Governor). 

Recall that Quigley email to Treasury (reproduced in yesterday’s post).  The Governor was so ill-disciplined and out of control that in response to what Quigley recognised was a perfectly reasonable question from a mid-level Treasury official, Orr lost it, and then wouldn’t apologise, either immediately or after the meeting (instead Quigley was left to go and make his own apologies for Adrian).  And sufficiently out of control, and unresponsive to what must have been feedback from his own chair, that the “losing his cool”, “emotions running high” behaviour was on display again several days later to a meeting with the Minister himself.      In a normal employee such behaviour, especially repeated and without prompt and full apology, might of itself almost have been grounds for dismissal.  (Humans make mistakes, even public sector chief executives, sometimes provoked, sometimes not.  But when made aware you apologise, ensure it won’t happen again, or….you really aren’t fit to lead people and public organisations.)

Willis was again at pains to suggest that the employment of the Governor was nothing to do with her, but purely something for the Reserve Bank Board.   As a matter of law it simply isn’t so (I ran through the relevant provisions a couple of days ago), and the fact that it isn’t so has nothing to do –  contrary to the Minister’s claim –  with the “independence” of the Reserve Bank.  There are plenty of roles and powers for the Minister of Finance in the Reserve Bank Act (as well as appointing and dismissing and receiving resignations from the Governor).  For example, the Reserve Bank has what is known as “operational autonomy” on monetary policy, but they work to an inflation target by the Minister.   In banking supervision and crisis management, some powers are exercised wholly by the Bank while others need ministerial approval.  The Minister is directly party to the Funding Agreement. Parliament could have chosen to give the Minister no role re the Governor’s appointment etc but it never has (fortunately or there would be no political accountability at all).  The Minister is responsible for the Governor, while the Board –  whose chair is removable at will be the Minister – monitors etc the Governor, accountable to her. 

At the very end of the interview Willis is asked

So far, we’ve had two quite different stories from Quigley, neither of which appears to be the truth. First, back on 5 March we were assured it was just “a personal decision”, with denials of any policy or conduct or similar issues being involved. We were intended to believe the man was tired, the job was done, and it was time to do something else. Then on 11 June, the Bank’s carefully crafted statement told us a new story. In this story there had indeed been material differences between the Board and the Governor over what they could live with in the next Funding Agreement. This we were told

“caused distress to Mr Orr and the impasse risked damaging necessary working relationships, and led to Mr Orr’s personal decision [ that term again] that he had achieved all he could as Governor of the Reserve Bank and could not continue in that role with sufficiently less funding than he thought was viable for the organisation”.

This time we were clearly intended to believe that the “personal decision” [which in a narrow and formal sense it was] was really just about (strongly felt) policy and resourcing differences.

Had you read either or both of those accounts, you might have believed (and were clearly supposed to) that the very first the Minister of Finance would have known that anything so dramatic was afoot was when on 27 February Quigley advised Iain Rennie of something briefly (words were withheld), who in turn advised the Minister briefly (words were withheld), who responded (puzzlingly) with nothing much more than something like “thanks for the update”.

But look at what the Minister said yesterday afternoon

You don’t usually have “employment discussions” when someone comes to you and says their job is done and they are going to leave, and even when the CE comes out of a Board discussion on funding and concludes it might be better for everyone if he, the CE, moves on. There will have been standard resignation and notice provisions in the Governor’s contract. Easy enough to have HR put those in train.

“Employment discussions” between the Governor and the Board preceding his resignation strongly suggest that serious issues were raised by the Board with the Governor, serious enough to have potential implications for whether they would be happy for him to continue as Governor. Which would be consistent with my source’s story, from the post on Tuesday:

And you can well understand why it might trigger Orr’s resignation, since getting to such a point clearly indicated a serious loss of confidence in the Governor, and quite possibly an almost irreparable breakdown of trust.

The Minister continues to state that she does not know the contents of the exit agreement then negotiated between expensive senior lawyers for both the Board and Orr. Which, on her account of what went on, should be simply extraordinary, because (a) the resignation would have to come to her, and b) she is the only guardian of the public interest here, and the one who would, in principle, have to account to Parliament for any deals done. She and her office, or at very least Treasury, should have been all over any terms – especially around non-disclosure matters – Quigley was agreeing with her (outgoing) Governor. And yet we must presumably take her at her word that she was not, and the OIAed paper trail suggests no Treasury advice on such matters at all.

One of the things that has puzzled me in the last few weeks is the absence of advice from either Treasury or the Board chair (or Board generally) to the Minister on the looming resignation. Last month I had an OIA response from Treasury (briefly written up and linked to at the end of this post), with almost nothing there (not withheld, just nothing there).

And then on 30 June I had a response to an OIA to the Bank. The relevant bit of the request was this

and their response was

Which isn’t exactly what you’d have expected if the initial Quigley spin had been anything like the truth or if the 11 June statement had been anything like the full story.

But it would make a lot more sense if the Minister of Finance had been the one initiating/prompting the actions that led directly to Orr’s “personal decision” to resign.

There is no direct evidence of that at this point. But something along those lines might explain rather a lot.

Let’s go back to that meeting on 24 February between the Minister, the top Bank people, and (presumably) very senior Treasury people. If Adrian had again lost his cool (“emotions were running high”) what do we supposed happened afterwards? Every one just put it down to a bad day and moved on? It doesn’t seem very likely. After all, we know that a few days previously Quigley had taken the initiative to apologise for Orr’s conduct to a mid-level Treasury staffer. Was he likely to have done much less after his CE blew up in a meeting with the Minister herself? As for the Minister, surely she’d have debriefed with her political advisers – “can you believe that?” sort of thing (of course, they probably could because Orr’s behaviour and style has been well known, including to the Minister, for years), or “we have to do something about him/something has to be done about him”. Perhaps she had a chat with Iain Rennie, or perhaps people in her office passed on the reports of the Treasury meeting a few days previously?

It doesn’t seem at all impossible – and I’m not sure any OIA so far (that I’ve heard of) would have captured this – that she, or someone senior acting on her behalf, got hold of Quigley (keeping Rennie in the loop) and indicated that Orr’s performance was intolerable, and that he really had to go. The specific incidents may have been like a heaven-sent opportunity, with Orr laying himself open, by having openly embarrassed the Board chair and Board as a whole, at a very delicate time re the Funding Agreement, by egregious behaviour – unacceptable in any official – in front of the two groups (MInister and Treasury) they needed to avoid antagonising to try to get a decent settlement. Perhaps Quigley intimated that he had a long list of behavioural issues re Orr that he’d built up over several years, and reckoned the Board would probably have had enongh too. Both sides will have known that only the Minister could fire the Governor – and she wouldn’t want to have done that directly – but it will have become apparent that they had leverage and could put pressure on, that would be likely to result in his “personal decision” to leave. And if something like that is what went on, maybe the Minister – conscious of maintaining semi-plausible deniability – indicated that whatever it took should be done, and don’t bother me with (or show me) the details.

It fits the facts we have better than any other story so far, including in making sense of why Willis has been so over the top in her disavowal of any involvement and insisting (contrary to the law) that hiring and firing etc Governors was just a matter for the Board, nothing to do with her. And, of course, of why there was an exit agreement – negotiated by senior counsel at all – with gag orders etc: they wouldn’t have been willing, probably, to directly fire Orr (judicial review has always been a risk too), and so he could insist on (some) terms, but it isn’t clear that Quigley isn’t using them to protect himself too.

If the truth is anything like this – another layer behind the story from my source, which itself so far looks sound – perhaps where they (the Minister in particular) misjudged was in putting too much confidence in Quigley to deal with the public side of things (if so, pretty inexcusable on her part as Quigley has no track record of being a deft and effective or trustworthy communicator). Both after 11 June and again yesterday the Minister has indicated that she isn’t satisfied with what the Board has said (or not said). From the interview yesterday

“I have also however previously shared my disappointment at the way information on this matter has been shared with New Zealanders. Today I had a prescheduled meeting with the entire Board of the Reserve Bank and at that meeting I sought to convey to everyone present that I was disappointed with the way that this matter had been handled given the ongoing public speculation because it is in New Zealand’s interest that the Reserve Bank maintains its reputation at all times and I think with better handling we would not still be having these interviews and this discussion.‘

Well, indeed, but what did you expect? They never seem to have had lines that they’d effectively stress-tested (to stand up for more than a few minutes – 5 March – or hours – 11 June) and hadn’t even got the process straight (witness what the Bank has already confirmed that the Minister was putting pressure on on the afternoon of 5 March for Quigley to do a press conference he didn’t really want to do – something surely that should have been sorted out in advance and properly rehearsed). The Minister clearly now isn’t that happy with the ongoing OIA obstructionism, and she is quite right to suggest that better handling of this whole thing would have seen it as yesterday’s story, one for next history of the RB, pretty quickly, perhaps within a week or two of 5 March. Instead, here we are, months on, and so many unanswered questions, including from the Minister herself, and with the Ombudsman all over the issues.

The Minister’s main message yesterday – to various outlets – was that she still had confidence in Neil Quigley as Board chair (which since she could have fired him at will and hasn’t we pretty well knew that by revealed preference).

But why? Some speculate that perhaps it has to do with the medical school – might not be a good look, might undermine confidence, to toss Quigley out the very week the government had granted him his controversial new medical school.

But it might also be that in some sense in fact she is deeply grateful to Neil Quigley, for having done the dirty work, possibly at her own bidding, and got rid of Orr. Perhaps somehow that compensates for the Clouseau-like performance over months since – only worse than Clouseau because it is quite clear that Quigley wasn’t just bad at this stuff, but that he had, and has, consciously and repeatedly set out to mislead New Zealanders.

In one of those quotes a little way back up the page the Minister rightly stressed the importance of the reputation of a central bank. The Bank knows it too. This is from their recent Statement of Performance Expectations

But the problem is that we (and they) are starting from things as they are, and it is hard to see anyone with even a modicum of interest could have any trust at all in our powerful independent central bank and those who run it. There have been repeated policy failures, bloated budgets (and spending last year left to run wild while the Minister did nothing to rein in the Governor or Board chair), lies to Parliament, lies to the Treasury (see final bit of this post on Quigley and the first MPC), pretty weak (or worse) policy communications, top tiers of management currently held by people simply not fit for the job, a Governor with serious behavioural issues left unchecked for years, and now all this……the active misleading, the cover-up, and (from the chair) the sheer disdain for any sense of public accountability or interest. Oh, and a Minister who did nothing about any of this for her first year or so in office – about conduct, about fiscal excesses, about replacing the chair, about filling board vacancies, about simply insisting on something a lot closer to both excellence and openness.

And that is among the reason why Quigley really should resign or be sacked now. There will be a new Governor later in the year. That person will need to sweep clean. But how can we have any initial confidence in a new Governor – whether some stray Canadian hand-me-down not likely ever to make Governor at home, as speculated in the press the other day, or whoever – when that person has been selected by a process led by the same chap who delivered us Orr in the first place, who championed his reappointment despite all failings being evident by then, who presided over that budget-blowing (well Funding Agreement blowing) last year, and who can’t or won’t even give a straight story – somewhat diplomatic as it might have to be – about the early departure of the last Governor.

Anyway, some questions to ask. Perhaps the story here is also nothing like the truth. But it is beyond time for the truth to be told and a clean breast to be made of things. And if what happened is something like what is suggested here, it should mean some very serious questions indeed for the Minister of Finance as regards her part in misleading New Zealanders. Not exactly a sound basis for trust.

(UPDATE: To be clear, if the Minister did engineer Orr’s departure along these sorts of lines, then well done her – found an opportunity and seized it – and there should be no harrumphing about affronts to central bank independence. But the subsequent spin, misdirection etc would still raise very real questions.)

Bad behaviour: an update

Since I published the post on Tuesday, reporting what an anonymous (currently or recently former) insider had told me about events around the Adrian Orr resignation, what new we’ve heard or learned seems (to say the least) not inconsistent with the substance of that person’s story.

As it happened, the one concrete revelation may almost have come about by accident. In my post on Tuesday I’d written that Board chair Neil Quigley had contacted Treasury quite agitated about a Treasury record of a meeting between senior Bank and Treasury people on 21 February. It was only yesterday I reread my source and realised I’d made a mistake, and that bit of the story related to the meeting between the Bank, Treasury, and Minister of Finance on 24 February. But by then the Herald had asked Treasury about the earlier meeting (which was actually on the 20th). Treasury could, fairly easily, have stonewalled, but in fact they confirmed that Neil Quigley had emailed one of their staff after the meeting in respect of the Governor’s behaviour at that meeting. Today they have released that email exchange.

We don’t know how bad it got but…..things have to have been pretty bad for the Board chair to have taken that initiative (and notice the Treasury official’s “emotions can run high” – about funding debates, among normal disciplined people???), presumably having failed to persuade his chief executive, the Governor, that he himself needed to apologise. So, if we don’t yet know a lot with certainty about the 24 February meeting, and the record thereof, we now definitely know that Orr’s conduct was a significant issue just days before the exit agreement negotiations started, following the Board meeting on the 27th.

We don’t know with certainty that Quigley emailed Orr on the 27th attaching a statement of behavioural/conduct issues going back several years, and asking for a response, but…..the Reserve Bank refuses to deny the existence of such a document (there are multiple OIAs from people trying to smoke it out). Even allowing for their dogmatic “we’ve said all we are saying or legally can say” line, if the story was simply untrue, and had no basis in fact, surely it would be in both Orr’s and Quigley’s interests to have it denied in no uncertain terms (free opportunity to tar me as well I guess). The obstructiveness is, almost certainly, pure choice. And despite their claims otherwise, there has been no evidence of good faith dealing with legitimate public interest at almost any time since 5 March, when Quigley began his unsuccessful attempt to mislead us into believing that it was just “a personal decision’ [as in one sense it was: Orr is a person, he did decide] of someone who was tired or thought a big job had now been done and it was just time for a change.

The Reserve Bank and its Board appear to be attempting to hide behind claims that there are legal restrictions on what they can say, including in response to OIAs (and remember that any request for information can in technical terms be considered an Official Information Act request whether it is answered on the spot or months later). This was a line they have also fed to the Minister who said the other day:

First, consider the Official Information Act itself.

There are conclusive reasons for withholding information. But they relate to national security, diplomacy, and one the Bank has occasionally used on me (very dubiously even then), things that if released could

What was going on around the unexpected sudden departure of the Governor just does not count.

So then we are down to section 9 which has a whole long list of other reasons why information can be withheld, all prefaced with the public interest override. It seems probable that 9(2)(a) is what they will be relying on

although whether it is Orr or Quigley, or perhaps both, they are trying to protect is perhaps open to question. For Quigley, of course, there would no case at all – embarrassment of someone who appears to have actively, deliberately, and repeatedly sought to mislead the public from his highly paid perch as chair of a government board is exceptionally unlikely to count as decent grounds.

Employees are a different matter. If some junior employee was quietly exited you’d expect 9(2)(a) to apply, in all but the most extreme circumstances (if I recall correctly I was once – possibly still – a party to such an arrangement – as manager that is, not employee). But on this occasion we are talking about the utterly unexpected no notice departure of one of the most senior, powerful, and controversial public officials. And it is also clear that the Bank – and its board chair – have already sought to obstruct understanding, transparency and accountability on repeated occasions. Not just by trying to convince us it was just “a personal decision” (tired, job done etc) but by obstructing (for months) and still OIA requests that included requests for material that cannot be any stretch of the imagination come wholly under 9(2)(a) at all (eg there are four board meetings in March – one the day the resignation was announced – where they have not even acknowledged the request for the minutes, let alone provided those minutes, even heavily redacted). They are trying to stonewall and obstruct understanding, and they should not be allowed to do so. 9(1) would give them ample grounds to release almost anything that has been requested, if they were at all interested in the public interest (in scrutiny, accountability, transparency….and little things they say they value like trust in an independent central bank). I say “almost everything”. If there really is the “Statement of Concerns” document, with its list of (alleged) behavioural/conduct issues, I don’t feel a need to see it; the fact of its existence and being sent to the Governor with a request for a response would then provide ample certainty, that what actually happened was a negotiated exit in the context of severe relationship breakdown and loss of mutual confidence, brought to a head by actual and recent serious conduct incidents.

The remaining uncertainty is around the exit agreement negotiated with Orr. As I noted weeks ago, if someone resigns because they are tired etc, you don’t need expensive lawyers to negotiate exit agreements. Tired and job done are perfectly legitimate comprehensible reasons, with nothing to hide. You might agree to waive notice, but it doesn’t take a lawyer for that.

But in this case the expensive lawyers (“senior counsel”) were brought in by both sides.

This is what the Bank told us about the agreement on 11 June

I’ve now lodged a request for a copy of the items: “a process for agreeing a public statement”, and terms around “confidentiality, non-disparagement”. These seems likely to be very process oriented (very unlikely to describe whatever bad stuff Orr is claimed to have done) so there shouldn’t be any grounds to withhold, and there is a clear public interest in such a release, given that no one has given clear answers about the parameters of what the Bank promised not to say or why (or, I guess, what Orr promised not to say). I’m not optimistic, but we’ll see.

As far as I can see (but I’m not an OIA lawyer) you can’t just contract out of the OIA by signing an NDA (with quite as broad a reach as suits two people trying to avoid transparency, scrutiny or accountability). Ombudsman guidance notes suggest as much, but who knows. It looks as though whatever the NDA provisions in the exit agreement are, they could still be overridden by the “public interest” test in section 9 (the more so perhaps now, with so much effort to mislead already, than on 5 March). Perhaps the Bank has committed not to do so unless the Ombudsman explicitly rules otherwise – which could be years away, although I’m sure that I like all who’ve appealed related issues to the Ombudsman hope he is going to give this issue some urgency. We don’t know, and it isn’t good enough to simply wave your hands and say “we’ve done all we legally can”, often without even telling us the nature of what they’ve got and have withheld, or to explain what the parameters are of what they contracted to.

If this really is what it increasingly looks like, a negotiated but pressured exit, precipitated by real behavioural/conduct issues, perhaps some limited sort of non-disclosure provisions might have been a price worth paying. But even if so the public interest – transparency, accountability and all that – had to be paramount, and any restrictions had to be very tightly limited. And non-disclosure agreements don’t give license to simply make stuff up, and actively mislead the public. If Quigley is – as he probably is – so tone-deaf and indifferent to wider public interest considerations not to see that (and to recognise that interested parties were not likely to give up easily on seeking answers), the Minister (and Treasury) should have insisted on it. And despite the Minister’s attempt to disclaim all responsibility, recall that Orr’s resignation was to her, she is the only one who could have fired him, the board chair serves at her pleasure, the board operates accountable to her, the board operates within broad parameters in her letter of expectation. If she knew nothing about it, that is on her. She, it seems, had days to ensure that the public interest was being protected, and that real accountability would be protected.

As for the Minister of Finance, what is new from her is that she says that the first she knew of that Quigley email to Treasury was yesterday. Quite possibly so in the specifics, but Treasury is formally charged by her (and funded) to act as monitor on the Reserve Bank. If they had not been keeping her abreast of conduct concerns which weren’t exactly new – and many of them in the public domain anyway – they simply weren’t doing their job.

There isn’t much else to say about the Minister beyond the scepticism I noted in yesterday’s post. Does anyone believe she didn’t know what was going on? But in reflecting on the mystery of her dogmatic insistence that it is all nothing to do her, two old lines did come to mind:

  • methinks she doth protest too much, and
  • who will rid me of this turbulent priest [or Governor]?

If somehow she did use an opportunity that Orr created by his behaviour in mid-late February to prompt Quigley and the Board to somehow engineer an exit (that list of behavioural/conduct issues Quigley seems to have had must have been tended and grown over several years) then….well done Minister. If not, well….the mysteries are still there.

As to Quigley, whether or not the Taxpayers’ Union is generally to your taste, it is hard to disagree with this concluding paragraph of their call this afternoon for Quigley to go.

UPDATE: The one other thing I meant to include here was a suggestion that some journalist might ask the Bank (or other plausible entities where people might have become aware of the relevant bits of information – eg Treasury, or MoF’s office) if they’ve launched a leak inquiry. If it is all make-believe stuff and nothing of substance was true in what my source said then…..there wasn’t a leak. If some or much or all of it was substantively true then, given the Bank’s determination to say nothing more, there was a leak from somewhere. I have no idea where the source works or worked, but there is probably a quite limited range of options, and the Bank must be one of them.

Willis and Quigley questioned

Following on from my post yesterday, two of the key players in the story (one of whom is keen to minimise her role) faced questions.

The first was the Minister of Finance who was questioned by a number of journalists before going into Parliament’s debating chamber early yesterday afternoon. The Herald posted the audio, and I’ve made a transcription here.

Comments by Nicola Willis on Adrian Orr departure Transcript of 22 July comments

Ever since the announcement of Orr’s resignation on 5 March, when he departed with no notice on the very eve of a major international conference he’d been quite ebullient about planning to host, the Minister of Finance has attempted to distance herself from it all.

At times she has asked us to believe that she didn’t actually know any more than we did about why Orr resigned (“I have always been able to speculate” was one of her early lines), which can really only be true if she let it be known to The Treasury and the board chair that she did not want to know, and if Orr himself gave no reasons in the letter of resignation which he had (by law) to have addressed to her (I have asked for a copy of that letter and of any reply). What responsible Minister of Finance, advised by the Secretary to the Treasury (in turn advised by the board chair, Quigley) that Orr had indicated he would resign would not ask (a) why, and b) seek out details of when and on what terms? A resignation with three months notice might be a very different matter (including in terms of temporary replacements etc) than leaving with no notice at all. Someone tired and wanting to retire to his farm very different from someone going following a scandal about to be revealed or an irrevocable breakdown of trust. No one can seriously believe that she didn’t know (even if what paper trail we actually have is thin at best).

The thrust of Willis’s comments yesterday was, again, that it was nothing to do with her and all a matter for the Bank’s Board. That is playing fast and loose with the law.

As a reminder, the Board does not appoint the Governor. The Minister (via Cabinet and the Governor-General) does, albeit she can only appoint someone the Board recommends. The Minister is the only person who can fire the Governor. The Board members are all appointed by the Minister and are, by law, accountable to her for the performance of their duties. Board members can only be dismissed for just cause, but the board chair is not only appointed by the Minister but can be removed by her at will (no substantive cause required although she has to consult the person before dismissing them). Resignations of a Governor are made, again by law, to the Minister of Finance. The Board does not even get to set the Governor’s pay (that is a matter for the Remuneration Authority) although it does get to set the other terms and conditions of employment (presumably including standard resignation and notice provisions in the Governor’s contract).

I noted that only the Minister could fire the Governor (and only for, statutorily identified, ‘just cause’, which doesn’t include policy disputes). The Board has a responsibility to monitor the Governor’s performance and is obliged by law to report to the Minister if they think there is just cause for the removal of the Governor (a couple of grounds – re obstructing the Board – can only be used by the Minister if there is a positive recommendation to act from the Board). They simply do not hire or fire the Governor, notwithstanding the Minister’s attempts to influence the general sense otherwise. The Governor is the Minister’s responsibility. Which is as it should be given (a) how much power Governors wield, and b) that only the Minister is accountable to Parliament and the public.

Instead we get stuff like this (which probably captures the flavour of the rest)

Or

The Board chair serves at your pleasure Minister. If the Board is not being adequately transparent with, and accountable to, New Zealanders, and you do nothing about the chair, that responsibility is on you.

And note that rather than answer the very final question about the non-disclosure agreement apparently signed with Orr – the terms of which we also don’t know – Willis simply walked away.

In an earlier post, I identified a substantial list of questions for Willis. None of them has yet been answered. All remain germane to understanding what happened, and the context for what happened.

I’m almost inclined to wonder if there is not yet one more final layer behind the story in yesterday’s post. Why is the Minister so determined to try to convince us it is all nothing to do with her, when a powerful senior official appointed by the Minister of Finance, dismissable only by her, suddenly ups and leaves with no notice (but several weeks of pay nonetheless)?

The second interview yesterday was one Heather du Plessis-Allan did with board chair Neil Quigley. You might wonder how she got him on her show, given his usual reluctance to engage with journalists on Bank matters, but apparently he wanted to be heard in defence of his medical school, and that provided the opening for questions on Reserve Bank stuff. The audio is here (starting about 4 minutes in) and my transcription is here

Transcript of Heather du Plessis interview with Neil Quigley 22 July 2025

I hadn’t previously noticed that the 2021 Reserve Bank Act now requires the Board to operate “in a manner consistent with the spirit of service to the public” (that Peter Hughes phrase that is supposed to guide all the doings of the public sector as a whole). I’d be surprised if anyone thinks that the Board’s approach since lunchtime on 5 March has shown any resemblance to being “consistent with the spirit of service to the public at all” (and probably not in the days prior when they appear to have, with the Minister’s acquiescence or not, signed up to a gag agreement with Orr to protect them, Orr, perhaps the Minister (or all three) but definitely not the public). Quigley last night was in his usual poor form, obstructive, misleading, and still defending the claim that it was just a “personal decision”.

Since it was such a good quote from Luke Malpass, it is a shame not to use it again

In this particular interview, Quigley spends some time trying to convince the interviewer that there is a material difference between saying that a departure was a “personal decision” (his actual words on 5 March) and saying that it was “for personal reasons”. It is angels-on-the-head-of-a-pin in this context.

In the interview, faced with repeated questions about claims reported in yesterday’s post, Quigley refused to say anything. He refused to say whether Orr had sworn in a meeting with Treasury on 21 February. He refused to say whether Orr had sworn at a meeting with Minister and Treasury on 24 February (he was at both meetings). He refused to say whether he’d sent an email to Orr three days later with the catalogue of conduct/behavioural issues. He attempts to justify his silence on some pretend right that Orr has to privacy, but of course by refusing to comment he confirms the essential truth of the claims. Had they been materially false, sure it was his obligation – having been directly involved or witness to all three, and as chair of the Board – to have refuted the claims in the strongest terms (quite possibly having a go at me as well, as gullible or worse) precisely to protect the former Governor. If none of this happened, surely Orr too would want us to know, lest we think worse of him than he really deserves.

Quigley’s other line was that all this was covered by “an Official Information Act request” (there were actually multiple requests)

This is simply nonsense. The Bank’s 11 June pro-active release covers nothing at all about the meetings on 21 or 24 February, nothing at all about the Board’s deliberations or communications with Orr, nothing about the substance of gag orders (or why they ever made), and nothing (of course) about the (claimed) 27 February email. In addition, the Bank has chosen simply to ignore (not to decline with specific reasons) whole categories of inquiry that made up those Official Information Act requests. What is truer is another a line he used which is basically that we said all we are going to say on 11 June, and tough luck on anything else. Which doesn’t seem like either the “spirit of service” or any sort of spirit of compliance with the Official Information Act itself. We shall one day – perhaps next year, perhaps the following one – what the Ombudsman makes of the defiance of the law.

The final aspect of Quigley’s specific comments I wanted to touch on was the convoluted round-in-circles discussion on the role of differences over the Funding Agreement played. For example

But that is actually quite telling. It goes to the point I have been making since 11 June, that this was not a departure simply over differences around the future Funding Agreement (bureaucrats face those sort of disappointments all the time, especially in the last couple of years). And, actually, the Bank has said as much. Remember this from their statement of 11 June

Even if this was true – and it seems increasingly unlikely that it was anything like the essence of the truth – it is such a severe difference of opinion, expressed presumably in ways from which there was no going back (unlike usual robust discussion among peers etc), that it was pretty clear the Governor had to go, that things just wouldn’t work in future if he stayed. That is the clear import of the Bank’s own statement, and the bit they released in error on the morning of 11 June, had tied that breakdown more closely not just to the board but to that meeting with the Minister. Of course, in some sense it was a “personal decision” (as Quigley claimed all along) but it had nothing to do with being tired, sick, or a sense of a job now completed. There is, as my source yesterday implied, a strong element of being pushed (and Quigly himself consistently refuses to shed direct light on that, despite his role supposedly being to serve the public, accountable to the Minister). It wasn’t (as Neil says) the funding discussion per se that “required” Adrian to resign – smart people will have robust arguments about resourcing and then, once settled, move on – but about things much deeper about Orr’s own conduct, quite possibly building on the list of behavioural complaints that Quigley seems to have compiled over several years.

Some straightforward answers would be nice – from the Minister, from the Board chair, perhaps even some board member who might consider breaking ranks (perhaps at the cost of their position) because they think the public deserves to know. The questions are about both substance and about process. Had we had an honest accounting months ago (at absolute latest when the Funding Agreement was signed), the issue would all be water under the bridge by now. Instead….most questions are still unanswered, and Quigley presumably hopes the Ombudsman takes his usual dilatory approach (on usual form, Quigley would be gone next July before we hear anything from the Ombudsman’s office).