Dairy: another day, another price slump

In the last 24 hours we’ve had two gloomy headline indicators out. The ANZ Commodity Price Index for July was out, with a record 11 per cent fall in the world prices of New Zealand export commodities. And the latest GDT auction saw another 10 per cent fall in whole milk powder prices, with portents of further falls to come.

Neither piece of news was that surprising on the day, but to say that is to risk underestimating the severity of what has been going on.

As the ANZ notes, the latest fall was the largest fall in the almost 30 year history of their series. What they didn’t mention is that it was the largest fall by a large margin. By an even larger margin it was the largest monthly fall in world dairy prices.
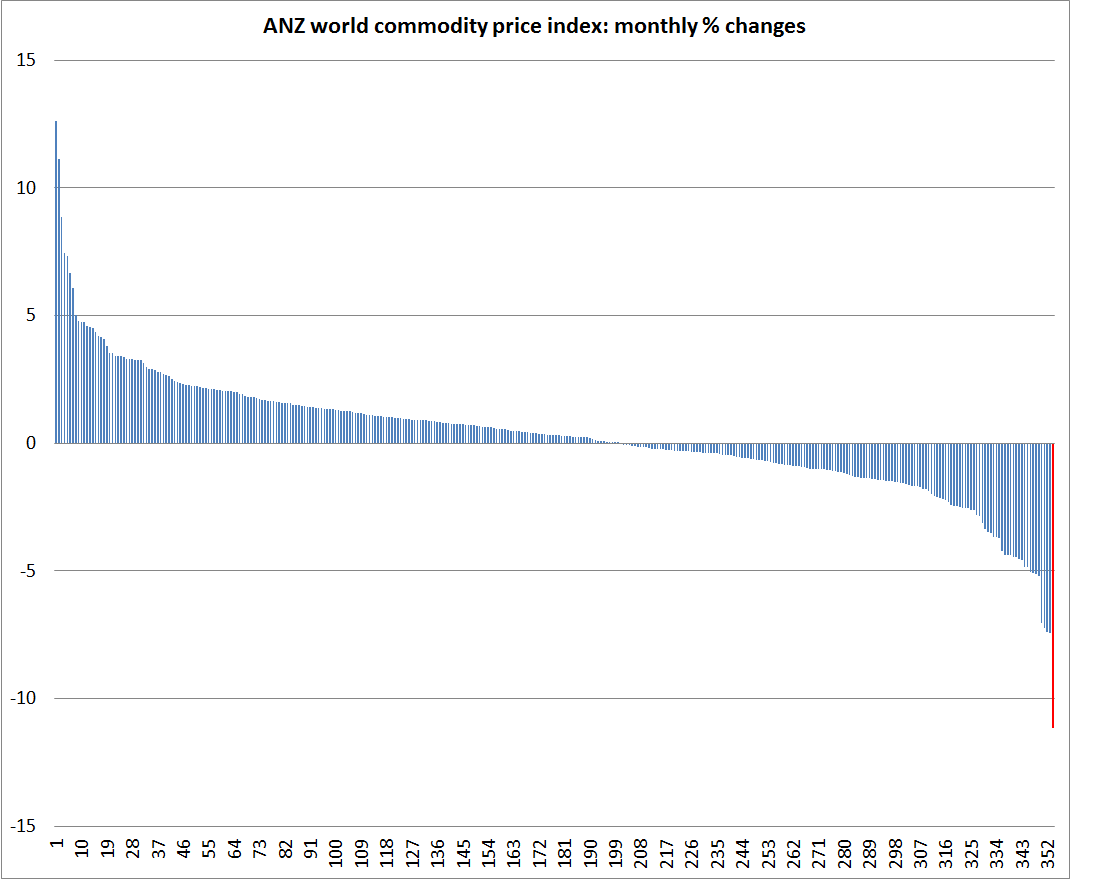
anz monthy changes

On the ANZ measure, the scale of the fall in commodity prices in the last year or so now matches what happened during the 2008/09 recession.
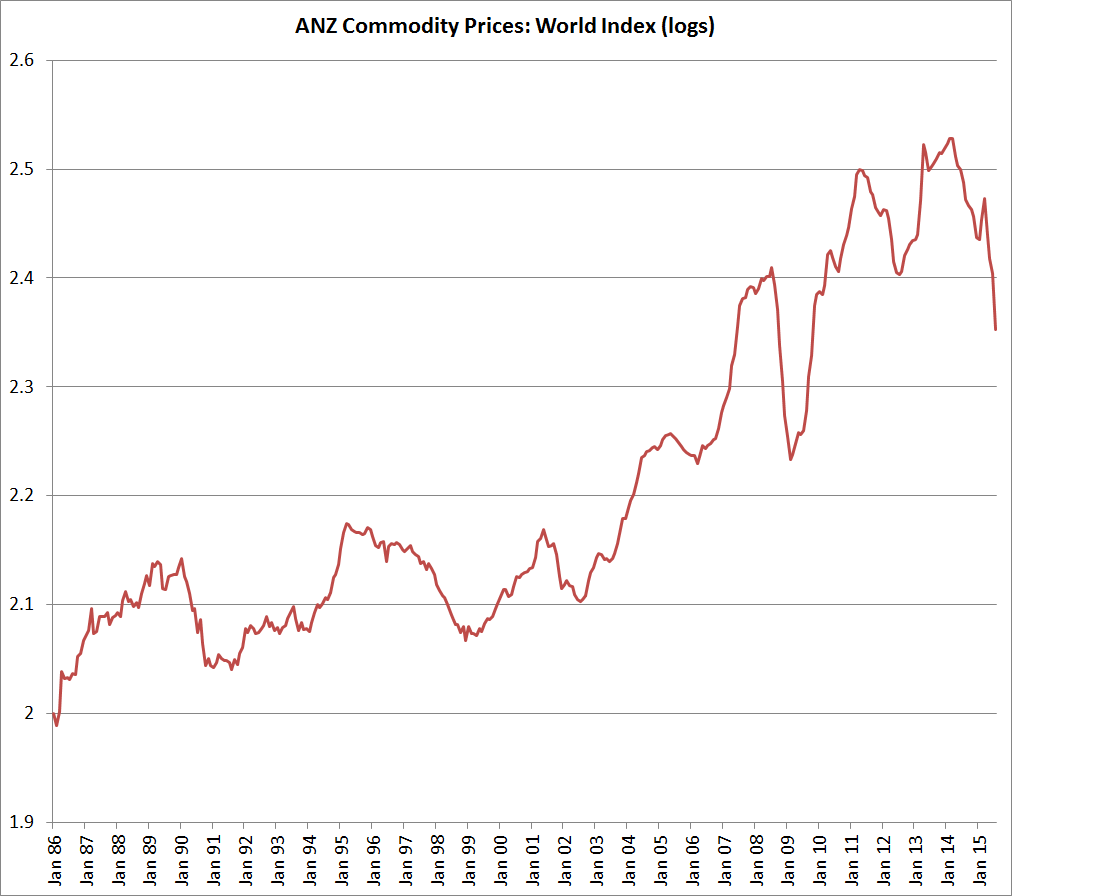
ANZ Commodity

For dairy prices themselves, the fall in the GDT index now materially exceeds the scale of the fall in 2008/09. Real dairy prices now appear to be around the lowest levels for 30 years – although not necessarily at levels wildly inconsistent with trends up to 2006.
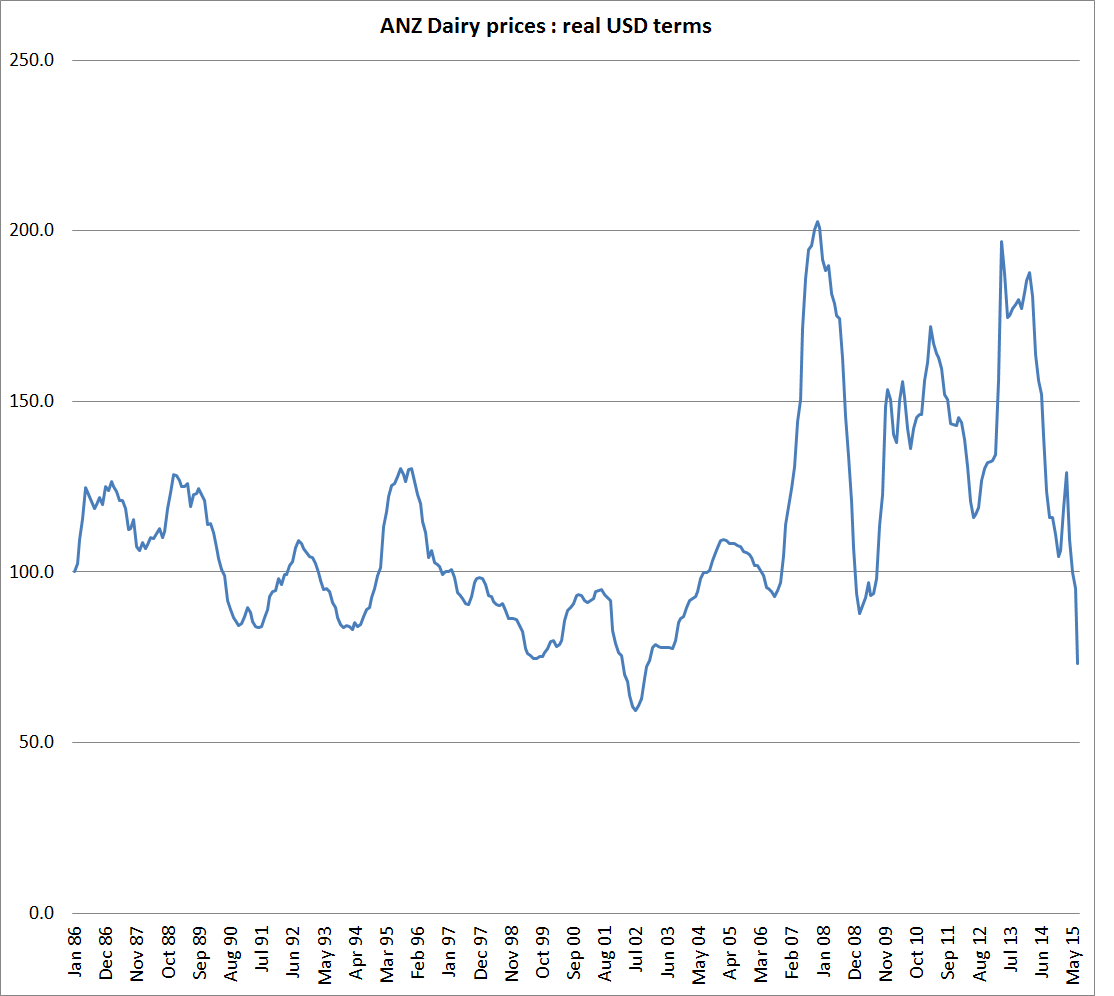
ANZ commodity real USD dairy

The fall in commodity prices didn’t cause New Zealand’s recession in 2008/09. A drought didn’t help. Neither did lingering inflationary pressures that for a while made the Reserve Bank reluctant to cut the OCR. And, of course, there was the recession that engulfed the rest of the world, which in turn helped exaggerate the fall in commodity prices. So I’m not suggesting that the falls in New Zealand commodity prices necessarily mean we are now heading for negative GDP quarters, but the loss of national income is now large and the risks of some pretty bad outcomes must be rising. There are no forces operating in the other direction, to boost growth rates. The real exchange rate is only around 10 per cent below the average for the previous couple of years – as I pointed out the other day, that is a pretty modest adjustment by historical standards.

For a few years, I’ve been intrigued by how little growth there has been in real value-added in the agricultural sector. The terms of trade have been high, and in particular world dairy prices have been high, and yet over 10 years or so there has been almost no growth in what SNZ record as real value-added in the agricultural sector. Here is the most recent version of a chart I’ve run previously.
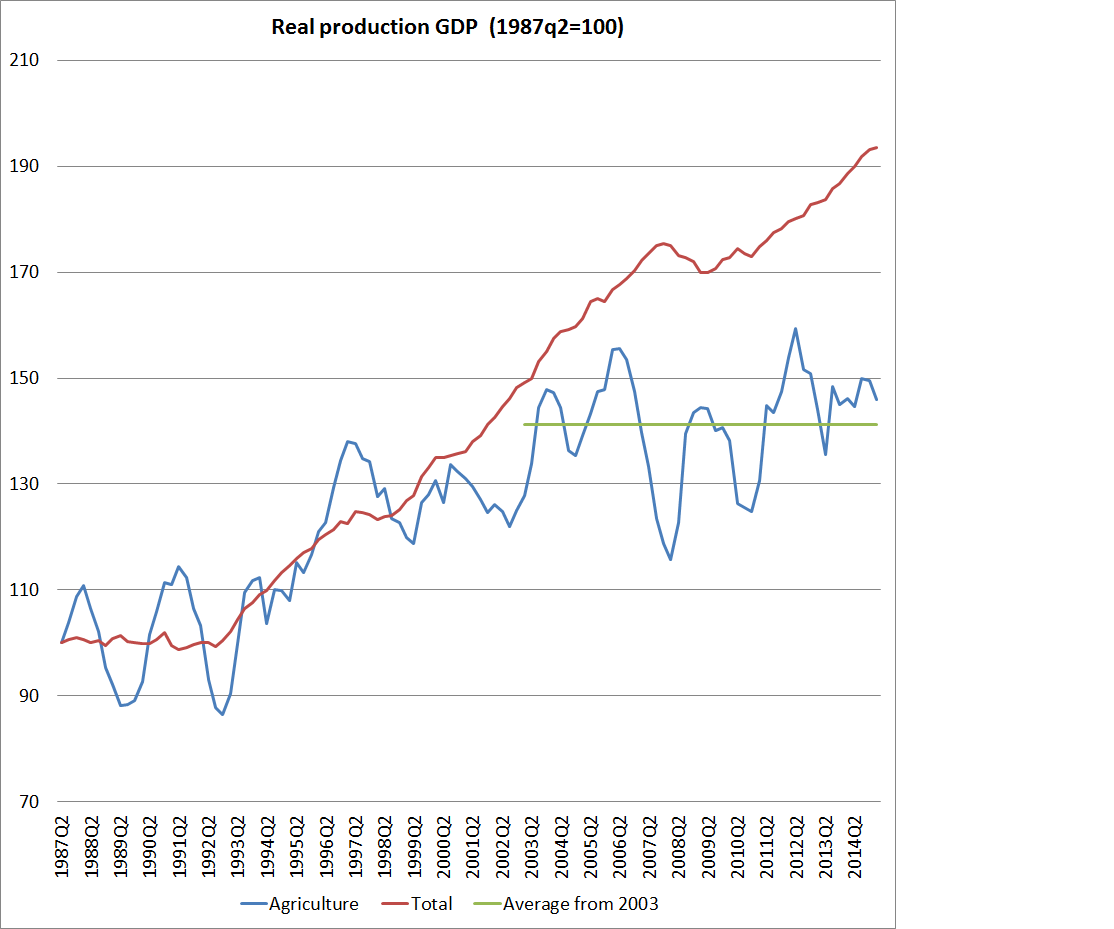
agriculture real GDP

Total factor productivity growth in agriculture has also been quite remarkably weak.

I’ve noted previously that some of this may have reflected the incentives of rising prices. It is well-known that dairy production processes have become much more input-intensive over the last decade or more.   Much of that is about supplementary feed, but it also includes irrigation and other more capital-intensive production models.  In principle, in the face of high product prices these additional inputs could improve the profitability of the agricultural sector, even though the real (constant price) value-added is not increased. If more inputs are being used to produce more outputs, and those outputs can be sold profitably, then it is just one of the ways in which farmers (and their suppliers) capture the benefits of the rising terms of trade.

I was never sure quite how persuasive that reassuring story was. But a reader has got in touch to point me to some papers which suggest that things might be nowhere near as rosy as that story suggests. A basic proposition of economics is that one should produce to the point where the marginal revenue from the additional production equals the marginal cost of doing so. Beyond that point, one starts losing money on every additional unit of production.

I don’t suppose anyone imagines that this model exactly describes how any single business actually operates.   But it is a tendency towards which economists typically, and implicitly, assume that firms in a competitive market will gravitate.  Why, for example, would one produce more if you were going to lose money on each new unit of production. And in the rural sector, where land is huge component of inputs, a farmer generating the highest rates of profit should be able to bid a higher price for land. Resources should gravitate to those best able to use them.

But there is no guarantee of this happening, especially over relatively short periods of time.

In their paper “The intensification of the NZ Dairy Industry – Ferrari cows being run on two-stroke fuel on a road to nowhere?”, presented at an agricultural economics conference last year, Peter Fraser and two co-authors (Warren Anderson, an academic at Massey, and Barrie Ridler,a Principal at Grazing Systems Limited) argue that many New Zealand dairy farmers have been applying anything but the principle of producing until marginal revenue equals marginal cost.  I spent quite a bit of time working with Peter during the 2008/09 dairy price crash – I knew about debt but he (at MAF) knew, and taught me, a lot about dairy. I have a lot of time for his (often-trenchantly-expressed) views.

Fraser et al argue that most of the farm models used by farmers and their advisors in New Zealand take an average cost approach rather than a marginal cost approach, which is inducing increases in production beyond the point of profit maximisation.

none of the mainstream dairy industry farming simulation models (e.g. the Whole Farm Model, Farmax, DairyMax, Udder) and performance measures (e.g. information derived from Dairy Base or Red Sky, benchmarks such as milksolids per hectare, average profit per hectare, gross farm returns, production at x percentile, etc.) are economic models or measures as none employ marginal analysis. As a result, none can profit maximise at a farm level and all are likely to lead to a production decision where marginal costs are greater than marginal revenue.

They argue that this misinformation has not been driven out by competitive processes partly because many dairy farmers are not necessarily setting out to be profit-maximisers.

The corollary is that if farmers are focused on accumulating assets then a ‘satisficing’ position of having sufficient cash flows to pay drawings and to service debt is likely to suffice. Critically, this can also explain why more resources are flowing into the dairy industry: farmers are willing to borrow (and banks willing to lend) in order to accumulate assets (and potentially realise [untaxed] capital gains, especially if converting a dry stock farm into a dairy farm, as this is akin to property development).

In short, a combination of systemic misinformation combined with farmer motives can go a fair way towards explaining why a $10 note may be left on the pavement after all.

One can debate whether this explanation for why is wholly persuasive (the more aggressive dairy developments in recent years, seem far removed from the traditional Waikato or Taranaki (satisficing?) family dairy farmer), but the fact that many farmers are not getting good marginal-based advice and analysis does seem reasonably clear.

Fraser et all go on to support their case with results from a Lincoln University model farm, suggesting that using more sophisticated models (using marginal analysis) profit maximisation would typically result from milking fewer cows (per hectare).

The argument appears to be that much of the growth in total milk production in New Zealand in recent years (perhaps 10-15 per cent of total production) is resulting from an average-cost led focus on boosting total production, rather than maximising profits. Even at the higher prices that were prevailing until recently, production volumes should probably have been lower (the authors also note the potential environmental benefits).

Quite how all this feeds into thinking about the current situation, and the likely response to falling payouts, I’m not sure.   Marginal revenue is plummeting, and even an average-cost based approach would presumably lead to some reduction in production. On the other hand, there is an awfully large stock of debt to service, and maintaining production levels remains sensible if (but only if, and only to the extent that) current payouts are covering short-run marginal costs.

Relatedly, a reader notes:

I would contend that the family farming structure adapts more readily to the pressure of a price slump. The corporates’ general means of survival is by committing more capital to sustain an existing production plan. Family farms shift more quickly into survival mode and if the household has a trained nurse or teacher sends her back to work to support the family household! The dairy industry in its drive to maximise total production has blithely discarded the flexibilities inherent in the cooperative based systems developed over the previous 150 years. It seems there may be a price to be paid for that negligence.

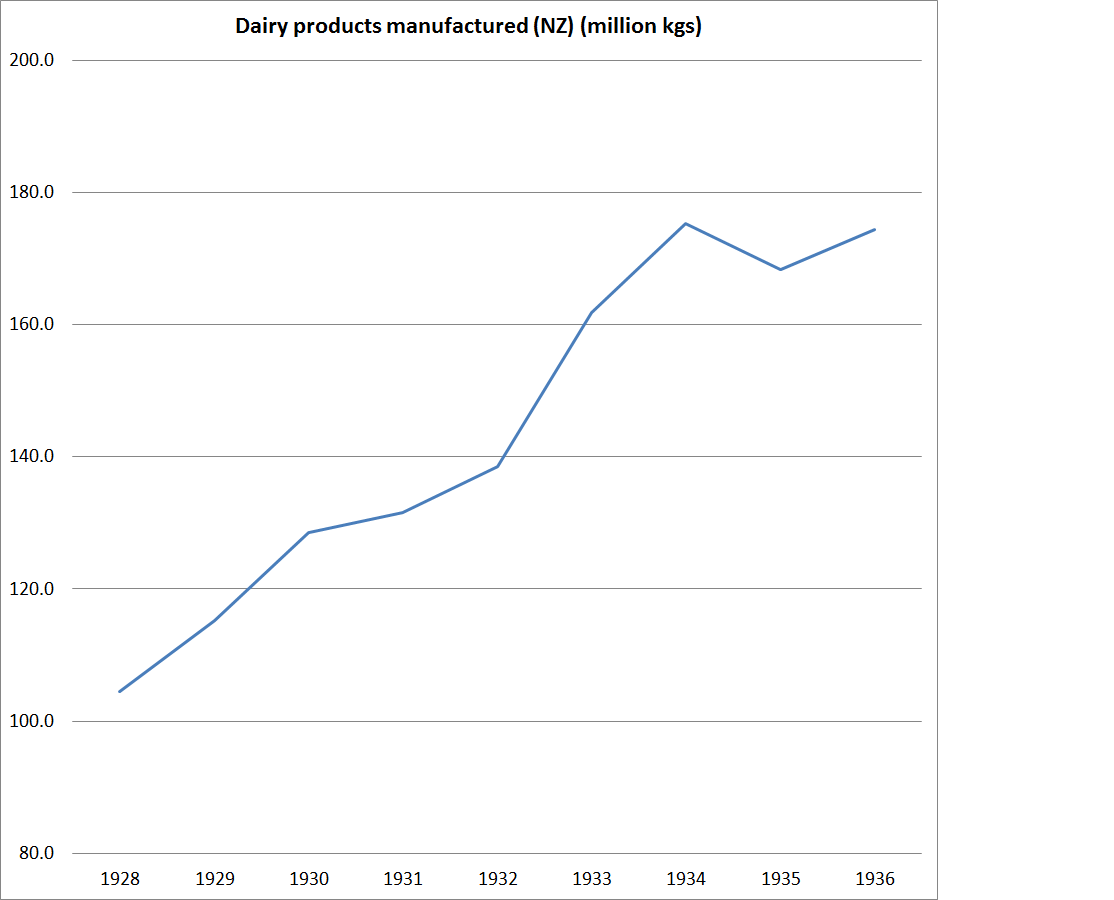
On which note, however, I have long been struck by the production response of the New Zealand dairy industry to the collapse of export prices in the Great Depression   If one didn’t price the farmer’s family labour, short-run variable marginal costs were presumably extremely low, and there was a great deal of debt to service.
dairy depression

I don’t claim expertise in this area, but I found the analysis stimulating and one reconciliation for those otherwise puzzling GDP data I showed earlier. It does look as though participants in the industry will need to think harder about how best to maximise returns, not just production. I like driving obscure and remote roads when we travel the country on family holidays, and I’m often prompted to wonder about the economics of collecting milk from the remote suppliers that linger in such places, and just how long that can go on.  On its own that is a small issue, but perhaps symptomatic of an industry not yet adequately focused on medium to long-term profit maximisation.   Industry structure issues often crop up in the context of discussions like this.  Co-operative structures or not should be a choice for farmers – and they are common internationally in the dairy sector – but direct government legislative interventions facilitated the existing, less than fully competitive, industry structure. So far, the gains to New Zealand from having done so are less than fully apparent.

Why have interest rates fallen so much?

When the Bank of England launched its new blog a while ago I suggested that, despite the promotional material suggesting it would publish materially challenging current orthodoxies, that seemed unlikely – unless, that is, it was to be a vehicle for challenging orthodoxies that senior management themselves wanted to challenge.

I haven’t seen any sign of orthodoxies challenged so far. But, on the other hand, the blog has proved an excellent vehicle for Bank of England staff to give greater visibility to work on a range of interesting, mostly empirical, economics and finance issues. And to do so in bite-sized, not overly technical, chunks.

A while ago I ran a series of posts (eg here and here) on why New Zealand’s real interest rates had been so persistently high relative to those in other advanced countries. Our real interest rates are much lower than they were 20 years ago, but so are those pretty much everywhere.

interest1

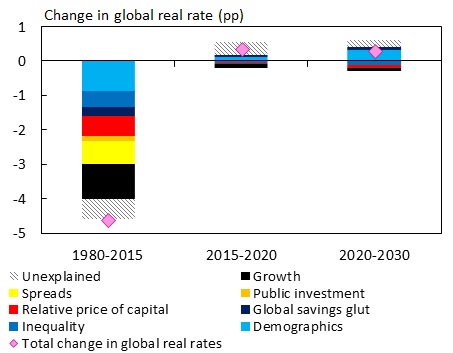
Over the last few days, two Bank of England blog posts (here and here) have looked at what lay behind that global trend decline – of around 450 basis points since 1980.   They use as a framework the idea that observed real interest rates, at least at a global level, reflect the interaction of desired savings rates and desired investment rates. At the global level, actual savings and actual investment are equal ,and the real interest rates adjust to reconcile any ex ante differences.

The authors identify a number of factors which they estimate can explain perhaps 90 per cent of the fall. These includes slowing global population growth, falls in desired public investment spending, the falling price of capital goods, an emerging markets “savings glut”, rising income inequality, slower growth rates, and so on. Here is their summary picture.

BOE world real rates

And here is how they apply the framework to thinking about the next few years.

Our framework allows us to speculate what will happen next (Figure 6, above). The big picture message is that the trends we have analysed are likely to persist: we do not predict a big further drag, or a rapid unwind of any of these forces. Some are likely to drag a little further (global growth is set to decline further out; the relative price of capital is likely to continue to fall; and inequality may continue to rise); but this will be broadly offset by a rebound in other forces (particularly demographics).  What happens to the unexplained component depends on what’s driving it. In Chart 6 we illustrate the implications of assuming it is largely cyclical. Despite that, this would still imply global neutral rates will stay low, perhaps around 1% in real terms over the next 5 years.

I don’t find every detail persuasive, but the broad story rings true. Interest rates (short or long term) are not low because of central banks, but because of rather more fundamental forces. And few of those seem likely to reverse any time soon.

Perhaps it would be helpful if the authors had been able to interpret their results for the last 35 years in a much longer historical context. Even if we can explain the fall in real interest rates since 1980, it is much harder (I suspect) to provide a compelling reason for why interest rates are now so much lower (in most countries) than at any time for hundreds of years.  Rapid population growth, for example, was substantially a post-WWII story.  But perhaps that reconciliation is one for another author.

In a New Zealand context, I remain fairly convinced that demographics have played a material role in explaining interest rate pressures here.   In particular, the policy-driven component, of our immigration policies over the decades.   As one small component of a world economy, the argument is not as straightforward as for the world economy as a whole. But with one of the faster population growth rates in the advanced world, it should not be any great surprise that we have seen persistent pressure on our real interest rates (and, hence, on the real exchange rate). We’ve shared in most of the fall in global interest rates, but there has been no sign of any closing in the large trend gap. In the 1950s and 1960s those pressures showed up in tight credit controls and import controls etc (to suppress demand by fiat).  Since liberalisation they have shown up as persistently higher average interest rates than those in the rest of the advanced world. As a result, business investment has been quite subdued, and what business investment there has been has been concentrated more heavily in the non-tradables sector than one might have otherwise expected in an economy that had undergone the sort of liberalising reforms New Zealand undertook in the 1980s and early 1990s.

Why?

Fossicking round in some old legislation yesterday, I stumbled on the Music Teachers Act.  I’d assumed this was one of those pieces of legislation that might have gone the way of Raspberry Marketing Regulations 1979, that governed the New Zealand Raspberry Marketing Council until 1999.

But no, the Music Teachers Act is still on the statute books.  It is

An Act to consolidate and amend the Music Teachers Registration Act 1928, and to make better provision for the registration and control of music teachers and the advancement of music teaching.

The prime function of the Act is to establish and govern The Institute of Registered Music Teachers of New Zealand, again with the statutory purpose of

Purposes of institute

  • The purposes of the institute shall be––

    • (a) to promote the general advancement of music teaching, and the acquisition and dissemination of knowledge and skills connected with music teaching:

    • (b) to protect the interests of music teachers in New Zealand:

    • (c) to protect and promote the interests of the public in relation to music teaching:

    • (d) to hold conferences on music teaching and related subjects:

    • (e) to publish a year book, giving an account of the proceedings of the institute, the names of persons currently registered under this Act, and such other matters as may be of interest to members of the institute:

    • (f) to grant prizes, scholarships, and financial or other assistance to any person or organisation that may further the aims of the institute:

    • (g) to administer the fund known as the Helen Macgregor Tizard Benevolent Fund, previously administered by the Music Teachers Registration Board of New Zealand.

Some of these might be worthy enough objectives in some lights, but where is the public policy interest?  And especially in protecting “the interests of music teachers in New Zealand”.  Consumers’ or customers’ interests perhaps, but legislation to protect the interests of music teachers.

The Institute seems to have no powers over anyone, and appears to do some worthy stuff.  But why does it need a statute to make such a body function effectively?  If it offers good courses, or even certification, surely it can do that on its own merits?   The New Zealand Association of Economists, for example, has no statutory backing.

I asked my children’s piano teacher yesterday what he knew of the Act, or the Institute.  He is a smart young guy, who is active in music teaching programmes in schools and privately.  And he had never come across the body.

So perhaps the Act does both little harm and little good. In other words, it is largely irrelevant.  Those of us hiring music teachers presumably do so mostly the old-fashioned way –  by repute, and word of mouth.  And we keep them on if we judge that they are helping our children learn.

For decades, governments have been reluctant to tackle occupational licensing (which is nowhere near as pervasive here as in the United States). But for a third term government with a light legislative agenda, perhaps this is one bit of ever-burgeoning statute books that can quietly be repealed.

(Right after they secure the freedom to fly remote-controlled toy helicopters in the local park.)

What legislation used to require of monetary policy

This was what section 8 of the Reserve Bank Act, and associated provisions, replaced.  It is easy to forget –  and for many younger readers, never to have been aware –  just how different things were.  Of course, we had a singe decision-maker back then too, although as Minister of Finance and an elected MP, the single decision-maker could be (and often was) tossed out of office.

8. Primary functions of Bank—

(1) The primary functions of the Bank

shall be—

(a) To act as the central bank for New Zealand; and

(b) To ensure that the availability and conditions of credit provided

by financial institutions are not inconsistent with the sovereign right of the Crown to control money and credit in the

public interest; and

(c) To advise the Government on matters relating to monetary policy, banking, credit, and overseas exchange; and

(d) Within the limits of its powers, to give effect to the monetary policy of the Government as communicated in writing to the Bank under subsection (2) of this section, and to any resolution of Parliament in relation to that monetary policy.

(2) For the purposes of this Act, the Minister may from time to time

communicate to the Bank the monetary policy of the Government, which shall be directed to the maintenance and promotion of economic and social welfare in New Zealand, having regard to the desirability of promoting the highest level of production and trade and full employment, and of maintaining a stable internal price level.

(3) The Bank shall, as directed by the Minister, regulate and control on behalf of the Government—

(a) Money, banking, banking transactions, any class of transactions of financial institutions, credit, currency, and the borrowing and lending of money:

(b) Rates of interest in respect of such classes of transactions as may from time to time be prescribed:

(c) Overseas exchange, and overseas exchange transactions.

(4) The Bank shall make such loans to the Government and on such conditions as the Minister decides from time to time, in order to ensure the continuing full employment of labour and other resources of any kind.

For those interested in the history, and how the functions/objectives/powers provisions changed (as they repeatedly did –  this was the 1973 formulation) there is an interesting Bulletin article here by Christie Smith and James Graham.  In case anyone thinks my post this morning was a recantation of a commitment to monetary stability (which it certainly wasn’t) I remain proud of the fact that my grandfather’s cousin was the Minister of Finance who introduced the concept of a stable internal price level to the Reserve Bank Act, and removed the formal power for the Minister of Finance to direct the Bank.  Those changes didn’t last long.

Should the statutory objective for monetary policy be changed?

Since 1989, section 8 of the Reserve Bank of New Zealand Act has read as follows:

The primary function of the Bank is to formulate and implement monetary policy directed to the economic objective of achieving and maintaining stability in the general level of prices.

That provision was widely seen as one of the centrepieces of the new Reserve Bank Act in 1989. It does not directly guide day-to-day monetary policy, but rather it should constrain the Minister and the Governor in negotiating Policy Targets Agreements (PTAs). PTAs must, by law, be consistent with section 8: as the Act puts it, the targets are “for the carrying out by the Bank of its primary function”.

The wording raises a variety of geeky questions.   Should, for example, the Act really describe monetary policy as the Bank’s “primary function”, or just treat monetary policy as one of a variety of functions Parliament assigns to the Bank?   Is it really sensible to talk of stable levels of prices, when neither the Bank (nor ministers, nor Treasury) has ever shown any interest in stabilising the level of prices, as distinct from the rate of change in those prices (“the inflation rate”). More troublingly, perhaps, can a medium-term trend inflation rate of 3 per cent (which we had got up to prior to the 2008/09 recession, and which would double prices every 24 years) really be described as “price stability”?

I’m not going to try to answer those questions today. But they illustrate that there is no particular reason to think that the current specification of section 8 should be treated as sacrosanct. My impression over many years at the Reserve Bank was of a tendency (I may have shared this attitude at times) to treat section 8 as the battle standard of orthodoxy, such that any change would be akin to allowing the barbarians to overrun the fortress.

Going into last year’s election, each of the Opposition parties (Labour, Greens, New Zealand First, Internet-Mana) was campaigning to change section 8 of the Reserve Bank Act.   Of course, typically they were looking for rather more change than just a change of overarching statutory objective, but two parties were quite specific in what they were looking to do with section 8 itself

In Labour’s case, as I noted a couple of weeks ago, they came up with this formulation

“The primary function of the Bank with respect to monetary policy is to enhance New Zealand’s economic welfare through maintaining stability in the general level of prices in a manner which best assists in achieving a positive external balance over the economic cycle, thereby having the most favourable impact on the stability of economic growth and the level of employment.”

And New Zealand First has sought to introduce legislation amending section 8 to read as follows:

The primary function of the Bank is to formulate and implement monetary policy directed to the economic objective of maintaining stability in the general level of prices while maintaining an exchange rate that is conducive to real export growth and job creation.”

In both cases, it would appear that the framework of a Policy Targets Agreement would continue.   Labour was quite explicit about maintaining the inflation target.

In fact, looking around the world’s advanced economies there is a wide variety of ways in which countries have written down what they are looking for from their central bank and monetary policy. In a fairly short issue of the Reserve Bank Bulletin published late last year, Amy Wood and I looked at the wide variety of ways legislation is written in 18 advanced countries (or regions in the case of the euro) that now use inflation targets as the day-to-day centrepiece of monetary policy.

There are big differences across countries. Some of those differences are about the age of the legislation. Old legislation looks quite different from newer legislation. Some is probably about the preferences of legislative drafters in different countries. And one important difference that became apparent is that in some countries they have written a limited statement of what a central bank can directly achieve, while in others they have written more about the longer-term desired outcomes that might flow from good monetary policy. And while acts of Parliament are one part of the mix, they often aren’t the only place in which society’s aspirations for monetary policy are set down.

At one extreme, in Sweden the only formal document – the central bank act – simply states that the goal of the Riksbank’s monetary policy is “price stability”. There are no other formal or binding documents (although there are plenty of Riksbank texts on what current governors interpret the Act as meaning).

The US legislation, by contrast, is a mix of medium-term objectives (things the central bank might more directly affectl) and desired outcomes from good policy. The Federal Reserve Act requires the Fed to “maintain long-run growth in the monetary and credit aggregates commensurate with the economy’s long-run potential to increase production”. Stable money growth was the thing the Fed could directly influence. But the Act goes on to state that this is to be done “so as to promote effectively the goals of maximum employment, stable prices, and moderate long-term interest rates”. Congress didn’t care about money supply growth for its own sake, but for the things that are thought to flow from it.

The Bank of Canada operates under very old legislation. The Bank is required to “regulate credit and currency to control and protect the external value of the national monetary unit” (this dates back to before the era of floating exchange rates), but again it does not do this simply for its own sake. Rather, Parliament goes on to explain that the desired outcome of monetary policy is “to promote the economic and financial welfare of Canada”

I could go on. Even the ECB, established by treaty rather than by national legislation, operates under provisions which state that while the primary objective is “price stability” a variety of good things that should flow from the work of the ECB specifically and the EU more generally (eg “…stable prices, sound public finances and monetary conditions and a sustainable balance of payments”).  When I first stumbled on that last clause, about a sustainable balance of payments, I wondered if the Labour Party people were aware of it.

In many countries, even with quite recent legislation, there is an explicit obligation on the central bank to work together with, or support, other government economic policies, at least so long as doing so does not threaten the primary price stability goal,

What about the New Zealand situation?

Section 8 of the Act is pretty clear and succinct about what monetary policy is for, but nature tends to abhor a vacuum. Trace through the evolution of the Policy Targets Agreements since 1990 and you will more and more stuff written down, that was previously unwritten and somewhat taken for granted. But political pressures and criticisms of the Bank saw more and more details added in.  The 1992 PTA was perhaps the most cut-down approach.

Price Stability Target Consistent with section 8 of the Act and with the provisions of this agreement, the Reserve Bank shall formulate and implement monetary policy with the intention of maintaining a stable general level of prices

But in late 1996, a revised PTA was signed as part of the National-New Zealand First deal. It moved beyond just writing down the direct stuff the Bank could manage, to articulating what the point of pursuing price stability was.   The ‘so that” language that Winston Peters introduced here paralleled the “so as to” in the Federal Reserve Act.

Price Stability Target

Consistent with section 8 of the Act and with the provisions of this agreement, the Reserve Bank shall formulate and implement monetary policy with the intention of maintaining a stable general level of prices, so that monetary policy can make its maximum contribution to sustainable economic growth, employment and development opportunities within the New Zealand economy.

In 1999, in the wake of the MCI debacle, Michael Cullen added this provision.

In pursuing its price stability objective, the Bank shall implement monetary policy in a sustainable, consistent and transparent manner and shall seek to avoid unnecessary instability in output, interest rates and the exchange rate

It isn’t in the Act, but it is no less binding on the Governor (and successive Governors who have signed it). Unfortunately, as I noted last week, it is a somewhat troublesome clause, in that no one has ever been sure quite what the practical import was. At one level it was uncontroversial – avoid “unnecessary instability” – but quite what is “necessary”?

In 2002, Michael Cullen and Alan Bollard reformulated clause 1, restoring a clean focus on price stability in a), which just mirrors section 8 of the Act, while adding a separate sub-clause outlining what the government’s economic policy was looking for, and a sense of how price stability contributes.

Price stability

a) Under Section 8 of the Act the Reserve Bank is required to conduct monetary policy with the goal of maintaining a stable general level of prices

b) The objective of the Government’s economic policy is to promote sustainable and balanced economic development in order to create full employment, higher real incomes and a more equitable distribution of incomes. Price stability plays an important part in supporting the achievement of wider economic and social objectives.

With a change of government in 2008 there was a change in economic policy goal

The Government’s economic objective is to promote a growing, open and competitive economy as the best means of delivering permanently higher incomes and living standards for New Zealanders.  Price stability plays an important part in supporting this objective.

And finally in 2012, the words –  already present in section 10 of the Reserve Bank Act since 1989 – about having regard to the efficiency and soundness of the financial system in conducting monetary policy were added.  Quite what these words mean in practice is also less than clear –  even after 26 years.

No other countries have a binding legal arrangement akin to the Policy Targets Agreement.

There is a wide variety of ways in which countries, with very similar practical monetary policies, write down what they want from their central banks.  So the current wording of section 8 should not be sacrosanct –  the only possible way sound money could be preserved.  Personally, I would have no great objection if the wording introduced to the PTA in 1996 were to be translated in an amended section 8 of the Act.    I’d probably have slightly more problem with the Labour Party’s version from the manifesto last year, but ultimately it is for politicians to lay out higher level objectives for the Reserve Bank, and monetary policy.

But, and in a sense this is the point of the Bulletin article, those sorts of alternative formulations would not, on their own, be likely to make any material difference to the way monetary policy was run.  Practical differences flow from different Governors and different Policy Targets Agreements.  If political parties want actual practical differences in how monetary policy is run, they need to look to what they are negotiating in the PTA, and with whom.  As it stands, although the Reserve Bank has made more than its fair share of policy mistakes, evidence suggests that in normal times it has responded to incoming data in much the same way as central banks in Australia, the US, or Canada do.  And legislatures in each of those countries have written things down in rather different ways, to each other and to New Zealand.

There is no harm in amendments that may have little practical impact.  Symbolism matters, and since few would argue that  price stability should be sought for its own sake, there should be no strong objection to writing down in statute what it is hoped that good monetary policy will help contribute to.  Indeed, I would argue that it is better to write it down in statute than to keep fiddling with the Policy Targets Agreement. PTAs can be signed in the dead of night, perhaps involving two people only, as part of bundles of post-election negotiations.  The first the public know about the new terms is when the parties publish the signed document.  By contrast, even in New Zealand, the legislative process is usually much more open and transparent. Bills typically go to select committees, which invite submissions and review the arguments from outsiders before making recommendations.  And the hurdle of making changes in law is higher than for the PTA –  which has become something each change of government feels obliged to change.

I would favour amending section 8.  We need to face the fact that New Zealand is probably the only advanced country in which monetary policy has been repeatedly an election issue.  There has not been an election since 1987 in which one or other party was not campaigning on changes to the Act or the PTA.  That is no passing discontent.

Changing section 8 isn’t the biggest issue to address is reforming the Reserve Bank, but it shouldn’t be treated as of no importance either.

Since I’m not a die-hard inflation targeter either, I would favour something along these lines

Monetary policy shall be formulated and implemented towards the economic objective of maintaining medium-term stability in the purchasing power of the New Zealand dollar, so as to  maximise the medium-term contribution monetary policy makes to full employment and to the economic and social welfare of the people of New Zealand.

With such a clause, clause 4b –  the troublesome clause about avoiding unnecessary variability – should be able to be junked.  Parliament will have made clear that the whole point of the Bank is to promote good economic outcomes, and the longer-term interests of New Zealanders.  But don’t lose sight of the fact that New Zealand’s real medium-term economic failures have little or nothing to do with the conduct of monetary policy, or the way the Reserve Bank Act is written.

Of course, there still will –  and should  –  be vigorous debates about what intermediate targets the Bank should be required to pursue.  Many will favour the status quo, others might favour NGDP targets, and some might come to favour wage growth targets.  Some might favour a more active role in exchange rate smoothing. But those debates too should be carried on openly.  As I’ve argued before, the Minister of Finance and the Treasury (with or without the cooperation of the Bank) should already be planning an open process for consideration of issues before the next PTA will be due in 2017.  As 2017 is election year, the earlier the better really.

Of course, there is probably another debate to be had, before the Act is next comprehensively reviewed, as to whether there should be a single overarching objective for monetary policy and financial regulatory policy.  I think that would be a step in the wrong direction.  They are two quite different functions, just as monetary policy and fiscal policy are quite different.  But perhaps that is a topic for another day.

The exchange rate “needs” to come down?

I’ve been continuing to reflect on Graeme Wheeler’s repeated observation that New Zealand’s exchange rate “needs” to come down. I’m still not entirely sure what he means. The exchange rate is an asset price and presumably should reflect all expected future relevant information, not just spot information about current dairy prices. And the market has no particular reason to focus on stabilising the net international investment position at around current levels. Indeed, although it is a convenient reference point, neither does the Reserve Bank.

“Need” or not, I’d have thought it was likely that the exchange rate would fall further.

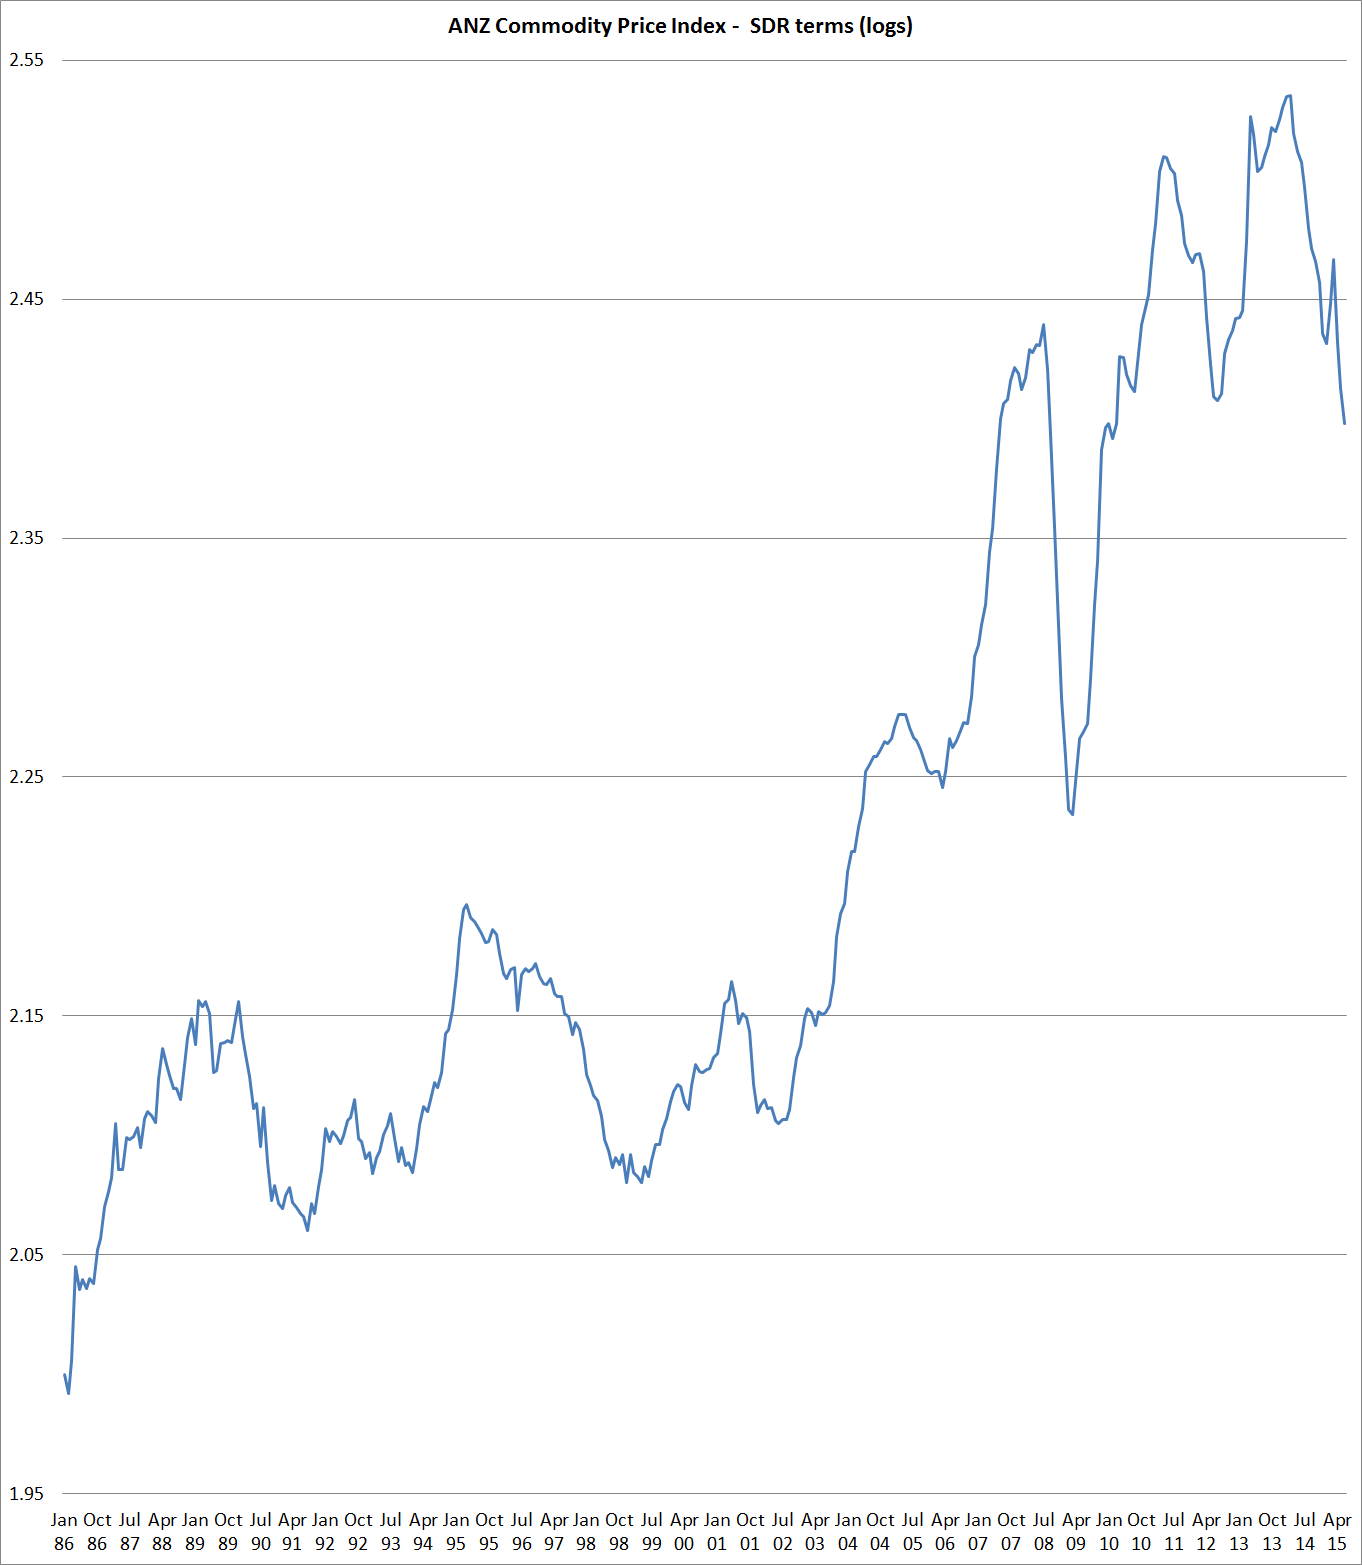
The ANZ Commodity Price Index, which lags behind (for example) falling GDT and futures dairy prices, has already had one of the larger falls in the history of the series.

ANZ Commodity

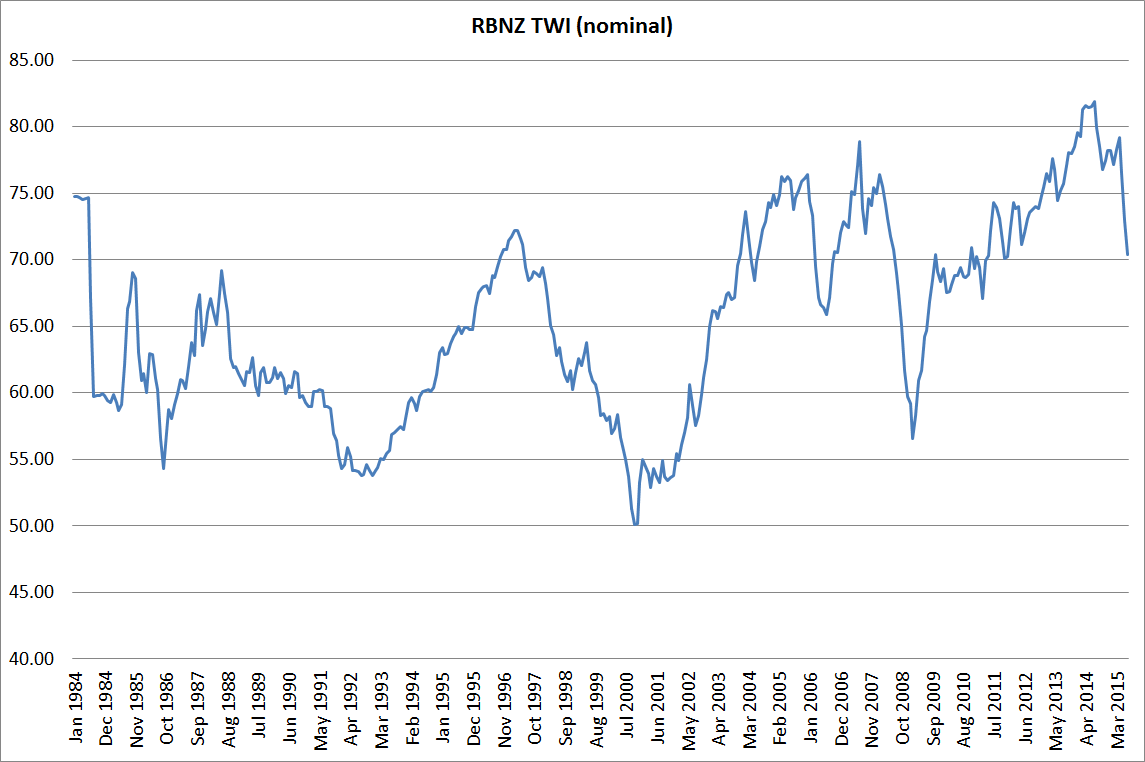
Meanwhile, the fall in the exchange rate, while material, remains pretty small by the standards of past New Zealand adjustments since the float in 1985. At the moment, the adjustment is comparable to what we saw in the shortlived growth (and risk) scare in 2006.

RBNZ TWI
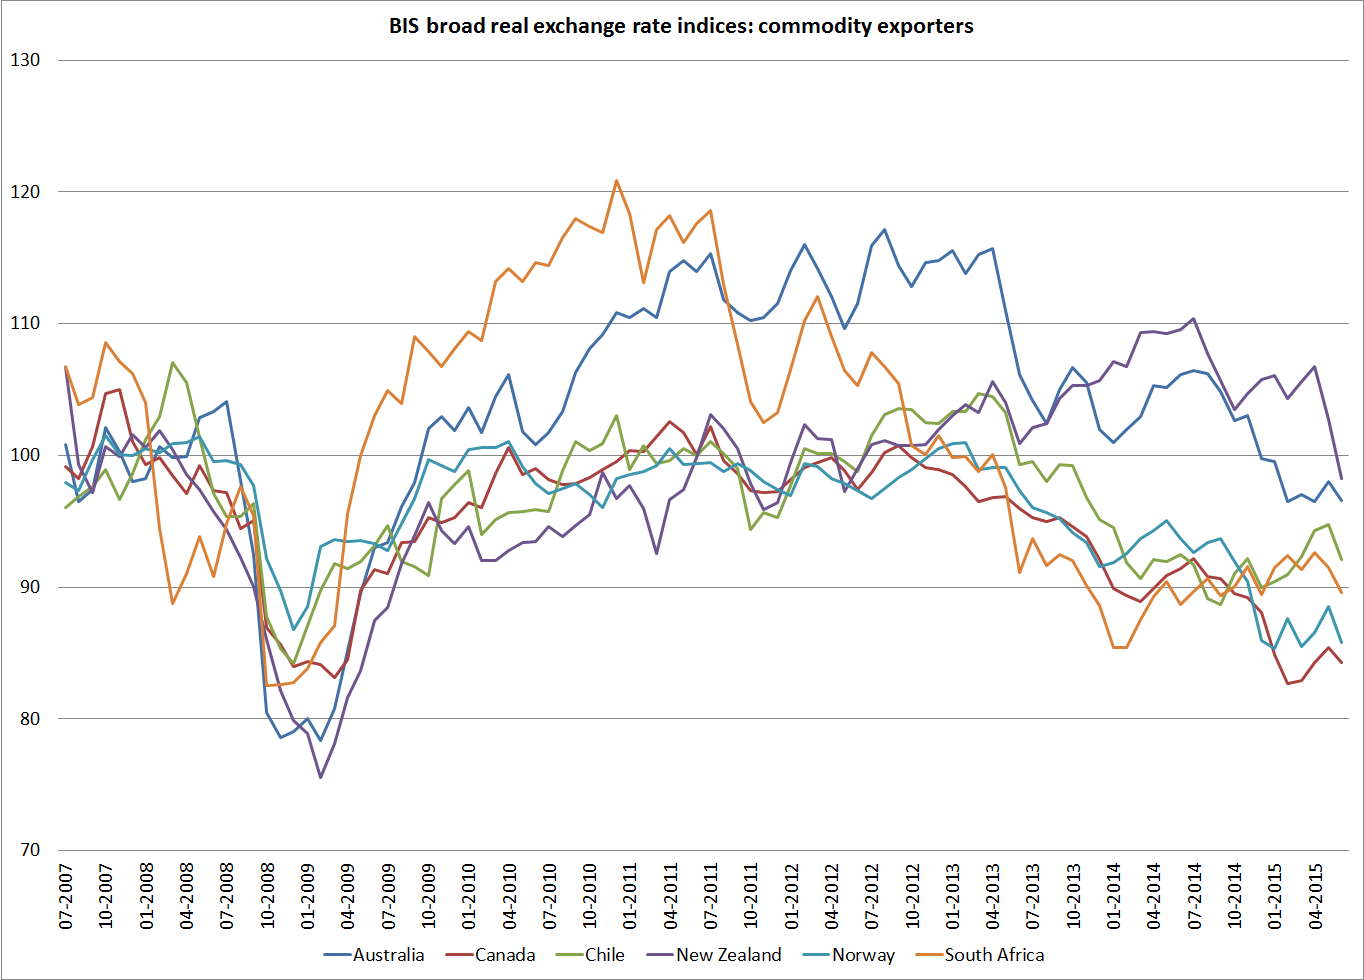
And here are the BIS real exchange rates for the five OECD commodity exporting countries, and South Africa. Each has experienced rather different commodity price pressures and opportunities. Here the exchange rates are each based to 100 at the average for each country in the year to June 2008 just prior to the global recession and crisis.

bis exch rates

New Zealand’s exchange rate doesn’t stand out dramatically, but it remains higher, relative to pre-recession levels, than in these other countries. In part that is likely to reflect yield differentials. New Zealand is the only one of these six countries still to have policy interest rates higher than they were 18 months ago. That is Graeme Wheeler’s choice, and while data may eventually force him to change his view, it is his view that for now determines short-term interest rates on offer in New Zealand

Investor finance restrictions: the Reserve Bank asserts a right to secrecy

The Reserve Bank has been consulting on a proposal to ban any lending with an LVR greater than 70 per cent to residential property rental businesses in Auckland.   I have been noting that the Governor acts as investigator, prosecutor, judge and jury in his own case in matters like this. I have also noted the contrast between the way the Bank handles submissions on its consultative documents, (releasing only a (self)-selected summary after the final decision has been made), with the process used in respect of submissions to parliamentary select committees, in which submissions are published (and the committee members are not themselves final decision makers on legislation).  This is a serious democratic deficit –  a unelected decision-maker keeping secret submissions on major economic policy initiatives, which will have pervasive effects on potential borrowers and on the efficiency of the financial system.

Under the Official Information Act, I asked for copies of the submissions the Reserve Bank has received on the Governor’s latest proposed controls.  This afternoon I received the letter below, refusing my request (it is, however, far the fastest they have responded to any of my OIA requests).

I have no idea whether their stance is legal, and will consider lodging a complaint with the Ombudsman, on the grounds that there is a strong public interest in having this information available.  Whether or not it is legal, it hardly seems wise for an unelected individual who exercises so much power, and who has already been challenged as having apparently misrepresented material in his consultative documents and responses to submissions.

There is a serious democratic deficit in the way the Reserve Bank is structured.  The Governor could choose to allay some of those concerns by the way he operates, but instead he adopts a secretive style while one individual makes these decisions, which appear to be at best weakly justified under the provisions of the Reserve Bank Act, which require its powers to be used to promote the soundness and efficiency of the financial system.  It is difficult for the public to have trust in a Governor who will not even make public the submissions he receives on his proposals, and is himself responsible for any summary of submissions that may later be published.

Dear Michael

On 14 July you made an Official Information request seeking: Copies of all submissions made to the Reserve Bank on the proposed changes and extensions to LVR restrictions.

The Reserve Bank recognises that there is a tension between the public interest in full disclosure and the statutory requirement to maintain the confidentiality of information we use to regulate banks. In order to balance transparency with confidentiality, our long-standing practice is to publish a summary of submissions rather than publish original documents submitted to us. We currently have work underway to publish a summary of submissions relating to our consultation on adjustments to restrictions on high-LVR mortgage lending.

Official Information Act section 16(2) says that we should provide requested information in the way that a requester prefers to receive it, unless doing so would:

(a)    impair efficient administration, or

(b)   be contrary to our legal duty in respect of the document.

Official Information Act section 16(1)(e) allows that information may be made available by giving an excerpt or summary of the contents.

Much of the information contained in the submissions that you have requested must be withheld in order to comply with the confidentiality provisions of section 105 of the Reserve Bank of New Zealand Act, and it would be administratively inefficient to publish our summary and repeat the work of summarising by redacting documents that are already being summarised for publication.

Accordingly, your request is refused on the following two grounds of the OIA:

  • s18(c)(i) – providing some of the information would be contrary to another Act; in this instance, section 105 of  the Reserve Bank of New Zealand Act, and
  • s18(d) – that the information is or will soon be publicly available; in this instance, as a summary.

The Reserve Bank expects to publish its summary of submissions near the end of August. The summary of submissions will include names of people and organisations that provided submissions, which gives you the option to directly approach submitters to ask if they will provide you with the information you’re seeking.

You have the right to seek a review of the Bank’s decision under section 28 of the Official Information Act.

Yours sincerely

Angus Barclay

External Communications Advisor | Reserve Bank of New Zealand

2 The Terrace, Wellington 6011 | P O Box 2498, Wellington 6140

www.rbnz.govt.nz

From: Michael Reddell ] Sent: Tuesday, 14 July 2015 11:59 a.m. To: macroprudential Subject: RE: Submission on proposed investor finance restrictions

Thanks Daniel

This is to request, under the Official Information Act, copies of all submissions made to the Reserve Bank on the proposed changes and extensions to LVR restrictions.

Regards

Michael

How have we been doing in recent years relative to the US?

The US Bureau of Economic Analysis released overnight some revised GDP estimates, not just affecting the last couple of quarters (the bits that tend to attract more headlines than they are worth), but going back several years.  The overall effect was to revise lower estimates of US GDP growth over the last few years.  The previous estimates of growth had, of course, already been very low by historical standards.

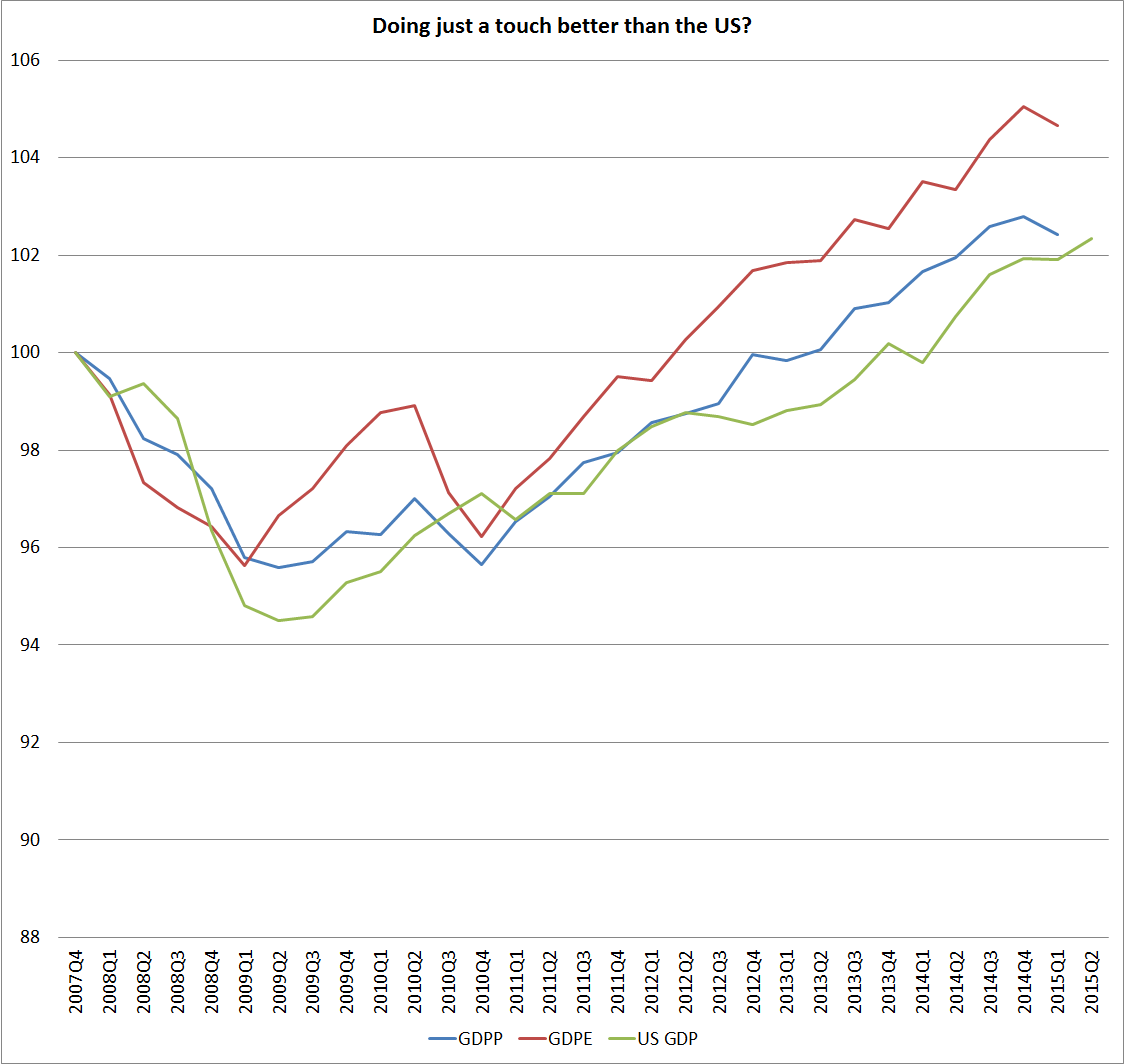
I’ve been intrigued, and have posted previously, about how similar the paths of NZ and US GDP per capita have been since 2007, despite all the differences between the two countries’ experiences (financial crisis and not, terms of trade boom and not, earthquake reconstruction and not, and even quite different labour market experiences).  So I was curious to check what the chart  –  showing real GDP per capita –  looked like following the latest US revisions.

nz vs us gdp pc

Statistics New Zealand publishes separate production and expenditure GDP series, and not infrequently there are material divergences between recent years’ estimates of the two series.  SInce 2007, on current estimates, GDP(E) has grown more than 2 per cent more (in total) than GDP(P).   Analysts tend to pay more attention to the production measure (GDP(P), but that is partly for historical reasons (it used to be less volatile).  The differences will largely be revised away over time, but we have no obvious way on knowing now which will better be seen as representing history.  The final revisions, years hence, could be higher or lower than both series, or somewhere in the middle.  My hunch is that they will be a bit lower: I understand that SNZ uses PLT met migration to feed into its population estimates, but experience suggests that in periods of strong inward migration net PLT understates the actual net inflow.  The next census –  the check on the level of population  – is still a few years away.

If the GDP(E) line, as it currently stands, were to prove to be the final story, we might end up taking a little comfort that we had done a little better than the US over this period.  As it is, for now I’m sticking with emphasising the cumulative similarities in GDP per capita paths rather than the differences.  And if we had crept a little ahead in the last year or two, the chances of maintaining that lead don’t look overly good right now.

And don’t forget the employment (or productivity) picture.  We are estimated to have generated very slightly more income per capita growth since 2007, but employment here dropped from 65.9 per cent to 65.0 per cent of the population from 2007 to 2014.  In the US employment dropped from 63 to 59 per cent of the population over the same period.  For good or ill, it took them less of their population to generate much the same per capita output gains.  That represents much more productivity growth than we’ve seen here.

TPP

A few earlier posts touched on some issues around TPP.

I remain pretty uneasy about the likelihood of overall net benefits emerging from this deal for New Zealanders.

And since this is one of those polarising issues – at least in New Zealand – I should restate (in a perhaps over-simplified way) my priors:

  • The ability to trade freely in goods and services is generally good and beneficial
  • Unilateral removal of New Zealand’s own trade restrictions has generally benefited New Zealanders.
  • We should have gone further and removed our remaining tariffs and either abolished, or sharply constrained, our anti-dumping regime.
  • A liberal foreign investment regime is generally good and beneficial.
  • New Zealand’s foreign investment regime is less liberal than it could and should be.   (There may, however, be important exceptions to the general case for a liberal regime.  Had the Soviet Union sought to buy up a large contiguous chunk of Northland I’d have had no hesitation in supporting a ban.  And non-resident purchases of houses, especially houses that sit empty, on a large scale might also be an exception,  but only given the absurdities of our domestic planning and land use restrictions.)
  • Intellectual property protections appear to have generally gone beyond what is appropriate to foster a climate of innovation.  Copyright is the most obvious example.
  • Strong government institutions, and particularly those which protect and ensure the rule of law, are important to any successful and prosperous society.
  • A key element of the rule of law is equal treatment of the powerful and the weak.
  • The freedom for domestic Parliaments to adopt even daft and dangerous policies is an integral part of the sort of system of government that we inherited from Britain and have made our own.

So I’m pre-disposed to favour trade and investment liberalisation.  In general, the more the better.

But even the academic literature tells us that free-trade agreements among groups of countries are not the same, and don’t offer the same welfare gains, as more generalised free trade. The Australian Productivity Commission reminded us of that again just last month. Australia’s own FTA with the United States has generally been regarded as having secured few (perhaps even negative) benefits for Australians.

And it is already apparent that intellectual property protections are set to be extended in any TPP agreement.  That is a win for the owners of those properties – few of whom will be in New Zealand – but where is the evidence of a general welfare gains for New Zealand citizens, or indeed, those of other countries?   (And this is so, even acknowledging Eric Crampton’s in-principle point about free-riding and pharmaceuticals).

And why do we want to further entrench investor-state dispute settlement provisions (ISDS), that provide greater rights to foreign investors than domestic investors have? We should, primarily, be making New Zealand law in the interests of New Zealanders, and I have not seen a single serous argument for how that end is served by providing better remedies to foreign investors than to our own. Disputes about government policy should be fought out in domestic political arenas, and disputes on law should be fought in the domestic courts. For better or worse, we ended “foreign” jurisdictions (the Privy Council) in domestic law a decade or so ago.    I’m not suggesting that foreign investors are any better or worse than domestic businesses – but we shouldn’t treat them differently. As I noted in an earlier post, previous great eras of foreign investment flourished without the need for such additional protections.

And while perhaps it is true that key points in any negotiations go down to the wire, shouldn’t we be uneasy that at this very late stage, such indications as there are suggest that the prospects of trade liberalisation gains that matter to New Zealand don’t look good? Dairy gets a great deal of attention in our media, but I wonder just how important any progress on liberalising it is in any other capitals? There seem to be more countries who care about resisting liberalisation, or for whom it just doesn’t matter, than who really care much about securing more dairy liberalisation.   That doesn’t sound like a recipe that leaves our negotiators much leverage.

And no doubt there is considerable truth in the proposition that negotiations need to take place in private.  No doubt, equally, if there was a will there would have been a way to be more open than the TPP process has been. After all, we used to think domestic government deliberations should be protected from public scrutiny as well. Now we subject them to extensive consultative processes, and the scrutiny of, for example, freedom of information acts.

Negotiations in private are a delegation of responsibility, by New Zealanders to responsible ministers. And trust is an important dimension of any delegation. Perhaps trust might be a little higher if New Zealand had a Trade Minister who, however competent, comes out with statements like this

“This is a moving game, and we need adults to do this – not breathless children to run off at the mouth when the deal is not actually finished.”

I guess he is old enough to have been a public servant before the Official Information Act.  But after a decade in Parliament those sorts of attitudes really aren’t good enough –  perhaps the only saving grace is that he is indiscrete enough to say what perhaps others only think.

I’ve expressed concern previously about the momentum that takes hold in these sorts of processes.  These negotiations have been going on for years.  New Zealand ministers and officials have prided themselves on having a key administrative role in them.  So how willing is the government, really, to walk away, on a hard-headed (rather than wishful) assessment of whether any deal actually benefits New Zealanders.  And will other hard-headed governments think New Zealand will really be ready to walk?  On its own.

Our Trade Minister is rumoured to be about to head off to Washington as our next ambassador, and the Prime Minister appears to enjoy his good relationships with, and easy access to, people like the Barack Obama.  Basic agency theory suggests we shouldn’t just assume that their interests (or any other past or future ministers) are sufficiently aligned with those of the principals –  New Zealand citizens and voters.  To walk away might mean putting ourselves “outside the club”, whatever that specifically means.  At a time when the government appears to be revelling in its position on the UN Security Council (and I still struggle to take seriously the idea of New Zealand as a key player, whether in the cause of Middle East peace, or the Security Council veto), there might be more reasons than usual to question how willing the government will be to step away if only a bad economic deal is finally on the table.

Perhaps the issue won’t arise.  Perhaps Malcolm Bailey’s comments this morning that the current dairy offers (whatever they are) should be “unthinkable” for New Zealand are just part of some orchestrated positioning exercise, with a bit of MFAT choreography, to try to prod slightly better offers out of our trading partners. But, at the moment, what we read and hear in the media doesn’t sound promising.  It doesn’t sound enough for even those instinctively inclined to support liberalisation to think that we New Zealanders would be better off it we signed up.    Bad deals have been done in past –  the Australian-US FTA –  and we can’t just assume away the possibility.

Of course, if a deal is signed it will still have to be ratified by Parliament (and through domestic processes in other countries).   No doubt the government will have a rough ride through that process –  no matter what deal is signed –  but equally I’d have thought that the support of ACT and United Future shouldn’t be hard to secure, and that there is little serious threat to its ability to secure ratification.

But if an agreement is signed, it is going to be important that there is serious scrutiny of it before Parliament is asked to ratify it.  There will lots of vocal commentators, and no doubt some of them will make useful and reasoned points that contribute to the debate.  But we need more than that, on what will be quite a detailed agreement.  We need a serious independent assessment of economic implications of whatever ministers have signed.  Perhaps the Productivity Commission could be invited to oversee that analysis. As it happens, the Commissioners include a former Secretary to the Treasury, and a former Director-General of Agriculture.  I doubt that the Productivity Commission currently has the in-house expertise at present to do the detailed work itself, but with the ability to (for example) contract modelling expertise the PC should be able to make a useful assessment, better informing any pre-ratification debate.

How is core inflation going to get back to 2 per cent?

No doubt I should find something more useful to do, but out walking by the sea in the sun, one aspect of Graeme Wheeler’s speech, and story, was still puzzling me. How, except perhaps by chance, does he expect to get core inflation back up to the target midpoint again in the remaining two years of his term?

Recall that:

  • core inflation, at around 1.3 per cent, is a long way from the midpoint of the target range
  • the PTA mandates the Governor to focus on the “medium-term trend in inflation”, and on keeping “future average inflation” (not one year’s headline rate) near the 2 per cent target midpoint.
  • The Bank reckons real GDP is currently growing at an annual rate of around 2.5 per cent
  • And its best estimate of the rate of growth in potential GDP is around 2.6 per cent
  • Inflation expectations are quite close to the target midpoint – and lower, relative to target midpoint, than they have been at any time in the history of inflation targeting.
  • The Bank’s current estimate of the output gap (June MPS) is around zero.
  • And, although not mentioned in the speech, the unemployment rate is above any reasonable estimate of the NAIRU.

There is nothing in that mix that would tend to raise core inflation from where it is at present.

A conventional model would suggest that to lift core inflation, quite substantially, from around 1.3 per cent to around 2 per cent would take some combination of a lift in medium-term inflation expectation (what people are treating as “normal” rate of inflation when negotiating contracts, and borrowing and lending), and a period in which some fairly material pressures build up on resources (“excess demand”). Increased pressure on resources would require a period, looking ahead, in which growth runs faster than potential and, probably, where the unemployment drops below the NAIRU.

Perhaps any temporary increase in headline inflation, on account of the lower exchange rate, will boost inflation expectations a little, but any lift would be unlikely to be sustained without some new resource pressures

But where is this faster growth going to come from?  I searched the speech in vain. The Governor talks of a few factors that might “support” economic growth. He lists “continued high levels of migration and labour force participation, ongoing growth in construction and continued strength in the services sector”. But note the repeated word: “continued”. We’ve had all these things over the last 12-18 months, and they generated “a little below trend growth”. Big increases in immigration boost growth rates, but steady high rates of immigration just, at best, maintain them. Construction activity had stepped up a long way over the previous couple of years, but few commentators (or indicators) suggest the rate of growth will be sustained. And all this is before the decline in the terms of trade – which easier monetary conditions may or may not adequately offset – has had its full effect, on the farm or in the wider economy.

If the rate of potential growth really is around 2.6 per cent, then it increasingly looks as though New Zealand needs two or three years of perhaps 4 per cent growth to be confident of getting core inflation to settle back around 2 per cent. If the NAIRU is 5 per cent, perhaps we need a couple of years with unemployment down around 4.5 per cent to lift core inflation back to around the target midpoint.

These are the sorts of outcomes we might have had in a more normal recovery. But – partly because monetary policy has been kept too tight – our recovery has been anaemic. At present, these sorts of outcomes seem likely only if the OCR is cut quite a bit more than the Governor currently seems to envisage.

But in a sense the ball is in his court. Perhaps he could tell us how he expects to see core inflation reverse the seven or eight years of decline, and get back to around the midpoint of the target range  What will boost growth sufficiently, and cut unemployment rate sufficiently, to put sufficient additional pressure on resources to achieve a substantial lift in the “medium-term trend in inflation”?

And all this assumes that the Bank is correct that growth is still around 2.5 per cent. We only have March quarter GDP data, and it is now almost half-way through the September quarter. I have seen some commentators suggesting that the June quarter may already have been weaker than would be consistent with 2.5 per cent growth. I have no idea if they are correct, but, if so, the challenges facing the Governor in getting core inflation back to target will be even greater than those I have outlined here.

In the speech, the Governor put quite some emphasis on the troublesome clause 4(b) in the PTA, and especially the highlighted words

In pursuing its price stability objective, the Bank shall implement monetary policy in a sustainable, consistent and transparent manner, have regard to the efficiency and soundness of the financial system, and seek to avoid unnecessary instability in output, interest rates and the exchange rate.

I describe the provision as troublesome because ever since Don Brash and Michael Cullen added it to the PTA no one – Bank, Minister, Board, markets – have ever known quite how to apply it. I’d just make two observations:

  • The medium-term price stability objective is paramount, and the medium-term trend in inflation is currently a long way from the mandated target midpoint.
  • Against that backdrop, more (upside) variability in output growth looks to be necessary.  Few people object to extra growth, especially when the starting point is one of no apparent pressures on resources or core inflation and lingering high unemployment..

Falling commodity prices and the unsettled world environment mean that it would be difficult for the Bank to deliver a couple of years of 4 per cent annual GDP growth even if they set out now to try. But as things are heading at present, the risks of something rather closer to 0.4 per cent growth are rising. Better to aim for 4, and perhaps deliver 2.5. If 4 per cent growth actually happened, inflation would start heading back to target and more of the people currently unemployed would be in jobs. And if only 2.5 per cent growth was achieved it might be enough to stop unemployment rising again. From where we stand right now, it is far from obvious what is lost, or even risked, by a more aggressive stance.

PS:   As it is, in pondering the Bank’s record on inflation in recent years –  it just isn’t there when they think it will be –  the old rhyme came to mind:

Yesterday upon the stair

I met a man who wasn’t there

He wasn’t there again today

I wish, I wish he’d go away

When I came home last night at three

The man was waiting there for me

But when I looked around the hall

I couldn’t see him there at all!

Go away, go away, don’t you come back any more!

Go away, go away, and please don’t slam the door

Last night I saw upon the stair

A little man who wasn’t there

He wasn’t there again today

Oh, how I wish he’d go away