What does the Governor say to the unemployed?

Graeme Wheeler yesterday gave a speech on current monetary policy issues and challenges. It was accompanied by an unusually long press release, and is probably best seen as a commentary, and elaboration, on the brief OCR statement released last week. I commented on that statement here.

I thought it was a very disappointing speech.

There is still no sign that the Governor recognises that he made a mistake in raising the OCR 100 basis points last year, in talking of further rate hikes as late as last December, and only beginning to cut rates in June. The fact that a mistake was made really should be blindingly obvious, even to him, by now. It should have been acknowledged and serious steps made to reverse it, and then we could move on. Instead, reluctance to acknowledge the mistake seems to have locked him into a mind-set in which he is now willing to cut the OCR as new weak data emerge, probably 25 points at a time, but is unwilling to unwind the excessively tight conditions he put in place last year. He repeatedly talks of GDP growth rates around 2.5 per cent as if these are good outcomes, but New Zealand’s population is estimated to have grown by 1.8 per cent in the last year. After an anaemic recovery, New Zealand is already experiencing weak per capita growth, before the full impact of the sharp fall in international dairy prices (let alone any threat from a weakening Asia) has been felt. And it is idle to talk repeatedly of the “need” for a lower exchange rate when he is personally deciding to hold the OCR at levels higher than the inflation target would appear to require.

Far too much weight in the speech is given to headline CPI inflation. As the Policy Targets Agreement has put it for years:

For a variety of reasons, the actual annual rate of CPI inflation will vary around the medium-term trend of inflation, which is the focus of the policy target.

The Governor has stated very explicitly in this speech that the Bank’s preferred measure of core inflation is the sectoral factor model measure. That measure it has its weaknesses, but it has the longest time series of any of the measures the Bank publishes, and it tends to be the measure I use most often too. As it happens, estimated sectoral core inflation over recent years has been being progressively revised downwards. And at 1.3 per cent now (and having been below 2 per cent for five years now) it is not just a “bit” (the Governor’s word) below the midpoint. For a very persistent slow-moving series, this is a huge deviation. “The medium-term trend of inflation” is nowhere near the 2 per cent target midpoint the Bank is required to focus on.

sectoral core

The Governor downplays this in two ways.

First, he explains away current low headline inflation mainly by reference to the fall in international oil prices and the rise in the exchange rate last year. Which is fine, and no serious observer is focused on headline inflation. But the Governor doesn’t mention tobacco tax increases, which have “artificially” and substantially boosted headline inflation in recent years. The Governor quotes the PTA to the effect that headline CPI inflation might deviate from the medium-term trend because of “shifts in the aggregate price level as a result of exceptional movements in the prices of commodities traded in world markets” [ie oil prices], but doesn’t mention that the next reason listed in the PTA is “changes in indirect taxes”. As I noted last week:

• Even with the rebound in petrol prices, CPI inflation ex tobacco was -0.1 over the last year – this at the peak of a building boom.
• CPI ex petrol inflation has never been lower (than the current 0.7 per cent) in the 15 years for which SNZ report the data.

We develop core inflation measures to adjust for these sorts of effects. Five and a half years with core inflation (on their own preferred measure) below the target midpoint, by slowly increasing margins, is a sign of a Bank that has got monetary policy repeatedly wrong. And that matters more under Graeme Wheeler, because he explicitly signed up to the focus on the target midpoint. Alan Bollard, by contrast, could (and did) point out that the midpoint had no special status in his PTAs.

And then the Governor tells us that he expects inflation to be back to target midpoint by the middle of next year. But here he is not talking about the “medium-term trend of inflation”, but about headline inflation. All else equal, if oil prices and the exchange rate stay around current levels, headline inflation is likely to pick up somewhat over the next 12 months. But the speech says nothing at all about the expected path of core inflation, or medium-term inflation measures more generally. A lower exchange rate provides a boost to the domestic price level, all else equal, but that just means the headline inflation rate rises for a year or so. What happens after that? As the Governor acknowledges, the Bank has overestimated medium-term or core inflation in recent years, but he offers us nothing, at all, to give us reason to believe that that situation has changed.   There is no sign of any correction to what has led them astray for the last few years.

For the last 15 years or so, the Bank has generally sought to “look through” the direct price effects of exchange rate changes, precisely because they usually tell us little about the underlying state of inflation pressures. Doing anything else – putting much weight on those direct effects in setting policy – risks the Bank holding the OCR higher than the medium-term trend in inflation would warrant. Not just the PTA, but plenty of good economic theory also, encourages the Bank to focus on the stickier prices, captured in (for example, and imperfectly) non-tradables or core measures.

In fact, some of the Bank’s own quite recent research suggests that we might not see even much of an increase in headline inflation. Here is one of their researchers, Miles Parker, in a paper published last year:

The net impact of a fall in the international prices of the commodities New Zealand exports  on the consumers price index (CPI) has been to lower New Zealand consumer prices, even  though the exchange rate has tended to fall when export commodity prices fall. Falls in  export commodity prices leave New Zealanders as a whole poorer and so domestic  spending, and pressure on domestic labour and capital, tends to ease. For exchange rate depreciations caused by other factors there appears to have been little net effect on  aggregate consumer prices, since a rise in tradable CPI inflation has been broadly offset by  a fall in non-tradable CPI. For each of these classes of exchange rate changes, the inflation  outcomes implicitly include the average response of monetary policy to such exchange rate movements over the period.

In other words, falls in the exchange rate happen for a reason, and have often been accompanied by such a significant weakening in economic conditions that they have often been associated with further falls in non-tradables and core inflation measures. That has to be a real risk now, as falling real (terms of trade) incomes and slowing growth in construction activity take hold.

What else is there to say? A few scattered observations:
• The Governor rightly observes that “in most advanced economies, policy interest rates are at historic lows”, but one could go further. In all OECD countries, except New Zealand, policy interest rates are lower (or no higher) than they were at the start of last year. New Zealand has seen no sign of the sort of medium-term inflation pressures that would have warranted – or warrant now – such a stance. The Bank thought such pressures would emerge, but they were wrong. Mistakes happen, but they need to be acknowledged and corrected for.
• I find it extraordinary that the Governor continues to articulate a view that high immigration has eased inflation pressures (outside the Auckland house market presumably). Until the last 12 months or so, the Reserve Bank has for decades consistently operated on the assumption, well-supported by data, that (whatever the possible long-term benefits) the short-term demand effects of immigration dominate the supply effects. Indeed, that result is apparent in the Bank’s own quite recent published research. Here is a picture from a 2013 Analytical Note

chris mcdonald
• It is puzzling that there is no mention of unemployment in the speech at all. It isn’t a fool-proof indicator by any means, but is probably better estimated and more easily interpreted that output gap estimates which the Bank continues to rely on (despite the inability of the Bank’s existing models to explain inflation). At 5.8 per cent, New Zealand’s unemployment rate is still disconcertingly high. It is all very well to laud rises in the participation rate, but there is no evidence that New Zealand’s NAIRU is anywhere near as high as 5.8 per cent. Many real people – with lives currently blighted by unemployment – would have been back in jobs if the Reserve Bank had not set the OCR so high over the last 18 months. What, I wonder, does the Governor have to say to these people when he meets them?

• This passage in the speech seemed particularly ill-judged:

Central bankers have found the post Global Financial Crisis (GFC) years to be a very challenging time for conducting monetary policy. High expectations have been placed upon central banks at a time when the economic, financial and political interlinkages in the global economy seem more complex, and where monetary policy has become the fall-back policy to promote a strong global recovery.

Few people will have much sympathy with highly-paid powerful officials bemoaning how difficult their job has been in recent years, as the Governor seems to.  He has options.

Many of the problems central banks in other countries have faced relate to running into the near-zero lower bound on nominal interest rates. New Zealand (and Australia) have not yet got anywhere near that floor. There is no evidence of “high expectations” having been placed on the Reserve Bank of New Zealand – indeed, the dismal inflation track record, with no obvious adverse consequences for the Bank, might suggest a central banking equivalent of the “soft bigotry of low expectations”. The Governor complains that “monetary policy has become the fall-back policy to promote a strong global recovery”. Most New Zealanders would have settled for a strong domestic recovery, but we just have not had one. It has been the weakest domestic recovery for many decades, despite the record terms of trade, and the boost to demand from a Christchurch-led building boom.

In a sense, the whole point of discretionary monetary policy is to allow monetary policy to promote strong bounce-backs when demand falls away and recessions happen. With hindsight it is clear that lower policy interest rates over the last five years would have given us both a stronger recovery, and a medium-term trend in inflation nearer the inflation target. There were no policy obstacles to doing so. I’m not suggesting there are no puzzles in the global events of the last few years, but if you have trouble reading the future, just look out the window and respond to the best estimates of the medium-term trend in inflation. Core inflation has been below target midpoint since December2009, and not once – not for a single quarter – has the OCR been cut below the level that prevailed back then.

• The Governor repeats a claim that “our economy has generated better growth…than many other advanced economies”. As I have documented on several occasions, and in several ways, while our total GDP growth has been relatively high, that is only because our population growth has been much faster than most. Growth in GDP per capita, or in any of the productivity measures, has been no better than mediocre, even relative to other countries’ weak performances. Quite why we have done so badly is still a bit of a puzzle, but endless repetition of an alternative wished-for story does not make it true.

• Somewhat puzzlingly the Governor claims that “some local commentators have predicted large declines in interest rates over coming months that could only be consistent with the economy moving into recession”. Actually, it isn’t only local commentators, but set that to one side. With core inflation measures so low, and no evidence adduced that core inflation measures are about to rise materially, it would be quite easy to make the case for a 2 per cent OCR right now. There was never any need for the OCR to have been raised at the start of last year (from 2.5 per cent) and core inflation pressures and measures are weaker now than they were then.  At present, with the threat from a weakening Chinese economy increasing, the risk is that having held the OCR too high for too long materially increases the chances of a couple of quarters, or more, of negative GDP growth. And the Governor needs to get some perspective on the scale of short-term interest rate falls that tend to happen in real recessions: 700 basis points over the 1991 recession, 550 basis points in the mild 1997/98 recession, and 575 basis point OCR cuts in 2008/09.  Against that background, arguments as to whether the OCR gets to 2.5 per cent or 2 per cent, from a recent (ill-judged) peak of 3.5 per cent, are interesting but bear no relationship to what any serious recessionary threat might require.

There are many more points I could make. There are puzzling sentences like “having the scope to amend policy settings, however, is a key strength of the monetary policy regime”. I’m not sure when anyone last suggested a regime in which policy settings could not be amended, but perhaps I missed something.  But I’ve probably taxed readers’ endurance enough already.

New Zealand deserves a lot better than this: better policymaking and better quality analysis and communication of the issues. And, of course, it is increasingly past time for reform of the governance of the Reserve Bank, to put considerably less power in the hands of one imperfect individual, the Governor (any Governor).

Meanwhile, what does the Governor say to any of those 146000 unemployed people he meets?

Reforming the governance of the Reserve Bank

The Green Party leader, James Shaw, has just put out a press release highlighting the Reserve Bank’s persistent forecasting errors, which have had the effect of keeping the number of people unemployed higher than it would otherwise have been in recent years.  James Shaw uses that record to reinforce the argument that too much power is vested in a single unelected individual, the Governor, and that the governance model of the Reserve Bank should be reformed, as (for example) The Treasury has previously argued.

As I have noted previously, the Bank’s serious forecasting errors are not primarily the fault of the single decision-maker model.  There was, unfortunately, widespread support at the Bank last year for the OCR increases, and it would have been hard even for a more independent committee to have resisted the push for the early increases.  But the succession of policy mistakes (eg having twice had to reverse OCR increases in the last five years) does reinforce the more fundamental arguments for a better, and more conventional, governance structure for the Reserve Bank.  It is not governed the way most central banks are, or the way most New Zealand government agencies are.  Even among central banks, only the Bank of Canada puts the legal authority to set the policy rate with the Governor alone, and the Bank of Canada Governor has a much less extensive range of powers than Graeme Wheeler (and his predecessors) have had.

I outlined my own case for governance reform here.

The Reserve Bank itself has been working on the issue.  I lodged an OIA request some time ago for

copies of any papers done by the Reserve Bank on statutory governance issues in the last two years  (i.e. since 1 July 2013).  To be specific, I am requesting:

  • any papers (draft or otherwise) provided to Treasury or the Minister of Finance on these issues
  • any papers provided to the Governor or the Governing Committee on these issues
  • any internal working or discussion papers on governance issues
  • any file notes or other records of discussions on these issues between the Governor, and the Secretary to the Treasury and/or the Minister of Finance.

The Bank has just extended my request for another month, telling me that they have found 9786 records or documents they need to check.  I suspect that means the initial search wasn’t very well-targeted, but there should be a few interesting documents to emerge in a month or so.  It will be interesting to see what model of change the Bank would prefer, if and when change comes, and their assessment of the pros and cons of the various approaches to dealing with the governance of the wide range of issues the Bank is given responsibility for.

It is a shame that the current government appears unwilling to address the issue.  It is one of those areas where change will almost certainly come, to bring Reserve Bank governance into line with modern public sector practice and the current responsibilities of the Bank.  It won’t surprise readers that I’m not a natural supporter of many Green Party issues, but I give them considerable credit for continuing to chip away at this issue.

Dairy lending and the Minister of Finance

I saw this Bernard Hickey piece yesterday afternoon, and have been mulling on it since.

Finance Minister Bill English has admitted the Government and Reserve Bank are in discussions with banks to ensure they don’t prematurely force dairy farmers into mortgagee sales that could trigger a dangerous spiral lower in land values.

If accurately reported (which it may not be), it is somewhat disconcerting.  What bothers me is the notion that the Minister of Finance (and perhaps the Governor of the Reserve Bank, although there is no confirmation of any involvement by the Bank) thinks he knows better than banks how to run their own businesses. Ministers of Finance often aren’t very good at presiding over the government’s own businesses – Solid Energy or Kiwirail anyone?

During the 2008/09 recession I did quite a lot of work at Treasury on dairy debt. Debt, and dairy land prices, had run up extremely rapidly in the previous few years, and there was concern about what the fall in commodity prices, and the seizing up in international funding markets, might mean for the dairy sector as a whole, and for those who financed them. I reminded the perennial optimists that the long-term real average dairy payout had been around $4.50 and that it would seem unwise to be planning (whatever one might hope for) on anything much higher in the medium-term future.

During that period, I took to describing dairy debt as “New Zealand’s subprime”. My point here was not that large losses were inevitable (in fact, in that episode NPLs did pick up quite notably, although not in a systemically-threatening way), but that the nature of the risk exposures were not generally well understood. At the time, banks were very dependent on wholesale market funding, and few offshore investors appreciated just how large New Zealand banks’ exposures to farms were (I recall checking out the US flow of funds data and finding that in an economy 100 times our size, farm debt in the US was only around 10 times that in New Zealand).

It was also never entirely clear that the Australian parents really appreciated the scale of the dairy debt boom, and competitive credit-supply war, their New Zealand subsidiaries had gotten into. And, of course, the market in agricultural land was not the most liquid in the world – like many markets there was reasonable liquidity in booms, and almost none in busts.   That illiquidity meant that it was very difficult for anyone to know the true value of the collateral underpinning dairy debt. As it was, dairy land prices fell very sharply (and never subsequently fully recovered the boom time peaks) even with very few forced sales. One of the risks of lending secured on farm land was that if one lender got very worried and starting a round of forced sales, it would seriously undermine the market value of the collateral other banks were holding. They all knew that – and they also knew about the goodwill in the rural community that had been burned off in the period of financial stress in the 1980s. And that created an incentive for what I describe as “hand-holding” – each tacitly agreeing (probably not in ways that create legal difficulties) to approach forced sales very very cautiously. That might seem a good outcome in some respects, albeit at the expense of transparency. In 2009 perhaps, with hindsight, it was: the downturn in dairy prices proved short-lived, and the recovery in the payout bought time for banks to manage out of their worst exposures.

But we didn’t know then, and we don’t know now, how long the low payouts will last for, and what either a market-clearing or equilibrium price for dairy land is. And when I say “we”, I include experts, stray bloggers, and the Minister of Finance and the Governor of the Reserve Bank. Uncertainty is a key feature of economic life, and one that people in positions of power too readily underestimate. There is probably a selection bias – people without a strong self-belief (and belief in their own views) tend not to end up at the top of politics. In some dimensions, the current position seems more worrying than the 2009 episode. Not much new debt has been taken on in recent years, and there hasn’t been a recent spiralling-up in land values. That suggests little risk of a systemic threat to the health of the banking system (but as I have noted previously it is not clear that the minimum risk weights the Reserve Bank requires on dairy exposures are really high enough). But, on the other hand, whatever is dragging milk prices so deeply down now is not the side-effect of a global liquidity crisis, the direct effects of which were reversed pretty quickly. Global commodity prices have now been trending down for several years, and there is little obvious reason to expect the trend to be reversed – although no doubt there will be plenty of volatility.

Perhaps there is nothing more to this story than a natural politician’s desire to sound sympathetic to business owners who find themselves in difficult conditions. I hope so.  But the Minister of Finance and the Governor of the Reserve Bank hold a lot of power over banks, and the fact that those statutory powers exist suggests it is even more important that the Governor and Minister avoid putting pressure on banks to make decisions that might suit a politician, but might not be in the interests of bank shareholders. Banks aren’t popular, but they are legitimate and important businesses, who are expected to make a return and act in the best long-term interests of shareholders. Plenty of times some discerning forbearance may have helped through a key customer in difficult times, but forbearance – whether by bank or regulator – can also be a recipe for worse problems, and bigger losses, down the track. The risks of that are much greater when people with no financial stake weigh in to try to tilt the attitudes of lenders. Neither the Minister nor the Governor has the information to make those calls well regarding dairy debt. In the Governor’s case, it is little more than a year since he gave this relentlessly optimistic speech, and I’m sure that without too much difficulty I could find similar examples from the Minister of Finance – it is, after all what ministers do.

Here is a link to my own piece on dairy debt from a couple of months ago.

Are we really better off than everyone but the US and Canada?

Yesterday I wrote that

the single economic issue that I care about most is reversing the decline in New Zealand’s relative economic performance that has been going on, in fits and starts, since at least the middle of the twentieth century, if not longer.

A few minutes after posting that I noticed a story about some new work by Arthur Grimes and Sean Hyland of Motu, in which they suggest that perhaps there isn’t a problem at all.   One of the authors was also nice enough to get in touch and alert me to it.   As they put it

“…New Zealand households have amongst the highest material living standards in the world”

They have quite a long technical working paper, which I have dipped into to answer some specific questions but have not read in full. But the seven page Motu Note, “The Material Wellbeing of New Zealand Households” tells, and illustrates, the story in a very accessible way. It also covers some consumption inequality results which I’m not going to touch on here at all.

Grimes and Hyland attempt to develop a measure of material wellbeing, using as their basis the durable goods held by households that have a fifteen year old in them.

This framework is applied to household level data from the OECD’s Programme for International Student Assessment (PISA) surveys, which include questions regarding the presence of household durables in the 15-year-old respondents’ homes, covering 16 consumer goods which range from the inexpensive (books), to expensive consumer durables (cars), whiteware (a dishwasher), utilities (an internet connection), and housing characteristics (the number of bedrooms and bathrooms in the house). This allows us to construct a dataset of household possessions for almost 800,000 households, covering 40 countries in the years 2000, 2009 and 2012.

And here is the picture with the headline-grabbing results. Having had below-average growth for the previous 12 years, these New Zealand households had, on this measure, material living standards in 2012 higher than the PISA-15 year olds households in all the other countries, except Canada and the United States.

grimes hyland

I found the exercise (which has been funded by a Marsden Fund grant) an interesting one, and yet I wasn’t really convinced. Here are some of the reasons:

  • How confident are the authors that PISA sample schools have been selected on the same basis in each country they look at?  PISA isn’t mainly designed to generate wellbeing measures, and any differences there will immediately flow into these durable consumption results.  I have read stories previously of strategic national selection of PISA sample schools
  • The general thrust of recent literature has been towards measuring some concept of wellbeing broader than GDP (or GNI, or –  better still – NNI, the gross income of New Zealanders, less depreciation).  It wasn’t clear to me why this particular subset of types of households, and types of consumption, should be thought superior to even traditional measures of consumption.
  • It wasn’t clear to me why durables consumption should be considered particularly important (except perhaps that the data are available in this sample).
  • Since the authors only look at the possession of these durables, not at the cost of them, they don’t factor in how much the cost of these items might squeeze out other consumption.  As a simple example, Amazon books are much more expensive here than in the United States (on account of transport costs).  We have a lot of them in our house, and less of other stuff than we otherwise would.
  • Perhaps these results might be relevant to child poverty debates, but we are typically more interested in how a country’s economy supports the consumption of all types of households within it.
  • Since the birth rate in, say, New Zealand, is much higher than that in, say, Italy, a typical Italian household with a 15 year old probably has 0-1 sibling, while a New Zealand household has 1-2.  In what sense are the consumption results then comparable?
  • And what about the many other consumption items.  For example, clothes, or restaurant meals, or foreign holidays (the latter more costly here than in, say, Belgium).  Perhaps access to beaches and mountains is a plus here, but access to good newspapers, and great museums and art galleries certainly weighs in favour of people of most of these countries over New Zealand.  And what of health or education spending –  actual individual consumption, but often provided by the state?
  • While it is reasonable to prioritise consumption over production, we know that savings rate vary quite widely across advanced economies.  Today’s savings support tomorrow’s consumption.  GNI (or NNI) measures provide a better sense of the consumption possibilities an economy generates than a particular subset of current consumption.

In wrapping up this post, I’m going to leave you with two charts.

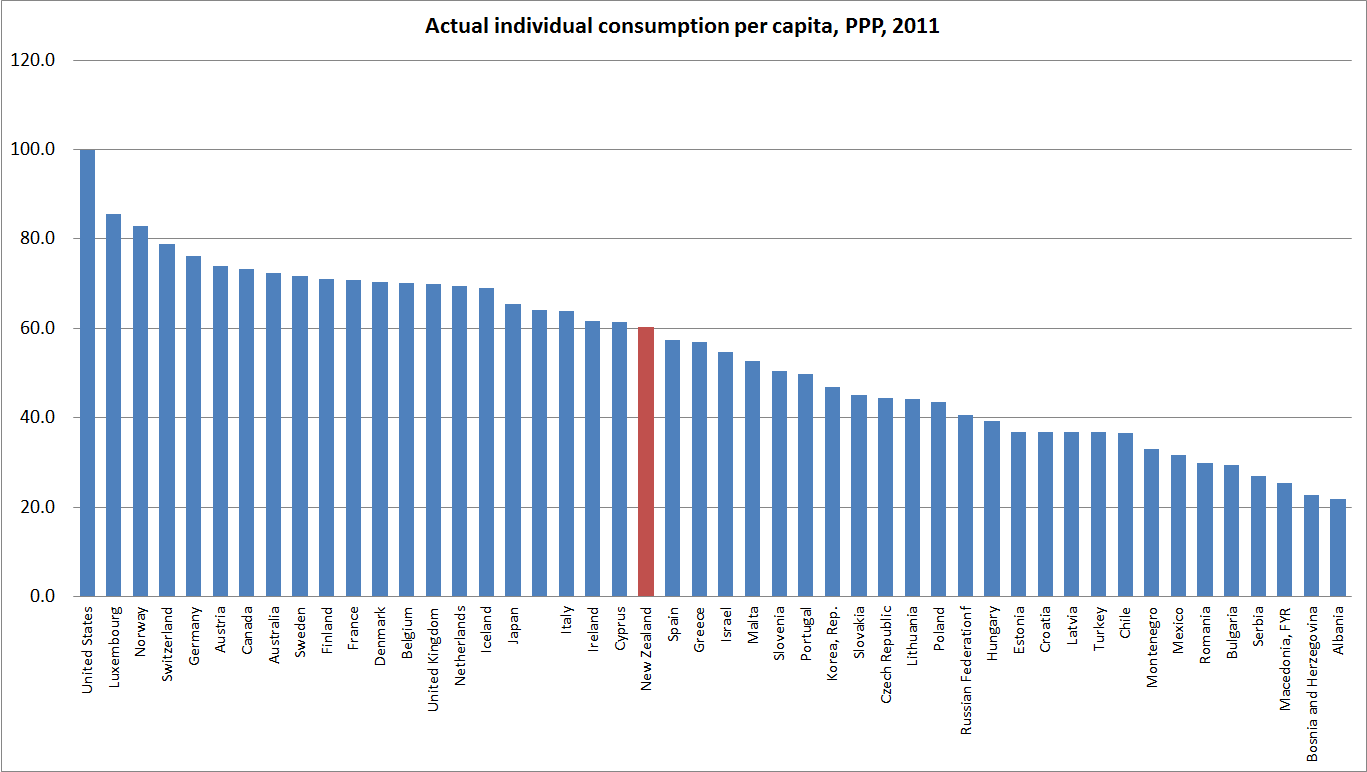
The first is from the 2011 World Bank International Comparisons Programme. They have developed a measure of actual individual consumption, across almost all countries, at purchasing power parity values (ie adjusting for the differences in what things cost across countries). Here are the per capita results for the subset of OECD-Eurostat countries (a slightly larger group than Grimes and Hyland use).

aic

Of these 46 countries, New Zealanders’ average consumption – across types of people – falls squarely in the middle of the pack, well behind most of the older OECD countries. Our ranking here looks quite similar to the rankings people are familiar with from GDP per capita, or even NNI per capita, charts. It isn’t a perfect measure, but it is much more comprehensive that the Grimes-Hyland one, and it isn’t obvious why it is misleading us about the material aspects of life in New Zealand relative to other advanced countries.

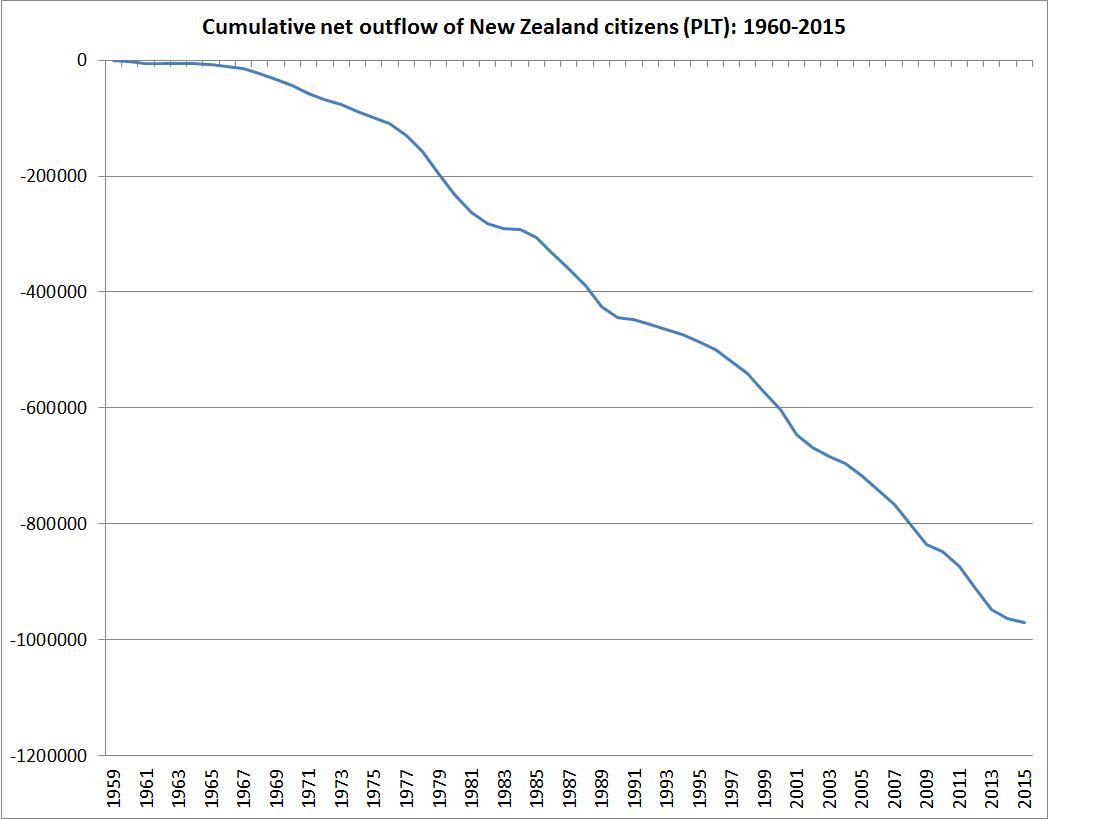
The final chart is just relevant to the New Zealand vs Australia comparison. On the Grimes-Hyland measure we score very similarly to Australia. Frankly that seems implausible as a representation of relative material living standards. Why? Because for fifty years large numbers of New Zealanders (net) have been leaving New Zealand, overwhelmingly for Australia.  Very few Australians have come the other way. There is quite a lot of cyclicality in the flow, but the trend is very clearly in one direction only.

cumulative plt since 1960

It wasn’t that way when more traditional GDP per capita estimates suggested that New Zealand and Australian economies were level-pegging. I entirely agree with authors who say that GDP per capita (or even NNI per capita) are not the be-all and end-all. People don’t change countries based on national accounts aggregates, or other international agency wellbeing measures. They are presumably changing countries because they believe the new country offers sufficient better material living standards, for them or their children, to offset the loss of the intangibles of home, extended family, and a culture and institutions one knows.   The choices people make reveal their preferences, and it is unlikely that over decades they’ve got it systematically wrong (after all, they could have come home again, as many did). None of us knows how much poorer material living standards are here than in Australia, but we can be pretty confident they are now, and have been for some decades, worse.

(Real researchers can stop reading here, but..) I helped the 2025 Taskforce put together their first report, on closing the gap with Australia. The report focused on policy, and as the primary underpinning for the analysis used national accounts measures, but at their request I put together this – purely illustrative – box. I stress the words “purely illustrative”- it was a matter of what I could find quickly. It isn’t comprehensive, but – as the box concludes – that is why we have, and try to improve, national income and expenditure accounts. 


Box 1: What do Australians get with their higher incomes?

Digging down to look at what people in the two countries actually consume can give a more tangible sense of the differences between New Zealand and Australian material living standards. Again, what is important in different climates varies, and tastes differ. But comparing living standards in New Zealand and Australia is easier than in most pairs of countries because the tastes and expectations are broadly similar.

These data are sometimes less reliable than the national accounts. Sometimes they are not compiled by national statistical agencies but by industry bodies. Even when statistical agencies are involved, things aren’t always measured exactly the same way in different countries. There is no single decisive fact. This box simply illustrates that across a very wide range of things that different people value or like to consume, the typical New Zealander has less than the typical Australian. Starting with where we live: the average size of a new Australian house or apartment built in 2007 was 212 square metres. In New Zealand, the comparable average was 193 square metres. Or what we drive: Australians have 619 cars per 1000 people, while New Zealanders have 560.

New Zealanders work more to earn our lower incomes: 887 hours a year are worked per head of population, as compared with 864 hours per head in Australia. Australians live longer: 81.1 years, compared with 80.2 years in New Zealand. Fewer people in Australia (111 per 100,000 people) die of heart disease each year than do in

New Zealand (127 per 100,000 people). Many fewer people die on the roads there: 7.8 each year per 100,000 people in Australia, 10.1 each year in New Zealand.  Australians have more televisions (505 per 1000 people) than New Zealanders do (477 per 1000 people). And there are more broadband subscribers (10.3 per 100 people, compared with 8.1 per 100 in New Zealand).

There are more cinemas per million people in Australia (92.4) than in New Zealand (82.2). And more mobile phones too (906 per thousand people versus New Zealand’s 861 per thousand). Australians drink more than New Zealanders: both alcohol (9.8 litres per capita versus 8.9 litres) and fruit juice (34.4 litres per capita versus 24.8).

This isn’t comprehensive by any means – that is why we have national income accounts. And there are some measures on which New Zealanders have more than Australians. Australia has 34.9 McDonalds outlets per million people, but New Zealand has 36.9 per million.

Lending to investors: still no smoking gun

I hadn’t paid any attention to the Reserve Bank’s new data providing somewhat more disaggregated information on new (ie the flow not the stock) residential mortgage lending. But the Herald’s cover story this morning sent me off to have a look.

There is only 10 months of data, and the housing market has some seasonal features. And the mortgage market has already been distorted by the Reserve Bank’s first set of LVR controls – which were always likely to have impinged most heavily on first-home buyers – so we aren’t even getting a clean read on the underlying patterns of mortgage demand.   But, from my perspective, the data reveal very few surprises, and the only thing that really took me by surprise was a pleasant surprise.

Here were a few of the points I noted as I worked my way down the Bank’s spreadsheet:

  • By value, 69 per cent of new mortgage loans over these 10 months were to owner-occupiers.  30 per cent were to “investors” (they have a residual category called ‘business” accounting for around 1 per cent).  According to the most recent census, the proportion of houses that was owner-occupied was less than two-thirds.  (The two numbers aren’t directly comparable, as local councils and Housing New Zealand own significant numbers of rental properties.)
  • By number, 81 per cent of new mortgage loans over these 10 months were to owner-occupiers.
  • By value, 15 per cent of loans to owner-occupiers were to first home buyers.  That might have been a touch lower than I expected.  First home buyers will generally be borrowing a larger proportion of the value of the house, but will also be buying cheaper houses.  FHBs will have been disproportionately squeezed by the Reserve Bank’s LVR controls.
  • By number, 8 per cent (by number) of owner-occupier loans were to FHBs over this period, but they accounted for a third of all owner-occupier loans with LVRs above 80 per cent.
  • Investors accounted for only 11 per cent (by number and value) of over 80 per cent LVR loans.
  • By number, 27 per cent of new FHB borrowers were borrowing in excess of 80 per cent LVR, and about 4 per cent of other owner-occupier, and investor borrowers.

high lvrs

  • 46 per cent of new investor loans were for LVRs of over 70 per cent (for some reason, the Bank is not collecting/reporting this data for the other categories of borrowers).

Almost all of that was quite unsurprising. And note that although the Herald devotes a lot of space to contrasting “first home buyers” with “investors”, it would seem more natural to compare all owner-occupier borrowers with all investors. Just possibly a comparison between FHBs and “first investment property purchasers” might be interesting, but we don’t have that data.

Perhaps the one thing that surprised me a little was how little high LVR lending has been going to investors over this period. Unfortunately, the period is distorted by the Bank’s controls, and it is at least possible that banks have been favouring FHBs since the LVR restrictions were put in place. And although the reporting is done at a highly aggregated level, I have heard stories of an upsurge in the proportion of loans being written by 79 per cent LVRs. If so, there is little or no effective risk reduction.   The Reserve Bank keeps on asserting that 70 per cent LVR loans to investors are just as risky as 80 per cent loans to owner-occupiers, but as Ian Harrison has been arguing, as yet they have produced little or no robust evidence to support that assertion.

I suppose what I take from these data is that, once again, there is no smoking gun to justify the Governor’s apparent determination to ban banks from lending a cent to residential rental services businesses in Auckland, when they have even a moderately high LVR.   Banks and borrowers are deeply irresponsible, and the Governor knows better….or so we are apparently to believe.   Recall that, across the whole country, between 3 and 4 per cent of new investor mortgages in the last 12 months have had initial LVRs in excess of 80 per cent.  Even if the number is double that in Auckland (and I’m not aware that anyone has that data), it hardly has the feel of reckless lending or borrowing behaviour.

The Reserve Bank has produced no evidence of any serious deterioration in lending standards. Add into the mix the still rather modest rate of growth in overall household lending, and the very encouraging results of the Reserve Bank’s own 2014 stress tests, and the case for such intrusive restrictions – with all the attendant efficiency and distributional costs – imposed by a single unelected official, is just not convincing.  Even if there were more substantial evidence to support the Governor’s concern, the soundness and efficiency of the financial system –  the only goal towards which the Bank can use its powers –  would be at least effectively protected, at less cost to individuals and to economic efficiency, through higher capital requirements.

The government’s immigration policy changes

The Prime Minister yesterday announced several changes to New Zealand’s immigration policy. This is an extract from the Minister of Immigration’s press release.

New measures to take effect from 1 November include:

  • Boosting the bonus points for Skilled Migrants applying for residence with a job offer outside Auckland from 10 to 30 points. [They require 100 points]
  • Doubling the points for entrepreneurs planning to set up businesses in the regions under the Entrepreneur Work Visa from 20 to 40 points.  [They require 120 points]
  • Streamlining the labour market test to provide employers with more certainty, earlier in the visa application process.

“Unemployment across the Mainland is nearly half that of the North Island, and labour is in short supply,” Mr Woodhouse says.“We’re looking at offering residence to some migrants, who have applied at least five times for their annual work visa. In return, we will require them to commit to the South Island regions where they’ve put down roots.”

Mr Woodhouse says the Government is also considering a new Global Impact Visa to attract high-impact entrepreneurs, investors and start-up teams to launch global ventures from New Zealand.

“I will announce further details later this year, but we envisage this visa would be offered to a limited number of younger, highly talented, successful and well-connected entrepreneurs from places like Silicon Valley,” Mr Woodhouse says.

I can’t see any background analysis to these measures, either on the MBIE website or with the Minister’s press release.  On the face of it, however, this looks like a set of measures that will, on balance, to undermine the quality of New Zealand’s immigration programme.

We all know about the infrastructure pressures in Auckland –  largely self-inflicted by central and local government.  Perhaps trying to steer some of the immigrants away from Auckland might temporarily ease some of those pressures a little.  But there is a price to be paid. Providing a significant increase in the number of points available for people with job offers outside Auckland must lower the likely average quality of incoming immigrants.  There is no sign that the permanent residence approvals target (135000 to 150000 on a rolling three year basis) is being increased, so people going to the regions –  taking advantage of the additional points for doing so – will be at the expense of otherwise better-qualified people who would have gone to Auckland.    Under the new policy, people will only have to stay in the regions for a year, so perhaps it will make only a very small difference over time to the number of immigrants who end up in Auckland.  But the ones who do come in, taking advantage of these additional points, will be – on average – less good quality people than the applicants who are squeezed out (people who might have a job offer in Auckland –  our highest paying and –  at least in a statistical sense –  most productive city).    Perhaps I’m missing a significant strand in the reasoning, but I can’t see the likely long-term economic gain for New Zealand.

The Global Impact Visa idea sounds superficially promising. But my impression from the Pathways Conference last week was that existing entrepreneur visa schemes had not worked particularly well.  It will be interesting to see the analysis behind this proposal, including an assessment of how the risks around it will be managed and overcome.  I remain a little sceptical of the attraction of New Zealand to “younger, highly talented, successful and well-connected entrepreneurs from places like Silicon Valley”.  The flow of people in that sector would seem more naturally to be in other direction.  I hope it is not an example of the old derogatory adage used about Britons working in Hong Kong:  FILTH  (“failed in London, try Hong Kong”).

Welcome to new readers

Welcome to readers who have visited this blog since my Q&A interview yesterday. Although the most recent post was on Australian monetary policy, my focus here is on New Zealand issues. The range of topics I touch on reflects some, slightly random, mix of my fairly wide-ranging interests, my experience, my reading, and what pops up in newspapers, speeches, or other blogs here and abroad.

The single economic issue that I care about most is reversing the decline in New Zealand’s relative economic performance that has been going on, in fits and starts, since at least the middle of the twentieth century, if not longer. We’ve done badly.  I want New Zealand to be a place my kids want to stay in, rather than joining the diaspora – the more than 900000 New Zealanders (net) who’ve left since 1970.

But much of the content of the blog so far has been on issues relating to housing, financial stability and banking regulation, and the Reserve Bank. That mostly reflects what has been going on in New Zealand this year, and choices that the Reserve Bank in particular has made. When I gained my freedom earlier in the year I didn’t set out to focus on the Bank. I think they’ve been making some poor calls – both on monetary policy, and around banking regulation – but even in respect of the Reserve Bank I’m more interested in advancing the cause of institutional reform than in this year’s specific decisions.

For the last couple of months, I have been categorising my posts so anyone new to the site can find a way in to the various topics I’ve covered. But for anyone interested in some more substantial pieces of my argumentation, you could try these links:
• A speech I gave in May on the “blunders of our governments”, that are primarily responsible for high house prices.
• A speech given at a LEANZ seminar in June on “Housing, financial stresses, and the regulatory role of the Reserve Bank”.
• A paper issued in May making the case for reforming the governance of the Reserve Bank
• My recent submission on the Reserve Bank’s proposal to restrict access to mortgage finance for residential rental businesses in Auckland.

In terms of the longer-term economic performance issues:
• This paper, written in 2013 for a Reserve Bank/Treasury forum on exchange rate issues sets out how I’ve been thinking about the issues.
• And these more-speculative speech notes also from 2013 take a longer-term perspective on New Zealand’s relative economic decline.

I welcome comments, and have been pleased (not to say relieved) at the tone that commenters have maintained. Thoughtful discussion and debate matter, and I hope that in some small ways this site can contribute.

Glenn Stevens on monetary policy

I’ve long had a great deal of time for the Reserve Bank of Australia. It is an institution made up of human beings, so they make mistakes from time to time (for a while, for example, their relentless optimism about China reminded one of a sell-side analyst) but it has been a strong institution for decades, successfully developing successive generations of governors and senior managers. Successful organisations tend to promote from within. The RBA publishes thoughtful analysis, and the speeches of senior managers are usually well-worth reading. I don’t recall any major innovations originating at the RBA, but they’ve avoided policy debacles like the MCI experiment, or rapid policy reversals.  All things considered – and setting to one side the serious issues around Note Printing Australia – I think the RBA has had a reasonable claim to having been one of better advanced country central banks in recent decades. At times, no doubt, fortune has favoured them. And perhaps too, there is a little in the old proverb about the grass always being greener on the other side.

Anyway, I was reading Glenn Stevens’ most recent (and quite short) speech, “Issues in Economic Policy”, on some of the challenges the Australian authorities, and the Reserve Bank in particular, face at present. The Governor grouped his remarks under four headings:

  • Negotiating turbulence (the international environment)
  • Accepting adjustment
  • Maintaining stability, and
  • Securing prosperity (a rather general discussion of the place of microeconomic reform)

What struck me, and prompted this post, was how scarce references to inflation were in the speech.  The Reserve Bank’s primary policy responsibility is the conduct of Australia’s monetary policy.  As the (non-binding) Statement on the Conduct of Monetary Policy between the Treasurer and the Governor put it:

Both the Reserve Bank and the Government agree on the importance of low inflation.

Low inflation assists business and households in making sound investment decisions. Moreover, low inflation underpins the creation of jobs, protects the savings of Australians and preserves the value of the currency.

In pursuing the goal of medium-term price stability, both the Reserve Bank and the Government agree on the objective of keeping consumer price inflation between 2 and 3 per cent, on average, over the cycle. This formulation allows for the natural short-run variation in inflation over the cycle while preserving a clearly identifiable performance benchmark over time.

There are only two references to inflation in the speech.  In the main one he observes:

A period of somewhat disappointing, even if hardly disastrous, economic growth outcomes, and inflation that has been well contained, has seen interest rates decline to very low levels. The question of whether they might be reduced further remains, as I have said before, on the table.

But the thrust of what followed was a bit surprising:

But in answering that question, it is not quite good enough simply to say that evidence of continuing softness should necessarily result in further cuts in rates, without considering the longer-term risks involved. Monetary policy works partly by prompting risk-taking behaviour. In some ways that is good: in some respects, there has not been enough risk-taking behaviour. But the risk-taking behaviour most responsive to monetary policy is of the financial type. To a point, that is probably a pre-requisite for the ‘real economy’ risk-taking that we most want. But beyond a certain point, it can be dangerous.

Deciding when such a point has been reached is, unavoidably, a highly judgemental process. And that is after the event, let alone beforehand. My judgement would be that policy settings that fostered a return to the sort of upward trend in household leverage we saw up to 2006 would have a high likelihood, some time down the track, of being judged to have gone too far. That is not the case at present, given the current rates of credit growth and so on. But the point is simply that in meeting the challenge of securing growth in the near term, the stability of future economic performance can’t be dismissed as a consideration.

It was as if the authors of the BIS Annual Reports had managed to infiltrate the RBA’s speechwriting team. The point of this post is not to make the case for further cash rate cuts in Australia. On the surface, some further easing looks warranted to me, but I’m not close enough to the Australian data to be confident of that view. My point is that the Governor looks here to be risking taking his eye off the inflation ball, and downplaying short-term macro stabilisation for some ill-defined concern about the longer-term. In any economy adjusting to an investment slump a reasonable case might be made that insufficient risk-taking is going on. And since there are no reliable direct benchmarks for the appropriate degree of risk-taking, a simpler benchmark might be levels of excess capacity in the economy. An unemployment rate of 6 per cent – above any estimates of NAIRU that I’ve seen – might reasonably suggest a need for rather more risk-taking across the economy, if the people who are unemployed are relatively quickly to find jobs.

The Governor goes on to note that “policy settings that fostered a return to the sort of upward trend in household leverage we saw up to 2006 would have a high likelihood, some time down the track, of being judged to have gone too far”. Central bankers worry about periods of rapid growth in credit and asset prices, but it is a curious historical episode to cite. After all, Australia came through that period of leveraging up (which had more to do with the interaction of planning restrictions and rapid population growth as with anything to do with monetary or banking policy) rather well. And if some of that was down to the good fortune of the terms of trade, it isn’t obvious that countries like New Zealand or Canada suffered seriously from the aftermath of rather similar domestic credit booms (although of course, post-2007 growth has been weak almost everywhere). There was little or no evidence that lending standards became pervasively and seriously too loose in Australia (or New Zealand or Canada) during the pre-2007 booms

Perhaps I’m over-interpreting the Governor, but his comments have a bit of a feel about them of the Swedish Riksbank’s ill-fated experiment in using monetary policy to lean against household debt accumulation, rather than keeping their eye firmly focused on the medium-term outlook for inflation. Economists and central bankers don’t know that much about appropriate levels of debt or about what macro policy can do about them. By contrast, we have a stronger sense of when the numbers of people unemployed are above normal, and a rather better (although far from foolproof) sense of what monetary policy can do about that, especially in periods when core inflation pressures (domestically and globally) are pretty quiescent (core inflation measures in Australia seem to be at or below the midpoint). And in Australia, the Reserve Bank’s Act explicitly enjoins the Bank to run monetary policy in a way that best contributes to “the maintenance of full employment in Australia”.  For practical purposes that doesn’t override a medium-term focus on keeping inflation near-target, but it does rank rather higher in the statutory list of considerations than visceral unease about the possibility, at some point down the track of excessive risk-taking.

On an unrelated point, for any readers interested TVNZ’s Q&A programme yesterday pre-recorded an interview with me, to be shown tomorrow. The questions were mostly around the Reserve Bank of New Zealand: actions, inactions, and frameworks. Unless I said something I really didn’t mean to say, I don’t think there is anything in the interview that regular readers won’t have encountered before. One question – how worried should we be about the New Zealand economy – caught me a little by surprise, and I’ve been reflecting further on that. I might jot down some thoughts on that here on Monday.

Immigration, and the evidence of things not seen

In the biblical book of Hebrews, there is a verse that reads “Now faith is the assurance of things hoped for, the evidence of things not seen”.

It seemed to be rather like that at the Pathways Conference that I attended part of in Wellington yesterday morning.  The Pathways conferences were established back in the 1990s and are held annually “to disseminate publicly funded research on international migration and demographic change”.  I hadn’t been to one before, and it looks like an excellent initiative, at least in principle.  The issues around immigration (here and abroad, past and present)  are fascinating and we (and other countries no doubt) need a “reasoned and deliberate” debate on immigration policy[1].  Funding enables the conference to be held at no cost to the participant, and enables academic and public sector researchers to discuss research results and immigration-related issues.  Given the significance of immigration in New Zealand, and the way it is seen as a significant “economic lever” (in the words of a senior MBIE official at the conference), we need scrutiny and debate.

There were around 120 attendees, but not a single member of the media.  That surprised me.   When I counted up the delegate list. almost 50 per cent were public servants (although I was a little surprised that no one from Treasury was there).

I suspect I may have been the only person present even mildly sceptical about the benefits of New Zealand’s immigration programme.  Certainly, none of the papers I heard, no comments from the floor, and none of the summaries of the remaining papers betrayed a shadow of doubt.      In fact, so certain of the direction of the argument were the organisers that they describe this year’s conference as being about “how New Zealand can better respond to these demographic changes in order to maximise the benefits associated with an increasingly diverse population”.  Perhaps there are such benefits, even net, but it would be better to demonstrate them, than simply assert them.  The tone of the conference –  supposedly about presenting publicly funded research  –  was apparent early on when the Minister of Immigration twice thanked conference attendees for all they (we?) did for “our migrant communities”.   And here I thought immigration policy was undertaken for the benefit of New Zealanders, whatever benefits there might be to the migrants themselves.

The contrast with the Australian Productivity Commission’s inquiry, which I wrote about last week, was striking.   There seemed to be no interest in questioning whether there were benefits, and if so who might be securing those benefits.  Nor much interest in innovative ideas (eg charging for migrant entry).  The Australian inquiry may well lead to no material changes in policy, but at least it should assure the Australian public of a serious and dispassionate analysis of the issues and options.

The Conference was described as being under Chatham House rules.  That seemed a little odd, at least in respect of the main presentations (as distinct from comments/questions from the floor), since the purpose was supposed to be about disseminating publicly funded research, to the public.    But the programme is on the web (see link) above.

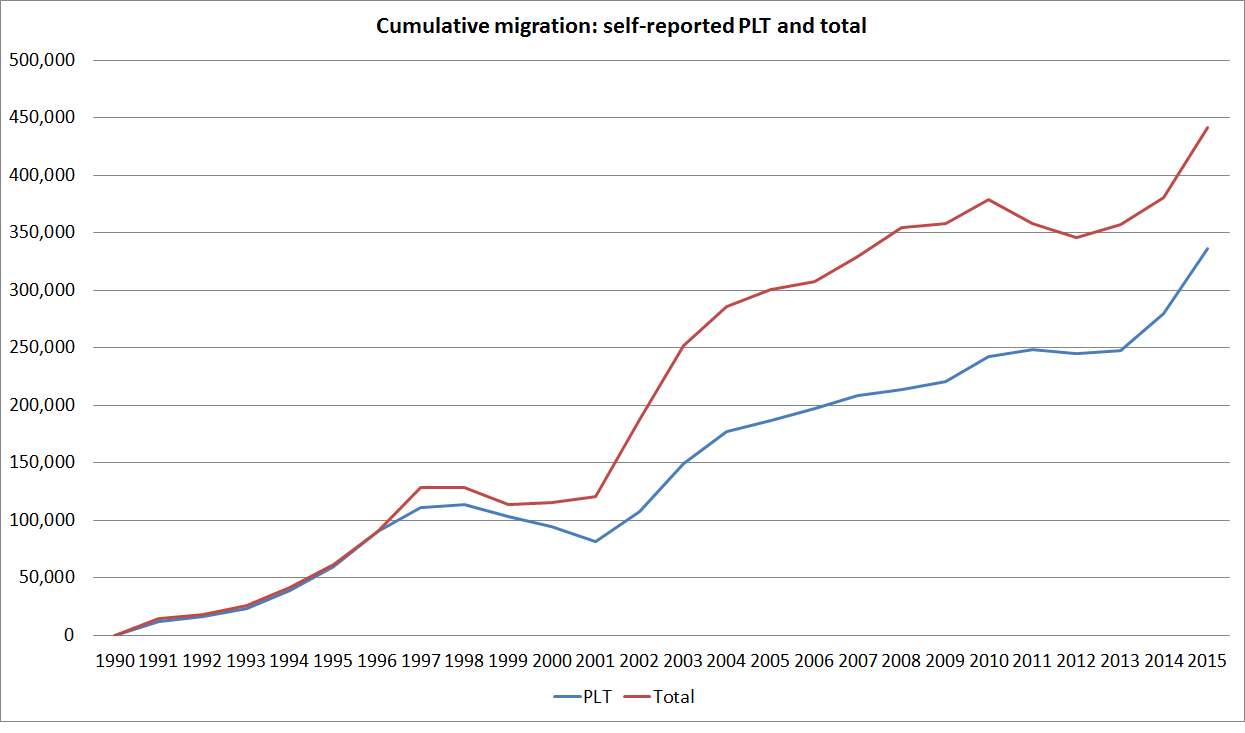
I found the Minister’s speech rather unimpressive.  The organisers described it as a “keynote” but it was anything but.  Unfortunately, I can’t quote from it, but suffice to say he appeared unimpressed by anyone –  be it the Herald, or perhaps even stray bloggers (with long-outstanding OIA requests in for departmental advice on immigration targets) –  suggesting that waves of migrants were putting pressure on resources or infrastructure.  A keynote actually addressing some of the issues might have been interesting.  And although the Minister and MBIE seem keen to remind people of the weaknesses of the PLT immigration data, they omitted to point out that in recent decades net PLT immigration has understated (not overstated) the net number of people coming to New Zealand.

cumulative plt since 1990b

In fact, what was striking about the morning was how little there was to give a listener any confidence that the “economic lever” (New Zealand’s immigration programme) was doing New Zealand much good.  I went along to listen, and was prepared to be sceptical.  But I didn’t really need to be.  Because what I heard wasn’t very encouraging at all.  Listening to people discussing the problems of designing an entrepreneur visa, for example, I became more sympathetic to the idea of auctioning migrant places.  And anguished talk of concern about how many migrants were going into low productivity sectors, rather than “where we want them to go” had much the same effect, and a desire to reach for my copy of Hayek, on knowledge problems etc.  The central planning tone (no doubt unselfconscious) was quite disconcerting.

One of the MBIE papers is on the web.  It discusses some work on investor migrants –  who already, in effect, buy their way into New Zealand.  The aim of the programme is to import people with business expertise and entrepreneurial skills, presumably to boost productivity in New Zealand.  And yet in these surveys of people at various stages of the investor migrant process  (and  in which respondents must have been at least partly motivated to give the answers MBIE wanted to hear, even if results were anonymised), 50 per cent of the money investor migrants were bringing in was just going into bonds, and only 20 per cent was going into active investments.  We aren’t short of money, but may be of actual entrepreneurial business activity.  And 70 per cent were investing only the bare minimum required or just “a bit more”.  And these people aren’t attracted by the great business opportunities in New Zealand, but rather by our climate/landscape and lifestyle.  It doesn’t have the sense of being a basis for transformative growth.  As even a fairly pro-immigration academic observed, New Zealand isn’t exactly likely to be first choice for the sort of person who might build the next great tech company.

In much of the debate around immigration in New Zealand it seems that people can’t quite make up their minds what sort of immigration we want.  On the one hand there is considerable emphasis on highly-skilled migrants. I can see the logic of that argument, even if I’m sceptical of what difference it might make.  But on the other, there was repeated discussion of the role immigrants play in the aged care sector and in the dairy sector.  Such migration is no doubt good for the migrant (migration usually is) but the basis on which it assists in lifting per capita incomes, and medium-term productivity, for New Zealanders is much less apparent.  As one senior official put it to me recently, the logic of bringing in large numbers of people to work cheaply on dairy farms isn’t obvious.  It may just allow farmers to bid land prices higher, or perhaps compensate for the self-inflicted problem of an overly high real exchange rate.

So there wasn’t much to go on if one wasn’t sure of the benefits of immigration in New Zealand.  But if you went along already convinced then no doubt faith carried you through the accounts of the practical limitations of how our immigration programmes actually work.

And, of course, I know that this was just one conference, and there are lots and lots of papers on immigration.  But few or none of them show, with any confidence, that New Zealanders are securing economic gains from this substantial economic lever that successive governments have sought to deploy.  We need a reasoned and deliberate debate, perhaps with our own Productivity Commission inquiry.

[1] Readers may recall that that was Shamubeel Eaqub’s description of the sort of debate he wanted about immigration, at least before he responded to my analysis with the label “racist”, a slur he has still not withdrawn.

How about giving inflation a chance

The Governor’s OCR press release this morning held few surprises. Disappointments, yes, but not really any surprises. Given that in the June MPS the Governor had articulated only a fairly modest change of view, and had refused to acknowledge any sort of mistake in how monetary policy had been run last year, it was hardly surprising that, at a review between MPSs, at which he does not have the benefit of a full new set of forecasts, he wasn’t willing to cut by 50 basis points, as some had suggested was likely.  From the tone of the news release, such a cut probably wasn’t even seriously considered.

But if two cuts in six weeks might have broadly kept pace with the deteriorating data over the last couple of months, it does not make any inroads into the overly tight policy put in place when the Governor (and his advisers) misread inflation pressures last year. And that is the bigger problem. The Bank still seems to think it has things broadly right.

Here was my list of some sobering inflation statistics from my post last week in the wake of the CPI

Reciting the history in numbers gets a little repetitive, but:

• December 2009 was the last time the sectoral factor model measure of core inflation was at or above the target midpoint (2 per cent)

• Annual non-tradables inflation has been lower than at present only briefly, in 2001, when the inflation target itself was 0.5 percentage points lower than it is now.

• Non-tradables inflation is only as high as it is because of the large contribution being made by tobacco tax increases (which aren’t “inflation” in any meaningful sense).

• Even with the rebound in petrol prices, CPI inflation ex tobacco was -0.1 over the last year – this at the peak of a building boom.

• CPI ex petrol inflation has never been lower (than the current 0.7 per cent) in the 15 years for which SNZ report the data.

• Both trimmed mean and weighted median measures of inflation have reached new lows, and appear to be as low as they’ve ever been.

This, by contrast, is the Bank’s take:

Headline inflation is currently below the Bank’s 1 to 3 percent target range, due largely to previous strength in the New Zealand dollar and a large decline in world oil prices.

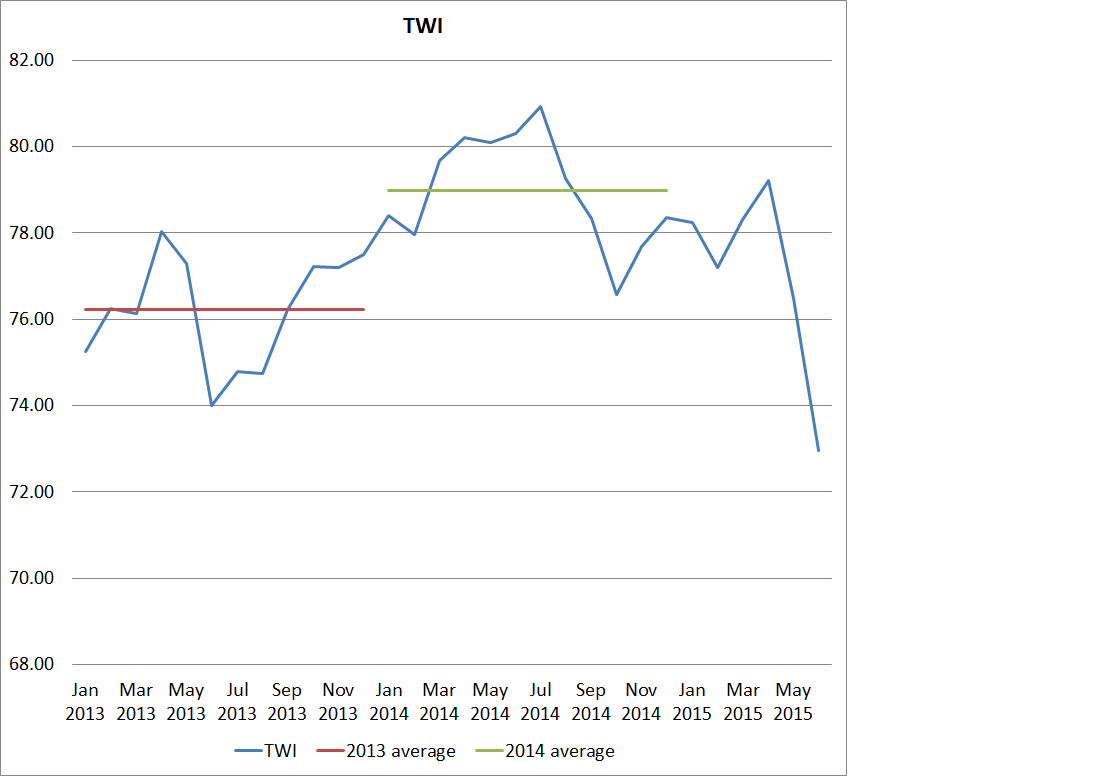
It just doesn’t wash.  CPI inflation ex-petrol was 0.7 per cent in the year to June.  CPI inflation ex tobacco (large excise increases) was…..actually not inflation, but slight deflation, a fall of 0.1 per cent in the last year.    And what of the exchange rate?  Direct exchange rate effects are not that large these days, but typically pass into consumer prices quite quickly (and one of the fastest routes is through petrol pricing).  The TWI in 2014 was around 4 per cent higher than in 2013, but that increase probably only subtracted around 0.4 percentage points from the annual inflation rate.  And as the TWI peaked in the middle of last year, the effect might have been even smaller by the year to June, the most recent CPI inflation we have.

twi to june 15

Focusing on headline inflation, as the Bank does in the extract above, seems like an effort to distract attention from the surprisingly weak core domestic inflation, whichever indicator of it one prefers to concentrate on.  And that weakness came at the very peak of a major building boom.

I was also a bit disappointed to see this sentence in the statement

While the currency depreciation will provide support to the export and import competing sectors, further depreciation is necessary given the weakness in export commodity prices.

Today would have been a good opportunity to have backed away from commenting on the exchange rate, except as it affects the inflation outlook, in these statements.  What does “necessary” here mean?  I assume it means something about stabilising the NIIP position (as a % of GDP) at a lower level, or improving the long-term growth prospects for New Zealand.    But that has nothing to do with monetary policy.  The nominal exchange rate is not an instrument in the Governor’s toolkit, and the real exchange rate is…well…a real phenomenon.  I happen to agree with the Governor’s unease about the level of the real exchange rate, but it is an endogenous real phenomenon.  Better for the Governor to focus on getting core inflation back to around the target midpoint  –  not just headline, relying on direct price effects of the lower exchange rate.  As it happens, the OCR path consistent with that obligation of the Governor’s would probably lower the exchange rate somewhat further as well.

I’ve made the point  previously, but will state it again.  When the Reserve Bank –  even more than other international central banks –  has misjudged inflation pressures for so long, it would be better for them now to err on the side of running policy a little looser than they really think wise.  Clearly there is something wrong in their mental model of inflation at present (and I’m not suggesting anyone else has a fully persuasive alternative), but after years of such low inflation, it might no bad thing if core inflation ended up a little above the target midpoint for a few quarters a year or two down the track.  I’m not suggesting a price level target, just that the policy reaction function needs to take more, and more aggressive, account of the repeated over-forecasting of inflation, and inflation pressures.  Among others, the 5.8 per cent of the labour force still unemployed might appreciate the chance to get back to work.