Len Bayliss RIP

I wasn’t planning to write anything today, but in the death notices of the Dominion-Post I noticed this morning the passing of Len Bayliss, one of the most prominent New Zealand economists of a previous generation (late 1960s to, say, the late 1980s).

I only met Len once, but when I first came to Wellington in the late 1970s he was a prominent public figure, and I was enough of a political/economic junkie to get a bit of a buzz from the fact that one of his sons was in my class at Rongotai College and that, for a year or two while I was at university, Len often caught the same bus into town each weekday morning as I did.

Len was born and educated in Britain, but wanted to get out of the United Kingdom after finishing his degree at Cambridge.  Eschewing South Africa for laudable reasons, he wrote to various banks and government agencies in Australia and New Zealand, and after an interview that seemed to be not much more than a cup of tea with a visiting Deputy Governor passing through London he was hired by the Reserve Bank of New Zealand in 1951, where he spent quite a few years in a vibrant economics department.

He moved on to the Monetary and Economic Council, and played a key role in that agency’s 1966 report calling for liberalisation of the financial sector –  which wasn’t particularly popular with the bureaucratic establishment.  But his most prominent perch was as the long-serving Chief Economist of the (state-owned) Bank of New Zealand, where he openly championed sound economic management and liberalisation.  In the early years of Muldoon’s Prime Ministership he served on the Prime Minister’s Policy Advisory Group and appears to have played an instrumental role in the financial liberalisation that government undertook in 1976/77.   Of Muldoon in this role he wrote

Excellent. He was the best boss I’ve ever had. Absolutely decisive. I wrote his speech for the Mansion House dinner, the most important speech he’d made after becoming PM. I gave it to him. He said send it to Treasury and see if it’s all right with them. They wrote back wanting something changed and wrote a little memo and he just put ‘No’. And he always was very proper. He may have been tough to his political opponents but as Bernard Galvin used to say, certainly in the time I was there, it was a very happy group. He never tried to force you to do anything. In a sense, he treated you just like a public servant, as a politician should treat them. He was decisive. He would argue very intelligently. Watching him at the Cabinet Economic Committee, he really tore strips off ministers who hadn’t done their homework. And I saw him several times in debates with Noel Lough [Deputy Secretary to the Treasury]. Noel Lough was a lovely bloke but Muldoon really won the debates.

After his secondment ended, Bayliss returned to the BNZ, from where a few years later, having become increasingly critical of the economic management of the New Zealand economy, he was put in a position where –  under fire from Muldoon, and with no support from the supine BNZ Board and management –  he felt he had no choice but to resign (at considerable financial cost to himself).

In the post-liberalisation year, Bayliss served on the Board of the BNZ, and he recounted in his published works the frustrations of trying to constrain a management gorging on bad credit, and eventually driving the bank to the point of failure.

At a macroeconomic level he had long-favoured liberalisation and stabilisation (cutting inflation, balancing the budget) but in the post-liberalisation decade he was increasingly uneasy about the persistently high real exchange rate –  a concern that he (rightly in my view) never lost.

As I said, I only met Len once –  although we had corresponded a bit since –  when the New Zealand Association of Economists asked me to record, and edit, a long interview with him (as part of a series on the life and work of prominent New Zealand economists).  The text of that interview has quite bit that might interest those concerned with the history of New Zealand economic and financial policy.

In preparing for that interview, I had been focused on the earlier decades and didn’t give the attention it warranted to his departure from the BNZ or his later time on the Board.   But

…as he records it, that interview and some follow-up questions from me prompted him to put together a volume of documents and recollections  –  Recollections: Bank of New Zealand 1981-1992  – dealing with his ouster from the BNZ and his later term as a government-appointed director of the BNZ as it descended into crisis and near-failure in the late 1980s and early 1990s.

And I used that material last year for a post on his ouster from the BNZ, having finally got under the skin of the Prime Minister once too often.

When some academic finally writes the definitive history of the financial debacle/crisis in New Zealand in the late 80s and early 90s, I hope they take time to draw on the perspectives and papers Bayliss has apparently lodged at Massey University.

His was a courageous voice, unusual for its day.  In an environment in which few could speak –  there weren’t many economists outside government –  it was a valuable contribution in articulating the increasing unease about New Zealand’s economic underperformance and poor economic management.

UPDATE (Oct 18)):  I was asked by the New Zealand Association of Economists to write an obituary.   It is on page 6 of the April 2018 issue of their newsletter Asymmetric Information.


A curious suggestion

There was a curious suggestion in the New Zealand Initiative’s new report on the handling of the Canterbury earthquakes and possible ways ahead.  Almost in passing they suggested that perhaps one way of handling failed insurance companies might be to consider an insurance company version of the Open Bank Resolution (OBR) scheme, that now sits in the toolkit as one (not terribly credible, in my view) instrument that might be used by a government to help manage a bank failure.

I think I see what motivated the suggestion.  After the February 2011 quake, AMI failed, but instead of being allowed to close, with losses lying where they fell, the government (backed by –  questionable –  advice from The Treasury and the Reserve Bank) launched a bail-out.  No policyholder lost anything.   It set a terrible precedent –  and wasn’t cheap either (final costs as yet unknown).   And the OBR scheme had been motivated by a recognition that governments would probably prove relucant to let major banks close –  how, for example, would solvent firms make their payrolls next week if their bank, relied on for overdraft facilities, suddenly closed?   Rather than jump straight to a bailout –  which would be expensive, send terrible signals about future distress episodes, but which would keep the lights on and the doors open – the OBR option was designed to allow a failed bank to remain open without any direct injection of public money.  Losses would rest with creditors and depositors, but the payments system and the information-intensive business of business credit needn’t be directly disrupted.

As I say, the New Zealand Initiative people really only mentioned the issue in passing, but interest.co.nz picked up the reference and devoted a substantial article to it, including an interview with my former Reserve Bank colleague Geof Mortlock.  So it is worth giving more space to my scepticism than the NZI reference alone would typically warrant.

In doing so, it is worth stressing that:

  • banks and insurance companies are two quite different sorts of beasts,
  • keeping a failed company open and operational is, at least in concept, a very different issue than protecting depositors or policyholders once a failure has happened.

Most of rely on banks being there almost every day.  Whether we rely more on cash –  and thus use an ATM every week or so –  or mostly on direct electronic payments, we count on our bank being there.  Incomes flow into bank accounts –  be it wages, welfare payments, or whatever –  and we count on being able to use those accounts to make routine payments, including things as elemental as food.   Businesses often rely on bank credit to make routine payments, including such regular commitments as wages or materials.  For small businesses in particular, those credit relationships are not easily or quickly re-established (and perhaps especially not if a bank with a quarter of all the country’s small businesses failed).

So there is quite a plausible case that there is some wider public interest in keeping the doors of a (large) failed transactions bank –  Lehmans might be quite a different issue –  open, even if the bank has been badly managed enough to have failed.   There is a basic utility dimension to some of the core functionality.   That is the logic of OBR –  creditors (including depositors) should take losses, if losses there are, but keep the doors open and the payments flowing (even if the available credit balances are less than depositors had been counting on).

What about insurance companies?  I’m sure most of you are like me.  You pay your bills each year, and hope never to have any other contact with an insurance company ever.  And even when bad things do happen, there (a) isn’t the same immediacy as about buying today’s groceries, and (b) a bad thing happening today isn’t generally followed by another bad thing happening tomorrow.

And banks are prone to runs in ways that insurance companies aren’t.  They are just different types of contracts, for different types of products/services.

But focusing on insurance companies, it is worth unpicking the two possible (decent, economic) reasons why people might make a case for keeping a failed insurance company open, even with writedowns of policyholder claims.

The first relates to the immediate interests of people with claims outstanding at the point of failure.  Typically that will be quite a small number of people  (in which case there is no real public policy interest at all, and the failed company can simply be allowed to close, as was done with one other small insurer after the Christchurch quakes), but not always.   AMI was brought low by one specific set of events –  the Canterbury quakes –  affecting quite a large chunk of their policyholders.    Had AMI simply been left to fail, and normal commercial procedures taken their course, what would have happened?  The policyholders with claims outstanding at point of failure (including those with houses damaged/destroyed in the quakes) had no particular interest in AMI continuing to trade as a going concern.  They just wanted their claims settled, to the maximum extent possible.  Wouldn’t a liquidator have needed to work out how large those claims actually were –  an issue still in dispute in some cases –  and then made a final division of the assets (including reinsurance) assets of the firm among all the creditors, including policyholders with claims?

Policyholders with outstanding claims had two interests:

  • being paid out (whether in cash, or new home –  under replacement policies) in full, or as near as possible, and
  • being paid out expeditiously.

Liquidation is unlikely to bring about either, but neither is an OBR-type of instrument.  The whole point of an OBR is that losses fall on policyholders with outstanding claims, and a statutory manager operating under an OBR faces much the same issues as a liquidator –  needing to know the final value of all outstanding claims before final payments can be made and (thus) losses allocated.

So the interests of policyholders with outstanding claims can either be met by a bailout –  often at considerable direct Crown expense, and rather bad market discipline incentives (although the role of reinsurance might mean those effects as less bad for banks) –  or by a policyholder protection scheme, something similar in conception to deposit insurance.  This is an option canvassed in the interest.co.nz article (and which I also favour, as a second best).   Such a scheme –  funded by levies on policyholders with cover –  could be rather better tailored.

As I’ve noted, one reason OBR will probably never be used is because losses will fall as heavily on “innocent” grannies as on sophisticated offshore wholesale investors.   There is public sympathy for one group, but not the other.  Deposit insurance allows that distinction to be drawn.     No doubt the same goes for the creditors of insurance companies.  There is likely to be a great deal of sympathy for a poor family with a modest dwelling caught up in an extreme series of earthquakes –  and an unwillingness to see them face, say, a one-third write-down in the value of their claim.   But probably no one (other those directly involved) cares greatly if a family trust with a $4 million house in Fendalton and an expensive holiday home in Akaroa finds that, after the failure of their insurer, they can afford to spend only $2 million on a new house.   It was one of the offensive things about the AMI bailout that everyone –  rich and poor, sophisticated and not –  was bailed out in full.

And so I probably would favour some sort of statutory policyholder protection scheme.  I’d probably limit it to house insurance, fund it through levies on policyholders, and perhaps payout 100 per cent of claims for the first, say, $500000 of a claim, 50 per cent of the next $500000, and then leave people to the market for sums beyond that.   It would meet most of the probable and inevitable political demand, if and when a major insurer fails amid a claims-surge such as a natural disaster, would facilitate early settlement of a major chunk of any residential claim, and would keep separate the protection of small policyholders from the managment of the failed business itself.

But perhaps the argument for something like an “insurance OBR” is stronger on another count, which has nothing to do with those with outstanding claims on the failing company at the point of failure.     When an insurance company fails, your existing insurance policies with that company are no good.   You need to take steps, perhaps quite quickly, to replace the insurance.

Sometimes that will be easy enough.  If a small contents insurer failed today, out of the blue, most customers would have no great difficulty getting a new policy in place quite quickly.    But in other circumstances it could be quite difficult.  The failed insurer might have specialised in a particular type of insurance which few other companies offered (this was an issue when the big Australian insurer HIH failed).

In a domestic New Zealand context, there seem to be two sorts of plausible problems.  The first is that one company –  IAG, through its various labels –  has around 50 per cent of the general insurance market in New Zealand.   As the interest.co.nz articles notes, even the Reserve Bank has expressed some unease about this concentration.   Should IAG fail, it might be very difficult for customers to replace their policies quickly with other companies.   “Might” because other companies, including abroad, might be keen to pick up the customer base, especially if the failure resulted from a well-understood, limited, idiosyncratic event.     But even if this is an issue, it looks like an issue that should have been able to be taken into account when the various takeovers that led to IAG’s dominant position were approved.

Perhaps more of an issue is if we were to see a repeat of a large failure associated with a series of destructive earthquakes.  In the wake of the Canterbury earthquakes –  and indeed, after Kaikoura in 2016 –  people kept their existing house cover with their existing insurer, but insurers were very reluctant (typically simply refused) to extend cover.  Even alterations to an existing dwelling didn’t get covered, and it was almost possible for a new purchaser to get insurance.  It was quite rational behaviour by the insurers –  risk (of further quakes) around the affected locality, and unpriceable uncertainty, had increased a lot.  That complicated the house sales market for a time –  an inconvenience but not the end of the world.  But imagine that a large company simply failed, leaving most of their customers needing to replace their policies immediately (from personal prudence as well, typically, as from a requirement of a mortgage lender).   There would simply be no takers, at least in affected regions.  I don’t suppose banks would suddenly start selling up customers caught temporarily without insurance, but one can’t deny that there would be an issue.  Politicians would respond.

Something like an OBR for general insurance might be a remedy to that particular problem.  The failed company would remain open, and presumably existing policies would remain in place.

But is it worth it?  Personally, I’m a bit sceptical.  There is no widespread public interest in the continuity of insurance companies across all products.  Housing may well be different –  and would no doubt be seen so politically.  But in the event of a failure, in circumstances akin to AMI (natural disaster with ongoing extreme uncertainty) but in which the insurer was actually allowed to close, might not a less bad, less intrusive, intervention be something like an ad hoc intervention in which the Crown took over the existing residential insurance policies for six months after the failure, in the expectation that after six months policyholders would have been once again able to make private insurance arrangements.   It doesn’t look like a scheme that would materially undermine market discipline –  those with outstanding claims at point of failure would still be exposed –  but might recognise that in certain rare circumstances markets can simply cease to function for a time.  And still allow the salutary discipline of a failed entity passing into history.

In sum, I probably would favour a limited policyholder compensation scheme, funded by policyholders, at least for residential insurance policies. It isn’t a first-best policy, but in a second or third best world it seems better, and fairer, than generalised bailouts such as the AMI one.  But an OBR-type arrangement doesn’t seem appropriate for the general insurance industry –  it wouldn’t speed final resolution of claims, wouldn’t focus protections where the greatest public sympathies are likely to be.     If it didn’t involve the sort of panoply of new controls and provisions the bank OBR system does, it just doesn’t seem well-tailored as a general response.


Land use regulations matter

Most local councils don’t employ economists –  or at least not ones we hear of.  The Auckland Council does have an economics unit, and the previous incumbent did some interesting and stimulating work.

But yesterday on interest.co.nz there appeared an article by two of the Auckland Council’s economists which argued, so the headline proclaimed, that “evidence from across NZ supports conclusion that land use regulation is unlikely to be the main culprit for house price rises”.   They even had an estimated empirical model in an attempt to back their claim.

But, frankly, it looks like an attempt to play distraction, and shift responsibility from their employer (and other local governments around the country).   And it is as if this is the very first time they had come to the subject and were, thus, unaware of the large number of thriving growing cities in the US with house price to income ratios not much more than a third of those in Auckland or Tauranga.

This is the centrepiece of the article

martin-norman-jan-18-2

Which might look superficially fine, at least until one stops to think about what is going on here.

Firstly, it appears to be an odd model, in that they appear to be explaining changes in nominal house prices, but without any explanatory variables like general prices or wages.  Over the best part of a decade, one might expect nominal house prices to rise by around 20 per cent as general costs and prices rose.   Perhaps they’ve estimated the model in real terms, but there is no suggestion in the article that they have done so.

Secondly, all else equal, lower real interest rates might indeed tend to raise the value of an asset in fixed supply.  But, on the one hand, this proposition doesn’t engage at all with the reasons why real interest rates might have fallen.  If, for example, expected future income growth has fallen at the same time – a part of the story in most explanations of the last decade –  any such asset price effect will be greatly weakened.   And, on the other hand, in a well-functioning housing and land market, the only fixed factor here is unimproved land.   And absent land-use restrictions, unimproved land in most places –  even most parts of a city –  simply isn’t worth much.  Perhaps you might think of $50000 per hectare for good rural land.    You could see long-term real interest rates fall 300 basis points (more than we’ve actually experienced), with no changes in future income expectations, and it still wouldn’t make that much difference to the free-market price of unimproved land (and the component of that used in a typical suburban dwelling).

Third, what about population increases?   Auckland (and Hamilton and Tauranga) have had a lot of population growth –  indeed, over decades Auckland has had one of the fastest population growth rates of any largest city in an OECD country.  And when regulatory obstacles –  land, consenting/construction or whatever –  get in the way then shocks to population will boost house prices.  There are regular population estimates published, which are easy to drop into a model.  And, no doubt, had Auckland’s population growth rate been half the actual rate, house and land prices would be somewhat lower.   But all this simply ignores the point –  the insight we really get from that swathe of US cities, (as well, actually, as from basic theory) – that population growth alone makes little or no sustained difference to house prices when the land and construction markets are free to work effectively.  So ascribing responsibility for house price increases to population growth is largely just cover for the regulatory failures of central and local government.

As a reminder, in fairly substantial US cities –  with growing populations –  we find median house (including land) prices of around NZ$250000 to $300000   (from the Demographia report: Des Moines US$198000, Louisville US$176000, Omaha $179000).

Noting that across local authority regions places with larger population growth rates have tended to have higher house price inflation, the Auckland City economists attempt to cover themselves this way

To point the finger at land use regulation would imply that all the areas with the largest population increases have the worst land use regulations and those with the smallest gains have the best regulations.

But that simply doesn’t follow.  Of course, it is often the interaction between population pressures and land-use restrictions that matters in determining what happens to prices.  And it is quite plausible that places with the fastest population growth might even have some of the less worse land-use restrictions, but those restrictions are simply placed under more pressure.  Land-use restriction is, to some extent, endogenous.

As the end of their article approaches, they argue that

Council, the Reserve Bank and the Ministry of Business, Innovation and Employment have all estimated Auckland’s housing shortfall at between 43,000 and 55,000 and growing. The Auckland Unitary Plan allows for up to one million potential new dwellings. Yet the plan was implemented a year ago, and there is no evidence of decreasing land prices.

Put another way: If having already zoned to develop 20 times the current housing shortfall is not bringing land prices down at all, can land use regulation in Auckland be the major cause of high house prices?

As I’ve noted here previously, those estimates of a “housing shortfall” are almost meaningless.   In the Auckland market as it stands, given the regulatory and other features, effective supply and effective demand appear to be in more–or-less balance.  What makes me say that?  The fact that prices haven’t moved much for a year or more.     No doubt there would be demand for many more houses if the price of land were lower, but at current land prices –  regulated and thus artificially scarce –  effective demand seems to be largely sated.

And what of the argument that “we’ve done the Unitary Plan and prices aren’t coming down, so the problem can’t be land regulation”?   Well, yes, of course it can.  If anything, given the manifestly obscene prices people face for land in  or around Auckland, Auckland Council officials (and their political masters) should be looking at the failure of land prices to fall back and concluding that their latest planners’ vision had failed.   It is all very well to talk of the potential for a million more houses, but these are the sorts of lines local authorities have run for a long time –  I recall councils running these lines when the 2025 Taskforce was looking at these issues.   I haven’t looked into the “million house claim” in any depth, but as I understand it, much of this potential is about the possibility of increased density on properties that the existing owners are simply never going to sell (they like living in their existing house/location).   There was probably a lot of theoretical capacity before the Unitary Plan, and of course there has been a lot more population pressure in recent years.

And the bigger issue is that when Council planners and politicians deem that certain places can be built on and others can’t etc etc, there isn’t much of the market at work.  A well-functioning land market would be one in which developers and land owners on the fringes of growing cities were in active competition with each other as to which could supply new sections and new homes more effectively, and where those options in turn competed with realistic options for increased density (according to the tastes/incomes of potential purchasers, not the whims and preferences of officials and politicians).     In a competitive market, holding costs are quite substantial –  not so where regulation rewards “land-banking” –  rewarding bringing land to market early.

The Auckland Council economists’ final line is cute in a way

In the case of Auckland at least, the answer is simple: You can’t live in a resource consent. It is because not enough houses are being built fast enough (for a range of reasons), rather than just the technical availability of developable land, that is keeping prices up. Land may be resource consented for development, but until houses are actually built on it, a premium will be placed on houses that are available.

And, of course, one can’t live in a consent, and we know from other work that the net addition to the housing stock in Auckland has been well less than the number of consents issued for various reasons (including that densification often loses existing houses).  But the point isn’t really relevant to the claim the economists are trying to rebut.

I did a brief post last year on one small example of undeveloped land on the fringes of Auckland –  property at Dairy Flat, still some years from actual development –  where various plots were selling at an average of $1.266 million per hectare.   When that sort of land –  with no prospect of a house on it for the next few years –   is still that expensive –  land which for rural purposes might be worth $30000 per hectare –  we know there is still something very wrong with land use regulation as it is being applied in Auckland.  If one looked, I can only assume we’d find similar examples around Tauranga.

None of this is deny that there might be problems around consenting processes, construction costs (and the construction products supply chain), and/or infrastructure, but please Auckland City stop trying to pretend that black is white and that land use regulation is not a major part of why house price to income ratios are so high in New Zealand –  not just in Auckland, or even Tauranga, but in places with few natural obstacles and modest population growth like Napier-Hastings, Christchurch, or even Palmerston North.

demographia 2 2018

Trade agreements and the new TPP

And so it appears that agreement has now been reached on a TPP-like agreement, minus the United States.   We haven’t yet seen the details (although this MFAT note is useful), but all the comments late last year suggested that the new agreement would stick as closely to the previously-agreed, but not ratified, TPP as possible (but presumably without the Joint Macroeconomic Declaration).

I wrote a few posts a couple of years ago, expressing doubts about the then-TPP agreement.  I wrote –  and write –  from the pro-trade, pro-market side of the argument.   Which, of course, is not the same as a “pro-business” perspective.

Sadly, TPP (and its replacement), like the welter of preferential trade agreements various governments have been signing over recent decades, isn’t necessarily a step towards free-trade at all.  That is a point the Australian Productivity Commission has long been making about such trade agreements –  probably since around the time of the Australia-US agreement which many independent experts concluded made Australia worse off economically (having been signed for political signalling purposes more than anything else).    These agreements keep MFAT officials busy, and ministers of trade looking as if they are “doing something”, but there isn’t much evidence (net) that they are making New Zealanders as a whole better off.

There were always arguments about how we couldn’t really afford (in some political sense) to stay out if everyone else in the region did a deal of this sort.  And there might be some force to that –  we aren’t the United States, say –  but it would be good to see the arguments made in the context of a robust independent assessment of the costs and benefits of the deal to New Zealanders.  There was nothing like that done here for the ill-fated TPP deal.  The new government has claimed to be interested in more-open government.  This would be a good opportunity to demonstrate that it was serious.

There were all sorts of things that disconcert me about the earlier agreement:

  • investor-state dispute settlement provisions should be an affront to every citizen of a functioning democracy with a decent legal system.   We allow foreign investors access to binding dispute resolution procedures against the New Zealand government that are not open to our own companies operating here (people complain, sometimes reasonably about discrimination against foreign investors, but the ISDS procedures invert the arrangements, preferencing non-citizens non-residents over our own people).  And it is no consolation to argue, as government do, “oh, but our own businesses get the same advantage in other countries”.  But if we care at all about nurturing democratic values and the rule of law in other countries, it shouldn’t be a ‘gain’ we are happy with our politicians negotiating.   If you want to do business in (communist) Vietnam, that is your affair, not that of the New Zealand government.
  • then there are the labour provisions (which I wrote about here), under which governments declare that domestic labour market regulation is a matter for international negotiation (and associated dispute settlement procedures).  A minimum wage might or might not be a good idea, but there is no sound reason why a requirement to have one should be made part of a binding international treaty.   At the more wishy-washy end of the scale there was this sort of stuff

And then we have provisions for Cooperative Labour Dialogue and the new Labour Council (and its associated “general work programme”). It isn’t clear why we would want to enter such arrangements even with other advanced countries, let alone with Vietnam or Peru. A recipe for small and lean government it is not ( and I won’t bore readers by listing the items (a to u) which the parties agree they might “caucus and leverage their respective membership in regional and multilateral for a to further their common interest in addressing labour issues – except to note that “work-life balance” appears on the list, and corporate social responsibility pops up again). Real resources will devoted to paying for all these new bureaucratic and political overlays.

  •  there are unsatisfactory provisions around financial crises.   For example, the TPP agreement required any country considering using direct controls (on foreign exchange flows –  of the sort used by several countries in the last crisis) to preference all flows associated with foreign investment over any other financial flows (including those relating to an identical asset owned by a resident.
  • or the weird provision which appears to bind governments to have to compensate foreign investors just as much as citizens in any cases of losses resulting from wars or civil strife.  As I noted in an earlier post, it would have appeared to require the British government, after the Blitz in 1940, to have compensated Swiss or Swedish owners of property on the same terms as it helped its own citizens.   Sometimes that might be appropriate or prudent, but probably not always, and why should it be subject of a binding international treaty, unable to envisage all contingencies.

It isn’t clear how New Zealanders –  or, indeed, citizens of most of the other parties to the new deal –  are going to benefit from the new agreement, which seems to extend the regulatory net even further, and further reduce the ability of citizens/voters to direct and control the activities of their own governments.

Among US commentators who were in favour of TPP it was common to talk of TPP as some sort of instrument in the rivalry with China; that TPP would somehow ensure that “we” would “write the rules of trade for the 21st century etc”.  I’m not sure these “rules of trade” look particularly attractive anyway, and of course if TPP were in any way a threat to China one could be sure that our craven governments (past and present) would not be in such a hurry to sign.

And, of course, if the government was really seriously about free-trade –  itself, a lofty and generally beneficial vision –  it could now unilaterally remove the remaining tariffs New Zealand keeps on imports from other countries; imposts that may benefit a few New Zealand firms, but almost certainly at the detriment of the New Zealand population as a whole.

Palmerston North or Des Moines?

I’m still enfeebled by the last of a bad cold –  three days of Wellington Anniversary Weekend and I didn’t even get out the front door –  so there won’t be much here today. But I noticed that Demographia yesterday released their annual report on median prices relative to median incomes in Anglo countries cities (and a few other places).

As three academics from the London School of Economics put it in their introduction

Before we can have useful debates or even give a balanced assessment of the issues we need good measures. Here Demographia has done wonders over the past decade to focus public debate on the inequity of rising house prices relative to incomes. As Oliver Hartwich in his Introduction to the 13th edition last year said “Demographia’s‘ median multiple’ approach…firmly established a benchmark for housing affordability by linking median house prices to median household incomes. It… is not a perfect measure because it does not account for house sizes or build quality. But it is the only index that allows a quick comparison of different housing markets, and it is the best approximation of housing affordability measures we have to date.”   We agree.

(The house size point matters when comparing, say, New Zealand or Australian price to income ratios with those in, say, the UK  –  where the typical house is notoriously small –  but much less so for comparisons across, say, the US, Canada, Australia and New Zealand markets.)

The big strength of the report is the collation of the data.   But the authors have policy prescriptions in mind too.  This is the more “analytical” of the charts in the report –  a variant of one they seem to show most years.

demographia chart 2018

No New Zealand city is large enough to feature, but the general point isn’t reliant on a single observation: by and large, cities with high price to income ratios have restrictive land use laws.   And no city –  in their sample –  with liberal land use laws has particularly high price to income ratios.

As so often, the US offers a high degree of in-country variability.  There isn’t just a single large city, or a single large fast-growing city. And there are very substantial differences in the land-use restrictions regime.  All within a country that has the same currency (and interest rates), the same banking regulations, and much the same tax system.

So here are the median house price to income ratios for the New Zealand cities in the Demographia sample and a selection of US cities.

demographia 2 2018

Did I cherry-pick the US cities?   Well, yes, in some ways I did.  If I’d simply wanted to show what can be done in the US, there are 10 cities with populations over 2 million with price to income ratios of 3 and under.  But some of them are cities that haven’t done very well economically, and really depressed places with falling populations can have house prices below replacement costs.

Instead, I picked out a selection of cities –  of different size, although all larger than the typical New Zealand city – in a different parts of the country.  I don’t know a lot about some of them, but many are regarded as pretty nice places to live –  at least if one gets over New Zealand priors in favour of cities by the sea (which, of course, Hamilton and Palmerston North aren’t).

As for population growth, I found some scattered snippets:

  • the Charlotte area is estimated to experienced a 15 per cent increase in population from the 2010 census to 2016,
  • the Nashville MSA is estimated to have doubled its population in the last 30 years, and had a rate of population increase similar to Charlotte’s in the most recent decade,
  • the Boise (Idaho) area has doubled its population since 1990,
  • according to the US Census Bureau, Des Moines has recently been the fast-growing city in the mid-west (at around 2 per cent per annum).

As regular readers know, I’m not a fan of government-fuelled population growth.  But in the US as a whole, immigration policy isn’t a large contributor to population growth, and so rapid population growth rates in individual cities are mostly about people and firms locating where the opportunities are.       And, perhaps, where the housing is affordable.

There seem to be plenty of examples in the United States in particular showing what can be achieved –  functioning affordable housing markets – even in areas with fast-growing populations.     Perhaps there is something amiss in our construction (and construction products) markets, but there has to be something seriously amiss with our land use laws and regulations when price to income ratios in what is –  for now –  by some margin our least unaffordable market are materially higher than those in flourishing US cities, such as some of those shown in the chart.

It would be good to see the urgent report the Minister for Housing commissioned before Christmas on the problems around housing in New Zealand highlight some of these simple, but telling, contrasts.

Some (Chilean) perspectives on monetary policy decisionmaking and communications

I’d had more or less enough for this week of thinking/writing about Reserve Bank reform issues, when a (central banker) reader sent me a link to an interesting new survey article by a couple of researchers at the central bank of Chile looking at various institutional arrangements, including decision-making and communications, at 15 inflation-targeting central banks (all from OECD countries).    I’d suggest The Treasury, and the Independent Expert Advisory Panel appointed by the Minister to assist with the review of the Reserve Bank Act, take a look at the paper.

It isn’t perfect by any means –  and there were a surprising number of small errors of detail or emphasis, including in places about New Zealand – but there is a lot of interesting material nonetheless.  For a start, they seem to have chosen pretty much the right group for comparison: the well-established market economies, with reasonably well-governed democratic societies.   One might quibble about the inclusion of Poland, or note that if Poland is included perhaps Hungary should be too, but if you are looking for insights and ideas as to how our central bank (in its monetary policy dimensions) should be organised –   and wanting something to read to complement the Reserve Bank piece I posted here yesterday –  this list of central banks/countries seems about right:

ECB, USA, UK, Japan, Canada, Korea, Norway, Sweden, Australia, Israel, Chile, Poland, Czech Republic, Iceland (plus New Zealand)

I wasn’t too interested in, and won’t comment further on, the detailed material on the specification of the inflation target itself (except to note to the authors that the New Zealand target now has an explicit midpoint reference) –  ground well-covered in various earlier Reserve Bank articles.

What of statutory decision-making structures?  Of the 15 central banks, only New Zealand and Canada do not have a statutory committee making monetary policy decisions.   That is well known.   What is less well-known perhaps is that all those 13 central banks with statutory committees operate by vote.     The authors note that Canada and New Zealand describe themselves as attempting to operate by consensus, but in fact of course in both places only one vote formally counts –   that of the Governor, who has the legal responsibility.     And even in New Zealand, although the three man Governing Committee is claimed to operate by consensus –  they refuse to release any minutes, even under the Official Information Act, to allow us to really know – the members of the wider advisory group make written OCR recommendations, in effect a non-binding vote.

In some of their writings, the Reserve Bank likes to claim that consensus-building models of decision-making are superior.   There may be some arguments on that side of the issue, but actually voting –  after examination of the issues, discussion and debate –  is typically how we make decisions in free societies: be it in elections themselves, decisions of a local tennis club committee, or our higher courts (five judges on the Supreme Court: the verdict supported by the majority rules).  There is no particular reason to think monetary policy decisions are not as well made the same way –  indeed, since there is a great deal of uncertainty, and decisions are revisited every eight weeks or so (so there are few irreversibilities) it seems a pretty demonstrably efficient approach.

The Reserve Bank has also sought to claim that small committees are generally better than large committees.  Again, at some point no doubt there is truth to that –  with all due respect to the Cabinet, the 20th person on any committee is unlikely to be adding much marginal value, and the incentives for any specific member of a committee that large to slack off (put in little effort or fresh thought) can be real.   But of the 13 inflation targeting central banks with statutory monetary policy committees, the median number of members is eight.    For a smaller country, a statutory monetary policy committee with five or seven members sounds about right for New Zealand (none of these statutory committees in other countries has fewer than five members).     Membership numbers don’t seem to be a luxury good: the authors present a chart showing no relationship between GDP per capita and the number of MPC members in an inflation-targeting country.

It is also clear that members of the statutory monetary policy committes are almost entirely appointed by politicians –  as most key positions in our societies typically are (from Chief Justice or Police Commissioner down).   There are some exceptions –  eg regional Fed Presidents in the US (who rotate through voting membership of the FOMC), but even that situation is now raising some concerns among scholars in the US.   And almost all of the central banks with statutory MPCs have external members, in some form or another (sometimes part-time, sometimes becoming temporary full-time executives, sometimes full-time non-executive): governments rarely seem to see monetary policy decisions as matters only for some career “priesthood of the temple”.

I was also interested in some analysis the authors had done on the extent of unanimity, or otherwise, among monetary policy committees where voting decisions are published.

To listen to our Reserve Bank, if voting records were published, or minutes in which individual members could outline their views on specific monetary policy decisions, it would be a recipe for mayhem.  They’ve talked of it creating confusion, and uncertainty, undermining confidence in, and the credibility of, the central bank.

Here is what the Chilean authors have to say about such individualistic committees.

In individualistic committees each member is held publicly accountable for their decisions, and each member is empowered with one vote. Decisions tend to be reached by majority vote, where the Governor tends to have the deciding vote in case of a tie. The high degree of individual accountability results in regular reservations, dissents, or minority votes against the final policy decision. Two regularly cited examples of this type of committee are those of the UK and Sweden. Importantly, when a certain degree of public disagreement among committee members occurs, market participants are generally not surprised and understand the differences as part of the policy process.

That is more or less the point I’ve been making.  One could say the same about the United States.  And recall that these authors are themselves from a central bank with a committee more towards the “collegial” end of the scale.

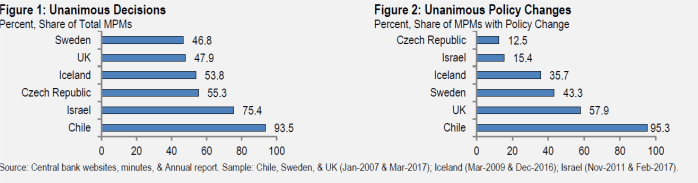
And, in any case, as they illustrate, even in individualistic committees raging dissent is hardly the norm.

central bank dissents

Roughly half of all the monetary policy decisions in the UK and Sweden in the last decade have been unanimous.  (On the other hand, even for central banks at the collegial end of the spectrum, not all decisions are unanimous).   I’m not sure why they didn’t include the Federal Reserve in this particular analysis, but I suspect the numbers there would show something similar to the UK or Swedish experiences.

There was also some interesting material on communications practices.  For example, all 13 of the central banks with statutory monetary policy committees publish minutes –  to repeat, every single one of them.   The timeliness varies –  the UK and Norway publish the same day as the monetary policy announcement, but a more typical lag in about two weeks –  and of course the nature of the content differs: some are pretty bland, while others (notably those of Sweden) although a full and careful articulations of the arguments and issues of concern to individual members.

But there was also some surprises (at least to me).  Our Reserve Bank grudgingly released background papers to a 10 year old interest rate decision, and consistently refused to release any background papers –  no matter how topical –  used in the preparation  of their interest rate decision or Monetary Policy Statement (eg the recent refusal to provide any background analysis papers on the impact of various policies of the new government).  By contrast, and at the other extreme, according to the Chilean paper the central banks of the Czech Republic and Norway “publish a version of the staff MPM [monetary policy meeting] presentations shortly after the meetings”.    I struggle to see any good reason why such background analysis should not be released publically with, say, an eight week lag (eg released after the OCR decision one after the decision to which the background material relates)

And a bigger surprise still was the publication of transcripts of monetary policy meetings.  I knew that the Federal Reserve was doing so, and had heard the odd mention of it happening elsewhere.  In fact, the authors show that seven of their central banks are now doing so (including the Fed, the ECB, the Bank of Japan, and the Bank of England).  The lags are quite long –  the Fed is the shortest at five years.  But, fascinating as some of the old Fed transcripts are, especially from the era before members knew they would be published, even I have my limits around transparency, and this is one of them.  As the Chilean authors note

as highlighted by the Warsh Review (2014), the publication of meeting transcripts (and minutes) may to a certain extent impair a candid discussion of policy options among policy-makers, and lead them to limit their interventions to written statements that express their view (and vote) without the consideration of the perspectives of other members. In this context, it is possible that policy deliberations may be driven to other settings where a formal record is not being taken. Moreover, some existing evidence for the U.S (Meade and Stasavage, 2008) suggests that the publication of FOMC transcripts reduced the likelihood of dissent among committee members, and made members less willing to change their positions over time.

But the fact that various major (and minor) central banks are publishing such transcripts again helps give the lie to our Reserve Bank’s constant claim that it is one of the most transparent monetary policy central banks in the world.

One final aspect the Chilean authors covered was the role (if at all) of a Treasury or government representative in monetary policy decision meetings.    In the Reserve Bank paper I linked to yesterday, the Bank authors attempted to minimise this issue.   They noted that in Australia the Secretary to the Treasury is a voting member of the Reserve Bank (monetary policy making) Board and that in the UK there is a non-voting Treasury observer  who attends (statutory) MPC meetings.   Of our 15 central banks, that is all they note (although in Colombia, one of the countries they look at, the Minister of Finance is himself a voting member).

But here is part of the fuller Chilean treatment of the issue

In a second large group of central banks, an important authority of the administration, such as the Minister of Finance or his delegate, is invited to attend and speak in the MPMs, but does not have the right to vote on the monetary policy decision. Within this second group, the degree of potential government involvement differs. In Japan for example, the representatives of the government (Minister of Finance, Minister of State for Economic & Fiscal Policy) may propose issues to be discussed in the MPMs, and may even formally ask the MPC to postpone a vote on monetary policy until the following meeting. In the case of the Bank of Korea, the representative of the government (Minister of Strategy & Finance) may publicly request the MPC to reconsider a monetary policy decision if it perceives that the decision conflicts with the government’s economic policy.

Their tables also lists Chile, the Czech Republic and the UK as having non-voting Treasury representatives.  In the comments on the Rennie review report from Charles Goodhart (ex UK MPC) and Don Kohn (a current member of the UK FPC) no concerns were raised about this aspect of the UK model.

I don’t have a strong view on the possible role of a Treasury representative on either a monetary policy or financial policy committee in New Zealand.  But there is enough precedent in other countries to suggest that option deserves more serious consideration than the Reserve Bank –  always keen to keep Treasury out of its hair –  gives it.     If there was to be non-voting observer, the rules of the game might be quite important –  the person would be there to inform, answer questions, and report (as in the UK) and shouldn’t see themselves as having a role to try to shape decisions.

The Chilean piece was interesting and refreshing.     They make it clear –  without directly engaging with New Zealand issues at all – that if the government reforms our Reserve Bank Act to provide for:

  • a statutory monetary policy committee,
  • all appointed directly by the Minister,
  • with a good mix of internals and non-executive internals,
  • and timely publication of minutes and vote number,
  • with perhaps even details of dissenting members’ views, and even
  • delayed publication of background papers

It would be placing the Reserve Bank of New Zealand’s new model of governance. decisionmaking and communications right in the mainstream of international practice for countries of our type.

As it happens, I saw last night one other snippet reminding us of how far central bank transparency could go.  The Financial Times had an interesting piece outlining concerns in some quarters about senior central bankers getting too close to private bankers (in the New Zealand in recent times –  but probably not generally –  the problem is more the opposite), with particular concerns about ECB head Mario Draghi.    Partly in response

The ECB also now publishes the diaries of its six executive board members after officials were found to have met private sector representatives around the time of monetary policy decisions.

It might be a worthwhile model for our new central bank Governor to consider emulating, along with (in time) his deputies and members of the new statutory decisionmaking committees.

Our central bank was once at the forefront of (some aspects) of central bank transparency.  These days, it has weak (formal) decisionmaking processes and doesn’t do at all well on the transparency front either.  Those issues should be tackled properly as part of the current review.


The Reserve Bank’s case for minimal reform

In early December, the Reserve Bank’s briefing to the incoming Minister of Finance  (BIM) was released, as part of the general release by the new government of the set of BIMs.     I wrote about the Bank’s briefing, and in particular about the appendix they included on the governance and decisionmaking issues.  In a departure from the now-common practice of including nothing of substance in BIMs the (unlawful) “acting” Governor –  I think I’ve gone a whole month without using that description –  took the opportunity to make his case in writing for minimal reform.

The Bank indicated that the appendix was itself a summary of a fuller document that they would make available to the Minister on request.  So I lodged an Official Information Act request for the fuller document, which they have released in full to me today.     It is really the sort of document that should be included with the collection Treasury has made available as part of the current Treasury-led review of the Reserve Bank Act, but as it isn’t there, I thought I should make it available for anyone interested ( RBNZ Memo – Review of policy decision process 16 Oct 2017 (1) ).

The paper was written by a couple of Reserve Bank managers –  Roger Perry, who manages a monetary policy analysis team, and Bernard Hodgetts who head the macrofinancial stability area –  and is dated 16 October, a few days before it became clear who would form the next government.   The paper itself is not described as Bank policy, but in the release I got today it is stated that

Please be aware that the document encapsulates Reserve Bank thinking at the time it was prepared.

Which suggests that at time it did represent an official view –  probably workshopped with senior management before the completed version we now have.     There is a pretty strong tone to the document suggesting that the authors did not expect a change a government (with only a couple of footnote references to possible implications of Labour Party policy positions in this area).

But, frankly, I was surprised how weak, and self-serving, the document was.  The Reserve Bank has been doing work on these issues off and on for several years –  there was the secretive bid a few years ago by Graeme Wheeler to get his Governing Committee enshrined in statute –  and yet there was little evidence of any particularly deep thought, and no sign of any self-awareness or self-criticism (over 30 years was there really nothing the authors –  or Bank –  could identify as not having worked well?).

There was also, surprisingly, no sign of any engagement with the analysis or recommendations of the Rennie report.  It is hard to believe that a report, on Reserve Bank governance issues, completed months earlier had not been shown to the Reserve Bank itself.   There was no substantive engagement with the models adopted in various countries that we tend to be closest too, or which are generally regarded as world-leaders in the field (by contrast, several references to the Armenian model –  to which my reaction was mostly “who cares”).    There was no reference at all to how Crown entities are typically governed in New Zealand –  that omission isn’t that surprising, given the Bank’s track record, but it should be (the Bank is after all just another government agency).  There wasn’t even any reference to how other economic and financial regulatory agencies in New Zealand are governed, even though the Financial Markets Authority is a new creation with a markedly different (but more conventional Crown entity) governance and decisionmaking model.

For what it is worth, on 16 October, the Bank seemed to favour:

  • enshrining the idea of the Governing Committee in law, but perhaps with slightly different versions of membership for monetary policy and financial stability functions,
  • legal decisionmaking power continuing to rest with the Governor,
  • the Governor’s appointment continuing to be largely controlled by the Board,
  • no publication of minutes or votes,
  • no external members of the committee(s).

But they make no serious attempt at critical analysis to support their case, let alone to engage with the risks of a system in which a single decisionmaker is key, and where that single decisionmaker is the boss of the other members of (what is really just) an advisory committee.   Or the anomalous nature of such a system in the New Zealand system of government, where even elected individuals rarely have such unconstrained authority, where committee-decisions are the norm (from Cabinet, the higher courts, through major Crown entities to school Boards of Trustees) and where Cabinet ministers (or Cabinet collectively) typically have the key role in appointing those who exercise considerable statutory powers.

The management of a central bank that can’t come up with better analysis than this really makes it own case for change –  legislative change, personnel change, and cultural change.

Remote regions, immigration, and prosperity

A couple of years ago I did a post on some remote and very small places, many of which had quite a lot of land and very few people.  My point was to suggest that New Zealand was quite unusual in having so many people in such a remote spot, all the more so when much of the population growth had been accounted for by deliberate immigration policy.    As readers will know –  apart from anything else, I keep pointing it out –  over at least the last 70 years, productivity growth here has been pretty poor and we’ve drifted a long way down the global league tables.  My proposition is that the two stylised facts aren’t unrelated.

At the time of the earlier post, my young daughter was fascinated by a book on remote islands.   At the moment –  a bit older now –  she’s got really interested in Wales and keeps telling me all sort of interesting snippets.  But talking with her about Wales reminded me that at the time of the Lions Tour last year I’d been meaning to write a post highlighting just how little population growth there had been in some of the outer reaches of the United Kingdom.

More generally, I’d been thinking about how global studies attempting to assess the economic impact of immigration focus on comparing across countries.  In some ways, that makes sense –  data are often easier to come by, and countries control immigration policies.    But I suspect there is information in the experiences of remote regions.   After all, if there were typically really good economic opportunities in remote regions, people in a country are free to move there.  The population of the United States, for example, has risen by over 200 million people in the last 100 years –  through a mix of immigration and (mostly) natural increase.  Those peope have been free to locate themselves where the best opportunities are.   One can think of parts of Canada or Australia in the same way.  And if our politicians had made different choices in the 1890s, we could simply have been part of the Australian Commonwealth, and it seems unlikely that the economic opportunities here would have been much different if that choice had been made.

Here I’ve focused on the last 100 years or so.   Why?  Mostly because just prior to World War One New Zealand had probably the highest (or 2nd or 3rd highest) GDP per capita of any country in the world (per the historical tables put together by Angus Maddison).  But it was also some decades on from the first big waves of colonial settlement (whether here, Australia, Canada, or the mid-west and west of the United States).  At around 1 million people in the 1911 Census, New Zealand was already a functioning country of reasonable size (not large, but there are many smaller countries even today).

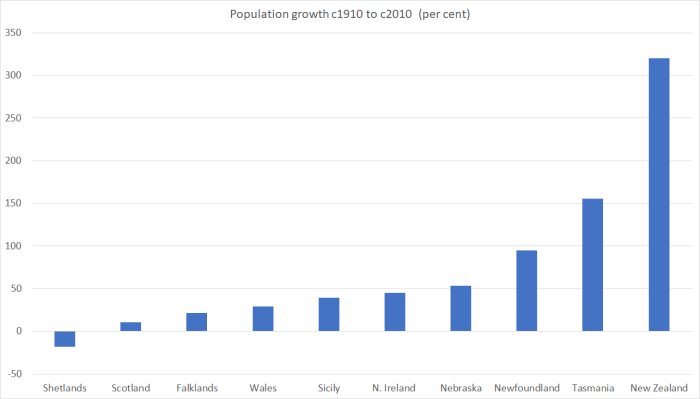
In this table I’ve focused on population growth between the Census nearest 1910 and the most recent Census (in most cases 2010 or 2011, but in New Zealand 2013).   The chart shows the percentage increase in population for these remote regions of countries, plus that for New Zealand  (Nebraska gets chosen as a “remote” US area mostly because I happen to have been there a few times.)

remote regions

Australia and Canada (and the US) have had rapid national population growth rates, but these remote regions  (Nebraska, Newfoundland, and Tasmania) have had much lower population growth rates than New Zealand.  (And, on checking, each of those three have lower population densities now than New Zealand does.)   But given that all of these regions have small populations, relative to the respective nation’s total population, there would have been nothing to stop lots of people gravitating to the remote spots if there was real evidence of good economic opportunities for many people in those places.

It has, after all, happened in some remote regions: West Australia for example, now has about 10 times the population it had in 1910, presumably attracted by the mineral resources that mean West Australia has the highest GDP per capita of the Australian states.    And two really remote parts of the United States –  which I didn’t show on the chart, partly because they were settled so much later (not admitted as US states until 1959) –  are Hawaii and Alaska.  Both have had faster population growth than New Zealand over the last 100 years (although between them only around 2 million people in total): in Alaska’s case no doubt the oil resources attracted people (Alaska also has among the highest GDP per capita of any state).

But over that hundred years –  or any shorter period you like to name really –  New Zealand (like Wales, Northern Ireland, Tasmania, Nebraska, or Newfoundland) has had no big natural resource discoveries, or asymmetric productivity shocks specifically favouring our location.   Like those places, we’ve only had the skills of our people and the instititutions we’ve built or inherited (in the case of this group a fairly-common Anglo set) to make the most of, and to overcome what appear to be the resurgent disadvantages and costs of distance/remoteness.  Our birth rates won’t have been much different over long periods, and New Zealand like all these places –  the Shetlands most extremely of the places on my chart –  have seen outflows of our own people.  The big difference here is immigration policy, which has actively sought to substantially boost the population.

Try a thought experiment.  Say the New Zealand and Australian governments had simply combined their respective immigration policies over the last 100 years or so  (eg if New Zealand was offering 45000 residence approvals per annum and Australia 200000 –  similar to the current policies –  the two countries simply said we’ll issue 245000 residence visas and the arrivals can go wherever they like), what would have happened.   By construction, the total population of the two countries would have been pretty much the same as what we actually see (5.4 million in 1910, and about 29 million now) but what would the distribution look like?     We know that in Australia –  given the same choice –  the remote region with a mild climate and no big new natural resources (Tasmania) saw much weaker population growth than the rest of Australia.   Why wouldn’t it be the case that New Zealand would have experienced much the same phenomenon?    At Tasmania’s population growth rate for the last 100 years we might now have a population of around 2.5 million.   After all, for almost 50 years now native New Zealanders have (net) been relocating to (the non-Tasmania) bits of Australia, so why –  given the free choice –  wouldn’t the migrants –  facing a free choice at the point of approval –  have done so too?

Would we have been better off?    The migrants who went to Australia instead presumably would have been –  both judged from revealed preference (they made the choice) and that incomes in Australia are higher than those here.  I’d argue that the smaller number of New Zealanders probably would have been economically better off as well.  Natural resources are still a huge part of the economic opportunities in these remote islands –  perhaps still 85 per cent of our exports –  and those limited resources would be spread across a considerably smaller number of people.  For those who simply prefer “more people” for its own sake, perhaps they’d have been worse off –  but then such people could have self-selected for Sydney or Melbourne (as Tasmanians of a similar ilk do, or people in Newfoundland who wanted to be part of something big self-select for Toronto).

I’m not suggesting something conclusive here, just that people pause for thought, and reflect on what questions the experiences.    For a remote place we aren’t particularly lightly settled, and especially not as a remote place without the sort of abundant natural resources of –  say –  a West Australia.  We’ve had no distinctive favourable productivity shocks, and we’ve long lost any claim to be the richest (per capita) country on earth.  It is no surprise that some people want to move here –  plenty would want to move to Nebraska if it had its own immigration policy like ours – but there isn’t much evidence, from experience of other remote regions, to suggest we benefit from them doing so.   Without big new natural resource discoveries, remote places –  regions, territories  – in the advanced world  tend to have quite weak population growth rates.  It isn’t obvious why in New Zealand we should let immigration policy up-end that otherwise natural outcome.

The Reserve Bank and financial regulation

Still working my way through the various articles and documents that turned up just before Christmas, I got to a lengthy issue of the Reserve Bank Bulletin, headed “Independence with acccountability: financial system regulation and the Reserve Bank”.   It is, I suspect, designed to fend off calls for any significant reform.

The Bulletin speaks for the Bank, and although as I read through the article I noticed distinct authorial touches and tendencies, when all is boiled down the author was sent into the lists to make the case for how things are done now: powers, governance, and accountability.  He does a pretty good job of presenting the party-line, against significant odds in many areas.    Even where one disagrees with the Bank’s case, it is a useful and accessible addition, in part because the Bank’s powers and responsibilities in regulatory areas have grown like topsy over the years and are scattered across various pieces of legislation.

Much of the first half of the article is designed to make a case for an independent prudential regulator, by reference to the theory and to the writings of the Productivity Commission.  But, for my tastes, it was far too broad-brush to add much value.  Probably no one disputes that we want the rules applied fairly and impartially, with politicians largely kept out of the process.  In the same way, we don’t want politicians deciding which person gets arrested and which not –  we want an operationally independent Police for that –  or who gets convicted  –  independent courts – or which airline passes safety standards and which not, and so on, so we don’t want politicians deciding to look favourably on one bank’s risk models and not on another’s.   There are many independent regulatory agencies –  or even government departments where the chief executive exercises responsibility in independently applying the rules –  but to a very substantial extent they apply and administer the rules, while other people make the policy/rules.

The Reserve Bank wants to make the case that in its area the rules/policy shouldn’t be set by elected people (whether Parliament itself, or ministers by regulation), but by an independent agency, and that the same agency should both make and apply the rules (without any possibility of substantive appeal).  It is the “administrative state” at its most ambitious –  unelected officials (a single one at present, not even directly appointed by a Minister) are lawmakers, prosecutor, judge and jury (and quite possibly the equivalent of the Department of Corrections as well).

The Bank seeks to rest a lot on the notion of time-inconsistency, a notion from the academic literature that is sometimes used to try to explain the high inflation of the 60s and 70s, and to make the case for an independent central bank to make monetary policy.  The idea is that even though one knows what is good in the long-run, the short-term benefits of departing from that strategy (and endless repeats of the short-term) mean that the long-term gains are never realised.  The solution, so it was argued, was to remove the short-term management of the business cycle from politicians.    I’m not particularly persuaded by the model as it applies to monetary policy (a topic for another day), and it is curious to see a central bank putting so much weight on that model after year upon year of inflation below target.  But today’s topic is financial regulation and financial stability, where the Bank would have us believe it is desirable/important to have the rules themselves –  the policy –  set by someone other than politicians.

No doubt it is true that there can be some tension between the short and the long-term around financial stability.  But that is surely so in almost every area of government life and public policy?  Underspending on defence now frees up more resources for other things now, but one might severely regret doing so if an unexpected war happens later.  Skimping on educational spending now won’t make much difference (adversely) to economic performance or the earnings of anyone (teachers aside I suppose) for a decade or two.  Running big fiscal deficits now can offer some short-term benefits, but at the risk of heightened vulnerability etc a decade or two down the track.   But in none of these areas do we outsource policymaking: they are political choices, and we then employ officials and public agencies to administer and deliver those choices.     The Reserve Bank has, as far as I’m aware, never offered any explanation as to what makes their specific area of policy different.   Sometimes they draw on academic authors writing about financial regulation, but many of those specialists fall into the same trap –  they see their own field, but never stand back and think about how democratic societies organise themselves across a wide range of policy.

As it happens, the current system around the Reserve Bank and financial regulation is a bit ad hoc and inconsistent to say the least, a point that the article more or less acknowledges.     Thus, for banks the Reserve Bank can vary the “conditions of registration” to change all sorts of big policy parameters, without any formal involvement from elected politicians at all (all the variants of LVR policy, from the first Wheeler whim were done this way).  But even for banks rules around disclosure have to be done by Order-in-Council, and thus require ministerial approval.  No one would write the law that way –  such different regimes for two different aspects of  bank regulation –  if starting from scratch (the actual legislation has evolved since 1986).

For insurance companies, the Reserve Bank itself can issues solvency standards (effectively, capital requirements for insurers), but for non-bank deposit-takers capital rules (and other main prudential controls) can only be set by regulation, again requiring the involvement and approval of the Minister of Finance.   (Incidentally, this is why LVR rules apply to banks but not non-bank deposit-takers: Wheeler could regulated banks directly, but couldn’t do the same for non-bank deposit-takers.

(And, as the Bank notes, it has “no direct role in developing rules associated with AMLCFT”, even though it administers and applies those rules for banks.)

At very least, there would appear to be a case for streamlining and standardising the procedures for setting the rules.     It isn’t clear why the Reserve Bank Governor should have almost a free hand when it comes to banks, but such limited scope to set policy when it comes to non-bank deposit-takers.   And, if anything, the case for ministerial involvement in settting the rules for banks is greater than that for the other types of institutions because (as the Bank acknowledges) bailouts and recessions associated with financial crises etc have major fiscal implications, and one might reasonably expect elected ministers to have a key role in setting parameters that influence the risk of systemic bank failures.   And, again as the Bank acknowledges, it isn’t easy to pre-specifiy a charter –  akin to say the Policy Targets Agreement –  for financial stability policy.

The Bank attempts to cover itself against suggestions that it might be, in some sense and in some areas, a law unto itself, by highlighting various ways in which the Minister of Finance might have some say.   There are, for example, the (non-binding) letters of expectation, the need to consult on Statements of Intent, and the potential for the Minister to issue directions requiring the Bank to “have regard” for or other area of government policy.     These aren’t nothing, but they aren’t much either –  and as the Rennie report noted, the power to issue “have regard” directions has never been used.    Even budgetary discipline is so weak as to be almost non-existent: there is a five-yearly funding agreement, but it isn’t mandatory  (something that needs fixing in the current review), isn’t particularly binding, and doesn’t control the allocation of spending across the Bank’s various functions.   The Minister of Finance doesn’t even get to make his own choice of Governor –  and all Bank powers still rest with the Governor personally.

The contrast with the other main New Zealand financial regulatory agency, the FMA, is pretty striking.   Policy is mostly set by the Minister (by regulation), advised by MBIE (to whom the FMA is accountable), and the powers of the organisation itself rest with the FMA’s Board, all the members of which are appointed directly by a Minister, and all of whom –  under standard Crown entity rules – can be removed, for cause, by the Minister.  Employees, including the chief executive, only have powers as delegated by the Board.    The FMA model is now a pretty standard New Zealand regulatory model, and an obvious point of comparison with the Reserve Bank.

Somewhat cheekily, the Reserve Bank attempts to present their own model as providing more scope for ministerial input than for the FMA  (see footnote 16, in which they note that for the FMA there is no power of government direction).   As regards policy, it isn’t necessary, since the government sets policy and appoints (or dismisses) the Board.   As regards the application of rules, one wouldn’t want –  and doesn’t have –  powers of government direction in either case.   As regards the banking system, mostly ministers can’t set policy, can’t hire their own Governor, and can’t fire him (re financial system policy) either.   The Governor and the Bank have far more policy power than is typical –  across other regulatory agencies –  appropriate, or safe.

The second half of the article is about accountability.  As they reasonably note, when considerable power is delegated to unelected agencies, effective accountability needs to provided for.    In their words “accountability therefore generates legitimacy and legitimacy in turn supports independence”.

It is, therefore, unfortunate that the Bank’s very considerable powers are matched, in this area in particular, by such weak accountability.   After pages of attempting to explain themselves and what they see as the various aspects of accountability, even they end up largely conceding the point.     These sentences are from the last page of the article

the BIS (2011) argues that financial sector accountability mechanisms should be focussed more on the decision making process rather than outcomes per se. This is because of the more intrusive nature of financial sector policy, and the issues associated with observing outcomes (lack of quantification and very long lags). Put another way, there should be less reliance on ex post accountability mechanisms and more obligations placed on ensuring decision-makers are transparent about the basis for their actions.

I’m not sure I entirely agree –  although there is certainly the well-recognised point that absence of crisis is evidence of nothing –  but at very least a focus on strong process might argue for:

  • a more effective separation between policymaking and policy administration (as is customary for many regulatory entities, but largely not for New Zealand bank supervision),
  • a decisionmaking structure in which power did not rest simply with a single individual, who is himself not directly appointed by an elected person,
  • decisionmaking structures that involve real power with non-executive decisionmakers,
  • effective and binding budgetary accountability,
  • a high degree of commitment to transparency and to ongoing external engagement,
  • a culture that is self-critical and open to debate,
  • perhaps some more effective scope for judicical review (including on the merits, rather than just process),
  • monitors with the expertise, mandate, and resources to ask hard questions and to critically review and challenge choices being made around policy and its application.

At present, as far as I can see, we have none of these for the Reserve Bank of New Zealand as financial regulator.

Take the formal monitors for example.  Parliament’s Finance and Expenditure Committee has little time, no resources, and little expertise.  The Treasury has no formal role, no routine access to Bank materials (or eg Board papers) and is probably quite resource-constrained in developing the expertise.

And what of the Bank’s Board?   By law, they play a key role, as agent for the Minister of Finance in monitoring the Governor, and (now) obliged to report publically each year on the Bank’s performance.    The Bank often likes to talk up the role of the Board –  doing so provides them cover, suggesting the presence of robust accountability –  but the latest article is surprisingly honest.  The Board gets a single paragraph, which simply describes the legislative provisions.  There is no suggestion of the Board have actually played a key role in holding the Bank (Governor) to account – not surprisingly, since in the 15 years they have been publishing Annual Reports, there has never been so much as a critical or sceptical word uttered.  Of course, it isn’t surprising that the Board doesn’t do a good job: it has no independent resources at all (even its Secretary is a senior Bank staffer), the Governor himself sits on a Board (whose main role, notionally, is to hold the Governor to account) and the Board members themselves typically have little expertise in the areas (quite diverse) around which they are expected to hold the Governor to account for.   (Their job is, of course, made harder by the rather non-specific mandate the Bank has in regulatory areas –  there is nothing akin to the Policy Targets Agreement (which has its own challenges in monitoring).)

What of some of the other claims about accountability?  The Bank points out that it is required to do regulatory impact assessments –  but these are typically done by the same people proposing the policies, and there is (or was when I was there) nothing akin to the sort of process some government departments have for independent panels vetting the quality of the regulatory impact assessments.

They are also required to consult on regulatory initiatives, and must “have regard” to the submissions.  But, except perhaps on the most technical points, there is little evidence that they actually do pay any real heed to submissions.    For a long time, they also kept the submissions themselves secret –  even attempting to claim that they were required by law to do so.  They’d publish a “summary of submissions”, which highlighted only the issues they themselves chose to identify.   As they note, and in a small win for a campaign by this blog, they have now started publishing individual submissions, belatedly bringing them into line with, say, Select Committees of Parliament or most other regulatory bodies.  But there is no sign of much change in the overall attitude, or of any greater openness to ongoing debate and critical scrutiny.

Then, of course, there is the Official Information Act.  The Bank is subject to the Act, but chafes under the bit, is very reluctant to release much, threatens to charge requesters, and generally seems to see the Act as a nuisance, rather than an integral part of an open and accountable government.

We had a good example just a couple of months ago as to how unaccountable the Bank is in its prudential regulatory areas.  It emerged that Westpac had not had appropriate regulatory approval for some model changes used in its risk-modelling and capital calculations.   But, as I noted at the time, the short Bank statement left many more questions than it answered, and no one –  including journalists asking directly –  has been able to get straight answers from them, even though capital modelling is at the heart of the regulatory system.

And, of course, if the formal monitors are lightly (or not at all) resourced, there isn’t much other sustained scrutiny.   Banks are scared –  and more –  to speak out: this is where culture matters a great deal, as banks will always have a lot of balls in the air with the regulator, and in an open society should feel free to openly challenge the regulator, without fair of undue repercussions.   Academics with much expertise in the area are thin on the ground, as are journalists with the time or expertise.

Mostly, in its exercise of its extensive financial regulatory powers, our Reserve Bank isn’t very accountable at all.   Providing it jumps through the right, minimal, process hoops it can do pretty much what it likes in many areas of policy, and the public is left just having to take the Bank’s word (or not) that things are okay.  That needs to change –  and thus phase 2 of the current review of the Bank’s Act needs to be taken seriously.    Making the changes isn’t about one single measure, and there are plenty of details that will take a lot of work, and thought, to get right.   Part of it is about building a better internal culture, one that (from the top) really wants to engage, and which welcomes challenge and critical review.

After yesterday’s post I had an email from a reader with considerable senior-level experience in the banking sector noting just how weak much of the formal scrutiny of the Bank is in these areas.

From my perspective the Bank would benefit from independent challenge about their prudential responsibilities, and cost-benefit analysis. I am unsure if they have reviewed this post the Westpac capital model issues.

I am unsure how the Board discharges the independent prudential review role effectively given their experience – two Directors have insurance experience  and no directors have Banking, payments system or other non-bank financial experience. Likewise experience of Insurance/Banking/Payments technology systems and risks. While there are some very good RBNZ executives they are not particularly strong in banking risk experience – funding, liquidity, credit etc.

…. I think it would be useful for the RBNZ at a governance level to have experience of how financial balance sheets, and liquidity operate under stress, they will have some very important decisions to make when the next financial crisis occurs.

Much of that rings true to me.    We have typically had Governors with more experience of macro policy, and perhaps financial markets, than of banking –  and yet financial regulation is a hugely important role in what the Bank does – and now have a new Head of Financial Stability with no background in banking or finance at all.   We have a Board responsible for monitoring the Bank across monetary and regulatory responsibilities, and with little specialist expertise.   The contrast with, say, the FMA is quite stark.

Quite what the right balance of a solution is, I’m not quite sure.   I favour moving to a committee-based decision-making structure, and moving more of the policy back to the Minister (with the Bank as a key adviser), but even a Financial Policy Committee might only have three or four externals on it, and no such group is going to encompass all the right bits of expertise.   As often, I guess it is partly about the willingness to ask the hard questions, and to be willing to commission independent expertise (whether from New Zealand or abroad, from academics or people with industry background) and to engage.   If the Board remains as a monitoring agency –  as Rennie recommends, but I’m sceptical of –  it needs to be provided with resources.   And the Minister needs to be willing to use his statutory powers to commission independent reviews of aspects of the Bank’s stewardship, to enable us (and the Bank) to learn from experience by critically evaluating performance (and process).  Personally, I’m still tantalised by the idea of a small independent agency resourced to pose questions, and commission research, on the stewardship of fiscal, monetary and financial regulatory policy.

If not all the answers are clear, what is clear is that New Zealand is a long way from having got the model right: the right allocation of powers, the right accumulations of expertise in the right places, the right cultures, and the appropriate mix of formal and informal accountability that can really give New Zealanders confidence in the regulation of the financial system.
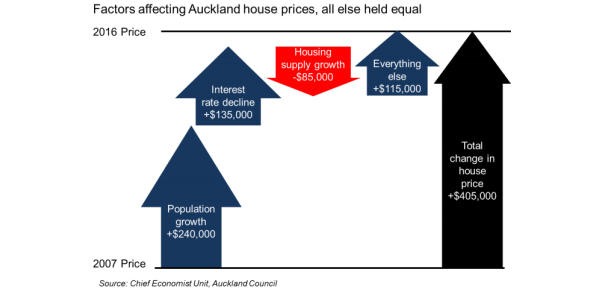
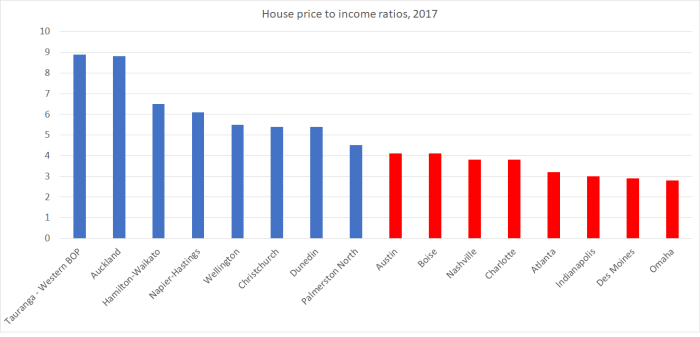
 

The Rennie report finally sees the light

Almost a year ago now, the former Minister of Finance Steven Joyce asked The Treasury to commission some advice on possible changes to the governance of the Reserve Bank.  We only found this out a couple of months later, and then only when hints of a review seeped out prompting a journalist to put the direct question to the then Minister.  It turned out that Iain Rennie, former State Services Commissioner (and before that former senior Treasury official) had been commissioned to write the report –  indeed, by the time we learned of the commission, Rennie had already largely completed his work.

All along the way, The Treasury has been incredibly obstructive about the review.   The terms of reference have never been released.    They eventually told us (some of) the people Rennie had talked to, and the names of the peer reviewers Treasury had used but refused to release drafts of the reports, comments made by reviewers, or the finished report itself.   They even took to arguing that it had all been Treasury’s idea, and that the report was just to inform Treasury’s own post-election advice, as if Steven Joyce had never been any part of the story.    Frankly, it was a pretty gross case of flouting the Official Information Act –  for what was, when all boiled down, a private consultant’s report, paid for with public money, on matters of organisational design and goverance of a single government agency.

But yesterday The Treasury finally (and quietly) released the report itself, along with comments from the peer reviewers (on an earlier version, itself still secret), some advice on the report from Treasury to the (new) Minister of Finance, and some recent comments from the Reserve Bank on the contents of the Rennie report (all available here).   I appreciate the pro-activity of The Treasury in at least letting me know that the report was now, belatedly, available.    The material is all now presented as background material for the current two-stage review of the Reserve Bank Act, including the contribution of the Independent Expert Advisory Panel.

The Rennie report itself is here.  It isn’t a bad report –  in fact, for a fairly short report done quite quickly, it is a bit better than I had come to expect.   In some respects, the details don’t matter that much –  it is just one person’s view (having consulted not very widely, and mostly with people inside the central bank “club”), and his report has been superseded by the wider review Grant Robertson has commissioned.  Rennie’s report will be just one input to that mix.

Then again, Rennie had been the State Services Commissioner.  And he’d been the Treasury Deputy Secretary responsible for things to do with macro policy and the Reserve Bank (at the time of the last major review, with Lars Svensson, at which time Treasury had opposed any change in the governance and decisionmaking model).

And Rennie is quite clear that:

  • the current single decisionmaker model is far from best practice, whether considered relative to other central banks/ financial regulatory agencies, or relative to the governance of other New Zealand public sector entities,
  • a single committee is not a sensible solution.  Rennie, in fact, ends up favouring three separate committees (a model very similar to the one used now in the United Kingdom –  one for monetary policy, one for (so-called) micro-prudential policy, and one for (so-called) macro-prudential policy),
  • an internal executive committee (or even several of them) is not an appropriate solution.  External, non-executive, members should be involved,
  • the Minister of Finance should have primary responsibility for the appointment of all the members of the decisionmaking committees, given that the committees exercise significant statutory powers.

And on monetary policy he favours a materially greater degree of transparency than exists at present, including favouring (on-balance) the individualistic model –  as, for example, in the US, the UK and Sweden –  where individual members are individually accountable for their advice and their votes.    Existing Reserve Bank management hates –  I don’t think that is too strong a word –  that model: they hated it when I was still at the Bank, and in recent months they have gone public with their intense dislike of it.

There are lots of other details in the report, some of which I strongly agree with (eg the Policy Targets Agreement shouldn’t be tied to the appointment of the Governor, and if the Board is to be retained as a monitoring agency, it needs some resources of its own, and the Governor himself should not be a member), and others of which I’m more sceptical of (eg the proposed role of the State Services Commission in advice on the selection of the Governor and Deputy Governors, or the idea of devising a –  meaningful –  formal charter for the prudential committees).   One of the peer reviewers –  my former colleague David Archer –  is keen on a greater formal role for Parliament in the appointments, something I’m sceptical of (it just isn’t our constitutional system).  But I would probably favour emulating one aspect of the UK system Rennie doesn’t really touch on: hearings by Parliament’s Finance and Expenditure Committee in which nominees to the various committees can be scrutinised by MPs (and reported on), although not a binding confirmation vote (as in the US).

There are also limitations to the Rennie report.   For example, he treats the current assignment of powers to the Reserve Bank as given (perhaps this was inevitable in what he was asked for, but isn’t a limitation of the current review), a particular issue in the area of financial regulation and supervision.   There also isn’t much richness to his treatment of other countries’ models –  and it remains surprising that he made no effort to engage with Lars Svensson, who was not only a former reviewer of the New Zealand system, but a former practitioner (member of the Swedish monetary policy committee) in the sort of system (open contest of ideas) Reserve Bank management hates.  And perhaps partly because Rennie seems only to have talked to insiders –  eg there was three pages of (totally withheld) material in the Reserve Bank Board minutes on his meeting with them, and no attempt at open consultation –  there is no serious attempt to evaluate how effectively (or otherwise) the Board model has worked over the years.

What of the Treasury’s comments on Rennie?  Their report is short and is mostly a summary of Rennie’s recommendation.  But it was good to see this observation

“we are strongly of the view that a committee decision-making model should be codified in the Reserve Bank Act, and agree that there should be multiple committtees which include external experts”

In the first stage of the current review the government has only committed to a committee, with externals, for monetary policy.  I hope Treasury sticks to its guns, and persuades the Minister of Finance that better governance and decisionmaking on the financial regulation side of things is at least as important, and needs it own statutory reforms.    As even Rennie noted, there is –  for example –  a stark contrast between the governance of the other main financial regulatory –  the FMA –  and that of the Reserve Bank.  In the former, a non-executive Board (all appointed directly by the Minister) has overall responsibility for the organisation and the exercise of its powers, with some specific powers being delegated the Board to the chief executive and staff.  That is a much more conventional, and defensible, model than the Reserve Bank model in which all the power is held by the Governor personally.    And the Reserve Bank exercises a much greater degree of discretion over policy itself –  especially as regards banks –  than the FMA does (where big picture policy is mostly set by the Minister on the advice of MBIE).

As I noted, in yesterday’s release there was also a short note by the Reserve Bank commenting on the Rennie report.  Even though the report was completed months ago, this note is dated 11 December, and is prepared for the Independent Expert Advisory Panel assisting the Treasury-led phase one of the current review of the Reserve Bank Act.  Presumably there are rather more substantive comments, which the Bank is keeping secret –  along with all the extensive background work  (Rennie mentions it) done a few years ago on these issues, which the Bank has previously refused to disclose.

The Reserve Bank does not like the Rennie report at all.

we believe that much of the analysis underpinning the report was insufficient, and consequently the conclusions of the report are unreliable, or would require considerable further analysis.

“Sniffily dismissive” was my own summary of the Reserve Bank’s reaction.

In hand-waving mode, the Bank loftily notes

The Report does not define the nature of the problem it is seeking to address and needs a clearer analysis of the current decision-making framework and why it needs amending. In proposing a particular set of changes to the decision-making framework, the Report fails to provide options and does not demonstrate why the particular changes proposed would result in better policy decisions for monetary or financial policy in New Zealand.

You might suppose that having a decisionmaking and governance model designed thirty years ago when

(a) few central banks had updated their laws in these areas for a long time,

(b) our own laws and practices for governing Crown entities had not really been updated,

(c) the prevailing conception in New Zealand was that monetary policy was simple, and that it would be easy to hold a single decisionmaker to account,

(d) when financial regulation was conceived as a small and largely passive part of what the Reserve Bank did and

(e) when open government was still a pretty new concept, largely unknown to central banks and related regulatory agencies

was sufficient grounds for a serious review, and the probability that better models could be designed.   One might be strengthened in that view if one was aware that (as Rennie notes) no central bank has shifted from a committee-based decisionmaking to a single decisionmaker model for monetary policy, or was aware that no other significant regulatory body in New Zealand was governed the way the Reserve Bank is.

Had a five person Commission spent a year on the report, no doubt there would have been a lot more richness to the background material.  But the case for change has come to be pretty widely accepted already, and even the Reserve Bank gives the game away by conceding that committee-based decisionmaking is generally better than that of a single individual.  Once they conceded that –  and they could hardly do otherwise –  much of the rest of the issue is about detail.

But it doesn’t stop the Bank attempting to distract the Independent Expert Panel.

The Report makes no attempt to document the processes that the Bank actually uses to support its decision-making, beyond the high level parameters established by the Act. Nor does The Report attempt to evaluate the mechanisms that the Bank currently has in place to help ensure that its decision-makers confront a broad range of policy perspectives, including a wide range of views of those outside the Bank. There is, for example, no mention of the role of the broader group of MPC members in providing policy advice to the Governing Committee, the use of external advisers on the MPC, the Bank’s programme of business and financial sector liaison, its active public outreach programme, or its participation in the international financial and economic community. These are all ways in which the Bank considers a diversity of external views and perspectives ahead of its monetary policy decisions.

But so what?   All central banks do this sort of stuff in one form or another, and yet almost all of them also have the respective country’s Parliament specify a statutory committee as the basis for monetary policy decisions.  And if it is good enough for the Governor to invite a couple of outsiders into his second-ring of advisers (these days: it was the first tier when the system was established) why shouldn’t Parliament mandate the involvement of external members?   Moreover, the case for reform has rarely been about the problems with an individual Governor, but about a core principle of institutional design –  resilience.  We don’t want a system that works adequately only when a decent Governor is in place, but when that is resilient to bad choices and bad individual appointees (because in human systems there will be some of those).

I don’t disagree with all the Bank’s comments.  They oppose establishing two separate statutory committees for the different aspects of prudential policy, and I agree with them on that (apart from anything else, the whole thrust of bank supervision –  in particular-  is systemic in nature).

Rennie’s report recommended leaving the precise composition of statutory committees as a matter for negotiation through time.  I think that is wrong.  That balance is sufficiently important that it should be specificed in legislation (as, I understand it, is the near-universal practice abroad).   The Reserve Bank is clearly opposed to any suggestion that external members should out-number internal or executive members.

There is a strong argument that external members should not be able to out-vote the internal members if the latter are in agreement. Such an occurrence could severely undermine the influence of the Governors and the credibility of the institution.

I disagree, and was pleased to see that external reviewer Archer took the same view.  He argued  –  noting that the “probability of groupthink increases with the presence of hierarchy”  –  that “the law should restrict the proportion of executive insiders to below half by a big enough margin that these tendencies have a chance to be offset.

On the Reserve Bank’s argument:

  • if the Reserve Bank insiders, with all the resources and professional expertise at their disposal, can’t persuade enough outsiders to their point of view, it suggests they haven’t got a particularly compelling case (and may in turn struggle to convince outsiders),
  • if the system is set up with, say a 4:3 mix of outsiders and internals, it is explicitly designed by Parliament not to make the Governor a dominant figure (let alone any deputies).  The Governor and Deputy Governors have important executive roles in the management of the institution (generating advice and research, implementing decisions etc) and there should be no automatic presumption that the holders of those offices should play the key role in deciding the OCR outcome,
  • other countries have managed situations in which the Governor has been outvoted, without undermining the institution, and finally
  • even if there were such concerns, the Governor (and other executive staff) always have the option of voting tactically, such that there is no a straight insider/outsider split.  In a number of overseas models, the Governor chooses to vote last.

Perhaps anecdotes aren’t worth much, but it is worth recalling that the senior managers of the Wheeler bank were unanimous in their support of the 2014 tightening cycle.  And wrong.   Groupthink among internals is one of the problems reforms should be trying to overcome.

The Reserve Bank is also pushing back against Rennie’s proposal that all members of the decisionmaking committees (all three of them in his case) should be appointed by the Minister of Finance.

As in any other senior management context, it is essential that the Governor has confidence in his or her senior staff. There are few examples where a Chief Executive has no input into the selection of the senior management team.   It is also surprising that the Report does not confront the dangers that could arise in a system where appointments to the Policy Committees were made by the Minister of Finance. While the Report’s recommendation appears to be made largely on the grounds of ensuring decision-makers have democratic legitimacy (as per the discussion in para 102), the potential risks of political appointments are not considered.

The first of those arguments might look superficially plausible, at least in a corporate context.  But this is a situation where people are exercising considerable statutory powers.  And in central banks it is not at all uncommon for senior figures (often “deputy governors”) to be appointed directly  by Ministers with no formal role for the Governor in that decision (in practice, no doubt there is often consultation).   That is the way things work at the Reserve Bank of Australia (although the Governor then gets to appoint all the actual department heads, which seems appropriate), and at the Bank of England (for deputy governors), and at the Federal Reserve, and at the ECB.  It is pretty much the norm in fact.     Things are different in more conventional models like the Financial Markets Authority, where power vests with the Board, not with management (even the CEO, let alone his/her deputies).

As for the second argument, yes of course there are risks with political appointments.  There are risks with democracy in fact.  But if the Reserve Bank criticises Rennie for not covering that issue in great depth –  he touches on it, and to some extent takes it for granted –  the Bank itself never acknowledges that direct political appointment is the norm in other countries, and seems to work.  Certainly, they cite no evidence suggesting that the New Zealand system has produced superior results to those abroad.  As it happens, Rennie does touch on and speaks favourably of consultation by the government with other political parties for some of these appointments (as is apparently required  by the NZ Superannuation Fund board).

The final Reserve Bank concern that I want to touch on today is the one that seems to concern them a lot: the idea (endorsed by Rennie) that individual members of the statutory Monetary Policy Committee should be individually accountable for their views: that votes, and views, should be minuted and disclosed, and that individual members should be able to openly voice their views (in, eg, speeches or interviews).     It is pretty much exactly the model that has been used in the UK, the USA, and Sweden for quite a long time now.

But here is the Bank.

The proposition that members of the monetary policy committee would be able (and expected) to highlight their individual policy views in public is problematic. While this approach is clearly adopted in some countries (notably the UK, US), we believe such an approach could be destabilising in a small open economy like New Zealand. Any perception of a rift between committee members would be likely to add unhelpful noise to the communication of policy as well as inviting outside lobbying around particular views. There are more constructive ways of conveying divergent viewpoints and the balance of risks around monetary policy decisions.

Neither here nor previously has the Bank –  Spencer, Bascand, McDermott, the existing senior management –  ever sought to clearly articulate what it is about the model used in other countries that would not work well here.   I gather they aren’t even able to do so effectively in private and they floundered in an earlier press conference when they tackled the topic.

What makes New Zealand so different from, say, Sweden –  another “small open economy” –  or in these respects different from the US or the UK (UK economists often like to claim it too is a small open economy)?    The Bank makes no effort to tell us.    They never grapple with notions of open government –  as Rennie notes, the principles of the Official Information Act bias towards openness –  but perhaps as importantly they never really grapple with the huge uncertainties that face monetary policymakers everywhere and always.  Differences of view among policymakers shouldn’t be seen as problematic –  and they don’t seem to create great problems in other countries –  but as, if anything, reassuring.  Groupthink is one of the perils of any institution, and it is perhaps particularly risky where so little of the relevant future is known with any confidence.

Here is David Archer –  former chief economist of the Bank, and now head of central bank studies at the BIS.

Apparent unanimity is quickly shown to be untrustworthy spin. The essential reason is that the future is largely unknowable, and it is foolish to pretend otherwise. Consider the records of the few central banks – including the RBNZ – that publish forward policy interest rate paths. Forecast paths are almost always poor predictors of reality, even in the RBNZ case where unanimity about the outlook exists by construction. Being honest about the limited predictive powers of even highly paid specialists is likely eventually to increase their trustworthiness, at least relative to the results of repeated false marketing
of ostensible consensus.

I’d agree with every word of that.  He argues for timely release of good and transparent minutes, which reflect the individual differences of view.

I don’t like to think that the existing management of the Bank are just trying to protect their own position –  although bureaucrats will tend to protect themselves and their bureau, often to the detriment of the public –  but without a more robust articulation of their specific concerns, grounded in the international experience, it is hard to conclude otherwise.    Policymaking is typically better for dialogue, debate, and challenge –  inside the institution, outside in, and across the boundaries between the two.    Where there is so much uncertainty, and no institutional monopolies on wisdom or knowledge, it is perhaps as important in these functions as in any other areas of government.  It might not be comfortable for the bureaucrats, but that isn’t the goal of policy or institutional design.  And excellent officials –  as excellent outsiders –  should thrive on the opportunities that open and transparent contest of ideas and analysis throws up.

For now, I urge Treasury and the Independent Expert Advisory Panel –  not a group of individuals I have huge confidence in –  to reject the Bank’s apparently self-serving arguments, and to make recommendations that would lead to the redevelopment of a leading open, transparent and accountable central bank.