Thinking about the euro and common currencies

There was interesting and stimulating piece by Matthew Klein the other day on the FT’s blog Alphaville headed “The euro was pointless”.  I’ve been a euro sceptic from way back, and am still counting the months until it dissolves.   A common currency should be an intrinsic part of common nationality, and if the latter isn’t going to happen neither, generally, should the former.  The exception, where there might be some gains from a common currency, and no real costs, could be if countries’ economies were so similar that they faced the same shocks and the same stresses.

That said, I’m not persuaded that Europe’s current plight can be attributed largely to the creation of the euro.  After all, the whole region is at or near the lower bound for nominal short-term interest rates.  If each of the countries had their own currencies, perhaps some would be doing a little better than they are, but on average interest rates couldn’t be lower, and there is no reason to think that, on average, the real exchange rate would be lower.  The zero bound looks as though it binds more tightly in countries/regions with little or no population growth than in others.

But what caught my eye was when Klein got into his stride with a discussion of  “the most natural currency union never to exist: Australia and New Zealand”.

I presume he is unaware that for the first 89 years of its modern existence, New Zealand to all intents and purposes did enjoy a currency union with Australia.  To the extent that one can even think of a NZ/Aus exchange rate until 1929 (or NZ/UK or Aus/UK ones) they were each 1.  After 1914 it was no longer a matter of law, but the private sector still found it worthwhile to manage the exchange rates to retain parity.  (Of course, prior to 1901, “Australia” was a geographical expression only –  a continent made of up of several different self-governing colonies).  There was no banking union or fiscal union (but a great deal of debt), although labour flowed pretty freely between the two countries in response to differences in economic performance.  In those days, of course, both countries traded primarily with the United Kingdom, and trade between them was not overly important.  Some of the shocks –  see the Australian financial crisis of the 1890s –  were nastily asymmetric.

(Here is a link to an earlier post on the longer-term developments in the NZD/AUD exchange rate.)

What about now?  We largely share the same banks, but not the same banking system (having different currencies and different regulators).  Australia is New Zealand’s largest trading partner, but it is by no means a dominant partner (and some of the trade is simply commodity exports –  oil notably –  where it really doesn’t matter if the product is shipped to Australia, or to, say, Singapore or Japan.)  Foreign investment flows are substantial, although in terms of Australian foreign investment in New Zealand the largest single component is the banks.

Klein argues that we do just fine with separate currencies, but I suspect he undersells the possible costs and benefits in the economic case for a common currency.   If the NZD/AUD is typically one of the least variable of New Zealand’s exchange rates, it is much much more variable than the exchange rate between, say, the Netherlands or Germany.  In just the last three years, the monthly average NZD/AUD exchange rate has fluctuated between 79c and 98c –  a difference of around 25 per cent.  Commodity exporters in the two countries have to live with that sort of variability (and more) in world markets for those products, but in the rest of tradables sectors most of the pricing variability comes through the nominal exchange rate.  Economists haven’t been very successful in identifying the empirical magnitudes of the costs of exchange rate variability, and Klein usefully reminds us of the cases of Hungary and the Czech Republic which, even with floating exchange rate, have become highly integrated with Germany (gross exports to Germany in excess of 20 per cent of each country’s GDP, compared with well under 10 per cent of New Zealand’s GDP in exports to Australia).

Nonetheless, it doesn’t seem plausible that the degree of variability in the NZD/AUD exchange rate is not reducing the amount of trade between the two countries to some extent.  Much of the integration of Hungary and the Czech Republic with Germany is, as he points about, about large scale FDI by the highly capital intensive (and highly internationalised) German car industry –  a scale of manufacturing that neither New Zealand or Australia has.  Fluctuations in the exchange rate can be managed within the balance sheets of the car companies themselves (and for them, FDI is often a way of managing the variability of exchange rates).  But that is not an option for smaller producers.  Typical Australia firms considering supplying New Zealand, and vice versa, have to manage themselves the still-substantial fluctuations in the exchange rate, in a way that small firms in the Netherlands don’t face in dealing with Germany, or those in the South Island don’t facing in dealing with the North Island.  Physical distance is still a barrier that is not going away, but it is hard to believe that the exchange rate is not also an obstacle to growing that foreign trade.  The overall effect on potential GDP might be small, but it must be bigger for New Zealand than for Australia, and….after our performance in the last few decades, every little would help.

But the other side of the picture is interest rates.  As Klein notes, we have had similar inflation rates (actually Australia’s have been a bit higher, reflecting the higher inflation target) but real interest rates in New Zealand have been persistently higher than those in Australia.  There have been brief exceptions, but consider the current (not unrepresentative) situation: Australia’s policy interest rate is 2 per cent, and its inflation target is 2.5 per cent, while our OCR is 2.75 per cent against an inflation target of 2 per cent.  Putting an Australian interest rate on the New Zealand economy in the last 20 years would have been a recipe for rather more rapid credit growth, a bigger boom, higher inflation, and a more serious risk of a nasty economic and financial adjustment somewhere down the track..  That is, after all, pretty much what happened in Ireland and Spain, where a German (or Franco-German) interest rate was put on economies that typically needed rather higher interest rates.

It is why, unless we are signing up to a full political union with Australia, I’d be pretty reluctant to think that a common currency was a reasonable proposition, even though such an arrangement might boost real trade.  Perhaps it would be different if we’d seen a couple of decades in which New Zealand’s real interest rates had persistently averaged very close to those in Australia..  And even then, there would still be that nagging “are you sure about what you are getting yourself into”.

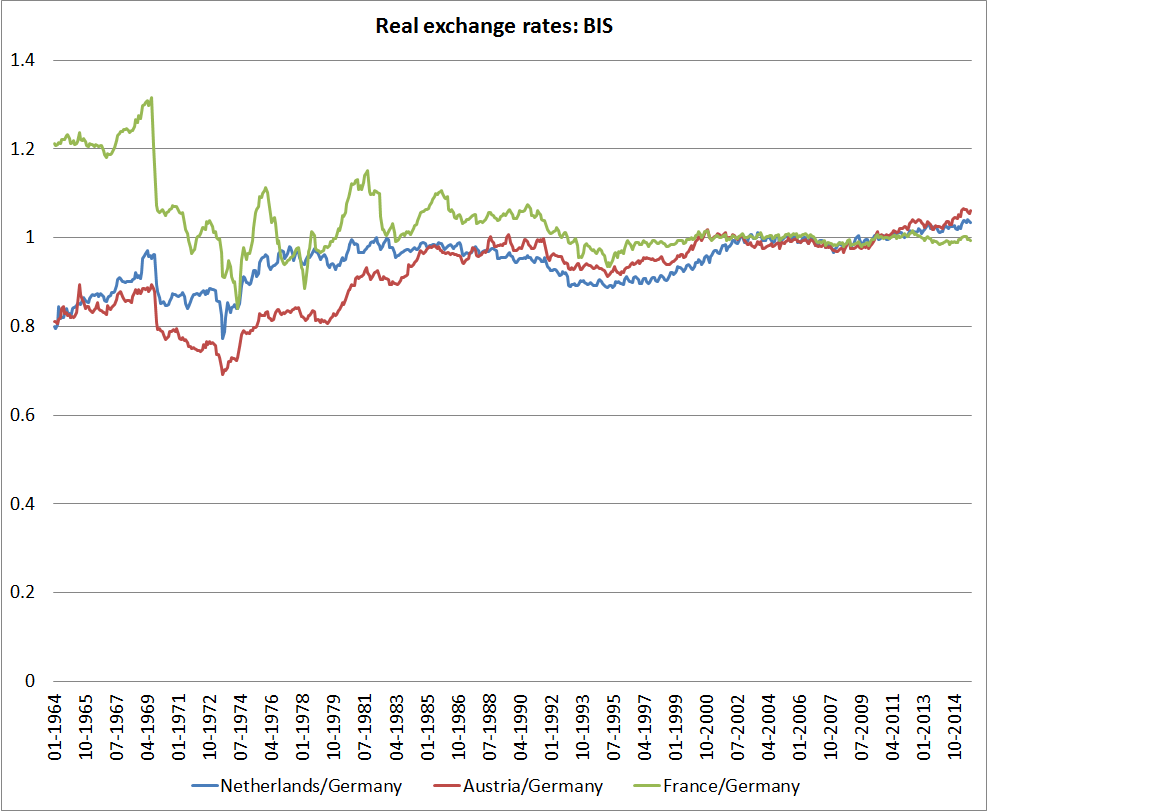
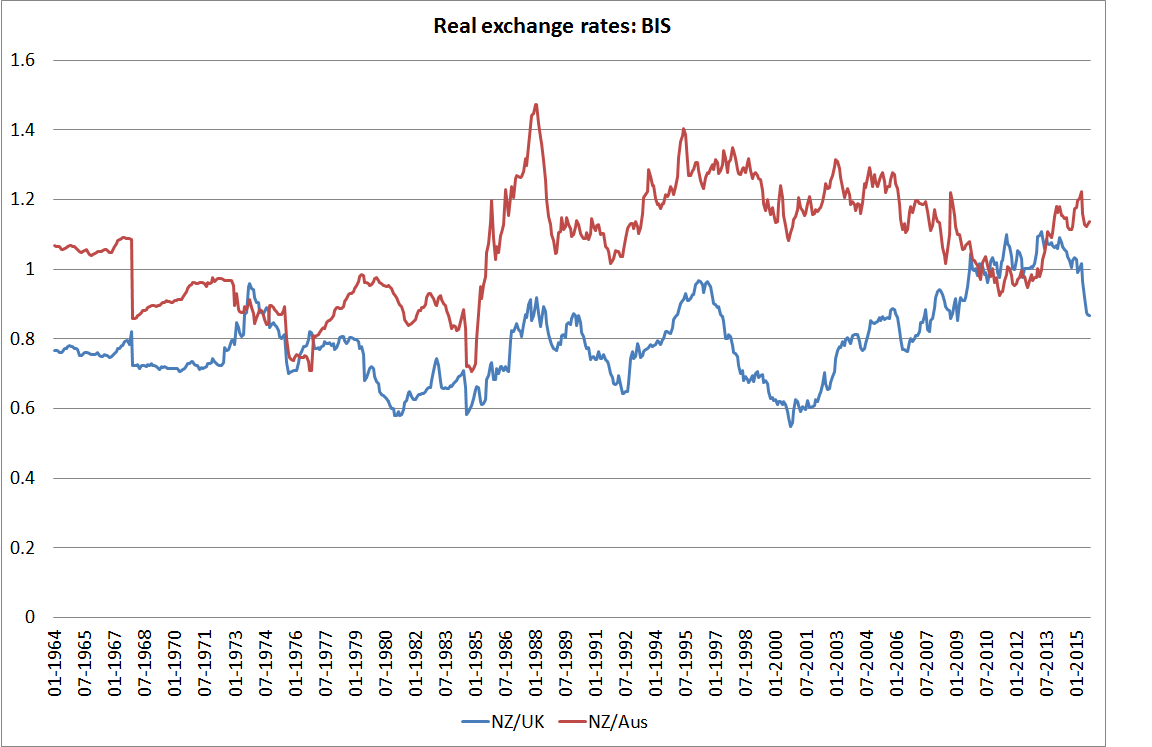
After all, one could easily look at France, Germany, Austria, and the Netherlands and think that a common currency and single policy interest rate worked fine there.  Real exchange rates had been pretty stable for decades (in contrast to, say, NZ/Australia or NZ/UK real exchange rates).

core RER

nz rer

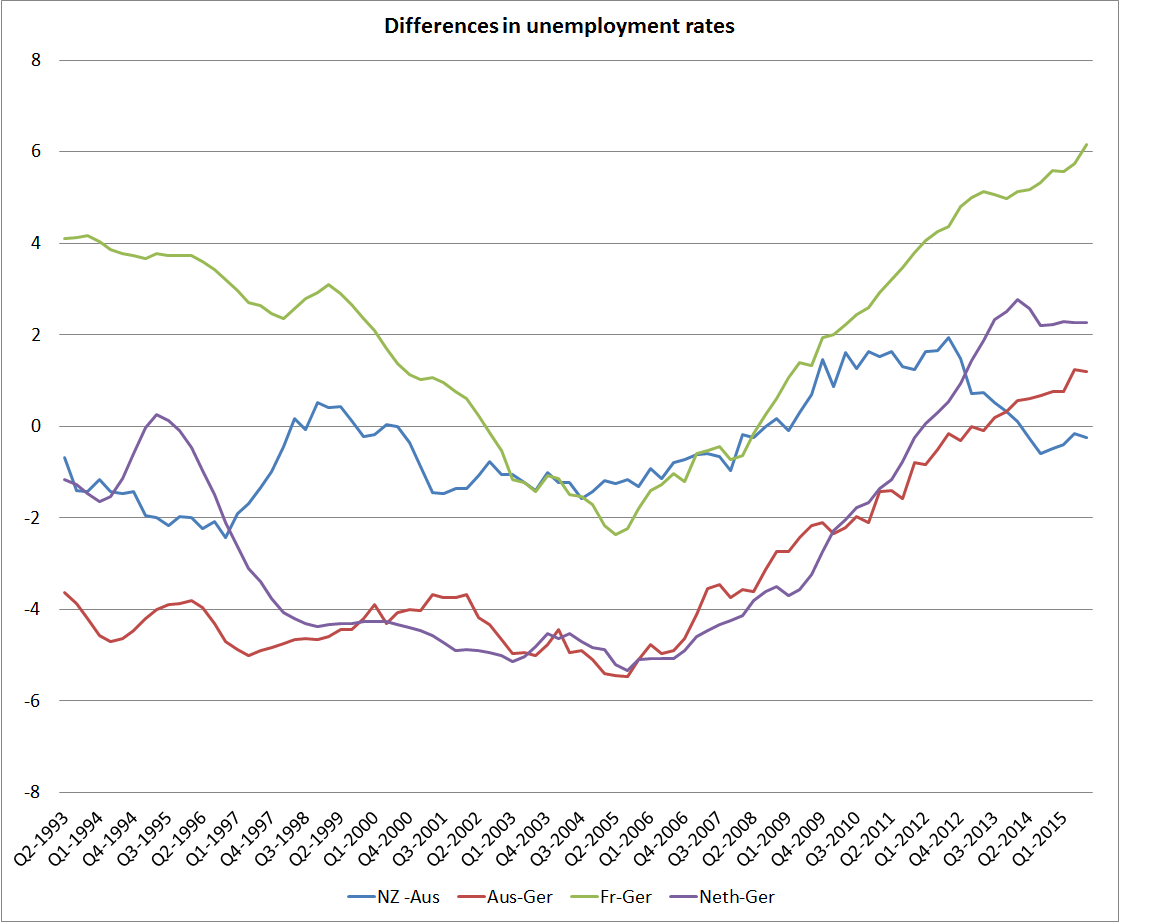
But notwithstanding that, or perhaps even because of it, the unemployment rates in New Zealand and Australia have tracked materially more closely over the last 20 years or so (data for all countries only exists since 1993) than the unemployment rates of France, Austria, or the Netherlands have tracked with that of Germany.  If stabilisation is a concern –  and it is usually does count for rather a lot in modern macro and modern politics –  it isn’t obvious that the euro has necessarily been a great economic choice even for this core group of countries.  In principle, microeconomic policy can deal with these difference, but somehow New Zealand’s and Australia’s arrangement look practically better –  not optimal necessarily (few things are) but not too bad as things are.

differences in U

Then again, if your countries are merging, and becoming a single state none of that may matter.  But there has never seemed much public appetite for that in Europe, and perhaps even less now than there was six months ago.

The nation as a club?

In a moment of weakness a while ago I agreed to participate in a Goethe Institute and New Zealand Initiative panel discussion. “The Sharing Game” later this month.  Here is a link to event for anyone in Wellington who would like to come along.

The topic is written in a perhaps rather Germanic style

Sharing and exchange are basic human cultural practices. They play as big a role in poor countries as in affluent societies. But when do we share – and with whom? What social and cultural developments emerge from the various forms and manifestations of sharing and exchange in times of immigration from cultures that are foreign to ours? How is New Zealand’s face changing through an ever increasing influx from immigrants – rich and poor? Is a bicultural society a utopia?

But I take it as a discussion and debate around diversity and its implications for New Zealand.   I presume I was invited as someone who has been a bit sceptical about the economic benefits to New Zealand of our large-scale immigration programmes.  Since most of those arguments were independent of who the migrants were –  they would apply if the migrants were all from the Home Counties –  the diversity issues are not ones that I have previously focused on very systematically or for very long.

But in thinking about the topic, and reflecting on the importance of openness to new ideas in the historical success of nations, I’ve also been wondering what a nation state means today.  What, for example, if anything does it mean to be “a New Zealander”, (is it just citizenship of this legal entity)?  Are there things that unite us, and how does an immigration programme like ours affect that over time?    Is the decline of religion – itself once an expression of a society’s shared understandings – relevant to the answer?   Quite how is the distinctive position of Maori in New Zealand affected?

This post is an advertisement rather than one offering any answers.  But as I was reflecting on the issue this afternoon and reading around the (unpersuasive to me) open borders literature I stumbled on this stimulating blog post by the Canadian (but British immigrant to Canada) economist Nick Rowe on whether we should best think of the nation as a club.

Don’t think of a country as an area of land. Think of a country as a club, to which a group of people belong. Nomadic tribes were not attached to any particular area of land. Settled agriculture on scarce land is a recent and contingent fact.

Clubs provide club goods to their members. Club goods are (at least partly) non-rival and (at least partly) excludable. Mutual defence is the most obvious club good that countries provide their members, but they often provide others too.

Membership of a club brings with it both rights and obligations. Membership of a club is itself a good. It’s an asset that provides a future flow of benefits (and costs). Membership of a successful club, that non-members want to join, is a very valuable good. Should that very valuable good be priced at zero?

Open borders is not about free trade in land or labour. It’s not about physical geography. Open borders is a proposal that membership of a club be a non-excludable good, and must therefore be priced at zero. Anyone can become a member of any club, without the club being required to give its consent. Countries may not charge non-members a one-time enrolment fee (or cherry-pick applicants) to become a member. Anyone who applies for membership must be granted membership, and pay exactly the same annual schedule of dues (taxes) as existing members to benefit from using the club goods.

Rowe uses the image to build a possible case for an entry fee for migrants, perhaps a substantial one. But it is also prompts a thought around whether there is a sense in which the club has, or needs to have, some meaningful common identity or sense of purpose (the basis for the provision of public goods).  I’m not sure, but as Rowe he notes later in the comments (as much worth reading, in many cases, as the post itself).

My thoughts themselves are not at all clear on the migration question. I just think that the Open Borders people are missing some important stuff. They think of open borders as something like free trade (they say in labour, but I would say in land). But countries are a lot more than just land. Even thinking of countries as clubs seems to me to be leaving out a lot of what is important. Countries are also homes, and extended families. We are born into one, and changing countries is a big deal, both for the migrant and for the hosts (if there are a lot of migrants).

I’m a migrant myself. My views have changed over the years. I have become more small-c conservative. I don’t like too much change, and I can respect others who don’t like too much change either. Countries, and communities, and social institutions, don’t just create themselves overnight.

I find it an interesting perspective to reflect on, and to wonder about the implications of.  I’m suspect the other panellists will be more optimistic than I am, but I wonder if any will lean strongly towards an open borders approach for New Zealand?

Medium-density housing in suburban Wellington

Partly in the cause of research, and partly because I have a bit more time these days, last night I went to my first ever Wellington City Council public consultative meeting.  The Council is keen to promote more medium-density housing in Island Bay (and several other suburbs).  To their credit, they have gone beyond the formal requirements of the RMA and are undertaking an informal community consultation, with information delivered to every household, very early in a process that they hope will eventually lead to a change in the district plan. I think I recall seeing a comment in the recent Productivity Commission report commending this WCC initiative.

The meeting wasn’t an edifying experience, but then I’m not sure that was a surprise.

It doesn’t help that the Council doesn’t have a great reputation in Island Bay at present, despite (or perhaps even because of ) the Mayor being a local resident.  There has been a sense of them ignoring community opinion –  the seawall, severely damaged in a storm almost 2.5 years ago, still not repaired, and a hugely acrimonious debate over a rather expensive new cycle-way which can’t pass any conceivable cost-benefit test.   All that makes for a degree of cynicism –  vocally expressed last night – about the genuineness of any consultative process.  (And all that is before one considers the folly and hubris of an organisation that wants to put tens of millions of dollars into an uneconomic airport runway extension. )

There is also a degree of hostility to the local Special Housing Area. I don’t fully understand that hostility.  The moribund buildings of a former Catholic school (closed by the church 35 years ago) are less than a couple of hundred metres from our place, and I have long looked forward to them being replaced with houses or apartments[1].   Island Bay is a popular place to live, and this private land is not currently being used at all.  If someone is keen, at last, to develop it, it might be small step towards keeping housing only moderately unaffordable.

But that is all by way of background to the medium-density housing consultation, which continues to puzzle me.  Question 1 on the WCC consultation form says “Where should medium-density housing development happen in your suburb?”, which on the one hand presumes that people agree that such development should happen at all, and on the other leaves me scratching my head thinking “well, surely on any site where someone finds it worthwhile to do so”.   And then “what standards of design should the medium-density housing meet?”, and I’m thinking “whatever works best for developers and willing buyers”.   But I’m pretty sure I was the only person in the room last night thinking anything remotely along those lines.  Not that I would be any more sympathetic if it was, but Island Bay is not some olde worlde place with uniform Edwardian architecture.  It is a pleasant mix of the old and new, where the number of dwellings per square kilometre has increased enormously in the 37 years since I first came here (through some mix of infill, new streets further up hills, and medium-density developments on several larger existing sites).

Instead, it was a case of the regulatory state run rampant (from both the supply and demand side).  The Council staff had a Powerpoint presentation which started well –  headed “Housing Supply and Choice”- but it was pretty much downhill from there.  Instead of a focus on facilitating landowner rights, consumer choice, and competition, the whole thing flow from a central planner’s identification that Island Bay is one of those places with a strong “town centre” and hence a candidate to promote medium-density dwelling.  I was trying to work out why Island Bay is identified and not, say Seatoun –  similar public transport, similar vintage houses –  and I can only conclude that it is because the latter lacks a supermarket, an anchor of the “town centre”.  It puzzles me what happens to the Council’s logic if the(small by modern standards) supermarket were to close –  or if the Council were, for once, to do a hard-headed cost-benefit analysis and close the small local library.    The local identities who have run a stationery and children’s bookshop for the last 40 years are just about to retire, and the chances of that business continuing can’t be strong.

But part of the consultation is about preparing a “plan to guide development in Island Bay town centre”.  The so-called “town centre” is perhaps 15 private shops, in a higgledy-piggledy variety of styles, several of which are threatened by the Council/government earthquake-strengthening requirements.  But why do we need bureaucrats “planning” a “town centre” to “ensure coherency across different developments and help contribute to a more attractive and vibrant centre”?    At the meeting, the bureaucrats talked of checking to ensure that “we have located the town centre in  the right place” –  to which one response might be that the market already resolved that one more than 100 years ago.  Sometimes I think I must be missing something important, but then I think it is just bureaucrats and local politicians run amok.

And the Council draws on some demographic projections for the next thirty years to argue that they need to facilitate housing for older people who will want to downsize but stay in the neighbourhood.  Quite possibly there will be such a demand –  I expect to be one of the older people, although I don’t intend going anywhere  – but when you rely on such projections, and especially when you can’t even adequately explain how they are done, you are on a hiding to nothing.  Council staff drew a lot of fire for those numbers.  Much of it was quite ill-informed, but it was hard to have much sympathy.  Inevitably, holes appear the moment you prod, ever so gently, a projection of that sort. Choice and flexibility etc should be the watchword not “we wise bureaucrats have identified this specific need 25 years hence and want to change the law now to meet it”.

And then Council staff talk of undertaking a “character assessment of the suburb”, and burble on about wanting to “make sure that all new development is high quality, the design and appearance fits in with the surrounding environment, and it can stand the test of time”.    Just like the IMF the other day, the Council is keen on only “high quality” housing, but why is that something for them to decide, rather than willing buyers and sellers?

And so it goes on.  Bureaucrats talk of a desire to “decrease private motor vehicle use” and “encourage more walking”  (and hence medium-density housing might be encouraged five minutes walk from the town centre but not seven).  What happened to facilitating choice I wondered?  Oh, and fixated on accommodating possible demands from old people, the chief planner present commented that the Council wanted to encourage medium density housing in which the core living facilities were on the ground floor.  It gets tedious to say it, but isn’t there a market test in these matters?  Dwellings that meet market demand will sell better than those that don’t.  And aren’t maximum site coverage rules one of those things that work against single storey dwellings?

So the Council staff were bad, but they met their match in the residents.  There was a strongly negative reaction to the notion that anyone outside Island Bay should have any say on the proposed changes – forcing staff to downplay the very suggestion.  There was a great deal of concern about protecting people’s house prices (up), but no apparent sense that allowing land to be used more intensively would, all else equal, make it more valuable not less.  There was concern about what sort of socially-undesirable people might move into these new dwellings (and this is one of the more left wing suburbs around), and so many demands for controls and restrictions that –  briefly – the Council staff were forced to defend the ideas of choice and private property rights.  One person was appalled at the idea of three storey dwellings – this is a suburb surrounded by, and partly built on, high hills. And not a mention from the floor – although it was hard to get a word in – of the idea that people should be able to use their own land as they liked, or of the attractions of helping keep places only moderately-unaffordable so that perhaps one day our children might be able to buy here.

Council officers were reduced to plaintive observations that “the city is growing and people have to live somewhere” (downtown high rises appeared to be the response from the floor), which I might have sympathised with were it not for the historical evidence that as cities get richer they tend to get less dense not more dense –  something the planners are no doubt oblivious to, and perhaps disapproving of.  Harder to encourage walking I suppose, as if technological change had not given us options.  The invention of the tram helped open up places like Island Bay in the first place –  otherwise it was a bit far to walk to work.

I recently criticised the Productivity Commission for the bits of its land supply report that appeared to endorse the way some (most?) Councils were setting out to promote compact urban forms (rather than to facilitate choice and respond to individual preferences).  I came away from last night confirmed in that view.  I’m all for allowing more intensive development, not just in individual suburbs but across Wellington (and all other areas for that matter).  But the pressures to do so, and the sorts of vocal clashes I witnessed last night, arise largely because Councils are reluctant to see the physical size of the city grow.  Wellington might not have much flat land –  although most people probably don’t live on flat land in Wellington anyway –  but any time I fly in or out of the place I’m reminded that it is not short of land.   Regulatory restrictions –  and perhaps at the margin the rating system –  combine to make it optimal for developers to release land only slowly, and that helps keep the price of all urban land high.  For landowners in existing suburbs part of the appeal of more intensive housing (eg infill on existing rules) is realising the value that regulatory restrictions had artificially added to land prices.  If a section on our main (flat) street, The Parade, is worth $500000 or more, subdivision and more intensive development must be attractive.  If it were worth $150000 –  which it might well be if  new building opportunities were readily available on the periphery (or in greater Wellington’s case, most actually between Wellington on the one hand and Porirua and Lower Hutt on the other)), more people would probably prefer to keep a decent-sized backyard or front lawn.  I’d probably still favour allowing more intensive development, but I don’t think we’d see much of it, especially this far from the centre of town.  Space appears to be a normal good.

As it is, the confrontations will go on.  I don’t like to predict how our one will end, but whatever the outcome the process is a pretty unedifying, and unnecessary, one.

[1] There is a beautiful chapel in the buildings, and I would be sorry to see it go. But I’d also be reluctant to see my rates used to save it, especially if doing so compromised the development opportunities of the site.

Are land taxes the answer to house prices?

I’ve been pondering a post on land taxes for some time, but was prompted to jot something down today by a couple of recent pieces, including in today’s Herald  by two lecturers in politics at AUT, Nicholas Smith and Zbigniew Dumienski.  Sub-editors present their arguments under the headline “Land tax best fit for housing crisis”, and the authors’ own conclusion is only a little more nuanced.

Given the multiple problems stemming from Auckland’s housing crisis, an LVT stands out as the best-rounded of the policy options on the table. Not only would it address house price inflation, it could also result in a more efficient use of land, mitigate urban sprawl, lower the burden on the natural environment and reduce the risk of real estate bubbles; all without undermining the foundations of economic growth.

I’m not a land tax expert, but I’m no longer so convinced.

Which doesn’t mean that I’m inherently unsympathetic to the argument for a land tax. In fact, I once wrote a Treasury paper on overall economic policy direction, that ended up on Bill English’s desk, and which was, with hindsight, rather too readily enthusiastic about a land tax.

In principle, taxing things that are in fixed supply has some theoretical and practical appeal.  Collection is pretty easy –  every piece of land has an identifiable owner.  And  whereas if one taxes business profits (say) heavily there will be less investment taking place,  taxing land won’t make much difference to how much land there is  (it will make some difference because the value of land is partly about work done to it (drainage etc).

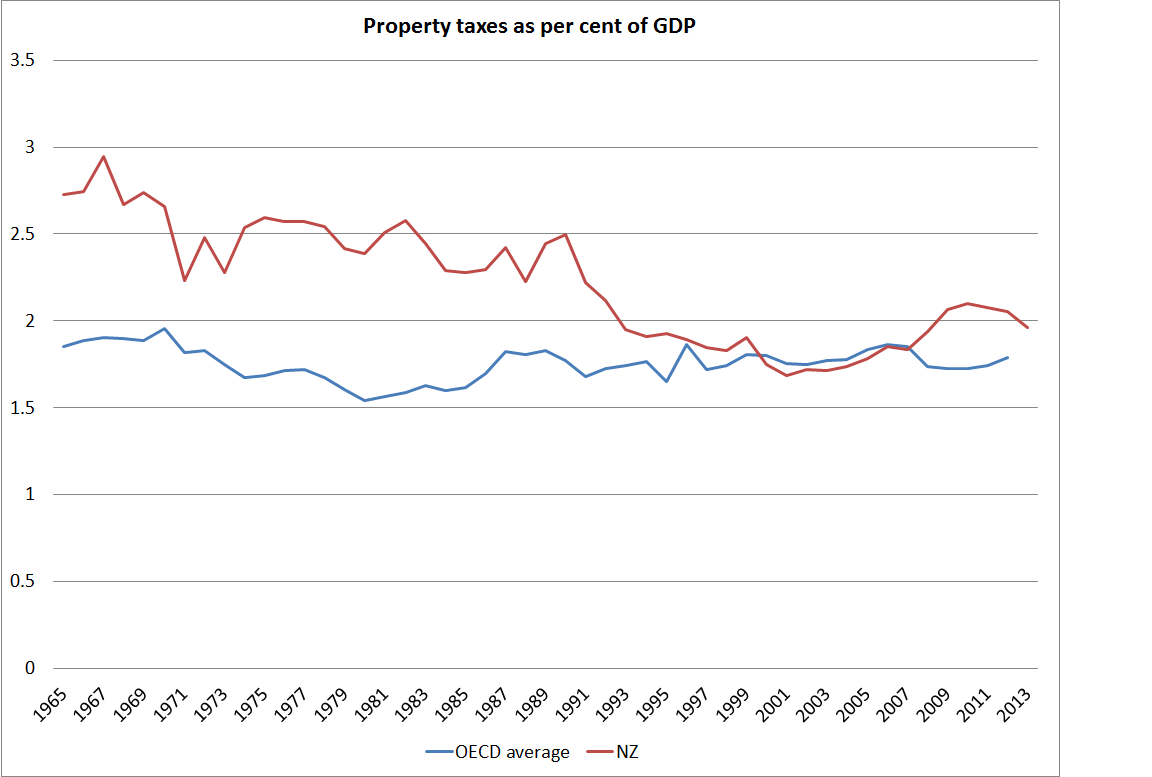
And, of course, as the authors point out we’ve had a land tax previously –  it finally disappeared in the early 1990s, by when it apparently applied mainly to land under urban business districts.  And we still have, in effect, some partial land taxes: in some areas, local authority rates are levied on the basis of land values, and in many places (especially Auckland) even the capital value rating system have come a lot closer to a land tax as the land share of a typical “house + land” has climbed sharply.  And OECD data show the New Zealand property taxes, as a share of GDP, are already a bit above the OECD average.

property taxes

Had we put a land tax on in 1840, and kept it in place ever since, I’m not sure I’d be arguing for abolition now.  But the historical track record of the tax we had was not that good.  Apart from anything else, the rules kept changing (and changing), with the base being progressively whittled down.  Smith and Dumienski note that “it was arguably an important factor contributing to New Zealand’s once-famed egalitarian character”.  I’d be keen to see the evidence for that claim.   New Zealand economic historians, at least those I’ve read, don’t seem to have seen the land tax in quite those terms.

Any material change in the tax system involves significant redistributive consequences (or big compensation packages).    No doubt there isn’t much public sympathy for “land bankers” in and around our cities (and since these people are mainly profiting from other regulatory distortions, I wouldn’t have much sympathy either).  But what, say, about the sheep farmer, in an area where values haven’t been much affected by dairy conversion opportunities?

I’m also not quite sure what sort of tax rate the advocates of a land tax have in mind.  People often glibly talk (and I have in the past) of a 1 per cent annual land tax as if this is a pretty small amount.    But real risk-free returns are not what they were.  New Zealand has probably the highest real interest rates among advanced economies and a long-term real interest rate here (20 year inflation indexed bond) is still just under 2.5 per cent.  The comparable US yield when I checked this morning was 1.1 per cent, and that is now quite a common sort of rate internationally.  People (especially central bankers) keep talking about interest rates “normalising”, but real interest rates have been trending down now for decades, and no one really knows with any confidence whether the process has ended, let alone whether it will be materially reversed.   In this climate, a land tax of anywhere 1 per cent would seem quite incredibly burdensome (in a way that it might not have seemed in New Zealand in the 1990s when real risk-free interest rates were touching 6 per cent).  Even if one could make a theoretical case for such an onerous tax, the political economy suggests that it could not be sustained (and would not be expected to be sustained).

Perhaps we could have a rather lower rate of land tax?  Perhaps a half or a quarter of a per cent land tax could be politically sustained?  But then one is left asking whether it is really all worth it.  Bearing in mind that urban land is already taxed, would it make that much difference to the cost of urban land –  the issue Smith and Dumienski are driving at  – or allow a material gain in economic efficiency from shifting away from more distortionary taxes (eg lowering our high taxes on capital income)?   After all, most people now agree that the real issues around urban land prices are not ultimately the tax system, but the regulatory restrictions on land use that central and local governments facilitate.  To some small extent, those restrictions seem endogenous to land prices –  ie when land prices get sky high (or least rise rapidly) there is pressure to ease the land use restrictions. If so, perhaps a land tax would just allow Councils to keep tighter restrictions in place for longer, undermining any possible efficiency gains from a land tax.

But let’s get back, in conclusion, to the Smith/Dumienski list of benefits.  They argue that a land tax would

  • address house price inflation,
  • result in a more efficient use of land,
  • mitigate urban sprawl,
  • lower the burden on the natural environment and
  • reduce the risk of real estate bubbles;

All without undermining the foundations of economic growth.

What’s not to like?  Well, first, in principle a land tax should lower the value of land (ie a one-off shift in the price). But it is not obvious that it will have much impact on either house price cycles, or trend pressures resulting from, say, the interaction of population pressures and land use restrictions.    Perhaps the authors have in mind some more sophisticated land tax that would  effectively be  a capital gains tax, but they don’t suggest so in their article. And as we know, real world capital gains taxes don’t appear to have done much to improve the functioning of housing and urban land markets

Would it result in a more efficient use of land?  I suppose that depends on one’s model, but I’d have thought that taxing an asset will result in a more intensive use of that asset, with no necessary presumption that the more intensive use is more efficient.  Of course, it might be less inefficient than the alternative possible taxes, but that is a different issue surely?

Relatedly, if land (across the country, not just in cities) is used more intensively, why is there a “lower burden on the natural environment”?  Land in its natural state poses no such burden, but if (say) farmers need to use marginal land more intensively, to maximise profit subject to a land tax, I’m not sure why this is an environmental gain.

And I simply don’t see the argument made that to “mitigate urban sprawl” is an appropriate public policy objective.  As is well known, urban areas in New Zealand make up a very small proportion of New Zealand’s total land area, and I’d have thought that revealed preference (reflected in prices) suggested that the most valuable use of land on the fringes of cities was typically for housing, rather than for agriculture.  “Sprawl” is just the pejorative term for “space” –  most people seem to want some (and historically as cities get richer they have gotten less dense) much though the planners might disapprove of their preferences.

To repeat, I’m not in principle opposed to a land tax, but I’m:

  • sceptical that it could be imposed, in an efficient way, on an enduring basis
  • sceptical that it would allow much effective tax system rebalancing
  • and doubtful that, on the scale at which it could be imposed, it would really make much sustained difference to urban land prices, and trends in them over time.

There is no great secret to why New Zealand urban land prices are high. It is largely down to the impact of the central and local government regulatory restrictions on land use.  Far better to tackle those at source, and give freedom back to landowners.  Competitive market processes could then be expected to produce affordable houses, as they have in much of the United States (which doesn’t mean Mt Eden prices will ever be the same as Invercargill ones).    Of course, one can reasonably argue that such reforms themselves might not prove durable, and if reform were totally “open slather” that would probably be true, but whether or not we have a land tax is simply not at the heart of the urban land price issues.

I’d welcome comments and thoughts on this issue, and if (for example) Andrew Coleman, at Otago, felt inclined to add one of his occasional, typically very insightful, comments drawing on his own past work (eg here) in the area I’d be very interested to read it.

Some FSR omissions

Sometimes you read a document, particularly one that has interesting material in it, and react (positively and negatively) to what is in front of you.  It is harder to spot what isn’t there.

After my earlier post I went out, and as I walked the streets it struck me that I didn’t think I had seen any mention of credit standards in the Financial Stability Review.  I got home and checked.  Searching the whole document, none of these terms appeared:

“credit standards”

“lending standards”

“credit policies”

“lending polices”

In fairness, there was a brief mention of the difference between how much banks would lend thirty years ago ( in the 1980s when banks were really only just moving into housing lending) and now, but I don’t think that really fills the bill.

At one level that wasn’t too surprising –  I’ve highlighted previously how their Head of Financial Stability (and Deputy Governor) had managed to give a whole speech on housing and housing finance risks without mentioning bank lending standards.  But it was pretty disappointing nonetheless.  Bad loans collapse banks and financial systems.  Sometimes macroeconomic circumstances turn out quite differently than anyone could have expected and even what were objectively pretty good classes of loans can get into trouble.  But, mostly, the really bad losses arise from a climate in which lending standards have been pushed progressively lower and laxer.   Very aggressive lending on Irish property development springs to mind, and the policy-driven deterioration in US mortgage standards.

But if it is the sort of omission we have come to expect from the Reserve Bank, that doesn’t make it any more acceptable.  Surely we should expect our bank supervisors to have a good feel for trends in bank lending standards, and to be able to adduce evidence to support their view?  APRA manages to, so why not our Reserve Bank.  So far, they have given us no evidence of, say, a sustained deterioration, beyond the point of prudence, in the lending standards of our banks over, say, the last decade, or even just the last couple of years (the latter being the period in which they have adopted much more aggressive regulatory interventions).

Incidentally, I also checked and found that the phrases “credit to GDP” and “credit to GDP gap” did not appear –  even though I’m not aware of any systemic financial crisis which has not been preceded by a recent substantial increase in credit to GDP (increases 10 t0 15 years ago don’t count).  It was also a little surprising that the terms “exchange rate”, “real exchange rate” or “TWI” don’t seem to appear either, even though the thing that usually goes hand in hand with a sharp run-up in credit to GDP, in foreshadowing heightened risk of crisis, is a material appreciation in the real exchange rate.    In the period 2002 to 2007 we had both –  and the banks had much smaller (liquidity and capital) buffers –  and yet the banks still came through unscathed.

If the Bank can’t point to detailed prudential evidence (deteriorating lending standards) or adverse trends in the big macro indicators (rapidly rising debt etc), it is really difficult to be confident that their recent regulatory actions are necessary, and well-warranted bearing in the mind the costs to individuals and businesses, in promoting the soundness and the efficiency of New Zealand’s financial system.

The RB Financial Stability Report

This won’t be a long post.  Today’s Financial Stability Report was pretty uneventful relative to May’s .

The body of the report had some interesting material, both on dairy exposures and housing lending.

But I had a number of concerns.

My most important was that the Financial Stability Report was, again, in breach of the Act. The Reserve Bank can write as much interesting analysis as it likes, and good analysis is always welcome, but they must comply with the Act.  Section 165A says as follows:

A financial stability report must—

  • (a) report on the soundness and efficiency of the financial system and other matters associated with the Bank’s statutory prudential purposes; and
  • (b) contain the information necessary to allow an assessment to be made of the activities undertaken by the Bank to achieve its statutory prudential purposes under this Act and any other enactment.

Much the same words are in section 162AA as well.  And this document simply does not comply.  It hardly comments on the efficiency of the financial system at all, at a time when the Bank is imposing ever more-extensive and complex controls on the activities of banks.

These are the four references to “efficiency”:

  • The first, on page 52, is simply one item in a list in an Abstract, summarising the chapter
  • The second , page 54, is purely descriptive, and deals only with payment systems (“the Reserve Bank has an objective of efficiency”)
  • The third, on page 56, refers to a goal as part of the “regulatory stocktake”, to improve the efficiency of regulation of banks
  • And the fourth, on page 58, is also purely descriptive (“ The Reserve Bank acknowledges that appropriately robust outsourcing arrangements can improve a bank’s efficiency”)

Not one of these refers to the efficiency of the financial system, and none offers any analytical perspectives.  But the Act is quite clear.  I hope some MP chooses to ask the Bank about it when they appear at FEC, and that the Bank’s Board –  legally charged with holding the Governor to account –  poses the question, and perhaps chooses to highlight the omission when they next write an Annual Report.  As it is, the accountability model is not working.  The Governor is imposing more and more controls, taking us further from an environment of regulatory competitive neutrality (across institutions, across types of loans, across places of loans and so), and he simply does not provide the material that would enable us to assess the Bank’s activities against the statutory responsibility to promote the soundness and the efficiency of the financial system.

Somewhat related to this point around efficiency, the Bank continues to assert that its LVR controls are reducing risk in the financial system.  But I don’t think I’ve seen analysis from them, either when the first controls were introduced, or with the latest extension,  looking at how banks will choose to maximise profits for their shareholders if they are prevented from undertaking some classes of lending.  There may be perfectly satisfactory and reassuring answer, but if banks are not able to undertake their preferred types of lending (which must be the case, or controls would not be binding) surely we should expect them to seek out other opportunities, which might –  or might not –  be just as risky as those the Reserve Bank is restricting?  The concerning dimension is not just the absence of the analysis, but the fear that the silence might suggest the Governor has not even thought about the issue.

What else struck me?

The Bank’s continued obsession with “investors”.  When pushed, the Governor will say that the Auckland housing situation is mainly a supply issue, but if supply remains severely restricted by regulation, and demand increases (eg with an acceleration in population growth) quite what would he expect, but some increase in people purchasing in expectation that tomorrow’s price will be higher than today’s?   And in a city where the combination of policy failures has pushed the home ownership rate down so far, what is surprising or troubling (from a financial stability perspective) about around 40 per cent of mortgage loans being for rental property purchasers?    They haven’t addressed these issues, which again makes it hard to assess their activities.

I was also struck by the mire the Bank has made for itself.  The Reserve Bank is  primarily a macroeconomic policy agency, and even in its financial stability role it has a systemic statutory focus.  And yet we have the Governor and Deputy Governor being quizzed about housing developments in Hamilton and Tauranga (4 and 3 per cent of the country respectively) and the Governor responding in some detail about the nature of the demand in those two markets (although with no apparent sense of any model of equilibrium prices).  Fortunately, they did say it was “too early” to be considering Hamilton or Tauranga specific measures.  I hope it always is.  The Bank, and those holding it to account, should be prompted to reassess and pullback from trying to run system-wide financial stability policy TLA by TLA.    More and more they turn themselves into people doing inherently political stuff, with no political mandate, and soon no doubt (if it hasn’t happened already) they will be being lobbied by councils and other entities in Hamilton, Tauranga and who knows where.

It was good to see journalists asking about the Bank’s stress tests.  The Governor and Deputy Governor now openly acknowledge that the banks, and the financial system, would be just fine if the system faced a shock of the size (very severe) the stress tests were done on.  That really should be largely the end of the matter for them.    Instead, they go on about how in a downturn banks might rein in their lending.  Indeed, and it is surely up to them –  the owners of private businesses –  to make choices about whether, and to what, extent it is economic to lend, and (hence) whether to raise new external capital.  We have monetary policy to deal with any associated economic downturns that lead to inflation undershooting the target.

Perhaps it is just me, but I continue to be struck by how little thoughtful cross-country or historical comparative analysis is provided in the FSRs (or in other associated documents, such as the Bulletin).  No two situations are ever fully alike, across time or across countries, but those comparisons are often the most helpful benchmarks we have.  And if the Reserve Bank can illustrate for us which comparators it regards as useful, and which not, and lay out the reasons for those judgements, it can help enable us to better assess how the Bank is handling its responsibilities in this area.  One difficulty for people doing the assessment is that almost all the factual and analytical material in this document could have allowed the Bank to have reached quite different conclusions  (eg high capital standards, strong liquidity buffers, moderate credit growth, all suggest that despite the rapid growth in Auckland house prices, the financial system is robust and efficient, and no further regulatory measures have been needed over the last couple of years).  We know what the Governor thinks, but how are we to know –  or at least have greater confidence –  whether he is right, or whether the alternative story would have been better?    The Bank needs to be doing, and publishing, more research in this area.

Oh, and finally, in the press conference it was hard not to conclude that the Deputy Governor looked rather more gubernatorial  and on top of his material than the Governor did. And it no doubt helped that Grant actually looked at the camera and the questioners.

The social democrats from the IMF

The social democrats from Washington –  the IMF –   have been in town, and today released their preliminary report.  It is quite strikingly different to the last one, released in March last year.    The so-called Concluding Statement, at the end of the team’s 10 days or so in New Zealand, isn’t very long, and can’t cover lots of things in depth, so keep that in mind as you read the rest of this post.

The mission team will have spent a lot of time with Treasury and Reserve Bank staff.  Indeed, the draft of the Concluding Statement will have been haggled over in a meeting with fairly senior officials from the two agencies, and it is pretty rare for the final product to contain anything that those agencies have much disagreement with.  Indeed, Fund missions can get so close to staff in the host countries that even when two countries, reviewed by teams led by the same mission chief, have much the same circumstances, the policy advice will at times differ –  seemingly to reflect what the authorities in the two countries want.  A great example last time round was direct regulatory interventions in the housing finance market, which the IMF has enthusiastically supported here, but had been silent on in Australia.  I’m not sure if the mission chiefs are still the same for the two countries, but checking the most recent concluding statement for Australia, I notice that the inconsistency has persisted.

Rereading the 2014 Concluding Statement the upbeat tone was unmistakeable.

“the economic expansion is becoming increasingly embedded and broad-based”

“with the economy set to continue to grow above trend in the near-term, pressures on core inflation should follow”

“we welcome the RBNZ”s shift toward a policy of withdrawing monetary stimulus, with the clear signal that it expects to increase rates steadily over the next two years”.

Oops.

(Although no doubt the Governor was pleased with the statement at the time.)

There is, of course, no hint in today’s Statement that the Fund might have misread things that badly last year.  Space constraints I suppose.

But what about this year’s Statement?

I was interested to read that “inflation is projected to rise to within the RBNZ”s target range of 1-3 per cent in 2016, as the impact of the decline in oil prices drops out, and the depreciation of the New Zealand dollar passes through”.  No mention anywhere, at least as far as I could see, of any rise in core inflation towards the mandated target midpoint.  But I guess they are running the same lines the Governor always does –  over-emphasising the one-offs (especially now that the exchange rate has rebounded) and quietly ignoring the persistent undershoot of core inflation.

But in some ways what really struck me about this year’s Statement was the wholesale leap into advocacy of a range of microeconomic and structural policies.  It is a very different emphasis from last year.  I know the Fund has changed mission chief for New Zealand, but surely there should be more continuity in the analysis and advice than this?

What do I have in mind?

Somewhat surprisingly, the Fund weighs in on immigration policy, noting that “continued high net immigration could pose challenges for short-term economic management, but in the longer run would boost growth”. Well, no one will really dispute the short-term demand pressures, but where is the IMF’s expertise in immigration?  How have they concluded that our past immigration has boosted (per capita) growth?  They might be right (or not) but how does it relate to the core macroeconomic and financial stability mandates of the IMF?

The Fund then suggests, in a paragraph on government finances, that “in addition, investment in infrastructure and housing (in high-quality projects) should be accelerated where possible to support higher housing supply in Auckland, and infrastructure improvements”.  Where is the evidence of the central government infrastructure shortfalls?  Government capital expenditure in New Zealand has been among the highest in the OECD, as a share of GDP.  And what leads the Fund to think the government should be building houses itself (only high quality ones  mind)? It all seems rather unsupported, and far from the principal mandate of the IMF.

They note too that “intensifying efforts already underway to boost higher density housing would be welcome”. What gives the IMF the basis for suggesting government policy should be skewed towards higher density housing?  And how does it all connect to macroeconomic stability anyway?

Last year, the IMF was cautious about further regulatory prudential measures –  tools should be “used sparingly and with caution”, but this year they are champing at the bit –  no doubt reflecting the Governor’s new enthusiasm.  After a perfunctory observation that “the impact of the new [prudential] measures to reduce financial stability risks will need to be evaluated”, they rush straight into “but the authorities should be prepared if further steps are needed”.   I suppose that could be seen as just contingency planning, but there is no sense here at all that these interventionist measures could conceivably have costs, or that any benefits might be small.

Last year , there was no mention of tax issues at all, but now not only are “the newly introduced measures to deter speculative investment“ welcomed (those evil  “speculators” at it again –  can’t have them in a market economy) but “and further steps in this direction should be envisaged”.   The Fund apparently favours “a more comprehensive reform to reduce the tax advantage of housing over other forms of investment“  [that would be unleveraged owner-occupiers they were targeting?] and “reducing the scope for negative gearing”.    Many people might agree with the Fund, as a matter of tax policy, but where is the evidence, including the cross-country insights that (these issues are important that) the Fund is supposed to be able to offer?  And where is the consistency from one mission to the next?  If agencies like the IMF have substantive use –  as distinct from a convenient echo of the preferences of the Reserve Bank or Treasury –  it has to be keeping a clear focus on the longer-term issues that matter to macroeconomic and financial stability.

There are some odd features to the statement.  In one place, they say that “stress tests  indicate that the sector [banks] can withstand “a sizeable shock to house prices, the terms of trade and economic activity”, but then a page or so later they observe “financial system stress tests suggest it is able to withstand –  at least in the short-term  –  adverse developments related to China spillovers, dairy prices and the housing market”.  I think the final haggling session with officials must have missed something, and will be interested to see if the “in the short-term” caveat reflects something coming out in tomorrow’s FSR.

The other odd feature is this “on the one hand, on the other hand” paragraph

Monetary policy has been focused on the primary objective of price stability. Only if financial stability risks become broad based and prudential policy is insufficient to contain them, then using monetary policy to ‘lean against the wind’ could be considered as part of a broader strategy to rein in financial stability risks. Even in this case, the benefits would need to be weighed against the output costs and the risk of policy reversals.

They would have been better simply to have left it out.  Monetary policy in New Zealand has no statutory basis for pursuing anything other than medium-term price stability, and it hasn’t even been doing that overly well.  Having already had only an anaemic recovery, partly because of an overly cautious Reserve Bank, and two policy reversals –  a record for the OECD –  the IMF might have been better advised to simply urge the Reserve Bank to do its job –  deliver inflation consistently around the middle of the target range.    When they get back to the office, perhaps the mission staff could talk to Lars Svensson, currently at the IMF, about the attractions (or otherwise) of using monetary policy to “lean against the wind”.

The Concluding Statement wraps up with a discussion of Medium-Term Policies.   Last time round, they had a balanced, but high level, discussion which noted structural imbalances between savings and investment (by definition, since the current account has long been in deficit], and noted that structural measures might be needed “to address the savings-investment gap”.    Probably reflecting the IMF’s limited expertise in the area, it went no further, and did not even attempt a diagnosis as to whether any issues might more probably be found on the savings side than the investment side.

But this time round savings is confidently identified as the problem.  We have, according to them “chronically low national saving” and “raising saving is the key to addressing this vulnerability”, “in particular household saving”.    They don’t back any of this up, they don’t suggest reasons why private savings behaviour might be inappropriate, or identify policy distortions that are creating problems.  Instead, they jump straight in to solutions

comprehensive measures to encourage private long-term financial saving should be considered, including through reform of retirement income policies. Options include changing the parameters of the Kiwisaver scheme—e.g., default settings, access to funds, and taxation—to increase coverage and contributions while containing fiscal costs, and adjustment of parameters of the public pension system. This could help deepen New Zealand’s capital markets and broaden options for retirement planning.

“Broadening options for retirement planning” fits how with the Fund’s mandate, or expertise?  Did they recognise that New Zealand already has both a low elderly poverty rate and fiscal expenditure on public pension that, while rising quite rapidly, is not high by international standards?

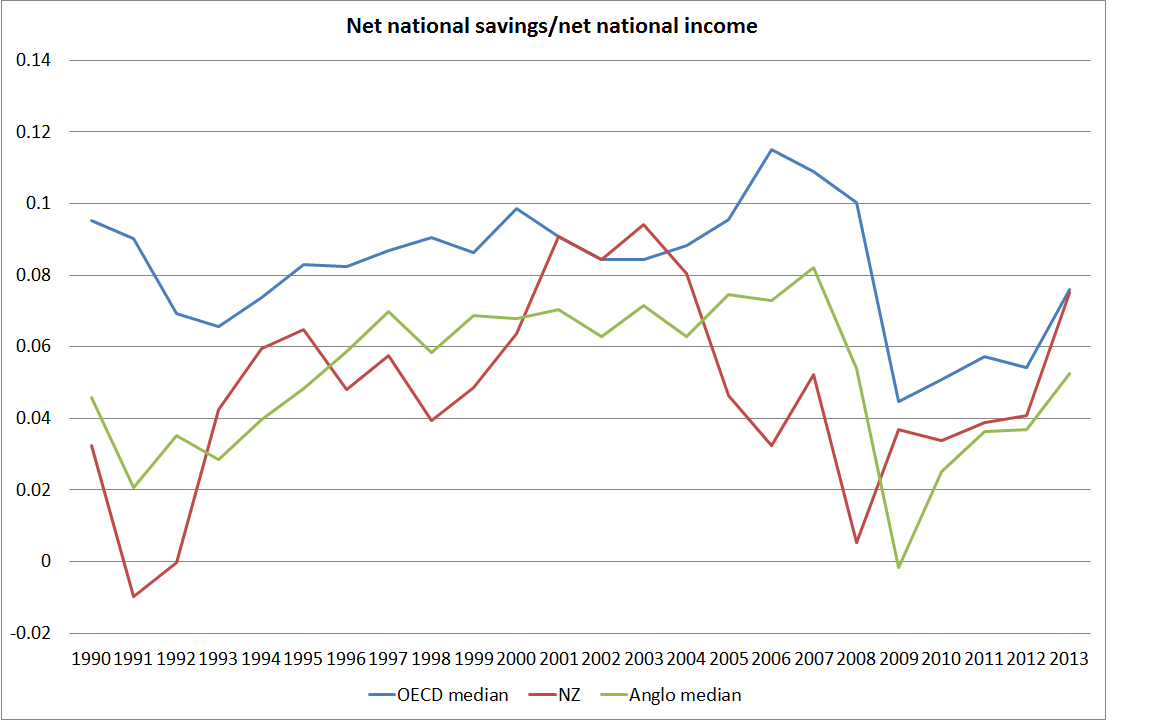
Did they, for that matter, even attempt to back up the claim that New Zealand has “chronically low national savings”.    If you are going to compare national savings rates, you really have to use national income as the denominator (ie savings of residents relative to the incomes of residents) .  In this chart, from the OECD database, I’ve compared New Zealand’s net national savings rate (as a percentage of net national income) to the median for the other Anglo countries (Australia, Canada, Ireland, US, and UK).

net savings

Both lines are below the median for the OECD grouping as a whole – although in the most recent year we were almost bang on the OECD median –  but over 25 years our net savings rate has simply fluctuated around the median of those countries most culturally similar to us.  Where is the “chronic” savings problem?    And given how strong our public accounts are –  better than those of any of the Anglo countries other than Australia –  how likely is that our feckless private sector is behaving as irresponsibly as the IMF mission staff suggest?   Perhaps Treasury has updated its view again, but I was involved in an exercise a couple of years ago in which Treasury made a pretty concerted effort to look for areas where policy might be driving down private savings rates (relative to those in other countries).  They looked hard, but it was a pretty unsuccessful quest.

And, finally, here is the IMF”s last paragraph

Despite the implementation of successful structural reforms in the 1980s, productivity levels have remained low compared to OECD peers. To raise productivity, the government’s business growth agenda has identified a number of policy priorities. Specifically, the Productivity Commission has highlighted the need to raise productivity in the services sector (which accounts for 70 percent of the economy). Measures include boosting competition in key sectors such as finance, real estate, retail, and business and other professional services; and leveraging ICT technology more intensively, including by enhancing skills.

I thought, and think, that most of the reforms of the late 1980s and early 1990s were in the right direction.  But a sceptic might reasonably ask what is the definition of “success” when productivity gaps have not just remained large, but widened further since then.  Perhaps more importantly, what is this paragraph doing here?  Long-term income convergence issues aren’t really in the IMF’s remit, and the IMF doesn’t seem to have anything useful to offer on the subject.  The paragraph is little more than an advertorial for the Business Growth Agenda –  itself so far signally unsuccessful in lifting exports or closing productivity gaps –  and the Productivity Commission.

We really should expect something better, and more authoritative and more focused, from the IMF.  Perhaps it will come with the full report in a couple of months time, but I’m not optimistic.

Flexicurity: the way ahead for New Zealand?

I finally caught up yesterday with Grant Robertson’s interview on The Nation.

There was the odd good aspect.  It sounds as though the variable Kiwisaver policy, as a tweaky tool to supplement to monetary policy, is heading for the dustbin, joining the capital gains tax proposal.  Other bits bothered me –  in particular, the lack of any sense in Robertson’s comments of the importance of markets, competition, relative prices etc.  He is clearly a believer in the power and beneficence of “smart active government”.

And I’m still a bit uneasy when I hear Robertson talk about changing the Reserve Bank Act to place a specific onus on the Reserve Bank to promote employment (or reduce unemployment).  It will be important to see details.  In principle, an amendment to section 8 of the Reserve Bank Act to say something along the lines of “achieve and maintain a stable level of prices, so that monetary policy can makes it maximum contribution to sustainable full employment and the economic and social welfare of the people of New Zealand” might do no harm.  It would, in fact, be not dissimilar to words that have been in the Policy Targets Agreement in the past.  On other hand, requiring the Bank to, say, actively target the lowest rate of unemployment consistent with maintaining price stability would be another matter.  Right at the moment it might be quite good advice to this Governor, who seems particularly uninterested in the plight of the (cyclically) unemployed.  But over time it would risk imparting a bias to the Reserve Bank’s choices that might well lead to persistently higher inflation outcomes over time.  That wouldn’t help anyone.

But the bit of the interview I was most interested in was the discussion around a possible different approach to help facilitate people moving from one job to another, as technology and opportunities evolve and change.  Robertson seems taken with the Danish “flexicurity” approach.  I didn’t know much about it, but in my younger days the idea of active labour market policies had had some appeal, so I thought I would take a quick look.  In some respects, Denmark’s experience is one to try to emulate:  prior to World War Two it was largely an agricultural economy, heavily reliant on agricultural exports to the United Kingdom, but poorer than us.  Now, while agriculture still plays an important part in the Danish economy ,other sectors have become much more important in the external trade and Denmark’s per capita income is far higher than New Zealand’s.

Here is how the Danish government describes “flexicurity”

A Golden Triangle Flexicurity is a compound of flexibility and security. The Danish model has a third element – active labour market policy – and together these elements comprise the golden triangle of flexicurity.

One side of the triangle is flexible rules for hiring and firing, which make it easy for the employers to dismiss employees during downturns and hire new staff when things improve. About 25% of Danish private sector workers change jobs each year.

The second side of the triangle is unemployment security in the form of a guarantee for a legally specified unemployment benefit at a relatively high level – up to 90% for the lowest paid workers.

The third side of the triangle is the active labour market policy. An effective system is in place to offer guidance, a job or education to all unemployed. Denmark spends approx. 1.5% of its GDP on active labour market policy.

Dual advantages The aim of flexicurity is to promote employment security over job security. The model has the dual advantages of ensuring employers a flexible labour force while employees enjoy the safety net of an unemployment benefit system and an active employment policy.

The Danish flexicurity model rests on a century-long tradition of social dialogue and negotiation among the social partners. The development of the labour market owes much to the Danish collective bargaining model, which has ensured extensive worker protection while taking changing production and market conditions into account. The organisation rate for workers in Denmark is approx. 75%.

The Danish model is supported by the social partners headed by the two main organisations – The Danish Confederation of Trade Unions (LO) and The Confederation of Danish Employers (DA). The organisations – in cooperation with the Ministry of Employment have also jointly contributed to the development of common principles of flexicurity in the EU, resulting in the presentation of the communication “Towards common principles of flexicurity” by the European Commission in mid-2007.

And here is a link to an accessible VoxEu piece from a few years ago on the flexicurity approach and Denmark’s experience after 2007.

The Danish “flexicurity” model has achieved outstanding labour-market performance. The model is best characterised by a triangle. It combines flexible hiring and firing with a generous social safety net and an extensive system of activation policies. The Danish model has resulted in low (long-term) unemployment rates and the high job flows have led to high perceived job security (Eurobarometer 2010).

….

The employment protection constitutes the first corner of the triangle. For firms in Denmark, it is relatively easy to shed employees. Not only notice periods and severance payments are limited, also procedural inconveniences are limited. The employment protection legislation index of the OECD for regular contracts is only 1.5. The Netherlands and Germany, countries with employment protection legislation, have an index of 2.7 and 2.9 respectively.

And here I started getting a bit puzzled.  Denmark certainly makes it a lot easier than many European countries to shed employees.  But it is even easier in New Zealand.  On all 4 components of the OECD’s indicators of employment protection legislation, New Zealand ranks as less restrictive than Denmark –  quite materially so by the look of it.

The OECD indicators on Employment Protection Legislation
Scale from 0 (least restrictions) to 6 (most restrictions), last year available
  Protection of permanent workers against individual and collective dismissals Protection of permanent workers against (individual) dismissal Specific requirements for collective dismissal Regulation on temporary forms of employment
OECD countries
Australia 1.94 1.57 2.88 1.04
Austria 2.44 2.12 3.25 2.17
Belgium 2.99 2.14 5.13 2.42
Canada 1.51 0.92 2.97 0.21
Chile 1.80 2.53 0.00 2.42
Czech Republic 2.66 2.87 2.13 2.13
Denmark 2.32 2.10 2.88 1.79
Estonia 2.07 1.74 2.88 3.04
Finland 2.17 2.38 1.63 1.88
France 2.82 2.60 3.38 3.75
Germany 2.84 2.53 3.63 1.75
Greece 2.41 2.07 3.25 2.92
Hungary 2.07 1.45 3.63 2.00
Iceland 2.46 2.04 3.50 1.29
Ireland 2.07 1.50 3.50 1.21
Israel 2.22 2.35 1.88 1.58
Italy 2.89 2.55 3.75 2.71
Japan 2.09 1.62 3.25 1.25
Korea 2.17 2.29 1.88 2.54
Luxembourg 2.74 2.28 3.88 3.83
Mexico 2.62 1.91 4.38 2.29
Netherlands 2.94 2.84 3.19 1.17
New Zealand 1.01 1.41 0.00 0.92

And then I wondered about just how the unemployment rates of the two countries had compared.

denmark U

At least for the last 15 years, our unemployment rate has hardly ever been higher than Denmark’s.

And what of the share of the population in employment.  There the difference in recent years is quite startling, and all in favour of New Zealand.  The sustained fall since 2007 in the Danish share of the population that is employed is among the largest in the OECD, matched only by Greece, Ireland and Spain.

denmark E

Of course, the recent employment (and unemployment outcomes) aren’t just the result of employment protection legislation and active labour market policies.  Demand is an issue too, and by pegging to the euro Denmark gave up the ability to use monetary policy to support demand (and the euro area authorities have largely exhausted their capacity).  I guess the Danish unemployment rate isn’t too bad, but I wasn’t quite sure what the Danish labour market experience had to offer that should attract New Zealand.

I imagine that life on the unemployment benefit is a bit more pleasant in Denmark than in New Zealand, but it isn’t obvious that the Danish structure, as a package, is producing, over time, better outcomes than what we have here.  And their model is vastly more expensive, and more heavily regulated, consistent (of course) with Denmark’s position as the OECD country with the third largest share of government spending as a per cent of GDP (57 per cent).  New Zealand, by contrast, has total government spending of around 41 per cent of GDP

Perhaps more regulation and more spending was Robertson’s point.  I guess we have elections to debate such preferences, but it seems a stretch to believe it would be an approach that would make our labour market function better.  It isn’t obvious Denmark’s does.

A surprising clause in the TPP investment chapter

Article 9.6bis: Treatment in Case of Armed Conflict or Civil Strife
1. Notwithstanding Article 9.11.6(b) (Non-Conforming Measures), each Party shall accord to investors of another Party and to covered investments non-discriminatory treatment with respect to measures it adopts or maintains relating to losses suffered by investments in its territory owing to armed conflict or civil strife.

I was a bit surprised to find this one.  Presumably this refers to cases where the state is not bound to provide compensation, but does so discretionarily?  Why would countries sign up to a policy in which they have to treat the losses of citizens/residents the same as the losses of foreigners?  And why only for cases of “armed conflict or civil strife” –  but not, say, earthquakes, bank failures, or other vicissitudes of life?    London was badly bombed in the blitz in 1940.  Is this seriously suggesting that the British government, if it offered any compensation to any of the victims, had to treat, say, the owners of Swiss banks or factories the same as the owners of British banks or factories.  Why would they want to pre-commit to that, in respect of ex gratia measures?

There might be plenty of occasions when a country might want to treat these two groups of people equally, but why should it sign up to committing in advance to such equality of treatment?

Public policy should be made primarily in the interests of the citizens (and perhaps residents) of the country concerned.  In all manner of areas, we treat residents different from non-residents (eg access to public schools and the public health system, let alone voting).  In some cases, we even treat citizens differently from non-citizens: both might go prison for a crime, but the non-citizen can be deported too.  It isn’t always obvious where the lines should be drawn, but draw them we do.  And sometimes we revise them in light of specific circumstances.  But why pre-commit to treat any compensation for this particular class of losses equally between New Zealanders and others?

PS.  On the off chance that “non-discriminatory treatment” only refers to how different countries’ overseas investors are treated, it still seems an odd and inappropriate thing to pre-commit too.  In any “armed conflict”, some other countries will have been allies, other perhaps very friendly, and others neutral or perhaps mildly hostile.  Why would we pre-commit to treating investors from each of those countries equally, in offering discretionary compensation for any losses resulting from armed conflict (or civil strife)?

Temporary safeguards, crises, and TPP

I still have no idea whether the TPP agreement our government has reached is, on balance, a net benefit to New Zealanders.  Without a proper independent assessment and analysis, undertaken by an agency that is both competent and independent (in the New Zealand case, think of the Productivity Commission), it is going to be difficult to know.   Imposing more regulation, across a range of quite diverse countries, doesn’t have the same presumption of economic benefit that lower tariffs do.  And the addition of yet more international meetings of officials and politicians seems like pure loss.

I’ve printed off, but not yet read, the modelling exercise done for MFAT –  the government’s negotiators –  that suggests annual benefits of as much as 1 per cent of GDP, at least for the subset of provisions they looked at.  And on Saturday, a form email from Tim Groser dropped into my inbox, urging me to sign a National Party petition to show my support for New Zealand’s exporters back TPP as “vital” to our economic future.  Frankly, it seems a little desperate when the Minister of Trade is having to generate his own petitions.

Some of the things I’m most uneasy about are matters of principle.  I think it is simply wrong that foreign investors should have access to different courts than New Zealand firms and individuals do in respect of issues relating to their activities in New Zealand.  Equal and common access to justice should be a foundational principle of our longstanding democracy –  no doubt things might be different in the brutal and corrupt communist regime that is our new treaty partner Vietnam .  This isn’t an argument about how many claims there will ever be against New Zealand (probably few),  but simply about differential access to justice. Our Courts should be open to all who seek justice in New Zealand (and open more generally), and there should be no special jurisdictions for favoured parties.   And New Zealand law should be made by the New Zealand Parliament, with any interested parties (domestic or foreign) free to make their cases in the public debate here.

Out of interest, I have dipped into a few of the chapters of the TPP is the days since the text was released.  I wanted to focus this morning on bits of Chapter 29, Exceptions and General Provisions, and especially Article 29.3 Temporary Safeguard Measures.  I had some peripheral involvement in New Zealand’s stance on these provisions, but here I just wanted to comment on what has finally been agreed.

The Article is only a couple of pages long, and the key points are here:

  1. Nothing in this Agreement shall be construed to prevent a Party from adopting or maintaining restrictive measures with regard to payments or transfers for current account transactions in the event of serious balance of payments and external financial difficulties or threats thereof.
  2. Nothing in this Agreement shall be construed to prevent a Party from adopting or maintaining restrictive measures with regard to payments or transfers relating to the movements of capital:

(a) in the event of serious balance of payments and external financial difficulties or threats thereof; or

(b) if, in exceptional circumstances, payments or transfers relating to capital movements cause or threaten to cause serious difficulties for macroeconomic management.

Since 1982 New Zealand has not had current account restrictions in place, and since the end of 1984 we have not had capital controls in place.  I hope we never adopt such controls again.  But it is the sort of decision that an elected government should be free to take.

New Zealand, for example, adopted current account convertibility controls briefly during the Great Depression, and then had both capital and current account controls in place from the foreign exchange crisis of 1938 until the early 1980s.  There were legal limits in place on what you could import, how much you spend on an overseas holiday, and official permission was required for, for example, overseas magazine subscriptions.  And that was before starting on the capital restrictions, on New Zealanders having money abroad, and on foreigners have money here.  It isn’t a world I ever want to go back to.

But capital and current account controls have not gone from the face of the earth.  In recent years, one OECD country (Iceland) and one EU country (Cyprus) have put new controls in place, and in the previous 15 years Malaysia and Argentina had also deployed such controls.

It is probably inconceivable to the US –  a very large country, and home of a “reserve currency” –  that such restrictions could ever be warranted outside wartime (unlike, no doubt, numerous other direct controls like FATCA or AML/CFT ones), but for small and highly-indebted countries it is another matter.  If New Zealand were to face a severe outbreak of foot and mouth disease, at a time when financial stresses were heightened anyway, controls might be an option a New Zealand government would want to consider.   Same might go for a severe flu pandemic, of the sort that so much planning was done for last decade, which closed down for a time world financial markets.  There would be costs and benefits to adopting controls, but it should be a choice for New Zealand governments to make.  It is about keeping a full arsenal of risk management options.

So I’m pleased to see that both 1 and 2 made it into the final agreement.  After all, any controls need to be consistent with the Articles of the International Monetary Fund –  which we’ve belonged to since 1961.  The IMF articles don’t put any particular restrictions on capital controls, but require approval from the Fund for any current account restrictions.  That approval is supposed to be provided in advance, but Iceland secured approval retrospectively in 2008, so these aren’t just abstract issues.

But the TPP articles goes further, and in some respects where they go are quite concerning.

Here are the main conditions controls have to meet

(c) avoid unnecessary damage to the commercial, economic and financial interests of any other Party;

(d) not exceed those necessary to deal with the circumstances described in paragraph 1 or 2;

(e) be temporary and be phased out progressively as the situations specified in paragraph 1 or 2 improve, and shall not exceed 18 months in duration; however, in exceptional circumstances, a Party may extend such measure for additional periods of one year, by notifying the other Parties in writing within 30 days of the extension, unless after consultations more than one half of the Parties advise, in writing, within 30 days of receiving the notification that they do not agree that the extended measure is designed and applied to satisfy subparagraphs (c), (d) and (h), in which case the Party imposing the measure shall remove the measure, or otherwise modify the measure to bring it into conformity with subparagraphs (c), (d) and (h), taking into account the views of the other Parties, within 90 days of receiving notification that more than one half of the Parties do not agree;

(f) not be inconsistent with Article 9.7 (Expropriation and Compensation);

(g) in the case of restrictions on capital outflows, not interfere with investors’ ability to earn a market rate of return in the territory of the restricting Party on any restricted assets; and

(h) not be used to avoid necessary macroeconomic adjustment.

4. Measures referred to in paragraphs 1 and 2 shall not apply to payments or transfers relating to foreign direct investment.

5.  A Party shall endeavour to provide that any measures adopted or maintained under paragraph 1 or 2 be price-based, and if such measures are not price-based, the Party shall explain the rationale for using quantitative restrictions when it notifies the other Parties of the measure.

In principle, (c) looks fine –  “unnecessary” damage should be avoided in the same way our Reserve Bank should avoid “unnecessary” exchange rate variability.  But what is unnecessary and who defines it?   And (d) too –  responses should be proportional to the seriousness of the situation, rather than using a minor crises as a pretext of abandoning openness.  I never really looked into (f) when I was involved in official discussions and I’m not starting now.

But here is where I start getting more uneasy.  On my reading of (e), under no circumstances can capital or current account controls be in place for more than 2.5 years.  New Zealand previously had them in place for 45 years, but more relevantly Iceland only this year announced plans to remove controls put in place, in response to a severe crisis, in 2008.    This provision goes well beyond anything in, for example, the multilateral framework of the IMF Articles of Agreement, and even provides a veto power to (a majority of) the other countries on even having controls in place beyond 18 months.

It might seem unlikely that the veto would ever be exercised (such is international politics that rather than upset a partner one could just let the last 12 months of controls run out)…..but, unlike the IMF, disputes under this Agreement can (presumably)  be dealt with through the ISDS process.  So rather than mere political lobbying about whether extending controls is a good idea, interested private foreign parties could seek remedial action.  Could they, for example, take a claim against another foreign government for failing to be stringent enough in evaluating whether any extension of New Zealand’s controls was really warranted within the terms of the agreement?

Which brings us to (h) above  Not avoiding “necessary” macroeconomic adjustment might sound uncontroversial, but…..any such controls substitute, almost by construction, for other forms of macroeconomic adjustment.  One could always let the exchange rate go lower (shifting more resources into exporting), or default (reducing the amount of resources that need to be shifted into exporting).  Is it really appropriate to have such judgements –  about the best mix of policy tools in a crisis – reviewed by courts –  let alone private foreign tribunals?

(g) has long puzzled me, (even though it sounds reasonable) because it has never been entirely clear what it means.

And if 5 has ended up in a reasonable place, it still seems to have a stronger preference for price-based measures (fees and taxes) rather than quantitative restrictions than may really be warranted.  I’m all in favour of price-based measures as a general principle, and think that many of the quantitative restrictions countries put in place are quite costly (think quotas rather than tariffs).  But the track record is that many of the authorities with a strong rhetorical commitment to price-based interventions actually themselves use quantitative restrictions  when under pressure.  I’ve frequently pointed out to people that during the 2008 crisis, short-sales prohibitions were common interventions in many countries (including the US).  Personally I thought they were wrongheaded, but smart people –  and, more germanely, people with a political mandate, disagreed.  I’m not sure I noticed price-based measures in FATCA, for example.   “Temporary safeguard measures” shouldn’t be used very often at all, but if they are used only in extremis it is quite likely that quantitative restrictions will be the most effective, and perhaps even efficient, remedy at times.  As a simple example, when the exchange rate is collapsing, or expected to collapse, almost no credible fee or tax will discourage someone who just wants his or her money out.

But my biggest single concern around the temporary safeguards provisions relates to 4.  This clause prohibits any current or capital account restrictions applying “to payments or transfers relating to foreign direct investment”.    I think that is a bad policy to pre-commit to for several reasons:

  •  There is no good reason to preference foreign direct investment over other flows, capital or current
  • The agreement contains no definition of foreign direct investment
  • This exception opens potentially large enforcement problems.

If anything, one could probably mount an argument for putting the restriction in the reverse.  After all, as the footnote to this article points out “FDI”, as envisaged here, tends to be undertaken to establish a “lasting relationship” –  unlike (say) as foreign investor buying a 90 day bank bill –  and this agreement allows controls for only 30 months at maximum.  If you establish a lasting relationship, isn’t it reasonable to share the opportunities and restrictions of the residents of the country?  In bank crisis resolution for example (eg the OBR), the focus is on quickly re-establishing the liquidity of transactions balance accounts, with much less immediate interest in the liquidity of longer-term claims.  Why reverse things here?   And why are countries agreeing to preference flows that relate to a foreigner’s investment in New Zealand over those of an identical asset (say, another sawmill) held by a New Zealander.  And note that the prohibition here is not just on the capital proceeds of the sale of an FDI asset, but on the earnings of that asset.  Under TPP, it appears that a country could put in place restrictions on a foreign owner remitting interest receipts (from, say, a government bond) abroad, but not on a foreign owner (of, say, a factory or a bank) remitting interest on a related party loan, or on remitting a dividend.  What is the ground for such a differential treatment?  I can’t see it.

The clause has a footnote

For the purposes of this Article, “foreign direct investment” means a type of investment by an investor of a Party in the territory of another Party, through which the investor exercises ownership or control over, or a significant degree of influence on the management of, an enterprise or other direct investment, and tends to be undertaken in order to establish a lasting relationship.  For example, ownership of at least 10 per cent of the voting power of an enterprise over a period of at least 12 months generally would be considered foreign direct investment.

But what, if any, legal force does that have? It is descriptive rather than prescriptive.  That might be fine for statistical classification purposes, at a time when there are no controls.  But it looks to provide no effective buffer against the numerous attempts that will come, if controls are ever put in place, against attempts to get round the law.  If, for example, a foreigner’s government bond matures and they invest the proceeds as 100% of the shares of “XYZ Asset Management Company”, the only asset of which is the proceeds of the bond, is that foreign direct investment (for the purposes of this agreement)?  If it is held in that form for at least 12 months?     People more skilled in financial engineering than I am could surely quite easily invent countless more clever ways of bringing their funds within this ill-defined ambit of “foreign direct investment”.

And all these matters appear to be resolved, when disputes are taken, not openly by domestic courts under domestic law,  or even through state to state dispute resolution mechanisms such as those under the WTO, but by offshore administrative tribunals litigated by individual aggrieved private companies.

For some people on the libertarian side of things, all these objections will be moot.  Who cares, they might argue.  Controls such as these are always and everywhere a bad idea, and anything that makes them harder to enforce is a good thing.  If we must have such provisions in international agreements to fend off the antediluvians, this is the second-best way of rendering them meaningless.

And I can see the logic of their argument. But it doesn’t appeal.  Strong and successful countries make their own laws, and set their own constraints.  Democracy and national sovereignty are probably never absolute principles, but I think New Zealand governments should have the option of imposing these sorts of controls, and trying to make them work, especially in crisis circumstances –  which one could readily envisage lasting longer than 30 months.  The longstanding multilateral framework, reflected in  the IMF Articles, agrees.  If New Zealanders really want to rule out the crisis controls options, that’s fine too.  But write and debate a constitution and establish these economic freedoms in such a national, domestically justiciable, document.

As it is, even our own Treasury and Reserve Bank signed up to a non-binding international declaration the other day which said that “we further recognize that excessive volatility in capital flows can create policy challenges that may require a policy response”.  Personally I’m sceptical, but they signed it.  Are they really saying that in no conceivable circumstances can those “serious difficulties for macroeconomic management” ever last for more than 30 months?  I’d be interested to see their analysis/evidence for that proposition.