Exporting: the failure of one small OECD country

The current government has a published target for increasing the share of exports in GDP.  I’ve argued previously that that was unwise, for a bunch of reasons, including the risk that it can encourage measures that might boost exports (to meet the target) but which don’t pass standard tests of good economic policies. I’d probably put enhanced film subsidies in that category –  the export incentives of the current generation.  But, equally, setting targets without any supporting economic strategy to deliver sensible results that meet the target has its own problems.

Despite all that, I suspect no one who cares about improving New Zealand’s medium to long-term economic performance is indifferent to the export performance of New Zealand firms, and the  New Zealand economy as a whole.  After all, the wider world is where most of the potential markets are –  especially for firms from smaller countries.  Perhaps there are examples, but I’m not aware of cases of countries that have markedly improved their economic performance on a sustainable long-term without a robust export sector (and tradables sector more generally) being part of that success.

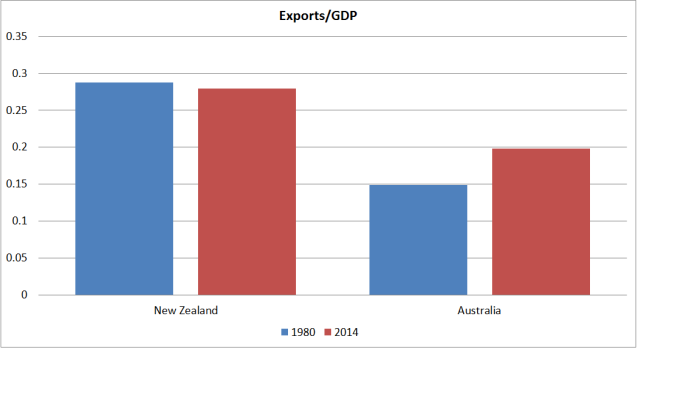
I showed a chart the other day with a snapshot comparison of export shares in Australia and New Zealand in 1980 and 2014.  New Zealand hadn’t done well.  But how have we done over the decades not just by comparison with Australia, but compared with the wider group of advanced countries?

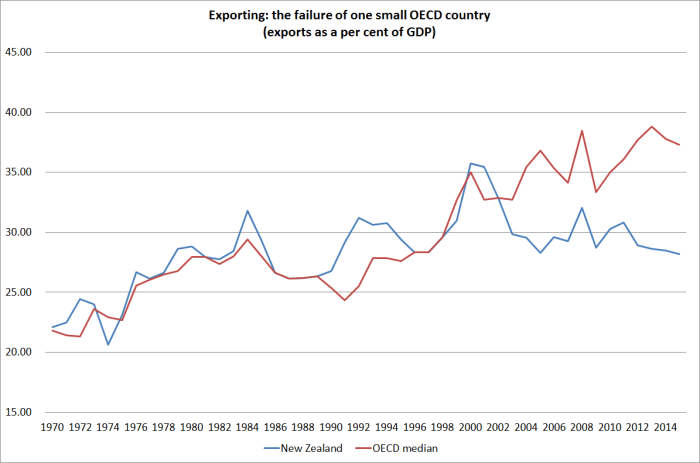
The OECD has data on exports as a share of GDP going back to 1970 for 27 countries, including New Zealand.  Here is the chart, comparing New Zealand with the median of those OECD countries.

exports as a share of GDP

For an individual country, in particular, there is quite some variability.  Thus, the combination of the sharp fall in our exchange rate in 2000 with high dairy prices temporarily boosted New Zealand’s exports to around 35 per cent of GDP.  But if one focuses on the trends, one could say that broadly speaking we had kept pace with the growth of exports in other OECD countries until around 2002/03.  But over the last 15 years, even though world trade growth slowed sharply late in the 2000s and has never really recovered, New Zealand has fallen well behind.

Only rarely is all the information in a single chart.   This isn’t one of those times.  Part of what has gone on, especially in Europe, is the growth of “global value chains”: whereas previously a car might have been designed and built entirely in Germany, and then exported, now often enough there is a lot of gross cross-border trade in the design and manufacturing phase, before the finished product is sold.  That inflates gross exports (and imports) and overstates the growth in economic value-added associated with exporting.  We don’t have up-to-date value-added data, nor a good long time series.  On the other hand, this didn’t suddenly start becoming an issue in 2003.

We also know that:

  • small countries tend to export and import larger shares of their GDP
  • far-away countries tend to export and import smaller shares of their GDP

Both these points need to be kept in mind. The first doesn’t have any very obvious implications: were Belgium to split in two, exports and imports as a share of the respective  GDPs of Flanders and Wallonia would rise even if no transactions were done differently after the split than before it.    But the distance point does have implications.  For whatever reason, distance is an obstacle to foreign trade, even that in services (it is probably not typically the dollar transport costs, but something about time taken to ship goods, and the physical proximity of people –  customers, potential staff, even competitors), and makes it harder –  all else equal –  for distant places to prosper.  Not surprisingly then, one doesn’t find too many people in very distant places.

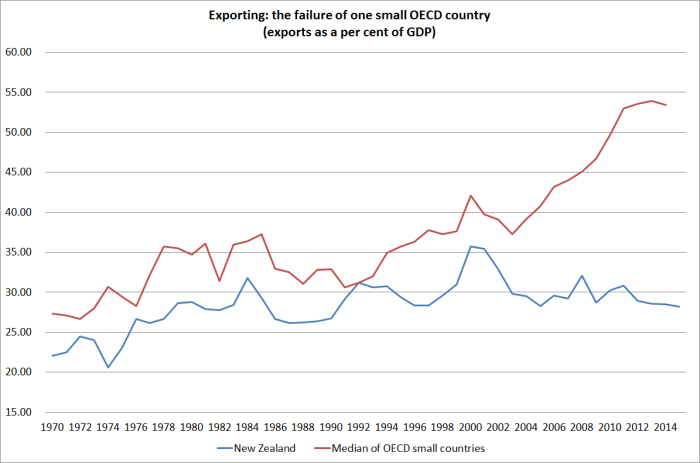
But reverting to size, here is how the chart above looks if we focus only on the small countries the OECD has data for.  In 1970 only two OECD countries –  Iceland and Luxembourg –  had smaller populations than New Zealand.  We had just under 3 million people, and at the time Norway, Ireland, Denmark, Finland and Israel had fewer than 5 million people.

exports small countries

The recent divergence is, if anything, even more stark.  Our export share of GDP in 1970 was already low by small advanced country standards –  and had shrunk, as one would expect, during the years of heavy protectionism.  But the gap has materially widened only in the last 15 years.  Some of that will be the (profitable) growth in Europe in cross-border trade as part of the production process. But it certainly isn’t the whole story.

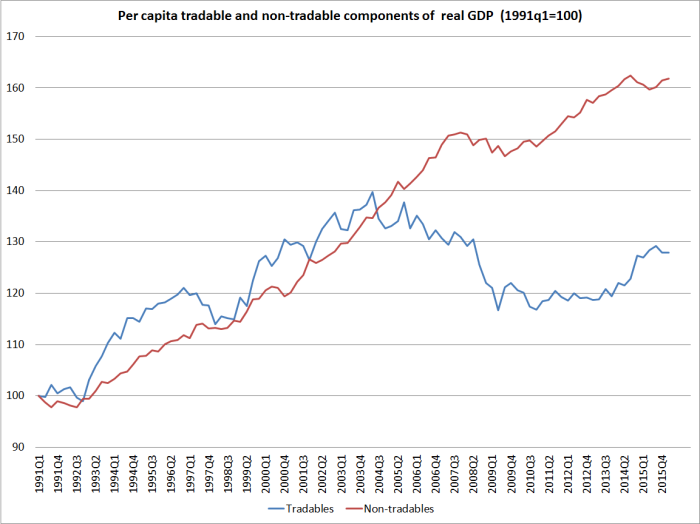
What makes me fairly confident of that claim?  Two things really.  The first is this chart (which I’ve run before), the indicative breakdown of New Zealand’s per capita GDP into tradables and non-tradables sectors.  Something here changed, quite materially, in the early 2000s.

pc gdp components

And the second is our exchange rate.  Here is the real TWI, using Reserve Bank data updated to capture the last few months.

real exch rate

Our real exchange rate has always been quite variable.  But if anything over the last decade or so there has been a bit less variability than in the preceding decades.  And probably more importantly, the average real exchange rate since the start of 2004 has been 20 per cent higher than the average over the previous 20 years (the period for which the Reserve Bank has the data).

That would be great if it had reflected a marked improvement in our relative productivity performance. But, of course, it hasn’t.  And perhaps unsurprisingly our tradables and export sectors have really struggled.

Of course, the real exchange rate isn’t simply a policy lever governments pull.  It is an outcome of other factors –  some policy, some market.  And quite what those factors were is a topic for other days.  For today, I simply encourage to reflect on how poorly New Zealand continues to do, and especially in building and expanding sales to the rest of the world, drawing on the high level of skills of our people, and the talents of our firms.


Immigration is “a good thing”, and that is all we need to know

I’ve been struck again over the last few days by the determination of our “elites” –  whether from the left-liberal end of the spectrum, or the (rather smaller) libertarian end – not to actually engage with the data on New Zealand’s experience of large scale immigration.

In their amusing tongue-in-cheek simplified retelling of English history, 1066 and all that, Sellars and Yeatman had most things classified as “a good thing” or “not a good thing”.

There seems to be a world view, straddling National, Labour and the Greens, and ACT as well, that in some sense “immigration is a ‘good thing'” and that is really all that needs to be said on the matter.  Much the same goes for the media.  The plebs just need to get with the programme –  perhaps having it explained to them again, slowly and clearly this time, that immigration is a “good thing”.   Any skepticism is too often deemed to reveal more about the character of the sceptic, than the merits of the economic case.

There is a respectable theoretical argument (at least within the narrow confines of economics) to be made for an open borders policy.  But the fact that no political party I’m aware of –  here or abroad –  actually argues for such a policy is probably quite telling.  Within the EU, there is a particularly respectable case for open borders –  the EU-enthusiasts see the countries of Europe as being on a transition to a political union.  Only brutal authoritarian countries –  think China – want to control migration of citizens within their own country.  But, as it happens, most Brits didn’t want to be part of an EU political union, preferring to govern themselves.  Polls suggest citizens in most other EU countries also don’t want such a union.

Even without political union, there can be a reasonable case for an easy flow of people across borders.  New Zealand and Australia are two different countries, and that doesn’t seem likely to change.  And yet there have never been direct immigration restrictions on people moving among the various colonies (pre 1901) or between the Commonwealth of Australia and New Zealand (since then).    In practical terms, the barriers to moving – especially from New Zealand to Australia –  have been getting higher in the last few decades, as Australian welfare provisions etc and citizenship have become progressively less readily available to New Zealanders.  On my reckoning, New Zealanders have gained considerably from this ability to move to Australia, especially as the large income and productivity gaps have opened up in the last 50 years.  Some New Zealanders relocated and took direct advantage of the higher incomes and better opportunities abroad.  The rest of us benefited –  at least in principle –  because the departures from this land of (apparently) diminished opportunities eased the pressure on living standards here.   Whether Australians have benefited from the easy flow of people across the Tasman is more arguable.  There are reasonable arguments (and, thus, models) for small gains, small losses, and not much difference at all.

Even within the context of a system of immigration controls, there can be a variety of motives for allowing immigration.  There is the humanitarian perspective that governs refugee policy.  We don’t take refugees because it is good for us, but because it is good for them –  people whose homelands have become impossibly difficult.  If the refugee intake ends up benefiting us economically that is a bonus, but it isn’t –  or shouldn’t be –  what drives us.   And, of course, we allow New Zealanders who marry abroad to bring their spouse home, and to become a New Zealander.  Again, there isn’t an economic motivation behind those provisions.    And some countries have real problems controlling their borders, and get stuck with people they never intended to allow in.

But we do control our borders and the bulk of New Zealand’s non-citizen immigration programme has an economic focus.  MBIE, and the government, have described the immigration programme as a “critical economic enabler” for New Zealand –  a phrase which sounds sillier, and emptier, each time I write it, but which is at least honest.  We take migrants   –  lots of them (three times the per capita inflow in the US) – on the hypothesis that doing so will help New Zealanders economically over the medium to long-term.  We certainly needed “critical economic enablers”, so poor has our economic performance been over the post World War Two decades.  And there are plausible hypotheses for how immigration can help, at least in the abstract.

But several decades on, surely the advocates, administrators, and cheer leaders of the programme should be able to point to economic gains for New Zealanders? It doesn’t seem an unreasonable request, given the economics-based case made for the programme.   The presence of a wider range of ethnic restaurants, or the success of the All Blacks, are all very interesting –  although, to be honest, I hadn’t seen too many new English restaurants (the UK is still the source of more new residents than any other country)  – but that isn’t the case that has been made.  New Zealanders are supposed to have been made better off economically by large scale immigration.  And if there is evidence of those gains, the champions of the programme are strangely reluctant to cite it.

And so we have Liam Dann in the Herald this morning

Australians have been panicking about immigrants and to some extent their loss has been our gain.

Migration-driven GDP growth through a period of commodity price downturn has been a timely break for our economy.

….

There are risks that high immigration disenfranchises those at the bottom of the social ladder.

We need to ensure we have social policy to protect people from losing out and turning their anger towards migrants. We need to remember the current surge is not driven just by the more highly visible arrivals of different culture and ethnicity.

It is being driven by New Zealand passport holders.

History tells us this wave will not last. And that when it passes it will have left this country richer and stronger.

It is a strange argument.  After all, had the economy of our largest trading partner been doing better, presumably that would have helped our economy not hurt it.  And if demand had been weak here –  as actually it has been –  we could have had lower interest rates and a lower exchange rate, the latter in particular would likely to have been helpful.

And then, apparently confusing the variability in the NZ citizen immigration with the baseline large inflow of non-citizen migrants, he worries about people at the bottom “losing out”.  But this appears to be only about perceptions because he knows that when the current immigration surge ends “it will have left this country richer and stronger”.    That is, certainly, the logic behind the immigration programme.  But where is the evidence?  There is no sign that the income or productivity gaps between New Zealand and Australia are closing.  They haven’t closed after the previous waves of immigration either.  It seems to be based on little more than a wish  – and that same underlying belief that somehow high immigration is a “good thing”.

The Prime Minister on Q&A yesterday was no better.   Corin Dann put to the Prime Minister the case recently made by leading businessman (and economist) Kerry McDonald that high rates of immigration to New Zealand are quite damaging.  The Prime Minister responded that he “didn’t think the evidence bears that out”.   But he offered no evidence at all.   He mentioned wage increases in New Zealand, but when the interviewer pointed out that there was still a very large gap to Australia, all the Prime Minister could offer was the defensive “well, we’ve trying to close that gap for a long time” (really?) and “most New Zealanders would say we are making some progress”.  If the numbers supported his case, presumably he’d have quoted them.  They just don’t.  As I illustrated on Saturday, the gaps to Australia have just continued to widen –  not by large amounts in any one years, but little by little.  There is still a net outflow of New Zealanders to Australia, and if it isn’t as large as it was that seems to be mostly because the Australian labour market is tougher than it was, rather than that New Zealand is doing well.  (Again, as I illustrated on Saturday, both New Zealand and Australia have relatively high unemployment rates at present, and the gap in our favour is no larger than it was on average over the last couple of decades).

The Prime Minister was challenged on political spin in the interview, and he acknowledged that both governments and oppositions do it.  It was certainly on display in the answers on immigration.  The Prime Minister likes strong immigration because it is a “vote of confidence in New Zealand”.  Which might sound good for the first five seconds, until one remembers that for New Zealanders not leaving it is mostly that Australia isn’t doing that well either right now, and for those coming from emerging countries, New Zealand is richer than, say, India, China or the Philippines.  None of that tells one anything about whether New Zealanders are gaining from the large scale programme.  Similarly, the PM fell back on the “house prices are a quality problem” type of argument –  suggesting that Auckland was no different than cities around the advanced world with population pressures.  Perhaps he could check out Atlanta and Houston some time.

In a serious interview, on a major issue, the Prime Minister was simply unable to offer any evidence –  or even good arguments –  for how New Zealanders were actually benefiting from the immigration programme that he continues to run (the same programme his predecessors ran).  It should be a clue that there just aren’t such benefits.  With all the resources of the state at his disposal, including state-funded research programmes for advocates of the current policy, and he can’t articulate the benefits for New Zealanders.  Something seems wrong.

This week’s Listener –  house journal for the left-liberal establishment – had a lot of advocacy material on (the perils and woes of) Brexit –  epitomized perhaps in the column of the Otago university professor who concluded

Enough is enough. The British Government must halt its plans to proceed with Brexit and organize a second legally binding referendum to determine Britain’s future relations with the EU.

Vote again –  and again –  until the people deliver the approved answer.

Political columnist Jane Clifton dealt with immigration issue.  She observed

But the bitterest Brexit realisation is the damage that ensues when governments fail to “sell” immigration.  That’s the most urgent lesson for our MPs to swat up, because anti-immigrant sentiment is seldom far from the surface here. A sizeable bloc of British voterdom simply does not believe that immigrants enrich their country and stoke economic growth and job opportunities. And who can blame them, since in many long-term depressed areas, there’s precious little evidence of it.

Here, immigrants are increasingly copping referred anxiety about Auckland’s growing pains. Rather than document and illustrate the benefits of migration, the Government simply refuses to engage on any other level than to call the anxious xenophobic or racist

I’m not sure that last phrase is correct.  So far, to the extent there has been a discussion, it has mostly been free of that sort of thing.  [UPDATE: That was before I saw these comments from the Minister of Immigration.]   But the more general point holds.  The government simply does not, and perhaps cannot, illustrate the benefits of the programme for New Zealanders as a whole.  The alternative approach seems to be instead to whistle to keep spirits up, and attempt to spin the problems into a story of some sort of success.  If there really is now a robust case to be made for current policy, it should be beneath our government to rely on such feeble assertions.   Clifton herself, of course, seems unable to recognise the possibility that there may not be such benefits to New Zealanders –  that it might just be an economic experiment that has failed.

These days, we have serious figures from the centre-right, such as Don Brash and Kerry McDonald, arguing that our immigration policy is flawed, and probably damaging to the fortunes of New Zealanders, but our media and political elites remain enthralled with an “immigration is a good thing” mentality, unwilling or unable to engage with the specifics of New Zealand’s circumstances, location, and general ongoing economic underperformance.

And it carries across to housing policy.  In the last week, there have been a couple of serious contributions to the debate as to “what should be done” about housing, from, Eric Crampton and Arthur Grimes (and here). I agree with a fair amount of Crampton’s piece, and disagree with a fair amount of Grimes’s –  which is notable for wanting to ride roughshod over the rights and interests or existing residents.  But where they unite –  from the left-liberal end of the spectrum and the libertarian end –  is in avoiding any serious discussion about the high baseline target rate of immigration.  Now, I’ve always argued that as a first best we should try to sort of our housing supply issues –  Atlanta and Houston have –  and ideally have a separate conversation about immigration (since my arguments about the damage immigration policy seems to be doing are not at all reliant on house price stories).  And if there were any evidence that rapid inward migration was in fact boosting the fortunes of New Zealanders as a whole that might be a particularly robust case.  But…..there is none, or certainly none that the advocates have advanced.  Instead, we know that Auckland’s GDP per capita has been falling relative to that in the rest of the country for 15 years (as far back as the data go) and the margin by which GDP per capita in Auckland exceeds that in the rest of the country is now very low by international standards.  And if there is no sign that rapid immigration-driven population growth is helping lift New Zealanders’ income, while the political difficulties of fixing housing supply remain large, the  case for cutting back the target inflow is strong.  Doing so would immediately ease house price pressures  –  and without riding roughshod over property rights through use of compulsory acquisition powers that the government and economists now seem to favour –  and at worst not harm our medium-term income prospects.

As a reminder, the OECD produced new data only last week suggesting that the skill levels of adults in New Zealand are among the very highest anywhere (and that, as in most advanced countries, the skill levels of the average immigrant are a bit lower than those of the native-born.  To the extent we’ve managed to grow our exports –  the foundation of long-term prosperity  –  it has mostly been in natural resource based industries (complemented by the heavily subsidized film industry and the subsidized export education industry) where numbers of people just don’t help much, if at all.  There is no compelling economic case –  and recall it is economics that supposedly drives our immigration policy –  for using policy to deliver lots more people to New Zealand.  The Prime Minister, the leader of the Opposition, the Greens leaders all seem to disagree, as do the media establishment, but none of them can offer a clear simple straightforward data-driven explanation for why.

I’m not sure if there is a risk of a serious social/political backlash of the sort senior lawyer and former ACT MP Stephen Franks talks of.  But I certainly hope there is an economic backlash before too long. The alternative is, most likely, that our long slow relative decline continues –  and any other decent policies we adopt, and the skills and capabilities that our people possess, are constantly battling up hill, in face of an ideology (no doubt mostly well-intentioned) convinced that “immigration is a ‘good thing’ for New Zealand”.  In economic terms it doesn’t seem to have been so for a long time.

In a Listener article a few weeks ago, my former colleague (and New Zealand historian) Matthew Wright was writing about the early pre-1769 history of New Zealand.  One line in particular caught my eye:

New Zealand was the last large habitable land mass on Earth reached by humanity. The long journey of our species from Africa’s Rift Valley into the wider world ended, it seems, on the Wairau Bar.

New Zealand has produced pretty good living standards, at such great distance, for a small number of people.  In the halcyon days  –  when our relative performance was at its best –  we had a quarter the population we now have.  New Zealanders saw something going wrong decades ago and started leaving in large numbers –  in outflows that, as a share of the population, are really large by past international standards –  and haven’t yet seen fit to reverse that judgements.  Distance isn’t dead, but our government’s immigration policy –  in thrall to the ideology –  seems to assume that wishing it so can make it so.  We need to be much more cautious, and evidence/experience driven, in continuing to pursue an economic case for an ever-larger population


NZ and the UK: strongest performers in their blocs?

An article in yesterday’s Herald caught my eye. In a double-page feature on Brexit, it was headed “Options beyond the EU” and featured some comments from the former New Zealand Minister of Finance, Ruth Richardson.  I was a bit puzzled by the article, which didn’t really seen like a New Zealand article, but wasn’t attributed to any foreign newspaper or wire service.  When I checked it out, it turned out that it was a backgrounder that had run as part of a series in the Telegraph three months ago looking “at four non-EU economies to see if they could provide a model for Britain’s post-Brexit future”.  One was New Zealand.   (The Telegraph had gone so far as to described Richardson as  a”great economic reformer”, although the Herald quietly deleted the “great”.)

Several passages interested me:

Ruth Richardson, a former New Zealand finance minister and a great economic reformer, believes there is a clear parallel between the two nations, and the choice that each will face. “When Britain decided to become very closely connected [with the EU], Britain was regarded as the sick man of Europe,” she says, with the UK “almost on the brink of the International Monetary Fund dictating policy” to it. Similarly, “when New Zealand decided to explore closer economic relations with Australia, we were clearly the sick man of Australasia”.

However, Richardson says, “nations ought not to be trapped by historical perspective”. She believes that the arguments behind a once sensible decision may have shifted. As in business, decisions over a country’s political future should be made on the basis of what will work best in the here and now, Richardson says.

Both the UK and New Zealand have risen to become the strongest performer in each of their respective blocs, and the reasons to pivot towards emerging markets have become clear.

And

A pair of radical politicians helped New Zealand through this difficult period. Richardson was the finance minister in a Right-of-centre National party government from 1990 to 1993, and her efforts, combined with those of her predecessor, the Labour party’s Roger Douglas, transformed the economy from one at the bottom of the pile to something far more dynamic.

Shaun Goldfinch, a New Zealand-based academic, says that the country moved from being “one of the most hidebound economies outside the former communist bloc, to among the most liberal in the OECD”.

I wasn’t entirely sure that I recognize the pictures being drawn here.

In both cases, it is a picture of economies transformed –  the UK and New Zealand having ‘risen to become the strongest performer in each of their respective blocs’ (the EU and the CER respectively).

The UK entered the (then) EEC on 1 January 1973.  The initial six members of the EEC had been France, (West) Germany, Italy, Belgium, Netherlands, and Luxembourg.  I’m going to ignore Luxembourg in subsequent comparisons, and focus on the five reasonably large initial EEC economies.

For the UK the path to the EEC was pretty slow.  The first de Gaulle veto had occurred in 1963, and the second in 1967.    Over the 1960s, annual UK inflation  was around 1 percentage point above the median of the five EEC countries.  In 1972, just prior to joining the EEC, that gap was 1.4 percentage points.   Things got a lot worse in the following few years, but even then there was only one year –  1975 –  when the UK had the highest inflation rate of these six economies. Italy was typically worse.

And in the 1960s, real GDP per hour worked in the UK is estimated –  using the Conference Board data – to  have been almost exactly equal to that of the median country of the EEC-5.  Britain’s unemployment rate had been slightly below the median of the unemployment rates of those other European economies.

Of course, Britain had its challenges –  economic, and the psychological/political hurdles of the end of empire –  but it was hardly a basket case.

And nor has it, very obviously, gravitated to top of class since then

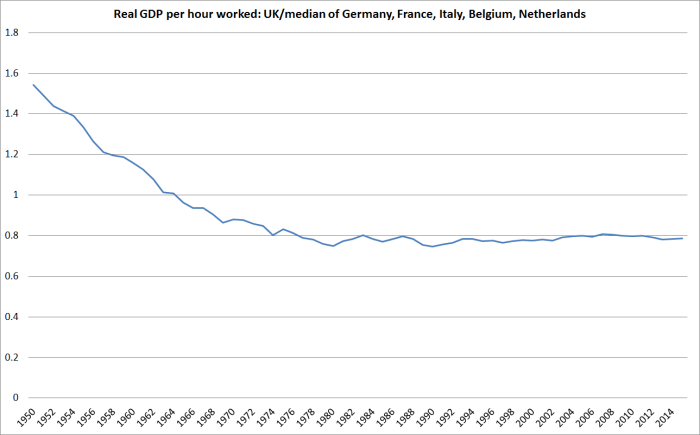
Here is real GDP per hour worked.

uk gdp phw

The decline in Britain’s GDP per hour worked, relative to those of the EEC-5, ended in around 1980.  And it has gone almost exactly sideways ever since.   Of these five European countries, Britain now only matches the real GDP per hour worked of Italy.  In the other four countries, labour productivity is around a quarter to a third higher than that in the UK.  Perhaps entering the EU staunched the decline, but there were probably a variety of other factors including financial liberalization (financial services being a huge chunk of British exports), the Thatcher reforms, and the end of the post-war catch-up phase.  But……Britain now has a lower level of labour productivity than all but one of these five European peers: it does no better than 80 per cent of the median of these other countries.  Not exactly a “top of class” performance.

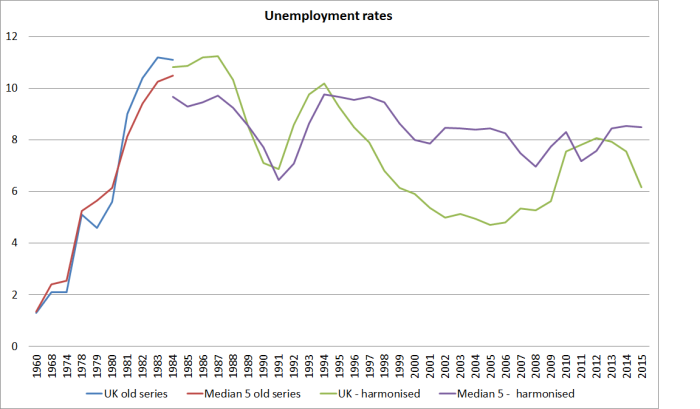
One area where they have done better is unemployment.  The following chart shows the UK unemployment rate and the median rate for the same five European countries.  It combines official current OECD data (on harmonized definitions) since 1983, and several years of earlier OECD data from their Historical Statistics: 1960-1988 publication.

uk unemployment rates

Over the last 20 years or so, the UK has clearly done materially better than these five European countries.  Each of the other five is in the euro, but that shouldn’t explain any difference given that these five countries include four of the larger euro-area economies.  But even among those other five countries, the Netherlands has typically had a lower unemployment rate than the UK’s –  although that isn’t so right now.

And what about the New Zealand/Australia comparisons.  Negotiations on the CER agreement began in 1979, and the agreement was signed in early 1983.  Given that there are only two countries in Australasia, I won’t dispute the description of New Zealand by then as the “sick man of Australasia”.  Our economy had been very severely hit by the post-1973 fall in the terms of trade.   The large outflow of New Zealanders to Australia really gathered pace in the 1970s.  Neither country was running macro policy –  or micro policy –  that well, but New Zealand was generally accepted to be lagging somewhat behind Australia.  We compounded the problems with the Think Big energy projects programme in the early 1980s, which temporarily boosted demand, but simply threw away some of the nation’s wealth.

But the story wasn’t totally bleak.  Our unemployment rate, while rising, had been consistently below that of Australia. And over the years when CER was being negotiated, New Zealand’s real GDP per hour worked was about 79 per cent of that of Australia –  alert readers might notice that that is about the same ratio as that between UK GDP per hour worked today and that of the EEC-5 (see chart above).

I’m not about to dispute that lots of worthwhile reforms were done here during the subsequent years.  And I think it is likely –  although hardly certain –  that CER was helpful to both countries (although trade diversion effects were probably material in some sectors).  And there are whole sectors of the economy where I think policy  in New Zealand could reasonably be judged better, at least in terms of encouraging resource utilization, than that of Australia.  The labour market is one of them –  we don’t need elections called on the ostensible grounds of breaking the power of corrupt trade unions.  I know some readers disagree, but I think our approach to retirement income policy is superior to Australia’s.  And I often like to mention that taxi industry, where deregulation has given us a much better outcome than Australia has.

But has it made us the strongest performer in our little two country bloc?  Not really.

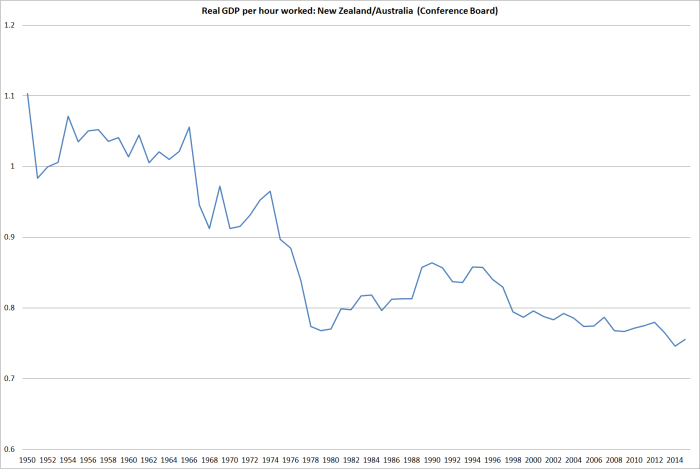
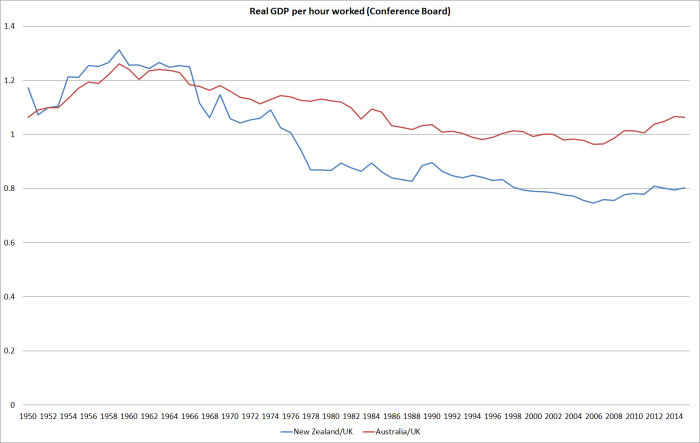
Take the real GDP per hour worked comparison, again from the Conference Board.

nz au real gdp phw

The late 1970s were a very bad period, as reflected in these data.  But on this measure things improved a bit of the 1980s –  partly no doubt the unsustainable boom that bust after 1987 –  before tailing off again.  Today, New Zealand’s GDP per hour worked is a little worse, relative to Australia’s, than it was when the CER negotiations got underway.  Perhaps the exam paper was upside down when that “best in class” grade was being awarded?  Of course, both countries are richer, and more open, than they were back then, but Australia has kept on doing a bit better than us.

And a significant part of the liberalization and reform process in both countries was the opening to external trade (not just bilaterally).  Here is the data for exports as a share of GDP.

exports nz and ausNew Zealand’s export share of GDP hasn’t changed in 35 years.

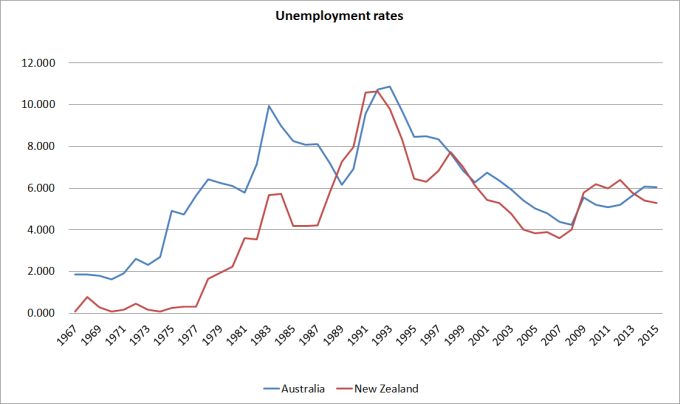
Of course, there are some area in which we do better –  and we have the distinct attractions (to New Zealanders at least) of no snakes or crocodiles.  As I noted earlier, the labour market tends to be one such area.  Here are the unemployment rates for the two countries back to the 1960s (prior to 1986 the New Zealand data are estimates, but good enough to be used by the OECD).  I have taken account of the revised data Statistics New Zealand published earlier this week.

u rates back to 60s

Our unemployment rate has been below that of Australia most years since 1967.  Only on two occasions was our unemployment rate higher – the first episode was in the wake of the post-1976 share and commercial property crash, and the second was in the couple of years after 2009 when Australian commodity prices –  and the associated business investment boom – were at their peak.  We should, of course, welcome the fact that our labour market typically generates less unemployment than Australia’s does, but it is worth mentioning that the gap in our favour is smaller than it was pre-liberalization.

No doubt our economy is rather more “dynamic” than it was –  although it is fair to wonder quite what that words mean specifically –  but it isn’t obviously much more successful., not even relative to Australia.  Compared with the late 70s, both countries now have low and stable inflation –  but their inflation rate is nearer target than ours.  Both countries have low levels of public debt, but in flow terms at present our government accounts are roughly balanced while theirs are still in deficit.    We have a slightly larger reliance on foreign capital (larger net IIP position as a share of GDP) than Australia does, but perhaps they have a slightly more compelling story about the new business investment (tradables sector) that capital has financed.  Both countries have seriously dysfunctional housing markets – it is hard to tell which of two bad performers is worse.  Oh, and New Zealanders are still (net) moving to Australia, not coming home again.

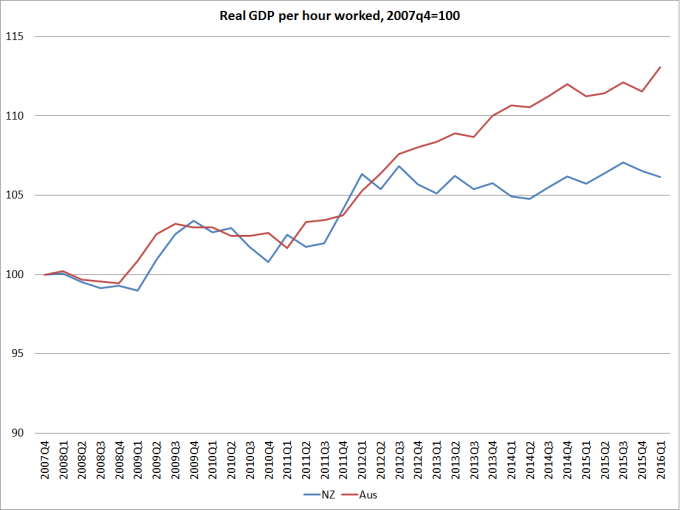
It is election day in Australia.  I was amused when Malcolm Turnbull became Prime Minister and talked about wanting to emulate New Zealand’s approach to economic reform.  In the intervening period, there hasn’t been much sign of reform in Australia –  any more than there had been in New Zealand –  but for all Australia’s challenges, it has still managed more productivity growth in recent years than New Zealand has.

real gdp phw nz and aus

As I noted earlier, the United Kingdom has hardly been a top-of-class performer in Europe in recent decades.  The sobering thing is that over the last few decades, Australia –  with all its newly developed mineral wealth –  has managed to do no better on the productivity front than just about keep pace with the UK.  New Zealand, of course, couldn’t even manage that.

real gdp phw nz aus uk

If Britain is searching for lessons and models in a post-referendum world, New Zealand might offer a model of good intentions.  As for outcomes, not so much.


.

What the Board might (but surely won’t) say

Yesterday was the end of the year for the Reserve Bank, and attention will be turning to the annual accounts and the Annual Report.  There are two relevant Annual Reports, required by law. The Bank itself is required to produce an Annual Report, but so is the Bank’s Board.

The Reserve Bank’s Board is quite different from a corporate board, or from boards of other statutory bodies.  The Board has no responsibility for running the institution – whether in a managerial sense, or setting strategic direction or policy.  The Board, in effect, selects the chief executive, but there the similarities largely end.  The Board isn’t charged to work with the Governor to collectively deliver the Reserve Bank’s goals.  Instead, it is explicitly charged with holding the Governor to account for his stewardship of the Bank.  In that role, their primary responsibility is to the Minister of Finance and to the public.   They are given privileged access to information, but are expected to be willing to stand at arms-length from management generally, and the Governor in particular.

Of course, structural flaws in the model make this hard to do effectively.  When a Board appoints someone as Governor, they naturally have a strong desire to see their choice validated, and hence a natural instinct to “back their man”.  The superficial similarities to corporate boards probably don’t help –  since many of the Reserve Bank Board members sit on other private or government boards.    I’ve also been critical of the Board for allowing itself, over the years to get too close to management – repeatedly making former staff chair of the Board for example –  and for seeing one of its role as helping sell the Bank’s messages.    But again, under-resourcing (the Board has none) tends to reinforce this dependent relationship

Last year, for the first time, the Minister of Finance sent a Letter of Expectation to Rod Carr, the chair of the Reserve Bank’s Board, setting out what he expected from the Board (I wrote about it here). In that letter, the Minister was quite explicit in drawing attention to the different nature of the responsibilities of this Board, and he outlined some clear expectations for what he thought the Board should report on.  He certainly wasn’t just interested in a list of meetings attended or papers received –  as past Board reports have often been.  He also explicitly noted that “greater visibility of the Board’s activities would also be welcome”.

So as the Reserve Bank’s Board begins to think about how it might shape and phrase this year’s Annual Report, bearing in mind the Minister’s written expectations, I thought I’d have a go at a version of the Board’s Annual Report that I think would be more consistent with (a) the data and evidence, and (b) the Board’s actual responsibilities.    Sadly, I will be surprised if any of these points are made, or even if the issues are treated in a substantive and balanced way, while reaching different conclusions.   But here goes:

Annual Report of the Board of the Reserve Bank of New Zealand
Year ended 30 June 2016

The Board of the Reserve Bank of New Zealand has quite different roles and responsibilities than boards of most other statutory bodies, let alone those of private sector companies.  Following receipt of the letter of expectation from the Minister of Finance in November 2015, we have taken the opportunity to reflect again on how best we can fulfil the role provided for us in the Act.  That role is primarily about holding the Governor to account for his stewardship of the Bank, on behalf of the Minister of Finance and the people of New Zealand.  Doing that well involves striking a difficult balance.  We are provided with privileged access to information, and the ability to engage with and question the Governor and his staff.  But we need to maintain a considerable distance from the management of the Bank, and ensure that we are exposed to, and consider, alternative perspectives on the Bank’s performance, in reaching our own assessments.   We are not here to be cheerleaders for the Bank, and regret that at times in the past we have allowed ourselves to become part of the Bank’s outreach efforts –  which compromises our subsequent ability to evaluate management, and to be seen to do so in an objective fashion.   And equally we need to bring a professional detachment to our evaluation, and not allow ourselves to be unduly influenced by the part we or our predecessors had in appointing any particular Governor.

We are also conscious that the Board has limited resources.  The role of Board member is a part-time position, remunerated on the basis that members will typically spend no more than perhaps two days a month on Bank matters.  Few of us are experts in the subject matter the Bank in responsible for, and we have no independent budgets or staff resources.  The Governor  –  whose performance we are charged with evaluating – controls the papers that come to the Board from the technical experts on staff.  Indeed, we are dependent on the Bank for even secretarial and administrative support.  We do not think that is an adequate model to enable the evaluation task to be done well, and we have written to the Minister of Finance suggesting that the Board be provided with a limited amount of independent resource (including the ability to commission external advice) to be better able to fulfil the role that he, and others, rightly expect of us.

The Reserve Bank has a wide range of tasks and statutory responsibilities.  That breadth of functions, and the extent of the powers delegated specifically to the Governor, is unusual –  both in New Zealand public agencies, and among central banks and financial regulatory bodies internationally.  We work within the framework Parliament has given us, but we are uneasy about how different the Reserve Bank framework now looks.  We would encourage the Minister to consider establishing a process to review whether the design of the institution and its governance model is the best possible model for New Zealand in coming decades.

The Reserve Bank has a substantial body of high quality staff.  We thank them for their dedicated input over the last 12 months.

As we reviewed the Bank’s performance over the last 12 months – and particular that of the Governor, who we are specifically charged with holding to account –  we have found a number of areas of concern.

The most obvious is the way in which inflation has undershot the midpoint of the target range –  the midpoint having been specifically identified as the focus as recently as the 2012 Policy Targets Agreement.    Many –  although not all –  advanced country central banks have been grappling with persistent surprising weakness in the inflation rates in their respective countries.  Of course, unlike many of those central banks, the Reserve Bank of New Zealand still had ample tools at its disposal –  the OCR has been consistently above 2 per cent, while in most advanced countries rates close to, or even below, zero have been more common.

We also recognize that many of the more prominent local commentators had similar, or even more optimistic, views on inflation, than the Reserve Bank did.  Perhaps there is comfort in a crowd, but unlike the other commentators, the Reserve Bank has been charged with delivering inflation at or near target.  It hasn’t done so over the last year, and unfortunately that followed several years of undershooting.  We disagree with the senior Bank manager who was recently quoted as suggesting that six years was too short a timeframe to evaluate monetary policy performance over.

It isn’t our place to second-guess specific monetary policy judgements made by the Governor.  But it is our duty to stand back and consider lessons from the patterns that start to emerge over time.  We are concerned that the Bank may have allowed itself to become too inward-looking, and too reluctant to foster or engage with alternative perspectives –  whether internally, or externally.  In an area in which there is so much uncertainty, this would be a serious weakness in the institution.  In most institutions, any such reluctance stems from signals –  deliberate or inadvertent –  sent from the top.  In this respect, we have been concerned that the Governor has not been willing to openly admit that mistakes were made in the setting of monetary policy in recent years.  To err is human.  To wish to deny error is also, perhaps, human, but unhelpfully so.  “He Knew Was the Right” is the title of one of Anthony Trollope’s novels. That character’s certainty did not end well.

We have already drawn attention to the well-known fact that most advanced countries now find themselves having exhausted their conventional monetary policy capacity.  If policy interest rates can still be cut at all, it is only by very small amounts by the standards of past cycles and shocks.  New Zealand is fortunate in that respect that the OCR is still some way clear of zero.  But that is no basis for complacency, and unfortunately we have seen little sign of the Reserve Bank taking steps to address the risks.  In typical past downturns the Reserve Bank has often had to cut interest rates by 500 basis points.  In a future downturn that can’t be done.  And yet there is no sign –  including in the latest Statement of Intent –  of any work programme to anticipate these risks and to, for example, seek to remove the near-zero lower bound on nominal interest rates.  With so much advance notice, New Zealand should not find itself unable to use monetary p0licy sufficiently in the next serious downturn.  As the Governor has rightly noted, risks abound globally.

We note, with some concern, issues that have been raised over the last year about the consistency of the Reserve Bank’s monetary policy communications.  We would expect management to take these concerns into account, but we recognise that inconsistent communication (or at least perceptions of it) has also been an issue facing some other central banks, including the Federal Reserve.  Our assessment thus far is that the communications problems are mostly a reflection of the underlying issues central banks have had with correctly reading and interpreting inflation, and inflation risks.  In the Reserve Bank’s context, they have probably been amplified by the lack of clarity around the role of house prices in the way the Bank has been conducting monetary policy.

The Reserve Bank’s second main area of policy responsibility is the regulation and supervision of various institutions in the financial sector, under a mandate of promoting the efficiency and soundness of the financial system.

As the Bank has noted in its own reports, New Zealand’s financial system is sound.  Demanding stress tests suggest that there is no credible threat to the soundness of the system, based on the lending patterns and standards observed in recent years.  Those patterns can change, and quite quickly, and the Bank needs to be closely monitoring developments, especially in the banking sector.

In recent years, however, the Governor has articulated concerns that house price developments, especially in Auckland could –  if left unchecked –  develop in ways that could pose a systemic threat. In turn, the Bank has used several unprecedented regulatory interventions –  unprecedented in New Zealand, even in the decades of direct controls – to attempt to influence access to housing finance.  In recent months, the Bank has signaled the possibility of yet more controls, when only three years ago it was explicitly talking of the first wave of controls as “temporary” in nature.

In his letter of expectation, the Minister indicated that he expected us to explicitly address both the soundness and the efficiency dimensions of the Bank’s responsibilities.  We are concerned that the Bank has not been giving sufficient attention to the way in which direct controls impede and impair the efficiency of the financial system. Recent FSRs, for example, have given efficiency little or no attention.

In a wider sense, we are uneasy that the Bank has been adopting successive waves of controls with too little robust analysis or research underpinning them.  Here we have in mind two particular types of research. First, the Bank has published nothing in recent years looking carefully at the experiences of the countries which did, and did not, experience financial crises or systemic stresses following the last credit boom prior to 2007.  And there has been nothing looking carefully at New Zealand’s own experience during that period –  a a huge, widely spread, credit and asset boom, and no serious or systemic stresses followed.  For an institution provided with a substantial amount of research resource, we don’t think that is a satisfactory state of affairs.  And second, we have seen no research from the Bank reviewing literature on government failure, or examining the various regulatory failures and knowledge gaps that plague well-intentioned efforts to use regulatory restrictions in all sorts of sectors.

Again, we do not see it as our role to reach different conclusions than the Governor on specific interventions.  But we are concerned at signs that the institution is insufficiently skeptical and self-critical.  That is often a recipe that leads over-confident regulators into sub-optimal policy responses.  We think the Bank, and those monitoring it, would also benefit from some more structured published research around its wider financial regulatory activities.

Relatedly, we would urge the Bank and the Governor to recognize that, under their current mandate, house prices are not something the Bank is responsible further.  That is quite clear in respect of monetary policy –  the Policy Targets Agreement charges the Bank with focusing on the CPI, and the Bank has long been of the view that house prices should not be in the CPI.  But it is also true of the financial stability responsibilities.  The current level of house prices appears to be a serious national issue, but it isn’t one of the Reserve Bank’s responsibilities.  We have not been presented with evidence over the last year, and nor has such research been made public, that direct interventions in the housing finance market are a better response –  better balancing soundness and efficiency concerns, and the knowledge problems facing all regulators –  than, say, requiring larger buffers through higher capital requirements and more demanding leverage ratios.

The Board’s responsibilities do not simply involve the Bank’s prime policy roles, but also involve monitoring the handling of administrative and management matters. Two in particular have come to light during 2015/16.

The first was the OCR leak that occurred at the March 2016 Monetary Policy Statement.  The  inquiry into this, established expeditiously by the Governor, highlighted not just that there had been a deliberate leak, but that the Bank’s system were sufficient weak (reliant on trust) that it was almost inevitable that at some point a leak, deliberate or accidental, would occur.   We endorsed the decision to discontinue lock-ups –  a practice adopted in few other central banks now –  and believe that the penalty imposed on the culprit (MediaWorks) was appropriate, if belated.  We are concerned, however, by evidence that the Bank’s senior management, and our own Chair, allowed apparent personal animus to colour their reaction to the events, and how they were brought to light.  We appreciate the actions of the person who alerted the Bank to the possibility of a leak.

The second relates to the Reserve Bank staff superannuation fund.  The Board is required to approve rule changes to this scheme, and appoints two of the five trustees (the Governor is a third). We have been seriously disconcerted to learn about substantive errors and at least one breach of the law that occurred around rule changes undertaken some time ago.  The trustees have already had to apologise to members for one breach of the law, and we are now aware that one major rule change –  which benefited the Bank financially, potentially at the expense of members –  was done illegally.  That would be concerning enough in itself, but we have now learned that this information was known to trustees (including senior Bank management) 25 years ago and it was neither acted on nor were members informed.  In fact, members were asked to consent to other subsequent rule changes – which did materially benefit the Bank financially – where knowledge of that past error would have been material information for some members in deciding whether to consent.  Other important rule changes appear to have been made without member consent; changes which could have materially disadvantaged members.  These are not standards of management or governance which we find acceptable, especially in a scheme dealing with the life savings of many of our former (and current) staff.  We apologise for the mistakes of our own predecessors in this area, and we have urged the Governor, and the other trustees whom we appoint, to act expeditiously to remedy past wrongs.

All New Zealand institutions are small by international standards, but the concentration of expertise on matters macroeconomic and financial (unparalleled anywhere else in New Zealand) and the Bank’s typically high standards in recruiting staff should enable the Bank to be at the forefront of engagement on the relevant policy and analytical issues, shaping the debate by the quality of the research and analysis, and unafraid to engage, including openly, with alternative perspectives.  Unfortunately, that has often not been the case in recent years.  We don’t think that is because the quality of the staff has deteriorated.  We note concerns that have been expressed in some quarters about the Governor’s apparent reluctance to participate in serious searching interviews.  Given the extensive powers the Governor wields, we think this choice has been unwise, and would encourage the Governor to adopt a more open approach.  Similarly, the Bank’s reputation for being highly obstructive in handling Official Information Act requests seems neither good policy consistent with the law, nor consistent with the approach to forward-looking transparency in monetary policy that the Bank has done so much to foster over the years.  Transparency can’t just involve telling people what the powerful want them to know.

In recognition of some of the weaknesses in how the Board has fulfilled its role in recent years, we have decided that it is time for a change of Chair. The Board will shortly elect a new Chair. In future we will aim to ensure that the role is not held by former Reserve Bank staff.

The Reserve Bank is a powerful and important organization in New Zealand.  But it has fallen short of what the public should expect from it in a number of major areas.  The Governor recognises this and has committed to work to lift performance over the remainder of his term.  We appreciate that.  As we move towards the appointment of a new Governor next year, we are committed to identifying candidates who would continue to lift the performance of the institution, producing the right blend of sound judgement, analytical excellence, operational efficiency, and a commitment to transparency and accountability and two-way engagement, of the sort the country deserves.

Rod Carr, Chair

Keith Taylor, Deputy Chair


As I say, I don’t expect to see even a substantive discussion of these issues in the Board’s actual report.  But time will tell.

In the meantime, while I’ve been writing this post and in and out this morning, responses from the Board and the Bank to several longstanding OIA requests about the OCR leak have turned up, on the very last day of the long extension the Bank gave itself.  I haven’t yet looked at the contents (now available here), but the lengthy delays just reinforce the point about the Bank’s lack of any serious commitment to institutional transparency.
 

Skills matter….and we already seem to have them

Earlier this week the OECD released Skills Matter, a 160 page report on the results of a programme of surveys of adult skills in OECD (and a handful of other) countries.  As usual with OECD reports, it is full of fascinating charts.  Here is how they describe the programme:

In the wake of the technological revolution that began in the last decades of the 20th century, labour market demand for information-processing and other high-level cognitive and interpersonal skills is growing substantially. The Survey of Adult Skills, a product of the OECD Programme for the International Assessment of Adult Competencies (PIAAC), was designed to provide insights into the availability of some of these key skills in society and how they are used at work and at home. The first survey of its kind, it directly measures proficiency in several information-processing skills – namely literacy, numeracy and problem solving in technology-rich environments.

It is worth emphasizing that the survey involves attempting to directly assess skill levels, not formal qualifications.

The first such survey was done a few years ago, but this is the first round to include all OECD countries and, in particular, the first to include New Zealand.   They even provide a 20 page country note on New Zealand.

The bottom line for New Zealand?  The news is good.

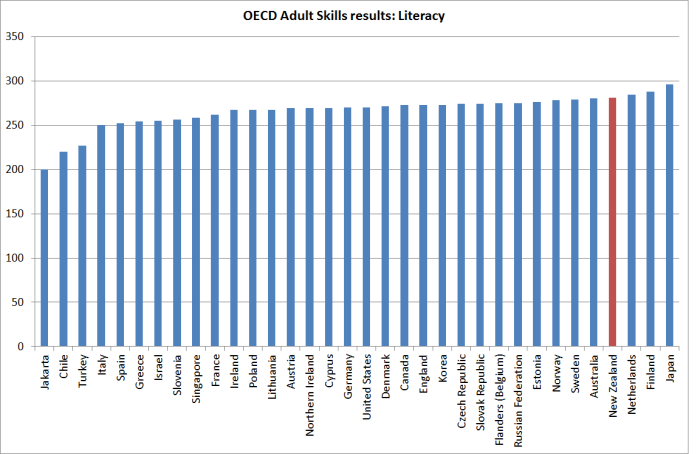
Here is how our adults scored on literacy.

oecd literacy 2

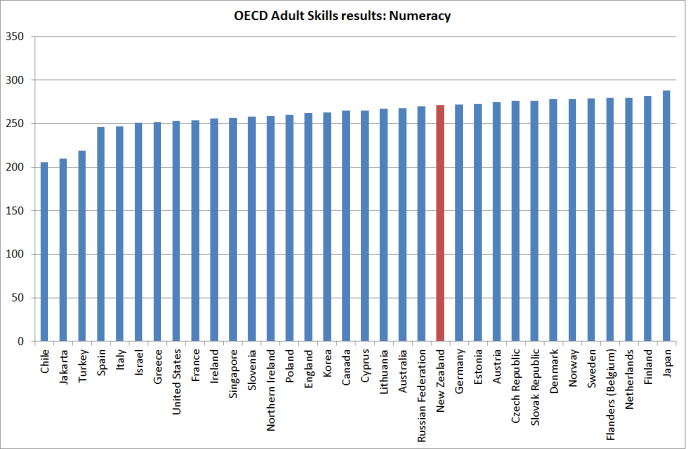
And numeracy

oecd numeracy

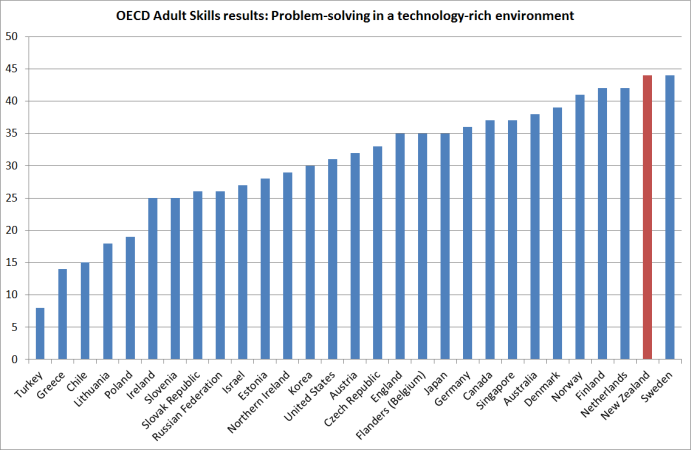
And on “Problem-solving in technology-rich environments”

oecd problem solving

Looking across the three measures, by my reckoning only Finland, Japan, and perhaps Sweden do better than New Zealand.    Perhaps there is something very wrong with the way the survey is done, and it is badly mis-measuring things, but those aren’t usually the OECD’s vices.  For the time being, I think we can take it as reasonably solid data.  And the broad sweep of the cross-country results makes some sort of rough sense: typically the poorer countries are to the left of the charts (relatively less highly-skilled).

But if the skill levels of our adults are so high, on average, by international standards (and, as it happens,  we have quite a high rate of tertiary qualifications as well), it should perhaps raise questions again about the size and nature of our immigration programme.

After all, as I noted, the poorer and lower productivity countries are generally to the left of these charts. But New Zealand is one of the less well-performing OECD countries on that score.  Here is real GDP per hour worked for OECD countries in 2014.

real gdp per hour worked 2014

And when the OECD lines up the skills scores against the productivity data one of the largest gaps (lagging productivity) is for New Zealand   The cross-country scatter plots don’t show a tight relationship by any means, but they do tend to suggest that the skills and talents of our people aren’t what holds New Zealand back.

And yet we aim to grant 45000 to 50000 new residence approvals each year (a scale three times the size of US and UK programmes, per capita), supposedly with a focus on skilled migrants.  What is the logic?  And where is the evidence that this is the right place to focus in tackling New Zealand’s long-term economic underperformance?  Reinforcing those doubts, we know that other data show the incremental returns to tertiary education –  a different thing from skills, but one hopes not wholly unrelated –  are also among the lowest in the OECD.

A reasonable person might instead look at the data and suspect that, for whatever reason, the economic opportunities in New Zealand just aren’t that good.  Perhaps that is about location and distance, and a seeming inability to break out of a dependence on (a fixed supply of) natural resources or to increase productivity in those natural resource sectors rapidly enough.  But whatever the underlying reason, the opportunities haven’t been found here –  our export share of GDP has been static for decades, per capita tradables sector production hasn’t changed for 15 years, and a huge number of New Zealanders have kept on leaving for better opportunities abroad (mostly in –  on these measures –  slightly less skilled Australia).

One might have severe doubts about the logic of using policy to actively pursue bringing in lots more people  –  it might be no more sensible here than it would be in Wales, or Scotland, or Nebraska, or Newfoundland, or Tasmania (who’ve been spared the depradations of Think Big bureaucrats and politicians with immigration as a lever).  Perhaps it would be a little less worrying if the new arrivals were typically very highly-skilled people –  but recall that the highly-skilled people we already have aren’t succeeding in generating high returns (high productivity) here now.

But in fact, our immigrants aren’t that highly-skilled at all.  At the frivolous end of the spectrum, we were giving a small number of Essential Skills work visas to shelf stackers and kitchen hands.  More seriously, among those gaining residence visas in the skilled migrant category, the top four occupations in the last year for which we have official data were

Occupation 2014/15
Number %
Chef 699 7.2%
Registered Nurse (Aged Care) 607 6.2%
Retail Manager (General) 462 4.7%
Cafe or Restaurant Manager 389 4.0%

But it isn’t just a matter of occupational lists.

As it happens, the OECD report looks directly at the skills level of immigrant populations.  There are a few countries where immigrant population skill level match those of native born populations.  Perhaps that isn’t too surprising where most migrants come from countries with very similar cultural or linguistic backgrounds.  Among subsets of migrants, one could think of the flow among NZ/Australia/Ireland/UK, or between Chile and Argentina, or between the Czech Republic and Slovakia.  At the other extreme, some countries now face the challenges of very large skills gaps between migrants and native-born (most of the Nordic countries are now in this situation).  New Zealand doesn’t do too badly on this count – after all, we have control on who comes in, we have a notional skills focus, and the UK remains the largest single source of residence approvals. But there is a clear skills gap between immigrants and native-born New Zealanders.  Importing people doesn’t look as though it has been a means of raising skill levels here, or in most other countries.  In general that shouldn’t be surprising –  successful countries solve their own problems, and when they succeed they might share their bounty with newcomers. But a different sort of people is very rarely the answer to serious economic challenges.

On paper, there is some evidence suggesting that migrants to New Zealand have higher formal qualifications than the average New Zealander.  Nonetheless, as Julie Fry reported in her Treasury working paper a couple of years ago

Evidence suggests that immigrants are, on average, more qualified than the
New Zealand-born.  However, they also face language and adjustment barriers, at times including discrimination, which on average take 10-20 years to overcome.  In common with overseas patterns, recent New Zealand immigrants have poorer outcomes than others in the labour market, although those outcomes improve over time.   Immigrants who are from culturally similar source countries (such as Australia and the United Kingdom) adjust more quickly.   On average, migrants from Asia take longer to adjust, and migrants from the Pacific Islands never reach parity with the New Zealand-born, reflecting the fact that they enter mainly on family reunification grounds and non-skills-based quotas.
Our immigration policy seems seriously misguided.  It has been sold as a “critical economic enabler“, but if anything looks more as though it might be serving as a disabling factor.  There is no evidence that we are short of people, or of skills.  Skill levels  –  individually and collectively –  could no doubt always be higher than they are.  But immigration policy hasn’t been, and isn’t, raising skill levels in New Zealand –  nor is it doing so anywhere else in the OECD.
(And to anyone who wants to run an individual sector skills shortages argument, I commend to them the post I wrote on that topic a couple of weeks ago.)


The End of Alchemy?

I’ve been reading recently a couple of books by former officials, the common theme of which is probably “avoiding the next collapse”.

Mohammed El-Erian spent much of his career at the IMF, and at one stage was even touted as an outside possibility to become Managing Director of the Fund (being Egyptian when people were trying to break the European lock on the job).  These days he works for Allianz, the big German insurance and asset management company, and previously ran PIMCO, a major subsidiary of Allianz.   I’ve always been a bit skeptical of El-Erian but picked up his book The Only Game in Town –  which a reader had kindly passed on  – with interest.   His key idea is that there has been too much reliance on central banks in the last decade to stimulate activity, and that countries need a wider range of policy responses, better targeted at the underlying issues, to get us back on a more sustainable path.

Initially it sounded plausible, and there is some interesting material in the book, but I came away unconvinced that El-Erian really had much of significance to add to the current debate.   A key part of his argument rests on the not-uncommon line that global monetary policy is incredibly stimulatory (the same line Graeme Wheeler runs here), which gives little weight to the idea that the neutral or natural rate of interest might have changed (fallen) quite substantially.  The fact that advanced country inflation is so low, despite the low interest rates, suggests there isn’t very much stimulation going on.  And there are external reasons to think that neutral interest rates have fallen –  notably the falling rates of population growth (involving less need for new capital) and the declining rate of productivity growth (also likely to associated with a reduced demand for new capital).  If so, central banks haven’t been the heroes of the last few years (as El-Erian’s tale has it), but rather bureaucrats sluggishly recognizing and reluctantly adjusting to the changing external conditions –  often enough champing at the bit to take interest rates back up to levels that might have been appropriate a decade ago, but simply aren’t now.

And yet in the index to  El-Erian’s book there are no references to neutral or natural interest rates (let alone Wicksell), and no references to demography or population growth rates.  In the text there are many more references to PIMCO than to productivity.

Of course, markets have often also been slow to recognize what has been going on  –  and probably no one has a fully convincing answer –  but most central banks deserve little of the praise El-Erian bestows on them.

Of course, his praise of central banks is partly a rhetorical device – a stick with which to beat governments, most of whom have done little in the way of structural reform in recent years.  But he doesn’t actually have much specific to offer on boosting productivity growth. And I’m also more than a little sceptical because of El-Erian’s enthusiasm for multilateral solutions (“the world needs to return to the wisdom of strong multilateralism’) –  perhaps a not unexpected enthusiasm from a former senior IMF official and quintessential internationalist.  In a book published only a few months ago, El-Erian laments the seeming inability of the EU to deliver on their “ever closer political union”: perhaps he might lament it, but few citizens of European countries seem to.  He can’t seem to face the alternative –  that the process might actually be about to head in reverse.    Perhaps even less relevantly, he calls for reforms of the IMF as key part of his list of desirable changes.  Whatever the answers to the current problems ailing the world, I find it difficult to see that:

  • giving the IMF more money
  • giving China more say
  • removing the European lock on the MD job, and
  • strengthening the ability of the Fund “to name and shame countries”

is a material part of the answer.  What legitimacy, one might reasonably wonder, might the IMF have?  What interests does it pursue?  And even if it had legitimacy, none of those measures are ever likely to materially change economic outcomes for the better.

But the main point of this post was to write about The End of Alchemy, by Mervyn King, the former Governor of the Bank of England.  It is a book prompted by the financial crisis of 2008/09, but it isn’t directly about that crisis.  It isn’t a memoir. King suggests that such books are “usually partial and self-serving” –  no doubt, but surely readers can compare and contrast and reach their own judgements (for example, I found his former boss, Alistair Darling’s account of the crisis very useful) – and reckons that future historians can have his account “when the twenty-year rule permits their release”.  Of course, British taxpayers can’t force former Governors to write a memoir, but when a longstanding Governor (including through the biggest crisis in modern times) of considerable intellect and capacity with the pen retires laden with state honours (Knight of the Garter and peer of the realm –  Lord King of Lothbury)  perhaps it wouldn’t have been unreasonable to have hoped for a bit more accounting for the crisis and his role in it.  Ben Bernanke’s book won’t be the last word on the US crisis, but the debate is better for it having been written.

Following the end of his Bank of England term, King visited New Zealand a couple of years ago, and I had the opportunity to participate in a couple of roundtable discussions with him at the Reserve Bank.  I wasn’t the only person who came away from those sessions struck by his reluctance to acknowledge any mistakes whatsoever.  Even tactically, after such a costly banking crisis and disruptive few years, one might have expected some minor concessions, but there was nothing. Senior people tend to look better, more credible and authoritative, for being seen to recognise that all humans –  even them –  make mistakes, even if just small ones.  It was, for example, no secret that in the years prior to the crisis King had had little or no interest in the financial stability functions on the Bank of England.

In many ways King’s book is much more ambitious than any memoir, and it is a stimulating contribution to a different debate: how should we best organize banking systems and financial regulation to produce the best long-term outcomes for the countries of the world.  It is quite ambitious in its reach –  both in the material he covers, and in audience he aims at.  It is explicitly not a book aimed just at economists, but at “the reader with no formal training in economics but an interest in the issues”.  I suspect the book will stretch such readers, but mostly in a good way –  even if I disagree with him in a number of areas, I’d recommend it.  There is a lot of context and background material that is often taken for granted (as well as fascinating bits of obscure history such as the monetary arrangements of French overseas territories in WWII), and King writes fluently and authoritatively.  The downside, perhaps, is that there is so much background, that King devotes less space to fleshing out the case for his alternative perspective than might have been desirable.

There is a lot of stuff in the book that I like.  King is very skeptical of central banks’ forecasting capabilities –  which, of course, didn’t stop him presiding over the development of the current forecast-based system at the Bank of England –  and has long been recognized as a sceptic of the euro.  He is one of the few senior (establishment) people in Europe willing to openly discuss –  and not deplore – the possibility of a break-up of the euro.

And some of his practical policy suggestions seem very much along the right lines.  Higher capital ratios for banks, with an important role for a more constraining leverage ratio (a tool used by most bank regulators, but eschewed by our own Reserve Bank), are appropriate responses to the high (demonstrated) risk that governments will bail-out failing banks, and to the limited ability of apparently-sophisticated capital models to truly capture the changing nature of the risks around complex credit exposures.  Higher required capital ratios, especially for large banks, come at little or no efficiency cost, especially in jurisdictions where the tax system treats debt and equity reasonably neutrally.    And higher liquidity requirements are a prudent part of any system in which, come a crisis, a central bank will act as lender-of-last-resort in the face of intense liquidity pressures.  Requiring banks to hold a larger proportion of liquid assets, so that they can’t just “force” central banks to lend on assets that are highly illiquid even in good times (which is what happened, including in New Zealand, in 2008/09), is a step in the right direction.  Most central banks have moved this way since the 2008/09 crisis, and market pressures have (for now) worked in the same direction.  King suggests that what has been done already is not enough.

But I’m still left uneasy about some key aspects of his argument.

For example, he puts a lot emphasis on the point that credit to GDP ratios are a lot higher than they were a few decades ago (although in places like New Zealand and Australia data suggest they may still be lower than they were in the 1920s).  In this context he discusses the possible contributions of falling real interest rates and a liberalization of domestic and international financial systems.  But in many countries, the largest single component of domestic credit is lending for housing.  And in many countries –  the UK and New Zealand among them –  it is now widely recognized that planning restrictions have created artificial scarcity in urban land supply, bidding the prices of urban land and houses.  Younger generations purchasing houses need to borrow more to buy such houses (in effect, borrowing from the older generations, including –  indirectly –  the sellers),  That raises the level of gross credit in an economy, and perhaps even erodes the financial stability of the system, but it is best understood as an endogenous response to the binding planning restrictions (especially in combination with population growth pressures), not as something driven out of the banking system.  And yet in a book of almost 370 pages there is no mention of this factor at all.    Perhaps banks have aided and abetted the rigging of urban land markets by governments, but the fault surely largely rests with governments not banks.

His historical account of the evolution of central banks, and particualry of the Federal Reserve, is entirely conventional, in playing up the number and severity of  the crises the pre-Fed United States experienced. But he doesn’t seriously engage with either the argument that the crises were themselves partly the outcome of the extensive regulatory restrictions the US had in place in those pre-Fed decades, nor with the experience of some other countries –  notably Canada – which operated for decades with no central bank and no systemic crises.  This isn’t the opportunity to review all the arguments and evidence on those issues, but on my reading King comes down far too readily on the side of the instability of the system –  perhaps with some of the zeal of a convert.

In many ways, Britain itself is a good illustration of the point. Prior to 2008/09, the last really serious systemic financial crisis in the United Kingdom was that prompted by the outbreak of World War One (an episode King discusses, and which is more fully dealt with here).  That crisis wasn’t really the result of any systemic weaknesses in the financial system –  rather governments suddenly changed the rules of the game, having more pressing geopolitical concerns in mind.  Even the crisis in the United Kingdom in 2008/09 was primarily the result of the troubled banks’ exposure to offshore markets –  loan losses on UK domestic banking books never posed a systemic threat.  The key offshore market, the US, was one that was highly distorted by other regulations.

King concludes his book thus

A long-term programme for the reform of money and banking and the institutions of the global economy will be driven only by an intellectual revolution. Much of that will have to be the task of the next generation. But we must not use that as an excuse to postpone reform. It is the young of today who will suffer from the next crisis –  and without reform the costs of that crisis will be bigger than last time.

But I simply didn’t find persuasive the claim that the costs of the next crisis will inevitably be bigger than the last one.  After all, in most countries the experience of the 2008/09 recession was much less severe than that of the Great Depression –  the last really big common advanced country crisis.  Perhaps this points to one of the other issues that King didn’t really address.  If the extent to which GDP per capita and productivity measures are today so far below the pre-crisis trend level is all down to the financial crisis itself, and the associated failings of the financial system, then perhaps King’s case gets stronger.  But he doesn’t make the case for that claim, and since the productivity slowdown was already underway well before the financial crisis, it isn’t necessarily an easy case to make successfully.

Since I got to the end of the book, the title itself has been troubling me.  King is careful to define his “alchemy”

By alchemy I mean the belief that all paper money can be turned into an intrinsically valuable commodity, such as gold, on demand and that money kept in banks can be taken out whenever depositors ask for it.  The truth is that money, in all forms, depends on trust in its issuer…..For centuries, alchemy has been the basis of our system of money and banking.

No one, surely, disputes the importance of trust in a market economy. But if there are distinctive characteristics of  the issue as it affects money and banking, the issues around trust aren’t unique to money and banking.  I trust that the food on sale at the supermarket hasn’t been poisoned.  If ever widespread doubt arises about the validity of that assumption, there will be serious economic disruption.   Perhaps we could prosper with a different banking system –  most practical alternative suggestions seem to me unlikely to make very much difference –  but the West has done quite astonishingly well with the one it has (notwithstanding the current mediocre decade).

And King simply does not seriously engage with the question of how government, bureaucracies, and “government failure” have given risen to some of the distinctive challenges around the banking system.  If, for example, a tendency to bail-out failing banks is a feature of the political system, if regulators tend too easily to see things from the perspective of the regulated, and so on, how confident can we be in the robustness of alternative policy models, which depend on the active ongoing decisions of a new generation of policymakers and officials?  I think King is partly right to describe the last crisis as not primarily the fault of particular individuals –  many of whom were responding to the incentives they faced –  but have the political and bureaucratic and market incentives really changed that much?     Would, for example, Gordon Brown (keen on promoting the City of London as a global banking centre) have appointed Mervyn King as Governor in 2003 if Mervyn King had been known to be all over the issue of financial stability and actively making the case for much tighter controls on banks and the banking system?   What is it that means those same incentives and constraints won’t be at work again as the memory of the last crisis fades?

King devotes some space to the debate as to whether monetary policy should be used to lean against asset price booms and the build-up of credit (or just focus on the inflation target, in the upswing, and after any bust).  This was a major debate at the Bank of England –  including at the Monetary Policy Committee level –  as far back as the late 1990s.  King seems to hanker for the “do something” camp –  that perhaps “doing something” with monetary policy might have led people to reassess their future income prospects earlier, and limited the extent of the imbalances that built up. Of course, as he recognizes there were problems. In a world of national policymaking, a central bank that tried to lean against the boom would tend to see a higher exchange rate, and in some respects a more unbalanced economy.

I’ve always thought that the other problem was that –  thankfully –  central banks typically have a rather constrained form of independence.  Had the Fed or the Bank of England –  or the RBNZ for that matter – tightened monetary policy materially more aggressively during the boom, the pressures on policymakers to change the target –  or the powers of the central bank –  would have been great.  In Britain, the inflation target is set each year by the Chancellor –  I find it scarcely credible that Gordon Brown would have welcomed a years-long undershooting of the inflation target he himself had set, and not just as a result of “forecasting errors”, but as a matter of deliberate policy choice.  Perhaps there is something in the old line about the job of the central bank being to remove the punchbowl just as the party is getting into full swing, but the actually the waiter can really only remove the punchbowl with the consent of the partygoers.  In the last boom, there was simply no appetite anywhere for materially tougher policies –  and no one knew the future, and many credit booms (even those of 00s) haven’t ended badly.  King rightly stresses the importance of “radical uncertainty”, but central banks and financial regulators are no more gifted with insight or fine judgement than the rest of society.  And they face institutional incentives, for good and ill, as the rest of us do.

King is clearly uneasy about the current low level of world interest rates. And in one sense, he is right to be so –  we all want to better understand the underlying forces that have delivered such interest rates (not just policy rates, but the extraordinarily low bond yields).   And it is also, clearly, correct that monetary policy is not an instrument that can generate the sort of faster long-term productivity growth that most countries would now welcome.  But to suggest, even if only implicitly, that somehow things would have been materially  better if only policy rates had not been held so low for so long seems more like wishful thinking than hard-headed analysis.  If he has such analysis, it didn’t make it into the book.

It is an interesting and stimulating book, well worth reading.  In a way it is shame that he overreaches.  His mostly-sensible actual policy recommendations do not, to me, seem to represent anything like the sort of transformation his title implies.  But nor, I suspect, is such a transformation needed.

Is NZ less receptive to immigrants than Australia?

Tyler Cowen had an interesting and thoughtful piece on Marginal Revolution yesterday, headed Why Brexit happened and what it means. He summarises his answer as “ultimately the vote was about preserving the English nation” –  on this telling, primarily about immigration. And despite his own pro-immigration inclinations, he runs a sympathetic interpretation of why a majority of British voters might reasonably have voted as they did.

He runs a story in which there is something distinctly different about Britain (along with Japan and Denmark)

One way to understand the English vote is to compare it to other areas, especially with regard to immigration.  If you read Frank Fukuyama, he correctly portrays Japan and Denmark, as, along with England, being the two other truly developed, mature nation states in earlier times, well before the Industrial Revolution.  And what do we see about these countries?  Relative to their other demographics, they are especially opposed to very high levels of immigration.  England, in a sense, was the region “out on a limb,” when it comes to taking in foreigners, and now it has decided to pull back and be more like Denmark and Japan.

The regularity here is that the coherent, longstanding nation states are most protective of their core identities.  Should that come as a huge surprise?  The contrast with Belgium, where I am writing this, is noteworthy.  The actual practical problems with immigration are much greater here in Brussels, but the country is much further from “doing anything about it,” whether prudently or not, and indeed to this day Belgium is not actually a mature nation-state and it may splinter yet.  That England did something is one reflection of the fact that England is a better-run region than Belgium, even if you feel as I do that the vote was a big mistake.

I’m not sure I’m totally persuaded by the idea that immigration was the main factor explaining the British vote.  One of a package of issues no doubt, but whether it is the main story is another question.  After all, Lord Ashcroft’s poll asked thousands of people why they had voted as they did.  Here were the results

Leave vs Remain podium rankings

  • Nearly half (49%) of leave voters said the biggest single reason for wanting to leave the EU was “the principle that decisions about the UK should be taken in the UK”. One third (33%) said the main reason was that leaving “offered the best chance for the UK to regain control over immigration and its own borders.” Just over one in eight (13%) said remaining would mean having no choice “about how the EU expanded its membership or its powers in the years ahead.” Only just over one in twenty (6%) said their main reason was that “when it comes to trade and the economy, the UK would benefit more from being outside the EU than from being part of it.”

Among both Labour or Tory voters the biggest single reason for voting Leave was, on respondents’ own accounts, “the principle that decisions about the UK should be taken in the UK”.    If governments are going to do something as silly as ban powerful vacuum cleaners, at least it should be our own government that does it.

Perhaps voters were reluctant to own up to concerns about immigration as the most important factor?  And perhaps immigration and the changing character of the country was important beneath the surface –  as the economic underperformance of the last nine years has probably been.  But it isn’t an open and shut case that this was mostly an immigration referendum.  After all, stories – accurate or not –  about the EU wanting to ban bendy bananas, or force people to use metric units, have had considerable traction in Britain for decades.

And if you were British you might reasonably think you would be at least as well off having your own government makes the choices for you.  Things might seem different in the rest of Europe where, for example,

  • in 1970, Spain, Portugal and Greece were under authoritarian dictatorships,
  • in 1980, the Baltic states didn’t exist as recognized entities, and Poland, Rumania. Bulgaria, the Czech Republic, Slovakia, Slovenia, Croatia and Hungary were all under failing Communist rule (and four of those countries didn’t even exist independently),
  • Finland Ireland, and Norway (the latter not in the EU, only the EEA) weren’t independent countries as recently as 1900,
  • Germany had its unsavoury 20th century history (accompanied by Austrians cheering for the Anschluss),
  • Denmark, Belgium, Netherlands and Luxembourg were all occupied by Germany for several years,
  • Having been defeated by Germany in 1871, and narrowly  (and at vast cost) winning World War One, France then endured the shame of German occupation in World War Two, the collaborationist Vichy regime, and the crisis of 1958,
  • Malta’s 40 years between independence and joining the EU was the historically abnormal self-rule phase.

It doesn’t leave many countries where citizens can look back over the last 150 years and say “yep, we ran ourselves over long periods of time pretty well really”.   But Britain did. Now, as we know, there is plenty of anti-EU sentiment in much of the rest of Europe as well, but it seems quite readily understandable, just in terms of their own country’s history, that UK voters would prefer their own governments to make decisions for them.    And it doesn’t take a huge political and bureaucratic edifice to establish a free trade area, or a mutual external defence arrangement (such as NATO).

Having said all that, what really prompted me to write this post was this line in Cowen’s post.

Of course, USA and Canada and a few others are mature nation states based on the very idea of immigration, so they do not face the same dilemma that England does.  By the way, the most English of the colonies — New Zealand — has never been quite as welcoming of foreign immigrants, compared to say Australia.

I’m at a loss to know what he is basing that final sentence on.  For better or worse –  and given the economic opportunities here, I think it has been mostly for the worse –  that proposition seems to be defied by the data.

At times, I’ve had people run the line to me that since in 1500 the non-indigenous populations of New Zealand, Australia, Canada and the United States were all, essentially, zero, and since New Zealand has by far the smallest population of any of those countries we must have been less open to immigration.  But those other places started European settlement and immigration earlier than we did –  and were closer to Europe, at times when travel costs (mostly elapsed time) mattered hugely.

I’m going to start my comparisons from 1870.  That is partly because I was using the Maddison database and its first annual New Zealand population numbers are for 1870.  But it also seems reasonable on other grounds. In both New Zealand and Australia the influxes (and outflows) associated with the respective gold rushes were over by then, and by 1870 the New Zealand Land Wars were winding down –  never thereafter was there any serious question about settler control of the North Island.  The large scale Vogel immigration and public works programme began shortly thereafter.

Here is a chart showing the total populations of New Zealand and Australia since 1870, both normalized to 100 in 1870, and done in logs so that readers can see changes in growth rates over time.

aus and nz popn since 1870.png

Over the full period –  145 years – New Zealand’s population has grown materially more rapidly than Australia’s.  Of course, the largest differences were in the first decade, but the gap hasn’t narrowed since.

I’ve often run the argument that New Zealand’s post-WWII immigration policy was materially misguided, at least on economic grounds, given the absence of new favourable productivity shocks or technological opportunities that would support top tier incomes for a rapidly growing number of people in these distant islands

Here is same chart starting from 1945.

aus and nz popn since 1945


You can see the period from the mid 1970s to the late 1980s when New Zealand had very low rates of net immigration, but over the full period New Zealand’s population growth has still modestly exceeded that of Australia.

And here is the most recent period since 1991 –  which uses official New Zealand population data, and ties in quite well with the change in immigration approach in New Zealand that largely prevails to today.

aus and nz popn growth since 1991

Again, our population growth has been a bit faster than that of Australia.

Now it is perfectly true that in the immediate post World War Two period, Australia was much keener on taking continental European migrants than we were.  Then again, in the 1960s and 70s we had large inflows of Pacific Island migrants, and there was nothing comparable in Australia.

But, and here is my other key point, we’ve had faster population growth than Australia even though we’ve had huge outflows (net) of New Zealand citizens, that swamp any outflow from Australia of Australian citizens.

Here are the numbers on the total net outflows of New Zealand citizens for each decades since the 1950s

Net PLT outflow of NZ citizens (March years)
1950-59 -2494
1960-69 -34,057
1970-79 -161,231
1980-89 -229,874
1990-99 -146,229
2000-09 -263,651
2010-16 -138,705

That is a total of 976000 people, from a country which at the start of the period had only 2 million people and now has around 4.6 million people.

Some of the people who left will have died by now, but official estimates reported by Statistics New Zealand suggest 600000 New Zealand born people living abroad (and perhaps 1 million New Zealand citizens living abroad).     Australia has five times the population of New Zealand, and yet estimates of the total number of Australians living abroad are around one million.

Yes, there are differences in rates of natural increase from time to time, but the big story of recent decades in particular has been one in which New Zealand has taken materially more non-citizen migrants (per capita) than Australia has, reflected in the slightly faster population growth we’ve had despite the huge continuing outflow of New Zealanders.

In fact, you can see this in the respective policy-controlled bits of the immigration programmes.   This chart is cobbled together using data since the late 1990s on Australian permanent migration approvals under their Migration stream and Humanitarian stream, and New Zealand data on residence approvals. To the Australian numbers I’ve added the net inflow of New Zealand citizens to Australia, and to the New Zealand numbers the (much smaller) net number of Australian citizens moving to New Zealand.

migration rates nz and aus

Most years, the rate of permanent immigration of non-citizens to New Zealand has been higher  –  often materially higher – than that to Australia.  And the Australian numbers have dropped back since the end of this chart as the flow of New Zealanders moving to Australia has fallen back.

Perhaps Cowen had some less numerical basis in mind for thinking that New Zealanders have been less welcoming of immigrants than Australia.  But I’m not quite sure what it could be (although there is always this site).  And given our continuing economic underperformance, it is quite remarkable how receptive New Zealanders have been to such high rates of immigration (roughly three times per capita the size of net non-citizen inflows to the US and UK) –  especially as the programme is repeatedly sold as an economic-based measure, a “critical economic enabler” in the words of the government department responsible for immigration policy matters.


More states or fewer?

I was going to write something today about monetary economics, the 2008/09 crisis, and reform options for financial systems and economies, but….the Brexit aftermath is pretty much all-absorbing, at least to a politics/economics/geopolitics junkie.   So far, it is difficult to see why anyone would be very surprised about what has happened since Friday, but of course it is very early days.  Media coverage seems dominated by perspectives from those –  including the journalists writing the stories – almost personally affronted that the populace of a major, quintessentially moderate, country could have voted as they did. The stories highlight, without really needing to try, the disconnect between what might be loosely described as a metropolitan urban liberal mindset that downplays the local in favour of a network of internationalist rule-setting, and what might loosely be described as a more small-c conservative mindset that puts a greater emphasis on the local and the national as the basis for rule-setting and governance.  Peter Hitchens highlights this contrast in his column here – highlighting how detached the majority of MPs of both main UK parties have become from the views and attitudes/priorities of very large shares of their voters.  The situation probably isn’t much different in a whole variety of advanced countries.

But what got me particularly interested over the weekend was talk of the United Kingdom itself breaking up.  Of course, that started a long time ago.  The Irish Free State (as it was then called) became independent in 1922.  If Northern Ireland should eventually reunite with the Republic of Ireland –  and frankly I would be surprised if it happens in the next few decades, given the risk of reigniting the decades-long civil conflict – it would only be the culmination of the Home Rule movement that was convulsing British politics as far back as the 1880s, and which saw Britain facing the possibility of an army mutiny and civil war on the eve of World War One.

The chances of Scotland becoming independent seem somewhat higher –  after all, the Out vote got 45 per cent in the last referendum only two years ago.  If the headline-grabbing opportunity to push for a new referendum is the desire to stay in the EU –  and for all the hype, even 38 per cent of Scots wanted out –  they had better hope there is still an EU to belong to a decade hence.  But even if not, is the idea of Scottish independence so different from that of Irish independence –  which we all now take for granted, even if (at the time) it probably came at a considerable economic cost?  Scotland had been independent for hundreds of years, and if it did well economically from the Union and its people played a huge role in the British Empire, who could begrudge them the right to govern themselves?

After all, although it wasn’t always so, the people of England and Wales make up 90 per cent of the population of today’s United Kingdom.   Even without Scotland and Northern Ireland, England and Wales would be the fourth most populous country in Europe, just a little behind Italy.

But then I got thinking about other countries.  Hasn’t a move towards more countries been underway for some considerable time?  The unification of Germany and of Italy were huge developments in the mid 19th century, but they were largely completed by 1870.   Our own Land Wars finished around the same time, securing a single state entity on these islands. The US grew hugely (in territory) during the 19th century, but had largely reached its current size with purchase of Alaska (from another large state) in 1867.  Even the acquisition of Hawaii was almost 120 years ago now.

I found a list of countries ordered by population in 1900.  Here was the 25 largest:

China 415,001,488
Indian Empire 280,912,000
Russia 119,546,234
USA 75,994,575
Germany 56,000,000
Austria-Hungary 51,356,465
Dutch East Indies 45,500,000
Japan 42,000,000
United Kingdom 38,000,000
France 38,000,000
Italy 32,000,000
Ottoman Empire 30,860,000
Spain 20,750,000
Brazil 17,000,000
Mexico 12,050,000
Korea 12,000,000
Northern Nigeria 8,500,000
Egypt 8,000,000
Morocco 8,000,000
Philippines 8,000,000
Southern Nigeria 7,500,000
Siam 7,200,000
Persia 7,000,000
Romania 6,630,000
Belgium 6,136,000

Of these, the two parts of Nigeria (both then administered by the UK) are now one country.  Quite a few of the other countries are much the same as they were then, subject to some (mostly relatively minor) border adjustments (eg the return of Alsace-Lorraine to France).

But the bigger story surely is the break-ups.   What was the United Kingdom is now two countries, the UK and Ireland.  What was Korea is now –  at least for the time being –  two countries, North and South Korea.  India as it was is now Sri Lanka, India, Pakistan, Bangladesh and (depending where the boundary lines were drawn) Burma.  And the erstwhile Russian, Austro-Hungarian, and Ottoman Empires have split into dozens of new independent countries between them.

What of today’s 25 most populous countries?

China 1,376,048,943
India 1,311,050,527
USA 321,773,631
Indonesia 257,563,815
Brazil 207,847,528
Pakistan 188,924,874
Nigeria 182,201,962
Bangladesh 160,995,642
Russia 143,456,918
Mexico 127,017,224
Japan 126,573,481
Philippines 100,699,395
Ethiopia 99,390,750
Vietnam 93,447,601
Egypt 91,508,084
Germany 80,688,545
Iran 79,109,272
DR Congo 77,266,814
Turkey 78,665,830
Thailand 67,959,359
United Kingdom 64,715,810
France 64,395,345
Italy 59,797,685
Tanzania 53,470,420
South Africa 54,490,406

Of these countries, only the last two comprise what were smaller entities in 1900 –  and neither is, perhaps, an advert for the cause of ever-larger unions.   Tanzania was previously the colony of Tanganyika and the protectorate of Zanzibar (ruled by a Sultan, under British oversight).  Zanzibar was granted independence in 1963, but this was quickly followed by a bloody revolution, at the end of which Zanzibar was absorbed (semi-autonomously) into the new Tanzania.  And, of course, South Africa in its current legal form was the fruit of the Boer War, essentially a war of conquest in which –  at great cost –  the British Empire and the British colonies beat the Afrikaaner states.

Have there been other mergers attempted?  Well, yes, after World War One the artificial state of Yugoslavia was created by the powers.  That has now long gone.  Czechoslovakia also emerged from that settlement –  also (peacefully and successfully) gone.  In the 1950s there was political union between Egypt and Syria: it last for all of three years.  The British created the Federation of Rhodesia and Nyasaland in the 1950s, and it was also gone a decade later.

Can one think of exceptions?  No doubt.  Various colonial enclaves have been reabsorbed by the surrounding power, peacefully or otherwise –  Goa, Hong Kong, Macau.    But there isn’t much else for more than 100 years, and none that I can think of where the voluntary choice of the respective populaces has led to the formation of larger states from smaller states (happy to hear if I have forgotten any).  Germany reunited –  but then it never separated voluntarily, and indeed in 1945 the intention was never two separate states.

None of this should really be very surprising.  The other great trend of the last couple of hundred years has been towards democratic government. People clearly  seem to want to rule themselves with – and be governed by  – people with whom they feel some significant sense of common identity and shared perspectives (which might be ethnic, or religious, or linguistic, or simply historical).  Little really –  in the scheme of things –  divides New Zealand and Australia, and yet there is no great appetite for the two to become one.   The metropolitan elites might wish it were otherwise –  and might even believe quite genuinely that everyone could be better off it only things were done their way –  but the citizens of the world show little sign of being convinced by their story.  Are the people of the world poorer as a result?  Possibly –  despite the huge volumes of cross-border trade –  but some things seem to matter more to most of them.

And it isn’t as if the trend towards more and smaller states looks like having run its course.  Even in Western Europe, there is Scotland, demands from Catalans for independence, and the ever-present question of what unites Belgium other than, say, a football team.

In that light I was quite puzzled by Wolfgang Munchau’s FT column today. In many ways it was a hardheaded piece, noting that the risk from the UK referendum for the rest of Europe may be greater than those for the UK.  Highlighting Italian risks in particular –  and Italian stocks fell savagely on Friday –  he ends

To prevent such a calamity, EU leaders should seriously consider doing what they have failed to do since 2008: resolve the union’s multiple crises rather than muddle through. And that will have to involve a plan for the political union of the eurozone countries.

How he imagines that the citizens of the Eurozone countries will ever agree to political union, especially now, is beyond me.    I guess the traditional European elite approach is not to give them a say.

UPDATE: For anyone wanting a more systematic treatment of some of these issues, see Alesina and Spolaore The Size of Nations (my copy of which I finally found on my shelves).  They devote an entire chapter to the EU.  In a book published in 2005 – with an expanding EU, and the general contentment with the early years of the euro –  they seem (perhaps understandably) slightly  uncomfortable with how the EU fits with their general model in which lower trade barriers and fewer wars would typically result in more states, not fewer.  But they conclude their EU chapter boldly: “Quite simply, it is not possible for Europe to become a federal state”.


Makhlouf again

In almost any well-functioning country, The Treasury should be one of the very best government agencies: a repository of wisdom, experience, rigour, and the skepticism that comes from seeing all too many “bright ideas” put forward over the years.  If the Secretary to the Treasury is going to give public speeches –  and there are reasonable arguments that someone in that role shouldn’t (one doesn’t come across public speeches from the chief executives of MBIE or MFAT, two other major departments) –  we might reasonably expect something judicious and rigorous, and which provides at least some fresh and interesting insights on the issues he is addressing.    It should be a public reflection of the very best of the sort of insight and advice The Treasury is offering their primary “customer”, the Minister of Finance.

As an example, speeches by Ken Henry, the former head of the Australian Federal Treasury, almost always met that standard –  I looked forward to reading them, and expected to see some or other issue or argument a little differently as a result.  It isn’t about whether or not one agrees with the points the speaker is making – often one learns most from thinking hard about cases made by able advocates of an alternative view –  but about the quality of what is on offer.

The speeches of our current Secretary to the Treasury simply don’t reach that standard.  On Thursday I wrote about Gabs Makhlouf’s recent speech about disruptive technological change.  Only a true believer can have felt better for reading it –  deriving, perhaps, a sense of validation in having such a senior official, a pillar of the establishment, say it.

Perhaps more disconcerting was Makhlouf’s speech earlier this week titled (apparently with reference to the title of Oscar Wilde’s famous play, The Importance of Being Earnest: A Trivial Comedy for Serious People) The Importance of Being Auckland: Strengths, Challenges, and the Impact on New Zealand, delivered to something called the “Committee for Auckland Advisory Group Summit”.

It is a disappointingly poor speech –  I wish I could say I was surprised, but I wasn’t really.  It was a piece that combined lightweight analysis, (very) selective choices of evidence, and a use of rhetoric that might have been becoming from a Cabinet minister pursuing voters, but should have been beneath a senior public servant.  It was all too similar to previous speeches: not just one bad example amid an otherwise solid record.

There were three main parts of the speech.  I don’t have anything to say on the material on infrastructure, much of which is simply a list of points from another report.

Makhlouf begins with a celebration, in a section headed “Auckland’s Strengths”.  The text reaffirms Makhlouf’s position as a true believer: a rapidly growing population is apparently something to celebrate, and the cultural/ethnic diversity of the city is “exciting”.  Here is what he has to say

Why do I find this exciting? It’s because high levels of diversity provide dividends including through increases in innovation and productivity.

Auckland’s diversity is particularly critical for our international connections. There’s much more to international connections than trade. It’s the other international flows – flows of capital and people, and the accompanying flow of ideas – which are the key to reinventing trade, and which will lay the foundation for a more prosperous New Zealand in the long-run.

The high number of overseas-born Aucklanders can bring new skills, new ideas and a diversity of perspectives and experiences that help to make our businesses more innovative and productive. And perhaps most importantly, they often retain strong personal and cultural connections to other parts of the world, which opens up, and helps us to pursue, new business opportunities.

Auckland is truly New Zealand’s gateway to the world. It’s not just that there is a big number of companies here doing business internationally. It’s the port and airport linking the country to global markets; and tertiary institutions, researchers and innovators linking us to global knowledge.

Which might all sound fine,  until one starts to look for the evidence.  And there simply isn’t any.  Perhaps 25 years ago it was a plausible hypothesis for how things might work out if only we adopted the sort of policies that have been pursued. But after 25 years surely the Secretary to the Treasury can’t get away with simply repeating the rhetoric, offering no evidence, confronting no contrary indicators, all simply with the caveat that in “the long run” things will be fine and prosperous.  How many more generations does Makhouf think we should wait to see his preferred policies producing this “more prosperous New Zealand in the long run”?

If the Secretary to the Treasury was going to address the economic issues around Auckland, one might have hoped there would be at least passing reference to:

He might also have linked to the recent presentation by Jacques Poot (in a Treasury guest lecture), in which Poot was keen not to sound very optimistic about just how large those economic benefits of diversity really are, or to the work of Bart Frijns – an (immigrant) professor in Auckland (see last sentence of the extract above) –  whose recent work suggests that on some measures, in some contexts, there may be net costs, not benefits at all.

Of course, one can’t say everything in a single speech, but when a credible case could be made that the Auckland-centred model is in serious trouble, it is bordering on the seriously unprofessional to not even allude to any of these sorts of points, even if only to explain why the Secretary interprets then differently than, say, I might.

So keen was Makhlouf not to undermine his good news creative fiction about the Auckland economy that the one difficulty he does allude to is buried under a different heading “Social Outcomes”.

Let me start with social outcomes. Auckland scores well on quality of life indicators but other measures suggest not everyone is able to enjoy what Auckland has to offer. Social outcomes vary significantly across Auckland, highlighting the potential importance of sub-regional thinking and analysis to lift social outcomes across the board in Auckland.

Issues with the labour market contribute to patchy social outcomes across the city. While Auckland has higher productivity than other urban centres in New Zealand, it also has an underutilised labour force. For example, the five year average unemployment rate in South Auckland is 11.7 percent compared with 6.3 percent for the rest of Auckland and 6 percent for New Zealand overall. That’s the sort of discrepancy that has a real impact on the quality of life of families and communities.

To the first paragraph one can only say “And?”   In what city –  or decent-sized town –  ever did “social outcomes” not “vary significantly”?

Similarly, differences in the unemployment rate across groups within cities will occur everywhere –  if we had the data, I’m sure the unemployment rate would be higher (and probably the participation rate lower) in Porirua than in Karori/Kelburn.  It might be good if were not so, but it isn’t obviously an Auckland-specific issue.   After all, across the country as a whole, the average unemployment rate over the last five years for Europeans has been 4.3 per cent, while that for Maori has been 14.7 per cent, and that for Pacific populations has been 13.4 per cent.  Given that the population of South Auckland is disproportionately Maori/Pacific, the issues in South Auckland seem most likely to be mainly national than (intra-Auckland) suburban.

But there is an Auckland underperformance that might almost escape you if you didn’t read that second paragraph quite slowly and carefully.  The unemployment rate in Auckland is higher than that in the rest of New Zealand.   For a long time, that wasn’t so.

auckland U makhlouf

The chart shows the gap between the unemployment rate for New Zealand as a whole.  Over the history of the HLFS until around 2007, Auckland’s unemployment rate averaged a bit below that of the rest of the country.  There was some clear cyclicality to the gap –  Auckland’s economy/labour market seems to have been more badly hit in recessions (I’ve highlighted the 1991 and 1997/98 recessions) and does relatively better in good times.  In a well-functioning economy, that better performance is what I’d expect.  After all, the Auckland labour market is so much deeper, and more diversified, than that in other centres, that it should be easier for workers and firms to find each other, matching the  skills offered and required, than in a smaller area, typically prone to more idiosyncratic shocks.

But even by the end of the last boom, Auckland’s advantage seemed to be fading.  And in every single quarter since the start of 2007 –  nine years now –  Auckland’s unemployment rate has been above that in the country as a whole.  The gap is slowly closing again –  but the operative word is “slowly”.  It is a quite stunning example of the (frankly rather surprising) extent of Auckland’s economic underperformance.  It certainly has “social” implications for the people adversely affected, but make no mistake, it is a striking economic issue.    And with barely a mention by the government’s chief economic adviser in a speech on the importance of Auckland’s economy.

I was going to write quite a bit about the second half of Makhlouf’s speech, on house prices and housing supply.  I have lots of scrawls in the margins of those sections, about both substance and style.    Like Graeme Wheeler, Makhlouf appears to have it in for “speculators”.  And I’m sure, for example, that Makhlouf’s comments that central and local government have “been working well together” in “addressing the housing challenge” must be a great comfort to those priced out of the market by the combination of central and local governments rules and policies.  They are probably more interested in outcomes –  which are shockingly bad – than in knowing that the bureaucrats are working well together.

But perhaps the line that caught my eye most was one that Treasury consciously chose to highlight on its Twitter feed: “Auckland NIMBYism hurting New Zealand”.    Perhaps “NIMBY” is a convenient shorthand in the popular press, and among sloganeers.  One might have hoped that the Secretary to the Treasury might have avoided clearly pejorative labelling of people, whose interests stands in the way of his preferences.  There is no analysis –  even by way of allusion – to the fact that in most new residential developments, private covenants (voluntary contracts) provide exactly the sorts of binding protections (and more) that residents of Orakei or Epsom might be looking to councils for in the current Auckland debate.  Reasonable people might differ on where the lines should be drawn, and quite which existing features of communities should be able to be protected.  But to simply decry the interests of property owners seems closer to demagoguery than to detached analysis and insightful policy advice.  It also occurred to me to wonder quite what the longstanding residents and property owners in existing suburbs might make of someone fairly fresh off the plane from the UK telling them how their suburbs should be changed.  I’m quite sure that Makhlouf has the best interests of New Zealanders at heart, but when you are a newly-arrived outsider, sometimes you need to be conscious of quite how you sound, and quite what your stake is in the country you are advising on, relative (say) to those who have lived their whole lives in Auckland.

In closing his speech, Makhlouf offered this odd paragraph:

The famous photographer Sir Cecil Beaton once appealed to people to “be anything that will assert integrity of purpose and imaginative vision against the play-it-safers, the creatures of the commonplace, the slaves of the ordinary.”   From what I can see, many Aucklanders are heeding that call in their own way.  And having the right infrastructure, supported by economic incentives that send clear, efficient and effective signals, will enable Aucklanders to continue to exercise their dynamism and diversity and to do the best that they can do.

When I looked up Beaton, his seemed a somewhat reckless life, ending in financial stress.  Perhaps it is the style the dreaded “speculators” emulate –  but then we already know Makhlouf disapproves of them.  Surely most people, in most places, in most times, crave the security of a home, an income, a family, the commonplace things that mostly conduce to sustained happiness (and prosperity for that matter). Risk is, of course, part of life, and many of the great financial successes involved some mix of great risk and great luck.  But we seem to be in an upside-down world in which a Secretary to the Treasury (self-described cautious guardian of the government’s finances) scorns the natural concerns of the vast mass of people.  One might add, that  –  with the full support of the Treasury –  we’ve been eschewing the commonplace, and the “play-it-safers” in our Think Big policy for Auckland over the last 25 years.     And there is little good –  for the vast mass of Aucklanders (and New Zealanders) – to show for it.

Makhlouf quotes various English figures in his speech.  I’ve always been quite keen on Kipling.  In his famous poem “If” comes the lines

If you can make one heap of all your winnings
    And risk it on one turn of pitch-and-toss,
And lose, and start again at your beginnings
    And never breathe a word about your loss;
…
you’ll be a Man, my son!
I’m not sure that giant policy experiments, showing no sign of paying off 25 years on, are really quite what Kipling had in mind.  But I’m sure that simply ignoring the signs that things aren’t going well wasn’t.
New Zealanders deserve a great deal better from the Secretary to the Treasury.


Brexit

I guess people need to mourn their defeats, but flicking around various TV channels’ coverage the comment that staggered me most was that of the prominent English historian, Simon Schama, who declared –  well before the result was clear –  “if Leave wins, it will be a repudiation of knowledge; a repudiation of reality’.

Or simply, perhaps, just a choice by UK voters to have their country governed by their own MPs, their laws interpreted and applied by their own judges, and so on.   Rather like New Zealand, Australia, Canada, or the United States.   Many other commentators have seen the vote as a vote against the Establishment,  which is no doubt true in part  – as the election of Jeremy Corbyn was, and perhaps the success of date of Donald Trump has been – but if so, comments like those of Schama, totally dismissive of the choices of his fellow citizens, might go down as a classic example of the sort of attitude and approach that many saw encapsulated in the EU model, and the way in which too many countries have been governed in recent years.

The market reactions so far seem hardly that surprising – except perhaps in highlighting the bounded rationality that had left so many (I was among them) almost unable to believe that, even though the polls had been a dead-heat for weeks, a Leave vote could actually happen.

The headline fall in the value of sterling is striking  – currently down 9.9 per cent against the USD.  But it brought back memories of the wild days of the New Zealand foreign exchange market, especially in the early years after the 1985 float.   But as recently as 28 October 2008, the NZD was down 9.3 per cent in a day (and more like 12 per cent against the yen).  The trend was strongly down in that global crisis and recession, but there was also a sharp bounce the following day.  I recall watching CNBC each evening during the 08/09 crisis.  It might be another few days for that  –  and to be glad it is “spectator sport” rather than something I have direct exposure to.


UPDATE: I thought this piece by US economics columnist Megan McArdle was a very nice articulation of views I share almost entirely.

UPDATE 2:  An absolutely fascinating set of results from exit-polling of referendum voters