Reserve Bank on the economic impact

In mid-April, The Treasury released some economic scenarios for how things might play out as the country and economy work through –  and perhaps beyond – Covid-19.  I wrote about that document here.  The focus of those scenarios was on peak levels of (for example) unemployment, and on the multi-year path back to full employment.  It was a quite limited exercise –  although valuable for what it was –  in that all the variation across the scenarios was about the degree of government (a) restrictions, and (b) stimulus.

A day or two later, the Reserve Bank appeared before the Epidemic Response Committee and they gave the Committee some numbers for the estimated GDP losses at each level in the government’s (then) schema of alert levels –  this was before the current “Level 3” rules were adopted, let alone the new (“Level 2”) ones to be announced today.   The comparative losses across the various levels at that point were as follows

Loss of GDP (%) while restrictions in place
Treasury Reserve Bank
Level 4 40% 35%
Level 3 25% 20-25%
Level 2 10-15% 10%
Level 1 5-10% 5%

In a post a day or two later, focused on the loss of GDP during the “Level 4” period, I suggested that the Reserve Bank in particular was probably understating the severity of the loss.  I noted that senior officials in some European countries had been talking of a 35 per cent loss during the period of peak restrictions, and yet our own restrictions then were regarded as among the most stringent anywhere in the advanced world.  As a cross-check on my thinking I went through the 50+ sub-sectors of GDP that SNZ publishes data for and made some back-of-the-envelope estimates for each, which ended up in aggregate consistent with my view that even The Treasury might be a little light (although the uncertainties are huge). Checking my spreadsheet, I see that the final number I came to them was a 42 per cent loss relative to normal, which I’d be happy to call “40-45 per cent”.

Yesterday, the Reserve Bank released a staff working paper with some more detailed estimates.  This will be background material for the MPC’s deliberations in advance of the Monetary Policy Statement next week.  They appear to have revised some of their estimates since that select committee appearance in mid-April.  The centrepiece of the publication is probably this table.

RB scenarios may 20

At least for the stage we are now in and those ahead of us (one hopes no more “Level 4”, but who knows), these estimates are lower –  less heavy losses-  than those the Assistant Governor gave Parliament (see earlier table).    Of course, there are huge margins of uncertainty that render all point estimates things to be used advisedly, but when the same institution publishes point estimates a few weeks apart, the differences may still be worth paying some attention to.

On the other hand, there are things that confound the comparison.  For example, the actual “Level 3” rules we currently live under are more constraining than the “Level 3” the government initially published in late March (or which we lived under for two days in late March).  But that then makes the contrast between the “Level 3” estimates given to Parliament a few weeks ago, and those they are coming up with now, a bit puzzling.   Despite what still seem like relatively tight restrictions, the Bank thinks half the fall in GDP in “Level 4” is recovered in “Level 3”.

Another important aspect is that the Bank appears to be trying to be clearer about what the current numbers actually represent.  This is their description

This paper estimates the direct costs to economic activity while the measures are in place. Any ongoing impacts to GDP, or to wellbeing are beyond the scope of this analysis.

We estimate the impacts on GDP of the following measures:

• Lock down of all non-essential activity (alert level 4)

• Restrictions on trading activity (alert level 3)

• Border restrictions

• Domestic travel restrictions

• Mass gatherings and public venues

Now even this isn’t quite right, since as they note in passing later much of the fall in GDP would have happened anyway, with no New Zealand government restrictions at all: tourism was falling away sharply, as was domestic air travel, physical distancing was becoming increasingly prevalent and so on.

And as the restrictions are eased back, what is lawful is not necessarily what will occur.

In “Level 4” however, things are a bit clearer.  Things were –  often rather loosely –  described as “essential” (those Cookie Time biscuits, cigarettes, Arobake cakes etc), and what could lawfully be done was (largely) the binding constraint.   So for Level 4 what could be done and what were done were probably quite tightly aligned: if there were to be a GDP  figure for that month or so, the Bank presumably thinks it would have been 37 per cent lower than normal.

But that won’t be the case as the restrictions are wound back.  As one –  probably extreme – example much as the Bank thinks a lot more of the economy can operate now, no one in my (high income) household has spent an additional cent on any New Zealand business that we weren’t patronising in “Level 4”.    It seems that what the Bank is actually describing for Levels 3, 2 and 1 is something much closer to the lawful capacity of the economy (including the reduced productivity of many operations that are allowed to open in some form or other, or work from home) than to the actual likely GDP effect.  Thus, they appear to be saying that 81 per cent of the normal level of the economy could be produced in “Level 3”, not taking a view on the extent of demand.  Actual GDP may be –  I suspect probably is –  much weaker than that.

Of course, as one runs up the levels, things get murkier again. At “Level 1” it appears that everyone in the economy could work, and perhaps only international airline operations would be (in effect) regulatorily restricted; it is just that a key chunk of demand just won’t be there (Rotorua and Queenstown hotels/motels will be quite free to open –  as they are now I think –  but there might be rather few takers).  And since this is a stylised exercise, that does not include the effects of fiscal or monetary policy responses (feeble as the latter has been so far), they can’t be thought of a forecast that, say, if we are at Level 1 in three months’ time, GDP will then only be 3.8 per cent less than normal.  The Bank’s exercise also makes no attempt to allow for confidence factors, no attempt to allow for the derived loss of activity elsewhere in the economy from a shock to a particular sector, no attempt to factor in a severe world economic downturn (in a wider world when Covid is still far more present), and so on.

These are not, repeat not, criticisms of what the Bank has published.  What they have published in a useful exercise, all the more so for the detail they have provided, but it is important to recognise what it is and what it is not.  Especially beyond “level 4”, it can’t be thought of as a GDP forecast at all.

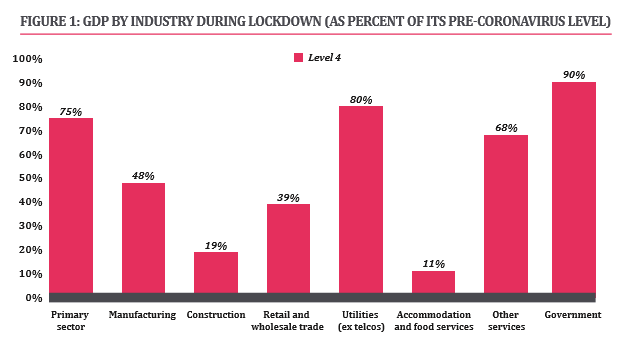
They have a summary chart of the sectoral effects in “Level 4”.

rb sectoral

There is also a more detailed table at the 19 sector level, with their estimates for both “Level 4” and “Level 3”.   I went through the detailed spreadsheet I did on 18 April and compared my numbers with theirs for “Level 4”.   For some sectors, my estimates of losses were a bit smaller than the Bank’s (notably primary) but for others mine were larger. I really struggle to see, for example, how the “Government” sector (Public Administration and Safety) will have been operating at 90 per cent of normal during “Level 4”, or how “Health care and social assistance” will have been operating at 90 per cent, when all elective surgery was cancelled and GPs reported a significant drop in business.   “Education and training” operating at 90 per cent also seems ambitious –  especially as I get emails from my children’s schools telling me they are having to cut back their NCEA credits offered this year (suggesting effective productivity is well less than 90 per cent).

For what it is worth, I’m still comfortable with my 40-45 per cent.  I’d say “time will tell” but it won’t.  For a start, we don’t have much good monthly official data in New Zealand, and Statistics New Zealand seems to have been quite badly prepared for a serious pandemic and is going to really struggle to produce even decent quarterly estimates (especially those productivity losses, even if people have been getting paid).

I don’t have detailed “Level 3” estimates of capacity to compare with those the Bank has put out.  But I’d just reinforce my point: what they seem to be describing is something more akin to capacity than to actual, and the actual level of GDP now may well still be more like 30 per cent below normal even if the Bank is right in saying that in principle it could trade up to 80 per cent of normal.  Few of the scattered aggregate indicators we have suggest anything like that sort of actual rebound –  and my anecdote of the day was wandering past a local cafe this morning offering coffee and food (presumably within the rules) with, at the time, precisely no customers whatever.

What time will tell is what the Reservev Bank and the MPC have come up with in their publications next week.  The Governor has talked in terms of a scenarios focus, and that makes a fair amount of sense, but I hope we will get much detail than (say) the Treasury scenarios document offered, and some richness in thinking about how private sector behaviour might respond, how the severe global downturn will affect us, and so on.  Precise numbers will only take us so far – especially as the Bank may have to choose whether to forecast reality or what SNZ might first publish –  but they should be a framework for something more specific than we have now, and something to compare (one hopes) with whatever The Treasury comes out with in the Budget the following day.

(The Bank’s paper would, however, have been better without awkward injections of commentary about their estimates of the effects on the “Maori economy” – something never defined.  There was, for example, no commentary on the Presbyterian economy, the Asian economy, the left-handers’ economy and so on –  not even the “European New Zealanders” economy.   There is, it seems, no stopping the energetic political signalling, and associated abuse of once-scarce public money, by the Governor.)


Negative interest rates

How long have I been banging on about the potential limitations of monetary policy in the next recession and issues around negative interest rates?  The first such post I could find on the blog was almost five years ago to the day, and as I’ve noted previously it had been a concern for some time before, going back to 2010 in the wake of the last serious recession and then the internal working group I chaired at the Bank when Alan Bollard rightly was concerned about downside risks at the height of the euro crisis.  (That was the report, adopted by senior management, which recommended that steps be taken to ensure that banks could operate effectively with negative interest rates.)

Ken Rogoff has been writing about such issues, and publishing in various prestigious fora, for at least as long.   And Rogoff is a Professor of Economics at Harvard and also served as Chief Economist at the IMF for a couple of years.    He and Carmen Reinhart wrote the book This Time is Different: Eight Centuries of Financial Folly  that attracted so much attention in the wake of the 2008/09 crisis.   As I noted in a post a couple of years ago he and another former IMF chief economist Olivier Blanchard proposed dealing with the lower bound issues by raising inflation targets (the suggestion at the time was to something like 4 per cent), which would –  if successful –  raise neutral nominal interest rates and provide more policy leeway in the next recession.

In the last few years his focus has shifted to addressing the lower-bound issues at source.  There was his 2016 book The Curse of Cash which I wrote about here in which –  among other issues physical cash raises –  he addressed the lower bound issues and proposed to address them in part by progressively removing higher denomination banknotes, leaving in time nothing higher than a $20 note.  More recently still there have been various papers, including last year’s paper (with a PhD student co-author) “The Case for Implementing Effective Negative Interest Rate Policy”.   And there have been a couple of short papers in recent weeks.    There was a piece on Voxeu by Rogoff and LIlley about three weeks ago.  This was the abstract

In the aftermath of the Global Crisis, conventional monetary policy has been constrained by low interest rates in many major economies. This has spurred debates on the possibility of introducing negative interest rates in the monetary policy toolkit. This column uses evidence from the US to show that not only do the markets expect the low interest rates to persist into the future, but they also expect the use of negative interest rates down the line.  Moreover, markets no longer believe that even quantitative easing can bring inflation to target, which leaves very few alternatives for monetary policy apart from negative interest rates.

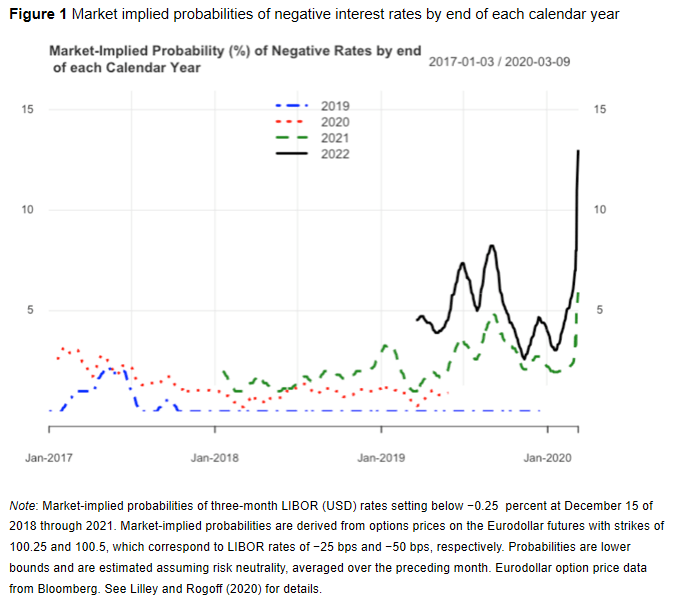
As here, breakeven measures of implied inflation expectations in the US are now well below target.  There is a nice chart for the US suggesting that (at least then) markets there had already moved to put a non-trivial probability on materially negative short-term interest rates in the next couple of years.

rogoff

Focusing on the medium-term implied inflation expectations they note that this

…suggests that the market’s change in beliefs has moved beyond the present crisis, and it now has re-evaluated the extent to which it expects the Fed to be constrained more generally. One problem with such a scenario is that it poses a perverse feedback loop. As the Fed becomes more constrained by the zero lower bound, the expected inflation rate falls, lowering the neutral nominal interest rate, which in turn makes the zero lower bound more binding.

Very much the same point I’ve been making here.

This week Rogoff has a very accessible piece on Project Syndicate (thanks to a reader for drawing it to my attention) under the simple and stark heading “The Case for Deeply Negative Interest Rates”.  His summary

Only monetary policy addresses credit throughout the economy. Until inflation and real interest rates rise from the grave, only a policy of effective deep negative interest rates, backed up by measures to prevent cash hoarding by financial firms, can do the job.

Some of the emphases are a bit different in a US context  (where much of government at all tiers is highly indebted)

For starters, just like cuts in the good old days of positive interest rates, negative rates would lift many firms, states, and cities from default. If done correctly – and recent empirical evidence increasingly supports this – negative rates would operate similarly to normal monetary policy, boosting aggregate demand and raising employment. So, before carrying out debt-restructuring surgery on everything, wouldn’t it better to try a dose of normal monetary stimulus?

More generally

It is not rocket science (or should I say virology?). With large-scale cash hoarding taken off the table, the issue of pass-through of negative rates to bank depositors – the most sensible concern – would be eliminated. Even without preventing wholesale hoarding (which is risky and expensive), European banks have increasingly been able to pass on negative rates to large depositors.

Some issues are relevant to the US and the euro-area but not in same form to us

A policy of deeply negative rates in the advanced economies would also be a huge boon to emerging and developing economies, which are being slammed by falling commodity prices, fleeing capital, high debt, and weak exchange rates, not to mention the early stages of the pandemic. Even with negative rates, many countries would still need a . But a weaker dollar, stronger global growth, and a reduction in capital flight would help, especially when it comes to the larger emerging markets.

In our case, a much lower exchange rate would make a material difference to the fortunes and prospects of the tradables sector.

Rogoff ends

Emergency implementation of deeply negative interest rates would not solve all of today’s problems. But adopting such a policy would be a start. If, as seems increasingly likely, equilibrium real interest rates are set to be lower than ever over the next few years, it is time for central banks and governments to give the idea a long, hard, and urgent look.

From which I’d depart only in replacing that “long” in the final line with a “short and intense” –  this isn’t the time for year-long reviews, but for early and decisive action (as has been managed on so many other fronts in recent months).

There has been a view in some quarters over the last few years that negative interest rates don’t work (in the sense of boosting demand, credit, inflation or whatever) and could actually be contractionary in their effect.  I’ve been sceptical of that, but also inclined to wonder whether results for slightly negative interest rates  –  where there might be threshold effects –  would generalise to deeply negative wholesale and policy rates.   Rogoff links to a recent paper, newly updated last month, by several researchers mostly at the ECB which uses very disaggregated data to suggest that actually negative interest rates in Europe have worked.   Their abstract is as follows

Exploiting confidential data from the euro area, we show that sound banks pass on negative rates to their corporate depositors without experiencing a contraction in funding and that the degree of pass-through becomes stronger as policy rates move deeper into negative territory. The negative interest rate policy provides stimulus to the economy through firms’ asset rebalancing. Firms with high cash-holdings linked to banks charging negative rates increase their investment and decrease their cash-holdings to avoid the costs associated with negative rates. Overall, our results challenge the common view that conventional monetary policy becomes ineffective at the zero lower bound.

The channels they examine look to work a little differently with negative than with positive rates, but not less effectively.

Another central bank with significant experience with mildly negative rates in Sweden’s Riksbank.  A year or so ago, a couple of Riksbank researchers published an accessible treatment of the Swedish experience, from a top-down perspective.    They summarise their results (with all sorts of caveats in the body of the paper) this way

It has been suggested that the response of bank lending rates to interest rate cuts may become weaker when the policy rate passes below a certain level. This column argues that in the case of Sweden, the pass-through of policy rate cuts below zero to the economy has been reasonably good and monetary policy has been effective even at negative policy rate levels.

As all researchers in this area recognise, a big problem is that limited data.  Only a few central banks have had negative policy rates, almost entirely in a single economic cycle, and none of them have taken the policy rate very deeply negative and dealt directly to the ability for big players to convert into physical cash.  So we cannot say with certainty what would happen if we took the – fairly straightforward –  steps that would enable the OCR to be cut to -3 or -5 per cent.  But the signs look fairly promising, whether on the limited experience we have, or  pretty basic economic theory (all else equal, holding New Zealand dollars will typically be much less attractive if NZD assets are earning a lot less than those in other countries).  And the idea of simply letting the Reserve Bank sit on its hands and do almost nothing that matters macroeconomically (hand-waving around big bond purchase programmes is mostly a distraction in macroeconomic terms, whatever value it might initially have added to market functioning).

You’ll recall that Westpac’s economists last week came out picking that the MPC will abandon its firm pledge not to cut the OCR further and go modestly negative later this year.  That would be welcome –  better than the status quo –  but inadequate, and not commensurate with the scale of the adverse economic shock.  In my post the other day I argued that in next week’s Monetary Policy Statement

The MPC on 13 May should:

  • abandon the “no change for a year pledge”,
  • cut the OCR to zero,
  • announce that the OCR will most likely be cut further in June (which would get many of the benefits immediately, but give a little time if there are some real system issues re a negative OCR), and
  • commit to have in place by June robust mechanisms that for the time being removed, or greatly eased, the current effective lower bound on short-term wholesale interest rates.

As it happens there have been a few other contributions on monetary policy locally this week.

Yesterday morning I heard the local chief executive of Westpac on RNZ talking about all the system and documentation changes that would be needed –  one has to assume he was talking about his bank, as he was quite specific in some cases –  to cope with negative (retail?) rates.  Unfortunately, the interviewer simply took Mr McLean at his word, and didn’t either challenge him on just how vital these things were or why – with 10 years global notice – a big bank like his appeared to have done nothing before now. (My initial reaction was a bit like that to the Governor –  if Mr McLean had spent less time championing all the right-on causes he and the Governor are so fond of –  especially climate change –  and actually managed his bank, his borrowers might be rather positioned now.)  Of course, from a public policy perspective, the bigger question is about years of failure from the Reserve Bank –  under Wheeler, his “acting” replacement, and more recently under Orr –  to ensure that the banking system could readily cope with the sort of cuts to the OCR that it was easily foreseeable some shock soon might make necessary.  In Orr’s case, it is particularly inexcusable given that big interview he gave eight months ago articulating why he favoured negative interest rates as a policy option.  “Saving the world” might seem more glamorous, but stabilising the local economy and keeping inflation target was actually his job.

Then there was a strange comment reported from the Leader of the Opposition.

Bridges said fiscal policy, rather than monetary interventions from the Reserve Bank, would need to do the heavy lifting in the Covid-19 response.

That clearly isn’t true –  it is simply a choice by the MPC to do nothing, and by the government which does not use clear legal statutory powers to compel them to act differently.  Sadly, it is still too much of the conventional wisdom.   I’d probably have forgotten about except that this morning Bridges is reported as worrying about risks of too much public debt being taken on.  Macro policy squares that circle –  delivers accelerated recovery without lots more debt –  by using monetary policy: yes, deeply negative rates in this context, to provide the support and stabilisation into the recovery towards full employment.  Such, it seems, is the power of conventional wisdom and the fear of successive Oppositions –  Robertson in Opposition was quite as bad, in less important circumstances –  to challenge anything that the (on their record) not-overly-capable RB/MPC does.

And finally, another reader this morning sent me this clip from a recent BNZ research report, previewing next week’s MPS.

We would strongly argue that lowering the cash rate further would provide almost no assistance to the economy. The cost of debt is the last thing on anyone’s mind now. The lack of availability of debt might be a concern and, for many, the lack of income to repay debt will be a pressing problem. Pushing interest rates sub-zero will do nothing to ameliorate those issues. Moreover, even if the cash rate was to go negative, it would not be fully passed on to borrowers as the banks will still be funding themselves with positive interest rates. Term deposit rates are excruciatingly low for many as it is. The last thing the household sector would want is zero rates across the board. And even at zero, it would mean bank funding costs well above the cash rate.

The research report is headed “RBNZ Can’t Save the World”, to which one can only agree.  What it can do –  what it is charged with doing –  is keep inflation and inflation expectations at around 2 per cent, and support as rapid as possible a return to full employment.  At present, those two goals are tightly aligned, given how high unemployment is forecast to be, and how far medium-term inflation expectations have fallen.

Perhaps it as well to remember here that the BNZ has been the most consistently “hawkish” –  pro tightenings, often uneasy about easings –  of any of the local banks for many years.  That has made them more wrong than most.

But that specific extract above simply makes little sense.  Sure, most businesses would probably prefer a quick and full rebound in demand/activity over a fall in their debt interest rate, but it isn’t as if the two concerns are in conflict –  in fact, lower interest rates and lower exchange rate will, in time, do their bit to support a stronger recovery.  And despite the bank economist’s claim that no one much cares about interest rates, the evidence is pretty clearly against that in the very low interest rates being offered on the government’s scheme (and the Opposition’s proposal yesterday).  In fact, the worst credits in the country –  those who can’t raise funds elsewhere –  get the cheapest rates, while deposit rates –  in the middle of a savage slump – remain positive in real terms, barely down this year, sending all the wrong signals.  And then there is the distraction: as BNZ knows only too well, if the OCR were taken to -0.5 per cent –  as Westpac suggests will happen and should happen –  retail rates, deposits and lending rates, would be still positive.  For now, negative retail rates are some way away.

And if, perchance, depositors were reacting negatively to, say, 1 per cent term deposit rates, what are they going to do instead?  Spend the money?  Well, that’s good – that is monetary policy working.  Shift it to another currency? Well, that’s good –  a lower exchange rate would be monetary policy working.  Seek to buy another asset?  Well, that’s pretty good too –  increasing both wealth effects and Tobin’s Q effects encouraging new investment, so that’s monetary policy working.  And, of course, in aggregate it is not as if deposits are going anywhere –  it is a closed system, with a floating exchange rate.  Your purchase is my sale etc etc.   Oh, if it makes people worry a bit about future inflation, that’s good too –  that’s monetary policy working to hold up, or lift, inflation expectations to something like target.

Like Ken Rogoff, I think the case for deeply negative interest rates now is pretty overwhelming.  It would ease the pressure on fiscal policy, it would support the tradables sector (on which our future prosperity rests), it would ease servicing costs on existing borrowers (and bring market rates closer to rates the government itself is happy to lend at).  There is nothing particularly odd about negative rates, at a time when savings preferences are high and investment intentions are very weak –  the interest rate simply serves to reconcile the two, while getting the economy towards full employment –  and in the particular circumstances of New Zealand, a materially negative OCR would be needed to even get retail interest rates close to zero.  As it is, recall that New Zealand now has materially higher retail rates than Australia, despite the deeper economic slump. That is a choice –  an anti-stabilisation choice –  made by the MPC, blessed by the Minister of Finance.


The Douglas-MacCulloch plan

I was going to attempt to articulate today where I agreed and disagreed with both the New Zealand Initiative’s Bryce Wilkinson and Social Credit on money, banking, fiscal policy etc (Social Credit having taken out a half page advert in Saturday’s Herald to attempt to rebut Bryce’s recent Herald op-ed, itself drawing on a longer recent Initiative publication).  Perhaps tomorrow.

But in this morning’s papers I saw reference to a new plan (and/or critique of other plans) for policy in responding to the economic challenges of Covid, under the joint authorship of former Minister of Finance Roger Douglas and Auckland University economics professor Robert MacCulloch.  MacCulloch kindly sent me a copy of the ten page underlying paper which goes under the title “In a New World, New Thinking is Required: Why Prioritization of Resources is Crucial to New Zealand’s Economic Recovery in the Wake of Covid-19”.  MacCulloch’s Herald op-ed puts it more pointedly and succinctly under the headline “The time has come for trickle-up economics“.

Here is their Executive Summary

The Covid-19 outbreak has not only precipitated a health emergency, but also an economic crisis, unparalleled in modern history.  For New Zealand to emerge from that crisis in a relatively healthy state, the Labour government will need to provide a clear framework for recovery, implementing policies which clearly prioritize those most affected by the societal and economic lockdown necessitated by the outbreak. To date, such prioritization has been lacking, with the Wage Subsidy Scheme unfairly advantaging big business and the professional elite, at the cost of money and resources which could have been better directed towards assisting the newly unemployed – namely workers, their families, and small business owners.

Ultimately, poorly targeted support in the form of helicopter payments, wage subsidies, or broad-based tax cuts (such as a moratorium on GST) is wasteful, and will only serve to entrench inequalities that existed prior to the pandemic.  Equally, the time and costs inherent in planning large-scale new infrastructure projects – and the fact that they offer little practical help to the majority of workers who require help now – means that they should not be regarded as a panacea, aiding economic recovery.

Instead, clear, innovative policies, which not only prioritize those most in need, but which also lay the groundwork for further social and economic reform in the medium to long term, are required.  For workers and their families, support can be offered via the mechanism of special risk accounts, tailored to meet their individual needs.  For small business, help can be provided by facilitating conversations between businesses, landlords, and banks, as well as providing – upon the provision of an approved business plan – forgivable government loans.

Finally, to help manage the recovery, and ensure our younger generations are not saddled with debt, the government must also identify, and eliminate, unnecessary spending, privilege, and waste.  It can find an extra $15 billion per annum by doing so, contributing to the recovery in the short term, and – more generally – to implementing wider scale reform once the immediate crisis has been put behind it.

It is an interesting argument.   If it weren’t already a sadly-debased word, one might almost be tempted to label it “populist”.  Douglas and MacCulloch don’t seem to have a problem with the idea of a wage subsidy scheme per se, but object to big businesses having claimed it.

Whilst the scheme, which already comes at a cost of $10 billion, has undoubtedly provided short term support to those who needed it – workers and small businesses – it has also been used to prop up corporate monoliths and institutions who should have been left to fend for themselves or – at the very least – should have received assistance in the form of a loan, instead of a handout.

But it isn’t clear why they think small businesses are worthy but big businesses (and the employees of the respective businesses) aren’t.     Big businesses can often operate on very tight margins, and plenty of small businesses have had no special problems at all.

Personally, I’m not persuaded of the merits of how the wage subsidy was designed: as I’ve noted before the roots were in that perspective from months ago when the government thought the coronavirus issues were about China and the slow recovery of New Zealand exporters to China (including tourism).  You had only to affirm that your revenues would be down 30 per cent in one month to get three months of wage subsidies, even though the “Level 4 lockdown” – the worst, government-imposed, period for many – was only about five weeks.   But the large vs small company distinction simply doesn’t make a lot of sense to me, and (relative to need) there is no obvious reason why large companies should have more resources to tap than small companies.

My own unease about large companies is the special unit the government has set up in The Treasury to assist big companies.  Since the initial Air New Zealand bailout not much has been heard of its activities, but the risk is that prominent, persuasive and well-connected big firms will end up much better treated than the small firms.  Partly as a result, as far as possible, I favour one model for all.   Done openly and transparently (there being all too little of that, not just around eg Cabinet papers and associated advice, but I think I saw an article recently noting that the deeds under which the Business Finance Guarantee Scheme are operating are also not being disclosed).

In many respects, however, the focus of the Douglas/MacCulloch paper is more forward looking from here.

They start with a point on which I totally agree with them

To date, there has been little sense that the government has a cohesive economic plan to take us forward, either in terms of building the solid foundations required to help navigate our way out of the crisis (the short term response), or in terms of preparing the policies that will help New Zealand not simply recover, but stand stronger than ever (the medium to long term response).

They set out quite a lengthy list of “objectives for reform”, most of which I’d agree with, before moving on to some specifics, noting that

Right now, the protection of individual New Zealanders and their families must be the government’s number one priority.

They propose moving away from a model that has worked by funding employers to funding households/individuals directly

The mechanism for such support would be a special risk account, tailored to meet the specific needs of individuals and their families (if they have one). It would operate as follows:

• Step One: A company or employer makes it clear in writing that they cannot support an employee during the crisis or in its immediate aftermath.

• Step Two: The employee is either made redundant, or temporarily underemployed/unemployed, with the expectation that they will be re-employed once the crisis has passed and the business – inasmuch as it is possible – resumes its normal footing.

• Step Three:  A special risk account is set up and documentation downloaded into that account for the employee to fill out.  This documentation will help him/her identify any special support they require, including meeting mortgage or rent payments, as well as family, sickness, or any other (pre-qualified) payments.

• Step Four: Government provides payment (for a prescribed term and up to a specified limit) directly into the special risk account. If the account holder is already receiving unemployment support, which will be the case in many instances, then this payment will top up that support.

It does seem materially more resource-intensive than the wage subsidy scheme, so could not have been put in place at scale as quickly.  I suppose it has the advantage of directly getting money in the hands of households, but then the established welfare system does that anyway (complete with supplements like the Accommodation Supplement).

The authors argue

By tailoring assistance to individual workers, the government can ensure that the support it provides meets specific needs, in a way that poorly targeted helicopter payments, subsidies provided to businesses, or even broad based tax cuts (such as a moratorium on GST) cannot.  Not only that, such support also provides workers with a measure of respect, as well as a sense of autonomy and self-responsibility, that can only help to engender confidence, both at an individual and societal level.

There is something to the first sentence, relative (say) to those favouring lump sum handouts to everyone. On the other hand, some of the other ideas they seem to be pushing back against are more about demand stimulus in a recovery phase, rather than dealing with the direct income support issues.

The second section of the plan is about small business.  It begins

Small businesses are the lifeblood of New Zealand’s economy.  Sadly, not all of them are going to survive the health imperatives of the Covid-19 outbreak, which saw their closure.  It is important, however, that as much as can be done, is done, to help viable businesses recover.  In the short term at least, this will require other interested parties to step up, including banks and landlords, proffering help to small business owners by sharing their burden.

Not too sure about that “lifeblood” bit –  there are lots of them but the smaller number of much larger businesses also employ a lot of people and are the vehicles through which much GDP is generated.  But set that to one side now.   What about those “banks and landlords”?

In such an environment, the hard-nosed approach adopted by some landlords is short-sighted.  If a small business owner cannot meet the costs of a lease, and is forced to relinquish his/her business, then the property is likely to sit empty, with little prospect that it will be leased again in the short term. Much better – and more realistic – is the approach taken by groups like Westfield, who have signaled their intent to drop rents in their malls.

One might well agree with all that – and it would be consistent with an interesting post from Bob Jones a day or two back from his perspective as a large landlord –  but it isn’t really clear what it has to do with the government.  After all, tenants and landlords agree on how to allocate risk within their relationship, and they can also agree to vary those provisions, so what role for the government.

Similarly, the banks

 Here, the banks have an important role to play, coming to the party by negotiating adjustments to mortgage payments that reflect the new economic realities of life, post-Covid.

And, of course, banks have put in place residential mortgages “holidays” (delayed payments) and put a lot of commercial customers temporarily onto an interest-only basis.   But again, if customers have taken a fixed interest rate that was an agreed commercial risk-sharing arrangement.  And if they are on a variable rate, it might be better to look to our central bank, which sets the short-term interest rates that influence variable loan rates –  and which, thus far, refuses to cut them any further come what may.  Surprisingly, in a piece on macrostabilisation and recovery, monetary policy isn’t mentioned at all.

Douglas and MacCulloch go on

Of course, simply reducing rents, or even imposing a ‘rent holiday’ for a couple of months, will not be enough to save many businesses.  It is here that the government has a role to play, supporting viable businesses in the form of forgivable loans.

And their plan?

The following, four-step strategy, is suggested as a way of supporting small businesses in trouble:

• If a business is unable to meet the costs required to open its doors again, or faces short-term difficulties, it will be required to meet with a business consultant, accountant, or government appointed consultant.

• As part of the consultation, it will be determined whether or not the business has a viable future.  If a path forward can be found, then a business plan will be created.

• In the first instance, this plan will form part of any conversation that takes place between the business owner and his landlord, as a means of setting new, realistic rent payments that will help keep the business afloat.  If necessary (and in the manner outlined above), the landlord’s bank should also be party to this conversation.

• Should rent mitigation not be enough, the business owner can also approach the government for a forgivable loan.  An assessment will be made at this point about the viability of the business plan, and – if successful – a tailored loan will be provided to help the business recover.

It should be noted that the intent of this plan is not to provide loans to companies that have access to plenty of liquidity and other sources of capital.  Rather, given the large sums that will inevitably be involved, the plan is for the benefit of those businesses that have been unduly affected by the lockdown and which need our support in the short-term.

It isn’t clear what the criteria would be for forgiveness?  Presumably many businesses will end up defaulting anyway –  as under the government’s IRD scheme for SMEs –  but is the debt forgiven if your business survives or if it fails?

What is also striking –  and this is a point I’ve made about many schemes –  is that there are likely to be many businesses that, in principle, could be viable if we could simply wipe 2020 from the calendar and resume life in 12-18 months time.  But in many cases it simply will not be worthwhile –  the business will never generate enough –  to justify taking on a lot more debt now.

The third strand of their plan is under the heading Infrastructure.  They are sceptical of large-scale infrastructure projects

Put simply, large scale infrastructure projects are not only expensive, they take a long time to plan and implement; time we simply don’t have right now.

Mostly, as I’ve written elsewhere, I agree, although not always for their reasons (I rather doubt availability of labour is going to be a big constraint).    They are keener on the housing side

If the government is to institute a big infrastructure push, then housing is perhaps the one area where this makes sense.  It is an industry that employs a large number of people, and new housing stock can help resolve a long-standing social and economic problem confronted by many New Zealanders – the inability to afford their own home.

Perhaps, but as they surely know land prices –  not houses –  are the biggest obstacle.  Not in the paper itself, but included in a Stuff article on the paper, Sir Roger is quoted thus

One area where there should be increased stimulatory spending is housing. In this area, Douglas described something like a supercharged KiwiBuild paired with planning reform and a shared-equity scheme.

Douglas said the key to getting housing right was “making a large quantity [of houses] available”.

The Government had to go into section development, while making sure land was released for building by reforming planning laws. There was plenty of land out there, but not enough capital to develop it.

Low-income people could be helped into housing through a shared-equity scheme, where the Government would take on part of their mortgage.

When asked how his state-backed building scheme would succeed where KiwiBuild failed, Douglas said it was a matter of getting the right people involved to notch up big productivity gains.

Among other issues one could raise, it isn’t fully clear to me how they can tell big business to look after themselves because there is plenty of capital available, while telling us the problem around housing is lack of capital to develop land.   And I’m not sure the label KiwiBuild should really ever be used again for something an advocate wants taken seriously.

The penultimate section of the paper is headed “Where Will the Money Come From?”, which doesn’t really seem to distinguish between the large deficits that are more or less inevitable (even on their reckoning) right now, and the fiscal prospects in say five years time (which don’t look bad at present to me, especially given our low starting level of debt and low debt service costs).    Anyway, their specifics are

It is also why we must look to eliminate privilege and waste, both of which have been part of New Zealand’s economy for too long. In total, there are $15-16 billion dollars of savings we might make per annum, simply by removing unnecessary government spending:
1. Ending Waste: By removing Kiwi Saver tax breaks and subsidies, by ending future government contributions to the New Zealand Super Fund, by retargeting income derived from those funds, and by reducing the excessive Votes available to government departments, we can quickly access approximately $9 billion per annum

2. Eliminating Privilege: Unnecessary privilege is entrenched in New Zealand society.  By ending corporate grants and tax breaks, by stopping the Provincial Fund, by removing high income families (approximately 15% of the population) from access to Working for Families and Winter Energy subsidies, and by ending tertiary education grants for students other than those from low capital and low income families, we can make further savings around $7 billion per annum.

That is a bit of a mixed bag.  They aren’t specific on the “corporate grants and tax breaks” they want to end, although if that includes film subsidies I’d certainly agree with them.  But not all these savings are real savings, except within the current government accounting framework.  I might (do) agree we shouldn’t be putting money into NZSF, but it is still government money – it is why when I talk about net debt I always use an NZSF-inclusive figure.  Stopping contributions might free up some cash, but cash isn’t the real constraint here.  Similarly, they might want to take NZSF earnings straight into the Budget, but it doesn’t change the substance – the earnings still improve the Crown’s position.    I could happily sign up to a list of perhaps 20 government agencies to abolish entirely, but……sadly or otherwise, those aren’t where the big bucks are.

Douglas and MacCulloch end their paper with a section on “Building a Better Future”.    Like me, they are energised by the continuing relative decline in New Zealand’s productivity performance (and, I think, fearful that things may only worsen relatively in a post-Covid world).  Douglas and MacCulloch have written previous papers about far-reaching welfare reforms –  I wrote (sceptically) about one such presentation here –  and it is clear that that is still a focus now.  They end this way

In an upcoming paper, the authors will examine in more detail what has gone wrong, why we should immediately set up working committees (SOE style) to make recommendations for the future, how we can free up an extra $20 billion via vastly improved productivity outcomes thanks to structural social welfare reform, and how we can use that money (along with the $15 billion previously freed up thanks to the elimination of waste and privilege) to institute innovative policies in areas as diverse as health, housing, education, welfare, personal tax, company tax, and superannuation.

Ultimately, we have a choice. We can either muddle through as we are – relying on policies that haven’t worked since the 1950s and which are ill-suited to our quickly changing world – or we can opt for a reset, introducing social and economic policies that will make New Zealand not only a richer but more equitable place to live; a country where every New Zealander has the chance to take control of their lives and secure a better future for themselves and their families.

It will be interesting to see their fuller plans.  I wholly agree on the need for something quite different, although am more sceptical than they are that the welfare system as currently configured can explain any material amount of our continuing long-term relative economic decline.

I ended that earlier post this way

In many respects, the saddest line of the day was one made almost in passing by Professor MacCulloch. He told us that he administers a fairly generously-funded visiting professorship at the University of Auckland, which aims to bring in distinguished or innovative, leading international thinkers to contribute to policy debate and development in New Zealand. But the last three people who had been invited had declined the invitation to come. There was, so far as they could tell, nothing bold or interesting on the table here, no real prospect of significant reform, or interest in it from our political leaders.

Things were very different, in that regard, 20 or 30 years ago. It is not as if, sadly, we have in the interim solved all our problems, and re-establishing a position as a world-leading economy, or a world-leader in dealing with the various social dysfunctions. We just drift, and allow our elites to tell themselves (and us) tales about how everything is really just fine.

I guess at least we know things aren’t fine right now, but the contest ahead at present seems to be mostly between those who think New Zealand as it was last year is fine and those keen on building some version of new inward-focused Jerusalem that does not involve successfully earning our way in the world.

As for me, I still think some variant of my “national pandemic insurance” approach is the best – and most equitable – way to frame and think about immediate assistance, continue to think that monetary policy should have a key stabilisation, support and recovery role, and that we need to be looking outwards much more, with activity led from the private sector if we are (a) to get back to full employment as quickly as possible (not repeating the very slow post-2009 fall in unemployment) and (b) have some chance of finally building a more productive and prosperous New Zealand, reversing the gaps to much of the rest of the advanced world that have opened up and kept widening for decades now.



Two recent contributions

For anyone interested, here is the link to my discussion with Prof Steve Keen on Jim Mora’s show on Radio New Zealand yesterday morning.    Despite the RNZ headline, the trans-Tasman travel “bubble” idea wasn’t any sort of focus, although Keen and I have quite different views on the issue beyond the very short-term.  The thrust of my policy prescription post-Covid is outward to the entire world as much as we can, on the basis that there is no credible alternative path to a more productive and prosperous future.  Keen, by contrast, favours a future in which New Zealand and Australia together trade as little as possible with the rest of the world.   It seemed like a pretty bleak future to me, but at least he was honest enough to acknowledge that his preferrred path is one in which as nations we would be materially poorer in future, for the environment.

Sadly, the discussion did not get to Keen’s “modern debt jubilee” proposal that I discussed in a post last week.

The Small States and the New Security Environment (SSANSE) project is a collaboration of university researchers in a number of countries, including (in New Zealand) Canterbury University’s Anne-Marie Brady.   Here in New Zealand, the initiative seems to encourage research and debate on a wider range of issues than the programme title itself might imply, and they have a page of contributions on a range of policy issues from quite a range of authors, under the heading “Pop-up Think Tank“.  Anne-Marie has launched what she calls a Commission for a Post-Covid Future, and invited various people to contribute short papers.

As her tweet says, mine is apparently the first such paper to be released, in an abbreviated form on The Spinoff this morning.  (The fuller version should eventually be on the SSANSE site, but here it is as well

Rebuilding New Zealand’s shattered economy post-Covid

(UPDATE: More nicely formatted on the SSANSE site here)

From the first page

post-covid 1

and from the body

post-covid 2

Macro policy has a big part in getting back to full employment

post-covid 3

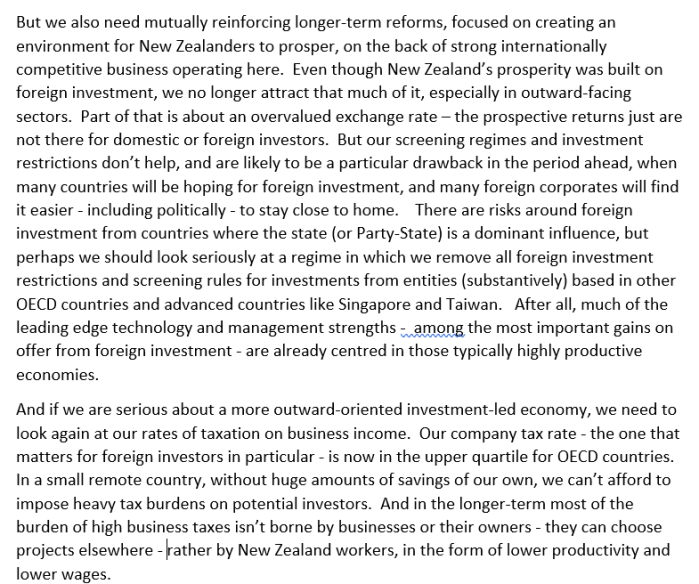
And longer-term, there are bits my friends from the market-oriented right will like

post-covid 4

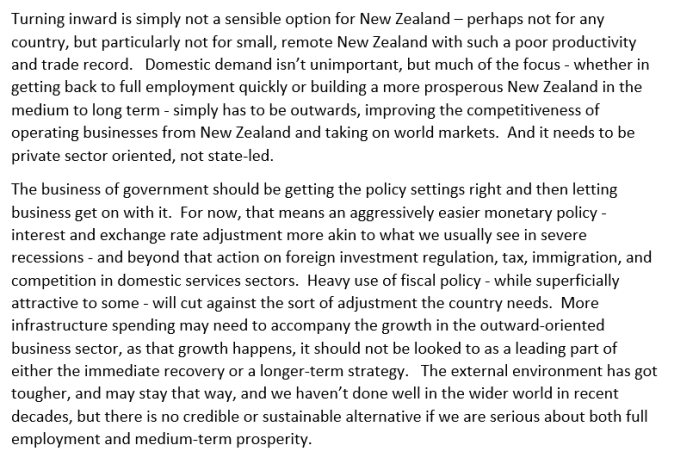
and a bit many of them will deplore

post covid 5

ending this way

post covid 6

For anyone doubting that “we haven’t done well” bit in the last few lines, I refer you to the charts in my post on Saturday.

Oh, and the allusion to the once-upon-a-time campaign promise to “restore New Zealand’s shattered economy” was conscious and deliberate.  They had good intentions too, even did some useful reforms, but they wouldn’t embrace the outward-oriented market-led approach that the situation really demanded.  In many respects, our starting position now is quite a bit worse than it was then.


New Zealand: the foreign trade failure

To have listened to Winston Peters’ speech in Parliament the other day –  which wasn’t all as bad as the media reporting had led me to believe – or the joint Herald op-ed from the New Zealand, UK, Australian, and Singaporean trade ministers, you might have supposed that New Zealand’s was some great foreign trade “success story”.  I put it in quote marks because of course Winston Peters –  our Foreign Minister –  seems to want to undo some of that alleged “success”, seeking “far greater autonomy for New Zealand”.  Here is the full relevant quote

Now, New Zealand First is resolved that our future economy will have these features about it, because they’ve learnt something. One: far greater autonomy for New Zealand. In short, if we can grow it or make it at near competitive prices, then we will grow it or make it, use it or export it, rather than use valuable offshore funds importing it.

Some mix of mercantilism  (more exports good for their own sake) and insulationism (less international trade all round).

And here was a key quote from the article by David Parker and his peers

We are four independent trading nations who have derived success by operating globally. Almost two-thirds of Britain’s economy is made up of trade. One in five Australian jobs is trade related. In New Zealand that number is one in four. Nearly two-thirds of Singapore’s GDP is generated by external demand.

Success story? That would be the country that has spent 70 years slipping, sporadically but decisively (never really interrupted) down the OECD productivity league tables.  Productivity growth, after all, being the main basis for improved material living standards, and for many non-material options.

Here is foreign trade as a per cent of GDP (average of imports and exports) for each OECD country for the latest calendar year the OECD has data for (mostly 2019).

foreign trade as % of GDP

I use foreign trade (imports and exports) to make the point that, for a whole economy, we mostly export to import (some of vice versa as well).  But we are also fourth to bottom if one looks as exports alone.

Perhaps you think that doesn’t really matter much; after all, much richer Australia and the United States have lower trade shares than us.  Unfortunately for that story, larger countries tend to do a lot less foreign trade (as a share of GDP) than smaller ones –   there simply are lots more home markets for firms in the US – and even Australia has a population five times our size.

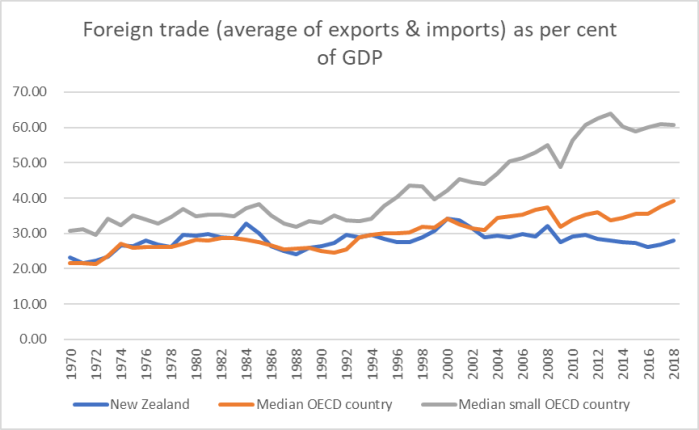
Ah, but we opened up our economy decades ago –  all that stuff Winston Peters lamented much of –  and we’ve signed all those trade agreements ministers and officials like to boast about.  Surely, then, we trade more heavily than we used to, surely we’ve improved our relative performance?

foreign trade since 1970

But no.    New Zealand’s foreign trade now is a bit less (share of GDP) than it was in 1980, and if we started behind the other small countries, we’ve lagged further behind, especially this century.

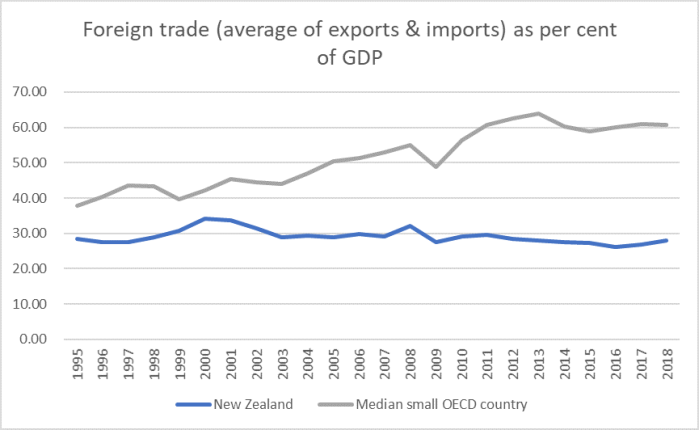
And since the OECD only has data for all countries since 1995 here is the NZ vs small countries comparison just since 1995.

foreign trade since 95

I suppose at least the gap hasn’t widened further in the last five or six years.

And then people (reasonably) point out that in some countries –  notably in Europe –  there is a lot of cross-border trade in partly-assembled products.  That is a plus for those countries, whose firms really can gain by specialisation in specific aspects of a production chain, but it does inflate the gross foreign trade numbers.

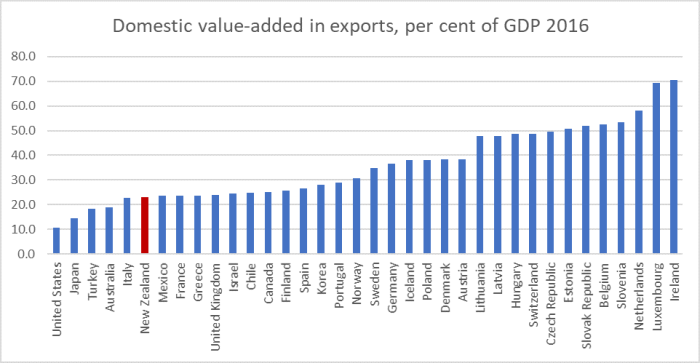
Fortunately, the OECD has developed indicators of the amount of domestic value-added in each country’s exports  (there is a range of other indicators in the value-added database as well, but here I’m just going to fall back on exports).  In some (particularly central European) countries only just over 50 per cent of gross exports represent domestic value-added.  In New Zealand (and Australia and the US) that share is close to 90 per cent.

So how does domestic value-added in exports look as a share of GDP across the OECD countries (these data are available only with quite a lag, so the latest numbers are for 2016)?

value added exports

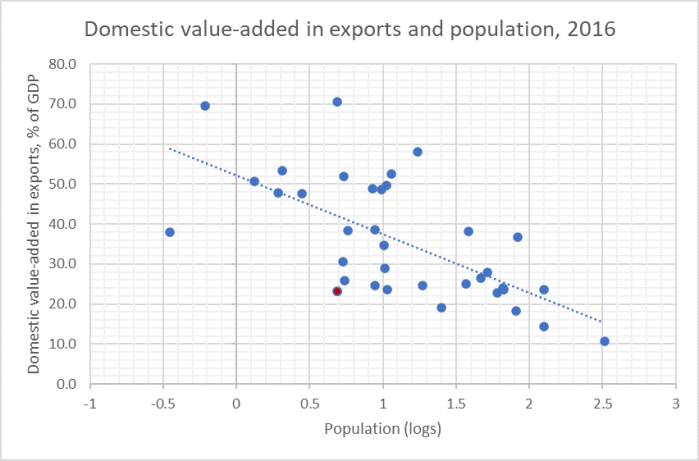
It lifts New Zealand slightly up the league table, but all the countries below us have much larger populations –  and domestic markets –  than we do.  By contrast, all the countries to the right of the chart are small (or in the Dutch case just a bit above small).  And of the small countries – 12 million or fewer people (from where there is a step up to the Netherlands) our population is pretty close to the median.

dom value add and popn

It isn’t the tightest relationship in the world –  there is a lot else going on –  but the point that small countries tend to export (and import) more is pretty clear.  And New Zealand –  red dot –  stands out well below the line.

Our trade performance has been –  is –  woeful.  We simply don’t export (or import) much for a country as small as we are. In fact, not many countries –  even very large ones –  export/import less than we do as a share of GDP.

So the self-congratulatory lines that David Parker (and MFAT officials, and a succession of previous National trade ministers) run is deeply flawed.  But at least, in some sense, their hearts are in the right place, seeming to recognise that a more outward-oriented New Zealand is the only sustainable path to much greater prosperity.  From Winston Peters, on the other hand, the idea that we should be importing even less –  in a small country that already imports the fourth lowest share of GDP in the entire OECD –  is just headshakingly bad.

(If perhaps not quite as bad as Steve Keen who proposes that New Zealand and Australia are ideally placed to be some sort of long-term “trade bubble” –  doing as little as possible, even beyond Covid –  with the rest of the world, as if we’ll suddenly become a major market for coal, LNG, and iron ore and they will suddenly become a leading market for dairy, lamb, and export education.)


Looking towards the MPS

It must be a busy busy time in the upper ranks of the bureaucracy and their political masters as they rush to complete the Budget –  due on the 14th –  and whatever schemes, plans, and campaign promises the governing parties have in store for us.  Between the three parties that make up the current governing majority, it is sadly hard to think of a single policy proposal in the last couple of months that might actually improve New Zealand’s woeful longer-term economic performance.  Indeed, the risk seems to be that the three parties between them have in mind something more akin to a Great Leap Backwards.

But it is policy deliberation time at the Reserve Bank too.  Their next Monetary Policy Statement is due on the 13th.  In many respects, it should not be very interesting.   After all, only little more than six weeks ago the Monetary Policy Committee firmly pledged to not change the OCR at all –  no matter how bad things got – for the coming year.   Quite possibly, the MPC will decide to increase its bond purchase programme, but if you think that will make much difference in macroeconomic terms, I’m sure vendors could interest you in all sort of dodgy deals (bond purchases aren’t dodgy per se, but just don’t achieve much useful and are mostly political theatre here in the current context).

What the Monetary Policy Committee should be doing is quite another matter.  When they made that rash commitment not to cut the OCR any further, no matter what, for at least a year, the Governor was still in some sort of alternative reality: at the press conference after the announcement he was refusing to concede that New Zealand would necessarily experience a recession, and seemed to have no conception of what was already breaking over the world and what was about to break over New Zealand.  He wasn’t alone –  this was, after all, still in the days of mass gatherings that even the PM was keen on –  but he and his Committee are the ones charged with the conduct of monetary policy (I was going to say “responsible for monetary policy”, but the Act is quite clear that the Minister of Finance shares that responsibility).

The economic situation has got a whole lot worse since then.   And that is so even if you are optimistic that New Zealand might soon emerge to the government’s “Level 2” –  whatever that will specifically mean by the time we get there.  Apart from anything else, the rest of the world –  including China –  is in the midst of a very severe economic downturn.  Recall 2008: there wasn’t too much initially wrong here, but a very sharp global downturn still had big adverse ramifications for us and our economy, that took years to recover from.

And with the deterioration in the economic situation, confidence that the Bank will deliver on the inflation target the government has set for it has also drained further away.   That was a risk that greatly concerned the Governor only six or eight months ago when the MPC acted boldly last year.  It should concern him/them much more now when are actually in the midst of a savagely deflationary shock (globally).

Westpac’s economics team had an interesting note out earlier in the week  in which they noted –  correctly in my view – that

In our assessment, the RBNZ is going to have to deliver much more monetary stimulus.

They still seem to be believers in the bond purchase programme but argue that even after an increase in that programme

 In our assessment even more monetary stimulus will eventually be required.

They now expect that the Reserve Bank will move to a modestly negative OCR,  in November.

As they note, there are two possible obstacles.  The first is this claim the Bank keeps making that “not all banks’ systems can cope with negative interest rates”.   Westpac –  being a bank I guess-  seems to think this is some sort of adequate excuse.  I certainly don’t.  Even allowing for the Governor’s utter negligence in not having ensured all systems were in place  –  the Bank having been aware of the possibility of negative rates for years – it is simply inconceivable that any significant financial institution can be unable to cope with the sorts of modestly-negative OCR levels Westpac is talking about (-0.5 per cent).  Perhaps they and the Reserve Bank really have been remiss and some banks’ retail systems or documentation aren’t really positioned for negative retail rates, but with term deposit rates above 2 per cent and lending rates a lot higher than that, negative retail rates simply aren’t a material issue at present if the OCR is only going to go to -0.5 per cent.   We need the additional monetary policy support now, not months from now when the Bank and the banks might finally have sorted things out.   Institutions that might not be able to cope should simply be left exposed.

And Westpac again

The second impediment is that lowering the OCR this year would break the RBNZ’s commitment to keep the OCR at 0.25% until March 2021. The RBNZ could probably hold its head high by pointing out that the Level 4 lockdown was a truly extraordinary event, and we doubt they would come in for much criticism. However, any move to break an earlier commitment would have to be carefully explained and justified.

I don’t think any of that makes much sense.  If the Bank on 16 March didn’t realise the risks ahead of them –  lockdowns weren’t exactly unknown globally by then, and a sharp downturn was on its way anyway –  the MPC members simply aren’t fit to do their job.  Of course, they could shamefacedly say “Oops, sorry, looks like we made a pretty bad misjudgement, and we now need to change course”, but actually acknowledging error isn’t the official style, let alone Orr’s.  And as for “carefully explained and justified”, well maybe, but Orr’s style so far has been nothing like that  –  we’ve just seen one lurch after another (recall the 50 basis point cut last year, not foreshadowed at all) where they mostly make up the rationalisations after the event.

We get to a similar bottom line I guess….and I suppose Westpac has to be more respectful of the Bank or else senior officials might (a) stop talking to them, and/or (b) complain to the chief executive.

Westpac expects that Bank will walk away from the “no cuts for a year” line in August, preparing the way for an actual cut in November –  six months from now.

A journalist asked me yesterday if I thought they would abandon the pledge in May. My response then was a quick no –  it seemed too close to when the pledge was first made, and to walk away at the first opportunity would deeply degrade the value of any future forward guidance commitments the MPC might offer.   But on further reflection I wonder if there isn’t more chance than I initially thought that they will simply walk back much of the “no cuts” commitment this month.  After all, their messaging and policy haven’t been consistent and discplined through time in the MPC’s first year, so why suppose it would start now?   And, realistically, against this economic backdrop it just looks silly to continue to pledge not to cut the OCR come what may.   After all, some journalist might actually ask hard and persistent questions challenging the Governor to justify that bizarre pledge (not likely, but you never know), and that might be a challenge even for our loquacious Governor.   Then again, maybe we would simply get handwaving and more claims about all the good the bond purchase programmes have done –  bluster over analysis

And there seems to have been something of a change in market sentiment too.  The 90 day bank bill rate has fallen by 17 basis points since mid-April and is now at a level consistent with markets pricing a reasonable probability of an OCR cut at some point in the next three months.  Longer-term rates are falling too –  the 10 year nominal government bond yield this morning was a mere 0.69 per cent.

But long-term bond yields don’t really matter much in New Zealand –  to anyone other the government,  It isn’t as if there are lots of long-term fixed rate mortgages repricing off the 10 or 15 year bond rates.

And if wholesale interest rates have been falling this week, the exchange rate hasn’t been.  In fact, yesterday’s reading of the TWI was less than 5 per cent below the December average –  and in those far flungs days people were getting upbeat about economic prospects here and abroad this year.    Back on 16 March, the Governor claimed the exchange rate was doing its “buffering” job…….but not really very much at all, relative to the scale of the shock.

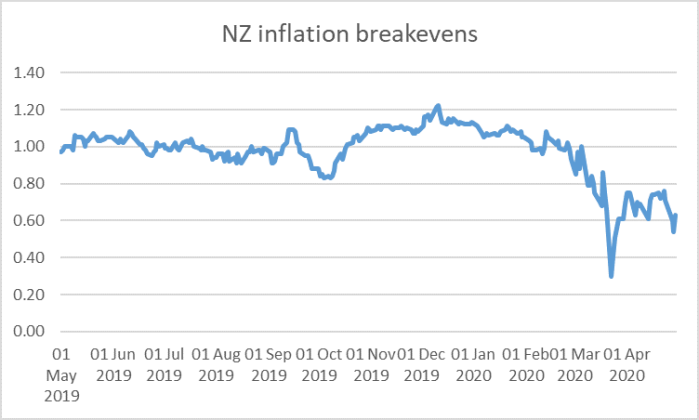
And what about inflation expectations?  If there was a modicum of relief in the specific inflation expectations questions in the ANZ Business Outlook survey yesterday, there was none in the “pricing intentions” results (or, for that matter, in the volatile ANZ consumer expectations measures out today).    And what of the wholesale markets?   This is the chart of inflation breakevens –  the gap between nominal and indexed 10 year bond yields.

breakevens may 20

These implied expectations had already fallen away quite a lot over the last few years –  a 1 per cent average of 10 years is just not even close to the 2 per cent target –  but have dropped away quite a bit further since then (five year breakevens are even lower).  And recall that these are the same upbeat global markets that now have equity markets showing strength that puzzles most economic analysts: it is hardly as if an excess of gloom is currently driving markets.

It also isn’t just some New Zealand idiosynrasy –  thin markets and all that.    The drop in the implied US breakevens is of similar magnitude to that in New Zealand (and I happened to watch a webinar yesterday run by Princeton economics department and in an online poll of their viewers, the breakeven numbers weren’t regarded as out of line with reality).

In other words, real retail interest rates have not come down much at all, the exchange rate has not come down much at all, and inflation expectations have been (a) falling and (b) always well below the target midpoint.  Add in the unemployment we are seeing, rising by the day, it is a standard prescription which in normal times a central bank would see as a pretty compelling basis for a much looser monetary policy.

With an economy that has been shrinking fast, and seems set to remain well below normal for quite some time, it remains pretty extraordinary that both term deposit rates and low-risk retail lending rates (conventional variable mortgage rates) are still materially positive in real terms.    Run your eye down the term deposit offerings listed on interest.co.nz and the big banks are typically still offering 2.3 per cent for six months, and their standard variable rate mortgage seems to be priced between 4.4 and 4.6 per cent.

Cross-country comparisons of retail rates are hard –  product features differ etc, and our sort of variable rate mortgages are largely unknown in the US –  and so I rarely do them.  But I thought some Australian comparisons might be relevant –  after all the RBA’s policy rate is also 0.25 per cent.  But the gap between the policy rate and retail rates is larger here than in Australia.

Thus, whereas ANZ in New Zealand is offering 2.3 per cent for NZD six month deposits, ANZ Australia isoffering 0.9 per cent for AUD six month deposits.    Westpac NZ is also offering 2.3 per cent, while in Australia they are also offering 0.9 per cent.

For a variable rate mortgage, ANZ locally is offering 4.44 per cent.  In Australia, ANZ will lend Australian dollars on a variable rate mortgage at as low as 2.72 per cent (although there is myriad of product offerings).  The best Westpac offering I could see (in Australia) was a bit higher, but still a long way below Westpac’s New Zealand variable rate of 4.59 per cent.    This issue here is not about bank margins (between borrowing and lending rates) but about monetary policy, which influences the overall level of rates.

And if Australian nominal retail interest rates are lower than New Zealand’s, recall that the RBA’s inflation target is centred higher than New Zealand’s –  centred on 2.5 per cent inflation –  so that in real, inflation-adjusted, terms the gap in favour of Australian’s retail customers is even greater.   Now, to be sure, Australian real retail rates are usually lower than New Zealand’s –  all New Zealand’s real interest rates generally usually are  – but when we have a larger adverse shock than Australia, that shouldn’t be the case right now.  And when the Governor tries to tell us –  as he tried to tell Parliament –  that New Zealand interest rates are as low as they can go, he is simply wrong.  Real retail interest rates are far too high for this economic climate and need to come down.

Getting them down further remains technically easy.   Simply lower the OCR to -0.5 or -0.75 per cent and there will be no large-scale transfer to physical cash.  And as I’ve argued before dealing with the large-scale cash conversion risk is also relatively trivial as a technical matter.  The Reserve Bank simply refuses to do it, and the Minister of Finance apparently refuses to insist on it.  In this climate –  and given the margins between the OCR and retail rates in New Zealand –  an OCR of -5 per cent would be more appropriate, and if it were implemented decisively –  lowering the exchange rate, boosting inflation expectations, easing servicing pressures (why all the focus on rents, and almost none on interest rates?) and signalling a climate supporting a quick return to full employment – the extremely low rates might not even be needed for long.  But stick around current levels and the growing risk is that it takes many years to get off the lows, and inflation expectations keep drifting down, reinforced by repeated weak actual inflation outcomes.

The MPC on 13 May should:

  • abandon the “no change for a year pledge”,
  • cut the OCR to zero,
  • announce that the OCR will most likely be cut further in June (which would get many of the benefits immediately, but give a little time if there are some real system issues re a negative OCR), and
  • commit to have in place by June robust mechanisms that for the time being removed, or greatly eased, the current effective lower bound on short-term wholesale interest rates.

An apology would be good too, and some long-overdue openness from the invisible –  but supposedly accountable – external members.  But I won’t push my luck.  If they got the substance of policy right now, the past failures could be largely set to one side.

(Oh, and if they wanted to they could offer to buy some more government bonds, but get the basics right and the theatre won’t be necessary.)

A debt jubilee?

In the Western tradition, the idea of the year of jubilee comes to us from the Old Testament.    The idea was to avoid permanent alienation of people from their ancestral land –  in effect, land transfers were term-limited leases, and if by recklessness or bad luck or whatever people lost their land it was for no more than fifty years. In the fiftieth year –  the Year of Jubilee –  all would be restored: land to the original owners and hired workers could return to their land.   It wasn’t a recipe for absolute equality –  the income earned wasn’t returned etc –  but about secure long-term economic and social foundations.

For many –  for me –  it has an appeal, although one could argue that in many respects modern society already reflects some of the vision underlying the original near-eastern ideas: after all, we prohibit slavery, we allow personal bankruptcy (and discharge from bankruptcy without paying all the original debts), we provide education free at the point of use, and a welfare system for those who might otherwise fall through the cracks.

But this post isn’t about exploring those ideas, but about one very specific modern championing of the idea that we hear a bit more of again at present: the idea of some sort of debt jubilee in which, in a highly-indebted system, the outstanding debt is, in some form or another, simply written off.

One person who has been championing such a scheme for some time is Professor Steve Keen, an Australian economist now teaching at a university in London.   He has quite a following in some circles – I used to read his blog moderately regularly for a time, and perhaps 7 or 8 years ago The Treasury hosted a visit here (in the course of which his stocks sank among most officials).  However, he was interviewed a few weeks ago by Gareth Vaughan at interest.co.nz on his ideas for policy in the wake of the coronavirus.  He and I share the view that the biggest macroeconomic risks at present are deflationary rather than inflationary but, it would seem, we agree on little else.   You can read or listen to his other ideas for yourselves if you choose, but one strand of what he was championing was a “modern debt jubilee”.

I do not wish to be seen to be critiquing or attacking a straw man, but I have had difficulty finding anything online that sets out in very specific terms exactly what he has in mind.

Here is what he said in the interview

Firstly, Keen says, they should be implementing a modern debt jubilee now.

“It’s quite feasible to do it [but] I never thought it would happen. People asked me what chance I thought this had of happening. I said it’s less than a snowflake’s chance in hell. We are in hell now and the only way out of hell, as well as getting a vaccine for the virus, is to reduce this burden of private debt otherwise we’ll have a financial collapse after the coronavirus,” says Keen.

The alternative, he argues, is mass loan defaults.

“You simply have to accept that debt can’t be repaid when too much debt has been issued. So we have to reduce private debt and we have to do it now. [We] should do a debt jubilee now, not once we get through this crisis. Otherwise there’ll be many people who can’t pay their rent, as well as people who can’t pay their mortgages,” says Keen.

“If we do it now we’ll enable the payments system to continue functioning. If we don’t do it now then it’s quite possible the payments system will collapse. Small businesses won’t get any cash income, households won’t get wages. Everybody will end up having no money in their bank accounts because that money will be used to pay off debt.”

What Keen’s advocating for is governments’ capacity to create fiat money being utilised to distribute an equal amount of money per person across entire countries.

“And people who were in debt would get their debts reduced, either by an offset account or by actually paying their debts down. People who are not in debt get a cash injection. And that cash injection can also be used to buy newly issued corporate shares which are used to pay down private debt. So as well as reducing household debt, you reduce corporate debt and you also democratise the ownership of corporations,” says Keen.

And although I have found a couple of other references (including here and here)  there is still no sight of some critical parameters.

Nonetheless, it is worth bearing in mind that elsewhere in the interview he describes the large increase in household debt in recent decades as “unconscionable debt” and repeatedly highlights the very large increase in the ratio of household debt to GDP in New Zealand since about 1990 (about 30 per cent then, about 100 per cent now).   And although he talks about “reducing” household debt, “jubilees” have connotations of very substantial writedowns, so he clearly isn’t talking about something like dishing out, say, a mere $10000 per household/person.  The Reserve Bank tells us that as at the end of last year recorded household debt was about $310 billion.

Moreover, Keen also tells us (see extract above) that he thinks the same amount should be distributed to everyone.  I’m not sure whether he really means “everyone” or just adults, but since under-18s can’t contract binding debts there shouldn’t be any need for jubilees for them.  That still leaves 3.8 million residents (and here I’ll just ignore the fact that a significant number of them are temporary non-citizen residents; I just want to get a sense of the plausible scale of what Keen might be calling for, not tie down every detail).

As we all know, recent first home buyers in Auckland typically have to take on fearsome levels of debt.   They appear to be the sort of people Keen focuses on, since he blames the rise in house prices on banks and their over-aggressive (“unconscionable”) lending setting up a house of cards that might otherwise be about to tumble.  I presume a $500000 mortgage isn’t at all uncommon (last year the nationwide average first home buyer mortgage was about $400000) and many will be larger than that.

Now, of course the typical new buyers are a couple, but for those marginal Auckland purchasers that might still be $250000 each.

I presume Keen does not have in mind giving them –  and all the rest of us –  $250000 each, although doing so would certainly allow most (but not all) mortgage debt to be fully repaid.     But even if we wanted to make possible a 60 per cent writedown for those couples with the new unconscionable $500000 mortgage, he’d still have to be looking at $150000 each, as gift/grant from the Crown.  Across 3.8 million adults, that seems to come to $570 billion dollars.

All paid for, in his own words, through the Crown’s ability to create fiat money –  change the Reserve Bank Act and get for the Crown an (interest-free) overdraft of $570 billion.  Halve the payment and it is still serious money.

You’ll have noted that Keen is also concerned about corporate debt –  a big concern at present in some countries (where it has grown rapidly in recent years) but much less so in New Zealand.  For those –  most of us –  without mortgages (whether because we have paid them off, or never been able to get into the housing market in the first place), we get a rather large addition to our bank balances.   Keen notes that the proceeds could be used to buy “newly issued corporate shares which are used to pay down private debt”.

I don’t know about you but I know what I would be doing not just with my $150000 but with all my non-indexed financial wealth the minute I thought that anything like what Keen was proposing was likely to be implemented: I’d be looking to put it into real property (houses, gold, whatever) or getting it into the currency of a country not adopting such a policy.  Anyone with non-indexed debt at present would prudently be doing the same –  and locking in a long-term fixed interest rate – not using the proceeds to pay off debt.  It might be hard to generate inflation at present, under present –  largely self-imposed – constraints, but simply handing $570 billion will do it.

I hope all regular readers will recognise that I am not one of those looking for inflation under every stone.  I worry about deflationary risks at present –  as does the market – and I do not believe monetary policy is doing anything like enough to respond to those risks at present.  Much as I am sceptical of the idea of giving out some modest amount (say $2000) to everyone as some sort of stimulus, in the current climate – large negative output gap, little or no inflation –  such a payment, even funded directly by the Reserve Bank –  would be net stimulatory in the near-term.  There is a considerable amount that can be done to get us back towards full employment as soon as possible.

But not by simply handing out $570 billion, with no obligation to repay.

(Presumably Keen does not think his scheme would dissolve into very high inflation, but I’ve never seen him anywhere articulate the case for why not.)

When I think of debt writeoffs, I think of explicitly recognising that someone has to bear those costs –  on any very substantial scale there are few/no free lunches.  Banks will have to write off some debt –  perhaps quite a lot –  over the next few years, and their shareholders will bear that cost.  That is the business they went into.  Writing off mortgage debt more generally on the sort of scale Keen seems to envisage can only be done by imposing fearsome losses on others.  It is so utterly different from that Old Testament conception (which, in effect, limited the scale of liabilities anyone could run up in the first place).

I have some sympathy with the view that requiring young –  and now not so young –  people to take on multiple hundreds of thousands of dollars of debt to get into a basic house in our cities is pretty unconscionable and deeply unjust. But, frankly, that isn’t fault of the banks but of the central and governments that make land –  a resource we have in abundance – artificially scarce.  In fact, I’ve even gone so far as to argue that if ever we managed a government with the courage to fix the land market, it might be both opportune (building coalitions) and just to offer some compensation to the losers –  those more or less compelled to take on very high debt in recent years just to get a foot on the ladder.   But there would be an explicit, shared, cost to that.

And more generally I’m not persuaded that current debt levels –  public, private or total –  in New Zealand pose any vast threat of economic or financial collapse.  Keen likes to highlight how much debt has risen since, say, 1990, but it isn’t obvious why that is the most relevant benchmark.  In a speech I wrote with Alan Bollard a few years ago, I included a chart showing that mortgage debt (house and farm) was materially lower then  as a per cent of GDP than it had been in 1920s New Zealand,  I rechecked the numbers this morning and the picture today is the same as it was in 2011.  Contrary to Keen, our banking system looks pretty robust, not ricketty.

I also take the view that there is plenty that can and should be done to assist individuals and firms through the next few months.  There is a strong case for income support (broadly defined) or even income insurance (of the sort I’ve championed here) but that is very different proposition than somehow looking to wipe out debt without identifying whose claims to real resources will be wiped out to pay the economic cost of that (as distinct from the “which account to write the cheque on” issue that Keen deals with).

You might be wondering why I bothered with this post, or dealing this extensively with a pretty extreme idea.  The reason is that Radio New Zealand is recording tomorrow (for broadcast on Sunday morning) an interview with both me and Keen. I might have more to say about some of his other ideas –  some of which make Winston Peters championing New Zealand manufacturing seem moderate –  next week. In the meantime I wanted to understand as well as I could what Keen was actuallly championing on the debt front.  As I said, I don’t want to attack a straw man –  that never persuades anyone –  but I simply haven’t yet found an articulation of what he is proposing that looks economically feasible or sensible.


Diverted down historical byways

Get me onto interwar economic history and I can get a little carried away.  I don’t like to think quite how many books on the Great Depression – in all manner of countries – and events either side of it I bought when I first got fascinated by it, and my interest continues.  New Zealand is a fascinating subset of that history/experience, although it is still the case that there is no single comprehensive economic, and economic policy, history for New Zealand in the interwar period, even though so much of interest/importance was going on.

Anyway, after yesterday’s post a reader kindly sent me a copy of a new NBER working paper by two prominent economic and monetary historians, Michael Bordo and Christopher Meissner.  Their topic is “Original Sin and the Great Depression” –  no nothing theological, but rather referring to the difficulty most countries long had (many still have) in borrowing externally in their own local currency.    It is an interesting paper and they’ve used some fascinating high frequency data (by 1930s standards) in some of their estimates, but the key bit from my perspective was the question of how foreign currency debt might have influenced the willingness, or otherwise, of countries to devalue, or allow their currencies to depreciate, during the Great Depression.    This has often been perceived to be an issue in more-recent decades: a currency depreciation greatly increases the local currency value of foreign currency debt, and if much of the debt (public or private) is (a) in foreign currency and (b) not supported by export industries, earning foreign currency, it can act as an obstacle to necessary adjustment.  As it was in places in Latin America in the 1980s, so in places in east Asia in the 1990s.

Bordo and Meissner try to unpick whether this was a constraint on countries in the 1930s –  a consideration that lead them to delay longer than otherwise the sort of break with gold and the exchange rate adjustment that ultimately looks to have been important in the eventual recovery.  They find some suggestive evidence that this was so and that market pricing recognised the issue (thus, a higher risk premium was priced into the yields of countries that depreciated).  They line up data, for example, on when countries defaulted (if they did) and when they went off the Gold Standard.

I wouldn’t be surprised if a more detailed examination of the issue proved that there was something to the thesis.  But it probably needs a more -in-depth treatment to account for the huge variation in what exposure to exchange rate fluctuations actually meant across a wide range of countries.  In some cases it is simple – a country with its own currency, but with much/most of its debt raised on market in foreign currency (whether sterling or USD).  In other cases, it isn’t.  For example, in the United States much debt –  including most government debt –  was denominated in USD, but also contained a gold clause –  guaranteeing that the lender was protected against any exchange rate change (I only discovered yesterday that much Canadian debt also had such clauses).  I wrote here about the recent book on the abrogation of the US gold clauses by Roosevelt.  In effect, it was a sovereign default, and is treated as such by Bordo and Meissner).   But Canada also overturned its gold clauses, and it isn’t treated as having defaulted.      On the US side, public debt going into the Depression was low and I don’t recall ever reading that the gold clause had been a constraint on action prior to 1933.

Also, among advanced countries, war debts and reparations were at the time one of the most important form of inter-country liabilities, and although those obligations generally weren’t expressed in local currency terms, they also were generally not expected to be resolved through market mechanisms (and the debts were not traded, so there is no secondary market pricing).  And although the authors claim to have dealt with these debts, almost all of which were eventually defaulted on (Finland was the exception that paid in full), their tables of countries which defaulted don’t line up well at all with what we know of the defaults on war debt.    Thus, the UK defaulted on its war debt to the US (denominated in USD) and is (rightly) treated as a defaulter.    But neither New Zealand nor Australia is listed as having defaulted, even though neither paid any more on their substantial war debts to the UK.  (Both countries also “defaulted” on domestic debt –  the New Zealand story is here.)

As a matter of interest, this table is from Eichengreen.  The Hoover Moratorium was a standstill on servicing war debts and reparations in 1931, but the table captures annual savings/losses that became permanent over the following few years

hoover

In per capita terms, New Zealand was the second-biggest gainer (after only Germany) – we lost reparation payments due but saved a lot on the war debts we never again serviced (and which the UK never pursued us for).

But to an extent this is by way of rambly preamble to my New Zealand specific bugbear with the paper, which includes this table.

bordomeissner

Not only did we default –  domestically, and externally (those war debts) –  but we were not on the Gold Standard.   This is a not-infrequent mistake made by overseas academic researchers –  Eichengreen, for example, has a table in which he has New Zealand leaving gold in 1929.

We did not.  We had not been on the Gold Standard since World War One started in 1914 (as I wrote about in an early post here).  We did not return to gold in 1925 when the UK returned.  From August 1914 onwards, bank notes (issued by the trading banks) were not convertible into gold on demand, and banks were not required to keep any particular level of gold.  There was no central bank, buying/selling gold at a fixed parity. We were not on the Gold Standard –  even if that state of affairs was maintained by wartime regulations still in effect years later, rather than by a formal new statute.

In the, perhaps vain, hope of making a small contribution to putting a stake through the heart of this particular myth, here is an extract from Sir Otto Niemeyer’s report to the New Zealand government in February 1931.  Niemeyer was a senior Bank of England official commissioned by the New Zealand government to visit New Zealand and to report on policy options re banking and currency, including around a proposed new central bank.   Here are the opening two paragraphs of his report.

niemeyer

Banks held gold.  The fact that they did so may have given some comfort to depositors.  A solid loan book would generally do that too.  But gold played no continuing part in the New Zealand monetary system after 1914.   To repeat, after that date we were not on a Gold Standard.

Of course, quite what standard we were on is another matter.  There was no central bank. In practice, as Sir Otto goes on to note –  and as everyone recognised at the time –  the key constraint on banks’ activities in New Zealand (lending) was the availability of sterling balances in London, combined with the customary practice –  and it was no more – that banks managed things to keep New Zealand deposits exchangeable into sterling at very close to parity.  In the jargon, there was no nominal anchor in the system – neither metallic, nor a central bank required to keep something akin to price stability.    It was a very unusual system, that perhaps should not have worked, but it did more or less.   Partly as a result there was little real sense –  and I gather this was true in Australia as well –  that a New Zealand pound (a pound liability issued by a bank in New Zealand) was in some sense different from an English pound.

But to revert to the question of debt and the Depression, New Zealand’s government was heavily indebted going into the Depression and the debt ratios got much worse at the Depression went on.  Here is total New Zealand government debt as a per cent of GDP from the IMF’s Historical Public Debt database.

IMF public debt

and here is a chart from a paper Bryce Wilkinson did for the New Zealand Initiative a few years ago showing both public debt (slightly different series) and external debt as a per cent of GDP.

bryce debt

(Around this period the Australian charts are quite similar)

Bordo and Meissner include a chart suggesting that in 1928 our ratio of foreign public debt to exports –  some sense of servicing capacity, and New Zealand was a big exporter at the time – was the fourth largest of the countries they study.

Curiously, and something I learned the other day from another new book, despite these astonishingly high levels of government debt (and heavy external debt) as the Depression began New Zealand had the highest possible credit rating from Moodys.

moodys depn

In a way, it worked out okay.   We defaulted on the war debts, but for the sorts of public issues Moodys’ was rating, no foreign holder lost a penny (not even a (new) New Zealand penny let alone the (more valuable after 1933) UK penny).   But it need not have been that way: the debt burden was punishingly high, markets were temporarily closed to any new issues, and by the end of the 1930s, New Zealand external finances were even more severely constrained, the possibility of default was in the wind.

To some extent, these public debt series overstated the burden on the taxpayer.  Quite a bit of what the Crown borrowed was on-lent, particularly to farmers. On the other hand, farm debt was a pretty major area of difficulty during the Depression, with repeated interventions to ease the burden (on good farmers).  New Zealand was heavily indebted –  government and private (estimates of total mortgage debt as a per cent of GDP then exceed those now).

But if public debt was high going into the Depression it went higher, in two separate stage.  First, the denominator –  GDP –  fell sharply.   Nominal GDP in 1932 is estimated to have been a third lower than in 1929 –  the fall split roughly evenly between quantities (real GDP) and prices.      And then  –  and this is the link to Bordo and Meissner –  the exchange rate was formally devalued at government initiative (even though there was not yet a government-issued currency) in January 1933.    That raised the local currency value of the foreign debt –  more so, at least initially, than it contributed to the recovery of nominal GDP.   Government debt as a per cent of GDP peaked (on both charts) in 1933.

Devaluation had been an option debated for some considerable time.   Most local economists were in favour, as (of course) were the farmers –  the prospect of more local currency for each pound sterling earned was attractive to say the least.  On the other hand, it was something others were more sceptical of –  all such policy choices are distributional in nature.  Importers and associated merchants were one group, but the trade unions were also wary –  whatever you believed about the responsiveness of the economy over time, tradables prices (including food) seemed likely to rise.  Of course, a rise in tradable prices was the whole point.

What is less clear is how much influence the additional debt service costs had on the Cabinet’s thinking.  It was a real factor, at least in the short run.  On the other hand, ministers will have been conscious that earning the foreign exchange to meet the foreign debt commitments was made a bit easier by the devaluation, and those sterling earnings were also critical influences on local banks’ ability to lend, and thus to support any prospects for recovery.  The Bordo and Meissner paper does not seem to take this factor into account.

As I noted earlier, when the New Zealand government coercively restructured domestic debt (in effect, defaulted) they did not attempt the same on the government’s foreign debt.   There are likely to have been a variety of factors at work, including a more generalised desire to have continued near-term access to UK markets (and New Zealand and Australia had both developed reputations as rather over-eager borrowers in the 1920s) and the little-known Colonial Stocks Acts (which I thank a commenter the other day for drawing my attention to again) under which the UK government had –  with our consent –  the authority to disallow specific legislation that disadvantaged holders of New Zealand debt in the UK.   Whatever the combination of factors, the focus of the government’s efforts and rhetoric were instead on raising the world price level –  lifting commodity prices generally, and those denominators (GDP).  That made a lot of sense with so much excess capacity and such a fall in the price level.  It was something Britain and the Dominions joined in committing to in the British Empire Currency Declaration of 1933.

As a final observation in this (discursive) post, when people talk at present about the fiscal costs of responding to the Covid-19 slump you sometimes hear talk of debt getting to “wartime levels”.  People who used those references typically have places like the US and the UK in mind.  As you see from the charts above, public debt kept dropping as a share of GDP through the rest of the 1930s –  mostly rising GDP rather than falling debt –  and even in 1946 New Zealand’s public debt, while high by today’s standards was about 148 per cent of GDP, lower than it had been in 1929.  Between heavy taxes and Lend-Lease obligations the US ran up to us, the war wasn’t one that left us under a heavy burden of debt.  At the end of it all, we’d built up enough unsustainable financial claims on Britain that a considerable chunk were, under pressure, written off.  The UK, in effect, defaulted on us.

Golden fetters and paper chains

In various posts over the years I’ve mentioned how countries finally got out of the Great Depression.  Generally that involved breaking the link between their respective currencies and gold and then being able to adopt more-expansionary macroeconomic policies.  That was relatively easy to do as a purely technical matter, but it took a long time for countries to get there (a handful of significant countries not until 1936).  I’ve worried aloud that given how low the starting point for nominal interest rates was going to be that in the next serious downturn the refusal of central banks –  and it is simply a refusal –  to take policy rates deeply negative would end up as much the same sort of fetter as gold once was.

The definitive book-length treatment of this angle on the Great Depression is Berkeley professor Barry Eichengreen’s  Golden Fetters.  It was published in 1992 – decades ago now – and going by the marks in the margin of my copy I seem to have read it once a crisis since then.  It is one of those books that repays rereading, partly because the contemporary context against which one reads it is different each time.  I read it again last week.

What follows is informed by Eichengreen, although refracted through my lenses.  There are places where Eichengreen’s argument isn’t fully persuasive (and he has one or two facts wrong about New Zealand).

Much of the book is scene-setting for the experience of the Great Depression.  That includes a perspective on the pre-War Gold Standard, which tied together most of the major (and many of the minor) economies of the time, with a leadership role played in particular by the Bank of England.    In many of the core countries –  UK, France, Germany notably –  central banks played an important role, but in other countries operating on a gold standard there was no central bank at all (most importantly, the United States, but also countries like New Zealand and Canada-  all three of whom were net capital importers).    Price levels didn’t change much over time (the British price level was about the same in 1914 as it had been in 1834), capital flowed freely, trade (and migration) was extensive, and if there were periodic crises or threats to the system, central banks worked together to maintain stability.

World War One greatly disrupted the picture.  Some countries formally went off gold, others didn’t formally but there were enough interventions that the pre-war parities didn’t act as any sort of constraint on price levels.  Huge debts –  internal and external – were run-up in the process, and the US moved from being a net borrower to being a net lender to the rest of the world.  And in the aftermath of the war there were reparations obligations established, huge distributional fights (inside countries) as to who should cover what portion of the accumulated costs, and some countries collapsed into hyperinflation sooner (Austria) or later (Germany).   All manner of other countries had much higher price levels than pre-war, and in some –  notably France –  high inflation remained an issue well into the mid-1920s.

Against that backdrop, in many quarters a return to a money convertible to gold was seen as partly as a key confidence-building commitment, and partly as a return to something like normality.  It took a long time –  in one case, Japan, it din’t actually happen until early 1930 – and for good reason.  There were debates about which rate to restore parity at –  the UK eventually, perhaps unnecessarily, chose to re-peg at the pre-war parity, which implied several more years of moderate deflation.  For France, having had so much inflation, the pre-war peg quickly became unrealistic and they stabilised at a considerably devalued exchange rate to gold.  For Germany, of course, hyperinflation made a nonsense of the pre-war parity.

There hadn’t much gold mined in the previous few years, and yet global price levels were much higher than they had been.  That in itself posed some challenges.  But international cooperation and trust wasn’t what it had been pre-war either.  And particular policy choices made by the US and France meant that those two countries’ central banks accumulated an increasing share of the world’s gold are were unwilling and/or unable to let those inflows flow into much looser domestic monetary conditions (France, for example, having just stabilised was understandably averse to a fresh wave of inflation).  The UK –  still operating as a major global financial centre, significant source of long-term foreign lending –  operated with low gold reserves.  Germany, with a populace only too conscious of hyper-inflation just a few years previously, had high minimum gold cover requirements, but those buffers couldn’t be cut into.  Higher interest rates in the US – as in 1928/29 – forced both the UK and Germany to adopt tighter domestic monetary policy.   And so on.

The Depression itself got underway in a variety of countries influenced by various factors, domestic and international.    The 1929 sharemarket “crash” wasn’t particularly important, except perhaps in shaping the mindset of various US policymakers (including at the Fed) who were uneasy about much looser monetary policy because they reckoned the excesses of speculation needed to be purged.    Some countries were affected worse than others early on –  Australia for example on the worse side, and France on the more positive side.

Generally, however, monetary conditions did ease as the respective economic conditions deteriorated.  But the fixed exchange rate system, underpinned by convertibility to gold, severely limited what could be done with either fiscal or monetary policy –  and that was true even in the countries with large gold holdings, the US and France.

The financial crisis aspects really intensified in mid-1931, in Austria and Germany (where there were significant domestic banking system issues) initially, and then spilling over to the UK, where the economic slump itself had been relatively mild –  relative being the word –  but the pressure eventually told on gold parity.   The re-formed National government –  still led by former Labour Prime Minister Ramsay McDonald –  decided not to impose further pain on the domestic economy (which might have been insufficient anyway) and went off gold.    The break in the parity was initially envisaged as temporary, and it was some months before domestic policy itself became much more expansionary.  But the consequence of the lower exchange rate –  although many smaller countries moved to peg to sterling, giving rise to the “sterling area” which persisteed for several decades) and easier domestic monetary conditions meant that the UK was the first significant economy to recover from the Depression.

The US held on to the old gold parity until April 1933, and while that old parity held it acted as a real and binding constraint on the ability of domestic authorities –  including the Fed – to run much easier policy.   Fear of devaluation sparked capital (and gold) outflows.   But as Eichengreen records, many of the senior Fed officials were not that keen on much easier policy anyway, and some saw the roots of the Depression primarily in past speculative excesses.  Even in the US, concern about possible inflation risks – in the depths of a deflation –  were heard, and were evidently sincere.  The US later returned to a gold parity (while prohibiting for decades citizens from holding gold) but at a much-devalued exchange rate.

Those inflation concerns were all the greater on the Continent.  Germany never abandoned the old gold parity, but just rendered it non-binding with an increasing complex of exchange controls and other payments restrictions.   But for the remaining gold countries –  most notably France, Belgium, Netherlands and Switzerland –  the tensions grew between the desire to maintain the parity –  whether as symbol of normality or (more strongly in the French cases) ran increasingly up against the losses of competitiveness producers in those countries faced as other countries devalued, and the market recogmition of those pressures (thus capital flight).  It wasn’t until 1936 that those parities were finally abandoned.

As Eichengreen notes, at the end of it all, by the late 1930s, real exchange rates among the major economies had not changed that much at all.  Some countries had got the initial advantage of moving earlier (the UK notably) but in the longer-term the beneficial effect was not breaking the gold parity and getting a lower exchange rate, but breaking the constraints (domestic and international) on domestic macro policy (fiscal and monetary).  As he also notes, it wasn’t enough just to break from gold, since countries also had to be willing to break with the Gold Standard ethos, and allow/adopt looser macro policies.  One obstacle to that had been the fear of inflation.  That fear might look unreasonable –  whether from this standpoint, or contemplating a country with a deep deflation in the early 1930s –  but the hyperinflationary and high inflation experiences really weren’t that far in the past, and had been utterly destructive for many.

Eichengreen has a nice table late in the book illustrating how industrial production –  the main macro variable at the time, before quarterly national accounts were a thing –  responded in different groups of countries.

eichengreenLook at the last two columns and you can readily see the difference of experience in the countries that went off gold/devalued (sterling area and the “other depreciated currencies” lines) with the experience in the gold bloc countries, where even by 1935 industrial production was still 20 per cent lower than in 1939.

It need not have been.  It wasn’t as if the 1920s and 1930s were a period of underlying economic stagnation.  The US –  by then the world’s leading edge economy – experienced really strong total factor productivity growth in both the 1920s and the 1930s.  I’m sure some economic ups and downs were inevitable, but nothing on the scale and duration of what actually happened in the 1930s was in any way inevitable –  it was largely the consequence of a succession of choices, of almost entirely well-intentioned people, working against the backdrop of presuppositions, presumptions about normality, and the backdrop of some deeply unsettling experiences, that led to those savage and prolonged losses.   When countries broke the golden fetters –  and for many it was regretted initially or felt to be hugely risky – economies started to recover, and the gains in an increasing number supporetd a sustained global recovery in demand.

(You might be wondering where New Zealand fits in all this.  That is mostly another post.  We had no central bank.  We went off gold in 1914.  That left our banks issuing their own currency, in practice loosely pegged to sterling (but not legally so), with banks managing domestic credit based on their holdings of London funds.  Our exchange rate – managed by the banks – was allowed to depreciate a bit, but the big movements were in September 1931 when the UK went off gold and their exchange rate depreciated against the rest of the world and so, thus, did ours, and –  more importantly –  then in January 1933 when the government initiated a formal devaluation against sterling (still not having a central bank) over the objections – and resignation –  of the Minister of Finance (and with not a little domestic unease and debate).  In 1931 and 1932 even after the UK went off gold our economic policy options were very very few, and our devaluation was much more of a turning point (probably helping that it was followed a couple of months later by the beginnings of the US reflation).  I have an old post on New Zealand and the Great Depression.)

Of course, the point of the post is to draw some loose comparisons between the golden fetters of the early 1930s, which proved so costly in the specific circumstances of the time, and what I’ve taken to calling the paper chains, the refusal of the world’s central banks now to do anything about taking official interest rates deeply negative, even though standard macroeconomic prescriptions –  such as the Taylor rule –  suggest that is exactly what should be done.

I’m not suggesting it is some sort of allegory for our age, in which every detail of the 1930s can be mapped to something now.  It can’t.  It is really just about a single point: that self-imposed constraints, which can seem very very important to preserve at the time, can actually in some circumstances prove incredibly costly, and in those circumstances the sooner they are jettisoned the better.

One area in which the parallels certainly aren’t exact is around fiscal policy.  Most countries in the 1930s had very little freedom of fiscal action initally, precisely because of the monetary/gold parity constraints  –  increase your fiscal deficit and the resulting increase in demand will also result in increased current account outflows (of gold).    In some cases – New Zealand –  there was just no effective borrowing capacity at all –  thus, Keynes’s advice to Downie Stewart that I’ve quoted here previously (“if I were you I’d try to borrow; if I were your bankers I would not lend to you).  We have nothing like those sorts of technical constraints.  But that doesn’t mean there are no limits in practice –  as we saw after 2008/09, public tolerance of continued very large ongoing fiscal stimulus, even in badly affected countries, was really quite limited.  In the real world, fiscal policy isn’t any sort of fully adequate substitute for monetary policymakers choosing to sit on the sidelines –  dealing, perhaps, with market liquidity issues, but not doing much about the overall stance of monetary policy, even as deflationary risks mount (thus, real retail interest rates have not fallen at all in New Zealand and Australia this year, despite the huge economic slump).

There is a, perhaps understandable, sense in some quarters that there wasn’t too much wrong with economies last December.  Perhaps, but things have now changed, and if one strand of macro policy – typically the most important for cyclical purposes, and easiest to adjust –  is allowed to sit on the sidelines doing nothing –  and elected ministers have the power to change thatg –  there is risks that this economic downturn ends up much more severe and protracted than it needs to be.  All because central bankers won’t break free of their paper chains and their old mindsets (aggravated in New Zealand’s case by the stunning negligence of a Reserve Bank that talked modestly negative interest rates for some time but did nothing at all to ensure there were no technical/systems obstacles): we pay the price for both lack of preparation and the reluctance/refusal to break the paper chains and put in place quickly the sorts of rules and practices that could allow official rates to be taken deeply negative for a time, in turn supporting demand (directly and via the exchange rate) and supporting medium-term expectations about the economy and inflation.


Social Credit – too timid by far this time

Social Credit ideas have a long history in New Zealand.  The originator, Major Douglas, even visited New Zealand in 1934 and testified to a parliamentary committee.  The ideas influenced Labour in particular in the 1930s, and some who later played very prominent roles in National.  We got our very own political party – the Social Credit Political League – in 1954 and from time to time Social Credit did very well in the polls (and under FPP even managed four MPs at the different times from the 1960s to the 1980s).  I recall a time –  perhaps 1980 –  when Social Credit briefly polled ahead of Labour.  There had been an entire Royal Commission in the 1950s, mostly intended to debunk them, but  they weren’t deterred –  as a young economist at the Reserve Bank, a fair amount of my time was spent responding to letters, to us or the Minister, from Social Credit monetary reformers.  Some of were admirably dogged, and typically very polite, although one particular frequent letter writer once lamented that his letters were getting nowhere with us and felt as if he might just as well jump off a cliff.  Our then chief economist suggested that perhaps writing a book might help, and a year or two later we got the book in the mail.

It is a fascinating history but today I’m not going to wallow further in it.  The key policy plank always used to be cheap Reserve Bank credit as the macroeconomic answer.

It still appears to be so.   Social Credit still exists in New Zealand.   Democrats for Social Credit got 806 party votes at the last election.  And on Saturday I opened both papers – Dominion-Post and Herald – to find full page adverts from the NZ Social Credit Association.

social credit apr 2020

Several economists and various other commentators have extracts of their work presented as supporting the Social Credit vision/platform (to be fair, the advert makes clear that none of the people concerned have any association with Social Credit or with the advert).  It isn’t hard to find such quotes –  as my wife notes, I should probably count myself lucky that none from me appeared (after all, that quote from Shamubeel Eaqub is very much in line with my post the other day noting that there was no real macro difference between the Reserve Bank, at its discretion, choosing to buy bonds on the secondary market and choosing to buy them direct from the government).

Anyway, Social, Credit is trying to gather signatures for a petition (although not, it appears, a real parliamentary one) as follows:

We are calling on the New Zealand government to use the Reserve Bank (which the government owns) to fund the Covid-19 economic rescue package.

It is, they claim

The world’s first fully-funded plan to reclaim our environmental and social well-being

And here is underlying graphic

socred 2

The thing that seems to unite most monetary reformers is that they believe monetary policy and things around “the money supply” are much more powerful, much more important, than most monetary economists and central bankers do.

Before addressing what the Social Creditors are proposing, I should say that I am not one of those who thinks governments can do little or nothing useful in severe economic downturns  (there are a few such people, at least in principle, although few are visible/audible right now).  I’ve been championing here a more aggressive use of fiscal policy in the short-term (the 80 per cent net income guarantee for 2020/21), and for a much more aggressive use of conventional monetary policy.  Macro policy can help get the economy back to work as promptly as possible, but borrowing from the Reserve Bank –  whether at 1 per cent as Social Credit used to call for, or 0 per cent as they may now belief –  is largely irrelevant to the solution.

Note –  and here perhaps I depart from some of my friends on the right –  I did not say reckless and highly inflationary (as, for example, Social Credit prescriptions in the 1950s would have been).     There is far too much jumping at inflationary shadows still –  as there was 10 years ago in some circles (in the US in particular), and (so I was reminded rereading Eichengreen over the weekend) in the depths of the Great Depression –  at a time when the predominant macro risk (reflected in market prices themselves) is deflation.  Just largely irrelevant for now.

There is much talk of the government simply borrowing from “its own bank”, the Reserve Bank.  But the Social Creditors don’t seem to realise that there is really no such thing –  in any substantive sense.  After all, to most intents and purposes the Reserve Bank is just another division of the government –  the bit the banks bank with.

Take a really really oversimplified example.  The government wants to spend $20 billion in the depths of the recession and gets the Reserve Bank Governor to agree to lend it $20 billion (the government’s account at the Reserve Bank goes up by $20 billion and the Bank’s holdings of government bonds go up by $20 billion).  For most macro purposes, the interest rates charged/paid on either leg doesn’t really matter.

Now, assume the government goes and spends the money, perhaps distributing it in something like the wage subsidy programme.  The government’s operating account at the Reserve Bank will drop by $20 billion, and the accounts the banks hold at the Reserve Bank will rise by $20 billion (as recipients of the wage subsidy payouts bank the proceeds).

For the government sector as a whole, the net effect of this set of transactions in that the government sector has borrowed $20 billion from the banks.

Which is just what Social Credit thought they were avoiding.    They weren’t.  And the other relevant detail here is that the Reserve Bank pays interest on those deposits banks hold with them: at present 0.25 per cent per annum on the entire stock.

Banks, of course, have their own liabilities on the other side of their balance sheets, on which they too pay interest.    Some of them might be “wealthy foreigners”.  Others will be Grandma.

And what determines (or is supposed to determine) the rate the Reserve Bank pays on the deposits banks hold with it –  the OCR?  Why, that would be the inflation outlook, since they are required to aim to keep inflation at or near the target the Minister of Finance sets for them.

Perhaps advocates of Social Credit will be saying “ah, but 0.25 per cent is still cheaper than the interest rates the government might pay if it issued the bonds directly on market” (at present, long-term bond yields are a bit below 1 per cent, but would be higher than that if the Reserve Bank were not in the secondary market).   And that is true, but a 10 or 15 year bond yield is capturing, among other things, implicit expectations as to what monetary policy will be doing –  where the OCR will be set –  for the next 10 or 15 years.  Perhaps rightly, perhaps wrongly, at present the consensus view is that on average over that period the OCR will be higher than it is now, once the economy gets back to something more like full employment.

If that is right then, all else equal, even if the government has locked in zero interest funding itself from the Reserve Bank at zero per cent interest, the Reserve Bank would find itself having to pay higher interest rates over time to holders of settlement cash balances (or it might auction off some of its bonds to reduce settlement cash balances, but the macro effect would be much the same).    Reserve Bank interest expenses are a net cost to the Crown just as surely as if the Crown issued the debt directly on market.

And if the Reserve Bank did not make those adjustments –  higher OCR if and when inflation pressures eventually recovered – the result would be higher inflation.  And high inflation would be just as surely a “tax” –  transferring real resources from the public to the Crown –  as the taxes Social Credit claims they offer a path to avoid.

Perhaps the bigger problem still is that the Social Credit proposals are probably inadequate to the needs of the hour.

As I’ve noted in various posts in the last week or so, the Reserve Bank has added a huge amount to banks’ settlement account balances in total (balances last week were more than $20 billion higher than usual).  The “money supply” –  particular aggregate measures the Bank publishes – will also have increased to some extent (we’ll be waiting for weeks to see the end-April numbers).   But the higher settlement cash balances simply don’t mean very much.  For banks, it is just another asset –  a rock-solid one (which must be welcome) paying a reasonable interest rate for now, 0.25 per cent.    It isn’t as if there is much real effective credit demand at present, and the nervousness of many households and firms is probably reflected in quite a strong desire to save.

And whichever mechanism the Reserve Bank uses to buy bonds isn’t itself affecting how much the government is spending.  You might think (I suspect Social Credit do) that the government should be spending more.  That’s fine, but it won’t have any problem raising those funds –  whether it does so by issuing bonds on market, or issuing them to the Reserve Bank.  And it isn’t as if a shortage of settlement cash is constraining bank lending at present –  instead it is primarily weak demand from demonstrably creditworthy borrowers and perhaps an absence of attractive projects to fund (two sides of the much the same coin).

If the Social Creditors wanted a monetary policy that made a real difference in the current climate they’d give up their small ambitions and focus instead on where the big gains might really be on offer.

Perhaps a 1 per cent interest rate sounded really low to Major Douglas back in the 1920s, or to Social Creditors in most of the decades since.     These days it would be a very high interest rate, quite out of line with the needs of the economy.   Same goes for that 0.25 per cent the Reserve Bank is paying on the tens of billions of settlement cash balances.   Same really goes for zero, when so much of the government debt of major advanced economies has been earning a negative yield for some time.  Not surprisingly then, on the one hand our exchange rate is staying quite strong –  really unusual for a serious New Zealand recession –  and expectations about future inflation are falling (in turn raising the real interest rate –  a simply insane outcome in the midst of a deep recession with a highly creditworthy sovereign borrower).  But it isn’t wealthy investors or evil foreign banks who are determining that our interest rates are still so high: instead, it is Adrian Orr (and his Monetary Policy Committee, several of whom share the Governor’s left-wing credentials) and Grant Robertson, he who is always talking about the significance of full employment, but yet who does nothing to bring about the much lower (short-term) interest rates the current situation calls for.   Even in the last US recession, highly orthodox researchers within the Federal Reserve system concluded that a Fed funds rate of more like -5 per cent would have been helpful.  Our starting point this time, is worse than the US’s in 2008 (the Fed funds rate then started at 5.25 per cent).

In this environment, Social Credit is a distraction, but then so is the Governor’s bond-buying programme itself.    As in the Great Depression it was breaking free of the “golden fetters” that eventually allowed robust recovery, so this time it is the self-imposed “paper chains” – the refusal to do anything about seriously negative interest rates, that will impede prospects for any sort of robust recovery (and, not incidentially, worsen the worthy outcomes in the Social Credit graphic above).  Bond-buying programmes at yields well above the current natural rate of interest are just flashy-sounding asset swaps with little macro significance.

(And in case people are worrying about threats to central bank independence, recall that (a) the Bank’s current bond-buying programme, and any purchases it might in future make directly from the Crown, are a discretionary choice for Bank, and subject to the inflation target, and (b) central bank independence is not an absolute, or even always helpful –  the Fed, for example, was independent in the early 1930s and consistently resistant to doing very much of what needed to be done to get the US economy going (statutory powers for the Minister to (a) set the Bank’s target, and (b) override the Bank in some circumstances, but openly, exist for a reason).

And two final historical points:

  • one of the quotes Social Credit use is from Bernard Hickey about the 1930s.  Not only was the macro environment rather different –  fixed exchange rate and all that –  but the experiment did not end well (being used when the economy was already back near full employment) leading to a crisis in which a sovereign default would have been the outcome but for the looming war, and the imposition of tough exchange controls that took decades to get rid off
  • Canterbury economics academic Paul Walker has links here to a couple of pieces on Social Credit from the 1950s, including extracts from the Royal Commission report.