China’s fertility rate in an Asian perspective

The media are full of stories of the Chinese government/party decision to abandon the evil one-child policy and replace it with a marginally less evil two-child policy.  It is interesting to see the change presented by the authorities as a response to an ageing population, and I’ve seen various commentaries over the last few years suggesting that this easing could make a difference to the economic prospects of China, even perhaps only over the shorter-term as some couples took advantage of the slightly less repressive regime.

As a rank outsider, I’ve been more than a little sceptical since I started paying attention a few years ago to birth rates in the rest of Asia, and especially in the wealthier bits of Asia, to which China has been making some progress in converging.  As far as I know, in none of these countries have there been direct attempts by governments to suppress, by regulation, the birth rates (indeed, Singapore has been actively trying to encourage a higher birth rate).

Here is the time series (from the World Bank database) for China, Japan, and the four other predominantly ethnic Chinese countries/territories (Taiwan, Singapore, Hong Kong and Macao).

tfr time series

And here, from the CIA Factbook are the countries/territories with the lowest total fertility rates in the world, plus China and Thailand.  (The levels are slightly different in the two different sources –  the CIA numbers are 2015 estimates –  but the broad picture is the same).

tfr

The countries with the greatest cultural similarity to China have the lowest fertility rates in the entire world –  only around one child per woman.  The other advanced Asian economies (Japan and Korea) are only a little higher, and one of the other emerging middle income Asian countries (Thailand) already has a TFR below that of China (although, on the other hand, Malaysia’s is higher).

Perhaps the policy change will materially boost China’s birth rate, but it would really stand out relative to the rest of advanced and emerging Asia if that were to happen.

Who speaks for the 35000 unnecessarily out of work?

The Labour Party’s finance spokesperson, Grant Robertson, yesterday took the opportunity of today’s OCR review to make another statement on monetary policy.  I was pretty critical of his previous effort, which seemed to involve trying to blame Bill English for Graeme Wheeler’s errors and misjudgements.

The latest statement is little more inspiring.  It was good to see him focus on the high and rising rate of unemployment, and to point out that inflation hasn’t been at the 2 per cent midpoint since that target was set three years ago.

But he wants to use this record as a basis for amending the Reserve Bank Act to “put employment up as a core objective“.  I presume he would really mean low unemployment, since the Reserve Bank would (reasonably) point out that employment growth and participation rates have done quite well over the last few years.  And unemployment is the measure of excess capacity in the labour market.

Robertson talks about a dilemma that the Governor apparently faces.  But there simply isn’t one.  Inflation (and more particularly core inflation measures) is well below where it should be, and unemployment is (rising and is) much higher than it needs to be (than any plausible NAIRU).  That is a classic case of a demand shortfall, and the standard prescription is looser monetary policy.  Lower interest rates and a lower exchange rate will tend to raise both activity and inflation, and lower unemployment.

There are times when monetary policy faces hard choices –  when keeping inflation near the target might involve measures that will temporarily raise unemployment.    Some of them are explicitly addressed in the Policy Targets Agreement (and have been ever since 1990), and others are captured in a more general way –  the PTA is quite clear, for example, that the focus of monetary policy is supposed to be on the medium-term trend in inflation, not the near-term wobbles.  And, for better or worse, for 15 years the PTA has explicitly enjoined the Bank to avoid unnecessary variability in output.

I’m not a diehard defender of the way the monetary policy bits of the Reserve Bank Act are worded, or even of inflation targeting itself.  There might even be some sensible ways of formulating section 8 of the Act to include references to unemployment.  But section 8 of the Reserve Bank Act has almost nothing to do with the combination (persistent low inflation and persistent high unemployment) that Robertson rightly worries about.   Rather those outcomes are about a persistent series of misjudgements by the Governor (and, apparently, most of his advisers).

I’ve pointed out previously that central banks in other countries have also been taken by surprise by the events of the last few years.   But most of them have reached the limits of conventional monetary policy.  Several – including the ECB and the Swedish Riksbank –  even started to tighten, only to have to fully reverse those tightenings.   But the Reserve Bank of New Zealand is the only advanced country central bank that has (a) never been constrained by the near-zero bound on nominal interest rates, and (b) has twice (repeat twice) started tightening only to have to reverse itself again.    Taken together with the outcomes (too-low inflation, and too-high unemployment) it is a pretty poor track record.  And the Bank –  the Governor, recalling that the system is one of personalised accountability – has not been seriously called to account for that failure.

Legal responsibility for calling the Governor to account rests with the Minister of Finance and the Reserve Bank’s Board.  As I’ve noted, the Board seems to see itself as champions and defenders of the Bank, rather than being there to provide serious scrutiny and challenge.  And it isn’t clear that the Minister does more than grumble privately, and occasionally make slightly cryptic public asides.

But where has the political Opposition been?  In both his last two statements, Robertson absolves the Governor of any responsibility –  in his view the problem is the mandate, or even the Minister, not the month to month choices the Governor has actually been making.

Perhaps it is easy to call for changes in the mandate. It isn’t going to happen any time soon..  It might be harder to actually have a go at the Governor.  And one shouldn’t do so lightly, but this is an episode of repeated failure, and a stubborn reluctance to acknowledge, or learn the lessons from, those failures.  Of course, lots of the great and good have agreed with the Governor’s stance –  as I’ve pointed out before the NZIER Shadow Board’s recommendation have tended to mirror what the Governor actually does.  But they have been wrong, not just once, but again and again.  And the Governor is the person who is paid to get it right more often than not.   Why isn’t Robertson taking more of a stand and saying so.

And what about the governance arrangements?  Robertson notes that the Act was passed in the 1980s and is ‘out of date and out of touch with changes in the global economy’.  But if he looks at central banking legislation around the world what he will really find is that it is the governance aspects of the Bank –  the single decision-maker –  that look odd.  As the Reserve Bank’s survey showed, there is a wide variety of ways of expressing the statutory objectives for monetary policy, but there has been no trend away from something like a medium-term focus on price stability.  Our Governor simply has too much power.  Treasury reports that the Minister likes the current model because it provides better accountability, but where is the evidence of the accountability in the failures of the last few years?  The Minister can’t be blamed for who was appointed as Governor –  he had to appoint someone the Board nominated –  but he and the Board can, and should, be blamed for how little effective accountability there has been.

The unemployment rate is currently 5.9 per cent (and expected to rise further).  A reasonable estimate of the NAIRU might be 4.5 per cent.  If so, that is about 35000 people who are unemployed now who might not be unemployed if the Governor had run monetary policy, within his current mandate, rather better.  Even if the NAIRU, is nearer 5 per cent, it is still more than 20000 people unnecessarily out of work.   Does he get out and meet any of these people?  If so, I wonder how he explains his failure, and excuses the way his choices have blighted the lives of these people?

I suspect the answer to my question is “no”.  In fact, I just had a quick look through the list of audiences the Governor has given on-the-record speeches to since he took office.   There are various official forums and conferences, but not one of the remaining nine speeches was to groups representing workers, beneficiaries, or the wider community.  Most are to top-end business audiences (the “Admiral’s Breakfast Club” in Auckland, the Institute of Directors, INFINZ, Chambers of Commerce etc), and speeches given by the Deputy Governors seem to be to equally select audiences.  Perhaps the Governor gets no invitations from other sorts of groups, although in my experience that is unlikely.  Perhaps he gives lots of off-the-record speeches to such groups, and just by coincidence it is only the on-the-record speeches that were to upper-end business groups?

I’m not suggesting that the Governor is exercising anything other than his best judgement in making OCR decisions.   And his business audiences would also typically have been better off if the Bank had not been persistently and unnecessarily holding back the recovery, but his choices typically hit hardest on those at the bottom.  And it isn’t apparent that he is even listening to their plight, simply taking comfort from the echo chamber of the elite.

Traditionally, one might have expected an Opposition Labour Party to be their loud and clear voice.  Robertson’s is currently anything but that.

Thinking about housing again

I gave a talk in Nelson last night on housing issues.  It was largely a rework of material I’ve used before (posted here and here) so I won’t post the text here.   I’m not sure the speech quite hit the mark for the audience, but as always when I put together a presentation I find that I learn something in the process, or  some things come together more clearly in my own mind.

By Auckland standards, Nelson-Tasman house prices aren’t that high.   In real terms, house prices are still lower than they were in 2007.   But a median house price of around $400000 against a median household income of not much over $60000 reminds us just how high price to income ratios are across most of New Zealand (my old home town of Kawerau remains an unattractive exception).  Most of the “problem” is in the land.

As I often do, I devoted a bit of time to explaining why I don’t think features of the tax system are a material part of the explanation for high New Zealand house prices, or for the cycles that we –  and other countries  – experience.  As a slight counterbalance, I took the opportunity to put in another plug for land-value rating by local authorities, a case also recently made by the Productivity Commission.  Most New Zealand local authorities now use capital value rating, which – relative to a land value base –  provides less of an incentive to bring vacant land into development.  In principle, and all else equal, greater use of land value rating should help to dampen urban land prices, and close the gap between rural and peripheral urban land prices.

But one of the audience, a highly-respected figure in Nelson, with decades of experience in the building industry and on the local council, pointed out to me that Nelson city had, some decades ago, moved to land value rating.    Urban land prices remain very high.  It isn’t obvious that land value rating has been very helpful in easing land supply pressures.  Then again, nothing operates in isolation.  Neighbouring Tasman District Council, where much of the (flat land and) population and housing growth has been, still operates a capital value rating system.  And an ever-growing District Plan, that now runs to 1000 pages in Nelson City, probably has not a little to do with the continuing high land prices, and the continued excessively costly houses, in that part of the country.

A variety of factors no doubt explain the shift to capital value rating, although one can’t help wondering if the pervasive biases of so many councils towards more intensive, rather than extensive, development isn’t part of the story.  Many councils really don’t seem to want more land developed, or they want it developed only at a pace that suits them.  It is probably unrealistic to think that councils would favour a move back towards land value rating when those same councils are the ones applying land use restrictions in the first place.  If councils were committed to making urban land affordable, they could quite readily do it now.    Instead, as the Productivity Commission put it –  seemingly approvingly –  in its report last week:

Many urban councils in New Zealand have a clear idea about how they want to develop in the future, and how they intend to meet a growing population demand for housing.  Many larger cities have chosen to pursue a compact urban form.  Yet some of our cities have difficulty in giving effect to this strategy”.

Sadly, the Productivity Commission seems to see councils, and the planning regime, as part of the solution rather than as a large part of the problem.

I hadn’t been thinking much about housing while I was on holiday, but a conversation with friends we were staying with, in their growing prosperous (2 per cent unemployment rate) Midwest small college city, had got me thinking. I’d asked about local house prices and they’d commented that their house was probably worth about US$175000 –  decent-sized section, four bedrooms, and five minutes walk from the local college.  And they observed that prices had been moving up, and local sentiment was that they were really quite expensive.  In exchange I offered them scare stories about Island Bay prices, and vague references to the scandalous Auckland prices.

I didn’t give it much more thought until I got home and started preparing last night’s talk.  That observation that US$175000 was quite expensive was still running round in my head, and so I printed out the latest Demographia tables.  I’ve often used Houston as an example of a large, fast-growing, city with very moderate house prices –  in fact, lower in real terms than they were 35 years ago.   But, actually, Houston prices aren’t at the low end of the range –  the median house price was about US$200000 there last year.  Astonishingly cheap, absolutely and relative to income, by New Zealand standards but not by US standards.   Detroit (inner city) is a byword for cheap, but among cities with over a million people (and remember that Auckland hasn’t that many more than a million), these places last year had median house prices in a range of US140-175K (and price to income ratios of around 3).

Cincinnati

Grand Rapids

Pittsburgh

St Louis

Atlanta

Indianapolis

Kansas City

Louisville

Columbus

Oklahoma City

Memphis

Tampa

And there are dozens of other similarly affordable smaller cities.  I haven’t checked each of them, but I suspect “densification” hasn’t been a big part of keeping housing affordable.

Of course, the US has places at the other end of the range as well –  places I’ve barely heard of as well as Los Angeles, Honolulu, San Diego, San Francisco, and so on.

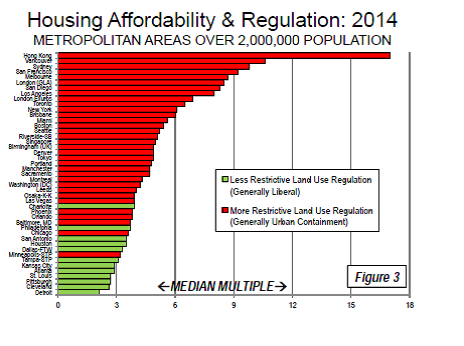
What marks out one group from the other isn’t being a “global city”, or a growing city:  it is mostly the land-use restrictions.  As Demographia highlight,  there are no cities  with high house price to income ratios that have liberal land-use regimes.

demographia

Which brings me back to a speech given last month by Bill English on housing affordability.  I noticed it has even been getting some coverage abroad, and it certainly has some useful perspectives on some of the issues (although looking through my copy I noticed I’ve scrawled “dubious” in a surprising number of places).  I liked the idea that our Deputy Prime Minister was making the case that urban planning has become a net drag on the country, and especially on its poorer and more vulnerable people, for whom housing has become progressively less affordable.  I was surprised to learn that the government now subsidises 60 per cent of all rentals in New Zealand.  And as the Minister notes of the 3000 page Auckland Unitary Plan “no one person [ or, one might add, no committee or Council] could possibly understand all the trade-offs in that plan”, or the implications of those choices.

I did, however, splutter at the suggestion that planning was an externality that central government might have to deal with just like “other externalities, such as pollution”.  The Minister seems to conveniently forget that the powers local governments have all flow directly from central government legislation – the centrepiece of which, the Resource Management Act, was passed by a government in which he served as junior backbencher.  Individual members of central and local governments may have their hearts in the right place, but this is ultimately a problem of central government failure at least as much as of local government failure.

And there are few signs that the problems are going away.  But perhaps that shouldn’t surprise us.  As I’ve noted here previously, I’m not aware of any examples of places in advanced economies where tight land use restrictions once in place have ever sustainably been removed.  When I first made this observation, I made it pretty tentatively.  I’m not an expert in the details of urban planning or familiar with the hundreds of individual regimes in various countries.  I was half-expecting that someone would come back to me quite quickly pointing me to a compelling case study of successful liberalisation.  So far no one has.  And I haven’t heard the Minister of Finance or the Minister of Housing highlight such studies.  I haven’t seen the New Zealand Initiative do so, and I haven’t seen Demographia do so, even though they have every incentive to highlight such examples if they exist.  I still hope there are such case studies out there, but it looks increasingly unlikely.

Bad policies don’t last for ever, but they can carry on for a  very long time.  I highlighted last night that New Zealand once had the unique feature of a car market where second-hand cars held their value and (by repute at least) were at times worth more than new cars.  My maternal grandfather often liked to tell the story that he reckoned my father was keen on marrying my mother as much because she owned a car as anything else (she’d done an OE and had overseas funds).  The insanity of the import licensing and local assembly regime eventually came to end, but it took a very long time –  sixty years or more.  Is there any reason to be more optimistic that housing will once again be affordable in New Zealand any decade soon?  If house prices had been bid up simply on the back of reckless bank lending policies, then perhaps so. But that isn’t the New Zealand story. Ours is a story of microeconomic policies, implemented and maintained by successive central and local governments, with the clear and predictable effect of making housing, and the sort of housing people want, much less affordable than it needs to be.

Fallow: the case for a lower OCR is compelling

Brian Fallow’s weekly column in the Herald yesterday  was fairly pointed.

Some further easing in the official cash rate seems likely, Reserve Bank governor Graeme Wheeler reiterated last week.

Well, good.

Because the case for more easing is compelling.

I agree with him.  Whatever measure of inflation one uses –  headline, exclusion measures, filtered measures  –  inflation has been persistently below where the Governor agreed to keep it, and shows no sign of rising (much or for long) any time soon.  On the Reserve Bank’s own numbers, the output gap is still modestly negative, and the unemployment rate has risen and is above any sort of NAIRU estimate.

But that wasn’t my reason for writing.  Instead, Brian notes a few considerations, including those mentioned in the Governor’s recent speech,  that might hold the Governor back

Housing is the first.  The Governor appears to have reversed himself, and gone back to thinking that (Auckland) house prices should be a factor in setting monetary policy.  But the Minister of Finance mandated him to target the medium trend in consumer price inflation, and New Zealand’s measure of consumer price inflation does not  –  rightly in my view (and that of most others) –  include existing house  prices or land prices.   House price inflation in Auckland is certainly scandalous, but the responsibility for that outcome is directly attributable to the choices of elected central and local governments.  The Reserve Bank’s role should simply be –  and in statute is –  to ensure that banks are sufficiently resilient to cope if nominal house prices ever fall sharply.

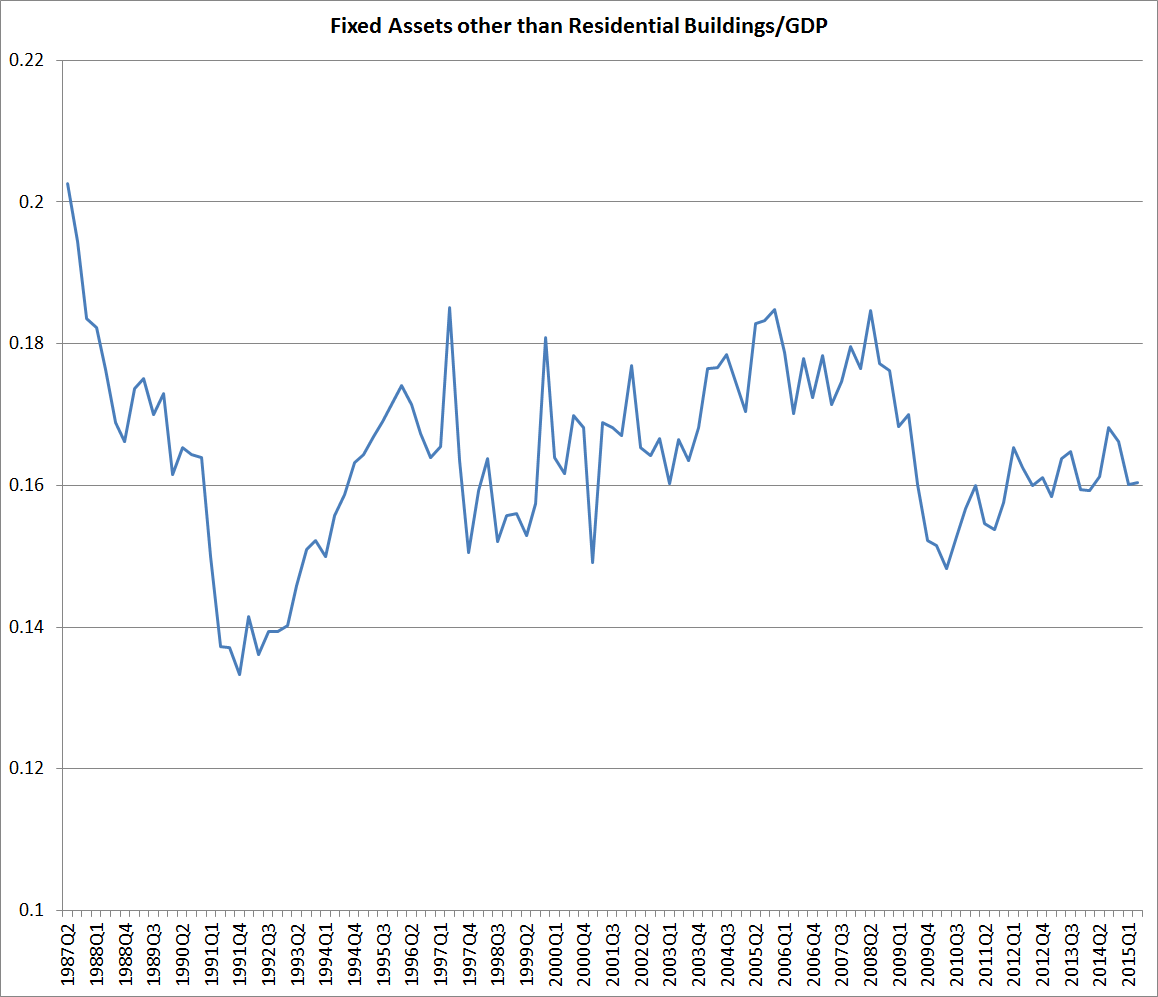
The second issue related to investment.  The Governor had suggested that the Bank needed to ask “whether borrowing costs are constraining investment”.   It isn’t clear why the Governor regards that as a relevant consideration –  absent some wild investment excess (1987 perhaps?), more private sector investment is generally a good thing.   Brian Fallow suggests that investment is sufficiently strong that there is no issue on that score anyway.  I’m not sure I agree.  Excluding residential investment, investment as a share of GDP remains pretty subdued. Historically, business investment as a share of GDP has been surprisingly low  in New Zealand relative to that in other advanced countries, given our faster trend rate of population growth, and now investment is low even relative to that history.  And that despite the rapid rate of population growth in the last couple of years.

investment to gdp

Not that the government’s ambitious export growth target is any concern of the Reserve Bank’s, but it is difficult to see anything like the targeted transformation in export performance occurring with these sorts of investment rates.  Of course, the big issue there is likely to be the real exchange rate –  still sufficiently high that even the Governor seems to comment on it whenever he can.

I touched last week on how odd it is to think of holding back on cuts now to save ammunition in case things get really bad again.  But Brian comes back to this issue by another angle.

But we can’t forget that New Zealand remains abjectly reliant on importing the savings of foreigners. The risk premium they demand to keep on doing that puts a floor under banks’ funding costs and the interest rates borrowers see, regardless of how low the OCR might go.

Here I think he is wrong.  I’ve dealt previously with the question of whether foreign lenders typically demand a “risk premium” for lending to New Zealanders (in NZ dollars).  The evidence strongly suggests that they don’t – and haven’t.    But if they were particularly concerned about New Zealand risk, there are two ways to get compensated for that risk.  The first would be to seek a higher interest rate.  They couldn’t typically get it at the short end, since the Reserve Bank itself directly sets the OCR based on domestic conditions.  They might perhaps get it on longer-dated assets (bonds), but expectations of the future OCR typically play the most important role in influencing the level of longer-term interest rates.

A much more plausible place to see any risk premium, in a floating exchange rate country, would be in the level of the exchange rate –  in other words, a surprisingly weak exchange rate.  Nervous foreign investors would be reluctant to buy NZD instruments at the interest rate set on those assets by domestic economic conditions.  But they might be happier to do so if the exchange rate were lower.  A lower exchange rate today, all else equal, means more prospect of some appreciation (and extra returns) in future.  It is a bit like the share market –  if concerns about a company, or the whole market rise, investors get compensation for the additional risk through a lower share price.  The lower exchange rate, in turn, helps rebalance the economy and reduces, over time, perceptions of risk.

But in thirty years of a floating exchange rate, I can think of only a handful of occasions when New Zealand’s exchange rate has been surprisingly weak (relative to New Zealand cyclical fundamentals)  –  most obviously at the height of the global crisis in 2008/09.  Global risk aversion was then at its height, and the NZD was caught in the backwash.  It isn’t a remotely typical story, and there is no sign that it is relevant now.  As the Governor keeps noting, the exchange rate is still rather high.

A materially lower OCR would lower domestic borrowing rates, which would provide a little support to lift investment.  But even if it did nothing at all on the score, it would work by lowering the exchange rate, in turn boosting returns to actual and prospective exporters.  Yes, it would increase the cost of domestic consumption a little, but the trade-off would be a stronger recovery, more resilient against any new wave of adverse shocks, lower unemployment, and –  not at all incidentally –  measures of medium-term inflation which would be rather nearer the rate the Minister of Finance asked the Governor to achieve.

The Reserve Bank apparently agonised for a while in 2008/09 about this idea that a too-low OCR might somehow create troubles with foreign investors.    Given the pace of the fall in the exchange rate during the international crisis, and the novelty of such low interest rates, they were perhaps understandable questions then.   But I doubt it is a factor that weighs much in the Governor’s deliberations now.  We shouldn’t welcome foreign investor concerns or heightened perceptions of risk –  they are a real cost –  but if those concerns exist, we are likely to be much better off absorbing them in a depreciated exchange rate, than trying to lean against them with unnecessarily high interest rates.  The alternative (‘lean against”) approach has usually been damaging, or disastrous, wherever it has been tried (think of all too many emerging market crises).

In the end, I think Brian agrees.

Even so, rather than keeping powder dry, the better way of mitigating the effects of another negative shock from the rest of the world might be for the bank to impart as much momentum as it can to the economy before the headwinds turn gale force.

It isn’t always and everywhere good advice, but given our continuing anaemic economic performance, it seems like very good advice right now, whether or not the headwinds ever gain further strength.  The debate probably shouldn’t be around whether the OCR should be 2.75 or 2.5, but why it should not quickly be cut to something more like 1.75 per cent.

The Treasury on Reserve Bank governance

Regular readers will know that one of the constants of this blog has been making the case for reforming, and modernising, the governance of the Reserve Bank.  The current model is out of step with international practice, and with the way other government agencies are run in New Zealand.   I’ve held this view for a long time, although the concerns are becoming more pressing as the Reserve Bank assumes, and is given, ever more discretionary power.     The current Governor is probably in the wrong job  (a huge role, making the holder probably the most powerful unelected person in New Zealand).  But the case for reform would be strong even if we had the best conceivable person as Governor.  Typically, we will have someone who is about average.

There has been a growing recognition of the case for change.  In 2012 The Treasury recommended to the Minister of Finance, before the current Governor was appointed, that further work be undertaken with a view towards moving to a committee-based decision-making framework.  At the time they found that most market economists were sympathetic to change.  At a political level, the Green Party has openly and repeatedly argued for change, while the Labour Party has come and gone on the issue.  But it isn’t an obviously ideological issue –  just a matter of finding a good governance model for an increasingly powerful New Zealand policy agency.

Graeme Wheeler himself recognised some of the weaknesses of the current system, and established the Governing Committee as the forum in which major decisions would be made.  He retains the legal power, and all the other members of the committee owe their positions, and remuneration, to the Governor, but in principle it represented a small step forward.  Whether it represents any real gain is impossible for outsiders to tell.  The Bank has flatly refused to release minutes of the meetings of the Committee, on any topic whatever, and –  in truth –  governance arrangements are really only tested in times of stress, and where there might be strong differences of view. Quasi-insiders –  the Bank’s Board –  could provide us with an assessment of how the new model is working, but their Annual Reports suggest that they are more interested in being champions of the Governor and the Bank rather than in providing substantive reports analysing and scrutinising the performance of the Governor and Bank.

The Bank has also refused to release any papers from its own work on reforming the governance model.  That refusal confirmed that a substantial amount of work had been done, at least some of which had been discussed with the Minister of Finance.

Fortunately, the Treasury generally takes a more accommodative approach to Official Information Act requests.  There are plenty of things about The Treasury that I am critical of, but they seem over the years to have displayed considerably more respect for the spirit of the Official Information Act and its role in New Zealand’s system of governance.  When the Reserve Bank refused my request for governance papers, I lodged a very similar request with The Treasury.

Yesterday, they released several papers, which are available here.

Treasury governance papers OIA response

There are a couple of nice and substantive background papers.  Some are focused just on monetary policy governance, but Treasury also recognises that the Reserve Bank has a much wider range of functions, and hence that any review of the legislative governance model really needs to look at the entire institution and all its roles and responsibilities.

Treasury still appears to favour change.   In particular, in a June paper to the Minister of Finance, commenting on the Reserve Bank’s draft Statement of Intent (page 48 in the release document) they note:

A key change from the previous year’s SOI is that a workstream on “best practice institutional frameworks…has been dropped.  In the Treasury’s view, this workstream would be worth continuing.  Nevertheless, we understand that the decision to drop this workstream is consistent with your feedback that the current decision making structure best supports accountability.

Recommendation

Note that the RBNZ is discontinuing its workstream on “best practice institutional frameworks”.  The Treasury would prefer this workstream to continue.

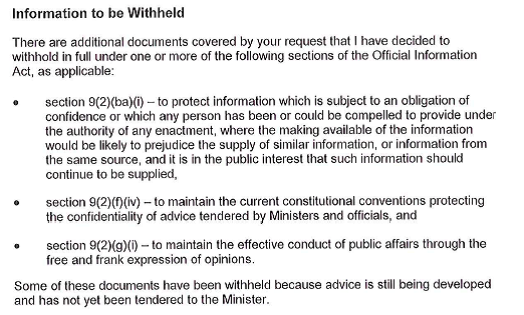
They have withheld a variety of other documents.  I’m not sure quite what the first ground (below) means in this context –  perhaps information from foreign agencies? –  but what is interesting is that the statement declining to release the other documents reveals that Treasury is continuing its own work on the issue.

Tsy governance OIA

At one level, it is nice to finally have public confirmation of the fact that the Minister of Finance has again rejected reforming the governance of the Reserve Bank.  Treasury reports that this is because the Minister thinks a single decision-maker best supports accountability.  But hardly any other country agrees with Mr English, and none do so among those who have reformed their arrangements for the central bank and financial supervision activities in the last couple of decades.    And we don’t apply that model to any other area in public life in which government agencies are making policy decisions.   There is a strong case for change, and no doubt in time change will happen.   It is a shame that the Minister is clinging to an outdated model, which is not serving New Zealand that well.  But well done to the Treasury for continuing the background work in thinking through the issues and options,

1876 revisited?

The New Zealand Initiative was out this week with a new report, In the Zone: Creating a Toolbox for Regional Prosperity.

If I’ve understood correctly their proposal, local authorities would be able to seek approval from central government to run policy experiments in their own areas (freeing up the Overseas Investment Act, legalising drugs, prohibiting prostitution, banning private schools, introducing capital punishment, banning immigration –  or the reverse of each of these).

Frankly, it seemed to be a solution in search of a problem.  I’m all in favour of a bit of localised regulatory competition –  the sort of thing that was, for example, possible in respect of building and land supply in Auckland before the ACT Party leader legislated to merge all the councils in the Auckland region into a single body.    The authors rightly cite the advantages the US federal system offers –  data on all sorts of different approaches to doing things.  And I wouldn’t challenge that.  But the data from those experiments are widely available.  Same goes for the Canadian provinces, or –  nearer to home – the Australian states. Or insights from different countries within, say, advanced country groupings such as the OECD.   In fact, in many areas New Zealand ministers already participate in the Australian inter-governmental councils, sharing experiences.  Perhaps the report would have benefited from some Australian perspectives –  including on the relentless rise of the federal government at the expense of the states.

But as the authors note, New Zealand’s population is around that of a median US state.  And we’ve been along this way before –  the provincial governments that played such a major role in New Zealand government (in many ways more important than central government) until they were abolished in 1876.  Indeed, the NZI authors prompted me to pull down from the shelves my copy of Morrell’s history of the provincial system –  a system ended for a mix of good and bad reasons.

The authors are keen on regulatory competition, but pull back from favouring the re-establishment of provinces.  It isn’t quite clear why.  They argue that “a federal system could be too costly in a small country” but then note that

We risk too little recognition of regional differences under our current domestic policy settings.  New Zealand is not expansive enough in size or disparate enough socially or culturally to warrant having a federal system of governance.  But national level policies do impose challenges to regional growth that could be better addressed through regionally specific regulation.

In some cases, perhaps.  But it is only going to happen, to any material extent, if something like a federal system was established and entrenched.  In other words, if the ex ante power is genuinely given over to local authorities  And even then, in provincial/federal systems the interests and needs of Toronto or Sydney frequently differ from those of remote rural bits of Ontario or New South Wales.

To see the problem, take one of NZI’s proposals.  They argue that the West Coast local authorities could seek specific RMA amendments to better support mining developments. But why do they think that environmentalists in Auckland or Wellington would be more willing to see the law changed just because it would apply only to the West Coast?  People think of the West Coast as part of one country, their country, and those opposed to mining would fight tooth and nail against any legislation that central government sought to pass to create this specific regional dispensation.  The words “thin end of the wedge” will pop up repeatedly whenever one of these proposals is made.   CAFCA won’t be any more relaxed about freeing up foreign investment, just because the initial exemption is only for Wellington.

After all, as the authors suggest, the central government should only agree to dispensations it would be happy to see applied everywhere.  Quite how this discipline would be enforced  –  especially since each dispensation would presumably have to be legislated separately – is not made clear in the NZI document.  Nor how they would prevent an incoming central governments of a different political complexion simply repealing all regional provisions that they didn’t like.

And I don’t see why they think a federal system might be too costly but their system would be materially cheaper or better.  Their system seems to be a recipe for each of the regional councils, or possibly territorial authorities (of which there are almost 70), to grow their own bureaucracies, to identify better policies across a whole range of possible areas than those dreamed up centrally.  And since all these experiments would have to be approved (and legislated)  centrally –  unlike in genuine federal systems –  it isn’t clear that the NZI reform would not further increase the size of the Wellington bureaucracy.  Small countries can –  and do –  manage to succeed, but we need to recognise just how limited the stock of capable policy bureaucrats is in a small country.  In a country of 4 million people I’m not sure the case is strong for competing immigration (or drugs, or crime, or education, or…) policy managers in Invercargill, Gisborne, Christchurch and Auckland.

It all seems to involve a vision of capable well-intentioned people on both sides.  Actual politics is a great deal messier, with deals done to assist supporters or more general electoral prospects in particular regions.   And many differences on policy are differences of values –  and only a minority of those differences divide regionally.

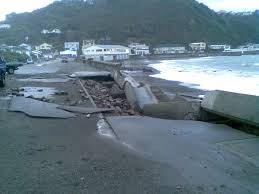
The authors reasonably caution us against automatically regarding central government as competent and local government as incompetent. As they note, even central government put money into the debacle that was the Dunedin Stadium –  although amounts that were chickenfeed relative to the national budget.  And Think Big –  the energy resource development strategy from the 1980s –  certainly swamps any regional or territorial bad policy choices.  But there is something to be said for specialisation.  Local governments often don’t do the basics that well, and do worse the further they get from basics.  If, to take a local example,  two years after the storm, the Wellington City Council still hasn’t fixed a short local stretch of seawall, I certainly can’t count on central government doing so.

seawall

Local governments already seem too busy and self-important with grandiose ten year economic development plans – imposing visions of who should live where, in what sort of accommodation, or promoting uneconomic runway extensions.    Pandas anyone?   And for all the talk of greater flexibility of land supply, has any local council anywhere in New Zealand –  even where there is no huge growth pressure – gone to the limits of the current law in freeing up residential land supply?  The New Zealand Initiative and the Productivity Commission (in their new report yesterday) seem to have acquired a touching faith in local councils, frustrated either by their voters or central government –  but what that faith is based on is less than clear.

The authors enthusiastically cite the Shenzhen special economic zone.   We should always pause and reconsider when advocates for reform cite Chinese examples.  As a reminder, China is a struggling repressive middle income country  – where central government is firmly in control –  and whose economic performance over the last 200 years makes even New Zealand look good.  Oh, and that is before starting on the matter of the number of their own people policymakers have been responsible for the deaths of (whether in famine, civil war, or in utero).

Trials and experiments are, no doubt, good things.  But this NZI proposal does not look like one of those experiments that should be given a chance to fly.  I’m a South Islander by birth and inclination, and if someone proposed a genuine federal model for New Zealand –  South Island, lower North Island, and Upper North Island –  I’d probably be emotionally sympathetic to it.  But even then I’d refer supporters to the Australian experience, and wonder just how much genuine decentralisation would occur and for how long.  Fortunately, perhaps, the differences among the regions are not yet so great that people see their primary identity as regional rather than national.  Unless that changes, the big policy fights –  including over reducing the economic role of government –  will just have to go on at a national level, as they mostly do in Australia.

UPDATE:  I’ve been pointed to some similarly sceptical remarks by the Deputy Chair of Parliament’s Finance and Expenditure Committee made at the launch of the NZI report.  (Being a Wellington MP, he nonetheless seems disconcertingly sympathetic to the runway extension.)

If only economic performance matched the rugby

I’m not much of a rugby fan, but even I noticed a certain amount of enthusiastic coverage of the All Blacks’ comprehensive defeat of France last weekend.

If only we could match that performance in the economic comparisons.

Over the long haul, we’ve done rather badly relative to France.  Our GDP per capita was well ahead of theirs, but is so no longer.  And if you are inclined to take some heart from the performance over the last 20 years, pause for a moment.

fr vs nz real gdp pc

A rather large chunk of that improvement in the relative GDP per capita performance has reflected the volume of labour input.

fr vs nz hours worked

Hours worked per capita have carried on falling in France, while those in New Zealand have fluctuated around a fairly stable mean since 1950.  In 1950, New Zealand’s hours worked per capita was in middle of the pack for advanced countries.  Last year, among Western European countries and the offshoots (NZ, Australia, Canada, US), only Iceland and Switzerland had longer hours worked per capita than New Zealand.  France, by contrast, has one of the lowest levels of hours worked per capita of any advanced country.   I’m not making the case for more (or less) hours, just that in New Zealand’s case it looks as though we’ve needed to work more hours  just to maintain our tenuous foothold on the GDP per capita rankings.  All sorts of distortions – but notably high taxes – help explain the low levels of labour input in France, and no doubt there is a price for those distortions, but New Zealand is not an obviously compelling alternative model.

Relative to France, labour productivity growth has also been disappointing.  And over the last few years, from 2007, neither country has recorded any material labour productivity growth.  And the average level of labour productivity in France is now estimated at just over 50 per cent higher than that in New Zealand (in 1950 ours was more than 50 per cent higher than theirs).

fr vs nz gdp per hour

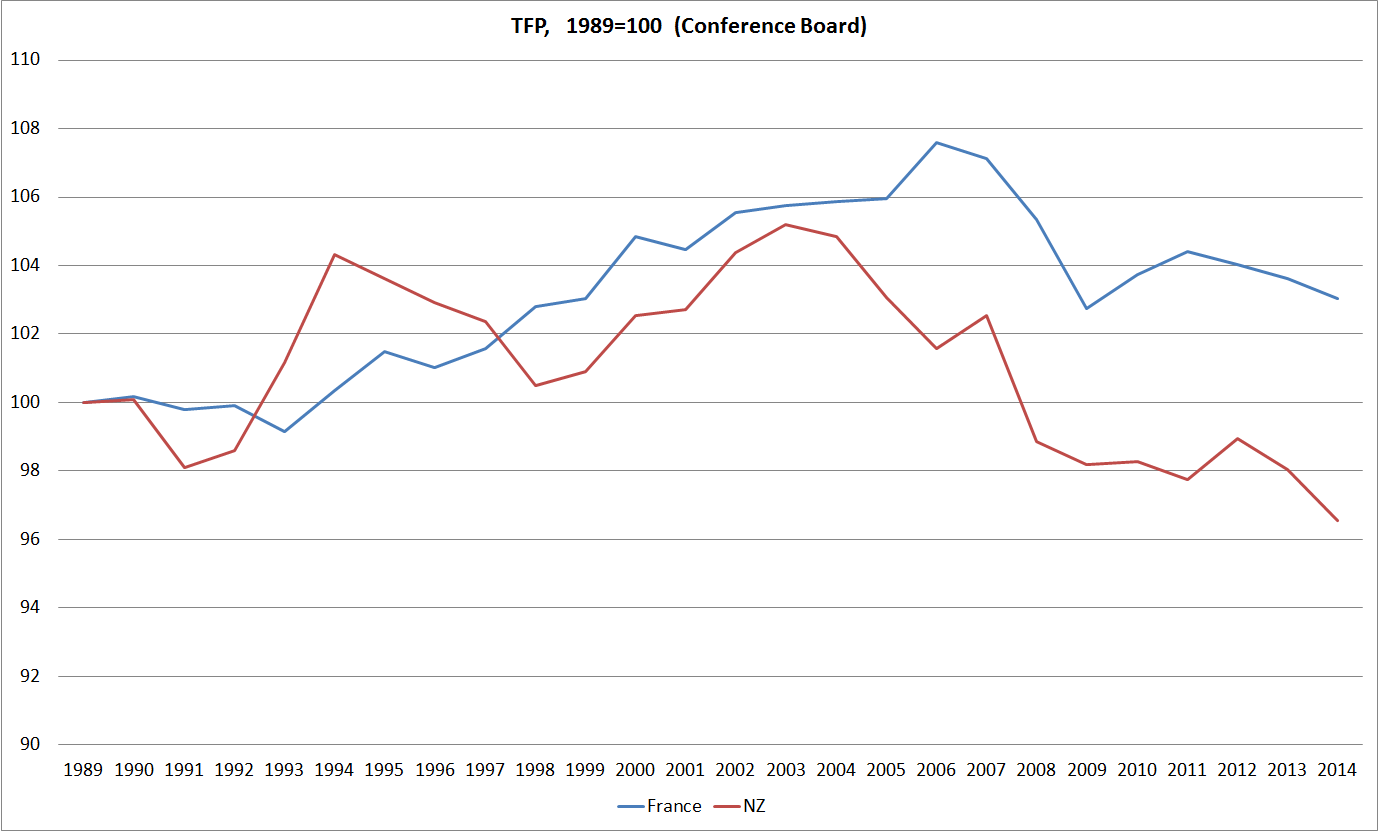
And if neither country’s MFP growth has been particularly impressive, over the period for which the Conference Board has published detailed estimates (since 1989), New Zealand’s has been worse than France’s.    Indeed, France was almost the median OECD country over the full period.

fr vs nz tfp

Average real GDP per hour worked in France is among the highest in the advanced world –  not too different from that in the United States for example.  A common argument has been that the high average labour productivity is largely the mirror image of the low level of hours worked per capita, and low overall employment rate. The less productive people simply aren’t employed in France, while they are in some other OECD countries.  The employment to population ratio in France is around 41 per cent, compared with over 50 per cent in, say, New Zealand, Australia and Canada.

Perhaps there is something to this story, but I’m not convinced it can explain all of what is going on.   Over 50 years or more, labour productivity in France and Germany has tracked very closely together, the two economies produce similar things and are quite highly integrated.  And yet Germany has an employment rate almost identical to New Zealand’s.

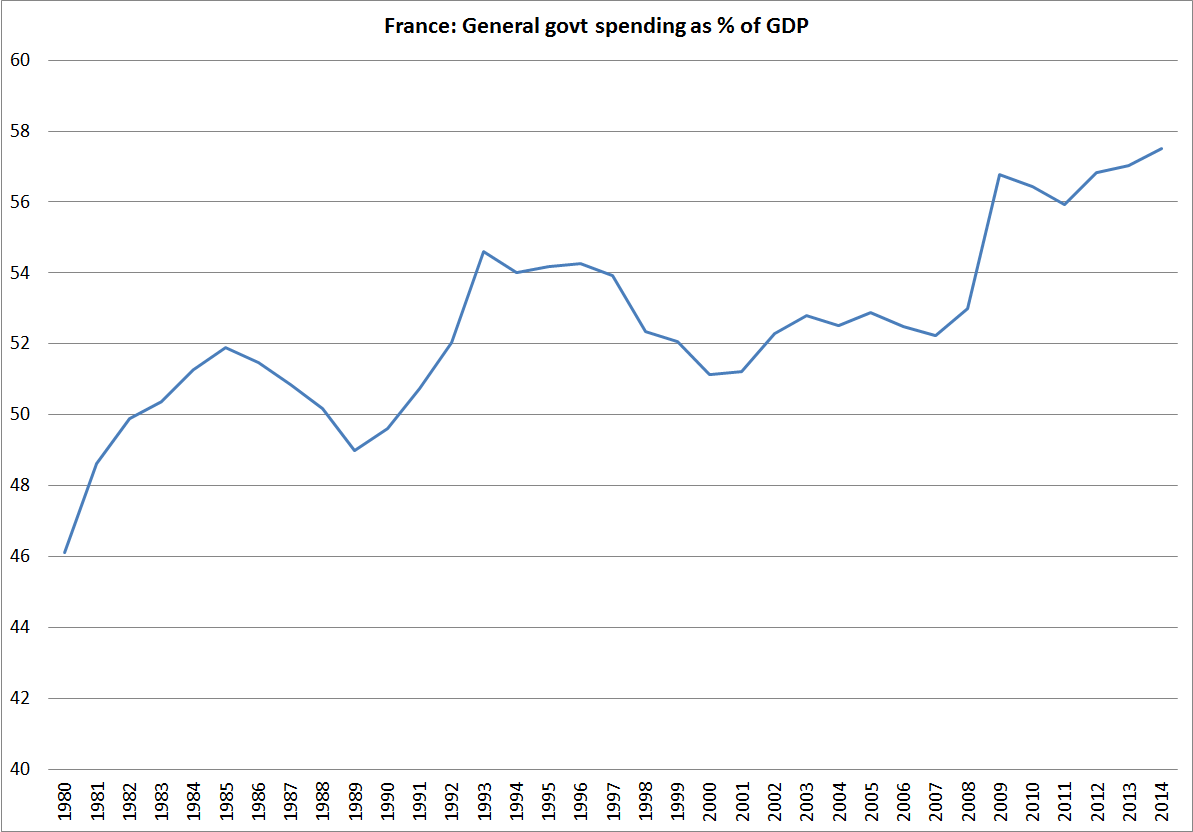
Of course, France has things going for it that New Zealand doesn’t.  Being very close to other major rich countries means that France does not suffer any “tax” from small size and great distance.  Then again, actual French taxes remain among the highest in world, and government spending as a share of GDP still seems to be edging upwards.

fr govt spending

I’m left a little puzzled. I think I’ve worked my way to a story about why New Zealand has done as poorly (relative to the advanced world as a whole)  as it has over the last several decades, but I’m still a bit puzzled as to why France has continued to be quite as moderately successful as the statistics suggest it has been.      Perhaps the cracks are now showing?

Fiscal policy – a response to some comments

Following my post on Saturday about macroeconomic policy options, a reader posted the following substantive and interesting comment, which I thought warranted more of a response than a few lines buried in the comments.

The fiscal advice you propose is consistent with mainstream new-Keynesian models. This is the sort of outcome you get from the IMF modeling of the impact of a tighter fiscal stance in NZ in 2010 WP 10/128.

However, all these models assume that central bank acts rapidly and forcefully and is able to return inflation to target and output back to potential in short order (12-18 months or quicker because they assume that the monetary policy maker has a model of the economy that tell it in advance where output will be with certainty). This has not been the case. It is now 6 years since inflation has been at target and output at potential.

In these circumstance looser fiscal policy in the past (all else being equal) would have lead to high output, lower unemployment and inflation closer to target. All around welfare is higher. Perhaps we should leave aside the issue of what the fiscal policy maker should do if they share your beliefs about the RBNZ meeting its future target. Although just for the sake of playing devil’s advocate it would seem to me to be hard for the central bank to react to a fiscal loosening in this situation in the same way they might at close to full employment and their inflation objective.

Just looking at the near term it appears to me we face the risk of fiscal policy again being contractionary (perhaps only mildly) at a time when output is below potential – and fiscal policy will again be pro-cyclical.

Now there might be a good reason for all this if NZ was struggling with a large public debt burden and had no history of delivering fiscal consolidation. Yet this is not the case on either count. If you look at the IMF fiscal number and look at the change in primary balance (I used a 3 year average over the crisis period compared with calendar 2015) you will find that NZ adjustment (~ 7.5) looks like around the level of Portugal and Spain and Greece (Ireland is off the chart because of the size of the fiscal support provided to the banks through the accounts in these years). This is all in the context of macro models that suggest the appropriate pace of debt reduction from once in a generation shock is slow…..

And what about commodity prices?. I think the way to think about this is that you might tell you something about the right level of structural balance to aim for abstracting from the cycle. In my humble opinion it cannot tell you too much about the right fiscal stance from a cyclical point of view. To see this just imagine that this approach would have suggested a rapid tightening of the fiscal stance in 2010 as commodity prices returns to their peak despite the economy being in a deep slump. Another way to see this is to look at the cyclically adjusted balance scenario with the terms of trade at their 30 year average – this suggests that the structural balance is 2.5 percent worse than the forecast in every year.

Lastly, the decision needs to be made under the knowledge that the outcomes are asymmetric. If the central bank does its job as the macro models predict then we get a slightly different mix of output. But output reaches potential – no harm no foul. On the other hand if this is not the case then the outcome of looser policy will be much like I describe above for the past 5 years – higher output, employment, and welfare. All without reference to the risks of deflation or the zero lower bound.

There are a number of different points here.

I had noted that if a tighter fiscal policy had been adopted over the last few years that should have eased pressure on demand, the exchange rate and the OCR.  But as the commenter points out, it has been quite some years since core inflation was at target, and output also appears to have been consistently below potential (at least judging by the unemployment rate, if not by eg the Reserve Bank’s output gap estimate).

If so, mightn’t a looser fiscal policy –  as suggested by Brian Fallow –  have delivered some better economic outcomes?  I don’t think so.  The repeated mistakes the Reserve Bank has been making over the last few years have not had to do with fiscal policy.  The Bank’s approach is simply to take announced fiscal policy –  Treasury’s own numbers –  and build those assumptions into its own economic forecasts.  Internally, I was sometimes critical that we were too willing to base policy on government promises –  which is all forward operating allowance estimates are –  but in recent years doing so hasn’t provided a misleading steer.  The government got the Budget back to balance roughly when it said it would.

All that means that, as they said they were doing all along, the Reserve Bank set the OCR a bit lower than they otherwise would have because of the fiscal adjustment that was promised (and delivered).  Had the government planned a slower pace of fiscal consolidation, the Reserve Bank’s demand and inflation forecasts would have been a little stronger, and the case for tightening in 2013 and 2014 would have appeared even stronger to them than in fact it did.  The mistakes were about how the economy was working, not about the government’s own fiscal actions.

Only if fiscal policy had been surprisingly loose (unrecognised by the Reserve Bank) might there have been some windfall macro gains –  output a bit higher and inflation nearer target.  But no one wants to go back to a world of non-transparent fiscal policy –  perhaps especially not where one part of government (Treasury) keeps fiscal actions secret from another part of government (the Reserve Bank).

The commenter suggests that “we face the risk of fiscal policy again being contractionary (perhaps only mildly) at a time when output is below potential”.  The PDF with the supplementary Budget information on the Treasury website won’t open so I can’t check the fiscal impulse etc numbers, but two thoughts (a) surely any contractionary discretionary fiscal policy over the next few years must be pretty mild? and (b) whatever is flagged in the Treasury numbers is already included in the Reserve Bank’s forecasts and policy.  Since we are still nowhere near the zero lower bound, it seems unlikely that any additional fiscal contraction over the next couple of years will be holding back economic activity or inflation.    The Governor can fully offset the effects of well-signalled, relatively modest, fiscal actions.

I had made the point that the Budget had been flattered over the last few years by the high terms of trade.    If anything, I argued, a case could be made for having got back to balance a bit sooner than the government chose to.  After all, as Treasury’s numbers show, if one redid the fiscal numbers with the terms of trade set at their 30 year average, there would still have been a material (although not unduly alarming) deficit even in 2014/15.  My commenter seems to see this as an argument against faster tightening, but I don’t quite understand why.  A rising terms of trade does not of itself argue for faster discretionary fiscal consolidation, but rather for recognising that much of any improvement in the reported conventional cyclically-adjusted balance estimates is just arising from the boost to the terms of trade, and the underlying extent of adjustment still required remains as large as ever.  The improvement in New Zealand’s fiscal position has been flattered by the impact of the terms of trade.

Judging how much fiscal consolidation there has actually been is more of an art than a science.  My commenter presented one set of numbers, which suggests that there has been a very substantial fiscal consolidation in New Zealand in recent years, even by comparison with some of the benchmark austerity countries like Spain and Portugal.

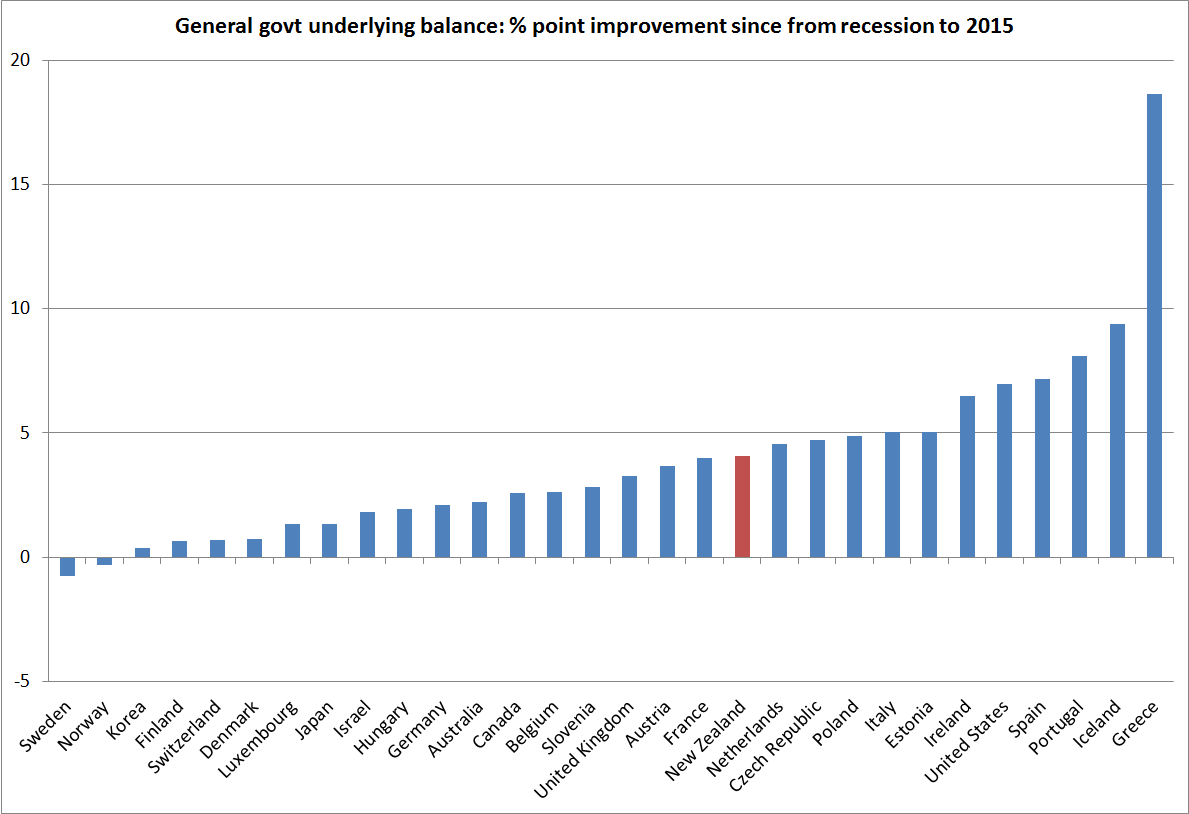
I’ve got an alternative take, using the OECD’s underlying balance measure –  which is both cyclically-adjusted, and removes identifiable one-off items (eg bank recapitalisation s in a single year, or earthquakes).  Since the most recent OECD numbers are a few months old, the numbers aren’t quite as up to date as the IMF ones, but it is unlikely that the picture would change very much with a few months extra data.

OECD gen govt underlying balance

Here is the increase in underlying surplus (reduction in the underlying deficits) as a per cent of GDP,  from the low point reached over 2008 to 2010 to the latest 2015 estimate.  Over that period, the median OECD country reduced its underlying fiscal deficit by 3 percentage points of GDP, while New Zealand’s adjustment was 4.1 percentage points.  But New Zealand’s numbers were flattered by the fact that we had among the strongest terms of trade of any OECD country over that period.  If that were corrected for, the extent of our fiscal adjustment would be even more unremarkable, and much less than those in Ireland, Iceland, Portugal, Spain and the US.  And, of course, over that period our debt has increased.

It is quite reasonable to argue that New Zealand was under no particular market pressure to have adjusted that fast (neither was the US).  But on the other hand, unlike all these countries other than Iceland, we still had plenty of room for conventional monetary policy to offset the short-term demand effects of contractionary fiscal policy.  And although New Zealand did not use fiscal policy actively to counteract the 2008/09 recession (unlike the US, UK, or Australia, for example) it is worth reminding ourselves how large the deterioration in New Zealand’s underlying fiscal position was: on this underlying balance measure, only Spain and Iceland saw a larger fall in the underlying surplus from years just prior to the recession to the recessionary low.  Fortunately, we had started from large surpluses.

In making choices about fiscal policy now, the effects are not asymmetric.  The Reserve Bank will offset any  discretionary fiscal easing now –  the revised assumptions will feed straight into the forecasting models.  We won’t end up with higher output, higher employment, or higher inflation, we’ll just end up with slightly higher (than otherwise) interest rates, exchange rates, and public debt (and temporarily higher spending or lower taxes).  It is only when conventional monetary policy has reached its limits (say, an OCR at -0.5 per cent) that discretionary fiscal policy is likely to play a useful stabilisation role.  And we provide the best chance of that being a politically viable and economically credible option, for the several years of stimulus that might then be required, if the government keeps a tight rein on fiscal policy now.  I don’t favour running large structural surpluses in boom times –  it is a recipe for fiscal splurges of the sort the 2005-08 government took.  But adverse shocks are inevitable from time to time, and one of the best ways to cope with them is to keep public debt very low, and ensure that the budget runs modest structural surpluses in the more normal times.  Even then , a severe adverse economic shock may well undermine tax revenue sufficiently that there will often be surprisingly little discretionary fiscal leeway.

An official target for house prices to disposable incomes

Getting back to thinking about housing issues, in preparation for a speech next week, I noticed that the Auckland Council’s Development Committee had adopted a target of reducing the Auckland ratio of median house prices to median disposable income to five (from around ten at present) by 2030.

The target appears to have been adopted following the recent report on housing affordability issues by the Council’s Chief Economist. That report,  if rather patchy, has some interesting material I’d not seen previously, such as the estimated range of costs of some of the view shaft restrictions on building that Auckland currently has in place.

I wasn’t that impressed by the new target.  The report notes that house price to income ratios probably “should” be around three, and then adopts a target which, even if taken seriously, would still leave price to income ratios 15 years hence well above the sorts of levels that should be able to be sustained over the longer-term.  Targets for asset prices leave me queasy at the best of times, but set that ‘theoretical” objection to one side for now.

But what chance is there of this target being taken seriously?  It is being adopted by the Development Committee of a Council that is a year out from an election.   Five sets of local authority elections will occur before 2030.    And unlike central government there is no strong party discipline in local government, which means there is even less meaningful basis for anyone to believe that a target adopted today by a committee of the current Council will translate meaningfully into action over the next 15 years.

There is an old cynic’s line that in making a prediction one can safely offer a number or a date, but would be most unwise to include both.  Probably the same goes for target-setting.  But an alternative formulation might be that if you must include a number and a date, set the date so far into the future that no one is likely to even remember it when the date comes round, and all those involved in setting the target will long since have moved on.     Concrete targets around things the Auckland Council can actually control for the 12 months between now and the next election  –  or at a pinch the one after that, which sitting councillors might campaign on next year  –  might have been more impressive.

Targets like this have more of a feel of “virtue-signalling” –  adopted and articulated to signal that the adoptees “feel the pain” rather than because they necessarily intend to do much about the problem in question.  To say that is not to doubt the goodwill of the Auckland councillors, simply to observe that in isolation this target gets some cheap feel-good headlines (the word “ambitious” gets associated with one’s name, and not necessarily in a Sir Humphrey sense) and commits them to precisely nothing.

In fact, I was reminded of some previous targets.    Numerous governments have talked about getting New Zealand back into, say, the top half of OECD per capita income rankings.  Not that long ago there was the goal of catching up with Australian per capita incomes by 2025.  No doubt all those involved would have welcomed achieving the targets, but weren’t willing to actually do anything much themselves to achieve them.  And having served their short-term purpose (fill out a speech, fend off a minor party or whatever) the targets themselves would soon be forgotten.

Getting rather long in the tooth now, I was also reminded of the 1989 Budget.  The then Labour Government was in increasingly desperate straits.  The economy was doing badly, the financial crisis was continuing to unfold, the tensions within the Cabinet grew more intense by the day, and Labour’s position in the polls looked bleak.  The Minister of Finance needed something a bit new for the Budget, and so a serious of macroeconomic targets were announced.  By December 1992, the government  –  which looked most unlikely to be re-elected anyway –  would aim to:

  • Reduce public debt to 50 per cent of GDP
  • Reduce inflation to 0 to 2 per cent
  • Reduce unemployment below 100000,
  • And get first mortgage interest rates in a 7-10 per cent range.

This was actually the first time the 0 to 2 per cent inflation target had been given a specific target date.

At the time, the new Reserve Bank legislation was being considered by Parliament.  That legislation would give someone –  the Reserve Bank Governor –  specific responsibility for getting inflation to the target by a particular date.    And it was (over)achieved, (nobody having mentioned the need for a severe recession when the targets were articulated).

But none of the other targets was ever heard of again. No one was made responsible, no one took them seriously, and there was no reporting and monitoring mechanism established.

I hope the Development Committee’s target is the next step in a serious process of freeing-up housing supply, and making housing and urban land in Auckland affordable once again.  But I’m not convinced.  I’m still not aware of any Anglo country major city in which planning restrictions have been materially and sustainably unwound to facilitate a responsive and affordable housing market (are there such examples?)  Perhaps Auckland can be the first, but there is little sign of the vision, passion, commitment, and political leadership –  whether at central or local government level –  to really address, and reverse, these issues.

(And, of course, we could get to the goal –  and beyond –  much more quickly if the target rates of inward non-citizen migration –  being reviewed by Cabinet now –  were materially reduced.  That could be done quickly and easily –  and it has worked previously.  It might buy time for a considered reassessment of the planning rules, in a rather less-fevered, less threatening, environment.)

On macroeconomic policy options

There have been a couple of odd comments this week about the use of macroeconomic policy tools in New Zealand.

In his weekly column yesterday, Brian Fallow suggested that it had been unwise to have put so much emphasis on getting the budget back to balance, and that it was time for more fiscal stimulus.  Of course, there is nothing sacrosanct about getting back to balance by any particular date, but if anything I thought our government had been rather too slow to get there.  With the benefit of record –  and probably unsustainable –  terms of trade – there wasn’t really much excuse for having run deficits in the last few years.       And a tighter stance of fiscal policy should, at the margin, have eased the upward pressure on demand, the OCR, and the exchange rate.

Fallow draws on the generalised advice of the IMF to advanced economies.  But most of those advanced countries can’t do anything much with conventional monetary policy even if they wanted to.  Quite a few advanced countries (including the euro area) already have negative policy interest rates, and many of the others –  US, UK, and Japan among them – are essentially at zero.  Perhaps new rounds of QE might make some difference –  I rather doubt they could do much – but to all intents and purposes monetary policy options are exhausted.    That is partly the fault of central banks and finance ministries that have done nothing material over eight years to remove the near-zero lower bound on nominal interest rates but, choice or not, it is the situation today.

If there is still excess capacity in many of those countries, and if many of them face widening output gaps if world activity growth continues to slow, the appeal of looking to fiscal policy for stimulus is understandable.  In general, I’m not sure it is a call that should be heeded to any great extent, as most of the larger countries already have rather sick fiscal positions –  made considerably worse when those countries resorted to fiscal stimulus, to loud cheering from the IMF, in 2008/09.

New Zealand –  and some other advanced countries such as Sweden, Finland, Estonia, Australia, and Switzerland –  is in the fortunate position of having a low level of public debt.  That means we do have some room  to use fiscal policy if such stimulus is required.  But even that potential isn’t limitless. Faced with another severe recession, even allowing the automatic stabilisers to work would add materially to the government’s debt over several years.  In such a downturn, it is probable that the government’s speculative investment vehicle – the New Zealand Superannuation Fund –  would lose a lot of money.  And for those who worry about the financial stability risks of the house prices more than I think warranted, bear in mind the potential need to bail out banks and their creditors.   If there is a severe downturn, we need the political room to allow those buffers to work, not to have to resort to pro-cylical fiscal policy

Fallow –  and many international commentators –  have favoured additional government spending because interest rates are low.  But remember that interest rates are low for a reason –  it isn’t just some number thrown up by a random number generator.  I’ve argued previously that the effective cost of capital the government should be using in deciding on even good quality projects is probably in excess of 10 per cent (the sort of standard private businesses use), not something close to the government bond rate.   And all this is before the questions that must be asked about the poor quality of too much government spending.

There are distinct political limits to how much fiscal stimulus any government can do, even in a crisis.  Why fritter away that potential now, when our OCR is still 2.75 per cent?  New Zealand has far more monetary policy headroom still open to it than most other countries do.  There are real macroeconomic issues in New Zealand –  as Fallow points out, the high and rising unemployment rate suggests that the economy continues to run below capacity  –  but as Eric Crampton noted in his response to Fallow yesterday, it is not as if monetary policy has been tried and failed.  Rather, because of the repeated mistaken calls by the Reserve Bank, monetary policy has barely been tried.

ANZ advocated fiscal stimulus back in July.  I set out here the reasons why I thought that was the wrong call. I don’t think I’d resile today from anything in that piece.

But the other odd comment on New Zealand macroeconomic policy came from someone who really should have known better.    In his speech on Wednesday, the Governor of the Reserve Bank

It is important also to consider whether borrowing costs are constraining investment, and the need to have sufficient capacity to cut interest rates if the global economy slows significantly.

I’ll largely ignore the first part of the sentence (although if inflation is low and unemployment still high, isn’t more private sector investment generally likely to be a good thing?).  It was the second half of the sentence that really reads oddly –  and arguably, worse than oddly.

This idea of keeping some powder dry in case there is a renewed sharp slowdown pops up from time to time in international commentary.  We’ve even seen the argument made that the Federal Reserve should raise interest rates now so that it has room to cut them if there is a future slowdown.  But it is a deeply flawed argument.  It may have some merit on the fiscal side –  higher public debt now leaves less room to run up more debt later on  – but in respect of monetary policy it is just wrong.

Monetary policy that is tighter than strictly necessary (in terms of the PTA) now, is likely to both weaken the economy (relative to the counterfactual) over the coming 12-18 months, and further low inflation and inflation expectations.  Lower inflation is undesirable (in terms of the PTA itself) and low inflation expectations are deeply problematic.  Lower inflation expectations, all else equal, raise real interest rates for any given nominal interest rate.  The experience of advanced world since 2007 says that one of the biggest macro management problems of a sharp slowdown in the presence of low inflation is getting real interest rates low enough.    It was easy to get real interest rates materially negative in the high inflation 1980s but it is almost impossible to do so now.  In other words, holding up nominal interest rates now increases, perhaps materially, how much one might need to cut rates if a severe downturn happens, while doing nothing to create that extra space.

The Governor has rather reluctantly come to acknowledge that global deflationary risks.  The last thing anyone in his position should be doing right now is making choices that would make it harder to handle the next sharp slowdown.  But that is what he appears to be set to do.

If anything, those countries that still have monetary policy room to move should be doing so now.  Real interest rates should be as low as possible, consistent with the PTA –  and perhaps especially in a country that starts with the highest real interest rates in the advanced world.  Rather than core inflation of 1.5 per cent or less, the Governor should be rather more comfortable with core inflation around 2.5 per cent.  The best way to get that sort of outcome would be to have cut the OCR over the last couple of years, not raised it.

As a commenter here the other day put it, this idea that we should hold the OCR up now so that it can be cut later “is like keeping your shoe laces tied so tightly that it cuts off your circulation, just so it feels good to loosen your laces later.”

Between the failure to do anything about the zero lower bound –  which the Governor now (belatedly)  implicitly acknowledges to be an issue –  or, absent that, to consider a higher inflation target, the Governor and the Minister have left New Zealand less well placed than it could have been if there is a new sharp global slowdown in the next few years. But the decisions that keep on delivering such unnecessarily low rates of core inflation (and high unemployment) are those of the Governor alone.

Plenty of market economists have commented on yesterday’s inflation numbers.  My only contribution is a simple chart of a new series Statistics New Zealand has just started publishing.

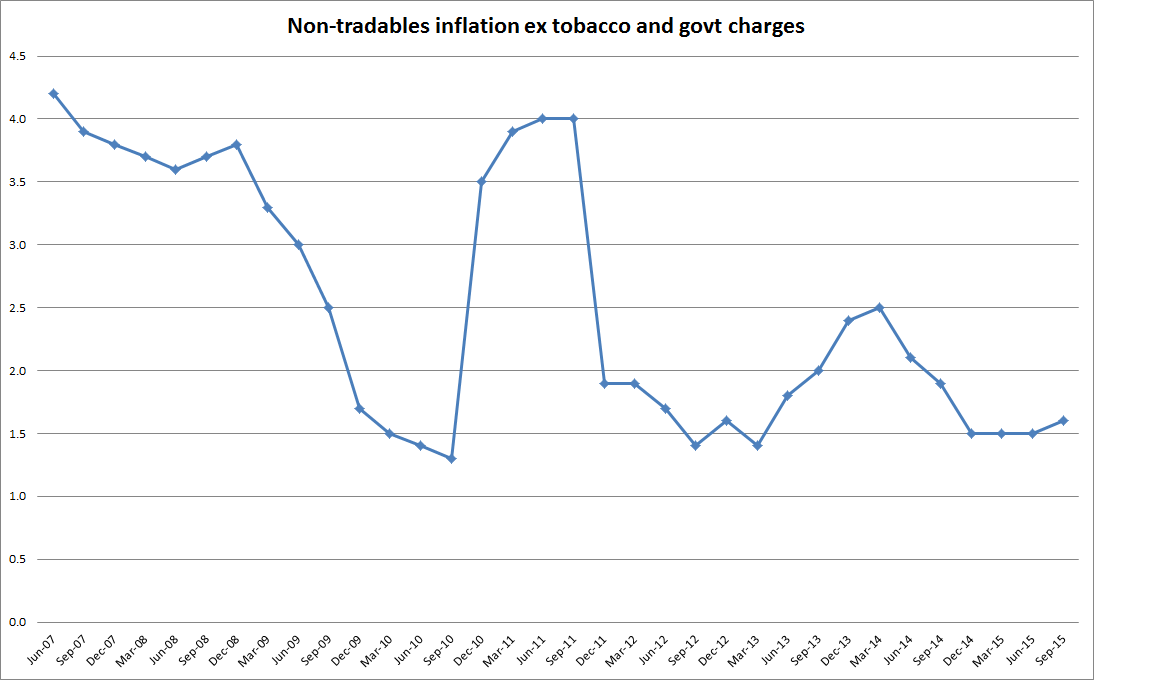
Non-tradables inflation has long been the focus for analysis of the underlying inflation position.  Tradables inflation is thrown around by short-term swings in international oil prices and level shifts in the exchange rate, and non-tradables inflation should provide a better guide to underlying inflationary pressures. But non-tradables inflation is made harder to read because of repeated tax increases (notably tobacco taxes) and changes in government charges –  which don’t reflect anything about the state of the domestic economy.   It is quite common internationally for statistical agencies to publish series excluding taxes and government charges.  And now SNZ has provided us with this series for New Zealand.  It has the advantage, over the Bank’s sectoral core factor model measure, that it is not prone to revisions.
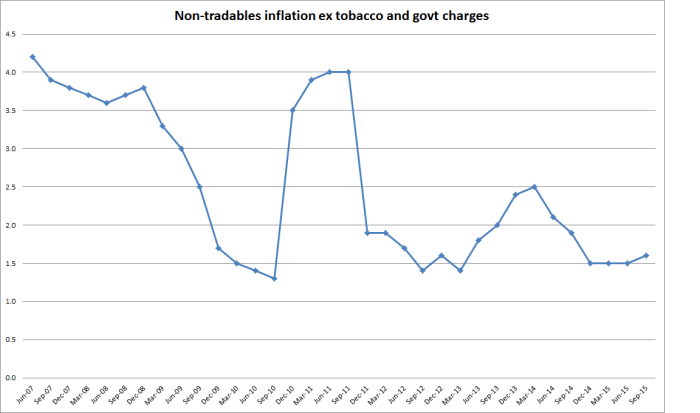
PNT ex

Note that this measure of non-tradables inflation is running at only 1.6 per cent, barely above recessionary low.  Non-tradables inflation should be expected to run above tradables inflation on average over time (there is typically more scope for productivity gains in tradables than in many non-tradables).    Indeed, if CPI inflation was going to average around 2 per cent –  the Bank’s target  –  non-tradables inflation shoiuld probably average somewhere in the 2.5-3 per cent range (and perhaps tradables might be in the 1-1.5 per cent range).     Non-tradables inflation is extremely low in New Zealand –  it is too low and should, as a matter of active policy, be raised.

No doubt the Governor and his economists will say that that is what they have been trying to do.  But if so, they have repeatedly failed.  Becoming reluctant to cut the OCR further because of the housing market (one of the channels through which lower interest rates work –  a buoyant housing market is a desired feature not a bug) or for fear of hitting zero in a global downturn is a recipe for continuing the mistakes of the last few years.

To repeat Eric Crampton’s line: monetary policy has scarcely been tried.  It should be.