A new BIS paper that undermines the Reserve Bank’s case

At the end of my long post yesterday on the Reserve Bank’s latest efforts to spin the Governor’s plans to increase very markedly minimum capital ratios for locally-incorporated banks, I noted

PS.  As Martien Lubberink at Victoria has pointed out there is another international agency paper out just recently that really doesn’t help the Bank’s case much if at all. I might touch on that tomorrow.

His post is here (complete with the sly –  if obscure, presumably deliberately so –  dig at the Governor in the final paragraph).

The paper he was referring was recently published by the Bank for International Settlements as a Working Paper of the Basel Committee on Banking Supervision, with the title “The costs and benefits of bank capital – a review of the literature”.   The paper was released only a couple of weeks ago, and it should be studied carefully by anyone interested in the issues here in New Zealand, including (one hopes) the Reserve Bank.

The paper begins

In 2010, the Basel Committee on Banking Supervision published an assessment of the long-term economic impact (LEI) of stronger capital and liquidity requirements (BCBS (2010)). This paper considers this assessment in light of estimates from later studies of the macroeconomic benefits and costs of higher capital requirements.

That earlier paper is referenced everywhere the issues are discussed, including in the Reserve Bank’s papers earlier in the decade, and in its consultative document for this review.   It supported –  to some extent made –  the (macro) case for higher capital ratios, in particular higher than had been in place up to that point (shortly after the crisis).  A review and update of the issues, by a group involving officials from the BIS, the Bank of England, the Banque de France, the Fed and Comptroller of Currency (among others) has to be taken seriously, including when the authors highlight the limitations of their own work, and outline areas needing further research.   The paper looks at many of the same studies the Reserve Bank cites but –  in Lubberink’s words –

The conclusions of the Basel Committee study, however, are different. They are much more modest than the findings of the RBNZ.

Before going on, I should say that I have serious problems with elements of the approach taken in the earlier and more recent BCBS papers (various points outlined at greater length in my own submission).   In particular, this work (and the Reserve Bank) treats all output losses in recessions associated with financial crises as being attributable to the financial crisis (bank failures etc) itself.  That is almost certainly wrong, and substantially overestimates the cost of crises themselves –  the loan losses that lead to bank failures arise from misallocations of investment resources (and/or overheated economies) and those misallocations will be corrected anyway (with likely output costs), whether or not any bank fails.   Remarkably –  and this is clearer in the more recent paper –  they also treat output losses in countries that didn’t have domestic financial crises (think Australia or Canada in 2008/09) as costs of financial crises, rather than allowing for the more plausible story that common third factors will have been driving, say, productivity growth slowdowns across the advanced world.  As I’ve argued (and as Cline, in a PIIE paper a few years ago, also made the case), if you want to isolate the output costs of financial crises, a better way is to look at the differential growth performance between (otherwise similar) countries that did and did not experience domestic financial crises.

A great deal turns –  in these sorts of modelling exercises – on how costly the modellers assume crises will be.  Both my points in the previous paragraph suggest the BCBS conclusions –  as to how much capital is likely to be warranted –  are likely to materially overstate the “true” numbers.

There are all sorts of other limitations to the BCBS work. For example, it focuses on “banks”, but doesn’t address the fact that for an individual country – think New Zealand –  a capital requirement on locally-incorporated banks won’t affect branches of foreign banks operating locally, or non-bank lenders.  Disintermediaton costs don’t figure.  It also, more generally, won’t apply to debt capital market funding.   Unlike the Reserve Bank, the BCBS paper does touch on the issue of alternative resolution mechanisms –  the Bank long favoured the OBR approach, but it was never mentioned in the consultative document, even though the more confident you are of OBR (I’m not, but they were) the less capital is required –  but it doesn’t touch on the issue of a banking system in which the large banks all have strong foreign parents.  And it doesn’t take account – in the macro calculations – of the possible income losses to New Zealanders from the higher equity returns to foreign shareholders (much of the overseas modelling seems assume redistribution of income within the country).  This latter point, in particular, has been covered in Ian Harrison’s papers.

On my reading, this is the bottom line chart in the BCBS paper.
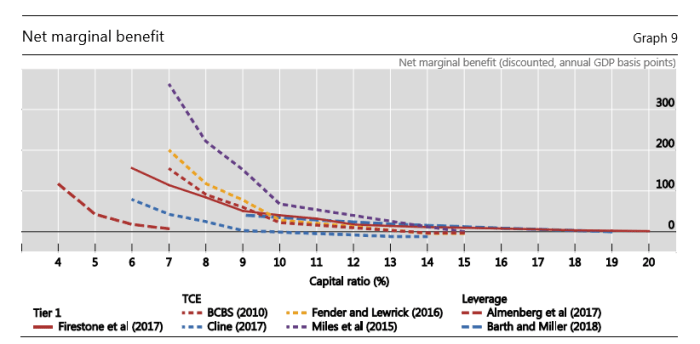
bcbs chart.png

They report the net marginal economic benefit (slightly lower GDP each year, offset against savings from a less serious crisis decades hence) from higher bank capital ratios, drawn from a series of studies.    On these models there were really big gains in lifting capital ratios, up to around to around 9-10 per cent.  If there are gains at all –  and they don’t report margins of error around these estimates –  they are looking extremely small beyond about 13 per cent.    Perhaps that doesn’t sound too far from the 16 per cent number the Reserve Bank is proposing for the big banks but (among other limitations, many made inevitable by data limitations):

  • this modelling is done on actual capital ratios, not regulatory minima (a 16 per cent minimum ratio is likely to see banks aim for something between 17 and 18 per cent actual ratio), and
  • none of this modelling takes account of differences in accounting and regulatory treatment across countries: conventional wisdom, (backed by estimates done by PWC) suggest that effective capital ratios in New Zealand (and Australia) would be far higher if things were measured the same way they were done in various other advanced countries, and
  • none of it takes account of the regulatory floor in how risk-weighted assets are calculated.  As the Bank is quite open about, a significant part of what is proposing is that in calculating risk-weighted assets, the big banks will have a floor of 90 per cent of what the standardised rules would generate (the more normal floor is, as I understand it, about 72 per cent).  A 17.5 per cent headline actual capital ratio would, on RB proposed rules, be akin to something like 20 per cent in the sort of framework the BCBS authors are looking at.

Nothing in this paper suggests any reason for confidence that effective capital ratios of, say, 20 per cent of risk-weighted assets would be generating net economic benefits, even on the (overly pessimistic) macro assumptions the authors are using.  But that is what the Reserve Bank claims to believe.  The onus, surely, is on them to show us, and to engage on their assumptions and analysis – in open dialogue – well before decisions are made.

And then lets go back to the macroeconomic inputs.    If most of the costs of recessions associated with financial crises would have happened anyway (see above) then the output losses used in these models are substantially overstated.   Higher capital ratios make no difference to whether those losses occur.  Cline (the lower blue line in the chart) uses assumptions more similar to mine: you can see where the crossover point (to net costs) is for him.

Note too that real interest rates and the real cost of capital are higher in New Zealand than in most advanced countries.  The median (real) discount rate used in the studies the BCBS paper looks at is something like 3.5 per cent and none uses a real rate higher than 5 per cent.  A standard New Zealand Treasury guidance for cost-benefit analyses on regulatory proposals is (real) 6 per cent.  Using a higher discount rate materially reduces any benefits from a crisis assumed to arise, probabilistically, decades in the future.   And yet even on the studies reviewed by the BCBS, there is no consensus in favour of anything near as high as the effective capital ratios the Governor is proposing.

And, as I’ve pointed out previously, all this work implicitly assumes that any higher capital ratios can be made binding for decades to come.  Since there is no pre-commitment technology, and actual rules have been changed every few years, there should be a further discounting of any potential gains, particularly in light of the inevitable transition costs from big increases in capital requirements (which are frontloaded, and represents permanent losses, for what may be a temporary policy).

It was also interesting to be reminded, in an annex, of this feature of the earlier (LEI) BCBS modelling

The main results of the LEI appear in Table 8, p 29, of BCBS (2010).  The calibration used is the following:

• the probability of a crisis is 4.6% for a capital ratio of 7%, and declines at a diminishing rate to 0.3% for a capital ratio of 15%.

In other words, a probability of a crisis every 333 years with an (actual) capital ratio –  calculated as more conventionally abroad –  of 15 per cent.  And yet the Reserve Bank’s proposals were supposed to be calibrated to a crisis every 200 years, and yet still somehow generate effective capital ratios of 18 per cent plus for the big banks.

Now in many respects Martien Lubberink’s comment is fair, that for all sorts of reasons

studies on bank capital are more quicksand than a sound foundation for policy recommendations.

And yet, they have been repeatedly invoked by the Reserve Bank, and –  when read carefully – do still provide a commonsense test against which the benchmark the Governor’s ill-considered far-reaching proposals for New Zealand.

The whole exercise really should be suspended.  Come back to it perhaps in a few years’ time when a revised Reserve Bank Act is in place, and when there has been proper parliamentary and public scrutiny of the assignment of powers to the Reserve Bank (which policymaking powers should rest with ministers and which with agencies).  And use the intervening period to undertake some serious local research, working collaboratively with APRA (recognising the common risks, common ownership, likely common resolution) and engaging in workshops and seminars to tests the strengths and weaknesses of staff thinking and research well before decisionmaking authorities reach a provisional view.

And, in meantime, take comfort from the fact that before the IMF suddenly swung in behind the Governor, when there were no institutional pressures at play that international agency only a year ago told us, and told the world, that there were ample capital buffers in the New Zealand banking system.

IMF capital

The risks haven’t changed materially in that time, it is just that the gubernatorial whim has since been revealed.  Such whims are a terrible basis for making serious policy, especially when there are no checks, no appeals, on the Governor’s ability to impose such substantial transitional and ongoing costs on New Zealanders.


,
Reserve Bank still spinning

Earlier this week, the Reserve Bank published (almost all of) the submissions it received on the Governor’s proposal to increase very markedly the share of bank balance sheets that need to be funded by equity.

Welcome as it is to have the submissions –  it is easy to forget that not four years ago the Reserve Bank was still reluctant to publish any submissions it received at all (even though it was the norm for government agencies, parliamentary select committees, and so on) –  the Governor sought to use the occasion for some more spin in support of his proposal (on which he alone will, a few months from now, make the final decisions –  the rest of us, whether Minister of Finance, banks, businesses or citizens will simply be stuck with the results of his whim, with no mechanisms for appeal or review.)

Instead of just releasing the submissions –  which could have been done weeks ago, very shortly after submissions closed –  the Bank chose to release a 22 page document labelled “Summary of Submissions” and a lengthy and argumentative press release in the name of the Deputy Governor.

I haven’t read all the submissions, or even looked at them all, but one reader –  distracting himself from other stuff he should have been doing –  did look at them all, and sent me a spreadsheet with the names of the submitters, the length of each submissions, and broad tenor of any comments.

A good consultative process draws out perspectives or comments or evidence that the consulting agency may not have thought of, may have chosen to ignore, may have interpreted differently, may have missed the point of, or whatever.  Having received that material, the consulting agency would carefully consider those perspectives, (in principle) looking to make the best decision, open to a revised perspective.   Of course, that sort of openness is rare –  it runs against human nature, particularly where the people making the final decision are the people who proposed the scheme in the first place.

And a consultative process shouldn’t be thought of, or presented as akin to, a public opinion poll.   If one wanted to make such decisions by public opinion poll then I guess (a) we wouldn’t delegate them to a specialised agency, and (b) we would commission a properly structured poll.   Apart from anything else, (a) people who are opposed to what is proposed are typically more likely to submit than those in favour, and (on the other hand) (b) especially when the numbers involved are small, it is easy for a handful of low-information submissions to be generated on either side of the issue.

The Reserve Bank, however, has tended to present the submissions as something of an opinion poll.     There was the silly line that “in general, submitters support the Reserve Bank’s objective to ensure that New Zealand’s financial system is safe” –  yes, and we support motherhood and apple pie too.  The issue isn’t whether the system should be “safe”, but how safe, and at what cost, on what assumptions.  And then

There was significant and wide-ranging media and public interest in the How much capital is enough? (PDF 545 KB) paper, with written feedback from 161 submitters.

Yes, 161 submitters is a lot more than the nine submissions they received on the previous paper in the longrunning capital review  but in the grand scheme of things –  considering the scale of the changes the Bank is proposing – it isn’t many.   And more than 20 per cent of the submissions turned out to be six lines or less: whether the submitter was for or against what the Governor was proposing (and in some cases it really isn’t clear) there is no useful information for a proper consultative process in submissions that short (unless perhaps one of the big banks had submitted “Dear Adrian, We agree.  Do start soon.”, which they didn’t).

Thus, when the Deputy Governor says

Many submitters, particularly from the general public, support the proposed higher capital requirements for banks.

He is correct.  Many did.  Very briefly.  Usually without much engagement in the argumentation and issue (although one of the Governor’s mates did write in to offer support and some argumentation, although strangely even he referred to some evidence that capital ratios should be 13-14 per cent, which led him to the view that the Bank’s proposed (minimum) ratio of 16 per cent was “acceptable”.)

And look at this attempt to play the populist card – the public versus the banks – a bit further

Some submitters, in particular banks and business groups, question whether the proposed increases are too large and too costly.

As they know very well, there were a variety of other serious –  more than half a dozen lines long – submissions from people with no vested interests who were very sceptical of the Bank’s proposal, and of the argumentation and evidence in support of it.

You also have to wonder how well the Bank would be able to defend a claim (perhaps in a judicial review) that the consultative process was a sham.  The Deputy Governor again

Increasing the amount and quality of capital can be reasonably expected to mean that banks can survive all but the most exceptional shocks, Mr Bascand says. “We think the costs of doing so are outweighed by the benefits – someone’s cost is for society’s broader benefit.”

(do note the attempt to play vested interests again: “someone’s cost”).  Isn’t it still months until the final decision is supposed to be made?  And yet the Deputy Governor can confidently declare not just ‘in putting out the consultative document we thought it likely benefits would exceed costs”, but (present tense) “we think the costs…are outweighed by the benefits”.  And if the Deputy Governor already knows perhaps he could release that cost-benefit analysis that so many submitters and other commentators have been calling for.  I guess they haven’t yet back-fitted the numbers to suit the Governor’s conclusion yet.

Continuing with the spin, the Deputy Governor moved on to invoke support from the International Monetary Fund and the OECD, both of whom released comments on the New Zealand economy last week.

Following its recent mission to New Zealand, the International Monetary Fund has released a Concluding Statement that highlights the need for strengthening bank capital levels and that the proposals appear commensurate with the systemic financial risks facing New Zealand. The Organisation for Economic Co-operation and Development’s latest Economic Survey of New Zealand expects increases in capital will likely have net benefits for New Zealand.

It is hard to make much of the IMF comments at this stage.  They are not much more than a couple of sentences in a press release, with no published supporting analysis.  And the Fund almost always backs the authorities – who are the people they talk to most  –  especially when central banks and regulators want to put more restrictions on banks. Why wouldn’t they?  Any economic costs don’t sheet home to them.  But the IMF’s support isn’t without its problem for the Reserve Bank.     Here is what they said

The new requirements would increase bank capital to levels that are commensurate with the systemic financial risks emanating from the dominance of the four large banks with similar concentrated exposure to mortgages, business models and funding structures.

Which, by logical deduction, appears to be saying that current levels of capital are grossly inadequate to the risks the New Zealand banking system faces. But there was no hint of these serious risks in past Financial Stability Report from the Reserve Bank (although they amped up the rhetoric in the latest one), and –  perhaps more to the point –  no hint of that in past IMF Article IV staff reviews or Executive Board discussions.  This snippet is from last year’s Article IV report, published as recently as June last year.

IMF capital

Not a word from staff, from the Board –  or, indeed, fron the New Zealand authorities in their published comments –  of a pressing need for a huge increase in minimum capital ratios.

The Deputy Governor also attempts to deploy the OECD in support.  They typically aren’t particularly expert in such matters, but here is what they actually said:

The Reserve Bank has proposed large hikes in bank capital requirements. High bank capital requirements reduce the cost from financial crises, but might also dampen economic activity through higher lending rates. On balance and nothwithstanding considerable uncertainty, increases in bank capital are likely to have net benefits, but the impacts should be carefully monitored.

Take it from me – I negotiated line by line wording on numerous OECD reports –  that is about as tepid as it gets.  It doesn’t even endorse the huge increases in minimum capital the Governor is proposing –  the comment is simply about “increases”, and there is a long way from current levels to what the Governor has planned.

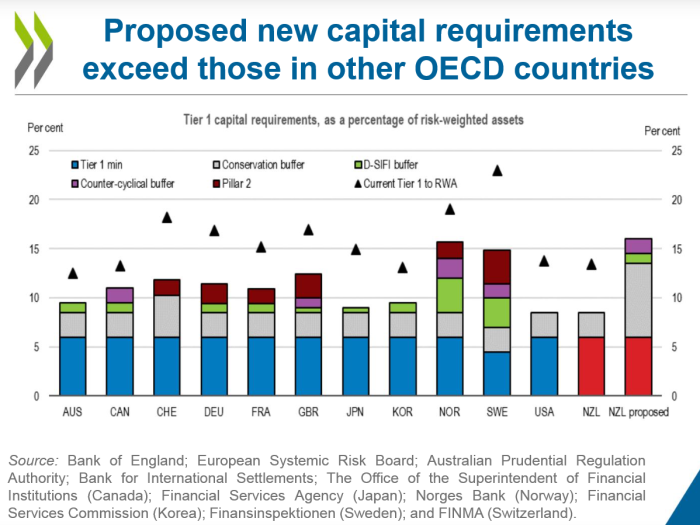
And if you doubt my take on the OECD, here is their own slide from the presentation when they released the report in Wellington last week.

OECD capital.png

And these comparisons are just of headline required ratios (triangles are actuals I presume), while part of the Reserve Bank proposal is to materially increase the calculation of risk-weighted assets for the big 4 banks, to an extent that would, in effect, add another three percentage points or so to those New Zealand numbers, which already –  in the OECD’s words – “exceed those in other OECD countries”.

So, spin all the way down.    Complete with the observation about their continuing consultation –  fishing around to find some supporters perhaps

It is continuing its stakeholder outreach programme, which includes conducting focus groups to understand the public’s risk appetite, and engagement with iwi, social sector and industry groups, financial institutions and investors. It has also engaged three external experts for an independent review of its proposals.

They elaborate a little in the document that supposedly summarises the submissions.  On the iwi point “a workshop with Maori service providers” –  but why, what specific issues might there be for “Maori service providers” (whatever they are) from any others –  Catholic, Pacific, or whatever?   And the workshop they plan with “social service providers and NGOs” really looks like an attempt to drum up support for the shonky “social costs of crises” material they’ve run previously, and which Ian Harrison (in particular) has comprehensively demolished.  I will be lodging an Official Information Act request for the reports etc from any focus groups –  again it looks a lot like an attempt at distraction, a populist Governor trying to summon a mandate from “the people”, rather than from Parliament.

Also from that Summary of Submissions, this attempt to spin the issue (wasn’t this supposed to be a summary of submitters’ view and analysis?)

It’s about keeping New Zealanders, their investments, and the economy safe from the disastrous impacts of financial instability and the failure of a registered bank, which historical evidence suggests can be very long-lasting and go beyond just the financial costs for people.

Loaded language (and not even particularly well written).  Nothing like a bogeyman to scare people with I suppose, but surely only fairly geeky people even read a document like this.  Who is the Governor hoping to impress?  Not much sign of calm, balanced, detached and objective consideration, that’s for sure.

(Having said that, it was noticeable reading through the Summary itself how few arguments staff managed to find from the submissions in support of what the Governor was proposing.)

The other person who has weighed in this week is the Minister of Finance, with a rather plaintive appeal to everyone to get on and talk nicely, as if he was a harried parent pleading with children to just play nicely (“pleeeeeeease”) at the end of a long tiring day.   The Minister is reported to have called for a “mature debate”, observing

“I want to remind all parties that we are still in a consultation process. I am calling on all interested participants to listen to and work with each other constructively as this work is carried out.”

It wasn’t exactly authoritative.

Perhaps he might address his concerns specifically to the Governor, including via the Acting Secretary to the Treasury and the Bank’s Board (whose job to work for the Minister and the public to monitor and hold to account the Governor).   And perhaps he needs to wake up to the power asymmetries here: we have a single unelected official (largely appointed by some other unelected board members, all appointed by the previous government), championing huge increases in minimum capital requirements, having made no effort to socialise thinking or test reasoning before settling on a view, and is now judge and jury in a case he himself is prosecuting.  And the “defendants” –  not just banks, but the wider economy –  have no rights of appeal.  And the way the Governor has conducted himself –  dismissive of sceptical comments, strong elements of pre-meditation, no cost-benefit analysis, no serious analysis of the transition, no serious engagement with the Bank’s preferred resolutiuon tool (the OBR), “independent” experts handpicked by him to review the proposal (but barred from talking to anyone else without his permission) and so on –  doesn’t exactly inspire confidence.  He talks a lot about “making banks safer”, but all independent analysis  –  and their history –  suggests the banks are fairly safe already: we could reduce lots of risks in society to near-zero (the road toll for example) but the costs just aren’t worth it. He simply hasn’t made the case that this proposal –  which he cannot commit would even endure beyond his governorship – is worth the risks and costs.

The Minister of Finance does not have formal powers to stop the Reserve Bank.  It is right and proper that the Minister should not be able to interfere with supervisory decisions or judgements involving individual institutions, but what is going on here is probably the largest policy initiative (bigger than, eg, outsourcing/local incorporation) around bank regulation in many decades.  Big policy calls –  in areas where there is huge uncertainty (as the OECD, among others, says there is here) – really should be a matter for politicians.  At very least, they shouldn’t be a call for a one-man band with a bee in his bonnet (and without even any particular specialist technical expertise).

If the Minister really wanted to display some leadership he would call in the Governor (in consultation with the Secretary to the Treasury) and strongly urge that the entire review be put on hold.   There are several and sufficient reasons to do so:

  • the government has made provisional decisions around deposit insurance, but there has been no attempt to link that initiative and the bank capital proposal,
  • Phase 2 of the review of the Reserve Bank Act is well underway, and the provisional intention is that the Governor should no longer be the sole decisionmaker on matters of prudential policy, and that in future Treasury should play a stronger review role,
  • there is absolutely no urgency about doing anything about bank capital now (as every one recognises banks are strongly capitalised and have strongly capitalised parents, and it is only a few years since capital ratios were increased),
  • if anything, there is a strong case for doing nothing right now: the looming economic slowdown and diminished inflation pressures that are leading to OCR cuts remind us again of the approaching limits of conventional monetary policy.  The last thing we should be doing in that climate –  when stress tests etc show that bank balance sheets are sound –  is throwing more sand in wheels, potentially impeding credit availability over the next few years.

Of course, the Governor could refuse such a request, but he would be very unwise to do so.   The Governor has no public mandate, no independent source of legitimacy, and this is not an issue about the supervision of an individual institution –  it is about overall economic management, where the big parameters (eg inflation targets, debt targets……and financial stability goals, which are harder to pin down) should be made by those we elect, and can toss out again.   It should hardly be controversial if the Minister were to suggest to the Governor that he would be prepared to legislate so that in future changes in bank conditions of registration –  the lever the Bank uses –  could only be done by Order-in-Council, not simply on the Bank’s whim.  After all, that is how the prudential regime works for non-banks (and you’ll note there is no proposal in front of us to markedly increase capital requirements for non-bank deposit takers).

We need expert advice from the central bank – something we aren’t getting at present –  and expert independent adminstration of the rules, but the big policy calls (which involve significant risks, which no one can determine definitively) need to be the responsibility of the elected government.

For anyone interested, my own submission is here.

PS.  As Martien Lubberink at Victoria has pointed out there is another international agency paper out just recently that really doesn’t help the Bank’s case much if at all. I might touch on that tomorrow.


Emissions and immigration policy

Just listened to an RNZ interview with National’s climate change spokesman Todd Muller, around the silly question of whether or not a “climate emergency” should be declared.  Muller called it symbolism, but symbols have a place –  it is much worse than that, just empty feel-good virtue signalling  (whether or not you think our governments should be more aggressive in doing something to lower New Zealand emissions).

But Muller introduced his comments referring back to a sense as early as 1990 that something needed to be done.  And it reminded me of the single worst policy National and Labour have presided over for the last 30 years, in terms of boosting emissions from New Zealand: immigration policy.

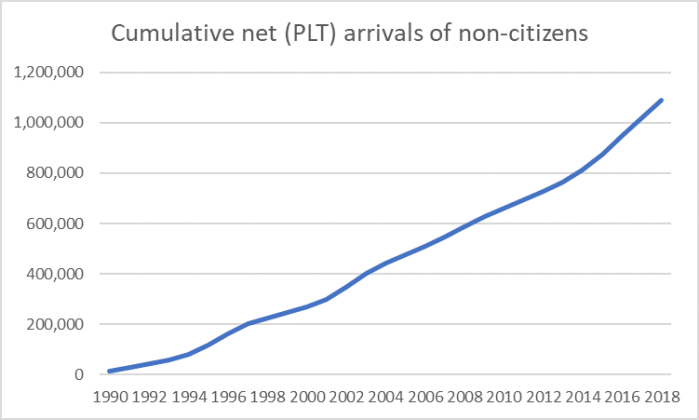
New Zealand’s population in 1990 was about 3.3 million.  Today it is almost five million.  And here is a chart, using official data (which has some weaknesses, but the broad picture is reliable) of the cumulative inflow of non-New Zealand citizens since 1990.

PLT 2019

That data series was dumped last year, but you can add another 60000 or so people in the year since then.    Almost all of them needed explicit prior approval from New Zealand governments –  more than 1.1 million of them.

Over such a long period, the cumulative inflow becomes a little misleading.   It understates the impact.  Of course, over 30 years some of the migrants will have died, but many more will have had children (or even grandchildren).  Those children will (mostly) be New Zealand citizens, but that doesn’t change the fact that their presence –  and their emissions (resulting from their life and economic activity) – results from explicit immigration policy choices.

Those who are made uncomfortable by all this but simply wish to dismiss it will say “oh, but emissions and climate change are a global problem, and it doesn’t really matter where the people are”.  Strangely, this is not usually an argument the same people invoke when they favour (say) New Zealand oil and gas exploration bans, or other New Zealand specific actions that will have either no impact on global emissions, or only a trivial impact.

As you will no doubt recall, it is not as if New Zealand is already some low-emissions nirvana.  Per unit of GDP (average) emissions in New Zealand are among the very highest, and per capita (average) emissions are also in the top handful of OECD countries.    The typical migrant to New Zealand is not coming from a country that has higher emissions than we do.    Rather the reverse.  Of course, it isn’t easy to distinguish (empirically) the marginal and average emissions, but it is simply silly to suggest that the policy-driven rapid population growth has not had a material impact in boosting total New Zealand emissions –  migrants drive cars and fly, migrants live and work in buildings (that often use concrete), migrants have even helped maintain the economics of the dairy industry.  On a cross-country basis, I showed in an earlier post the largely unsurprising relationship betwen population growth and change in emissions over decades.  New Zealand’s experience was not an outlier (except perhaps in the sense of much faster –  policy-driven –  population growth, reflected in the emissions growth numbers.  If anything, and at the margin, New Zealand’s immigration policy has probably increased global emissions.

Of course, there would be a reasonable counter-argument to all this if it could be confidently shown that the high rates of immigration –  highest in the OECD for planned immigration of non-citizens over the period since, say, 1990 – had substantially boosted average productivity in New Zealand.  Then the additional emissions, and associated abatement costs (not small), would simply have to be weighed against the permanent gains in material living standards from the immigration itself.  But even the staunchest defenders of high –  or higher still – rates of immigration can’t show those sorts of productivity gains and (since demonstrating it would be a tall order) can’t even come up with a compelling narrative in which large productivity gains from immigration go hand in hand with the continued decline in our productivity performance relative to other advanced economies.

If the government (or the National Party) were serious about “doing our bit” (or just “being seen to do our bit”) about emissions and climate change, and if –  at the same time –  they really cared much about living standards of New Zealanders (‘wellbeing’ if you must), they would be taking immediate steps to cut permanent immigration approvals very substantially.  Not only would that lower population growth and emissions growth relatively directly, but it would result in a materially lower real exchange rate, which would greatly ease the burden on competitiveness that other anti-emissions measures are likely to impose over the next few years, would ease pressures on the domestic environment (and might even, thinking of my post earlier this week, ease the economic pressures on the dairy industry, while providing margins to deal directly with the environmental issues around that industry).

For the country as a whole –  New Zealanders –  it would be a win-win.   That isn’t to pretend there would not be some individual losers –  we’d need fewer houses, potentially developable land would be less valuable, and some industries (particularly non-tradables ones) that have come to rely on migrant labour would face some adjustments.  But, and lets face it, there is no sign the existing model –  in place in some form or another for several decades –  has worked well for the average New Zealander –  the productivity performance has been lamentable, and we’ve created a large rod for our own back on the emissions front.

But our political parties – every single one in Parliament, based on words and on their records in government –  would prefer to pretend otherwise, and keep on with the failed, corrosive, immigration policy, which hasn’t worked for us, is unlikely to ever do so (given our remoteness etc) and is so far out of step with what the bulk of advanced countries do.


The Government’s Industry Strategy

When I heard yesterday that the now-former Economic Development minister David Parker had made an encore appearance to launch something called “From the Knowledge Wave to the Digital Age”, I wondered why he would want to remind anyone of the Knowledge Wave, a conference held under the previous Labour government in late 2001. Of course, my impression of that event was somewhat jaundiced by the fact that my boss, then-Governor of the Reserve Bank Don Brash, had made a “courageous” and somewhat ill-judged speech at the conference –  against the advice of many of his senior staff, at least as to content – that with hindsight could have been read as an audition for his post-Bank forays with the ACT and National parties (although I’m 100 per cent sure it wasn’t intended that way).

But the bigger problem is that, for all the talk, all the ink spilled, at that conference and through the subsequent Growth and Innovation Framework nothing much changed for the better.  The productivity gaps (New Zealand vs other advanced countries) didn’t start to close, the economy didn’t become more foreign trade (outwards and inwards) oriented, there were no fresh waves of greenfields FDI.   Instead, we had a reasonably strong cyclical upswing (rapid house price inflation, general inflation showing signs of getting away)…..followed by a nasty recession and a sluggish subsequent decade.

David Parker gave a speech at the launch of what is supposed to be “the Government’s Industry Strategy”, and that is going to be my focus here.  I haven’t read the full 50 page document, but I’ve skimmed through it and will include a few observations drawn from that.

Perhaps how people react to “Industry Strategy”  is one of the ways one tells them apart.  I was a bureaucrat for a long time  (but in the era in which the Reserve Bank believed in letting markets work and eschewed direct government interventions as much as possible), but when I hear the words “Industry Strategy” my heart does not leap with excitement, rather I think of the Soviet Union, the eastern-bloc, the People’s Republic of China (that not-overly-productive middle income country), or even –  more mundanely –  New Zealand’s own past failures in this regard: plans and conferences and strategies, often with little to show for it (when we are fortunate) but often enough with white elephants to mark the landscape, or memories of money just poured down the drain.  But I guess it is different in today’s Labour Party, or in today’s MBIE –  the modern version of the Department of Industries and Commerce (too many in the National Party seem to have had the same inclinations).   The government has a plan, a strategy –  or a whole series of them –  not for the economy as a whole (getting the basic structures right etc) but for individual industries.  And, with little accountability and no market discipline at all, they are keen to use your money and mine to back those strategies, boldly going where private investors have, thus far, decided not to.

As often with David Parker, there are sometimes glimpses of recognition of real problems.

I believe there is no doubt we inherited an economy based on excessive property speculation and high rates of immigration driving consumption led growth. The latest OECD report on New Zealand confirms this.

The infrastructure deficit left behind – not just schools, hospital, roads and public transport, but also private and public housing – will take a decade to catch up.

This is serious, but the adverse effect on productive investment was also profound.

Low per capita investment in our productive businesses has inhibited the diffusion of technology, and the development of innovative new products and services.

I wouldn’t frame some of it quite that way (notably that Labour trope about “excessive property speculation”) but, broadly speaking, he isn’t wrong.   Perhaps a shame there is no mention of the real exchange rate, at all, but it isn’t nothing.

The problem is, though, that this is buried deep in a speech which is mostly full of breathless energetic accounts of great things already done and great stuff the government (and industry) are about to do.

The flip side of the enormity of the 4th industrial revolution on the future of work, is the correspondingly huge potential for business.
It is an exciting time.
A myriad of new ways of new products and services are being made possible.
Most improve productivity.
Many are needed to decarbonise the world to avoid catastrophic climate change, or to combat pollution of our rivers and oceans. Others will overcome debilitating disease, improving the lives of millions.
I believe that it is the duty of every government to address both the future of work, and to maximise the up-side by chasing down as many of these commercial opportunities as we can, so as to harness the new jobs and value.

(I’m still old-school enough to think of outrages when I see the word “enormity” but let that pass).

Notice that second to last line, it is the “duty” of governments to “chase down” commercial opportunities.   In part, presumably, because in the Minister’s view it is all some sort of zero-sum game.

It is a race. Others want the prizes that we seek. 

Which isn’t the way most economists think of economic growth and development, perhaps especially not in a country that start so far behind the global productivity frontiers.

And then it just becomes completely delusional

Since the 1970s successive governments have wrestled with our productivity challenges; how we add value, upskill and diversify our economy.

We should acknowledge the important milestones and efforts of yesteryear.

They show that when we together have a plan and chart a direction, our economy strides forward.

To repeat, there is no time in the last 46 years –  say, since the UK entered the EEC (the Minister’s reference point) –  when New Zealand has made any sustained progress in closing the productivity gaps to the other advanced economies.  Instead, as I illustrated in Monday’s post, they’ve kept on widening.  They are widening now, after five years –  both governments –  of no productivity growth.

Of course, the officials themselves know this –  even if they squirm in their chairs  –  and, to his credit, Parker didn’t stop them including this chart in the fuller document.

MFP parker

It isn’t the chart I’d have chosen myself, but it makes the point nonetheless.  And recall that all three of these countries were already materially richer, with higher levels of labour productivity in New Zealand, back in 1990.

In fairness, the Minister does have a place for the private sector

Government can direct investment towards the regions, and champion sectors where we see a comparative advantage, but it is the mobilisation of the private sector which delivers the jobs the big gains.

Better if they just left aside the picking winners –  or even propping up losers –  implicit in the first half of the sentence.

And this is where the Minister praises the Knowledge Wave and the Growth and Innovation Framework, going on to note

Our predecessors identified three priority areas. These were chosen because of their potential for export growth and because of the underlying importance that competence in the sector had to the wider economy. Spillover benefits.

The crucial sectors identified were ICT, biotechnology (with a food and beverage bent) and, thirdly, the creative sector and design.

They got it right and I am pleased to doff my cap to those who called it at the time.

Not that reference to export growth.   We get this guff

Our telco competence is a considerable achievement, and a prerequisite to the development of Xero, Vista, Coretex and a myriad of other companies that sell software as a service, which have flourished.

And the other sectors have boomed too.

Fisher and Paykel Healthcare. A2 Milk and a range of other food and beverage companies. Weta Workshops and its spinoffs. Now household names. Billions of dollars in enterprises that have helped build our country.

The Growth and Innovation framework is the GIF that keeps on giving. Computer gaming, robotics, customer service avatars, nutrient monitoring software.

The race is on.

Our TIN200 companies are growing strongly, with technology exports now our third largest export sector (after tourism and agriculture). New hires abroad as well as export sales growth are described in the TIN200 report on the table.

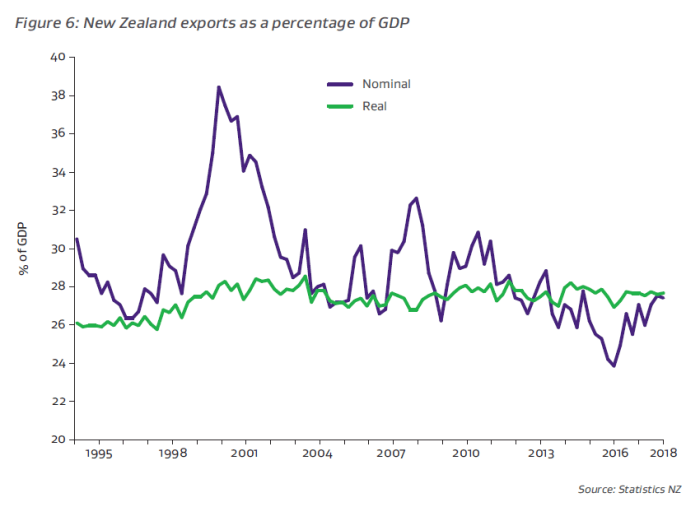
One can pick all sorts of holes in that  (massive film subsidies for example, or the fact –  as I’ve documented here before –  that on no proper statistical definition of exports are “technology exports” “our third biggest export sector.  But don’t worry about those sort of picky details.   Wouldn’t the Minister’s text lead an uninformed reader to suppose that the outward orientation of New Zealand’s economy had markedly increased since the early 2000s?   Nothing in the speech suggests otherwise, but (again) lurking in the full report was the sort of chart I run here regularly.

exports parker.png

It just hasn’t happened.   There are individual success stories, of course –  as there have been throughout our history –  but it doesn’t add up to much, when productivity growth has lagged further, and our export/import shares have gone sideways or downwards.     That, apparently, was the legacy of those earlier planners (actually I doubt all their words etc added up to much at all).

But the Minister is breathless in his enthusiasm and goes on

Kiwisaver and the Cullen Superannuation Fund have deepened our investment skills and capital markets.

New Zealand Trade and Enterprise has been important in helping many exporters sector navigate their risky journey into new markets.

Our seed or angel investment capital market has matured. The innovation ecosystem has strengthened as management capability and globalisation ambitions have both grown.

We still suffer a gap in series A and B capital rounds, which this slide shows – something we have addressed in our latest Budget.

The $300m boost, and lead being shown by our largest NZ investor – the Guardians of the NZ Superfund – will attract private sector investment and help our firms to achieve their potential.

This will help to directly fill the current ‘capital gap’, and draw in other capital from NZ and abroad.

Give me leave to differ.   National savings rates haven’t improved materially, whatever NZTE has done –  let alone all those preferential trade agreements, which Parker is trying to negotiate more of – exports haven’t become a more important part of the economy, more firms aren’t showing they can foot it globally.       And when you are reduced to lauding a government money-pot, with no market disciplines and little accountability, as your catalytic hope, it is all a bit thin, and worrying to boot.      And I have no real idea what that final sentence means –  but if he means low rates of business investment, in reasonably well-run countries, private firms will invest eagerly to take advantage of profitable opportunities, when they exist.

The breathless energy continues

There is no time for delay. The seemingly exponential growth in opportunities will within just a decade or two morph into the law of diminishing returns.

At one level its simple, if we want these innovative parts of the economy to grow faster, we have to apply more of our precious resources to the task.

Don’t ask me what it means, but it would certainly good if there was some serious recognition from the top of government that our economic performance has really been pretty lousy for decades and an evident determination to get to the bottom of why, rather than just trying to pick a few more “winners”.

The gush goes on, sector by sector (you can read it for yourself), but haven’t we heard it all before.  They were probably discussing such things, enthusiastically, at the National Development Conference 50 years ago.

The speech ends with a full page on “Industry Transformation Plans”. I’m guessing they probably won’t come to much, so perhaps little harm done, except that more years pass, and more energy is devoting to avoiding the real issues.  Here is a sample of the Minister’s great enthusiasm for what government can and will do with these plans.

These describe an agreed vision for the future of a sector, and set out actions required to realise this vision.

Industry Transformation Plans are in train across large sectors of our economy – in agriculture with the Primary Sector Council for example.

Our first Industry Transformation Plan was the Construction Sector Accord. It was co-developed by an industry Accord Development Group. Industry leaders working with the Government.

Our next Industry Transformation Plans focus on four other priority sectors: food and beverage, digital technology, forestry and wood processing, and – as I have said – agritech.

The Prime Minister’s Business Advisory Council and the Future of Work Tripartite Forum will provide strategic leadership.

Key components of each plan will include assessments of the opportunities and risks from digitalisation, the future of work and skills training.

Risk sharing between government, businesses and labour to enable skills training to upskill existing workforces will be crucial to avoid the rising inequality which will otherwise flow from the future of work.

Each plan will also set out decarbonisation pathways, ways to increase exports, as well as an assessment of capital constraints. Partnerships are needed.

Business, workers and government all have a stake in every industry and we need to partner to make a real difference for New Zealand.

It is almost literally incredible.  The hubris, the lack of any apparent recognition of the limits of government knowledge, the complete absence of any sense of the benefits of vigorous competition, of creative destruction even, or market disciplines and so on.  Bill Sutch might have been proud.

It is sad in a way.  I suspect David Parker is better than this, and knows that this sort of stuff just isn’t likely to be any more transformative than the last (or first) wave of goverment talkfests.  But when you aren’t willing to even think about tackling the real issues  – the real exchange rate doesn’t appear in the 50 page document either –  I guess you need a lot of sound and fury, lest –  just a year out from an election –  it look as if the government is doing nothing, has no ideas, or doesn’t really care.  Sadly, all the talk is likely to signify almost nothing, in making a real difference, reversing the economic underperformance, and even building (in the government’s own words) “an economy that is more productive, sustainable, and inclusive for all New Zealanders”.


Apocalypse Cow

That was the title of Wellington economist Peter Fraser’s talk at Victoria University last Friday lunchtime on why Fonterra has failed (it is apparently also a term in use in various bits of popular culture, all of which had passed me by until a few moments ago –  and a Google search).    Peter is a former public servant –  we did some work together, the last time Fonterra risks were in focus, a decade ago –  who now operates as a consultant to various participants in the dairy industry (not Fonterra).   He has a great stock of one-liners, and listening to him reminds me of listening to Gareth Morgan when, whatever value one got from purchasing his firm’s economic forecasts, the bonus was the entertainment value of his presentation.       The style perhaps won’t appeal to everyone, but the substance of his talk poses some very serious questions and challenges.

The bulk of Peter’s diagnosis has already appeared in the mainstream media, in a substantial Herald  op-ed a few weeks ago and then in a Stuff article yesterday.  And Peter was kind enough to send me a copy of his presentation, with permission to quote from it.

His starting point is with the misplaced belief among senior political figures 20 years ago that by allowing the creation of Fonterra –  using legislation to override the Commerce Commission – the door would be opened to the evolution –  in pretty short order –  of something equivalent to New Zealand’s Nokia.  In revenue terms, the promise had been

From a starting point of only $5B, they outlined a six-fold increase in revenues in only 10 years to $30B.

Critically, just under two-thirds of the $30B would come from what is euphemistically known as ‘value add’: specialised ingredients and biotech-heavy products.

So this was almost $20B of revenue from a starting point of ‘nothing’.

Actual revenue now, 17/18 years on, is about $20 billion (including a structural improvement in world dairy prices) and relatively little is from those vaunted specialised products.   The rate of return on that business, in turn, is barely higher than that on the bulk commodity business.

And

A much cited figure is the 2018 value report published by the International Farm Comparison Network (IFCN). This ranked Fonterra 17th out of the 20 companies in terms of value creation.

Its figures show while Fonterra collects the second largest amount of milk (and is the world’s largest milk exporter), its estimated turnover per kg of milk solids is only US60c.

By comparison, Danone is the 11th largest milk processor, but it turns over US$2.40 for every kg to make it the best performer. Nestlé is next at US$1.90 per kg. The average across the entire group is $1.00.

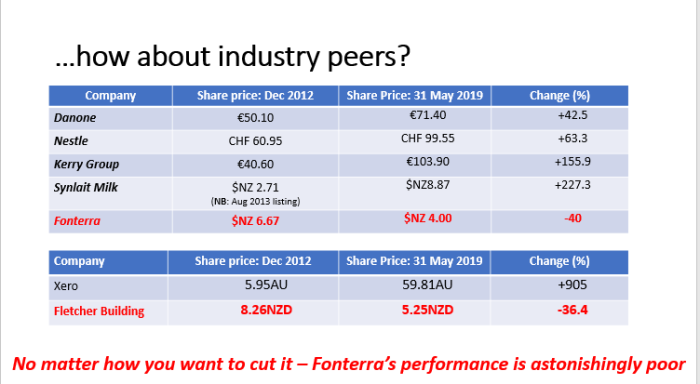
The “failure” is nicely illustrated in the share price (the non-voting shares were listed in 2012).   The comparison against the NZX index is stark, as is that against industry peers.

fraser 1

Apparently the share price fell further in June (and Peter told us that on Thursday the share price closed a touch below the initial valuation back in 2002).

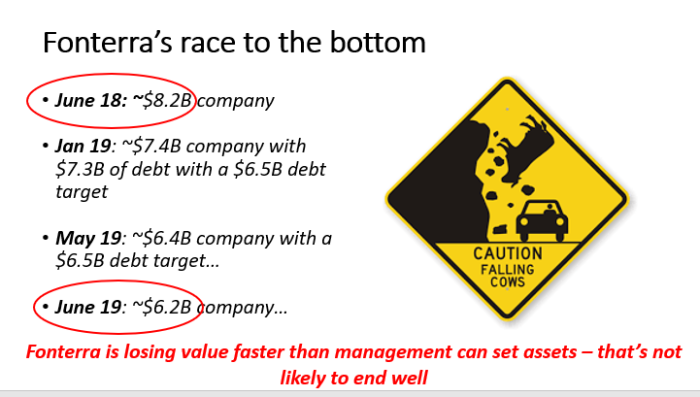
Fonterra asset sales have been in focus this year.  They started when the market value of the company was much higher than it now is, and haven’t kept up, so that the ratio of market value to debt is now higher than it was.

fraser 2

For various reasons I don’t want to get into the fine details of DIRA, but as I understand the essence of Peter’s story is that:

  • farmers themselves never much cared about the added-value ideas (New Zealand’s Nokia and other dreams).  Why would they?  They are farmers, and their interests were primarily about a high price for their milk, and a high/rising price for their land.
  • between provisions in the legislation and in the constitution of Fonterra, the rules mean Fonterra has been paying materially too much (Peter says 50c per kg)  for milk purchased from suppliers,
  • dividends on the shares have been limited,  which doesn’t matter to (voting) farmer shareholders, but does matter to the outside shareholders, and retentions (or retaining earnings) –  now the main source of additional capital in a cooperative –  have also been low.
  • given Fonterra’s dominant market position, the too-high milk price also drives up the price of milk other industry participants have to pay.   That has encouraged more milk production – including “half way up Mt Cook”, and with associated environmental issues –  but also makes it difficult for firms to make profitable investments in other (value-added) products.

Peter again

…the idea of using the ingredients business as a springboard to a value creation business was part of the original concept and is actually a good one.

The problem is, it basically didn’t happen.  There are two reasons for this.

Firstly, Fonterra relies heavily on payout subordination so has very high gearing – something it seems the Board has failed to learn from after courting near disaster during the GFC.

This constrains Fonterra’s ability to borrow further, such as for acquisitions or to finance value creation activities.

The other problem is woeful levels of retentions, which are critical for a coop because without new capital from a growing milk supply, retentions are only other way of getting new capital.

So Fonterra remained a capital starved, deeply indebted and under performing farmer-owned cooperative.

That “near-disaster” ten years ago (his account here) was when I first met Peter.  Global funding markets was seizing up, world dairy prices had fallen sharply, land prices were falling, and lenders to dairy farmers were becoming seriously uneasy (including parents in Australia that hadn’t fully appreciated quite how much exposure, to a sector with very illiquid collateral, had been taken on).   In those days, struggling farmers had one buffer and Fonterra one exposure, that doesn’t exist today –  redemption risk (on the farmers’ own production-related shares in the co-op).

That particular risk has now been shifted back onto farmers, which probably leaves Fonterra’s own lenders a bit more comfortable (but in turn removed one discipline from the Board).  But there is still a hugely high level of debt (presumably largely from international markets and banks).

Peter argues that, unless something dramatic changes pretty soon, Fonterra is likely to run into crisis within the next five years or so (and, he argues, since the current government probably likes to believe it will still be in office five years hence, they really need to focus on this now).

I was among those at the presentation the other day who weren’t entirely sure how this mooted crisis would come about, or what form it might take.   After all, Fonterra isn’t a conventional company.  The traded shares –  the price of which has been falling away –  are not a direct stake in Fonterra.  The share price could go to zero (if, say, unit holders lost confidence there would ever be dividends, tied to value-added returns) without rendering the co-op itself insolvent.    The banks and bond markets that have lent to Fonterra are exceedingly unlikely to lose their money –  that is what (milk) payout subordination means –  but it is likely that quite a few of the existing facilities have caveats and covenants about financial conditions Fonterra has to meet.  And the asset sales programme of recent months seems fairly explicitly premised on the idea that the market price of the shares (and those the notional market value of the co-op) mattersa, including to lenders.    Presumably there has to be a risk that if Fonterra’s underperformance continues, lenders would become increasingly reluctant to renew existing facilities, and the costs of what credit they could still obtain would rise?

And, of course, there is only so much money to go around (perhaps rather less if commodity prices were to fall away sharply in a recession in the next few years), and what is paid to providers of capital (debt or equity) can’t be paid to farmers.  The dairy farm industry has an uncomfortably high, and rather concentrated, level of debt already. And dairy land values are underpinned, to a considerable extent, by the actual and expected milk price.  50 cents off the milk price for one year might not make much difference to land values, but if Fraser is right and prices are perhaps 50c too high generally, adjusting the milk price itself into line with that would severely impede the profitably of many dairy farms (as Fraser notes, on-farm costs have been rising, and much of any margin New Zealand dairy farmers had relative to the rest of the world appears to have been greatly eroded.  Fonterra also risks losing suppliers, and ending up with stranded assets.

The sketch outline of Peter Fraser’s story –  directional pressures – seems plausible to me, but here I’m mostly trying to tell his story rather than sign up to it all.  I don’t claim enough industry familiarity for that, and haven’t been exposed to serious alternative arguments –  if there are some, bearing in mind the repeated underperformance over a long time now.  The Fonterra statement to Stuff, in response to Fraser, didn’t instill great confidence

Fonterra managing director co-operative affairs Mike Cronin responded in a statement:
“Our focus right now is on the future of our co-op. We’re well down the path of a strategy review which will enable us to deliver on our potential and meet people’s expectations. We know where we want to go, but how we get there will take time. We will play to our strengths – our New Zealand provenance, our pasture-based farming model and our dairy know-how.”

Fraser’s presentation ended with these lines

fraser 3

That final line –  Westland as dress rehearsal –  is also where I want to end.    Fraser argues that, most likely, Fonterra will need extensive recapitalisation and that –  short of nationalisation –  there is no likelihood that the New Zealand market could provide the necessary capital, and thus that a foreign takeover is the most likely market solution.

Perhaps it would be the eventual market solution, but I struggle to believe that the market would be allowed to operate in such a case.  The politics of foreign ownership of Fonterra would be too much for any major political party –  in today’s climate – to swallow.  Most likely, we’d have government moneypots –  the New Zealand Superannuation Fund and ACC –  corralled to provide the new capital  (those two are already half owners of KiwiBank, and NZSF falls over itself to pursue politically-attuned projects).

If I read Peter correctly, he believes things could be turned around.  But that there is little sign of it from either Fonterra –  and no demand for it from their farmers –  or from the government.


40 years on

The almost-always-upbeat Herald “Business Editor at Large” Liam Dann had a column yesterday reflecting on the changes in the New Zealand economy  in the 30 years since he was studying 7th form economics in 1989.  “Studying” may be an overly generous term here: in Dann’s words

Let’s ignore the fact that I was a distracted surfer with a bad blonde haircut, prone to sitting with the most disruptive kids in the room.

As it happens, it is 40 years since I was studying 7th form economics (I was the nerdy kid).

In the 30 years since Dann’s 7th form economics teacher was bemoaning all that was wrong with the New Zealand economy then, inflation has come down, the unemployment rate is lower, and governments normally aim to run operating surpluses. We were in the middle of an extensive economic restructuring back then, and the full aftermath of the massive credit and asset price boom of the previous handful of years was just about to be felt (DFC, for example, failed in late 1989, while the second BNZ crisis was still another year away).    Net public debt in 1989 was about 40 per cent of GDP  –  not disastrous, but far from good either –  but (little recognised at the time or later) the government was already running primary surpluses (ie deficits were mostly financing costs, the real consequences of which were, in turn, overstated by the effects of inflation).

But I wondered how the comparisons looked with 1979, my 7th form year.   Inflation in 1979 had been even worse than it was by 1989 (when we were already well on the way to getting back to something like price stability), but on the other hand the unemployment rate in 1979 is estimated to have been (backdated HLFS estimates) only  about 1.4 per cent.  Quite a difference from today.     And, somewhat to my surprise when I checked the Treasury’s numbers, net public debt as a share of GDP in 1979 was much the same as it is now.  And if the financial sector in 1979 was still more regulated than it is today – I was regaling my kids yesterday with stories about how the last restrictions on current account foreign exchange transactions didn’t come off until 1982 –  at least at the time the policy changes were in the right direction (liberalising), not the wrong direction as we’ve now been for the past six years.

Some things are clearly better than in either 1979 or 1989 –  New Zealand’s terms of trade reached the end of a longrunning decline in about 1988 and (equally outside our control) have been quite a lot stronger since then.  For such small mercies we should be grateful (a 20 per cent lift in the terms of trade is roughly equivalent to a 6 per cent lift in average national incomes).

And I’m not here disputing that in material terms the average New Zealander is materially better off than our parents were in 1979 or 1989 (be it life expectancy, smartphones, cheaper cars, overseas holidays etc).  That is true of almost every country in the world (think Venezuela for the sorts of places that are exceptions.    And those also aren’t the arguments Liam Dann seems to be making when he says of the present –  the headline to his column  –   “The economic numbers that would have blown us away in the 1980s”.

Instead he talked about how hard it was (in prospect) to get a job as a young person in 1989.  Maybe, but as it happens the employment rates for 15-19 and 20-24 year olds are pretty similar now to what they were in 1989 (and, sure, more people go on to tertiary education now, but it will be a rare tertiary student now who doesn’t have a part-time job.

Now, in a way I have been a little unfair to Dann so far.  Despite the headline, I don’t think his intention was to be that upbeat.  Later in his column he notes high levels of private debt, and the incidence of homelessness (although weirdly he presents the latter as being in some sense the “price of economic stability” –  which is simply wrong.    But he avoids actually identifying the policy changes –  land use restrictions etc –  that have meant that whereas in 1979 (in particular, near the trough of a multi-year real house price slump) or in 1989, houses were relatively affordable, they simply are not today.  I’ve noted previously, that I bought my first house in 1989.  In today’s dollar terms, that house cost just under $300000, just down the road from where I live now.  The same house today would probably cost $850000+ (the median price now for this suburb is just over $900000).    It leaves me very glad I was 26 then, not 26 now.

Perhaps the worst of it is diminished ambitions.

Back in the late 1970s, people talked in terms of how we’d crippled out export prospects, recognising that a small country’s prosperity depended on lot on the ability to create a climate in which locally-based firms were taking on the world and winning.  People talked in terms of the tax on actual and potential exporters that tariffs and quotas represented, and looked forward to a day  when we’d stop tying two arms behind our back.  By 1989 many of these restrictions etc were well on the way to being removed, but everyone knew it took time for the gains to flow –  indeed, we had expert overseas advisers highlightin the significance of the real exchange rate (then temporarily boosted by the drive to get inflation down).

And yet 30 or 40 years on, the foreign trade shares of GDP (exports and imports) are much the same now as they were then.   There is still lots of talk about export-led growth etc, but no remotely credible story from our politicians or officials as to how this might –  at last – come to be.

And then, of course, there is the small matter of productivity. It isn’t everything, but (in words not original to me) when it comes to long-term average material living standards it is almost everything.

The 1970s were a disastrous decade for New Zealand productivity.  We slipped a long way down the OECD rankings in a single decade.

And here is an adaptation of a table I’ve shown here previously (I’ve just added a 1980 column), comparing average labour productivity in New Zealand and in the leading bunch of OECD countries.

Table 1: Labour productivity: New Zealand and a leading OECD group
GDP per hour worked
USD, constant prices, 2010 PPPs
1970 1980 1990 2017
New Zealand 21.4 22.7 28.5 37.3
Netherlands 27.5 40.2 47.7 62.6
Belgium 25 37.9 46.6 64.8
Denmark 25.1 34.8 44.7 64.9
France 21.6 32.0 43 59.8
Germany 22.3 32.2 40.6 60.5
Sweden 27.2 34.5 38.8 61.7
United States 30.9 35.9 41.8 64.2
Median of seven 25.1 34.8 43 62.6
NZ as per cent of median 85.3 65.2 66.3 59.6

We’ve lost quite a lot more ground since 1979/80 or 1989/90.  In fact, the period of worst relative performance on this metric has been in the last few years, when we’ve managed no productivity growth at all.  No individual year is disastrous, but cumulatively it represents as astonishing slippage, that should be alarming – and once seemed so to our elites.

(This table compares New Zealand with the OECD leading bunch now.  I also did the comparison against the seven countries in the leading bunch in 1989 (Italy was one of those countries).  We also kept on losing ground against them, although –  logically –  a bit less so.)

Relative to what might have been our potential –  the global advanced country productivity frontiers, in a countries none of which have anything like ideal policies –  we’ve done poorly on the economic fronts that really count.  Sure, we have achieved a much higher degree of macro stability –  and that is no trivial achievement, although most countries like us (small advanced) have done something similar.    But we’ve fallen further behind on productivity, and rendered the housing and urban land market seriously dysfunctional.  Firms don’t find it more attractive to trade globally from here.   And there isn’t much sign our “leaders”  –  political or bureaucratic –  care much, are interested in finding the answers or acting to bring about better tomorrows.

Liam Dann writes

It has struck me that were I to time-travel back and share New Zealand’s current economic statistics with Mr Shaw, he would be gobsmacked by the nation’s success.

To be honest, reflecting on what I’ve written here, if I could time travel back to 1989 and share New Zealand’s economic situation now with my 1989 self –  a young policy manager and economist at the Reserve Bank – the young me would have been gobsmacked by the extent of the failure and (more so) by the apparent indifference to it, the refusal to grapple with what it would take to make things better.  (Although I would have been pleasantly surprised by the inflation track record –  I recall in the early 90s casually offering a bet to one bank chief economist that inflation wouldn’t average below 3 per cent for the following 15 years.)

What is really depressing – with a son doing Year 12 economics this year (a year that focuses on macro) – is the thought that in thirty years time he might look back astonished at how poorly New Zealand has continued to do relative to countries that were once its peers.

A last post on Makhlouf

One final post before the waters close over the issue.

When I wrote my post on Thursday afternoon about the SSC report on Gabs Makhlouf’s conduct in the “Budget leak” affair, Makhlouf himself had still made no comment.  By then, he had made no comment at all for four weeks, since the press release put out –  hand in hand with one from SSC – at 5am on Budget day.  Among other scrutiny he had avoided, he’d deliberately stayed away from a select committee hearing he would normally have attended, thus denying MPs any last chance to question his conduct.

But later on Thursday afternoon, Makhlouf issued a short statement  (4:41pm being about as close to close of business as he could possibly get).   In the circumstances, it is worth quoting in full.

“Mr Ombler’s investigation was conducted thoroughly and fairly. I have read the report carefully and encourage others to do so. I apologise that Budget information was not kept secure. The inquiry that I asked the SSC Commissioner to undertake will help us understand exactly how that happened and how to stop it happening again.

The report confirms I acted at all times in good faith and with political neutrality. It also confirms that I acted reasonably, other than in my descriptions of the incident. I am pleased that my honesty and integrity are not in question.

It has been my privilege to have had the opportunity to serve New Zealanders and I’m very proud of what my Treasury team has achieved over the last 8 years.”

He’d probably have been better off to have said nothing, and left us wondering. We already knew from the SSC report that Makhlouf disputed all the report’s adverse findings, and showed no sign of any contrition, or even of a sense that with the benefit of hindsight he should have done things differently.  But, perhaps, (we might have wondered) in his heart of hearts he really knew things hadn’t been handled well.

What does Makhlouf’s statement actually say?

The first paragraph is, in context, mostly an exercise in distraction. He apologised that the Budget information itself hasn’t been kept secure but (a) he had more or less taken institutional responsibility for that a month ago, and (b) that wasn’t the subject of the SSC inquity that had been released earlier on Thursday.  That report was about Makhlouf’s own conduct after the premature access to Budget information came to light.  It was a pretty damning report, especially when read in full (which I join him in encouraging people to do), and read knowing it was written by and for people who had worked closely with Makhlouf, including at the height of the “Budget leak” affair  (the timeline in the report has Peter Hughes in two meetings with Makhlouf, Ombler in one, and there was sufficient coordination and discussion that Treasury and SSC were issuing simultaneous press statements on 30 May).   It was only two weeks since Hughes had gushed about Makhlouf: if they had thought they could acquit him of everything, most likely that would happily have done so.

The final paragraph is irrelevant to the topic of interest on the day.

Which leaves simply that second paragraph.  A very senior public servant needs to draw attention to the fact that an inquiry judged that he was acting in good faith.  “Good faith” is an incredibly weak standard, and I don’t recall anyone –  through the whole affair –  suggesting that his actions were taken other than in good faith.   16 year olds probably mostly act in “good faith”, but it doesn’t mean they make good calls.

And what of political neutrality?  Sure, there is no suggestion that Makhlouf was some Labour hack, but who ever thought otherwise?  After all, he had been appointed and reappointed, with the consent of ministers, under a National government.  Had the tables been turned, and Labour MPs had done the same thing under a National government presumably Makhlouf would have handled things in exactly the same way.

That is, badly.

And then we get the central sentence of the short statement

It also confirms that I acted reasonably, other than in my descriptions of the incident.

As I pointed out in my earlier post, the “reasonableness” test used by Ombler was a very weak one –  nothing about whether the actions were what could reasonably be expected from a senior longserving Secretary to the Treasury –  and yet there were still three explicit findings against him, about “unreasonable” choices.   Read the report itself and Ombler could easily have identified several more (for example, Makhlouf’s refusal to accede to the urging of the head of the GCSB –  actual technical experts –  to correct the inappropriate use of the word “hack”, or his meeting with the Minister in which he was reading out the draft of the infamous press release (containing “hack”) but clearly didn’t understand enough to be able to answer the question of why GCSB wasn’t investigating).

But stick with the three adverse findings by Ombler.  Gabs attempts to diminish them, calling them just being about how he “described the incident”.

It is barely even accurate and is highly misleading. Here is the extract from the report

Mr Makhlouf did not act reasonably in relation to:

  • his use of the phrase “deliberate and systematically hacked” in his media statement issued at 8:02pm on Tuesday 28 May
  • his use of the bolt analogy in media interviews on the morning of Wednesday, 29 May
  • in his media statement on the morning of Thursday, 30 May, continuing to focus on the conduct of those searching the Treasury website rather than the Treasury failure to keep Budget material confidential.

The first involved a press release –  on what was already a very sensitive political issue –  the second involved a sustained round of interviews (he had chosen to do, at the request of the Minister) with four of New Zealand’s main media outlets, and the third  –  about a release on the morning of Budget day, amid seriously escalated political tensions –  goes directly not just to description but to mindset and perspective  (as Ombler noted, even during the inquiry interviews Makhlouf continued to hold to an interpretation of Budget confidentiality conventions that (a) no other serious observer holds, and (b) which Ombler politely takes apart).

Those alone were really serious failings, and Makhlouf accepts not one of those findings.

He might take comfort (as he does)

I am pleased that my honesty and integrity are not in question.

But that isn’t really the point is it? What is in question is his competence, his judgement, his ability to lead under fire, his willingness to listen to others, his ability to recognise mistakes and learn from them –  let alone his willingness to account to the people of New Zealand for his handling of this episode, played out in the full glare of the public spotlight.

The whole episode, right to the very end, reflects pretty poorly on Makhlouf and on SSC, including the fact that Makhlouf didn’t front up to the media at all, and that SSC didn’t insist (Makhlouf was still their employee on Thursday). No one could force him to hold views that he didn’t, but if he is going to refuse to accept any responsibility, or acknowledge any misjudgements, he should at least have had the decency to have fronted up to the media and faced, and answered, serious questioning.  As it is, he got off without even a formal reprimand – enabling him to get away with spin like this press statement –  and simply refused to explain his view.  Peter Hughes argued that Makhlouf’s reputation had taken a big hit anyway, and that that was really what mattered for those in these “big jobs”.    But it isn’t.   The old biblical maxim is relevant here

“For unto whomsoever much is given, of him shall be much required,”

People in those “big jobs” have money, power, influence, status, connections –  in Makhlouf’s case even citizenship –  bestowed on them.   We should expect much higher standards of responsibility and accountability for them.     Sure, there are then bigger costs (to those individuals) when they fail and are held to account, but that is how the system is supposed to work –  the quid pro quo for all those things society bestows on them.   It reminded me of Victoria academic Lisa Marriott’s work

Associate Professor Lisa Marriott, from Victoria Business School, has spent six years looking at the unequal treatment of people who commit welfare fraud compared with those who commit tax fraud, with her research showing that beneficiaries are treated more harshly at every turn.

I don’t suppose it is conscious choice, but it seems to happen anyway.  In Makhlouf’s case, the system worked to minimise the price he paid, the accountability, for some really severe misjudgements and a refusal to accept he’d done anything wrong. (Of course, the circumstances of the calendar helped too – had his term still had six months to wrong, it is hard to see how he could have survived in office, avoiding facing media or parliamentary questions, all while maintaining he had done nothing wrong.)

Pottering around doing chores this morning, I listened again to Makhlouf’s Radio NZ interview on 29 May, and the discussion with RNZ’s political editor immediately after the interview. It was fascinating to do so having to hand the SSC report and the detailed timeline it contains.  We now know a lot about what Makhlouf really knew (or should have), what advice he’d taken (and rejected) and so on…..and it was a reminder of just how much of a political firestorm this was (a point the SSC report largely ignores, even though Makhlouf was –  in good faith no doubt –  inflaming it): the RNZ political editor was talking of this as an episode that could cost with Bridges or Robertson their jobs (at this point, Makhlouf was the unquestioned good guy).  It would be tedious to run through many details, but suffice to say that although Makhouf had a fair idea of the nature of what had gone on (the report makes that clear) he made no effort in the interview to hose down talk of a serious cyber-attack and he explicitly rejected the idea that there had been any incompetence or sloppiness at the Treasury end (when the report makes clear that Treasury had a good idea on the previous afternoon that the clone site indexing issue was a probable explanation).  He fed the frenzy, played distraction……and was still playing distraction in his statement this Thursday, as he headed out the door, refusing to take any questions,

In my very first post on this business I wrote

Whatever your view of how Gabs came to be appointed and reappointed, or of his overall stewardship of the office of Secretary to the Treasury, it is a sad business in many ways.

And, of course, it has only gotten worse –  and sadder –  since then.  What a sad, rather tawdry, way to end an eight year term as the most senior public servant in New Zealand.

And yet it was (and remains) all of his own making, as –  instead of hosing things down, making amends, apologising –  he climbed onto the pyre as if determined to commit reputational-suttee.

Perhaps acknowledging nothing, conceding nothing, avoiding a formal reprimand, helps him in some short-term sense –  harder for the Irish to backtrack perhaps? – but he leaves a severely-dimished figure, and you have to suppose his future colleagues around the ECB Governing Council will always look rather askance at him, wondering about his judgement, pressure under fire and so on.

It is sad to see, especially when it is someone one has had a little to do with. As an outside observer and commentator I’ve been a bit ambivalent about Makhlouf.  Mostly critical of his stewardship to be sure, but there was a reasonable speech just a couple of weeks ago, and it is only a couple of months ago since, out of blue, one Saturday afternoon I had an umprompted text from him.  He must have been reading this blog.  He chose to remark on two “particularly good posts on [  ] and [  ] this week”.


Cavalier lawlessness

There does seem to be a growing sense among far too many public agencies that laws don’t really apply to them, only to other people.    This is particular so in respect of the Official Information Act.

A TVNZ journalist nicely illustrated this sort of contempt for the law in a tweet the other day

In similar vein, I had an experience a couple of months back in which the Police simply ignored the statutory deadline (“no later than 20 working days”).  Since they were the Police – ideally, examplars of upholding the law –  I lodged a complaint with the Ombudsman.  The Ombudsman actually dealt with the complaint reasonably promptly and I had a letter from them basically saying “we pointed this out to the Police, who accepted that they had missed the deadline”,  and “and now there is nothing more we can do”.  There are no sanctions in the Act, and not even the pretence of an apology from Police.

The Ombudsman also dealt reasonably promptly with a similar complaint about the Reserve Bank.    They had delayed and slow-walked (using the formal extension provisions in the OIA) the release of material supporting their position on the bank capital proposals –  material which, when finally released, turned out to be quite limited, and which had been given to other members of the public long before.     The extension looked to have been pure delaying tactics, deliberately obstructive, and so I complained to the Ombudsman.  And, much to my surprise, I had a letter earlier this week from a new Assistant Governor at the Bank

rb apology

That was a first.

Sadly, it doesn’t seem to be a marker of a genuine change of approach, just that they are a bit more bothered (than Police, say) of falling foul of the Ombudsman.  They tend to delay until the Ombudsman belatedly determines there is a problem, and then suddenly play nice.

In late March, the Minister of Finance announced the appointment of the members of the new Monetary Policy Committee. On 29 March (three months ago tomorrow) I lodged Official Information Act requests with the Minister of Finance and with the Reserve Bank Board (responsible for determining the names the Minister could accept or reject).   Given that, on paper at least, this was a powerful new body, it seemed not unreasonable to ask questions, including about any back channels through which (say) the Minister might have sought to get his preferred people onto the Board’s list (in most countries, the Minister of Finance can simply appoint directly the people conducting monetary policy).

Both the Minister and the Board initially extended my request.  I didn’t have much problem with that (plausibly there was quite a bit of paperwork to sift through etc) and the issue wasn’t overly urgent.   The Minister of Finance complied with the law and released a set of papers to me a few weeks ago.

Not so the Board (or the Bank handling the processing for them).  They initially extended my request to the same date as the Minister had done.  That didn’t seem unreasonable, even if the delay was quite long, and I’d envisaged there might need to be consultation between the two offices.  But deadline day arrived.  The Minister responded, and sent the requested material.  But the Reserve Bank Board (staff on their behalf) sent me an email saying they were further extending the deadline to 26 June (Wednesday this week)

“because of the consultations necessary to make a decision on the request such that a proper response to the request cannot be made within the original time period”

And so time passed. I fully expected a response on Wednesday –  it was, after all, almost three months they’d had by then.  But midnight came and went and there was nothing.

And so, having had that nice letter from the Bank’s Assistant Governor early in week, I sent her an email yesterday morning, reminding her that the extended deadline, set by the Bank itself, had passed.  I ended

I hope this further delay is pure oversight and that I will have a response very very shortly.

But no.  I didn’t actually get a reply to that email, but it clearly sparked action because much later in the day I had an email from someone down the line.

rb delay.png

Well, that’s nice isn’t it.  Not even a new deadline, just an indication.

So this is the third extension on a single request.  The first was made (well) within the orginal 20 days, the second was made on the final day of the extended period, and the third quasi-extension, well it came after the second deadline had already expired, and it looks as if it might not have made at all if I hadn’t approached the Assistant Governor.

But there is this thing called the law, under which agencies are required to operate. It is not voluntary, or just a nice idea, it is the law.   And here is what the Ombudsman’s office has to say about agencies extending request (the document is their guidance to government agencies on handling OIA requests).

Nothing in the OIA prevents multiple extensions being made, providing any extensions are made within the original 20 working day time period after receiving the request. For example, if an agency notifies the requester of a one week extension, and then later realises that a two week extension is actually necessary, a second extension may be notified as long as the original 20 working day time period has not yet passed.

You simply can’t extend a request again once the initial 20 day period has passed (in this case, that date would have been in late April).  That isn’t my reading of the Act, my opinion, it is the determination of the Ombudsman, who is responsible for enforcing the Official Information Act and holding agencies to account.  As it happens, the State Services Commission has also issued OIA guidance to agencies, and their text on extensions repeats the Ombudsman’s stance, without question or challenge.

Perhaps the Reserve Bank’s lawyers have a different interpretation (untested in the courts, the only way the Ombudsman’s view could be overturned). Or perhaps the Bank just doesn’t care.  Laws are for other people.

The Ombudsman even offers some suggestions for agencies (I guess unexpected obstacles do come up from time to time).  It is commonsense really, the sort of thing any decent public-spirited person would want to do anyway (but not apparently the Bank).

If it looks like it will not be possible to meet either the original or an extended maximum time limit, the agency should consider contacting the requester to let them know the current state of play and reasons for the delay. Requesters will appreciate being kept informed, and may be more understanding if the agency ends up in breach of the timeframe requirements.

Agencies should be aware, however, that a failure to comply with a time limit may be the subject of a complaint to the Ombudsman.

And so, in the spirit of sweating the small stuff –  how are public agencies to be held to account if we don’t make a fuss and use the avenues that are open to us? – but with a somewhat heavy heart (couldn’t they just obey the law instead?), I will be lodging another complaint with the Ombudsman later this morning.

The request was made to the Board of the Reserve Bank.  They don’t work for the Governor or the staff, rather the staff provides secretarial and adminstrative support to the Board.  Neil Quigley, vice-chancellor of Waikato University, is chair of the Board, and he and the Governor between them need to take responsibility for this lawless obstructionism.  “Culture and conduct” is one of the Bank’s trendy mantras.  It really needs to start close to home.

UPDATE: The Governor recently told an acquaintance of mine that he doesn’t read this blog, but clearly someone at the Bank does.  I finished the post, went off to clean the house, and came back to find this.

RB OIA

Again, that’s nice, and slightly better than nothing.  But, the law…….  As the law is written, and applied by the Ombudsman, the response was finally due on 11 June.

The law.


The SSC on Makhlouf

The SSC report (undertaken by Peter Hughes’s deputy) on Gabs Makhlouf’s conduct in the “Budget leak” affair late last month was finally released this morning, along with a statement from the State Services Commissioner himself, and a press conference (for which we appear to have to rely on media reports).  It was a very mixed bag but (remarkably) manages to show Gabs Makhlouf’s conduct and judgement in an even worse –  materially worse –  light than most would have expected, even having followed the media stories at the time and since.  Had it not been his last day in office anyway, his position would surely have been utterly untenable.

As it is, Peter Hughes appears to find himself betwixt and between.  He is clearly keen to distance himself from Makhlouf.  (As one small example, I was bemused that he had his comms person contact me last night to correct a mistake in my post yesterday, expressed thus: “in the current political climate, Peter feels it important to make clear that he did not reappoint Makhlouf” (previous Commissioner Iain Rennie had): not exactly standing behind your employee.)   And many of the words in his official statement, and (particularly) those reported from the press conference sound good, and pretty hardhitting.  From the official statement

“I have concluded that Mr Makhlouf failed to take personal responsibility for the Treasury security failure and his subsequent handling of the situation fell well short of my expectations.  Mr Makhlouf is accountable for that and I’m calling it out.”

and

At a press conference on the report, Hughes said his expectation of what chief executives should do when things go wrong was “very clear” and the chief executives knew it.

“They need to own it, fix it and learn from it. And I expect people to stand up and be accountable, and I am disappointed that Mr Makhlouf did not do that on this occasion,” Hughes said.

“The right thing to do here was to take personal responsibility for the failure, irrespective of the actions of others and to do so publicly. He did not do that.”

There were no hugs for Makhlouf (see Iain Rennie/Roger Sutton).  And yet that was it.  Hughes is reported as saying that were Makhlouf not leaving anyway he’d have looked at some formal reprimand (easy to say now, all hypothetical), and yet to do so now would be “cynical and meaningless”.  I don’t see anything cynical about it at all, and the meaning would be to show citizens and voters that there is at least some degree of formal accountability for people at the top.    Hughes went on to say that in these ‘big jobs” reputation is everything, and Gabs’s will have taken a big hit.  That is no doubt true, and as report makes clear it was entirely self-inflicted.  But what employers and governments can do is to make formally clear –  endorse the reputational hit – that conduct of this sort is utterly unacceptable, and judgement this poor would not be tolerated in very senior public servants.

And it got worse

“We can’t run the public service on the basis that you’re only as good as your last mistake. We can’t do that – that’s The Apprentice, it’s not Fair Go New Zealand. I have to look at this in the round, I have to look at this in terms of his eight years of service, and that’s what I’ve done…

What message does that send?  That really severe misjudgement by one of the most senior public servants in the end doesn’t matter that much, cos’ he’s a good bloke?  It is fine to talk in terms of learning from mistakes –  and just possibly, if this were a new Secretary to the Treasury one week into the job it might be applicable here –  but this was someone who had held top office for eight years and yet, when the heat really came on, performed very badly.  And, worse, as the report makes clear still today does not accept that he did anything wrong.  No “learnings” in that case.

And, of course, this was the same Peter Hughes who just two weeks ago at the gala farewell for Makhlouf, hosted by the Minister of Finance at the Beehive said

“Thank you from the people of New Zealand. Our country is a better place for your work.”

He said Makhlouf had brought “strong leadership and a great deal of personal integrity” to Treasury.

He had been “authentic and straight up” and had been calm and unflappable.

“I will certainly miss your calm authority,” Hughes said.

As I noted in a post at the time

In no conceivable universe (except perhaps some parallel one inhabited by SSC) could Makhlouf during that Budget episode be said to have displayed “calm and unflappable” leadership.  Had he done so, there’d have been no inquiry.

And the inquiry report demonstrates just how far from calm and unflappable Makhlouf’s conduct appears to have been, and how little “strong leadership” and “personal integrity” has been on display.    That gush, when Hughes must already have known much of what would be in the report –  a lot of it was in the media, some involved meetings he himself had attended –  seems both borderline dishonest, and if not then casting some doubt on the judgement of the State Services Commissioner himself.

It is perhaps worth noting too that the Minister of Finance has been playing the whole thing down even more than the Commissioner.  His statement makes no reference at all to the adverse findings in the Deputy Commissioner’s report (even though in my reading of the report, the Minister emerges not too badly –  recognising that the report dealt only with his, and his staff’s, interaction with officials).

But what of the Deputy State Service Commissioner’s report itself.   There was a great deal of interesting material, which puts Makhlouf in a very poor light, even though the standard Mr Ombler was asked to use was a fairly weak one, interpreted in ways that made it weaker still.   The standards he was asked to use were whether Makhlouf acted in “good faith”, “reasonably”, and “maintaining political neutrality”.   I didn’t have too much difficulty with how he interpreted good faith and the political neutrality (and as I’ve said before I thought most likely Gabs acted in good faith, and was not knowingly partisan), but here “reasonable” is defined as an action/decision that was “one that was open to be reached and is within the limits of reason”.   Either in how his mandate was written or how he interpreted it, there is no sense of a standard being whether actions/decisions were of a standard that might be reasonably expected from the most senior public servant in the land, who had held that high office for eight years.

And yet even on that rather generous standard, Mr Ombler still found that Makhlouf failed to act reasonably in three important respects.

Mr Makhlouf did not act reasonably in relation to:

  • his use of the phrase “deliberate and systematically hacked” in his media statement issued at 8:02pm on Tuesday 28 May
  • his use of the bolt analogy in media interviews on the morning of Wednesday, 29 May
  • in his media statement on the morning of Thursday, 30 May, continuing to focus on the conduct of those searching the Treasury website rather than the Treasury failure to keep Budget material confidential.

Very little of what Makhlouf did during this period, after the first few hours, seems to meet a standard a fair-minded observer should expect from such a senior public servant.

Among the puzzles is just who Makhlouf was taking counsel from, if anyone, during this period.  Paragraph 10 of the report list the people Ombler talked to in the course of his investigation, but although various Treasury officials are listed, only one of Makhlouf’s second tier is mentioned (a new acting Chief Operating Officer on secondment from elsewhere in the public sector).  But none of the rest of his second tier –  the people he’d been working with for years, and who had a better sense of The Treasury, the Budget –  is mentioned. It is most unlikely –  in Budget week –  they were all away.  Did he really not talk at all to Struan Little, the Deputy Secretary responsible for the Budget, who takes over as Acting Secretary tomorrow.   Did people like him not take Gabs aside and suggest he was losing perspective?  If not –  based on all else in the report – that reflects poorly too.  We know that when Makhlouf decided –  late on the Tuesday night –  to do a round of media interviews the next morning, he explicitly rejected his Communications Manager’s offer to help him prepare lines/answers  (he went on to do those interviews with no outside prep, and not that much sleep apparently either).

What also becomes clear is that, although Treasury staff initially thought there had been a leak, by pretty early on (1pm on the Tuesday) they were converging towards recognising that the material may well have been taken from searches of their own website (all that clone site indexing stuff), and by 3pm that day they had turned off the function that was creating the snippets (of the sort that had been released earlier that morning).     They told Makhlouf this by 5pm, before Police, GCSB or anyone else was much involved (although one gap in the report is there is no discussion of contact between Treasury staff and the Minister’s office during the afternoon  – it is just impossible to believe there was none).

What is more, the report records that Makhlouf told the Minister of Finance (7;15pm on the Tuesday) that it was ‘very likely” that the information released had been accessed through deliberate searches on the website (all that clone indexing stuff again was explicitly mentioned).  Sure, they don’t seem to known that with certainty, but a calm chief executive would surely have taken it as the most likely explanation and tailored his actions and comments accordingly (while not closing down other lines of inquiry).

The timeline in the report has a lot of detail on the back and forth among Treasury, GCSB, and Police over this period.   GCSB seem to have made clear that it wasn’t a matter for them, and  –  since Treasury already knew the likely nature of the way the information had got out  –  to the extent there was anything for Police, it was already clear that it probably wasn’t about what had gone on, but on the narrower question of whether that activity had been illegal.

But none of that stopped Makhlouf.    At 8.02pm he had gone out with his, now infamous, “deliberate and systematic hacking” statement, and (by implication) associating GCSB with his statements/actions.  He had sufficiently little understanding himself that he told the Minister he didn’t know why GCSB weren’t investigating, and yet went on to tell the Minister he thought he (Makhouf) had to make a statement.  He read out the draft statement to the Minister –  hadn’t even given him a draft in advance to reflect on –  and at the same time said he wasn’t going to do media interviews. The report notes that the Minister’s staff who were in the meeting gained the impression that what had gone on was a far more serious computer system intrusion than what (Treasury staff already knew was most likely) the case.  It looks a lot like a chief executive, stung by the breaches on his watch, probably rather emotional, not turning to wise counsellors, and not ensuring that he had himself fully understood what staff were telling him.   Any statement should have been toning down the issue, accepting (probable) responsibility, not amping it up and (a key point in the SSC report) attempting to shift responsibility.

It got worse.  Treasury hadn’t shown GCSB their draft statement (with the word “hack”) and when Andrew Hampton saw it he texted Makhlouf and said Treasury needed to correct the statement (Hampton’s comms adviser then lodged a complaint with Treasury at not being shown the draft statement –  as would be conventional when one government department refers to another in a statement).  Makhlouf and Hampton talked and Makhlouf simply rejected the advice (even though GCSB is a key adviser on cybersecurity threats etc).

Earlier in the evening, Makhlouf hadn’t intended to do media interviews.  That was about his last good call in the whole affair.  But late in the evening, the Minister’s press secretary rang to ask him to do so, and Makhlouf agreed.  He seems to have taken no advice, including on possible responses, and instead got up at 4:30 on the Wednesday morning to prepare himself, where he came up with the infamous and highly misleading bolt analogy.

According to the report, by about 1:40pm on the Wednesday Treasury not only had a high degree of confidence that the “leaks” had simply involved systematic searches, but they had been told Police weren’t taking the matter any further.   Makhlouf told the Minister this at about 5:30 on the Wednesday.  He said he would make a media statement (and a parallel one from SSC) but thought it could wait until Friday, after the Budget was out of the way.  It was just another in a series of extraordinary lapses of judgement.    Wisely, the Minister’s office got back to Makhlouf shortly thereafter to indicate the statement should go out before the Budget.  (Presumably it was about this time the National Party had indicated they would hold a briefing in the morning to reveal how they got the information.   The report is endlessly cute on this point –  despite the fact that Treasury had a near-certain view of how the information had been found, we are expected to believe that they had no strong sense, even quite late in the piece, that National staffers had done the searching).

A reasonable person might have supposed that, having amped the issue up in his press release on Tuesday night, raised the stakes further in the media interviews on Wednesday, and (as background noise) having had senior ministers alleging all sort of impropriety, that a statement would be rushed out just as soon as it could possibly be got together (perhaps even a press conference with Makhlouf and his head of IT).  But no.  And Ombler concludes that this was all quite reasonable because “it takes time to draft an appropriate media statment and to appropriately consult other agencies”.    Except that the decision to do a press statement had been done by 6pm, the draft was sent off to various agencies –  including SSC (who thus saw the draft of the statement they now rightly criticise Makhlouf for) –  at about 8pm, the Minister’s office had it by 8.53pm, and the whole thing was finalised and sent out to various officials under embargo just after 9:30,    There was no reason why it could not have gone public then, not released into the dead of dawn, at 5am the following day.

Except, of course, that the statement was not well done.   As the report concludes, Makhlouf ended up focusing more on the people who had found the information than on the failures of The Treasury itself, and played up an extraordinary interpretation of Budget confidentiality conventions that surely no one else would have regarded as reasonable –  and which Ombler decisively picks apart.  Such conventions bind ministers and public servants, not people who find information through weaknesses in your website.  According to the report, Makhlouf even now rejects this interpretation.

The report suggests that Treasury staff themselves seem to have got caught up in a similar defensive mindset. In a way that is understandable: the “leak” would have been deeply embarrassing, but it was Makhlouf’s job to lead the organisation above the embarrassment and to do the right thing.  He simply didn’t do that, and no one else –  in his department or elsewhere in the public sector (the very top tier of public servants) – was willing or able to stop him.  Where, for example, was his employer –  Peter Hughes – after the first statement, after the interviews, or when he got the draft of Thursday’s statement (and the timeline records he was in two meetings with Makhlouf on the Wednesday afternoon, but the report tells us nothing about what he said or did with those opportunities).

Bottom line seems to be that Makhlouf does not regard himself as having done anything wrong.  Even with the benefit of hindsight, the report contains no sense of Makhlouf looking back with regret or wishing some things had been done differently (and he had a draft of the report, so had the opportunity to inject such perspectives if Ombler had missed them).  Consistent with that there was no contrition or apology at the time, and not a word from Makhlouf since.  He deliberately avoided parliamentary scrutiny at FEC the other day, and there has been not a word from him today.   And at the close of business today he is off, no longer accountable to anyone in New Zealand at all.  It is a shockingly poor standard of conduct on display.  He could not have survived in office –  with these findings and no contrition –  had it not been his final day.  It must be a tough day for Treasury staff, many of whom will probably be going out of their way to stay clear of Makhlouf (even those who otherwise have good impressions of him).

We –  citizens –  deserve much better.  We deserve more answers from SSC themselves.  And, one would have to say, the people of Ireland –  and of Europe –  deserve much better: if this is how their new Governor (and ECB Governing Board member) reacts under pressure when something goes wrong on his watch, it is a real worry as economic and financial pressures and tensions build.    And it is a reminder of how utterly crucial it is for anyone near the top to have at least one person they trust who is willing to tell them to their face when the top person has stuffed up, lost perspective, got it wrong.  If Gabs had such a person, they were missing in action in Budget week.

Thoughts prompted by the OCR review

When I read yesterday’s OCR review release from the Reserve Bank, my first thought was actually about process.   This was the first interim –  ie between full Monetary Policy Statements – OCR review since the new Monetary Policy Committee took over responsibility.

The actual statement from the committee was about 175 words long.   It was accompanied by the summary record of the meeting (“the minutes”) that was about 530 words long.     That looks anomalous.   When there is a full MPS (with projections), the minutes are – in normal times –  not much more than a modest supplement.   But when there are no numbers and the press release itself is so short, the minutes are always likely to be the main event.    Given the way the Minister of Finance has chosen to set up the new system –  “minutes” released simultaneous with the policy decision (not done in plenty of other countries), and minutes not generally conveying individual views –  I wonder what the point is of having both statements on the occasion of interim OCR reviews.    There is nothing in the press release that couldn’t quite easily have been included in the minutes (almost all of it is there anyway) and having two documents just opens up risks of conflicting wording or differences of emphasis (in this case, the minutes are clearer on the likelihood of another cut than the statement is), for no obvious benefit.    It isn’t a big issue, but if I were in their shoes I’d be taking another look in the light of experience.    As it is, when one document has three times as many words as the other, the focus of attention is likely to fall on the longer fuller document.

Having said that, (with a sample of only two cases admittedly) experience is already confirming that the summary record of the meeting is really just a long-form version of the policy statement (whether the OCR review one, or the first page of the MPS).    I get that, for largely inexplicable (and unexplained) reasons, the Minister of Finance was keen on encouraging consensus decisions –  not an approach we take, for example, in the appellate courts, when individual judges are responsible for their own views and free to express them –  but the minutes we’ve so far really add nothing.   Take the possibility of an OCR cut yesterday.  This what they said, all of it.

The Committee discussed the merits of lowering the OCR at this meeting. However, the Committee reached a consensus to hold the OCR at 1.5 percent. They noted a lower OCR may be needed over time.

Wouldn’t a useful summary record have given some indication of the arguments members (perhaps only some) found persuasive in favour of a cut and the considerations that led them (by consensus) to conclude that it wasn’t an appropriate decision right now.  There is no sense of richness to the discussion, no insight into the thought processes or arguments or models being used, just nothing.       And this is early days, when presumably the Committee wants to put the best foot forward, to suggest real change, real gains in transparency.    It was predictable that the new-look committee would probably become little more than a slightly different front window for the Bank’s longstanding preference to tell us only what they think we need to know, only when they want to tell us.  It could have been different, even under the severe limitations of this legislation, but it would have been an uphill battle even with the right people  –  and there is now documentary evidence that several of the likely best people were simply excluded from consideration from the start. MPC members are free to speak publicly, but thus far none has.   It is a shame, but it is what I pointed out in my submission on the legislation last year, that the monetary policy reforms always appeared more cosmetic than real.

As for the actual OCR decision, I think it was the wrong decision (although I wouldn’t make too much of the point).  Data have weakened here and abroad, inflation is –  and has persistently been – below target, the exchange rate is holding up, and there is little real prospect of a sustained reacceleration of growth or of inflation pressures.  Oh, and market measures of medium-term inflation expectations are around 1 per cent, not 2 per cent.   In that climate, being a little pro-active and cutting the OCR now looks to have been the better choice.   It isn’t clear what the risks to moving would have been.   It is only six weeks until the next MPS, but (a) the MPC won’t have a lot more domestic information between now and then (eg the labour market data come out only 27 hours before the next release, and won’t be properly incorporated –  or in the projections at all) and (b) the way the global situation is going one can’t rule out the possibility that another cut could have been warranted by then.   Then again, markets strongly anticipate central banks.

Perhaps the saddest bit of the press release was this plaintive, orphaned, line

Inflation is expected to rise to the 2 percent mid-point of our target range,

The Bank has been saying this for years. December 2009 was the last time annual core inflation (on the Bank’s sectoral factor model was as high as 2 per cent).  There is no support offered for their view, either in the press statement or in the minutes, and no evidence even of any discussion to risks around the story.  I guess anything is possible, but it simply doesn’t seem the most likely story any longer.   The Bank’s former chief economist used to argue that they had to say this (that inflation was heading back to 2 per cent) because if they didn’t, it meant they should have been changing the OCR.  Well, quite.  But in these circumstances, the line should just have been quietly dropped –  or some more analysis/argumentation provided to support their beliefs.

Earlier in the week, the NZIER released their Shadow Board exercise, in which a group of economists and business people offer their advice, and their range of views, on where the OCR should be set (conditioned on the target the Bank is given).  I know various readers are dismissive of the exercise –  and it does appear to be limping on towards eventual termination, rather than helping shape the debate –  but I’ve always had a geeky interest in exercises like this, even while noting that the Shadow Board tends to adjust into line with the Reserve Bank, rather than providing much collective leadership or independence of perspective.  This was in evidence in the NZIER press release this week

NZIER’s Monetary Policy Shadow Board has adjusted their recommendation in the wake of the Reserve Bank’s OCR cut in May.

It is strange that experts would adjust their view of what the OCR should be just because the Reserve Bank –  with no monopoly on knowledge and huge margins for error –  changed its view.   But here were the individual views of the panellists.

shadow board 19

I’ve always been puzzled too by how anyone could be 100 per cent confident of their view of where the OCR should be.   When I was on the Reserve Bank’s OCR Advisory Group (a forerunner to the MPC), we introduced a survey of this sort, where each member’s advice to the Governor had to include a probability distribution (summing to 100 per cent) on what the OCR should be (eg 50% 1.5 per cent, 25% 1.25 per cent, 25% 1 per cent).  Being a bit stubborn, and reminded of the breadth of the historic confidence intervals in OCR forecasts, I always tried to discipline myself to spread my probabilities over perhaps six alternative OCR settings, with not too high a probability on the OCR I actually recommended.  Apart from anything else, it was a helpful prompt to think about what would invalidate my central view.   Most of these respondents don’t seem to do anything similar.  For what it is worth, my current distribution might look something like this

0.5 or less 5
0.75 10
1 20
1.25 35
1.5 17.5
1.75 7.5
2 or more 5

The most interesting view in the chart (setting aside how tightly bunched his views were) is that of former Reserve Bank chief economist Arthur Grimes, who indicated a 50 per cent probability that the OCR now should still be 1.75 per cent. In his comments he notes

Conditions imply no need to change the OCR right now, but that has to be balanced against the unnecessary (and unwise) cut to the OCR at the last decision. Hence it is a 50:50 call as to whether the cut should be restored or whether to leave the OCR as is.

It is an interesting stance, more “hawkish” (for example) than the (typically) most hawkish of the local banks (BNZ), and it is a shame no media seem to have asked Arthur to elaborate on his view.  He must hold it strongly –  the words are much more forceful than just the numbers would have been –  and it would be interesting to read his fuller reasoning.  After all, although my central view appears to be substantially different to his, the margins of error/uncertainty in this game are quite large enough that he could prove to be correct (my own probabilities – above –  overlap with his).     Perhaps it is just that Arthur is downplaying the target midpoint, even though it is highlighted in the target given to the committee, and in that case it is just a personal policy preference.  But if it is a genuine difference of model, of making sense of current or prospective economic or inflation developments, it would be interesting to see his reasoning.

But for me, the downside risks, and the asymmetric nature of the consequences of being wrong –  surprising high inflation means getting into the top half of the target range for the only time in more than a decade, while the approaching limits of conventional monetary policy mean that any further slippage in inflation expectations could really aggravate the next significant downturn, arguing for erring –  if it all –  on the side of a lower OCR.