Previewing PREFU

No doubt there will be a great deal of coverage of fiscal issues later in the day, once the PREFU numbers are out.

There will, no doubt, be lots of talk of possible operating surpluses years down the track. Little or no weight should be put on those numbers, which have in any case been gamed by the Labour Party in government (they tell Treasury what their policies – future operating allowances etc – currently are and Treasury simply represents that in their fiscal forecasts), and which represent aspiration rather than specific commitments and adjustments which would turn those stated aspirations into reality.

But even though both sides will no doubt utter pieties about getting back to surplus some time, both have been operating this year in ways inconsistent with such pieties. It seems safer to judge parties by their specifics (actions and immediate commitments) than by rhetoric about the medium term.

Labour is not necessarily making big specific campaign commitments now. That is because they already got their bids in in this year’s Budget, which was significantly expansionary (and not just because of one-off weather expenses).

Here was how the IMF saw things fiscal (based on actual policy, legislated in this year’s Budget) in their annual review of New Zealand published a few weeks ago.
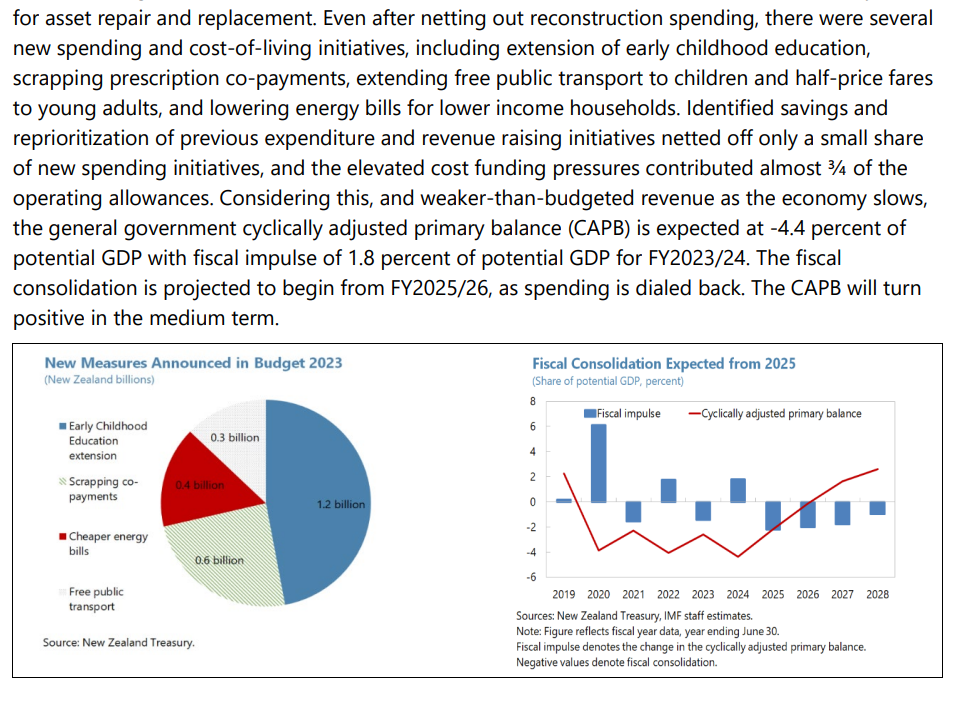
Last year’s Budget had been expansionary too.

The IMF followed this analysis, in which they highlighted just how large the cyclically-adjusted primary deficit is, with the observation that while some post-cyclone stuff needed to be done the New Zealand authorities should aim for a “frontloaded fiscal consolidation”. In other words, cutting the underlying now……not several years down the track.

The IMF’s fiscal impulse estimate was very similar to The Treasury’s, as reported in the Budget documents in May

It wasn’t good fiscal policy, and it was operating directly in conflict with monetary policy, increasing the amount of interest rate adjustment the Reserve Bank had to do to get inflation down again.

We haven’t seen anything like a fiscal plan from Labour yet, but there have been individual policy promises. On the tax side, Labour wins the “mess up the tax system” award by paying for one policy (GST off fresh fruit and vegetables) which is abominated by pretty much all experts and will mess up a good tax (doing any good very inefficiently), by adopting another highly distortionary and inefficient tax (removing tax depreciation from non-residential buildings). But there don’t seem to have been any particular questions raised about the costings (and while there have been about the dental promises, they are years down the track).

So Labour’s approach to fiscal policy this year has been quite expansionary, worsening the fiscal situation and complicating monetary policy and the fight against inflation. Using the IMF’s numbers – but before whatever deterioration this afternoon’s numbers show – I ran this chart last week
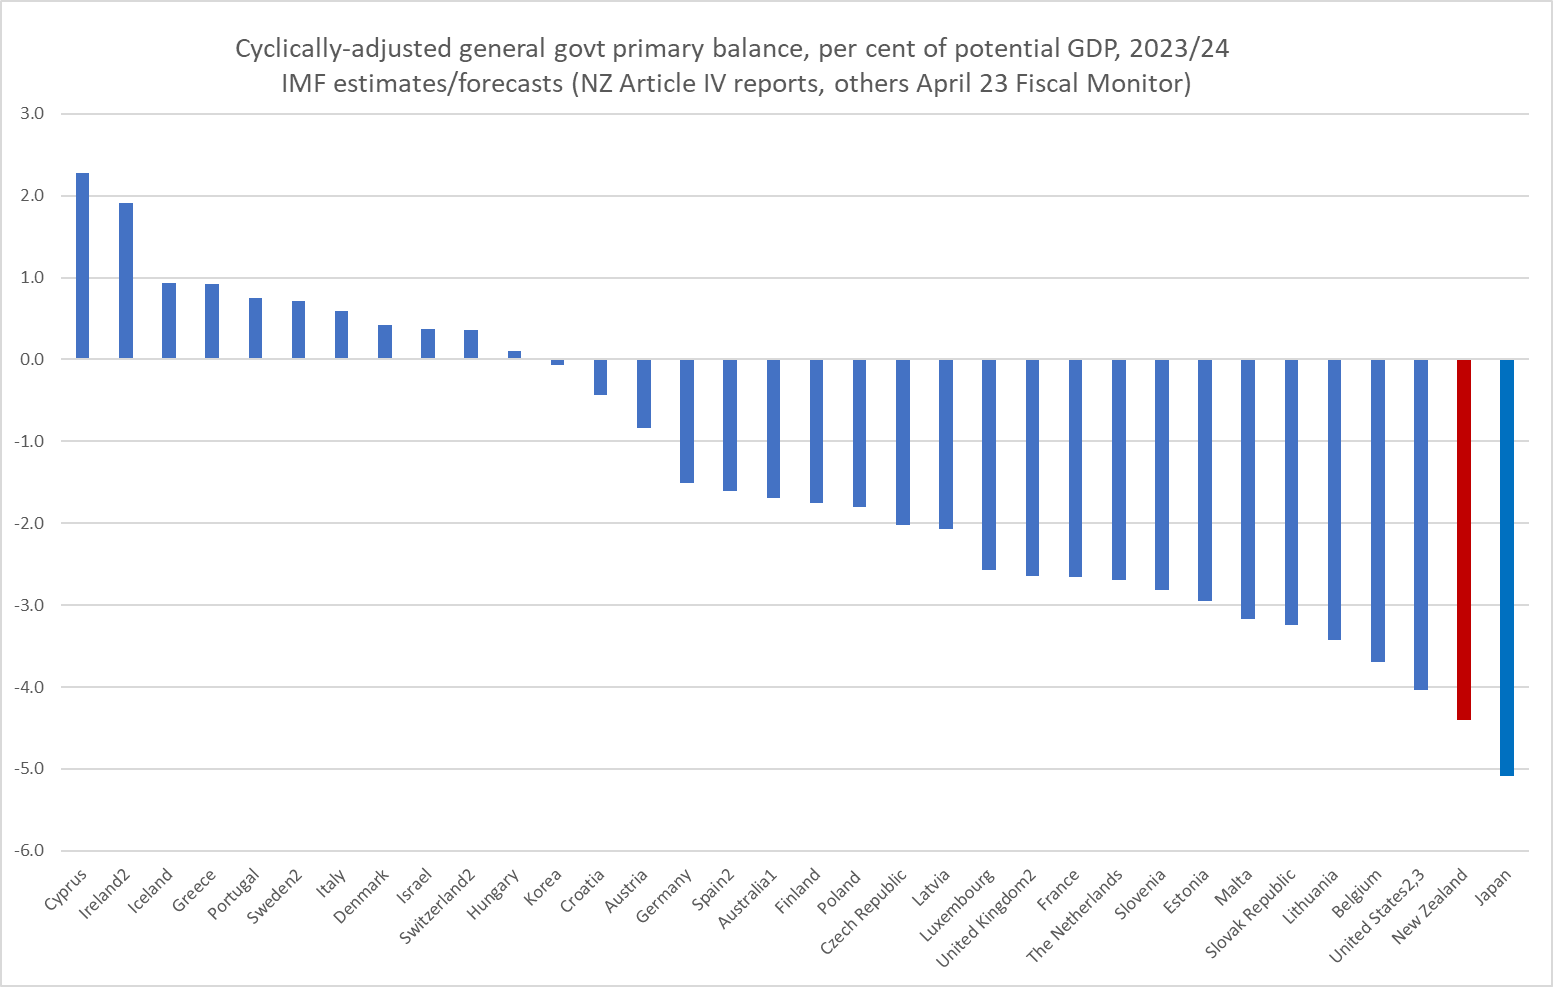
We have, currently, one of the largest fiscal deficits of any advanced countries.

What of the main Opposition party, National? Opposition parties are at a slightly disadvantage in electoral auctions because governing parties, being the government of the day, get to legislate their excess first.

But National seems quite content to go along with that as the starting point. A couple of weeks ago they came out with their tax and spending plan (I wrote about it here). It claimed to be a fully-funded package that would not worsen the fiscal situation beyond what Labour had already delivered. Which would be bad enough: Labour runs successive expansionary budgets, dramatically worsening our underlying fiscal position, and National goes….well, that’s fine, we’ll just reorganise some tax and spending settings and not feel obliged to do anything about the deficit itself. They claimed at the time that they’d have a separate “fiscal plan” coming after the PREFU, but Luxon was quoted yesterday as saying that whatever was in the PREFU wouldn’t change anything about the (flagship) tax and spending plan released a couple of weeks ago. That isn’t really surprising (I pointed to this likelihood in my earlier post) and I guess now the question will be whether they bother announcing a “fiscal plan” at all. If they do, it seems unlikely to have any more substance than Labour’s pieties (an operating surplus by the end of the period, but no clue as to how concretely that might be delivered). Neither party in campaign mode shows any sign of actually cutting anything….. more a case of finding more relatively inexpensive baubles to throw at voters.

National also wanted us to believe that their fully-funded package would not add to demand and inflation pressures. As I noted in my initial post, that didn’t seem very likely, as the package delivered lots of people with high marginal propensities to consume, while being funded in substantial part from overseas house buyers (not, by construction, paying tax from New Zealand produced incomes).

But the actual situation is worse than that. No expert, no one who has looked carefully at the data or other relevant experiences, thinks that the proposed foreign buyers’ tax will raise anything like the $735m National expects year in year out (if there is pent-up demand perhaps it would get quite a bit closer in the first year (only), but not beyond that). The gap is quite large in the context of their package.

And so we go into the PREFU this afternoon, and whatever spin the two parties’ spokespeople are going to put on fiscal prospects with (a) a governing party that has already run up really big deficits, adding more fiscal expansion in their election year budget, with no specifics on how they might close those deficits (including in the face of ongoing cost pressures), and b) a main Opposition party which was seemed content to go along with Labour’s expansionary stance (just rearranging some of the tax and spending pieces), but in fact seems to have ended up with an even more expansionary stance themselves. (It doesn’t do to overstate the differences: the big picture is really large fiscal deficits and rising debt, which doesn’t seem to greatly bother either party, while the probable shortfalls in National’s package around the foreign buyer tax amount to an additional 0.1 per cent of GDP on the deficit each year. The additional credibility damage is probably greater than the fiscal damage.)

Finally, the debt. We have had 20 years in which New Zealand governments’ ran net debt as a share of GDP materially lower than the median OECD country. That gap is closing fast (this chart is using data well before the recent deterioration in New Zealand revenue flows).

And it isn’t a Covid thing. The point made by the chart is that the median country saw a brief Covid blip, but now has net debt as a share of GDP a bit lower than in 2019. In New Zealand, by contrast, by the big Covid spending well behind us, both parties seem okay with debt still rising rapidly (they may say otherwise, but judge them not by the handwaving medium-term rhetoric but by their specific and immediate actions and commitments.

“He immediately repaid the money spent…putting the matter right at the first opportunity”

Or not

The words in the title to this post were uttered by (outgoing) Public Service Commissioner Peter Hughes in a press release issued a month ago today.

You might recall the story:

  • the outgoing head of the Ministry of Pacific People’s (MPP) Mr Leauanae was given a lavish farewell (costing taxpayers $40000) before he moved down the road to run another second-tier government department (the Ministry of Culture and Heritage (MCH)), where he was given another fairly OTT official welcome,
  • instead of being given a card and a couple of book vouchers (say), Mr Leauanae was given lavish personal gifts, $7500 of which was paid for by taxpayers (via MPP), this at a function where the then Minister of Pacific Peoples was an attendee (and apparently a speaker)
  • for his welcome at MCH, attended by several Cabinet minister, his former ministry (MPP) spent $4100 on travel costs for Mr Leauanae’s family and personal guests.

I wrote a couple of posts about it here and here, and then lodged some OIA requests.

The PSC could be read as a fairly stern rebuke in some ways. It included lines that MPP’s expenditure had not been “moderate and conservative”, and had not complied with either MPP’s own policies or PSC’s “model standards” for chief executives. He added that “taken together, the Ministry of Pacific People’s expenditure on the farewell and the welcome were an inappropriate use of public money”.

And yet the principal culprit, Mr Leauanae, seemed to pay no price at all (nor is there anything suggesting his underlings at MPP did). He was the culprit in two senses: first, he was the chief executive of MPP and so personally responsible for its policies, key people, institutional culture, and so on. It happened on his watch in an agency which, while bloated, is still small in absolute terms (about 130 staff), and, second, he knowingly received the gifts and the travel.

But Hughes is keen to emphasise that it was all paid back and to suggest it was done pronto. These are the quotes from his press statement:

“On being made aware of the money spent on gifts he immediately repaid the $7,500 and returned all the gifts.”

“He has since reimbursed MPP $4,115.38 for travel costs associated with all family members and guests.”

“When he became aware of the matter, he immediately repaid the money spent on gifts in full and returned all cultural gifts to MPP. He also repaid the money spent on travel for his family and a guest who did not have a formal role in the welcome. That is appropriate and I thank Mr Leauanae for putting the matter right at the first opportunity.”

If you read those quotes carefully you will see an implied difference in timing as to when the two amounts were returned, but the press release ends on that note “I thank Mr Leauanae for putting the matter right at the first opportunity”.

But he didn’t. And the evidence, from PSC’s OIA response, leaves no room for doubt on the matter.

The farewell from MPP was on 14 October last year and the welcome to MCH was the following Monday, 17 October.

So let’s suppose that not knowing anything about taxpayer-funded expensive gifts in advance, Leauanae is embarrassed to receive them on the 14th. Not wanting to embarrass people on the spot, he reluctantly takes them, but vows to quietly return then straight away. Perhaps his family members never told him they’d got free tickets to welcome (doesn’t seem very likely, but just grant the possibility for the moment) and he only finds out on the Monday morning of the welcome, and again resolves to put things right straight away.

When then would you consider the latest that reimbursement could have been made and the Peter Hughes description (“put the matter right at the first opportunity”) would still have been valid. For me, I can’t see how anything later than the close of business on the Monday (14 October) could be described that way. Perhaps you are more generous than I am and allow a few more days leeway.

What actually happened was nothing of the sort. Instead Mr Leauanae took the expensive gifts, took the travel for family and friends, and got on with his new, somewhat bigger, government chief executive role.

And PSC (and ministers) did nothing. As the PSC report tells it, it wasn’t until 19 December (more than two months later) that PSC decided to have a look at things, and then only because there had been an OIA request to MPP about the expense of the farewell, and MPP have copied their response to the OIA to PSC. This in itself is all quite extraordinary, and suggestive of a PSC that simply wasn’t doing a decent job itself. We are told that Hughes himself was not at the farewell but some of his staff were. We know the Minister of Pacific Peoples was, and material MPP has provided suggest one other public sector CE probably spoke at the event (it would be quite normal for a bunch of senior public servants to be at such a CE farewell, even if he was only moving down the road). And either no one expressed any concern about (a) the lavish event, or (b) the gifts or PSC knew and didn’t care, at least until the issue looked as though it might go public via the OIA.

Christmas intervened and the PSC investigation didn’t get started until mid-January when they wrote to the acting CE of MPP.

To drag the story out, by this point three months on from the events, Mr Leauanae had taken no steps at all to return gifts or reimburse the money. The final Hughes report notes, of the travel expenditure, “He [Leauanae] advised it was always his intention to pay for his family and personal guest’s travel costs”, but not only had he not done so, he seemed to have later untroubled by any qualms of conscience. He’d done nothing to reimburse the cost of that travel.

The inquiry into the MPP farewell took PSC a while, but eventually the investigation led to Mr Leauanae returning the gifts and repaid the amount of taxpayers’ money that had been spent on them ($7500). The documents PSC released to me show that the money was repaid on 3 March and the gifts were returned on 7 March. That was six weeks or so after the investigation got underway, almost five months after the event. Only Peter Hughes could consider that to be “at the first opportunity”.

I had asked PSC to justify the “at the first opportunity” statement – not then knowing the dates. They simply refused to answer, claiming that the justification is in the report, which it isn’t (including because the report does not use the phrase, which appears only in the Hughes press release).

But there is still the travel for the MCH welcome to consider. Having been caught out and presumably rather strongly “encouraged” to return the gifts and reimburse the cost, you might have thought that an honourable man – the sort of person we might want to entrust the running of a government department – would have said “oh, and by the way, MPP actully paid for some family travel for my MCH welcome. I guess I shouldn’t have taken that either, and I’ll reimburse that cost today too”.

An honourable person might have done that. Leauanae didn’t.

In fact, at this point PSC was not even aware that taxpayers’ money had been used to pay for the family travel to the MCH welcome. The whole MPP inquiry seems to have been wrapped up – although strangely not released to the public as they had told MPP in January they intended to do – when on 19 June (months later) Hughes decided to expand the scope of the review to examine both MPP and MCH expenditure on the welcome. A copy of the Hughes letter to Leauanae (as head of MCH) is on the PSC website.

But not even that seems to have prompted Mr Leauanae to think “gee, I really should have got on and reimbursed that family travel we never should have accepted. I’ll put the payment through now”.

Because it was not for another month, on 24 July, that Leauanae finally reimbursed MPP for that travel.

And Hughes wants us to believe that it had all been sorted out and reimbursed at the first opportunity. In fact his underling (who signed the OIA response) repeats what is obviously false, re the farewell spending, that “upon being made aware of the expenditure, the outgoing Secretary returned all the gifts and reimbursed the Ministry”.

He just didn’t. Here is PSC’s own little table from the OIA response.

I’d also requested from PSC copies of any contacts with Mr Leauanae seeking these reimbursements. I half imagined something pretty stern and reproachful. It was after all wildly inappropriate for this money to have been spent on him and his family, and he was still (and is) a serving public sector CEO, in a public sector whose Commissioner is fond of emphasising not a culture of entitlement or of what one can get away with but the “spirit of service”.

I suppose it is just possible their response is to some clever reinterpretation of my request to enable them to hide stuff. But PSC did not tell me that they were withholding anything, so we must take them at their word that these were all the communications.

There is this text from Leauanae to Heather Baggott (a deputy SSC Commissioner, who as it happens had been acting CE at MCH when the expensive welcome was being put together)

So they’d had a really good chat. Months on. And Baggott’s response is also provided

And that’s it apparently for the farewell spending. No reproach, no reprimand, just a good chat among the chaps, all cleared up and no harm no foul.

For the family travel expenditure it is even worse. There is apparently nothing in writing at all from PSC. There is simply this one liner from Leauanae to an Assistant Commissioner at PSC.

Notice his very careful wording. He reimbursed MPP as soon as they told him the dollar amount that had been spent. But that doesn’t even come close to matching the Peter Hughes description “I thank Mr Leauanae for putting the matter right at the first opportunity”. No, it was months later, in two stages, with no evidence of anything proactive from Leauanae himself.

In a country with high standards of integrity (let alone frugality) in its government and public service the whole thing should be just astonishing and almost unimaginable. We no longer have that in New Zealand. Even so, what was known when the story first broke still prompted considerable public and political blowback. Who has $40000 farewells, and expensive welcomes, especially when it is just a public servant transferring from one agency to another? Who takes lavish personal gifts and unauthorised family travel, even if later they reimburse the money?

But there are plenty of other questions. How did the lead public sector agency (PSC) – responsible for public sector standards and especially the conduct and performance of CEs – allow all this to happen, and how was it that it didn’t even launch an investigation for more than two months after the events? How is it that there appears to have no black mark against Leauanae’s professional standing, and he still holds a CE job, despite behaviour that in junior staffer would probably have been met with dismissal? Where is the government in all this? Ministers were at both events, and are now well aware of the PSC report. Is this really acceptable behaviour from a government department CE in this day and age – or are both frugality and basic ethical standards just tossed out the window?

And why did Peter Hughes simply lie to and actively mislead the public? Reread the post if you think those words are too strong. The farewell expenditure/gifts were not returned/reimbursed “immediately Leauanae became aware of the matter” but months later, weeks after even the inquiry started, and the MCH welcome spending wasn’t reimbursed for several more months later. None of it was done ‘at the first opportunity’ as if there had just been some unfortunate and very brief, almost pardonable, misunderstanding. None of that is revealed in the report Hughes had had carefully constructed or in his press release. Nothing, it seems, must be allowed to damage the image of one of his CEs.

It is simply dishonest and disgraceful. Responsibility for the PSC Commissioner rests with the Minister (Little) and the Prime Minister (Hipkins, who was himself minister until January).

I’ve never had anything to do directly with Hughes. My closest encounter was in 2019. I’d made a mistake in a post here about outgoing Treasury Secretary Gabs Makhlouf, stating that Hughes had been responsible for his reappointment. I was quite surprised to get a phone call that evening from SSC’s comms guy stating that “Peter has asked me to ensure that you are aware that that reappointment was made by [his predecessor] Iain Rennie” (and I of course corrected the post).

But the Leauanae affair and what should really be called the Hughes affair – actively misrepresenting things in a public statement – appear to be all on Hughes himself.

Just making stuff up: the chair of the RB Board and the blackball on expertise

The government-appointed (and reappointed) chair of the Reserve Bank Board has been in the news today, after the reports earlier this week that in his role as Vice-Chancellor of Waikato University he’d been negotiating policy around a future new medical school at Waikato with National’s health spokesman Shane Reti. I don’t have any particular problem with such talks per se but what caught attention was this spectacularly inappropriate line

Reti seems to be a person of decency and integrity and one can half imagine him wincing when he read those words. Who, he might have asked himself, is the senior person who not only runs a public university but also chairs a major government board, who actually says such things, let alone writes them down.

There is also a (paywalled) Newsroom article this morning [paywall now lifted here] on Quigley, explicitly questioning his ability to keep holding the Reserve Bank job. I don’t think Quigley is a political partisan (National or Labour) – and he has had roles from both National and Labour governments – but he again displays a serious lack of judgement and tone-deafness (of the sort that was on display when he finally got one of his RB Board members to step down from an insurance company directorship, not because having such a role was a terrible look but because the OIA might lead to some scrutiny, or had never raised a concern at the government appointing the chair of Kiwibank’s then owner to the board of the bank regulatory agency). He can’t match the Governor for lowering the standing and reputation of the Bank – but then for the Governor it is a fulltime job – but it is a pretty consistently poor and damaging record.

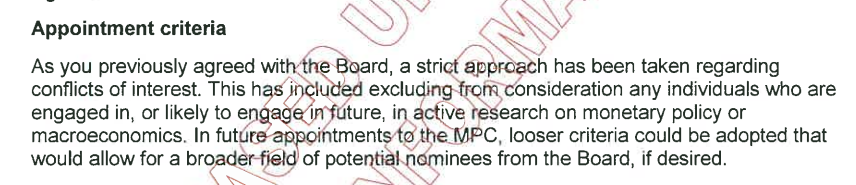
And then there was the question of the ban put in place in 2019 on appointing people with active or likely future macroeconomic research expertise to the initial round of Monetary Policy Committee vacancies. It is clear that there was such a ban (now removed for the round of vacancies coming up next year) and that the Minister of Finance and the Bank’s Board (chaired by Quigley, with Orr a member who had to be formally consulted as well) had agreed on the ban.

Quigley claims otherwise. That there never was such a ban, that it all a castle built in the air on a paper written to the Minister of Finance (released to me in 2019) by a Treasury manager responsible for governance and appointments. He had had, he claims, no idea until last year where such curious, incorrect, ideas (of the sort people like me and Eric Crampton, and fulltime journalists, notably Jenee Tibshraeny, now of the Herald) had been writing about had come from. This was the extract in question.

Quigley even got Treasury and the Minister to say in public that it had all been a misunderstanding, and that there had never been such a ban.

About a month ago I wrote a long post based around an OIA response from The Treasury in which I had asked for background relevant to that Treasury statement. I outlined what Quigley had told Treasury twice, months apart, earlier this year, and compared it carefully to what had been revealed in (a) past OIAs from the Bank and Minister, (b) things I knew from first hand accounts, and c) comments from the Minister, the Bank, former Reserve Bank Assistant Governor John McDermott, and former ministerial adviser Craig Renney. I pointed out that the ban had been commonly and widely understood, not just among Reserve Bank watchers in New Zealand but in markets overseas (a Treasury manager reported having been challenged on it in Australia), and not in ways that were welcoming – more along the lines of derisive comments that the Reserve Bank of New Zealand was the only central bank in the world where actual research expertise would have been a formal disqualifying factor. As I had noted in one post, not even Trump’s Fed appointment standards had dropped that low. There had been plenty of opportunity for Quigley and the Bank (or the Minister) to have corrected the story at any time over several years, and Orr in particular has not been backward in coming forward when he thinks people aren’t representing him or the Bank in a way he likes. I’d encourage you to read that post as I don’t want to repeat it all here.

At about the same time as the Treasury OIA had been lodged back in June Eric Crampton and I independently lodged (somewhat overlapping) OIAs with the Bank re aspects of the blackball and its removal. Being the Bank, they were very slow to respond but we both finally got responses on Tuesday. There is a couple of hundred pages of material, although bulked out by releasing back to us both the 42 page response the Minister had given me in 2019, which they had probably in turn just got from my website (it was in the mix because last year a senior Bank official sent it to Quigley, who then started on his “no, no, that wasn’t so at all” line.) Both responses are linked to below (Eric’s first – with his permission- then mine which came in two separate big documents).

RBNZ OIA release to Crampton Sept 23 re MPC expertise blackball

RBNZ OIA release to MHR Sept 23 re MPC expertise blackball Part 1

RBNZ OIA release to MHR Sept 23 re MPC expertise blackball Part 2

The documents make interesting, and slightly depressing even incredible (literally almost unbelievable), reading in places.

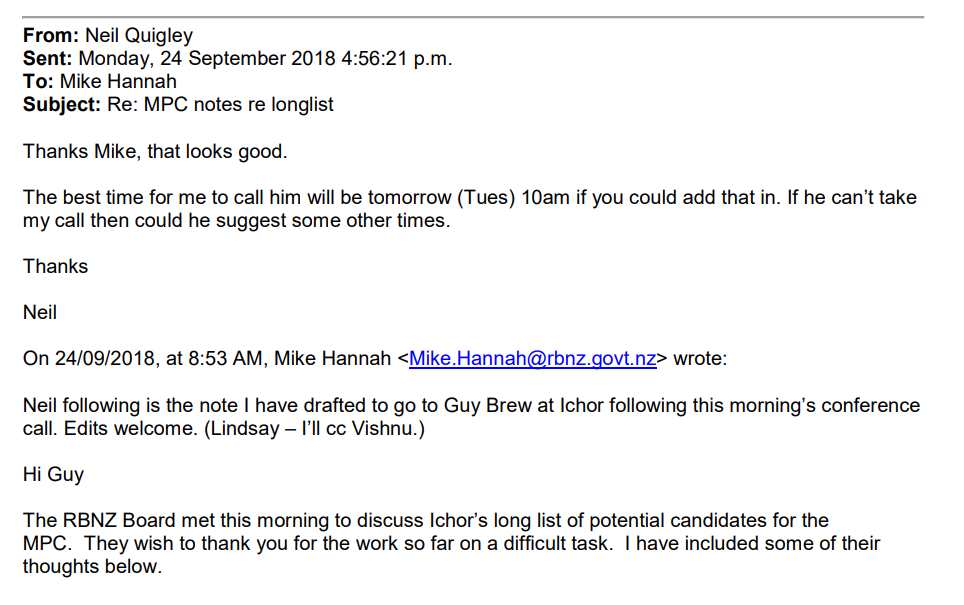
The document set starts on 18 May last year when the Governor (Board member) sends an email to Nick McBride (the Bank’s in-house lawyer) cc’ed to his boss (one of Orr’s DCEs) asking about whole situation re ”criteria and expectations” for external MPC members, noting 

McBride says he doesn’t really know what went on (“as far as I know it was worked out between MoF and the RBNZ Board”) while noting (quite correctly) that there was nothing in the Act or the MPC charter or code of conduct that required or reflected a blackball on expertise. (Among outside critics I think this has been common ground all along. It would have been even more absurd had the law somehow enforced the ridiculous ban.) McBride comes back later that day with the extract (above) from the 2019 Treasury paper, pointing out that it had been released to me and had been what had sparked the coverage. McBride disavowed any knowledge of what had happened beyond that account. Neither he nor Orr seem to be in any doubt that there was such a restriction put in place for the 2019 appointments.

Nor had there been any doubt earlier in 2022, when Tibshraeny had been asking about the blackball in the context of the approaching expiry of the terms of two external MPC members. The Bank knew then, but outsiders did not, that the plan was simply to reappoint the incumbents so inside the Bank it appears the issue hadn’t arisen until Tibshraeny got what was probably a throwaway line from the Minister in a press gaggle, that he wasn’t aware of any change of criteria, and she then sought comment from the Bank. No one in any of the emails seems to have doubted that there was a ban – no one seems to have known much – but they just wanted to put Tibshraeny off (‘best not to throw any chum in the water’) so they agreed also just to line up with the Minister and say “no change”. So relative to what we previously knew, it is probably safe now to say there was actually no new information in those 2022 comments from MoF or the Bank. There is no record of them having consulted either Orr or Quigley at that point.

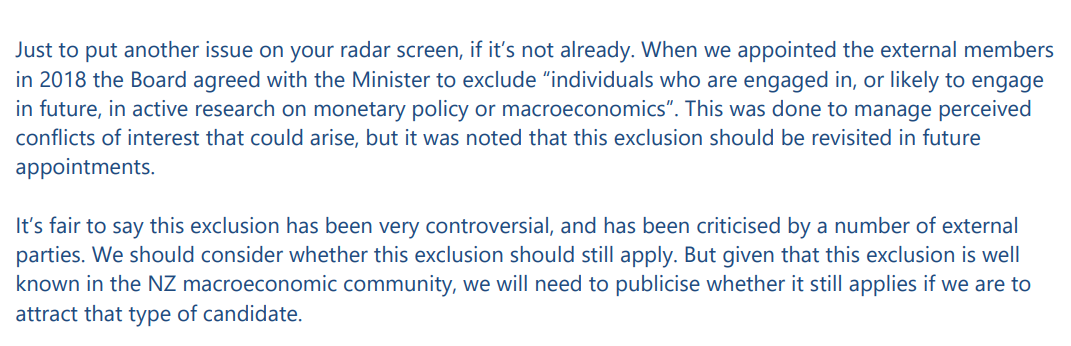
The final bit in the response to Eric Crampton was this from February 2023, when work was going on on the process and criteria for the next set of MPC expiries/vacancies. McBride and one of Bank’s governance people explicitly draw Quigley’s attention to the 2019 paper (Gael is Gael Webster, the Treasury governance and appointments manager who had signed out the paper). Note that section 9(2)(a) is a withholding ground around personal privacy: we might wonder whose.

It is pretty extraordinary, if this were an honest account, that the Board chair had never once in the previous 3.5 years asked someone why this view – that there was an expertise blackball, which he says he was aware of – was abroad. Extraordinary and not at all plausible, given that until last year the appointment of MPC members and of the Governor was the single most important powers the Board had.

My OIA had covered only material from this year and picks up in mid-February (just prior to that exchange with Quigley) as staff are reviewing processes etc for advertising for MPC vacancies. (Interestingly, the Comms manager suggests this would be a good case for pro-active release of relevant material, not a concept the Bank displays any practical sympathy with ever). The draft document they are commenting on includes among the things to be done

and in comments McBride recognises the ban, commenting that “the board needs to be clear about its attitude to including MP [monetary policy] subject experts on the MPC and this should be resolved at the outset.

The Economics Department is a bit slow with its comments, and didn’t comment until the next draft in early March. Chris Bloor, one of their experienced and respected managers, observed

to which the person leading the process responds

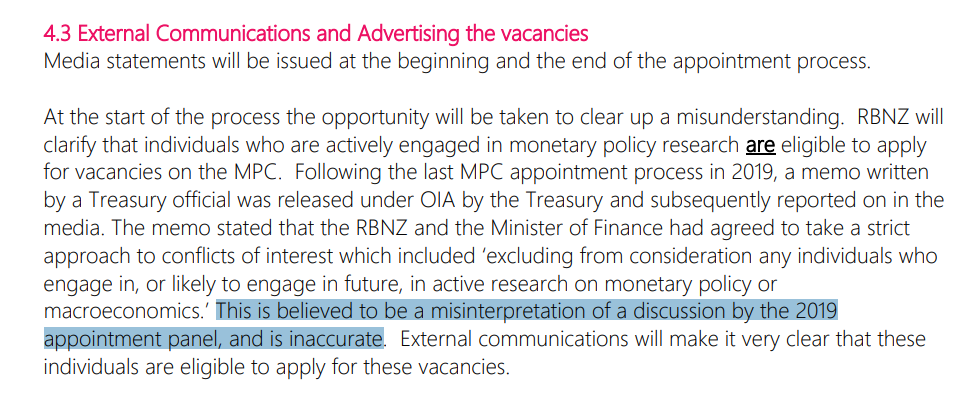
But they really weren’t very sure. In early April a paper went to the Reserve Bank Board on the MPC appointment process and it included this

And that was all that was new in the papers relevant to the issue. Note that there is no suggestion that anyone made any effort to contact Treasury or Gael Webster specifically, they simply went along with a story Quigley had given them years after the event. It seems not to have occurred to anyone (or perhaps it would be lese-majeste in today’s RB to have done so) to ask “but what about all those statements that have been made in defence of the ban previously?”, or “but if so many people had got the wrong end of the stick outside and abroad, why did we never clear up the confusion?”

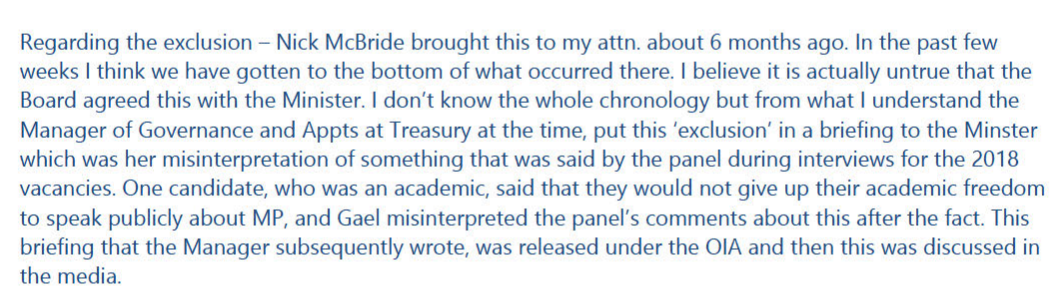
I’m quite prepared to believe that there was an interview with an academic applicant (recall that academics themselves weren’t barred, and (non-macro) Prof Caroline Saunders was appointed), who told them “they would not give up their academic freedom to speak publicly about MP” [as MPC members in many other countries do speak] but on the most charitable interpretation Quigley must have been conflating two quite different events and sets of circumstances.

As I discussed in the earlier post, all those years ago a qualified academic told me that they had contacted the recruitment firm the Board was using and been told that they would not be considered because they did and might do in future macroeconomic research on matters relating to monetary policy, and that this was a criterion choice adopted by the Board. The same academic then saw Quigley at a function and asked him about this apparent ban, including if it was really the Board’s view. As recounted to me, and repeated recently, Quigley’s response was along the lines that they wanted to be very cautious and risk-averse for the first set of appointments and that the criteria might be relaxed in future rounds. That was well before anyone was longlisted, let alone shortlisted or interviewed. My interlocutor couldn’t even get on the page to be asked about how they would operate in practice if appointed. And you will note that that conditional statement about future appointments is very similar to the wording used in that 2019 Treasury memo that Quigley now seeks to disavow, throwing the author under a bus.

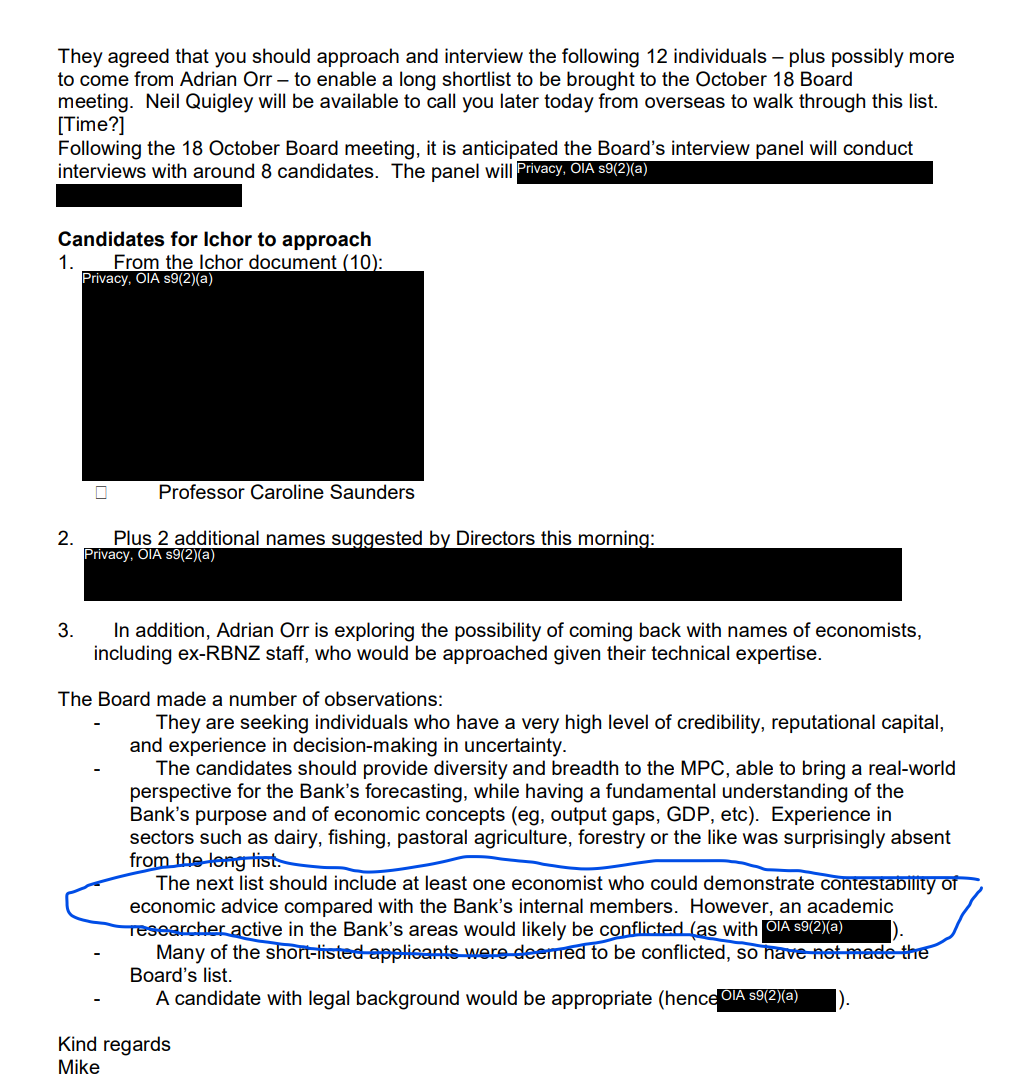
And how about some of the evidence I cited in the previous post? Here Quigley raises no objections to the Board Secretary’s account of a Board discussion of individuals and (see highlighted bit) criteria.

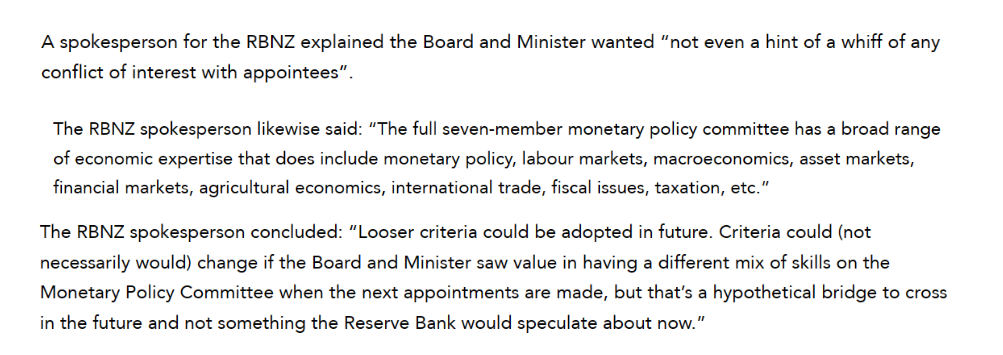
Here was how the Bank’s spokesperson was defending the blackball in 2019. Note the explicit use (their own words) of the line that “looser criteria could be adopted in future”.

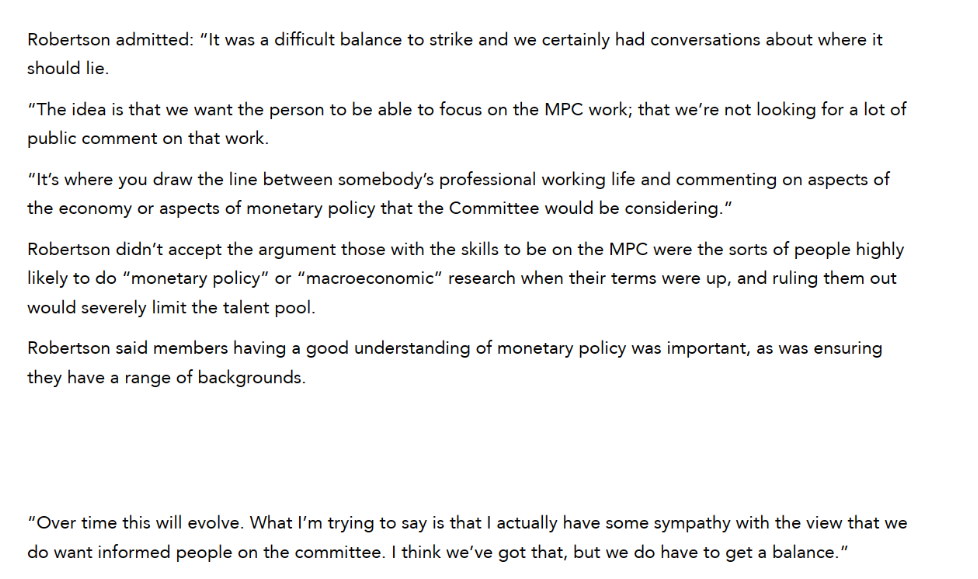
And here was the Minister of Finance’s defence of the blackball in 2019; he also explicitly stated “over time this will evolve”.

There is simply no evidence for the (contemporary) Quigley version of events – the one he got Treasury to embarrass itself by making a statement defending (having asked no questions themselves, but happily tossing a former staff member under the bus).

(Having read the latest OIA releases I went back this morning and read the Bank’s 2019 release to me on matters around the MPC selection and appointment process. On rereading it I noticed that they had not disclosed any communications to or from the recruitment firm (nor identified such material with statutory grounds for withholding). A new OIA has been lodged this morning which may yet shed some new light.)

It is quite clear that there was a blackball on expertise (which has now, formally, been removed) and when Quigley told Bank staff and Treasury (twice) that it was not so, at best he was confused, and at worst deliberately trying to lay a false trail to cover later embarrassment at such a bizarre rule, all while deflecting blame onto an experienced professional who had been working for another government agency. Neither option reflects any credit on Quigley or the Bank whose performance he is supposed to oversee and hold to account. Once again it brings the institution into disrepute (though more so him as an individual and statutory officeholder).

One is always suspicious of what isn’t in these releases. There is relevant material that has been in other releases, including from Treasury, but not released in this set, and there is no record of any discussion (written or oral) between the Governor and his Board chair about any of these issues. That simply doesn’t ring true. But whether true or not, there is quite enough material in what we do know to conclude that, wilfully and deliberately or not, Quigley was simply not telling an accurate story when he has tried to convince staff and Treasury that there never was a blackball. He should be held to account for that. He should not – for this and a variety of other reasons – be the chair of our central bank and banking regulator, from whom we should expect openness. transparency, integrity, accountability….and the humility to acknowledge honestly when mistakes have been made (in this case both the blackball itself and the spin, attempting to rewrite history at the expense of others).

UPDATE: Eric Crampton has a follow-up post in which he bends very very far over backwards to find a charitable explanation. I don’t find it persuasive, and he doesn’t take account of several important items above, but it is worth reading as an alternative take.

NZ in fiscal perspective: cross-country and across time

Yesterday’s post outlined some of the fiscal balance numbers that should get more focus in New Zealand but typically don’t (partly because The Treasury does not usually also make their numbers available in internationally comparable definitions and formats).

That post was partly background to today’s, in which I want to show first how the current New Zealand fiscal numbers – as at this year’s Budget, so near-certain to be less favourable next week at least in headline terms – compare with our own experience in recent decades, and then to put New Zealand’s numbers into international comparisons, both across countries (other advanced countries) and across recent decades. It will cover some ground similar to a post a couple of weeks ago, but whereas that week I was writing a series looking at countries which had their own monetary policies (with an inflation lens in view), and thus the euro-area was a single observation, in this post I’ll be looking at advanced countries (using IMF and OECD data) regardless of what monetary policy arrangements they have. The focus here is entirely fiscal.

I’m also not going to be paying any attention to anyone’s forecasts beyond 2024 (ideally 23/24). Fiscal numbers up to fiscal year 21/22 are hard, those for 22/23 are estimates (from the Budget), and those for 23/24 (also Budget) are based on (now) legislated taxes and appropriations. For anything beyond that one can look at cost pressures, one can look at political party promises, one can look at announced (frequently revisited “fiscal rules”) and so on, and do a different sort of analysis. But bottom-line fiscal forecasts several years ahead have little or no meaning.

The first chart shows the government’s (and, apparently, Treasury’s) preferred indicator: the operating balance (OBEGAL) as a per cent of GDP. As a reminder this is a theory-free and total Crown measure. The data go back only to 93/94.

On this measure we had 15 years of surpluses (under governments of both stripes). Then through some mix of poor Treasury advice and severe recession there were deficits, briefly but greatly exacerbated by the fiscal effects of the Canterbury earthquakes. This measure was back to surplus in 2014/15 and (rising) surpluses continued to be run by governments of both stripes for the following five years. Covid meant a loss of revenue and a choice (widely supported) to provide a lot of fiscal income support. A really big operating deficit in 19/20 understandably followed. Renewed lockdowns in late 2021 had a similar but smaller effect on the 21/22 numbers, but by then the economy was running strongly and inflation was rising sharply, and inflation is at least initially a windfall for the fiscal authorities. For the last two years (free of required Covid spending), the deficits are just under 2 per cent of GDP. The economy was more than fully employed in 22/23 and in the Budget forecasts was expected to be around fully employed on average over 23/24 (small negative output gap, unemployment rate averaging a bit below NAIRU).

As I noted yesterday, Treasury doesn’t publish a long-term time series of cyclically-adjusted balances, but this chart back to 2008/09 shows much the same picture

You might reasonably be a little sceptical about whether the cyclical adjustment effects are quite large enough (but New Zealand automatic stabilisers are not typically regarded as overly powerful), but these are the best estimates Treasury was giving us (and the government). There really isn’t much case for running cyclically-adjusted operating deficits (even OBEGAL deficits). It has the feel of borrowing to pay the grocery bill.

Governments (and Treasury) have chopped and changed the debt definitions they like to focus on. For the current (and better) favoured net debt measure, they have only backdated the series as for as 2004/05. But here is the chart, expressed as a per cent of GDP

Still not very high in absolute terms, but now the highest in at least 20 years (and in practice quite a bit longer than that).

And here is one last chart just using Treasury headline series; this one one which doesn’t get much attention but is measured a bit more like the IMF and OECD series we’ll come to later

It is a less rosy story after 2008, as the return to surplus lasted only two years (16/17 and 17/18) and the forecast deficit for the current year (23/24) is about as large as that in 2010/11 (earthquake year), and almost as large as the two peak Covid years. Treasury don’t do cyclical adjustment on this series but any adjustments would be fairly similarly small as those for the operating balance (above).

Those four charts just use series straight from The Treasury’s website. There are no adjustments, no approximations, no derivations, just reportage. And because they are idiosyncratic New Zealand series we can make comparisons only over time and not across countries.

As I noted in yesterday’s post, primary deficit measures (ie excluding interest) are a common feature in international agency perspectives (and databases) on fiscal stances. Treasury does not publish any such measures for New Zealand. We can, however, make an approximation. They are only approximations as the only long-term time series for finance costs that Treasury provides is core Crown while the OBEGAL operating balance is total Crown concept, and while residual cash is a core Crown measure it is cash-based while the core Crown numbers are accruals. In addition, in principle one should exclude interest receipts as well, but the time series data only breaks out only finance costs. It is less than ideal – Treasury, please start publishing some proper primary balance numbers – but I’m going to here adjust both the operating balance and residual cash for core Crown finance costs and keep my fingers crossed that if the levels aren’t quite right the comparisons over time will be more or less valid.

The primary operating balance is all but in balance this year (at least as at this year’s Budget), albeit a very long way below the primary surpluses we once more or less took for granted.

And if one wanted to tell a more favourable (and analytically valid) story one could note that in the last couple of years more than all the finance costs have just been compensation for inflation (eg 6 per cent inflation in the year to June while all government bond and OCR rates have been below that). If we did an inflation-adjusted operating balance series it really would have been probably around balance in 22/23. But that won’t be so in the current year, at least on current Reserve Bank inflation and OCR forecasts.

But at this point I’ve largely exhausted what can be done with official New Zealand data and have to turn instead to the OECD (mainly) and IMF databases, the two main compilations of (as far as possible) consistently-reported fiscal data and estimates/forecasts. These measures are all for the (national accounts) general government concept (which does not map directly to Treasury data for even central government New Zealand data), encompassing all levels of government. We don’t have provincial/state governments in New Zealand, and local government is small, but for valid cross country comparisons general governnment is the way to go. As to timing, the OECD numbers are from June (so probably incorporate budget numbers), but the IMF Fiscal Monitor numbers are from April (but we have a partial update from the IMF Article IV report released last week)

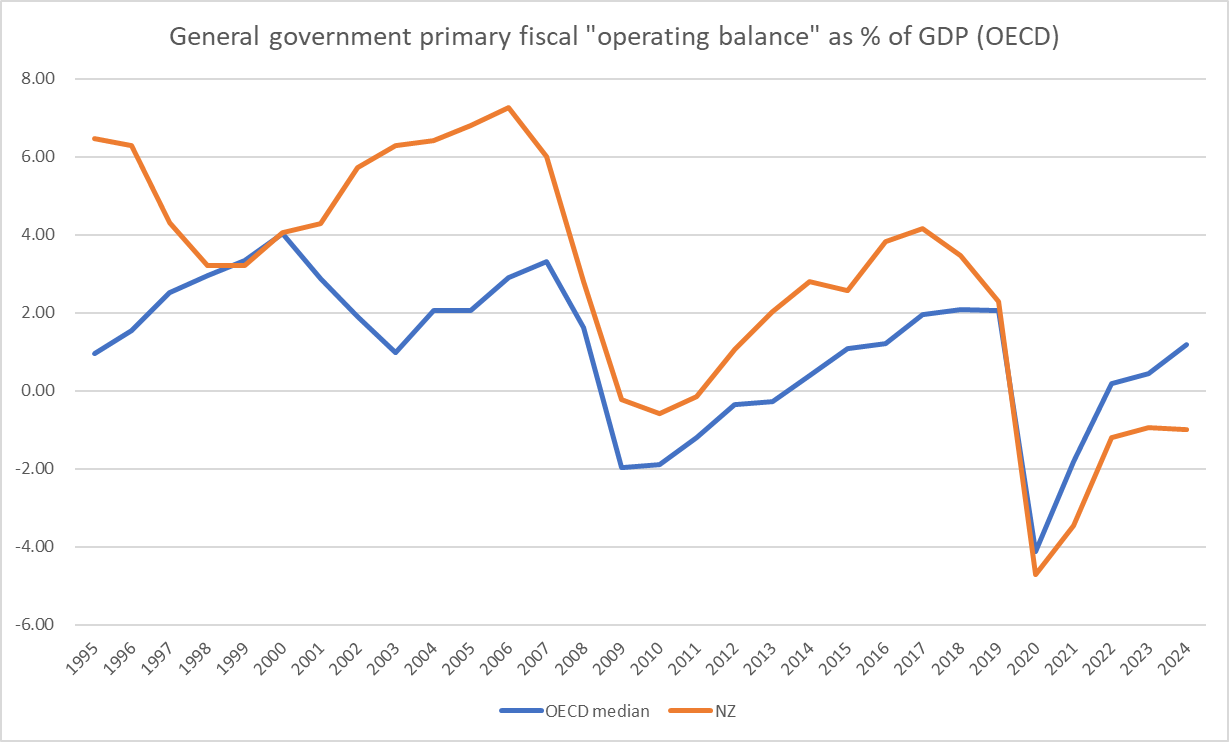
Neither the IMF nor the OECD report operating balances, whether headline or primary. However, if one digs down in the databases one can construct one’s own (as they provide data on current disbursements, current receipts and net finance costs as shares of GDP). Here is how we’ve compared against the 32 OECD countries (not including the Latin American ones) for which there is complete data.

Prior to Covid there was only year in the 25 in which New Zealand’s primary operating balance was even marginally below the OECD median. Since then, we’ve been running larger deficits and if anything the adverse gap was thought earlier this year still to be widening.

For this year, they had New Zealand’s deficit 7th largest in the OECD, and next year 6th largest. That was months ago.

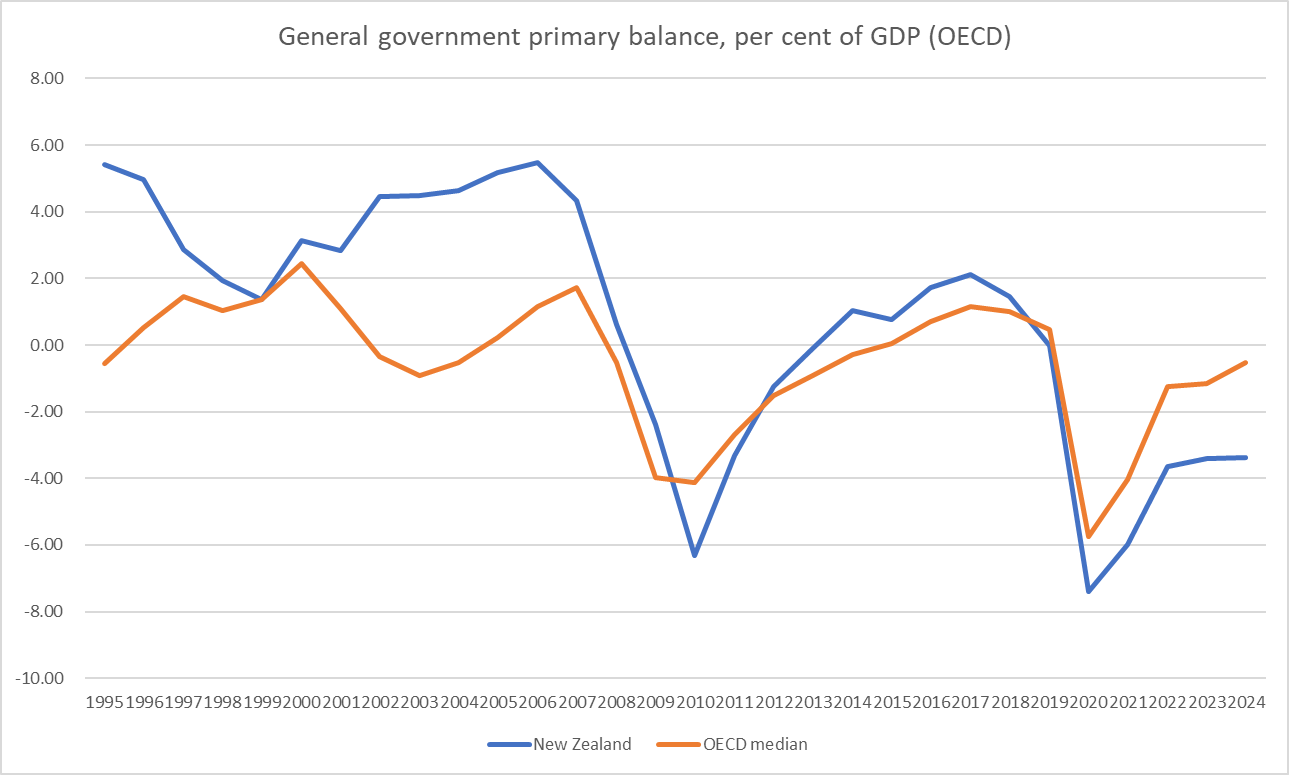
And here is one of the series that the OECD themselves headline, the primary overall balance (current and capital)

The picture is fairly similar to the (derived) “operating balance” one. Previously the only time we’d been worse than the OECD median was with the Canterbury earthquakes (which put a large liability on the Crown through EQC). We used to better. Now we are worse. (On these forecasts a few months ago, 5th worst this year, second worst next year).

I’ll spare you the cyclically-adjusted version of this chart, just noting that on OECD cyclical adjustment methodology (consistently applied across countries) as at a few months ago the median OECD country was expected to be running a (tiny) surplus next year and New Zealand a substantial (2.5 per cent of GDP) primary deficit. Only Japan was then expected to have a larger cyclically-adjusted primary deficit.

And one last fiscal balance chart. This one shows the national accounts net lending measure for the general government sector

We used to be consistently better. Now (since Covid began and on mid-2023 forecasts even this year and next) we are materially worse. The differences here are not small (a 2 percentage point difference now is roughly $8 billion per annum for New Zealand).

And here is a chart of general government net financial liabilities as a per cent of GDP.

The New Zealand line looks a lot like the (shorter run) of central government Treasury data shown earlier. But it is the international comparison that is interesting. We often here talk about how low New Zealand government debt is, but actually the median OECD country just isn’t that heavily indebted either (although places like the UK, US, Japan, and Italy really are). We are still lower than the median country, but on these projections from some months ago the gap is closing fast. And notice that the median OECD country experienced a one-year blip up for Covid costs (and revenue losses) but now has lower net debt as a share of GDP than in 2019. New Zealand not so much. We have had one of the largest increases in net debt, as a share of GDP, whether one looks at the entire period since 2019 or just the final three years (our need for heavy Covid spending, like that of other countries, largely ended in calendar 2021). It is worth remembering that today’s highly indebted countries were not always so (eg as recently as 2001 the UK had lower net general government financial liabilities as a per cent of GDP than we do now).

Finally we turn to the IMF. They have a smaller set of indicators, but the same headline and cyclically-adjusted primary, overall, and net lending balances, and a net debt measure. To avoid being repetitive, I won’t run all the charts. They don’t provide such a long run of historical data but the broad pictures seem pretty similar to those with the OECD numbers.

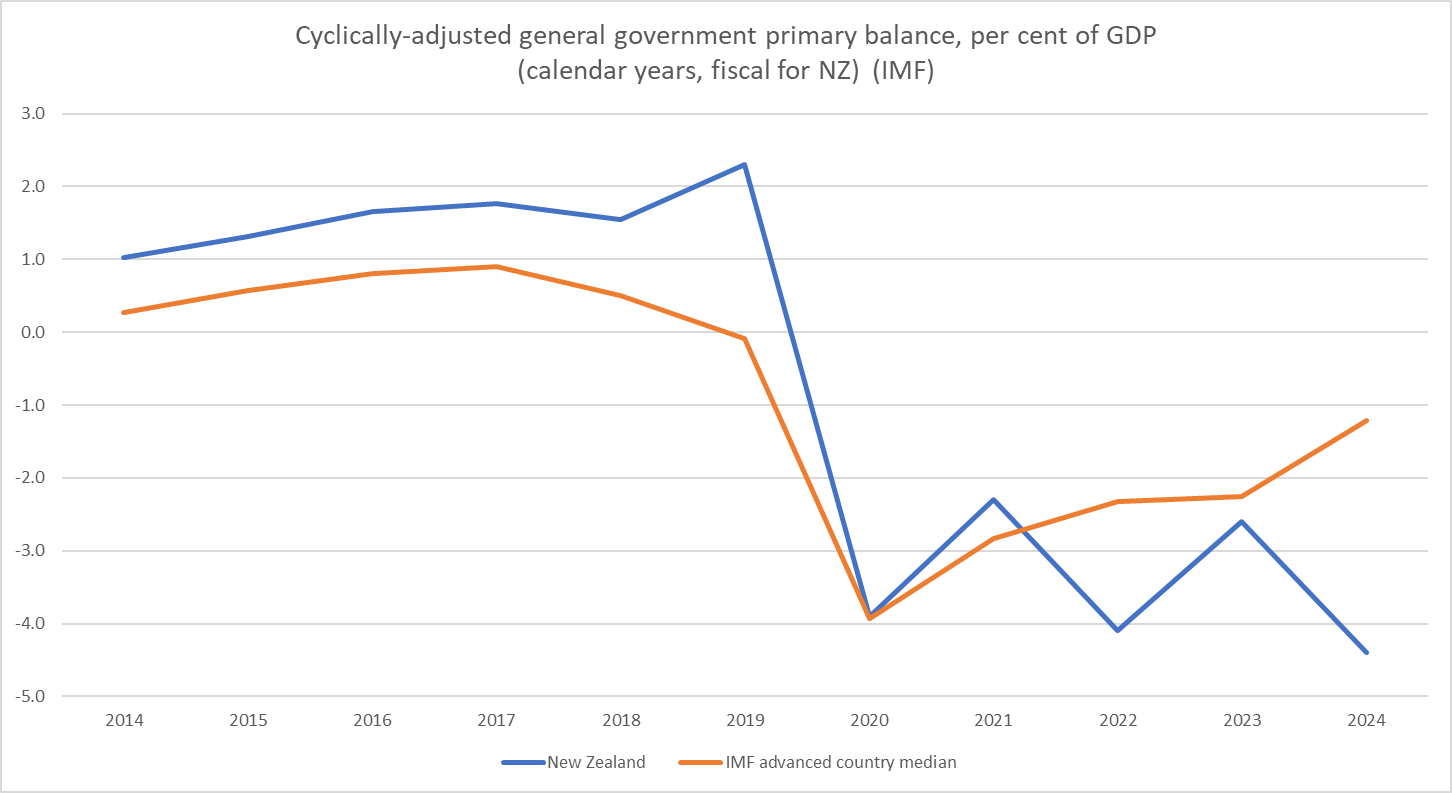
However, in their Article IV report on the New Zealand economy last week the IMF provided an updated forecast series for several fiscal variables. Although the numbers were published last week the report was finalised in July, based on a mission here in June. This was the report that suggested that “frontloaded fiscal consolidation” should be the focus, pointing out in the text that the Budget had been quite expansionary (NB: contrary to the assertions of the RB Governor) that they estimated a cyclically-adjusted primary deficit of 4.4 per cent of GDP for fiscal year 23/24).

Here is a comparative chart for the last decade. We used to better. Now we are (quite a bit) worse. On the IMF’s cyclical-adjustment methodology our primary deficit this year will be larger than in any of the heavy Covid expenditure years,

And for a straight cross-country comparison (using the IMF’s Article IV estimate for the New Zealand 23/24 fiscal year and the average of their calendar 23 and calendar 24 estimates for the other countries.

Looking at the change since 2019, New Zealand has had the worst deterioration in its cyclically-adjusted primary balance as a per cent of GDP of any of these countries. The deterioration in the net lending indicator looks to have been very similar.

And one final chart. The IMF has a different measure of net debt again (and there is a slightly different group of countries than the OECD) but the picture for the last decade is broadly what we’ve already seen from the OECD data.

Here I have shown the IMF’s 24/25 number, not because it is sure to happen (next year’s Budget will be a thing) but because this is the most recent set of official agency numbers, and presumably part of the backdrop to that “frontloaded consolidation” call that both parties seem determined to ignore prior to the election. For this group of advanced economies the median country’s net debt to GDP has increased hardly at all since 2019. Back then the median was far above New Zealand. All it would take is another year or two of New Zealand governments continuing as ours have done in the last few years and we’d have net debt above the advanced country median (whether you like at this IMF version or the OECD one above). I hope there wouldn’t be many takers for that option, in our underperforming low productivity growth economy.

Every single of one of these charts is based on data either up to date to Budget time, or in the IMF’s case perhaps a month later. It is clear that the revenue picture to be revealed in the PREFU will be worse. (Labour’s changes last week to forward operating allowances will limit the damage to forward deficit estimates both those and the departmental baseline adjustments should be treated at this point as little more than electoral vapourware. Lines on graphs do not amount to concrete decisions to cut this or that and keep it cut. And cyclically-adjusted deficits do not fix themselves.)

Thinking about fiscal policy

The numbers The Treasury will release in its PREFU next week will make it fairly easy to follow some bits of New Zealand fiscal policy over time, less so others, but do almost nothing to facilitate international comparisons, and discourage New Zealand users and analysts from looking at fiscal policy in the way most other economic analysts and the international agencies do. It is fairly transparent, but in an insular way.

New Zealand’s government accounting framework often wins plaudits. As a matter of accounting, no doubt the plaudits are largely fair (although I’m not an accountant, and have previously suggested that some accountants rather overrate the contribution of the New Zealand model). It just isn’t a framework used widely for economic analysis or as a good basis for holding governments to account for the conduct of fiscal policy.

The focus here tends to be on the operating balance (excluding gains and losses). Last year, for example, the current government articulated its primary fiscal goal as being to (eventually) deliver and maintain an average (OBEGAL) operating surplus of between 0 and 2 per cent of GDP. It is a fairly theory-free measure

attractive mainly for being relatively more controllable year to year than a simple operating balance would be. But it is the first of the handful of “Fiscal strategy indicators” in the tables Treasury publishes. It was the measure that was forecast to turn positive (surplus) in 2025/26 in this year’s Budget (before they realised they’d forgotten to allow for the near-certain loss of lots of tobacco excise revenue), but in 2024/25 in last year’s Budget (and perhaps in 2026/27 in next week’s PREFU). It is the measure that was still in material deficit in 2022/23 and 2023/24 even at Budget time, before the deterioration in the tax revenue this (calendar) year became apparent.

But an operating balance measure (OBEGAL or total) isn’t widely used for fiscal analysis purposes elsewhere. In fact, if you turn to the two main compilations of comparable cross-country fiscal data – the IMF Fiscal Monitor and OECD Outlook – you won’t find any operating balance data at all (although you can put together such numbers yourself from components in the OECD database).

There are a couple of good reasons why that isn’t the focus.

Operating balances sound good and commercial, somewhat akin to a profit and loss account for a business. Capital expenditure typically doesn’t appear in a profit and loss account, and nor should it (as with New Zealand government accounts depreciation appears in a profit and loss account, and in the government’s operating balance). But when a business does capital expenditure it does so with the goal of generating future income (or maybe reducing future costs) but that is rarely the case with government capital investment spending. New Zealand’s total Crown OBEGAL does take account of the Crown’s ownership interests in various profitable businesses (which is not the case with the standard general government concepts used in the national accounts and in most cross-country fiscal analysis, where commercial business interests are excluded by construction) but most total Crown capex is just another form of spending. It might – like operational spending – be done for good reasons, it might have expected benefits down the track, but any such benefits are rarely fiscal in nature. And today’s capex is tomorrow’s depreciation (with no new matching revenue). In principle, the worse the project the larger and sooner the economic depreciation.

The second reason is the role of interest (financing costs). It is very common in overseas and international agency fiscal analysis to focus on primary balances, which exclude financing costs. These series are prominent in IMF and OECD tables. In New Zealand the Treasury publishes no primary balance measures at all and never seems to discuss the concept (one can construct some yourself, although probably only as reasonable approximations)

There are two good reasons for a primary balance focus. The first is that interest payments mostly reflect past fiscal choices rather than today’s (if your country ran up a high debt a decade ago, you are most probably still servicing that debt now). It is a real fiscal burden now (and thus primary balances aren’t the only relevant metric) but what matters more for the future debt trajectory is what choices are being made now re non-interest spending, and revenue. Broadly speaking, if you are running a primary surplus debt (to GDP) is likely to be heading in broadly the right direction, and if you are running a material primary deficit, then debt probably isn’t going to be heading in the right direction (it depends on your respective interest rates and GDP growth rates).

The other reason for a primary balance focus hasn’t been very relevant in advanced countries for several decades but is now: inflation. When inflation is low nominal interest rates tend to be low. When inflation is high nominal interest rates tend to be high. If interest rates are 2 per cent and inflation 2 per cent, the substantive economic implications for government finances are no different than if inflation is 5 per cent and interest rates are 5 per cent (real rates are the same). But nominal interest is what is recorded in the government accounts (and in those New Zealand government operating deficit numbers I mentioned earlier). It makes a difference: at present government bond rates and the OCR (much of the Crown’s debt is currently those RB settlement account balances) have increased a lot, but are actually both still below the rate of inflation. In economic substance terms, the operating deficit numbers in the Budget (and those to be published next week) are materially overstated.

(Inflation adjustment issues are pretty pervasive – company accounts and individual debt burdens, not just the government’s – are just another reason why we shouldn’t be tolerating a central bank doing such a poor job on core inflation that we have start thinking again about how inflation distorts both behaviour and accounts.)

Now it is true that The Treasury doesn’t just publish (total Crown) operating balance (OBEGAL) numbers. Second on that table of Fiscal Strategy Indicators is a measure called “Core Crown residual cash”. Unlike the OBEGAL it is (a) measured on a cash basis (not accruals), b) is a core Crown measure (not total Crown), and c) it treats all cash (capex and opex) alike. It is, in other words, much more akin to the series that show up in those international databases (but note that neither core Crown nor total Crown is the same as “central government” for national accounts purposes, let alone “general government” – which is vital for cross-country comparisons with countries where state/provincial and local governments make up a much bigger share of overall government activity)

When I went to work for a while at The Treasury I vividly recall one of their more astute analysts encouraging me to focus on this measure. Few in New Zealand seem do (and I only inconsistently across time). Neither political party seems to. And in case you were wondering, in this year’s Budget – recall, before the fall off in tax revenue – the core Crown residual cash deficits were expected to be 5.7 per cent of GDP in 22/23 and 6.5 per cent in 23/24.

The ups and downs of the economic cycle affect fiscal balances. Expenditure is affected to a small extent (eg unemployment benefits) but the main impact is on the revenue side (tax receipts). Consistent with that it is common to look at, and the international agencies, publish estimates of cyclically-adjusted deficits (total and primary).

The New Zealand Treasury does typically publish estimates of the cyclically-adjusted operating balance, but not of even any other measures, and notably not of any primary balance measure. One could do one’s own rough and ready adjustments to the alternative series, but how much better if Treasury were doing the adjustments themselves, using disclosed the contestable methodologies. There is also no long-term consistent time series (eg published with the annual long-term fiscal data on The Treasury website). There is no one right answer to how much allowance should be made for cyclical factors in doing cyclically-adjusted numbers – it is the same contests around the output gap and the NAIRU as monetary policy makers repeatedly face (and estimates are likely to be revised, perhaps quite a bit, over the years) – but in big booms and deep recessions it is important to try (normally we would not want deep fiscal cuts if we could be reasonably confident a deficit was mostly a reflection of a deep cyclical downturn).

Until relatively recently, The Treasury used to publish (but buried very deep in an Additional Information document) the operating balance on a terms of trade adjusted basis (a higher/lower terms of trade – variable and largely outside New Zealand control – can flatter/punish fiscal outcomes independent of government fiscal policy choices. Here is an example, from the 2017 PREFU, of how much difference Treasury thought the rising terms of trade had made in improving fiscal outcomes over the previous decade.

As the terms of trade trended upwards fairly consistent over 15 years, the adjustment perhaps became somewhat moot. In the last few years, on the other hand, the terms of trade have been falling back.

Much of this post so far has been about how we might better analyse New Zealand numbers in isolation, but international comparisons also matter. Why? Because there are no single right and wrong answers about the appropriate deficits or surpluses or debt levels, but we can often make better sense of our own data if we can compare and contrast with developments in other advanced economies. But comparing and contrasting needs to involve data compiled as consistently as possible across countries (as, say, with cross-country comparisons of GDP growth and productivity, and where comparisons of inflation are often complicated by the absence of such consistently compiled measures). For those purposes, the fiscal databases and forecasts done by the IMF and the OECD are the standard. In those databases we can find raw and cyclically-adjusted primary and overall fiscal balances, gross and net debt measures, and measures of net lending (savings less investment), all on a general government basis.

Both the IMF and the OECD produce numbers for New Zealand, including forecasts for the coming years. These are typically done starting Treasury’s fiscal numbers and adjusting for (a) different views on the state of the economy, and b) the methodological differences between the New Zealand measures and these internationally conventional ones. At times – eg the IMF Article IV report last week – they will provide some updated estimates, but generally the IMF and OECD numbers are published only twice a year.

But in the Treasury numbers accompanying the EFUs there is no attempt made to present their updated numbers in an internationally comparable format (not even just as an appendix), whether flow or stock measures. On the face of it, doing so should be a relatively mechanical exercise that would require a one-off investment to set up but almost no marginal resource cost beyond that (especially when the non central government components of general government are small and slow moving in New Zealand). And yet they choose not to do it, and as a result serious international comparisons are harder than they need to be. There will be some new IMF WEO estimates for New Zealand in October, but they are likely to emerge just a couple of days before the end of our election and won’t be able to inform discussion/debate of the fiscal situation. But Treasury could have produced their numbers in IMF and OECD formats.

This has been something of a background post with little data and just one chart. Tomorrow I will do a post looking at some of these better measures (NZ specific and internationally comparable) across time and across countries (OECD and IMF advanced economies) to put some light on how things stand right now, and have evolved in recent years. PREFU will then give us some more – apparently gloomier (although how much of that will be judged cyclical?) – data next week.

Making the PREFU more useful

Anyone with even a vague interest in matters fiscal (or those with little real interest but some responsibility) is now awaiting next Tuesday’s pre-election fiscal update (PREFU).

PREFU is a good to have, and much better than nothing, but could be made quite a bit more useful and relevant for what must be presumed to be its ultimate purpose, informing the pre-election debate around matters fiscal. The current law governing PREFU is a single (full page) clause in the Public Finance Act.

For a start, it should probably be moved a week or two earlier. The law requires as follows

The Minister must, not earlier than 30 working days, nor later than 20 working days, before the day appointed as polling day in relation to any general election of members of the House of Representatives, arrange to be published a pre-election economic and fiscal update prepared by the Treasury.

which would be fine if we thought of polling day as 14 October. 12 September (next Tuesday) is more a month before that. But since that law was passed, advance voting has, for good or ill (I think mostly ill), come to make up a very large share of votes cast, and advance voting opens less than 3 weeks after the PREFU will be brought down. Changing the law to require the PREFU to be published 20-25 working days before polling opens would seem consistent with the spirit of the original legislation now that voting arrangements/patterns have changed so markedly.

Obviously there are trade-offs. There are significant lags involved in bringing the Treasury EFUs together, but the point of the exercise is to inform voters and enable scrutiny, debate, and challenge, including around political parties’ programmes in response to the PREFU numbers (this is mainly an issue for Opposition parties, as the governing party not only has the advance information from Treasury but can ensure some of its policy stance is included in the PREFU numbers themselves, when communicated to Treasury as government policy (eg stance of future operating allowances)). Note that the PREFU is not, and cannot realistically be counted on as, the “opening of the books” for an incoming government, because in unsettled times numbers can move about quite a bit even in the period between PREFU numbers being finalised and a new government taking office (this was an issue in 2008 for example).

PREFUs look a lot like the Budget and Half-Yearly economic and fiscal updates (BEFUs and HYEFUs) – here is the link to 2020’s and here is 2017’s (one prepared in more settled times) That is encouraged by law, since the things Treasury has to cover in each of these documents is the same. In respect of the economic forecasts, that is probably fine: after all, forecasts of the overall economy are just that: forecasts. A myriad of private choices, here and abroad, and the cyclical stabilisation activities of central banks, will influence outcomes, but mostly those outcomes are beyond the government’s (or Treasury’s) control. The economic outlook is a backdrop for fiscal numbers and, perhaps, fiscal policy.

I’m sure there will be some gotcha-type focus next week on some of the macro numbers. Will, or won’t, Q2 be shown as having experienced positive GDP growth. Given (a) the long lag on Treasury’s numbers, and b) that the actual official SNZ estimate is out the following week, much of that might be good fun but largely pointless. Same probably goes for their view on near-term inflation (if you could ask the Treasury forecasters next Tuesday their best guess of Q3 inflation it would almost certainly be different by then to what will be in the document they publish that day). That’s inevitable.

The real focus is, or should be, on the fiscal situation, which one or other party will be directly responsible for in a few weeks’ time (and one party is of course responsible now).

The operative bit is 26U(2) above. Hence, the government’s fiscal announcements last Monday, trimming future operating allowances etc, in ways quantifiable enough to be included by Treasury in the fiscal forecasts we will see next week. The Minister of Finance could, if s/he were sufficiently cynical, set the future operating allowances to zero and Treasury would have to include that “government policy” in its PREFU fiscal forecasts. The Secretary to the Treasury does not have any leeway to forecast how that policy might actually play out over several years. It is her legal responsibility simply to ensure that the forecasts accurately reflect the policy the Minister has communicated to her.

In the normal EFUs there is somewhat more restraint on Ministers of Finance. You could communicate to The Treasury low operating allowance numbers for this EFU but….you will still be minister in a year or two’s time and will be accountable for the eventual numbers. It isn’t perhaps much of a restraint – forward fiscal paths often have a “line on a graph” quality to them (with no specifics as to how these numbers will be delivered) – but it is something. In a pre-election EFU, no one is accountable for anything really (well, the Secretary is, but for faithfully representing government policy in the tables).

In the 2020 PREFU there was a bit of sensitivity analysis published – we were in the midst of pretty extreme Covid uncertainty at the time – but more normally there appears to be little or none (check again 2017’s and you will find none re the fiscal position itself, only (buried deep in supporting documents) on the cyclical adjustment estimates).

My focus here is not so much on the uncertainties of this year’s tax take. They are no doubt real, but economic cycles ebb and flow. Fiscal analysis really should focus mostly on cyclically-adjusted concepts and numbers.

But what we don’t get from Treasury in the PREFU documents – or anywhere else (other perhaps than in the periodic long-term fiscal report, which isn’t focused on the next 2-4 years) – is any sense of the state or implications of the cost pressures that will be difficult for any party in government to avoid. Political parties can and should debate what programmes should be provided and what not. Treasury can’t offer any particular insight on those debates. But it can, and should, be offering some sense of the spending implications of projected population growth, projected inflation, projected private sector real wage growth, and so on. If the past is any guide, next week’s PREFU will show us none of that. The revenue implications will be taken into account but, except where the law requires indexation (for example), not the expenditure implications. Unless conscious and deliberate other choices are made, those sources of pressure will increase government spending over time. But Ministers of Finance are simply free to give the Secretary to the Treasury a path for future operating allowances which need not bear any relationship to, or be based on any analysis of, largely inescapable cost pressures.

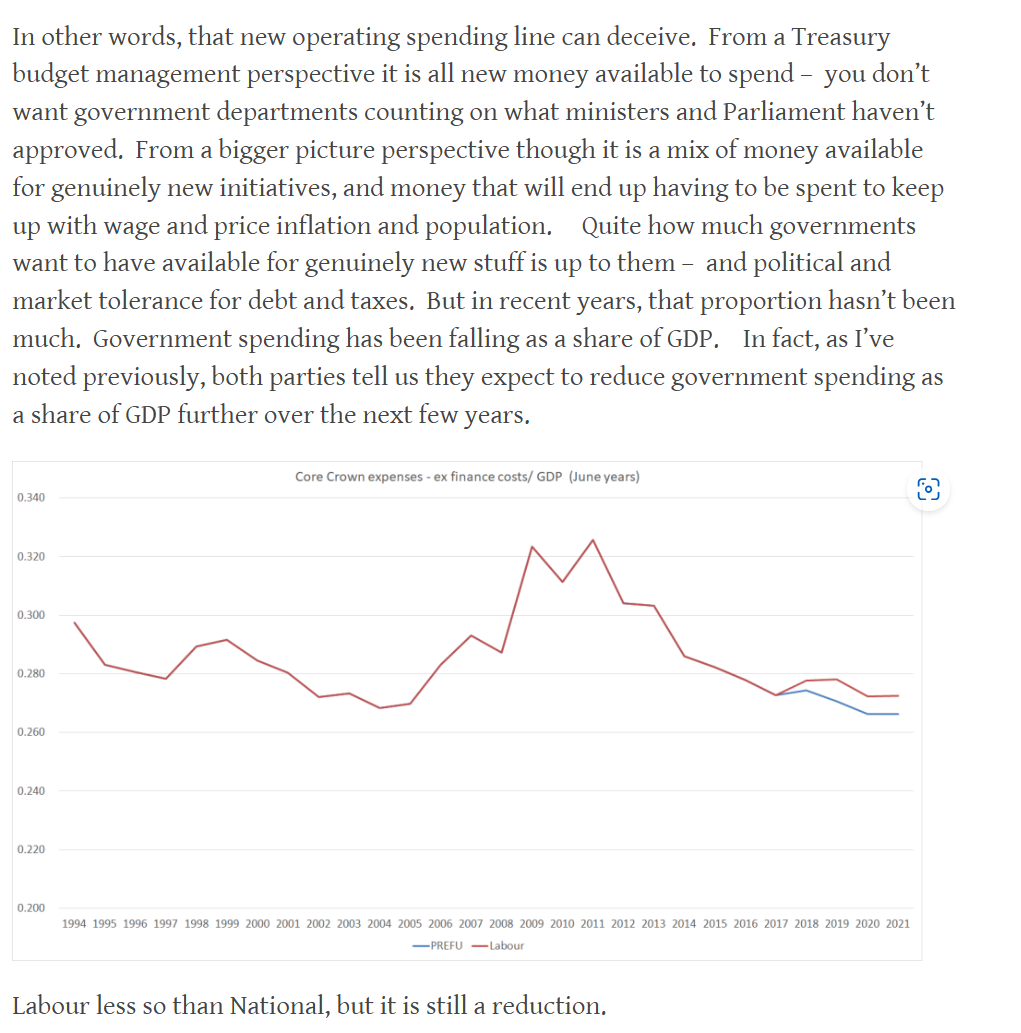
This might be seen primarily as a dig at the current government. It isn’t. In 2017 there was a huge political and analyst debate about alleged Labour “fiscal hole”. Many of the claims proved to be overblown but the “largely inescapable cost pressures” point was very real. At the time, and at the prompting of several former senior Treasury officials, I wrote a post on exactly that issue. By that time we had both the PREFU (reflecting incumbent government’s plans and operating allowances) and the then Opposition’s own fiscal plans (at present we have numbers from neither side). This text and chart was from that post

and after I’d worked through various detailed numbers around forecast influences that would boost costs

Neither side told us how they envisaged reducing government spending as a share of GDP. In a mechanical sense (PREFU and Labour’s parallel) they added up, but in substance they didn’t. Some related points were also in this post.

I expect that in next week’s PREFU there will be an operating surplus shown at some point in the relevant horizon (perhaps a year later than was suggested in the Budget). Quite probably – given that National seems to have no interest in an aggressive fiscal consolidation – that will suit both parties, but in both cases it will avoid the hard discussions around the choices that will bring about such surpluses. Countries don’t get from cyclically-adjusted deficits to surpluses by magic – or by simply drawing a line on a graph. Both sides are already guilty of “line on graphism” with what are no more than assumptions about savings that might be made without addressing programmes or choices that would make such savings sustainable.

It isn’t that medium-term fiscal projections are always useless. Sometimes legislation will already have been passed that will come into effect only gradually, and we want to be able to see the implications of those legislated commitments. But that really isn’t much of an issue at present. And absent such slowly unfolding adjustments it really means that almost no attention should be paid to any fiscal deficit numbers in PREFU beyond the current financial year: this year’s Budget has been passed and what is authorised isn’t vapourware. But what parties tell us vaguely they might do in future (and both are guilty) isn’t really worth much at all.

I ended that 2017 post with this suggestion

I stand by that call. I’m quite confident there has been a lot of very low quality spending in recent years, but I also suspect that the things governments need to spend money on are benefiting temporarily from the big surprise inflation. I’ve made the point here that teachers were more or less forced to accept a real wage cut, and a big cut relative to private sector wage developments. Recruitment and retention challenges are, shall we say, not unknown in the sector, and if we care at all about a high quality education sector then over time (and whatever else needs sorting out) we will need to pay accordingly. The senior doctors dispute seems to have similar characteristics. But how large and pervasive are these effects across the board? Treasury is best-placed to know, and to tell us. If the amounts are material then whatever savings can be made from genuine bloat might not reduce deficits at all but just end up having to be spent to be able to maintain or secure high quality core services. Treasury is obliged to publish a lot, but it could publish more and more useful standardised information along these lines.

Policy costings: a case study

I’ve written a few posts here over the years about the idea – which apparently Labour, National, and the Greens are now keen on – of a state established and funded policy costings unit. The most recent two were a month ago, here and here. I’m a longstanding sceptic of the case for such a unit, seeing it is just a way to get more state funding for political parties, and not dealing with any of the common arguments made for such units.

It is election season now and some of the arguments have, in effect, been put to the test. This week National released its tax and spending plan, producing numbers suggesting that what they planned to spend was fully funded by other cuts and new taxes. I wrote here about the macro issues and implications of/around the plan, largely taking as given the specific numbers the party supplied.

I’m not close enough to any of the line by line numbers to know whether each of them is solidly costed. Their economic consultants say they have been, and (assuming there were no silly mistakes made by accident) National does have a pretty strong incentive to ensure the numbers are each reasonably robust. So, for now, I’ll assume they are (with a few possible caveats about the foreign buyers tax, see below).

[and, later, on that tax]

…As for the revenue estimates ($750 million a year), they seem quite high, and the tax rate seems high by most international standards (Singapore is a lot higher). Only time will tell how many people not living here so want a New Zealand house they will pay a 15 per cent tax to do so.

Individual costings really weren’t and, as macroeconomic commentator, still aren’t my focus. In the grand scheme of things, the overall package involves adjustments of less than 1 per cent of GDP per annum, most costings don’t seem to have been contested, and in an age of MMP even a big party’s plans are likely to be implemented a bit differently than the pre-election promises. The foreign property buyers tax itself is expected to raise revenue equal to 0.2 per cent of annual GDP (and the gambling tax about 0.05 per cent of annual GDP).

But both as a potential voter and as someone interested in institutional proposals, notably that for policy costings offices, the subsequent debate has been interesting. I don’t really understand the issues around the online gambling costings (and the amounts involved are much smaller) so I’m going to focus on the foreign buyer tax. On that score there seem to be two quite separable concerns raised:

  • first, how consistent is the proposed tax with various tax and trade treaties New Zealand has signed? and
  • second, even if the tax were able to be put into effect as National tells us it envisages it (excluding buyers from Australia and Singapore, as with the current outright ban), just how much revenue would the tax be likely to raise year in year out?

Of course, the more there are issues under the first leg, the more questions could legitimately be raised about the revenue estimates.

Based on what they have told us, in the lead up to the announcement National did what one might have expected from a party seeking to win the right to lead the government after the election.  It hired a firm of advisers (Castalia) and asked them to review the draft numbers.   From what National has said (and I recall one media outlet being shown Castalia’s comments), National went with numbers that were generally at the conservative and cautious end of the spectrum.   Castalia apparently also cast a fresh eye over the numbers in light of the government’s fiscal announcements last Monday (although this is unlikely to have meant much since how much baseline spending can be saved – by either party –  isn’t really something a consultant can tell you, since it is mostly about the resolve of the politicians’ themselves once in office). 

In addition to having consultants review modelling numbers, the National document told us they’d sought legal advice

National has sought legal advice on whether the replacement of the foreign buyer ban with a foreign buyer tax is consistent with New Zealand’s existing free trade agreements – that advice confirms such a replacement would be consistent with those agreements. However, this policy assumes Australian and Singaporean citizens will not be affected by the tax as they are not currently affected by the foreign buyer ban.

and a Newshub article yesterday reported that National had sought both legal and tax advice on these issues.

Image

So far and mostly so good.  We don’t just have National’s word for the numbers, but an established firm –  yes, paid for by National, but with an ongoing reputation to guard – is reported as telling us they thought the numbers overall had been cautious and conservative.

But then the questions arose. First, around the legality of imposing such a tax on various countries.  Some of the points were from Labour Party spokespeople (eg this press statement).   They are the political opposition so we might have no more particular reason to take their claims on trust than to take National’s on trust, but they do make some specific points, which to a lay voter seem like questions deserving an answer.  In fact, there might be both legal questions and questions about whether the proposed tax is within the spirit of agreements that New Zealand governments have voluntarily entered into (and which National is not on record as having opposed, or is now proposing to withdraw from).   (Non-specialists among us might also wonder why if absolute bans –  the ultimate in discrimination – mostly are legally okay (we now have one), a tax which would be less onerous would not.)   As National notes, some other jurisdictions have such taxes, but the issues here isn’t one of merits, but what specific New Zealand agreements do and don’t allow (and noting that New South Wales appears to have recently withdrawn its version of such a tax because of federal tax treaty issues).

And then questions arose around the modelling (ie even if the law could be done as National had suggested whether it would raise $750 million or so year in year out).   Various economists and property analysts (people without apparent strong party loyalties that might make their perspectives suspect) raised doubts.  On the property experts side this article from today’s Post seems representative.

tax doubts

There are, of course, some enthusiastic real estate agents.  I read an article reporting one agent saying he’d had US billionaire clients on the phone within hours.  I don’t doubt there would be interest: the question is how much, and how much beyond the first wave (a quick Google suggests there only 2700 billionaires in the world).
Without seeing National’s modelling, it isn’t really possible to reach a confident view on their numbers.  But what makes me cautious is that I’ve seen no one –  neutral expert or even National surrogate arguing that the numbers are really on the cautious side and a more realistic assessment might be higher again.  It seems hard to find revenue estimates for other countries’ foreign buyer taxes –  often they are designed to deter purchases rather than to raise revenue – although I found a reference yesterday suggesting that a similar tax in Toronto (a metropolitan area with more people than New Zealand) was raising only about $200m per annum.

So wouldn’t this have been a clear case for a policy costings office?   I don’t think so.

National has used its (scarce) resources to pay for analysis and advice and has told as much as it seems to want to tell us.  Debate and scrutiny has ensued.   As a geeky analyst and undecided potential voter I’d really like them to release their modelling and any Castalia comments on it, and either the advice or a fairly full summary of the advice from the “legal and tax experts”.   It would be good even if they had some known National-sympathising experts who they could wheel out to make the case for (a) the legal problems not being what some suggest they might be, and b) the robustness of the numbers  (I don’t really expect Willis or their Revenue spokesperson to spending lots of time in public debate in the middle of a campaign).

But here’s the thing. It is their choice what to release (or not), and our choice as voters to draw our own conclusions.    Elections are most unlikely to turn on a specific like this, which is ultimately fairly small in the scheme of things (eg against the backdrop of some of the largest primary fiscal deficits of any advanced country at present, 0.2 per cent of revenue isn’t nothing but it is almost lost in the rounding – and is less than the non-specific proposed bureaucracy savings).  For some people and at the margin, it may shake confidence.    Go back to that quote from my post earlier in the week:   my starting point was to think that National had strong incentives to make sure that their numbers were robust, so as a starting point I took them as given.  Now that questions (apparently serious questions) having been raised, they have chosen not to release anything more or to address the specific concerns.    It is a legitimate choice (they are free to make it), but I (and the handful of interested analysts and potential voters) can draw my own conclusions. For me, I’m less confident now that the numbers add up, and also less confident than I might have hoped in their commitment towards being an open and transparent party in government.  It reinforces my wider doubts about their overall fiscal stance.

And that seems to be the political market working.  Parties will make choices about what they think a sufficient number of voters care about, or even about what sufficiently vocal commentators might shape public thinking over.  It is very unlikely that details of this tax score highly on either count.   Is that a bad thing?   I don’t really think so.    Voters are making judgements about values, about competence, about desires (or lack of them) for change.   And frankly, if fiscal issues were to become an issue, such concerns should probably centre on things individually more important than details of this tax.   The merits of unprincipled tax policies (this foreign buyers’ tax, Labour’s proposed GST exemptions, or the distortionary new depreciation provisions both parties have individually proposed to foist on the business sector) for example should probably count for more.  Or the sheer size of deficits  – without precedent in New Zealand now for many decades on the eve of an election.  But in the end, voters and parties will make their own choices, and nothing this week suggests to me that we’d have been better with some state-funded tax and trade lawyers and economist adding to the mix.  Precise numbers almost certainly do, and in my view probably should, matter less than what we learn about parties and their spokespeople in how they handle issues like this.

National’s tax and spending plan

National announced its tax and spending plans this morning. You can read the full 29 page document.

In the way of all parties and bureaucratic agencies these days, everything gets quoted as a four year figure: $14.7 billion sounds like a lot but it about $3.7 billion a year, which is about 0.8 per cent of annual GDP. Cost things over 10 years and you could if you wanted call it a $35 billion plan, with no more or less meaning (and, to be clear, all parties and agencies engage in this headline-inflating exercise).

Today’s plan is sold as being fully separable from National’s fiscal plan, which we will apparently get to see after they’ve had time to digest the PREFU numbers (coming on 12 September). It is a clever wheeze – it seemed to work – in allowing Willis and Luxon to deflect all and any questions this morning regarding the deficit and the possible/eventual/one day return to budget operating balance or surplus. They sold this line on the basis that today’s package was itself fully-funded from new initiatives of one form or another, so that in principle the net impact on what fiscal numbers The Treasury comes up with this package could just be slotted in with no net fiscal effect.

I’m not close enough to any of the line by line numbers to know whether each of them is solidly costed. Their economic consultants say they have been, and (assuming there were no silly mistakes made by accident) National does have a pretty strong incentive to ensure the numbers are each reasonably robust. So, for now, I’ll assume they are (with a few possible caveats about the foreign buyers tax, see below).

But the overall argument – “this isn’t our fiscal plan, come back next month for that” – doesn’t really wash. It might if the budget now was pretty near balance, or even in surplus. No one would, or perhaps should, be very worried about modest changes in a comfortable fiscal position.

But we don’t have a comfortable fiscal position.

These were the fiscal numbers the International Monetary Fund put out yesterday in their annual New Zealand review

The blue numbers are more or less solid (actual fiscals are, but the cyclical adjustments could still change a bit), while the red numbers – calendar 2023 and 2024 – are going to be heavily influenced by choices and decisions the government has already made. The best advice from the IMF is that no progress has been made in reducing the deficits first run up in the Covid disruption years, even though actual Covid spending is no longer a thing. The Fund includes projections for the further-out years in which the operating balance goes back to respectable surplus for calendar 2027 and 2028, but those are really just assumptions, and don’t rely on specific identifiable tax or spending decisions that would bring about such an adjustment. I should stress that these are cyclically-adjusted numbers, so the ebbs and flows of the economic cycle don’t provide either the problem or the solution. These sorts of numbers led to the IMF recommending – in really quite pointed language for a diplomatic agency talking of a country that has been among the star fiscal performers for decades – “frontloaded fiscal consolidation” and steps to ease the fiscal pressure on monetary policy.

(The government’s control of the timing of the release of the IMF report, kicked to after Monday’s modest fiscal announcement, means these sorts of lines have had almost no media coverage. And of course no one seems to have gone and asked the Governor “what is this fiscal pressure on monetary policy/inflation the IMF talks about; you have claimed in the last two MPSs that there was none?”)

Last week I ran a post here using the OECD’s fiscal numbers. Those numbers will have been finalised a bit earlier than the IMF’s but are available on a consistent cross-country basis. Using that data you can see how large our (cyclically-adjusted) general government deficits now are relative to other OECD countries (and to our own past). The picture of recent years is a little different, but the final year deficit is also large.

Or here (not cyclically-adjusted)

We have a primary deficit that is large in absolute terms, and among the largest in the OECD.

These international comparisons aren’t done on the New Zealand operating balance definition. On that metric, the cyclically-adjusted operating deficit will be a smaller percentage of GDP, but there is little case for a cyclically-adjusted operating deficit (paying for the groceries etc) at all.

These structural deficits do not heal themselves. And while fiscal drag has been a bit of a help in limiting the deterioration in recent years, the forecast return to lower inflation means not even much of that support will be on offer.

Both Labour and National profess allegiance to the idea of an operating surplus…….but seem to have not the remotest interest in telling us what choices they are going to make to get us there. Discretionary choices/adjustments of perhaps 3 per cent of annual GDP might be required.

Today, however, is National’s day. This was their big tax and spending plan. Willis told reporters this morning that “your tax cuts are coming no matter how much Labour proves to have wrecked the joint”. So the tax cuts are iron-clad, and having bitten the bullet – after railing at Labour’s new taxes for years – and put several new tax increases on the table, it is hard to see they are suddenly going to pull a whole bunch more tax increases from their hat a couple of weeks hence to close the deficit.

It is always possible, they could announce some big new expenditure cut – killing off a few big wasteful specific programmes – but it doesn’t really seem in character, and would completely blunt the message from today that “tax cuts are coming”.

It is much more likely that – having announced their big tax and spending plan today – that is largely it. It may be fiscally neutral in its own right, which is better than the alternative of adding to the deficit, but they aren’t going to do anything much about the deficit at all. No doubt Labour won’t either – it will just handwave around whatever the PREFU shows, having cut (with no accountability whatever re eg likely cost pressures) future operating allowances on Monday. It will be a case of “trust us”, without even any credible evidence from either that ‘we know what we are doing” or really care one way or the other. We are at risk of sliding towards the normalisation of operating deficits, of borrowing to pay the grocery bill. The sort of really poor fiscal management you see in places like the United States federal government.

If asked, perhaps National will talk up cutting public sector bloat. I’m sure there is a fair amount to go round (and no one has mentioned the big increase in Reserve Bank spending that the government snuck out last week), but (a) in this morning’s announcement they ruled out a whole bunch of agencies, both because of Labour’s own vapourware announcements on Monday, and because they want any savings redirected to frontline services those agencies provide. That latter might be laudable but it doesn’t represent fiscal savings.

And, in any case, today’s package already relies on unspecific cuts in public sector bloat.

That is $4bn of the $14.6 billion cost of the overall package (30 per cent). I’m not disputing that there are (substantial) savings to be made, but savings made to finance tax cuts (as in this morning’s package) can’t then be used to also close the deficit. Both Labour and National talk of cutting consultant spend. That is cheap talk, unless (a) it amounts to a reduction in total spend, not just taking people onto the permanent staff (shifting the line item, but not changing the total, and b) identifying what work future governments don’t want done.

To the extent there is genuine bloat, the tax cuts package will have grabbed it. To cut further – cut the deficit – they would need to cut deeper and that would mean harder choices, which so far they’ve shown no inclination to be willing to make (nor Labour, but this is National’s day). And all this assumes that cost pressures are adequately captured in current baselines (which I doubt – citing for example the real wage cut forced on teachers despite apparently very real recruitment and retention challenges).

Finally a few thoughts on specific items. Childcare subsidies aren’t really my thing (better to collapse house prices), but both parties seem to like them. I like them cutting back the brightline test tax (less good than abolishing it, but…) and the restoration of interest deductibility for residential rental property owners (like any normal business). On the other hand, there is no commitment to inflation indexing income tax brackets even going forward (if they’d committed they’d have to have costed it).

But what got my goat were the first two of the new taxes.

Is it marginally better to have no ban on foreign buyers buying very expensive houses but having to pay a high tax to do so than to have an absolute ban? I might grudging acknowledge that, but any gain is marginal at best, and it is a policy that David Parker might have dreamed up in a moderate moment. It is an unprincipled revenue grab, which is wildly inconsistent with the party’s rhetoric (mostly good rhetoric) that freeing up the responsiveness of housing supply is what matters, and that we should be encouraging and facilitating more foreign investment generally. And from a party which claims to be – and historically has been – keen on immigration, it just seems weird (conflicting messages) again to not be allowing anyone who moves here, even on a work visa for several years, to buy a house. They are all over the place with barely a hint of philosophical consistency. It is all made more weird by this line from their document in which they seem to argue that their foreign buyer tax policy will itself somehow dampen property price growth.

As for the revenue estimates ($750 million a year), they seem quite high, and the tax rate seems high by most international standards (Singapore is a lot higher). Only time will tell how many people not living here so want a New Zealand house they will pay a 15 per cent tax to do so.

And then there was the other unprincipled revenue grab, the removal of tax depreciation for non-residential buildings. This measure – which increases the tax rate on businesses – was first introduced by National in 2010 to help fund that tax switch package, with no credible or rigorous underpinnings at all. Buildings depreciate (land doesn’t). In 2020 Labour restored this depreciation provision, and was supported in doing so by their own Tax Working Group. And now both Labour and National are campaigning on getting rid of it again, with no more rationale than that they need revenue (and no doubt tax depreciation provisions won’t show up in the focus groups). The intellectual bankruptcy behind this is evident in National’s document

No rationale at all beyond claiming it was a “tax break”. They rightly pushed back when Labour called interest-deductibility a tax break – it wasn’t, business operating expenses are generally deductible – and depreciation is no different. (Arguably, simply calling it a tax break is no worse than Labour pretending the 2020 change as a temporary Covid stimulus measure when they were quite clear at the time it was permanent, but…..it is a close call. Our political parties………)

Finally just a fairly small technical point. Willis claimed this morning that the National package would not add to inflation pressures. The justification for this claim is that the package is fiscally neutral. That isn’t necessarily sufficient for there to be no net demand impact. For example, the tax cuts etc are skewed towards people who probably have a very high marginal propensity to consume, and the revenue sources probably less so. Perhaps more important, and as someone pointed out over lunch, 20 per cent of the revenue is coming from the foreign buyers tax. Since the higher end, most lucrative, foreign buyers – some billionaire wanting a luxury mansion – mostly won’t be paying the tax out of New Zealand income that additional tax revenue may not represent any diminution of demand in New Zealand. These are small points – the whole (funded) package is less than 1 per cent of GDP – but all else equal I would expect it to be slightly stimulatory. Those compiling Treasury’s fiscal impulse measure might think the same.

The IMF probably wouldn’t think it was a step in the right direction. Perhaps the same will be able to be said for Labour’s plans as they unfold?

UPDATE: On the fiscal impulse issue, the removal of the regional petrol tax in Auckland has the potential to be net stimulatory, at least for a time, as the Auckland local authorities had to wind down projects or identify alternative revenue sources. Re the foreign buyers tax, there may be an incidence question (purchasers of mansions may be able to push the tax incidence back onto vendors, but probably not purchasers of $2.1 million houses in Roseneath or Epsom (where there would normally be more potential domestic purchasers)). In any case, I think most estimates of spending from capital gains – by fairly well-off vendors- probably assume a lower MPC than spending from income.

Does any political party care?

I had to check up a specific productivity number this morning and noticed that it had got to the time of year when the OECD finally has a complete set of real GDP per hour worked (labour productivity) data for 2022. Data for 2020 and 2021 had been messed around by Covid disruptions, and measurement challenges around them, but if the illness was still around in 2022 the direct disruptions mostly weren’t.

Anyway, here is how the chart of labour productivity levels looks across countries

If you want, you could ignore the countries at the very top (notably Ireland, where the data are badly messed up by international tax distortions) and the Latin American OECD diversity hires at the very bottom. But it is not an encouraging picture for New Zealand.

Last year, the Secretary to the Treasury commented on some measurement work that Treasury and SNZ had been doing that suggested, on plausible grounds, that our hours worked numbers may overstating how they would look on a properly internationally comparable basis. She suggested that if such an adjustment was made – and it was for a variety of other countries last decade – it could lift GDP per hour worked by up to perhaps 10 per cent (wouldn’t change GDP per capita or wage rates of course). If we were to add 10 per cent to the New Zealand number in the chart above we’d be around where Slovakia, Slovenia, Japan and Israel are now.

But if there is something to that point – and there appears to be – any such adjustment would affect all the historical data as well, so that the growth rates over time won’t be materially affected, or (thus) comparisons of how New Zealand has or has not dropped down the OECD league tables.

A little arbitrarily, I wondered how New Zealand had done on that count over the last 10 years. Ten years is a nice round number, but it also happens to encompass a period half governed by Labour and half by National

Here I’ve shown the (ranked top to bottom) levels of real GDP for 2012 and 2022, and in the final column I’ve identified where a country has changed by more than two rankings over that decade.

Most of the material movements are in the bottom half of the table. There are some stellar performers, most notably Turkey and Poland. And there are some really really mediocre ones: Portugal and our own New Zealand. We’ve dropped six ranking places in a club of only 37 members in just a decade. It took me a little bit by surprise, and I think partly because the New Zealand debate (such as it is) rarely focuses on the countries that are now most similar to us in productivity terms.

Just as context, I then dug out the numbers for 2000. As it happens, the New Zealand ranking in 2012 was exactly the same as it had been in 2000. It is over the last decade that the decline down the OECD league tables has resumed.

Productivity growth is, ultimately, the basis for so much that people want for themselves and from their governments. “Productivity” isn’t the language of the focus groups or polls that seem to drive our politicians these days, but it is a critical New Zealand failing. We aren’t getting poorer in absolute terms, but we drift behind more and more advanced countries in the wages we can support, in the public services we can offer our citizens, in the private goods people can afford to purchase and enjoy.
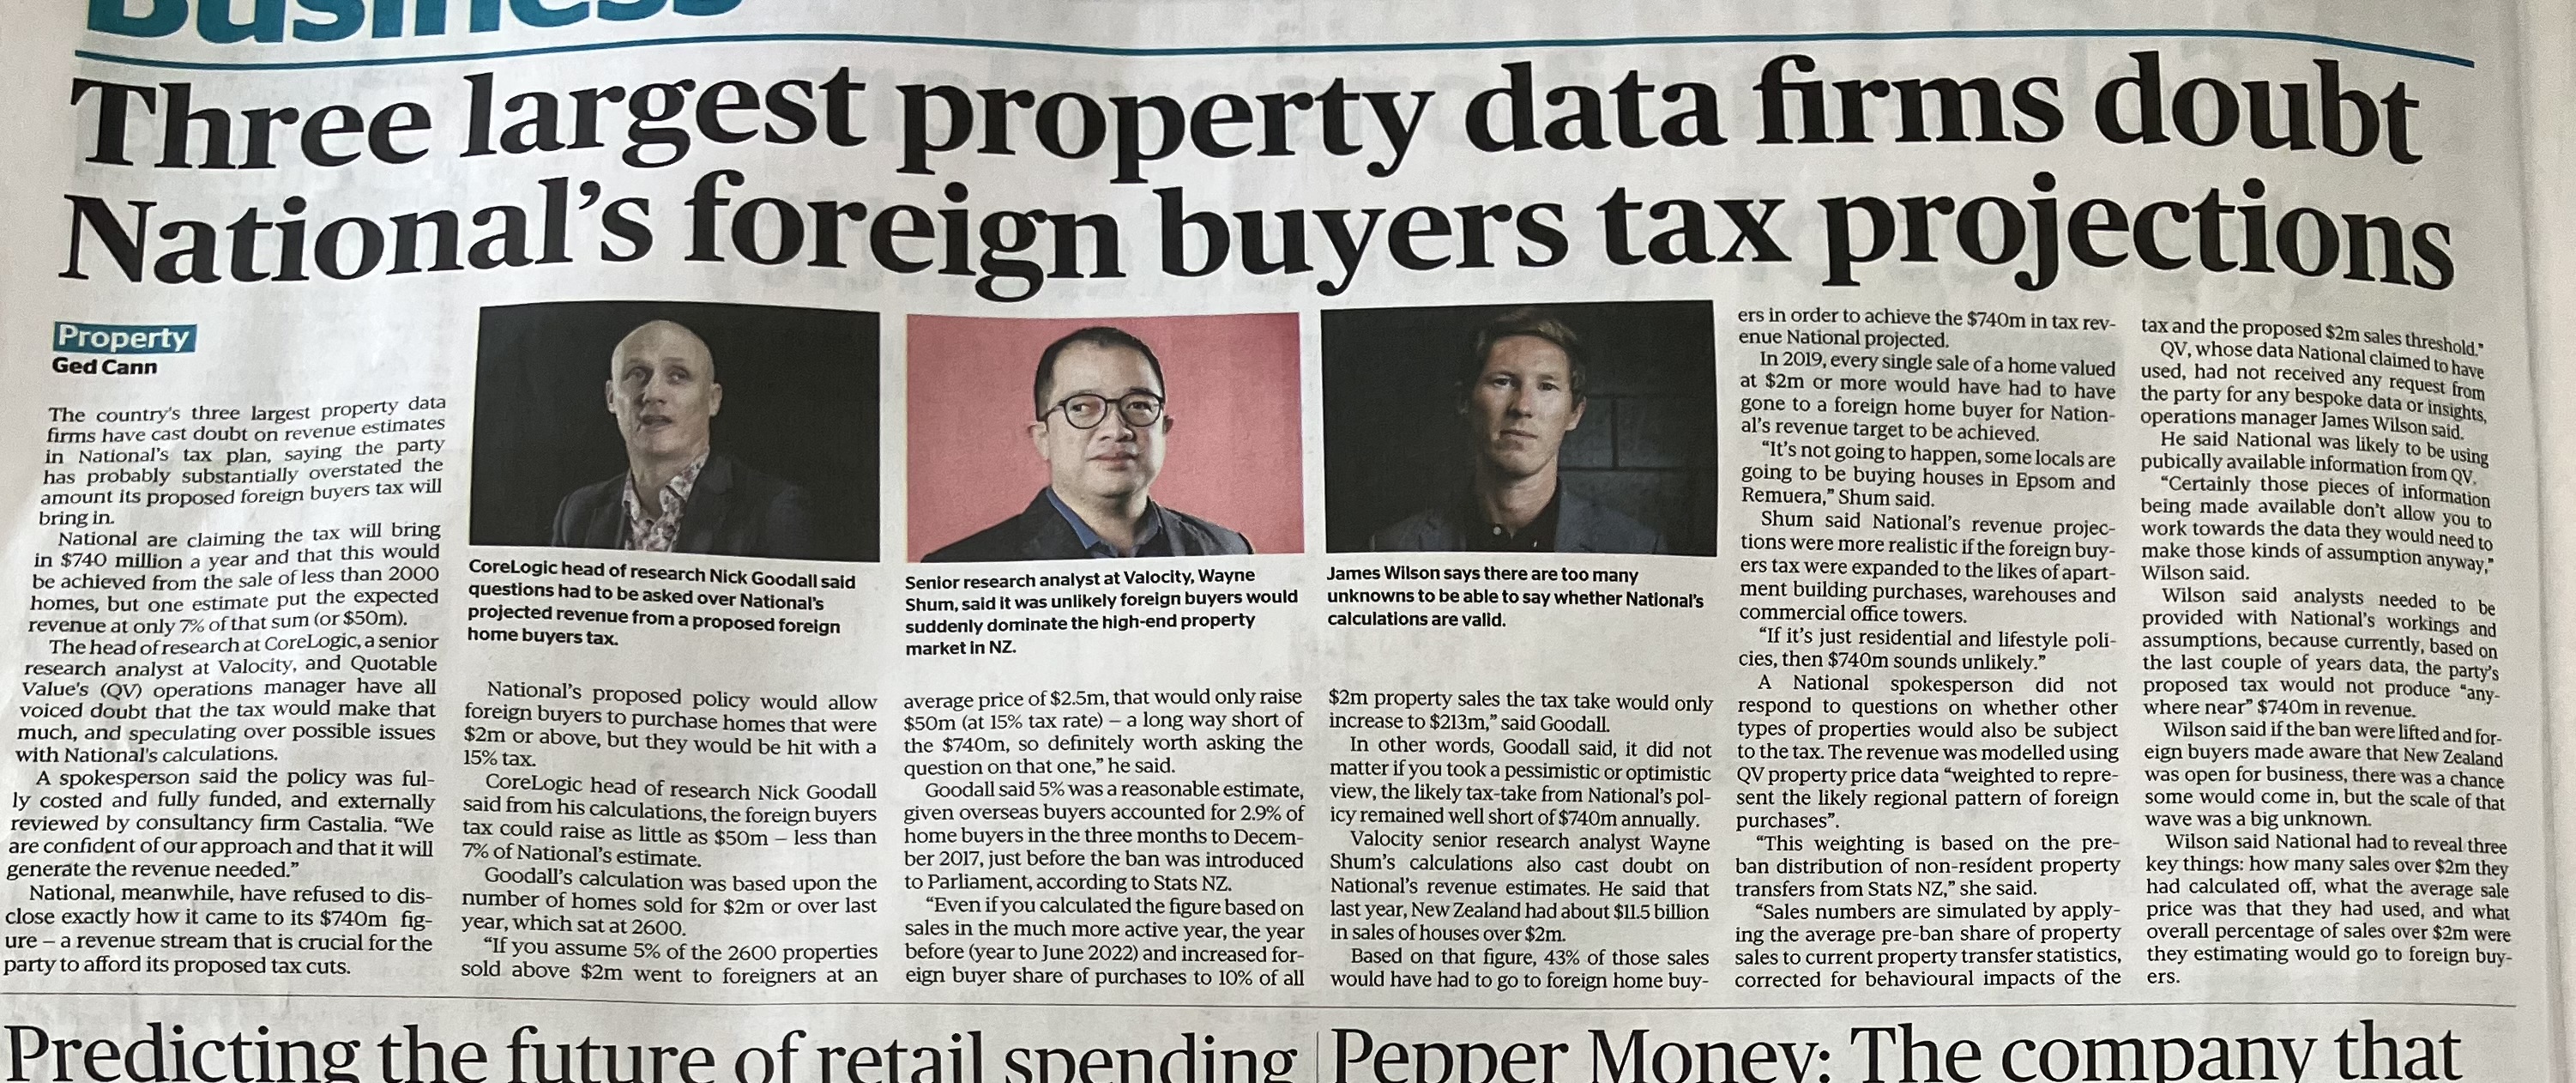
But there is no sign that either of our major parties (well, or the minor parties) care, or have any ideas, any credible narrative, to reverse our economic decline. It is followership at its worst: competing in the race of “I am [aspire to be] their leader; I must see where they are going and follow them”. Real leadership would be something quite different than just rearranging the deck chairs, competing as to who can offer the best handouts.
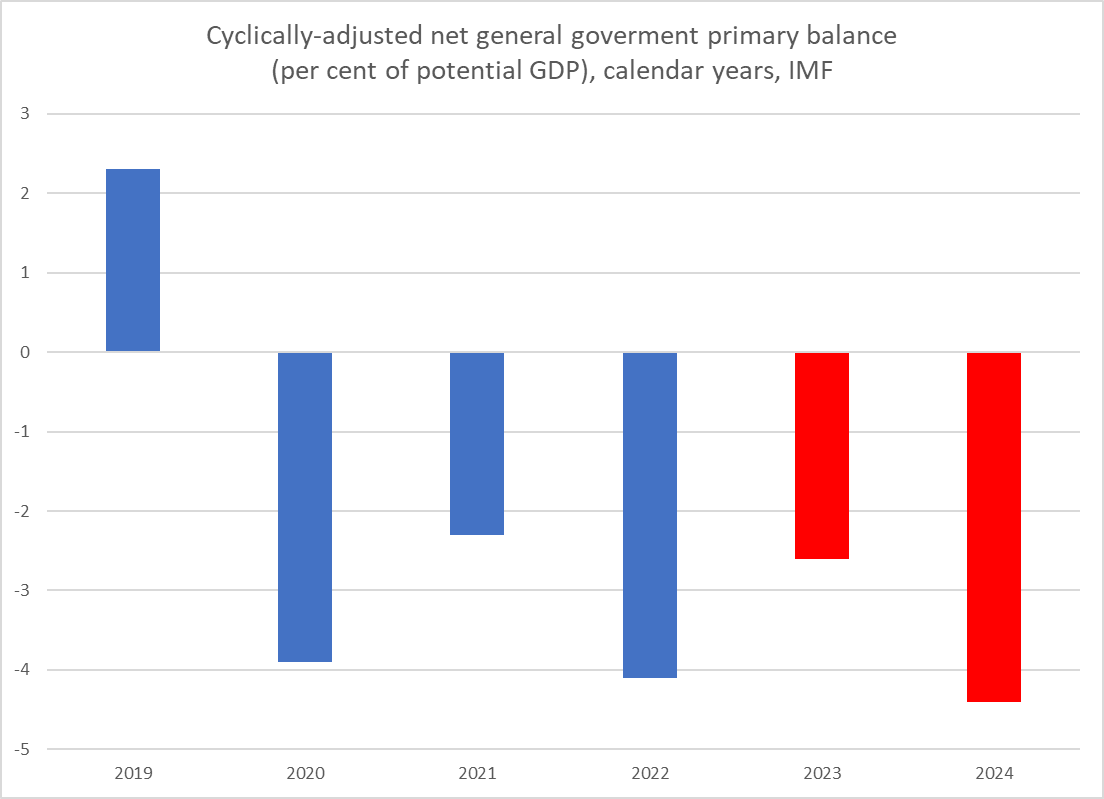
I’m occasionally inclined to defend our politicians on the basis that our economic agencies don’t have much to offer them, but (a) those agencies have been degraded by much the same sort of politicians (in some cases, one lot did it, and the other lot keep quiet), and (b) real leadership seeks out, draws out, invites, examines, tests, scrutinises ideas and evidence, drawing around him or her advisers who could inform a better way, that a leader might champion, persuade and so on.

But neither Hipkins nor Luxon – or most of either’s predecessors – seem cut from that sort of cloth, perhaps not even interested or aware of what they don’t do or offer. Both seem content to preside over drift, just so long as they and their mates get to hold office rather than the other lot.

But we haven’t had a three year negative output gap

One of the great things about being a prominent organisation that releases complex material to select media under embargo is that you can get uncontested coverage in the first (and probably only) news cycle. Adrian Orr will have been glad of that when it came to the embargoed release yesterday (the public only got to see it at 5:43 this morning) of the IMF’s Article IV report, and in particular the short (600 words) annex on the fiscal implications of the Reserve Bank’s LSAP programme – the one on which the Reserve Bank has so far lost $11bn.

It was 10 days or so ago that we first heard that some such paper was coming. The Governor was being interviewed by the Herald‘s Madison Reidy after the Monetary Policy Statement. She asked Orr about the LSAP losses and noted in contrast the fiscal costs of the storms/cyclone this year. In his usual effusive style he responded that the LSAP itself had already more than paid for the cyclone recovery costs, moving on to suggest that only accountants could think otherwise “who know the cost of everything and the value of nothing”. He then went to say that the IMF had a paper, which he hoped would be published, showing that the LSAP had actually improved the government’s finances, and that it would offer the “proper story” not some “piecemeal accounting story”.

That caught my eye. Knowing that the IMF Article IV report was due before long, I wondered if they’d have a Selected Issues paper on the topic. These are supplementary research pieces, usually 15-20 pages or so, undertaken by Fund staff (often on topics requested by the authorities) as part of the Article IV review process. The latest two such papers are here.

But it proved not. Instead, we got only a little annex on the topic (600 words and two pictures) on pages 64-66 of the main report. The “proper story” it certainly isn’t – and in fairness to the Fund, as distinct from the Governor, it doesn’t really purport to be. What it is is a little exercise by a few researchers (not working specifically on New Zealand) using a model, as yet unpublished, that they have developed for work on central bank exit strategies, showing that on certain assumptions something like the LSAP could end up producing net fiscal benefits. Surprise, surprise. Of course. It could. The question really is about the realism of the assumptions etc.

Orr, and probably the Fund, will have been pretty happy with the Herald‘s coverage this morning, under the headline “Reserve Bank’s money-printing buoyed Govt books, says IMF” (well except that – rightly – the Governor and IMF would disavow the suggestion that the LSAP was “money-printing”: it was just an enormous asset swap). The results could be read as backing the Governor’s claim – a year ago in an interview with the same journalist – that the benefits to the economy had been “multiples” of the direct cost (although she seems not to have realised that because she contrasts these results with Orr’s 2022 claim).

The first of the two charts really captures the gist of why the little model analysis sheds no useful light at all (SS here simply means steady state).

I showed the top left chart to a 3rd year economics undergraduate, who immediately spotted the problem. It isn’t very hard.

You’ll note that in this example real GDP falls materially below the steady state, or potential, and stays there – converging ever so slowly – for years. By construction of the model, the LSAP intervention – about the scale of the actual LSAP programme – lifts real GDP, but again throughout the entire forecast period real output is at or below potential. There is, in other words, a negative output gap right through the period in the scenario. As the model is constructed, the LSAP intervention boosts real GDP, so that there is a smaller negative output gap. But it is always either negative or zero. Thus, the LSAP has unambiguously boosted real GDP, and thus tax revenues. Working back from the (few) numbers in the little note, and knowing the tax/GDP ratio in New Zealand is about 30 per cent, the total GDP difference must be of the order of 7-8 per cent of GDP. The current LSAP losses to the Reserve Bank are just over 2.5 per cent of GDP, so on those numbers the gains from the LSAP would be “multiples” of the Reserve Bank losses.

But have we had a negative output gap throughout the last 3+ years since the LSAP got underway at the end of March 2020?

Not according to the Reserve Bank, or to any other serious macroeconomic analyst. But since it is the Reserve Bank making the bold claims, and because their numbers are easy to find, here is the Reserve Bank’s current view of the output gap over the period since the start of 2019. I’ve also shown their projections from the last (pre Covid, pre LSAP) MPS.

The output gap is now estimated – several years on – to have been negative for only two quarters, March and June 2020. Every quarter from September 2020 onwards has been positive.

Doesn’t that just mean even more tax revenue and more net benefit?

No, it doesn’t. What went with the persistently positive and large output gap? Why, that was the sharp and now sustained rise in inflation. And how do the Reserve Bank’s modelling and forecast efforts envisage that core inflation comes back to target again? Why, via (raising the OCR and engendering) a fairly protracted negative output gap

and when output is running below potential for several years (and on these projections it isn’t even back to potential by 2026), tax revenue will, all else equal, be running lower than it would otherwise have been. In fact, the way the forecasting models are set up, things are pretty much symmetrical – it will be take roughly as much excess capacity as there was excess demand. We simply haven’t been in the world the IMF’s little desk exercise assumed/portrayed. And thus the numbers are just pretty meaningless when it comes to making claims about the fiscal or other net costs/ benefits of the LSAP. In his day, the Governor would have recognised that once he read the short note and thought for a minute or two.

There are many other limitations to the analysis, even on its own terms. First, the subsequent inflation seems to be treated as quite unrelated to the (with hindsight excessive) stimulus that had gone before. Second, while they assert that the LSAP was a better (net cheaper) intervention than anything else they make no attempt to show this. Thus, had we wanted to throw another $11bn at the economy we could instead have simply given the money to households ($2000 or so per capita). That almost certainly would have engendered a significant demand response (and more than what most New Zealand economists outside Bank believe the LSAP actually did). And we know that actually the OCR hadn’t been lowered to any sort of effective floor, just to the 0.25 per cent the MPC had chosen to set it at. So at least some of any stimulus the LSAP provided could have been done simply by setting the OCR lower – at no risk to the Crown at all. The Funding for Lending programme, used long and late by the Bank, seemed to be an effective tool for stimulus…..and involved no financial risk to taxpayers at all. Had the Bank been doing its job in the run-up to Covid, the negative OCR tool would have been available from the start. You might not like that tool, but the Governor had told us before Covid that he did, and it could have been used at no financial risk to the Crown.

And all this simply assumes – no serious attempt has ever been made to show – that in the specific circumstances of New Zealand (where shorter-term rates are overwhelmingly what matter, and they were anchored by OCR expectations), the LSAP had any material (even inflationary) stimulus at all, to justify the huge financial risks that were taken with no serious advance scrutiny, and which ended up going very bad.

I could take the opportunity to run through all the arguments around LSAP effectiveness again, but I won’t. About a year ago Orr made a strong play to defend it, and the alleged benefits, and I spent a long post then unpicking his arguments. Sometimes – there are so many – one just forgets occasions when Orr has just made stuff up. He was at it again this week.

As for the IMF piece, it is what it is. If you ever find yourself in a deep economic hole, seemingly intractable, you want all the monetary policy stimulus you can get. Best of all, use the OCR and use it aggressively. Perhaps QE can add some value on occasion (probably not much in New Zealand, but perhaps anything might help then in such a scenario). But that – we now realise – just isn’t where the New Zealand economy – or most other economies – found themselves after March 2020. In fact, it is the Reserve Bank itself that now reckons the economy was already overheating – GDP above potential – by the second half of 2020.