A chart for New Zealand’s national day

Cross-country comparisons of material living standards aren’t easy to do well, and especially for earlier historical periods when data are often patchy, to say the least.

But Professor Angus Maddison made the effort of compiling estimates for a range of a countries –  in some cases going back (with estimates every few centuries) as far as the year 1AD.  He used the best estimates he could find from other researchers where they were available, and did his own estimates to fill in some of the gaps.  As one gets further into the 20th century, more official or semi-official estimates could be used.

His fullest set of estimates for the last couple of hundred years was for a group of 16 Western European countries and the four advanced “offshoots” –  New Zealand, Australia, Canada, and the United States.     The estimates have to be taken with a considerable pinch of salt, but in broad outline they seem fairly consistent with other research on the relative prosperity of various countries.

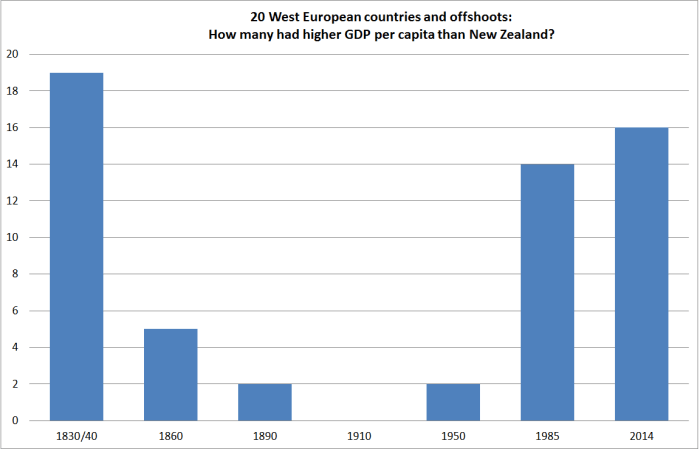
Maddison reports an estimate for each country for either 1830 or 1840.  For New Zealand he uses an estimate for 1840 that was consistent with his estimates for much of Europe in 1000AD (and the same low estimate as he uses for pre-settlement Canada, US, and Australia).  If that estimate is even roughly right, then material living standards in New Zealand at the time the Treaty was signed were lower than those in all other 19 countries.

Here is how that ranking is estimated to have changed (using the Conference Board’s Total Economy Database, which builds on Maddison’s work, for the latest observation).

waitangi


Through some combination of immigration of people and technology, substantially (and often forcibly) displacing the previously dominant population and culture, fifty years later GDP per capita in New Zealand is estimated to have been among the very highest in the world.  One wouldn’t put much weight on precise numbers, but on this particular series, in 1910 no country had a higher GDP per capita than New Zealand.

But 100 years on, 16 of these 19 countries now have higher GDP per capita than New Zealand does.

Absolute living standards in all of these countries are, of course, far higher than they were in 1840.   And the evidence strongly suggests that living standards in New Zealand –  and Canada, US, and Australia –  are now far higher than they’d have been without European settlement (see here or here).  But the last 100 years has been a fairly dismal relative performance by New Zealand.  And there is no sign of that reversing again.

Government bailouts and market discipline

The speech and Bulletin put out by the Reserve Bank yesterday made much of the importance of market discipline in the financial sector.  The two documents have slightly different lists of conditions which the respective authors think make it more likely that market discipline will be effective, but a common element is “market participants [must] have incentives to monitor financial institutions”.  Toby Fiennes argues that in the New Zealand context:

“some aspects of the regulatory framework, such as Open Bank Resolution (OBR) and no deposit insurance, reinforce these incentives.”

and O’Connor-Close and Austin, in the Bulletin, add in

“nor is there any policyholder protection scheme for insurance firm customers.”

This has been a longstanding view held by the Reserve Bank.  I’ve long thought it was wrong.

Of course, if you were confident that, were a bank to fail in which you were holding deposits or other interest-bearing securities, you would lose money, and no one would bail you out, you would have quite a strong incentive to pay attention to the health of any institution in which you had a reasonable amount of money, and (to economise on monitoring costs) to hold  your money, as far as possible, with those institutions generally regarded as safest.

Same goes for insurance.  If you had your house insurance with an insurance company, and no one would bail you or it out if the company failed, you’d have quite an incentive to insure with companies that would prove resilient through the worst of shocks.

In the case of banks, OBR is designed to make it more technically feasible for political leaders to let major banks fail.  In that model any losses  (mostly) fall on the creditors, and yet the failed bank can quickly re-open, keeping the day-to-day flow of transactions and routine business credit operational.  It is technically elegant system.  But whether or not it is ever used is not up to the Reserve Bank.  That is matter for whoever is Minister of Finance at the time –  and no doubt the Prime Minister of the day too.

Suppose a big bank is on the brink of failure.  Purely illustrative, let’s assume that one day some years hence the ANZ boards in New Zealand and Australia approach the respective governments and regulators, announcing “we are bust”.

Perhaps the Reserve Bank will favour adopting OBR for the New Zealand subsidiary (since the parent is also failing they can’t get the parent to stump up more capital to solve the problem that way).    But why would the Minister of Finance agree?

First, Australia doesn’t have a system like OBR and no one I’m aware of thinks it is remotely likely that an Australia government would simply let one of their big banks fail.  But in the very unlikely event they did, not only is there a statutory preference for Australian depositors over other creditors, but Australia has a deposit insurance scheme.

I’m not sure of the precise numbers, but as ANZ is our largest bank, perhaps a third of all New Zealanders will have deposits at ANZ.

So, if the New Zealand Minister of Finance is considering using OBR he has to weigh up:

  • the headlines, in which ANZ depositors in Australia would be protected, but ANZ depositors in New Zealand would immediately lose a large chunk of their money (an OBR ‘haircut’ of 30 per cent is perfectly plausible),
  • and, even with OBR, it is generally accepted (it is mentioned in the Bulletin) that the government would need to guarantee all the remaining deposits of the failed bank (otherwise depositors would rationally remove those funds ASAP from the failed bank)
  • and I’ve long  thought it likely that once the remaining funds of the failed bank are guaranteed, the government might also have to guarantee the deposits of the other banks in the system.  Banks rarely fail in isolation, and faced with the failure of a major banks, depositors might quite rationally prefer to shift their funds to the bank that now has the government guarantee.

And all this is before considering the huge pressure that would be likely to come on the New Zealand government, from the Australian government, to bail-out the combined ANZ group.  The damage to the overall ANZ brand, from allowing one very subsidiary to fail, would be quite large.  And Australian governments can play hardball.

So, the Minister of Finance (and PM) could apply OBR, but only by upsetting a huge number of voters (and voters’ families), upsetting the government of the foreign country most important to New Zealand, and still being left with large, fairly open-ended, guarantees on the books.

Or, they could simply write a cheque –  perhaps in some (superficially) harmonious trans-Tasman deal to jointly bail out parent and subsidiary  (the haggling would no doubt be quite acrimonious).  After all, our government accounts are in pretty reasonable shape by international standards.

And the real losses –  the bad loans –  have already happened.  It is just a question of who bears them.  And if one third of the population is bearing them –  in an institution that the Reserve Bank was supposed to have been supervising –  well, why not just spread them over all taxpayers?    And how reasonable is it to think that an 80 year pensioner, with $100000 in our largest bank, should have been expected to have been exercising more scrutiny and market discipline than our expert professional regulator (the Reserve Bank) succeeded in doing?  Or so will go the argument –  and it will get a lot of sympathy.

(There is provision in the OBR scheme for a “de minimis” amount below which the haircut might not apply.   If the de minimis amount is, say, $500 –  roughly a fortnightly New Zealand Superannuation amount for a couple –  it is neither here nor there for the scheme as a whole.  But a high de minimis amount looks a lot like ex post unfunded deposit insurance.)

Note that I’m not arguing that bailouts are “a good thing”, simply that having the OBR tool really does not dramatically alter the incentives politicians will face in dealing, at the time, with the imminent failure of a large bank.   And rational investor know that.  For the case of a large bank, OBR simply isn’t really a time-consistent strategy for politicians.

Some people at the Reserve Bank will accept the point, but argue that we still need OBR to have a credible weapon to wave in front of the Australians in a crisis.  If they think New Zealand might just be “crazy” enough to use it, it might  –  so it is argued – help us negotiate a slightly less unfavourable bail-out deal.  Perhaps.  But Australians can read domestic politics too.  I have no problem with having it in the toolkit –  perhaps it could be useful for a small bank  –  but no one should pretend that it solves bail-out risks and restores retail market discipline, red of tooth and claw.  And the probability of a bail-out, with a focus on protecting retail deposits, probably weakens market discipline at the margin even among wholesale investors.

And what are the precedents?  25 years ago the Bank of New Zealand was bailed out.  Yes, the government was the largest shareholder at the time, but I didn’t detect any sense –  at the very peak of the Douglas-Richardson era – that ownership determined whether the government of the day let the BNZ survive or fail.

More recently, the retail deposit guarantee scheme was put in place in late 2008 – not just for finance companies, but for the big banks too.  The decision was made by the previous Labour government – but it was endorsed by the Key/English led Opposition, and was recommended (in substance if not in precise detail) by the Reserve Bank and Treasury. I wrote many of the papers.

And more recently still, AMI was bailed out –  by the current government, on the recommendation of the Reserve Bank and Treasury.

In his speech, Fiennes note that

“it is of course true that many people expect governments to stand behind their deposits. That expectation was reinforced by the widespread Government guarantees (including in New Zealand) during the GFC.  The existence of an expectation, though, is not a sound reason to adopt deposit insurance”.

That might be true if depositors had no leverage.  But they do. It is called the ballot box, and politicians are very well aware of it.

If depositors, or policyholders, expect bailouts, and political leaders have incentives to respond to, and deliver on those expectations, then it may be a much less inferior option to adopt an explicit retail deposit insurance scheme upfront.

Deposit insurance need not be a substitute for OBR, but may actually make it a little more credible that OBR could be allowed to work.  If there is a bail-out, it will benefit not just New Zealand retail depositors, but wholesale lenders too, domestic and foreign.  There is likely to be much less political appetite for bailing out the wholesale creditors (especially the foreign ones), but a simple bailout does not enable one to distinguish.  By contrast, a properly specified deposit insurance scheme enables one to be very clear upfront which deposits are likely to be covered, and which not –  and to charge for that coverage accordingly.  In event of a bank failure, OBR could be applied to all creditors, with the deposit insurance scheme “reimbursing” the retail depositors to the extent defined in the scheme.  And in the event of a serious bank failure, the ability to impose loss on (particularly) foreign lenders (though in practice all wholesale creditors) is a net welfare gains to New Zealanders.  Letting losses fall on New Zealand retail depositors might be reasonable economics, but (a) it probably doesn’t work politically, and (b) it simply transfers the losses from one set of New Zealanders to another.

Deposit insurance schemes are not ideal –  and the Reserve Bank speech and article repeat some of the challenges.  But bailouts are not ideal either, and experience suggests very strongly that bailouts remain the preferred default option at the point of crisis.  As someone put it to me recently, in some sense if you don’t have an explicit limited deposit insurance scheme then, de facto, you have an implicit unlimited deposit insurance scheme (ie bailouts).  And reasonable depositors will know it.

And if deposit insurance schemes aren’t ideal, they are fairly ubiquitous.   As this recent IMF Working Paper points out (p32) every single advanced economy member of the IMF has an explicit deposit insurance scheme, with the exception of Israel, San Marino, and New Zealand.  San Marino aside, every European country, advanced or emerging, has such a scheme, and Africa is the only continent where a majority of countries do not have such schemes.  It has never been clear why the Reserve Bank thinks New Zealand can, or sensibly should, sustain being different, given the political economy pressures that all governments face.

And it is not as if deposit insurance has been withering since the financial crises of 2008/09.  As the IMF paper illustrates, coverage has often been extended, and co-payments wound back.

I noted this morning that, for all its insistence on having regular private data that creditors can’t get access to, the Reserve Bank continues to assert that, in effect, it has no financial “skin in the game” –  the risks are with creditors. In a second-best world, a deposit insurance scheme actually helps ensure that government agencies really do directly have skin in the game; financial risk if things go wrong.  That might actually sharpen accountability.

It was really rather naughty, and unhelpful, of the Reserve Bank not to have devoted some space to the political economy pressures, and the New Zealand bailouts/guarantees to which they (and The Treasury) have been party.  Of course, it might have been difficult to have done so, and would have undermined a good story, but it would have got us closer to better understanding the real choices and tradeoffs that societies face and make in this area, ex ante and ex post.

Of course, the decision on a deposit insurance scheme is not one for the Reserve Bank.  It is a government decision, and one that would require legislation to implement. It is understandable that the current government feels badly burned by the cost of the guarantee of South Canterbury Finance.  But given the incentives that governments will inevitably face if a major bank, or insurer, is on the brink of failure, it is surely time to shift direction, and put in place an explicit insurance scheme, for which depositors would be charged. Doing so would probably, overall, strengthen market disciplines a little, not weaken them as the Bank argues.  Bailouts of all creditors might still happen –  between Australian government pressure, and the threat of disrupted access to foreign funding markets –  but at least (a) the government would have raised some revenue in advance of the costs, and (b) we would be able to have more rational, and emotionally (and politically) plausible, arguments about the reasonableness of allowing unsophisticated investors who had taken little or no obvious risk (deposits in one of our larger banks) to face large unanticipated losses.

At interest.co.nz, Gareth Vaughan recently had a nice piece also making the case for deposit insurance in New Zealand.
 

Bank regulation: the Reserve Bank’s unease about transparency

The Reserve Bank has been firing out on-the-record speeches this week. I discussed the Governor’s troubling effort here, and may come back to that again in the next few days.  I probably won’t say much about the Assistant Governor’s lecture yesterday –  except perhaps to draw attention to his claim that ‘there are times when the Bank will know more about the economic situation and outlook than does the public or market participants’.  Really?   I guess the last three years, when the Governor has consistently failed to get inflation near the 2 per cent target, and has had to dramatically and grudgingly reverse his own rather strident policy stance, hasn’t been one of those times.

Perhaps more interesting were the two releases late yesterday afternoon on the role of market discipline in the context of prudential regulation of banks (in particular).   Toby Fiennes, the head of the Bank’s prudential supervision area delivered a speech to some of those he regulates headed “Regulation and the Importance of Market Discipline” , and an issue of the Bulletin by two of his staff headed “The importance of market discipline in the Reserve Bank’s prudential regime” was released.    In both of yesterday’s releases there is a refreshing reaffirmation of the importance of market discipline –  even if the actual direction of policy isn’t really that consistent with the rhetoric.

The Fiennes speech is a mix: in part a lecture on the Bank’s view of the importance of market discipline, and partly a report on the outcome of the Bank’s recent tidying up exercise, the so-called  “regulatory stocktake”.  I wrote about the results of that process here (and a mere four months after first requesting them I have recently had released to me around half of the submissions the Bank received on the stocktake consultation ) [1].

I wanted to touch on just two aspects of the stocktake material.  I was one of several submitters who had made the case that all submissions on Reserve Bank consultative documents should be published (as is now common practice in other government agencies and parliamentary select committees).  The Bank has always been very resistant to such openness. But in its release in December, there were encouraging signs

Our current approach is based on our understanding that respondents prefer to keep their submissions confidential. Prior feedback indicated that banks, in particular, were reticent to share cost information and the Reserve Bank is concerned that the publication of submissions would impact the quality and detail of the submission feedback. On the other hand we also recognise the importance of transparency in the policy-making process, so we will return to this issue and consult on a revised approach under which the default position would be that all submissions are published on our website (although submitters could ask to have any confidential information in submissions redacted).

Unfortunately, the discussion in last night’s speech –  when Fiennes went out among the banks –  was weaker than what they put out in December.

Some submitters suggested that we publish all written submissions on our public consultations. Our current approach is based on prior feedback, which indicated that respondents prefer to keep their submissions private on the grounds of commercial confidentiality. We will test this more rigorously with stakeholders. The alternative would be to publish all submissions by default unless submitters ask for them to be withheld or redacted.

Talk of a new default position of publication has disappeared.  What I wrote in December seems even more apposite in light of last night’s comments

I think this statement tells one a lot about the extent to which the Reserve Bank sees its clients as primarily the institutions it regulates, rather than the public the institution exists for.  I’m sure that banks would generally prefer to keep their submissions confidential, and it is precisely for that reason that their submissions, in particular, should be made public.  It is too easy for a cosy relationship to develop between the regulator and the regulated

I hope that the Reserve Bank remembers that its primary stakeholders are the public, and the representatives of the public (the Minister and members of Parliament), not the entities they are statutorily charged with regulating.

But to balance that unease, I want to give Fiennes kudos for one aspect of his speech. In my submission to the stocktake I had argued that if the Bank was serious about promoting market discipline, it shouldn’t be devoting undue time to refining disclosure statements, which the Bank quite openly states don’t contain the information the Bank itself uses. Instead, I argued, the Bank should require that all the private information the Reserve Bank now collects should be published on the relevant bank’s website at the same time it is supplied to the Bank.  Recall that the Bank is keen to emphasise that creditors, not the Reserve Bank or the Crown, bear the losses in the event of a bank failure.

The Bank’s published response to the submissions did not deal with that proposal at all.  But last night’s speech did.  Here is what Fiennes said

As some of you may have read, several submitters argued that we should publish all of the information we receive through private reporting, potentially publishing a monthly dashboard of this information.

While this principle has some appeal, there are two main reasons why we do not consider it appropriate.

First, the potential trade-off between timeliness and data quality. We sometimes accept a marginal reduction in data quality in private reporting in exchange for receiving the information quickly. While this is appropriate for supervisory purposes, public disclosure needs to maintain a high minimum accuracy in order to support the credibility of the regime. This is underscored by the penalties in the legislation for false disclosure, and is an issue we are giving careful thought to in the design of the dashboard.

Second, there is the issue of commercial sensitivity. Often the private data we received is commercially sensitive, or might be open to misinterpretation if released without the appropriate context – especially if this was occurring in a situation of rapidly rising financial system risk.

At least now we can better understand the Bank’s objections. But I don’t find the counter-arguments persuasive.

Fiennes asserts that the Bank can “sometimes” live with a “marginal reduction in data quality…in exchange for receiving the information quickly”,  but that they can’t possibly expose the public to this “marginal reduction”.  But it is the money owned by the public that is at stake in these banks: Reserve Bank staff and management have nothing directly at stake.  More generally, the Bank doesn’t seem to recognise that all sorts of real and financial markets trade on imperfect information all the time –  in monetary policy, the constant revisions to GDP data for years afterwards are just the most obvious example.  If the information is sufficiently valuable to the Reserve Bank that it will use statutory powers to compel banks to supply it (without charge) that information, then such timely information should be at least as valuable to the public who are investing with the banks.  If the data really helps shed light on the financial positions of banks, investors have more use for it than officials.

The Reserve Bank’s other counter-argument is “commercial sensitivity”.  But if the Reserve Bank really needs this timely information to do its job, how can depositors and other lenders not need it to evaluate the changing nature of the risks they are running?  No doubt the same sorts of arguments were run when disclosure statements were first developed in the 1990s.  Fiennes is also concerned that data might be “open to misinterpretation if released without the appropriate context” –  but nothing stops the disclosing bank itself, or the Reserve Bank , or any private sector commentators providing that context.  Any data can be misinterpreted   – and can also be explained.  Fiennes amplifies the point by arguing that misinterpretation is perhaps especially likely “in a situation of rapidly rising financial system risk”.   But disclosure isn’t overly valuable to any creditor in good times – the value of having that information is precisely when actual and perceived risks are rising.  And, to be boringly repetitive, it is depositors’ and investors’ money that is at stake.

Here was some of my discussion of the issues in my original submission:

Moving in the direction discussed just above would, of course, represent a substantial change in  approach.  Timely statistical returns of the sort banks supply to the Reserve Bank can’t first go through a full audit sign-off and director attestation, but the Reserve Bank itself –  by its own  revealed preferences –  clearly thinks that in terms of knowing what is going on on a timely basis, those protections are less important than getting timely information.  If things are very timely there will almost inevitably be the occasional error, but that is not an argument against the idea.  After all, even Statistics New Zealand (perhaps even the Reserve Bank) occasionally finds mistakes in its data.  The concern shouldn’t be errors –  people are human and will err –  but about the risk of being deceived.  But adequate protections against deliberate attempts to deceive either the Reserve Bank or creditors (by deliberately supplying erroneous or misleading information) surely either already exist in statute or common law, or could be legislated separately.  And the fact that the Reserve Bank’s own analysts would be reliant on the same data that were going public would provide an additional layer of comfort –  since the Bank is readily able to ask, and require answers to, probing follow-up questions.

I am also not suggesting an absolutist approach to this issue.  I have no problem with the answers to  ad hoc inquiries by the Reserve Bank of an individual bank not being published.  And in times when an individual institution may be approaching crisis, there probably inevitably needs to be a degree of confidentiality around the handling of that detailed information involved in crisis management (although such material should probably still be discoverable after the event).  Indeed, protecting that sort of information was a part of the justification for the (now abused) section 105 secrecy provisions in the Reserve Bank Act.  There is no foolproof dividing line, but I would suggest as a starting point that any statistical returns which are (a) regular, and (b) required of all (or a significant subset of) banks should be subject to my immediate disclosure rule.  And perhaps the Reserve Bank Board could offer an attestation in its Annual Report that it has satisfied itself that staff and management are operating the system in a way that ensures all regular supervisory information is being made available to depositors and other creditors.

I still think the case for full and immediate publication of all regular bank statistical returns is strong.

New Zealand’s regime around depositor protection is extremely unusual internationally –  something I will come back to in a follow-up post.   We don’t protect depositors.  Perhaps keeping information private –  having the real oil only going to the Reserve Bank –  might be acceptable in some idealised world in which bank regulators were consistently wise, insightful, benevolent and consistently right. (“we’ll look after everything for you”).   But they aren’t.  They are human beings, and their track record (around the world) isn’t particularly good.  That isn’t a comment about the Reserve Bank of New Zealand in particular –  it hasn’t been put to the test in the last 20 years –  but about bank regulators more generally (and other regulators for that matter).

Regulators simply do not have the incentives to process and interpret information correctly –  and it isn’t their money at stake.  Sometimes they get too cosy with those they regulate.  At other times, they get too cosy with their political masters. And often enough – being human –  they simply pursue their own bureaucratic interests –  a bigger agency, with more power, more information, not too much scrutiny and a quiet life.  There isn’t much reason to think that Reserve Bank regulators will consistently make better use of ‘private data’ from banks better than the people who have lent to those banks will.  Disclosure can be messy, and bureaucrats abhor messiness.  But the contest of ideas and interpretations, and the intense scrutiny of available information (partial as it might often be), is the essence of competitive market processes.  Tidiness, not so much.   If regulators need data promptly, so do those who invest with the banks they regulate.


[1] The Bank told me a week ago they were going to post that release on their website (here), but have not yet done so.  If anyone wants a copy of those submissions please email me.  [UPDATE: The Bank has now posted the release.]


TPP: some economists

Eric Crampton had a post this morning drawing attention to recent posts on TPP by Brian Easton (“to the left of the NZ economist punditsphere”) and me (“to the right of the same”).

In our posts we primarily asked slightly different questions.  Brian posed the question “Can we afford not to adopt the TPPA?” .  He doesn’t express a strong view one way or the other on the economic merits of the deal itself (but, as Eric notes, he doesn’t come across as overly enthusiastic).  Instead, his focus is on the fact that the deal has already been agreed, and that if New Zealand were not to ratify it now, it could be deeply damaging to a range of international relationships.

The logic in this column is that we now do not have much choice about the TPPA. The government is trapped into agreeing to it because rejecting it has implications for other trade deals and our wider international relations.

That is probably right.  I didn’t give that dimension much attention in my post, as I take for granted that having signed the deal the current government will ratify it.  It doesn’t need a vote in Parliament to do so, but would have the numbers even if it did.

My focus was different –  more about the question of whether we, as New Zealanders, should welcome, or regret, that the deal was done at all.  Given that the deal has been done, the implications are quite different if it eventually falls over because the US political process rejects it (neither a President Sanders nor a President Trump might even submit to Congress), than if a single minor country (eg New Zealand) were to walk away unilaterally.

I suspect we’d be better off if the deal had not been done.     But I’d feel more confident of any view  –  positive or negative –  if we had had a proper independent evaluation of all the aspects of the agreement from a capable independent agency (such as the Productivity Commission).

I was also interested in Eric’s own take on the deal

I’ll remain a fence-sitter as it would take just too much work to come to a strong view on it. My confidence interval on whether the thing’s worth signing spans low/mid positive and low negative figures, and it wouldn’t be easy to tighten that up. If Congress decided not to pass it and the other partners could then clear out the worse parts on copyright, it wouldn’t bother me that much – though the deal on copyright is far better than I’d thought it could have been.

Eric is also on “the right of the economist punditsphere” (probably more so than I am).  In a sense, his point about “it would take just too much work to come to a strong view” echoes the argument for a proper independent expert evaluation.

And, of course, from the left was the sceptical paper on The Economics of TPPA which I linked to other day, which had substantial input from economics academics Geoff Bertram and Tim Hazeldine.

Perhaps I’ve missed someone, but I haven’t seen a ringing endorsement of the overall economic benefits to New Zealand of TPPA from any New Zealand economic commentators.      Perhaps the overall deal is slightly beneficial, or slightly detrimental, to New Zealand’s overall interests.  And different people might reasonably reach different views, by placing different emphases on the various strands of a complex deal.

In the Herald this morning, the Trade Minister argues that “today is exceptionally important day for New Zealand”.  Frankly, that seems unlikely either way.  He claims to believe that his own National Interest Assessment understates the likely economic gains to New Zealand.  It seems unlikely, but it would be interesting to see his argumentation and evidence.

Either way, I had a circular National Party e-mail from McClay yesterday, with a link to a site allegedly “setting the record straight on TPP”. He lost me here

FALSE: Supporting the TPP is a left-right issue

Actually, it’s an economic literacy issue.

I know it is politics, but I rather wondered who the Minister of Trade thought he was convincing.  The issues are important enough –  whether McClay is right or some of the sceptics and outright opponents are – for a rather more serious level of discussion and debate.

Rather desperate defensiveness

The Governor of the Reserve Bank has this afternoon delivered his annual speech to the Canterbury Employers Chamber of Commerce.  In many respects it was an elaboration on last week’s brief OCR review statement –  “we might have to cut the OCR, and risks are tilted to the downside, but we don’t really want to”.

Beyond that, it wasn’t an impressive effort.  Once again, the Governor simply does not seriously engage with the arguments made by those who suggest that a lower OCR would have been, and would be, preferable.  Instead, he basically makes up an inflation story that simply isn’t supported by the numbers, and attacks straw men.  The defensiveness is disheartening.

Lets take the numbers first.  On several occasions the Governor repeats the claim that “Annual headline inflation is currently 0.1 percent. This is primarily because of the negative inflation in the tradables sector, and the decline in oil prices in particular.”

First, you can’t just ignore tradables prices –  when the target is expressed in terms of CPI inflation, and around half the index is tradables.  CPI inflation is a weighted average of tradables and non-tradables inflation, and tradables inflation is typically lower than that for non-tradables.  Perhaps one might set tradables to one side for a time if the exchange rate has just been moving very sharply –  exchange rate changes do tend to affect the level of domestic tradables prices (and so temporarily affect the inflation rate).  But the peak in the New Zealand TWI was 18 months ago now.  If anything, the lower exchange rate has been holding up, perhaps only a little, tradables prices in the last year.  And non-tradables inflation in the last year was only 1.8 per cent.  If inflation was really consistent with the target midpoint, we should expect to see non-tradables inflation around 2.5 per cent.  It is a long way off that at present.

Second, the Governor repeats the story from last week’s statement that really it is mostly about falling oil/petrol prices.  But it takes no sophisticated analysis to read the SNZ CPI release, or consult the Reserve Bank website, and find that CPI inflation ex petrol was 0.5 per cent last year –  at a time when the exchange rate has been falling.  The Governor also invokes the cut in ACC motor vehicles levies in his defence –  which would be fine, except that he completely ignores the offsetting government decision to increase tobacco excise tax yet again.  SNZ publishes a series of non-tradables inflation excluding government charges and the alcohol and tobacco component.  That series increased by 1.8 per cent last year –  exactly the same as the overall non-tradables inflation rate itself.  In other words, administered government taxes and charges do not explain low headline inflation, and neither (to a great extent) does low petrol prices.  To argue otherwise  –  without much more supporting analysis –  just isn’t supported by the data.

Here are a range of analytical and exclusion measures that one might reasonably look at in assessing current core inflation

Annual inflation, year to Dec 2015
Trimmed mean 0.4
Weighted median 1.5
Factor model 1.3
Sectoral factor model 1.6
CPI ex petrol 0.5
CPI ex food and vehicle fuel 0.9
CPI ex food, household energy and vehicle fuel 0.9
CPI ex cigarettes and tobacco -0.3
Non-tradables ex govt charges and alcohol and tobacco 1.8

As he did in last week’s release, the Governor focuses on the sectoral core factor model measure –  which just happens to  be the highest of any of the inflation measures.  Since previous OCR releases had not focused on specific core inflation measures, we might have hoped for either a balanced assessment from the Governor, or a more in-depth case for why we should regard the sectoral factor model as the best measure.  Why not, for example, (and at the other extreme) the trimmed mean (which has had quarterly deflation in three of the last five quarters)?  But there was simply nothing : just assertions.  (Incidentally, even if the Governor is correct that the sectoral factor model is the best read, it is quite a slow-moving smooth series, and a deviation of 0.4 percentage points from the target midpoint would not be insignificant. )

So perhaps we can debate quite where the underlying rate of inflation really is –  as I noted last week, neither the Governor, nor anyone else, knows that with any certainty.  But the Governor doesn’t engage in that debate, he reverts to attacking straw men.

Once upon a time –  a quarter a century ago, says he gulping –  a wise boss at the Bank objected when I was drafting Monetary Policy Statements attacking anonymous views of outsiders (“some commentators said”) and suggested that if we wanted to deal with criticisms we should identify them specifically, and respond to what people had actually said.  It took more work, but he was right.

By contrast, we hear today from the Governor the lofty declaration that “the Policy Targets Agreement is a relatively simple document [arguable, but we’ll let that pass] we continue to be surprised at the wide range of interpretations that we see in the media and in the commentaries”.  Really?    But the Governor gives no indication as to whose interpretations he has in mind, and what those interpretations might be.    I see comments occasionally from people who argue that the Act or the PTA should be changed, but I don’t recall seeing any very great divergences over the last few years in the interpretation of the PTA itself.  Yes, there is some uncertainty about what, if anything, the longstanding obligations to “have regard to the soundness and efficiency of the financial system” and to avoid “unnecessary variability in exchange rates, interest rates and output” might practically mean –  but there is nothing new about that, and the Bank itself can’t give an straightforward answer to those questions (a lot, inevitably, is “it depends on the specific circumstances”).  But the debate about the conduct of monetary policy over the last few years has mostly been squarely within an entirely conventional framework.  The Governor and his advisers (and initially many of the bank economists) expected inflation to pick up and hence thought the OCR needed to be raised a lot.  Others were more sceptical.  But both sides of the argument operated largely within a forecast-based model  –  suggesting that the OCR should be adjusted in line with the medium-term outlook for inflation.  As it happens, the Bank –  and those who adopted the same line –  were proved wrong –  but it wasn’t really a dispute about the PTA itself.  They were forecasting differences and –  while forecasting is hard –  the Bank and the Governor have been repeatedly wrong-footed by the data.  They had the wrong model.  Again, some of their international peers made the same mistake –  others were just constrained (or thought they were) by the near-zero lower bound.

The Governor also devotes space to attacking a related straw man. Indeed, this one is the centrepiece of the press release he put out with the speech:

“Mr Wheeler said that the Bank would avoid taking a mechanistic approach to interpreting the PTA.  Some commentators see a low headline inflation number and immediately advocate interest rate cuts:, he said.  A mechanistic approach can lead to an inappropriate fixation on headline inflation”

This is just the flailing around.  All his predecessors have also sought to avoid taking a ‘mechanistic’ approach to the PTA, so there is just nothing new or interesting in the assertion that he doesn’t want to be mechanistic (although some have argued that “mechanistic” might describe his own 2014 stance).   Perhaps more pointedly, I’d challenge the Governor to name a single commentator who has suggested that policy should be run in reaction to current headline inflation.  I can’t think of any.  I’ve been more dovish than probably any other commentator over the last year, and if anything I have repeatedly criticised the Governor for an unwarranted focus on headline inflation in his OCR releases (when he was arguing that the lower exchange rate would soon have inflation back to rights).  Who are these “mechanistic” people the Governor has in mind?

It is good to know that the Governor will “continue to draw on the flexibility contained in the PTA”, but in the end the PTA requires the Bank to focus on keeping inflation near 2 per cent.  It simply hasn’t succeeding in delivering that sort of outcome –  in fact, not once since the current Governor took office.  I’ve suggested that one practical approach to those repeated errors might be to aim for inflation a little higher than 2 per cent.   If the past forecasting errors continue –  and they may, because no one fully understands what is going on globally – it is more likely that actual inflation will end up around 2 per cent.  And if the forecasting errors do go away, actual inflation would come in a bit over 2 per cent –  not ideal, but not the worst outcome after years of undershooting, and consistent with the sort of flexibility the PTA provides.  Perhaps that is one of the strange interpretations of the PTA the Governor has in mind?    But it certainly doesn’t argue for driving policy off current headline inflation.

The country really deserves more engagement from the Governor, and some intelligent debate.  There are puzzles in the data that aren’t easy to resolve (there are new ones in today’s HLFS).  Resolving them and getting appropriate good quality policy from the most powerful  unelected official (and agency) in New Zealand isn’t helped by some mix of lofty condescension and attacking straw men –  cases no one is making –  rather than grappling with the alternative issues and arguments.

With all the resources at the Governor’s disposal, we should expect more from him than is evident in this defensive piece.  Those charged with holding him to account – the Board, the Minister, and Parliament’s Finance and Expenditure Committee should be asking hard questions, of him and of themselves.


Natural resources and economic performance: Anthony Trollope’s observation

The great Victorian novelist Anthony Trollope (and senior public servant in the British Post Office) visited Australia and New Zealand in 1871 and 1872.  His son had become a New South Wales sheep farmer, so the trip was partly about family, and partly an income-earning opportunity to write a book about the Antipodean colonies.

Much of the material from the New Zealand leg of the trip –  two months travelling from Bluff to Auckland –  was reproduced in With Anthony Trollope in New Zealand 1872, edited by A H Reed, and published in 1969.  I read the book over the weekend (having dipped into it, and found some quotes on railways and the incentives facing officials and politicians, here).

In 1872, it was only 32 years on from the Treaty of Waitangi  –  as close as 1984 is today to 2016.  All the New Zealand and Australian colonies were young –  it was only 84 years since the Sydney penal colony –  and whenever I read about the period I’m struck by how rapidly development occurred in many of these places.

By 1872 New Zealand had already been through some turbulent times.  The 1860s had brought the South Island gold rushes, and the huge influx of miners, but they were also the time of the worst of the land wars in the North Island –  where the burden on manpower and government finances was so severe that one sometimes wonders why the British government persevered. Trollope records contemporary British estimates that the New Zealand “wars with the Maoris…have been declared by competent authorities at home to have cost England twelve millions [and] have cost that colony nearly four millions and a half”.   Nominal GDP for New Zealand is estimated to have been only £4.4m in 1859 and £16 million by 1870.    Fortunately for the New Zealand taxpayer, Britain bore most of the fiscal cost.

One of the issues often debated is the role of natural resources in explaining the wealth of nations.  Natural resources alone don’t make a country prosperous –  think Bolivia, Angola or Iran –  but it can help a lot, especially in a country with a fairly small population –  think Equatorial Guinea, Kuwait or Brunei.  The natural resources have always been there, but it takes technology, management. and capital to utilize them, and really bad governance can impede all of that, and see any gains rapidly dissipated.  Among advanced countries, I think there is little doubt that Norway (in particular) and Australia would not have reached their current living standards without the natural resource endowments their people and institutions have enabled those countries to tap.  I’m going to come back to the case of Australia in the next few days.

Trollope was writing about the situation in 1872, and he included an interesting couple of paragraphs (pp38-39) about what we might term a “natural experiment” –  contrasting the performance of the province of Otago (which at the time had its own provincial government, with quite extensive powers) with that of the colony of Western Australia.

I will quote a few words from a printed dispatch respecting Otago, sent home by Sir George Bowen, the Governor of the colony, in 1871 – “after the lapse of only twenty-three years” –  from the first settlement of the province, – “I find from official statistics that the population of Otago approaches nearly to 70000, that the public revenue, ordinary and territorial, actually raised thereon exceeds  £520,000; that the number of acres farmed is above a million; that the number of horses exceeds 20000; of horned cattle 110.000; and of sheep 4,000,000.  The progress achieved in all the other elements of material prosperity is equally remarkable; while the Provincial Council has made noble provision for primary, secondary, and industrial schools; for hospitals and benevolent asylums; for athenaeums and schools of art; and for the new university which is to be opened in Dunedin in next year”.  I found this to be all true.  The schools, hospitals and reading-rooms, and university, were all there, and in useful operation; – so that life in the province may be said to be a happy life, and one in which men and women may and do have food to eat, and clothes to wear, books to read, and education to enable them to read the books.

The province is now twenty four years old…. Poor Western Australia is forty-five years old, and, with a territory so large, that an Otago could be take from one of its corners without being missed, it has only 25,000 inhabitants, and less than one million sheep, –  sheep being  more decidedly the staple of Western Australia than of Otago. I do not know that British colonists have ever succeeded more quickly or more thoroughly than they have in Otago.  They have had a good climate, good soil, and mineral wealth; and they have not had convicts, nor has the land been wasted by great grants…  And in Western Australia gold has not been found.  I know no two offshoots from Great Britain which show a greater contrast”

Western Australia was settled a little before Otago, and was materially closer to Britain (making it cheaper to immigrate to).  The cultural backgrounds of the settlers were very similar, and both operated under British law and institutions.  And yet Otago had prospered and Western Australia had underperformed.  There seems little real doubt that natural resource discoveries –  gold primarily – was the difference at the time.

Natural resources very rarely make a country or region rich forever –  usually only human skills and capability do that.  The South Island gold didn’t last long, on any scale, and in time Western Australia would become a major exporter of mineral products –  which couldn’t readily be exploited with 1860s technology.  Today, partly as a result, Western Australia has around 2.5 million people, and the Otago and Southland regional council areas (roughly the old Otago Province) have around 270000 people.

TPP – are we really going to be better off?

As a social conservative, I’m instinctively queasy about an international treaty being signed in a casino complex.  As an economic liberal, I’m almost equally queasy about a major economic treaty, claimed to improve standards of economic policymaking etc, being signed in the flagship building of a company for whom our government not long ago did a constitutionally questionable private deal.

But, of course, the real issues about TPP have nothing to do with the specific place where the agreement will be signed.  What is in the 6000 pages agreement is what matters.

New Zealand –  like other countries –  would, of course, benefit from free trade.  That is now pretty widely accepted, but for a long time it wasn’t.  Oddly, Andrew Little claims that Labour has been a party of free trade since it first formed a government in 1935.  He seems to have forgotten the whole panoply of controls on trade and payments imposed by that very government, and substantially re-imposed by the next Labour government (1957-60).   Savage, Fraser, Nash, Nordmeyer and Kirk –  whatever their other merits –  simply weren’t free traders.

But it is now generally accepted that free trade is economically beneficial  (accepted as rhetoric –  even though we still have self-defeating tariffs in place ourselves which (no doubt very slightly) unnecessarily lower our own living standards). TPP does lower some tariffs, and provides somewhat greater access for some products to some markets.  Those look like worthwhile gains, but this is nothing resembling free trade.  Not only do many of the barriers remain high, but this is a regional deal. It is a standard result in the trade literature that regional deals can end up making countries worse off, rather than better off.   In its report last year on trade agreements, the Australian Productivity Commission –  no haven of economic neanderthals –  made that point very strongly.

Our government recently published its own National Interest Assessment of the TPP deal.  It argues that the trade dimensions of the agreement will make New Zealand materially better off –  nothing transformative to be sure, but on the face of it worthwhile gains.  But how credible is the argument?  I wasn’t persuaded.

The NIA is in the nature of an advertorial –  a piece written by and for those who agreed the deal.  Of course they are going to say that the deal is in the best interests of New Zealand, and no doubt they believe it.    But as others have pointed out, it relies on modelling that was done (a) before the agreement was even reached, (b) assuming that the tariff cuts all benefit New Zealand (rather than those who import the products we sell, and (c) without any detailed analysis of the impact of the liberalisation of the non-tariff measures in the agreement.  And there is no mention of trade diversion, or of the increased complexity of the system as a result of the proliferation of regional trade agreements.  Perhaps the effects are small, but the issues should at least have been addressed.

Others have argued that the overall gains to New Zealand on the trade front are likely to be exceedingly small.  Those arguments look to have some force, but also need expert evaluation.  Any judgement around the likely economic impact of the trade aspects of the TPP agreement would be more credible if they flowed from a detailed analysis undertaken by an independent agency.  I’ve argued previously that the New Zealand Productivity Commission would be a good candidate.

If there are overall gains to New Zealanders from the trade liberalisation dimensions of the deal, they need to be weighed against what is in the rest of the deal.

I’ve touched previously on a couple of concerning, or just puzzling issues (here and here).  In a future financial crisis, the TPP agreement requires countries considering using direct controls to preference all flows associated with foreign investment over any other financial flows (including those relating to an identical asset owned by a resident).  Existing multilateral arrangements still look superior, and more flexible, than what is in the TPP.  And the NIA’s section on the investment chapter of the TPP does not deal with these additional constraints at all.

I wanted to touch on just two other aspects of the agreement, the investor-state dispute settlement provisions, and the labour chapter

When citizens are discontented with their government, they can either lobby to change the government’s mind or vote to change the government.  In some cases, they may have redress through the domestic legal system.  Our courts are –  mostly –  open, impartial and competent.  We have established rules of evidence, bodies of precedent, and appeal processes –  heirs to hundreds of years of British legal development. We even have processes for, in extremis, the removal of judges for serious misconduct.   Individuals and companies can both lobby governments.  Where judicial remedies are open, both can seek to exercise them, regardless of whether the companies are owned by New Zealand or foreign shareholders.   Companies can’t vote of course – whether New Zealand ones or foreign-owned ones.

It seems like a pretty good system.  It seems to have worked.  So why have governments been signing up to arrangements that allow  alternative remedies specifically for foreign investors?  TPP represents a substantial extension of the possible number of such suits (even if some of the procedures appear to have been improved from some of those in earlier agreements). To be clear, a foreign-owned company in New Zealand will have different remedies open to it than a New Zealand owned company operating in exactly the same business in New Zealand (and it is symmetrical: a New Zealand owned firm in the US would have  different remedies available to it than a US-owned firm doing exactly the same business).

The background to these provisions dates back several decades, and related initially to foreign investments in countries with distinctly questionable legal and judicial systems.  Perhaps there might have been a case for recipient countries to agree to such provisions (just as two private parties might agree that a contract will decided under the rules of another country’s law –  English law is a common example).  But even then, only perhaps.  As I noted last year, it wasn’t the way Britain went about things when it was the leading economy and leading capital exporter in the 19th century.  The British approach then was one of caveat emptor.

More to the point, these ISDS provisions have now become prevalent in deals among countries that have good domestic legal and judicial systems, and it is just not apparent what interest of the citizens of TPP countries is being served by having further extended the ambit of such agreements.  From a foreign investor’s perspective, additional options are always more attractive than fewer options, but why would the governments of our countries provide greater rights, and more remedies, to a company simply because it is foreign-owned? A Peruvian-owned grocery chain operating in New Zealand would have different remedies available than a New Zealand owned grocery chain operating in New Zealand.  I can see no good reason –  nor for the reverse favouritism (benefiting New Zealand investors in, say, Peru).  In the process of doing so we undermine the role of our domestic judicial systems, in favour of international bodies where there is little accountability, few or no appeal rights, and no real sense of the domestic environment.

The National Interest Assessment document, perhaps unsurprisingly, dealt with very few of these issues.  In particular, it does not once mention the role of domestic judicial systems, or make the case for different remedies being open to foreign-owned rather than domestic owned firms.  It does, however, note that although the New Zealand government has not yet faced an ISDS suit,  TPP may increase the risk of future such suits.

Unease about the prevalence of ISDS provisions doesn’t seem to be an issue where opinion divides on predictable ideological lines.  In the same report I mentioned earlier, the Australian Productivity Commission expressed its concerns about such provisions, noting among other things that in recent years 40 per cent of all ISDS cases have been taken against governments of advanced countries, presumably countries with fairly well-developed legal and judicial systems.  The Cato Institute, a high profile US think tank    self-described as “libertarian” (rather than promoting specific corporate interests), has been producing material sceptical of ISDS provisions for some time.  As one of their analysts put it quite recently, while noting that changes could be made to deal with some of the more egregious aspects of ISDS arrangements:.

But more fundamentally, we should rethink the need for the system. These treaties were designed to address a problem from decades ago that is fading from memory. What, if any, problems arise with foreign investment today? The most prominent one is probably lavish subsidies from governments that are regularly given to foreign investors, and international limits on such practices could be of value.

The final area I wanted to touch on is the growing role of international treaties etc in constraining domestic law and regulatory freedom.  As many commentators have pointed out, every international agreement New Zealand signs ties our hands to some extent or other.  But that simply means we should ask hard questions about the details of the treaties we are signing up to.  Again, this isn’t an issue that divides neat on traditional left vs right ideological grounds –  both sides can be equally suspicious of domestic political processes, and as enamoured of constraining governments in international agreements that make it harder to do things their own citizens might favour.  On the sceptical side, I have sitting beside me the January 2016 issue of the “right-wing” political and cultural magazine The New Criterion which has several articles worrying about the implications of the growing number of such agreements.

Much of the local debate around TPP appears to be around issues associated with public health, the environment, and the Treaty.   But I found the labour chapter interesting.  In this chapter we appear to be signing up to an international agreement to constrain countries’ flexibility around labour law across the TPP group of countries. Indeed, the government  –  which has itself done some modest reforms to increase the flexibility of labour markets –  celebrates this: in discussing the labour provisions the NIA begins “The Labour Chapter of TPP constitutes the strongest outcome on trade and labour contained in any FTA negotiated by New Zealand”.

But why should domestic labour laws be subject to constraints in international treaties?

The NIA goes on to note –  recall this is our own government speaking – that “it is inappropriate to encourage trade or investment by weakening or reducing labour laws”.  I was somewhat staggered when I first read those lines –  I seemed to recall that the government had made the case for its own domestic labour market reforms on the basis of promoting the competitiveness of the New Zealand economy.  And sure enough, here was the Prime Minister announcing National’s 2011 employment relations policy.

 “A flexible and fair labour market is critical for building a stronger and more competitive economy, and creating more real jobs,”

Does the government not, for example, recognise that a lower exchange rate improves the competitive position of New Zealand firms by, for a time, lowering the effective real wages of New Zealand workers?  Sometimes that is a vital part of successful economic adjustment.   What conceivable economic logic is the government using to support that idea that ability to amend labour laws play no part in shaping a successful competitive economy?

Similarly, why are we signing a treaty that appears to commit New Zealand to having a minimum wage?  What does it have to do with promoting free trade (or even investment)?   There are arguments to be had around the economic impact of minimum wage provisions, but not all countries appear to have such provisions (not even all advanced countries) and surely it should be a matter of choice for each country’s own domestic political processes?

I’m also a little puzzled how this chapter works. In a unitary state such as New Zealand, all labour law is national, but in federal systems such as the United States and Australia, much labour law is done at the state level –  and the TPP labour chapter appears to cover only federal labour market legislation or regulations in those two countries.

Much in this chapter  seems to represent bad and unnecessary policy – a proliferation of bureaucracy at best, and the totally unnecessary sacrifice of domestic policy flexibility at worst.

At the vacuous end of the spectrum are provisions like “each Party shall endeavour to encourage enterprises to voluntarily adopt corporate social responsibility initiatives on labour issues that have been endorsed or supported by that Party”.  In one sense, it commits each country to almost nothing.    But it will no doubt be used by empire-building (or even just risk averse) officials, and perhaps politicians, to spend more public resources developing “voluntary” codes of “corporate social responsibility” –  after all, if they had no such codes, or firms weren’t sufficiently encouraged to comply with them, it might open New Zealand to a challenge from another government, or firms in other countries.

And then we have provisions for Cooperative Labour Dialogue  and the new Labour Council (and its associated “general work programme”).  It isn’t clear why we would want to enter such arrangements even with other advanced countries, let alone with Vietnam or Peru.  A recipe for small and lean government it is not ( and I won’t bore readers by listing the items  (a to u) which the parties agree they might “caucus and leverage their respective membership in regional and multilateral for a to further their common interest in addressing labour issues –  except to note that “work-life balance” appears on the list, and corporate social responsibility pops up again).  Real resources will devoted to paying for all these new bureaucratic and political overlays.  It seemed laughable to suggest, as the NIA does (p22) that the additional cost of all the TPP institutional arrangements, outreach activities etc will be only $1m per annum, across all areas of government.

Now, I’m sure that the pressure for this labour chapter did not come from the New Zealand government but from the centre-left United States government  –  the front page of the US Trade Representative’s TPP page has always been sobering on that score (the unholy alignment of US labour interests and US-based businesses concerned to undermine the competitiveness of firms in emerging markets).  But what is our own government doing championing this additional overlay of domestic and international bureaucracy?  Perhaps it won’t materially alter anything specific the current government wants to do, but these agreements last a lot longer than the next 18 months, and have a way of evolving obligations and constraints that were not always apparent at the start.

So I’m left, so far, unconvinced by the case for the TPP deal.  The trade benefits seems likely to be small –  but without an authoritative independent assessment it is hard to know –  and set against those possible small gains are certain costs and risks, some in areas (such as our judicial system, and dispute settlement systems in society) that really shouldn’t be up for grabs at all.  Add in the additional overlay of an extension of bureaucracy around the 14 countries –  and the desire to spread those regulations to a widening group of countries –  in areas where regulatory competition seems more desirable than otherwise, and it doesn’t look like a deal that should automatically summon support from all thinking people.

It looks and feels like a deal that would better never have been agreed.  And if it falls over eventually because, for example, it can’t get past the US Congress –  or a future President refuses to even submit it to Congress –  New Zealand and other countries might be better off as a result.

Assuming the agreement does go ahead, our government argues that for New Zealand not to participate would risk isolating New Zealand, contributing to our economic decline.    Perhaps (and there might well be net costs to being outside a ratified agreement) although that argument might be more convincing if the last 70 years had not been a story of barely-interrupted economic decline, or if the government had a credible narrative for how to reverse that decline.  Nothing the current government, or its Labour-led predecessor, have done, looks to have been successful in even beginning to reverse  it.  But the growing burden of the regulatory state –  advancing domestically, and by treaties such as this, certainly doesn’t look like a way to reverse our decline.

Immigration effects and the OIA

The economic impact of immigration received considerable attention in the Reserve Bank’s December Monetary Policy Statement.  That made sense –  the net inflow (a small net outflow of New Zealanders and a large net inflow of foreigners) over the last year or so has been one of the larger net inflows seen for some time, and has led to an estimated population growth rate higher than we’ve experienced for decades.  Changes in immigrant numbers affect the labour market, the housing market, demand for government infrastructure etc.   A forecast-based monetary policy needs a good story about (a) what will happen to net migration, and (b) what the short-term economic effects of those immigration developments will be.  And making sense of what has already happened requires disentangling the various influences –  including those associated with changes in immigration.  It is particularly important in New Zealand, where the level of inward non-citizen migration is larger than in most advanced countries, and where the variability in the net flow of New Zealanders and foreigners is larger than most.  Watching the Republican debate the other day, I heard Marco Rubio argue that the US was the world’s most generous nation because it took around a million legal migrants a year.  That is about 0.3 per cent of the US population.  Our annual non-citizen residence approvals target is around 1 per cent of our population.

But reverting to the Reserve Bank view, the material in the Monetary Policy Statement and associated press conference wasn’t that convincing.  Here is what I wrote about it then:

I am also puzzled about the Bank’s stance on immigration, and the evidence base that lies behind it. The Governor is clearly at one with New Zealand elite opinion –  he told the news conference that he thought high levels of immigration were “a good thing for New Zealand” and that he did not think there should be any immigration policy changes.  Views differ on the long-term economic impact of immigration, and many certainly agree with him, but why was this a subject the Governor is commenting on at all?  Historically, the Reserve Bank has been studiedly neutral on the long-term issue, and focused (rightly) on the short-term cyclical implications.  Governors who use the platform they have been given to advocate their personal policy preferences in other areas risk further undermining support for the autonomy they enjoy in respect of monetary policy.

But even the Bank’s view on the cyclical impact of the recent high levels of immigration seems confused.  In chapter one (the press release) they assert that high levels of immigration have reduced capacity pressures and contributed to  a lowering of inflation (ie supply effects exceed demand effects).  In chapter 5, they produce a scenario about the impact of immigration staying unexpectedly high over the next year or two.  In that scenario they explicitly articulate what appears to be their latest new view, in which a change in immigration has no net short-term impact on capacity or inflation pressures (short-term demand effects are just matched by short-term supply effects).  There is no analysis in support of any of this.  And there is no engagement with their own past research, or with the consensus view of New Zealand macroeconomists going back decades that whatever the possible long-term gains from immigration, in the short-term the demand effects dominate the supply effects (which shouldn’t be surprising, since the per capita capital stock requirements of each new person are materially greater than one year’s labour supply).  It was only two years ago that they published a research paper which showed these results.

mcdonald rresults

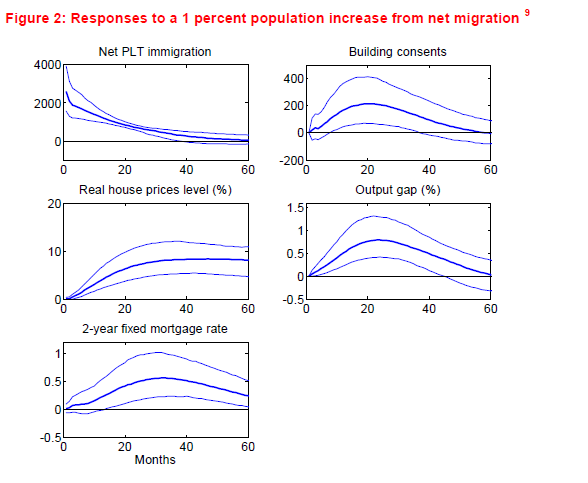
Demand effects exceed supply effects in the short-run (of several years).

The Bank seems all over the place on these issues. Perhaps they have fresh new research on the issue, but they put out two new Analytical Notes this morning, and there was nothing on immigration. I have asked for copies of any analysis they have produced in support of their new view, including how it might relate to the 2013 research.

For decades, the Reserve Bank has been clear that the short-term demand effects of immigration outweigh the short-term supply effects in New Zealand.  That was typically the view of other macro forecasters, and it was also the consensus among New Zealand economists throughout the post-war period.  It isn’t surprising (modern economies need lots of physical capital – and building a house typically takes more than the value of a year’s labour) –  and it says nothing about whether or not large scale immigration is beneficial in the long-run.  But the Reserve Bank has now apparently changed its stance, while providing analysts, commentators, and the public no basis for their new stance.  Perhaps the new stance is correct, but we should be able to evaluate their arguments and evidence.

So on the morning of the MPS release, I lodged a request with the Bank for

Copies of any analysis undertaken by, or discussed by policy committees at, the Reserve Bank since 1 June 2015 about the determinants of net migration in New Zealand and the economic impact of immigration.  I am interested both in any material shedding light on the Bank’s evolving views around the balance between supply and demand effects of immigration (including any reflections on the ongoing relevance, or otherwise, of the results published in Chris McDonald’s 2013 Analytical Note) [from which the chart above is taken], and anything shedding light on the Governor’s comment this morning that the high level of net immigration is a “good thing” for New Zealand.

It wasn’t a “gotcha” request.  I assumed there must be some new modelling or research behind the Bank’s stance, and was keen to see it, and cover it here.  It was also surprising that a Reserve Bank Governor would comment explicitly on longer-term immigration policy so I wondered if they had new evidence, or were influenced by new evidence from others, to justify that stance.  I also drew the request quite narrowly, focusing on the previous two forecast rounds only, and not asking for emails.  I was quite genuinely interested only in either research papers (there just aren’t that many  in any five month period) or analytical pieces discussed at the Monetary Policy Committee (again, it seemed unlikely there would be many –  immigration not having featured in the Statement of Intent as a key aspect of the Bank’s research programme.   Moreover, since immigration had been a prominent aspect in the Monetary Policy Statement released just that morning, it was hard to imagine that any extensive investigation would be required to unearth papers, which had been prepared and discussed in the previous few weeks.  And as I noted the other day, the Reserve Bank has tried to convince us of how transparent it is around its  “policy objectives, policy proposals, economic reasoning, and of our understanding of the economy”, so it seemed reasonable that they would be keen to get any material out as soon as possible.

And since the Official Information Act requires agencies to release material “as soon as reasonably practicable” the naively optimistic strand that lurks within me wondered if I might get something by Christmas.  Silly me.

Instead, I had an email from the Bank just before 5pm last Friday –  the very last day of the 20 working days available to the Reserve Bank to respond.  I was advised that

The Reserve Bank is extending the time limit for a decision on your request to Monday 29 February 2016, as permitted under section 15A of the Act, because the request necessitates a search through a large quantity of information and meeting the original time limit would unreasonably interfere with the operations of the Bank.

That is certainly a statutory ground on which a deadline for dealing with a request can be extended.  But it is highly unlikely to be a legitimate argument in this instance.  As I noted, it is not plausible that there is huge amount of material.  And as for unreasonably interfering with the operations of the Bank, recall that these aren’t ancient historical papers, or about some obscure points of policy; they are recent papers directly relevant to the Bank’s primary function, where it prides itself on transparency.  And the OIA had already given the Bank extra time (since deadlines are automatically extended over the summer holiday period).

Frankly, I’m not sure what the Bank has to hide.

But it feels like deliberate stalling and, accordingly, I have appealed this decision to the Ombudsman.    I am beginning to worry that perhaps there is nothing there at all.

That would be a concern –  and especially from an agency which wants to convince us that its new charging policy is itself in the public interest [1], and indeed supports access to official information.


[1]  Somewhat curiously, despite the alleged need to “search through a large quantity of information” and the risk that doing so might “unreasonably interfere with the operations of the Bank”, there has not yet been any suggestion of a charge for meeting this request.


Unprecedented…in a sample of four

The Reserve Bank had an interesting brief issue of the Bulletin out yesterday, reporting the results of some fairly straightforward data analysis as to how house prices (more accurately, house plus land prices) have behaved over the last fifty years or so, and how prices in Auckland relative to those in other parts of the country have behaved going back a few decades.  It is almost wholly a descriptive piece, offering no views on why things happened as they did, and little on what those patterns might mean.

The author –  Liz Kendall –  has done to work to construct a quarterly series for each TLA and a range of regional indices, using QVNZ data.  It would be nice to have those indices generally available, but perhaps restrictions on the use of the QV data precluded that?

The author identifies six distinct upswings in real national house (+land) prices since 1965, and as she notes the recent one has been relatively muted (for the country as a whole) –  despite all the fevered talk of low interest rates driving prices higher, ignoring the fact that interest rates are low for a reason (weak demand at any higher rates).

There wasn’t much of a upward trend in real New Zealand house prices, as far as we can tell, until the last 15 or 20 years.

rb housing 2

There was a huge boom in the early 1970s, as some combination of very low real interest rates and very rapid inward migration drove prices up.  But that increase was fully reversed over the following few years as credit conditions tightened, real incomes came under pressure, and significant net outward migration relieved pressure on the housing (house+land) stock.  The lack of any strong trend is consistent with what we see in the advanced countries that have a much richer longer collection of historical data –  including Australia and the United States.

Kendall illustrates that house prices in Auckland have not always been that highly correlated with those in the rest of the country.  There is clearly a common element to house prices in the country as a whole, but there are times when each region- including Auckland – “does its own thing”.  For example, in the 2002 to 2007 boom real house prices rose by materially less in Auckland than they did in the rest of the country (taken together).  And in the last three or four years, Auckland prices have risen much faster than those in the rest of the country.

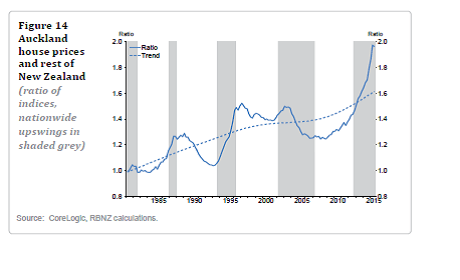
The punchline of the article appears to be this chart

RB housing 1

For the period since 1981 –   only 35 years –  it shows the ratio between Auckland house+land prices and those in the rest of New Zealand, and a moving average trend in this ratio.  The trend has no economic significance –  it simply smooths through the ups and downs in the actual data, and the more recent observations might end up being quite materially revised (up or down) as new data emerge (there are always “end point problems” with these sorts of filters).  The ratio is currently 22 per cent above this particular trend line, but when we look back 10 years hence who knows how large we will estimate that gap to have been.

I had just a few other thoughts on the article:

First, it was a shame that the authors did not look at Christchurch separately.    They look at an entity called “Greater Wellington” (Wellington, Upper and Lower Hutt, Porirua and Kapiti) but it is puzzling that they don’t even break Christchurch (an urban area of a similar population) out separately (just bunching it with Nelson, Dunedin and Invercargill), let alone look at a combined “Greater Christchurch” entity (Christchurch, Selwyn and Waimakariri).  At least in recent years, it has only made sense to think of the three TLAs together –  and price behaviour in that area has been distinctively different from, say, the rest of the South Island).

Second, it might have been interesting to see whether the differences between prices in other TLAs and the rest of New Zealand (perhaps excluding Auckland) were similar to, or different than, the pattern we observe in Auckland, including whether those patterns have been changing over the relatively short period under study.

Third, I would go easy on the word “unprecedented”.  In a short article, it is stressed several times that the gap between the increase in Auckland house (+land) prices and the increase in prices elsewhere in the country is “unprecedented”.  But they have regional data only since 1981, and in that period there have been a grand total of four upswings.  It is true that there is no precedent in the data, but there isn’t much data.

Relatedly, the article highlights how ill-served New Zealand is with historical economic and financial data.  That isn’t the responsibility of the Reserve Bank –  largely a policy and operational agency –  but it is a limitation that all users face.  Between the continued underinvestment in historical official statistics, and the lack of academic economists working on New Zealand economic history, and doing the leg-work to develop longer-run analytical series (as has been done for house prices in Australia, the US and various other countries), we have a relatively poor sense of what is normal or abnormal.  For example, it would be interested to know whether similar divergences occurred in the early 70s, in the post WW2 house (+land) price boom (when wartime controls were lifted), to be able to see what sort of regional divergences occurred during the Great Depression, and to be able to understand 19th century regional house price shocks (for example, the impact of the gold rushes on Dunedin prices, or of the land wars on Auckland prices).

The subtext in the Reserve Bank article is that what goes up comes down again.  In this article, it isn’t a particularly powerful point (and, in fairness the article doesn’t make much of it directly), since there will always be times when one region or another (even the largest) lags behind house price inflation in the rest of the country.  But there is no natural equilibrium  relationship between Auckland prices and those in the rest of the country –  as experience in the US demonstrates, it is mostly a matter of policy choices.  With weaker immigration and more liberal land-use policy around Auckland, real Auckland house+ land prices could be much lower absolutely, and relative to the rest of the country than they have been in recent years.  Many cities much bigger than Auckland in the US have house prices much cheaper, relative to surrounding areas, than Auckland does (I stayed recently with some friends in a small college city in the middle of the US where house prices were higher than those in the nearest, fairly prosperous, city of a million or more).

Finally, on the housing sector, SNZ released building consent data yesterday, completing the data for 2015.  The authors of the press release pointed out that the number of residential consents was the ninth highest ever –  which isn’t very impressive, since most macro series reach their highest or maybe second highest level each and every year.  What wasn’t pointed out was the way New Zealand’s population has increased –  not only is stock of people living here much higher than it was in previous housing booms, but the population increase over the last year or so has been larger –  even in percentage terms –  than at any time for decades.  Unfortunately, we don’t have an official population series that goes back prior to 1991, but using one of those from the international databases, here are residential building permits per capita since the series the mid 1960s.

residential building permits per capita


Last year’s building permits per capita were only just back to the average for the last 35 or so years –  even though the fast rate of population growth might normally have suggested, in a less regulatorily-impeded market, that consents per capita might have been considerably higher than the average over that period.

Which countries have been seeing export growth?

No one really doubts that over the longer term a better performing New Zealand economy –  absolutely or relative to the rest of the advanced world  –  would be likely to involve faster growth in exports.  It isn’t that exports are a special or unique type of product, or that tax breaks or other regulatory distortions should be put in place specifically to target exports.  It is simply that the rest of the world is a big place, and New Zealand is a small one.  The best prospects for high living standards here, at least for any given size of population, involves successfully selling more stuff to the rest of the world (which enables us to consume lots of stuff produced efficiently in other places).  The idea is implicit in the government’s own target to see exports as a share of GDP rise from around 30 per cent to around 40 per cent over the next decade or so.  But the general notion isn’t original to this government –  it has been a feature of New Zealand economic debate, and aspirations, for decades.

New Zealand hasn’t done particularly well on that score – nominal exports as a share of nominal share have barely changed over the last 25 years.

exports to gdp

Nominal export values are, of course, thrown around by fluctuations in export prices –  a particularly important consideration for a commodity exporting country.

But what about export volumes?  I dug out the OECD’s quarterly data on real export volumes.  I had a look at what had happened to export volumes for OECD countries (plus Latvia and Lithuania) since the end of 2007.    There is no ideal starting date, but the end of 2007 is just prior to the widespread recession of 2008/09, and in many countries export volumes slumped during the recession and subsequently recovered and I wanted to avoid those short-term fluctuations..

If we look at total export volume growth since the end of 2007, New Zealand doesn’t look too bad.  Total export volume growth was a little faster than for the G7 countries taken together, although a little slower than the EU countries or the euro area.  When one allows for the rising role of global value chains, which have boosted gross cross-border trade in many European countries (and which aren’t a feature of commodity trade), perhaps New Zealand’s performance doesn’t look too bad.

real exporrt vol growth

But, of course, New Zealand has had much faster population growth than most OECD countries – in some sense then we’ve needed more export growth than, say, a country with no population growth might have needed.  The OECD doesn’t have quarterly per capita data, and tracking down quarterly population estimates for many countries would take more effort than I have time for at present.

Instead, this chart simply subtracts the growth rate of real GDP since 2007 from the growth rate of real exports over the same period.   On this indicator, we are right back towards the bottom of the OECD.

gap between X and GDP growth

It isn’t necessarily a surprising result.  On the one hand, we’ve had to divert real resources from other activities to undertake the repairs and rebuilding in Christchurch. And on the other hand we have chosen –  as a matter of active policy –  to increase the population quite rapidly, which meant that resources that might otherwise have been able to be used to grow export businesses (at a probable lower real exchange rate) have had to be used to build the domestic capital stock (public and private) a higher population needs.

But if it shouldn’t be a surprising result –  just a logical outcome of shocks and choices –   it certainly isn’t one suggesting we’ve made any progress towards positioning New Zealand to begin to close the gap between our productivity and material living standards and those in the rest of the advanced world.