How key appointments are made

After a spate of posts in the last few days about the Reserve Bank reforms, I’d intended to change topics for a while.   But then I noticed that the new Opposition spokesperson on Finance, Amy Adams, had weighed in, expressing concerns about a couple of aspects of what the Minister of Finance had announced on Monday.

This is how interest.co.nz reported Adams’ concerns

Under the new Policy Targets Agreement (PTA), [actually, under the amended Act] a seven-member Board – with four internal Reserve Bank members and three external appointees, selected by the Minister on the recommendation from the RBNZ board – will be established.

There will be a Treasury representative who will sit on the committee as well but will not have voting rights.

Adams says the fact that Robertson is able to appoint almost half of the board “creates a live question about the degree to which that allows him to exert political influence.”

Although National supports the introduction of the MPC, she says the Reserve Bank already operates with an informal decision-making committee within the bank and that process was working well.

Adams has also taken a swipe at the fact a Treasury representative will sit on the MPC.

“They are the senior Government official, their job is to deliver on the Government’s objective,” she says.

“So, you’re effectively going to have a senior Government official that reports to the Minister and three people who are appointed by and able to be removed by the Minister, sitting in and influencing those decisions and those discussions.”

I don’t want to spend much time on the issue of having a non-voting Treasury representative as part of the new Monetary Policy Committee (MPC).  Reasonable people can differ on the merits of that, and whether there are any real benefits.  On balance, I favour the model the Minister of Finance has adopted.   But in terms of the concerns Adams raises, it is worth remembering that in Australia the Secretary to the Treasury (in a more politicised public service) is a voting member of the RBA Board, and no one questions the operational independence of the RBA.  And in a more direct parallel to the model proposed here, in the UK –  under a modern governance system established only 20 years ago  –  there is a non-voting Treasury representative at MPC meetings, and that seems to have been generally accepted to have worked well, and not to have undermined the independence of the Bank of England (although the individualist approach –  where MPC members can speak out –  probably provides an added safeguard).    It will be important to look at the specifics of the legislation on this point, and for there to be good protocols in place, but I don’t think that what has been announced to date poses particular problems.   If the Minister wants to put pressure on the Governor (now) or the Committee later on specific OCR decisions, he doesn’t need mid-senior level Treasury officials to do so.

In that interest.co.nz article, I’m quoted as suggesting that Amy Adams is “completely wrong” in her point about the appointment process.  That is for two, quite different, reasons:

  • first, Amy Adams’ comments suggest she hasn’t understood that the Minister will only be able to appoint people nominated by the Board (as is the case for the Governor now).  The Minister can reject nominees, but can never replace those names with his own people.   The Minister has no discretion.
  • second, direct and largely unfettered ministerial appointment is the way we typically do things in the New Zealand system of government, including for very sensitive positions for which the integrity and independence of the individuals is paramount.   It is also the way most key decisionmakers on monetary policy in other countries like our own are appointed.

Here is how appointments are made to various key public sector roles in New Zealand

Chief Justice Governor-General on advice of the PM
Other judges Gov-Gen on advice of Attorney-General
Police Commissioner Gov Gen on advice of the PM
Electoral Commissioners Gov Gen on advice of House of Representatives
Auditor General Gov Gen on advice of House of Reps
Ombudsmen Gov Gen on advice of House of Reps
Privacy Commissioner Gov Gen on advice of Minister of Justice
Human Rights Commissioners Gov Gen on advice of Minister of Justice
Commerce Commission Gov Gen on advice of Minister of Commerce
Parole Board Gov Gen on advice of Attorney General
Health and Disability Commissioner Gov Gen on advice of Minister of Health
Broadcasting Standards Authority Gov Gen on advice of Minister of Broadcasting
Electricity Authority Gov Gen on advice of Minister of Energy
IPCA Gov Gen on advice of House of Representatives
Takeovers Panel Gov Gen on advice of Minister of Commerce
Transport Accident Investigation Commission Gov Gen on advice of Minister of Transport
Financial Markets Authority Gov Gen on advice of Minister of Commerce

And, of course, the Governor-General is appointed by the Queen on the advice of the Prime Minister.

Every single one of these really important positions  –  with the potential to do considerable mischief as well as good –  is appointed directly by elected politicians.  It is how we get accountability –  we can toss out politicians, they are forced to take questions in Parliament etc etc.   In some cases, there might be statutory qualifications appointees have to meet –  eg lawyer of seven years standing –  but I’m not aware that in any of these key public roles the relevant Minister, or Parliament itself, is constrained to only appoint someone other people have given them as nominations.

There is no obvious reason why the key decisionmaking roles at the Reserve Bank should be any different  (and the key roles at the Bank aren’t the Board itself –  which is really just a nominating (and cheerleading) committee –  but the Governor and the members of the future Monetary Policy Committee).  These people have a great deal of effective discretion and, if they get things wrong, can cause, or materially exacerbate, recessions or booms.  The standard approach anywhere else in the New Zealand public sector would be for such appointments to be made by the Governor-General on the advice of the Minister of Finance.   We can hold the Minister accountable, but have no way of holding the Board accountable (indeed, when the new MPC is appointed most of the Board members themselves will have been appointed by the previous government).

Direct and unfettered appointment by an elected politicians is also the way for most monetary policy decisionmakers in other countries like ours.     There is a nice summary table in this Reserve Bank Bulletin article from few years back.     As just a few examples:

  • in Australia, all members of the Reserve Bank Board (the monetary policy decisionmaking body), including the Governor and Deputy Governor are appointed directly by politicians,
  • the same is true in Norway,
  • in the UK, seven of the nine MPC members are directly appointed by the Chancellor of the Exchequer (two are senior staff, appointed by the Governor),
  • ECB Governing Board members are all directly appointed by politicians
  • All members of the US Federal Reserve Board of Governors are appointed by the President, subject to Senate confirmation.  (Heads of the regional Feds –  who sit, by rotation, on the FOMC – are not, and there is some question about the constitutionality of those arrangements.)
  • All members of the Swedish monetary policy board are appointed by a parliamentary committee,
  • Bank of Japan monetary policy members are appointed by the Cabinet
  • In Israel, five of the six MPC members are appointed by the government (one by the Governor).

It would be a much more normal approach, and one that provides ongoing democratic legitimacy, for the Governor and Deputy Governor and all external members of the MPC to be appointed directly by (the Governor-General on the advice of) the Minister of Finance.  Those choices shouldn’t be restricted to those on a list delivered by faceless company directors, with no subject expertise and no democratic legitimacy or accountability (and who may well have been mostly appointed by the previous government).  If the MPC is to have more than two internals –  as the Minister proposed in his announcement on Monday – perhaps it would be reasonable for one additional internal to be appointed by the Governor, in consultation with the Minister (the Bank of England approach).     There is no obvious role –  or likely added value –  from involving the Board in the process at all.  Arguably, involving them in appointments not only lacks democratic legitimacy, but also detracts from their primary role of (on behalf of the public and the Minister) holding appointees to account.

As I’ve suggested previously, if there was still unease about the Minister appointing cronies –  though see the long list above of important positions that ministers do directly appoint to –  I’ve suggested there might be merit in requiring non-binding confirmation hearings before Parliament’s Finance and Expenditure Committee before the Minister’s appointees take up their roles.   This approach has been adopted in the UK.

As I hope I’ve shown, the model I’ve argued for –  and will continue to advocate –  is not some radical politicisation of monetary policymaking, nor even some idiosyncratic Reddell scheme.  It is the normal way we do things in New Zealand.  It is the way most democracies appoint most of their monetary policy decisionmakers. (It was also much the model advocated by one other submitter to the review.)  One might have hoped that the Opposition spokesperson on Finance, herself a former senior minister, would know that.

Then again, one might have hoped that The Treasury and the Independent Expert Advisory Panel (appointed by the Minister to assist with the review of the Reserve Bank Act) might have recognised that.

As part of Monday’s announcement, a variety of papers were (commendably) pro-actively released.  One of those papers was the report of the Independent Expert Advisory Panel.   This is their discussion of appointment processes

The Panel recommends that all MPC members are appointed by the Minister of Finance on the recommendation of the Board. This is the current process for appointing the Governor. As each committee member will hold considerable decision-making powers that impact on the wider public, the Panel considers Ministerial appointments necessary to ensure members have democratic legitimacy. Ministerial appointments are consistent with typical international practice, and the arrangement whereby the Minister appoints on the recommendation of the Board should be retained to ensure merit-based selection of external MPC members, and to limit the risk that policy decisions of the MPC are politically influenced.

They don’t seem to have recognised at all the distinction between the Minister being free to appoint whoever he or she wishes – the typical model abroad, or for other government agencies here –  and a situation where the Minister can appoint only those someone else has nominated.  The former has democratic legitimacy (even if it has other risks), while the latter provides little more than a figleaf.  And, frankly, if I were worried about political influence on decisions, I’d probably be more concerned about the Police Commissioner and judges –  see table above –  but the Panel doesn’t even engage with these parallels.  They appear to have been signed-up members (perhaps only implicitly) to the “central banks are different” school of thought, beloved of central bankers.  Central banks are just one of many important official agencies and, without compelling arguments to the contrary, should be subject to much the same appointment, governance and transparency provisions as those other agencies.  The Panel makes no effort to identify the compelling argument for such a different approach.

Then again, it appears that The Treasury was no better, and their failure is even less excusable, given their role as one of the public sector central agencies.       Treasury’s advice to the Minister of Finance on Stage 1 of the Reserve Bank Act review was released, as was the Regulatory Impact Statement that accompanied the Minister’s Cabinet paper.

In the Treasury advice there is only this

the Treasury does not support the Reserve Bank’s recommendation to have internal MPC members appointed by the Reserve Bank Board on the recommendation of the Governor. This is because it would mean decision-makers are not directly appointed by a democratically elected Minister, as is the typical practice internationally, and also because it would introduce a hierarchy into the committee, with the Governor having an explicit power over other committee members.

Treasury shows no sign at all of having recognised the distinction between the fig-leaf approach (Minister can appoint only people others have nominated) and genuine appointment by a democratically elected Minister.  The latter is the typical practice internationally.  The former is the  –  highly unusual –  model for the Reserve Bank.

Perhaps even more astonishingly –  given that the advice document no doubt had length constraints and was highlighting only points where there was disagreement with the Panel –  the Regulatory Impact Statement also shows no sign of recognising the standard New Zealand model for key appointments, or the typical central banking practice, as a serious option for consideration here.    They claim to have restricted the options they evaluate to those “the Treasury considers most appropriate”, and yet they include no discussion at all of what should really have been a default option –  appointment as most key public sector appointments are done in New Zealand, by the Governor-General on the (unfettered) advice of the Minister of Finance.  There might prove to be compelling reasons to depart in some respects from that model, but not to include it at all seems to border on the negligent.

Revisiting 1996

After the 1996 election, and as a small part of the deal whereby New Zealand First went into government with National, the Policy Targets Agreement governing monetary policy was amended.  The first section now read, adding the text I’ve underlined.

1. Price Stability Target

Consistent with section 8 of the Act and with the provisions of this agreement, the Reserve Bank shall formulate and implement monetary policy with the intention of maintaining a stable general level of prices, so that monetary policy can make its maximum contribution to sustainable economic growth, employment and development opportunities within the New Zealand economy.

Going into that election, New Zealand First had campaigned for material changes to the way monetary policy was run.  What it got was an increase in the target range (from 0 to 2 per cent, to 1 to 3 per cent) and those new words.   Inside the Bank, we never paid any attention to the words ever again.   They never came up in policy deliberations.   They were seen as some mix of political rhetoric and a statement of the obvious –  from our perspective, pursuing price stability was the best and only contribution monetary policy could make to those other worthy things.  Note that in negotiating the drafting, Don Brash even got the crucial word “sustainable” in.

In the new Policy Targets Agreement signed yesterday, this is how the equivalent paragraph reads.

1. Monetary policy objective

a) Under Section 8 of the Act the Reserve Bank is required to conduct monetary policy with the goal of maintaining a stable general level of prices.

b) The conduct of monetary policy will maintain a stable general level of prices, and contribute to supporting maximum sustainable employment within the economy.

All but equivalent I’d say.   Curiously enough, I didn’t see the parallel drawn in the material Treasury released (including the RIS) on the new formulation of the monetary policy objective.

To be sure, as I noted in yesterday’s post on the PTA, the new PTA does include a couple of other references to employment.  Employment is added to the list of things where the Reserve Bank Governor is supposed to seek to avoid “unnecessary instability”.  However, this is the clause the Reserve Bank has been relying on in the last few years to defend its belated and reluctant response to core inflation outcomes persistently well below the target midpoint.  And the Bank will be required to discuss, in each Monetary Policy Statement, how current OCR decisions are contributing to supporting maximum sustainable employment.   The Minister has attempted to suggest that this provision will give bite to the new employment focus.  If he really believes that, then –  despite all the time he spent on FEC  in Opposition –  he obviously hasn’t looked at all carefully at how the Reserve Bank complies with the current statutory provisions governing Monetary Policy Statements –  formulaic at best.  As I noted yesterday, it is easy to predict the formulaic language now –  brand new recruits could write the words, (and may well do so).

I’ve been a bit ambivalent about changing the statutory (or PTA) goal for monetary policy.   Active discretionary monetary policy exists for output and employment stabilisation reasons, and in principle it is worth recognising that.   Since day one of the current Reserve Bank Act, that focus has been implicit in the way Policy Targets have been constructed.  It is not a new thing.    On the other hand, there has been a suspicion that Grant Robertson was more interested in things looking a bit different –  like that wording Winston Peters had introduced in 1996 – than in things actually operating differently, and thus on occasion I’ve suggested this change was more about political positioning and “virtue-signalling” than anything else.

And that might be fine if the Reserve Bank had been doing a superlative job in the last decade, but somehow there was still debate in some quarters as to whether output/employment stabilisation was a legitimate objective at all.  But they haven’t.   Core inflation has been persistently below the target midpoint –  the focus of the PTA –  for years, and even on their own (diverse) estimates –  see their chart below – the unemployment rate was above the NAIRU for almost all the decade.

nairu x2

That combination just shouldn’t have been.    Monetary policy – again on the Bank’s own reckoning –  works much faster than that.  Instead, through some combination of forecasting mistakes and biases towards tighter policy –  recall Graeme Wheeler’s repeated hankering for “normalisation” and his actual ill-judged tightening cycle –  they allowed the economy to run below capacity for years, more people than necessary to stay unemployed for longer, and didn’t even come close to deliver inflation averaging around 2 per cent.

And yet when –  as he was on Radio New Zealand this morning – the Minister of Finance is asked what difference the new PTA (and proposed statutory amendment) will make he flounders, and won’t even refer to the experience of the last decade.    His officials seem to be as bad.  In the Regulatory Impact Statement section on the proposed new objective, here is what The Treasury had to say

The main non-monetised benefit is to ensure that monetary policy decision-makers continue to give due regard to the short term impacts of monetary policy on the real economy. This is intended to improve the wellbeing of New Zealanders by ensuring that monetary policy seeks to minimise, or does not exacerbate, periods of economic decline.

The new Governor’s comments yesterday were along similar lines –  just recognising how things are done already.

So the experience of the last decade is just fine is it?   If so, the proposed law change really must be just about political rhetoric and positioning.

To be clear, there are limits to how much any new words themselves could have changed the Reserve Bank’s approach to monetary policy.  And, as everyone recognises, in the longer-term, monetary policy can only affect nominal variables (inflation, price level, nominal GDP etc) not real ones (employment and output).   But the government –  supported by advice from The Treasury –  appears to have chosen the weakest formulation possible, with little or no effective buttressing elsewhere in the Policy Targets Agreement.   There is, for example, no requirement to publish estimates/forecasts of “maximum sustainable employment” or associated concepts such as the NAIRU, and no requirement to account, look backwards, for how monetary policy has done in effectively minimising cyclical deviations in employment/unemployment.

Individuals and organisational culture matter a lot.   Arguably they matter more, at the margins, than precise wording in documents like the PTA.    The Reserve Bank’s culture appears over the last decade to have backward-looking, constantly fighting the last war –  surprisingly strong inflation in the years running up to 2008 –  insular, and –  as has been the case for decades –  not really much interested in labour market outcomes at all.  In all that, they’ve been backed by the Reserve Bank’s Board.

Adrian Orr is a strong character, and has an incentive –  all those Stage 2 review battles to fight –  to at least sound different than his predecessor Graeme Wheeler.  Then again, he emerged through a selection process undertaken by the Board –  which was explicitly happy with what had happened in the previous decade –  and his Minister has given no indication that he is anything other than happy with the actual past conduct of monetary policy.  A pessimist would suggest that, to the extent we see change, it will be cosmetic more than substantive.  Cosmetics have their place, but substance –  avoiding repeats of situations where at the same time core inflation is well below target and unemployment is well above a NAIRU, including in the next recession – matters rather more.

It is interesting to ponder how the new Governor –  single decisionmaker for now –  will address the question of what “maximum sustainable employment” is.      I’m expecting something reasonably vacuous and circular –  “since we (again) forecast inflation getting back to target in a couple of years time, by definition – by construction of our model –  employment must be close to the sustainable maximum”.    Doing so will be easier because the employment rate has no public resonance in the way that the unemployment (or even underemployment) rates do.

But here is a chart of HLFS employment rates since the survey began in 1996.

employment rates by sex

Female employment rates have been trending upwards, as one might expect as part of social changes.   However, male employment rates (73.4 per cent) are still well below where they were in 1986 (77.2 per cent).   In plain English senses, there is little reason to suppose we are anywhere near maximum sustainable employment rates for the economy as a whole.  I’m sure the plain English sense isn’t intended, but still.

And those male employment rates aren’t just about more young people being in tertiary education –  who are, in any case, outweighed by more old people working.  Here are the three prime-age male employment rates

employment rate prime age males For all three groups, employment rates now are materially below those thirty years ago, in a more deregulated labour market.
It just reinforces my sense that in making changes they’d have been better off using unemployment rates as a reference point, and requiring the Bank to produce a richer array of labour market analysis.   The actual new wording will easily translate to nothing if that is what the Governor wants.

And, finally, almost in passing, there has been coverage of former Reserve Bank chief economist Arthur Grimes’s criticisms of the change in the monetary policy objective, in which he talked of a “disastrous route”, a “crazy target”, the potential for the changes to destabilise the economy and so on.  He went on to assert that most episodes of financial instability in the world have flowed from the the United States, and a lot of that has been caused by their dual objective system.

I’m not quite sure which episodes Arthur has in mind with that latter comment, although I assume that the 2008/09 crisis is the principal one he is thinking of.   It is perhaps worth remembering that our Reserve Bank itself has produced research suggesting that the way it was reacting to incoming data in the decade or two prior to 2008 was very similar to the way the Federal Reserve and the Reserve Bank of Australia were reacting.   That isn’t surprising. In practice, whatever the precise wording of the respective mandates, all three were functioning as flexible inflation targeters.  It hasn’t been easy to rerun the model for the last decade –  since for a prolonged period the Fed was at an effective interest rate floor.       The way the two Antipodean central banks have conducted policy have still been fairly similar and thus –  even though neither reached the effective interest rate floor –  both countries have had below-target inflation in the context of labour markets that haven’t exactly been overheating (the RBA still thinks unemployment there is above the NAIRU).

Of course, these comments are a bit of a double-edged sword.  I think Arthur Grimes is quite wrong in his suggestion that our changes are very damaging and dangerous.  On the other hand, they are also a reminder that individuals and institutional cultures (and blindspots) often matter more than precise specifications of statutory objectives.  Changing the statutory mandate here, in deliberately vague ways, won’t make any helpful difference –  other than perhaps in political marketing –  unless the new Governor is about to lead some material culture change, and bring a fresh focus on avoiding prolonged periods of unnecessarily high unemployment.

It is his first day, so only time will tell.  For now, the signs aren’t encouraging.  But perhaps there will pleasant surprises in store.

Proposed Reserve Bank Act changes – Stage 1

My previous post concentrated mostly on the new Policy Targets Agreement, which will govern monetary policy, under the current Act, for the next year or so.

In this post, I want to concentrate on the announcements made by the Minister of Finance about the first stage of his planned legislative reforms.    There is a summary graphic, and a set of questions and answers.

The proposed reforms represent a step forward.  We’ve been in the peculiar position for almost 30 years in which one individual, not even appointed directly by the Minister of Finance, made all the monetary policy decisions.  It made it easy to know who to fire –  that was the argument made for the model in the late 1980s – but it was a model that was out of step with how almost every other public agency was run and (as became increasingly apparent) with how monetary policy was run in most other countries.   In a free and democratic society, committees –  with ranges of views, and the implicit checks and balances a range of individuals provide –  should be how major public authority decisions are typically made.   It is little consolation that successive Governors drew on advisory committees to assist their decisionmaking: on the one hand, all members of those committees owed their positions to the Governor, and on the other, institutions need to be resilient to bad appointees, not just get along moderately well in normal times.   And if some advisers were happy to disagree (and Governors sometimes even welcomed a range of views), others weren’t –  I recall one Assistant Governor who told us that he saw his role on the OCR Advisory Group as being to back the Governor.

But that particular battle now appears to have been fought and won –  albeit belatedly (Treasury –  and the Green Party –  were calling for structural reform years ago).    The Labour Party campaigned on, and the government has now promised legislation to give effect to, moving to a statutory committee model.  Today’s announcement fleshes out some –  but not all –  of the details.

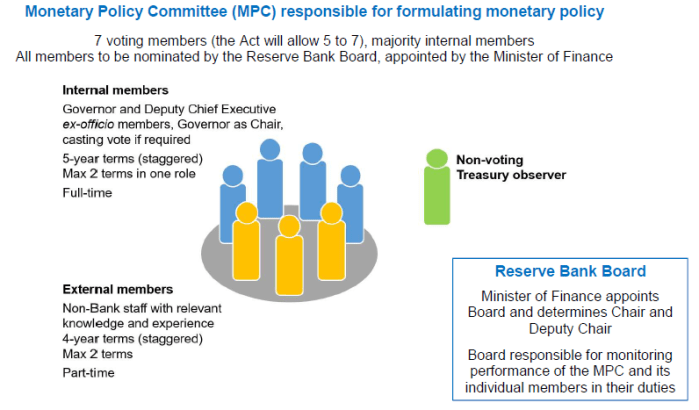
Here is the summary graphic

rb reform graphic

The key aspects are that

  • there will always be a majority of Reserve Bank staff,
  • there will be a minimum of two externals,
  • appointments will be made by the Minister of Finance but s/he will be able to appoint only people nominated by the Reserve Bank’s Board.

This model is a slight improvement on what the Labour Party campaigned on.  In that model, the Governor himself would have appointed all the MPC members, internal and external.  But the improvement is slight, for two reasons:

  • first, because a majority of the committee will be internal, all appointed to their executive day jobs (eg Assistant Governor, Chief Economist or whatever) by the Governor.  No Board is going to turn down the Governor’s recommendation as to which of his staff should be on the MPC.   Thus, the Governor in effect appoints the majority of the committee.  For a good Governor –  really welcoming diversity and debate –  it mightn’t be a problem.  For more average appointees, it reinforces the risk of continued groupthink and a voting bloc on the committee.  Remember that the executive members have their pay and promotion determined by the Governor,
  • second, because the Reserve Bank Board is likely to look largely to the Governor for advice on who should be the external appointees to the committee.   Recall that the Governor himself is a member of the Board –  even though its prime job is to hold him to account –  and most of the Board members have no subject expertise, no resources, and little reason not to defer to the Governor (whom they themselves appointed).  Perhaps some reasonable people will be found to serve, but it seems exceptionally unlikely that anyone awkward, or with a materially different perspective, will be allowed in the door.  In all likelihood, we’ll end up with something not much improved on the model in place for the last 17 years or so –  in which the Governor has had a couple of part-time external advisers, appointed mostly for their business connections and knowledge, rather than their perspectives on macroeconomic policy.

This simply isn’t the way public appointments should be made.   The Minister of Health appoints people directly to DHBs, the Prime Minister directly determines who will be appointed as the Commissioner of Police, ministers appoint directly members to the board of all sorts of decisionmaking crown entities (including, in the financial areas, the Financial Markets Authority), and so on.

And direct appointment by elected politicians is the way most top central bank appointments are made in other countries.   In Australia, it is true of the Governor, Deputy Governor, and all the RBA Board members. In the UK, all but two of the MPC members are directly appointed by the Chancellor, and in the US all the members of the Federal Reserve Board of Governors are appointed by the President, subject to Senate confirmation.

I hope someone asked Grant Robertson why he resisted bringing the appointment process for the Reserve Bank of New Zealand positions into the international mainstream, because I don’t understand it –  and there is nothing to justify his choice in rhe Q&A material that has been released.    Ministers may not have much subject expertise, but they have legitimacy –  they are elected, and have to front to Parliament each week.  The Reserve Bank Board members have no subject expertise, and no legitimacy –  indeed, at any one time, half will have been appointed in the previous term of government.  They might be competent behind-the-scenes professional director types, but that’s all.  And yet they are being empowered to choose who will run New Zealand macroeconomic policy.  It is a gaping democratic defict that really should have been fixed, not exacerbated.   And it is not as if the Board’s practical track record might persuade one to set aside principled objections to the process –   they’ve just been cheerleaders, more focused on having the Governor’s back, than on serving the public interest.

The appointment process is one reason why I call today’s announcement as a big win for Reserve Bank management.  Committee appointments will safely be in the hands of the Governor and his team (Board and management).

The other reason why it is a big win for Bank management is the announcements about the processes that the new Monetary Policy Committee will be expected, or required, to adopt.

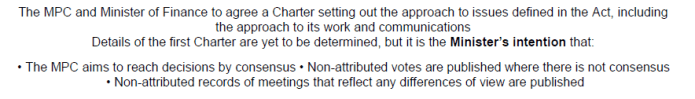
Here is part 2 of the Minister’s graphic

RB graphic part 2

The idea of a charter makes sense.  Arrangements around how the new MPC should work are probably better not legislated –  although I think a requirement to publish minutes (although not the form of those minutes) should be in statute –  and thus able to evolve with experience and individuals.   Beyond that, I think the Minister has made the wrong choices when articulating what he will be looking for, largely caving to the preferences of the Bank’s management, who were horrified by the idea of open debate and a transparent recording of views and associated individualised accountability.

Several of better inflation-targeting central banks are much more open –  notably, those of the UK, the US, and Sweden.  But here is what the Minister proposes

How will the MPC take decisions?
It is expected that the MPC will aim to reach decisions by consensus. Where a consensus cannot be reached, decisions will be taken by a majority vote, with the Governor having the casting vote if necessary.

The Governor will chair the MPC and will be the sole spokesperson on its decisions.

What documents will the MPC publish?
In addition to Monetary Policy Statements, it is intended that the first Charter agreed between the Minister and the MPC will require the MPC to publish non-attributed meeting records that reflect differences of view between MPC members where they exist. It is also intended that the MPC will publish the balance of votes for any decision where a vote is required, without attributing votes to individuals. This approach will balance the need for transparency about the decision-making process with the need for clarity and coherence in communicating the MPC’s decisions.

Frankly, it seems unlikely we will ever see vote numbers.  Recall that the Governor has an internal majority on the MPC, who can – and may well –  caucus before the meeting and agree a collective view.  The externals start out in a minority,  will have already passed some sort of inoffensiveness test to get appointed, and they appear unable to articulate their views in public, so the incentive to record an anonymous dissenting vote seems pretty low.   A management-driven “consensus” seems likely to be the default option, and over time that will become the self-reinforcing norm, because the signal in one external insisting on recording a dissenting vote will be sufficiently attention-grabbing that often enough people just won’t go that far.  Far better to normalise the fact that there is –  and should be –  quite a range of views, whether about how the economy will unfold and how monetary policy should respond to the risks.   As I’ve noted before, it is not clear how the citizens of the US, the UK, or Sweden or worse off for an open and transparent process of individual responsibility and accountability, and an ongoing moderately open contest of ideas.  Bureuacrats don’t like it –  of course – but we should be designing public agencies around the interests of the public, including those scrutiny and accountability, not around the interests of the bureaucrats.  In this case again, Grant Robertson appears to have bowed to the personal interests of the officials.

There are some good aspects to what the Minister has announced:

  • as I noted in my earlier post, the move away from a Policy Targets Agreement model to a system in which the Minister sets the operational objectives, and the associated official advice is pro-actively published, is a step forward, and almost inevitable with the move to a committee.  But there are lots of operational details to be clarified, including (for example) how frequently the Minister can change such objectives (the default PTA has been for five years),
  • on-balance, the inclusion of a non-voting Treasury observer on the MPC is probably a modest step forward, but it depends how it works.  The documents suggest this person is simply there to pass on information about fiscal policy, and given the substantial time commitment the MPC role is likely to entail it could end up filled by a fairly junior Treasury person (by contrast, in Australia the Secretary to the Treasury sits on the RBA Board),
  • the Minister is moving to provide for the appointment of the Board chair and deputy chair to be made directly by him (the normal model) rather than chosen by Board members themselves.  At the margin this will help remind the Board that they work for the Minister and the public, not for the Bank.  To be fully effective, however, the Minister should also amend the Act to allow him to dismiss Board members for failing to be sufficiently vigorous in holding the Governor and MPC members to account.

But there are also lots of issues that aren’t sorted out in the announcement today and which will only become clear when the legislation emerges (or in some cases when the charter is signed).  For example:

  • what are the limits of what the new MPC will be responsible for?    The Q&A material says that “For example, the MPC will also have responsibility for strategic choices around the monetary policy tools used by the Reserve Bank”, but does this include foreign exchange intervention strategy, issues around issuing digital currency, the terms of which the Bank issues physical currency etc (all relevant to zero lower bound issues).  Then again, perhaps these things don’t matter because the Governor has a built-in majority on the MPC?
  • what can individual MPC members be fired for (given expectations of consensus decisionmaking), or will the formalised accountability model –  which never amount to much in practice –  be largely got rid of?
  • whose will the forecasts in the Monetary Policy Statement be?  At present they are, formally, the Governor’s forecasts.

And then there is the Stage 2 part of the review of the Reserve Bank Act.   The Q&A document says

Phase 2 of the Review is currently being scoped. It will focus on the Reserve Bank’s financial stability role and broader governance reform. The Panel is due to give the Minister of Finance its recommendations for the scope of Phase 2 of the Review shortly. Announcements on this will be made in the coming months. Subsequent policy work will commence in the second half of 2018.

But given the increased role for the Reserve Bank’s Board in today’s announcement, the government seems to have already decided to retain something very like the current governance model and in particular the role for the –  historically useless –  Board.  I guess there is still time to reconsider before the Stage 1 proposals are legislated, but they’d be better off splitting up the Bank, setting up a Prudential Regulatory Agency, taking appointment powers directly into the Minister’s hands (perhaps with some non-binding confirmation hearings) and getting rid of the Board altogether.

Meantime, they will be celebrating at the Reserve Bank tonight.  As far as possible, the (effective) status quo has won out, and a more open and contestable system has lost out.

On the new PTA

The last ever Policy Targets Agreement was released this morning, signed by the incoming Governor and the Minister of Finance.  With it came the decisions the government has made on reforms to the legislative framework governing monetary policy (decision makers, governance, transparency etc).  We are now finally getting past the year in which first the outgoing Governor was a lame-duck, and then the period when there was no lawful “acting Governor” or lawful “Policy Targets Agreement” –  and even if you did regard both as lawful, they were no better than caretakers.   With the government’s planned reforms such an unfortunate hiatus should never happen again (as it doesn’t happen abroad).

The Policy Targets Agreement is the key document in short-term macroeconomic management in New Zealand: it is the mandate for the Governor in his role as single decisionmaker on monetary policy, and monetary policy is the active tool for short-term economic stabilisation.   This one isn’t expected to have a long life.  Once the new legislation is in place –  scheduled for next year –  the Policy Targets Agreement will be replaced by a mechanism in which the Minister of Finance unilaterally sets the operational objectives for monetary policy (the UK system), although only after receiving (published) advice from the Reserve Bank and the Treasury.   That is a welcome change –  not only does it put responsibility for goal-setting firmly where it belongs (with elected ministers) but it removes the awkward aspect of the current system, in which an incoming Governor has had to agree targets (sometimes dealing with quite technical points) before being appointed, and often with only limited staff advice.   It was also a necessary change once a committee, with evolving membership –  rather than a single individual –  was made responsible for monetary policy.

The new (shortlived) Policy Targets Agreement has a few changes, although mostly not of great substance.

  • there is an even longer statement of the government’s political aspirations (‘inclusive economy”, “low carbon economy”, an economy that “reduces inequality and poverty”) none of which has anything to do with monetary policy.  Closer to economic policy, there are worthy aspiration (“a strong diversified export base”) which monetary policy can’t do anything about, and government policy isn’t doing anything about.
  • the substance of the document has been shortened a bit, but mostly not in a good way.  For example,
    • if I welcome the deletion of the reference to asset prices added in 2012, I’m uneasy about removing the explicit expectation that in monitoring inflation the Bank shouldn’t just look at the headline CPI.
    • And perhaps it isn’t of much substance, but I’m interested that they chose to remove “average” from the requirement that policy “focus on keeping future inflation near the 2 per cent mid-point”.
    • And I am a little uneasy about the removal of the list of the sorts of event/shocks that might justifiably warrant inflation being away from target, and the removal of the requirement to explain, when inflation is outside the target range, what they are doing to ensure that future inflation remains consistent with the target.  At the margin, it slightly weakens formal accountability (weak enough in practice anyway) and –  in the current climate –  may weaken the impetus to get core inflation back to 2 per cent (after so many years),
  • there are several changes relating to the new employment aspect of the objective (which, contrary to Arthur Grimes, I consider neither ‘disastrous’ nor ‘crazy’, and which risk being more feeble and virtue-signalling in nature than anything else).
    • at a high level there is an expectation that “the conduct of monetary policy will….contribute to supporting maximum sustainable employment”,
    • adding “employment” to the list of in the provision requiring the Governor to seek to avoid “unncessary instability”, and
    • a requirement to explain in Monetary Policy Statements how “current” monetary policy decisions contribute to “maximum levels of sustainable employment”

Quite what, if any difference, these provisions make will really depend on the new Governor’s assessment.   His press release suggests no difference at all

Mr Orr said that the PTA also recognises the role of monetary policy in contributing to supporting maximum sustainable employment, as will be captured formally in an amendment Bill in coming months.

In other words, just formalising what is already there.  An approach that, not incidentally, delivered us an unemployment rate materially above the NAIRU –  on the Bank’s own numbers –  for most of the last decade.   At present, we can probably expect lots of rhetoric –  repeated references to the contribution the Bank is making –  and nothing of substance, although in fairness it may be hard to tell for some time (since the unemployment rate is now closer to a true NAIRU than it has been for some considerable time).  It will be interesting to see the Governor’s first MPS and the associated press conference.

Personally, I’d have preferred that the new requirements were specified in terms of unemployment –  explicitly an excess capacity measure. There probably isn’t a great deal in the issue, except that the current formulation tends to treat high rates of employment as a “good thing”, when there is little economic foundation to such a proposition. By contrast, minimising (sustainably) the rate of unemployment is more unambiguously a “good thing”.

Perhaps more disappointingly, it is fine to require the Bank to explain how current monetary policy decisions are contributing to maximum sustainable employment.  But that is the sort of obligation an undergraduate student of economics could meet without difficulty and without much substance.  It is unfortunate that the Bank is not being required to:

  • explain how past monetary policy decisions have actually contributed to maximum sustainable employment,
  • explain how its future monetary policy plans will do so (the Act requires the Bank to explain policy plans for the (rolling) next five years),
  • publish estimates of the maximum sustainable level of employment.

Finally, with the OCR at 1.75 per cent and the current economic expansion having run for eight or nine years, it is disappointing that the Minister and incoming Governor have not signalled anything about the importance of preparing for the next recession, and reducing the extent to which the near-zero lower bound (inability to take the OCR below about -0.75 per cent) could severely limit the capacity of the Reserve Bank to maintain price stability (or contribute to maximum sustainable employment) in the next recession.  That recession  –  timing unknown of course –  remains much the biggest threat of unnecessarily high unemployment.  And yet it still doesn’t seem to be being taken seriously.

I’ll do a separate post on the planned legislative reforms.   For now, suffice to say that if it is a small step in the right direction, it is a big win for the Reserve Bank establishment.

On aspects of Reserve Bank reform

On Tuesday Adrian Orr will take up the office of Governor of the Reserve Bank and thus become, for a time, the most powerful unelected person in New Zealand.  In some respects he will in fact be more powerful than the Prime Minister, albeit over a much narrower range of functions, because it is much easier to oust a Prime Minister (see Tony Abbott and Kevin Rudd) or to vote her down in Cabinet than it is to constrain, or oust, a Governor.

It is a statutory requirement that a Policy Targets Agreement, governing the conduct of monetary policy, be agreed between the Minister of Finance and any person he is considering appointing as Governor before that person is appointed.  It is less than ideal that, three days out from Orr taking office, 3.5 months on from the appointment being announced, there is still no Policy Targets Agreement.   Have Treasury and the Minister lost sight of the merits of predictability and certainty, and the fact that markets (and individuals and firms) operate on a forward-looking basis?     But, apparently, the PTA will finally be signed/released on Monday, just a day before Orr takes office.   One can only hope that there will also be a pro-active release of the background papers relating to this major component of New Zealand macroeconomic policy.  If not, I will immediately be lodging OIA requests.

We are also told that information on decisions the government has made about “the new decision-making structure at the Bank” and other material on Stage 1 of the review of the Act (focused on monetary policy) will be released on Monday. If the government has done the right thing, before too long Orr will be stripped of much of his personal power, to become primarily an agency chief executive, and perhaps primus inter pares on one or more committees.   That would be a long overdue reform.  Perhaps the Independent Expert Advisory Panel –  which, thus far, has operated totally in secret – might open themselves to questioning?   Perhaps too we might get some hints as to what Stage 2 of the review –  content as yet undefined –  will cover?  You can expect there will be several posts on these issues next week.

As for Orr himself, only time and experience will tell what sort of job he will make of being Governor.  Today’s Herald has what can only be described as a puff-piece profile –  they managed preferential access to the previous Governor (notoriously media-shy), and presumably are targeting ongoing good relations more than serious scrutiny.  After having had monetary policy a bit too tight for most of this decade, we can only hope that their cartoon –  the new Governor appearing to keep money securely locked away –  isn’t inadvertently prophetic.

New Reserve Bank Governor Adrian Orr. Picture / Rod Emmerson

There was another, rather more interesting, piece –  from BusinessDesk –  offering some  thoughts from various economists on Orr taking up his new role.

Hawkesby likened Orr to UK politician Boris Johnson. “The stereotype of a central bank governor is someone whose communication is cautious, reserved and dry. Adrian is more like Boris, with communication that appears more spontaneous and witty,” he said.

TD’s Beacher warned, however, “there is the risk that his ‘good clear communicator’ reputation means he could make a poor choice of words on occasion when explaining the bank’s stance on policy settings.”

I greatly enjoy a good Boris Johnson newspaper or magazine column, but a comparison to Boris Johnson seems a backhanded compliment at best.    My own thoughts on Orr, and some of the opportunities and risks were in these two posts –  here and here.).

But the main prompt for this post was an interest.co.nz column from a day or two ago by my former Reserve Bank colleague, and now consultant on things to do with financial regulation, Geof Mortlock.  That website often runs to long headings for their articles.  This one is headed

Ex-RBNZ and APRA official, Geof Mortlock, argues the RBNZ’s regulation of the financial sector is so inadequate this responsibility should be passed on to a new agency

The article is well-worth reading for anyone interested in New Zealand financial system regulation and supervision, or in the governance and conduct of the Reserve Bank.

A few weeks ago I outlined the case (and here) for splitting the Reserve Bank in two, and shifting the regulatory and supervisory functions into a new agency, perhaps called the Prudential Regulatory Agency.   Various other people have supported that sort of change, one senior business figure commenting that, if starting from scratch, structural separation would seem like a ‘no-brainer’.     My case for that reform was summarised this way

In favour of that position is that:

  • it is the more common model in advanced countries today (including Australia),
  • the synergies and overlaps between the various functions of the Reserve Bank are pretty slight (and probably no greater than, say, those between fiscal and monetary policy),
  • structural separation would allow for clearer lines of accountability, and
  • structural separation would allow for the creation of stronger, more effective, cultures  –  with appropriately skilled chief executives –  in each of the two successor institutions.

And so I welcome the fact that Geof Mortlock is also calling for structural separation

In my assessment, the best way to achieve the needed changes is to remove the financial regulation functions from the Reserve Bank and move them to a new, separate agency. I am sceptical of the willingness or ability of the Reserve Bank to change its cultural DNA.  Moving financial regulation out of the central bank was done in Australia with great success. Likewise, this has been done in many other countries, such as Canada, Germany, Japan, Sweden and Switzerland.

At present, we don’t even know whether the government is open to considering this option –  since nothing is yet identifiably included in the proposed Stage 2 of the review –  but they should.  It would be likely to make possible –  although there are no guarantees – a better monetary policy agency and a better regulatory one.

The bulk of Mortlock’s artice is actually about the Reserve Bank’s conduct of its regulatory responsibilities.  On some counts I strongly agree with him, and his observations and criticisms echo points I’ve made here on various occasions

The Reserve Bank’s approach to policy formulation and consultation on regulatory initiatives is deficient. Too often, the Bank has allowed far too short a period for affected parties to make submissions on regulatory proposals. All too often the Bank has often given the strong impression that it has little interest in the submissions it receives – i.e. that it is consulting for the sake of appearance and has no intention of modifying its approach in light of submissions. It generally provides inadequate responses to submissions and insufficient justifications for any decision to reject points raised in submissions. The argumentation for policy proposals is often poorly developed. Cost/benefit analysis is typically provided to justify the Reserve Bank’s preferred option, rather than being objectively and rigorously developed at an early stage in the policy formulation process. There is very little substantive independent assessment of the Reserve Bank’s cost/benefit analysis. In stark contrast, the Australian system provides for much more rigorous independent assessment of all regulatory proposals.

All of these deficiencies need to be rectified by imposing on the Reserve Bank much stricter requirements on consultation and cost/benefits analysis, and by bringing much stronger external scrutiny to the process. Similar arguments can be made for other regulatory agencies.

One could add that the Bank’s regulatory impact statements are typically a joke, with no independent internal or external review –  and thus simply serving to provide support for whatver a particular Governor has chosen to do.

One could also add that the Reserve Bank remains highly averse to public scrutiny of its regulatory role, regularly falling back on statutory provisions –  which themselves should be reviewed and refine –  designed to protect commercially-confidential information obtained in the midst of a crisis, but used much more broadly than that.  Thus, the Reserve Bank recently refused to release any of a consultant’s review of the director attestation regime –  a central element in the prudential system. The utter lack of transparency around the Westpac capital models issue, or the stuff-up around the Kiwibank capital instrument are other examples.    Perhaps more than some other government agencies, the Reserve Bank tends to treat the Official Information Act as a nuisance that really shouldn’t applied to them, rather than as an intrinsic part of our democratic system, and a normal part of being a government agency.   The “but we are different” mindset is a hard one to break.

Quite a bit of the rest of the article –  on the Reserve Bank’s regulation/supervision activities and rules –  I disagree with.   It is nearer territory Geof spent has most of his time on than it is for me.  Then again, Geof has been a regulator for a long time, and appears to make his living in part from providing advice on fitting in with international frameworks and standards.   Of itself, that doesn’t invalidate his views, but it is worth remembering the old maxim that

I suppose it is tempting, if the only tool you have is a hammer, to treat everything as if it were a nail.

And there isn’t much sign of any cost-benefit analysis in his proposals for spending quite a lot more money (or so it would appear) on these functions.  I’m certainly sceptical of governments and bureaucrats wanting to spend more of our money on ‘financial literacy’ (as Geof suggests).  ‘Physician heal thyself’ comes to mind –  as Geof notes, the Reserve Bank will not even produce decent cost-benefit analyses for most of what it imposes on us.

I don’t doubt that the Reserve Bank could do some things quite a bit better –  process and culture included. I have also argued for removing some of the regulatory powers back to the Minister of Finance, and for more standardisation of the regime applying to all deposit-takers.   But I’m more sceptical that even more supervision is likely to be the answer to anything much.  A fair chunk of the global enthusiasm for more regulation, more supervision, over the last decade has been about backside-covering by politicians and regulatory agency officials after the crisis of 2008/09, with little attention to the inevitable limitations of regulation/supervision, including the incentives and constraints that face officials in regulatory agencies.  Action was demanded, and action was delivered, but the analytical basis for much of that action was often thin, and not well-grounded in serious sceptical scrutiny of the causes of the crisis.

And it is perhaps worth bearing in mind that New Zealand’s track record of financial stability has been pretty good.  Geof argues that

The Reserve Bank is also not well placed to proactively identify and resolve emerging problems before they become obvious or the financial institution is about to fail. The recent failure of CBL Insurance is an example of this. In earlier years, the Reserve Bank was slow to detect and respond to problems in DFC (which failed in 1989) and BNZ (which came close to failing in 1990).

I‘m not sure this is very persuasive.  On the one hand it is worth bearing in mind that it appears the Reserve Bank was onto the CBL problems well before the market was –  including bankers lending CBL new money –  and the DFC/BNZ failures were almost 30 years ago, under different legislation in the earliest days of the Bank having any prudential responsibilities and in the immediate aftermath of far-reaching financial liberalisation (followed by booms and failures in various other countries including Australia and the Nordics).   And on the other hand, we could note the crises and failures/near-failures (of regulated institutions or indeed the system) of the last decade in countries as various as the United States, United Kingdom, Switzerland, Denmark, Belgium, Netherlands, France, Greece, Italy, Spain, Ireland and so on.  In many of those countries, the IMF had previously provided a tick in its FSAP reviews.  Several of those countries will have –  and did –  prided themselves on their regulatory agencies, on-site or in-depth detailed scrutiny and all.     Neither New Zealand nor Australia (nor Canada, nor Norway for that matter) ran into such problems.    APRA may like to flatter itself that Australia‘s avoidance of crisis was down to their fine supervision –  I’ve heard senior people run that line – and that New Zealand, free-riding on fine Australian supervision, was in the same boat.   My response to that claim would be, at best, ‘case not proven’.

It is also worth bearing in mind that the Reserve Bank isn’t the principal in this business, but the agent.  It hasn’t been –  and isn’t –  funded for more intensive regulation and supervision, and that is a choice successive Ministers of Finance –  advised by Treasury over the years –  have made.  In a sense, the Reserve Bank has done what Parliament  –  and Ministers –  asked it to do, and in that sense that question isn’t just about the Reserve Bank’s competence and capability but about choices our political system makes regarding the intensity of regulation.

All that said, if we might differ in emphasis, and in our confidence as to what value regulators and supervisors can add, we seem to be at one in favouring structural separation.  A good part of the case for such a reform is the ability to build a culture dedicated to doing excellently, and only, the regulatory and supervisory functions Parliament delegates to the Bank.  It is telling that, for a function that now bulks so large in the Reserve Bank‘s mandate, recent Reserve Bank Governors have had little background in banking or of financial system regulation (certainly true of Bollard and Wheeler, and to a lesser extent for Adrian Orr).  At best, financial regulation and supervision is a part-time focus for the Governor.  And the new Head of Financial Stability –  an appointment made by Graeme Wheeler as he was leaving, without advertising the position –  has no background in those areas at all.  We can and should do better.  That ball –  structural reform and separation –  is now clearly in the Minister of Finance‘s court.


So much company tax, so little investment

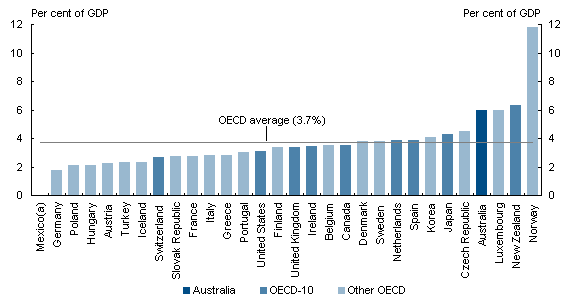
Almost 10 years ago I stumbled on this chart in the background papers to Australia’s tax system review.

Chart 5.11: Corporate tax revenue as a proportion of GDP — OECD 2005

Aus company tax as % of GDP 2008

I was intrigued, and somewhat troubled by it.   New Zealand collected company tax revenue that, as a share of GDP was the second highest of all OECD countries.   And yet New Zealand:

  • didn’t have an unusually large total amount of tax as a share of GDP, and
  • had had quite low rates of business investment –  as a per cent of GDP –  for decades, and
  • as compared to Australia, just a couple of places to the left, New Zealand’s overall production structure was much less capital intensive (mines took a lot of investment).

And, of course, our overall productivity performance lagged well behind.

Partly prompted by the chart, and partly by a move to Treasury at about the same time, I got more interested in the taxation of capital income.   After all, when you tax something heavily you tend to get less of it, and most everyone thought that higher rates of business investment would be a part of any successful lift in our economic performance.  That interest culminated in an enthusiasm for seriously considering a Nordic tax system, in which capital income is deliberately taxed at a lower rate than labour income.  It goes against the prevailing New Zealand orthodoxy –  broad-base, low rate (BBLR) –  but even the 2025 Taskforce got interested in the option.

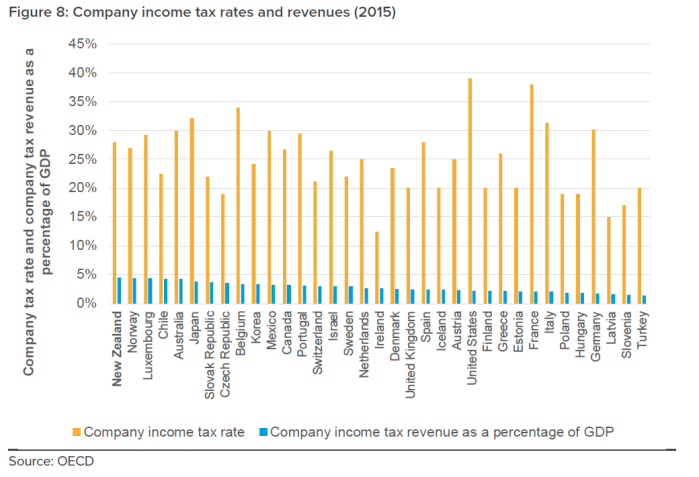
Flicking through the background document for our own new Tax Working Group the other day I came across this chart (which I haven’t seen get any media attention).

company tax revenue

It is a bit harder to read, but just focus for now on the blue bars.   On this OECD data New Zealand now has company tax revenues that are the highest percentage of GDP of any OECD country.   A footnote suggests that if one nets out the tax the government pays to itself (on businesses it owns), New Zealand drops to only fourth highest but (a) the top 5 blue bars are pretty similar anyway, and (b) it isn’t clear who they have dropped out (if it is just NZSF tax that is one thing, but most government-owned businesses would still exist, and pay tax, if in private ownership).

So for all the talk about base erosion and profit-shifting, and talk of possible new taxes on the sales (not profits) of internet companies, we continue to collect a remarkably large amount of company tax (per cent of GDP).  Indeed, given that our total tax to GDP ratio is in the middle of the OECD pack, we also have one of the very largest shares of total tax revenue accounted for by company taxes.

The Tax Working Group appears to think this is a good thing, observing that it

“suggests that New Zealand’s broad-base low-rate system lives up to its names”

There is some discussion of the trend in other countries towards lowering company tax rates, but nothing I could see on the economics of taxing business/capital income.  It is as if the goose is simply there to be plucked.

There are, of course, some caveats.   Our (now uncommon) dividend imputation system means that for domestic firms owned by New Zealanders, profits are taxed only once.  By contrast, in most countries dividends are taxed again, additional to the tax paid at the company level.    But, of course, in most of those countries, dividend payout ratios are much lower than those in New Zealand, and tax deferred is (in present value terms) tax materially reduced.

And, perhaps more importantly, the imputation system doesn’t apply to foreign investment here at all.   Foreign investment would probably be a significant element in any step-change in our overall economic performance.  And our company tax rates really matters when firms are thinking about whether or not to invest here at all.  And our company tax rates are high, our company tax take is high –  and our rates of business investment are low.  Tax isn’t likely to be the only factor, or probably even the most important –  see my other discussions about real interest and exchange rates – but it might be worth the TWG thinking harder as to whether there is not some connection.

Otherwise, as in so many other areas, we seem set to carry on with the same old approaches and policies and yet vaguely hope that the results will eventually be different.


A couple of Reserve Bank items

I had been meaning to write about a speech given last week by Grant Spencer of the Reserve Bank on so-called “macro-prudential policy”.  It was a thoughtful speech, as befits the man, and the last he will give as a public servant before retiring next week.

That it was thoughtful doesn’t mean that I generally agreed with Spencer’s (personal, rather than institutional) views.  There were at least two important omissions.  First, as it has done over the last half-decade (and more) the Bank continues to grossly underplay the importance of land-use restrictions in accounting for increases in the prices of houses (and particularly the land under them).  Until they get that element of the analysis more central, it is difficult to have much confidence in what they say about housing markets, housing risks, or possible Band-aid regulatory interventions of their own devising.    And second, they constantly ignore the limitations of their own knowledge.  I’m not suggesting for a moment that they are worse than other regulators in this regard –  who all, typically, have the same blindspot –  but it might matter rather more from a regulator than exercises, and wants to be able to continue to exercise, large discretionary intervention powers, with pervasive effects over the lives –  and financing options –  of many New Zealanders.   If they won’t openly acknowledge their own inevitable limitations, and discuss openly how they think about and manage the associated risks, how can we have any real confidence that they aren’t just blundering onwards, fired by good intentions and injunctions to “trust us” rather than by robust analysis.  In respect of both these omissions, I hope –  without much hope –  that the new Governor begins to put the Bank on a better footing.

When someone asked me the other day if there was anything new in the speech, one thing I noticed was how far the Bank’s current senior management appears to have come over the last few months around possible changes to the governance of the Bank’s main functions.   Casual readers might not notice the change, because it is presented as anything but.  Specifically, this is what Spencer had to say.

Given the planned introduction of a new decision making committee (MPC) for monetary policy, the Review should consider establishing a financial policy committee (FPC) for decisions relating to both micro and macro prudential policy. The Reserve Bank has supported a two-committee (MPC/FPC) model in place of the current single Governing Committee, for example in the Bank’s 2017 “Briefing for Incoming Minister”.

Of course, it is only a few months since the Bank’s expressed preference was simply to take the existing internal Governing Committee (the Governor and the deputies/assistant he appoints) and recognise it in statute, as the forum through which the Governor would continue to make final decisions.

And what of the claim that the Bank has –  not just does now –  supported a two-committee model, including in its Briefing to the Incoming Minister late last year?  At very best, that is gilding the lily.

As I noted at the time, both in the main text of that Briefing, and in the fuller appendix (both here) they devoted most of their effort to defending the existing Governing Committee model.    The main alternative they addressed was a Monetary Policy Committee  but even then the most they favoured was enacting the current Governing Committee model, perhaps with a few outsiders appointed by the Governor, and with the Governor remaining the final decisionmaker
“Provided the Governing Committee remains relatively small, we believe it should continue to make decisions by consensus, with the Governor having the final decision if no consensus can be achieved.  “
The only mention of a Financial Policy Committee is (from page 9)

The Reserve Bank considers that some evolution in its decision-making approach may be appropriate.  We recommend that the review of the RBNZ Act be limited to your stated change objectives.  We consider a review along these lines could be completed reasonably quickly and we would be happy to prepare a draft terms of reference, in consultation with the Treasury.  A variety of arrangements are possible and these are discussed, alongside the rationale for the Bank’s preferred model, in Appendix 6.

Other legislative changes that may be desirable over time include:

– Creating separate decision-making committees for monetary and financial policy

Note the suggestion to the Minister to keep the forthcoming review of the Act to the minimum of what Labour had promised (which dealt only with monetary policy), with some vague suggestion that at some time in the future –  but not in this review –  separate committees “may” be appropriate.  It could scarcely be called a full-throated endorsement of change.

Of course, the Bank lost various battles.  The first stage of the review is being led by Treasury (dealing with the monetary policy bits) and the second stage will look at (as yet unidentified issues).   And it seems they must have recognised that the ground is shifting, and that it would be hard to defend the current single decisionmaker models for the Bank’s huge regulatory (policy and operational) powers once momentum gathered behind a committee model for monetary policy.  Whatever the reason, it is a welcome move on the part of the current management.  Of course, we have no idea what the new Governor –  taking office in a few days –  thinks about suggestions to curtail his powers.

And just finally on the speech, one element of good governance is obeying, and respecting, the law.    Once again, Spencer’s speech and press release have been put out under the title “Grant Spencer, Governor”.  He simply isn’t.  At best he is “acting Governor”, a specific provision under the Reserve Bank Act.  A “Governor” has to be appointed for a minimum term of five years.   If it were a lawful appointment, there is nothing shameful in being acting Governor –  the one previous example, Rod Carr for five months in 2002, never purported to be the Governor.   As it is, my analysis stills suggests that the appointment was unlawful, and thus Steven Joyce and the Bank’s Board (by making the appointment) and Grant Robertson (in recognising it) both undermined the law and good governance and marred the end of Spencer’s distinguished career.  At very least, those provisions of the Act should be reviewed as part of Stage 2.

Meanwhile, we are still waiting for the now-overdue results of Stage 1, for the report of the Independent Expert Advisory Panel (which, as far as we can tell, has neither sought submissions nor engaged in consultation) and for the new Policy Targets Agreement which wil guide monetary policy from next week.

Still on matters re the Reserve Bank, there is a column in the Dominion-Post this morning by Rob Stock having a go at the Open Bank Resolution (OBR) and associated hair-cut of creditors and depositors option for handling a failed bank.  Like me –  and many other people, including the IMF and The Treasury –  Stock favours deposit insurance.  But he seems to see deposit insurance and OBR as alternatives, whereas I see them natural complements.  Indeed, the only way I can ever see the OBR instrument being allowed to work, if a substantial bank fails, is if deposit insurance is also in place.

Stock introduces his article with a straw man argument that ordinary depositors can’t really monitor banks and so shouldn’t be exposed to any financial loss if a bank fails.  Not even the first point is really true.  There are, for example, published credit ratings, and any changes in those credit ratings –  at least for major institutions –  get quite a lot of coverage.  A huge amount of information is reduced to a single letter, in a well-articulated series of gradations.   Should one have vast confidence in ratings agencies?  Probably not –  although perhaps not much less than in prudential regulators, based on track records.  But if your bank is heading towards, say, a BBB- rating and you have any material amount of money it would probably be a good idea to consider changing banks, or spreading your money around.    No one thought that South Canterbury Finance or Hanover were the same risk as the ANZ, at least until the deposit guarantee scheme made putting money in SCF rock-solid safe, whereupon many depositors rushed for the higher yields.

But there is a broader point that many risks in life aren’t able to be fully monitored, controlled, hedged, avoided or whatever  One might become a highly-specialised employee in a firm or industry that fails, or is taken out by regulatory changes.  Regions and towns rise and fall, and take house prices with them.  Governments might one day free up land use laws, reducing house and land prices to more normal levels.  Wars and natural disasters happen.  Chronic illness can strike a family. Even a marriage can be hugely risky.    For the median depositor there is typically much less at stake in their bank account (and typical losses –  percentage of liabilities – on failed retail banks aren’t that large).

Are there potential hard cases?  For sure, and Stock cites one of them.   If you’ve just sold your mortgage-free house –  for, say $1 million –  and are settling on another house next week and your bank failed in the course of that week, you could be exposed to quite a loss even though you’d had no desire to be a creditor of the bank.   Cases like that are one reason why I favour the Reserve Bank opening up electronic settlement accounts –  central bank e-cash if you like –  to the general public.  There wouldn’t be much demand, but on those rare occasions like the house settlement example, you might happily pay for the peace of mind of an effective government guarantee.  I’m looking forward to the new Reserve Bank Bulletin article on such matters next month.

I don’t think those few extreme examples warrant full insurance for all individual depositors, no matter the size of their balance.  There are many classes of people struck by not-easily-monitorable illiquid risks (see above) I’d have more sympathy with.  But I’m a political pragmatist, and as I argued previously I just cannot envisage an elected government allowing a major bank to fail, allowing all creditors to be haircut, if there is no protection at all.    That is especially so when, almost by construction, the Reserve Bank –  the government’s agent –  will have failed in its duties (and probably kept crucial information from the public, as in the recent insurance failure case) for the situation to have got to that point.    A full bailout will typically be the path of least resistance.

And a full bailout will mean not just bailing out the grandma with a $30000 term deposit, or the person changing homes with $1m temporarily on deposit, but bailing out wholesale creditors –  domestic and foreign –  with tens or hundreds of millions of dollars of exposure.     Do that –  or set up structures that aren’t time-consistent and encourage people to believe in bailouts –  and any market discipline, even by the big end of town, will be very severely eroded.  And, in a crisis, we’ll be transferring taxpayers’ scarce resources to people   including foreign investors – who really should be capable of looking after themselves.  It has happened before and it will happen again.   But deposit insurance –  funded by levies on covered deposits – increases the chances of being able to impose losses on the bigger creditors if things go wrong.

Perhaps OBR would still never be used.  And there are costs to the banks in being pre-positioned for it.  But we shouldn’t easily give in to a view that any money lent to a bank is rock-solid, backed by government guarantees.  It is not as if there aren’t plausible market mechanisms that could deliver much the same result, at some cost to the depositor (eg a bank or money market fund that held only short-dated government or central bank liabilities).   But there is little evidence of any revealed demand for such an asset –  the cost presumably not being worth it to most people, to cover a very small risk.  By contrast, we voluntarily pay for fire or theft insurance –  often to cover what are really quite modest risks.

There may not be any more posts this week (and if there are, they won’t be of any great substance).   I have a couple of other commitments on Thursday and Friday and, as I’m sure many have discovered before me, broken bones seem to sap an astonishing amount of energy for something so small.

Taxes, housing, and economic underperformance

Two local articles on possible tax system/housing connections caught my eye this morning.  One I had quite a lot of sympathy with (and I’ll come back to it), but the other not so much.

On Newsroom, Bernard Hickey has a piece lamenting what he describes in his headline as “Our economically cancerous addiction”.    The phrase isn’t used in the body of the article, but there is this reference: “our national obsession with property investment”.   Bernard argues that the tax treatment of housing “explains much of our [economic]underperformance as a country over the past quarter century”, linking the tax treatment of housing to such indicators (favourites of mine) as low rates of business investment and lagging productivity growth.

Centrepiece of his argument is this chart from the Tax Working Group’s (TWG) discussion document released last week.

TWG chart

Note that, although the label does not say so, this is an attempt to represent the tax rate on real (inflation-adjusted) returns.

It is a variant of one of Treasury’s favourite charts, that they’ve been reproducing in various places for at least a decade.   The TWG themselves don’t seem to make a great deal of it –  partly because, as they note, their terms of reference preclude them from looking at the tax-treatment of owner-occupied housing.  They correctly note –  although don’t use the words –  the gross injustice of taxing the full value of interest income when a large chunk of interest earnings these days is just compensation for inflation, not a gain in purchasing power at all.   And, importantly, the owner-occupied numbers relate only to the equity in houses, but most people get into the housing market by taking on a very large amount of debt.  Since interest on debt to purchase an owner-occupied house isn’t tax-deductible –  matching the fact that the implicit rental income from living in the house isn’t taxed –  any ‘distortion’ at point of entering the market is much less than implied here.

Bear in mind too that very few countries tax owner-occupied housing as many economists would prefer. In some (notably the US) there is even provision to deduct interest on the mortgage for your owner-occupied house.   You –  or Bernard, or the TOP Party –  might dislike that treatment, but it is pretty widespread (and thus likely to reflect some embedded wisdom).  And, as a reminder, owner-occupation rates have been dropping quite substantially over the last few decades –  quite likely a bit further when the latest census results come out.  Perhaps a different tax system would lead more old people –  with lots of equity in a larger house – to downsize and relocate, but it isn’t really clear why that would be a socially desirable outcome, when maintaining ties to, and involvement in, a local community is often something people value,  and which is good for their physical and mental health.

So, let’s set the owner-occupied bit of the chart aside.  It is simply implausible that the tax treatment of owner-occupied houses –  being broadly similar to that elsewhere –  explains anything much about our economic underperformance.  And, as Bernard notes, it isn’t even as if, in any identifiable sense, we’ve devoted too many real resources to housebuilding (given the population growth).

So what about the tax treatment of rental properties?   Across the whole country, and across time, any distortion arises largely from the failure to inflation-index the tax system.  Even in a well-functioning land market, the median property is likely to maintain its real value over time (ie rising at around CPI inflation).  In principle, that gain shouldn’t be taxed –  but it is certainly unjust, and inefficient, to tax the equivalent component of the interest return on a term deposit.     Interest is deductible on rental property mortgages, but (because of inflation) too much is deductible –  ideally only the real interest rate component should be.  On the other hand, in one of the previous government’s ad hoc policy changes, depreciation is not deductible any longer, even though buildings (though not the land) do depreciate.

But, here’s the thing.  In a tolerably well-functioning market, tax changes that benefit one sort of asset over others get capitalised into the price of assets pretty quickly.  We saw that last year, for example, in the US stock market as corporate tax cuts loomed.

And the broad outline of the current tax treatment of rental properties isn’t exactly new.  We’ve never had a full capital gains tax.  We’ve never inflation-adjusted the amount of interest expense that can be deducted.  And if anything the policy changes in the last couple of decades have probaby reduced the extent to which rental properties might have been tax-favoured:

  • we’ve markedly reduced New Zealand’s average inflation rate,
  • we tightened depreciation rules and then eliminated depreciation deductions altogether,
  • the PIE regime – introduced a decade or so ago –  had the effect of favouring institutional investments over individual investor held assets (as many rental properties are),
  • the two year “brightline test” was introduced, a version of a capital gains tax (with no ability to offset losses),
  • and that test is now being extend to five years.

If anything, tax policy changes have reduced the relative attractiveness of investment properties (and one could add the new discriminatory LVR controls as well, for debt-financed holders).  All else equal, the price potential investors will have been willing to pay will have been reduced, relative to other bidders.

And yet, according to Bernard Hickey

It largely explains why we are such poor savers and have run current account deficits that built up our net foreign debt to over 55 percent of GDP. That constant drive to suck in funds from overseas to pump them into property values has helped make our currency structurally higher than it needed to be.

I don’t buy it (even if there are bits of the argument that might sound a bit similar to reasoning I use).

A capital gains tax is the thing aspired to in many circles, including the Labour Party.   Bernard appears to support that push, noting in his article that we have (economically) fallen behind

other countries such as Australia, Britain and the United States (which all have capital gains taxes).

There might be a “fairness” argument for a capital gains tax, but there isn’t much of an efficiency one (changes in real asset prices will mostly reflect “news” –  stuff that isn’t readily (if at all) forecastable).   And there isn’t any obvious sign that the housing markets of Australia and Britain –  or the coasts of the US –  are working any better than New Zealand’s, despite the presence of a capital gains tax in each of those countries.   If the housing market outcomes are very similar, despite differences in tax policies, and yet the housing channel is how this huge adverse effect on productivity etc is supposed to have arisen, it is almost logically impossible for our tax treatment of houses to explain to any material extent the differences in longer-term economic performance.

And, as a reminder, borrowing to buy a house –  even at ridiculous levels of prices –  does not add to the net indebtedness of the country (the NIIP figures).  Each buyer (and borrower) is matched by a seller.  The buyer might take on a new large mortgage, but the seller has to do something with the proceeds.  They might pay down a mortgage, or they might have the proceeds put in a term deposit.    House price inflation –  and the things that give rise to it –  only result in a larger negative NIIP position if there is an associated increase in domestic spending.  The classic argument –  which the Reserve Bank used to make much of –  was about “wealth effects”: people feel wealthier as a result of higher house prices and spend more.

But here is a chart I’ve shown previously

net savings to nni jan 18

National savings rates have been flat (and quite low by international standards) for decades.  They’ve shown no consistent sign of decreasing as house/land prices rose and –  for what its worth –  have been a bit higher in the last few years, as house prices were moving towards record levels.

What I found really surprising about the Hickey article was the absence of any mention of land use regulation.  If policymakers didn’t make land artificially scarce, it would be considerably cheaper (even if there are still some tax effects at the margin).   And while there was a great deal of focus on tax policy, there was also nothing about immigration policy, which collides directly with the artificially scarce supply of land.

I’ve also shown this chart before

res I % of GDP

These are averages for each OECD country (one country per dot).  New Zealand is the red-dot –  very close to the line.  In other words, over that 20 year period we built (or renovated/extended) about as much housing as a typical OECD country given our population growth.    But, as I noted in the earlier post on this chart

The slope has the direction you’d expect – faster population growth has meant a larger share of current GDP devoted to housebuilding – and New Zealand’s experience, given our population growth, is about average. But note how relatively flat the slope is. On average, a country with zero population growth devoted about 4.2 per cent of GDP to housebuilding over this period, and one averaging 1.5 per cent population growth per annum would have devoted about 6 per cent GDP to housebuilding. But building a typical house costs a lot more than a year’s average GDP (for the 2.7 people in an average dwelling). In well-functioning house and urban land markets you’d expect a more steeply upward-sloping line – and less upward pressure on house/land prices.

And, since Hickey is –  rightly – focused on weak average rates of business investment here is another chart from the same earlier post.

Bus I % of GDP

Again, New Zealand is the red dot, close to the line.   Over the last 20 years, rapid population growth –  such as New Zealand has had –  has been associated with lower business investment as a share of GDP.  You’d hope, at bare minimum, for the opposite relationship, just to keep business capital per worker up with the increase in the number of workers.

This issue, on my telling, isn’t the price of houses –  dreadful as that is –  but the pressure the rapid policy-fuelled growth of the population has put on available real resources (not including bank credit).  Resources used building or renovating houses can’t be used for other stuff.

And one last chart on this theme.

productive cap stock

The blue line shows the annual per capita growth rate in the real capital stock, excluding residential dwellings (it is annual data, so the last observation is for the year to March 2017), but as my post the other day illustrated even in the most recent national accounts data, business investment has been quite weak.   I’ve added the orange line to account for land and other natural resources that aren’t included in the official SNZ capital stock numbers.  We aren’t getting any more natural resources –  land, sea, oil and gas or whatever –  (although of course sometimes things are discovered that we didn’t know had been there).  The orange line is just a proxy for real natural resources per capita –  as the population grows there is less per capita every year, even if everything is renewable, as many of New Zealand’s natural resources are (and thus the line is simply the inverted population growth rate).

In New Zealand’s case at least, rapid population growth (largely policy driven over time) seems to have been –  and still to be – undermining business investment and growth in (per capita) productive capacity.   Land use regulation largely explains house and urban land price trends.  And it seems unlikely that any differential features of New Zealand’s tax system explain much about either outcome.

The other new article that caught my eye this morning was one by Otago University (and Productivity Commission) economist, Andrew Coleman.    He highlights, as he has in previous working papers, how unusual New Zealand’s tax treatment of retirement savings is, by OECD country standards.  Contributions to pension funds are paid from after-tax income, earnings of the funds are taxed, and then withdrawals are tax-free.   In many other countries, such assets are more often accumulated from pre-tax income, fund earnings are largely exempt from tax, and tax is levied at the point of withdrawal.   The difference is huge, and bears very heavily on holding savings in a pension fund.

As Coleman notes, our system was once much more mainstream, until the reforms in the late 80s (the change at the time was motivated partly by a flawed broad-base low rate argument, and partly –  as some involved will now acknowledge –  by the attractions of an upfront revenue grab.

The case for our current practice is weak.  There is a good economics argument for taxing primarily at the point of spending, and not for –  in effect –  double-taxing saved income (at point of earning, and again the interest earned by deferring spending).  And I would favour a change to our tax treatment of savings (I’m less convinced of the case for singling out pension fund vehicles). I hope the TWG will pick up the issue.

That said, I’m not really persuaded that the change in the tax treatment of savings 30 years ago is a significant part of the overall house price story.  The effect works in the right direction –  and thus sensible first-best tax policy changes might have not-undesirable effects on house prices.  But the bulk of the growth in real house (and land) prices –  here and in other similar countries –  still looks to be due to increasingly binding land use restrictions (exacerbated in many places by rapid population growth) rather than by the idiosyncracies of the tax system.

Eaqub on NZ policymaking

Shamubeel Eaqub’s column in yesterday’s Sunday Star-Times got me thinking.

The column is headed Policy flip-flopping on the road to progress although Eaqub seems to lament two quite different things.  The first is what he suggests is a tendency for policy to reverse course depending on which party is in office.

On tax, we have seen little leadership. The Helen Clark-led Labour government raised income taxes for high income earners, because they wanted a progressive tax system.  The John Key-led government then lowered those taxes, as it took its turn at the policy-making helm.

This kind of turn-based policy making which favours ideology is bad. It creates instability and loses sight of the long-term issues governments should be dealing with.  Instead we need a long-term and deliberate approach which can overcome this kind of policy yo-yo.

And the second is something about failures of New Zealand policymaking more generally

Bad policies often hang around like weeds, because we don’t have a good system to review past policies and undo them if necessary.

The demands for action and leadership are justified. But we should not be so hasty to deride collaborative and transparent approaches to policy development.

They are a good counter to the current way that has allowed big social and economic issues to accumulate over decades.

I’m not convinced on the first score.  For decades now, the similarities between our two main parties have been much more apparent than the differences.  Even in the brief periods of radicalism, Labour briefly wrong-footed the National Party in the mid 1980s, then National had its own brief spurt of reforms in much the same general spirit, and then before long both parties had settled back to doing not very much at all.  In many ways, the similarities aren’t so surprising –  there is plenty of political science and economics literature to predict that sort of clustering to the centre.

There are exceptions of course –  such as the maximum marginal tax rate example Eaqub describes.   Another example might have been the 90 day trial periods promised (and implemented) by National in 2008, and being partially unwound now.   And the exceptions aren’t necessarily a bad thing.  We do, after all, live in a democracy, where parties compete for your vote.  One likes to think that at least some of that competition might be based around different visions, and differences of the best practical ways to achieve even agreeed outcomes, not just on (say) who has the cutest kids or makes the best pizza.  Reasonable people will, at times, take a quite different view on (a) priorities, and (b) mechanisms (not just what “works” but what is “socially acceptable”).   The hankering for “a long-term and deliberate approach which can overcome this kind of policy yo-yo” has disconcerting similarities to the talk of the alleged superiority of the approach adopted in the People’s Republic of China: one party, and now one leader, indefinitely supposedly facilitates good long-term reform.  None of that pesky competition of ideas, interests, and individuals.  Shame about the outcomes there.

So which party is in office is supposed to make a difference –  and not just to the faces on the covers of the women’s magazines.

But I’m much more sympathetic to Eaqub in his concern about longer-term policymaking and associated advisory capability.   And that probably does spillover into Eaqub’s concerns about some of those short-term initiatives parties promise to win elections

Too many policies are populist, turn-based or just ill-thought out

Eaqub laments the state of the public service.

The civil service has a role here, as the generators and repositories of policy ideas, rather than just the delivery mechanism of ministers’ ideas that it has become.

Beaten into submission over decades, our civil service is more likely to say “more research required” on a problem, like an academic, rather than offer a well-formed recommendation.

In some respects it is hard to disagree.   Observing the quality of the analysis and advice coming out of The Treasury and MBIE instills no confidence whatever.  But while ministers have not often not welcomed, and at times actively discouraged, free and frank advice, the problem isn’t only with politicians.  The Treasury’s continued failure to have a compelling narrative of why our economic performance continues to lag behind isn’t really Bill English’s fault –  it is the failure of the institution itself (more interested, apparently, in well-being studies) and perhaps of those –  the State Services Commission –  that appoints heads of government departments.  Sir Robert Muldoon –  no great fan of The Treasury –  didn’t prevent The Treasury being well-positioned in 1984 with ideas, analysis and energy that helped facilitate the reforms of the following decade.  But that was probably an historical exception, and perhaps it is unrealistic –  even in a small country –  to really expect the public service to lead in ideas-generation around desirable reforms.  Apart from anything else, the incentives are all wrong, and the inevitable constraints militate against it.

Perhaps we have bigger weaknesses than our public service?    Think-tanks are few –  and our most consistently fertile one (the New Zealand Initiative, and is predecessor the Business Roundtable) tends to be located towards a libertarian end of the spectrum where very few likely voters are.  And in many areas, the contribution to policy-related analysis and debate from university academics is pretty thin, or often almost non-existent.  There are understandable reasons –  the PBRF ranking/funding model prioritises refereed journal articles and academic books, and recruitment policy (no doubt for good short-term economic reasons) often prioritises cycling through young foreign academics with little knowledge of, or interest in, the specifics of New Zealand.   Whatever the reasons –  and some of them may just be the limits of a small country – the policy-related inputs are often pretty thin.

But I wonder if the bigger issue still isn’t the lack of demand for anything different.  After the ructions of the 80s and early 90s there seemed to be both a shared elite consensus that reforms had been done pretty well, and it was only a matter of time until we saw the fruit.  And when the fruit (mostly) didn’t show up to the extent hoped for, there was a shared reluctance at a political level to risk more change –  perhaps particularly on the left (where the Labour Party had split).   For many people, life in New Zealand isn’t too bad at all, so why risk rocking the boat –  memories (and folk memories now) of the 80s and 90s.

And the “policy elite” (whether or a broadly-left or broadly-right persuasion) still mostly tend to hold some views that probably haven’t served New Zealand that well.  For example:

  • the broad-based low rate (BBLR) tax system, which keeps getting praised (including abroad) but typically isn’t imitated.   We tax returns to savings materially more heavily than most countries do, and that is increasingly true of business investment too,
  • the deep-seated belief that high levels of immigration are a “good thing” –  generally, and for New Zealand (even as the proponents are unable to produce evidence of those benefits for New Zealand).  The belief might be rooted in history (settler societies and all that), general economics literature, and the dread fear of being accused –  eg by the NZ Initiative –  of “racism” or “xenophobia, but whatever the reason, it no longer serves us well,
  • the endless deference to the People’s Republic of China, and the narrative that has somehow been allowed to grow up that somehow our fragile prosperity depends on keeping on side with the PRC,
  • the indifference to the fact that New Zealand has had consistently the highest real interest rates in the advanced world (and amomg the slower rates of productivity growth) –  the rhetoric for a long time (again a legacy of past decades) was that such differences can’t persist, unless they are risk-based,
  • a shared belief in the importance of technology and the tech sector, and more of a desire to belief than a willingness to ask hard questions about the likelihood of such industries developing, and remaining, here,
  • the implicit belief that our physical location doesn’t matter much (occasional talk about “costs of distance” notwithstanding) and thus an implicit view that analysis fit for small northern European countries is just fine for a really remote South Pacific one,
  • a largely shared indifference to the persistence of a very high real exchange rate.  Some of this indifference no doubt relates to the memories of controlled exchange rates past, or to journal articles characterising exchange rates as random walks, but again whatever the reason, it holds people back from seriously engaging with this symptom of our problems.

Of course, there are other issues on which the “policy-elites” are on the side of the angels –  there is probably a pretty strong consensus on raising the NZS age and even age-indexing it in future –  but there are high political barriers.

And other issues like house prices – perhaps even family breakdown –  where New Zealand’s policy failures aren’t much different from those in many other parts of the Anglo world.

Probably it is much easier to do reform, and even craft some sort of elite support for it, when the issues look like ones that involve converging towards what everyone else is doing.   That was, more or less, the story we told in the 80s and early 90s.  Even when the details of things done here were sometimes world-leading, the overall narrative was one in which we had failed to open up and reform in a way that other countries had, or were doing.  We just need to catch-up, and in the process could do some innovative stuff.

But what of now?  No country anywhere is doing much to do structurally with house prices –  and for most people in most of the rest of the world, those successful parts of the US without the problem seem to be treated as little more than a curiousity, of which most are barely aware.  No one is fixing the “family breakdown” issues either, and so we drift like the rest.

And addressing our economic underperformance looks as though it might require stepping away from some of the OECD rhetoric.   That can be hard to do (perhaps especially for officials), absent some compelling figure with an alternative narrative and the political skills to take people with him/her.

To get back to Eaqub’s article, he began by noting that

When a new government forms, there is usually a flurry of studies, task forces, working groups and advisory panels.

That has been right, at least with recent governments.  But perhaps what is most notable about many of those groups is the typically limited resources and limited time they are given.  He cited the Jobs Summit –  done over a couple of months, culminating in a one-day jamboree –  or the 2025 Taskforce (so under-resourced the one foreign appointee couldn’t really believe it). But he could have mentioned the current Tax Working Group too, which is operating on pretty tight deadlines, with limited specialist expertise.   Some of these groups, even with limited time/resources, have produced some useful material.  But they are often more about political management than about actually getting to the bottom of some serious and knotty problem.

This post has been pretty discursive, probably more useful for clarifying my thinking than for anyone else.  I think my bottom line is something along these lines:

Political flip-flopping is the least of our problems.   And the public service –  while quite degraded in its policy capabilities –  is perhaps not a body one could ever hope for much from on a sustained basis.  Our university and think-tank sectors are weak, when it comes to policy analysis and associated innovation.  But perhaps the biggest obstacle to change –  whether around the issue this blog most often focuses on, productivity underperformance, or most others –  is the absence of any political (or, presumably, public) demand for different outcomes, buttressed by “policy-elites” who seem to share assumptions and presuppositions that might have looked fine 25 years ago, but which –  on my argument – don’t do so now.  Without alternatives –  that might go over well at the OECD, the IMF or the like – it is just easier to hold on to those presuppositions, and the comfortable life most enjoy.       It is a recipe for continued drift, which is of course what we saw under the last two governments and what we seem set for under the current one.   It isn’t obvious what, or who, might credibly lead us to something different.

House prices: Cleveland and Wellington

A few months I signed up to get the e-mail newsletters of US analyst Aaron Renn.

Aaron M. Renn is a senior fellow at the Manhattan Institute, a contributing editor of City Journal, and an economic development columnist for Governing magazine. He focuses on ways to help America’s cities thrive in an ever more complex, competitive, globalized, and diverse twenty-first century.

There is an interesting mix of material on urban issues.   But this morning, one newsletter in particular caught my eye.  The title was a warning: “Sprawl in its Purest Form, Cleveland edition”.    The article began this way.

…..the image below contrast[s] the amount of urbanized land in Cleveland’s Cuyahoga County in 1948 vs. 2002. The county population was identical in both years: 1.39 million.


And the piece goes on to lament how costly the spread of suburbia is, concluding that

As a rough heuristic, development of new suburban footprint should largely be limited to the growth rate in households to avoid saddling a region with excess fixed cost.

It might be music to the ears of some of our own planners, and the politicians who continue to enforce their policies.

Renn laments the fact that, at least in this case, when cities can spread and new houses can easily be built, while the population doesn’t change much, existing houses lose value

If you keep building new homes but you aren’t adding households, then older homes at the bottom of the scale will be abandoned. And all up the stack homes are devalued.

In the same way, when we had restrictions on importing cars in New Zealand for decades, secondhand cars didn’t depreciate much.  Most of us prefer access to newer cars.

I had a look at some Cleveland data.  And sure enough not only has that county’s population been largely unchanged, but greater Cleveland (MSA) with just over 2 million people also hasn’t had much change in population for 50 or 60 years (if anything falling slightly more recently).

I also had a look at house prices.   Demographia reports that Cleveland median house prices are 2.7 times median incomes in Cleveland, averaging US$146000 last year.  Average per capita GDP in the Cleveland metro area was around US$56000 in 2016.

On the other hand, a friend had mentioned the other day a house, perhaps 150 metres from where I’m typing, that had sold the other day for  $831000.    It is a small house (100 square metres) on a pretty tiny section (324 square metres) –  with a major construction project almost on the doorstep for the next 18 months or so – and as far as I can see nothing out of the ordinary.  That is the point –  it isn’t egregiously expensive for Wellington (let alone Auckland) in this day and age.    It is about what one might expect, given our laws and regulatory practices.     Average GDP per capita in Wellington in the year to March 2016 was around $NZ67900 –  a fair bit less than in Cleveland.

Homes.co.nz records that the same Island Bay house sold in 1985 for $76500.   Apply the Reserve Bank’s inflation calculator and in today’s dollars that would be the equivalent of $207000.  The actual recent sale price –  the real increase in price –  was four times that.

How have Cleveland house prices done over time?  Here is a chart, back to 1985, from the FRED database.

cleveland prices

Nominal prices have increased quite a lot.  But in real terms, applying a US inflation calculator, Cleveland house prices have barely moved –  up a bit in the boom years, down in the recession, but over 33 years virtually no change at all.  Houses were highly affordable then, houses are highly affordable now.    And lest you assume Cleveland is some economic wasteland, the FRED database also suggests that the unemployment rate there has been averaging about 5 per cent in the last year or two, very similar to that in New Zealand.

I usually focus on cities with fast-growing populations in discussing US examples of low and affordable house prices – eg Atlanta or Nashville.   And I’ve never been to Cleveland, and have no particular idea how attractive or otherwise parts or all of it are (in Wellington, Porirua and Wainuiomata  –  for example –  also have their downsides).   But the ability of the citizenry to readily expand the physical footprint of the city seems like a success story, producing housing market outcomes that seem much more appealing –  particularly to younger people trying to enter the market –  and affordable than what we now seem to manage in our larger New Zealand cities.

We should steer well clear of “rough heuristics” or tighter rules that try to limit the expansion of the physical footprint of cities, or allow officials and politicians to determine which land can and can’t be built on, in what order.   A competitive market for urban land –  peripheral and central –  remains the best prospect for once again delivering what should be a basic expectation: affordable housing.

Sadly, I noted in ACT’s newsletter earlier in the week, a link to a parliamentary question from a few weeks ago in which the Minister for the Environment indicated that “Cabinet is yet to make any decision about whether to review the Resource Management Act”.  I’ve long been sceptical as to whether, even if some Labour parts of a left-wing government was willing to think about serious reform, such reform would be possible given the reliance on the Greens to pass government legislation.  Sadly, for now it increasingly looks as if those fears are being realised.

House –  and land prices –  need to fall.  This government, like its predecessor, seems at  scared of such an outcome, and unwilling to take steps that offer the prospect of sustained much lower prices.