A possible alternative governance approach

In my previous post, I noted that I had previously outlined a possible alternative governance model for the Reserve Bank.  That model was buried many pages into a linked paper, so here are the key elements of a better alternative model.  It has significant similarities with the approach adopted by the British government when they recently reformed the Bank of England and the organisation/governance of a very similar range of functions to those undertaken by our Reserve Bank.  In this model, a Governor plays an important central role, but is not –  except perhaps by the strength of his arguments – a dominant figure.  A significant part of the Governor’s role is to facilitate the work of the various committees, in which he is (formally) no more than primus inter pares.

My main point in writing this note is to make the case for moving away from the current single decision-maker model. That model now suffers from an increasingly severe deficit of democratic legitimacy and lacks robustness.

However, in the interests of contributing to the debate, and providing an alternative model against which to look at the current system, I have outlined below the key features of an alternative model that seems to me best suited to the current responsibilities of the Bank, the size of our country, and practice in other areas of government.

Key elements of such a model would be:

  • The Reserve Bank Board would be reformed to become more like a corporate (or Crown entity) Board, with responsibility for all aspects of the Reserve Bank other than those explicitly assigned to others (NZClear, foreign reserves management, currency, and the overall resourcing and performance of the institution).
  •  Two policy committees would be established: a Monetary Policy Committee and a Prudential Policy Committee each responsible for those policy decisions in these two areas that are currently the (final) responsibility of the Governor.  Thus, the Monetary Policy Committee would be responsible for OCR decisions, for Monetary Policy Statements, for negotiating a PTA with the Minister, and for the foreign exchange intervention framework.  The Prudential Policy Committee would be responsible for all prudential matters, including so-called macro-prudential policy, affecting banks, non-bank deposit takers and insurance companies.  The PPC would also be responsible for Financial Stability Reports.
  •  Committees should be kept to a moderate size, and should comprise the Governor, a Deputy Governor, and between three and five others (non staff) all of whom would be appointed by the Minister of Finance and subject to scrutiny hearings before Parliament’s Finance and Expenditure Committee.  There should be no presumption in the amended legislation that these outside appointees would be “expert”, although it might be reasonable to expect that at least one person with strong subject expertise would be appointed to each committee.
  •  The Secretary to the Treasury, or his/her nominee, would be a non-voting member of each committee.

A common argument against this sort of model is the small size of the population in New Zealand.  I think this is a materially overstated concern:

  • As noted earlier, ministers manage to fill countless boards and committees, covering a wide range of functions – some more important than others, some more technical than others.  
  • If it is difficult to find enough good people to serve as a voting committee, it is at least equally likely to be hard to consistently find a top-notch person to serve as Governor. 
  • No other small advanced economy has either a single decision maker, or a committee of internal management experts only. 
  • While I don’t generally favour using foreign appointees on policymaking bodies, it is likely to be more feasible and acceptable to use foreign appointees in a system in which the foreign member is one vote of five or seven, than in the current system (which is all or nothing). Bank of England policy committees have had foreign members appointed by the Chancellor on several occasions. 
  • In respect of monetary policy, the Bank has managed for 10 years or more to fill two external monetary policy adviser positions.

In the same paper, I explained why I did not the thing the model proposed by Lars Svensson in 2001, apparently similar to what Graeme Wheeler probably favours, would be the right solution.

In 2001, Lars Svensson’s report to the Minister of Finance proposed legislating for a small committee of internal experts (senior managers of the Reserve Bank[1]26, working in executive roles in the monetary policy area, whether initially appointed from outside or within) to make monetary policy decisions.

Simply legislating for a committee of fulltime executives would have some modest advantages over the current situation.  Whatever decision-making benefits might arise from committees, per se, would presumably be captured.  However, without much more substantial structural change, it would represent a material further dilution of ministerial responsibility for monetary policy.  The Minister appoints (and, in principle, can dismiss) the Governor, but has no involvement in appointing those in the Bank’s management hierarchy.

The Svensson solution was designed for monetary policy.  In principle, there is no reason why there should not be a similar internal committee for prudential matters, probably with somewhat overlapping membership[2].

But it is not clear why a model of this sort it would appeal to political decision makers (Minister of Finance, and MPs).  The model was rejected by Michael Cullen in 2001, and has not since been revived by any politicians.

In such a model, the Governor would clearly be the dominant figure. He or she would be the chief executive to whom the other members work. The chief executive would presumably set their salaries, and determine resourcing for their individual departments. In practice, it is not a model which would provide much additional resilience in the face of a bad Governor, and it would remain well out of step with decision-making models elsewhere in the public sector.

As a decision making model, it would also seem to confuse the important role of technical expertise as an input to the decision-making process, and the policy decision itself.  To illustrate the point, consider the role ministers play in decision-making in our system of government.  Ministers (individually or in Cabinet) make policy decisions in a wide range of areas, in which typically only by chance are they technical experts.   They can draw on a wide range of advice, technical and otherwise, whether from the public service or from outside.

Parliament has chosen not to have ministers making decisions on many of the Reserve Bank’s areas of responsibility, but that is mostly about the incentives that politicians are perceived to face (electoral cycles).  It has never been about a need to have all decisions made by executive technical experts[3].

It is important, and valuable, to keep a clear distinction between expert advice, and a decision-making process.  Doing so helps ensure that a range of options is examined in a careful and balanced way. When the Governor and his/her own executive deputies are those making the monetary policy decisions, and are directly responsible for those generating the underlying analysis, there is a heightened risk that they will receive staff analysis tending to support their own known biases and predilections (staff respond to incentives). Similar risks arise around regulatory policy decisions.  A very good Governor might be able to manage this risk, but it is not one that we generally take in public sector organisational design.  In respect of fiscal policy, for example, there are two clearly separate roles – adviser and implementer (Secretary to the Treasury) and decision maker (Minister).  The Secretary is responsible for the quality of the advice and analysis going to the Minister, but the Minister is responsible for the policy.  There is no comparable separation of responsibilities in respect of the Reserve Bank’s activities.

In short, simply legislating a series of internal semi-expert committees would still not represent particularly good governance.  It would remain well out of step with conventional practice in the New Zealand public sector.  Expert committees can, and do, play a valuable advisory role in policy development, and can play a decision-making role in technical implementation decisions, but – outside the Reserve Bank – I am not aware of any area of New Zealand policy governance in which material policy decisions (as distinct from the application of policy to particular entities) are delegated to an expert panel.

[1] Governor, Deputy Governor, Head of Economics, Head of Financial Markets

[2] In the current management structure, perhaps a Monetary Policy Committee made up of the Governor, Deputy Chief Executive, Head of Economics and Head of Financial Markets, and a Prudential Policy Committee made up of the Governor, Deputy Chief Executive, Head of Prudential Supervision, and Head of the Macro-financial Department

[3] Otherwise, for example, there would presumably be much more stringent qualifications for a Governor laid down in the Act.  Each of the three people who have held office under the current model have had a background in economics, but I don’t think any of them would have described themselves as technical experts in monetary policy or banking regulation.
Towards a better-governed Reserve Bank

Yesterday saw comments on Reserve Bank governance from a couple of senior politicians.

The Green Party’s new finance spokesperson, Julie Anne Genter, put out a press release yesterday arguing that

The Reserve Bank made the right decision today to cut the OCR – effectively reversing the mistaken OCR increases in 2014 – but concentrating this power in just one person isn’t the right way to make good decisions,” Green Party finance spokesperson Julie Anne Genter said.

“We’d like to see the Reserve Bank’s decision-making power broadened to more than just one person – decision making by a panel of experts from across the economy would be in line with what happens in other OECD countries.

“Over-forecast inflation has kept interest rates higher than they should have been in recent years, which has cost the economy jobs

I happen to think she is right.  We don’t change the governance model to produce a different OCR decision on any particular day, but as one part of securing a better, more transparent, more resilient central bank.  There are no guarantees, but such a central bank is less likely to make mistakes like last year’s monetary policy –  recall that this is the only central bank in the world that has twice started tightening and then had to reverse itself.  Other countries don’t run things the New Zealand way, and we don’t run other areas of government this way either.  The case for change is pretty clear, and multi-dimensional.

I was interested in one aspect of her statement.  The Greens have previously favoured making the Reserve Bank’s Board the decision-making body for the Bank (which would parallel the approach in Australia), and have at times talked of ensuring that there are representatives of industry, employees etc on the Board.

But in this statement she calls for a “a panel of experts from across the economy”, which appears to suggest something rather more technocratic  (and, hence, perhaps more aligned with a majority of OECD countries, which often have decision-making committees with a majority of at least semi-expert members).  I’m not sure if they intended to convey a change of approach –  perhaps she just want to sound more internationally conventional –  but the change of tone is interesting.

Genter followed up her press release with an oral question in the House yesterday afternoon (number 9), asking the Minister of Finance if he still had confidence in the Reserve Bank following yesterday’s decision, using it as a hook to ask a series of supplementaries about governance (in one of which she repeated the point about a “panel of experts from across the economy”).  The questioning didn’t go overly well for her.  That was partly because the Minister of Finance was away, and Steven Joyce answered for him.  But it was also because she allowed some serious questions about governance to be tied too closely to a specific OCR decision, which allowed Joyce to bat her away with comments along the lines that he didn’t agree there had been a mistake, and we didn’t want politicians second-guessing individual OCR decisions.

Nonetheless, the responses that she received were still interesting.

First, there was a slightly backhanded compliment

Hon STEVEN JOYCE : The suggestion that the member makes, of having a panel of people making the decision, is, I have to say, not the silliest suggestion in monetary policy we have heard from the Greens over the years, and many countries—

and

Julie Anne Genter : Does he agree with Treasury’s advice to him that “The current single decision-maker approach poses risks”, and that “on balance, we think there would be benefits to moving towards a monetary policy committee in the future.”; if not, why not?

Hon STEVEN JOYCE : I am, of course, aware of that policy advice. But it is important to note that the New Zealand system has served us very well, I think, over the last 26-odd years. Yes, you could have a change at some point, but, again, I think that if you wanted to do it, and it is not a proposal that we are at all considering at this point, but if it was something that you wanted to do, you would have to do it for the right reasons and not because you disagreed.

and

Julie Anne Genter : Is the Minister aware that no other OECD country with a central bank gives so much legal power to a single official?

Hon STEVEN JOYCE : As I said previously, I am aware of that. Actually, as I said to the member in one of my earlier answers—this is on behalf of the Minister of Finance—actually, there is a range of ways in which that is done internationally. But the basis on which you would change that is not on the basis that a number of members of Parliament think that the Reserve Bank Governor had made the wrong or unnecessary decision in a previous year, which the member asserted in one of her previous questions.

Julie Anne Genter : Given that the only independent review of New Zealand’s monetary policy framework since the 1989 Act was put in place recommended changing the law in regard to bank governance, and that no other OECD country with a central bank gives so much power to a single individual, will his Government consider updating the law?

Hon STEVEN JOYCE : I thought I had answered that previously, but the answer is no, we have no plans to do so at this stage.

Not once did the Minister defend the basic elements of the current governance structure.  He defended operational independence for the Bank (which Genter didn’t seem to be questioning), he claimed that the system had served us well for 26 years, but there was no principled defence of allowing so much legal power to a single individual.  And he didn’t even rule out change, just noting at the end of the questions that the current government “have no plans to do so at this stage”.

I’ve been a bit puzzled as to why the current government has been resistant to change.  The independent review undertake for the previous government recommended legislative change (and the range of things the Governor is personally deciding has widened materially since then), the Treasury favoured change[1], they found that many market economists favoured change.  And most of the Opposition parties appear to have favoured change –  Labour seems to have come and gone on the issue, but is hardly likely to be a robust supporter of giving so much power to one official.  And, of course, we have good reason to believe – although he is now highly secretive about it –  that Graeme Wheeler favours change.

Among those favouring change, there will be a variety of different motivations and a variety of different alternative models in view.  I sketched out my preferred model here, but I know able people with different perspectives on the details of a new model.

I suspect that the Minister of Finance has little time for the Governor’s preferred model, of legislating to entrench a system in which Reserve Bank senior staff alone get to make the decisions.  Michael Cullen certainly didn’t like that specific option when Lars Svensson recommended it.  And this isn’t just an issue of monetary policy, and there are likely to be quite some differences  –  including with Treasury  – around the Bank’s prudential powers.  But the reluctance to open up the issue is still a bit of a puzzle.  Graeme Wheeler’s poor stewardship of the office of Governor is strengthening the case for change, but these are decisions that really should be made independent of the personalities, and of the foibles of the individuals involved.  That was why the Treasury advice in 2012 was appropriate –  ie flagging the issue with the Minister before it was apparent who would be nominated as the next Governor.

Perhaps the Minister of Finance worries that opening up the issue now would:

  • Be seen as political interference in current monetary policy
  • Be seen as a vote of no-confidence in the current Governor
  • Be seen as a win for Opposition parties, and particularly the Greens.

I hope none of those is the explanation for inaction, but I don’t really understand what is.  It seems most unlikely to be a strong in-principle preference for a model that gives unprecedented amounts of power to a single unelected official (or else presumably Steven Joyce would have run those lines)

Good legislation takes time. Graeme Wheeler will soon start the last two years of his term.  Now is the time for the Minister to open up the issue.  Perhaps he could ask Treasury to prepare a consultative document on the issues and options and put it out for several months of submissions and discussions.  That could allow legislation to be drafted next year, and to be in place so that the new Governor, taking office in late September 2017, would take office knowing that it was on the basis of the new model, while allowing Graeme Wheeler to see out his term on the arrangements that he was appointed on.  There is nothing sacrosanct about those arrangements –  Parliament makes the rules and can change them –  but the timing would now work quite well.  Moreover, since revitalising the Reserve Bank, and making it more rigorous, open, and resilient, will probably require a quite different sort of person, the change of Governor would be a good time for a new law to take effect.

There probably aren’t many votes in Reserve Bank reform, but good governance reforms, bringing our Reserve Bank more into line with international practice and the way other government agencies in New Zealand are run, would be one part of a good legacy for a long-serving Minister of Finance.

[1] I don’t know where Treasury now stands on the issue but have lodged an OIA for copies of any work they have been doing on the issue.

Some thoughts on the Monetary Policy Statement

What to write about the Monetary Policy Statement?

The Governor continues to deny that any mistakes were made last year. I’m not sure why. As I’ve said before, perhaps the first OCR increases were defensible (certainly lots of onshore economists thought so), but to keep on hiking and then take a year to start cutting, quite grudgingly, even as core inflation stayed very low, was just indefensible. The Governor and his staff are human, so they will make mistakes. They should acknowledge this one and then move on. Unfortunately the continuing reluctance to admit any mistake, perhaps even to themselves, is colouring how they are running policy now. The OCR is still higher than it was at the start of last year – the only OECD country of which that is true – even as inflation expectations have fallen further. What is it about a situation of rising unemployment, near-zero per capita GDP growth, and well-below-target inflation makes them think we’ve needed higher real interest rates?

I was disappointed, if not overly surprised, by the questioning of the Governor at the press conference this morning. Here are a couple of questions I think we should expect the Governor to provide straight answers to:

  • Governor, the Reserve Bank – like its peers abroad – has been telling us for years that core inflation is just about to pick up, and it hasn’t. If anything, it has kept drifting down, and with the unemployment rate still rising it is likely to fall further. In the very first paragraph of your Annual Report last year you once again told us that inflation was heading back to the midpoint. Again it hasn’t done so. . How have you corrected for this persistent bias, and why should we (or the public) have any more confidence in your inflation outlook now?
  • Governor, given the Bank’s persistent forecasting bias – shared, of course, by local market economists – why not adopt a strategy that aims to get core inflation to something nearer 3 per cent. Given the (unintentional) biases you’ve shown to date, that might give us a good chance of actually getting core inflation up to 2 per cent.  If inflation really looked to be rising strongly – to something well above 2 per cent – surely you have plenty of time to correct when you actually see the material increases in inflation?.

There was, as far as I could see, no particular basis in the document for a belief that core inflation is about to head back towards 2 per cent. Indeed, there is almost an attempt to sweep those awkward measures under the carpet, and to focus instead on headline inflation. Yes, headline inflation will probably pick up to some extent, and perhaps it will even creep over 1 per cent early next year. The evidence for that proposition isn’t great, and the Bank’s own past published research has cast doubt on it. Some tradables prices will no doubt rise – some already have – but exchange rates fall for a reason and are often accompanied by falling non-tradables inflation.  It is those core or domestic components of inflation that really matter, and there was nothing in the Governor’s July speech or in this document to think the downside surprises have come to an end. Indeed, the Bank acknowledges that non-tradables inflation is likely to fall further (partly for one-off reasons), and as they are projecting the unemployment rate to carry on rising it would be surprising if their favoured core inflation measure did not fall further.

I’ve gone on quite a bit over the last few months about the apparent indifference to the unemployed. No one thinks that a 5.9 per cent unemployment rate is New Zealand’s NAIRU, the rate has been rising for several quarters already, and the Reserve Bank is now forecasting that the unemployment rate will rise even more. There is, conveniently, no chart of the unemployment rate in this MPS, but the tables at the back show them forecasting an unemployment rate up to 6.1 per cent next March, and only back down to 5.9 per cent a year later in March 2017. The unemployment rate was only 6.2 per cent in March 2010, just after the 2008/09 recession ended.  Seven years on they expect no material inroads will have been made on the unemployment rate.

That March 2017 unemployment rate of 6.1 per cent is well within the sort of window that monetary policy can do something about. But the Governor is doing next to nothing more about it (these unemployment forecasts are after taking account of today’s cut and one more OCR cut). Lest I upset some economists, I should be clear that I’m not suggesting that monetary policy has very much impact on the longer-term average unemployment rate, but it has a considerable influence on fluctuations around the normal or natural level (itself determined by some mix of regulation, demographics, and so on). If core inflation was already 2 per cent and clearly rising, higher short-term unemployment might be an unavoidable price of keeping inflation in check. But core inflation is now 1.3 per cent, and probably falling. There is really no excuse for the OCR still to be so high. This is one of those times when there is no nasty trade-off: looser monetary policy would raise inflation (which we need, to get back to target) and lower the unemployment rate. Targeting house price inflation in Auckland isn’t part of the Reserve Bank’s mandate.

I don’t really understand why this high unemployment rate doesn’t seem to bother more people. I don’t hear market economists talking about it, or business journalists. I don’t hear business lobby groups doing so. The libertarian economist Bryan Caplan wrote a nice piece a couple of years ago about the grave evil of unemployment, and the way that people on the right tended not to take the problem seriously. But curiously, I also don’t hear the political Opposition talking much, or with much intensity, about unemployment.

And, as I’ve noted before, I really wonder what the Governor says to the unemployed people when he runs into them? How does he justify the Bank having run monetary policy in ways that delivered years of above-trend unemployment, scarring permanently the prospects for some of the people concerned. Mistakes happen, but the minimally decent thing to do is to acknowledge them and apologise. And how does he justify not adopting a more aggressive policy now, a stance that might get more of the unemployed back to work sooner?  The Chief Economist gave us a little lecture about the neutral interest rate having fallen 3 basis points a quarter for the last decade, but whatever neutral is –  and no one knows –  there is no sign that keeping medium-term trend inflation near 2 per cent requires an OCR as high as it is now.

I was encouraged by one aspect of the Governor’s press conference. He seems to be becoming slowly more uneasy about the situation in China. In answer to one question he uttered the dreaded d word – deflation, observing that if there was a substantial depreciation of the yuan that would export deflation around the world. He actually sounded worried. Given that almost every emerging market currency has depreciated markedly against the USD in the last 12 months or so, and that the Chinese are rapidly running through their foreign reserves, he probably should be worried. But if he is worried, he should be doing some preparation, focusing on keeping inflation expectations up, and on removing the obstacle that the near-zero lower bound poses for monetary policy. We still have some way to go to get to zero, but that space is steadily diminishing, and if the Bank’s Statement of Intent is any guide, he is doing nothing pre-emptive about managing the risk.

I wonder how the Bank’s Board and the Minister of Finance feel about this Monetary Policy Statement. Is the Minister yet asking for advice from the Board and/or Treasury on just what is going on?

The Governor on goverance

I will have some thoughts on the Monetary Policy Statement itself later, but I wanted to comment briefly on the answer Graeme Wheeler gave to a question at the press conference.

Jenny Ruth from NBR asked him whether he thought the governance model for the Reserve Bank should be changed.  He simply never answered the question.

Instead, he gave a fairly long description of the current system, although only as it applies to quarterly Monetary Policy Statement decisions.  He suggested that people were misunderstanding the current system, but as he described it, it is all very well known.   The process starts with several days of meetings with lots of staff in attendance.  Then a Monetary Policy Committee, apparently now with 12 members including the two external participants, offers advice on the appropriate OCR decision.  The Governor now makes his final decision on the OCR in a meeting of the Governing Committee (himself, his two deputy governors and the assistant governor).  He added that for the last decade there has not been an occasion when the Governor made an OCR decision that went against the advice of the majority of his advisers.    That is no doubt true (I was on the relevant committee for most of the time), although there were several episodes in earlier years when the Governor went against the majority of his advisers (and on at least one of those occasions was right to do so).

But Graeme Wheeler deliberately avoids addressing the issues that those calling for change have made:

  • There is no other advanced country central bank or financial regulatory agency that gives so much legal power to a single official.
  • There is no other autonomous public agency in New Zealand which gives so much legal power to a single individual.
  • The only independent review of New Zealand’s monetary policy framework since the 1989 Act was put in place recommended changing the law (as it happens, to something like the Governor’s de facto model).
  • The issues are really about risk –  not about, say, the current stance of monetary (or prudential policy).  We need regimes that cope with mediocre governors, not just good ones.
  • All the advisers owe their appointments, and in most cases their pay and promotion prospects to the Governor.  That alters their incentives to disagree with the Governor, at least in respect of Governors –  like the current one –  who do not welcome debate or dissenting opinions).

The issue has never been one around whether, in normal circumstances, a Governor would take decisions his staff disagreed with, but about institutionalising a regime that encouraged challenge, debate, and openness to a range of perspectives, not just those of the Reserve Bank’s staff.

In his reply to Jenny Ruth, the Governor mentioned the speech on governance he gave in 2013.  I mentioned that a couple of weeks ago.

In 2013 he gave a speech in which he informed the public that he had decided to make decisions in the forum of a Governing Committee –  himself and his three deputy/assistant governors.  He retained the legal powers and responsibilities, but he envisaged working formally in that committee model.   In his speech, he spoke quite favourably of central banks where decisions are the responsibility of executive committees.  And there was no first principles defence of a single decision-maker model.

So it is pretty clear that the Governor favoured legislative change, and along the lines of an internal executive body (which also happen to be much the same lines as Lars Svensson recommended in that review 15 years ago).  He has also made some rather rash comments to staff about his views on the rather different governance ideas of some particular political parties.

Why is he not willing to come out and say that he favours legislative change, even if only to cement the de facto position? It could be argued that such law changes are matters for politicians not central bankers themselves, but the Governor hasn’t been shy of, eg, offering his support for tax changes and other matters rather further from his patch.

As it happens, it isn’t clear that anyone is now strongly defending the current law, which still vests all the legal powers in a hands of a single individual.   But for the Governor to openly favour change would open up debate to a wider range of governance options, and more searching scrutiny of the Governor’s powers outside monetary policy.  And he isn’t keen on debate.

We know that the Reserve Bank has been doing work on the matter. Only recently they refused to release any of it to me, including on the implausible, surely spurious, ground of potential damage to the “substantial economic interests of New Zealand”.  This is, sadly, par for the course when it comes to our highly non-transparent central bank.  It doesn’t publish its economic model, it doesn’t publish submissions on its regulatory changes, it won’t publish work it has been doing on governance reform,  it doesn’t publish minutes of the Governing Committee meetings on policy issues, and it won’t publish the background papers to its Monetary Policy Statements. 

It is past time for change.

Net economic benefits from refugees?

I noticed an odd story in the Dominion-Post this morning.  In the hard copy it is headed “Economic benefits to compassion”, while on Stuff it goes under the title “Refugees are good for NZ’s economy, say economists”.  The first heading seems like a category error, while the second is almost certainly wrong.

Let’s take the category error.  Surely we exercise compassion for its own sake, not looking out for what is in it for us?     We might, reasonably, count the costs and consider the risks.  In some sense, no doubt, the Good Samaritan did.   But if an act –  personally or nationally –  is about compassion, it is somewhat sullied by attempting to tot up what is in it for us.  Perhaps some see a refugee programme as an “economic lever” too, but I doubt there are many.

An economist then suggests that we should think of the money spent on resettling refugees as an investment.  But he lost me when he started talking about the economic benefits of other areas of government spending such as sport.  Does anyone really think that governments (central and local) spending money on the Rugby World Cup had a net economic benefit?  Or the America’s Cup?   The absence of economic benefits isn’t necessarily a reason not to spend the money:  there is nothing wrong with a party from time to time, so long as we recognise that it is a party, not an investment opportunity.

Perhaps even more egregious, a refugee advocate compares the cost of new refugees with the new flag proposal, noting that people have talked of billions of dollars of possible benefits from a new flag and that we should, similarly, be thinking about the opportunities the refugees create.  In fact, only the Prime Minister has mentioned such benefits, and no one else seems to agree with him.  But again, to change the flag, or not, shouldn’t be primarily a matter of economic costs and benefits.

But if we do want to do the economic calculations, how likely is it that new Syrian refugees will prove to be of net economic benefit to New Zealand (ie improving economic outcomes for New Zealanders)?  Professor Paul Spoonley is confident, but it is not clear what he bases his confidence on.    He notes that the average migrant to New Zealand is estimated to have made a positive fiscal contribution, but:

  • That is an average across all migrants, and everyone recognises that there are far higher upfront costs for refugees than for most migrants
  • The one careful study on fiscal contributions was a snapshot done a decade ago, and not looking at the lifetime fiscal costs and benefits.
  • That study was also done when the government was running very large surpluses (ie taxes on everyone were higher than they needed to be)
  • Fiscal costs/benefits are not the same as economic costs/benefits.

Spoonley recognises that refugees start at a disadvantage, but still believes they are “likely to make a net positive contribution”, albeit over a longer timeframe.

But reading the article reminded me of a table I had seen in the immigration papers MBIE released to me.  For those granted residence approvals between April 2001 and March 2009 it showed the proportion (of those 18 and over) who were on welfare benefits, and the proportion earnings wages and salaries as at 31 March 2011.  These new residents had, on average, been in New Zealand  for six years by this time.

For those who came under the skilled/business streams (about half the total), only 1.5 per cent were on welfare benefits and 71.8 per cent were earnings wages and salaries.  Even that latter number seemed surprisingly low, but let’s treat it as some sort of benchmark for now.

The table does not show the figures separately for refugees.  But it does report the numbers for those under the combined “International/humanitarian” stream, which includes 750 refugees per annum, and around 1500 people under the Samoan quota and Pacific Access category.  These latter are people who do not meet our skilled migration requirements, but who all come from countries where English is widely used (Samoa, Kiribati, Tonga).  It is a lot easier for them to adjust than for refugees from most countries.

And yet for the combined “international/humanitarian” stream, after six years in New Zealand  only 50.9 per cent (of those 18 and over) were earnings wages and salaries and 25 per cent were receiving welfare benefits.   I think it is reasonable to presume that figures will have been worse (perhaps materially worse) for the refugee quota alone.   Why would the Syrian refugees be different?.

Between coming from a non-English speaking environment, from a country whose economic institutions have been moribund for decades, and which had managed no convergence with the advanced world over the 50 years before the conflict, the chances are simply not good that these refugees, as a group, will end up making a net economic contribution to New Zealand.  And it is most unlikely that they will even make a positive fiscal cost.

None of which is an argument for not taking refugees.  Doing so is mainly a humanitarian choice, not something we do because we benefit from doing so.  I don’t have a strong view on how many refugees New Zealand should take [1], but I don’t think possible economic benefits to us should be a factor one way or the other.

UPDATE: A commenter correctly notes that we might reasonably consider the most effective way in which to provide assistance, and “most effective” would include a whole variety of possible costs.  In principle, benefits to us may reduce the net costs of some forms of assistance.  But my wider point holds, that the decision to assist shouldn’t be driven materially by any expected benefits to us.

[1]  Subsequent to writing this post, I have written a post on refugees and migrants on my Christian blog.

Does the law prohibit the Reserve Bank releasing submissions?

After my post earlier this afternoon someone mentioned the possibility of getting copies of the submissions on the investor finance restrictions under the OIA.  You might have thought so too.  At the time submissions closed, I did.  But no.

A few weeks ago I posted briefly about the response I had received from the Reserve Bank to my request for copies of each of the submissions they had received on the (then) proposed investor finance restrictions.

The Bank refused my request,  arguing that it would be met by the then-forthcoming “summary of submissions” which they would prepare.   Moreover they argued that while the OIA obliges the Bank to provide documents in the form sought by the requester, there was an exception if to do so would “impair efficient administration” or “be contrary to any legal duty of the …organisation in respect of the document”.

The Bank argues that it would “impair efficient administration” to provide me copies of the documents, with appropriate redactions, and that providing a summary of the submissions will fulfil its statutory requirements.  That is clearly not so.   I requested copies of all the submissions, which includes the ability to look at them individually.  When it produces summaries of submissions the Bank attempts to distill themes or representative arguments, on which it then comments.  If it were providing summaries of each of the submissions individually, I might be content, but a self-selected summary across a whole range of submissions is simply no substitute.   As I have pointed out previously, the contrast with submissions to select committees of Parliament is striking. The submissions on the legislation relating to offshore buyers’ and tax numbers are on the website in full.    Submitters include some of the same people who submitted on the Governor’s proposals ( eg one bank, and the Bankers’ Association).

And, as I noted this afternoon, the actual response to submissions that the Bank released did not contain, even remotely, a representative sense of the nature of the issues raised in my own submission (the only one I have a copy of).

In its response to my OIA request the Reserve Bank also noted that “much of the information contained in the submissions that you requested must be withheld in order to comply with the confidentiality provisions of section 105 of the Reserve Bank of New Zealand Act”.  And it seems that this provision is probably at the heart of the issue.

What does it say?  Here are the key provisions

105 Confidentiality of information

  • (1) This section applies to—
    • (a) information, data, and forecasts supplied or disclosed to, or obtained by,—
      • (i) the Bank:
      • (ii) a person appointed under section 99(2)(b), section 101, or section 119—
      • under, or for the purposes of, or in connection with the exercise of powers conferred by, this Part:
    • (b) information and data derived from or based upon information, data, and forecasts referred to in paragraph (a):
    • (c) information relating to the exercise, or possible exercise, of the powers conferred by this Part.
    • 2) Information, data, and forecasts to which this section applies shall not be published or disclosed by the Bank, any officer or employee of the Bank, or a person appointed under section 99(2)(b), section 101, or section 119, except—
    • (a) with the consent of the person to whom the information relates:
    • (b) to the extent that the information is available to the public under any Act, other than the Official Information Act 1982, or is otherwise publicly available information:
    • (c) in statistical or summary form arranged in such a manner as to prevent any information published or disclosed from being identified by any person as relating to any particular person:
    • (d) for the purposes of, or in connection with, the exercise of powers conferred by this Part:
    • (e) in connection with any proceedings for an offence against this Act:
    • (f) to any central bank, authority, or body in any other country which exercises functions corresponding to or similar to those conferred on the Bank under this Part for the purposes of the exercise by that central bank, authority, or body of those functions.
There are lots of words, but if public submissions on proposed new regulatory controls could be considered as “information, data and forecasts” supplied to the Bank then it would appear, under 105(2)(c), that the Bank cannot release any information about individual submissions, except in summary form. Even when policies, like the LVR restrictions, are to be applied generally (as distinct from supervisory intervention that might affect only one banks) we cannot know the substance of the submissions made on those proposed restrictions.

This seems like a travesty of democracy. Submissions –  on major new public policy initiatives – can be disclosed to foreign central banks or supervisors, but not to the New Zealand public. Any views banks or members of the public might submit to the Reserve Bank on monetary policy would typically be discoverable under the OIA, but those on prudential matters are apparently not. And this is so, even though for monetary policy there is a relatively specific objective for which the Governor can be held to account, while there is nothing remotely specific about how the statutory objectives for prudential policy should be measured.

Probably no one has any real problem with keeping confidential some private information about individual businesses.  But opinions and material supplied as part of a law-making process, which is what these consultative processes are, should be a quite different matter.  Submissions to Parliament’s select committees are published, and yet select committees are not even the final decision-maker on anything.  On proposed new statutes the whole House has a final vote, and on proposals that came initially from a Minister and Cabinet.  By contrast, when (unelected) Graeme Wheeler makes laws  –  having proposed them himself  – citizens are apparently not entitled to see the evidence, and submissions, he receives before making these decisions.

Like so much about the Reserve Bank Act, it is past time to reform these provisions.  Good access to official information is vital if we are to ensure that such a powerful institution is to be robustly accountable.  At present, there is far too little effective accountability and scrutiny.  A system in which the Governor can tell us as much, or as little, and then with his own slant, on the submissions he receives should be seen as simply unacceptable.  In this case, quite a simple amendment to the Reserve Bank Act would rectify the situation, making explicit that submissions on proposed changes to conditions of registration, or any other restrictions that affect all institutions, are not covered by the section 105 exemption, and should routinely be published on the Reserve Bank’s website.

Of course, if anyone else wants to request copies of the submissions, the Bank should presumably respond immediately declining their request and explaining why.  Unless they want to reconsider and change their interpretation of section 105, any delay would itself be a breach of the Official Information Act.

Two central banks on property: a study in contrast

Luci Ellis, head of the Reserve Bank of Australia’s Financial Stability Department,yesterday  gave a speech titled “Property Markets and Financial Stability: What do we know so far?,  at a real estate symposium at the University of New South Wales.

The Reserve Bank of Australia is a fairly hierarchical organisation, and so although Ellis is a department head, there is an Assistant Governor (several of them) and a Deputy Governor and the Governor above her.  It is a reminder of how deep a bench of talented people the RBA has.

I didn’t agree with everything in Ellis’s speech by any means – among other things there is an uncharitable dig at the 1990s RBNZ, and I was surprised to find no references to land use regulation at all –  but it is the sort of speech that one comes away from with plenty of food for thought.  It is thoughtful and balanced, offering some fresh insights, and reframing other material in an interesting way. It will repay rereading.   Taken together with the speech from Wayne Byres, chairman of APRA, that I discussed recently, it is the sort of material that gives one some confidence that the key Australian institutions  have thought carefully and deeply about property market issues and risks.  And that they have sought to use historical experiences, and those of other countries, for illumination and not just for support.  Not everyone in Australia will agree with Luci Ellis’s way of looking at the issues, but it would be foolish not to grapple with the arguments and evidence that people like her advance.

The contrast with our own Reserve Bank is a sorry one. Our central bank does plenty of speeches, but most of them are pretty lightweight affairs.  As they will, and must, market commentators scour them for hints about near-term policy direction, but I don’t think any reasonably well-informed observer comes away from a Reserve Bank speech –  whether from Wheeler, Spencer, Fiennes, McDermott, or Hodgetts – feeling that they now understand the isssues, or even the nature of the questions, better.  Sadly, it isn’t only the Reserve Bank: the quality of the economic analysis from our key economic policy agencies more generally now seems patchy at best.  I bang on here about the New Zealand’s slow continued relative economic decline, but when I look at the quality of the policy advice etc (whether it is MBIE or Treasury on (eg) immigration, or the Reserve Bank) I sometimes wonder if we should really be surprised.

I’m not going to try to excerpt Luci Ellis’s speech, simply encourage anyone interested in the substantive issues to read it.  Little of it is Australia-specific and many of the insights and questions are relevant to the discussions and debates that should be occurring in New Zealand.

Rather than excerpt the core content of the speech, I want to draw attention to just one section about good public policy processes.  Here is what Ellis has to say:

But the policy imperatives inspiring the work make it even more important to be scientific in our approach. By scientific, I mean the idea that the celebrated physicist Richard Feynman talked about in a much-cited university commencement address (Feynman 1974).

“Details that could throw doubt on your interpretation must be given, if you know them. You must do the best   you    can – if you know anything at all wrong, or possibly wrong – to explain it. If you make a theory, for example, and advertise it, or put it out, then you must also put down all the facts that disagree with it, as well as those that agree with it.”

It’s an argument for nuance, for being rigorous about your approach and for being prepared to admit you might be wrong. But I don’t want to understate the challenges this poses in a policy institution.

I hadn’t come across Feynman’s speech previously, but it is also worth reading.   Here is the fuller version of the bit Luci Ellis quoted from.

It’s a kind of scientific integrity, a principle of scientific thought that corresponds to a kind of utter honesty–a kind of leaning over backwards. For example, if you’re doing an experiment, you should report everything that you think might make it invalid–not only what you think is right about it: other causes that could possibly explain your results; and things you thought of that you’ve eliminated by some other experiment, and how they worked–to make sure the other fellow can tell they have been eliminated.

Details that could throw doubt on your interpretation must be given, if you know them. You must do the best you can–if you know anything at all wrong, or possibly wrong–to explain it. If you make a theory, for example, and advertise it, or put it out, then you must also put down all the facts that disagree with it, as well as those that agree with it. There is also a more subtle problem. When you have put a lot of ideas together to make an elaborate theory, you want to make sure, when explaining what it fits, that those things it fits are not just the things that gave you the idea for the theory; but that the finished theory makes something else come out right, in addition.

In summary, the idea is to give all of the information to help others to judge the value of your contribution; not just the information that leads to judgement in one particular direction or another.

The easiest way to explain this idea is to contrast it, for example, with advertising. Last night I heard that Wesson oil doesn’t soak through food. Well, that’s true. It’s not dishonest; but the thing I’m talking about is not just a matter of not being dishonest; it’s a matter of scientific integrity, which is another level. The fact that should be added to that advertising statement is that no oils soak through food, if operated at a certain temperature. If operated at another temperature, they all will–including Wesson oil. So it’s the implication which has been conveyed, not the fact, which is true, and the difference is what we have to deal with.

And this, I think, is what most seriously troubles me about our own Reserve Bank’s contributions to the discussion of property risks etc.  Whether it is speeches from the Deputy Governor, the Governor’s own comments at FEC, consultation documents, and responses to consultation documents, we’ve seen far too little of the sort of scientific integrity that Feynman was talking about.  We might not expect much from advertising agencies, or from politicians.  But we really should expect it from an independent technocratic agency such as a central bank.

We had some glaring examples of how not to do policy in the Reserve Bank’s processes that led to the decision to treat lending on investment properties as riskier than other housing lending.  Ian Harrison documented various examples of selective quotation, dubious use of published studies etc. I gather that the Bank reckons it has found some holes in Ian’s arguments, but it shouldn’t have needed him to be raising the issues at all.  We should expect an organisation like the Reserve Bank to go out of its way to make its case, and to make its case more convincing by showing that it was aware of, and had drawn attention to, any potential pitfalls or weaknesses in the arguments, or case, it was making.

My own concern is much more with the new investor finance restrictions.  Perhaps they are an appropriate response to the situation, but even if so we will never be able to have a well-founded confidence in such a conclusion because of the poor quality, highly selective, case the Bank has made, the secrecy with which it guards the submissions that were made on its proposals, and the cursory or non-existent responses it has made to concerns and criticisms of its consultative document.

My submission to the Reserve Bank  on the proposed restrictions is here. Here is an extract that summarised some of my key concerns

My concerns about the substance of the proposal fall under five headings:

  • The failure to demonstrate that the soundness of the financial system is jeopardised (this includes the failure to substantively engage with the results of the Bank’s stress tests).
  • The failure of the consultative document to deal remotely adequately, with the Bank’s statutory obligation to use its powers to promote the efficiency of the financial system.
  • The failure to demonstrate that the statutory goals the Bank is required to use its power to pursue can only, or are best, pursued with such a direct restriction.
  • The lack of any sustained analysis (here or elsewhere in published Bank material) on the similarities and differences between New Zealand’s situation and the situations of those advanced countries that have experienced financial crises primarily related to their domestic housing markets.
  • The failure to engage with the uncertainty that the Bank (and all of us) inevitably face in making judgements around the housing market and associated financial risks, and the costs and consequences of being wrong.

The absence of any substantive discussion of the likely distributional consequences of such measures is also disconcerting.  Distributional consequences are not something the Reserve Bank has ever been good at analysing.  In many respects they were unimportant when the Bank’s prudential powers were being exercised largely through indirect instruments (in particular, capital requirements) but they are much more important when the Bank is considering deploying direct controls.  In particular, the combination of tight investor finance restrictions in Auckland and the continuing overall residential mortgage “speed limit” is likely to skew house purchases in Auckland to cashed-up buyers.  In effect, to the extent that the restrictions “work” they will provide cheap entry levels.  New Zealand first home buyers and prospective small business owners will be disadvantaged, in favour of (for example) non-resident foreign owners.    At very least, it should be incumbent on the Bank to spell out the likely nature of these distributional effects.

Conclusion 

The restrictions proposed by the Reserve Bank do not pass the test of good policy.  The problem definition is inadequate, the supporting analysis is weak, and the alignment between the measures proposed and the statutory provisions that govern the use of the Bank’s regulatory powers is poor..

The Reserve Bank refuses to release the submissions it receives (unlike, say, parliamentary select committees) and instead published what it loosely describes as a “response to submissions”, together with a Regulatory Impact Assessment(RIA).   I had intended to comment in detail on these documents, but did not get round to it when they came out a few weeks ago, and won’t bore readers with that now.  Instead, lets take a higher level approach.

The RIA is barely five pages long, and two of those pages are largely devoted to three simple charts.  There is no attempt at a cost-benefit analysis, or to quantify any of the judgements. There is also little or no engagement with the relevant statutory provisions of the legislation the Reserve Bank operates under.

The response to submissions was 10 pages long, but most of this is devoted to operational details of the proposal, with only three pages given over to the policy issues themselves (is such a restriction an appropriate, and net beneficial, policy response to a real and substantive issue).  Although the document is described as a response to submissions, most of the points I included in my summary above are not even mentioned, let alone dealt with or responded to.  Since the Bank keeps submissions secret, it is only if submitters themselves choose to publish their own submissions that we can know what points are being made.  We should be able to count on a more honest reporting of the issues that have been raised (there were, after all, only 13 submissions).

The Bank may have a strong case for its position, but all it has done –  in the consultation document and response – is a piece of advocacy work.  It has made no sustained attempt to outline the strengths and the weaknesses of its case. There is, for example, no substantive discussion of the efficiency issues even though financial system efficiency is a key element in the statutory objective and LVR limits cannot but impair the efficiency of the system.  And there is no recognition, or consideration of the implications, of the fact that many countries have had rapid credit growth and high house prices, while avoiding a financial crisis.   It is simply poor science (in Feynman’s terms) and poor public policy.   And the points around the distributional effects of the policy are not even touched on.    Such selectivity speaks poorly of the Bank as a public policy agency.

I don’t want to idealise the Australian institutions, which (being comprised of human beings) have made their own misjudgements over the years.  But at present the quality of the material the RBA and APRA are putting out shows up the Reserve Bank of New Zealand in a particularly poor light.  New Zealanders deserve better from such a powerful institution, and from those who are paid to hold it to account.

Let’s hope they manage a better quality of argument and engagement in the Monetary Policy Statement tomorrow.

Economic performance since 1952 for Her Majesty’s realms and territories

Today Queen Elizabeth becomes the longest-reigning British monarch (as others have noted, she became New Zealand’s longest-reigning monarch a couple of years ago).

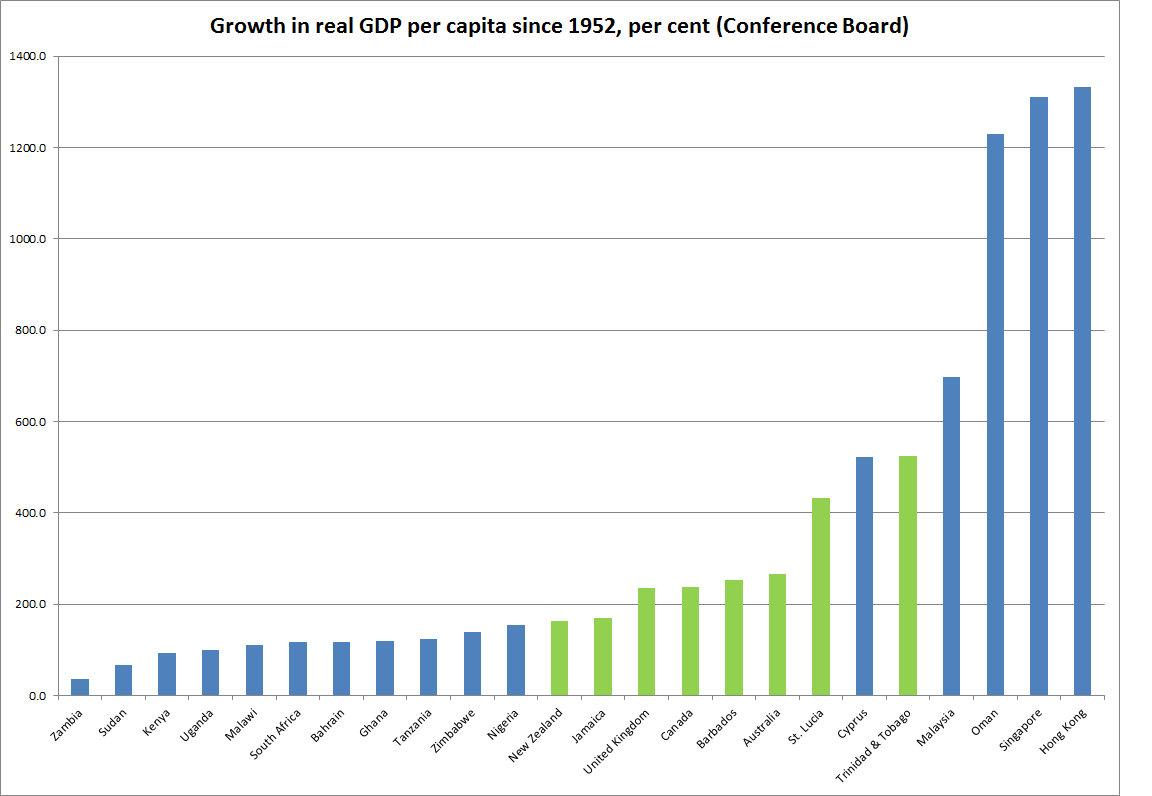
By 1952 a few places that had been British possessions or protectorates had already become independent (eg India, Pakistan, Israel, Ireland) but the extent of Her Majesty’s territories was still quite astonishingly large.  The Conference Board has GDP per capita numbers back to 1950 for a fairly large number of countries.  I found useable data for 24 countries (probably fewer than half the total) that in 1952 were either British possessions or (New Zealand, Australia, South Africa, and Canada) were independent but shared the Queen as head of state.

Here is how those countries have grown since 1952.  The green bars represent those countries in this sample which have the Queen as head of state today.

1952

In 1952, on this measure, New Zealand has (just narrowly) the highest GDP per capita of any of the three old dominions.  And although the point of this post is mostly whimsical, it is hard to go by without the sad picture of New Zealand’s deep and prolonged relative decline.

dominions

Closing the gap with Australia: only the OECD seems to think so

A friend asked me yesterday for the latest GDP per capita numbers for New Zealand and Australia.  His interest was a point estimate, to compare current levels in the two countries.  I went back to him with the series I would normally consider best for that purpose: the OECD’s measure of current price GDP per capita, converted to a common currency (usually USD) using the estimated purchasing power parity (PPP) exchange rates.  Unlike constant price measures, current price measures take full account of changes in the terms of trade –  which aren’t things governments can do much about, but which can materially affect living standards in countries like ours (in which the terms of trade are quite variable).

To my surprise, Australian per capita GDP on that measure was only about 22 per cent higher last year than New Zealand’s (= New Zealand’s being 18 per cent below Australia’s).   And if one believed that measure, the last few years had been just great for New Zealand (at least relative to Australia).  On this measure we’d long been drifting gradually further behind Australia, only to have experienced a startling reversal in the last few years.  It was as if that once-upon-a-time goal of catching Australia by 2025 was coming into view, all without actually doing any significant economic policy reforms.

gdp pc nz vs au

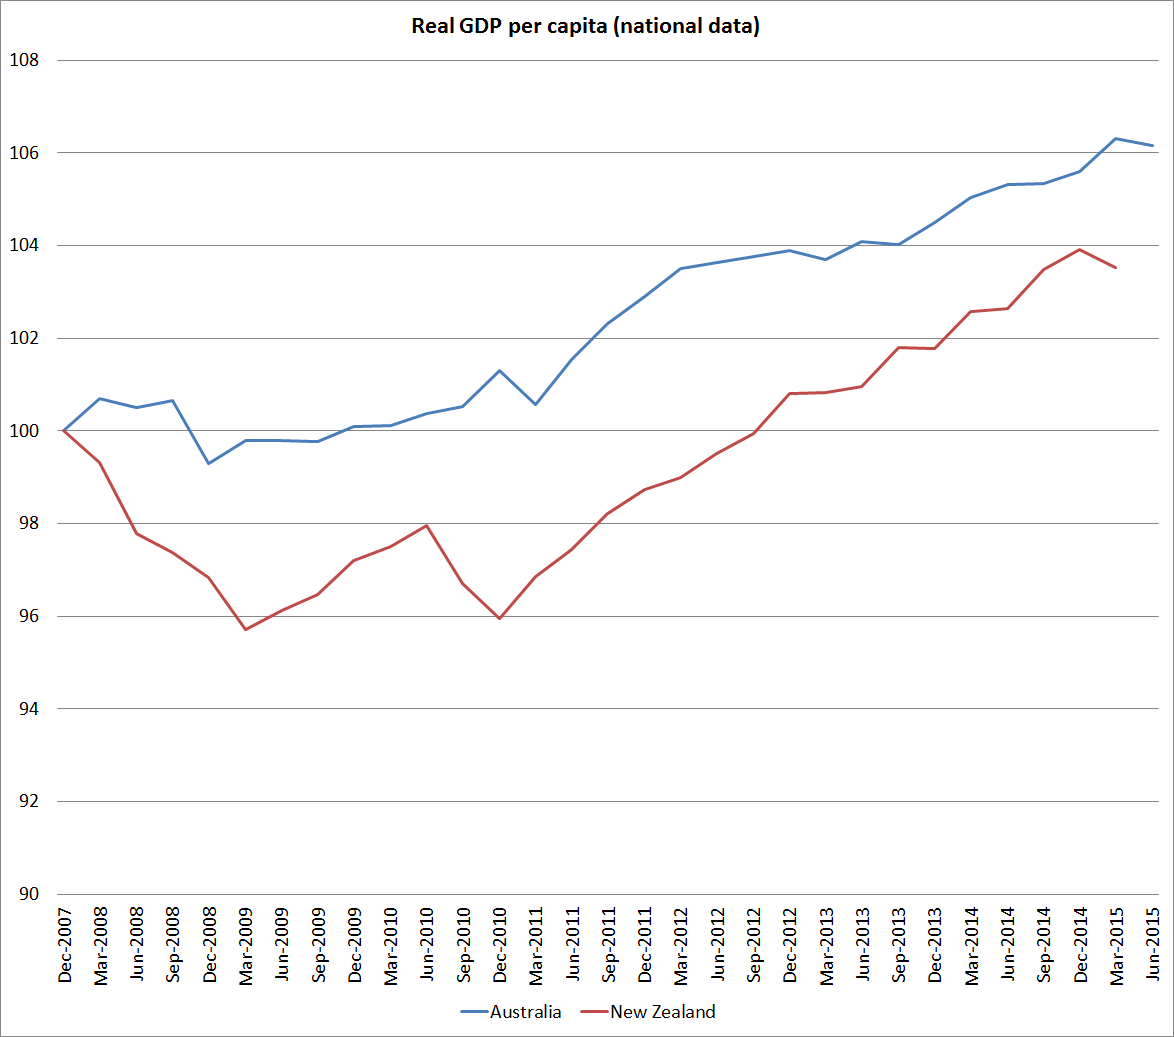
Of course, it was too good to be true.  But it prompted me to have a look at a variety of other measures of how the two countries have done since 2007 (just prior to the global recession).  I started with national data, calculated in local currencies, and deflated by domestic estimates of changes in prices.

Here is real GDP per capita for the two countries, where we’ve done a little worse than Australia.

national real GDP pc

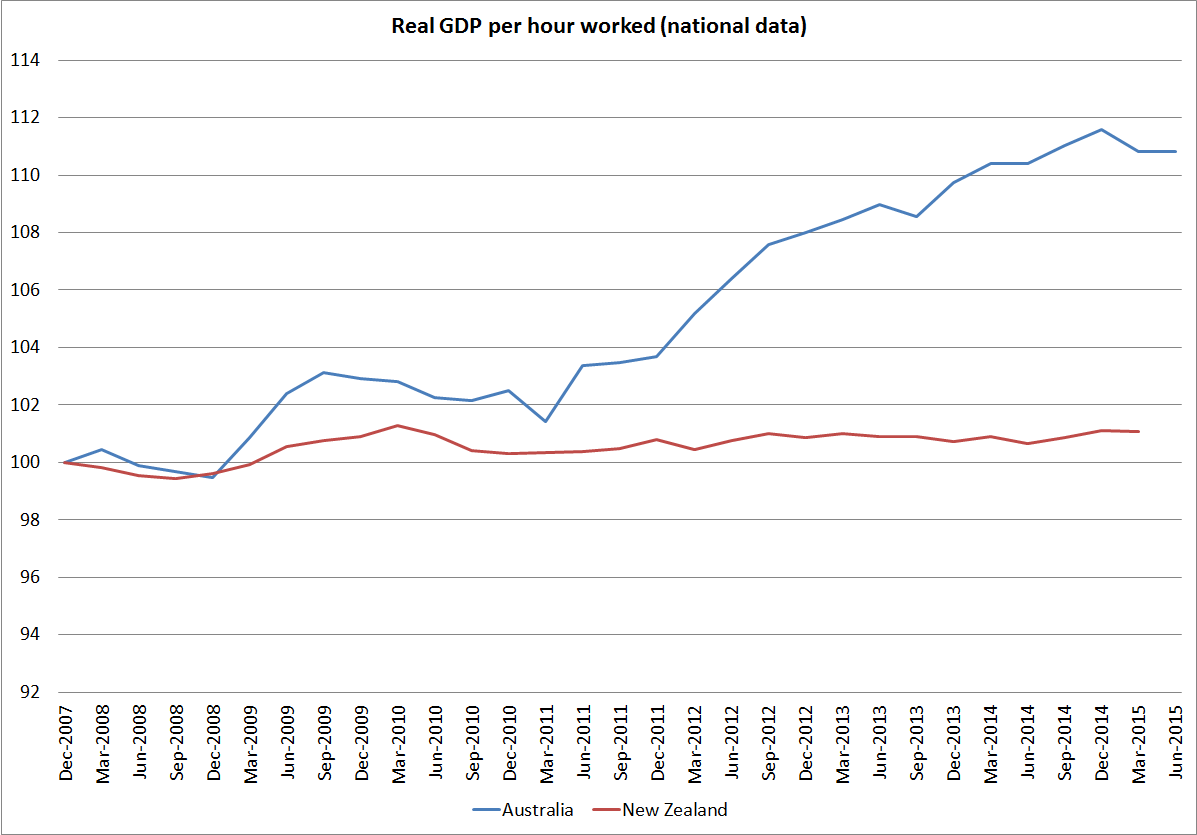
And here is real GDP per hour worked, where the differences are quite extraordinarily large (and not in New Zealand’s favour).

national real GDP phw

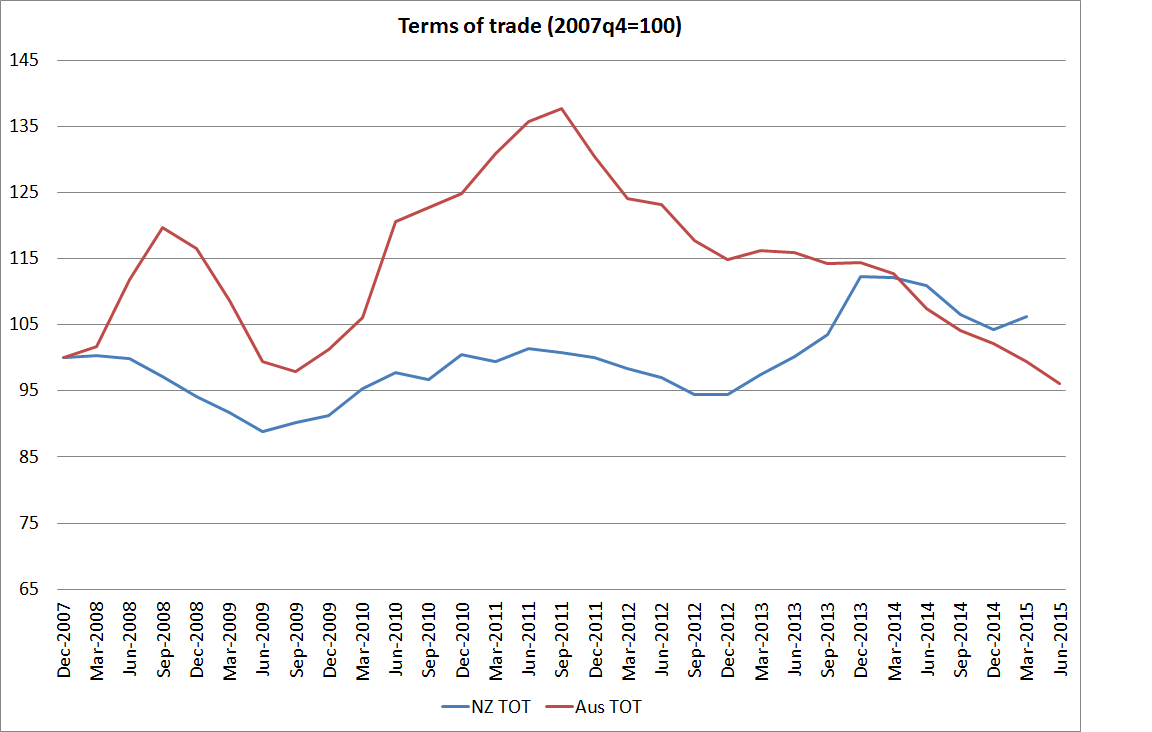
Australia’s terms of trade rocketed up over 2010 and 2011, but have since fallen back very sharply. Over the full period since 2007, we’ve now done a little better than them, and foreign trade is a larger share of our economy that it is of Australia’s.

terms of trade since 07q4

And here are the two countries’ respective measures of real income, which take account of the effects of the terms of trade.  We are now just slightly ahead of them over that full period.

national rgndi

And what about the international databases?  The Conference Board has measures of real GDP per capita and real GDP per hour worked, converted to a common currency using PPP exchange rates.  They have much the same picture as the national data.

Here is real GDP per capita –  we’ve lagged further behind.

conf board real gdp pc

And real GDP per hour worked, where again the New Zealand numbers have been very poor.

conf board real gdp phw

And the OECD’s real (constant price) measures also show something similar.  Here they use 2005 PPP exchange rates.

oecd real gdp pc

oecd real gdp phw

So none of these national or international measures suggest anything particularly encouraging about New Zealand’s performance in recent years.  So far, our terms of trade have held up a bit better than Australia’s, but they are outside our control, and at best all that terms of trade strength has done is offset a lamentable productivity performance.  And most observers expect our terms of trade to fall further (as, of course, may Australia’s).

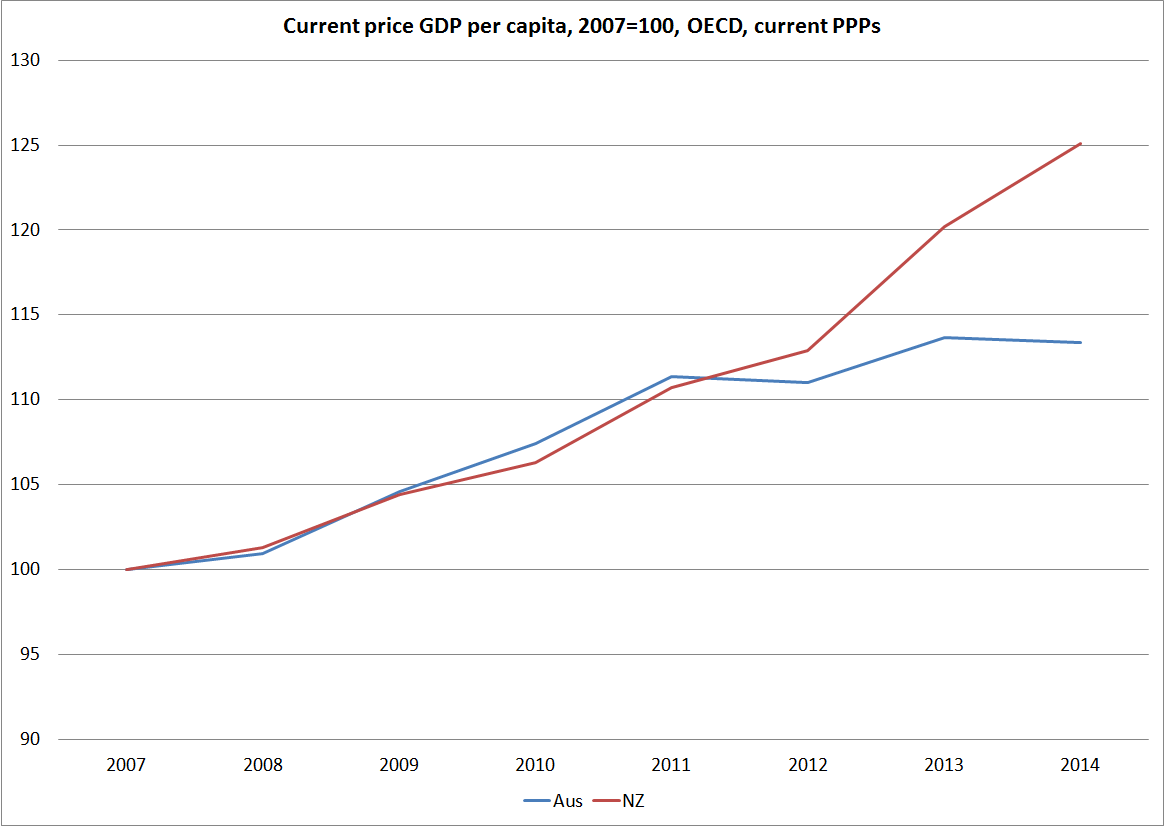
Which brings us back to the OECD’s current price estimates.  Here is how we are shown as having done relative to Australia since 2007.

current price gdp pc oecd

It looks too good to be true, and it is.

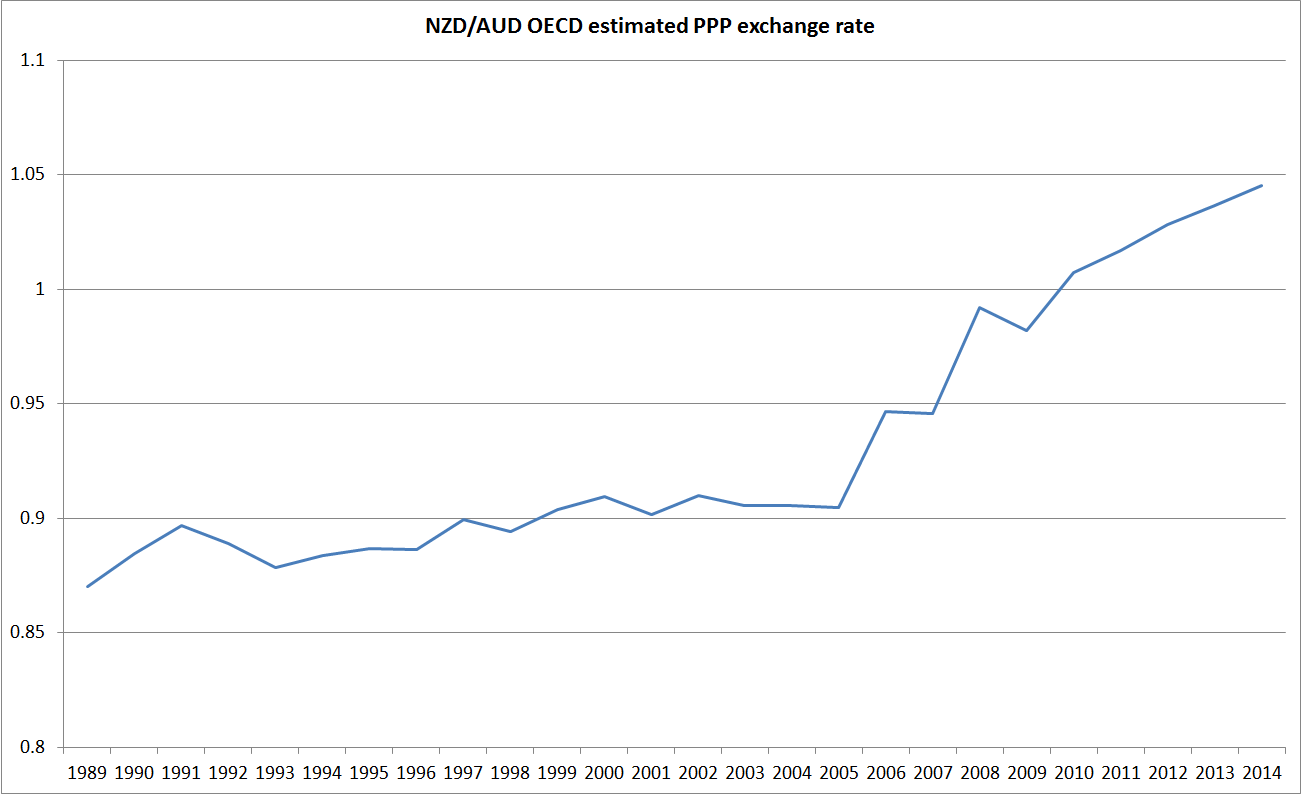
The OECD generates these numbers by converting national data into a common currency using estimated PPP exchange rates.  PPP exchange rates are, broadly, the exchange rates that would equalise price levels in the respective countries.  They can’t be directly observed and have to be estimated.  For established advanced countries you would not expect the PPP exchange rates to fluctuate much, and the biggest influence over time will often be any differences in inflation rates.  Thus, Australia has a slightly higher inflation target than New Zealand does, and Australia’s inflation rate has averaged a little higher than New Zealand’s over the inflation targeting period.  That should have been reflected in a very gradual, quite modest, rise in the NZD/AUD PPP exchange rate.

ppp nzd aud

And that is exactly what we saw until 2005.  But since then the OECD estimates that the exchange rate that would equalise prices in the two countries has risen by 15 per cent.  It simply doesn’t seem plausible – there has been nothing that structural in the two countries that could explain such a change in such a short period of time.  I’ve asked the New Zealand desk at the OECD if they have any idea what is going on, but in the meantime I will be steering very clear of the OECD’s current price estimates.

There is no one “right” international comparison of income/GDP levels. But whatever the “true” difference between Australia and New Zealand – perhaps 35-40 per cent – it remains large.  On some key measures – notably productivity estimates – it has continued to widen.  But then why would we be surprised?  If we keep on with much the same policies why would we expect much different outcomes?  New Zealand has been one of the least successful Western economies in recent decades –  indeed, probably for the last 100 years.  As I’ve highlighted previously, since 2007 many European countries have done extremely badly but even in that period, when floating exchange rate commodity exporters haven’t done as badly, we’ve not managed to make any progress in closing the large gap to Australia.

We can do better, and the failure to even start doing so reflects poorly on our political leaders and their senior official advisers, neither of whom seems to have a credible alternative strategy.

What New Zealanders thought of immigration and population issues

I got onto the New Zealand Election Survey when I was going through some old files and found a hard copy of a blog post Eric Crampton had run in 2011 on some earlier polling questions (including from previous NZES surveys) about immigration.  That prompted me to look up the 2014 survey to see if it had anything on immigration.

There is only a single question this time:

The number of immigrants allowed into New Zealand should be

Increased                                            10.7 per cent

About the same as now:                     37.4 per cent

Reduced                                              45.1 per cent

That seemed consistent with some other polling I’d seen.  Plenty of people seem to be happy with the current level of immigration, but a large number would prefer a lower level.

The 2011 survey, by contrast, had a variety of questions about population and immigration.  NZES uses many of the same respondents from survey to survey, and there was a very similar question to the 2014 question, producing very similar results.

Should the number of immigrants allowed into New Zealand be changed?

Increased                            13.1 per cent

Left about the same            34.1 per cent

Reduced                              44.5 per cent

But the 2011 survey also had four other questions about population and immigration.  The first was about the economy.

New Zealand needs more people to grow its economy

Agree                                    41.7 per cent

Neither/don’t know               26.1 per cent

Disagree                              29.2 per cent

The next was about skilled migration.

New Zealand needs to import more skilled workers

Agree                                  40.2 per cent

Neither/don’t know              18.3 per cent

Disagree                              38.3 per cent

Respondents were then asked about wider impacts

Immigration threatens the uniqueness of our culture and society

Agree                                   37.7 per cent

Neither/don’t know              21.3 per cent

Disagree                              37.8 per cent

And finally

A bigger New Zealand population would overstress our environment

Agree                                    55.4 per cent

Neither/don’t know               19.0 per cent

Disagree                              22.6 per cent

The first three 2011 questions seem broadly consistent.  People think that a rising population is good for the economy, and so don’t support (say) closing off immigration.  In fact, many think the current level of immigration is just fine.  The skilled worker question is potentially ambiguous –  do the people saying we need to import more skilled workers mean increasing the stock (which any immigration of skilled workers does) or increasing the flow (ie increasing the rate of skilled immigration beyond current levels)?

On the “uniqueness of our culture and society” question, opinion is evenly split.  In principle, and for some, losing “uniqueness” might be a good thing –  those emphasising the benefits of so-called “super-diversity” might have answered “agree” and still favour current or higher levels of immigration.

But, in some ways, the question I found most interesting was the environmental one, in which a huge majority think that a bigger New Zealand population would “overstress” our environmental.  Perhaps it is worded in a loaded way, but the margin is so large that can’t be the whole story.  It was a surprise to me –  personally I’m very fond of England’s green and pleasant land, even with 50m+ people.

Overall, there seems to be quite a tension among these respondents.  They believe a story that a larger population would be good for the economy, while worrying that it would “overstress” the environment.

The 2014 survey asked respondents about where they stand between protecting the environment and promoting economic development (thus skewing choices even in the way the question was posed).  22 per cent of respondents put themselves in the middle of the 7 step scale.  24.1 per cent leant towards “do more to encourage economic development” while 46.3 per cent leant towards “do more to protect the environment”.

Perhaps consistent with all this is the ambivalence about the current level of immigration.  A plurality want to reduce it somewhat, but perhaps mostly for environmental reasons.   A large proportion of people are comfortable enough at current levels, and a small proportion –  perhaps the strong believers in the potential gains (or libertarians simply focused on the likely benefits to the migrants  – favour a higher level of immigration.

There hasn’t been much of a public debate around immigration, but these sorts of results provide some small insights into what is shaping public attitudes to immigration.