Reforming the Fed…and the RBNZ

I’ve been working on a review of an interesting new book by an American academic, Peter Conti-Brown, with a background in law and financial history, on reforming the governance of the US Federal Reserve System.  The Power and Independence of the Federal Reserve is a funny mix of a book.  At a time, in the years following the 2008/09 financial crisis, when all sorts of people from different parts of the political spectrum have concerns about the Fed –  be it concerns about the influence of bankers, unease about the quasi-fiscal choices the “technocratic” central bank has been making, pushes to “audit the Fed” and so on –  the author sets out to aim for a pretty broad audience.  It isn’t just an academic tract –  he clearly hopes to be read by think-tankers, Congressional staffers and intelligent voters who perhaps have a vague sense that “something is wrong”.   It is difficult to imagine an equivalent book in New Zealand selling more than 100 copies.  There are some advantages to size.

There is the odd amusing story to spice up the text.  Picture the early Board members of the Fed worrying about where they would rank in the official US order of protocol.  Unimpressed at the State Department’s ruling that they would “sit in line with the other independent commissions in chronological order of their legislative creation” they escalated the matter all the way to Woodrow Wilson.  The President, clearly unimpressed with the pretensions of the Board members, told his Treasury Secretary “well, they might come right after the fire department”.   The State Department ruling stood –  in order of precedence, Fed Board members ranked behind the board of the Smithsonian.

One of Conti-Brown’s key themes is that if laws matter, and of course they do, individuals and the intellectual climate of the times matters more.  He devotes quite a lot of space to illustrating how, with largely unchanged legislation, the conception of the Fed, and the relationship between it and politicians (especially Presidents), has changed markedly over the decades.  (A somewhat similar story might be told about the Reserve Bank of Australia, over its rather shorter history.)  Marriner Eccles –  chair of the Fed under Franklin Roosevelt –  saw the role of the Fed as being to work hand in glove with the Administration.  The modern conception of an operationally independent central bank is very different –  perhaps especially in the US where the Administration has no role in setting policy targets (unlike, say, the UK or New Zealand).

Of course, the notion that individuals matter shouldn’t really be a stunning insight.  But much of the modern notion of an operationally independent central bank rests of the implicit view that there are technocratic answers to the problems we delegate to central bankers.  If so, then it really shouldn’t matter much which technocrat holds the key job(s) at the central bank.  That view was near-explicit in the way the New Zealand framework was set up: set the goal clearly enough, and make the Governor dismissable if he fails, and pretty much anyone will do.

Life –  macroeconomics, and financial regulation –  isn’t like that. Central bankers and financial regulators make choices, especially (but not only) in crises and, whatever the relevant legislation says, the values, ideologies and experiences of those who hold decision-making powers will matter, at times quite a lot.

And so much of Conti-Brown’s book is, in effect, around appointment and dismissal procedures for key positions in the Fed.  He is particularly exercised about the positions of the heads of the regional Feds, and indeed of the regional Federal Reserve Banks themselves (“we get a sense [from past Congressional testimony] that nobody knew exactly how to define these strange quasi-private quasi-public structures”).

The US Constitution itself has an appointments clause.  “Officers of the United States” can only be appointed by the President with the “advice and consent” of the Senate.    There is an exception for “inferior officers”, for whom Congress may specify that the President alone or the head of an agency (him or herself a principal officer, appointed by the President with Senate advice and consent) may make the appointment.  Members of the Fed’s Board of Governors are “principal officers” and are subject to Senate confirmation.    The President can also dismiss principal officers, but the courts have also ruled that, for independent agencies such as the Fed, the President cannot dismiss a principal officer at will (eg just for policy differences).

Regional Fed presidents, who exercise what looks like considerable authority as rotating members of the FOMC, are not appointed by the President, do not face Senate scrutiny, and are also not appointed (or dismissable, even for cause) by people who are themselves principal officers.  In Conti-Brown’s words “the Reserve Banks and FOMC, as currently governed, are unconstitutional,  The separation between the US president and the Reserve Bank presidents is simply too great”.

Conti-Brown argues that the role of the regional Presidents, and their relationship with the rest of the system, should be markedly changed.  He proposes putting the Board of Governors clearly in charge, giving them exclusive responsibility for the appointment and dismissal of regional Presidents, and effectively reducing the regional Feds to no more than branch offices.  In his model, the regional Fed Presidents would all be removed from the FOMC, except as (in effect) senior staff observers, so that all monetary policy decisions will have been made only by people selected by the President, and subject to the Senate advice and consent process.

I’m less persuaded by that as a solution.  For a start, from a distance, it looks politically unsaleable.  Even if the locations of the regional Feds reflects the politics and economics of 1913, rather than 2016, those institutions are “facts on the ground” and there would presumably be a great deal of resistance to removing that regional vote, and explicitly undermining the clout and status of the regional institutions.  An alternative model, which he discusses, seems more plausible.  Instead of subordinating regional Fed Presidents to the Board of Governors, why not instead make each regional Fed appointment a presidential appointment, with the full advice and consent process?   It looks like a model that achieves much the same end –  presidential appointment (and dismissability) and Senate scrutiny, without risking undermining the intellectual diversity that strong regional Feds have at times brought to the system. (I was struck a few years ago by the ability of a senior (regional) Fed researcher to publish a scholarly book that was quite critical of the Fed’s handling of monetary policy, including in quite recent years.)

Conti-Brown also proposes changes at the Board of Governors.  He rightly highlights that the legislation vests power in the Board of Governors itself, not in the Chair, and yet –  to a greater or lesser extent –  all modern chairs have been allowed to assume a disproportionate amount of power and influence.  Conti-Brown cites one former senior staffer as saying he would never have wanted to be appointed to the Board, as he would have far power/influence there.  Part of the issue arises because of the repeated reappointments of chairs.  Conti-Brown proposes term limits for the chair (two five year terms, so that there is a serious scrutiny of appointees at least every 10 years), and changes to the Board appointment terms as well.  Personally, I suspect the recent proposal by former senior Fed economist, and now Dartmouth professor, Andrew Levin, for a single non-renewable seven year term for all senior Fed officials (board, chair, regional Presidents) would be a better way to go.

Conti-Brown also argues that key staff at the Board of Governors also have a big influence on policy, and that consideration should be given to making them presidential appointments, so that their values, ideologies, experiences etc can be tested and scrutinized.  He is particularly concerned about the role of Fed’s General Counsel, whose advice has mattered a lot in handling financial crisis and regulatory issues.  Making such positions presidential appointments seems like a step too far.  Of course, advisers should be expected to have some influence.  But the formal powers in the system rest with the Board of Governors (and the FOMC), the people who chose whether or not (and to what extent) to accept the advice offered by even the most senior staff.  Ensure strong public scrutiny of those people for sure.  But not the next tier down.

As so often with American books on public policy issues, it is light on international comparisons.  Appointment and dismissal procedures for central bankers (and financial regulatory bodies) differ widely.  Then again, I’m not aware of any other advanced countries with a system even remotely like that of the United States.  The structure looks out of step with what we expect in public policy agencies today, and parts of it appear to be unconstitutional.

I found the US issues and analysis fascinating.  But that is partly because thinking about the systems used in other countries, especially key ones, can help one think about the model for New Zealand.  We don’t have a written constitution, and we don’t have a federal system.    But we do, I think, expect that delegated powers will be exercised by people appointed by people we elected.  That is typically the case with the numerous Crown agents and entities.  Board members and Board chairs are appointed by the relevant Minister, and key decision-making powers typically rest with the Boards themselves.

That isn’t the case with the Reserve Bank of New Zealand, which exercises a great deal more discretionary policy flexibility (in monetary policy, and in financial regulatory matters) than any other statutory agency I’m aware of in New Zealand.    There are some plausible reasons for putting some of the Reserve Bank’s functions at a considerable arms-length from day-to-day ministerial intervention (one could think of the administration of prudential policy as it applies to individual institutions), but even if one accepted all those arguments, there still don’t look to be good grounds for our governance model.

In the United States, the United Kingdom or Australia, the Governor (or chair) of the central bank is appointed by the government of the day.  In the US case, the Fed chair is subject to Senate advice and consent, but only a presidential nominee can be appointed.  The Senate cannot substitute its own candidate.  In both Australia and the UK, the respective central government has untrammeled ability to appoints its own candidate.  In the euro-system, there is lots of horse-trading and haggling among heads of government and finance ministers, but Draghi was appointed by politicians, from a field identified by politicians and their advisers.

Contrast that with the New Zealand system.  The Minister of Finance appoints the Governor, but he can only appoint a candidate nominated by the Bank’s Board.  The Minister can reject a nomination (as the US Senate can) but at no point in the process can he or she impose their own candidate.  Now, of course, the Board itself is appointed by the Minister, gradually.    Board members are appointed for five year terms, and although there are provisions for the removal of Board members, removal can only be done for cause (oddly, one possible cause is obstructing the Governor, but there is nothing comparable about the Minister). A new government might easily take more than a whole three year term to be able to achieve a majority of its own appointees on the Board.  And the Minister of Finance does not even get to determine which of the Board members serves as chair, typically a quite influential role in any Board.

This was a model that was set up when the conception of the role of the Reserve Bank was (a) quite narrow, and (b) highly technocratic.  If the Minister could specify a PTA clearly enough, who was on the Board or who was Governor wouldn’t matter much at all.  But as everyone now recognizes, PTAs can’t sensibly be written that clearly, and there is nothing comparable for the other functions that the Governor exercises considerable discretion over.  The values, ideologies and experiences of whoever is appointed as Governor are likely to matter considerably –  much more so in New Zealand, since a single individual exercises those powers, with few near-term checks and balances.

So, operating wholly behind closed doors, the members of the Bank’s Board get to determine the person who wields more power, and more discretionary power, than almost any person in New Zealand, at least in matters economic.     The individuals on the Board are probably mostly good and quite capable people (I know several of the current Board moderately well).   But whose values and interests, and what “ideologies” or implicit models, are they serving  or reflecting (consciously or otherwise)?  What accountability is there for the choices they make, which can have material implications for short-term economic performance and for the soundness and efficiency of the financial system?  It seems like a model with all too little democratic legitimacy.

If we are going to stick with the single decision-maker model for the time being (it will, surely, in time be amended) at least we should move back to a more conventional system in which the Minister of Finance (or Governor-General acting on advice) makes the appointment.  He can take advice from whomever he wants –  Treasury, the Bank’s Board, lobby groups, his colleagues –  but his nominee should have to go through proper select committee hearings before taking up the role.  We don’t have a model of parliamentary ratification of appointees in New Zealand, but the British model in which appointees to the Bank of England policy committees face considerable scrutiny in select committee hearings seems to add some value to the process, even though the committee cannot formally stop an appointment going ahead.   It might be harder to do well in New Zealand, since there is less of a hinterland of MPs not eagerly jockeying for the next promotion to the ministry, but it has to be better than what we have now.  At very least, Opposition MPs on the relevant committee could question, scrutinize and challenge the person the government has appointed to the role of Governor.  The current Governor might, for example, have been scrutinized on how he thought about the housing market and the role of policy.

If we going to keep the role of the Reserve Bank Board as being primarily about holding the Governor to account, direct ministerial appointment of the Governor also seems preferable.  Under the current model, the Board is responsible for the person appointed as Governor.  That gives them an interest in judging that person to have done the job well (if the Governor is judged to have failed in that regard, it is at least in part a reflection on the people who chose the Governor).   Monitoring someone clearly appointed by the Minister could be another matter (although structures still create risks that the monitoring Board gets too close to the Governor).

Over the longer-term, I think we need to move to a system in which committees appointed the Minister of Finance (and subject to parliamentary scrutiny before taking up the role) make monetary policy decisions and whatever financial regulatory decisions should appropriately be delegated to the Reserve Bank.

In the meantime, there is the becoming-pressing issue of the expiry of Graeme Wheeler’s term next year.  As I have noted previously, it expires right in the middle of the likely election campaign (almost three years exactly since the last election).  All main Opposition parties are campaigning for a different approach to monetary policy (time will tell what that specifically means).  How can it be appropriate for a Board appointed exclusively by the current government to be recommending an appointee as Governor (who will exercise huge discretionary powers over our economic fortunes and financial system), to a Minister  whose government might be out of office by the time the new appointment takes effect.  A new government might have a quite different emphasis and should, in my view, more easily be able to give effect to that.

I’m not sure what the right answer is, given the current legislation. I’ve previously, somewhat reluctantly, suggested that Graeme Wheeler, if willing, should be offered a one year extension to his term, allowing the longer-term appointment to be made under the new government (National or Labour led).  However, his performance over the OCR leak issue (including , in effect, minimizing the serious misconduct of a major corporate)  makes me wonder whether even for a short period that would be a prudent option.  Appointing an acting Governor –  probably one of the existing deputies –  for perhaps six months, might a better option.  There is statutory provision for it –  it was what happened when Don Brash resigned.

The US model does look as though it needs reforming.  But, perhaps even more pressingly, so does New Zealand’s. It is simply out of step with

  • the range of functions and discretionary activities the Bank now undertakes
  • overseas practice in central banking and financial supervisions
  • governance of other independent Crown entities in New Zealand.

It puts too much power in the hands of one person, and that a person whose appointment is largely determined by unelected people, operating with little or no effective scrutiny.
 

Housing, land tax, and associated things

The Prime Minister attracted considerable coverage last week for his suggestion that a tax might be applied non-resident (however defined) holdings of land.  The Prime Minister wasn’t very specific about the options he had in mind, but it probably didn’t matter – it got some mostly favourable coverage on an issue (house prices, in Auckland in particular) where the government probably senses that it might be politically vulnerable.

Quite how house prices play politically has never really been clear to me.  I’ve noted before that I’m not aware of a single example of a city or country that, having once put in place restrictive land use regulation, has ever substantially unwound those controls.  I can well understand existing users’ unease about greater intensification, and in particular the coordination challenges that can arise. Existing owners as a whole in suburb near the central city might be (considerably) better off financially from allowing their land to be used more intensively, but that won’t necessarily be so for each of them if such development occurs piecemeal, or if benefits are captured by those first in the queue.   The market seems to deal with these issues through private ex ante contracts, the covenants that are now used in most new subdivisions (and which the Productivity Commission was quite disapproving in its report last year).

And I can also understand that no one really wants the value of their property to fall much.  Of course, for many it actually doesn’t matter very much.  If you haven’t got a mortgage and plan to live in the same city for the rest of your life, the market price of houses in your area just isn’t (or shouldn’t be) that important to you.  For those with very large recent mortgages it is another matter.  For them, and especially those who aren’t owner-occupiers, falling house prices look like a visceral threat.

But then the mortgage-free are in many cases those with children, already adult or approaching adulthood, who face the huge –  increasingly insurmountable – hurdles to entering the owner-occupation market.  That should be quite some motivation to be concerned about policies which keep house prices very high, or keep driving them up further.  Increasing the physical footprint of cities, and allowing that process to happen in ways and in places that offer the best opportunities (rather than where Council officials and politicians dictate) looks as though it should be the answer.  But bureaucrats and politicians obstruct those processes, and seem to get away with it because the issues are complex, and because they cover their tracks, blaming high house (and urban land) prices on banks, the tax system, the building industry, “speculators”, “land bankers”, becoming a “global city”, or whatever.

Other bureaucrats and politicians peddle the line that high levels of non-citizen permanent immigration are somehow good for us.  High house prices are just one of those things –  a price of progress, indeed of success, so the Prime Minister would often have us believe.

Once in place, distortionary policies, even very costly ones, often last for a long time.  We saw that in New Zealand with the import licensing regime first put in place in the 1930s, which wasn’t finally abolished until 1992.  It was an enormously inefficient system, driving up costs on many items (and restricting choice) for most people, it was contested politically (largely unwound in the early 1950s, and then re-imposed by the next government).   But the entrenched interests of those who benefited from the system (or thought they did) combined with ideologies of “national development” to make it very difficult to undo.  Licence-holders themselves obviously benefited, but many of the employees of firms producing products protected by the licensing regime thought they did too.    And transitions are/were costly – we saw a lot of that in the 1980s, when big steps were finally made in dismantling the regime.  A larger proportion of the population is employed now than was then, but that didn’t mean the transition wasn’t difficult, and even traumatic, for many individuals, and even for whole towns.

One might have hoped that the rigged housing market was different, but it doesn’t seem to be.  The distributional effects (winners and losers) are far larger than any aggregate adverse effects (I’m skeptical that GDP is much smaller than otherwise because the housing market is so badly distorted).  And unfortunately, those most adversely affected tend to be the poorer, younger, less sophisticated elements in society –  those on the peripheries.  One might have hoped that one or other main party would have made grappling with these issues a real priority, consistent with the underlying values they claim to represent:  National perhaps on some ‘property-owning democracy’ line, in which communities will be stronger etc when property ownership is more broadly based, providing a “fair go” to the hardworking and aspiring classes.  Or Labour, built on a fight for the rights and interests of ordinary workers, campaigning for the full inclusion and equal opportunities for peripheral groups.

But it simply doesn’t happen.  Instead, the Prime Minister keeps talking of high house prices as “a good thing”, and a sign of success.  And for all the somewhat encouraging talk from Labour’s Phil Twyford, less than 18 months out from an election, there is little public sense of a party making fixing the housing market a defining issue.  Time will tell.  Rigged markets are hard to unscramble –  politically hard, not technically so.    Doing something far-reaching could be very costly for groups who would quickly become quite vocal, and loss aversion is a powerful force.

Where do land taxes fit within all this?  I outlined some of my skepticism about a general land tax in a post late last year.    But the Prime Minister’s latest comments relate only to non-resident purchasers.  The theoretical arguments for a general land tax don’t apply to one explicitly targeted at a specific subgroup.  Instead a land tax appears to be one of the few possible tools (specific to foreign purchasers) left to the government –  having signed up to a succession of preferential trade (and other) agreements – if, as the Prime Minister put it, it could be shown that non-resident purchasers were a big influence on the housing market.  Of course, we haven’t yet seen the data the government has started collecting, but even when we do there will no doubt be lots of debate about what it means.    Say that it shows that 1 per cent of purchases in the last six months have been from non-resident foreigners.  One per cent doesn’t sound much.  But the significance depends on a various things, including a variety of elasticities.  If the supply of houses and urban land was totally fixed (it isn’t, but this is just an illustrative example), a one per cent boost to demand could have a considerable impact on the price of houses.  If New Zealand residents were deterred from buying by even the slightest increase in price, then an increase in non-resident foreign demand might have very little impact on price even if supply was largely fixed.    Various quantitative researchers will have various estimates of these different elasticities.   But some past work has suggested that a 1 per cent increase in population, say, can have a material impact on house prices.

I had a couple of posts on the non-resident purchases issues last year.  Despite my general stance strongly favouring a pretty liberal regime for foreign investment, the housing supply market is so badly messed up that I don’t think we should rule out restrictions targeting non-resident foreign purchasers, as a second or third best option (perhaps especially if there was evidence that a large proportion of such purchases were being left empty).  The capital outflows from China –  which is where the main issue is –  are historically unprecedented.  They aren’t a normal phenomenon of an emerging economy, but a reflection of a whole variety of things that are badly wrong with the governance and rule of law in China.

But is a land tax the answer?  If it is, it is a pretty unappealing one.   It would seem to be a tax planners’ dream.  One of the appeals of a general land tax is that the land is fixed, and some identifiable entity (person, company, trust, government) one owns each piece of land.  It doesn’t really matter who owns it, but someone will have to pay the tax.  A land  tax focused only on some definition of non-resident purchasers means it makes a huge difference who owns the land.  If I own it, there is no tax liability.  If a family in Shanghai owns it there is.  Which looks like a pretty clear incentive to have the land owned by New Zealanders, and (to the extent there is demand) the things on the land owned by the foreigners.  No doubt lots of clever intrusive anti-avoidance provisions could be added to any land tax legislation but to quite what end?  Are we better off if, say, the non-residents purchasers bought apartments (which typically have a smaller land component) rather than, say, standalone houses?  Perhaps if it stimulated a supply of new apartments –  for which there would be an enduring demand –  but not if it largely just reallocated who owned what within an existing housing stock.

And there is, of course, the question of what might be a reasonable rate of land tax.  Long-term New Zealand government bond yields in New Zealand are among the highest in the world.  At present, those real bond yields are just over 2 per cent per annum.  Imposing a tax of 1 per cent per annum on value of land (including farm land?)  would be a very heavy burden in such a low yield environment.  Perhaps it might not matter too much to those seeking to safeguard their capital (return of capital rather than return on capital), but if so it might not make that much difference to offshore demand either.   I’ve seen talk of higher rates –  Rodney Hide’s Herald column yesterday talked of a 3 per cent annual rate –  but in such a low yield environment such tax rates could quickly starting looking like expropriation, confiscatory in intent.  I suspect our preferential trade agreement partners might start looking askance at that.

For what it is worth, I think a serious response to the house and urban land price affordability issue would have several dimensions, including:

  • limiting the assessability and deductibility of interest to the real (inflation-adjusted) interest only.  The ability to offset losses in one activity against profits in others is a good feature of the tax system not a flaw, but there is no good economic case for taxing the inflation component of nominal interest, or allowing borrowers to deduct the inflation component.  This is a small issue, especially at present when inflation is so low, but it would be good tax policy and work towards slightly better housing market outcomes.
  • creating a presumptive right for owners to build, say, two storey dwellings on any land, with associated provisions to developers/purchasers to cover the costs of associated infrastructure (whether through private provision, or differential rates).
  • sharply cutting the target level of residence approvals under the New Zealand immigration programme, from the current 45000 to 50000 per annum to perhaps 10000 to 15000 per annum.  Since there is no evidence that New Zealanders, as a whole, have been gaining from the high trend levels of immigration –  and indications that Auckland, prime recipient of the inflows, has been persistently underperforming, this would represent immigration policy reform in any case.  But it would also have material implications for trend housing market pressures as well.

The third element would be the one that would be easiest to implement.  But, of course, like the policies around housing supply –  or import licensing (see above) –  the distributional implications of the current arrangements (positive and negative) are probably larger than the overall economic effects.  Those who see themselves as “winners” from the current arrangements –  a funny mix , including those who genuinely benefit, and those with a “feel good” preference for diversity  –  are likely to be more vocal, and more easily heard, than those who pay the price of an misguided approach to economic management: a “critical economic lever” (MBIE’s words) that has done little or nothing positive for New Zealanders as a whole.  The parallels with Think Big in the 1980s, or with the protective regime of the 1930s to 1980s, each well-intentioned and with their own internal logic, are sobering.


Diversity dividends? Maybe not

The belief that “diversity is good”, and probably “and more diversity is better” pervades our public debate.  Sometimes people just mean intellectual diversity, sometimes diversity of managerial style, sometime gender diversity, sometimes ethnic diversity, sometimes diversity of nationalities.  But too often is all lumped together in some amorphous mass.  Who, after all, would argue that diversity might not always be good?

Enthusiasm for diversity pops up all over the place.  The Secretary to the Treasury  –  often, it seems, something of a bellwether of elite sentiment –  has celebrated diversity and called for more of it (but Eric Crampton has cast significant doubt on Makhlouf’s use of the literature on gender diversity).

Even amid the general elite celebration of “diversity”, I was a bit surprised to note a letter in last week’s Listener from a representative of top-tier law firm Russell McVeagh declaring that at that firm “we have made diversity our No. 1 priority in the past couple of years”.  If I were a client, I’d probably have hoped that delivering top-notch legal advice had been the top priority.  It may well have been, but it is telling that it sounded better to claim that diversity was their “No. 1 priority”.

Of course, a range of perspectives on many issues that face firms or public agencies or even individuals is likely to be helpful.  For hard issues there is rarely only one useful way of looking at a problem, and all of us are prone to our own biases and blind spots.  Then again, all cultures (national, organizational, local, or even family) rely on not too much diversity, and on shared assumptions (usually tacit) about how things are done,  how differences are dealt with, debate encouraged (or suppressed), and about what sorts of behaviours are acceptable and which ones are not.  And so on.  It is simply how societies work, and that doesn’t change because a particular tide of liberal opinion wishes it were otherwise.

The alleged benefits of “diversity” are part of the case often made by the champions of our large-scale non-citizen immigration policy.  Late last year, supported by taxpayer funding, lawyer Mai Chen published a 400 page Superdiversity Stocktake , championing the benefits of the diversity of ethnicities and nationalities that now make up modern New Zealand.  She champions in particular the alleged economic benefits

Most of the benefits from superdiversity, such as greater innovation, productivity and investment, increase New Zealand’s financial capital, whereas most of its challenges adversely impact New Zealand’s social capital

Ian Harrison has done a nice piece reviewing how flimsy the economic case, and the evidence cited for it, in the Superdiversity Stocktake really is.  But “diversity is good” seems to remain one of those mantras that business and political leaders repeat to each other.

Professor Bart Frijns of AUT (himself an immigrant) has been doing some interesting empirical work on one particular aspect of the impact of diversity.  His co-authored paper is The Impact of Cultural Diversity in Corporate Boards on Firm Performance , and a couple of weeks ago I went along to hear him present it at a Victoria University seminar.

Frijn and his co-authors look specifically at the impact on the performance over 13 years (2002 to 2014) of 243 listed UK firms (excluding financial sector ones), making up 95 per cent of British stock market capitalization, of having directors who were not British citizens.  Performance is here measured by the change in the market value of the firm (share price) relative to the book value (Tobin’s Q) and return on assets.  The proportion of firms with at least one foreign director has been increasing, reaching 72 per cent by the end of the sample.  Previous studies along these general lines have, so they report, produced mixed results, but those results included negative effects from the presence of foreign independent directors.

Here is the abstract to the paper

We examine the impact of cultural diversity in boards of directors on firm performance. We construct a measure of cultural diversity by calculating the average of cultural distances between each board member using Hofstede’s culture framework. Our findings indicate that cultural diversity in boards negatively affects firm performance measured with Tobin’s Q and ROA. These results hold after controlling for potential endogeneity using firm fixed effects and instrumental variables. The results are also robust to a wide range of board and firm characteristics, including various measures of ‘foreignness’ of the firm, and alternative culture frameworks and other measures of culture. The negative impact of cultural diversity on performance is mitigated by the complexity of the firm and the size of foreign sales and operations. In addition, we find that the negative effects of cultural diversity are concentrated among the independent directors. Finally, we find that not all aspects of cultural differences are equally important and that it is mainly the diversity in individualism and masculinity that affect the effectiveness of boards of directors.

As someone who hadn’t looked into this literature in any detail previously, those results surprised me.  As a sceptic of the value of such “diversity”, I might have expected them to fail to find any statistically significant economic benefits (to the owners of the firms), but in fact they found statistically significant negative effects.    Try as they might, they couldn’t consistently get rid of the negative effects.  They test for all sorts of things.  Does being based in a metropolitan area as opposed to a smaller town matter?  Does the complexity of the business matter?  Does it matter whether the foreign directors are independents or executive directors?  Does it matter if the firm is also listed in the US?   The negative effects aren’t there in every possible alternative specification –  they disappear for executive directors, for very complex firms,  and for those with large proportions of foreign sales for example  – but there were no alternative specifications that generated statistically significant positive results.

The authors look at the nationalities of the foreign directors, using a (now quite old) cultural values framework developed by Hofstede for classifying each country.  People from different countries (loosely “cultures”) differ on things like individualism, uncertainty avoidance, attitudes to the relationship between superiors and juniors (“power distance”), and “masculinity” (assertiveness, outspokenness, driven-ness, rather than gender per se).  They also use some more recently developed “cultural scores” capturing dimensions like religion, language, or even genetic differences.    As they note in the abstract above, not all cultural characteristics seem to matter much, but “individualism” and “masculinity” did in the results of this study.

Why might these effects exist?  Boards need a variety of perspectives on the sorts of issues they face.   But one element of a common culture is about trust, and cultural diversity seems to have the potential to undermine some of that trust (if one doesn’t understand quite how someone operates one is less likely to trust them, and perhaps less likely to take seriously their perspectives – even if you were part of appointing the person to the group).  Thus cultural diversity looks as though it can be disruptive to group problem solving.  There are benefits, but there are also costs, and –  at least in this study –  the costs generally seem to have outweighed the benefits.

However good this particular paper is, it is only one study.  And, importantly, it is only one dimension of diversity, or even cultural diversity.    In fact, it is only measuring nationality diversity –  anyone who is a naturalized British citizen, no matter how recently, is British for the purposes of this study, even though their cultural similarity with most natural-born British directors might be considerably less than that of, say, an Australian citizen director who might have resided in the UK for thirty years.  (As it happens, around half of all the foreign directors were from Anglo countries).   And it doesn’t deal with cultural diversity within countries at all –  the differences between a black and white South African director (in this period, only a decade after apartheid), and between most white and black British directors (given the socioeconomic disadvantages in the background of most of the latter) may be as important as those between “South Africans” and “British” directors.

Knowledge advances one paper – and one database –  at a time.  Other authors will be able to refine, or perhaps even refute, some of these results, and perhaps extend the analysis further.  But it is the sort of paper that should be taken seriously by those enthusiastically championing the possibility (near- certainty many would have us believe) of diversity economic dividends here in New Zealand.

I was interested to see yesterday an article from the Financial Times economics columnist Martin Wolf on immigration and the Brexit debate.  Wolf is a pretty reliably voice for elite informed UK opinion.  He regards himself as a classical liberal,  but seems to me pretty representative of a David Cameron/Tony Blair view of the world.

Economists tend to think it evident that immigration is beneficial to all parties. I am not convinced. High net immigration imposes significant negative externalities: greater congestion, more stress on social services, higher land prices and a need for significant investment in infrastructure and housing. If necessary investments are made, people suffer significant costs. If they are not, the costs will be higher still.

All this cannot be entirely ignored. Moreover, while I fully accept the arguments for the benefits of diversity, I understand why many differ, even feeling that they are “losing” their country. Some would argue that this idea of having inherited property rights in a country is illegitimate. I feel it is politically fundamental.

There are issues, and questions, which need to be addressed, perhaps even more so in New Zealand –  where immigration has been on a much larger scale, and for longer – than in the UK.


Food, culture, regulation….and a walk with the kids

Spurred by a Herald article yesterday, my kids and I went for a walk (well, we do most days but this one had a specific purpose).  The newspaper was reporting  new Auckland university research showing –  shock, horror – that.

“Sixty-nine per cent of urban schools have a convenience store within 800m and 62 per cent have a fast-food or takeaway shop in that distance”

Frankly, I was surprised the number was that low, but then in Wellington one finds small schools in all sorts of odd nooks and crannies.  My three kids now go to three different schools, and each of the schools has shops nearby.  But, as it was nearest, we walked around the area that encircles my youngest child’s decile 10 primary school.  And what did we find?

On the first corner:

  • a dairy
  • a specialist pie shop

On the next corner:

  • two dairies
  • a Chinese takeaway
  • the Empire Cinema, with its neighbourhood café and gelato outlet

And then in the main shopping area

  • the supermarket, (as the kids pointed out, it was chock full of all sorts of stuff, “good” and perhaps “not so good”)
  • a Hell Pizza outlet
  • two fairly casual daytime cafes with plenty of take-out options
  • a combination fish and chip shop/Chinese takeaway
  • the video (and Post) shop, with lots of sweet and savoury nibbles
  • an Indian takeaway
  • another dairy
  • a lunch-bar/bakery
  • the butcher –  bacon and cheerios don’t score well on the “disapproval” lists, and that is before getting onto the question of red meat.

And that was without including the:

  • bottle store and bar, and
  • three other evening-focused restaurants, two offering take-out
  • and a couple of arty galleries/shops selling quite good chocolate.

But so what?  If 70 per cent of urban schools are close to at least one convenience or takeaway outlet, isn’t that simply telling us that our schools are typically in the heart of our neighbourhoods.  Which is probably where they should be.   And I’d be surprised if the number of dairies and takeaway places has changed much in the almost 40 years since I was getting off the school bus at one of these corners (although there was no gelato back then, even in this Italian-influenced suburb).

Buried in the Herald article, well past the calls for governments to “do something”, was this comment from the lead researcher

But she acknowledged that no link between obesity and access to unhealthy food shops had been clearly established by research.

‘The evidence is quite mixed…You don’t have to wait for the evidence to take action.  It’s the same with the sugar tax –  there’s no definite evidence. It’s hard to get definite evidence in science.  The fact is, unhealthy food is so available, accessible, affordable, we should protect children from potentially harmful products. ‘

At one level one can sympathise.  Definitive evidence is certainly hard to come by in lots of areas (including the ones I’ve been closer to, in macroeconomics).  But it is also a good reason for governments to be particularly wary of optional regulatory interventions, that directly impinge on ordinary citizens’ choices and options.

And that is even if one granted that obesity was somehow the government’s problem.  The common argument is that the public health system makes it so, because the government bears the medical costs of the choices people make.  There is something to that of course –  although we all die of something, and the longer-lived cost more in New Zealand Superannuation, rest-home subsidies etc)   – but as an argument it has chilling implications: we should give the government the right to coercively regulate all manner of behavior, simply because the government bears one lot of the costs if things go wrong?  I support a public health system, but taken very far this argument will eventually risk undermining support for such a system, and that would be unfortunate.

In fact, most of the costs of obesity fall on the individuals concerned, and perhaps their families.  A shortened life expectancy, or more sick days, has a cost to the person concerned.  The benefits from the food consumption, or choice to do things other than exercise, also accrue to the individual.

Do people always make wise choices?  Of course not.  Do children and young people always do so?  Even more so, of course not.  Part of growing up is taking risks, and pushing the boundaries.  But a big part of good parenting is to constrain the choices, and to educate kids in a way that means they are less likely to push the boundaries too far.  It is about the ability to say no. It is about the ability to offer treats, in sensible sizes and sensible frequencies. And to balance that with a good basic balanced diet, with all sorts of foods mostly in moderation. And for adults to model eating sensibly –  both within the family, and within whatever other groups the family might be part of (church, marae, sports club, or whatever).  That is a big part of what culture is –  memorizing, practising and reinforcing a sense of the way we do things, ways that support getting through life reasonably successfully.

Do governments have a role in all this?  I don’t see one (and was unnerved  to read that the Health Minister is apparently proud of the fact that the government has “22 initiatives targeting child obesity”).  Which Ministers  (or their Opposition peers) would I regard as good role models, or qualified to provide guidance on shaping the next generation?  A few perhaps, but not many.   Speaking personally, I’ve never found the presence of dairies, takeaway, or even the layout of supermarket shelves, makes my parenting more difficult.  Perhaps others have a different experience  but –  to loop back to the Auckland University researcher’s acknowledgement –  some robust evidence would be nice before governments rush in, trying to tell people where they can locate their businesses, who they can sell to, and so on.

But my inclinations are more austere Puritan than New Zealand Initiative libertarian, and so although I don’t see a role for government controls in this area, I was quite shocked last night when my elder daughter told me that her intermediate school sells potato chips and a variety of other foods of dubious nutritional value at the morning break.  I’m running for the Board of Trustees –  just to make some points in my campaign statement, rather than expecting the Green voters of South Wellington to prefer someone like me – and if elected would want to encourage the school to look again at quite what products it was offering for sale.

Speaking of the New Zealand Initiative, Geoff Simmons of the Morgan Foundation had an op-ed in this morning’s Dominion-Post attacking the Initiative for its new report The Health of the State and its skeptical take on specific taxes on disapproved classes of food (and alcohol and tobacco).  Simmons leads with the point that the Initiative is “corporate-funded”, as if somehow that matters  It is not as if there is any secret as to where the Initiative gets its money from – its members are listed in the Annual Report, and if anything I was rather disconcerted to learn that the Wellington City Council (always happy to intervene in anything) was a member (and Auckland University in fact).  There are lots of things I disagree with the Initiative on, but the issue should surely be the quality of the argumentation, analysis, and evidence. That goes for the Morgan Foundation surely just as much as for the New Zealand Initiative –  both privately-funded research and advocacy bodies, whose presence lifts the generally weak level of public debate in New Zealand.

Simmons suggests that it is really all about “ideology”.  I don’t think that is right –  there is plenty of debate, or should be, about evidence (partial as it inevitably often is).   But he ends his column this way:

“Instead of a facile debate over whether a sugar tax would work or not, we should be discussing which we value more –  living in a free society where you can eat what you like and burden the state, or whether we value having a healthy productive society”

Surely there is room for both?  A serious ongoing debate about the impact and efficacy of proposed interventions, using insights from overseas experience, from other similar interventions, and so on.  But also a debate about what sort of society we want.  Personally, I like the idea of a free society, in which people can eat whatever they like –  but typically choose to restrain themselves, in food as in all other areas of life.  We don’t exist as servants of the state – if anything, it is the other way round.  Civilisation and prosperity have always required restraint and self-discipline in a whole variety of areas of life.  But the track record of governments in creating such cultures doesn’t look good:  governments more often corrode cultures than foster successful ones.


The Treasury on lock-ups

I just received from The Treasury the response to my OIA request about Budget (and similar) lock-ups.  Not quite as fast a response as that from Statistics New Zealand, which I commented on last week, but well within the 20 working days, and thus most welcome.

No doubt they will put the response on their website in due course, but here is the document.

Treasury OIA response on lock-ups

As I’ve noted from the start, I’m less bothered about pre-release lock-ups for Budgets than for OCR announcements or the release of key macroeconomic data.  Most of the time, most of what is in the Budget is not that market-sensitive –  and what is headline-grabbing has often been well-foreshadowed by Ministers and their staff.  And Budgets often have a large range of complex material, straddling numerous portfolios areas.  When new initiatives are announced often the details can be tricky, and important. But I don’t think Treasury can be complacent about these lock-ups –  there is sometimes material there that is market-sensitive.  Advance news about the bond programme would, at times, be very valuable.  There is a difficult balancing act, since Budgets are a mix of political management and  other, perhaps market sensitive, material.

Like the Reserve Bank in the past, and SNZ still, the Treasury seems to rely mostly on trust for the security of the lock-ups.   Attendees are not even required to surrender phones or mobile devices, just required not to transmit with them.  Apparently “compliance is monitored throughout”, but presumably by wandering around. I imagine the Reserve Bank staff did that in their lock-ups.

I had asked about any reviews undertaken in light of the Reserve Bank’s experience.  As is already known, after “discussions” the Secretary to the Treasury has decided to go ahead with this year’s lock-up.  There is no suggestion that those discussions included any effort to identify whether leaks had occurred in the past, along the lines of what happened at the Reserve Bank.  The Deloitte report gave no suggestion that the MediaWorks breach was accidental, and there are even suggestions afoot that the journalist involved may have been under management instructions to send draft stories from the lock-up (see John Drinnan’s comment at the end of this post).   If a story was deliberately sent from the OCR lock-ups, might the same practice have occurred, with the same people, at previous Budget/HYEFU lock-ups?  I don’t know, but then neither –  it would appear – does The Treasury.

Treasury is probably quite safe this year, since everyone (no doubt including MediaWorks) will be hyper-sensitive to the Reserve Bank experience.   But weak systems create a high risk that there will eventually be breaches.


A wrong decision, but perhaps not too surprising

Graeme Wheeler’s OCR decision this morning –  perhaps he will tell us how many of his advisers backed this one? – was the wrong decision.  Core inflation measures remain well below the midpoint of the inflation target, and there are few or no pressures taking inflation sustainably back to the midpoint, even though it is now almost 11 months since the Reserve Bank began unwinding the ill-fated 2014 tightening cycle.

Keeping medium-term inflation near 2 per cent is the monetary policy job that has been given to the Governor.    Nothing else matters very much in the Policy Targets Agreement.  There has been talk in some quarters that the inflation target should be lowered.  The Minister of Finance says he hasn’t found that case persuasive, and he sets the target.

But if it was the wrong decision, it perhaps wasn’t too surprising a decision.  Graeme Wheeler has been reluctant to cut the OCR all along.  He continues to talk of how “accommodative” monetary policy is, but that appears to be referenced against a view that the “neutral” interest rate is 4.5 per cent (their last published estimates, although one hears that they tell investors in private meetings that that estimate is now around 4 per cent –  perhaps reflecting the fall in inflation expectations?).  He thought he was getting things “finally” back to normal when he launched the 2014 tightening cycle, talking confidently then of the prospects of 200 basis points of tightening.   It would be better, frankly, if the concept of a neutral interest rate was largely excised from central bankers’ vocabulary for the time being, because neither they nor we have any good sense of what “neutral” actually is.  Any such estimates have too often been a dragging anchor, helping hold back central bankers from the sorts of policy adjustments that meeting their respective inflation targets would have warranted.

So the Governor has been consistently reluctant to cut the OCR –  and even more reluctant to admit his past mistakes – and has only done so when the weight of evidence has overwhelmed his preferences.  Last year it seemed to be some mix of further falls in dairy prices, the failure of inflation to recover,  and/or high unemployment.  As recently as the start of February, in his forthright speech, the Governor was again holding out against the prospect of further cuts –  never ruling them out, but making pretty clear where his inclinations lay.  But then the data overwhelmed him again.   The new inflation expectations data shook the Bank, and the deteriorating global economic outlook and rising financial market unease (including widening credit spreads) prompted a move in March, with the prospect (projection) of one more cut to come before too long.

But in the past six weeks, there hasn’t been that much news, and little to change anyone’s baseline story.  There hasn’t been any new labour market data, the CPI had something for everyone, there was no material new inflation expectations data, and if the global economic outlook still looks unpromising, financial markets have recovered somewhat (including credit spreads banks face) and oil and various hard commodity prices have been rising.  If your reference point is that the OCR “really should” be something more like 4 per cent, why would you take the “risk” of cutting the OCR now?  It might be different if your reference point was that core inflation measures have been persistently below target for years, and that that gap shows little or no signs of closing.

What of the housing market?  I explicitly commended the Governor’s approach to house prices at the time of the March MPS:  asked about the risks that a lower OCR could provide a big further impetus to house prices, he  had simply observed “well, that’s just something we’ll have to keep an eye on”.   It helped that, at the time, the Bank  noted that house price pressures in Auckland had been “moderating”.  Recall that house prices are explicitly not something the Reserve Bank has a mandate to use monetary policy to target.

Six weeks on and house price issues are all over the headlines again, given added impetus by the Prime Minister’s talk of land taxes for non-residents etc.   The Bank’s tone has changed, although it is still somewhat cautious: “there are some indicators that house price inflation in Auckland may be picking up”.  Frankly, it would be surprising if it were not –  new distortionary policies introduced by the Bank and the government late last year should only ever have been expected to have had short-term effects.  Nothing fundamental about the market has changed.  It still isn’t the Bank’s responsibility at all, and certainly not something that should be driving monetary policy.  But when all his inclinations seem to be against cutting, unless “forced” to by new data, and with a potentially awkward Financial Stability Report only a couple of weeks off, it would have been another reason to hold back.

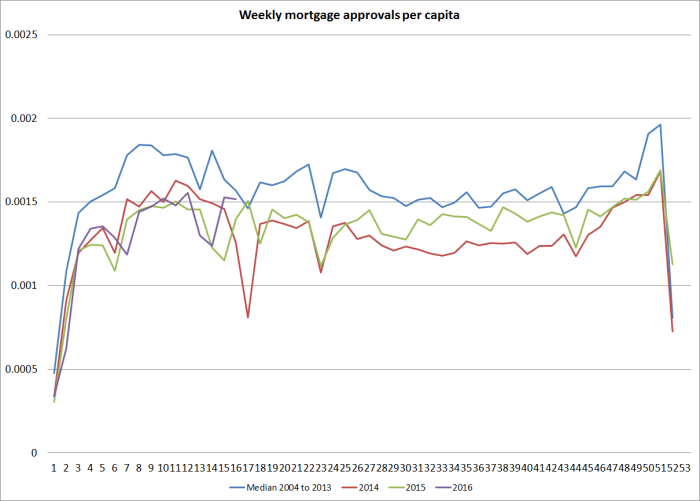
Are house prices really taking off?  The Dominion-Post would have one think so, highlighting this morning a sharp rise in the price of a house in the sunny but unprepossessing suburb of Berhampore, perhaps a kilometre from where I sit.  In terms of activity levels, I run this chart of the number of (per capita) mortgage approvals from time to time.  There doesn’t seem anything extraordinary about current volumes of mortgage approvals (again, the x axis is weeks of the year, numbering 1 to 52/53).

weekly mortgage approvals

Various people who talk to the Reserve Bank have been telling me since March that the Bank has finally “got it” and recognized that the overall domestic and economic climate is such that materially lower interest rates were needed.  I wish it were so, but I think today’s statement confirms my “model”, in which the Bank will cut only reluctantly, and only if  –  in effect – “forced” to.  The Governor just doesn’t seem worried about having the economy is a position where  the best guess of next year’s inflation rate would in fact be 2 per cent.  He seems content so long as (a) he can mount a semi-credible story that headline inflation gets back above 1 per cent before too long, and (b) so long as the measures of core inflation don’t consistently drop below 1 per cent.  Otherwise, house prices seem to play too large a role in his “reaction function” –  he can play them down and suggest they aren’t a consideration when they look a bit quiescent, but they act as quite a drag on good monetary policy at any other time.

I’m not overly keen on central banks reacting much to exchange rate movements in most circumstances.  Often enough, the exchange rate changes reflect something “real” or fundamental going on.   The Bank’s own research has suggested that falls in the exchange rate haven’t materially boosted overall inflation –  probably for exactly that reason.  But it is the Governor who keeps going on about the exchange rate and how uncomfortable or inappropriate or undesirable it is.  And yet the one thing he can do that make a difference to the exchange rate is the stance of monetary policy.  A lower OCR, all else equal, will tend to lower the exchange rate.  As it, the Governor must have gone into this morning’s announcement knowing that it was almost certain that there would be quite a bounce in the exchange rate.   Despite the absence of media lock-ups, there didn’t seem to be much uncertainty about the market reaction this morning.

Trade-weighted index measure of the exchange rate:

twi

And so we are delivered an exchange rate a full per cent higher than the level the Governor considered inappropriately high at 8:59am. That seems unnecessary and unfortunate.

The disastrous New Zealand (especially Auckland) housing market is primarily the responsibility of elected central and local government politicians.  It is not something to be controlled or moderated, except incidentally, by good monetary policy (to be aimed at stability in the general level of prices) or regulatory imposts on banks (supposed to be used only to promote the soundness and efficiency of the financial system.    If the Reserve Bank thinks banks need more capital, let it make such a proposal, advance the evidence, and consult on it.   If it thinks  banks are making reckless lending choices, again let them lay out the evidence in the forthcoming FSR, and tell us about the conversations it is having with bankers, and any regulatory measures it is thinking about.  But it simply is not a matter for monetary policy.

Looking ahead, there is not much key New Zealand macro data due before decisions are made on the June MPS.  The quarterly labour market data are out shortly, but after the noise in  the unemployment rate recently, it may be difficult to get much very new from that data yet.  Perhaps as important might be the next Survey of Expectations, and particularly the inflation expectations results in it.  Today’s statement is quite relaxed about inflation, and adamant that “long-term inflation expectations are well-anchored at 2 per cent” (not “seem to be”, not “close to”, but “are”  and “at”).

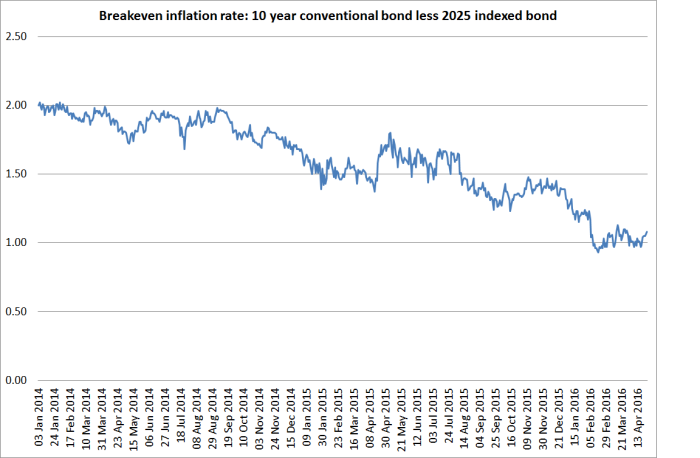
That certainly isn’t the message from financial markets.  Yes, I know that the implied inflation expectations from indexed bonds aren’t a perfect indicator –  then again, neither are the other measures of expectations or core inflation –  but the current level, just above 1 per cent, seems pretty close to the average of the various core inflation measures the Reserve Bank highlighted in the last MPS.  The central view just doesn’t seem to be that we can count on 2 per cent average inflation any time soon.  That should be a mark against the Reserve Bank.

iib breakevens

In closing, I should note a couple of small aspects of the Bank’s press release that I welcome.  I (and no doubt others) had lamented the Governor’s recent high profile focus on a single, complex, prone to end-point issues, measure of core inflation.  In this statement, that is replaced with a  simple “core inflation remains within the target range”.  Only just within, I would argue, but it is better than putting so much official weight on a single measure.

And in the final paragraph, I have noted for some time an unease at how much weight the Bank has been putting on recent and near-term headline inflation in these statements  –   in the near-term, headline inflation is thrown around by all sorts of things.  This time, they have gravitated towards something more (PTA consistent) medium-term in focus: “we expect inflation to strengthen as the effects of low oil prices drop out and as capacity pressures gradually build”.  One could reasonably question whether there is any sign that capacity pressures really are building, or are likely to over the next year or two –  after all, they have been relying on this “gradual build” for some years now – but at least it puts the emphasis in the right place: the factors that shape the medium-term outlook for inflation.


Lessons from the losers: Reflections on (Struan) Little

As I noted a few weeks ago, about fifteen years ago Struan Little, then at The Treasury, sparked my interest in Uruguay, and comparisons between its long-run economic performance and that of New Zealand.  When I wrote that earlier post, I searched around to see if anything Struan had written on New Zealand’s economic performance was on the web.    Nothing was now, but it became clear that something had been.  Various old articles (eg here) referred to a paper released at the end of 2001 by Treasury, drawing “lessons from the losers” –  other reasonably advanced. reasonably democratic, countries, or regions, with some similarities to New Zealand, which had also done poorly.   The paper had even been cited by the IMF in one of their Article IV reviews of New Zealand.

The author no longer had a copy of the paper, but fortunately Treasury was able to track it down for me.  The OIA response should be on their website before too long, but in the meantime here is the document itself, “Growth and Policy in other countries: lessons from the losers”, dated 31 October 2001.

Lessons from the Losers by Struan Little

As Treasury is at pains to note, this was a personal thinkpiece, and although it was publicly released back in 2001 to influence debate and discussion, it was never finalized.  It isn’t a long paper (12 pages of text), so couldn’t cover everything, or document every caveat or qualification, but papers like this help us see the issues in slightly different ways.  It is to Treasury’s credit that they made space for the work to be done, and then put it out proactively for discussion.

In his stimulating paper, Little thinks about New Zealand’s experience in light of  eight comparators, four of which he saw as having had a “disappointing economic performance over a long period of time”

  • Uruguay
  • Switzerland
  • Tasmania
  • Atlantic provinces of Canada

And four of which “have gone through very difficult periods but moved on to become some of the richest economies in the OECD”

  • Denmark
  • Finland
  • Iceland
  • Ireland

The inclusion of Switzerland might surprise some, since it is –  and consistently has been –  one of richest countries in the world.  But its productivity growth had been strikingly weak over several decades.  Overall, it is a fascinating alternative lens to look at New Zealand’s experience through  – a contrast to, say, simply looking at the US or the UK, or even the OECD as a whole.

To structure his discussion, Little drew seven “broad lessons”

  1. Losers can’t be saved.    He isn’t quite as pessimistic as this sounds but observes “once you are gifted with the “loser economy” tag, there is no single policy (or even groups of policies) that can easily reverse this decline”.
  2. Don’t just blame size and distance.
  3. We spend a lot on education and training but do we get results?
  4. Technology-Driven Productivity Growth Went Out with the Tech Bubble. NZ firms don’t do much (that is classified as) R&D spending, but “the links between R&D and economic success are not clear”.
  5. You are either on the internationalization bus or plugging through the mud. NZers attitudes to internationalization weren’t very positive, and the volatility of the real exchange rate had been a problem, holding back our tradables sector/
  6. Social consensus matters
  7. Are individual interventions effective?
    • Size of government doesn’t matter
    • Centralisation isn’t all bad
    • FDI can help
    • Public infrastructure investment can be a waste of money

His own view, in conclusion, was that three policy areas were paramount for New Zealand, if it was to sustain a higher growth rate in future

  • Sound and stable macro policies, with a particular emphasis on a less volatile real exchange rate.
  • A shared social vision as to New Zealand’s future
  • Greater internationalization (changing attitudes, more emphasis on trade agreements, and “perhaps greater assistance to exporters”.

Any 15 year old paper on a topic of this sort is going to read a bit oddly in places –  at the time, for example, Italy was cited as an example of a notably successful economy (unfortunately it has had no per capita growth at all since then).  And although all of his four success stories remain much richer than New Zealand, each has had a new very rocky time in the last decade or so.

And whatever any author writes on a topic like this is going to be partly a product of his/her experiences and context.  2001 was two years into the first term of the Labour government, and I suspect Michael Cullen would not have been unreceptive to many of the sorts of messages in this note (which is perhaps why Treasury was able to publish it).

But I wanted to comment on one of the strands of policy Struan emphasizes, and then highlight a few that I was interested to find no mention of (perhaps partly reflecting the fact that today’s context is different to his).  And then offer a few thoughts on whether “losers’ can be saved.

The first is the volatility of the real exchange rate.  Little notes the materially greater volatility of New Zealand’s real exchange rate than those of Denmark, Iceland, Finland, and Ireland and observes:

“I see this as one of the key reasons why our export performance has been relatively weak compared to more successful economies.  While more extreme than New Zealand, the experience of Uruguay and the Southern Cone countries shows than an upward appreciation of the real exchange rate can undermine a reform programme and prevent a country from getting out of a low growth trap……..I would hope that improvements in our monetary framework may resolve the real exchange rate issue.”

What was the context?  We had had a relatively volatile real exchange rate in fifteen years since the exchange rate had been floated.  In 2001 the real exchange rate was actually very low –  only just off its all-time lows –  but there had been a lot of recent focus on the conduct of monetary policy.  In fact, Struan and I had been the bulk of the secretariat to Lars Svensson’s review of New Zealand’s monetary policy arrangements, which had been commissioned by the incoming Labour government –  concerned about the exchange rate, and disconcerted by things like the Bank’s unfortunate Monetary Conditions Index experiment.  That inquiry had reported earlier in 2001.

The Reserve Bank has always cautioned against emphasizing the volatility of the real exchange rate as a factor in New Zealand’s economic underperformance. As various people have noted, our real exchange rate is not extraordinarily volatile by advanced country standards –  which sample you compare it with matters a lot –  and much of the volatility reflects the real and financial external shocks the country faces. I largely agree with the Bank’s perspective on this issue –  and it isn’t obvious that much could be done to attenuate the big cycles in the real exchange rate anyway –  but we need to be open to the possibility that the impact is greater than we realise (if, eg, fluctuations in commodity prices contribute directly to exchange rate fluctuations, making it very difficult for other industries to successfully emerge and compete internationally).  But changing the details of the monetary policy framework isn’t likely to make much difference –  we’ve been through a wide variety of regimes over the decades, and had quite big real exchange rate fluctuations in each of them.

I’ve been more concerned about the average level of the real exchange rate.  Right from the early days of the reforms, experts (themselves supportive of the reform programme) have emphasized the importance of a lower real exchange rate as part of a path towards rebalancing the economy and establishing a stronger growth trajectory.  It was the Reserve Bank and Treasury view as far back as 1985.  Leading international scholars like Anne Krueger and Sebastian Edwards re-emphasized it –  partly in reference to the Latin American experience Little alludes to in the quote above.   It isn’t a line that is so widely heard in the mainstream these days, but the failure to achieve any per capita growth in New Zealand’s tradables sector in the 15 years since Little was writing suggests that the issue has not gone away.  Our persistently high (relative to other advanced countries) real interest rates look to be related to the failure of the exchange rate to adjust –  but that gap wouldn’t have been so evident in 2001.

T and NT components of real GDP

Reading through Little’s paper yesterday, three omissions struck me:

  • first, there was no specific mention of Auckland whatever.  I’m not critical of that  –  as I’ve made clear, I think the policy focus on growing Auckland is seriously misguided –  but one could not imagine a similar paper today not touching on the Auckland (and agglomeration) issues.
  • second, there was no mention of taxation and particular not the taxation of capital.  Perhaps it isn’t a material explanatory factor, or a tool that might make much difference, but the Irish experience with a very low company tax rate, and the Nordic experience with setting tax rates on capital income much lower than those of labour income look as though they should be candidates for inclusion in a list of explanatory factors.
  • third, there was no mention of immigration (policy) at all.  Emigration –  from all the “losers”  – got a mention, but not the role of policy-facilitated immigration of non-citizens.  Perhaps it just reflected the times – overall net immigration was quite modest around the turn of the century –  but the scale of our non-citizen immigration programme, unparalleled in the other countries and explicitly seen as an economic growth lever, looks as though it probably should have rated a mention of some sort.  (Of course, the paper was written just before the New Zealand house price boom started, so not even immediate house price effects of immigration were salient then).

Perhaps relatedly, in his final section Little talks of the contrast between fixed and mobile factors of production, emphasizing labour (“at least to an extent”) and social institutions as fixed factors.  It was a surprise that, in an economy whose exports are overwhelmingly natural resource based, our land wasn’t considered as an important fixed factor –  an opportunity and, perhaps, a constraint.

I’m explicitly not writing to criticize Little’s paper.  There is so little good material on these issues, and his note offers a lens that helps stimulate one’s thoughst even when not fully agreeing with it.  But there is perhaps one area where experience might suggest he was a little too pessimistic.  Even his “losers” can, it seems, turn themselves around, at least to some extent.

Of course, even in 2000 we knew that in some cases –  the better countries of Eastern Europe were already rebounding from the dark decades of Communist rule.  But it seems to have been true of some of Little’s losers too.

Switzerland’s productivity growth still isn’t stellar, but the Swiss have very large net foreign assets. I checked the net national income per capita data from the OECD this morning, and over the last 15 years, Switzerland –  already richer than most –  has outstripped growth in the OECD as a whole, and in the United States in particular.

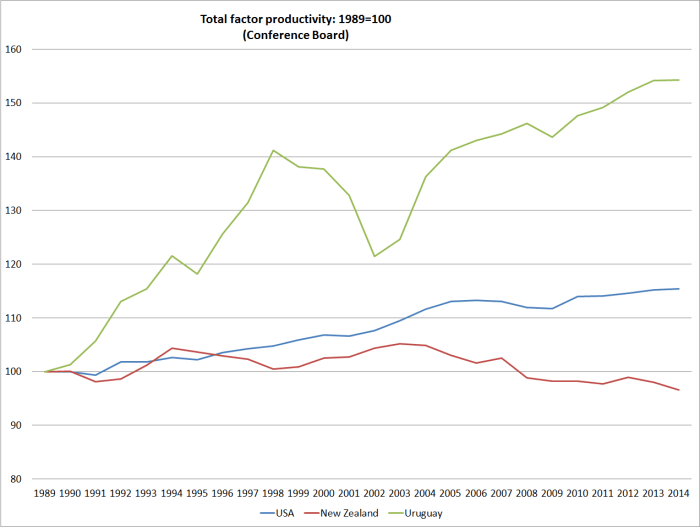
For Uruguay, I showed this chart a few weeks ago, of TFP growth over the last couple of decades.

uruguay nz 4

Uruguay has a long way to go, but they’ve made an impressive start.

And what about Tasmania?  The Australian state GDP data start from 1990, and Little writing in late 2001 discusses the record in the 1990s.  Here is how NSW and Victoria, on the one hand, and Tasmania on the other have done over the subperiods 1990 to 2001 and 2001 to 2015.

real gspQuite a rebound in relative performance.
New Zealand, meanwhile, has shown no signs of even beginning to close any of the big gaps in productivity  –  if anything, on many measures they are still widening.

In terms of my narrative of New Zealand’s policy problems, one thing that marks out territories, states or regions from countries is that the former do not have an immigration policy.  Population growth in Tasmania may be very slightly influenced by Australia’s overall immigration programme, but largely people move to Tasmania only if the relative opportunities within Australia are better in Tasmania than they are elsewhere in Australia.    Tasmania looks like the sort of place –  like my story of New Zealand –  that can generate good incomes for a small number of people.  And in the last 25 years, Tasmania’s population has increased by around 12 per cent, while the populations of New South Wales and Victoria have increased by more than 30 per cent.   By contrast, in New Zealand’s case, the central government’s immigration policy directly boosts the population of the entire country.  Unlike Tasmania, we’ve had more than 35 per cent population growth since 1990, mostly concentrated in Auckland.  In such an unpropitious location for economic activity, it has just made it that much harder to even begin to close the income gaps.

Old papers aren’t to everyone’s taste, but the issues Little’s paper treats (or those treated in my own speculative entry to the field from a few years ago) haven’t gone away.  Unfortunately there is little sign of our political leaders –  government or opposition –  really doing much to reverse the decline of this “loser”.


Financial capability: what New Zealanders could do with from their governments

I’ve written previously, and skeptically, about the financial capability strategy the government released last year. It is something of a wonder that civilisations have reached their current prosperity and sophistication without the aid of governments and their officials strategizing and pontificating about what we, citizens, “need” to know about money.  “Building the financial capability of New Zealanders is”, we are told, “a priority for the government”.  But what business is it of theirs?   And each time I read that line, I can’t help thinking that it would be better, and much more legitimate, if it were reversed: building financial capability of governments (and its agencies and officials) should be a priority for New Zealanders.

Last week, the bureaucrats were at it again.  The Financial Markets Authority published a so-called White Paper, with a Foreword written by the Chief Executive (so this is no mere background research paper, simply reporting the views of the authors), headed Using behavioural insights to improve financial capability.   The paper seems to be laying down markers for future regulatory initiatives.  It is probably better that the paper is out for scrutiny, rather than being held closely among the various government agencies.  But as I read it, the words of Jesus kept coming to mind

You hypocrite, first take the plank out of your own eye, and then you will see clearly to remove the speck from your brother’s eye.

The report is full of enthusiasm for understanding better the way in which consumers make decisions –  as if marketers and advertising agencies have not been doing that for decades.   It does so by drawing on a variety of insights from the behavioural financial literature, but in a fairly highly simplified (and one-sided) manner –  the entire report has 12 pages of text, with plenty of white space.   The behavioural financial literature does offer some fascinating perspectives on how people make decisions, but not often on why they have evolved to make those decisions that way.   And it does offer useful insights for marketers, and even for government officials trying to improve compliance rates (getting taxes, fines or fees paid on time).  Framing clearly matters.

But the leap from better understanding how consumers and citizens makes decisions to recommendations for policy interventions is not typically based on very much at all.  Assertions such as the claim by FMA CEO Rob Everett that “it is no one’s interest….for any investment decision to be made on the basis of bias or behavioural idiosyncrasy” seems to be based on nothing at all.  Or to be charitable, perhaps it is based on some benchmark of conforming human behaviour to some simple, particularly sterile but tractable, economic model, rather than recognizing that our biases and idiosyncracies (as he calls them) are often intrinsic to our humanity.  The authors seem to have a particular distaste for any involvement of emotion in decision-making.

It is a short paper, and so in a sense it is all too easy to pick holes.  But these bureaucrats appear to want to shape policy thinking, and they made the choice about what to put out for discussion.  So when they say “we overspend on credit cards and pay down debt less than we should”, we might reasonably ask not whether they can cite a single paper that shows that under certain experimental conditions this result might be able to be produced, but rather “where is the systematic evidence of a problem?”    Advances outstanding on credit cards at present are less than 3 per cent of GDP –  any credit card debt ever is too much for me personally, but across the economy  it is hard to find evidence of a problem spiraling out of control.

And, of course, much of the discussion of these issues has a subtext of unease about the choices people make for retirement provision. But again, where is the evidence of a problem justifying policy intervention?  The FMA paper asserts that “most people struggle to plan for future needs”,  But, as is widely recognized, New Zealand has one of the very lowest rates of poverty among elderly people of any advanced country, and older people seem to score their own life-satisfaction quite highly.  Is there any public policy interest at all in particular consumption outcomes for middle and upper income people in their later years?  Subject to the basics being met –  which they clearly have been in New Zealand –  I can’t see one.

Thus, when the paper cites interesting experiments which can lead to people saving more, it never stops to ask “by what measure, against what benchmark, is higher savings a desirable outcome for these population groups as a whole”.  There is simply no evidence of a “savings problem” in New Zealand, either at a micro level or a macro one.  Kiwisaver’s auto-enrolment (with opt-out) feature is described as “demonstrating the success of this approach”, but against what benchmark? To what end?

And when they report that research “shows people who have a plan are more likely to feel prepared for their retirement. The effect was consistent across all income levels”, are they telling us anything more than that some people like to have all the i’s dotted and t’s crossed, and they feel better if they have a “plan”.  It tells us nothing whatever about the ability of people to get through life.

In devising regulatory interventions, when they are well-warranted, it is important for regulators to understand how humans are likely to behave and respond.  And if those insights help get fines or taxes paid more promptly, then I’m right behind the use of them.  But when governments and their officials think they can do better than people, and market institutions, somehow correcting for the “flaw” in human nature, which have evolved over tens of thousands of years, we should be much much more skeptical.

Among the many reasons for such skepticism is the unspoken point that government officials and ministers, even those in the FMA, are human beings too, subject to all the same characteristics of human nature.  There is no class of detached super beings able to wisely choreograph the rest of us (directly or indirectly). And frankly it would be frightening, not reassuring, if there were,

But none of the weaknesses of regulators or governments appear in this White Paper at all.  There is a passing acknowledgement on the final page that “not every intervention is good” (really????) but no sense at all of the weaknesess, or biases to which regulators and officials and politicians are prone.    A good first question for every official or politician proposing new controls is something along the lines of “and what biases etc are you subject to, and how do the institutions protect citizens from (unwitting) bad outcomes from that actions of people like you –  including if the regime was run by your politicial opponents or the officials from the agency you have least time (and respect) for.”

As I noted earlier, a much stronger case could be made that citizens need a stronger financial capability among our governments and government agencies, and protections from all the “biases” or behavioural inclinations to which governments are prone.  Governments get countries into expensive wars.  Government choices are most often at the root of financial crises.  Governments mess up countries’ growth (and future consumption) prospects.  Governments badly distort housing markets.  Governments build expensive white elephants (whether sports stadiums, Think Big projects, or airport runway extensions).  Governments regulate on the whims of key individuals, with little or no regard for the consequences.  Governments put in place new programmes with little ability to assess longer-term consequences for individuals or society (eg welfare systems). Governments repeatedly eschew rigorous cost-benefit analysis.  And so on.   Not all governments, not everywhere –  and almost always with good intentions – but all too often.

This isn’t an anti-government tirade.  Societies need governments.  And they need governments to do well what only governments can effectively do (police, defence, administration of justice and so on). But the fact that we need governments does not mean that we safely can, or should, trust governments and their agents and agencies. Before they try to sort out human nature, we might more aptly aim to put in place much stronger checks and balances to restrain the flaws and biases to which governments seem intrinsically prone.

Last week, US economist Bryan Caplan on Econlog drew attention to a fascinating looking (quite long) new paper from Texas A&M University School of Law, “Behavioral Public Choice and the Law”.  I haven’t read it all yet, but I intend to.  The table of contents alone looks promising.

public choice

When we’ve seen the FMA –  and perhaps more importantly policy agencies like Treasury and MBIE –  seriously grapple with this sort of literature, I might be more interested in listening to their proposals for how they think government interventions might help improve citizens’ own decision-making.

This looked as though it should be a good topic for the New Zealand Initiative to pick up, following on from their new report on other paternalistic interventions (sugar taxes and the like). But then I noticed that the chairman of the FMA is also on the Board of the New Zealand Initiative.


Some perspectives on reform and the RB in the 1980s

A new book came in the post the other day.  It is a scholarly look at the long-term relative economic performance of New Zealand and Uruguay, something I wrote about quite recently and a subject I may come back to when I’ve read the book.

But there is an old line, especially applied to newspaper and magazine articles, that when the coverage of something you know about doesn’t ring true, be wary of the rest of the article.  And flicking through this new book my eye lit on a strange reference to the Reserve Bank.

In a paragraph on the reform period from the mid-1980s to the early 1990s (“which showed characteristics of a coup”), the author writes

Douglas as well as further members of the Cabinet, the Business Roundtable, and other strategically located institutions represented the exclusive inner circle of the new right. Until at least 1988, they used their large human capacities at the Treasury and the Reserve Bank to suppress alternative views and to limit the choices for MPs to a laissez-faire policy agenda.  Just as under Muldoon before, opponents were driven out to other departments and the private sector through informal pressure or became subject to petty harassment [ a footnote at this point adds “even university staff were affected, as controversial articles were less likely to be published in 1990 than in 1930”].

Very little of this rings true to me.

I’m not going to speak much of the Treasury, except to note that (a) Roger Kerr always spoke of how Muldoon respected the traditional boundaries of the public service, allowing Treasury (and people like Kerr) to develop their more market-oriented approach to analysis and advice (even if the Minister himself was not receptive to much of that advice), and (b) that I do know a few very able (and later successful) people who were either turned down from jobs with Treasury in the late 80s, or chose not to apply, because they were not-entirely-sympathetic to the reform process.  Plenty of people from the “right” in Treasury left for the private sector during those post-liberalization years –  opportunities abounded.

What of the Reserve Bank?  I was a manager in the Bank’s Economics Department (then, its main economics and policy wing) from 1987 to 1993.  At any one time, there were around six of us in the management group (led by Grant Spencer, and then Arthur Grimes), and above the department were the Governor and two or three Deputy/Assistant Governors.  There were a handful of other key people leading other departments (Financial Markets, International, Financial Institutions).  I suppose we should be flattered to be described as “large human capacities”, but to read the extract above one might suppose this was some phalanx of right-wing zealotry, demolishing all in our path.

There was a fair amount of turnover at the Bank during these years.  It wasn’t mostly people fleeing to the rich rewards of the financial markets –  mostly that was the next tier down –  but people coming and going from positions with international agencies such as the IMF and World Bank and advisory positions in developing country central banks.  I jotted down a list of 24 people who held the various key economic roles in the Reserve Bank over those years, and went looking for the right wing zealots.  No doubt some would class Roderick Deane in that category, but he had left the Reserve Bank in 1986.  What was left was a very short list.  I recall one very able colleague who wrote a nice think piece on free banking, and another who (in the abstract) was keen on open borders.  We liked to believe we were keen on rigorous economic analysis –  others can judge how well we did.  Most probably believed in fewer controls rather than more, and lower inflation rather than the New Zealand track record of the 70s and 80s.  Probably all wanted to be part of turning around New Zealand’s disappointing economic performance.  But a haven of ideological zealots it was not –  and what research we were publishing was mostly quite technocratic (at the time, most of the Bank’s research resource was devoted to building a new macro model, which proved largely useless amid the transitions and data discontinuities) and not much oriented to the overall policy framework at all.   Assistant Governor, Peter Nicholl, was said –  I never knew if it was true –  to have been involved in the Labour Party in his younger days before Labour became market-oriented, and at least two of us canvassed for National in the 1984 election (I blame my colleague..).  Largely, we were not-very-ideological technocrats.  I wasn’t much involved with recruitment at that time, but I don’t recall any suggestion of ideological tests

Even when it came to the new goal of price stability, launched on  the public somewhat surprisingly one April Fool’s Day, and us a day earlier, by Roger Douglas, the Bank was hardly champing at the bit to get going and eliminate inflation.   Grant Spencer – then chief economist –  and Peter Nicholl, his boss –  were both pretty wary, very uneasy about the (unemployment) costs of getting there.  For some, enthusiasm waxed and waned as economic fortunes changed.

In fact, that was somewhat so for the institution as a whole.  Don Brash is other name associated with an ideological perspective.  Don only joined the Bank in late 1988, but was hardly pursuing very low inflation aggressively –  at least from the perspective of the in-house hawks (it did, after all, take more than seven years to get inflation down). Don was also the one who signed up to Mike Moore’s Growth Agreement with the trade union movement during the 1990 election campaign.  Don recommended extending the target date from 1992 to 1993, explicitly to help allow room for a fall in the real exchange rate, to assist with rebalancing the economy.  And during 1991 Don and his, by then deputy, Peter Nicholl shocked some of younger enthusiasts by easing policy on the argument that “preserving the framework [RB Act] was more important [in the near term] than price stability”.  (Some of this material I dealt with here.)

I’m not suggesting that we were without fault, but equally –  and contrary to the impression given in the quote above –  we were operating in a climate in which everything was contested, and no one was confident that the reforms would endure.  It is fine to say that both main parties supported the reforms, but the big divisions were within the two parties not  between the leadership of the two (Labour had large left-wing factions which had Jim Anderton as their most prominent figure, and National had Sir Robert Muldoon, Winston Peters –  and Bill Birch, then still mostly thought of as the former minister of Think Big).  It is no secret, for example, that National’s support for the Reserve Bank Act was the result of an extremely close caucus vote, which Muldoon missed on account of illness.  Even when National won the 1990 election, we in the Reserve Bank were not remotely confident that the Richardson wing would be in the ascendant (or for long).  For the first year of that government, we (and Treasury) were constantly uneasy that political fortunes would change quickly, and many of the reforms could go as quickly.

I was also a bit surprised by the comment about the universities. I know various academics felt quite embattled, and ignored (and there was some grievance about cuts of government funding for the NZIER eg), but from our perspective in the Reserve Bank we also felt embattled, and were the subject of frequent academic attacks  (those were the days, unlike now, when university economics academics were very engaged with policy issues).  There had been the several rounds of exchanges between Victoria academics and the Bank and Treasury in 1985, on the analysis in the respective post-election briefings.  And when the Reserve Bank legislation was going through Parliament in 1989, the New Zealand academic economics community was pretty united in opposition (there may have been the odd supporter, but they kept very quiet).  This was the occasion of one of the more embarrassing lines I wrote in my decades in the public sector: we published an official response I had written to one prominent submission that had noted the absence of local academic support for the legislation: that said, we asserted, more about the quality of New Zealand academic economics than about the merits of the proposal.  We felt pretty embattled –  even if it didn’t always look that way to outsiders.

There was a lot about the reform period that isn’t particularly attractive, and of course –  although I continue to think that most of what was substantively done was in the right direction –  it doesn’t help that our relative economic decline continues, albeit at a slower pace.  New Zealand political institutions in those days  (single chamber, FPP) allowed small groups of politicians to do a lot quickly with few formal checks and balances. Publishing manifestos the week after an election, or simply abandoning high profile campaign promises really shouldn’t be the done thing.

But this simply wasn’t a period of a monolithic reforming class dominating everything.  Battles within parties were often vociferous, and opponents often had to be bought off with one concession or other.   And Roger Douglas was ousted after only four years, and Ruth Richardson was to last only three years as Minister of Finance.  As it happens, most things that were done haven’t been reversed, but that was never inevitable.  Things were contested and challenged –  perhaps not as well as they could have been (the quality of public debate has long seemed to lack something, on all sides) –  and probably nobody emerged unscathed, or totally satisfied.

Perhaps one small marker of the times was a snippet I stumbled on in a scholarly biography of Ken Douglas, picked up at a charity sale over the weekend.   Douglas was then the head of the trade union movement, and was not exactly from modernizing centre-left: he was prominent in the Moscow-aligned Socialist Unity Party (openly defending, only a few years previously, the Soviet invasion of Afghanistan and the suppression of the Polish Solidarity movement). The book records that in 1988/89 there was a political furore over the possibility of Douglas being appointed to the Board of the Reserve Bank.  It didn’t proceed – the government at the time would not confirm or deny the possible appointment, suggesting there was something to it (and Douglas has subsequently confirmed that he was approached.)  Would it have been an inappropriate appointment? Not necessarily, but that the idea was even raised goes against any sense of Roger Douglas, and his Treasury and Reserve Bank “large human capacities” simply ramming through anything they liked.

I really hope the rest of the Uruguay/New Zealand book is better. If so, I’ll let you know.


Should household debt be a worry?

Westpac had a note out the other day under the heading “Household debt levels now higher than before the financial crisis”.  Using December data for household and consumer debt (including debt used to finance residential rental businesses) and comparing it with household disposable income, they calculated that household debt was 162 per cent of income, compared to 159 per cent at the previous peak in September 2009.

Using slightly different numerators or denominators alters the picture only a little. Debt to income ratios fell back during and after the 08/09 recession, and have been increasing quite a bit in the last couple of years.  Credit growth has picked up and income growth has slowed.  I prefer to focus on debt to GDP measures, and here is my version of the chart.

household debt to gdp

The ratios haven’t yet reached the previous peaks, but aren’t that far away, and may well go past the previous peak this year.  One gets much the same picture looking at broader credit aggregates relative to GDP.

One could look at these trends in a variety of ways. I’d tend to emphasise the fact that over the last 7.5 years there has been no growth at all in the ratio of household debt to GDP, whereas over the previous 15 years that ratio had increased by around 60 percentage points.   Westpac seems much more worried than that.

But there are a couple of important things we know (or know we don’t know):

  • that we have no idea what any sort of “equilibrium” ratio of household debt to income is.
  • that when household debt levels were first at these sorts of levels, around the time of the 08/09 recession, it didn’t lead to any serious stresses on the financial system –  we had a pretty serious recession, mostly reflecting global developments, and yet there was never any question about the soundness of the New Zealand financial system.
  • that vanilla household debt has very rarely been at the heart of serious financial system problems in this or other countries  –  the Reserve Bank drew our attention to that in an article only a couple of years ago. Lending on speculative commercial (and residential) developments, and other (typically unsecured) business lending, has usually been the presenting source of financial system problems.

But I’m also puzzled by two points about the Westpac piece –  one presence, and one absence.

Westpac talks of high house prices boosting consumption.

household C to GDP

But household consumption as a share of GDP is currently just slightly below the average ratio for the last 30 years or so.  This shouldn’t be very surprising –  higher house prices don’t make New Zealanders as a whole any better off.  A longer discussion of this issue is contained in this Reserve Bank Bulletin article from a few years ago.

The “absence” is any sense that changes in household debt to GDP (or income) ratios are not mostly some exogenous phenomenon of reckless banks and households taking on new debt with gay abandon.  I discussed this issue a couple of weeks ago.  If there are shocks to the population, and land supply restrictions exist, then house prices will rise.  New purchasers will typically (and probably rather reluctantly) need to take on more debt than their predecessors did.  As a result, debt to income ratios will rise. Since the housing stock turns over only quite slowly, an initial shock boosting house prices will go on boosting debt to income ratios for many years.

In the chart below I’ve done a very simple exercise.  I’ve assumed that at the start of the exercise, housing debt is 50 per cent of income, house prices and incomes are flat, and people repay mortgages evenly over 25 years.  Only a minority of houses is traded each year, but each year the new purchasers take on new debt just enough to balance the repayments across the entire mortgage book.

And then a shock happens –  call it tighter land use regulation –  the impact of which is instantly recognized, and house prices double as a result.  Following that shock, house purchasers also double the amount of debt they take on with each purchase, while the (now rising) stock of debt continues to be repaid in equal installments over 25 years.

In this scenario remember, house prices rose only in year 1.  There is no subsequent increase in house prices or incomes.  But this is what happens to the debt to income ratio:

debt to income scenario

In this particular scenario, 100 years after the initial doubling in house prices, the debt to income ratio is still rising, solely as a result of the initial shock, converging (ever so slowly by then) to the new steady-state level of 1.  One could play around with the parameters, but a permanently higher level of real house prices will, in almost any of them, produce a permanently higher level of gross housing debt, and it will take many years to get to that new level.  The flipside, which I could also show, is the deposit balances of the other parts of the household sectors – the young who have to save for a higher deposit (even for a constant LVR) and the older cohorts who extract more money from the housing market when they downsize or exit the market.  Higher house prices do not, of themselves, require banks to raise more funding offshore.

This is deliberately highly-stylized, but it is designed to illustrate just two main points: higher debt ratios can be primarily a symptom of higher house prices (rather than any sort of cause) and the adjustment upwards in debt levels following an upward house price movement can take many years to work through.

Given the huge population pressures, especially in Auckland, and the lack of much material progress in easing land use constraints, it is hardly surprising that real house prices have increased quite a lot further in some places. If anything, it might be a little surprising that debt to income ratios have not increased more. But these things take time – the point of the chart above.

Westpac has long been of the view that low interest rates have been a major factor explaining rising house prices.  I’ve never found that story particularly persuasive.  We’ve had a 600 point cut in the nominal OCR since 2008 (and a bit more in real terms).  If all else was equal and the Reserve Bank had not cut the OCR as much no doubt house prices would be lower (and quite a lot of other aspects of the economy would be doing even less well).  But the OCR cuts have been done for a reason: the economy hasn’t been performing that well, and inflation has persistently surprised on the downside. In Wicksellian terms, it looks a lot as though the natural interest rate has fallen quite a bit.  Westpac worries about what happens when (if) interest rates rise, but they are only likely to rise much if the economy is performing much better, and is generating much stronger income growth (which would support the existing debt).

There is a still a strong sense around that, when it comes to housing, what goes up must come down.  But when a market is so heavily influenced by regulatory factors, there is no such natural adjustment.  As a loose parallel, we have plenty of people who find it hard to get a job, but the minimum wage keeps on being increased.  Urban residential property prices, especially in Auckland, are a disgrace –  the responsibility of the choices (active and passive) of a succession of central (and local) government politicians. They are hard to defend under any conception of justice or fairness. But there is little sign that they are any sort of macroeconomic risk.  Debt to income is little higher than it was a decade ago, consumption to GDP has not gone crazy, there is nothing of the sort of debt fuelled speculative construction boom seen in, say, Ireland, and there is no sign of reckless behaviour by lenders.  And the banks are very well-capitalized.  It is awful for the many adversely affected, but there is no reason why things should necessarily change much for the better any time soon,

Finally, one of the points of the Westpac note seemed to be to foreshadow the risk of new layers of regulatory controls (so-called “macro-prudential” measures) being imposed on the banking system by the Reserve Bank.  Perhaps they are right about what might be coming. But there would be no good (financial system soundness) basis for further intrusions on the ability of borrowers and lenders to freely arrange finance.    There is simply no evidence that the soundness of the financial system is at risk –  or would be even if, say, the population pressures reversed and land use restrictions were freed up.  Then again, the last two sets of LVR restrictions, undermining the efficiency of the financial system and the wider economy in the process were unwarranted, but that didn’t stop the Reserve Bank charging ahead then.