The Governor states his medium-term plans

The Reserve Bank published its annual Statement of Intent on Friday.  I hesitated to write about the document, because to write about it I have to read it.   I always avoided doing so when I worked at the Bank.

The requirement to publish an SOI was added to the Act about 10 years ago.  And dry as they typically are, the SOIs were presumably intended by Parliament to help us understand what the Governor plans that the Bank will be doing over the next few years, and to help us –  and the Board and Parliament – hold the Governor to account.    It should give us a sense of where he sees the bigger looming issues.

Here is what the Act says:

162A Obligation to provide statement of intent

162B Content of statement of intent

162C Process for providing statement of intent to Minister

There is a reasonable amount of material in the document, and tempting as it is to comment on “the Bank’s aspirational goal of being the Best Small Central Bank” (the first time I’ve noticed this in a public document) I’ll save that for another day.  Instead, I want to look at what the Governor does, and apparently does not, see as the priorities for the Bank in the next few years,  in the three broad areas of the Bank’s main statutory responsibilities:

  • Currency
  • Monetary policy
  • Banking supervision

Currency

Two of the Bank’s 10 strategic priorities relate to physical currency

  1. Delivering New Zealand’s new banknotes

The release of Series 7 banknotes (Brighter Money) is scheduled for

the end of 2015 and in 2016. A successful release will require continued

extensive interaction with the Canadian Banknote Company, and

increased engagement with the public, the financial services industry,

and other key stakeholders.

  1. Developing a plan for future custody and

distribution arrangements for currency

The Bank will review its currency operating model and supporting

infrastructure to ensure that the currency needs of New Zealanders will

be met in the future. The review will assess the current operating model,

and identify options for the custody and distribution of currency. The

Bank will consult and collaborate with key stakeholders during 2015-

16 to ensure that the review’s recommendations are understood and

supported.

Those look fine as far as they go, even if the first now seems more operational than strategic.  But neither in this list, nor in the “functional initiatives” section, is there any sense of the significance of the zero lower bound, and the role that central bank physical currency monopolies play in exacerbating periods of economic weakness when policy interest rates get to (just below) zero.  New Zealand has been fortunate not yet to have the zero lower bound (ZLB) issue, but with a policy rate at 3.25 per cent and which is widely expected to fall quite a bit further it is not that far away.  We went into the last downturn with policy rates of 8.25 per cent.

Issues around the central bank physical currency monopoly, and whether (for example) retail electronic outside money might help alleviate the ZLB problems cannot be dealt with or resolved overnight.  But that is why it is so disappointing that nowhere in this medium-term document is there any sense that the Bank is taking the issue, and associated risks, seriously.  It looks as though they will be quite content to just run the risk that one day we get to an OCR of zero, unbothered that nothing was done to get ready for (and mitigate the risk of) that day. For countries that got to zero in 2008/09 it was a pardonable surprise perhaps, but the rest of the advanced world has now put us on notice.  This was a chance to be pro-active, and mitigate future risks, but the Governor does not seem interested in even commissioning work to look in more depth at the issues and options.   There aren’t straightforward “right or wrong” solutions, but the issues and options need serious analytical work now.

Monetary policy 

Not one of the Reserve Bank’s strategic priorities for the next few years relates to monetary policy, which remains (by statute) the Bank’s primary function.  This is so despite:

  • several years in which inflation has consistently undershot the targets agreed between Ministers of Finance and successive Governors
  • the salience of the zero lower bound issues to the ability of monetary policy to adequately deal with possible future serious shocks.  In view of the Governor’s worries about the potential threats to financial stability, it is all the more surprising that nothing major appears to be on the work programme to deal with these issues.
  • A new Policy Targets Agreement is due in just over two years (so inside the period covered by this SOI.

I have some sympathy with the argument that normal year-to-year issues in monetary policy don’t easily fit a “strategic priorities” framework, so perhaps the persistent forecast errors (and associated monetary policy mistakes) might not be expected to appear, even though they are now quite persistent, and have come at quite some cost to the unemployed.

But the ZLB issues certainly aren’t just routine issues.  They have represented a major constraint on the ability of central banks in other countries to do the sort of macroeconomic stabilisation expected of them.  Should we be doing something about removing the technical ZLB constraint?  If not, should we thinking harder about raising the inflation target midpoint?  What are the costs and benefits of the various options, and what might the implications be for other areas of policy (eg the tax system).

But the “functional initiatives” list offers nothing either. Here is what it says:

The Bank’s Economics Department has four key work streams for 2015.

  1. Macroprudential and monetary policy interface: undertake analysis and develop frameworks to better understand the interaction between macroprudential and monetary policy.
  1. Support the formulation of monetary policy: understand how events such as a construction and housing boom, fiscal consolidation, and international developments will shape the next business cycle.
  1. Monetary policy research: undertake analysis to improve the Bank’s understanding of the New Zealand economy and key monetary policy issues.
  1. Exchange rate analysis: reviewing the Bank’s frameworks for assessing the long-term sustainable level of the exchange rate and analysis of the cyclical impact of the exchange rate on New Zealand economic activity and inflation.

Nothing particularly objectionable there, perhaps, but nothing that seriously engages with the sorts of issues I listed above either.

Banking supervision

The Bank has three strategic priorities related to banking supervision:


  1. Exploring macro-prudential policy options to manage the financial stability implications of housing cycles

The Bank will explore macro-prudential policy options for managing the financial stability implications of housing market cycles. It will continue to investigate the interactions between monetary policy, prudential policy and the objectives of price and financial stability. The Macro-Financial department will lead work through the Macro-Financial Committee and

Governing Committee, with support from the Economics and Prudential Supervision departments.


  1. Updating the prudential policy and supervision frameworks.

The Bank will implement changes arising from the regulatory stocktake and will review other key policy settings. These will include outsourcing requirements on banks, and capital and liquidity settings in light of the revised Basel standards.


  1. Developing a comprehensive stress-testing framework for the New Zealand banking system

The Macro-Financial and Prudential Supervision departments are developing a comprehensive stress-testing framework to gauge the resilience of the banking system to adverse shocks. The Reserve Bank will work with the banks to identify and implement improvements to the banks’ technical stress-testing frameworks and processes. In addition,

the Bank will ensure that stress tests become a centerpiece of banks’ internal risk management, and are regularly scrutinised by senior management and boards.

One might question just how “strategic” 5 and 6 are – presumably here the Governor just means “we will put a lot of time into”?  I noticed that the Governor says he will “ensure that stress tests become a centrepiece of banks’ internal risk management”.   But banks might reasonably ask the same of the Reserve Bank.  The Bank is currently trying to further restrict banks’ business operations, even though the latest stress test results suggest there is no threat to the health of individual banks, or to that of the financial system as a whole.

There is also a long list of “Initiatives and strategies” in this area:

Initiatives and strategies

To address these issues, the Bank will:

  • explore additional macro-prudential policy options for managing the financial stability implications of housing market cycles;
  • work with the banks to ensure that stress-testing models and processes are robust and a core centrepiece of the banks’ internal risk management

continue to assess the linkages between monetary and macroprudential policy to ensure that complementary or opposing effects between the two policy areas are properly taken into account;

  • continue to enhance the reporting of financial system stability and efficiency, and policy assessments, contained in the FSR and other reports;
  • publish a stress-testing guide with a view to improving the stresstesting practices of New Zealand banks, and continue to develop a comprehensive stress-testing framework for New Zealand banks, a joint initiative with the Macro-Financial department;
  • complete the regulatory stocktake by consulting on and implementing initial enhancements to improve the efficiency, clarity and targeting of prudential standards for banks and NBDTs, and identifying separate areas for further work;
  • maintain supervisory engagement with executives and directors of regulated banks;
  • complete a review of, and consult on, the outsourcing arrangements that currently apply to ‘large banks’;
  • work closely with banks to ensure timely compliance with new outsourcing requirements;
  • review the Bank’s existing liquidity policy against finalised international liquidity standards;
  • review the Bank’s broad suite of capital requirements;
  • consult on a range of amendments to the statutory management powers in the Reserve Bank of New Zealand Act 1989 to clarify aspects of the legislative framework for the Open Bank Resolution policy;
  • promote legislative changes recommended by the review of the prudential regime for NBDTs that was completed in 2013;
  • finalise policy to strengthen the Bank’s oversight of financial market infrastructures; and
  • implement the business-as-usual supervisory framework for licensed insurers.

Again, what is there is not objectionable, but I think some questions should be asked about what is not there.    For example:

  • There is no sign of any proposed rigorous (let alone independent) ex-post evaluation of the Bank’s LVR regulations, even though they have been a major innovation in New Zealand policy.
  • There is no sign of any particular work on the efficiency of the financial system, even though any (arguable) soundness benefits from measures like the actual and proposed LVR controls come with undoubted efficiency costs.
  • There is no sign of any initiatives to lift either the quantity of quality of the Bank’s research and policy analysis in prudential regulatory and financial stability areas.  For example, there is no sign of any work programme on how to best interpret the lessons of other countries which have, and have not, experienced financial crises in the last decade or so.

More generally, there is no sign of an organisation that recognises the importance of, and wants to foster,  the robust contest of ideas, internally and externally.

In a sense, none of this should be very surprising.  As I have been highlighting, too many of the Reserve Bank’s powers (ie all of them) rest with the Governor alone.  But the draft of this SOI will have been seen by the Minister, and it might be interesting to ask the Bank or the Minister for a copy of any comments the Minister provided. Probably a draft went to the Reserve Bank’s own Board –  but the Board exists to review the Governor’s performance after the event, not to set strategic priorities, approve functional initiatives, or even set Budgets.   The SOI is a reflection of the single decision-maker’s preferences and priorities –  a model which has both strengths, and some significant weaknesses and risks

There is no suggestion of any further work on possible improvements in, or changes to, the statutory governance of the Bank.  I have just lodged an OIA request with the Bank asking for copies of any work done in this area over the last couple of years.  Of course, decisions on governance and statutory changes are a matter ultimately for the Minister and Parliament, but in his early months the Governor did appear to recognise some weaknesses in the current model, prompting him to establish the Governing Committtee (him, and the three deputy/assistant governors), as a forum in which the Governor would make major decisions, to help mitigate some of the internal risks in the current statutory system.

The Reserve Bank’s Statement of Intent stands referred to Parliament.  It might be interesting for the Finance and Expenditure Committee to ask the Governor about the some of the issues raised here.  Other departments have an estimates hearing before their funding is appropriated.  There is nothing similar for the Bank’s five year funding, but the SOI does provide a basis for some scrutiny and challenge.
The Reserve Bank’s releases on proposed investor finance controls

I noted yesterday that the Reserve Bank had also released some papers on the proposed new LVR restrictions on Thursday.  When that release was pointed out to me yesterday, the Bank’s website suggested that the papers had been released in response to an OIA request.  The papers still appear in the obscure corner of the Bank’s website where (in a welcome development) they have started publishing some of the responses they make to OIA requests.

But when I checked again this morning, the table now says of the latest release:

Date of Response Subject matter
25 June 2015 Loan-to-value ratio (LVR) restrictions, proactively released, jointly with the Treasury

Go through to the detailed page, and it suggests that the release is partly pro-active and partly a response to an OIA request.

This is information relating to loan-to-value ratio (LVR) restrictions that has been released proactively and in response to requests for information under the Official Information Act 1982 (the Act).

I’m a little confused.  But if there genuinely is a pro-active component to the Bank’s release then I welcome it, even if (say) they may just have released one additional paper to provide context for a few that were covered by the OIA.

It still leaves a little bit of a puzzle about the Treasury’s (entirely pro-active) choice to release.  Sometimes documents requested of one organisation cross-reference material generated in other organisations, but that does not appear to be the case here.  Perhaps the OIA request to the Reserve Bank included material the Bank held, even if it did not generate it.  If so, no doubt the Bank held copies of at least some of the Treasury papers?    But having been on the receiving end of numerous OIA extensions from the Bank (and recently one from Treasury), when documents written little more than 20 working days ago are pro-actively released, it has the feel of a genuinely deliberate timing choice.

But enough of the bureaucratic process stuff.  What I had intended to write about was the content of the Bank documents.  They released six, one of which (the 17 Feb one) I had previously seen.

Date Released on 25 June 2015
19/5/2015 Memo to Minister on draft consultation paper on LVR policy (PDF 818KB)
30/4/2015 Memo to Minister on estimated impact of changes to LVR policy (PDF 1.36MB)
24/4/2015 Memo to Minister on potential adjustments to LVR ratio policy (PDF 2.67MB)
21/4/2015 Memo to MFC on Proposed changes to the LVR policy (PDF 350KB)
2/4/2015 Memo to MFC on revisiting the case for regional targeting of marco-prudential policy (PDF 134KB)
17/2/2015 Memo to MFC on effectiveness of a tighter investor LVR limit (PDF 99KB)

We don’t have much context for this release.  In particular, we don’t know the scope of any OIA request the Bank may have been responding to, but if these papers are intended to reflect the analysis the Bank undertook in developing the proposed control on investor lending (and the Auckland-specific nature of the new policy), they are surprisingly short and weak.  Recall that the Bank is,  implicitly, saying the banks and borrowers are so risky and irresponsible that not one single (practical) cent can safely be lent by banks to Auckland residential property investors on LVRs over 70 per cent without jeopardising the soundness of the financial system.  That is a pretty ambitious claim.  It is not supported.

I have been critical of the Bank for not making a stronger case for its proposed controls.  The one comfort I suppose that we can take from these papers is that they are not hiding anything from us.  But if this is all there is – the extent of their engagement with the law, the economics, the stress tests, the uncertainty –  it is even less surprising that The Treasury was also not convinced that a compelling case had been made for the new controls.  Unfortunately, the Reserve Bank also continues to repeat to the Minister of Finance its claims that lending to investors is generally materially riskier than other housing lending.  An attendee at the LEANZ seminar the other night told the audience that he had gone through all the references the Bank has previously invoked in support of its claim, and had found that they simply did not say what the Bank claimed they were saying.  If that assessment is correct, it is pretty concerning, and should be so to the Board and the Minister –  charged with holding the Governor to account on our behalf.

A process issue struck me in reading the papers.  In discussing the possible new policy, the 21 April paper lists a possible timeline.  It suggests that a consultation period should end in “late June” and “Release final policy position and revised conditions of registration” in “mid-July”.  Allowing perhaps 10 working days to read, analyse, and reflect on submissions, write up recommendations to the Governor, write-up a response to submissions, and finalise the new conditions of registration themselves does not suggest that the Bank had in mind a very open process of consultation.  Actual timing slipped somewhat, as the consultative document was not released until early June, but we should hope that they take a little more than 10 working days to work through all the issues likely to be raised in submissions.

As I noted yesterday, the cause of serious scrutiny of the Governor’s proposals (and of open government more generally) would be advanced if the Bank were to publish on its website, as they are received or at least on the closing date, all the submissions they receive.  They are, after all, public, official, information.

Earthquakes, lives saved, and the OIA

I’ve posted a couple of times (here and here) on a “blunder of our government”; the plans and legislation to impose earthquake-strengthening requirements on many building owners, with seemingly little regard for any sort of robust cost-benefit analysis.  A sense, following the Canterbury earthquakes, that “something must be done”, plus perhaps some lobbying from vested interests, is the only way I can account for even the latest modified proposals.

This isn’t really my area, but I have great deal of time for my former RB colleague Ian Harrison who has led a lot of the thinking critiquing the government’s proposals.    EBSS (“working towards a rational seismic strengthening policy”) has been trying to use the Official Information Act to better understand the analysis and reasoning behind the government’s proposals, and its claims regarding the costs and benefits.    Their website is worth keeping an eye on from time to time, and they have a new post up about their latest request to MBIE.   I suspect they won’t mind if I reproduce it here.

The classic schoolboy excuse for failing to hand in homework looks credible compared to the excuse that MBIE has made for not provided us with documents requested under the Official Information Act.

In our analysis (the Minister’s new clothes) of the new seismic strengthening policies announced in The Building Minister’s speech in May we pointed out some ‘schoolboy’ errors  and suggested that there might be more.

The Minister said that the policies would save 330 lives over the next 100 years, but when MBIE last did the analysis in 2012 only 24 lives would be saved. We were also told that the whole strengthening exercise would cost only $770 million when the Tailrisk Economics analysis suggests that the true cost could be 10 times that amount.  The differences are critical to an understanding of the merits of the new policy.

To get to the bottom of the evidence on balance of the costs and benefits we asked for the following documents:

All documents relating to the following information presented in the Minister of Building and Housing’s speech on 10 May 2015 on the Government’s new seismic strengthening policies

(a)

  • The estimate of lives saved by the policy
  • The cost of the policy
  • The difference in risk between buildings near the 34% threshold and those with lower %NBS
  • The relative risk of dying in a car accident compared to dying in an earthquake

(b)   All documents relating to seismic strengthening policy for the period 1 April 2014  to 9 May 2015

Our requests were refused (past the statutory deadline for making information available) under section 18(c)(ii) of the Act, “as the making available of the information requested would constitute contempt of Court or the House of Representatives.” The rationale was that the Earthquake Prone Building Amendment Bill is currently before the Select Committee and that “all of the Committees’ ‘other proceedings’, including advice MBIE has provided to the Committee, are strictly confidential to the Committee”.

What MBIE seems to be saying here is that every document relating to seismic strengthening that has been produced by MBIE over more than a year have been provided to the Select Committee.

MBIE’s apparent claim is not plausible.   While MBIE might be entitled to withhold the advice they have specifically provided to the Select Committee there is no justification for a blanket refusal to provide the requested documents.

We suspect that what is really going on is that the Minister really hasn’t done his homework on the costs and benefits of his new policies and that MBIE is trying to cover it up.  On the 330 deaths there must be a strong suspicion that there has been a blunder or the evidence was engineered..

The material under (a) in particular seems like the sort of stuff that, in a genuinely open government, would have been pro-actively released a long time ago

The Treasury on the new proposed LVR limits

UPDATE: There was also a release yesterday of some Reserve Bank papers on these issues.  The Reserve Bank papers are described as being released in response to OIA requests.  The Treasury papers were pro-actively released, but apparently in coordination with this Reserve Bank release.  I have not yet read the RB papers.

I got home late last night and missed the significance of Stuff’s story about the newly-released Treasury papers on the Reserve Bank’s proposed new LVR controls.

But reading the package of material that The Treasury released, it does not paint a particularly pretty picture.

First, it is interesting that Treasury has pro-actively released this material, about the proposed investor restriction that the Reserve Bank is currently consulting on.  It was not extracted from them reluctantly by a citizen’s Official Information Act request.  One assumes that they released the material with at least the acquiescence of the Minister of Finance.   I’m all for transparency, but this release suggests something quite uncomfortable about relationships between the Reserve Bank, Treasury, and the Minister –  something already hinted at in the Minister’s comments on a couple of occasions about the Bank’s handling of monetary policy.

I don’t agree with everything in the Treasury papers –  for example, invoking the results of a DSGE model as a basis for advice on the timing of a relaxation of LVR limits is not particularly persuasive.   But the bottom line seems to be that Treasury, the government’s chief economic policy advisers, are also not convinced that the case has been made for the proposed new investor controls.

For the moment, as they note, decision rights on these matters rest exclusively with the Governor, but if the Governor can’t make his consultative paper convincing to The Treasury  –  who are by no means as sceptical of the general case for active regulatory interventions in this area as I might be  –  it should be a little concerning to the rest of us.

Here is what Treasury had to say on the substance a month ago in their aide memoire to the Minister on the Bank’s consultative document:

Overall, we do not think that the consultation document makes a compelling case for the proposed use of these macroprudential settings, due to the concerns below. Nevertheless, the RBNZ does have the decision rights, and so our focus will be to work with the RBNZ to make improvements in some key areas. Our main focus will be to encourage:

  • Clarification of the problem identification, evidence and channels. We accept that house price changes can have macroeconomic implications, but the RBNZ’s mandate is to promote financial stability. Therefore, the policy should be reframed to focus more clearly on reducing systemic risk, rather than on prices in a particular market.
  • Additional evidence on the investor segment. The evidence presented is somewhat mixed on the extent that high-LVR investors underpin systemic fragility, as they are a relatively small part of the market and many may be able to alter their portfolio. Similarly, we will be asking the RBNZ to provide further information on the extent to which the increase in investor activity may have been encouraged by the original LVR policy.
  • Discussion on the risks of relaxation of the speed limit outside of Auckland should credit growth and prices pick up again. Although we appreciate that the policy was designed to be temporary, and that the RBNZ prefer light touch regulation, there are a number of potential downsides. In this case, the policy rule is not clear, and the RBNZ policy settings are reactive to recent data. This may lead to an active management of policy settings, which may increase market uncertainty and reduce RBNZ credibility. This is particularly important around LVR limits – Treasury modelling using a DSGE framework suggests that the costs of taking the limits off early may be greater than leaving them in place for longer.
  • Evidence from policy evaluation and additional cost benefit analysis of this policy to be published, including with respect to the other options available. The consultation paper contains little discussion on some of the possible unintended consequences, such as: increased risk of disintermediation or higher non-bank lending; the possibility of shifting demand towards cashed-up buyers; or risks that investors leverage up property outside of Auckland. We will also be asking the RBNZ for more detailed evaluation on the impact of the existing LVR policy, and of the unintended consequences compared with the impacts anticipated in the Regulatory Impact Statement.

The points expressed about process are also a bit disconcerting:

Process

A robust process of consultation is a characteristic of good regulatory practice and should occur within government at the options stage well before the policy is made public.

The late notice and lack of consultation complicates the ability of government agencies to coordinate, which could lead to government policy that conflicts or pays inadequate attention to government’s wider economic objectives.

We will raise these issues with RBNZ and propose process changes to address these concerns.

As I noted in my address last night, under the current Reserve Bank Act model the Governor comes close to being prosecutor, judge, and jury in his own case.  That is a dangerous feature.  Managing the risk makes it all the more important that the Bank goes out of its way to engage pro-actively with the Minister and with Treasury when it is proposing new regulatory measures.  Consultation matters for a whole variety of reasons, but Treasury’s views and questions can, among other things, offer one arms-length test of just how persuasive the Bank’s arguments are.

A more pro-active release policy from the Bank would also be welcome.  Perhaps, for example, the Reserve Bank could consider posting all submissions on the current consultative document on the Reserve Bank website, as and when they are received.  These proposals need all the scrutiny and debate they can get.

Housing, financial stresses, and the regulatory role of the Reserve Bank

Last night I spoke to the Wellington branch of LEANZ on “Housing, financial stresses, and the regulatory role of the Reserve Bank”. They had a good turnout and some stimulating discussion ensued.

The text of my address is here

Housing, financial stresses, and the regulatory role of the Reserve Bank LEANZ seminar 25 June 2015

The presentation was organised in three parts:
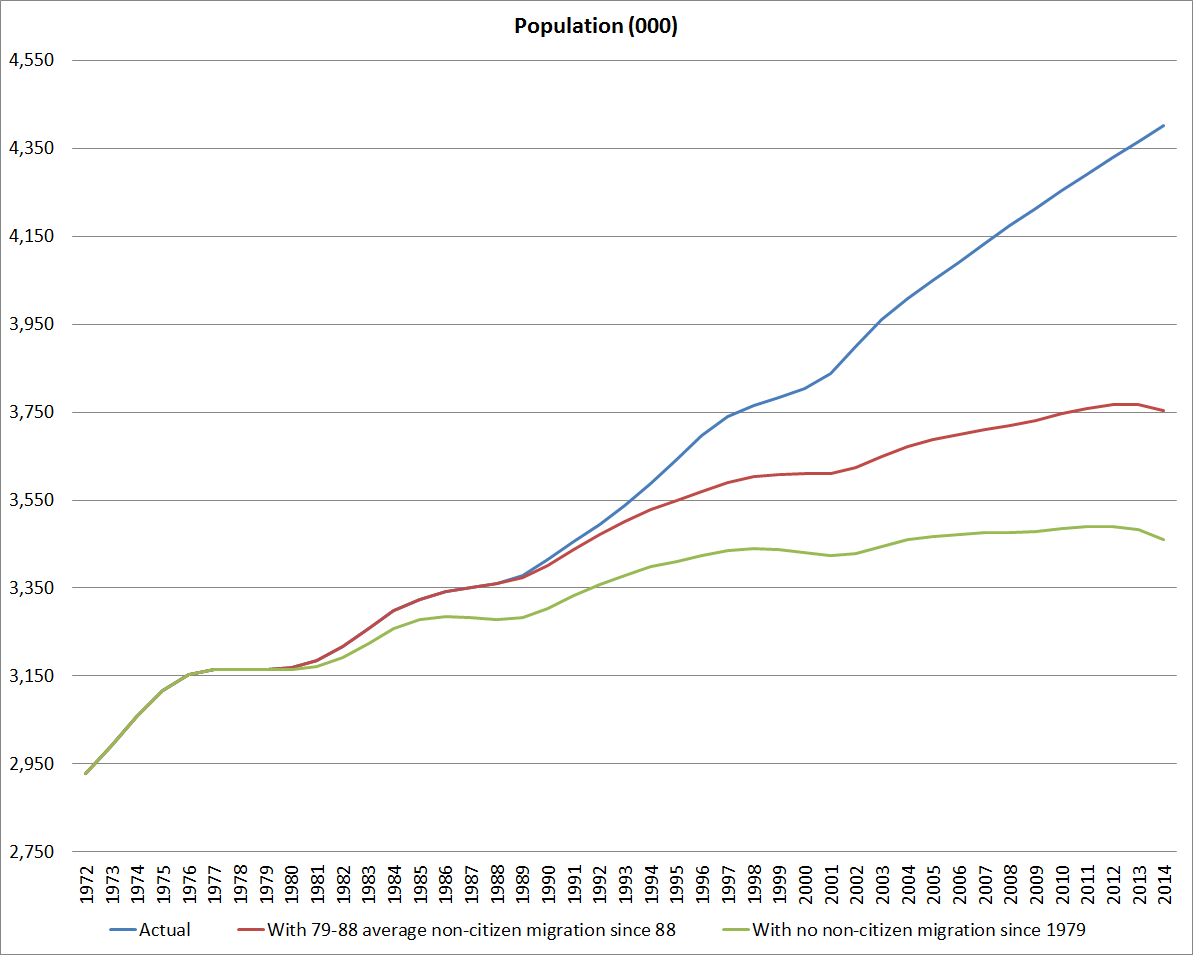
• Making the case that high house (and land) prices in Auckland are largely a predictable outcome of the interaction of supply restrictions and high target levels of non-citizen immigration. With, say, 1980s levels of non-citizen immigration, New Zealand’s population would be flat or falling slightly. Much of that ground will be familiar to regular readers of this blog.   It matters because what has raised house prices in New Zealand is very different from what raised them in the crisis countries. In the United States, government policy initiatives systematically drove lending standards downwards in the decade prior to the crash, and in Ireland and Spain, imposing a German interest rate on economies that probably needed something more like a New Zealand interest rate systematically distorted credit conditions across whole economies. New Zealand – and other countries with floating exchange rates and private sector housing finance markets – had no such problems.  Credit was needed to support higher house prices in other advanced economy, but it was not the driving force behind the boom.

If I am right that the New Zealand house price issues result from the interaction of our planning regime and our immigration policy, then these are structural policy choices that systematically overprice houses, largely independently of the banking and financial system.  They are not ephemeral pressures –  here today and gone tomorrow.  They have been building for decades.  I hope they are reversed one day, but there is no market pressures that will compel them to (any more than there are market pressures that compel the reversal of planning restrictions in Sydney, London, or San Francisco).  These distortions are not making credit available too easily and too cheaply right across the economy  (which is the single big difference between NZ or Australia, and say the Irish, US or Spanish situations).  They are simply making houses less affordable.   The Reserve Bank has no better information than you, I, or the young buyers in Auckland do, on whether and when those policy distortions will ever be reversed.   And even if the policy distortions were corrected, it is pretty clear that real excess capacity (too many houses, too many commercial buildings) is a much bigger threat than simply an adjustment in the price of banking collateral.   No one thinks Auckland has too many houses, or too much developed land.

• The core of the paper was the proposition that the Reserve Bank’s actual and proposed LVR restrictions appear both unwarranted by, and inconsistent with, the Reserve Bank’s statutory mandate to promote the soundness and efficiency of the system. In subsequent discussion, a very senior lawyer went so far as to suggest that the Bank might even be acting ultra vires. My arguments around the LVR policies had a number of dimensions including:
o The almost total absence of any sustained comparative analysis of the international experience of the last decades, including the issue of why some countries (Spain, Ireland, and the United States) had very nasty financial crises and housing busts, and others (New Zealand, Australia, the UK, and Canada) did not.
o The lack of any engagement with New Zealand’s own experience in the last decade. Risks appeared much greater in 2007 than they are now, and yet the banking system came through a severe recession, and sluggish recovery, unscathed.
o The lack of willingness to engage openly with the results of the one piece of sustained work the Bank has done, the 2014 stress tests, which suggested that the New Zealand banking system, on the current composition of their asset portfolios, could relatively easily withstand even a very severe shock.
o The failure to address the efficiency dimension of the Bank’s statutory responsibility. Both the actual and proposed LVR controls will impair the efficiency of the financial system.
o The failure to identify and address the distributional implications of the controls.
o The failure to grapple with the limitations of the Bank’s (and everyone else’s) knowledge. There might be an arguable case for controls if we could be sure a crash was coming 12 months hence, but in fact the Bank has no better information than you or I do as to when, or if, there will be a substantial fall in nominal house prices.

• Discussion of the regulatory powers of the Bank, and its governance. As I put it in the conclusion:

These concerns bring into focus the weaknesses that have become increasingly apparent in the Reserve Bank Act. That Act was a considerable step forward in 1989, at a time when only a modest and limited role was envisaged for the Reserve Bank. But it is now 2015, and the legislation is not consistent with the sorts of discretionary policy activities the Bank is now undertaking, with modern expectations for governance in the New Zealand public sector, or with how these things are done in other similar countries. Doing some serious work on changing the single decision-maker model would be an excellent place to start, but it is only a start. A much more extensive rethink and rewrite of the Act, and the Bank’s powers, is needed to put in place a much more conventional model of governance and accountability, especially in these regulatory areas.

Trade agreements, TPP, and the Australian Productivity Commission

I’m on a tight deadline today and wasn’t going to write anything here, but a reader pointed me in the direction of the Australian Productivity Commission’s newly-published Trade and Assistance Review 2013-14, which devotes an entire chapter to “Issues and concerns with preferential trade agreements” (pages 61-86 here).

As the Sydney Morning Herald summarised it:

The Productivity Commission has launched a scathing attack on Australia’s latest series of free trade agreements, saying they grant legal rights to foreign investors not available to Australians, expose the government to potentially large unfunded liabilities and add extra costs on businesses attempting to comply with them.

Allowing for the relative restraint of bureaucratic language on the one hand, and newspaper style on the other, “scathing attack” doesn’t seem like an unfair description.  Perhaps as importantly, the report raises serious questions about TPP, (although the APC has not seen the documents being negotiated).

As regards rules of origin (whether for goods or services) the APC makes their points about cost and complexity by simply relentlessly listing the different rules of origin in the various Australian FTAs for the item “Bed linen, table linen, toilet linen and kitchen linen”.  They report estimates that “the cost associated with origin requirements could be as high as 25 per cent of the value of goods trade with ASEAN”.  By contrast, unilateral abolition of domestic tariffs, or comprehensive multilateral agreements avoids these costs.  The APC makes quite a lot of the point that time, and political capital, spent negotiating FTAs may be, in part, at the expense of unilateral liberalisation of international trade and domestic competition-enhancing reforms.

The APC report also devotes considerable space to investor-state dispute settlement (ISDS) provisions.  They seem very sceptical of the case for these provisions (and note that 40 per cent of those launched last year were taken against developed countries – presumably countries with robust domestic legal systems).  As they note, signing up to ISDS provisions involves new, unfunded, contingent liabilities for governments while, in their view, there is no sign that the ISDS provisions Australia has already signed have done anything to increase either inward or outward Australian foreign investment.  They also note that the Chief Justice of the High Court of Australia has publicly expressed concern about the risk that ISDS provisions could undermine the authority of domestic courts.

Finally, the APC notes the difficulty of assessing the potential impacts of trade agreements.  They argue that this makes a ‘compelling case for the negotiated text of an agreement to be comprehensively analysed before signing”.  At least in Australia, actual analysis and evaluation appears to have fallen far short of this standard.

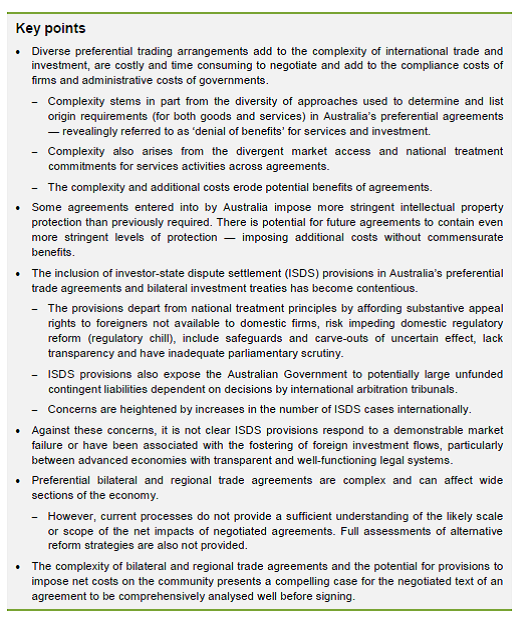
Trade agreements aren’t going to be a much of a theme on this blog, but I found it interesting that as orthodox and pro-market body as the APC felt it appropriate to reiterate its scepticism on FTAs in this way.    Here are the key points from the APC document.

apc

For New Zealand, there still seem to be some important questions to be answered around TPP, and before it reaches a point where a government majority simply votes a signed agreement through the House.   There is no sign yet of material dairy trade liberalisation, intellectual property protections are likely to make us worse off (and perhaps also the ordinary citizens of other countries, even those who host large intellectual property owners), while further ISDS provisions, for which there is no identified market failure, seem set to strengthen the hand of foreign investors relative to domestic ones, undermining the primacy of our own Parliament and courts, for no obvious gain.   I am also uneasy about the provisions that get inserted in these agreements to limit the ability of countries to respond to economic and financial crises.  I was involved in work on these while I was at the Reserve Bank, and again it is not obvious what the problems are with existing multilateral provisions (IMF and WTO).

I remain uneasy that New Zealand might end up signing an agreement primarily because of the momentum in the process, and the desire of our own elites not to self-exclude from “the club”, rather than because there are demonstrable gains to the national welfare of New Zealanders.  If so, it would be cause for concern.  I wonder what sort of robust economic evaluation is envisaged here before MPs are asked to vote on any agreement?

Real economic costs of financial crises – part 1

A couple of days ago I looked at how one might best classify countries, as to whether or not they had experienced a “financial crisis” since 2007.  But this chart is one reason why I’ve become increasingly sceptical that “financial crises”, however one defines them, have large or enduring adverse real economic effects.  I think I first saw it in a sets of slides by Nobel laureate Robert Lucas, and every so often I would use it to try to stir up a bit of debate at the Reserve Bank.

maddisonUS

It is a quite simple chart of real per capita GDP for the United States, back as far as 1870.  These are Angus Maddison’s estimates, the most widely used set of (estimated) historical data, and as Maddison died a few years ago they only come as far forward as 2008.  The simple observation is that a linear trend drawn through this series captures almost all of what is going on.  More than perhaps any other country for which there are reasonable estimates, the United States has managed pretty steady long-term average growth rates over almost 140 years.  And yet, this was a country that experienced numerous financial crises in the first half the period.  Lists differ a little, but a reasonable list for the US would show crises in 1873, 1884, 1893, 1896, 1901, 1907, perhaps 1914, and 1929-33.  There were far more crises than any other advanced countries experienced.

And yet, there is no sign that they permanently impaired growth, or income.  One never knows the counterfactual, but right through this period the US kept on towards establishing the dominant position it was to hold in the decades after World War Two.  Even the Great Depression, awful as it was (costly as it was to many people) does not look to have had permanent adverse effects.  Another source I’ve bored people with over the past few years is Alexander Field’s excellent relatively recent book on US economic growth, productivity, and the Great Depression, A Great Leap Forward.  Field reports the best estimates for TFP growth in the US over the last century, and growth was faster from 1929 to 1941 than in any of the other periods he presents.  One might quibble about when to start and end these sub-periods, but 1929 was before the downturn became well-established, and 1941 is around when GDP per capita got back to pre-crisis trend (before temporarily going well above it in World War Two).

fieldtfp

The United States in the Great Depression had almost all the factors that are often cited to explain why financial crises might have permanent or very long-lasting adverse effects:

  • Lots of bank failures, and in a system without nationwide banks, disrupting the intermediation process.
  • Lots of corporate failures
  • Big changes in the price level (steep deflation)
  • Huge regulatory uncertainty (including around the robustness of the judicial system –  see, eg Roosevelt’s attempt to stack the Supreme Court)
  • Significant fiscal costs (in this case, not bank bailouts, but the defaults by other Western countries on the huge US World War One loans).

And yet the underlying rate of innovation is estimated to have gone on just as strongly as before.

This is not, remotely, to trivialise the Great Depression.  But it still looks a lot more like an event that became as severe as it was because of inadequate demand, and was resolved when sufficient strong aggregate demand returned (in the US case not until World War 2).  Output lost in the interim is a real and substantial cost to the people involved, but the numbers get really big if something changes the long-term future path of growth.  And there is no sign of that having happened in the many financial crises the US experienced from the 1870s to the 1930s.

A few years ago, Andy Haldane of the Bank of England got a lot coverage for a speech in which he presented this table, suggesting that the cost of the 2008 financial crisis could be huge –  100 per cent or more of annual GDP.

haldane

If so, it could be argued that everything should be done, all resources of the state thrown at, avoiding such events, which –  as Haldane put it –  our children and probably our grandchildren might be paying for.  But if there is little or no permanent reduction in the future path of per capita income, as a result of the financial crisis itself, the real economic costs of crises are much much smaller.  And the benefits of any regulatory measures to reduce the risk of crises are commensurately smaller –  all the more so when we allow for how little any of us know about the long-term costs and benefits of such regulatory restrictions.  Even recessions occurring at the time of a financial crisis can’t all (or perhaps even mostly) automatically be ascribed to the crisis itself.

I’ll have a few more posts on related issues in the next few days or weeks.  But recall where I started on this, and where I will loop back to. Per capita income GDP growth in New Zealand and the United States since 2008 has been very similar, even though New Zealand had only a minor domestic financial crisis, while the US was at the epicentre of a major global liquidity event,  and many significant US institutions failed or came close to failing, and US lenders experienced very large losses.   Sadly, as earlier posts have illustrated the relative productivity performance in New Zealand (relative to the US)  has been even weaker.

us vs nz 2

Immigration policy: 106 per cent of net new housing demand

I’ve just read Shamubeel and Serena Eaqub’s book Generation Rent¸one of the Bridget Williams Books series of short, often stimulating, books on New Zealand issues.    Housing is perhaps the ultimate topical issue, and I hope the Eaqubs’ contribution is widely read.

There is plenty in that I agree with, as well as quite a bit that I disagree with.  I might come back to the rest of the book when I have a bit more time, but today I wanted to focus on just one “framing” issue.   How one frames an issue often influences how readers think about it.

The Eaqubs have collected the data from old Yearbooks, and censuses, to show where population-based pressures on housing demand have arisen from over last fifty years (strictly, from the 1961 Census to the 2013 Census).  They present the influences under the following headings:

  • Natural increase,
  • Change in average household size, and
  • Net migration

Under this decomposition 61 per cent of the increase in the number of households has arisen from natural increase, 30 per cent from a reduction in average household size.  The remaining 9 per cent results from net migration.

Put that way, it allows them to present migration (and, hence migration policy) as a fairly minor issue, only really material in a short-term or cyclical sense. As we know net migration is quite variable and not particularly forecastable in the short-term.

But there is another way to look at the numbers.  The New Zealand government has no ability to control the movements of New Zealand citizens, inwards or outwards, so discussions of the role of immigration policy really should focus on the movement of non-New Zealand citizens.   Non-citizens can only come and live in New Zealand with the permission of the New Zealand government –  active permission is required in most cases, while policy allows Australian citizens to come and stay without prior approval.    There are lags in the system, and not everyone who is approved actually comes (or stays) but by and large we can think of the net flow of non-NZ citizens as the contribution of immigration policy.  Since 1960, there has been a net inflow of non-New Zealand citizens every (March) year except 1979.  If economic conditions here are poor, non-New Zealand citizens can leave again too.  In that sense the net inflow of non-New Zealand citizens understate the role of immigration policy in boosting demand for housing.

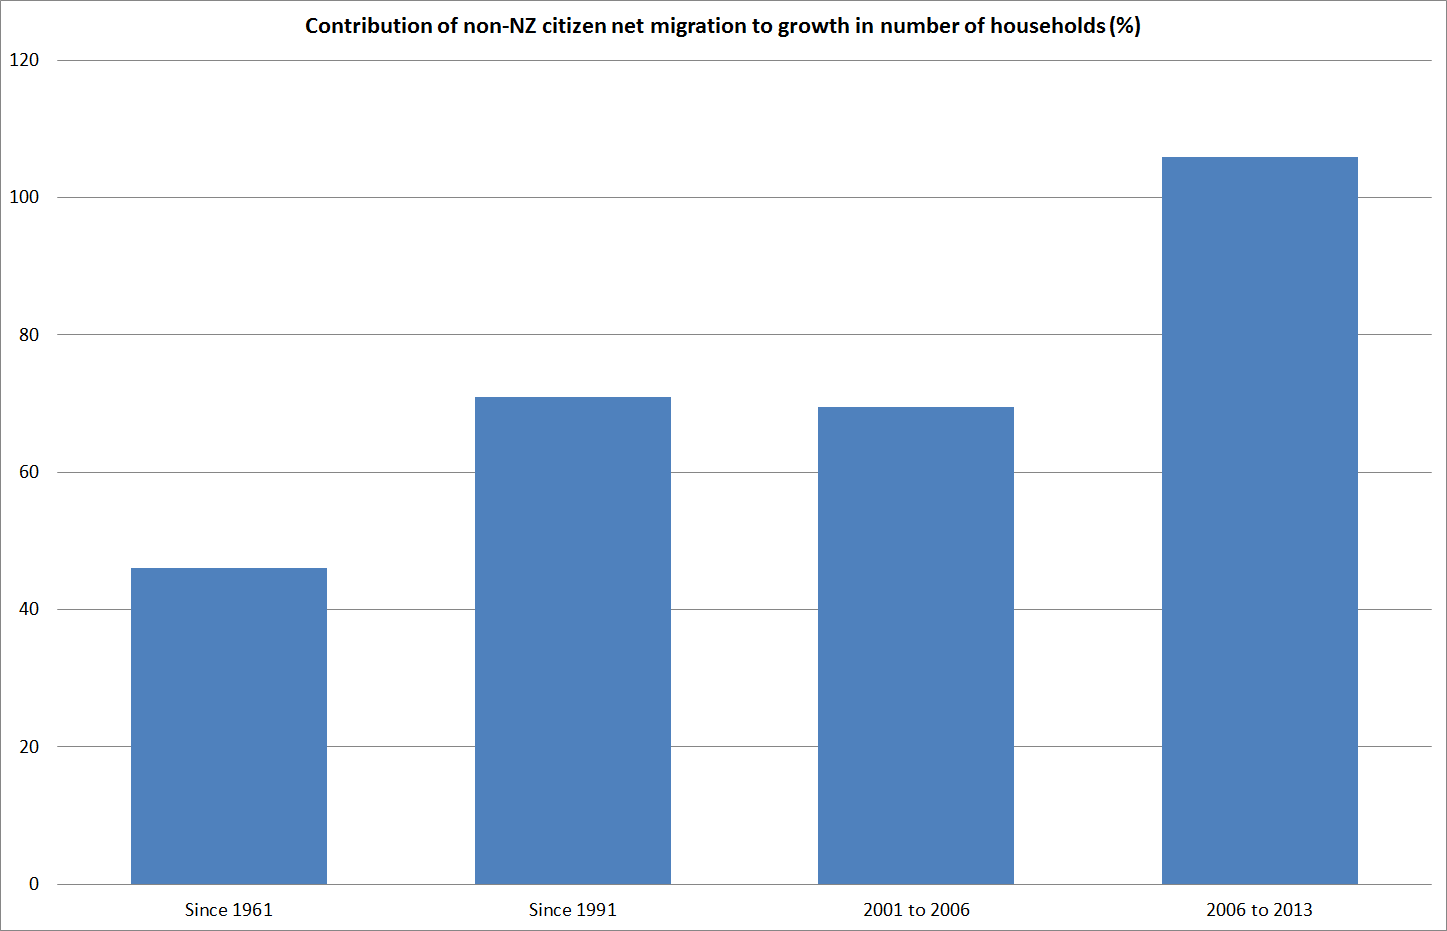
So what has the impact of non-NZ citizen net migration to New Zealand been?   In the 52 years from April 1961 to March 2013 there was a net inflow of 1139351 non-New Zealanders.  Over the same period (between the two censuses), the number of private occupied dwellings in New Zealand has increased by 918000.  With around 2.7 people per dwelling, the net inflow of non-New Zealand citizens has contributed 46 per cent of the total increase in the demand for houses since 1961.

The impact doesn’t happen all at once –  in 1961, people didn’t live at 2.7 per dwelling, but they do now.  And, of course, many of the non-New Zealanders who migrated in 1960s will have died by now.  But most of them will have had children or grandchildren since they moved to New Zealand –  and since the average birth rate in New Zealand has been above replacement, the effective contribution to housing demand from immigration policy is likely to have been higher than suggested by the raw numbers.  As birth rates have dropped, that may not be so in future.

Since 1961 there has been a variety of changes in immigration policy.  From the late 1970s to the late 1980s, inflows of non-New Zealanders were very small.  But what about the most recent since immigration policy was changed to actively pursue much larger inflows (at present, policy aims at 135000 to 150000 permanent residence approvals on a three year rolling basis)?

From 1991 to 2013, non-New Zealand citizen immigration accounted for around 71 per cent of the change in the number of households (or dwellings required).  For the last two intercensal periods the contributions of non-New Zealand citizen net immigration were as follows:

  • 2001 to 2006        70 per cent
  • 2006 to 2013       106 per cent

Even I was a little taken aback by the last number but, of course, it just reflects two things:

  • The chart I showed the other day illustrating that with no (or much lower) non-citizen immigration New Zealand’s population would now be flat or slightly falling
  • No change in the average person per dwelling number between 2006 and 2013.

non citizen plt to households

These numbers aren’t precise.  It is quite possible that new immigrants start off with a higher than average persons per dwelling –  as, on average, non-New Zealand immigrants are poorer than the average resident population.  And the number of people per dwelling is itself partly endogenous to house prices –  if house prices had not been so high, more people would have been able to fulfil their desire to, for example, live on their own.  It is also possible that without the high level of non-New Zealand inflow, the outflow of New Zealanders (which, all else equal, massively reduced the demand for housing) would have been a bit smaller.

But what the numbers do make clear is that immigration policy choices made by successive New Zealand governments account for a very large share of the new household formation, and housing demand, in New Zealand.  If anything, that share has been rising as natural increase slowed.

And, of course, these numbers also tell us nothing about what the appropriate target rate of non-citizen immigration is.  But, unless we can construct a regulatory environment in which the supply of housing and urban land are hugely more responsive to demand than they have been in recent decades, then any conversations around demand influences, and the potential influence of policy on them, needs to engage seriously with the role of immigration policy.  At present –  given what it is knows about supply responsiveness – the government’s immigration policy is actively driving house prices, especially in Auckland, at the reach of too many of those who would like to buy –  citizen or not.

ISDS provisions

In his column in the latest New Yorker James Surowecki looks at Investor-State Dispute Settlement (ISDS) provisions that feature in many bilateral and multilateral trade and investment agreements.  These provisions allow individual investors in some circumstances to seek redress against domestic governments not just in domestic courts, but before an international arbitration tribunal (most commonly the ICSID, which is based at the World Bank).

As Surowecki notes, “these provisions have been opposed by an unusual coalition of progressives and conservatives”.

Advocates argue that ISDS provisions help to encourage foreign investment.  For some of the opponents, that would almost be enough of an argument itself.  For them, foreign investment itself is threatening.   But plenty of people who are generally keen on pretty open foreign investment are also somewhat wary.  I reckon that regulatory obstacles, and screening regimes, in respect of foreign investment  in New Zealand should be materially reduced, but partly because I think foreign investment should be treated as similarly to domestic investment as possible, I’m not sure why we should be providing separate remedies, and separate quasi-judicial fora, for disputes taken by foreign investors.  If we do need greater protection for investors, and for citizens, against arbitrary actions of governments lets have that debate domestically, amend our domestic laws accordingly, and provide equal protection to all.

The first such ISDS provision apparently dates back only to a Germany-Pakistan agreement in 1959.  And, of course, a great deal of foreign investment happened before then – in fact, the whole first great age of globalisation, prior to World War One,  Huge amounts of debt and equity finance went abroad from Europe (the UK in particular) into colonies of settlement in particular.  That included countries with pretty good legal institutions from the start (such as New Zealand) as well as places like the new, and often shaky, states of central and south America.  And it wasn’t just colonies of settlement  –  destinations included Turkey, Persia and China.

Last week I was reading a fascinating older book about just these sorts of issues.  Finance, Trade, and Politics: British Foreign Policy 1815-1914 by D C M Platt, who went on to become a pretty eminent economic historian, looks in detail at how the British government dealt with the interests abroad of British lenders and investors (be they debt holders or concessionionaires or….).  The short answer is that, unless there were really pressing political considerations involved, or the initial obligations themselves arose out of an inter-governmental agreement, the British government took the stance, and held to it pretty firmly, that difficulties with foreign governments were mattered to be dealt with by the investors themselves in the courts, tribunals, and political processes of the country concerned.

The government, and Foreign Office officials, were constantly lobbied to provide additional support to British investors, and the pretty consistent response was “no”.  Governments were typically sympathetic, but they took the view that investors dealing in foreign countries needed to look after themselves.  This, recall, was the government of the strongest power at the time, the government of the country that was, by far, the largest source of foreign debt and equity finance.  And it was a great age of financial globalisation.  And not an ISDS in sight.  If the approach wasn’t followed perfectly, it still looks to me like a pretty good model, that worked pretty well.  Surowecki suggests that “in the old days, aggrieved American investors would call in the Navy to protect their interests”.  If so, it certainly wasn’t how the British did things.

A common argument from defenders of ISDS provisions is that very few claims are lodged, and in very few cases do ruling go against national governments.  But Surowecki notes that ‘nearly 100 have been filed in the past two years, as against some five hundred in the previous quarter century before that”, presumably partly a reflection of that fact that such provisions are becoming more common, but also (perhaps) of a greater degree of activism. He reports that investor-protection is an increasingly prominent part of US law-school curricula.

The other argument is that inclusion of ISDS provisions helps encourage foreign investment.  But the evidence I’ve read suggests, unsurprisingly, that this is true only for recipient countries that have had poor quality domestic legal systems.  For them, the offer of ISDS provisions is a credibility-enhancing device, designed to provide potential investors greater reason for confidence in the security of their investment.  The evidence also suggests that there are few or no gains in foreign investment flows between pairs of countries (eg US and UK) that already have perfectly good domestic legal systems.

From a New Zealand perspective, one argument might be “we have a good legal system, so there might be no gain, but there is no probable cost either”.  I’m not entirely convinced.  After all, Philip Morris is pursuing an ISDS case against Australia over plain-packaging of cigarettes, a remedy that would presumably not be open to them under Australian domestic law.  I’m not expressing (and don’t have) a strong view on that, as yet unresolved, case, but it seems to me that advocates of such ISDS provisions need to make a stronger case for why different remedies should be opened up to foreign investors, and why the domestic courts and domestic political process –  on which the rest of us must rely –  are not sufficient.  There may be such a case, but I’ve not yet seen it.

The unease should be heightened when we recognise the limitations of the ISDS process.  There are a couple of useful backgrounders on ISDS issues by Gary Clive Hufbauer on the Peterson Institute website (eg here).  Hufbauer is a supporter of ISDS provisions, but he draws attention to both the lack of appeal provisions in ISDS tribunals, and the lack of transparency (“ICSID does not require parties to post their briefs and arbitration decisions on the web so that the public knows the arguments and the rationale for any award”.   Appeal provisions are pretty fundamental to our system of justice.

Perhaps the argument for New Zealand signing up to such provisions, whether in TPP or other agreements, is that it helps New Zealand firms investing abroad.  But at a pragmatic level, the countries we are negotiating TPP with now almost all have pretty good domestic legal systems.  And why does the New Zealand government think it is part of its role to negotiate provisions to allow New Zealand investors more rights in respect of investment in overseas countries than those countries provide to their own domestic investors?   The hands-off approach was good enough for Palmerston, Gladstone, and generations of their contemporaries.

ISDS provisions are probably not the most important aspect of TPP, or other similar agreements.  But there doesn’t seem to be much else on offer.  Countries like New Zealand seem fairly certain to be losers from extended intellectual property protections, and the comments from John Key and Tim Groser still don’t suggest any prospect of great movement on dairy protectionism.  And if the strongest argument for TPP really is something like strengthening the US relative to China (a goal which I have no particular problem with),the longer-term success of any such strategy depends on perceptions of legitimacy.  Given the unease many people seem to feel about ISDS provisions, which can look (whether or not they are) like something that is “designed to put corporate interests above public ones”, and the limited evidence of any real economic gains from such provisions, it isn’t obvious why ISDS provisions serve the interests of ordinary citizens or governments, in democratic countries with robust legal and political systems. In the words of a contributor at Forbes, (not, probably, high on Jane Kelsey’s regular reading list) ISDS provisions seem disconcertingly like a “subsidy to business that comes at the expense of domestic investment and the rule of law”

Financial crises since 2007

I’ve been working my way through a series of posts on the post-2007 economic experience of a large number of advanced countries, with a particular focus on trying to make some sense of New Zealand’s (no better than middling) experience.

Today I wanted to have a quick initial look at the incidence of financial crises, since the shorthand for what has gone in recent years has often been “since the financial crisis” or “since the [so-called] GFC”.  Many authors, including some pretty serious and respected ones, have ascribed much of the poor economic performance to the “financial crisis”, adducing the experience as evidence supporting a case for much tighter regulatory restrictions all round.  And there are plenty of theoretical discussions as to how financial crises might have detrimental economic effects.

But what do we mean by a “financial crisis”?  Many authors who try to classify events do so by looking at the gross or net fiscal costs of a crisis (eg the costs of bailouts, recapitalisations, guarantee schemes and so on).  I’ve long thought that was a flawed basis for classification, for a variety of reasons:

  • A country that allowed its banks to fail, with no bail-outs, might have no direct fiscal costs at all, yet on any plain reading could have experienced a very substantial crisis.
  • Most (though not all) of any fiscal support for troubled financial institutions tends to benefit citizens of the country concerned, and so redistributes wealth rather than destroying it.  There may be all sorts of adverse incentive effects, and deadweight losses from the taxes required to cover the fiscal costs, but the level of fiscal support is not a very meaningful indicator of the cost to society.  In rare cases (eg Ireland) the fiscal costs themselves can become quite directly problematic, in terms of on-going market access, but that is not the general experience.
  • A country’s banking system might be very highly capitalised, such that no banks actually failed even under severe stress, and yet on most reckonings the country concerned would have experienced a financial crisis.
  • In some cases, banks will have experienced the bulk of their losses on offshore operations, while the intermediation business in the home economy might have been fine.  The home government might choose to bailout the bank concerned, but there are few obvious reasons to think that those offshore losses (and the choice to bail) will have much effect on the home economy.  A good example, in the most episode, was the losses sustained by German banks.  On many classifications, Germany shows up as having had a financial crisis, and yet almost all of the increased loan losses resulted from offshore exposures (particularly in the United States housing finance market).  If we are trying to understand the economic implications, it probably makes more sense to think of those losses as a US event than a German event.

So instead, I proposed a classification based on non-performing loan data, which the World Bank collects and reports by country.   The proposition here is that, if there are sustained economic consequences from something we can label a “financial crisis”, they are likely to arise primarily from the initial misallocation of resources that led to the loan losses in the first place.  Gross over-investment in a particular sector (say, commercial property in New Zealand in the late 1980s, or in Ireland in the last decade) eventually leads to losses.  The projects don’t live up to expectations, and real resources devoted to those projects can’t easily or quickly be reoriented to other uses. Buildings lie empty, or even half-completed. If there are problems, they arise whether or not any bank ever fails, or is bailed-out by the state.  And banks have to reassess their entire models for generating income, and are likely to become more risk averse as a result of the losses their shareholders faced.  There might be additional costs if a large number of major financial institutions actually close their doors permanently after a crisis (that argument is part of the case for the OBR tool in New Zealand), but relatively few major institutions actually closed their doors in the period since 2007.

The table below classifies countries based on data on banks’ non-performing loans (NPL) from the World Bank’s World Development Indicators. The 20 countries that had a substantial increase in the stock of domestic NPLs after 2007 (the final two columns), are treated as having experienced a domestic financial crisis.

Non-performing loans since 2007
NPLs
Source: World Bank.

Note:

Very low and stable: NPLs:                     less than 2.5 percent of loans throughout, remaining at a stable percent of loans

Moderate and stable: NPLs:                  2.5 to 5.2 percent of loans throughout, remaining at a stable percent of loans

Moderate and small increase:               : NPLs greater than 2.5 percent of loans throughout, increasing by less than 2.5 percentage points

Mostly, the classification looks intuitive, and much as expected. All advanced countries that had a support programme with the IMF during that period are in the financial crisis category. At the other end of the spectrum, the commodity-exporting advanced countries (including New Zealand) all avoided a domestic financial crisis on this, as well as other, measures.

Two points may be worth noting. First, although the extreme liquidity crisis in the United States in 2008/09 attracted headlines – and had global ramifications – loan losses in the United States have been overshadowed by those in many European economies.  One element of this is that more loans in the United States were not on the books of banks (and this is bank data). Second, although some banks in countries such as Germany and Switzerland got into material difficulties, in most cases those were the result of losses incurred in the United States.  As discussed earlier, these losses probably had different implications for the performance of the home (German or Swiss) economy than losses arising out of domestic lending business.

If this classification looks broadly sensible, it is somewhat ad hoc, and might not easily generalise to other crises and other times, even if broadly comparable data were available for earlier periods.

One can’t just jump from this classification to the chart of GDP per capita performance to see whether countries that had financial crises, on this measure, did worse than those that did not.  Apart from the many other influences on any country’s performance, it is also important to recognise that any causation can run in both directions.  The argument that a quite-unexpected period of very weak economic performance will have generated large loan losses (many projects will have been based on assumptions that, however apparently reasonable, did not play out as expected) is at least as strong (I’d argue stronger) than the proposition that “financial crises” themselves cause sustained economic underperformance.  Loan losses did not cause Greece’s problems, but were an integral of an overall process of economic mismanagement and misallocation of resources that led to Greece’s disastrous underperformance in recent years.

And what of New Zealand?  We have had pretty low banking system NPLs throughout.  Finance company losses mattered a lot to investors in those companies, but were still quite modest relative to the overall stock of loans in New Zealand.  There were fiscal costs, through the deposit guarantee scheme, but without the international rush to guarantee schemes there would have been much the same loan losses and probably no direct fiscal costs.

As no major institutions failed, and (economywide) there was little evidence of sustained over-investment in any particular class of asset, one would not generally think of New Zealand having experienced a domestic financial crisis.  Funding was disrupted for a time in late 2008/09, and that was among the factors inducing a greater degree of caution among lenders, but 6-7 years on it seems unlikely that any domestic financial stresses have materially affected New Zealand’s overall performance.  For some sub-sectors, the picture might have been a little different, as finance companies had been major financiers for property developments, but for the economy as a whole the effect seems likely to have been quite peripheral.  And yet, our economic performance has been similar to that of the United States, the epicentre of the initial crisis, and where the increase in actual loan losses was substantial.