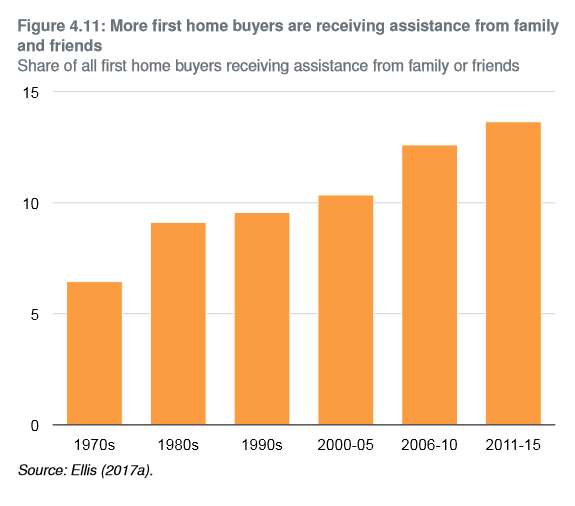Lawless Police

One shakes one’s head in wonderment that multiple guns could be stolen from a city police station in broad daylight (and chuckles at the suggestion I saw that perhaps Police could be prosecuted for failing to store firearms safely).  It isn’t, I guess, the direct responsibility of the government, but somehow it seems symptomatic of just how badly off course the government’s so-called “year of delivery”, transformational change etc, is.   The public sector can’t even get the basics right, even as the bosses parade around (in the Police case), advancing trendy political and social causes, asserting the right to carry firearms in all circumstances, and (wildly inappropriately for a supposedly neutral public servant) offering public adoration and praise of the Prime Minister.  How anyone can still have confidence in the New Zealand Police is a bit beyond me.

This is the same organisation which appears to simply choose to ignore the law when it suits.   Let me illustrate.

In mid-March, a reader drew my attention to an article in a Police magazine, gushing over the appointment of an Assistant Commissioner (formerly the police person in our embassy in Beijing) as a visiting lecturer

at the People’s Public Security University of China – the first foreigner to hold such a role.

The university is where China’s Ministry of Public Security (MPS) trains the elite of China’s police. …..

I wrote a post expressing astonishment that Police could think this was in any way appropriate, given the (official) PRC disregard for the rule of law, and the active part played by Ministry of Public Security in (for example) the large-scale repression and persecution of Uighurs in Xinjiang (or any of the other systematic repressions the PRC prides itself on).  Political loyalty to the CCP will be a key consideration in recruitment, and in helping the Ministry, New Zealand Police buttress the agencies of a regime responsible for so much evil.  Mr McCardle though seemed quite chuffed at his appointment.

He says the university appointment is an endorsement of the healthy state of the New Zealand-China bilateral relationship, and “underscores the idea that New Zealand has values and ideas worth considering in the Chinese context”.

It also aligns with the aims and values of the New Zealand-China Friendship Society and the pioneering work of New Zealander Rewi Alley who fostered a life-long friendship with China from the 1930s.

As I noted

And what about that weird stuff in the final paragraph of the quoted excerpt?  The New Zealand-China Friendship Society has been around for decades and long-served as a Beijing front organisation in New Zealand, right through the horrors of the Great Leap Forward, the Cultural Revolution, and on to their total silence today about repression in Xinjiang.    And Rewi Alley?   Well, he lived a fairly comfortable life in Beijing after the CCP took over, navigating this way through the thickets of changing CCP politics, reaching new lows when he published a jointly-authored book near the end of the Cultural Revolution defending the regime at its worst.  What possesses our Police to think these are “aims and values” to champion?   Why not, for example, the aims and values of the Tiananmen protestors, the Falun Gong movement, or the (underground) Catholic church?  But that wouldn’t fit the narrative I guess, of prostrating the New Zealand system before Beijing.

I wondered what thought, or analysis, went into the decision to accept this appointment, including whether relevant ministers had been aware in advance (and thus complicit).

And so I lodged a couple of Official Information Act requests, one with Police, and one with MFAT.    The request to Police asked

Please provide me with copies of all information relating to the appointment of Hamish McCardle as a Visiting Professor in the People’s Republic of China (as described in [the article])  Without limitation, this request includes any consultation with or advice to other government agencies, or government ministers (or their offices).

I had a response from MFAT fairly promptly, within 10 days or so of lodging the request.  MFAT noted that they were aware of my separate request to Police and responded that

MFAT 1That was useful information in its own right: presumably there had been no internal discussion at MFAT, and no briefing to, or consultation with, the Minister of Foreign Affairs.

And what of Police?  I had an automated acknowledgement of my request, and the MFAT response confirms Police were aware of the request.   Under the Official Information Act, agencies are required to respond as soon as reasonably practicable, but within no more than 20 working days.     That deadline has now long since passed and I have heard nothing at all from Police.

Given the other stuff going on after 15 March, I wouldn’t really have been surprised if Police had got in touch to explain that they needed an extension of time.  In the circumstances, I wouldn’t have been particularly bothered.   Agencies do it all the time, in much less compelling circumstances.  But I’ve heard nothing at all from the Police.  Earlier this week I even got in touch and pointed out that I had heard nothing, in case a reply had simply fallen through the cracks. I noted that if I had heard nothing by the end of the week I would be lodging a complaint with the Ombudsman.    As I now will be.

You might have hoped that Police would more scrupulous than any agency in ensuring that they, and their staff, complied with the law, letter and spirit.    But perhaps they’ve been imbibing some of the lawless values of the People’s Republic of China, whose repressive apparatus their Assistant Commissioner is now helping out, and with which they associate the once-honourable name of the New Zealand Police.  Opportunism not honour, just doing whatever they choose and think they can get away with, now seems to be the order of the day in the Bush-led New Zealand Police.

Police should start complying with the law, and releasing the relevant material under the Official Information Act.  Beyond that, they should rethink this appointment, and ministers should insist that McCardle withdraw from the appointment.  But, of course, there is no hope of the latter, as our government (and Opposition) fall over themselves to show who can do more to defer to the interests and preferences of the PRC.  And that, of course, is why the foreign interference inquiry Parliament’s Justice Committee is undertaking (submissions closed last night) has very little credibility: like foxes taking responsibility for investigating security on the hen house.

UPDATE: The PRC approach to policing and the rule of law –  the disappearance into custody, without charge or trial, of the (PRC) head of Interpol (as reported in a substantial article today in the Wall St Journal).  The sort of thing our Commissioner and Minister of Police are happy to associate with?


Bank capital proposals still inadequately supported

When I opened the newspaper this morning and found the headline “The world needs ethical leadership”, above a column written by someone whose own leadership often fell well short of that standard, it was tempting to go chasing hares.

But I’m more interested in the damage the current leadership of the Reserve Bank is doing both to the standing of the Bank as an institution and –  more concerning still – to the New Zealand economy and private firms operating in it, by the Governor’s plans to require banks to raise a great deal more equity capital to support their current levels of business.  This morning I want to comment on a couple of contributions to that debate from two of my former Reserve Bank colleagues.

Before doing so, note that I hardly ever agree with the newspaper columns of Business New Zealand’s head Kirk Hope, but his column today on the bank capital proposals is right on point.  He ends with suggestion that really should be uncontroversial

BusinessNZ recommends that the Reserve Bank should undertake a comprehensive cost/benefit analysis of the proposals before any further steps are taken.

In fact, the Reserve Bank tells us repeatedly it only intends to do such an exercise when it is too late for it to inform any public discussion or submissions –  it will support whatever whim the Governor finally runs with, rather than assisting the development of policy and the contest of evidence and arguments around the proposals the Governor is hawking, and which the Governor himself will get to decide on.

It has been a quiet week in central Wellington, with many people taking the chance to use a few days’ leave to get quite a long autumn break.  Nonetheless, a fairly good crowd turned up at Victoria University at lunchtime on Wednesday to hear Ian Harrison critically review the Reserve Bank’s capital proposals.  Ian spent most of his career at the Reserve Bank, and did much of the modelling work associated with the previous review of capital requirements, undertaken only seven or eight years ago.  Since leaving the Bank he has also consulted for commercial banks on risk modelling and associated capital issues.

I’ve already written here about Ian’s March paper reviewing the Bank’s proposals.  Since that paper was written the Reserve Bank has published another 50 page paper attempting to buttress their case, and Ian’s latest presentation –  also titled “The 30 billion dollar whim” (with no question mark) – attempted to take account of that paper.  He has a further review paper coming; one hopes in time to inform submissions before the Reserve Bank’s deadline on 17 May.

The Bank’s claim all along has been that these proposals are a win-win.  We can have a more stable banking system –  despite never having had a systemic banking crisis (at least outside an immediate post-liberalisation period) –  and higher (expected) GDP as well.  This is one of their charts.

win win

It has never really rung true, and none of what they keep on releasing really buttresses their case.   As I’ve noted previously, in his speech in February the Deputy Governor acknowledged that the proposals could cut the level of GDP by “up to 0.3 per cent” (say, 0.25 per cent then), and to pay that insurance premium each and every year, on a policy which could be cancelled at any time on the whim of some future Governor, it would have to save us from something truly devastating perhaps 75 years hence.   Countries with floating exchange rate, reasonable institutions, and governments that keep out of credit allocation, simply don’t have those sorts of truly devastating events.  As I and others (including a rather more prominent US author) have noted, in the serious recession of 2008/09, the (floating exchange rate) countries that had financial crises didn’t perform materially worse than countries that did not.   Most likely, what the Reserve Bank is proposing won’t move us north-east of the orange dot (as the Bank claims), but more likely south-east.   We’ll be poorer but the banks –  already a stable core of (what the Bank tells us every six months is) a stable financial system –  will be sounder still.  It doesn’t seem like much of a deal…….especially without a robust cost-benefit analysis that we can properly review, or any open engagement with the criticisms various people have advanced.

Ian Harrison also points out that the Bank appears not to have take explicit account of the fact that our main banks are foreign-owned.  As he notes, most of the international modelling on capital works on the assumption that banks are largely domestically-owned.  If higher capital requirements mean higher total equity returns to shareholders that in itself isn’t a loss to the domestic economy –  just a transfer from one lots of nationals to another.   There might still be some cost in the form of lost output, resulting from a higher economywide cost of finance and wider intermediation spreads  (eg the Deputy Governor’s “up to 0.3 per cent”).  But in New Zealand, if we compel banks to have much more capital to support their level of business, and there is no full offset between the cost of debt and the cost of equity (and the Reserve Bank accepts there won’t be), there is an expected net transfer from New Zealanders to (in this case) Australia and Australians.  That is where Ian’s $30 billion number (a present value calculation) comes from.   It doesn’t figure in any of the Reserve Bank documents, which seems on the face of it a rather gaping omission  –  especially from a Governor who appears to have a strong prejudice against Australian banks.

There was a lot of material in Ian’s presentation and I can’t cover it all here.  But a few other highlights:

The Bank likes to claim that their new approach –  specifically identifying how infrequently they think New Zealand should expose itself to a financial crisis (once in 200 years is the Governor’s stab in the dark) –  is a significant step forward, and determines the proposed capital ratios that emerge from the analysis.  Ian notes that, if anything, it appears to be the other way round: they initially used a 1 in 100 year framing, found that produced results they didn’t much like (something like current capital requirements), and with no supporting analysis at all –  there is a single sentence footnote –  switched to the 1 in 200 year framing.   Support rather than illumination springs to mind.  The Governor seems to have wanted high headline minimum capital ratios –  regardless of cost, regardless of the fact that the way ours will be calculated will be more demanding –  and to have cast around for anything to prop up such a case.

In his rather whimsical vein, Ian goes on to suggest that there is so little substance behind the proposal that perhaps the proposed 16 per cent minimum capital ratios (CET1) for big banks might as robustly have been derived from the Governor’s fling with the tree god Tane Mahuta: the kauri tree of that name has a girth of 15.44 metres apparently, and allowing a little for growth we get 16.  In a similar vein, he goes on to note that kauri trees are (apparently) bigger than gum trees, which perhaps accounts for the Governor pushing his requirements well beyond those in Australia.

Ian unpicks the relevance of various of the overseas paper the Bank cites, including noting how dependent any of the results are on specific assumptions, specific sample periods (especially around loan losses –  using a short period centred on 2008/09 will produce different results than, say, using the last 100 years).  In some of the Bank’s New Zealand analysis (including around the late 80s/early 90s) instea of using loan write-offs (recorded just once, when the write off occurs) they’ve used average annual non-performing loan data – even though the same non-performing loan can remain on the books for several years, but can only be written off once.

He noted briefly, as I have at more length here, the important distinction between (a) marginal effects and average effects (we should only focus on what further reduction in crisis probability this further big increase in capital requirements will result in), and (b) between the costs of the bad lending and investment choices that led to loan losses, and the cost of bank failures themselves (the Reserve Bank simply never addresses this latter point).

In passing he notes that references to reducing fiscal costs of bank failures tend to be overstated: the common reference point in 2008/09, and yet bank capital ratios are already materially higher than they were then, and even in 2008/09 the net fiscal costs (after recoveries and sales) were often quite small.  Oh, and OBR here is supposed to further reduce, or eliminate, fiscal costs.

In its latest document, the Bank devoted a lot of space to the alleged social costs (suicides, divorces, mental health problems) etc of financial crises.  Ian looked at all their references, and I don’t think it would be going too far to say that the Bank’s representations were borderline dishonest –  often drawing from countries without a decent social safety net (or countries without the buffer of a floating exchange rate).  Again, the idea that the Bank was looking for support rather than illumination sprang to mind.

Ian ended his presentation with a simple insurance parallel, suggesting (as above) that the Bank was inviting New Zealanders to buy (well, perhaps compelling us to buy) a very expensive insurance policy of the sort no rational agent would ever buy voluntarily.  All backed up with inadequate analysis and no serious engagement.

After Ian’s presentation there were several thoughtful questions from the floor.  Graham Scott, former Secretary to the Treasury  back in the reform era and currently a member of the Productivity Commission –  a “dry” if ever there was one – asked about the assumptions around the Modigliani-Miller proposition.   At the extreme, this proposition asserts that the financing structure of a firm (mix between debt and equity) doesn’t affect the value of a firm.  In this case, for example, requiring banks to hold even a 20 per cent capital ratio wouldn’t affect the economics of banking  (required rates of return on equity, and debt costs) would fall to fully offset the increased equity component.  It would suit the Reserve Bank case to be able to argue that there is such a full offset, but they don’t. Instead, they assume something like a 50 per cent offset (thus, over time required rates of return on banking in New Zealand will fall, but not enough to fully reflect the reduction in the expected future variance of earnings).

Graham Scott’s point – which echoes one I’ve alluded to here on a couple of occasions –  is that the 50 per cent offset assumption may still be too high.  He notes that the big Australian banks’ New Zealand subsidiaries are not listed entities.  From a shareholder (in the parent) perspective the operating subsidiaries here are little more than another operating division of a much bigger company.  Every manager in every operating division will always be looking for excuses to deliver low rates of return (circumstances, regulatory factors or whatever) while still collecting their bonuses and we might be sceptical that the parents will accept low rates of return on bank business here simply because our Reserve Bank says they have to hold more capital.   Correlations also matter –  reduced variance in New Zealand earnings, might do little to reduce the variance of the earnings of the parent.

I suspect that the direction of the effect Graham Scott points to is correct, but that the effects might be seen in a rather disruptive way.  As I’ve noted previously, the Bank’s capital requirements apply only to locally incorporated banks.  Big corporates will have no particular problem getting credit from overseas banks that aren’t incorporated here.  These might include the parent (Australian) banks, all of which also have branches here, or any other significant bank in the world (Fonterra is most unlikely to pay a higher cost of debt because of regulatory stuff our Reserve Bank does).   The bond market also offers a mechanism to take locally-incorporated banks out of the mix –  not just for big corporates, but potentially for securitised home mortgages.  Some credits can’t be easily or quickly securitised and they are likely to be the ones who bear the brunt of the changes.  Overall, credit may be harder to get and more expensive.  The other group who may bear the brunt will be depositors –  borrowers can over time change their credit provider, but retail depositors (in aggregate) have fewer options (eg overseas branch banks can’t take significant retail deposits).

But none of this –  not a single strand of it –  is analysed in any of the material the Reserve Bank has put out.  Nothing about transitions, nothing really about steady states, nothing about how the fact that the requirements will fall on some but not others will affect the future structure of the financial system.  It is really inexcusably poor policy development and communication.  One business figure put it to me recently that there is a risk that the Bank’s proposal will actually reduce the soundness of the financial system –  increasing the soundness of the core banks themselves (perhaps, unless the parents choose to partly liquidate their exposures, and we are left with banks without strong parents), but reducing the significance of those core banks (and leaving many credit exposures less transparent than they are now).  I’m not sure I would yet go that far, but the rather limited and mechanistic approach the Reserve Bank is taking is leading them to overstate even any possible soundness gains, even as they ignore the likely output costs.

It simply isn’t a standard of policymaking we should accept.  The Minister of Finance and The Treasury –  if the latter isn’t distracted playing sun-moon cards and talking about their feelings –  should be demanding better.

And that is more or less the theme of another former Reserve Bank regulator, Geof Mortlock, in his piece on interest.co.nz earlier in the week.  After noting how resilient the Reserve Bank’s own stress tests suggest the New Zealand banking system is, and noting some of the likely costs and disruption, Geof notes

One would think that these costs and other adverse impacts would have received a great deal of attention by the Reserve Bank in undertaking a cost/benefit assessment of the proposals.  But no.  By their own admission, they have not yet undertaken a comprehensive cost/benefit analysis.  (Perhaps Adrian Orr was too busy engaging in god-to-god dialogue with Tane Mahuta and the forest fairies to give serious policy matters his attention! Deities are so busy of course.)

I don’t agree with all Geof has to say –  he is much more optimistic about the value supervisors can bring to the table than I am – but on the lack of proper, searching, evaluation and robust ex ante cost-benefit analysis we are at one.  As Geof says, it just isn’t good enough.

Geof’s bottom line is this

What is needed is an in-depth independent, professional assessment of the Reserve Bank’s capital proposals. Treasury will no doubt review the Reserve Bank’s cost/benefit assessment once the Regulatory Impact Statement has been prepared. However, that is too late in the policy formulation stage. Moreover, with all due respect to Treasury, it lacks the depth of knowledge needed for a rigorous assessment of the different policy options and the costs and benefits of each. What is needed is for Treasury, at the direction of Grant Robertson, to engage a couple of independent professionals (such as an academic specialised in bank regulation and a recently retired foreign senior bank regulator – e.g. John Laker, former Chairman of APRA) to undertake a comprehensive assessment of the Reserve Bank proposals, plus alternative options. The findings of this assessment should be incorporated into the Treasury’s own review and the results be made public. The independent review would considerably assist the quality of the process of assessing the Reserve Bank’s proposals and may assist in reaching a more sensible outcome.
An independent review would sensibly include consideration of:

  • the magnitude of economic shock needed to cause any of the large banks in New Zealand to fail, and the probability of such a shock occurring;
  • the level of capital needed to enable banks to survive a plausible range of severe economic shocks;
  • the composition of capital requirements and other loss absorption facilities that would be suitable to enable banks to survive severe economic shocks, including whether (as in many countries) a substantial proportion could be in the form of debt instruments that convert to equity upon defined breaches of core equity capital ratios;
  • the impact of the proposed increase in capital ratios on bank lending, interest rates, property prices and economic growth (with implications for government revenue);
  • the impact of the proposed increase in capital ratios on banking system contestability, competitiveness and financial inclusion (especially for those on low incomes);
  • the alternative policy options for strengthening the resilience of the banking system, including strengthening Reserve Bank supervision of banks’ governance, risk management practices, lending policies, and recovery planning;
  • the bank failure resolution options that could be applied to maintain financial stability with minimal taxpayer risk (and hence reduce the need for high capital ratios).

The Minister of Finance and Treasury need to give serious attention to these matters. And the sooner the better.

I have a lot of sympathy with that.  If the Reserve Bank’s supine Board had been doing its job they would have strongly urged the Governor to take such a path –  and/or prior open consultation before the Governor himself took a view –  from the start.  It is all the more pressing that things be done properly, evaluated rigorously, contested vigorously, when it is the Governor personally who is championing these (extreme) changes and the Governor personally who will finally make the decision (with no rights of appeal or review).

As a final note, generally I don’t think the banks help themselves. On both sides of the Tasman banks are typically scared of being openly critical of their regulator.  I can understand that to some extent –  regulators exercise a lot (too much) power on a lot of dimensions –  and no doubt the banks will raise significant concerns in their own submissions.  But by the time the submissions are in – and especially by the time the public ever see those submissions –  it will be too late to marshall a wider pool of support for their case.  Sure, banks are not naturally particularly sympathetic entities, but this is one of those cases where what is bad for banks is probably bad for New Zealanders and the New Zealand economy as a whole.   Sadly, banks have made no effort to engage in any public debate on these issues over the 4+ months this Reserve Bank proposal has been in the public domain.



Polling marijuana

There was an interesting new poll out the other day on public attitudes to marijuana and the possibility of law reform (on which there is to be a referendum at the time of next year’s election).  The results certainly took me by surprise.

For the record, I don’t have very strong views on the law around marijuana.  A couple of years ago I’d got to the point where I’d probably have voted for full liberalisation, but since then I’ve swung back somewhat in the other direction (influenced in part by reviews of and extracts from this recent book, a copy of which I’m expecting in the mail any day now).  In an up/down vote today I’d probably vote against full liberalisation, but as to how I will actually vote next year, a lot might depend on the specific question.  One thing I really don’t like is a law on the books that isn’t generally enforced, but which leaves our untrustworthy Police free to use it when it suits them.

But I’d been under the impression that New Zealand public opinion was pretty favourable to substantial liberalisation of “recreational” use of marijuana.  So I wasn’t expecting this result.    Asked “which of the following statements comes closest to your opinion on cannabis?”, responses were as follows

mar 1

The margins of error get quite large quite quickly once the results are broken down, but young people are probably more favourable to liberalisation than old people, poor people probably more favourable than better-off people, and National voters much less favourable than Green voters (but only 53 per cent of the latter favoured liberalisation of recreational use, as posed this way).

The poll was commissioned by Family First who have been opposed to liberalisation of recreational use.  In itself, that doesn’t invalidate the results (probably almost anyone likely to be polling in this area in New Zealand is likely to be motivated in one direction or the other) but it is worth thinking about whether the questions posed are especially likely to skew the answers one way or the other.

One problem is this area is the array of possible options.  As someone without an intense interest in the topic, I struggle to remember the difference between, say, decriminalisation and legalisation, and as Family First notes the poll deliberately didn’t focus on either of those more-technical terms, asking instead about “lifting restrictions”.  In principle, you can lift restrictions partially or fully, and when I first looked at the question my immedate reaction was that it encompassed both. But perhaps many of the interviewees took “lifting restrictions” as removing all restrictions and penalties?  If so, that might help explain why support for recreational liberalisation appears so low.

Perhaps there is also an issue with posing both the medicinal and recreational options in the same question.   While lifting (in part or in full) restrictions on recreational use would seem to encompass freeing up medicinal use, it doesn’t actually say that.  Perhaps some people who care quite a bit –  or want to go on record as caring quite a bit –  about medicinal use plumped for that option, even if they actually favoured recreational use liberalisation, to ensure a resounding explicit vote on medicinal.  Presumably that won’t be the way next year’s referendum will be framed?

Some of the other results in the poll were also interesting.  There were six questions, and the questions on policy preferences is the last of them.  The preceding questions might, in principle, (been framed to?) influence how people answered the final question.

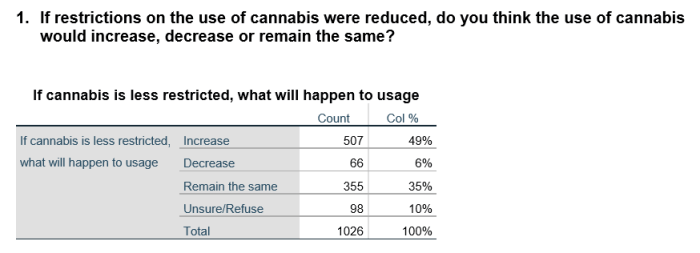
The first question was

mar 2

I’d have answered “increase” too, and I don’t think that result should be too surprising.  Reduce the effective price and, all else equal, consumption is likely to rise.  Note that the question is framed around “reducing” restrictions on use of cannabis, not about more specific choices, and that seems fine.

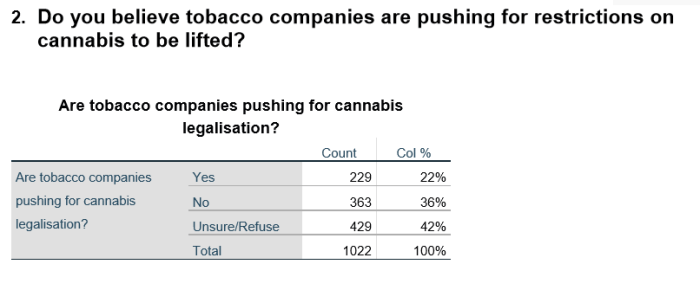
The second question was more puzzling

mar 3

I don’t know (and probably would have said so), but it would probably be rational for them to do so (the possibility of a new substance to market, and perhaps undermining restrictions on tobacco).  But one might wonder why the question was asked?  To prompt people to associate liberalisation with “big tobacco”?

What about question 3?

mar 4

This seems to be a pretty widespread concern (among serious opponents of liberalisation) so not an unreasonable question.  But note the “can” –  which is a possibility, and thus more likely to get a positive response than, say, a “does”.  Even 95 per cent of Greens voters –  people who end up favouring recreational liberalisation –  ended up saying “yes” to this one.

And then question 4

mar 5 Again, it is an argument you see around (including reviewing the experiences of US states that have liberalised), and actually the question doesn’t seem posed unfairly (both “more likely” and “less likely” are explicitly mentioned), and there is an overwhelming vote for “more likely”.    Of course, there might be a selection issue at work: respondents might think people likely to take marijuana were also already younger and less responsible (more risk-taking perhaps) so they might not be directly asserting causation.

Perhaps the same issue arises with question 5.

mar 6

Even 46 per cent of Green voters said “less likely” to this one, but again it isn’t quite clear what will have been going in behind the responses.  Some people will have been thinking ‘well, many firms have drug tests, and if you take drugs you will fail those tests and not get a job”.     Others will have been reflecting views on the potential work ethic of those who might take jobs.   Others again will have been worried about the potential mental illness effects (see earlier questions).

I don’t have too much of a problem with asking any of the questions that led up to question 6 (views on liberalisation itself).  After all, when the referendum comes people won’t be voting in a vacuum but will face a plethora of arguments, evidence, and pseudo-evidence on both sides.   Of course, if one wanted totally disinterested poll results –  wouldn’t that be great –  one might have wanted some other questions interspersed reflecting some of the arguments of those who favour liberalisation.  Perhaps “do you think people should be free to choose what they inject or inhale, without state restrictions?” or “even if you personally would never consider taking marijuana, do you believe Police should have discretionary power, often not exercised, to prosecute those who do?”, or “do you think current marijuana law encourages or discourages criminal gangs” or the like.

In the end, I’m not sure quite what to make of the results.    No doubt, the questions could be asked, and framed, in ways that produced higher numbers in favour of reduced restrictions on recreational use, and I doubt that –  in any real sense – only 18 per cent of New Zealanders favour some liberalisation of recreational use.  But I’m still left a bit surprised that, even on the questions asked on this poll, the support numbers weren’t higher.

Perhaps the result of next year’s referendum really will depend a lot on the specific question asked.  It would be good if, before long, the government were to give us some specifics on that, and on the whole associated regulatory or tax regime they are proposing.


Reforming housing/land, and compensating some losers

There seem to have been more than a few people on the left pretty deeply disillusioned with the Prime Minister after she walked away from the possibility of a capital gains tax, not just now (when the parliamentary votes for it probably couldn’t be found) but at any future time while she is Labour leader.    Some parallels are drawn with John Key ruling out doing anything about raising the age for New Zealand Superannuation while he was leader –  an important difference perhaps being that Key had never evinced any enthusiasm for such a policy, only to recant, let alone been the leader who put the issue back on the table.     Perhaps something closer was Key’s refusal to use whatever “political capital” he had to do anything much useful around economic reform.  But, again, despite occasional encouraging rhetoric while in Opposition, no one ever really thought Key was someone who would rock the boat, or was that bothered about doing useful longer-term stuff, as opposed to holding office and managing events as they arose).  Some, perhaps, thought Ardern was different.

But in the wake of the Prime Minister’s abandonment of the possibility of a CGT –  and whatever (quite diverse apparently) hopes people pinned to that quite slender reed – there is the growing question of what, if anything, the government might actually do. It is, after all, in their phraseology, supposed to be the year of delivery.

In his Political Roundup column yesterday, Bryce Edwards posed the question as “What will Labour do about inequality now?”.   There is a lot of talk about different possible tax reforms –  I might even come back and look at a couple in later post – and some reference to the forthcoming “wellbeing budget” (which can surely only disappoint, given the self-imposed fiscal constraints).   But there was nothing about the option most directly under government control which would probably make the biggest tangible difference to the most people, with clear efficiency gains not losses, and with the possibility of a considerable degree of across-Parliament support: fixing the housing and urban land market at source.

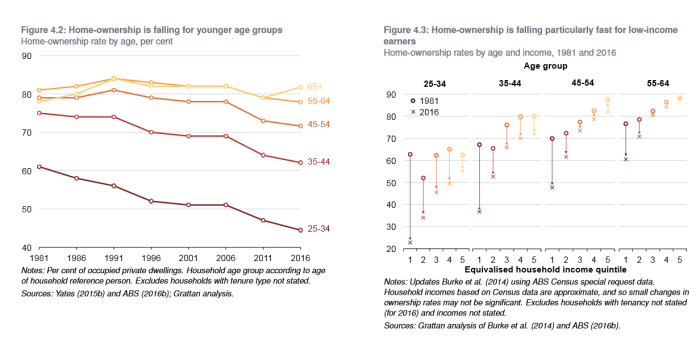
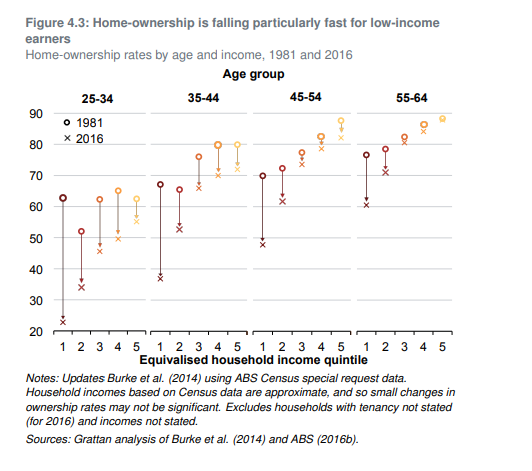
As a reminder of the symptoms of the problem, I ran this chart in my post earlier in the week. It is Australian data, but the picture seems unlikely to be much different in New Zealand.

aus 1

The young and the poor (especially the young poor, and probably especially the Maori and Pacific young poor) are increasingly squeezed out of the possibility of home ownership, for decades or at all.   There is no good economic or social case for tolerating this systematic penalisation of the more marginal groups in our society.

But there are obstacles to reform, including the economic interests of those who could suffer quite seriously –  through no real fault of their own –  if the situation was fixed.

Some elements of the government –  well, really only one, the Minister of Housing –  talks a good talk.  In a recent speech he talked up the prospect of reforms that the “flood the market” with development opportunities and thus lower, presumably quite considerably (when you use a strong word like “flood”), urban land prices.   It warmed the hearts of many (mostly rather geeky) readers, including me.   And yet I’m very sceptical that it will come to much. As I noted in a post shortly after the speech

And yet, I remain sceptical.  Perhaps Phil Twyford’s heart is really in this.

But is the Prime Minister’s?  Even though housing was a significant campaign issue, even though she has been in office for 18 months now, we’ve never heard her putting her authority behind fixing the housing disaster at source, let alone substantially lowering house prices.

And is the Green Party on board?  Quintessentially the party of well-paid inner-city urban liberals, are they really on board with bigger (physical footprint) cities, or with encouraging intense competition among landowners for their land to be developed next.  Some of them seem to believe that it would somehow be morally virtuous –  and “solve” the affordability issues –  if people lived instead in today’s equivalent of shoeboxes.

The approach of the Wellington City Council –  led by one of Labour’s rising figures –  just reinforced my doubts.

There are various practical issues to be worked through in any serious reform effort.  But one consideration that always seems to play on the minds of politicians (understandably enough I guess) is that lower house prices means lower house prices: in other words, people who currently own a house will find their asset worth a lot less than it was.     For those of us without a mortgage on our primary residence or with only a modest remaining mortgage, such a fall wouldn’t matter at all.   Our natural position is to own one house, and we intend to own one house (perhaps a different one) well into our dotage.  The label (the estimated value) attached to that property doesn’t really matter.  And for our kids hoping to enter the market in the next decade or two it is pure gain.

But it, understandably, feels quite different if you are one of the growing number of people who have taken out a very large mortgage (perhaps 80 per cent or more LVR) to get into a house.   If someone talks of halving house prices, that can sound pretty threatening.  As a result, very few politicians ever do (I recall Metiria Turei doing it, but only once, and……).    Banks have the legal right to call in their loan if the value of the collateral (the house) drops below the outstanding value of the loan, and although they probably wouldn’t do so in normal times –  when the labour market was okay –  it leaves people feeling quite vulnerable, and also quite trapped (hard to move cities if selling would immediately crystallise a large loss).

When house prices first shoot up there aren’t many people affected that way.  The longer they stay high –  five or six years now of the latest surge up –  the more people have taken out mortgages based on the high house and land prices.  Most of the owner-occupiers among them aren’t business operators or “speculators”, just people at a stage of life where they want to settle and to be secure in a place of their own.   And they –  and their parents – vote.

Of course, there is a whole other class of people who would lose from house and land prices coming down.  But mostly they are a less sympathetic group.   There are the “landbankers” –  people who responded to government-created incentives –  to sit on potentially developable and let the artificial scarcity push up the price of their asset.   That’s a business operation, and in business you win some and you lose some.   Risk is at the heart of business, and that means the possibility of real and substantial losses.  And there are those in the residential rental business, many of them (especially recent entrants) quite highly leveraged.  Halve the price of city properties –  and that is what re-establishing sensible price/income multiples would imply –  and many of those owners would be either wiped out, or see their real wealth (real purchasing power for things other than houses) very dramatically reduced.  But, again, it is a business, and business implies the possibility of gains and losses (one reason I was always at best ambivalent about a CGT was that no real world CGT really treated gains and losses symmetrically).

Of course, these business owners vote too, and will lobby intensively.  But (a) there are fewer of them than mortgaged owner-occupiers,(let alone unmortgaged renters, hoping to be mortgaged owner occupiers) and (b) they just don’t command the same public sympathy (and rightly so) –  we might sympathise with any business owner whose operation falls in hard times, but we know that is the nature of business.

Back when Jacinda Ardern first became leader of the Labour Party I did a post on what a radical reform package, that might really make a difference to our economic woes (housing and productivity), might look like.   Buried in that post was a suggestion for a partial compensation scheme for mortgaged owner-occupiers that might help smooth the way towards overdue structural reform.  I noted then the desirability of getting house prices down a long way.

No one will much care about rental property owners who might lose in this transition –  they bought a business, took a risk, and it didn’t pay off.  That is what happens when regulated industries are reformed and freed up.    It isn’t credible –  and arguably isn’t fair –  that existing owner-occupiers (especially those who just happened to buy in the last five years) should bear all the losses.   Compensation isn’t ideal but even the libertarians at the New Zealand Initiative recognise that sometimes it can be the path to enabling vital reforms to occur.  So promise a scheme in which, say, owner-occupiers selling within 10 years of purchase at less than, say, 75 per cent of what they paid for a house, could claim half of any additional losses back from the government (up to a maximum of say $100000).  It would be expensive but (a) the costs would spread over multiple years, and (b) who wants to pretend that the current disastrous housing market isn’t costly in all sorts of fiscal (accommodation supplements) and non-fiscal ways.

If I recall rightly, I came up with the rough suggested parameters as I was typing, but a couple of years on it still looks like the sort of thing that might be worth considering, perhaps with a larger cap on the maximum payout and a restriction to a first (owner-occupied) home.   The expected cost will have escalated since 2017, because we have had another couple of years of people taking our large mortgages on properties with values inflated by government-controlled regulation in the face of trend increases in demand), but so has the number of people unable to do what they would otherwise “naturally” do; purchase a first house in their mid to late 20s.

This is a sketch outline of a scheme, and like all such government schemes would need lots of detail to limit abuses.  But what are some of the features of the scheme:

  • you only get to lodge a claim if you sell your house (someone who is going to stay in the same house for 50 years doesn’t need any explicit compensation, even if they are left with a heavier servicing burden than might otherwise have been possible if they’d waited to buy).  Of course, some people will choose to sell and buy somewhere different just to crystallise the right to make a claim, but selling a house – a genuine arms-length transaction –  and moving isn’t cheap.
  • the nominal price has to have fallen more than 25 per cent to be able to make a claim at all.  For the last few years LVR restrictions have meant that most owner-occupiers have been borrowing only 80 per cent of less at purchase, and there will have been some principal repayments since then.      Relatively few people would be in a negative equity position if their house price fell by 25 per cent, and even fewer would be facing immediate pressure from their lender.  Owning an asset has to mean some exposure to reasonable swings in price.
  • beyond a 25 per cent fall, you could claim back up to half of subsequent losses from the government.  Thus, if you had bought an $800000 first house and the price halved, you would be eligible to claim $100000 back from the government (half of the difference between $800000 and $400000.   On reflection, and with such a large deductible (the owner takes the first 25 per cent loss) it might be more appropriate for a compensation scheme to cover 75 per cent of subsequent losses (in this example $150000).
  • any such scheme should have a maximum payout capped.  There is no obvious justice in paying out large amounts to a couple who happened to buy a $4 million house which then halved in price (there was a similar issue when the government bailed out AMI).

I don’t have a good sense of how large the cost might be (but it would be in the billions, spread over at least a decade).  Unfortunately, I’m not one of those who believes that fixing the housing market would produce significant productivity gains for New Zealand –  so it isn’t by any means a free economic lunch –  but the sheer injustice of what successive central and local governments have done to our young and poor cries out for action, and sometimes it is worth offering compensation to help pave the way for the sort of thoroughgoing reform that is desperately needed.

Fixing the housing/land market at source would be a huge step to improving the economic and social wellbeing of so many.  Compensating some of the more sympathetic of the losers from such a reform –  most of whom won’t be in an overly strong financial position themselves –  shouldn’t offend too many canons of justice. In an ideal world, one might seek to finance such a scheme from those who benefited greatly from the previous (well, current) rigged market – but that would be hard to do.  In the real world, we are fortunate that the government has fiscal surpluses and very low net debt (especially including the politically managed money pools in NZSF).

I’m not optimistic the government (Prime Minister) really has much interest in addressing the housing/land problems at source.  But if she is ever is tempted to take seriously Phil Twyford’s rhetoric, a compensation scheme of some sort might be an option to consider, to help dull the inevitable opposition in some quarters (some purely from business interests who would have misjudged, but some from people who through little fault of their own became trapped by these longrunning government policy distortions, that generated the scandal of the New Zealand housing market).


Lack of transparency and the MPC

The statutory Monetary Policy Committee is now responsible for monetary policy and we’ll see the first fruits of their deliberations in a couple of weeks.   It won’t just be the outsiders who are new, with two of the four internals having also taken up their jobs (in one case, joined the Bank) since the last Monetary Policy Statement.

In addition to the questions about how the Committee is going to work, what approach to policy they will take, whether the Governor remains as dominant as I fear, and whether a new era of greater policy transparency is really being ushered in, there are some other outstanding questions about the Committee.

One of them is how much the external members are getting paid.  The government simply refuses to tell us.  The same government that once promised to be the most open and transparent ever.

There was an article about this in the Herald ten days or so ago.  The government’s standard schedule of fees for appointments to public board and committees allows a maximum fee of $800 a day.  Perhaps $800 a day might, just, be reasonable for a role that involved only, say, 10 days work a year.    But the MPC jobs were advertised as involving about 50 days a year –  a fair chunk of anyone’s earnings potential –  and there are some material constraints on what other activities people on the MPC can do.   $800 a day is probably equivalent in annualised terms to around $175000 per annum.

And so, reasonably enough, the Minister of Finance sought approval to offer a higher rate to those appointed to the MPC, arguing that if more money was not on offer they might struggle to get the “right” sort of applicants.   These sorts of exceptions are made from time to time,

A spokesman for [State Services Minister] Hipkins said in 2017/18, the Government approved 43 “exceptional fee” proposals.

That number was 90 in 2016/17 and 42 in 2016/15.

The suggestion in the article is that the government may be paying up to $1500 a day to the MPC appointees

The letter also said the most comparable role within the state sector would be a member of the Commerce Commission, who earns a salary equivalent to a daily fee of $1565.

$1500 a day might be equivalent to an annualised rate of around $330000 per annum.

I don’t too much problem with that level of fee, provided the MPC members are going to do the job well, and not just become free-riders largely deferring to management.

After all, consider what the internals on the committee are getting paid.   Going by the remuneration tables in the Bank’s Annual Report, they probably get something like this:

  • Governor                                                                                    $700000
  • Deputy Governor and Head of Financial Stability,            $500000
  • Assistant Governor (Econ and Financial Markets)             $425000
  • Chief Economist                                                                         $325000

The Deputy and Assistant Governor roles are both second-tier appointments, while the Chief Economist is a third-tier role.

Of course, academics get paid less well than this (and two of the three external MPC appointees have academic backgrounds) but the private financial sector pays able economists well.

Another possible benchmark is the $447000 per annum paid to High Court judges.  We need skilled and capable people performing those roles, but there are potentially two layers of appeal above a High Court judge, and none at all above the (collective) decision of the MPC.

But if I don’t have a problem paying a reasonable price for the job, I do have a problem in not disclosing what these decisionmakers are getting paid.   You can readily see from the Annual Report what each member of the Reserve Bank Board gets paid (not that much, but then they don’t do much), and the mandatory disclosure (without names) of all salaries in excess of $100000 gives one a reasonable sense of what the senior managers involved are being paid.   But the government insists that the external members’ fees should remain confidential.  Their argument?

“This is on the basis that it could weaken the Government’s ability to negotiate fee levels by creating an environment where the exceptional fee becomes the norm.”

I don’t find that persuasive, and the secrecy is inconsistent with the sort of openness and transparency we should expect around public appointments.  Frankly, it suggests the government has its fee schedules in the wrong place, at least for substantive roles.

Perhaps the closest parallel to the external MPC members are the comparable positions in the UK.  In fact, the Minister of Finance cites them in his bid to get higher fees for the New Zealand appointees.  But the terms of conditions of UK MPC members are available for all to see.   As the Minister noted

It also noted MPC members at the Bank of England receive around $1900 in New Zealand dollars.

“Reserve Bank of New Zealand external MPC members will require similar economic and analytical skills, although their role is likely to be less public facing,” Robertson said in the letter.

If it is good enough for the UK, not always known for its public sector transparency, it should be the standard of openness we expect here.

There are also some questions around the transparency of the MPC appointment process itself.

As I noted when the appointments were made

But then I’m a bit troubled by the way in which the Board –  all but one appointed by the previous government – ended up delivering to the Minister for his rubber stamp a person who was formally a political adviser in Michael Cullen’s office when Cullen was Minister of Finance (Peter Harris) and another who appears to be right on with the government’s “wellbeing” programme.     They look a lot like the sort of people that a left-wing Minister of Finance –  one close to Michael Cullen –  might have ended up appointing directly……

I’m left wondering what sort of behind-the-scenes dealings went on to secure these appointments. I hope the answer is none. I’d have no particular problem if, while the applications were open, the Minister had encouraged friends or allies to consider applying. I’d be much less comfortable if he had involvement beyond that, prior to actually receiving recommendations from the Board. It isn’t that I disapprove of politicians making appointments, but by law these particular appointment are not ones the Minister is supposed to be able to influence. So any backroom dealing is something it is then hard to hold him to account for. Perhaps nothing went on, but I have lodged a series of Official Information Act requests with the Minister, Treasury, and the Board of the Bank about any contacts (written or oral) between them on this issue.

Since the Act is written in a way that encourages the public to believe that the first time the Minister would even hear of any potential MPC members would be when the nominations landed on his desk from the Board (which he could accept or reject, but not impose his own candidate), the response from the Minister of Finance to my OIA request should have been quick and simple.

Here was my request to the Minister.

I am writing to request copies of all material (written and oral) held by you or your office relating to the appointment of members of the Reserve Bank Monetary Policy Committee.  Without limiting that request, it includes a request for any information relating to any approaches made by you or on your behalf (a) encouraging specific individuals to apply, (b) encouraging the Bank’s Board to nominate or select any particular individual(s), or (c) discouraging the Bank’s Board from nominating any particular person or type of person.

In subsequent contact, it was agreed I wasn’t looking for purely adminstrative stuff (emails like “does anyone know if Bob Buckle has signed hs contract yet?”).

The request was lodged on 29 March.  I had a letter from the Minister last week extending my request to 11 June (so not just 20 working days, or even a 20 working day extension, but a bit beyond even that).  And the justification?  The claimed need to “search through a large quantity of information”.

That certainly does not suggest a Minister of Finance who had taken the sorts of hands-off approach his own brand-new legislation appeared to envisage.  In that case, there would have been nothing to find, nothing to search.  The Minister would have known there was nothing.

In principle, I’m not averse to the Minister of Finance having an active role in such appointments.  In my submission to FEC last year on the amendment bill, I argued that the Minister should have the power to appoint directly (as is typical with most other public appointments, and most other central banks roles in other countries).  The MPC is a major element in short-term economic management, and we expect to be able to hold the minister to account (we can vote against his party, but have no clout over central bankers).  Try to appoint a party hack and expect blowback in public or Parliament.   But the Minister and the Select Committee chose to reject that proposal, and to use the model –   in place for the appointment of the Governor –  in which, on paper, the Minister has no role other than to accept or reject a final recommendation.

It looks as though what we are left with is the worst of both worlds.  The Minister of Finance isn’t keeping out of the process, until the end when he says yea/nay to formal recommedations, but whatever his active involvement it is behind the scenes in ways which make it hard to hold him to account (if second XI type people, or people with strong ideological affinities to the government end up appointed, he can simply say “it was the Board that handed me these nominations”).    It seems to be neither open nor transparent.

I hope that when the Minister finally gets round to responding to the OIA request, the evidence will suggest these concerns are overstated.  But, on what we have to date, the indications aren’t promising.

Transparency was to have been a key aspect of the Reserve Bank reforms.  To date, that is looking patchy at best, around such basics as remuneration and appointment processes.  We can only hope – against hope –  for better on policy and policy communications.


Housing policy failures bear heavily on the poor

Last week a reader sent me the right hand part of this set of charts

aus housing 1

The data are for Australia, but it is hard to believe that, if we had up-to-date census data, the pictures now would be much different for New Zealand.

I’ve seen charts like the left hand one for New Zealand, but what I found sobering –  and frankly scandalous –  were the results for lowest and second lowest quintiles in the right hand chart.

A decent society has to be judged, in considerable part, by how it treats the poorest and most vulnerable among us.    People can run all the clever lines they like about how many of the people in those bottom quintiles have things now that comparable people in 1981 didn’t have.  But it is doesn’t excuse the entirely manmade disaster of the housing markets in New Zealand and Australia (and various other places).

In 1981, when our societies as whole were substantially materially poorer than they are now, (Australia’s real GDP per capita was about 80 per cent higher in 2016 than in 1981), young people at the lower end of the income distribution was just as likely to own their own home as those at the upper end of the income distribution.  But now people at the bottom are less than half as likely to own their own place.  In a well-functioning market that simply wouldn’t have happened. But we –  and Australia –  having housing and urban land markets rigged by central and local government politicians and their officials, and the people at the bottom are the ones who how most severely and adversely affected.

Sometimes people will try to tell you that preferences have changed, such that young(ish) people no longer want to own their own place to the same extent.    But look at how little the home ownership rates for the upper quintiles have changed.  That alone suggests that people are being forced to adjust to new affordability constraints, not that a whole generation of young people – given the opportunity –  no longer prefer to own their own place.

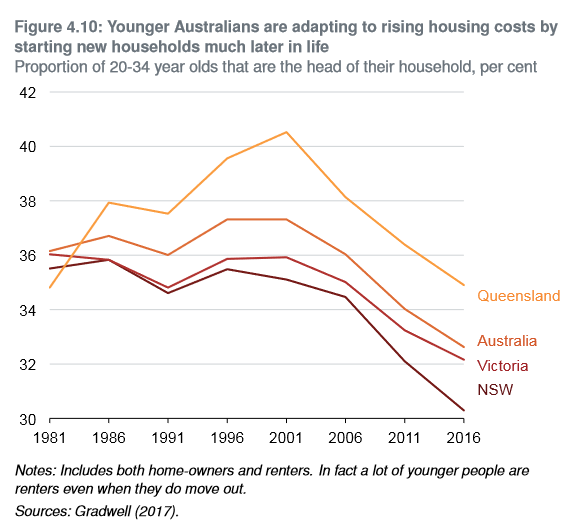
The chart is taken from a pretty substantial report by the Grattan Institute, a centre-left think-tank in Australia.   Flicking through some of the report, I found a couple of other charts.

One of the ways of adjusting to new, artificial, affordability constraints is simply to stay living at home for longer.

aus housing 2

Another is to get financial support from family.

aus housing 3

Back when real incomes were half what they are now (1970s), most people (in all quintiles) buying a first house by the time they were 34.  Now only about 35 per cent of lower income people are buying a first house by the time they are 44, and a much increased share of the (reduced percentage) buying a first home at all are needing financial help from family (presumably mostly) to do so.

There is simply no need for any of this –  the more so in a decade in which interest rates (and thus mortgage servicing costs) are lower than they been for generations.  It is what our governments have done to us, most notably to the poor among us.   It is shameful.

There are no excuses.  One day, those responsible (from both sides of politics) will face the judgement of history for their active complicitly, or quiet indifference.

And no, a capital gains tax would have made no material difference to any of these outcomes –  these are, recall, Australia data, and Australia had no CGT in 1981 but does now.  But perhaps some of the passion that fired those now so upset with the Prime Minister did reflect a sense of the failure of leadership in addressing this fundamental, longrunning, failure of policy around housing and urban land.  There is a real opportunity for the Prime Minister –  or for the Opposition –  to take a decisive policy lead, and actually make a change for the good, for the poor in particular.

(Not) reforming the calendar

A few weeks ago I was pottering in a local secondhand book shop and stumbled on Time Counts: The Story of the Calendar published in 1954 and written by British journalist Harold Watkins.   There was quite a bit of interesting history in the book –  including around the belated British adoption of the Gregorian calendar – but the main purpose of the book was to champion the then-rising cause of calendar reform.   The foreword was by Lord Merthyr, chairman of the British section of something called the World Calendar Association.

I’d never even known there was such a movement, which wasn’t just a marginal group of nutters and obsessives.   Their cause had been taken up by the League of Nations in the inter-war period, and at the United Nations in the late 1940s and early 1950s.    Numerous governments weighed in, mostly either supporting or somewhat indifferent to, the cause of calendar reform (in New Zealand’s case, the Labour government of the late 1940s had declared in favour).   At the time The Story of the Calender was published, it seemed as if there was a real prospect of reform.  But it didn’t happen.

It is hard to get inside the thinking of serious people who championed reform in a cause which has since died away almost completely.  Granting that the Gregorian calendar is an approximation (think leap years, and the adjustments at ends of centuries and of every four hundred years, and it is still an approximation) quite what was the practical concern?    What seemed to bother the advocates of reform was things like the irregular number of days in each quarter, the fact that any particular date falls on a different day of the week in successive years (you can’t immediately know that the 15th of July is, say, a Wednesday) and –  of course (and I’ll come back to this topic) – the moveable feast of Easter.  Oh, and you need a new calendar every year.

The first two of these simply don’t seem very burdensome at all.  But I guess that a key difference between now and 1954 is that we live in the age of ubiquitous computing power (smart phones in almost every pocket or hand-bag).  If, for some reason, I’m signing a contract maturing on 15 July 2099 –  and I wish to avoid weekends – it takes me perhaps five seconds to find that that will be a Wednesday.    If I’m analysing sales or production, seasonal adjustment procedures with trading day adjustments are relatively readily available, and so on.  And, on the other hand, there is something nice about not having one’s birthday celebration fall on, say, a Monday every year of one’s life.  And I rather like the fact that Christmas isn’t always on the same day of the week –  perhaps it is just what one is used to –  even if does mean that every year newspaper stories comparing retail volumes in the days leading up to Christmas are less valid than the publishers like to think because precise retail patterns depend to some extent on how close Christmas Day falls to the preceeding weekend.

Anyway, the reformers thought all these were significant issues worth addressing, and they managed to persuade a fair number of the governments of the world (from east and west, Christian origins and not) to go along.  There were, we are told, a bunch of different reform options, but support was greatest for the so-called World Calendar.    Here is a summary of what they were championing

The World Calendar is a 12-month, perennial calendar with equal quarters.

Each quarter begins on Sunday and ends on Saturday. The quarters are equal: each has exactly 91 days, 13 weeks or 3 months. The three months have 31, 30, 30 days respectively. Each quarter begins with the 31-day months of January, April, July, or October.

The World Calendar also has the following two additional days to maintain the same new year days as the Gregorian calendar.

Worldsday
The last day of the year following Saturday 30 December. This additional day is dated “W” and named Worldsday, a year-end world holiday. It is followed by Sunday, 1 January in the new year.
Leapyear Day
This day is similarly added at the end of the second quarter in leap years. It is also dated “W” and named Leapyear Day. It is followed by Sunday, 1 July within the same year.

The World Calendar treats Worldsday and Leapyear Day as a 24-hour waiting period before resuming the calendar again. These off-calendar days, also known as “intercalary days”, are not assigned weekday designations. They are intended to be treated as holidays.

And so each time 1 January would be a Sunday a few years hence, the reformers pursued their cause with renewed energy.    At the time this book was published, the next such occasion was 1 January 1956.  The transition to the new system would be most seamless if the world moved to the new system on a 1 January that was a Sunday.

It would be fascinating if someone were to write a proper scholarly history of this movement (I can’t find much when I looked), but it seems that all the enthusiasm finally came to naught because of religious objections –  religions, notably Christianity and Judaism – that worship on a seven day cycle.  Each regular week would still only have seven days, but around two additional days, weeks would have eight days.  Gathering to worship on the following (in the Christian case) day labelled “Sunday” would no longer be seven days since the last gathering (or the day of worship – and rest –  would drift off the official weekends).

I presume this was one of those issues on which zealots on both sides cared greatly, and few other people cared very much at all, which left the status quo in place by default.  The US Congress appears to have been responsible for the effective block on any action, when the US recommended in 1955 that the United Nations take the matter no further.   The Wikipedia entry on the World Calendar proposal records this statement from then-Congressman (later President) Gerald Ford.

“… I have received numerous letters in opposition to the proposed world calendar change. I am in complete agreement with the opinions expressed in these letters and I will oppose any calendar change. The Department of State advises me that the United Nations may set up a study group on calendar reform. Secretary John Foster Dulles and our representatives at the U. N. are not in favor of this action and the United States will officially oppose setting up this U.N. study group on calendar reform. I have also been informed that our State Department will hold to that position until there is Congressional authorization for the calendar study. From my observations it seems that Congress is in no mood to tamper with the calendar.”

And that, it seems, was pretty much that.  Apparently there is still a World Calendar Association, but it appears to be almost as unknown as its cause.

But what of the moveable feast of Easter (and associated days such as Ash Wednesday and Ascension, also public holidays in some countries)?   The Christian festival, and associated holidays, move around from year to year in a way that no ordinary person can really fathom, and we all simply have to look up the dates.  Some years Easter marks the end of the school term, others not.  Some years it falls in March and others in April and seasonal adjustment never quite captures all the effects.   And of course even with the wider Christian church (and Christian-shaped countries) there are competing dates for Easter –  the Orthodox churches mostly observe Easter next weekend.

Frankly, there probably is a case for a different model, at least if the (interested bits of the) world could snap their collective fingers and be with that model rather than the current one.  There would be some symbolic advantages for churches –  across the world celebrating Easter, the greatest festival of our faith, on the same day –  and some convenience for the rest of society, residually Christian or totally indifferent/opposed.

I had learned a few years ago that there was a strong movement back in the 1920s and 1930s to standardise the date of Easter.  But until I read Time Counts I was not aware that there is a law on the UK statute books, passed in 1928, to standardise the date of Easter Day to the first Sunday after the second Saturday in April (roughly the middle of the period in which Easter can now fall).  The law (a private member’s bill, following on from a League of Nations report) received the royal assent and sits on the books today (you can read it for yourself –  it is a very short law).  The change would have applied in the UK and its colonies and mandated territories, but not (of course –  but it is explicitly spelled out in a schedule to the Act) in the dominions (New Zealand, Australia, Canada, Newfoundland, Ireland, South Africa) or in India or Southern Rhodesia.

The law sits on the statute books today but the (UK) date of Easter didn’t change, because the operative provision required another vote of Parliament, which never occurred.

This Act shall commence and come into operation on such date as may be fixed by Order of His extent. Majesty in Council, provided that, before any such Order in Council is made, a draft thereof shall be laid before both Houses of Parliament, and the Order shall not be made unless both Houses by resolution approve the draft either without modification or with modifications to which both Houses agree, but upon such approval being given the order may be made in the form in which it has been so approved : Provided further that, before making such draft order, regard shall be had to any opinion officially expressed by any Church or other Christian body.

And that has never happened.  You can read more here about some of what happened (and didn’t) subsequently.  The short answer is that the Christian churches have never reached general agreement on change, and although they don’t have a legal veto, in practice successive British governments have taken the view that legal change can’t run ahead of the churches.  In practice, I guess the law is now really just an historical oddity – not unrelated to the fact that England has an established church.  The British government simply can’t, in practical terms, unilaterally change Easter.

If, in some sense, the (affected bits of the) world might be a little better off with standardisation, it isn’t easy to see a way forward that will actually result in change.  Apart from anything else, it is a coordination issue: change is only likely if all the (major) Christian traditions, and all or most of the countries where Easter-related public holidays are on the books agreed together to make the change.   And in highly-secularised societies such as our own, it is rather more likely that there would be support to scrap Easter public holidays altogether (perhaps replace them with a couple of other days scattered across the year) rather than to legislate new and permanent dates.  And institutional churches are hardly likely to favour change without the assurance that the public holidays would be shifted (even recognising places like the US where Good Friday isn’t a holiday at all).   And there would probably be vocal minorities –  including in the US (recall 1955)  – of Christians opposed to any change to Easter dates at all.  If we knew, with confidence, the exact date on which the crucifixion occurred, perhaps standardisation would be easier…..but we don’t.

(Of course, in a New Zealand context, we get the tiny minority of ACT supporters sometimes championing abolishing statutory holidays altogether, to be replaced with additional leave entitlements, but that is simply never going to happen –  and nor in my view should it (regardless of whether the existing holidays have Christian roots or not).)

And so I expect that even if I live to 100, we’ll still be operating on the Gregorian calendar, and for all its endearing oddity, Easter will still be a moveable feast.


Critics of the Governor

There have been a couple of media stories this week that were less than flattering about the Governor of the Reserve Bank, Adrian Orr.  I was going to say “new Governor”, but checking the calendar I see that in another month or so he will be a quarter of the way through his first term.

The first story was by Stuff’s Hamish Rutherford, and centred on the Governor’s plan to require banks to greatly increase the share of their assets funded by equity rather than debt.   In the on-line version of the story, Orr is labelled “Mr Congeniality”.  The story begins this way

Since Adrian Orr became Governor of the Reserve Bank of New Zealand he has built a reputation of being someone who likes to be liked.

Charming and jocular, but possibly sensitive to criticism.

But Orr is now in a battle with the bulk of New Zealand’s banking sector in a way which could see him demonised, probably with the focus on lending to farmers.

He knows it. Recent days have seen Orr on a campaign to explain itself.

I’m not sure he seems any different as Governor than he ever was before –  his well-known strengths and weaknesses have continued to be on display.

I’ve written quite a lot here about the substance and process around the Bank’s capital proposals – starting with the apparent lack of consultation and coordination with APRA, through to the weaknesses of many of the arguments the Bank advances, the lack of apparent understanding of how financial crises come to occur, the grudging and gradual release of further supporting material, and (presumably partly as a result) two extensions to the deadline for submissions.

In the article Orr is quoted thus, in perhaps the understatement of the week

The consultation process, in Orr’s words “could have been tidier”.

Done properly there would have been extensive workshopping of the technical material over months before the Governor ever put his name to a specific proposal.   As it is, we have a half-baked proposals, not benefiting from any prior scrutiny, and yet the same Governor who put the proposal forward is now judge and jury in his own case, with no effective rights of appeal for anyone.    And there is big money involved –  not just the additional capital that might need to be raised, but probable losses in economic output that will affect us all to a greater or lesser extent.

Presumably no one in the industry would go on record for Rutherford’s article.  Not upsetting prickly Governors is an art the banks have sought to master (even when it involved pandering to an earlier Governor who wanted a senior bank economist censored), although presumably the banks’ submissions will be fairly forthright.  (But will the public ever see those submissions?)

But some of the tone of the off-the-record concern is there in the article

Sources across several of the major banks are warning that if the bank pushes ahead with its plan it could act as a significant constraint on lending to farmers and small businesses,  sectors which are as economically important as they are politically sensitive

Both sectors are considered risky and when capital requirements go up the impact will be magnified.

Why those sectors?  Well, the “big end of town” (Fonterra, Air New Zealand or whoever) will have no difficulty raising debt either directly (bond market) or from banks that aren’t subject to the Reserve Bank’s capital requirements (which means every other bank in the world not operating here, as well as the parents of the locally-incorporated banks operating here).  And the residential mortgage market is both pretty competitive (including from some local institutional players that are less badly hit by the Governor’s proposals than the big banks), and more open to the possibilities of securitisation (which would then avoid the capital requirements too).   Idiosyncratic small and medium loans (including farm loans) aren’t, and farm loans in particular require a level of industry knowledge that newcomers won’t acquire easily (and offshore parents often won’t have).

Perhaps these effects will be large, perhaps they will be quite moderate in the end. But the point Rutherford didn’t make, but could have, is that none of this was analysed in the Bank’s consultative document.   When a really major change is proposed we should surely expect a serious analysis of transitional paths (not just for the banks, but for customers and the economy) as well as the long run.  But there was almost nothing, and nothing in any more depth has emerged in subsequent material that has seeped out.

It simply isn’t a good policy process, and that should concern both the Minister of Finance (and his advisers at The Treasury) and the Bank’s board.   The Governor simply isn’t doing a good job on this front.  If there is a compelling case for what he proposes, he hasn’t made it.  And that is almost as bad –  in a serious independent regulator –  as not having a good case in the first place.

The second article was by the news agency Reuters.   The focus in that article is Orr’s conduct of monetary policy, and particular his policy communications (which many had expected to be one of his strengths).

There are at least two strands to the article.  There are criticisms of Orr for not yet having given a single substantive on-the-record speech on either of his main areas of policy responsibility (monetary policy and financial regulation).  I’m among those quoted

Michael Reddell, an ex-RBNZ official who served with Orr on its monetary policy committee in the 1990s and 2000s, is critical of Orr for not giving a “substantive” speech on monetary policy in the past year.

“It would be unthinkable in Australia or the United States or even under previous governors here.”

I’ve been more and more surprised at the omission as time went on.  And in respect of monetary policy it is not as if there has been much from his offsiders either.  Sure, we get the rather formulaic paint-by-numbers Monetary Policy Statement every few months, but it simply isn’t the same as a thoughtful carefully-developed speech –  which shows more of how the individual/institution is thinking, and the omission has been particularly significant given that we had a new Governor and a refined mandate.

Orr’s response to this criticism is reportedly that it is “thin”.   Whatever that means, the fact remains that in other countries top central bankers talk, quite frequently, about their thinking in on-the-record speeches.  I’ve suggested, speculatively, that perhaps he doesn’t do serious speeches on core areas of responsibility because he just isn’t that interested (saving his passion for infrastructure, climate change, diversity, and all manner of other stuff he has little or no responsibility for).  I’d  like to be wrong on that, but nothing in this article provides any countervailing evidence.

But the bigger criticism in the Reuters article appears to come from financial market participants, concerned that they aren’t able to read the Governor’s policy intentions well.

Many traders who spoke to Reuters in the past two weeks blame Orr for confusing the message, and some have even been critical of frequent references to legends of the indigenous Maori people in his speeches, saying they served little purpose for financial markets eager for more policy clues.
“I am extremely frustrated at the lack of communications for global market participants,” said Annette Beacher, Singapore-based macro-strategist for TD Securities.
“Since Adrian Orr has assumed the role, he’s managed to surprise the market every six weeks. We don’t hear anything from him in between policy decisions,” Beacher said, echoing similar complaints from others.
“So what do I recommend to my trading desk? I’m saying trade the data but we’re not quite sure what is going to happen at the next meeting. It’s not meant to be this way.”

Here, to be honest, I’m not sure quite what to make of the criticism (I mostly don’t hang out with international markets people).   I’m sure there is a great deal of eye-rolling at the tree god nonsense that Orr continues to champion, but perhaps here the longstanding central banker in me comes out and I wonder if the offshore market people aren’t being a little precious.    Markets should not need their hands held to anything like the extent some of the comments in the article suggest, and if there is a little noise in market prices as a result that isn’t necessarily a bad thing.

It seems that quite a few people the journalists talked to were grumpy about the move to an explicit easing bias at the last OCR review, I couldn’t help wondering how much of that was a disagreement with the Governor’s stance (market economists on average have been more hawkish than the Bank for years, and have been more wrong) and how much a sense that a forthcoming change hadn’t been signalled.  I was bit (pleasantly) surprised myself by the move to an easing bias, but mostly because I thought the Governor wouldn’t want to launch a change of direction days before the new MPC took over.  Perhaps that is one of the circumstances in which advance signalling  might have been appropriate?    And perhaps the two strands of concern come together here: we shouldn’t have the Governor or senior staff giving private previews to select contacts about their evolving thinking.  So it has to be serious interviews or serious speeches –  and, as Annette Beacher notes, we haven’t really had either.

The Bank has probably also suffered somewhat from being in transition. At the start of last year, they lost the ultimate safe pair of hands, longserving Deputy Governor Grant Spencer.  A new top-team took over, and within a few months Orr was restructuring, which included demoting longserving chief economist John McDermott.  He lingered for a few months before leaving entirely, but can’t have been entirely engaged.  The head of financial markets was also ousted, and it was only in late March that the new recruits started to take office.  As I’ve noted previously, on the monetary policy side of the Bank it is very much a case now of a Second XI at play (internals and externals) and there is now quite a challenge in getting communications onto a steady, sustainable, and functional path.   The goal shouldn’t be keeping overseas economists happy, but it is perhaps telling that Reuters couldn’t find a domestic one willing to go on the record defending the Orr approach.

What of the Governor’s response to all this?  I’ve already recorded his response to the concern about speeches.  Here is some of the rest of what he told Reuters

In an interview with Reuters earlier on Tuesday, Orr said he wants to reach out to a wider audience than just currency traders, analysts and bloggers.

“The broad audience for this bank is the public of New Zealand. We are seen as a trusted institution but they don’t know what we do. So that is my communication challenge,” he said.

Orr also defended the Maori references in his speeches as part of the bank’s efforts to reach out to wider groups.

“Metaphors have their limits and metaphors can be over used. I get all that, but metaphors need to be introduced and created sometimes.”

I quite get that he wants to communicate to people beyond just the likes of Annette Beacher or me.    But it is not much short of populism to pretend that the audience of people who do pay close attention to the Bank, and know something about it and other central banks (and can even think through the aptness or otherwise of his metaphors), don’t matter.  He can try to appeal over the head of the relatively knowledgable all he likes, but I suspect he won’t find many listening.  Most people have better –  more interesting and important to them –  things to do with their lives.  As it happens, the Governor released a while ago a record of which audiences he delivered speeches to last year, and despite all the rhetoric –  tree god and all –   I was a bit surprised by how relatively few and conventional the audiences were.  The only novelty seemed to be a lot of mention of the tree god – cue to eyes rolling from many of the audiences no doubt.   How many more readers, I wonder, have the cartoon versions of the MPS and FSRs won?  How many have tried twice?

There is a “retail communication” dimension to the Reserve Bank’s role –  when you are driving interest rate up (or down) and affecting people’s employment prospects, business profitability etc, you have to explain yourself.  Over 30 years of an independent Reserve Bank, successive Governors have done a great deal of it –  Don Brash almost to the point of exhaustion, in his nationwide roadshows.  But the core of the job is actually rather more “wholesale” in nature.  And the Governor doesn’t seem to have been getting that right –  at all re bank capital, and in some dimensions re monetary policy (I’m probably closer to his bottom line on the OCR than many other commentators).  All this should be a concern for the Minister of Finance, and for the Bank’s Board.

There is still time for the Governor to right the ship –  and perhaps the new MPC will end up helping –  but the signs aren’t good. Only this morning, a press release emerged from the Bank championing the cause of climate change.  Action may well be really important, but it just isn’t the core business –  or really any business at all in a New Zealand context, with the sort of loan book New Zealand banks have –  of the Reserve Bank.  It is what we have an elected government for.

Sadly, we can expect to hear more from the Governor on climate change and his tree god (flawed) metaphor, and there is no sign of any contrition around the lack of serious communication from him on monetary policy or (where he is still sole decisionmaker) financial sector regulation.


Reading the RBA FSR on bank capital

One of the frustrating things about the Reserve Bank’s consultation on its proposal to greatly increase the amount of capital (locally incorporated) banks have to have to conduct their current level of business in New Zealand, is its utter refusal to produce any serious analysis comparing and contrasting their proposals to the rules (actual and prospective) in Australia.   The larger New Zealand banks are, after all, quite substantial subsidiaries of the very same Australian banking groups.    If there is a case to be made either that the New Zealand proposals are not more materially demanding than those in Australia, or that, if they are, there is a sound economic case for our regulators to take a materially more demanding stance than their Australian counterparts, surely you would expect that a regulator serious about consultation, allegedly open to persuasion (and working for a government that once boasted that it would be the “most open and transparent”) would make such a case.   But months have gone on and there has been nothing.

It is striking that over the entire period when the consultation has been open we have not had a Financial Stability Report from the Reserve Bank (I guess it is just the way the timing worked, but still…).      With proposals out for consultation that would force banks to have much higher risk-weighted capital ratios, working to the statutory goal focused on the soundness of the financial system, you’d have to assume that any FSR would conclude that the financial system at present was really quite rickety.   Perhaps they will when the next FSR comes out late next month, but (a) it would be a very big change of message from past FSRs, and thus (b) I’m not expecting anything of the sort.

A reader pointed out that the Reserve Bank of Australia released its latest Financial Stability Review last week.   The RBA isn’t the regulator of the financial system, but works closely with APRA, and has some systemic responsibilities (including the analysis and reporting ones reflected in the FSRs).   Capital requirements (on both sides of the Tasman) feature in the chapter on the Australian financial system.

The discussion starts this way (ADI = Australian deposit-taking institution).

RBA 1

You’ll recall that the Reserve Bank of New Zealand’s proposal would (a) require major banks to have a minimum CET1 ratio of 16 per cent of risk-weighted assets, and (b) would measure risk-weighted assets in a more demanding way than Australia does.

Here is graph 3.6 –  a really nice chart with lots of information in a small space.

RBA 2

The first panel is the one of most relevance here, relating as it does to the four banks that have major operations in New Zealand.   The regulatory minima are shown in the two shades of purple, and the additional capital held above those regulatory minima is in blue.   Three of the four banks are already at the “unquestionably strong” benchmark level.

I also found the the second panel (other listed deposit-taking entities) interesting.  In a post earlier in the year, I suggested that too-big-to-fail arguments weren’t a compelling reason for higher minimum regulatory capital requirements, as there wasn’t obvious evidence that entities that no one regarded as too-big-to-fail were required by market pressures to have capital ratios materially above those prevailing at larger institutions.   This chart may suggest this point holds in Australia too (deposit insurance muddies the water, but does not apply to wholesale creditors).

The RBA discussion goes on

rba 3.png

with a footnote elaborating the point

RBA 4

Unlike the Reserve Bank of New Zealand, they don’t just claim it is hard to do international comparisons, and then blame copyright to defend not presenting any analysis.    And APRA has actually published its analysis comparing  the way risk weights etc are applied in Australia and other countries.

So the Reserve Bank of Australia (and, presumably, APRA) claims that the capital ratios applying to the major Australian banking groups are in the upper quartile internationally, based on actual CET1 ratios of “only” around 10.5 per cent.   The Reserve Bank of New Zealand, by contrast, has tried to claim –  with no real analysis, just a bit of gubernatorial arm-waving –  that its proposed CET1 minima of 16 per cent (measured materially more conservatively again) would also be inside the range of requirements in other advanced countries, probably also in the upper quartile.

At a substantive level, the two claims are just not consistent.    Perhaps the Australian authorities are wrong in their claims, but I doubt it.  I could advance several reasons to have more confidence in the Australia regulators’ claims:

  • they have a much deeper pool of expertise than the Reserve Bank of New Zealand, and two agencies (RBA and APRA) able to peer review work in the area before it is published,
  • the Australian parent banking groups are all listed companies and there is considerable broker analytical resource devoted to monitoring and making sense of the performance of those banks and the constraints on them,
  • for what they are worth, the credit ratings of the Australian banking groups are consistent with them having capital ratios and risk profiles in the upper (safer) part of the distribution of advanced country banks,
  • the Reserve Bank of New Zealand has simply avoided the Australian comparisons in all the material it has released (so far).

Whatever the absolute position, we can be totally confident that the Reserve Bank of New Zealand’s CET1 minima are far more demanding than those APRA applies to the Australian banking groups  (16 per cent minimum –  perhaps 17-18 per cent actual –  vs the benchmark actual of 10.5 per cent in Australia, where the New Zealand requirements will be measured in a more conservative way.  Not one shred of argumentation has been advanced by the Reserve Bank of New Zealand to explain why they, in their wisdom, think New Zealand banks need so much higher risk-weighted capital ratios.   There might be a case to be made –  something about risk profiles, or reckless Australian regulators perhaps –  but they just haven’t made it  (and it would have to be a pretty compelling case given that the major New Zealand banks have large parents –  to whom the regulator might expect to look in a crisis –  whereas the Australian banking groups don’t).   That simply isn’t good enough.

The RBA goes on to discuss the Reserve Bank of New Zealand’s proposals.

rba 5

That text correctly notes not suggest that the headline CET1 ratios required here would be much larger than those applying to the Australian banking groups, but would be measured in a more conservative way than has been the case hitherto (and more conservatively than APRA will be allowing Australian banks to do).

The rest of the paragraph interested me, especially that final sentence.  It appears to suggest that the rules would apply differently depending whether the capital of the New Zealand subsidiaries was increased through retained earnings or through a direct subscription of new equity by the parent.  In economic substance the two are the same, and regulatory provisions should be drawn in a way that reflects the substance.  But the paragraph is perhaps a reminder that one possibility open to the Australian parents, if the Reserve Bank persists with its proposals, is a divestment in full or in part.  Comments from the Reserve Bank Governor and Deputy Governor have suggested that they would not be averse to such an outcome, and might even welcome it.  I think a much less cavalier approach is warranted and that the New Zealand generally benefits from having banks which are part of much larger groups.

The RBA discussion also has a chart show bank profits in Australia since 2006 (I truncated a bigger chart so the dates aren’t showing).

rba 6

As they note, return on equity is less than it was in the mid-2000s, not inconsistent with the higher capital ratios (reduced variance of earnings) in place now.     The (simple) chart is perhaps consistent with the Reserve Bank of New Zealand’s story that banks will come to accept lower ROEs on their New Zealand operations over time if higher capital ratios are imposed, but (a) the transition may still be difficult (especially for sectors with few competing lenders), and (b) there is no guarantee, since shareholders will focus on overall group risk/return, not the standalone characteristics of one individual unlisted subsidiary.

Part of the Reserve Bank of New Zealand’s attempt to obfuscate the Australian comparisons is to muddy the waters by suggesting something along the lines of ‘total capital requirements will end up being much the same, but our banks will have much better quality capital’.

As you can see from their own text, the Australian authorities put much more weight on the core (CET1) ratios, where Australia’s (quite demanding by international standards) expectations will be a lot less than those proposed for New Zealand.  But the Reserve Bank of Australia text touches on the additional loss-absorbing capital as well.

RBA 7

RBA 8

Here is the summary of the APRA proposals.  These additional requirements, if confirmed, would be able to be met with ‘any form of capital’, including (for example) the contingent-convertible bonds (typically hold by wholesale investors, and which convert to equity in certain pre-specificed distress conditions) which the Reserve Bank of New Zealand has taken such a dim view of (to disallow for capital purposes).  This additional loss-absorbing capacity is typically regarded as much cheaper than CET1 capital, and (coming on top of upper quartile CET1 funding) serves just as well in protecting the interests of creditors in the event of a failure of a major financial institution.   For any banking regulator interested at all in efficiency that should count strongly in its favour, but even more so in New Zealand where the big banks are subsidiaries of the Australian banking groups, failures will inevitably (and rightly) be handled on a trans-Tasman basis, and where most of what matters is securing a substantial share of residual assets for New Zealand depositors and creditors.

But even allowing for all that, look at the nice summary chart from APRA of their proposals

APRA 1

If fully implemented:

  • the APRA proposal for Australian banking groups would amount to a 16 per cent total capital ratio requirement, with risk-weighted assets measured the Australian way, while
  • by contrast, the Reserve Bank of New Zealand proposal would involve a 16 per cent CET1 capital ratio minimum requirement (8 per cent in Australia – the CET1 and CCB components), with risk-weighted assets measured the New Zealand way, and
  • the Reserve Bank proposal include a plan to raise the minimum risk-weights (in a not unsensible way, considered in isolation) that would mean a 16 per cent CET1 requirement in New Zealand might be equivalent to something like 19 per cent range in Australia.  The proposed floor –  risk-weighted assets calculated using internal models, relative to the standardised approach –  in Australia is, in line with Basle III. 72.5 per cent, and the RBNZ is proposing a 90 per cent floor: apply a ratio of 90/72.5 to give an indication of the scale of the possible effect).

The simple summary is that (even if the Reserve Bank of New Zealand ends up scrapping any Tier 2 capital requirements, and it seems quite ambivalent about them in the consultation document) its capital requirements will be (a) materially higher than those applied to Australia to the parent banking groups, (b) materially more costly, because of a largely-irrational aversion to forms of capital other than CET1, even though we have good reason to take seriously the claims of the Australian authorities (and the sense of the rating agencies) that Australian banks are already among the better-capitalised in the world.

In hundreds of pages of material, slowly released over several months, the Reserve Bank of New Zealand has not provided a shred of evidence, or even argumentation, for why locally-incorporated banks operating here should face such an additional regulatory burden, with the attendant economic risks and costs.  Add in the refusal of the Bank to provide a decent cost-benefit analysis as part of the consultation (they promise only at the end of it all, when there is no further chance for public input, and no appeals), and there are few grounds to have confidence in what the Governor (prosecutor, judge, and jury –  with no appeal court) in his own case is suggesting.   We should expect better. The Minister of Finance (and the supine Board) should be demanding more.

For anyone in Wellington next week and interested, Ian Harrison (who used to do a lot of the Reserve Bank modelling work around bank capital) is doing a lunchtime lecture/seminar on the Reserve Bank proposals next Wednesday.   You might think I’m fairly critical of the Reserve Bank. Ian is more so, and tells me he has chased every reference in every document the Bank has published in support of its case, and still isn’t remotely persuaded of the merits of the Governor’s claims.

“We don’t tax businesses highly” and other misrepresentations

As we wait to learn where the government has setttled on the idea of a capital gains tax, Radio New Zealand had an interview this morning in which their presenter Guyon Espiner talked to a business lobby group opponent (John Milford of the Wellington Chamber of Commerce) of a capital gains tax.   I’m someone who is, at best, sceptical of the merits (and potential revenue gains) of a CGT, but it wasn’t the most effective case made against such a tax.

But what really prompted me to pay attention was when Milford argued that business was already quite highly taxed.  The interviewer responded along the lines of “oh, come on, the company tax rate of 28 per cent isn’t high at all”, and Milford simply let it pass and moved off to a claim that regulatory burdens and other costs were high.

We should not lose sight of the fact that we have one of the highest statutory company tax rates of any OECD country.  Here are the OECD’s own numbers for 2019 (incorporating all levels of government –  some countries, including the US, have state level company taxes as well as national ones).

corporate tax 2019

As almost everyone knows, headline corporate tax rates can mask a multitude of exemptions and deductions.  So here is the data on the tax collected on the “income, profits, and capital gains” of corporates, expressed as a share of GDP.  Data on actual tax collections takes time to compile, so these data are for 2017.

corp tax 2017

In this particular year, we took the second highest share of GDP in corporate tax revenue.      That rank bobs around a bit from year to year (in the year the Tax Working Group used in their discussion document, we ranked number 1) and it appears to matter a bit whether countries collect taxes from central government entities or not (we do), but no one seriously questions that however one looks at things, New Zealand is one of the handful of countries collecting the highest tax (share of GDP) from corporates.

The picture is further complicated by the fact that New Zealand (and Australia, but almost no one else) runs a dividend imputation scheme, such that for domestic resident shareholders (only), corporate tax is really a withholding tax, and tax paid at the corporate level is credited against the shareholder’s personal tax liability. In most other countries there is a double taxation issue (profits and dividends are taxed with no offsetting credits), and partly as a result dividend payout rates tend to be lower.  (This, incidentally, is one reason why there is a stronger case for a CGT in other countries than there is in New Zealand or Australia.)

Incidentally, here is how corporate tax revenue (same measure as in the previous chart) in New Zealand compares with that of the median OECD country over 50+ years.

corp tax hist

If anything, the gap appears to have been widening over the last 25 years or so.

It is worth remembering here that New Zealand is not, by OECD, standards a highly taxed country.  Over that entire 50 year period we’ve been around the median OECD country for total tax revenue as a share of GDP (currently just a bit below).   We also have relatively low levels of capital in our production processes (recall low rates of business investment, relative to population growth, over many decades), and yet we raise among the largest share of GDP from companies of any OECD country.

We also get quite a lot of revenue from taxes on good and services (mostly GST here).

G&S tax

We are also a bit above the median OECD country in the share of GDP taken in property taxes (mostly local authority rates, levied on property).

And, by contrast, the area where New Zealand collects hardly any tax revenue at all, as a share of GDP.

soc security taxes.png

I can’t highlight the New Zealand bar.  There isn’t one.  On this definition, we collect nothing (on other definitions one might include ACC levies, but their equivalent is presumably also excluded in the calculations for other countries).

Most advanced countries fund a significant chunk of their welfare systems (unemployment, disability, age pension) with explicit social security taxes, typically levied only on labour earnings (although some are directly paid by employees, and some directly by employers).  Of course, as the chart indicates there is a wide range in practices, but we (and Australia) are at one extreme, and partly in consequence we are the two OECD countries taking the largest share of total tax revenue in corporate taxes.

Does all this have much bearing on the case for a CGT?  Personally, I don’t think so.   A decent CGT –  that didn’t tax pure inflation and allowed proper loss-offsetting –  would be expected to raise very little revenue over time.   If there is an argument for a CGT it is mostly in some conception of “fairness”, which needs to be weighed up against problems such as lock-in, and of the consequent biasing of asset holdings towards big institutional entities and away from individuals.

But don’t try to use as an argument for a CGT that business activity in New Zealand is lightly taxed.  It isn’t.  In absolute terms, business tax revenue as a share of GDP is currently well above the average for the last 50 years.  In international comparative terms, we tax business activity more heavily than almost OECD country –  and perhaps it isn’t entirely coincidental that we sometimes anguish about why we don’t have more business activity.

I listened to more of Morning Report than usual this morning (kneading hot cross bun dough as I did) and had the misfortune to hear Business New Zealand chief executive commenting on government proposals to crackdown on the “exploitation” of migrant workers.  I haven’t looked into the details, so have no view on the substantive merits of the specific proposals (sympathetic as I am to the cause generally).  But people shouldn’t be able to advance their cause with straight-out lies.  Kirk Hope claimed that what the government was proposing was quite inappropriate in part because we currently have “record low” unemployment.   Perhaps his memory is short, but Business NZ used to have an economist who could have briefed him.  In the absence of that person, here are the data

U historical

Perhaps you might want to discount the first 20 years (although it was a real phenonenon), but current unemployment rates haven’t even reached the lows we managed for several years prior to the last recession.   And these days older workers (aged over 65) are a much larger share of the labour force, and naturally tend to have a materially lower unemployment rate (in other words, what might have been unsustainably low 15 years ago, is probably rather more sustainable now).