A few coronavirus economic policy points

I’m staggered at how the government and most of the media still seem to have a backward-looking approach to coronavirus, and the economic effects thereof.  When the New South Wales Minister of Health yesterday indicated that in his view successful containment was now very unlikely, one might have supposed this would be big news in New Zealand.  After all, not only are there lots of New Zealanders in Sydney, but lots of people travel to and fro each day, and there are no restrictions or isolation requirements on those travellers.  If –  and it is presumably still an if –  containment is not likely to be successful in Sydney then surely, given that we haven’t had travel restrictions up to now and are unlikely to put them in place on Australia, it isn’t likely to be successful here.  It was, after all, the Prime Minister the other day who talked (loosely no doubt) in terms of a “common border”.     But I haven’t seen or heard of any comment from any of our political leaders, and no media outlet I follow has highlighted the story even though –  if it is so –  it must have material implications for how life might unfold here very quickly.  (For example, there is a community festival just down the road from here on Sunday, which annually attracts 80000 people in a pretty confined space. I don’t go, but people who are planning to might want to rethink.)

On issues of substance most of our political leaders seem either missing in action or, again, mostly backward-looking, as if coronavirus is something that happened in China and we are now just working through over the next few months/quarters the economic consequences of what has already happened.   On the evidence to date it is far from obvious that the Prime Minister has what it takes to lead and effectively drive the national response to an emerging, highly uncertain, serious ongoing crisis.  The Minister of Health seems to be missing in action (which, one hears, is often how officials thought of him in normal times).  And who else is there?   Kelvin Davis? Winston Peters? Phil Twyford?   I’ve heard suggestions that Grant Robertson “gets it”, but there continues to be great reason to doubt that, whether in his speech last week, his Q&A interview at the weekend, or one with Mike Hosking this morning.  It is all focused on stuff that has already happened, and the outworkings of that, and not at all on the worsening outlook, and the near-certainty of huge disruption and cost when community outbreak becomes a thing here.    Thus he continues to talk about “measured proportionate sectoral” responses, when in reality much the economy is likely to be overwhelmed for a time by what is unfolding.  You get no sense of that from Robertson.

I was initially supportive of the travel ban the government put in place several weeks ago.  It seemed prudent, and of course the Chinese government had put its own restrictions on outbound tourism.  I see quite a lot of commentary about how that ban “bought us time” or “kept the virus out for several weeks”, and I guess in years to come researchers will try to unpick the evidence on that one.  But I must confess to being a bit more sceptical now than I was.  Canada, for example, had no travel bans of its own, and yet when I checked this morning they had about eight times as many cases as New Zealand…..and almost eight times the population.  (And are not far from Seattle).  Neither country seems to have done a great deal of testing, so it isn’t simply that one country was finding more because it was searching harder.   It is impossible to easily know the counterfactual, of course, but perhaps the horse had already bolted by the time the travel bans were put on?  Again, superfically it isn’t obvious that the UK experience (no bans) has been worse at this point than the Australia or US experience.

Consistent with my post yesterday, I remain deeply sceptical of sectorally-targeted or admin-intensive specific government interventions to assist.   I see that in today’s Herald Hamish Rutherford is championing those sorts of programmes, under a subheading “Govt must act now to help hurting sectors take heart”.   Frankly, it is never the government’s job to help firms or sectors “take heart”.  The head has to be what is engaged in times like this.     Debate around these issues isn’t helped by an ongoing refusal, pretty much all round, to call what is happening right now what it is: an economic recession.    We might not have hard data on that point for months (even March quarter GDP includes January where there was little or no effect) but here, now, in March it seems almost certain that the level of economic activity is falling.  It is almost certain to fall further, perhaps at times a long way.    Forget about every other sector, all the supply chain disruptions etc and just focus for a moment on travel.  These were some forward travel booking numbers for Australia published in The Australian this morning.

“Between Feb 24 & March 1, year-on-year, bookings were down 47% from UK, 52% from the US, 71% from Indonesia, 32% from India and 100% from China and Japan, along with widespread cancellations.”

Is there any reason to suppose the New Zealand picture would be much different?   Uncertainty is the enemy of new investment, and uncertainty –  pure uncertainty, not just risk –  is extreme at present.  At present, not even the Leader of the Opposition is willing –  quite –  to call a spade a spade.

In recessions, bad stuff happens.  Firms fail.  People lose their jobs.  Plans are wrecked or disrupted. Asset prices fall.  Government revenue takes a hit.  (Government financial assets fall in value: see NZSF).  It isn’t pleasant, and usually those who bear the brunt aren’t in any very direct sense causally responsible for what happens to them, or their firms.    Much of the argument for focused sectoral action –  there is a lot of this in Rutherford’s article –  is along the lines that unless all these firms and jobs are saved now, recovery will be materially harder than it needs to be: the capacity mightn’t be there to take up the recovery in demand.  But, again, all recessions are like that.  But it isn’t as if the capital stock is going away.  Motelliers in Queenstown might go bust – I saw one this morning quoted as saying he could cope with downturn in Chinese numbers, but it would be problematic if others stopped “and that now looks as if it is happening”.  But the motel will still be there.  A jetboat or paragliding or whatever company might fail –  and that is tough, the flipside of the success operators capture in unanticipated boom times –  but the physical equipment and the location are still there.  And since this seems to be a worldwide thing, even if staff have to move and look for other jobs, many (or a next generation) will be quickly enticed back for whatever drew them to (say) tourist work in the first place.

And while it might have been easy a few weeks ago to identify specific firms that had lost directly associated with the virus, those numbers are rapidly going to be overwhelmed as the effects spread across the entire economy  – just as surely, if indirectly, the result of the coronavirus, and measures to manage/avoid it.   In recessions, for example, property markets tend to do badly –  see the 15 per cent fall in real house prices in New Zealand in 2008/09 despite a 400bps fall in mortgage rates – turnover will drop etc etc, and real estate agents will quite genuinely be able to blame the coronavirus for the slowdown.

You simply can’t sensibly target each firm/sector in the economy.  It is why we have macro policy –  economywide instruments designed to do what can be done to stabilise the downturn (that may not be much) and then lay a platform for as fast a recovery in demand and activity as can be achieved.   As it is, it is simply bizarre that with all that is observably different since, say, December, and all that is pretty visible just down the track, our macro policy settings are barely changed:  short-term wholesale and retail interest rates haven’t moved, nothing about (short-term impacting) fiscal policy has changed, the exchange rate is certainly a bit lower (but a modest move by historical standards) and on the other hand it is likely that credit conditions are tighter than they were.   There is an urgency about action, but that action should primarily be focused at the macroeconomic level.

And, finally today, I have been wondering how one might do an analysis of just what economic price is worth paying, as a society, to try to contain/manage coronavirus.  The Chinese economy and society seems to have paid a fearsome price and yet to have successfully (for now anyway) kept the worst of the spread of the disease in Hubei province (for anyone doubting the logic, I found this thread from a China-focused researcher helpful).

Serious scholars suggest that if the virus were simply left unchecked, it might infect 40 to 70 per cent of the world’s population (say 50 per cent).  For all the uncertainty about the true death rate, assume for the sake of argument 1 per cent of those infected.  In New Zealand terms, that is a potential total of early deaths of 25000.

According to the Treasury’s CBAx spreadsheet, the value of a statistical life (price community would pay to avoid premature death) this year is just on $5m.   25000 people at $5m each is $125 billion.  However, the evidence so far – including the Chinese data –  is that the deaths are very concentrated among older people.   On the Chinese data –  which may have its weaknesses –  the median age of those dying looks to have been as high as the late 70s, whereas the median age for all New Zealanders last year was 37.3. Remaining life expectancy at 80 seems to be about a quarter of that at 37, so we can chop down that maximum possible saving (from avoiding premature deaths) to no more than, say, $31 billion.

But, of course, even that is too high, since the implicit assumption is that all those lives could be saved with appropriate policy responses.  And from everything I read that seems incredibly unlikely.  Often people seem to talk about using policy measures and costly private actions (distancing etc) to spread out peaks and reduce the intense, perhaps overwhelming, peak pressures on the health system, and thereby (a) reduce the number of deaths and (b) make the whole experience less intolerable for those who would die anyway and those who, while sick, live.   Obviously I have no idea how many lives might be saved in total, but no one seems to seriously suppose it is anything like all of them.  If it was half, it would –  all else equal – be worth spending $15 billion or so to avoid those premature deaths.

Of course, if we could reduce the number of those who got seriously ill (but didn’t die) as well, it would be fair to ascribe a value to that too, but if people are up and about again in a month –  or even two –  that number will be swamped by the costs of death, given that in many cases those getting the virus won’t themselves be that sick at all (bad colds seem to be “one of those things” in life).

This is mostly by way of leading up to the question of how large would be discretionary economic costs be.  Note that I emphasise the word discretionary.  What other countries do as a matter of policy, and what other individuals do as a matter of prudence/fear is largely outside our control.  Thus almost all –  the exception perhaps being around university students – the economic effects so far are outside our control, and so is the temporary collapse in the rest of our tourism industry currently getting underway.  We will pay –  in lost output –  those costs whatever New Zealand governments do.  If major cities in other countries shut down for weeks at a time, disrupting travel, supply chains, demand for commodities or whatever, we have no real control over that.   Annual GDP at present is around $300bn.  It isn’t hard to envisage a scenario, quite outside our control, in which GDP for this year as a whole is perhaps $10bn less than otherwise.  That is income/wealth that will never be made up, even if/when after the crisis we get back ont a pre-crisis path.

The big choices are likely to be around how early/aggressively our authorities choose to act in shutting down cities, discouraging (or banning) social gathering, restricting movement etc etc.  We don’t really have hard data for other places yet, but what we know of the Chinese data suggests that these costs too could be very substantial –  not only has much of China been closed for six weeks already, but they are a long way from being back to normal, and with no idea what sort of virus resurgence they would see if they tried.  Shutdown, possibly pre-emptively (if still possible), much of New Zealand at different times for, say, six weeks at time.  In doing so, you could easily cut GDP during those shutdowns by 50 per cent.  Even if things quickly got back to normal after that, you’d still be looking at, say, 5 per cent loss of GDP for the year as a whole.  5 per cent of GDP is $15 billion, lost and never coming back.

I’m not attempting to offer answers here.  There are so many imponderables, most especially about what difference the toughest sustainable measures can eventually make to the death toll.   But it would be good to think that some of those “brightest New Zealanders” Hamish Rutherford told us were beavering away on these issues have at least been trying to think about the options in a systematic cost-benefit sort of way (here I emphasise the past tense, since time would appear to be of the essence, and you would hope officials haven’t shared in their masters’ public-facing sunny optimism about the threats we face). But if they haven’t done it yet, they need to be doing so now, urgently.


Take a macro approach

There has been quite a bit of coverage in the last few days of business lobbies calling for special assistance to cope with the economic effects of the coronavirus to date, and signs too that the government is proving at least somewhat responsive.  In the Herald the PM is quoted as saying that the government will waive the standdown period –  typically a week – for those seeking to move onto a welfare benefit “because of the impact of Covid-19”.  In Parliament yesterday (emphasis added):

Rt Hon JACINDA ARDERN: I’m not going to make a prediction that no other economist is currently making or, indeed, Treasury. We are not predicting, but we are planning and preparing, because that is what we, of course, need to do in order to support those regions, in particular, that are most likely to be affected. We know those are likely to be—Gisborne, Hawke’s Bay, Tasman, and Marlborough are amongst the most exposed, particularly looking at the—

Hon Simon Bridges: It’s every small business in New Zealand.

Rt Hon JACINDA ARDERN:—impacts in China. But some analysis, obviously, Mr Bridges, demonstrates those impacts are particularly acute there, and then across the board for the likes of tourism and hospitality. In each of those regions we are looking to create tailored packages of support. That’s something that our Minister for Economic Development is currently working on.

In addition to all the other firms/sectors looking for assistance, there is a full page article in the Herald on the difficulties facing the tourism and hospitality sectors, including calls for wage subsidies.

Unfortunately, much of the way the Prime Minister talks about the issue –  and the Minister of Health on the health side –  suggests that the government is still acting as if coronavirus is a very bad thing (which, of course, it is) which has already happened somewhere else –  affecting our economy of course – and now it is really just a matter of time, albeit perhaps quite some months, until things get back to normal.  (It all seems consistent with the tone of the Director-General of Health who continues to play down the health risk in New Zealand, and – in public anyway –  to take the most short-term positive spin on almost every story/risk.  That matters because it suggests something of a government-wide mindset, with implications for the economic and economic policy issues that are my focus.)

In all the talk of this subsidy, that specific assistance, this tailored regional programme, no leading politician or official seems willing to front the fact that, difficult and costly as things have been so far for some individuals/firms/sectors, the only prudent approach is to plan on the basis that things will most probably get a lot worse before they get better.  It is fine to work on the basis that in a couple of years time things are likely to be more or less back to normal (as regards health/virus etc).  But two years is a long time away, and there is likely to be a great deal of disruption, uncertainty, and loss before we emerge safely on the other side.

Even if somehow the Ministry of Health was right and significant community outbreaks really don’t happen here, there still seem to be plenty of new and worsening ones abroad.  Even if China inches back towards normality –  and you could check out the new Caixin article on people just making stuff up there, about economic activity, to comply with top-down expectations –  much of the rest of the world seems to be heading in the opposite direction.  It isn’t just supply chains involving China, or tourists from China etc that we –  and others –  need to worry about.   If we do get significant outbreaks here we will have a whole new level of domestic disruption and loss (economic and other) as the measures –  imposed and self-chosen –  to manage the situation take hold.   Whole cities could come to a near-halt for non-trivial periods.

Frankly, it seems bizarre to be focusing on “tailored region specific packages” in this environment.  It looks remarkably backward-looking (focused on the stuff that has already happened), and to be not taking anywhere near enough account of the wider risks.  I presume somewhere in the Beehive or the upper levels of officialdom some people actually realise the magnitude of the issue/threat, and are taking it into account in their advice on specific policy proposals.  But there is no sign of that stuff in any of the outward-facing talk –  least of all from the Prime Minister.

Much of the talk seems influenced by the earthquake experiences, both Christchurch (especially after February 2011 and Kaikoura).   In particular, people talk positively about the short-term wage subsidies offered to some firms to help keep people connected to the labour market etc.  I think that, in passing, I have even referred favourably to that experience myself.  But it is a bad way of framing the current issue for a number of reasons:

  • trivially, Kaikoura was/is very small.  Whatever was done for people/firms there had no economywide implications,
  • second, and much more importantly, the nature of the shock and economic loss being dealt with was known.  Thus, although people fairly point out that there were aftershocks, and even worries about severe ones, when there were major earthquakes in Christchurch no one worried that there would be a big one –  or Rangitoto erupting –  the followng week/month in Auckland.
  • third, allowing for the aftershocks point, the worst event had already happened by the time the special programmes were launched.  We couldn’t be 100% sure of that at the time, but it is still a stark contrast to the situation we face now re Covid-19,
  • fourth, the earthquake shocks were known, from day 1, to be going to trigger a really significant boost to aggregate demand (repair and reconstruction) in and around the severely affected regions.  Activity might not resume quickly in some individual and specific sectors, but before too long there would be lots of jobs in total, and thus lots of wider demand.
  • fifth, even Christchurch was only about a tenth of the country.

By contrast this time, we know very little, and what we do know does not portend any great boost to demand and employment just a little over the horizon.   There could –  quite probably will – be very serious disruptions to come, perhaps across the economy as a whole.  Individual sector interventions are unlikely to scale effectively, and interventions announced now –  perhaps in some generous cast of mind – could very quickly be overwhelmed by the pressures of more serious widespread disruption and losses, whereby those “lucky” enough to be hit first-  in this case those who made themselves most dependent on one market, the PRC –  get the easiest largesse.

(I’m not even convinced of the case for suspending the standdown period.  This is a recession. We might hope it is brief.  It might be no one here’s fault. But most recessions aren’t in any way the fault of most of the individuals who bear the brunt of the downturns, and actually the best thing for people thrown out of work early is to reconnect to the labour market as soon as possible, perhaps before the labour market in aggregate gets much worse.  But this particular policy, because it can presumably be applied more or less with the flick of a switch (if it is avowedly temporary, and not tied to proving a Covid-19 connection), bothers me less than suggested admin-heavy targeted interventions, which might make good political theatre this week, but which could quickly look rather beside the point.)

And it isn’t as if these sort of tweaked tools are going to go to the heart of the issues either.  As I noted yesterday

Even direct short-term assistance won’t do much to slow the deterioration of economic aggregates –  won’t summon up more tourists, won’t fill gaps in supply chains, won’t offset the decline in spending if/when social distancing becomes more imperative.  By and large, we are stuck with whatever deterioration in economic activity the next few months bring, most of which will be events almost totally outside our control (overseas economic activity and the spread of the virus abroad and here).

If specific tailored micro policies aren’t the thing, that isn’t to suggest policymakers should be sitting idle.  Rather, macroeconomic measures with systematic whole economy effects should be in play, either deployed decisively right now –  in the case of monetary policy, which is easy to reverse later if necessary – or ready to go almost instantly as/when the full severity becomes a bit more generally apparent.  If it were me, I’d be suspending the forthcoming minimum wage increase as well –  whatever demand effects champions of high minimum wages might tout, in this environment raising already-high minimum wages will worsen the labour market ruptures politicians etc purport to be concerned about.

I don’t have a full suite of measures.   I still think a temporary reduction in GST has a lot of merit.  Perhaps a temporary (but significant) reduction in one of the lower income tax rates might have appeal –  and would ensure that the income effects to households were distributed relatively evenly.  (Incidentally, for any MMT champions out there, financing is pretty much a non-issue for now present, with long-term nominal bond yields at 1 per cent.)    And despite my general and long-term support for a substantial reduction in New Zealand’s permanent non-citizen migration numbers, I would be very careful to do nothing now to drive those numbers further down (they are likely to fall anyway), consistent with my point that the short-term demand effects of migration materially exceed the supply effects.    And there needs to be some hard-thinking about the potential private debt consequences of the (likely) substantial income losses –  that doesn’t just involve heavying the banks.  Banks, quite reasonably, will be more cautious, many borrowers will inevitably be less able to meet their debts. (The Chicago academic John Cochrane has a piece worth reading on some of those issues.)  (Hobbyhorse issue of mine, but very relevant: there should be action as a matter of urgency to addres, and greatly ease, the effective lower bound on nominal interest rates.)

I’m sure there are other options, that are focused, can readily be kept temporary, and which might plausibly have significant demand effects concentrated this year and perhaps next.    The design of a package with such measures –  econonywide in focus –  is where our economic boffins and their ministers really should be devoting all their design etc efforts at present.

If I’m underwhelmed at the political leadership around these issues, it is perhaps even more worrying to look at the officials and agencies supposed to support the Cabinet.   Our Treasury is led by someone with no New Zealand experience and (more concerningly, as I noted when she was appointed) no experience or background in national economic policymaking.  Our Reserve Bank is led by someone with little demonstrated capacity for deep and innovative thought, who has displayed more interest in things he isn’t responsible for than those he is.  MBIE is led by a former HR manager, and I could go on.  Perhaps there are some exceptionally able people the next tiers down, helping frame big-picture thinking and proposing well-thought-out specifics, but the names don’t really spring to mind.   Our public service (led from SSC, enabled by governments) hasn’t encouraged the fostering of those sorts of capabilities.  Our institutions have been allowed to run down, under successive governments, and we pay the price for that in tough and highly uncertain times.

I suppose I once got the idea that getting on the front foot might unnecessarily scare the horses (voters) and look “panicky”.  That might have seemed a plausible story a month ago, just like the “contained to China, to all intents and purposes” story might have seemed plausible then to some.   But it doesn’t now.  Politicians, officials, and the public need to recognise that things –  including economically –  are likely (few things are ever quite certain) to get much worse at times in the next few months before they get enduringly better.  Policy planning needs to be done on that basis, and “tailored region specific plans” don’t really seem like to cut it, or to be a wise use of scarce policy and adminstrative talent (or political capital for that matter).

Yield curve indicators, monetary policy, and the case for action

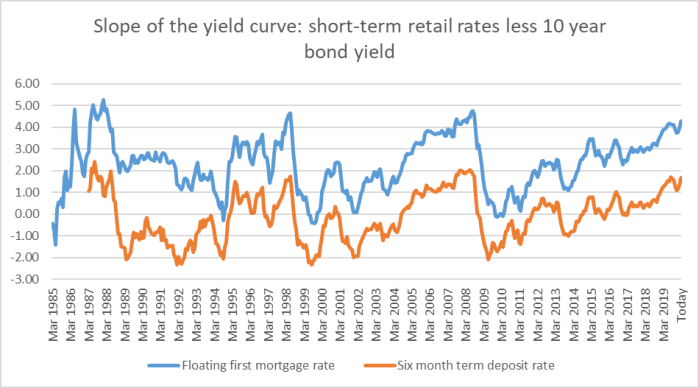
Six months or so ago, shortly after a flurry of attention in the US around the 10 year bond rate dropping below the three-month rate (which had been something of a predictor of weaker economic conditions) I wrote a post here on yield curve indicators in New Zealand.    Once upon a time, we used to pay quite a bit of attention to the relationship between bond yields and 90-day bank bill rates although, as I explain in that post, it isn’t a great indicator of future New Zealand recessions (and wasn’t really used that way when we did pay attention to it).

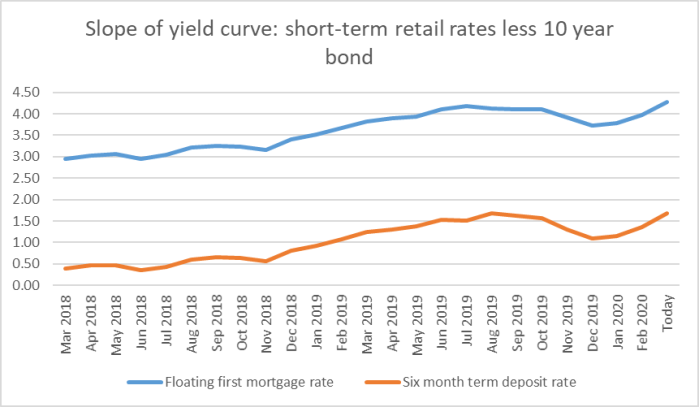
In the post I suggested it might be worth looking at a couple of other yield curve indicators, using the (fairly limited) retail interest rate data the Reserve Bank publishes, comparing short-term retail rates with long-term goverment bond rates.  The absolute levels wouldn’t mean much, but the changes over time might.   Here is a version of those charts updated to today (using current retail rates from interest.co.nz)

yield curve 20 1

and the same chart for just the last two years.

yield curve 20 2

For what it is worth, the only times these lines have been at or above current levels a New Zealand recession has followed.  And although the Reserve Bank interest rates cuts in the middle of last year did reduce the slope of the retail yield curves, we are now sitting right back where we were at the peak last year.

The Reserve Bank is, of course, now strongly expected to cut the OCR this month –  as Australia did yesterday and the US this morning, and as they should have done last month.  But do that and they’ll only take those retail yield curve slopes back to around where we were late last year –  and that on the assumption that long-term bond yields don’t fall materially further.  By historical standards that will look like relatively tight monetary policy, at least on this indicator.    And all that with credit conditions that tightened last year, look likely to tighten further because of the ill-considered capital requirement increases (they were warned about the risks that the transition period would cover, and exacerbate, the next major downturn) and –  despite political rhetoric –  are only likely to tighten further under the cloud of extreme uncertainty and actual/potential income losses currently descending.

In this climate, with the evident sharp slowing in economic activity, it would be more normal to envisage hundreds of basis points of cuts.  But, through official lassitude and a decade focused more on hoped-for rate increases than on the next severe downturn, cuts of that magnitude simply aren’t an option.

The constant pushback against the idea of OCR cuts now (whether last month, right now, or later in the month) is that they won’t achieve anything much in coping with the immediate disruption and the (probable) rapid increases in job losses over the next month or two.   And, of course, that is quite correct.

One also sees pushback using the argument that central banks shouldn’t be responding to share prices, noting that world markets are even now not much off their peaks.  Whatever the merits of that argument abroad –  and in general I don’t stock prices should (directly) drive monetary policy actions –  it is pretty irrelevant here: in all my years of involvement in advising on New Zealand monetary policy, the only time share prices ever really entered deliberations was in October 1987, and even then it was only as a proxy for the serious problems developing just behind the scenes.

But the fact that monetary policy doesn’t have much affect in the very short-term, particular amid really disordered conditions, is really rather beside the point.  If what you care primarily about is the employees and firms directly disrupted, there are plenty of direct options the government can, and probably is, considering.  But that is simply a different issue, even if one that operates in parallel.  Even direct short-term assistance won’t do much to slow the deterioration of economic aggregates –  won’t summon up more tourists, won’t fill gaps in supply chains, won’t offset the decline in spending if/when social distancing becomes more imperative.  By and large, we are stuck with whatever deterioration in economic activity the next few months bring, most of which will be events almost totally outside our control (overseas economic activity and the spread of the virus abroad and here).   We can support individuals to some extent, and perhaps can do something to increase the chances firms will still be there when the pressures pass.

But in many respects, monetary policy is also about the second leg of that. It is about getting in place early –  and providing confidence about –  conditions that will (a) support the recovery of demand as and when the virus problems pass, or settle down, and (b) helping ensure against that the sort of precipitate fall in inflation expectations (in turn confounding the economic challenges) that I warned about in yesterday’s post does not happen.   The importance of early and decisive action is compounded by several things:

  • the physical limits to conventional monetary policy (can’t cut very far, so need decisive early action to keep expectations up),
  • the probable political limits to fiscal policy (see 2008/09 globally)
  • the extreme uncertainty about the course of the virus or the economic consequences (like any city/country, we could face northern Italy or Korean disruption at almost any time),,
  • reasons to doubt just how rapid a recovery in demand will be (perhaps especially in tourism) and the likelihood of some –  growing by the day –  permanent wealth losses

All supported by the fact that, unlike other possible programmes, monetary policy action is readily reversible if the best-case scenario comes to pass.

I find two other thoughts relevant to the discussion.   It seems almost certain that the price-stability consistent interest rate is quite a bit lower than it was just a few months ago.  In normal circumstances, the job of the central bank is to keep policy rates more or less in line with that short-term neutral rate.  It might well be –  but no one knows –  that the fall is temporary, but the Reserve Bank’s job isn’t to back a particular long-term view (they have taken to talking recently far too much about the long-term, when their prime job is really quite short-term, about stabilisation) but to adjust to pressures evident now.

(In the same vein, we also hear the objection that the virus issues are “short-term” and thus no action is warranted.  Quite possibly, perhaps even probably, they are short-term, but so are most of the pressures central banks deal with.  Most recessions for that matter, even most crises.)

And finally, it is worth bearing in mind that many commentators are already highlighting debt service burdens for businesses where activity has fallen away sharply,     There are no easy answers to what the appropriate policy response, if any, is to those issues. But it is worth pointing out that there are likely to be permanent income/wealth losses, even if in a year’s time the path of GDP is back on the pre-crisis course.  Income not earned this year is unlikely to be made up for by more income later.  In the extreme, if the economy largely shut downs in certain cities or regions for a short time –  or if certain sectors (eg foreign tourism) largely shutdown for longer –  those losses will not be made back, and the debt (business and household, bank and non-bank, lease commitments and loans) that was being serviced supported by those actual/expected income flows will still be there.   Those losses have to be (will be) distributed somehow and frankly it seems reasonable that part of that would be by adjustments to servicing burdens.     People will say –  commenters here have –  that 25 basis points is really neither here nor there.  And, of course, that is true.  They will also say that the OCR is “only” 1 per cent –  also true – but retail lending rates are over 5 per cent (floating mortgages) or 9 per cent (SME overdrafts), and in a climate like the present.    Those rates really should be a great deal lower –  at least temporarily –  as, of course, should the adjustable rates being earned by savers/depositors.

Pro-active macro policy would be doing all it can, as soon as it can, whatever additional firm-specific measures the government might also try.  To repeat, the point isn’t to fix the immediate situation –  there is no such fix, absent the magic fairy curing the world of the virus overnight –  but to limit the risk of longer-lasting damage and better position ourselves for what could still be a difficult recovery, with permanent wealth losses.  The Reserve Bank should be taking the lead –  it is conceivable that if they are going to wait until the scheduled review date that even a 100 basis point cut could be under consideration by then –  but there is sufficiently little the Bank can do –  even about that medium-term horizon, that we should have well-targeted and designed effective and prompt fiscal stimulus as well (again focused on the six to eighteen month horizon).  If anyone influential is reading, I commend again –  as one part of a response – the case for looking hard at a temporary cut in GST).


Why economic policymakers need to respond aggressively

Yesterday I dug out some discussion notes I’d written while I was working at The Treasury during and just after the last New Zealand recession.  One of them –  written in June 2010, already a year on from the trough of the global downturn (although as the euro-crisis was really just beginning to emerge) – had the title “How, in some respects, the world looks as vulnerable as it was in 1929/30”.     The point of the “1929/30” was that the worst of the Great Depression was not in the initial downturn from1929 –  which, to many, seemed a more-or-less vanilla event – but from 1931 onwards.    It was only a four or five page note, and went to only a small number of people outside Treasury/Reserve Bank, but in many respects it frames the way I’ve seen the last decade, capturing at least some of issues that still bother me now, and lead me to think that  –  faced with the coronavirus shock –  macro policymakers should err on the side of responding aggressively (monetary and, probably, fiscal policy).

The more serious event –  akin to the 1930s –  didn’t happen in the last decade, at least outside Greece.    At the time, much of the focus of macroeconomic policy discussion  –  including in New Zealand –  was around ideas of rebalancing and deleveraging.    My note pointed out that, starting from 2010, it was very difficult to envisage how those processes could occur successfully over the following few years consistent with something like full employment.     To a first approximation it didn’t happen.  There was fiscal consolidation in many advanced countries, but not material private sector deleveraging. In most OECD countries it took ages –  literally years –  to get the unemployment back to something like the NAIRU.  And, of course, there was a huge leveraging up in China.  In much of the advanced world investment remained very subdued.

There were twin obstacles to getting back to full employment.  On the one hand, short-term policy interest rates in many countries had got about as low as they could go.  And on the other hand there was a view –  justified or not –  that fiscal policy had done its dash, and whether for political or market (or rating agency) reasons, further fiscal stimulus could not be counted on (even in a New Zealand context: I found another note I’d written a year earlier just before the 2009 Budget, which noted of “scope for conventional market-financed fiscal easing” that “our judgement –  more or less endorsed by the IMF and OECD – is that we are more or less at that point [scope exhausted]”.

The advanced world did, eventually, get back to more-or-less full employment.   But the world – advanced world anyway –  never seemed more than one severe shock away from risking dropping into a hole that it would be very hard to get back out of.  The advanced world couldn’t cut short-term interest rates by another 500 basis points.   For a time that argument didn’t have quite as much force as it does now –  when excess capacity was still substantial one could tell a story about not being likely to need so much policy leeway next time –  but that was then.  These days we are back starting from something like full employment.   There was also the idea of unconventional monetary policy instruments: but while some of them did quite some good in the heat of the financial crisis, and in the euro context were used as an expression of the political determination to hold the euro-area together come what may, looking back no one really regards those instruments as particularly adequate substitutes for conventional monetary policy (limited bang for buck, diminishing marginal returns etc).  And then there is fiscal policy.   Few advanced countries are in better fiscal health than they were prior to the last recession –  and New Zealand, reasonably positioned as we are –  is not one of the few, and the political/public will to use huge amounts of fiscal stimulus for a prolonged period remains pretty questionable.

Oh, and there is no new China on the horizon willing and able to have its own massive new credit/investment boom – resources wisely allocated or not – on a global scale to support demand elsewhere.

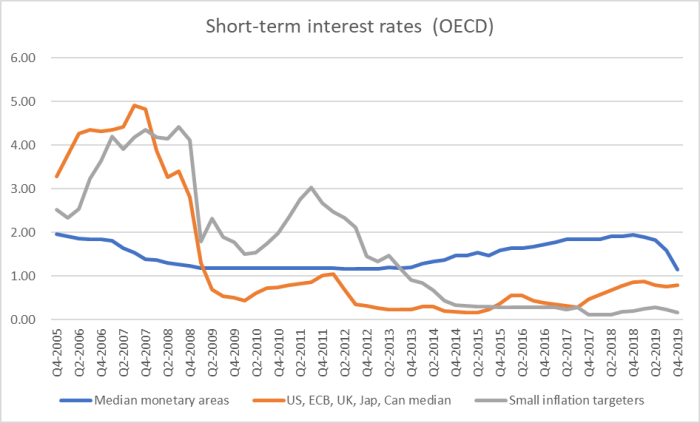
How about that monetary policy room?  Here are median nominal short-term interest rates for various groupings of OECD countries.

short-term 2020

You can see where we are 10 years ago.   Across all the OECD monetary areas (countries with their own monetary policy plus the euro-area) the median policy rate is about where it was then (of the two biggest areas, the US is a bit higher and the euro-area a bit lower).  Same goes for the G7 grouping.  And as for “small inflation targeters” (like New Zealand) those countries typically have much less conventional monetary policy capacity than they had in 2010 (New Zealand, for example, had an OCR of 2.75 per cent when I wrote that earlier note, and is 1 per cent now).

Back then, of course, the conventional view –  not just among markets but also to considerable extent among central banks –  was that before too long things would be back to normal.  Longer-term bond yields hadn’t actually fallen that far.  Here are the same groupings shown for bond yields.

long-term 2020

One could, at a pinch, then envisage central banks acting to pull bond yields down a long way (and with them the private rates that price relative to governments).  These days, not so much.  Much of the advanced world now has near-zero or even negative bond rates.  A traditionally high interest rate country like New Zealand now has a 10 year bond rate around 1 per cent.   Sure those yields can be driven low, but really not that much if/when there is a severe adverse shock.

And 10 years ago if anyone did much worry about these sorts of things –  and there were a few prominent people –  there was always the option of raising global inflation targets.  In the transition that might have supported demand and getting back to full employment. In the medium-term it would have meant a higher base level of nominal interest rates, creating more of a buffer to cope with the next severe adverse shock.   It would have been hard to have delivered, but no country even tried, and now it looks to be far too late (how do you get inflation up, credibly so, when most of your monetary capacity has gone, and it would hard to convince people –  markets –  of your sustained seriousness).

My other point 10 years ago in drawing the Great Depression parallels was that the Great Depression was neither inevitable nor inescapable.  But it happened –  in reality it might have taken inconceivable cross-country coordination to have avoided by the late 1920s –  and it proved very difficult (not technically, but conceptually/politically) to get out of.  The countries that escaped earliest –  the UK as a prime example –  did so through a crisis event, crashing out of the Gold Standard in 1931 that they would have regarded as inconceivable/unacceptable only a matter of months earlier.  For others it was worse –  in New Zealand the decisive break didn’t come until 1933, and even then saw the Minister of Finance resigning in protest.    If we get into a deep hole in the next few years –  international relations generally not being at their warmest and most fraternal, domestic trust in politicians not being at its highest –  it could be exceedingly difficult to get out again.  Look at how long and difficult (including the resistance of central banks to even doing all they could) it proved to be to get back to full employment last time.

In the Great Depression one of the characteristic features was a substantial fall in the price level in most countries.   The servicing burdens of the public and private debt –  substantial in many countries, including New Zealand/Australia –  escalated enormously, and part of the way through/out often involved some debt defaults and debt writedowns.

Substantial drops in the price level seem unlikely in our age.  Japan, for example, struggled with the limits of monetary policy and yet never experiencing spiralling increases in the rates of deflation (of the sort some once worried about).  But equally, inflation expectations ratcheted down consistent with the very low or moderately negative inflation, meaning real interest rates were never able to get materially negative.  Japan at least had the advantage that in the rest of the advanced world, nominal interest rates and the inflation rate were still moderately positive.

That could change in any new severe downturn.  A period of unexpectedly weak demand, with firms, households and markets all realising that authorities don’t really have much useable firepower, could see assumptions/expectations about normal rates of inflation dropping away quite sharply (in New Zealand they fell a lot, from a too-high starting point, last time round, even with unquestioned firepower at our disposal).  In that scenario, authorities would struggle to lower real interest rates at all for long –  falling nominal rates could quite quickly be matched with falling inflation expectations.  As people realise that, it becomes increasingly hard to generate a sustained recovery in demand, and very low or negative inflation risks becoming entrenched.  It isn’t impossible then to envisage unemployment rates staying very high –  unnecessarily and (one hopes) unacceptably high –  for really prolonged periods (check the US experience in the 1930s on that count).  An under-employment “equilibrium” brought by official negligence is adequately dealing with the effective lower bound on nominal interest rates.

I cannot, of course, tell if the current coronavirus is that next severe adverse shock.  But it looks a great deal as though it could be, and the risks are sufficiently asymmetric –  not much chance of inflation blowing out dangerously –  that we shouldn’t be betting that it won’t be.  Some people argue that since the virus will eventually pass for some reason it isn’t as economically serious as other shocks.   That seems wrong.  All shocks and recessions eventually pass –  many last not much more than a year or two  –  and the scale of disruption, and reduction in activity, we are now seeing (whether in the New Zealand tourism and export education industries, or much more severely in northern Italy, Korea and the like) has the potential to markedly reduce economic activity, put renewed downward pressure on inflation and inflation expectations (we see the latter in the bond market already), all accompanied by a grim realisation of just how little firepower authorities really have, or are really politically able to use.  (Ponder that G7 conference call tomorrow, and ask yourself how much effective leeway the ECB has now, compared to 2007, or even 2010. )

Against that backdrop, it would seem foolhardy now not to throw everything at trying to prevent a significant fall in inflation expectations, by providing as much support to demand and economic activity as can be done.   That means monetary policy, to the extent it can be used –  in New Zealand for example, a central bank that was willing to move 50 points last August, on news that was weak but not very dramatically so, should be champing at the bit to cut at least that much this month.  The downside to doing so, in the face of a very real threat to norms around inflation –  and a likely material rise in unemployment – is hard to spot.  And since everyone knows monetary policy has limited capacity –  and those who haven’t realised it yet very soon will –  we need to see fiscal policy deployed in support, in smart, timely, and effective ways.   In some countries it is really hard to envisage that being done well –  the dysfunctional US in the midst of an election campaign, starting with huge deficits –  but there really is no such excuse in countries such as New Zealand and Australia.  (Oh, and of course –  and after all these years –  something needs to be done decisively re easing the effective lower bound.)

(There is, of course, widespread expectations of a huge Chinese stimulus programme.  That is as maybe, although it will bring both its own risks –  domestic ones just kicked a little further down the road –  and the risk of new immediate dislocations, including the possibility of a significant exchange rate depreciation, exporting (as it were) deflationary pressures to the rest of the world.)

We are only one serious adverse shock away from a very threatening economic outlook, where the limits of macro policy would mean it would be difficult to quickly recover from. By the day, the chances that we are already in the early stages of that shock are growing.  Perhaps it will all blow over very quickly, and normality resume, but (a) even if that very fortunate scenario were to eventuate, the risks are asymmetric, and (b) we’d still be left sitting with very low interest rates and typically high debt, one serious adverse shock away from that hole.


Thinking about fiscal policy

A few weeks ago the Minister of Finance announced that the government’s Budget would be delivered on 14 May.    That really isn’t far away now.  I noticed the Minister, on TVNZ’s Q&A yesterday, suggesting the timing was opportune in light of the coronavirus.     Perhaps, but contemplate some relevant dates.   Last year’s Budget was delivered on 30 May and according to the documents these were the relevant deadlines

budget 19

Assuming much the same sort of timetable holds this year, the economic forecasts the Budget draws on will have to be finalised in not much more than three weeks from now.  The tax and other fiscal forecasts are finalised later but they draw on the economic forecasts.  And who supposes that there will be any meaningfully greater certainty in three weeks time than there is now?  In truth, the Budget economic forecasts will be little more than (well, really less than given the long publication lags) one potentially useful scenario.     They simply aren’t going to be –  and can’t be –  any sort of useful guide for policy in the current climate, and I hope the Minister and the Treasury Secretary (the forecasts are Treasury’s and the Secretary has to sign off on them) start making that clear soon.    Consistent with that, in setting budgetary policy no one should be getting hung up on (for instance) whether the bottom line is a small surplus or small deficit.   Any such forecast number –  in a period of extreme uncertainty –  will be just meaningless.

In his interview yesterday the Minister of Finance seemed to be saying much the same sort thing as in his speech on Thursday.   Much of it was, at one level, sensible enough, but to me it fell a long way short in grappling with the likely severity of the issues, and the related uncertainty, and with the vulnerability of the world economy and the limitation of current macro policy.   Perhaps it was partly what he was (wasn’t) asked, but he is an experienced politician and knows how to get across the messages he wants to convey.    When community outbreak becomes a significant thing here, there is going to be a lot of economic disruption (even in the most optimistic cases abroad, eg Singapore, containment so far has appeared to rely on extensive social-distancing –  voluntary and compulsory –  none of which is conducive to holding up short-term GDP (or similar indicators).

But even pending that, what will be happening to tourism right now?  We know tourism from China collapsed a month ago –  first PRC restrictions and then our own –  but what about travel from other markets.  How many people are going to be keen on booking new trips, or even – if they have the option –  embarking on new trips now? I don’t know about you but I flicked through the travel sections of newspapers yesterday and today, wondering quite how many takers there would be.  Allowing for both direct and indirect effects, tourism is estimated to be about 10 per cent of the economy and about 55 per cent that is international tourism.  Even if international tourism only halves for the duration –  and it would be a lot lower than that if there is significant community outbreak here, that alone is equivalent to taking almost 3 per cent out of GDP.   Sure, there is scope for some switching –  more domestic tourism, as New Zealanders pull back on their foreign travel –  but a couple of nights in Picton is for most hardly a substitute for the trip to Disneyland.     And, of course, there are more and more reports of business travel –  typically higher-end – being cancelled.   And all of that is just one sector of the economy: that associated with foreign travel.   It takes no account of scenarios in which people are unable to work, whether because of illness, movement restrictions, school closures or whatever.

There is simply no way of knowing how long or how deep the economic effects will be, or (for example) what public psychology –  including eagerness to spend and to travel –  will be like as the world gets through the other side.  But with strongly asymmetric risks I reckon there is a pretty strong for an aggressive macro policy response.  And some part of that clearly has to be fiscal, especially given the failure of authorities –  here and abroad – to deal with lower bound constraints on monetary policy (covered in my post on Friday).  If you are sceptical that I’m over-egging the monetary policy limits point, I’m not nearly as pessimistic as the local ANZ economics team

Not as pessimistic only in that I think the OCR can usefully be cut further than they believe.  But if they are right and we really will be at the conventional limits of monetary policy by May (the day before the Budget in fact) people really should start worrying, because the ANZ economic scenario is not as bad as it could get.  And there are few additional buffers that people can really count on in planning and forming expectations (including of inflation).

There has been quite a bit of talk about how monetary policy (and aggregate fiscal policy for that matter) can’t solve immediate problems –  even bizarre articles from people who should know better suggesting there is some sort of either/or dimension between medical solutions and macro policy responses.  And that is true, of course.    Macro policy can never deal with the sectoral effects of sectoral-focused shocks.  Macro policy is about stabilising the wider economy.  Macro policy also can’t do a great deal in the very midst of a crisis –  financial or otherwise.  But what it can do in the midst of a crisis –  perhaps especially a disease one, where moral hazard concerns are less of a worry –  is better than nothing (easing servicing burdens, easing the exchange rate, signalling activity, leaning (a little) against collapses in confidence etc).  Perhaps more important is the value of such tools when either the immediate crisis passes and we are left with chronic weakness in demand (perhaps for a few quarters, perhaps longer) and during the recovery phase.   Macro policy tools work with a lag, and it is well to get adjustments in place pretty early (which is why monetary policy flexibility is so good to have: it is a very easy instrument to adjust, including to unwind when the need has clearly passed).

What sort of fiscal policy?   I’m not that interested in specific assistance packages to individual sectors.  In some cases, that sort of action might be justified, but much won’t really be –  and the announcement a couple of weeks ago of funding to promote non-Chinese tourism looks even sillier now.  Realistically, political considerations are likely to be more important than anything else in shaping those sorts of handouts, but (fortunately perhaps) such specific interventions/distortions/bailouts aren’t likely to be large enough to materially respond to wider weaknesses in aggregate demand.

And whatever you think of the case for more – even much more – government infrastructure spending, there are long lags to getting any such projects up and going.  The case for a second Mt Victoria tunnel in Wellington might be rock-solid –  and it is even in Grant Robertson’s constituency – but it is no sensible part of a response to a coronavirus-induced recession, even if (say) you worried about several waves of the virus over a couple of years.

Generalised tax cuts in income tax rates –  which might or might not make sense longer-term –  aren’t particularly effective because (a) the overwhelming bulk of any cut would go to higher-income households, (b) there is no particular incentive to spend (and some of the things higher income people might othewise spend on –  an extra overseas holiday –  aren’t likely to be so attractive in the next few months, and (c) as the Minister observed in his interview yesterday, such cuts tend to be permanent.

One could do, as Hong Kong announced last week, some sort of lump sum distribution –  perhaps $1500 payment to each adult.  It is much more concentrated ($ value) towards people likely to spend additional cash, but it is still less likely to be spent at the height of a crisis than in other circumstances, just because people will be (eg) staying away from shops.  But perhaps a more significant issue is precisely that it is one-off –  you might get a one-month lift to demand and activity, but the situation is reasonably likely to require longer-term support than that.

The point of this past was really to explore one other option I haven’t yet seen mentioned: an explicitly temporary reduction in the rate of GST.     The idea has been around for a while, it was tried by the United Kingdom as part of their macro policy response in 2009, and was discussed in some detail in a paper presented in New Zealand almost 15 years ago by the (then) academic economist Willem Buiter, who had also served as a member of the Bank of England Monetary Policy Committee.

Buiter was invited to New Zealand as part of a focus in the mid-2000s (including this work) looking at possible tools that might enable more downward pressure to be maintained on aggregate demand –  keeping inflation in check –  without the concomitant upward pressure on the real exchange rate; the latter having become something of a sore point with both the Governor and the Minister of Finance.    One element of that involved inviting four international experts to offer advice.  The resulting papers, and discussant comments, are here.  Buiter was invited to focus on fiscal policy issues and his specific paper is here.  One of the options he explored (from p51 at the link) was using a temporary change in the rate of GST.

As a stabilisation option, supplementary to whatever monetary policy can do, a variable GST rate has one very big advantage relative to most fiscal options that are often touted.  Not only does a temporary cut put more money in the pockets of households –  and do so in a moderately progressive way (whatever lifetime consumptions patterns, in any particular period low income people typically spend a larger proportion of that period’s income, and face tighter credit constraints) –  but it provides an active incentive to spend now because you know that prices will be more expensive later.   Take as an example, an announcement that the rate of GST would be lowered by 2.5 percentage points for a year.  For a person/household facing the choice between saving and spending now, at the start of the period, it is akin to a 250 basis point cut in interest rates.  As the year goes on, the (annualised) effect gets even stronger (as we’ve seen with past GST increases, spending is brought forward to just before the increase).

There are all sorts of drawbacks with this instrument in general, whether used for temporary increases or temporary cuts, including judging when it would be appropriate to deploy the instrument (relative to, say, using monetary policy). Buiter favoured an independent committee –  akin to an MPC –  having the power to adjust the rate (something which I’m old-fashioned enough –  only Parliament should change tax rates –  to find abhorent).    But this is an unusually stark situation (and may well be starker still by Budget day) –  as, in a different way, was the UK financial crisis in 2008/09.    It is not just a matter of slowly accumulating pressures (or lack of demand pressures) but a stark, truly exogenous (to the New Zealand economy) event.  Defining a trigger for action shouldn’t really be a problem.  And we are very close to the limits of conventional monetary policy, so the tradeoff-among-instruments questions also presents less starkly than Buiter would have imagined.

One of the other drawbacks –  which the UK ran into –  is defining an exit point.   The period of weak demand around the world lasted much longer than any authorities expected in 2008 when they were devising responses to the financial crisis/recession.    The extent of that weakness was hard, perhaps impossible, to foresee.  With a pandemic virus perhaps it is a little easier – these things tend to sweep through in perhaps 12-18 months (even in 1918) so –  for example – a cut in the GST rate announced/implemented in May, to end at end of 2021 might seem reasonable (while still providing a substitution effect signal).  And if, spare us, at the end of the next year severe problems still faced us, then realistically choices could still be made then about whether to proceed with raising the GST rate or not (to not do so should require new legislation) –  there shouldn’t be (but who can really imagine) the same debates about whose fault it was the banks had failed etc.

One other drawback in the risk to inflation expectations.   Cut the rate of GST by 2.5 percentage points and the level of the CPI will fall by perhaps 2.1 per cent –  and the reported annual rate of inflation will be that much lower than otherwise for a year.   With a heightened risk of inflation expectations sliding away, there is a risk that those headline effects could accentuate the problem, even though none of the core inflation measures –  the ones most analysts emphasise –  would fall.   There is no easy way to know how large this effect would be, and it would be quite circumstance-dependent.  If, for example, the New Zealand dollar fell sharply –  as it usually does in severe adverse global events –  the direct price effects of more expensive imported tradable goods would lean against the GST effect on headline inflation (the UK, for example, had a sharp fall in its exchange rate around 2008/09).  And if the temporary GST cut was part of an aggressive multi-faceted (monetary and fiscal) stabilisation package, the (helpful) demand effects might well outweigh any risks of adverse headline effects on expectations.

The other downside concern might be implementation lags.  When I was around these sorts of discussions, IRD used to emphasise that these sorts of changes couldn’t be done overnight.  Announce on Budget day a GST cut starting three months hence, and the risk is that you worsen things in that three month period.   But when I went back to check the UK experience, I found that the policy had been announced on 24 November 2008, to come into effect on 1 December 2008.    If a change can really be implemented that quickly –  and hard to see why New Zealand IRD should be less capable than HMRC – a one week disruption might be tolerable.

Finally, relative to using monetary policy more heavily, fiscal options will tend to hold up the exchange rate more than otherwise.  That might be less of concern in a scenario in which it has fallen a lot anyway and –  as importantly –  monetary policy options are approaching their limits.

I am not, repeat not, recommending that the rate of GST be temporarily cut, even on the assumption that the economic situations looks as bad or worse late next month when final Budget decisions have to be made.   But, in a highly policy-constrained world, it looks like an option that should be pulled out of mothballs and looked at fairly closely by the Minister’s advisers, including a closer review of the strengths and pitfalls of the UK experience.   In situations like the one we seem to find ourselves in –  with the world one shock away from exhausting normal macro policy capacity, and that shock now seeming to be upon us –  it is probably better to err on the side of doing more rather than less, and to consider taking risks with instruments that would not normally count as ideal (in which category I put the variable GST).

And whether or not the Minister of Finance thinks it an option worth exploring, I’d welcome comments here, including from those closer to the operational details of GST than I am.


On reading the official pandemic plan

I’ve been dipping into the official New Zealand Pandemic Action Plan  –  all 193 pages of it –  a bit in the last few days.  The document has evolved over the years and now describes itself as

This edition of the New Zealand Influenza Pandemic Plan reflects the sophistication of a third generation, risk-based plan that promotes collaboration across all levels of government, agencies and organisations when planning for, responding to and recovery form a pandemic event.

and

Pandemics by their nature are unpredictable in terms of timing, severity and the population groups that are most affected. This version of the New Zealand Influenza Pandemic Plan establishes a framework for action that can readily be adopted and applied to any pandemic, irrespective of the nature of the virus and its severity.

It isn’t really clear what status the document has at present.  It was finalised late in the term of the previous government, it was finalised under a different Director-General of Health, and it was designed for an influenza pandemic, and the current virus is not influenza.    As the Ministry of Health notes, in any case it is only a “framework for action”, and has to be adapted for the particular virus –  and presumably for the policy preferences (on how best to respond, what trade-offs to make etc) of the government of the day.   As a document, or even a framework, it seems most likely to be useful the more closely to health the immediate issues are –  but even then, different virus, different issues.

There are various workstreams described in the plan.  One of them in “Economy” –  something I had quite a bit to do with in earlier iterations of the planning almost 15 years ago now – described from page 48 of the plan.  But it really does no more than list the key relevant official agencies (Treasury, MBIE, Inland Revenue, and Reserve Bank) and a brief plain-vanilla description of the sorts of roles and responsibilities those agencies have.  And that’s it.

The plan itself is dealt with in about 35 pages.  But about a quarter of those aren’t about immediate issues, but about longer-term planning and preparation (important of course, but not the uncertainties we now face).   The “Keep it Out” phase –  the one officials and politicians regard us as being in at present –  then takes another seven pages.    I presume it is mostly worthy and sensible stuff, although there is little or nothing about the frameworks or evidence base used to shape official advice to ministers (eg around border restrictions of the sort we have in place now).

The next phase is “Stamp it Out”

Objective
To control and/or eliminate any clusters that are found in New Zealand.

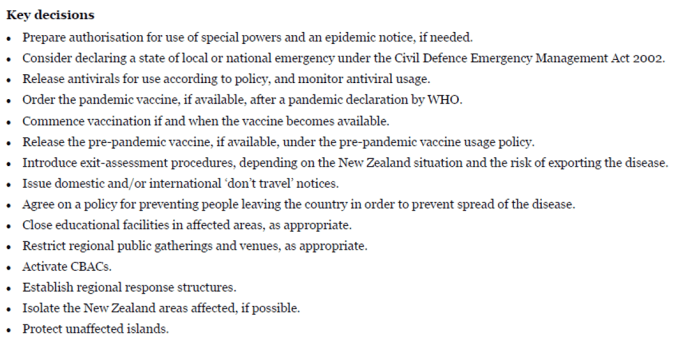
There is a set of key decisions listed

stamp it out

(Many of which won’t be relevant here/now, absent a vaccine)

And there is a detailed listing below that, but it is all lists, and no analytical or policy framework.  One hopes there are more-detailed analytical papers in the Ministry of Health or other agencies, but the Pandemic Action Plan document is what the public has.  The Ministry’s website claims that

The NZIPAP provides information to guide key decision-making.

But really the only information is a listing of issues, agencies, and formal statutory powers. Useful as far it goes, but not that much help –  in particular to the public.

And it is no different in the “Manage It” and “Recovery From It” phases.    Catchy phrases –  useful enough –  and long lists –  again useful enough –  but little substance to guide decisionmaking or public debate/scrutiny of governments plans and actions.

The second half of the document is a little more discursive, and perhaps more useful.   For example, there is a discussion of Public Information Management. But it is limited by the fact that it seems wholly focused on the Ministry of Health, and not on the key role that political leaders (notably the Minister of Health and the Prime Minister) play throughout any pandemic period.    And it is a bit disconcerting when the very first item in the key objectives around public information management

Key objectives are to:
- maintain public confidence in the response and in agencies’ competence and capability

That might be the Ministry’s aim –  pursuing its own interests –  but it isn’t clear it should be what would be most important for the public, who cannot simply assume (need to be shown by transparency, consistency, humility etc) that the response is being well-managed.

The section also seems disturbingly oblivious to both the extent of information available to the public from other countries and public health agencies and to the genuine political choices likely to be faced during the pandemic period.

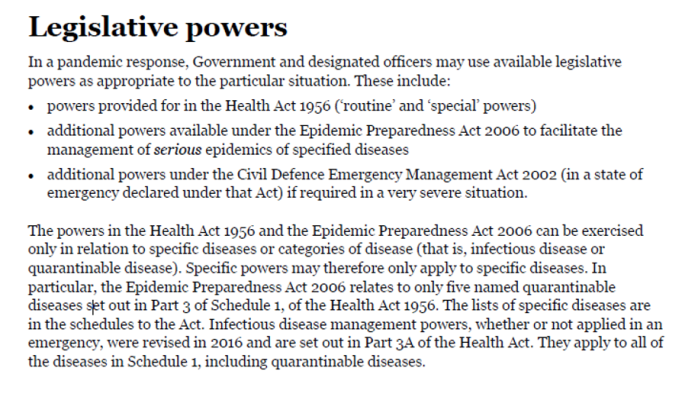
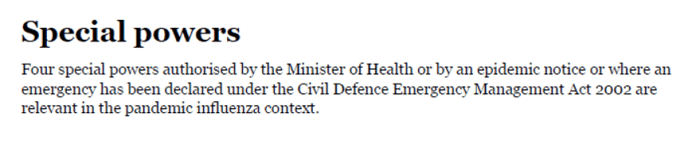
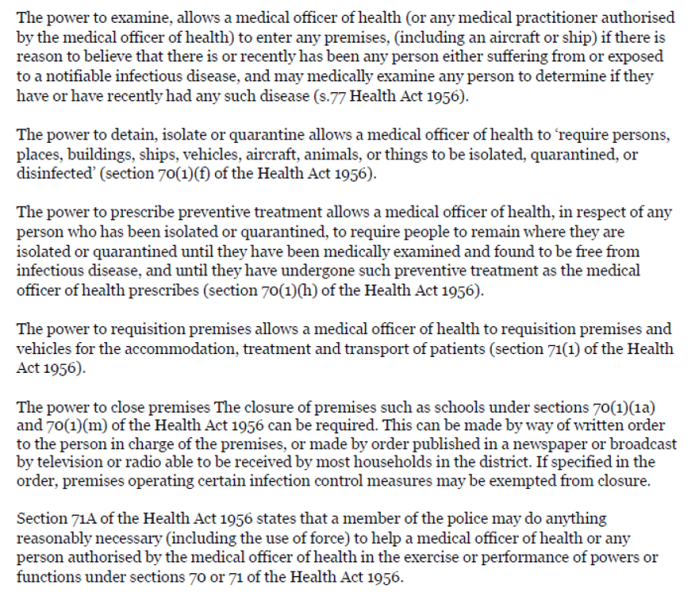
What first took me to the document was a desire to understand the relevant statutory powers and options.  There is what seems to be quite a good description (p109f).    Here is one summary

legis powers

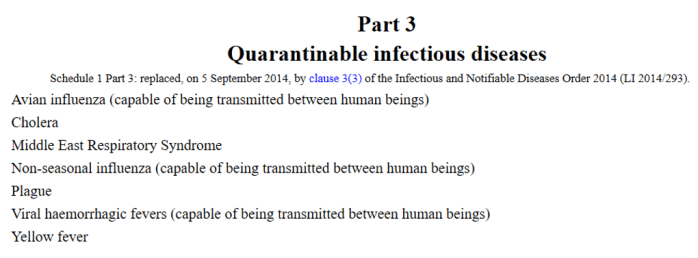
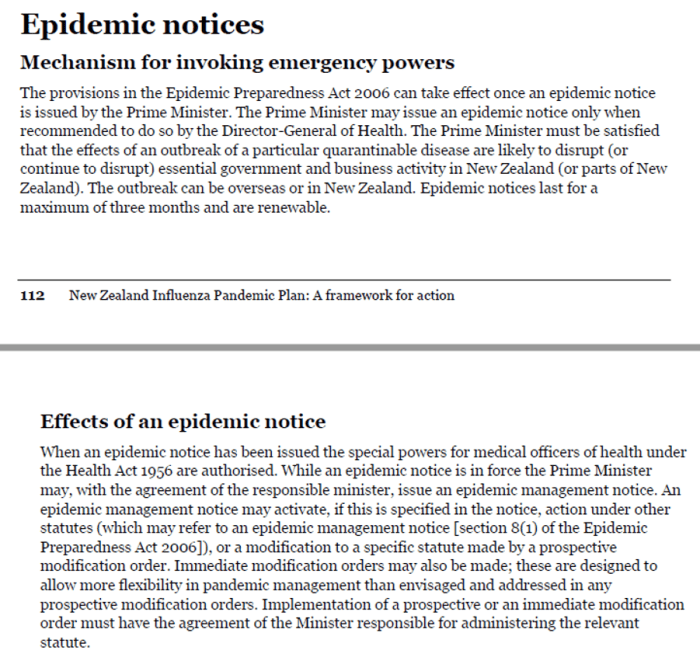
Do note that reference to the Epidemic Preparedness Act.  It has really far-reaching powers, which appear to allow the government to temporarily waive lots of legislation once the Prime Minister issues an authorising notice. But as the Plan says, it relates “only to give named quarantinable diseases set out in Part 3 of Schedule 1 of the Health Act 1956”.

quarantine

Remarkably, this schedule appears to be able to be updated by regulation, rather than by legislation – itself a little worrying given the scale of the powers given to the executive –  but you might suppose it was about time that the current virus was added to the list.

But to take the Health Act special powers first

special 1


special 2

All of which is good to know, but there is no discussion anywhere as to the circumstances, considerations etc that might lead to such powers being exercised.   Now, perhaps one could argue that they would be context-specific, but in a sense that is my point.  In the current context, the Plan itself offers little or guidance to the public, and we have had no guidance, consultation etc specific to the looming event from either the Ministry or (more importantly, since they are the ones we can hold to account) the Minister of Health or the Prime Minister.  (As there was no open discussion of considerations relevant to decisions around border closures, either the initial ones or subsequent decisions.)

And what about that Epidemic Preparedness Act?  Here is what the Plan says

epidemic preparedness act

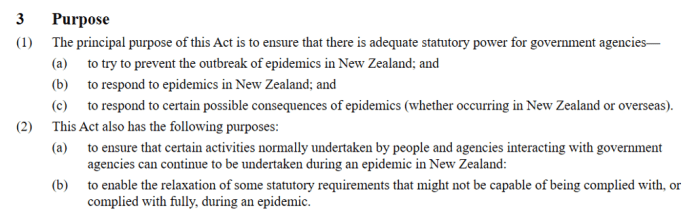
That is quite a mouthful.  The Act itself isn’t long, and if anything I found it a little clearer.  Here is the purpose statement

epidemic act

Such legislative overrides can themselves be disallowed by Parliament, which has to be called together pretty quickly if the Act is invoked –  unless, potentially an issue this year, the House has been dissolved for the election.

My point isn’t to debate whether or not these powers should exist –  although it does seem strange that the criteria relate to “essential government and business activity in New Zealand” (a term itself not defined anywhere, and you have to wonder how the Director-General of Health is qualified to judge what is “essential business activity”) not to human health, societal functioning etc (as well).   My point is that there is nothing in the Plan, and nothing we’ve heard from the officials or politicians on (a) what grounds they would look to invoke this Act, and (b) what statutory requirements they would look to suspend, in what circumstances (for those particularly worried, there are some core Acts they can’t touch).

Perhaps that might be unavoidable if there was a sudden outbreak of some disease with no real warning at all.  But we’ve had time –  now weeks and weeks of it – and there is nothing.  Ministers and officials act in ways that look as though they think “there, there, don’t worry your silly little heads about it, we’ll tell you what you need to know when you need to know it”.   But that is no standard for an open and democratic society.  It doesn’t even really seem consistent with the “public information management” themes, which talk about transparecy, building and maintaining trust.  You do that best by (a) being excellent, (b) being humble, but (c) being open and letting the public in on your thinking and planning, and being responsive to feedback.

As a good example, there is some discussion in the Plan of the possible closure of schools (and similar entities) –  pages 125 and 126 –  but it offers almost nothing.  And, as they note, much will depend on the circumstances of the virus.  In the current episode globally, we’ve seen many countries move to close schools, but one highly-regarded example of management (Singapore) where schools etc have been open throughout.  What is our government’s view on the matter at present, when New Zealand experiences community outbreak?  Surely it matters to the sort of planning individuals etc can/should be doing now.   If universities might end up closed quite soon, might that be relevant to questions around reopening borders to foreign students?   More generally, what is the government’s thinking on the movement restrictions etc being adopted in other democratic countries, notably Italy and South Korea.  Both ministers and officials seem missing in action –  no doubt talking among themselves, but not talking with citizens.

In an Appendix to the document there is a longer Public Information Management Strategy.  Much of it appears sensible enough.  There is even a specific extended section on

Key messages
It looks like a flu pandemic is about to start

Again, a lot of it seems sensible and seems consonant with what we are hearing from health authorities in various other countries. For example

plan

But we aren’t hearing any of this from our officials and ministers, even though –  as we’ve in the last week –  countries have gone from thinking they have no major immediate problem to full-bore crisis in a matter of days.  If anything, the Director-General of Health on RNZ this morning sounded rather Trump-like still talking of low risks of community outbreak in New Zealand  (when plenty of international experts talk in terms of having got well beyond that point everywhere, even if some still think Stamp It Out strategies can work –  viz encouraging signs from Singapore).    They still seem more interested in playing things down –  don’t worry your heads about it –  than in helping guide the public to realistic preparations and precautions, or even to offering substantive answers to specific reasonable questions about how the health system –  under pressure at the best of times –  would be able to step up, add capacity in short order etc when/if significant community outbreak becomes established here.  Perhaps there is a good case for such a choice, but we don’t see the Prime Minister or the Minister of Health even trying to make that case.

And since this blog is still primarily economics-focused, much the same point could be made about economic issues.  The Minister of Finance’s speech the other day seemed okay as far as it went, but it stopped well short of taking seriously the sort of disruption, risks and economic losses, if we see widespread closures (from regulation or fear) when the virus hits here.  There might not be much governments can do in the very short-term if those losses happen, but there are important specific issues, including those around how things like the food distribution system keeps working (if, say, one main city is largely locked-down and movement in and out restricted).

We really deserve and need more pro-active leadership and preparation from key ministers, and perhaps from officials too –  but they mainly work for and to the ministers, whose handling of these event may yet feature significantly in this year’s election campaign.


Preparing

In those distant days when world sharemarkets were still at or very near record highs –  actually, on Monday –  the Federal Reserve Bank of San Francisco released one of their short accessible Economic Letters summarising some research work done last year on the question “Is the Risk of the Lower Bound Reducing Inflation?“.   The views expressed are those of the authors, not the FRBSF let alone the wider Federal Reserve system, but the authors aren’t just fresh out of college either: one is the executive vice-president and head of research (one of the most senior policy positions) at the FRBSF, and the two authors are senior managers on the research side of the Bank of Canada.

Here is their summary

U.S. inflation has remained below the Fed’s 2% goal for over 10 years, averaging about 1.5%. One contributing factor may be the impact from a higher probability of future monetary policy being constrained by the effective lower bound [ELB] on interest rates. Model simulations suggest that this higher risk of hitting the lower bound may lead to lower expectations for future inflation, which in turn reduces inflation compensation for investors. The higher risk may also change household and business spending and pricing behavior. Taken together, these effects contribute to weaker inflation.

How does this work? Here is their description

If monetary policymakers are constrained by the ELB in the future, recessions could be deeper and last longer because central banks may be unable to provide sufficient stimulus. The greater decline in economic activity in this case would translate into lower inflation during such downturns relative to recessions when the policy rate is not close to the lower bound.

In addition, greater risk of returning to the ELB could also affect inflation during good times, when the economy is performing well and interest rates are above the lower bound. Investors and households often care about the future when making long-term investment decisions that are difficult to reverse, such as setting up a new production plant or buying a house. The possibility that recessions might be more severe in the future because of the ELB can affect their economic decisions today, prompting them to be more cautious to guard against this risk. For instance, households could start saving more in anticipation of possible harder times ahead. Similarly, businesses could engage in precautionary pricing by setting lower prices today if they anticipate a greater likelihood of deeper recessions in the future and do not review their pricing strategy frequently.

As something for the future –  perhaps the very near future –  it all seems a plausible tale, and is consistent with a line I’ve been running here for years, that when the next severe downturn comes markets (and other economic agents) will quickly focus on the limitations of conventional monetary policy and adjust their behaviour (for the worse, in cyclical terms) accordingly, deepening and lengthening the downturn.  But these authors go further and posit that people (real economy and financial markets) have already been factoring the ELB risks into their planning and decisionmaking, in turn directly contributing already to lower inflation and lower inflation expectations (than perhaps the current cyclical state of the economy might otherwise deliver).

I haven’t yet read their full working paper so can’t really evaluate the strength of their evidence on this point.  But if they are capturing something important about actual behaviour in the last decade or so, presumably those effects would be expected to have become larger the closer to the present we come.   Prior to 2007 the Fed (and other central banks other than Japan) had not reached the ELB at all. Immediately after the recession there was a pretty strong expectation that things would return to normal (including normal policy interest rates) before too long –  a view typically shared by markets and by central banks.    Only with the passage of time did those expectations gradually fade –  and perhaps more completely in Europe (where policy rates are still often negative, and pretty consistently lower than those in the US).

For New Zealand, of course, if there is anything to this story, it must be even more recent, having started with higher policy rates, and with markets and the Reserve Bank mostly looking towards higher policy rates until just the last couple of years.   The possibility of reaching the ELB in New Zealand has been a distinctly minority point (yours truly and perhaps a few others) for most of the last decade, in ways that leave me a little sceptical that the story will explain anything much of the inflation experience in New Zealand (or Australia) for the decade as a whole. In both countries, inflation has averaged materially below the respective target midpoints.

Whatever the case for the past, the FRBSF note ends with this point

These findings suggest that the puzzle of how to raise inflation to meet central bank goals may require new ways of addressing the risk of returning to the ELB and new ways of understanding how to set and meet inflation goals.

The problem is that there is a growing risk that it is now too late, and that central banks (and Ministries of Finance) have spent the last ten years not getting to grips with ensuring effective capacity for the next severe downturn, leaving things potentially almost paralysed when that severe downturn breaks upon us.  Which it could be doing right now.

Many advanced country central banks can now barely reduce the policy interest rate much at all –  the biggest problem with former Fed governor Kevin Warsh’s call yesterday for a coordinated international rate cut is that it would immediately highlight the limits, especially in Europe.  Even in a traditionally high interest rate country like New Zealand, there is perhaps 150 basis points of capacity, when the average recession in recent decades has involved 500+ basis points of cuts –  a point our Minister of Finance rather glossed over yesterday in his talk of the advantage of starting with relatively high interest rates.

As the FRBSF authors note

To compensate for this lack of conventional firepower, central banks can rely on unconventional policy tools, such as forward guidance or quantitative easing. While these tools proved effective during and following the crisis, it remains unclear whether they can fully compensate for the diminished conventional policy space and the more frequent encounters with the ELB

That is fairly diplomatic speak, as befits senior officials.  In reality, few really believe that unconventional tools under the control of central banks can adequately compensate for lack of conventional policy space.

In my view, those limits have not really been sufficiently focused on by markets, firms and households, or governments.  There has been quite a lot of wishful thinking around –  hankering for higher neutral rates, inability to spot an near-at-hand risk that might trigger an early severe downturn, or whatever.   But when people look at the looming coronavirus risks –  and markets will no doubt ebb and flow still, just as happened as the financial crisis unfolded a decade ago – and really begin to focus on what can, and will, be done, we are likely to see inflation expectations falling away much faster than in a normal downturn, in turn raising real interest rates and accentuating the problems, at a time when neutral interest rates are likely to be falling further (perhaps temporarily, but real enough for the time being).

To bring that back to the New Zealand situation, after ignoring the issue for a long time the Reserve Bank appears to have begun to take it more seriously in the last 18 months or so. But with little or no transparency and no apparent urgency.  We keep being told they are about to reveal their thinking –  I hope with a view to getting serious feedback etc –  but they’ve already mentioned enough that we can be sure that what they’ve had in mind simply will not make up for the limits of conventional interest rate capacity, even allowing for the likelihood that in such a severe downturn our exchange rate will fall a long way (as it did in most of those previous 500 basis point rate cut episodes).   There is also sadly little sign that the Minister of Finance has shown much leadership or urgency about seriously addressing this problem (again, nothing along those lines in yesterday’s speech –  good enough as far as it went, but it stopped short of the really serious issues/risks).

It would be easy for me to suggest that the Governor has been too much occupied with his tree gods, his climate change interests, his views on infrastructure or the distribution of income, rather than driving action urgently in this area of monetary policy capacity (core day job).  And that is no doubt true, but as a specific criticism it needs to be kept in perspective –  his predecessors had let the issue drift, and his peers at the top of many other central banks have also seemed to prefer to believe things would come right than to seriously prepare for the constrained alternative.  We risk paying the price now –  including with central banks paralysed by their own limitations and reluctant to act early and decisively to lean against (do what they can to buffer) the economic downturn (and downside risks to inflation and inflation expectations).

Quite possibly there is a place for fiscal policy in responding to a serious downturn, even one amid the chaos of a potential pandemic, but there needs to be a lot more realism about the likely constraints on how much, and how longlasting, any discretionary stimulus is likely to last.   There is no real excuse – even in a less fiscally constrained country like New Zealand –  for authorities not to have moved to greatly alleviate or remove the effective lower bound before now, and to have used relatively settled times to have socialised the case for doing so.

And even if the FRBSF authors are wrong about the influence of the ELB on inflation over the last decade, if it very quickly now becomes even more binding – starting from a lower initial level –  it will be front of brain for everyone through the next cycle.    It really needs to be dealt with now.  It isn’t technically hard –  there are various workable options –  but it needs leadership, will, and vision for something to happen, something which has the potential to limit the extremes (depth, duration) of that severe downturn whenever it finally strikes us.


Government spending and revenue: some comparisons

I had to look up this morning where New Zealand ranked among OECD countries in the total share of GDP taken in taxes.   The answer (for 2019) was 11th lowest, or 10th lowest if you (as you should, and as I do in the chart) use the denominator for Ireland (modified GNI) that the Irish authorities use.

taxes 2019

Among the English-speaking countries we often compare ourselves to, New Zealand and Canada are in the middle of the bunch, with the UK and Ireland higher and Australia and the United States lower.  Note that these are “general government” figures, including all levels of government in each country.

What about the spending side of the picture?  This is the chart for current spending across all levels of government.

spending 2019

New Zealand is towards the very bottom of that chart.  It is, however, fair to point out that when you have a low level of public debt you don’t face much an interest expense:  in terms of current purchases or transfers our overall level of current government spending goes a little further relative to most other OECD countries (with higher debts) than it might first look.

The big outlier, of course, if you compare that two charts is the United States, with yawning budget deficits.

What about the changes over time?  These OECD data only go back to 1986 for New Zealand, so I’ve started the chart from then showing (a) New Zealand, (b) the median of all OECD countries, and (c) the median for the OECD countries for which there is complete data from 1986 onwards.

spending time series

The gap between New Zealand current government spending and that in the median OECD country opened up 30 years ago.  In fact, the gap between New Zealand and the consistent-sample grouping (the orange line) has fluctuated around a fairly constant mean since the early 1990s, with no obvious differences based on which of the major parties was leading the government.

Of course, at the start of the period we still had fairly high debt and fairly high interest rates.  But that factor doesn’t look to explain much about comparisons for the last couple of decades.  This chart is of net interest expenditure as a share of GDP.

interest net

And what about changes in taxes (and social security contributions) over time?

taxes over time

On this measure, the gap between New Zealand and the complete-sample group of OECD countries (grey line) has widened further over the last decade or so.  Partly in consequence, whereas for the OECD as a whole (either series) the median country now has a higher tax share of GDP than it had in the late 1980s, we have lower taxes.  Consistent with that, of course, we also have lower current outlays than we had then, but it looks as though much of the difference will be accounted for by (a) in particular, lower (real and nominal) interest rates, and (b) lower debt.

I’m not attempting to draw any strong conclusions, just presenting the numbers.  They aren’t the only numbers that are relevant.  For example, as I understand it, the current disbursements series does not include depreciation, so in some respects it would be better to look at total outlays (in New Zealand, with a fast-growing population, government capital expenditure tends to be quite high).   Similarly the taxes and social security contributions series –  while important in its own right – is not a measure of total government revenue.  And I could track down the gross interest data and subtract that from the current disbursements series to get a consistent series of current primary spending.   Perhaps another day.

For now, I think one can safely say that New Zealand government spending and revenue are below those of the typical OECD country.  That wasn’t always the case, although much of what changed was servicing costs.  Whether that relatively modest size of government (spending and revenue) is a matter for concern or celebration will, I guess, depend on your ideology, your view (implicit or explicit) of various key elasticities, and perhaps your sense –   which should be detachable from ideology –  as to how wisely and well existing spending is being done.  For myself, I think there are areas where our government should probably spend more (health, access to justice, administration of justice, and statistics as just some examples), but I’m not convinced that even taken together they would amount to a strong case for higher taxes (when I think of potential savings –  on NZS, free tertiary education, the PGF as just some high profile examples).

Coronavirus can’t just be thought of as an illness for other countries

There was quite a bit of media coverage this morning around the potential economic impact of, and possible policy responses to, the coronavirus.   There have been commentaries from, or interviews with, various economists and a fairly substantive interview on RNZ with Grant Robertson, the Minister of Finance.  Each of them left me a little concerned, but of course the comments from the Minister of Finance –  who gets to decide things and is backed by phalanxes of official –  matter the most.

In his comments at the post-Cabinet press conference on Monday, the Minister indicated that he and his officials were working with three distinct scenarios.   There doesn’t appear to be anything in writing (eg on The Treasury’s website) but broadly the scenarios were as follows:

  • something (probably not too different than the Reserve Bank’s quite-sanguine recent published forecasts) that seems wholly focused on China, and with things beginning to get back to normal next month,
  • something where the effects, perhaps around a wider range of countries, linger for the rest of the year, and
  • a third scenario which he characterised as a serious global recession.

The government is still working with the first of those scenarios, although the Minister acknowledged that the risks of the second scenario looked to be rising.

Many of the other commentators seemed to be thinking along similar lines.  The NZIER, for example, released their quarterly forecasts overnight and their press release says

It is early days and there is a large degree of uncertainty over the magnitude and duration of the effects from the coronavirus outbreak. In the short-term, the uncertainty revolves around the ability of exporters to redirect their exports to other markets. Over the longer-term, the uncertainty is whether the coronavirus has any persistent negative effects on global growth.

And I’ve seen/heard other economists commenting on whether or not GDP growth for the first couple of quarters might or might not be negative (the popular definition of a recession –  more demanding here than in most countries, given our fairly rapid population rate).

But, frankly, it all seems a bit pointless, especially the very short-term forecasting, because all of them –  including the Minister of Finance –  seem to be dealing with a scenarios in which coronavirus is someone else’s health (and attendant domestic disruption) problem, for which New Zealand is only exposed to the global growth backwash.  Of course, that backwash might well be quite severe.   But none of them seem to be grappling with the near-certainty that coronavirus will soon be confirmed in New Zealand (based on what we’ve seen abroad, there must be a reasonable chance it is already here  –  and the Ministry of Health tell us that under their narrow criteria only 120 tests have taken place here).  And, more specifically, none of them is grappling with the possibility that we –  like any city in the world, it appears – could have Korean, Iranian, Italian, Bahrain situations here at any time from today (none of those countries seem to have thought last week that they’d be imposing all the the restrictions they now have).   If the experts who tell us there is now a high chance of a general global outbreak, perhaps infecting 40 to 70 per cent of the world’s population, are correct, probably most cities will face such a scenario.   And those sorts of events have the potential for huge disruption, and economic cost, which would swamp the sorts of narrow effects forecasters like the Reserve Bank have already allowed for.

Take as a scenario a significant outbreak in Canterbury (or Wellington).   Canterbury accounts for about 12.5 per cent of New Zealand’s GDP, and suppose that for a month economic activity in Canterbury is reduced to 50 per cent of normal  (some mixture of schools and daycare centres etc being closed, lots of people being sick or self-isolating because a family member was sick, restrictions on public gatherings, the evaporation of tourist arrivals, and fear).   If that was the only effect New Zealand’s GDP for the quarter of the outbreak would fall by 2.1 per cent –  not annualised, an actual fall of that amount.   That alone would be almost as bad as the worst quarter of our worst recession in modern times in 1991.      You could triple the effect if the outbreak was in Auckland (38 per cent of national GDP).

And even if by some chance the outbreak –  and tough restrictions –  was contained to a single city/region, the economic effects won’t be –  partly about domestic supply chains, partly about transport networks, and lot about precautions and fear.     If there is a Korean or Lombardy style outbreak in Sydney or Brisbane, we’ll already see a lot of costs start to rise rapidly here –  both domestic fear, and how many foreign tourists do we suppose would still be coming here?   So we can’t even assume that even if an individual city’s outbreak takes just a month to work through, that the national effects would be limited to a single month.     It isn’t inconceivable that we –  or small/compact countries like us –  could see the level of GDP fall by 10 per cent or more in a single quarter, and then take quite a long time to recover from the shock of what the society has just gone through.    Quite apart from anything else, that is quite a lot of lost tax revenue, even if 12-18 months hence things were more or less back to normal.

Of course, no one doing quarterly forecasts can allow for these sorts of events in their specific numbers, because we have absolutely no idea whether these scenarios hit tomorrow, next month, June (or, indeed, not at all).   But anyone –  policymaker, business, or householld – thinking about the outlook for the next year would be pretty unwise not to explicitly factor in a fairly probability that exactly that sort of highly disruptive short-term scenario could occur.     And then you have to factor in the near-certainty (so to speak) of extreme uncertainty, and associated disruptions –  forced on individuals or firms, or self-chosen as a precaution – across the world for much of the year ahead.   At very least, a lot of travel just won’t happen, a lot of investment projects will go on hold, and cash-flow/liquidity is likely to be a big issue for many firms and households, whether or not banks are more or less as supportive (or otherwise) in other stress periods.   Whether that will amount to the Minister’s “serious global recession” scenario or not, who knows (but probably, given other underlying vulnerabilities).

In many ways, GDP is just a headline number in thinking about the challenges we face, and in time it is likely to recover more or less fully (even allowing for the limits of monetary policy).  Much the bigger issue in the disruption to lives –  even lives lost –  lost jobs, debt defaults, perhaps stranded sick tourists, overwhelmed health systems, disrupted supply chains for things as (normally) mundane as food.  I suspect policymakers shouldn’t be focused so much on the Minister of Finance’s scenarios –  which in many respects from a New Zealand perspective are fairly vanilla as regards policy responses –  as on handling, and preparing for, the extreme but short-term disruption of actual coronavirus outbreaks here.

(As a reminder here of my post last week with some speculative thoughts on the potential economic ramifications if things go really bad.)

Of course, “preparing for” here should include preparing the public.  So far, both officials and ministers have been almost totally silent on that count.  In the early days, Health officials seem to be more interested in minimising the issue, but even having got beyond that they and their political masters seem to think all these issues are really just matters of bureaucrats, not for the public themselves.  News coverage seems more interested in what the government might or might not do to help currently-affected industries, and media representatives don’t seem to be pursuing ministers on how they will handle (the likelihood of) a significant outbreak here.  There was not a single question along those lines at the PM’s press conference on Monday.

There is, of course, a pandemic plan on the Ministry of Health’s website.   It was last updated in 2017, under a previous government.  It was designed with influenza in mind, and the current virus appears to be different in some material ways.     There is even an explicit appendix (p155f) on “public information management”, including for use at a stage when a pandemic might be looming.  But almost none of the messages mentioned there seem to be being conveyed at present.   There is no evident leadership –  from the Prime Minister, the Minister of Health, or some other minister leading the government’s response –  and no sense of what choices the government might make under what conditions.

As just one example, what approach does the government intend to take around schools and daycare centres?  Some places have closed them pretty quickly –  Hong Kong just extended school closures until April – while other places (notably Singapore) have left them open.   That single choice has big implications for many parents, and for their employers, and yet we’ve heard nothing, meaning no one can plan with reliable information.

Or at a more-mundane level, is there any sign of advice to people to consider stocking up on various non-perishables that might better enable them to cope with a few weeks at home.   Probably many of those paying attention will already be doing so (I certainly am) but a lot of people are probably barely conscious of the issue –  which could be on us tomorrow, or months away.  And what thought has the government given to people without the financial capacity to do much about stocking up –  living from pay cheque to pay cheque –  including if we were to see the sorts of runs on supermarkets you can see photos of from Milan.   If cities are more or less closed down, foodbanks aren’t likely to be available/effective either.    And what are the plans if 10 per cent of the population needed fairly serious medical treatment over a matter of a few weeks?   What plans might community support groups be making now?  Is it wise, or humane, to look at encouraging more young foreigners in now, when we might soon face serious stresses on our own health systems, with the visitors having few/no domestic support networks?  And so on.

There are lots of these sorts of questions/issues. Eric Crampton had a useful post on the point with some more of the relevant questions set out.  Perhaps there is some really effective planning going on behind the scenes, but even if so that simply isn’t good enough in the face of this sort of event, especially when we can all see and read about what is going on elsewhere and the advice being given elsewhere.   How much better to have some visible leadership and open serious conversations about how, as a society, we manage the high likelihood of extremely disruptive, costly, perhaps deadly, events quite soon.

A tweet from the Reserve Bank

I was in a meeting all morning and don’t have that much time this afternoon, so I should offer a special thanks to the Reserve Bank for suggesting a topic for today’s post.  It is prompted by this tweet, which turned up in my feed just as I was about to head into my meeting

The Bank used to use Twitter for not much more than sending out links to press releases etc.   But they seem to be trying to use it more actively, with a strategy (if any) that is less than entirely clear to the outsider.   For example, a couple of weeks ago there was the invitation to us all to submit questions via Twitter for the Governor’s MPS press conference –  which went rather badly when they only took two questions that were reframed as soft platforms for the Governor to declaim on some or other favoured topic.   Yesterday, there was a puff piece telling the world that the Bank was now 43rd most favoured employer for graduates in New Zealand.  I suppose that didn’t sound too bad –  small organisation and all that –  until I clicked on the link and found that the Bank came in behind 11 other government departments and a couple of local government entities.  Oh well, thanks for letting us know I guess.

This morning’s tweet has the potential to be quite a bit more concerning, on several counts.  Most concerning is that it reads as a statement of the institution’s view –  that of the MPC? – on matters directly relevant to monetary policy, launched into the ether with no notice at all.     That is no way to do monetary policy –  or rather it was the sort of way we did monetary policy 25 years ago, before we moved to a clearer, more scheduled, more predictable system.  This might seem like only a picky inside-the-Beltway issue, but this isn’t way things should be being done.  It would be interesting to know whether the MPC were consulted, or even advised, that a statement on the economic outlook was about to be made.

More substantively concerning is the content of the comments, perhaps especially when released in the middle of one of worst financial market trading days in several years.   Look at the substance of their new text: “we expect activity will pick up later this year, meaning more investment, more jobs, and higher wages”.      The link is to their cartoon summary of the Monetary Policy Statement, released almost two weeks ago, based on forecasts finalised almost three weeks ago.    Those were forecasts based on very short and quite limited negative coronavirus effect.    Those are the forecasts today’s statement links to.    How can they possibly still be the MPC’s best view now, when a growing range of medical experts now expect the virus to go round the world, infecting (in time) perhaps 40 to 70 per cent of the world’s population, with attendant disruption and uncertainty?  At very least, the risks to the happy upbeat story must be much more serious than the MPC thought them two or three weeks ago.

My guess is that the tweet wasn’t really intended as monetary policy and related economic commentary at all.  My guess is the MPC wasn’t aware of it, and quite possibly the Governor was not either.   Perhaps someone down the organisation running the Twitter account just thought it would be a good idea to tell us a bit more about the Bank (“we do forecasts”).    But official communications need to be managed better than that –  an excellent central bank, best in the world, would certainly do so.

Excellent central banks also communicate carefully and precisely about things bearing directly on their mandate.  A reader yesterday drew my attention to (something I’d missed) the way the Reserve Bank is falling short there too.   A good example was in the cartoon summary of the latest MPS, linked to in that tweet, where I found these

target 1

target 2

It isn’t just the cartoon version either.  Here from the MPC’s minutes

The Committee agreed that recent developments were consistent with continuing to meet their inflation and employment objectives

And my assiduous reader tells me the same phrasing pops up in comments made by the Governor, and in the last few MPS rounds as well.

Can you tell me what the Reserve Bank’s employment target is?

Trick question, as there isn’t one.

The MPC and the Governor surely know this, as their Remit –  the mandate set for them by the Minister of Finance –  is reproduced at the start of each Monetary Policy Statement.  Here is the central section

The current Remit sets out a flexible inflation targeting regime, under which the MPC must set policy to:

• keep future annual inflation between 1 and 3 percent over the medium term, with a focus on keeping future inflation near the 2 percent midpoint; and

• support maximum sustainable employment, considering a broad range of labour market indicators and taking into account that maximum sustainable employment is largely determined by non-monetary factors.

There is a clear and measureable inflation target, basically the one we’ve had for almost 20 years now.

And then there is a requirement to “support” maximum sustainable employment –  which is, more or less, what monetary policy tends to do when it acts to keep inflation near the inflation target.  There simply is not an employment target, so what are the Governor and MPC doing claiming that they’ve met this non-existent target.  It might be quite reasonable for them to argue that they believe they’ve done what they can to support keeping actual employment near maximum sustainable employment –  reasonable people might differ from them on that, but the debate would then be around an explicit mandate the Bank has been given.

Perhaps to many the loose language will seem harmless.   And perhaps when we are near to full employment it does little damage, but that won’t always be the case.  Come the next serious recession, unemployment will rise a lot/employment will fall a lot.  The Bank will do what it can to lean against those changes, but it won’t be failing –  not hitting a target –  just because the unemployment rate is high, perhaps even for several years (especially if the limits of monetary policy are reached).   More generally, it creates a sense in which someone there are equally important employment and inflation targets, when the Minister of Finance –  the one responsible for setting the target –  has clearly specified otherwise.

Mostly, it is probably some mix of sloppiness and the Governor’s ongoing efforts to play the “tribune of the masses” card.    And we should expect (demand) better than that from the Governor and the MPC – especially in formal written documents, whether aimed at the “specialists” Orr affects to despise or at a wider general audience.  You do not need to be sloppy in the use of language to communicate the essence of what you are supposed to be about.   From the Bank recently we’ve had loosely-grounded factual claims, outright misrepresentations, and repeated sloppy use of language to misrepresent the Bank’s mandate.  I’m guessing it would not go at all well with the Bank’s bank supervisors if they found the banks and financial institutions they regulate operating in so loose a way.  Apart from anything else, those supervisors might reasonably ask themselves “if things are this loose in what we see –  prepared for the public face –  what are things like where we cannot see, inside the organisation”.

These might be issues the Bank’s Board and the Minister of Finance –  both charged with keeping the Governor (and MPC) in line and accountable –  might be asked about.    I imagine they would just run defence for the Bank, but you never know.   Perhaps some journalist might approach an MPC member for comment –  and if, as most likely would happen, they simply refused to comment then report that stonewalling.