Weighed in the balance

The feckless leadership of this country heading into the deepening coronavirus crisis has been pretty astonishing to behold.  Of course, there is the Governor of the Reserve Bank (and his statutory MPC offsiders), whose complacent utterances and utter inaction have been well-documented here this week.   And there is the Ministry of Health which has been actively discouraging people from stocking their pantries, constantly talking down any areas of concern, refusing to seriously engage with the public on the worsening overseas situation (including Australia, with whom we share a fairly open border) and is still telling us the risks of community outbreak are low.  This was still on their website a short time ago

MOH virus

(And when a reader asked the Ministry of Health for the justification for this stance, the only reply he got was along the lines of “we clear all our statements with clinicians” , as if these anonymous “clinicians” are different from people in any other field of expertise, where there will be a wide range of views, particularly amid extreme uncertainty. )

And then of course, there is the Prime Minister and the Minister of Health. The latter, despite being an elected politician, simply seems to channel his officials –  and perhaps only in the aftermath when all the OIAs are in will we know whether officials are tailoring their stance to suit ministers, ministers are so incurious as not to ask the hard questions, or both.

But in a crisis the focus should naturally fall on the Prime Minister.  It is for rare events of this sort of magnitude that we elect people who purport to be leaders.  But again we’ve just had constant minimisation, “pat on the head –  there, there” idle reassurances,  and a sense of always dithering and being behind the play.  There is no sense that our Prime Minister has any conception as to just how bad the global situation is getting, how serious the Australian situation is becoming, or any willingness or ability to articulate a coherent alternative view (if she has really thought hard enough to come to one).  There is no fronting the public about how no health system can adequately cope with large outbreaks, and only last week in Parliament she was still trying to play down the prospect of even a mild recession in New Zealand.  More recently, nothing serious has been heard confronting the very serious economic dislocation we face, whether or not the happy talk from her and her officials re low risk of community outbreak happens to come to pass.

Who knows why?  People speculate that it is all about the Christchurch commemoration –  whether for cynical reasons or because some short-term empathy with those victims has totally distracted her from a focus on the much larger threat that is now about to overwhelm us, and for which she –  as Prime Minister –  can actually affect outcomes.  But whatever the explanation it is pretty inexcusable to have a “leader” so totally in reactive minimisation, avoiding fronting with the public, mode.

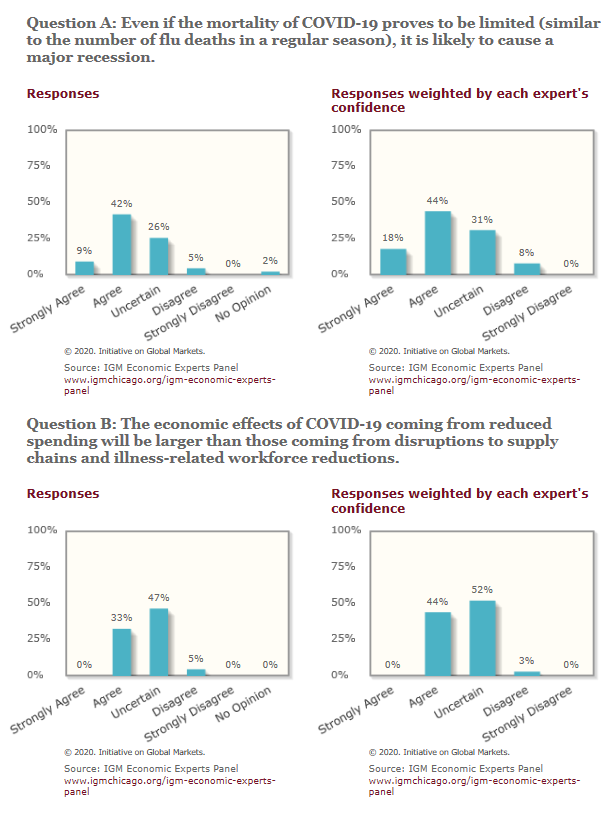
But not to divert too long or too far from the main focus of this blog – economics and economic policy – I thought it might it would be good to give some coverage to some survey results out this morning, asking leading economists in both the US and Europe about the outlook.

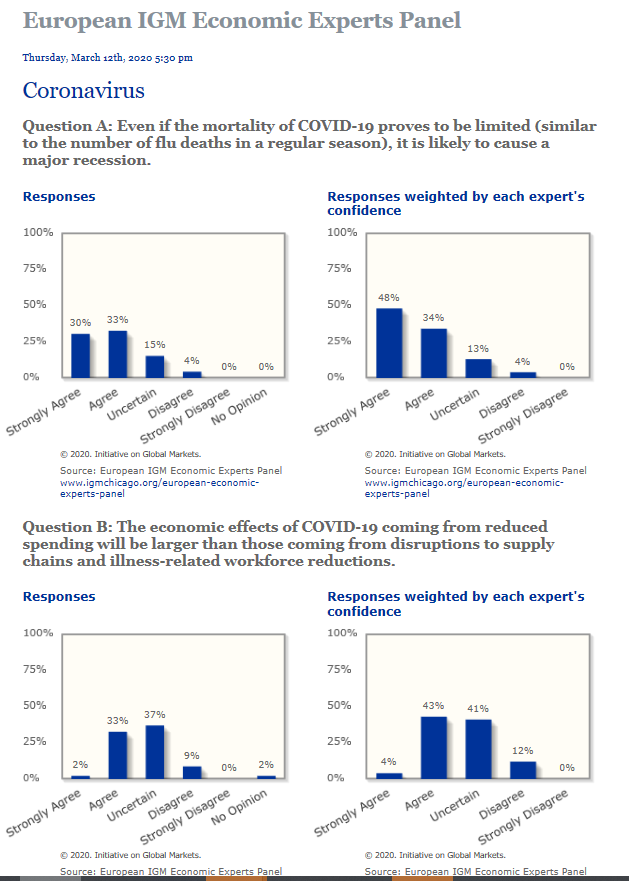
The virus situation in Europe is currently worse than that in the US, so lets look at the European results first.

europe igm corona

Weighted by expertise, 82 per cent of respondents expect a “major recession” (none of the silly debate that still seemed to be in focus in New Zealand even last week as to whether we’d have two slightly negative quarters).

And although for most macro policy purposes, it doesn’t much matter whether the disruption is coming from the demand or supply side (contra the Reserve Bank public handwringing), 47 per cent think the main effects will be coming from the demand side.  Only 12 per cent disagreee.

(In New Zealand, so far, there is little doubt that almost all the effects we’ve seen have been demand-side ones –  reduced (mostly foreign) effective demand for our goods and services.)

And here are the US results

US igm panel corona

Not quite as bleak –  yet –  but almost.

The release doesn’t say when exactly the survey was taken, although I’m guessing very recently.

There is not a shred of reason to believe that the New Zealand situation will be any different, and that would be so whether or not we somehow manage to avoid community outbreak (I’m sceptical, but I guess we should always allow for the possibility the Ministry might be right).   Much of the world economy is now shutting down –  perhaps not for long, but no one can be sure of that – in a way for which there is almost certainly no modern (post Industrial Revolution) precedent.

And yet you still hear nothing of this from our Prime Minister, our Minister of Finance (let alone our central bank – and numerous senior central bankers have been choosing to talk in public this week).  It is simply irresponsible, if they realise, not to be fronting the issue and offering honest leadership. If they still don’t realise, it is simply inexcusable, and not one of them would then be fit for the offices they hold.  Crisis reveal whether those holding office are really leaders: at present you could really only say of ours, weighed in the balance and found wanting.

Perhaps they will all yet redeem themselves.  We must hope so, as a matter of urgency.


Following the Ministry of Health’s messages

A couple of weeks ago I signed up to follow the Ministry of Health on Twitter.  Seemed a sensible thing to do: coronavirus and all that.

Since then I’ve been interested to watch their messaging very slowly change.  Two weeks ago (28 February) was when the first New Zealand confirmed case was announced.   We got this

By the next day they were so relaxed about the virus they took to tweeting woke public service stuff

Pretty sure that even then the disease had killed a lot more people than “fears, rumors & stigma”, but…well…presumably that wasn’t Dr Bloomfield’s view.

On 1 March, we had the “wash your hands” message

and there wasn’t anything on 2 March.

But by 3 March, it was time for some more off-topic political rhetoric from another government agency. the Ministry retweeting this.

Here was the 4 March messages

Never have they given us anything substantial to justify their view that the “risk of widespread community outbreak” not only is low, but is expected to remain low.   Small matter of all those other countries, including ones that had much the same border restrictions we did.

By 5 March we had

Probably (a) really up to the public, and (b) any reviewers when this is all over, to decide whether things are being well-managed, but we know that the Ministry’s prime communications objective (stated in the pandemic plan) is to maintain confidence in themselves, whether justified or not.

Also, much as we might sympathise with that family, surely the Ministry of Health’s prime task isn’t those individuals but the safety and wellbeing of the wider public?

There wasn’t anything much on their feed for a few days, but then there was this

Which displays no sense that the Ministry recognises that while it knows about the cases it knows about, it doesn’t know what it doesn’t know. There was also this.

Given the rate at which the virus was spreading globally, it wasn’t clear quite what evidence they had for their misinformation claim.

(Although perhaps they had in mind the Director-General’s several claims around the time that asymptomatic transmission of the virus simply isn’t a thing, a stronger statement that what was made in the WHO report he claimed to draw on, and not consistent with the views of a bunch of other international experts.)

And by 10 March we have this

Talk about confidence: “just wash your hands and don’t worry”.   Oh, and by the way we are so confident there is no risk that they actively advise people not to “stock up”  (not even just “not panic buy”).  I imagine most people have done as I have and ignored their advice.  After all, wouldn’t want chaos in supermarkets if/when community outbreak becomes a thing or when much greater social distancing is mandated.

Here they are on 11th. Public events finally come into view.

Then yesterday, there was a change of tack from the Ministry

The “risk is low” message had been dropped, and the asymptomatic transmission message had been toned down.

And what of today, the 13th?

The ground seems to have shifted quite a bit.  No attempts to downplay risks, no reaffirmation of the risks being low, just some advice about hygiene etc things to think about in deciding whether or not to go.

And to read Dr Bloomfield’s press release today there is also quite a different tone coming through

“Our key advice, which is fundamental to our response, is not putting yourself or others at risk if you are unwell. This means not going to work or going to places where there are other people if you are sick. All of us have a role to play in stopping further spread. I need to emphasise how critical this is as New Zealand responds to COVID-19,” says Dr  Bloomfield.

‘This is particularly important for concerts and other large gatherings we have coming up, including this weekend. Please stay home if you’re unwell.’

Having said that, I went and looked at the Ministry’s website, and there it still says

With continued vigilance the chance of widespread community outbreak is expected to remain low.

But with not a single sentence to justify the Ministry’s view.

People seem to speak highly of Bloomfield. Personally, I tend to be a bit sceptical of anyone appointed by Peter Hughes (State Services Commissioner) and as a mere curious citizen haven’t seen anything much to allay my unease in the last couple of weeks.  In its public communications, the Ministry seems constantly to have been playing down risks as much as they can –  even as the global situation deteriorates rapidly, and Australia’s situation worsens.    It seems fundamentally unserious and it seems not at all consistent with the ideas of an open society, transparency and challenge.    And frankly it undermines confidence in whatever the Ministry will be saying through the next phases of this crisis.  Whatever actual expertise some of them no doubt have, they risk coming across as unserious and not interested in levelling with the public.  (Same goes for some of Bloomfield’s comments about some east Asian countries that seem to have checked their outbreaks for now: no sense of engaging with the public as to what it would take (resources, commitment, compliance etc) and for how long, to even hope to emulate those stories).

Wouldn’t it have been good to have seen the Director-General engaging on, for example, the deterioration in the Australian numbers, directly confronting the facts that (a) there is an open border between the two countries, and (b) a fair amount of travel each way all the time and addressing the implication that we might, in effect, really be considered as being in a Common Virus Area with Australia.  If so, the complacency about New Zealand risk might be particularly worth challenging.

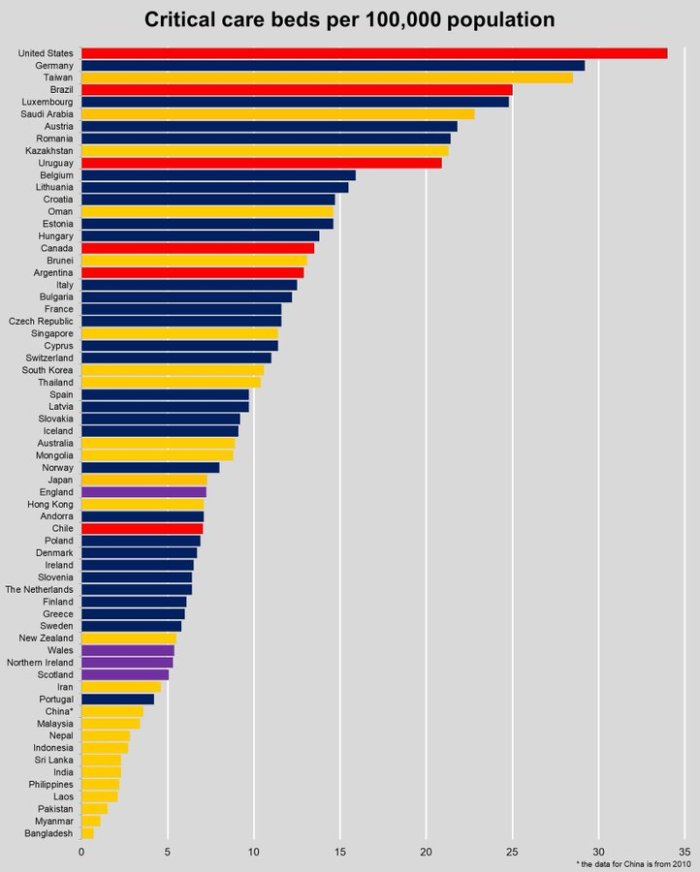
And wouldn’t it be good if Bloomfield –  or the Minister of Health or the Prime Minister –  fronted with the public about the very real challenges the health system will face if we get a serious outbreak here (low number of ICU beds per capita, looking at the Italian experience etc).  That is what good, honest, effective-over-time communicators would do. It is the sort of thing that over time builds confidence: a view that, for example, while officials may be optimistic now (rightly or wrongly) they have thought hard about what might happen, and aren’t just trying to sugar-coat their messages and keep the public quiescent.

Wouldn’t it be good if they could effectively and openly articulate for the public the “flatten the curve” strategy that drives so much of what is going on?

I really hope that what we don’t see is better than what we are seeing.  Because what we are seeing seems complacent and uninterested in genuine openness and engagement.  And that is no way for a democratic society to be operating, in which we simply defer to officials, take what they tell us only when they tell us, and not bother our pretty little heads about other stuff.


Face reality and scrap the package

Here in New Zealand we are waiting for the details of the government’s promised economic package, which –  we are told –  will be tightly targeted and focused on the industries that particularly suffered from coronavirus.

Even to write that sentence, is to recognise how absurd a position the government has put itself in.     They seem –  no real doubt about it, their own words say as much –  focused almost wholly on the firms/sectors that suffered from China’s experience with the coronavirus, even as something so much bigger is already beginning to sweep over us.  China, after all, if not remotely back to normal, is offering practical assistance to Italy.   That outlook was something the Minister of Finance and, even more so, the Prime Minister have consistently refused to face.  Perhaps they’ve known it internally –  there must, surely, be some good adviserssomewhere –  but nothing they’ve said in public has prepared New Zealanders for the reality of what is unfolding, and what is likely to happen in the coming weeks and months.  (Our media don’t seem that much better: the Herald today has a full page story on the front cover “The World Faces Reality”, but readers will still have little or no sense that the economies of many countries are about to substantially shutdown.)

Whether or not we get serious outbreaks here –  and who aside from the Ministry of Health would be willing to punt on us not – the New Zealand economy will be severely –  really really severely –  adversely affected.   And there is very little that economic policy tools, macro or micro, can do to lean against or mitigate that loss.  Economists have talked for years about the benefits of exchange, specialisation, personal interactions etc etc.  But for the next few months the emphasis seems likely to be increasingly on keeping your distance, hunkering down.    Huge amounts of output just are not going to happen, and there will be hardly a firm or sector not really severely adversely affected.

Whether or not the government’s plans were reasonable when they were first being conceived –  and just perhaps they might have been six weeks ago –  surely now is the time to bin that package they were planning to announce next week.  They need to start over, facing the reality now before us, not the (now rather limited) shock that first faced us (and certainly hit some individual sectors hard).

Sensible policy responses now –  whatever they choose to do around further border closures –  look much more appropriately focused on immediate crisis management.  In other words:

  • ensuring the income support is going to be readily and effectively available for the many (especially low income) people who won’t be able to work from home or who will have exhausted their sick leave (and any ex gratia generosity employers may still be able to offer). That might require legislation: if so, pass it,
  • ensuring that the food distribution system is going to be reasonably robust if we go through closed-down periods (in an early post here, I recounted an anecdote from an early phase of pandemic planning that scared me then: big supermarkets typically only have 1.5 days of sales in stock at any one time),
  • spending/doing whatever can still usefully be done to prepare for possible severe health system stresses (rather than just happy talking the public about how well prepared they are –  for 100 cases I’m sure, but not for several thousand).

and so on.

Now, sure there are probably other things to do.  The Reserve Bank should be cutting the OCR (for all the reasons I outlined yesterday) and they need to be prepared to roll out liquidity support type operations if financial sector funding stresses start affecting banks here.

But you simply cannot plan to target individual firms, when almost every firm is going to be engulfed.  It would inefficient, unmanageable, and would simply to fail to recognise the magnitude of the coming losses.

And there is no point in thinking of huge fiscal outlays, as general stimulus, right now.    If the government was going to plan to actually purchase physical goods and services well (a) what would it do with them?, and (b) soon enough, the capacity of the economy to deliver much (workers at work, functioning distribution systems) are going to be severely impaired.  And – the more likely option –  simply putting money in people’s pockets, whether by cash grants or tax cuts (GST or low income thresholds on income tax) aren’t likely to achieve much systematically useful either.   For a start, if you are sensible then in such a climate you won’t want more people eating out (say) or moving around holidaying, or going out to big sports matches or concerts (classic discretionary items).  And even if online retail really was still fully functional locally, it just isn’t that large a share of New Zealand retail.  More generally, quite-rational fear and uncertainty about the future will have people pretty reluctant to spend anyway.   That is sensible and prudent, and not really something governments should now be trying to undo –  even if our happy-talking Prime Minister was the other day encouraging people just to go out and spend.       We need to start thinking in terms of the deepest contraction in economic activity any of us –  except perhaps the handful still alive who experienced the Great Depression-  have ever seen.  It is the price the world is going to pay to “flatten the curve” (something we’ll come back to).

Big stimulus is probably going to be appropriate and required as and when the worst of the virus is past us, and people are genuinely and rationally able to see some light at the end of all this, building on the fundamentals already at work by then, speeding up the recovery.  Ideally, that would be a mix of fiscal and monetary policy, bending over backwards to help get economic activity levels back to normal.  So use the time now –  you’ll have plenty –  to prepare for that sort of strategy  (and perhaps for the inevitable bailouts and recapitalisations our politicians will find themselves unable to resist –  anyone suppose that if it comes to that governments of either stripe would let Air New Zealand fail (but I hope at least they wipe out the private shareholders if it does happen)).   It might even be time to consider changing a few individuals at the top (poor generals are found out in wartime and, in good armies, quickly replaced).

On the fiscal side, make sure  –  for example –  that a universal lump sum cash payout to all residents could be made (from the outside hard now to see how it could be done).  Ensure that a temporary GST cut could be implemented quickly and smoothly.  And insist that the work is done to largely remove the near-zero effective bound on lower interest rates. It can be done  –  it should have been done, here and abroad, five years ago –  and failure to act will simply unnecessarily hold back eventual recovery (and reinforce those downside risks to inflation expectations that I’ve often worried about here).

One of the key things we all have to recognise is that this situation is not going to be resolved any time soon.  For hints of that we can look to China.   Sure the new case numbers and new deaths have come right down –  more infections this week, I think, from arrivals from other countries than locally –  but nowhere are things back to normal. In Wuhan it seems that recovery has barely even begun.  Look at successive waves of things like we are now seeing on Italy –  or early signs in other countries too –  and there is going to be no confidence (including about travel) and no certainty for a long time.

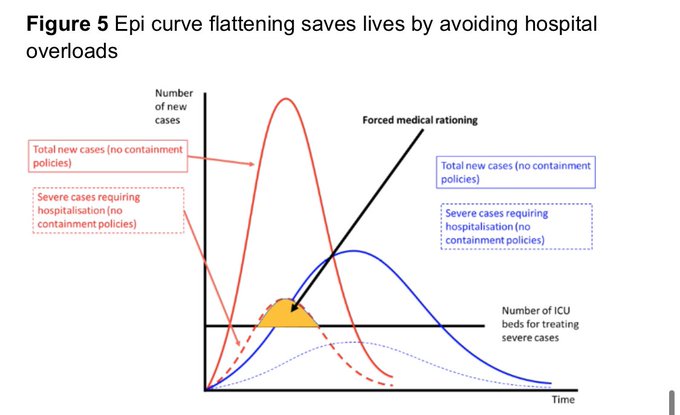
But perhaps even more importantly, remember that the virologists etc talk about the goal of current interventions being to “flatten the curve” .  This is perhaps the best version of the stylised chart I’ve seen, in a new article from the economist Richard Baldwin.

flatten

Perhaps it is a little cluttered, but it is trying to convey a lot of information.

The solid red line is a stylised representation of how new case numbers would look if there was no containment (given that there is no effective treatment).  You’ll have heard of experts talking of how if that happened perhaps 50 per cent of the world’s population would be infected before too long, since none of us has any natural immunity and the virus seems to spread easily.

The real worry in that scenario is the dotted red line –  people needing ICU-level care.   And this perhaps is where the chart is too sanguine.  On this version, the area under the dotted red line, and yet above the ICU bed capacity, is small relative to the total ICU demand.  But if 5 per cent of cases need ICU-level care (seems about right from what I’ve read) then it is worth remembering that New Zealand, for example, has about 175 ICU beds.   Perhaps with valiant efforts those numbers could be doubled in an emergency –  but doctor numbers can’t – but even that would mean that, if no one else was in an ICU bed at all, our system would be overwhelmed at 7000 cases at the same time (5 per cent of 7000 being 350).  That might seem a lot of cases, but recall that 50 per cent of New Zealand’s population is 2.5m people.

So trying to flatten out the curve is about trying to avoid the forced medical rationing already evident in the high-quality northern Italy health system and, presumably in the process, reduce the overall death toll (very old people will get treatment and as a result some will live who might otherwise have to be left to die). If the curve could be flattened out, by aggressive containment etc measures, the aim –  highly stylised –  is to produce something like blue line, where the ICU demand never quite exceeds the physical capacity.

But what isn’t often mentioned –  although it is quite clearly implicit in the stylised chart –  is that the aggressive containment measures don’t necessarily alter the likelihood that –  at least unless there is a widespread vaccine available next year –  many of us will still get it in the end (something like 50 per cent is still the number  – the sort of thing Angela Merkel said to the German people the other day).  It is just a matter of time, of stretching things out, and (thus presumably) of repeated waves or outbreaks in different physical locations.  Take Italy as an example, the current situation looks horrendous, but case numbers are not even close to 1 per cent of the population.

And, unless that narrative changes markedly as we learn a lot more, that seems likely to be the sort of scenario every country faces, in one form or another, for the time being.  There is nothing to suggest –  since no likelihood of a vaccine in that time –  that the problems/risks/disruptions will ease this year.  And the end of the year is still 9 months away.   Turning back to the economics, a great deal of economic output and wealth can, and probably will, be lost in that time.  It means –  sadly –  that there is likely to be plenty of time to think about planning for serious stimulation as we get to a recovery phase.   How many people are going to be keen to book travel, even if borders stay open or re-open and flights are still there?  How many people are going to be keen to spend (precautionary savings will look very rational for many if they still have an income)?  And who is going to be ready to commit to start investment projects, even if either debt or equity funders were willing to release the funds needed?

It isn’t hard at all to see New Zealand’s GDP for the rest of the year being perhaps 10 per cent lower than otherwise (that isn’t a forecast, just an attempt to suggest that the ballpark numbers people should be working with are very very large.  That alone would $25 billion of income lost that is mostly never coming back – even if next year we resumed the pre-crisis growth/income path – and losses which have to be (a) borne and (b) distributed. There will be significant business failures. There will be heavy job losses.  And, despite my scenario, it is not as if anyone –  government or private –  can safely plan on the losses being limited to this year and everything being pretty much normal thereafter.

There is a pressing need for the Prime Minister and the Minister of Finance to get real about the magnitude of the economic (and probable social) disruption we are going to face, the price we pay –  even though much of it will be out of New Zealand’s control –  to manage the virus.  Front the public and explain why now is no time for a limited backward-looking package, but for something much more dramatic and whole-of-nation crisis focused, with a time horizon that stresses that “normal” will almost certainly be some considerable time away.

Why the OCR should be cut substantially

I’ve seen a few people on Twitter, typically not economists, casting doubt on the case for an OCR cut.  Twitter isn’t really a suitable medium for serious engagement on the substance of such issues, so here is a short(ish) post, articulating a case that (I suspect) will seem pretty obvious, on most counts, to most readers.  I almost wrote the title to that post as “why the OCR should have been cut substantially”, but actually, and even though I thought the cut should have come in February, the actual announcement matters less than the confident expectation that the right thing will be done at the next scheduled opportunity.  Markets largely trade on expectations, even if short-term retail rates mostly move on announcements themselves.  Right now, it is the Bank’s talk –  see my last two posts –  that bothers me more than that the OCR is still at 1 per cent.

Why should the OCR be cut substantially?

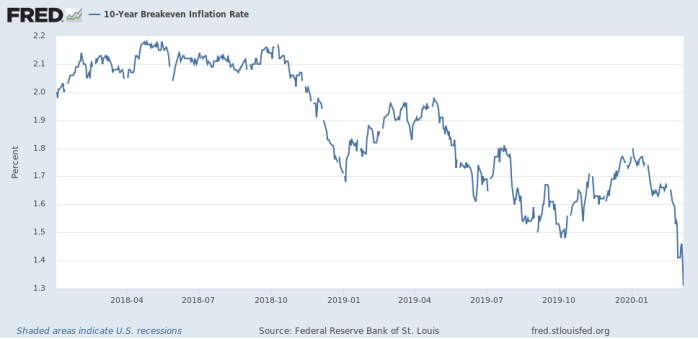
  • because inflation expectations have already been falling (reflected in the bond market and in the ANZ business survey) leaving short-term real interest rates higher than those at the start of the year.   Faced with the facts of this year in early January, no one would have prescribed higher real interest rates as part of the appropriate policy mix.
  • almost certainly neutral short-term interest rates (consistent with being at the inflation target with full employment) have fallen considerably in recent weeks/months.  A useful way of thinking about monetary policy is that it needs to involve at least keeping pace with changes (estimated only) in the short-term neutral rate.   How large has that change been?  Well, one low-end estimate could be obtained by looking at the inflation-indexed government bond market.  Very long-term interest rates won’t be much influenced by how much markets think the Reserve Bank will do this month or next.  So take the 20 year indexed bond and the 10 year one, and you can back out an implied 10 year real interest rate for the ten years 2030-2040.   Even that yield has fallen by 30 basis points since the end of last year, and most everyone would expect coronavirus no longer to be much of a factor.  For the five years from 2025 to 2030, the implied real yield has also fallen 35 basis points.
  • add these sharp falls in long-term real rates to the drop in inflation expectations, and then bring the next year or two into the mix, and it is pretty easy to mount a case for a 100 basis point cut in the OCR.  (In fact, if we were starting with an inflation target centred on 5 per cent and an OCR of 4 per cent (instead of 2 per cent and 1 per cent) almost certainly that is what would have happened by now.  In periods when there is a very sharp fall-off in activity, or a huge surge in uncertainty, you cut the OCR early and decisively.  I suspect fear –  the limits of conventional monetary policy and a lack of conviction in the limited unconventional instruments –  is probably afflicting more than a few central bankers, not just in New Zealand, making them nervous of the limits being shown up.)  If the OCR was roughly in the right place at the last review pre-coronavirus, it is simply inconceivable it should now be anything like as high as it was then.  And yet it is.
  •  a common argument is that an OCR cut won’t do much to demand now.  And I agree. In fact, in some respects it isn’t even obvious we should want to boost some forms of domestic demand now –  more people going out socialising etc.  The scale of the disruption and dislocation we will face in the next few quarters is almost entirely independent of what monetary policy does (any monetary policy effects will be swamped by the scale of the real shock).  But it will, all else equal, ease debt-servicing burdens for both firms and households –  and you’ll have noticed that binding cashflow constraints is one of the prominent themes under discussion at present.   Consistent with the previous point, time has very little value now (materially less than a few months ago) and, at the margin, people (savers) shouldn’t be rewarded for that time, borrowers (on floating rates) shouldn’t be paying for it.   Will people say that is tough on retired savers?  I’m sure they will.  But, tough.  There is huge income loss underway, and “valid” returns to financial savings are just lower than they were for the time being.  It won’t last for even, but it is some of the loss-sharing that needs to happen.
  • looking ahead, whenever the worst of the crisis is over lower interest rates will do the usual job monetary policy does and support a recovery as fast as feasible.  And we shouldn’t wait and cut then for at least two reasons:
  • the first is the exchange rate.  All else equal a lower OCR will lower our exchange rate (failure to lower the OCR will tend to hold it up).  International trading conditions have become very hostile in aggregate and a lower real exchange rate is a natural and normal part of the buffering process.  And despite Christian Hawkesby’s claim (in his interest.co.nz) that the exchange rate is now low, the extent of the fall so far is small by the standards of typical New Zealand recessions: we aren’t getting any interest rate buffering and we aren’t getting much exchange rate buffering either.
  • the second is about inflation expectations.  Core inflation is likely to fall. Headline inflation is also likely to fall (oil prices).  Inflation expectations have already fallen and are likely to fall further.   When interest rates are getting near the feasible lows, the only prudent thing to do is to act aggressively to leave no doubt in anyone’s mind –  markets or public –  that the authorities are doing everything possible to keep core inflation near 2 per cent.  If they don’t convince people, the road to recovery will be harder and slower.  It was the very argument the Governor was using briefly last year when he noted that the risks were such he’d rather inflation ended up above 2 per cent than risk that downside trap.
  • we can still cut materially.  The ECB can’t do much on that score at all, and several other advanced countries are also very constrained.   But we can.  We need to for ourselves, and we also do our (little) bit for the world.
  • it is what you do with a significant adverse demand shock.  In fact, in a standard Taylor rule guidance, it is even what you do with supply shocks that raise the unemployment rate relative to the NAIRU (as this one certainly is) –  I thank an academic for reminding me of this further hole in the Bank’s reasoning.
  • other countries have.  Not all of them – even those who could –  but the UK, Australia, the US, and Canada have.  Perhaps they are wrong, but they are all experiencing very similar shocks, and it is a bit hard to see why Adrian’s judgement on this would be so much superior to those of his peers.  Wisdom of crowds and all that.
  • there is no conceivable downside to cutting the OCR aggressively now.  We aren’t starting with core inflation even at target, let alone above.  In fact, it hasn’t been at or above for a decade.  So at worst, the lower OCR has no effect at all on anything above (very unlikely, since at very least it will alter servicing burdens in a useful, slightly stabilising way).  Or, it works remarkably and astonishingly well, so much so that core inflation surges above 2 per cent.  After the record of the last decade and the threat to expectations, I can only really accentuate the Governor’s message from late last year and say “if so, bring it on”.
  • OCR cuts are easy to reverse when/if warranted, not relying to anything like the same extent as most temporary fiscal measures do on having a secure view of the period over which support will prove to be needed.  It should barely need saying, we have no idea of that now.

And I haven’t even mentioned tightening credit conditions, rising risk spreads, rising cost of equity capital etc.  It really is one of those times for “all hands to the pump”, even recognising that come what may the economic times ahead are going to be difficult and costly and any macro (or microeconomic) policies are going to make only a limited  – but better than nothing – difference for now.

I was just re-reading the post I wrote on the morning just prior to the last OCR decision, making a quick summary case for a cut then.   Most of it still reads pretty well, even if –  like everyone (well, certainly every economist) then, I was grossly underestimating the severity of just what was –  and is – still unfolding.


Almost literally unbelievable

Our central bank that is.

Except that I had to believe it.  The Governor himself was being quoted again in a Stuff article and the video footage of a full interview with his deputy (on the economics and markets side) Christian Hawkesby was on interest.co.nz.

On Tuesday, as I wrote about in my post yesterday, we had the Governor telling us that monetary policy would have no more than a supporting role –  despite being the main cyclical stabilisation tool – that there would be no “knee-jerk reactions”, that we were in “a good space” and  –  perhaps most incredibly of all –  that “confidence and cashflow will win the day”.  Confidence that had tanked, cashflow that was rapidly becoming a problem for many.  It was –  or one really wished it was –  unreal.

But Orr and Hawkesby –  both statutory officeholders charged with the stabilisation role of monetary policy –  were back at it yesterday.  Clearly, the Governor’s voice is most important –  especially with no deep or authoritative figures elsewhere on the MPC –  so we’ll take his new comments first.

Not all of it was silly.  There was the standard advice to firms to talk to their banks early (I imagine that, where they still can, firms might be well advised to draw down any credit lines early too).  But then we get lines like this

Reserve Bank governor Adrian Orr has advised businesses to focus on things they can influence and banks to consider their “social licence” and play a long game to bridge the gap in activity created by the coronavirus pandemic.

“That is it all it is, just a gap,” he said.

Talk about minimisation.  If a firm takes a deep hit to its revenue for six or nine months, and has fixed commitments it can’t get out of at all, and other semi-fixed commitments, what was a viable business can quickly run through any remaining collateral and not be viable at all (the underlying business might be, but not the existing owners).  So sure it is a “gap”, but it could be a mighty big one, with quite uncertain horizons for anything like normality returning.

Most especially because the Governor –  like the Minister of Finance – gives no hint of recognising that the worst  (probably a lot worse) is yet to come.

(And what about that strange suggestion that firms should focus on what they can influence?    What they can’t, really at all, influence is what is likely to be worrying most, more so by the day.)

But the interview goes on

He said he did not believe there was a perception that the bank had been slow to respond to date.

Instead, there were benefits in the central bank getting more information about how consumer and investor behaviour was unfolding and the response of global governments, he said.

“While some talk about ‘what is your interest rate response?’, at times like this central banks have a much broader and important role which is around financial-market functioning and financial institution stability,” he said.

“There, we certainly aren’t sitting on our hands, watching, worrying and waiting.

“We are on high alert around how the financial markets are operating and our role in the provision of liquidity.”

I guess he isn’t reading much of anything –  unless he now has his media clippings selected only for their favourability to him –  if he really believes that first sentence.  Perhaps the case for an OCR cut at the MPS was borderline, but there were plenty of sceptics even then as to whether their talk was taking things seriously enough.  And I haven’t seen many people who thought has remarks on Tuesday were appropriate, responsible, timely, or whatever.  In the meantime, central banks in Australia, the US, Canada and now the UK have acted.

But it was the rest of that quote that really staggered me –  the claim that the Bank had a “much broader and more important role” in this situation around market functioning and financial institution soundness.  Again, what planet is he on?   No one, but no one, believes the coronavirus shock’s economic effects are primarily a financial stability issue.  Really severe recessions could in time generate significant credit losses, but that is well down the track (for banks of our sort).  In things to do with the Bank this is primarily a severe adverse shock to demand (almost wholly a demand shock for New Zealand so far, something neither Orr nor Hawkesby seem to grasp).  These are the guys who go on and on about their new employment-supporting mandate.  Lots of jobs are being lost right now, and will be over the coming weeks and months.   There may be other things governments can/should do, there may be other stuff other wings of the central bank need to focus on, but monetary policy is their macroeconomic business, the tool that can be deployed quickly and flexibly, and which has been in every past crisis.  But Orr and Hawkesby seem to prefer to sit on their hands and gather more information (of the gathering of information in fast-moving, exponential, crises there is no end).

Before coming back to Orr’s final comments, I add some remarks on Hawkesby’s interview.

Assistant Reserve Bank Governor Christian Hawkesby says the RBNZ’s main focus at this point of the coronavirus crisis is making sure the banking system remains strong.

Echoing comments Governor Adrian Orr made on Tuesday around confidence and cashflow being key, Hawkesby said the RBNZ is looking at how funding markets and banks’ relationships with their coronavirus-affected clients are holding up.

“That’s really our first point of call and our main focus – at least in these initial stages,” he told interest.co.nz.

Much the same themes, but how utterly irresponsible.  No sense of his responsibility as a (statutory) monetary policymaker, explicitly charged with a macrostabilisation role.  Doubly so because, as he goes on to acknowledge (and unlike, say, Italy)

“We have a well-capitalised banking system and a well-funded banking system.”

So try looking under the right lamp-post for issues that need to be addressed.

Hawkesby, like Orr on Tuesday, hosed down expectations of large, if not emergency, Official Cash Rate (OCR) cuts in the immediate future.

He said the government could move with more haste than the RBNZ, targeting those most affected by coronavirus.

He also claimed it was “early days”: early days was a month or six weeks ago, when the Bank was doing its MPS forecasts.  This is now a full-throated downturn –  where even the local banks are now talking, belatedly, of recession.

And what of that nonsense about the government being able to move faster.  Not only is it generally not true –  OCR decisions can be taken and implemented almost instantly –  but on this occasion neither party has actually done anything yet.   In  fairness to Hawkesby when I listened to the interview he seemed to be trying to make a point that sectoral issues are better targeted with sectoral policies, but that doesn’t really help him this time, as he went on to say

Hawkesby said: “What we need to think through is, to what extent is it [coronavirus] a supply-side issue around supply chains; around specific sectors being affected – in which case monetary policy can’t provide direct help.”

He said monetary policy would be useful if there is a spill-over effect and a lack of demand and confidence across the economy.

Perhaps he missed the data release on Tuesday showing that business confidence had fallen to levels last seen in 2009.  And when you are talking about the temporary collapse of one of our largest economic sectors –  overseas tourism –  you are dealing with pervasive effects that really only macro policy can do much to lean against.

It is almost as if these guys think they are running some sort of academic seminar, rather than being alert to real world developments –  here and abroad, including monetary policy responses abroad.  Whatever the explanation –  and no one seems to have a good one, they are just failing to do the basics of their job.  In none of any of that was there any mention of the idea that (at least temporarily) neutral interest rates will have plummeted –  the fall in very long-term bond yields is probably a bare-minimum estimate of how much –  and that much of the job of monetary policy is keeping actual short-term rates in line with shifts in neutral.  These guys would appear to prefer to do nothing, even as real retail interest rates are rising. (I’m sure they will move, perhaps quite a lot, as spiralling global crisis will produce a lot of reality to mug them with in the next couple of weeks.)

Oh, and as in the Governor’s remarks on Tuesday, there was nothing in either interview about the threat to inflation expectations. They are falling around the world, and in New Zealand –  seen in the bond market and in the ANZ business survey.  As I noted towards the end of yesterday’s post, it is a strange omission, because only a few months ago both Orr and Hawkesby were dead-keen on emphasising downside risks to inflation expectations and making the case for pro-active least-regrets monetary policy adjustments.  Good and sensible quotes from both of them are included in this post from late last year.    Not sure what happened to those central bankers.  The threats/risks must be much greater now.  But it all fuels a sense that these guys are just out of their depth, with no consistent mental models or sense of the world (or this event) found especially wanting by a crisis.

By contrast there was good workmanlike speech on coronavirus economic issues yesterday by Guy Debelle, Deputy Governor of the Reserve Bank of Australia, Hawkesby’s direct counterpart.  It was what serious normal central banking looks like.

But I wanted to come back to Orr’s final comment in his Stuff interview.

The coronavirus was a reminder of why policies such as the Reserve Bank’s decision to increase the capital requirements of the major banks and to ensure they could operate on a standalone basis had been pursued, Orr said.

“We try to implement them in peace time, because it is hard to implement them in war time – not that I am saying we are in war time.”   

He probably should get his lines sorted out with his deputy: you’ll recall that Hawkesby quote that, at current levels before any of the increased capital requirements take effect, we have a “well-capitalised” banking system.   Which is what the Bank’s demanding stress tests have always shown, and what numerous serious critics pointed out in the consultation process last year.

But even if we take Orr’s comment in isolation, he seems not to recognise at all that whether his announced higher capital requirements made sense in some long-run steady-state, they will have some adverse effects on the availability of credit, rates of investment etc through the transition period.  Orr confirmed that capital requirements in December and they are to be phased in over seven years.   Unfortunately, the beginning of that transition period – when bank behaviour is already being affected (and we saw this in the last credit conditions survye months ago – the next one, presumably taken this month, will be fascinating) – happens to coincide with the nastiest economic shock we’ve had in a long time.   But, at present, no bank’s capital ratios will be any higher now than they would have been if Orr had seen sense and not proceeded (so there is none of the additional buffer he is implying).   As it happens, reported capital ratios  –  though not of course actual dollar capital – would drop before long, because the change to the rules around aligning minimum risks weights for iRB banks with the standardised rules is being frontloaded.

And while no one could foresee that we’d have a severe pandemic shock this year, Orr was warned of exactly this sort of issue: in a climate with little conventional monetary policy capacity, sharply increasing capital requirements over a period when a new recession was fairly probable at some point would simply compound the real economic and economic policymaking challenges.  This was from my submission

Finally, in this section, there was no discussion at all of the macroeconomic context in which these proposals would take effect.  The proposals involved a transition over five years.  Nine years into an economic recovery, with slowing domestic growth and growing global risks there has to be a fairly significant chance that the next significant recession will occur in the next five years (i.e. during the proposed transition period).  That means a significant risk that regulatory policy would be exacerbating any downturn (through tighter credit constraints, reduced credit appetite, and potential higher pricing), in a downturn in which monetary policy is likely to be hard up against conventional limits (the Bank’s own analysis has suggested the OCR might be able to be cut only to around -0.75 per cent).  Of course, if bank balance sheets were looking shaky it would be prudent to move ahead anyway – better ten years ago, but if not then now – but nothing in the Bank’s published analysis (past FSRs, stress tests, consultation document) nor in the credit ratings of the relevant institutions suggests anything like that sort of vulnerability.  Without it, you will – with a reasonable probability – make economic management over the next few years more difficult (additional upfront potential economic costs), in exchange for the modest probability of making any real difference to (already very low) financial system risks over that period. It isn’t a tradeoff that appears to be worth making – at least not without much more supporting analysis than we have had to date.

I’ve seen no sign Orr or his colleagues ever engaged with this point.

And before passing on, don’t overlook this bit from Orr

“not that I am saying we are in war time”

Relentlessly determined to minimise just what is going on and the extremely challenging period –  of indeterminate length –  we are now entering.

But whatever should have been, the new capital requirements are what they are.

There is some discussion as to whether it might make sense to suspend implementation of the new requirements.  In the UK, the Bank of England last night released their Countercyclical Capital Buffer (an element of their capital requirements).  More generally, people are looking at the merits of some regulatory accommodation.

For now at least, I have to say I’m quite sceptical, at least in New Zealand (and I noticed Hawkesby suggested these were conversations for well down the track).  Sure, capital is there to be used as loan losses mount (which, of course, they haven’t yet).  But it is always worth remembering how important expectations are to behaviour –  for bank/bankers as much as anyone else.  So, sure, Adrian Orr could suspend the implementation of the higher requirements, but why would that materially alter the attitude of banks to taking on additional risk?  After all, the Governor tells us this is just “a gap”, but even when reality finally mugs him, the banks –  and their parents in Australia –  will know that the Governor is still sitting there waiting to resume the steady escalation in capital requirements as soon as some modicum of normality returns.   I’m not going to oppose suggestions of a temporary suspensionm but I doubt there would be much bang for the buck in doing so, at least while Orr is still Governor.

It really has been a reprehensibly bad performance so far in this crisis from the Governor, his monetary policy deputy, and the Monetary Policy Committee as a whole (all of whom must, for now, be presumed to be on board – although will the next OCR decision be the first time someone on MPC is willing to record a dissent?).  Looking to the statutue books, you might have been hoping that the chair of the Bank’s board and/or the Minister of Finance –  both responsible for the Governor and the MPC –  would be demanding something better, but I’m not holding my breath about either of them.

There are, of course, more ultimate statutory provisions.  They won’t be used.  But the case is mounting that the Governor, the Bank, Hawkesby, and (as far we can tell) the external ciphers on the MPC simply are not doing their monetary policy job.  It is an utter failure of leadership, something we are now seeing far too much of at the top levels of government as this crisis deepens.  We are paying for unserious appointments, weakening public institutions, in the quiet times.


The unseriousness and unfitness of the Governor

For months the Reserve Bank has promised us some insights on how they are thinking about options for unconventional monetary policy (for use if/when the limits of the OCR are reached).   Last week they announced that they would release yesterday a principles document and that the Governor would deliver a short speech.

In this post I don’t want to concentrate on the substance of the material on unconventional monetary policy.  It is quite troubling, especially when the limits of the OCR may well now be so close, but that will have to be the subject of another post.

In this post I want to concentrate on Orr’s comments about the immediate situation and the approach he and the MPC are taking to communication.

But first take a step back.  It might seem like an age ago but it is only four weeks since the Reserve Bank’s Monetary Policy Statement.  In that statement, and in the Governor’s press conference, the Monetary Policy Committee was really quite upbeat.  Coronavirus effects –  only around China –  would be relatively small and pass quickly.  In fact, the MPC was so upbeat they even moved to a very mild tightening bias.   There was little serious analysis of the monetary policy risks and options –  no analysis, for example, of past stark exogenous shocks and the monetary policy responses – including in the minutes of the MPC’s meeting.  As I wrote at the time

There is no sense of the sort of models members were using to think about the issue and policy responses.  There is no sense of the key arguments for and against immediate action and how and why members agreed or disagreed with each of those points.  There is no sense of how the Bank balances risks, or of what they thought the downsides might have been to immediate action.  There is no effective accountability, and there is no guidance towards the next meeting.  Consistent with that, the document has one –  large meaningless (in the face of extreme uncertainty) – central view on the coronavirus effects, but no alternative scenarios, even though this is a situation best suited to scenario based analysis.   It is, frankly, a travesty of transparency, whether or not you or I happen to agree with the final OCR decision.

In fact, the projections (as usual) had been finalised a week before the final decision –  that works fine often, but this was a very fast-moving situation.

And that was about it.  There were no subsequent speeches from the Governor or his fellow MPC members, internal or external.

Since then, of course, a great deal has happened, little of it –  at least in global terms –  for the better, whether in terms of the progress of the virus itself, business confidence, or financial markets.

And yet the Governor told us he was coming along to give a high-level speech about longer-term monetary options.   In his introduction to the written speech –  all 19 pages of it – he went so far as to claim

Any perceived monetary policy signals in this speech are thus in the eyes of the reader only and not intended by the author.

But context and tone matter a great deal and often tell us a lot.   And, in any case, it seems from various media accounts that Orr took questions at the little event he hosted to deliver the speech, and felt quite free in commenting on coronavirus and the place (or lack of it, as he saw it) for monetary policy.

That in iself, as a matter of process, was pretty appalling.    We are told by an interest.co.nz journalist that Orr did not use his speech text, but instead

Calm vibes from Orr today as he delivered a 30min speech using hand-written notes

but no one who wasn’t there –  and it was an invitation-only event – actually knows what he said, and what emphases he chose.  That is bad enough re the speech itself, but then he ran a Q&A session for which there is no public record, other than snippets from various journalists’ accounts.  On highly contentious, important, market sensitive issues that simply isn’t good enough –  and just would not happen at any serious central bank. (In fact, the Bank itself knows better. Last year they did one of these self-hosted events with (a) an open invitation, and (b) video footage of the speech and Q&As posted on their website, and on that occasion the content was pretty innocuous.)  Does the Monetary Policy Committee and the Bank’s Board –  the latter paid to hold them to account – just roll over and go along with this travesty of good process?  It appears so.

But, anyway, lets try to unpick what he said (and didn’t say) based on the fragmentary records we have.

First, the formal speech text –  which must have been carefully considered and haggled over internally (at least if there is any decent process in place at the Bank, anyone willing to challenge the Governor).   Here is the relevant section

The nature of the economic shock that authorities may be looking to mitigate will inform the choice of tools. A specific supply shock (where goods and services cannot be produced for some reason) may be better managed through fiscal support (both automatic stabilisers and/or targeted intervention), with monetary policy assisting rather than leading.

New Zealand’s current drought conditions in regions of the North Island provide an example of a supply shock. If the drought remains relatively region-specific, and/or short-lived, then monetary policy would have a very limited stabilisation role. Any resulting loss of production may be short-term, and automatic fiscal stabilisers and/or targeted government transfers and spending would be more effective at mitigating any broader economic disruption. Meanwhile, monetary policy would remain focused on any longer-term impacts on incomes and wealth, and hence inflation and employment pressures.

A similar set of considerations confronts policymakers globally at present with the spread of the Covid-19 virus. The eventual economic impact on global supply and demand will depend on the location, severity, and duration of the virus. The optimal mix of policy responses are driven by these same factors.

The severity in terms of disruption to economic activity depends on how the virus is contained and controlled, how long this will persist, and the collective response of governments, officials, consumers, and investors to these events.

The Reserve Bank’s Monetary Policy Committee will be picking through these supply and demand issues. We will need to account for international monetary and fiscal responses, financial market price changes (e.g., the exchange rate and yield curve), and domestic fiscal responses and intentions, to inform our response. We also remain in regular dialogue with the Treasury to assess how monetary and fiscal policy can be best coordinated.

We need to be considered and realistic as to how effective any potential change in the level of the OCR will be in buffering the New Zealand economy from shocks such as a lack of rainfall and the onset of a virus.

…

For us, these monetary policy and financial stability decisions are repeat processes as the duration and severity of events play out. We are in a sound starting position with inflation near our target mid-point, employment at its maximum sustainable level, already stimulatory monetary conditions, and a sound financial system.

Remember that this text is written knowing that the backdrop is the dramatically worsening coronavirus situation –  it isn’t 200 cases in a faraway land anymore.  He’s said nothing for weeks after an MPS that –  at very least with the benefit of hindsight –  didn’t really strike the right note.  He’ll have known the market developments since –  I’m thinking mostly of bond markets, but you can throw in equity markets and credit spreads too.  He may not have had the ANZ Business Outlook data when he finalised the text, but if he was very surprised by the data –  released an hour before the speech was given –  that would be a very poor reflection on the Governor’s comprehension of just what is going on.

So all this was very deliberate conscious drafting, clearly designed to play down, to minimise, the coronavirus economic issues and the scale of the adverse demand shock that has been unfolding for weeks now.   If a junior analyst had set it out this way, it would be one thing, but he is the Governor –  people pay a lot of attention to his words, even if they are often “cheap talk”.

You see, droughts are something the Reserve Bank has never responded to.   There isn’t even the sort of “longer-term” aspect for monetary policy he suggests –  in fact, there is really is almost no longer-term dimension to monetary policy at all;  discretionary monetary policy is designed to be about fairly short-term stabilisation.   So to frame thinking about a monetary policy response to coronavirus in the same breath as droughts, ending

We need to be considered and realistic as to how effective any potential change in the level of the OCR will be in buffering the New Zealand economy from shocks such as a lack of rainfall and the onset of a virus.

and with not a mention of the risks around inflation expectations –  which he was briefly rather good on for a month or so after last year’s unexpected 50 basis point cut –  tells you this is someone looking for excuses not to adjust the OCR, minded not to do so if he could get away with it (which he probably can’t).   A Governor (and MPC) who were seriously concerned –  who recognised, for example, that most of what we’ve seen in New Zealand so far is a big adverse demand shock –  doesn’t need to give away his hand on precisely how much the OCR might adjust, but would almost certainly phrase things differently than Orr did yesterday.  It had the feel of a speech that he might have given a month ago.  Then there might have been some excuses, but now there are none.

And then we turn to the fragmentary accounts of the actual delivered speech and the questions and answers.  The journalist from interest.co.nz reports that

He said, in a speech delivered in Wellington on Tuesday, that the RBNZ won’t have a “knee-jerk reaction” to coronavirus.

He also said monetary policy was in a “support role”, with fiscal policy (government spending) being at the “frontline”.

“Knee-jerk reaction” is one of those lines you use when you disagree with someone’s call for action, and prefer to avoid engagement on substance.  What Orr seems to think of as a “knee-jerk reaction” is (a) along the lines of the actions of the RBA and the Fed, and (b) what others would call bold and decisive leadership, or others still “just doing your job”.

As concerning is that next sentence.  It isn’t his job to decide whether monetary or fiscal policy should be emphasised.  His job is to take account of what he sees and act accordingly to contribute to stabilising the economy and supporting the eventual recovery.     If the government chooses to do something large with fiscal policy –  which there is no sign of yet –  that is certainly something for the Bank to take into account.  But as it is, no policy support –  monetary or fiscal policy –  has yet been given at all.   Sure, the Bank can’t cut the 500bps or so that is typical in a New Zealand (or even US) recession, but their job –  assigned by Parliament –  is to respond strongly to severe adverse demand shocks, and big drops in short-term neutral interest rates, to help stabilise the economy and inflation expectations.    As it is, nothing in the speech suggested any sort of strong lead from the Bank, let alone one that might very soon bring the unconventional tools into play.  It is some combination of an abdication of responsibility and of the Governor’s long-held personal political preference –  it has been backed by no analysis or research he’s produced, let alone by statute –  for a more active, bigger government, fiscal policy.

We then got more of the same in response to questions

Orr said coronavirus posed a fiscal and monetary policy challenge, “but monetary policy will remain in that support role with fiscal policy being very much the frontline activity as it is now”.

“We will be watching very carefully for what is the important monetary policy response we need to make, but we want to do that in the best and fullest information, not some knee-jerk reaction, because New Zealand doesn’t need a knee-jerk reaction.

“We’re in a good space. I’m not sure a knee-jerk reaction would be particularly useful.”

Slogans rather than analysis, again.  He’ll never have full information until it is far too late –  monetary policy has to react to what is evident now and projections of what is coming.  That is what it did in the past –  responding to 9/11, to the 2011 earthquake, even to SARs – but Orr and the Committee never engage with any of this experience or practice.

Oh, and then the final bit from that account that caught my eye was this

“Confidence and cashflow will win the day,” Orr said.

Except that business confidence is through the floor –  lowest since 2009 –  and cashflow is rapidly drying up for many.   Oh, and widespread social distancing, and all the economic costs and dislocation that entails, seems to be not far away at all.   It is as if he was on another planet, where whistling to keep your spirits up was the remedy.

(Reflecting on the Bank’s apparent indifference to the severity of what is unfolding, and its threat to medium-term inflation expectations and nearer-term employment etc, I was reminded of how badly the Bank handled the period of the Asian crisis, as we were playing with the MCI.  Many readers will be too young to really get the reference –  count yourself lucky, but I must write it up one day – but the Governor will recall. He was there too.)

And what of the Herald’s account?

There we got this added snippet following the dismissive “knee-jerk” comments

We’re in a good space.

Who knows, perhaps he just meant that government debt is low.  But there is no other way we can be thought of as “in a good space” to cope with a very sharp dislocation and loss of economic activity this year.  And perhaps he hasn’t noticed that real interest rates –  the ones people are paying/receiving –  have been rising this year.

The Herald reports commentary from an economist who was invited to attend

“He basically hosed down expectations of a sizable interest rate cut and an inter-meeting one,” Bagrie, who attended the speech, said. “He explicitly said, time is on our side.”

It demonstrably isn’t.  Does he have any conception of the exponential growth in case numbers, including in Australia with which we have a largely open border?  Has he not noticed travel bookings drying up –  still almost all a demand shock from a New Zealand perspective.  This is one of those climates where time was never on anyone’s side –  with hindsight (at least) action should have been in place weeks and weeks ago.

And a final quote

“Here in New Zealand we’re in this wonderful position where monetary policy is willing and able to do whatever matters, and fiscal policy is also in a strong and credible position [to respond].”

Except that from the Governor’s words and demonstrated behaviour –  with his Committee sitting in front of him, unwilling to say anything, apparently in support –  monetary policy is transfixed by the shock, doing nothing so far, and reluctant to do very much at all.  Without even so much as a hint of what the risks and downsides the Bank has in mind if monetary policy was used aggressively while it still can be?  I’m pretty sure there was almost no mention that one of the great things about monetary policy is that it can be quickly reversed when the need passes, and another is that it is really easy to implement, something that cannot be said for many of the fiscal schemes –  details of which we have yet to see –  that the Governor appears to so strongly favour, especially if/when the economic dislocation builds, people are sick and/or working from home, and firms and individuals across the economy are feeling the extent of the downturn, perhaps even a temporary shutdown, in the economy.

Fiscal policy isn’t the Governor’s job, although he needs to be aware of it and take it into account.  Monetary policy is –  his and the Committee, from whom we hear so little –  and he simply isn’t doing it.  It is an abdication of responsibility –  reasons uncertain –  that just confirms again his unfitness for the high office he holds.  It also raises equally serious doubts about the rest of the Committee –  I heard an extraordinary story yesterday of one external member scoffing at taking the economic effects of coronavirus seriously –  and those paid to hold them to account.

It reflects pretty poorly on the Minister of Finance too.  After all, the MPC is wholly his creation, and he has legal responsibility for the way they do (or don’t) their job.  And he is the only one in all this with any serious public accountability.

I’m going to leave you with one of the Governor’s good moments.  These words were in a speech he gave in San Francisco last year

In particular, it is now more suitable for us to take a risk-management approach. In short, this means we look to minimise our regrets. We would rather act quickly and decisively, with a risk that we are too effective, than do too little, too late, and see conditions worsen. This approach was visible in our August OCR decision when we cut the rate by 50 basis points. It was clear that providing more stimulus sooner held little risk of overshooting our objectives—whereas holding the OCR flat ran the risk of needing to provide significantly more stimulus later.

You have to wonder what about the world has changed that, in the Bank’s view, makes that sort of approach not the best way forward now –  when the downside risks are much starker and clearer than they were then.

My bottom line on the Governor is that he will probably do the right thing eventually, after toying with or trying all the alternatives.  The global situation looks set to get quite a bit worse in the days before the OCR review, and I suspect the MPC will find themselves finally mugged by reality, overwhelmed by events.  But we need, deserve, a better central bank, a better MPC, a better Governor, than this. After all, as he says, confidence matters, and it is hard for anyone to have much confidence in him, or to count on his words meaning anything from one week to the next.

UPDATE: And here were the quotes I couldn’t find quickly this morning re inflation expectations.  He was very concerned to hold them up then, but apparently much less so now when the substantive risks are so much greater.
 

Coronavirus economics: 10 March

Yesterday afternoon we had the latest round of official comment from the Prime Minister and the Minister of Finance, at the post-Cabinet press conference (transcript here).  It was really just more of the same.  The Prime Minister, in particular, tends to play down the risks to New Zealand, and offers little effective leadership.  Then again, the journalistic questioning didn’t seem very searching – no one, for example, asked about the rate at which Australian case numbers were growing and whether, with an open border and lots of travel (30000 arrivals a week from Australia) we aren’t really just in a Common Virus Area with Australia. “Wash your hands and carry on” seems to be the gist of her message –  as, no doubt, it was for many of her overseas peers….until it wasn’t.  There is still no pro-active discussion with the public about how the government is thinking of handling things just a little way ahead (do or don’t school closures play a part in their thinking, as just one example).

Much the same criticism can be mounted of their approach to the economic costs and dislocations, which will already be mounting by the day.   There are signs –  including in an RNZ interview this morning –  of some greater degree of realism from the Minister of Finance, but he must be constrained in his public comments by the apparent political imperative to play things down, and focus on the China-related disruption rather than on the widening and deepening global situation, and the implications of that for New Zealand.

The Prime Minister and Minister of Finance announced the gist of the package of measures they will actually announce next week (the Minister’s statement is here).   Even setting aside the lack of specifics, what they did announce still seems almost entirely backward-looking.

The Business Continuity Package includes:

  • a targeted wage subsidy scheme for workers in the most adversely affected sectors.
  • training and re-deployment options for affected employees; and
  • working with banks on the potential for future working capital support for companies that face temporary credit constraints;

As if the biggest disruptions and dislocations are not still yet to be, and when they unfold their effects will be pervasive –  almost every firm in the country will be hit to a greater or lesser extent.

Now, the Minister has said that he has officials working on longer-term options (and he is somewhat stymied by having a central bank –  his Monetary Policy Committee –  that isn’t doing its job).  And that leaves me thinking that this “package” to date is as much about politics and being seen to be doing stuff –  especially six months out from an election –  as about a serious response to a worsening situation.    Perhaps that is too cynical, but between Ministers and officials surely there is a recognition of what is near-certain to be, not far down the track?

It isn’t at all clear what sort of sensible dividing line the government has in mind for who is and isn’t going to be eligible (even now, won’t every business in Queenstown and Rotorua being feeling the effect?).  “Training options” must have seemed like a good idea to someone, but if far-reaching social distancing is coming soon –  as Siouxsie Wiles put it yesterday – it is hard to see polytechs etc effectively doing much of such training.

And, on the other hand, there seems to be no urgency around measures that might ensure adequate income support if/when we get to point where large numbers of people –  across a whole range of sectors – simply can’t work (quaratined, self-isolated, or whatever) and their employers’ can’t afford, or won’t pay them.

Then, of course, there is what they won’t do

Media: ANZ’s chief economist says scrapping next month’s minimum wage increase in response to coronavirus is a no-brainer. Are you considering that?

Robertson: No.

PM: No.

Media: Will you consider it at all?

Robertson: No.

PM: I think, in fact, one of the benefits that we have—perhaps relative to other economies—is not only are we well placed in terms of low debt; our position around surpluses, the upgrade package, so that stimulus already going into the economy. Also we have to keep in mind what we need people to keep doing, of course, is continue to spend and consume. And so also the adjustments we’ve already had to benefits, and I would say, of course, what people are anticipating in their wages, is all part of continuing to keep the economy ticking over.

So they might a good talk about maintaining labour market attachment, but they won’t even consider postponing the next minimum wage increase.  Minimum wage increases tend to have their most visible effects in downturns, amplifying the difficulty marginal new entrants and less-able workers have in getting (back) into a job.     As I say, so far the economic policy response looks more like politics.

The one bit of the ‘indicative package’ that was new was this

  • working with banks on the potential for future working capital support for companies that face temporary credit constraints;

That seems to be all we know for now.

But there is likely to be a significant issue there, one which is likely to get much bigger quite soon.

Hamish Rutherford has a piece in the Herald about this, drawing in part on a chat we had late yesterday.  I suggested that one option officials might have in mind could be some sort of guarantee scheme.   As far as we know, banks themselves don’t currently face funding constraints, so there shouldn’t be any need for direct government lending. But banks will become increasingly uneasy about continuing to extend new credit – increased overdrafts etc –  to firms that already have a lot of debt, and where it isn’t clear when (or even if) normality in business conditions and cash-flows will resume.

One other reason why we really don’t want direct government lending is that government (Treasury, Reserve Bank or whoever) has few or no credit evaluation capability, and even less so in extremely uncertain unsettled times.  If something is going to be done along the lines the Minister suggests, it needs to harness the interests and expertise of the banks themselves, who actually know about the businesses –  and key individuals – they’ve been lending to.

I drew some parallels with the guarantee schemes the government put in place –  supported by the Bank and Treasury – in 2008/09 for financial institutions.  The retail deposit guarantee scheme generated a great deal of controversy, but the wholesale guarantee scheme –  designed to help banks tap international markets –  was pretty well-designed (in my view, but I was the principal designer): we didn’t guarantee what didn’t need guaranteeing, and we charged a fairly significant price to banks using the guarantee to ensure they had incentives to graduate from it as soon as possible.  Broadly speaking, they were sensible interventions.  But it is important to remember the context.  Officials and ministers were pretty confident of the credit standing of New Zealand banks –  finance companies were a different issue – (and, where relevant, Australian parents) – we were providing guarantees into an environment where the credit quality of those we were dealing with wasn’t materially impaired, but rather global funding markets had dried up almost indiscriminately.   For what it was worth, we could also cross-check our judgements with market pricing –  CDS spreads – and with the views of external ratings agencies.

None of that is on offer if the goverment is serious about taking on business credit risk now.  Few New Zealand companies are externally rated, few have quoted CDS spreads.  Most just are not that big or (their finances) visible to anyone much other than their banks and owners.  And, of course, in many cases it would be the riskiest credits that banks would be looking to the government to support, creating major incentive and monitoring issues.  For a firm that has next to no debt and substantial physical assets, support from their own bank isn’t likely to be much of a problem for some considerable time.  But for the firms that were straining the tolerance of their bankers anyway, why would it be attractive for the government to take the risk?  Most firms will be somewhere in the middle, but remember that those with the higher current debt levels and those now bleeding cash fastest will be the ones eyeing up the possibilities of government support.  I really wish officials well trying to devise something workable, sensible –  oh, and scalable when things get a lot worse.

(I haven’t really touched on the Reserve Bank’s new capital requirements.  They will be accentuating the difficulties borrowers face this year, exactly as the Bank was warned in consultation last year –  whack on large new capital requirements with the likelihood of a severe downturn in the next few years and you will materially exacerbate problems, when there are few other effective tools.)

On matters re the Reserve Bank we are to get from the Governor this afternoon some thoughts on how the Bank might approach non-traditional monetary policy when/if the limits of the OCR are reached.  No doubt I will write about that material in the next few days, but in meantime as reference here is link to my post about an article the Bank published on the issues and options the Bank published a couple of years ago.

And finally, inflation expectations. I’ve been making the point that there really isn’t a great deal economic policy can do to limit the immediate costs and dislocations over the next few months, and that the focus should really be on getting in place early and decisively policies that will support a recovery as rapid as possible.  Part of that –  and a theme of mine throughout the life of this blog –  has been avoiding any sharp slippage in inflation expectations, which risks “trapping” economies in a very difficult position even after the worst is over, given the current limitations on monetary policy.  Real interest rates could be rising, not falling –  and in the current environment it is probable that real retail rates should be zero or even negative.   I’m sure all that seems quite abstract to many readers, so I wanted to end with a couple of concrete illustrations of the risk.

In this chart I’m sure the breakeven inflation rate for US government 10 year bonds (gap between yields on conventional and indexed bonds) as at the US close this morning.

US IIBs mar 20

These aren’t record lows, but the implicit expectations are much lower than they were averaging just a few months ago.  Much of last week’s 50 basis point cut, simply stopped real interest rates moving higher.   Now, sure, in tense periods these indicators can be thrown around changing (unobservable) risk premia, but this isn’t a time for complacency, when everyone knows there are severe limits to what more central banks can do.  Rational agents will be revising downwards their future expectations, and to the extent they do that poses big risks –  accentuating the deflationary climate that has been building for more than a decade now, not just in the US but throughout the advanced world.

What about New Zealand?   This chart simply shows the gap between the Reserve Bank’s 10 year bond data and the yield on the September 2030 indexed bond.  The latest observation is as at yesterday, but New Zealand 10 year bond rates don’t seem much changed this morning.

nz iib mar 2020

The recent movement isn’t as dramatic as for the US but (a) the starting level –  not much above 1 per cent –  was far too low already, and (b) the direction is clear, and concerning.

We need a much more pro-active central bank, doing its core job.

(In closing, it is curious to reflect that the biggest single form of stimulus to demand/activity in New Zealand since coronavirus become prominent is the spat between Mohammed bin Salman and Vladimir Putin and the resulting collapse in world oil prices.  Who knows how large the stimulus effect will be –  or how significant any countervailing havoc wreaked on, eg, US corporate credits –  but whatever the effect it is larger than anything/everything our goverment and central bank have done.)

Coronavirus economics and policy

Any guesses as to which country currently has the highest number of coronavirus cases per capita?   I’d have got this one wrong, until I happened to spot a table yesterday with some numbers for San Marino.

Anyway, here are the top ten for total cases per million people  (data updated to 1pm).

top 10 COVID 19

Leave out the tiny countries/territories and the next few are Switzerland, Norway, Singapore, Sweden, and France.

On these standard lists of countries and territories –  no matter how tiny –  there are about 230 countries/territories.  At present, New Zealand is about 60th (ie lower end of the worst quartile –  probably not the impression you’ve had from the Ministry of Health or ministers).  Here is a chart of which countries are, right now, just a bit better/worse than New Zealand.

nz covid

Australia, with which we have a pretty open border and lots of movement across it, has about three times the cases per capita.

I’m not sure that the per capita numbers mean a great deal, especially when very small absolute numbers are involved.   One infected family or small cluster here and we’d quickly go shooting up past Taiwan, and despite the confidence the Ministry of Health (and their Minister) keep expressing in public, neither they nor we know what they don’t know.    They presumably know most of the contacts of the people with confirmed cases, but none of the contacts of the cases they don’t yet know, let alone the contacts of those contacts.  It is striking how much open alarm there now is in the United States –  active cancellation of events, top universities moving to online only etc – even though in the per capita ranking the US isn’t much different than New Zealand (in fact, as recently as Saturday morning was a bit further down this unwelcome league table than us).    Perhaps it is a reminder that three weeks ago, Italy had no confirmed cases and now (eg) million people and the heartland of the Italian economy are in quarantine.  Two weeks ago, Italy had the same number of confirmed cases the US has now.

Of course, the other aspect of some relevance is the trajectory of cases numbers over time.  Singapore, Hong Kong, and Taiwan all have had more cases per million than New Zealand.  A few weeks ago there was a real fear of an exponential increase in those places, perhaps especially Hong Kong, where the travel restrictions from the PRC had been imposed only fairly sluggishly and the numbers moving were large.   And yet in all three places, the exponental increase hasn’t happened.   In fact, in Singapore and Hong Kong more than half of all the people with confirmed cases have now recovered.  Presumably the virus isn’t any different, so we should look to behaviour, policies and practices.

Our government and Ministry of Health like to talk up the travel ban, but (eg) Hong Kong never really had one (and places like Australia and the United States did).   What seems much more striking about Singapore and Hong Kong was the extent of social distancing that has been practised for some weeks now.  In Hong Kong’s case, schools and universities were closed. In Singapore, they weren’t but reports suggest huge numbers of people working from home etc.  That also seems to have been the lesson in how the PRC got on top of the virus, notably outside Hubei province.   I like to reason by reference to cross-country comparisons, and so it surprises me how little of the debate or media coverage here is looking through the range of other advanced country experiences.  Instead, we seem to get endless backward-looking upbeat comments from the Prime Minister, Minister of Health, and the Ministry of Health, who seem only interested in encouraging anything much more than hand-washing when it is confirmed that things really are much worse in New Zealand.  They seem reluctant to (a) acknowledge what they don’t know, (b) the nature of incubation periods (if/when things are confirmed to be much worse, we’ll wish policies and practices at least a couple of weeks earlier had been different.   There is a line I read recently that suggested that whatever a country does before a pandemic really breaks out will seem too much, and whatever it does afterwards will seem too little.  With other country’s experiences to go by, it isn’t obvious why our authorities are encouraging such a relaxed attitude.   Surely none of us wants to end up a Lombardy?

Where, of course, ICU beds are a real constraint, so much so that over the weekend there was mention of an Italian technical discussion document mooting the possibility of denying ICU care the very old.  I also happened see this chart over the weekend.  (Assuming these numbers are roughly comparable, you have to look a long way down this chart to find New Zealand.)

ICU

All of which is a bit of a distraction from the main –  economics and economic policy –  focus of this blog.    I’m running late today because The Spinoff asked me to write a short piece this morning elaborating some points I’d made earlier in a radio interview.     Here is what I wrote there, with some elaborations and additional points I didn’t have space for.

The economic implications of the Covid-19 public health emergency are formidable, and are growing by the day.

Most of what we’ve seen in New Zealand so far relates to the epidemic stemming from China and the steps taken to get things under control. Much of the policy discussion, including recent comments from the minister of finance, seems to have focused on attempts to assist firms and individuals in sectors which directly affected.

But that approach risks being a big mistake. It might have been fine if the only material outbreaks of the virus had been in China, and once they got things under control it was only a matter of time – albeit perhaps months – until those specific sectors and firms can get back to normal. But that simply isn’t what we face. Only yesterday the Italian government quarantined one of the major industrial regions of Europe.

Realistically, we have to suppose northern Italy won’t be the last place where life and production will be severely disrupted.  The trajectories of case numbers in various other European countries seem, to date, disconcertingly similar.  And then there is the United States.

Public health experts tell us the virus can be checked, but only with expensive and disruptive restrictions – voluntary or imposed, here or abroad. In her latest column here, Siouxsie Wiles notes:

Another thing we are all going to need to start doing soon is minimising or avoiding contact with other people. This is called social distancing. If you are greeting people, don’t hug, shake hands, hongi, or kiss. Bump elbows or feet instead. Work from home if you can. Much as it pains me to say it, social distancing also means avoiding public transport (get on your bicycle!). Similarly, it means avoiding gyms, churches, cinemas, concerts, and other events and places where people congregate.

Already, airlines report that forward bookings have dropped away sharply, and foreign tourism is heading towards zero for a time. It won’t be the only severely adversely affected industry, and the effects will be felt widely.

I found it very interesting that Wiles –  who seems to know whereof she speaks on the viral things, and seems to be no panic-monger –  was prepared to use, of New Zealand, the words “we are all going to need to start doing soon”.  That isn’t at all the message our happy-talking political and official leaders are giving.

Economic policy needs to be focused not primarily on the limited and concentrated economic disruption we’ve already seen. Instead, ministers and officials need to focus on the much, much larger, but scale-uncertain, losses and disruption that will soon break on us, and on vulnerable individuals rather than firms. As importantly, we need to be positioning ourselves to ensure that when the epidemic passes – and that could be some time – we are positioned to get overall demand and economic activity back towards normal as soon as possible.

Much of the economic loss and disruption we are near-certain to face over the next few months is now all but unavoidable. Nothing we do will put tourists back on plane, or open up supply lines from Milan, or whereever the next place to clamp down severely is. When people choose to stay home and maintain those distances, spending and economic activity will drop. It is the price we will pay as governments here and in other countries seek to spread out and reduce the incidence of the virus itself, and as individuals seek to limit our personal risks.

This point cannot be made too often.  Between choices here and individual and policy choices abroad much of the economic disruption is simply unavoidable.  There will be large losses of production, significant jump losses, material numbers of business failures, and significant permanent losses of wealth.     Much of what any spending can do now is really more (re)distributional in nature, than about changing the short-term course of GDP.   There is place for such distributional measures –  we don’t want sick people at work who can’t afford to take time off –  and in my view short-term measures should probably focus on income support, erring on the generous side where necessary.

Trying to directly assist individual firms is a fool’s errand. We just don’t know what we will be dealing with just a few weeks from now. Very soon the number of firms that can plausibly claim adverse effects will be huge. We simply don’t have the capacity to administer complex tailored schemes for huge numbers of firms, and the way would inevitably open up to all sorts of rorts and abuse.

To repeat, facing what is likely to unfold over the next few weeks or months, we need systems that are clean and relatively simple, and don’t rely on either government or the recipient firms being fully resourced to manage them.

That is why we have macroeconomic policy tools, which are designed to operate pretty pervasively when activity across the economy is hard-hit.

Monetary policy is typically the main one. The Reserve Bank is already quite badly behind the game in not having cut interest rates. No doubt they will do so later this month, but they need to cut the OCR hard, and to err on the side of what might look like doing too much. The risks of actually doing too much are slight, and the risks to falling short are substantial. Among them is a risk that expectations about future inflation drop materially further, which would raise real interest rates in the face of this severe and complex shock, greatly complicating the eventual recovery.

But monetary policy is approaching its limits. This is one of those (quite rare) times when monetary policy really needs to be supported by a significant and, when activated, fast-working boost from fiscal policy.

The OCR can probably be cut by up to 175 basis points.   Whether the last few cuts make any real difference, even to the exchange rate, is a contested point, but we won’t know if –  faced with big drops in activity in demand –  the limits aren’t pushed.

Big infrastructure projects are largely beside the point here – they simply take too long to get under way. One-off cash payments to households probably also aren’t the right thing, at least now. In the next few months people will be hunkering down anyway, and as I’ve already noted, a key consideration is providing support and confidence as and when the worst of the virus – and attendant direct economic disruption – has begun to pass. One possible tool, as part of a package, would be a significant, explicitly temporary, cut in the rate of GST.

Such a cut could be implemented quickly, would put more cash directly in the pockets of households, would operate in a somewhat progressive way (poor households spend a larger share of this year’s income than upper-income households) and explicitly encourages people to buy early rather than later (because you know prices will be rising again in, say, 18 months hence when the GST rate goes back up again).

This instrument was used in the UK in 2008/09.   The key point I’d add here is that in thinking about stabilisation and supporting recovery in the next 12-18 months we – including political parties from all sides of politics –  shouldn’t be focusing on our longer-term preferrred policy changes, but on things that are likely to do the stabilisation job (and can then probably be unwound –  as monetary policy).  That is also the way towards keeping a reasonable degree of cross-party consensus if the crisis is being welll-handled, rather than a sense that one side or the other is using the crisis opportunistically.

The key point now is that the government has to be looking forward, not backwards, and acting in ways that take seriously the sheer scale of the costs and dislocations we are just about to face. Whatever New Zealand does, we can’t avoid many of the short-term costs that are coming, but we can do a little to mitigate the damage (in an environment like this, for example, retail interest rates probably should be near zero, which they aren’t now) and official actions now can help create a climate most supportive of an eventual recovery. We need people to be confident of aggressive action focused on the real issues. In these circumstances, there are few or no returns to half-measures.

All manner of stresses and problems are likely to come to light, here and abroad, if this virus continues to wreak havoc –  or require far-reaching restraints (self or government imposed) over the next year or more – to keep it in check.  It would be foolhardy to assume that full recovery will be quick and easy, all the more so if macro policy has not done what it could to, for example, keep inflation expectations up.


Jami-Lee Ross’s speech

A couple of weeks ago I wrote the National Party, Jami-Lee Ross, and the party’s funding from PRC-linked sources.  Of Jami-Lee Ross –  and the desire of some in the media (and, of course, the National Party) to pile on to him, or to gloat – I wrote

Whistleblowers have a wide variety of motives, and not all of them are noble –  and even those with elements of nobility are not infrequently tinged with more than a little of the less savoury side of things.   And yet we rely on whistleblowers to uncover lots of wrongdoing: in specific circumstances, we even have statutory protections for them  (but whistleblowing often comes with costs to the whistleblower, perhaps especially if they themselves have been directly involved in the alleged wrongdoing).

and

Perhaps he just generally was not a very nice or admirable person –  there are, for example, those reports of his flagrant, repeated, violations of his marriage vows etc.  But the fact remains that this wrongdoing (as alleged by the prosecutors for the SFO) would not be known had Ross simply stayed silent, whether that had involved continuing his efforts to climb National’s greasy pole, or just moving on quietly.     Either might have suited the National Party.   But it isn’t clear why such silence – about these specific donations, or about his involvement with others (Todd McClay and the PRC billionaire) that aren’t illegal but aren’t universally regarded as proper either – would have been in the wider public interest. 

and

And to Ross’s credit, since the story first broke (and all the drama of that time) Ross does seem to made some effort to contribute constructively to the public debate on some of the policy issues around donations to political parties.  He participated in the Justice committee’s (rather lame) inquiry into foreign interference, and spoke very forcefully in the House when the government was pushing through its travesty of a foreign donations law in December (the one that accomplished almost nothing useful,but perhaps looked/sounded to some like action).    Who knows quite what mix of motivations he has.  Perhaps some desire to bring down the existing National Party leadership (in Parliament and outside) with whom he previously worked so closely.   Perhaps some element of genuine remorse, or recognition of how far he himself had been part of the system degrading.    In a way, his motives don’t matter –  it is the facts and the merits (or otherwise) of his arguments. 

We heard from Ross again this week.  Or, strictly speaking, Parliament did.  Few of the general public will have heard of his speech or, more particularly, its contents.  From what I could see there was very little media coverage –  I should have been able to say “astonishing little” but, sadly, there wasn’t much astonishing about the relative silence of our media and the complete and utter silence of the rest of our politicians and political class.   All of them appear to prefer to look the other way, and wish the issue would simply go away, whether for fear of upsetting Madame Wu and the PRC, upsetting the CCP’s local associates, or of revealing to the public just how tawdry and sold-out to Beijing’s interests so much of our politics seems to have become.

I could just link to the speech, but not many people click through to links.   So here, as permitted by Parliament, is the whole thing.  It isn’t long. I encourage you to read and reflect on it

JAMI-LEE ROSS (Botany): Facebook memories reminded me this morning that today marks nine years since I was first elected to Parliament. I certainly never expected nine years ago that I would be the centre of a debate over foreign political donations, and I’m using that term deliberately. Foreign political donations and foreign interference is what I want to focus my time on here.

In the Prime Minister’s statement, that we are debating, the Prime Minister lists as one of her Government’s achievements the banning of foreign political donations. It’s true that the new $50 threshold for overseas donations is an improvement. But, as I’ve said previously in the House, I doubt it will do very little to deter those determined to find other ways around the ban, including—

SPEAKER: Order! Mr Jackson leave the House.

JAMI-LEE ROSS: —using the wide open gap we still have where foreign State actors can funnel funds through New Zealand registered companies.

The foreign donation ban is one of the few recommendations that has spun out of the Justice Committee’s inquiry into foreign interference activities in New Zealand elections. That has been picked up. Probably the most important submissions that we received through that inquiry were those from Professor Anne-Marie Brady of Canterbury University and what we heard from the Security Intelligence Service (SIS) director, Rebecca Kitteridge. It was all eye-watering and eye-opening stuff and sobering for us to hear and read their evidence. We have not, and I think we still do not, take seriously enough the risk of foreign interference activities that we’ve been subjected to as a country. Ms Kitteridge rightly pointed out in her evidence that the challenge of foreign interference to our democracy is not just about what occurs around the election itself. Motivated State actors will work assiduously over many years, including in New Zealand, to covertly garner influence, access, and leverage.

She also specifically pointed out the risks we face from foreign State actors through the exertion of pressure or control of diaspora communities and the building of covert influence and leverage, including through electoral financing. After Pansy Wong resigned from Parliament, I was selected as the National Party candidate for the 5 March by-election nine years ago. It was made very clear to me at the time that I had to put a big emphasis on getting to know the Chinese community. It was also pointed out to me very early on that I must make good connections with the Chinese consul-general. Madam Liao at the time was very influential with Chinese New Zealanders, and important to my own success as well. In hindsight, it was naive of me to not think carefully about the pull that a foreign diplomat had on a large section of the population in my electorate.

The consul-general in Auckland is treated like a God, more so than any New Zealand politician, except probably the Prime Minister of the day. Each successive consul-general seemed to be better and more effective at holding New Zealand residents and citizens of Chinese descent in their grasp. Consul-generals Niu Qingbao and Xu Erwen were also treating us, as MPs—not just myself, others—as long-lost friends. All this effort, if you read Professor Brady’s paper called Magic Weapons, is a core plank of the Chinese Communist Party’s deliberate and targeted efforts to expand political influence activities worldwide. It’s also the very risk that Rebecca Kitteridge warned the Justice Committee about. Professor Brady’s paper is a 50-page academic work. I can’t do it justice here, but I recommend all MPs read it.

The activities of the Chinese Communist Party here domestically, where Chinese New Zealanders have been targeted, should be concerning enough for all of us. But the efforts that Chinese Communist Party – connected individuals have been making over the years to target us as politicians, and New Zealand political parties, also needs to be taken seriously. Every time we as MPs are showered with praise or dinners or hospitality by Chinese diplomats, we’re being subjected to what Professor Brady calls “united front work”. Every time we see our constituents bow and scrape to foreign diplomats, it’s a result of their long-running efforts to exert influence and control over our fellow Kiwis.

Both Professor Brady and director Kitteridge have warned about the risk of foreign interference activity where funding of political parties is used as a tool. This isn’t necessarily unlawful provided the donations meet the requirements of the Electoral Act. In 2018, I very publicly made some allegations relating to donations. I have said publicly already that the donations I called out were offered directly to the leader of the National Party at an event I was not in attendance at. I did not know at the time that those donations were made that they were in any way unlawful. I never had any control over those donations and I have never been a signatory of any National Party bank account in the time that I’ve been an MP. I never benefited personally from those donations. I was never a part of any conspiracy to defeat the Electoral Act. And the point at which I blew the whistle on these donations—first internally, then very publicly—that point came after I learned new information that led me to question the legality of the donations.

After raising these issues publicly, they were duly investigated first by the police and then the Serious Fraud Office. The result of those allegations is already public and I can’t traverse much detail here, but I will say that I refuse to be silenced and I will keep speaking out about what I know, and have seen, goes on inside political parties. I refuse to be quiet about the corroding influence of money in New Zealand politics.

Last year, I learnt, off the back of concerns I myself took to the proper authorities, that the National Party had been the beneficiary of large amounts of foreign donations. These donations are linked back to China and linked to the Chinese Communist Party, and with ease entered New Zealand. I didn’t go searching for this information. I was asked if I knew anything of the origins of the donations. I didn’t know. It was all new information to me, and I was surprised by what I learnt.

What I learnt was that large sums of money adding up to around $150,000 coming directly out of China in Chinese yuan over successive years ended up as political party donations. Two individuals, _________, were used as conduits for the donations.

These funds eventually made their way to the New Zealand National Party. The New Zealand National Party still holds those funds. The National Party is still holding at least $150,000 of foreign donations received in two successive years. I call on the National Party to return those foreign donations that it holds or transfer the money to the Electoral Commission. I doubt the National Party knew at the time that the money was foreign—I certainly didn’t either—but now that they will have that information to hand, they need to show leadership and do the right thing.

To avoid doubt, this $150,000 dollars’ worth of foreign donations is not the same as the $150,000 from the Inner Mongolia Rider Horse Industry company that they raised last year.

The warnings sounded from academics and spy agencies are not without reason. These two examples I give are very real examples of foreign money that has entered New Zealand politics. Professor Brady, with reference to the list of overseas members of the overseas Chinese federation, which is part of the Communist Party’s infrastructure, listed three top united front representatives in New Zealand:

_____, _____, and Zhang Yikun. All three are well known to political parties.

In a recent press statement from a PR agency, representatives of Zhang Yikun highlighted the philanthropic approach that he takes in New Zealand. The press statement on 19 February specifically said that he has been “donating to many political parties and campaigns.”, except his name has never appeared in any political party return. When asked by the media if political parties had any record of donations from this individual, all said no. But a quick search online will find dozens and dozens of photos of Zhang Yikun dining with mayors and MPs over the time, inviting them to his home, and his recent 20th convention of Teochew International Federation had a who’s who list of politicians turning up, including a former Prime Minister.

The foreign donations I mentioned earlier all have connections to the Chao Shan General Association. The founder and chairman of Chao Shan General Association is Zhang Yikun. To summarise these two bits of information, the largest party in this Parliament has been the beneficiary of large sums of foreign money. That money is linked to an individual who was listed as one of the top three Chinese Communist Party united front representatives in New Zealand. That individual’s PR agents say he has donated to many political parties and campaigns, yet he’s never showing up in any donation returns in the past.

One of Professor Brady’s concluding remarks in her submission to the Justice Committee was that foreign interference activities can only thrive if public opinion in the affected nation tolerates or condones it. We must not tolerate or condone any foreign interference activities. We must also not stay silent when we see problems right under our nose. It’s time for the political parties in this Parliament to address seriously the political party donation regime that we have.

I realise that both the two main parties in this Parliament often have to agree, but perhaps it’s time to put that out to an independent body. It’s too important for us to ignore, and it’s not right that we should allow these things to go on under our nose.

I seek leave to table two charts that show a flow of money from China into New Zealand and to the New Zealand National Party.

SPEAKER: I seek an assurance from the member that these charts are not integral to any matter currently before the courts.

JAMI-LEE ROSS: These charts have been prepared by the Serious Fraud Office and I cannot give you that assurance.

SPEAKER: You cannot give me that assurance. Well, I’m not going to put the question.

Source: Office of the Clerk/Parliamentary Service. Licensed by the Clerk of the House of Representatives and/or the Parliamentary Corporation on behalf of Parliamentary Service for re-use under the Creative Commons Attribution 4.0 International licence. Full licence available at https://creativecommons.org/licenses/by/4.0/.

Anne-Marie Brady fills in the gaps –  names – Hansard chose to omit from Ross’s speech.

I thought three things were particular interesting in what Ross said:

  • the explicit guidance given to him as a new candidate/MP about currying favour with the PRC Consul-General et al,
  • the allegation about the new large, apparently disclosed, donation from people with very strong PRC/CCP ties
  • and the suggestion, not verified in what we have there (tho perhaps in that SFO schematic he tried to table) of the funds for these donations having come initially from the PRC  (whether or not National initially knew that).

Quite possibly, none of that activity was illegal.  But even if so, none of it is proper –  at least in a political party that cares anything about the values and interests of the vast mass of New Zealanders.  Then again, this is the same party that just re-selected the former PLA intelligence trainer, (former?) CCP member, clearly still in the very good graces of Beijing, Jian Yang for their list –  the same MP who refuses to face questions from the English langauge media in New Zealand, the same MP in business with the party president who himself has been free with his praise of tyrants of Beijing.

But just as bad is the apparent determination of ever other political party –  but most especially Labour, the alternative main party –  to simply ignore all this. In some cases, perhaps, to envy National’s ‘success’ (until now).   Where is the leader of the Labour Party on these issues (you know her, she happens to be the Prime Minister).   Where are the Greens, who once could have been counted on to deplore this sort of thing?   Where, even, are the tiddler parties trying to convince us they offer something different and better than National and Labour?  ACT?  TOP?  New Conservative?  Maori?  Not a word.

I’m sure there is some sensitivity about not jeopardising the prospects of a fair trial in the specific cases the SFO has taken against three donors and Ross himself.   But there is no way that is anything like the whole story.   After all, all those other parties have been very very quiet on the Jian Yang story, ever since the first of it broke 2.5 years ago.  Prominent National and Labour figures, including Jian Yang, got together to have the Crown honour Yikun Zhang for, in effect, services to Beijing only 18 months ago.  There has been no action on closing the legal window for donations through companies owned by foreigners, let alone the (im)moral window that has had NZ citizens who are CCP affiliates donating heavily.  I’m quite prepared to believe that National is deeper in all this stuff than the other parties, but those other parties lose any excuse, any sympathy, when –  most especially the Prime Minister –  simply sit quiet and walk on past. In doing so, they demonstrate their own standards –  or lack of them.

It certainly is important to ensure a fair trial. But voters are also entitled to a fair election, where the sorts of material Jami-Lee Ross has highlighted, allegations made, are properly scrutinised and the actions of parties and key individuals contesting the election are put under the spotlight before the election.  The trial isn’t going happen before then, Simon Bridges refuses to answer even basic factual questions, and the media and his political opponents seem happy to just let it pass.   That is little more than a betrayal of the public interest.


A few coronavirus economic policy points

I’m staggered at how the government and most of the media still seem to have a backward-looking approach to coronavirus, and the economic effects thereof.  When the New South Wales Minister of Health yesterday indicated that in his view successful containment was now very unlikely, one might have supposed this would be big news in New Zealand.  After all, not only are there lots of New Zealanders in Sydney, but lots of people travel to and fro each day, and there are no restrictions or isolation requirements on those travellers.  If –  and it is presumably still an if –  containment is not likely to be successful in Sydney then surely, given that we haven’t had travel restrictions up to now and are unlikely to put them in place on Australia, it isn’t likely to be successful here.  It was, after all, the Prime Minister the other day who talked (loosely no doubt) in terms of a “common border”.     But I haven’t seen or heard of any comment from any of our political leaders, and no media outlet I follow has highlighted the story even though –  if it is so –  it must have material implications for how life might unfold here very quickly.  (For example, there is a community festival just down the road from here on Sunday, which annually attracts 80000 people in a pretty confined space. I don’t go, but people who are planning to might want to rethink.)

On issues of substance most of our political leaders seem either missing in action or, again, mostly backward-looking, as if coronavirus is something that happened in China and we are now just working through over the next few months/quarters the economic consequences of what has already happened.   On the evidence to date it is far from obvious that the Prime Minister has what it takes to lead and effectively drive the national response to an emerging, highly uncertain, serious ongoing crisis.  The Minister of Health seems to be missing in action (which, one hears, is often how officials thought of him in normal times).  And who else is there?   Kelvin Davis? Winston Peters? Phil Twyford?   I’ve heard suggestions that Grant Robertson “gets it”, but there continues to be great reason to doubt that, whether in his speech last week, his Q&A interview at the weekend, or one with Mike Hosking this morning.  It is all focused on stuff that has already happened, and the outworkings of that, and not at all on the worsening outlook, and the near-certainty of huge disruption and cost when community outbreak becomes a thing here.    Thus he continues to talk about “measured proportionate sectoral” responses, when in reality much the economy is likely to be overwhelmed for a time by what is unfolding.  You get no sense of that from Robertson.

I was initially supportive of the travel ban the government put in place several weeks ago.  It seemed prudent, and of course the Chinese government had put its own restrictions on outbound tourism.  I see quite a lot of commentary about how that ban “bought us time” or “kept the virus out for several weeks”, and I guess in years to come researchers will try to unpick the evidence on that one.  But I must confess to being a bit more sceptical now than I was.  Canada, for example, had no travel bans of its own, and yet when I checked this morning they had about eight times as many cases as New Zealand…..and almost eight times the population.  (And are not far from Seattle).  Neither country seems to have done a great deal of testing, so it isn’t simply that one country was finding more because it was searching harder.   It is impossible to easily know the counterfactual, of course, but perhaps the horse had already bolted by the time the travel bans were put on?  Again, superfically it isn’t obvious that the UK experience (no bans) has been worse at this point than the Australia or US experience.

Consistent with my post yesterday, I remain deeply sceptical of sectorally-targeted or admin-intensive specific government interventions to assist.   I see that in today’s Herald Hamish Rutherford is championing those sorts of programmes, under a subheading “Govt must act now to help hurting sectors take heart”.   Frankly, it is never the government’s job to help firms or sectors “take heart”.  The head has to be what is engaged in times like this.     Debate around these issues isn’t helped by an ongoing refusal, pretty much all round, to call what is happening right now what it is: an economic recession.    We might not have hard data on that point for months (even March quarter GDP includes January where there was little or no effect) but here, now, in March it seems almost certain that the level of economic activity is falling.  It is almost certain to fall further, perhaps at times a long way.    Forget about every other sector, all the supply chain disruptions etc and just focus for a moment on travel.  These were some forward travel booking numbers for Australia published in The Australian this morning.

“Between Feb 24 & March 1, year-on-year, bookings were down 47% from UK, 52% from the US, 71% from Indonesia, 32% from India and 100% from China and Japan, along with widespread cancellations.”

Is there any reason to suppose the New Zealand picture would be much different?   Uncertainty is the enemy of new investment, and uncertainty –  pure uncertainty, not just risk –  is extreme at present.  At present, not even the Leader of the Opposition is willing –  quite –  to call a spade a spade.

In recessions, bad stuff happens.  Firms fail.  People lose their jobs.  Plans are wrecked or disrupted. Asset prices fall.  Government revenue takes a hit.  (Government financial assets fall in value: see NZSF).  It isn’t pleasant, and usually those who bear the brunt aren’t in any very direct sense causally responsible for what happens to them, or their firms.    Much of the argument for focused sectoral action –  there is a lot of this in Rutherford’s article –  is along the lines that unless all these firms and jobs are saved now, recovery will be materially harder than it needs to be: the capacity mightn’t be there to take up the recovery in demand.  But, again, all recessions are like that.  But it isn’t as if the capital stock is going away.  Motelliers in Queenstown might go bust – I saw one this morning quoted as saying he could cope with downturn in Chinese numbers, but it would be problematic if others stopped “and that now looks as if it is happening”.  But the motel will still be there.  A jetboat or paragliding or whatever company might fail –  and that is tough, the flipside of the success operators capture in unanticipated boom times –  but the physical equipment and the location are still there.  And since this seems to be a worldwide thing, even if staff have to move and look for other jobs, many (or a next generation) will be quickly enticed back for whatever drew them to (say) tourist work in the first place.

And while it might have been easy a few weeks ago to identify specific firms that had lost directly associated with the virus, those numbers are rapidly going to be overwhelmed as the effects spread across the entire economy  – just as surely, if indirectly, the result of the coronavirus, and measures to manage/avoid it.   In recessions, for example, property markets tend to do badly –  see the 15 per cent fall in real house prices in New Zealand in 2008/09 despite a 400bps fall in mortgage rates – turnover will drop etc etc, and real estate agents will quite genuinely be able to blame the coronavirus for the slowdown.

You simply can’t sensibly target each firm/sector in the economy.  It is why we have macro policy –  economywide instruments designed to do what can be done to stabilise the downturn (that may not be much) and then lay a platform for as fast a recovery in demand and activity as can be achieved.   As it is, it is simply bizarre that with all that is observably different since, say, December, and all that is pretty visible just down the track, our macro policy settings are barely changed:  short-term wholesale and retail interest rates haven’t moved, nothing about (short-term impacting) fiscal policy has changed, the exchange rate is certainly a bit lower (but a modest move by historical standards) and on the other hand it is likely that credit conditions are tighter than they were.   There is an urgency about action, but that action should primarily be focused at the macroeconomic level.

And, finally today, I have been wondering how one might do an analysis of just what economic price is worth paying, as a society, to try to contain/manage coronavirus.  The Chinese economy and society seems to have paid a fearsome price and yet to have successfully (for now anyway) kept the worst of the spread of the disease in Hubei province (for anyone doubting the logic, I found this thread from a China-focused researcher helpful).

Serious scholars suggest that if the virus were simply left unchecked, it might infect 40 to 70 per cent of the world’s population (say 50 per cent).  For all the uncertainty about the true death rate, assume for the sake of argument 1 per cent of those infected.  In New Zealand terms, that is a potential total of early deaths of 25000.

According to the Treasury’s CBAx spreadsheet, the value of a statistical life (price community would pay to avoid premature death) this year is just on $5m.   25000 people at $5m each is $125 billion.  However, the evidence so far – including the Chinese data –  is that the deaths are very concentrated among older people.   On the Chinese data –  which may have its weaknesses –  the median age of those dying looks to have been as high as the late 70s, whereas the median age for all New Zealanders last year was 37.3. Remaining life expectancy at 80 seems to be about a quarter of that at 37, so we can chop down that maximum possible saving (from avoiding premature deaths) to no more than, say, $31 billion.

But, of course, even that is too high, since the implicit assumption is that all those lives could be saved with appropriate policy responses.  And from everything I read that seems incredibly unlikely.  Often people seem to talk about using policy measures and costly private actions (distancing etc) to spread out peaks and reduce the intense, perhaps overwhelming, peak pressures on the health system, and thereby (a) reduce the number of deaths and (b) make the whole experience less intolerable for those who would die anyway and those who, while sick, live.   Obviously I have no idea how many lives might be saved in total, but no one seems to seriously suppose it is anything like all of them.  If it was half, it would –  all else equal – be worth spending $15 billion or so to avoid those premature deaths.

Of course, if we could reduce the number of those who got seriously ill (but didn’t die) as well, it would be fair to ascribe a value to that too, but if people are up and about again in a month –  or even two –  that number will be swamped by the costs of death, given that in many cases those getting the virus won’t themselves be that sick at all (bad colds seem to be “one of those things” in life).

This is mostly by way of leading up to the question of how large would be discretionary economic costs be.  Note that I emphasise the word discretionary.  What other countries do as a matter of policy, and what other individuals do as a matter of prudence/fear is largely outside our control.  Thus almost all –  the exception perhaps being around university students – the economic effects so far are outside our control, and so is the temporary collapse in the rest of our tourism industry currently getting underway.  We will pay –  in lost output –  those costs whatever New Zealand governments do.  If major cities in other countries shut down for weeks at a time, disrupting travel, supply chains, demand for commodities or whatever, we have no real control over that.   Annual GDP at present is around $300bn.  It isn’t hard to envisage a scenario, quite outside our control, in which GDP for this year as a whole is perhaps $10bn less than otherwise.  That is income/wealth that will never be made up, even if/when after the crisis we get back ont a pre-crisis path.

The big choices are likely to be around how early/aggressively our authorities choose to act in shutting down cities, discouraging (or banning) social gathering, restricting movement etc etc.  We don’t really have hard data for other places yet, but what we know of the Chinese data suggests that these costs too could be very substantial –  not only has much of China been closed for six weeks already, but they are a long way from being back to normal, and with no idea what sort of virus resurgence they would see if they tried.  Shutdown, possibly pre-emptively (if still possible), much of New Zealand at different times for, say, six weeks at time.  In doing so, you could easily cut GDP during those shutdowns by 50 per cent.  Even if things quickly got back to normal after that, you’d still be looking at, say, 5 per cent loss of GDP for the year as a whole.  5 per cent of GDP is $15 billion, lost and never coming back.

I’m not attempting to offer answers here.  There are so many imponderables, most especially about what difference the toughest sustainable measures can eventually make to the death toll.   But it would be good to think that some of those “brightest New Zealanders” Hamish Rutherford told us were beavering away on these issues have at least been trying to think about the options in a systematic cost-benefit sort of way (here I emphasise the past tense, since time would appear to be of the essence, and you would hope officials haven’t shared in their masters’ public-facing sunny optimism about the threats we face). But if they haven’t done it yet, they need to be doing so now, urgently.