Risk-sharing mortgages: Mian and Sufi

Last week I wrote

In their recent book House of Debt, the US academics Atif Mian and Amir Sufi, argued that equity-sharing contracts should become the norm for housing finance.  They argue that such contracts would materially reduce the risk of financial crises, and that the main reason such contracts aren’t common is because of the tax system and the role of US government agencies.  I’m very sceptical of both claims

And here is why.

In the final chapter of their book (so it isn’t the focus of their analysis) Mian and Sufi advocate the introduction of what they label “shared-responsibility mortgages”.  Under these contracts, when house prices in the borrowers’ locality fall the borrower gets an automatic reduction in the principal amount of the mortgage.   The cost of this (what is, in effect, a) put option is covered by providing that five per cent of any nominal capital gain would go the lender (either when the house is sold, or when the loan is refinanced).  In some cases, that payment would go to the lender in just a year or two, but in other cases it might take many decades.

If such residential mortgages were widespread, no mortgage borrower would ever have negative equity in their house as a result of movements in the general level of houses  (severe neglect of maintenance, or specific issues in, say, the street your house was located in could still result in a small number of cases of negative equity).  Whenever general house prices (in your part of the city) fall, the loss is shared with the mortgage lender, and your equity share in the house does not change.

Mian and Sufi argue that this feature would have greatly reduced the severity of the 2008/09 Great Recession in the United States.  In their story –  the thrust of their book –  the severity of the recession was mostly due to the negative equity so many borrowers had once house prices fell, and the impact of those wealth losses on consumption.  I find that story unconvincing.  I’ll skip the detail here, but the paths taken by the New Zealand and the United States economies have been so similar since the mid 2000s, and yet New Zealand had very little sustained fall in nominal house prices, and few cases of material negative equity.  Given that, it is difficult to be confident that falling house prices, and associated wealth losses, are a key causal factor explaining why economies are still lagging so far behind pre-recession trend GDP levels.   For example, fluctuations in house-building activity –  booms and busts –  are much more important than Mian and Sufi recognise.

But I wanted to focus on the suggestions that shared-responsibility mortgages (SRMs) would materially reduce the risk of financial crises, and that the main reason they don’t exist is the role of various government interventions.

Why might the risk of future financial crises be reduced?   They argue that

the downside protection in SRMs would lead lenders to worry about future movements in house prices.  If house prices plummet in the near future, then more recently issued mortgages would generate the greatest loss for the lender.  The lender would have to be very mindful about potential “froth” in local housing markets, especially for newly-originated mortgages.  If lenders fear that the market might be in a bubble, they would raise interest rates for new mortgages in order to cover the cost of the increased likelihood of loss.  SRMs would therefore provide an automatic market-based “lean against the wind”.

To which I would make a few points in response:

  • Newly-issued mortgages have always been the ones at most risk of loss to the lender (borrowers borrow to the hilt, especially to get into a first house, and then typically see their economic position improve over time, through rising nominal wages and house prices, and gradual principal repayments).
  • The nature of very frothy markets is that no one pays much attention to downside risk (or at least, they pay rather less attention to it than in more normal times).  Recall Ben Bernanke’s pre-recession scepticism about the idea of any widespread house price overshooting in the United States.   In periods of extreme optimism and persistent rises in house prices, there may be at least as much lender focus on booking the 5 per cent capital gain as on the possibility of a future loss.
  • Risk isn’t changed by the introduction of an SRM, it is just reallocated.  In principal, lenders should be somewhat more wary about the downside risk, but borrowers have less reason to be concerned about things going wrong.  If house prices fall, their equity will be impaired but- by design – by nowhere near as much as under a conventional mortgage.  There is at least an arguable case that lenders are better placed to bear risk than borrowers, since they can diversify across individual borrowers and geographically.  Mian and Sufi offer no reason to think that the net effect of the reallocation of risk would be to reduce overall risk-taking in the house finance market in boom times.

Mian and Sufi outline one other argument that might act as a modest dragging anchor.  Any  refinancing would trigger the need to make the 5 per cent capital gain payment to the lender, so any cash-out refinancing (drawing more on the mortgages to buy a boat or finance a fancy holiday) would involve meeting the 5 per cent payment.  I suspect that (a) any benefits would be small, and (b) that if such SRMs ever came to market the option premium would probably end up built into the initial value of the loan (you need $300000 to purchase your house, but the loan is booked as $304200[1], and serviced over time on that basis).

The second element of the Mian-Sufi argument is that such  products have not emerged mainly because of mortgage interest deductibility for owner-occupied houses, and because of the dominant role of the agencies in influencing the structure of US mortgage contracts.  The authors report that interest deductibility is available in the US only when the home owner bears the first losses when house prices fall.

These may well be factors that impede the emergence of such contracts in the United States, and no doubt the tax laws could be revised in ways that would bear less heavily on the prospects for SRMs.  But Mian and Sufi’s argument is a very US-centric perspective.  We do not see such contracts having emerged in other advanced economies in which the state has little or no direct role in the housing finance market, and where interest on mortgages on owner-occupied properties is not tax deductible.  New Zealand (in particular) and Australia and the United Kingdom spring to mind.  Bank regulators might not like such products greatly, but capital adequacy frameworks cope with options in other markets, and products like SRMs did not exist either in the decades before risk-weighting and capital adequacy frameworks assumed a key place in the bank regulatory framework.

Robert Shiller has long argued for the emergence of a fuller range economic derivative contracts (house price futures, nominal GDP indexed bonds, and so on), but few of them have emerged.  Revealed preference is a powerful insight.

The Mian and Sufi  SRM is in this tradition – an interesting idea, which seems to have some appeal for some borrowers, few or no regulatory/tax obstacles in many countries, and yet they just have not emerged.  It is interesting to think about why?  Personally, I suspect SRMs have not emerged because conventional mortgages are not “horrible instruments” (Mian’s and Sufi’s term) at all but very attractive and effective instruments.     They have proved to be only moderately risky over many decades, at least  in systems (unlike the US in the 90s and 00s) where government mandates don’t try to override market judgements on credit quality.  In market system the risk around conventional mortgages is managed through lender decisions around initial LVRs and servicing capacity (and, of course, overall capital holdings.  Conventional mortgages also require limited amounts of ongoing monitoring.    Borrowers typically have the most to lose: on any individual loan a new borrower may have only 10% equity in the house so the lender can lose more dollars, but the potential loss for a borrower (in New Zealand or other with-recourse markets) is everything (all their assets).  The system has worked well for many decades, so what would be the impetus for change?  In some ways this comes back to Calomiris and Haber, and the suggestion that the US financial system was made fragile by design.  As they document, the situation in other countries is rather different.

Revealed preference is a powerful insight, but….as an analyst I’m still a bit puzzled why inflation-indexed mortgages haven’t emerged (in countries like New Zealand or Australia).   That might be a topic for another day.

Finally, and harking back to Islamic banking, I presume that SRMs would not be sharia-compliant.  They add some additional uncertainty regarding the future value of the loan but an interest rate is still a key feature of the structure.   Proper equity-finance structures for residential properties still look expensive to establish and monitor, and unlikely to emerge on any scale.

[1] Mian and Sufi estimate that the upfront option premium for the protection the SRM offers would cost 1.4 per cent of the initial value of the loan, on historical US house price performance
“Disciplining” the Reserve Bank

Vernon Small’s politics column in today’s Dominion-Post had this paragraph:

English has not overtly disciplined the central bank over its persistent failure to keep inflation close to the 2 per cent target, though he noted yesterday there was a mechanism in his policy targets agreement with the bank governor to address that.  There had been “ongoing discussions” over the bank’s performance and it was a question of how long it went on  –  currently more than two years (or “a wee while” as English archly put it).

It isn’t entirely clear how much of this is accurately reported, and how much is Small’s interpretation/translation of what he thought English said.  That isn’t my concern here. I want to focus on what options are open to the Minister of Finance if he was concerned.

The first is that there is no such procedure in the Policy Targets Agreement.  The PTA sets out the target, and how the Bank is supposed to respond, and report to the public, when inflation moves materially away from target.  The agreement also notes that

The Bank shall be fully accountable for its judgements and actions in implementing monetary policy.

but this adds nothing to the provisions of the Reserve Bank of New Zealand Act, which contain both the accountability provisions and remedies open to the government.

The Act is quite an elegant structure. The Minister takes the lead in setting the [inflation] target and the Governor has sole personal responsibility for implementing monetary policy in pursuit of the target.  The Minister also appoints the Bank’s Board, whose primary responsibility is to act as monitoring agents for the Minister – and, to a lesser extent, the public.  The Minister also has The Treasury, who have no formal institutional role in the monetary policy governance process, but act as the Minister’s own professional advisers and these (and many other) issues.

The Board can recommend that the Minister dismiss the Governor, and the Minister can seek the removal of the Governor with or without a recommendation from the Board.  The Governor can’t, of course, be dismissed on a whim, but only on the grounds laid out in the Act.  The essence of the framework is that the Minister appointed the Governor to do a job –  in respect of monetary policy, as specified in the Policy Targets Agreement –  and if the Governor isn’t doing his job satisfactorily he can be dismissed.  That was one of the ideas at the heart of New Zealand’s far-reaching public sector reforms in the 1980s –  operational independence for chief executives, but the loss of the sort of “tenure until retirement” such chief executives had previously had.  It was why, unlike the situation in most other countries, our Governor is the sole decision-maker on monetary policy: Ministers responsible for the legislation in the 1980s thought it wasn’t credible to fire a whole committee, but it was quite credible to dismiss a single individual[1].

But dismissal is an extreme option.  I’ve long argued that it is not a particularly credible threat either.   A Governor’s failure would probably never be black and white, and he has large institutional resources to defend his position, as well as the threat of seeking judicial remedies (interim injunctions, and/or overturning the decision).  Given how disruptive (including in international financial markets) and uncertain all that would be, all but the very worst Governors have effective tenure to the end of their terms. And that is probably how it should be.   The option of non-reappointment at the end of a five year term is another matter.

If perhaps there is some buyer’s remorse, I’m sure no one is talking of such options at present.

But what other options does the Minister of Finance have?

He could simply pick up the phone or arrange a meeting with the Governor.  No doubt the two of them talk about various things.  But while the Minister of Finance is quite within his rights to want to be sure that the Governor is operating monetary policy consistent with the Policy Targets Agreement, he wouldn’t (or shouldn’t) want to be seen to be putting pressure on the Governor in respect of a particular OCR decision.  Operational decisions around the OCR are the Governor’s alone (with plenty of advice of course).  Maintaining that distance, and respecting appearances, is one reason why it was most unfortunate that the Governor recently appointed the Minister’s brother as one of his monetary policy advisers.

The Minister could seek a report from The Treasury on their view of how well the Governor was doing consistent with the Policy Targets Agreement, could let it be known such work was underway, and could arrange for such a report to be published.  The New Zealand Treasury offers independent professional advice to the Minister of Finance and would have to take seriously such an exercise.  It might be expected to consult externally (but confidentially) to canvass opinion.   At present, for example, most financial market economists –  not the only relevant observers but not unimportant either –  in New Zealand seem quite comfortable with the Governor’s handling of monetary policy.

The Minister could also seek formal advice from the Bank’s Board, and let it be known that he was doing so.  This would be a totally orthodox approach – the Board exists as a monitoring agent for the Minister – and it was, for example, the approach taken in the mid-1990s when inflation first went outside the target range.   The Board has a number of able people on it, but as an effective agent for accountability risks being too close to management.   The Governor sits on the Board, the Board meets on Bank premises, it has no independent resources, and it has been chaired exclusively by former senior managers of the Reserve Bank.    It was striking that last year’s Board Annual Report (which is just embedded in the Bank’s Annual Report document) had nothing substantive on the deviation of inflation from the policy target.

Although it has no formal status, the practice has grown up of Ministers writing to chief executives, in this case the Governor, in an annual “letter of expectation”.  If the Minister has had concerns one assumes that he has used his letter to pose questions to the Governor around the deviation of inflation trends from the midpoint of the inflation target.  under the Official Information Act I have requested copies of such letters (I requested them  from the Reserve Bank, who have now transferred my request to the Minister of Finance).

The Minister also has reserve powers to act directly.  Section 12 of the Act allows the Minister, transparently and for a fixed term, to impose another “economic objective” than the “stability in the general level of prices”.  These powers have never been used, although the previous Minister of Finance talked openly of the possibility of doing so (at that time, discontent with the Reserve Bank resulted in a select committee inquiry into the future of monetary policy).  Using the section 12 powers does not technically alter the governance structure.  A new Policy Targets Agreement needs to be put in place, and the Governor then has responsibility for operating with that.  I’ve previously argued that the section 12 powers might be able to be used to direct the Bank to put short-term rates at a particular level, but there are other ways of skinning the cat that could, in effect, require the Bank to cut the OCR if the government were really concerned that the Bank was not operating consistently with the current Policy Targets Agreement.

I’ve been quite open that I don’t think the Reserve Bank –  the Governor –  has been making the right calls on monetary policy.    Interest rates have been too high now for some considerable time, and it is beginning to get beyond the point where reasonable people just see things differently.  I do think there is an onus on the Board to be asking some particularly searching questions, and to be letting the Minister –  and the public –  know the conclusions they reach, and any reasoning behind those conclusions. The Board is required to satisfy itself that each Monetary Policy Statement is consistent with the Policy Targets Agreement, and there is another Statement coming out next month.    There must now be some question as to whether they could do so if the current policy stance is maintained.

I don’t think it is time for the Minister of Finance to act, but he probably doesn’t need to.  Even garbled newspaper stories that talk of the Minister of Finance disciplining the Governor will no doubt have caught the Bank’s attention.

[1] Experience suggests that dismissing whole committees is perhaps less difficult than was then thought.  The Hawkes Bay DHB and Environment Canterbury examples spring to mind.

Housing loans: big buffers and moderate risks

Paul Glass, of Devon Funds, had an article in the Herald yesterday, containing his agenda for action for New Zealand economic policymakers.   I was sympathetic to quite a bit of his analysis, but this section caught my eye:

It’s a technical area, but the amount of regulatory capital held against residential mortgages should be increased substantially, not just tinkered with around the edges as is currently happening. This would limit the amount of debt available for mortgages.

It is a common view, but I think it is wrong.  I’m not sure what reasoning Glass has behind his recommendation, but Gareth Morgan has argued along similar lines for years.  Morgan argues that  the bank regulatory capital regime (whether Basle I, II, or III) artificially favours lending secured on housing, because the risk weights used in calculating the amount of capital that needs to held in respect of such loans are less than those used in many other types of commercial bank assets.

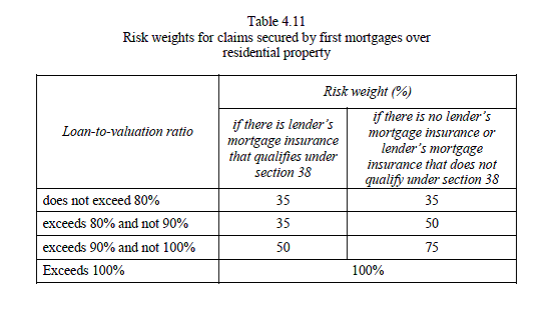
Calculation of risk weights for banks using internal ratings based model (the big 4 banks) is far from transparent, but the easiest way to see the difference is in the rules for other (“standardised”) banks.  Risk weights for residential mortgages are as follows:

riskweights

For loans with an LVR of less than 80 per cent, the risk weight is 35 per cent

By contrast, exposures to unrated corporate borrowers generally have a risk weight of 100 per cent.

But that is because the risks to banks from typical housing loans have been found to be less than those on many other bank assets.  This is not just an observation about boom times, or about New Zealand and Australia in recent decades, it is a result across many countries and many different circumstances.  Housing mortgages initiated by banks themselves, not under regulatory mandates to take on dubious risks, have rarely if ever played a major role in financial crises.  A recent Reserve Bank Bulletin reported on some of the international literature in this area.  A good example was Finland in the 1990s, where after a major credit boom and rapid growth in asset prices in the late 1980s, house prices fell by about 50 per cent in nominal terms, real GDP fell away sharply and unemployment rose substantially.  Banks took losses on their mortgage portfolios, but those losses were modest and not remotely enough to have threatened the health of banks.  The experience in the US since 2007 superficially looks like a counter-example, but binding federal government and congressional mandates played a key role in driving down the quality of new mortgage originations (and hence driving up subsequent loan losses).

It is not surprising that housing loan portfolios are not overly risky.  Lenders have a lot at stake, but they also have solid collateral.  Borrowers also have a lot at stake, especially in countries (like New Zealand and Australia with with-recourse mortgages).  You can escape your debts if you go bankrupt but fortunately (in my view) we don’t have a culture that is overly welcoming to bankruptcy.    And a owner-occupied home is not just a roof over the head, it is often also about a place in a community –  the local school, or sports club, or church.  So most residential mortgage borrowers do everything they can to avoid defaulting on their mortgage, and losing their house, even in very tough times.  There will always be a minority of bad borrowers, and other people who are just overwhelmed by events and the size of a shock.  Recent loans tend to be riskier than older loans –  most of us probably borrowed about as much as we could afford to get into a first house,  but mortgage portfolios age and typically get safer as they do.  And it portfolios of loans –  not individual loans –  that need to be evaluated in thinking about the risk to banks.

By contrast, the typical unrated business loans will have no collateral, revenue streams that depend quite strongly on the economic cycle (profits are more volatile than wages) and limited liability.   The nature of business is taking risk, and sometimes risks pay off and other times they go spectacularly wrong.  Empirical evidence is that a portfolio of unrated business loans is materially risker than a portfolio of unrated residential mortgages.  To be more specific, even in respect of property-based exposures, the evidence is that commercial property, and especially property development exposures, are far riskier (and more likely to lead threaten the health of banks and the financial system) than residential loan books.  Markets will, and regulators should, reflect that in their expectations around capital.

Actual risk-weighting for our big banks is more sophisticated than this description and, as mentioned, much less transparent.  Reasonable people can differ on whether anything is gained by having the IRB approach, or whether it would be better to simply use the standardised approach for all our banks –  all of which are relatively simple.

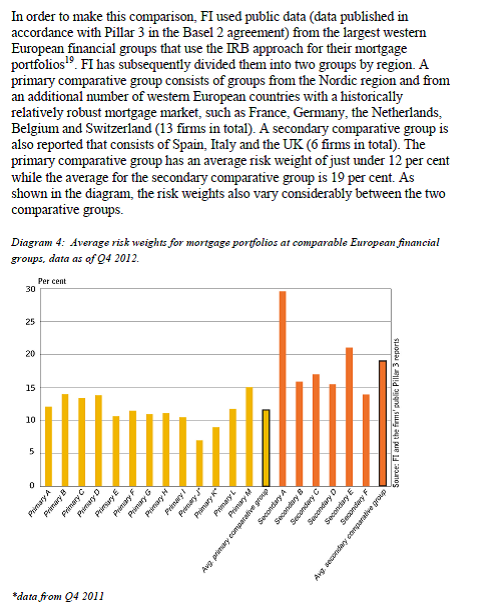
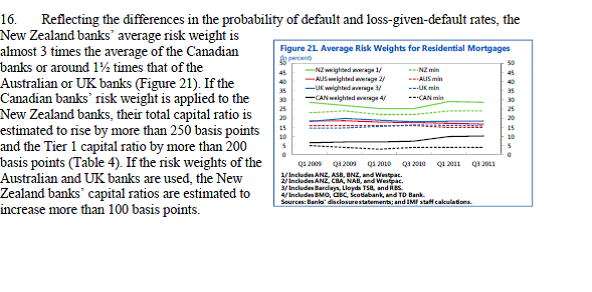
But not only is there good reason for residential mortgage risk weights to be lower than those on many/most commercial exposures, but New Zealand’s risk weights on residential loans are high by international standards.  This IMF piece, done a couple of years ago, contrasted effective risk weights on residential mortgages with those then in the UK, Australia and Canada

riskweights2

Sweden recently raised the minimum risk weights used by their banks on residential mortgages.  As part of the preparation for that move they produced this document, which includes this chart.  Again New Zealand risk weights on residential mortgage loans are higher than any of the banks in this chart – and are higher than the newly increased Swedish risk weights.

riskweights3

Residential risk weights, or overall required capital ratios, might still in some sense be too low in New Zealand.  But the onus should be on those calling for such increases to make the case that the threat to financial stability is greater than what is already allowed for in the bank capital framework.  The Reserve Bank did stress tests last year looking at the impact of a really quite severe adverse shock, in which nominal house prices fell a long way and unemployment rose substantially (it usually takes both to cause real trouble).  Not one of the banks, let alone the system as a whole, had its capital materially impaired in that scenario.  Those tests may well have been flawed, they may have missed something important, and they certainly won’t have captured everything that mattered, but on the information we have actually available the New Zealand banking system currently looks pretty well-placed to cope with a severe shock affecting the residential mortgage book.  With the stock of credit growing at only around 5 per cent per annum, that also should not be a great surprise.

And since housing seems to be one of those areas where to cast doubt on one possible explanation/solution is to risk being accused of thinking there is no issue or problem at all, I refer anyone inclined to react that way back to my take on housing.

Islamic banking and equity-based mortgages

Media reported yesterday on a local Muslim woman who had sought to interest New Zealand banks in offering mortgage products that met Islamic restrictions on the payment of interest.  The article suggested that a Kiwisaver provider was interested in offering such products.  There were some small lenders offering such products prior to the 2008/09 recession but they did not seem to survive.

I’ve long been intrigued by the ideas and practice of interest-free finance.  My own Christian tradition for centuries banned, or regarded with intense disfavour, lending at interest.  That drew first on Old Testament provisions, which prohibited Israelites from lending to fellow Israelites in need at interest (while allowing loans at interest to outsiders).  The stance was reinforced by perspectives from Aristotle, rediscovered in the Middle Ages, arguing for the inherent sterility of money.  Prohibitions on lending at interest were eventually removed but  it remains a powerful vision for some (for me).   Within the Christian community, outfits like the Kingdom Resources Trust in Christchurch try to put it into practice.

The injunctions against interest are apparently much stronger and more pervasive in the Koran. In his recent book, Beggar Thy Neighbour, Charles Geisst reports that “of all the prohibitions against undesirable activities in the Koran, usury is mentioned the most.  Interest, or riba, is considered usury and no distinction is made between them”.   This was a distinctly counter-cultural stance, as compound interest had apparently been common among Arabs before the coming of Islam.

If interest is prohibited, profit-sharing arrangements –  equity finance, in effect – are not frowned on at all.  They have a element of uncertain return – economic risk –  for which some reward is appropriate. Predominantly-Muslim countries, and individual Muslims. have grappled with how to apply the prohibitions on interest in today’s world.  The large Muslim minority in the UK and the large financial sector with global connections has led to considerable interest there.  In his pre-crisis heyday, Gordon Brown wanted London to become the global centre of Islamic banking.

My interest in interest-free finance once got me a trip to Iran, as a member of an IMF technical assistance mission. This was shortly after the Iran-Iraq War and the death of the Ayatollah Khomeini, in an earlier phase of opening to the West.  I got on the mission because of my (innocuous, non-US, non-UK) New Zealand passport.  From my perspective, two weeks in Iran was made easier by the fact that I didn’t then drink alcohol at all.

I was (am?) a bit of an idealist, and went in fascinated to learn more about trying to apply the interest-free teaching in practice.  And I like to think we offered them some helpful advice –  monetary policy without interest isn’t particularly intellectually or practically difficult.  But I came away somewhat disillusioned.  We met a variety of people – bureaucrats, bankers, and even some theologians (we wanted to better understand what the permissible limits were).  Some were more earnest than others, but the overwhelming impression I came away with was of people trying to devise instruments to the limits of the letter of the law (Koran), with little regard for the spirit.   I’m not, for a moment, suggesting that that was the approach of individual devout Muslims across the country, but among the groups we engaged with the focus was on products that had the economic substance of interest, but not the legal or exegetical label of interest.

I’m not sure that that was, or is, unrepresentative of many Islamic banking products.  Take mortgages as an example.  A widely-used UK website , Islamic Mortgages, covers a wide range of sharia-compliant mortgage products.

In a nut shell how does an Islamic mortgage work for different types of purchases?

Buying/selling:

  • you choose property, agree price, undertake survey
  • bank enters into contract to buy the property from vendor
  • bank sells property to you at higher price
  • the higher price is paid by you in equal instalments over a fixed term, irrespective of what happens to Bank of England base rate
  • Leasing:
  • choose property, agree price
  • bank undertakes survey, buys property and sells it to you for the same price, in return for payments spread over fixed period up to 25 years
  • in addition to monthly payments, you pay a sum for ‘rent’ – assessed annually in line with market trends
  • you can overpay (as with a conventional flexible mortgage) to buy the house more rapidly

These are interesting products in their own right, but the first is simply economically equivalent to a mortgage with a fixed interest rate for the entire life of the loan.    Neither the purchaser nor the lender will necessarily regard themselves as paying or receiving interest, but the payment streams over the life of the contract (“fixed term”) will be the same as those on a conventional table mortgage with a fixed interest rate for the same term.  And the risks  – credit, market, counterparty –  seem very much the same.

An alternative type of product might be an equity-based housing finance product.  In conventional housing finance markets, the purchaser puts up some equity, and a lender provides the balance.  The lender receives an interest-rate and is exposed to the (hopefully small) risk that the borrower defaults and that the house can’t be sold for enough to cover all the outstanding debt.  Any increases in the value of the house – whether changes in market prices generally, or as a result of improvements/extensions – accrue to the owner.

But it would be technically quite feasible to envisage a model in which the person wanting a house to live in, and the financier, became equity partners in a joint business venture to own the house.  You, the, resident would presumably pay rent to the joint venture, some portion of which would be passed to the equity finance partner, and when the house was eventually sold gains and losses would be shared, proportionately, between you and the equity partner.  You have risk, the equity financier has risk, and no one is paying or receiving interest –  in form or in substance.  It would be simple enough, technically, to structure the contract to allow the resident’s equity share to rise over time (instead of “principal repayments”, one uses the funds for equity repurchases from the JV partner).

I’m not sure if such contracts exist anywhere in the Islamic world.  In the West, without the theological concerns about interest, there is good reason why they don’t exist.

If I’m a young person in the West buying a first house, a bank might lend me 90 per cent of the value of the house.  Most mortgages are table mortgages and are repaid gradually, so that in time the owner’s equity share is large, heading for 100 per cent.  All the Bank cares about after that is my ability to service the debt.  And that depends largely on avoiding prolonged periods of unemployment.  If house prices fall that poses a risk –  banks can call in a mortgage if the value of the collateral drops below the value of the mortgage –  but it typically only crystallises if the flow debt service isn’t being met, and if house prices fall so far that not all the debt can be repaid when the house is sold up.   Within limits – quite wide limits – banks don’t care about or monitor the maintenance you do on your house.  If you don’t do the maintenance, mostly it is your loss.  And they don’t care at all about changes in market rentals in your neighbourhood, or for your specific type of house.  Conventional mortgages are simple, easy, and cheap to monitor.

But equity-sharing contracts would be enormously costly to monitor and manage, especially in a country with such a variegated housing stock (rather than lots of high-rise uniform apartments).  If you are only an equity partner in a house, your incentive to do maintenance is attenuated –  and likely to weaken especially in periods of personal financial stress.  So a financier providing a large equity stake would probably want to pre-specify maintenance obligations and standards (and would then need to monitor compliance).  You’d need to negotiate all alterations and extensions.  Rental rates vary, as do market values.  Perhaps a real rental yield could be pre-specified in the initial contract, but any arrangement for the resident to gradually buy out the outside equity partner requires an agreement on market value at the time of the transaction.  Transactions costs rapidly start to mount.  They might work within a relatively closed community – say, a local church community where effective monitoring costs might be reduced, or a small mosque-based credit union  –  but it is difficult to see them being effective, and economic, more generally.

In their recent book House of Debt, the US academics Atif Mian and Amir Sufi, argued that equity-sharing contracts should become the norm for housing finance.  They argue that such contracts would materially reduce the risk of financial crises, and that the main reason such contracts aren’t common is because of the tax system and the role of US government agencies.  I’m very sceptical of both claims, and would post the note I wrote on why –  but it would take 20 working days to get OIA clearance.  This post is quite long enough, but if anyone is interested I can explain my scepticism in a later post.

UPDATE: The later post on equity-sharing mortgages.

How strong a recovery?

One line sometimes heard in the current New Zealand economic discussion is a suggestion that New Zealand has. or has had, a “robust” recovery.  I reckon “robust” is generally a good word to avoid, since it has connotations of something well-founded and sustainable which, in a sense, only time will tell.  But just how strong has our recovery been?

Official quarterly GDP data go back only to 1987 [surely, surely, we need rather better funding for core official economic statistics] but Viv Hall and John McDermott have generated a series, using earlier annual estimates by SNZ and other authors, all the way back to 1947.

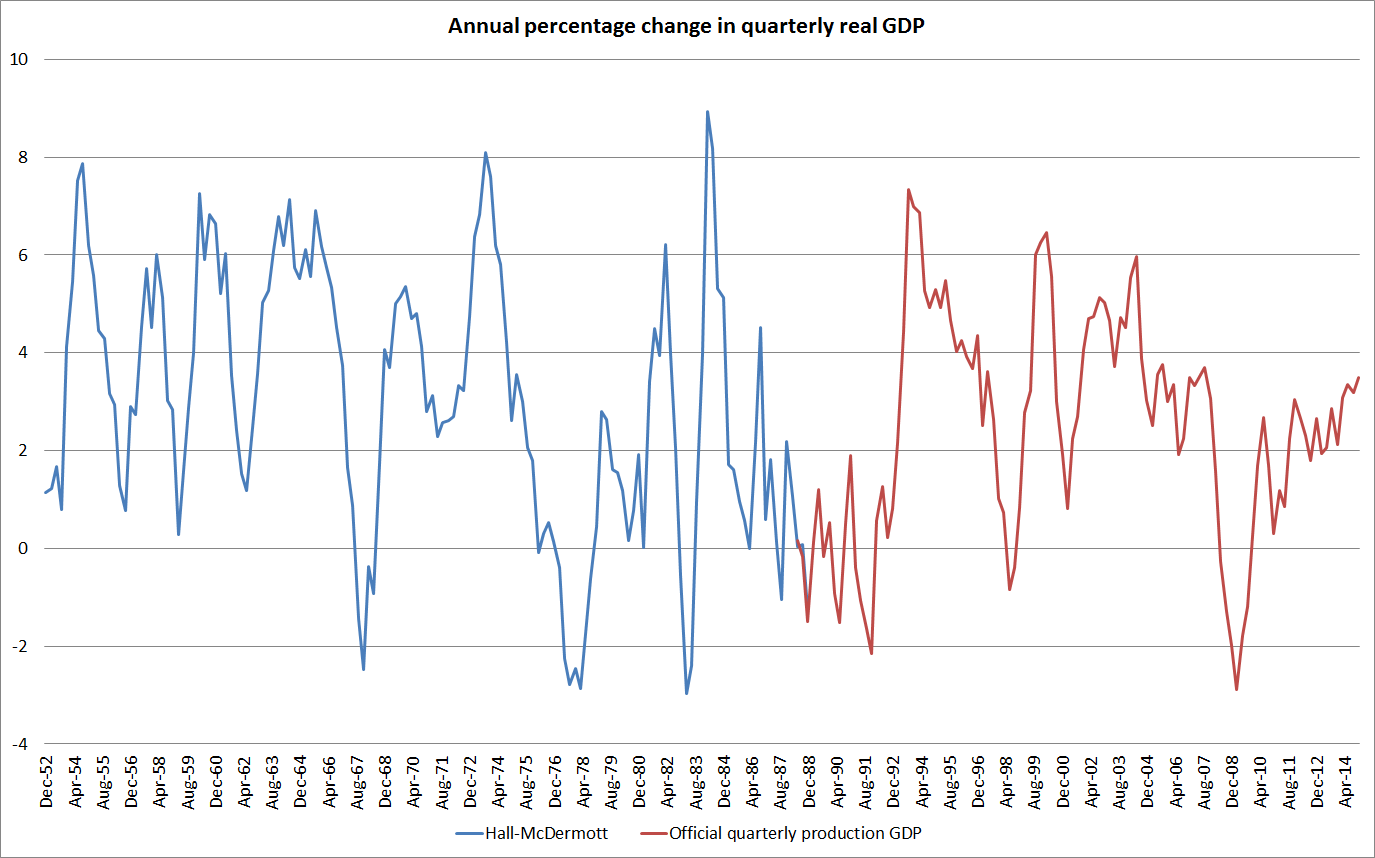
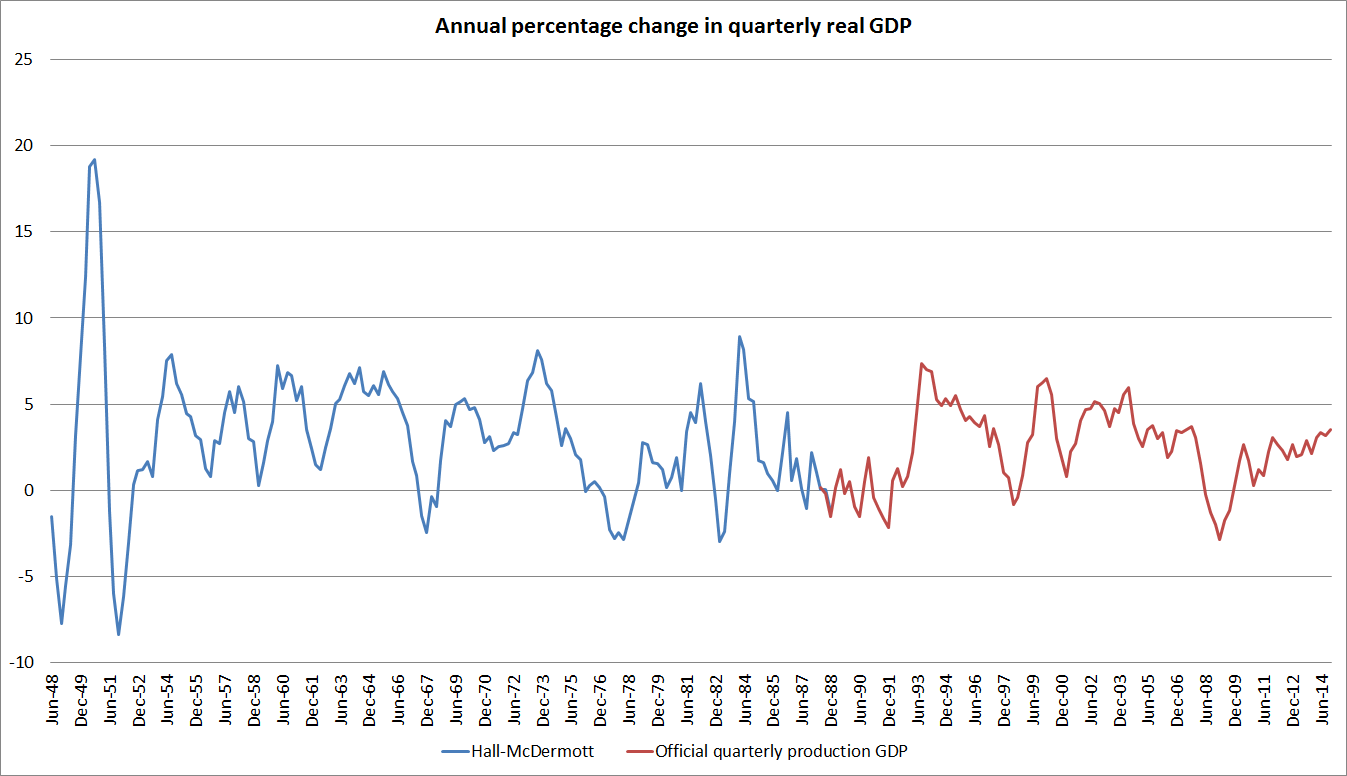
The chart below shows the annual percentage change in real quarterly GDP (seasonally adjusted, since that is how Hall and McDermott present their estimates).  There are some oddities around the estimates for the first few years (if I recall rightly, having to do with the level of aggregation in export prices used in generating the original annual real series) so here I’ve shown the data only from the year to December 1952 (a version showing the data all the way back to 1948 is shown at the end of the post).  It is a long time series by New Zealand standards.

gdp1

On these estimates, real GDP has been quite volatile over the years.  We’ve had five episodes in which GDP has fallen by 2 per cent or more between one quarter and the same quarter the following year.  The recession in 2008/09 was almost as deep as the deepest of these five contractions.  But what is noteworthy is just how subdued the recent recovery has been.  Annual growth has inched up to around 3.5 per cent, and few, if any, forecasters seems to be picking it to go any higher.  In past cycles, growth peaks in excess of 6 per cent have not been uncommon and periods of growth in excess of 4 per cent per annum have been the norm.

Of course, there is no doubt something to be said for some stability to growth rates. But there is probably more to be said – perhaps especially for those who became unemployed  –  for a quick rebound from a serious recession.  We haven’t had that sort of rebound.  Of course, most other advanced economies have not either but many of them have policy interest rates around zero and have largely exhausted the limits of conventional monetary policy.    Sometimes inflation doesn’t provide any leeway for an inflation targeting central bank to accommodate a strong recovery, but that hasn’t been a problem here.

One could mount an argument – reasonable people would differ on the point – that faced with a location-specific demand shock such as the Christchurch repair and rebuild process, it might have been quite reasonable to have expected a particularly strong rebound in GDP for a time, and perhaps even some overshooting in headline CPI inflation (since medium-term trends are what the Bank is instructed to focus on).

But whatever your view on that particular point, given the depth of the recession, how far below pre-recession trends GDP still is, and how low core inflation has drifted, peak GDP growth of 3.5 per cent should be counted more as a failure than as a success.  An economy firing on two, faltering, cylinders might be a better description than “strong” or “robust”.

One other argument I have heard against cutting the OCR now is the risk of a repeat of what is loosely characterised by my old colleague Rodney Dickens as “Alan Bollard’s go-for-growth experiment” of 2003/04.  That there was such an “experiment” is hard to disagree with –  the government had given Alan a higher inflation target, and he (and the then government) seemed to have a sense that the old-school Reserve Bank hardliners had been holding back New Zealand’s growth potential.  I think the characterisation is a little unfair on Alan, but even he later admitted that the policy approach in 2003 had been a mistake.

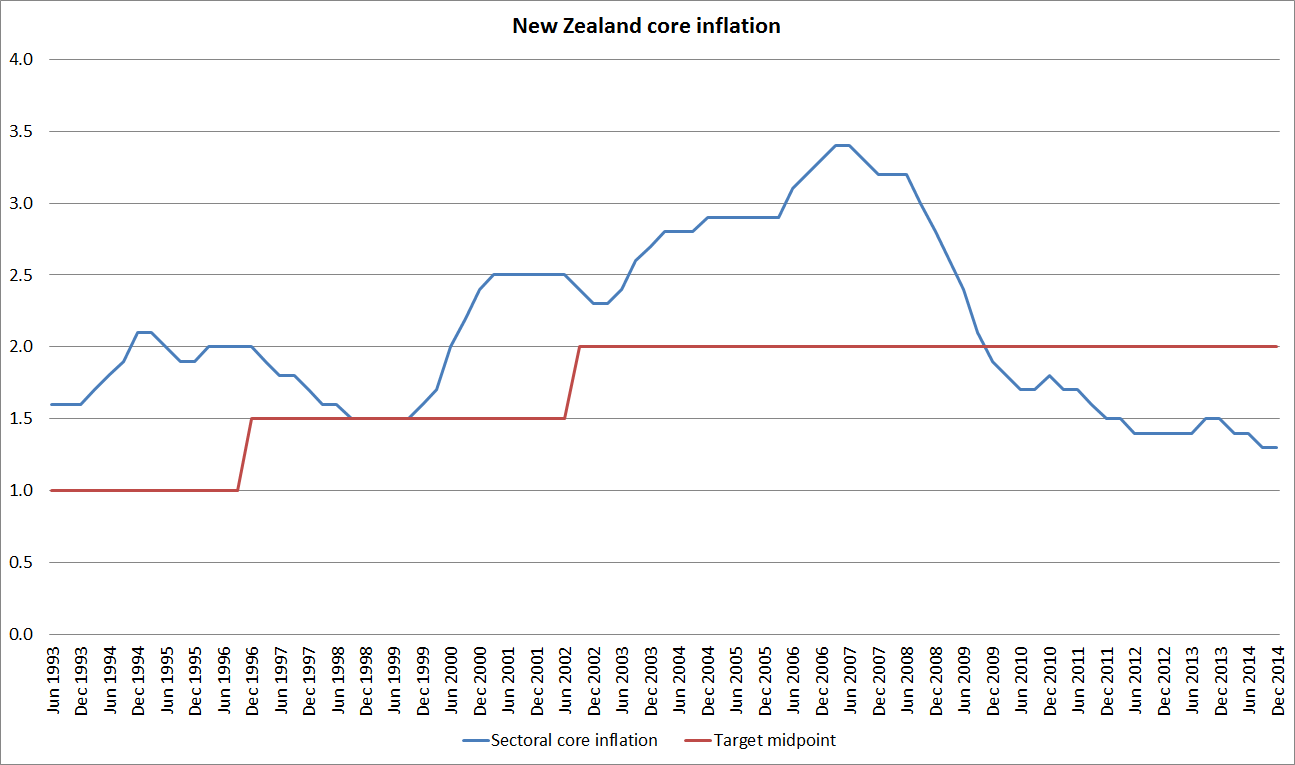
I could discuss the similarities and differences between 2003 and the current situation at some length (and I don’t feel defensive about 2003, as I working overseas that year), but the stark and simple contrast is captured in this chart, which I’ve run already this week.

core cpi

In 2003 and 2004, core inflation was well above the target midpoint, had increased materally over the previous year or so, and was increasing further.  Of course, the PTA at the time made no mention of the midpoint, but no one ever thought the top part of the target range was something to actively aim for.  This particular analytical series did not exist then, but it captures trends that were apparent in other ways of slicing and dicing the CPI.   Even allowing for the uncertainties (SARS etc), to have cut the OCR then and to have been so slow to move it back up when the initial scare passed, is hard to defend.  As Alan later said, it was a mistake.

What is the situation now?  The Bank has, as much by accident as by good planning, achieved something worthwhile in the last few years in finally demonstrating that core inflation will not always be in the top half of the target range.  But this is not a price level target regime, and the PTA is clear that the focus now needs to be on keeping future inflation near the 2 per cent midpoint.  Actual measures of core inflation have been falling for years, and are now well below the target midpoint.  A material increase in the (core) inflation rate would be highly desirable, given the target the Minister and the Governor have agreed.  It has been forecast for several years, but it has simply not arrived.  Perhaps it is just a “not yet”, but the case for OCR cuts now is very very different from the case in 2003.

Appendix:

The first chart above for the full period since 1948.

gdp2

Why not?

The Governor’s press release this morning, leaving the OCR unchanged, was no surprise.

But it continues to seem out of step with the data, and with his responsibilities under the Policy Targets Agreement. The statement has the feel of being written by someone who really really does not want to cut the OCR, but who won’t explain why.  It is if the current level of the OCR were being treated as an end in itself, or being held up in pursuit of some other goal, rather than being a tool for influencing the (rather too low) medium-term rate of inflation.

Fortunately, the statement corrects what must have been a mis-step in John McDermott’s speech last week.  Today the Governor states that:

It would be appropriate to lower the OCR if demand weakens, and wage and price-setting outcomes settle at levels lower than is consistent with the inflation target.

Last week, that criterion was expressed in terms of lower than the “target range”.

But there is no reference anywhere in the statement to the 2 per cent midpoint, even though the Governor and the Minister explicitly agreed that the midpoint should be the Bank’s focus.  And wage and price-setting outcomes are already inconsistent with the target midpoint and have been now for some years.  This statement offers no tangible basis for expecting that to change, just the limp observation that underlying inflation “is expected to pick-up gradually”.  Why?  When?  What is about to change that will now reverse a slide in core inflation that has been underway, more or less continuously, since 2007?  It has to be something more than just a belief that monetary policy is “stimulatory”.

Once again, the Governor anguishes about the exchange rate.  I agree totally with the substance of his references to New Zealand’s long-term economic fundamentals and how out of step the exchange rate is with them (it was the heart of this paper I wrote for the Treasury-Reserve Bank forum on exchange rate issues in 2013).  But……this is a press release about the nominal OCR, not about the real factors that shape New Zealand’s longer-term competitiveness.  And while the Governor observes that “the appreciation in the exchange rate, while our key export prices have been falling, has been unwelcome”, he seems unwilling to take the obvious step in response.  Exchange rates are largely influenced by expected relative risk-adjusted returns, broadly defined.  When New Zealand interest rates have been rising while those in most of the rest of the world have been falling, and we have a Governor who appears very reluctant to cut those interest rates, it is hardly surprising that we end up with a cyclically strong exchange rate.  Cutting the OCR won’t solve the long-term economic challenges:  they are about real factors, not monetary policy. But a strong sense from the Bank that the OCR was heading back towards 2.5 per cent over the coming year, or perhaps even lower, would be likely to make a useful difference.

And why not do so?  Core inflation is very low, the number of people unemployed (and underemployed) lingers uncomfortably high, inflation expectations are falling, farm incomes are falling, credit growth is pretty modest, and so on.  So why not cut?    Of course, no one can be totally certain that, with hindsight, cuts will prove to have been the right policy, but on the New Zealand and global data as they stand today –  and without a compelling case to suggest the inflation picture is about to change materially –  not doing so increasingly looks negligent.  In time, it is the sort of stance that also risks further undermining public and political support for the broad monetary policy framework, and the Governor of the Bank’s powerful position within it.

The Bank’s take on the rest of the world, as reflected in the press release, is both puzzling and disconcerting.  The Governor reiterates what appears to be one of his favourite lines, that trading partner growth is around its long-term average.  This is true, but largely irrelevant.  First, it simply reflects the fact that China is a more important trading partner than it was, and its growth rates are higher than those in our other trading partners.  But even China is slowing, probably quite sharply.  And commodity prices –  a key way the rest of the world’s economy affects New Zealand –  have fallen a lot.

In addition, in almost all of our trading partners – and in most countries that are not our trading partners –  GDP remains well below pre-crisis trend levels. Not all of that is excess capacity, but a significant proportion is likely to be.  Again, the Governor makes much of the low interest rates abroad, but seems not to put much weight on why those rates are so low.  There are all sorts of idiosyncratic factors in individual countries, but across the world interest rates are low and falling not because central banks have arbitrarily put them there (it isn’t some “monetary policy shock” in the jargon), but because markets and central banks both judge that underlying demand and inflation pressures require interest rates be at least as low as they are.  That is a very worrying perspective on the world, not a comforting one.

Finally, the Reserve Bank likes to claim that it is highly transparent, citing for example its scores in papers like this one.  But in many of the more transparent central bank we could look forward to the minutes of the meetings that led to the decision being published. In some central banks, even the range of views is extensively outlined.  The Governor has noted he now makes his OCR decision in the so-called Governing Committee, with his three senior colleagues.  But we do not have access to the minutes of these meetings, even with a lag, or to a summary of the advice provided to the Governor by his wider group of advisers, including the external advisers.  Transparency and open government are not just about announcing and explaining final decisions, but about the process whereby those decisions were reached.  Some other New Zealand government agencies are quite good at pro-active release of background material (for example, papers leading up to the Budget).  It is a model the Reserve Bank could look at emulating.  In the next few days, I am expecting a response from the Reserve Bank to my OIA request for background papers to an OCR decision from 10 years ago.  It will be interesting to see how they interpret the Act is deciding how to respond.

Tomorrow’s OCR announcement

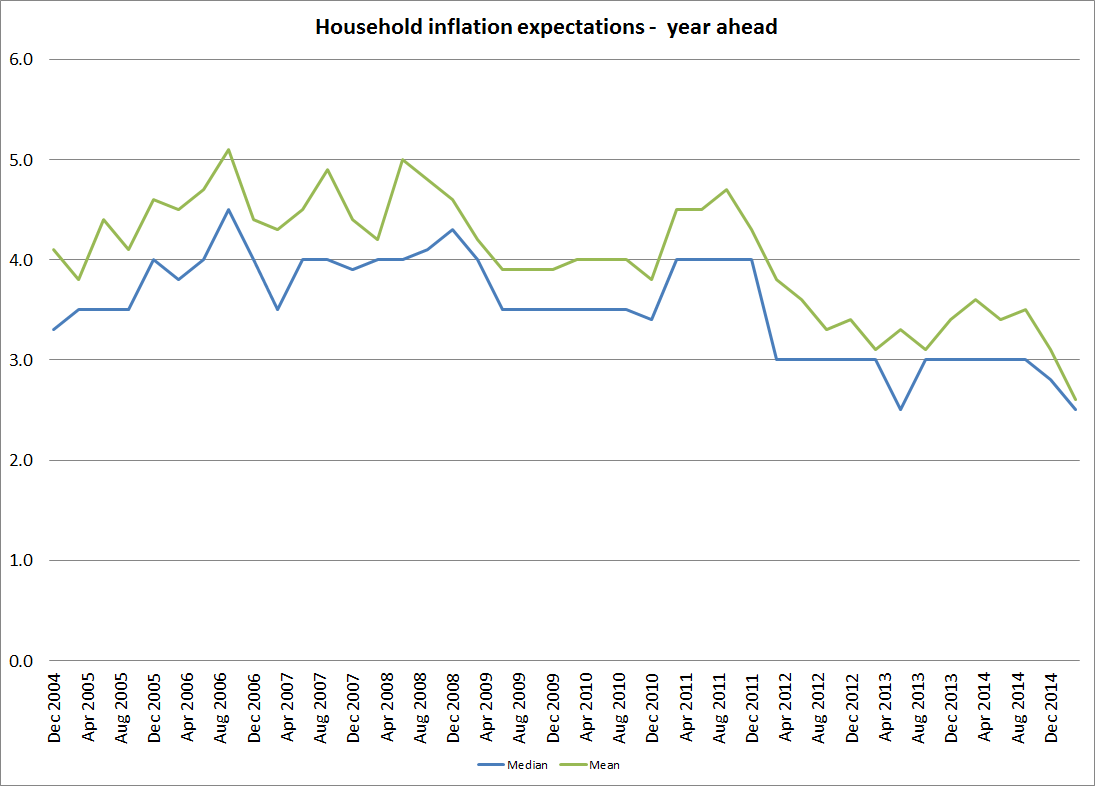
Tomorrow morning Graeme Wheeler, the single unelected official responsible for the conduct of New Zealand’s monetary policy, will announce his latest OCR decision.  That decision will, no doubt, already have been made – lags between decision and announcement are longer in New Zealand than in most other countries, even more so at Monetary Policy Statements  – and the only discussion now will be around wording the one page press release.   Do we really need to say anything this time about future policy?  Will that slight change of words spook the markets?  Is that claim really defensible?  How appropriate is it to comment on another country’s monetary policy?  How does talk about the exchange rate and the medium-term challenges it poses fit in a statement about today’s OCR.  How will local economists read it?  How will offshore markets read it?  Where are the political fishhooks?  Don’t we need a comma there rather than a semi-colon?  And so on. But the heart of the matter is the OCR decision itself – where will the interest rate the Bank pays on (some) settlement cash balances be set for the next six weeks or so.  The key influence on that should be the inflation target: a range of 1 to 3 per cent annual CPI inflation, with a focus on keeping future inflation “near the 2 per cent target midpoint”. The Reserve Bank would no doubt argue that that is exactly what they have been doing.  The target is not about inflation today, it is about “future inflation outcomes over the medium term”.   The Reserve Bank’s published inflation forecasts always show inflation coming back towards the target midpoint a year or two ahead.  They do that by construction, but policy over the last few years has been set consistent with that view.  The judgement was that interest rates needed to be first at 2.5 per cent, and then move progressively higher, to ensure that future inflation did turn out consistent with the inflation target.   Reading through the Monetary Policy Statement from last March, when the OCR increases began, it is quite clear that the Bank expected to see more non-tradables inflation, higher inflation expectations and higher wage inflation, even with the programme of OCR increases they had in mind. But the Reserve Bank was wrong.  There is no particular shame in being wrong, so long as one learns from one’s mistakes.  It isn’t clear that the Reserve Bank has been very good at that.  Of course, what matters is not that so-called headline inflation was 0.1 per cent in the last year.  All sorts of things will throw headline inflation around in the short-term and generally it won’t make sense for monetary policy to try to offset them.  That is why people develop measures of core inflation –  simple ones like CPI ex food and energy (volatile items), trimmed means, weighted medians, and the sectoral core factor model. Core inflation has been falling core cpi So have household inflation expectations household So have business wage and inflation expectations business And dairy prices – a major influence on incomes, and incentives to invest – have been coming in much lower than the Reserve Bank expected, consistent with the pretty relentless decline in global commodity prices. Had the Reserve Bank had known last March how the New Zealand economic data would turn out, I don’t think Mr Wheeler would have seriously considered raising the OCR then.  Had they done so anyway, they would, I hope, have faced very serious questions from their Board and from the Finance and Expenditure Committee: raising the OCR while showing forecasts suggested that core inflation would keep falling even further below the target midpoint looks like something other than inflation targeting. Everyone makes mistakes, and economic forecasting is something of a mug’s game,  But it is the Reserve Bank that chooses what weight to put on its own forecasts, and how far ahead to look.  When they have been so persistently one-sided in their errors, it is surely time to down-weight the forecasts quite considerably.  The “model” –  the way of thinking about what is going on –  just isn’t helping much, if at all. Such one-sided errors aren’t new.  During the boom years, the Reserve Bank was consistently surprised by how strong inflation was.  We didn’t fully understand what was going on, but didn’t correct for that and, as a result, by the end of the boom core inflation measures were above the top of the target range.  The underlying belief that surprisingly strong inflation pressures were just about to end is quite strongly parallel to what seems to be going on now – an apparent wish to believe that whatever has kept inflation down is just about to end. With perfect foresight the OCR would not have been raised to 3.5 per cent. No one has perfect foresight, but knowing what we now know  there is a strong case for starting to lower the OCR now.     As it is, it is not just that nominal interest rates were raised by 100 basis points last year (and not just the OCR, but floating mortgage rates) but that as inflation expectations are still falling, real borrowing rates are still rising further. Perhaps it would be different if there were strong, well-substantiated, reasons to think that underlying inflation pressures were just about to recover strongly –  and I stress “strongly”; it has taken five years or more for core inflation to drift this far below the target midpoint. But there aren’t.  The construction cycle looks to be pretty close to peaking .  Recall that the gearing-up of activity in Christchurch represented the biggest single project pressure on resources in New Zealand at least since Think Big, and yet core inflation just went on falling.  There is no sign of business or consumer confidence pushing up to new heights.  Export commodity prices are weak, especially for dairy –  and the exchange rate is at a level which, if sustained, can only act as a drag on other tradables sector activity.  And while I wouldn’t suggest setting policy on a non-consensus forecast for the rest of the world, no one really sees global activity or inflation posing a material new inflationary risk in New Zealand in the next year or two.  If anything, the deflationary clouds continue to gather. John McDermott’s speech last week was slightly encouraging –  a very belated recognition of just how weak inflation has been, and how little the Reserve Bank (or anyone) really understands about what is going on.  But I noted then this disconcerting line from the speech:

We remain vigilant in watching wage bargaining and price-setting outcomes. Should these settle at levels lower than our target range for inflation, it would be appropriate to ease policy.

In 2012, the Governor and Minister explicitly, and consciously, decided to include a focus on the target midpoint in the PTA.    It is the midpoint, not the bottom of the target range which the Bank should be focusing on. I can really only see one argument against an OCR cut, a line which I’ve seen reported in various media: the housing market, and what lower interest rates might do to house prices.  There are several points worth making briefly here:

  • In its monetary policy, the Reserve Bank is explicitly not charged with managing house prices.  The only target for monetary policy –  agreed with the Minister – is for the CPI.  Neither existing house prices nor land prices are in the CPI, and the CPI’s treatment of housing is one the Reserve Bank has endorsed.
  • To the extent that rising house and land prices in some parts of the country reflect the interaction of regulatory obstacles and population pressures, they are real relative prices changes –  not something that, even in principle, monetary policy should be paying much attention to.
  • House prices in much of the country have been flat or even falling.  There is no evidence of some generalised speculative dynamic, let alone a credit boom.
  • Any possible threats to future financial stability –  the case for which the Reserve Bank has not yet convincingly made – should be dealt with through prudential regulatory tools.  Higher required capital ratios, or higher risk weights on housing loans, would be an orthodox response if a cost-benefit analysis suggested that larger buffers were required.

Finally, the Reserve Bank does not have an explicit “dual mandate”.  But any time a central bank engages in discretionary monetary policy – as opposed to, say, a long-term fixed exchange rate – it is assumes such a responsibility de facto.  Changes in the OCR affect output and employment in the short to medium term.  Perhaps I’ve completely lost perspective, but it disconcerts me how little public attention the Reserve Bank gives to the number of people unemployed (and underemployed).  At 5.7 per cent, the unemployment rate is still well above normal, and underemployment measures in the HLFS have not come down much at all.  The decision to hold the OCR is not just a decision between higher and low inflation.  If it were, there would still be a case for a cut.  But the cut/hold choice is also one between a faster reduction in the number of people unemployed and a slower reduction.  Involuntary unemployment is a blight, that scars families and individuals, and often has permanent adverse economic effects on the unemployed.    When there is so much  inflation leeway –  inflation so far below target, with few looming inflation pressures – the plight of the unemployed should get more attention from the Reserve Bank, and from those who hold it to account.

Another potential “blunder of our governments”?

I commented the other day on possible New Zealand cases of government blunders.  My former colleague, Ian Harrison, reminded me of his work on another possible candidate, the Building (Earthquake-prone Buildings) Amendment Bill, currently before a Select Committee, which is due to report by the end of July.  Ian’s trenchant assessment of MBIE’s work leading up to this bill made pretty sobering reading the first time I went through it, and it was no less disquieting the second time.  I’ve seen no sign of any sort of substantial rebuttal to the thrust of the analysis Ian presents.

I’m certainly not indifferent to earthquake risk.  I live on the side of a hill in Wellington.  And my parents’ apartment block was severely damaged (and later demolished) in the February 2011 earthquake.  But this bill just does not look like the fruit of good public policy making, cost-effectively addressing real and substantive risks.  Perhaps the work of the Select Committee might yet limit the prospective damage and costs?

Eric Crampton discussed some of Ian’s earlier work a couple of years ago.  This suggestion made a lot of sense:

There’s a good case for having liability rules or standards for buildings that the public is forced to attend by the state: courtrooms, prisons, public licensing offices and the like. We can’t use a revealed preference argument around risk acceptance for those venues. But for other buildings where entry is voluntary, what’s wrong with mandating signs advising the public that “Engineering assessment suggests this building has (very low, below average, average, above average, seriously high risk) of falling down in case of earthquake. Entry is at own risk.”

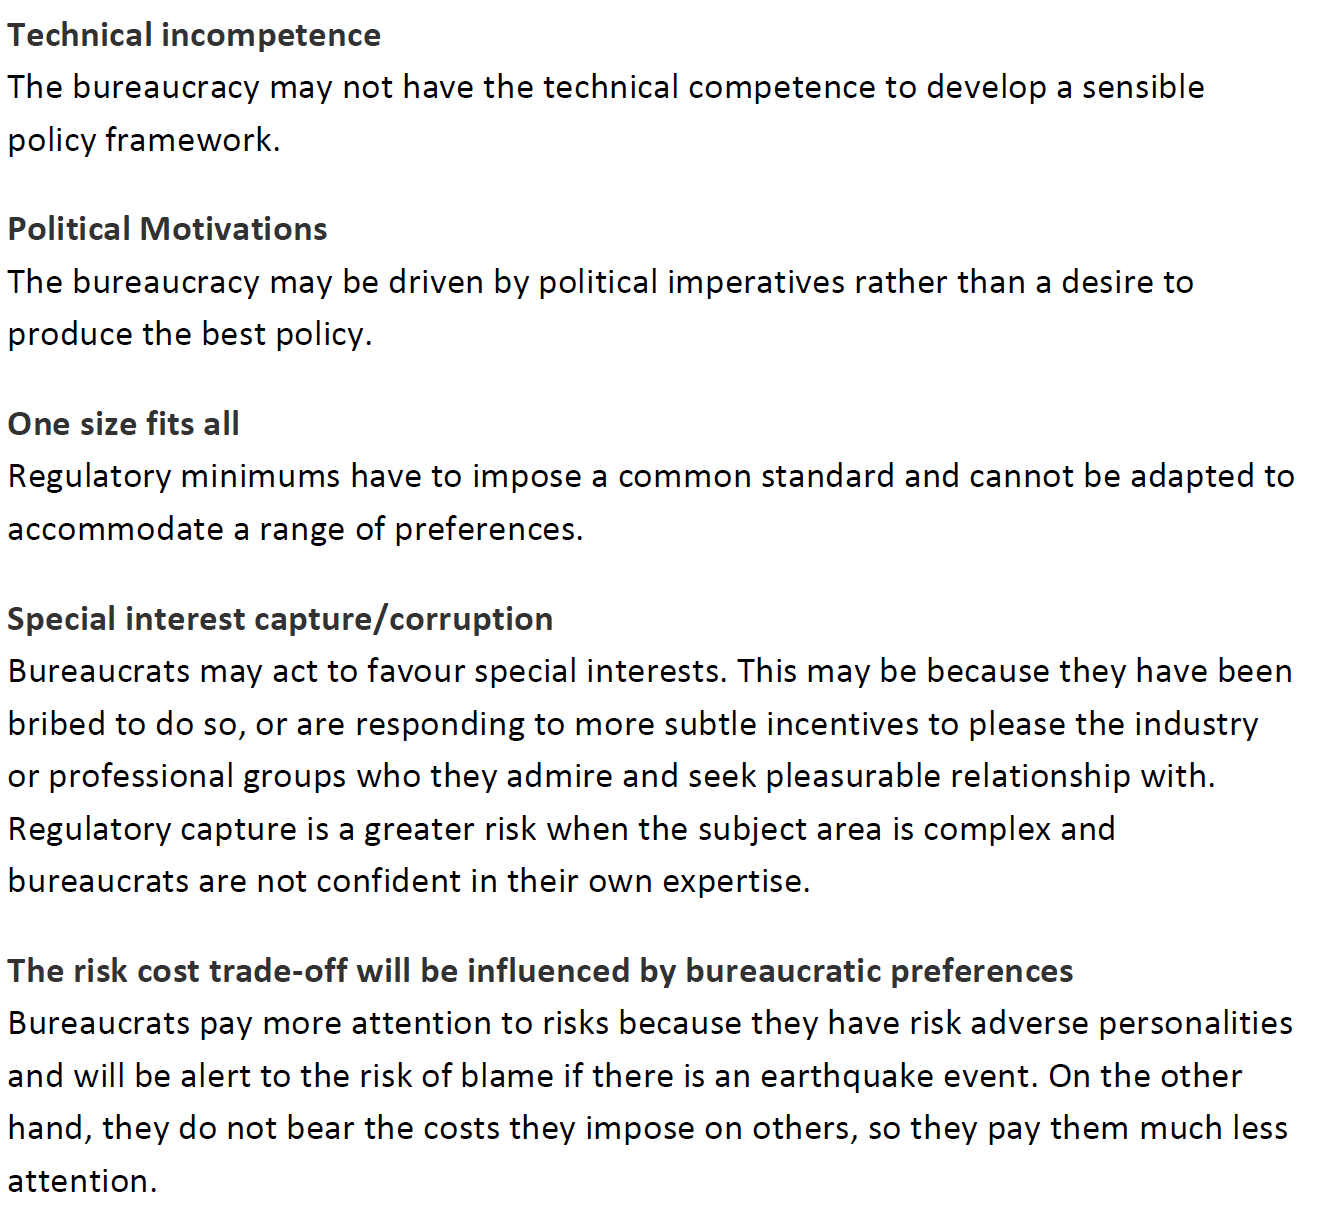
Ian’s focus is bureaucratic failures. I particularly enjoyed this, perhaps somewhat jaundiced, list of factors that lead official agencies, however well-intentioned, towards bad outcomes.

harrison2

harrison1

As King and Crewe’s book reflects, officials will make plenty of mistakes, but cases that rise to the level of  “blunders” hardly ever result from the efforts of officials alone.

Whither the inflation target?

I’ve just been finalising for publication some comments I presented late last year at the IJCB-RBNZ conference marking the 25th anniversary of inflation targeting, and reflecting again on the wider set of options from which authorities can choose.  Looking ahead, I’m not convinced that inflation targeting is clearly superior to the alternatives.  The slightly unconventional option that I would prefer to see explored in more depth is nominal wage targeting.   Wages are the stickiest of the nominal prices, and nominal wages are also the key element underpinning the servicing of nominal debt.

But that is a topic for another day.  Today I want to focus more narrowly on the question of “if we are going to run an inflation target, where should that target be set”.  In our system, the Minister of Finance has the lead in setting the target[1].

The approach to setting the level of the first inflation target was pretty simple. The Act specified that the primary goal of monetary policy was “stability in the general level of prices”, and in setting an inflation target range the idea was simply to have something as close as feasible to that.   I think most of those involved thought a 0 to 2 per cent annual inflation target was a pretty close approximation to “price stability”.

The more hard-line among us were a bit disappointed when Winston Peters and Don Brash later agreed to shift the target up to 0 to 3 per cent, and then Michael Cullen and Alan Bollard agreed to a further shift up to 1 to 3 per cent.   These changes seemed to arise from some mix of political product differentiation, and convergence towards the targets being used in other countries.  But I don’t think anyone at the Bank really thought these changes would make much macroeconomic difference, good or ill.  Nominal targets generally shouldn’t.  The tax system works a little less well with slightly higher inflation, but any downward nominal rigidities are also a little less pressing.

One factor that never got much attention was the near-zero lower bound on nominal interest rates.  We knew it was there –  if policy interest rates got much below zero people could simply shift to cash – but it never seemed likely to be much of an issue for New Zealand.

Craig Ebert, senior economist at the BNZ, put out an interesting note a month ago arguing that New Zealand should think seriously about lowering its inflation target.  The gist of the argument is that deflation isn’t particularly harmful and that the current global low inflation is, from a New Zealand perspective, a good thing, which should be accommodated rather than offset.

I’m not persuaded.   Deflation isn’t likely to be harmful if it results from positive productivity shocks, and occurs in economies where private debt has only a modest role.   In most of the older deflations that the recent BIS paper looked at, not only was private debt much less important than it is now, but the near-zero lower bound was not a binding constraint.  We have never had a period in (modern?) history when policy interest rates have been near-zero for so long, and when private debt (and private financial assets) have been so pervasively important.

Last year, a leading figure in global central banking over the last 20 years visited New Zealand.  I asked him whether, purely with the benefit of hindsight, he wished that inflation targets had been set nearer 5 per cent than 2 per cent.  Doing so would have provided additional leeway to reduce real policy interest rates, to more deeply negative levels, during the period since 2007.  I didn’t really expect him to agree with the proposition, but what really surprised me was how few arguments he could put up in defence of  inflation targets centred on 2 per cent.  For countries that have now spent years at the near-zero lower bound, the with-hindsight case for higher initial inflation targets seems pretty clear-cut.  In the old line from James Tobin “it takes a heap of Harberger triangles to fill an Okun’s gap”.   Yes, the tax system worked a bit better with lower inflation, but there are an awfully large number of people unemployed across the advanced world at present.  The limits of monetary policy are part of the story.

But where should inflation targets be set now?  Is there a case now for raising them to 4 or 5 per cent, as commentators as eminent as Olivier Blanchard and Ken Rogoff have suggested?  In particular, is there such a case for New Zealand?   Eric Rosengren, President of the Boston Fed recently called for a debate on whether the Fed’s inflation target should be raised.  The FT suggests he was the first serving policymaker to openly canvass the issue.

The issue is perhaps more relevant for New Zealand (and Australia) than for most other advanced countries.  Why?  Quite simply because advanced countries that are at the near-zero lower bound  at present have no way of credibly raising inflation, and inflation expectations, from something around current inflation targets to something around 4-5 per cent.

If they could then inflation expectations would rise and real interest rates would fall, drawing forward more demand, and absorbing the current excess capacity (getting people back into jobs).  But policy interest rates in these countries can’t (with current institutional constraints) be cut materially further, and no one really believes that QE can make that degree of difference.   And people might reasonably conclude that an announced higher target was simply a desperate measure for crisis times, and that the authorities would renege on it once economic recovery got underway.

Some have suggested that expansionary fiscal policy provides a way through.  In principle that sounds fine, but in most (but not all) of these countries public debt is already very high (and understated in official figures, which often don’t record public sector pension liabilities), populations are ageing and –  probably not unrelatedly –  the political appetite for materially expansionary fiscal policy is largely non-existent.  Witness, as an example, the current UK election.

New Zealand is not at the near-zero lower bound.  But neither was most of the rest of the advanced world in 2007.  Indeed, almost all those countries had policy interest rates then above New Zealand’s current 3.5 per cent.  In the last rate-cutting cycle, the OCR was cut by 575 basis points and in the previous cycle, in the 1990s, short-term interest rates were allowed to fall by a similar amount.    Future recessions will happen, and there is no obvious reason to think that they will be smaller than we’ve seen before.  But the OCR could not now be cut by 575 basis points or anything like it.  Our Minister of Finance, and his advisers, should be treating that as a pressing concern.

Nominal targets shouldn’t matter very much for medium-term economic outcomes.  And they wouldn’t without the near-zero bound, and the free option of converting to cash.   Some argue that a negative 5 per cent Fed funds rate would have been helpful in the US in the depths of the recession. But if such a rate had been implemented there would have been large scale conversions  to physical cash and effective interest rates would not have gone materially negative.  Every central bank knows this, and none has been willing to cut policy rates so far as to see those large scale conversions.  These provisions are acting as a real constraint on central banks now, and constraining the speed at which economies can rebound from recession.

New Zealand should be acting now to be better positioned when the next serious downturn comes.  We don’t know when that will be.  If things turn nasty in China, in the rest of the emerging world, or in Europe once the first country leaves the euro, it could be very soon.  But it could be years away.    Or it might never happen.  No one can forecast timings.  But contingency planning isn’t about timing, but about planning for identified vulnerabilities.

There are two broad options:

  • Serious policy work on overcoming the near-zero lower bound, or
  • Raise the inflation target

What could be done about the near-zero lower bound?

  • In the longer-term, it might involve looking to phase out physical central bank notes and coins (which now play a very small role in day-to-day transactions)
  • It might involve repealing the legislative monopoly the Reserve Bank has on issuing physical notes and coins. The scope for innovative market-led alternatives might make it easier to end physical issuance by the central bank altogether
  • The stock of notes and coins could be capped at current  levels.  To the extent that physical currency has value as a retail payments medium it would still be available, but if it became scarcer the price would rise.
  • Central banks could put impose a fixed fee for converting settlement account balances into physical currency.  A 10 per cent fee, for example, would be likely to provide material additional leeway to allow policy rates to be cut more deeply negative.

People like Miles Kimball, Willem Buiter and others have written on some of these issues in much more depth.  I’m not sure which of these options, or others that have been touted, would be best.  But they are issues that central banks and finance ministries should be exploring in more depth now.  In New Zealand’s case, a joint working party with Australian officials might be an efficient way to address the issues.

Dealing with the near-zero lower bound –  mostly a government intervention which has become troublesome – should be a better option.  Something like a stable value of money seems a better outcome for society than a steady targeted debasement of the value of the currency.    If that could be done, a lower medium-term inflation target, centred on (true) zero might be desirable.

But if –  for whatever reason –  the authorities are not willing to do anything active about removing the near-zero lower bound, then they need to be thinking much harder about raising the inflation target[2].  New Zealand can actually deliver higher inflation, and do it quite quickly.  The OCR is 3.5 per cent, and there is nothing to suggest that the transmission mechanism is so impaired that lower policy rates would not flow through into lower retail interest rates, a lower exchange rate, and to higher inflation.   In some ways it would be a shame to have to do it.  But the possibility of a prolonged period in which the scope for conventional monetary policy has been exhausted, and the number of unemployed people sits far above normal levels for years, is not a risk that a democratic government should contemplate with equanimity.

[1] Section 9 of the Reserve Bank Act requires that “The Minister shall, before appointing, or reappointing, any person as Governor, fix, in agreement with that person, policy targets for the carrying out by the Bank of its primary function during that person’s term of office, or next term of office, as Governor.”  Since the Minister has a blocking veto on any recommended person for appointment as Governor, the Minister should normally have the dominant influence on the content of the Policy Targets Agreement.

[2] And would then need to do something about indexation of the tax system.

Anthony Trollope and a blunder of our governments

Anthony Trollope, the great English novelist, was born 200 years ago last Friday.

He and his wife spent two months in New Zealand in 1872.  Trollope recorded his observations and experiences in Australia and New Zealand.  Large chunks of the New Zealand bits were republished in 1969 in With Anthony Trollope in New Zealand, edited by A H Reed.  I’ve dipped into this book over the last few days, and reproduced a few of his observations on Anglican Christchurch here.  His description of a visit to the, now long-lost, Pink and White Terraces is evocative and well worth reading

But Trollope also came to Wellington.  Recall that the early 1870s was the prime of Julius Vogel, first as Colonial Treasurer and then as Premier, leading a heavy borrowing programme to finance large scale public works, railways, and immigration.  Trollope’s time in Wellington coincided with a motion of no-confidence in Vogel moved in the House of Representatives by the former Premier Edward Stafford.

I don’t think Trollope could quite make up his mind about railways and New Zealand (not unexpectedly perhaps: he was a novelist from abroad and former public servant in the British Post Office).  He repeats, and appears to accept, the oft-heard argument that New Zealand was different from Britain, and that government must be involved in marshalling the capital for railroads.  He observes “nothing tends so quickly to enrich a country and to enable a people to use their wealth which God has placed within their reach, as a ready conveyance for themselves and their goods.  But, faced with specifics, he also observes  that a rail line to the “valley of the Hutt” appears of “questionable political economy”.

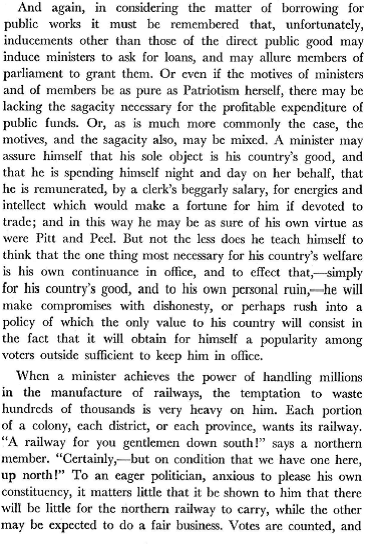
But Trollope really gets into his stride on the issue of incentives and (lack of) adequate disciplines once such works programmes are envisaged.

trollope1

trollope2

Logrolling, mixed motives, the self-delusions to which all office holders are prone, the lure of the immediate over the longer-term, it is all there.  This, after all, was the man who was shortly to write the excellent The Way We Live Now.

How far has the analysis of rail in New Zealand moved on?  The allure of rail seems to remain real in some quarters – and perhaps we all fall for it briefly any time we take, say, the Eurostar between Paris and London.  One very senior public servant was heard to utter, not six years ago, in a serious discussion of New Zealand’s disappointing economic performance, his view that one of New Zealand’s great failings over its history had been under-investment in rail infrastructure –  rail having been, he noted, one of the great legacies to the world of Victorian Britain.

The previous government bought back the rail company, and the current one seems to be pouring extraordinary amounts of money into the renamed Kiwirail.  There is little sign that any very rigorous cost-benefit analysis is being done to evaluate the prospective expenditure and continuing operations at poor economic returns.  Perhaps it is still too soon to tell, but I suspect that the continued heavy spending on an extensive rail network will prove a worthy candidate to add to a New Zealand list of blunders of our governments.